
Frozen Food Market Size, Share, Trends and Forecast by Product Type, Frozen Vegetable Snacks Type, Frozen Meat Products Type, Frozen Vegetables Type, Frozen Fruits Type, and Region, 2026-2034
Frozen Food Market Size, Share, Trends & Forecast (2026-2034)
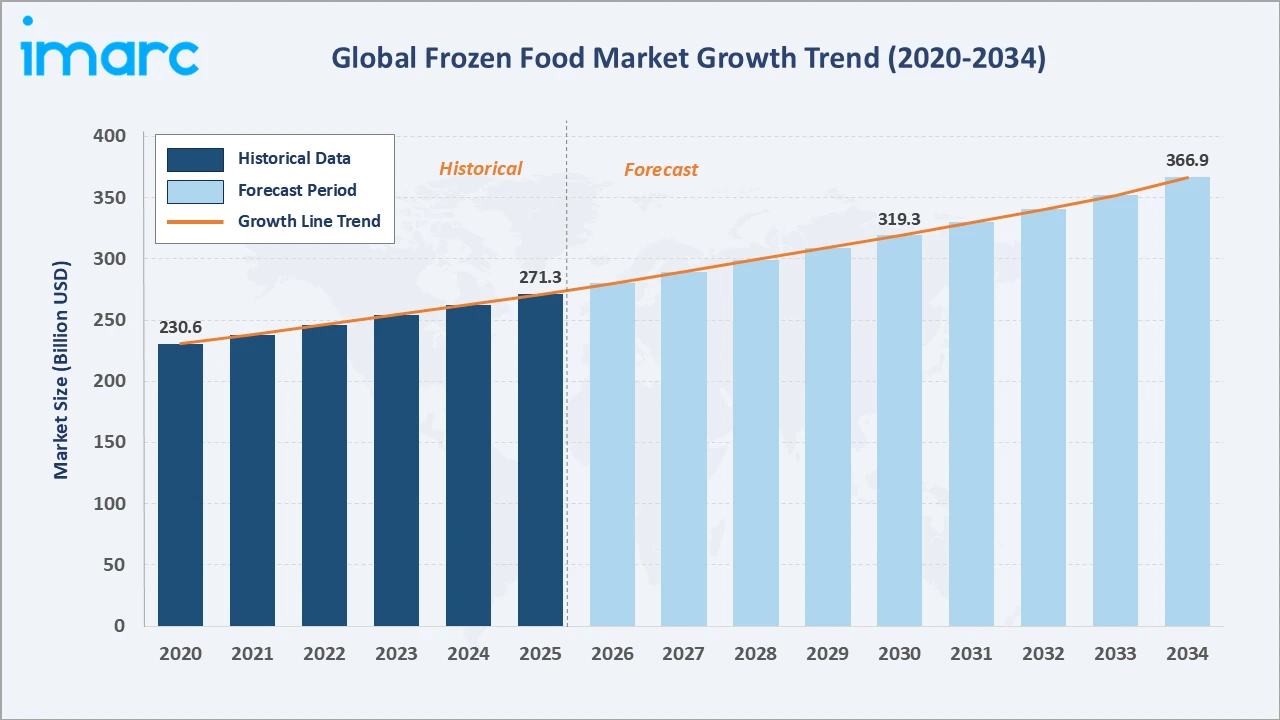
The frozen food market grew from USD 271.3 Billion in 2025 to USD 280.3 Billion in 2026 and is projected to reach USD 366.9 Billion by 2034, exhibiting a CAGR of 3.31% during 2026-2034. Rising consumer preference for convenient, ready-to-prepare meal solutions, rapid urbanization, and expanding cold chain infrastructure are the primary forces shaping market growth.
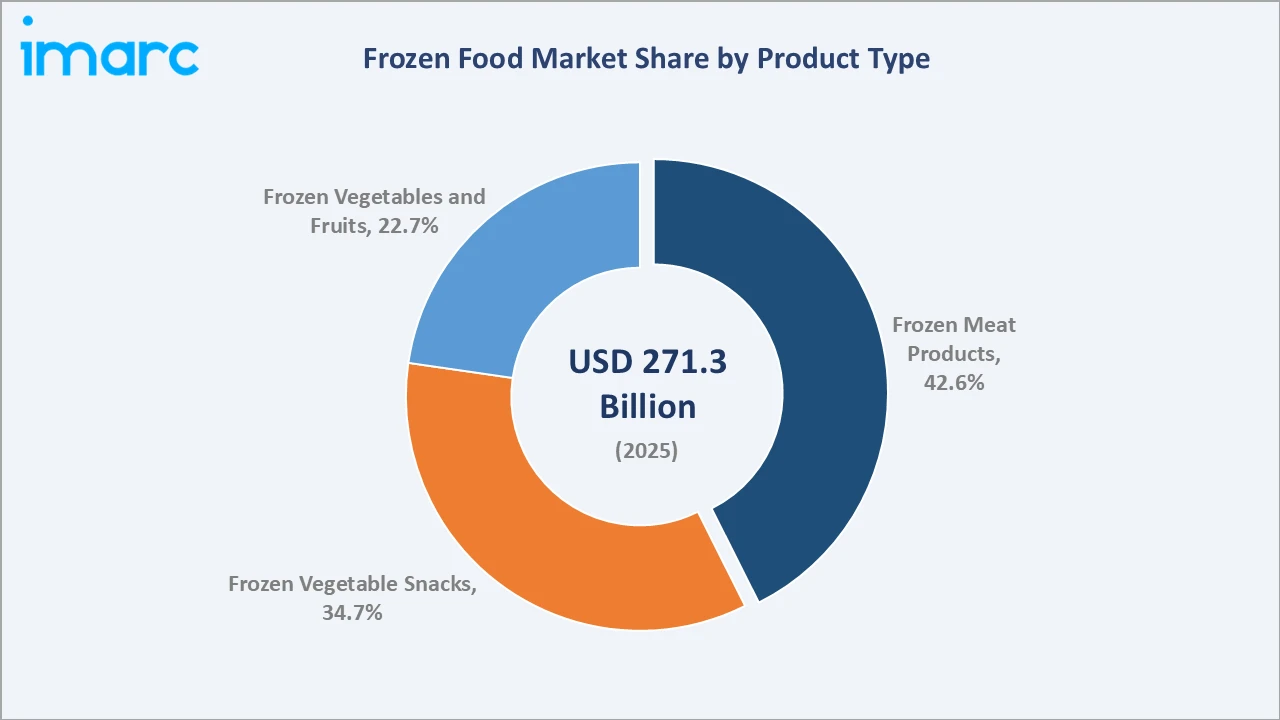
Frozen meat products lead the product type segment at 42.6% share in 2025. Among frozen vegetable snacks type, French fries command the largest sub-segment share at 38.4%. Europe dominates the regional landscape at 33.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 271.3 Billion |
|
Market Size (2026) |
USD 280.3 Billion |
|
Forecast Market Size (2034) |
USD 366.9 Billion |
|
CAGR (2026-2034) |
3.31% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Europe (33.8%, 2025) |
|
Second Largest Region |
North America (28.6%, 2025) |
|
Leading Product Type |
Frozen Meat Products (42.6%, 2025) |
|
Leading Frozen Vegetable Snacks Type |
French Fries (38.4%, 2025) |
The frozen food market size increased from USD 230.6 Billion in 2020 to USD 271.3 Billion in 2025 and is estimated to reach USD 280.3 Billion in 2026. The market is further expected to grow to USD 319.3 Billion by 2030 and USD 366.9 Billion by 2034. This steady trajectory reflects the deepening integration of frozen food products into global dietary routines, supported by improving cold chain access, product innovation, and rising organized retail penetration across Asia-Pacific and Latin America.
To get more information on this market, Request Sample
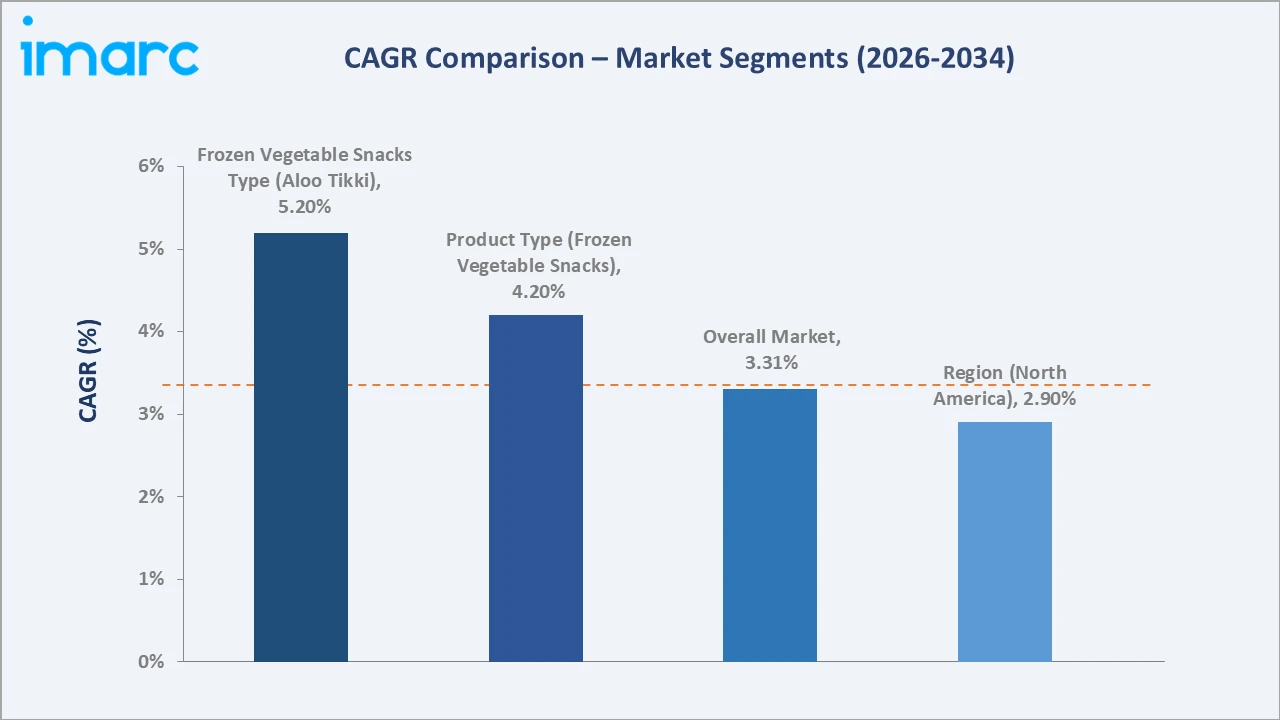
CAGR trajectories across product type, frozen vegetable snacks type, and regional sub-segments reveal meaningful variation around the overall 3.31% market rate. Emerging sub-segments such as aloo tikki at 5.20% and Asia-Pacific at 4.80% are expanding faster, driven by rising demand in developing markets, evolving snacking habits, and growing foodservice penetration.
Executive Summary
The frozen food market expanded from USD 271.3 Billion in 2025 to an estimated USD 280.3 Billion in 2026, positioning it among the world's largest and most consistently growing packaged food categories by absolute value. The market's scale is underpinned by rising consumer demand for convenient meal solutions, expanding organized retail and cold chain infrastructure, and increasing product innovation across health-oriented and plant-based frozen formats.
Frozen meat products command 42.6% of product type share in 2025, driven by strong consumer preference for protein-rich, ready-to-cook offerings across retail and foodservice channels. French fries lead at 38.4% of the frozen vegetable snacks type segment, fueled by their widespread popularity, ease of preparation, and strong demand across quick-service restaurants and household consumption. Europe leads regional share at 33.8%, anchored by established cold chain infrastructure and mature retail penetration.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Product Type | Frozen Meat Products – 42.6% share (2025) |
| Second Largest Product Type | Frozen Vegetable Snacks – 34.7% share (2025) |
| Leading Frozen Vegetable Snacks Type | French Fries – 38.4% share (2025) |
| Second Largest Frozen Vegetable Snacks Type | Bites, Wedges and Smileys – 24.7% share (2025) |
| Leading Region | Europe – 33.8% share (2025) |
| Second Largest Region | North America – 28.6% share (2025) |
| Top Companies | Nestlé S.A., McCain Foods Limited, Tyson Foods, Inc., JBS N.V. |
Key Analytical Observations Expanding On the Data Above:
- Frozen meat products dominance at 42.6% reflects high consumer preference for protein-rich, ready-to-cook offerings and strong demand from both retail and foodservice segments worldwide.
- Frozen vegetable snacks share at 34.7% is growing steadily, driven by the rising popularity of convenient snacking options and the expanding availability of frozen snack varieties in modern trade formats.
- French fries leadership at 38.4% is underpinned by its universal appeal across age groups, widespread availability through quick service restaurants and retail, and its compatibility with diverse cuisines globally.
- Bites, wedges and smileys at 24.7% are gaining traction among younger consumer demographics, supported by expanding school foodservice contracts and appealing product formats designed for convenience-driven households.
- Europe at 33.8% leads due to a mature frozen food culture, robust retail infrastructure, advanced cold chain networks, and sustained consumer trust in quality frozen food brands.
Frozen Food Market Overview
Frozen food refers to food products preserved through rapid freezing technologies and stored at temperatures typically at or below -18°C to maintain nutritional content, taste, and safety. The category encompasses frozen meat and seafood products, ready meals, vegetables, fruits, bakery items, and snacks, serving both household consumers and the broader foodservice sector across global retail channels.
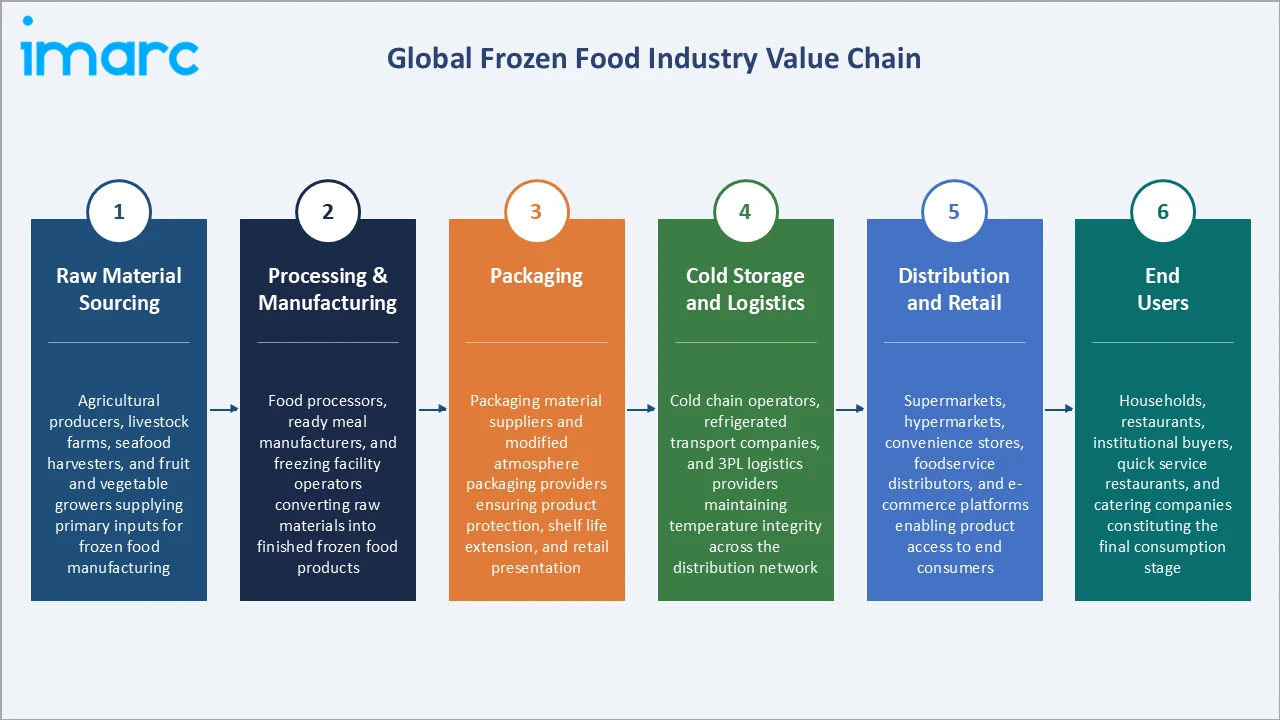
The global ecosystem integrates agricultural raw material suppliers, food processing and manufacturing facilities, packaging companies, cold chain and logistics providers, organized retailers, and end consumers. Supporting layers include regulatory bodies, technology providers specializing in freezing solutions, and e-commerce platforms enabling direct-to-consumer delivery. Together, these stakeholders drive a commercially viable and increasingly innovative frozen food supply chain.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
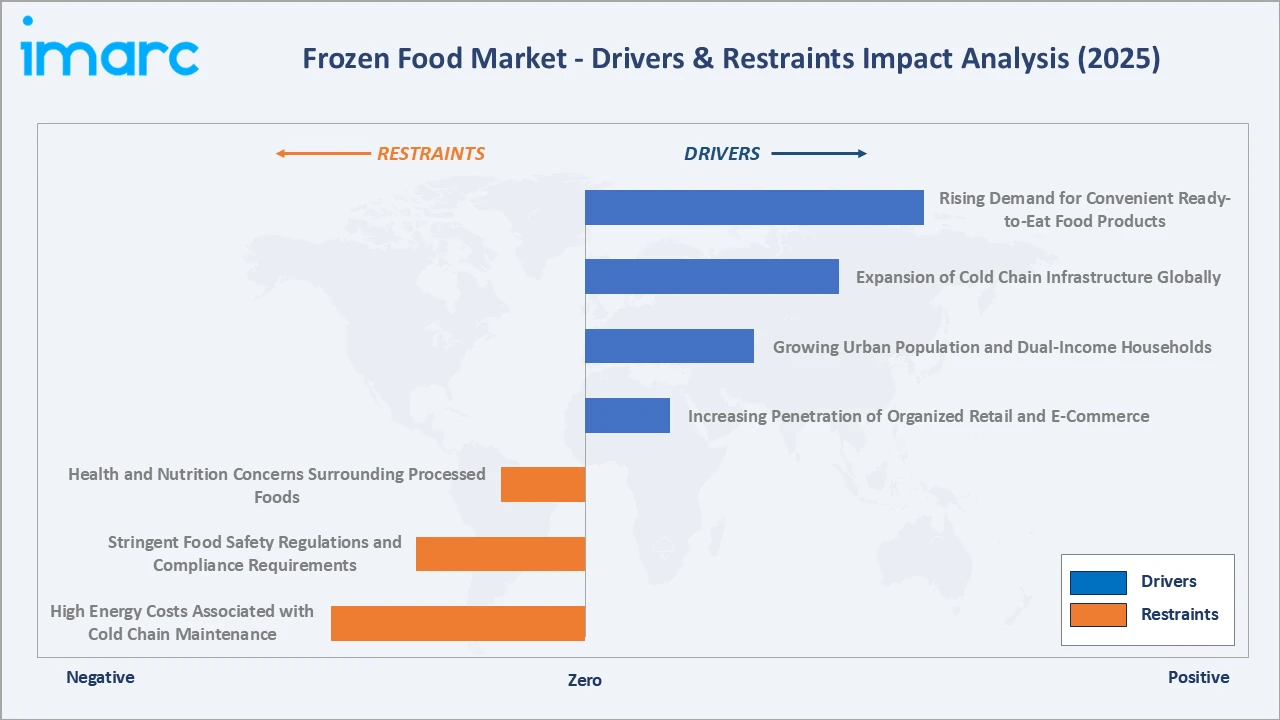
- Rising Demand for Convenient Ready-to-Eat Food Products: Urbanization and evolving lifestyles are driving sustained demand for frozen meals and snacks. According to the United Nations, more than 68% of the global population is projected to live in urban areas by 2050, creating a large and growing consumer base for time-saving frozen food solutions.
- Expansion of Cold Chain Infrastructure Globally: Governments and private investors across Asia-Pacific, Latin America, and the Middle East and Africa are actively investing in refrigerated storage and transportation networks, broadening access to frozen food distribution and enabling market penetration into previously underserved regions. These investments also feature in frozen food market news, highlighting the growing importance of logistics infrastructure in supporting industry expansion.
- Growing Urban Population and Dual-Income Households: Rising dual-income household numbers are reducing time available for meal preparation, increasing reliance on frozen convenience foods as a practical solution for everyday nutrition across a broad range of income segments and geographies.
- Increasing Penetration of Organized Retail and E-Commerce: As per IMARC Group, the global e-commerce market size was valued at USD 33.80 Trillion in 2025. The rapid expansion of supermarkets, hypermarkets, and online grocery platforms is improving product visibility and consumer access to frozen food categories, particularly in emerging markets where organized retail penetration is accelerating alongside rising income levels.
Market Restraints
- Health and Nutrition Concerns Surrounding Processed Foods: Growing consumer awareness regarding sodium content, preservatives, and caloric density in processed frozen products is prompting some segments to shift toward fresh alternatives, creating headwinds for traditional product formulations in health-conscious markets.
- Stringent Food Safety Regulations and Compliance Requirements: Manufacturers operating across multiple markets face complex and varying food safety, labeling, and cold chain compliance requirements, increasing operational costs and limiting the speed of product launches and market entry strategies.
- High Energy Costs Associated with Cold Chain Maintenance: Maintaining consistent sub-zero temperatures across storage and transportation networks requires significant and ongoing energy investment, increasing operating costs for manufacturers, distributors, and retailers throughout the frozen food supply chain.
Market Opportunities
- Growing Demand for Plant-Based and Health-Oriented Frozen Products: Increasing consumer interest in plant-based nutrition and clean-label foods is creating significant product innovation opportunities. Manufacturers that develop nutritionally optimized frozen alternatives with natural ingredients are well-positioned to capture high-value growth segments across developed and emerging markets, a shift widely reported in frozen foods industry news as a defining strategic priority for leading manufacturers.
- Expansion into Emerging Markets with Rising Disposable Incomes: Markets across Southeast Asia, the Middle East, and Latin America offer substantial untapped growth potential as rising disposable incomes, improving cold chain access, and expanding retail infrastructure create favorable conditions for increased frozen food adoption.
Market Challenges
- Maintaining Cold Chain Integrity Across Extended Distribution Networks: Temperature excursions during transportation and storage can compromise product safety and quality, leading to waste, consumer complaints, and regulatory scrutiny. Ensuring consistent cold chain management across geographically dispersed and multi-tier distribution networks remains a persistent operational challenge for market participants.
- Managing Consumer Perception Against Fresh Food Alternatives: Despite improvements in product quality and nutrition, a segment of consumers continues to associate frozen food with lower freshness and nutritional value compared to fresh equivalents. Overcoming this perception requires sustained marketing investment, transparent labeling, and continued product innovation aligned with consumer expectations.
Emerging Market Trends
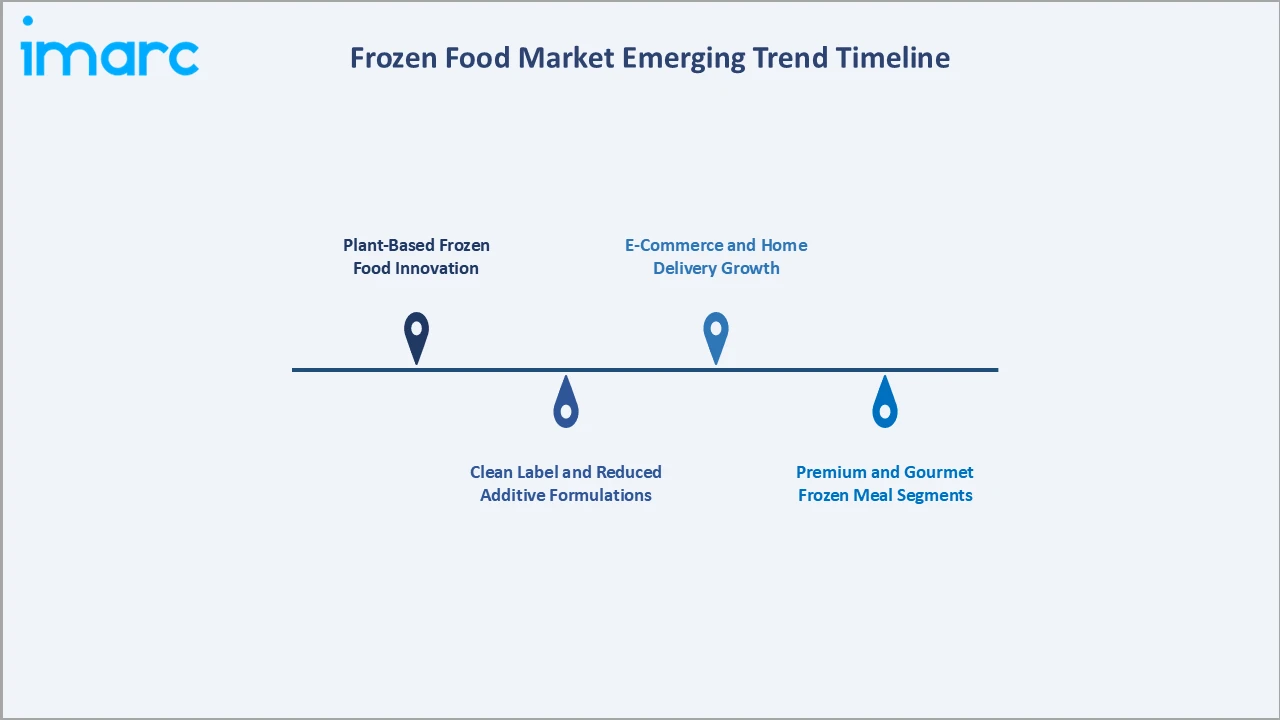
1. Plant-Based Frozen Food Innovation
The plant-based frozen food segment is one of the most dynamic areas of innovation within the global market. Major manufacturers are expanding frozen plant-based meat alternatives, dairy-free frozen desserts, and legume-based ready meals.
2. Clean Label and Reduced Additive Formulations
Consumers across key markets are increasingly seeking frozen products with fewer artificial ingredients, shorter ingredient lists, and transparent sourcing. This trend is driving manufacturers to reformulate core products by replacing artificial preservatives and flavor enhancers with natural alternatives, while maintaining the taste and convenience attributes that drive category appeal.
3. E-Commerce and Home Delivery Growth
Online grocery platforms and direct-to-consumer delivery services are reshaping frozen food distribution. Improved insulated packaging, specialized frozen delivery networks, and increasing digital grocery adoption are enabling manufacturers to reach consumers beyond traditional retail channels, with the frozen snacks market emerging as one of the fastest-growing categories in online frozen food baskets, opening new demand streams particularly in urban markets.
4. Premium and Gourmet Frozen Meal Segments
A growing segment of consumers in developed markets is seeking restaurant-quality frozen meals at accessible price points. The premiumization trend is driving investment in higher-quality ingredients, globally inspired cuisine options, and chef-developed frozen meal formats, expanding the addressable value proposition of frozen food beyond basic convenience.
Industry Value Chain Analysis
The frozen food value chain spans six integrated stages, from raw material sourcing through final consumption. Processing, manufacturing, and cold chain logistics represent the highest capital intensity, while retail and foodservice distribution determine end-consumer access and brand positioning across global markets.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Agricultural producers, livestock farms, seafood harvesters, and fruit and vegetable growers supplying primary inputs for frozen food manufacturing |
| Processing and Manufacturing | Food processors, ready meal manufacturers, and freezing facility operators converting raw materials into finished frozen food products |
| Packaging | Packaging material suppliers and modified atmosphere packaging providers ensuring product protection, shelf life extension, and retail presentation |
| Cold Storage and Logistics | Cold chain operators, refrigerated transport companies, and 3PL logistics providers maintaining temperature integrity across the distribution network |
| Distribution and Retail | Supermarkets, hypermarkets, convenience stores, foodservice distributors, and e-commerce platforms enabling product access to end consumers |
| End Users | Households, restaurants, institutional buyers, quick service restaurants, and catering companies constituting the final consumption stage |
Vertically integrated operators controlling both manufacturing and cold chain distribution are positioned to capture greater margin than single-stage participants. Strategic partnerships between food manufacturers and cold chain logistics providers are increasingly common as the market scales across emerging regions with developing refrigeration infrastructure.
Technology Landscape in the Frozen Food Industry
Freezing Technologies
Individual quick freezing (IQF) technology remains the dominant processing method, enabling rapid freezing of individual food pieces while preserving texture, flavor, and nutritional content. Cryogenic freezing using liquid nitrogen is gaining adoption for premium applications requiring ultra-rapid processing and minimal ice crystal formation.
Packaging Innovation
Modified atmosphere packaging and vacuum skin packaging (VSP) are improving product shelf life and reducing food waste across the frozen food supply chain. Smart packaging incorporating time-temperature indicators is emerging as a quality assurance tool, providing real-time cold chain monitoring from manufacturing to point of sale.
Cold Chain Monitoring and Automation
Internet of Things (IoT)-enabled temperature sensors and cloud-based monitoring platforms are being deployed across cold chain networks to enable real-time visibility, predictive maintenance, and compliance documentation. These technologies reduce temperature excursion incidents and improve distribution efficiency across multi-tier logistics networks.
Processing Automation
The leading frozen food companies globally are investing in robotic processing lines, automated portioning systems, and AI-driven quality inspection platforms. Automation addresses the growing volume demands of the frozen meal market, improving throughput consistency, reducing labor dependency, and enabling manufacturers to maintain product quality standards at scale across high-volume production environments.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Frozen Meat Products | 42.6% | 2025 |
| Frozen Vegetable Snacks Type | French Fries | 38.4% | 2025 |
| Frozen Meat Products Type | 🔒 | 🔒 | 2025 |
| Frozen Vegetables Type | 🔒 | 🔒 | 2025 |
| Frozen Fruits Type | 🔒 | 🔒 | 2025 |
| Region | Europe | 33.8% | 2025 |

By Product Type
Frozen meat products command a 42.6% majority share in 2025, driven by its high consumer demand across both retail and foodservice channels. The segment benefits from the broad availability of beef, poultry, pork, and seafood products in frozen formats, and from strong demand in institutional and quick service restaurant procurement globally.
To access detailed market analysis, Request Sample
Frozen vegetable snacks at 34.7% represent the second-largest product type category, benefiting from rising snacking occasions, increasing availability in modern retail formats, and growing consumer preference for convenient, portion-controlled snack alternatives across both developed and emerging markets.
By Frozen Vegetable Snacks Type
French fries represent 38.4% of the frozen vegetable snacks type segment in 2025, directly reflecting their universal appeal across age groups, widespread availability in quick service restaurants, and strong at-home consumption growth supported by air fryer adoption trends.
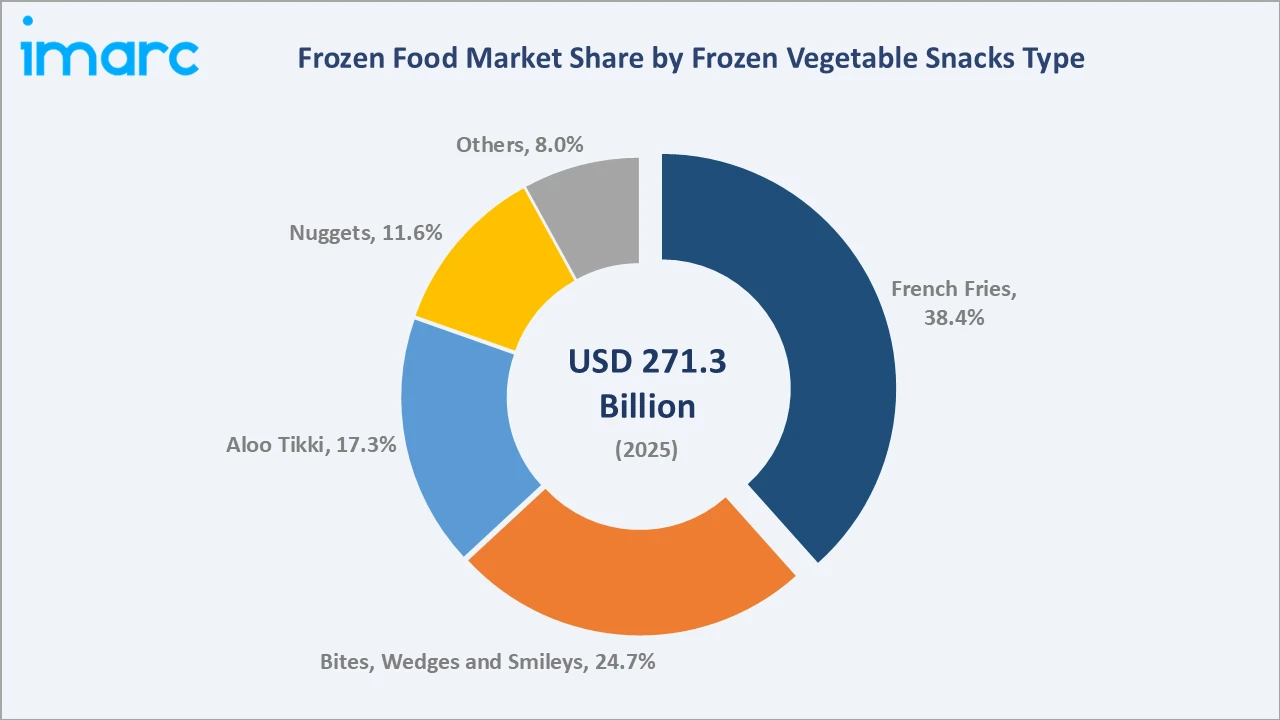
Bites, wedges and smileys at 24.7% is the second-largest sub-segment, gaining traction through school foodservice channels and family-oriented retail formats.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| Europe | 33.8% | Mature cold chain infrastructure, high frozen food per-capita consumption, strong retail penetration, and sustained product innovation across convenience meal and premium frozen categories |
| North America | 28.6% | High household frozen food usage, established foodservice demand for frozen proteins and snacks, expanding plant-based frozen segment, and widespread organized retail coverage |
| Asia-Pacific | 23.4% | Rapidly expanding cold chain networks, rising disposable incomes, growing urbanization, increasing consumer adoption of convenient frozen foods, and strong government infrastructure investment |
| Latin America | 8.1% | Expanding organized retail, improving cold chain logistics, rising urban population, growing middle class demand for frozen convenience products, and increasing foodservice sector penetration |
| Middle East and Africa | 6.1% | Growing organized retail footprint, rising food imports and hospitality sector demand, improving refrigeration infrastructure, and increasing consumer exposure to frozen food formats |
Europe at 33.8% in 2025 leads the regional landscape, anchored by decades of established frozen food culture, advanced cold chain infrastructure, strong organized retail penetration, and a broad product offering spanning premium ready meals, frozen meat, and vegetable categories.
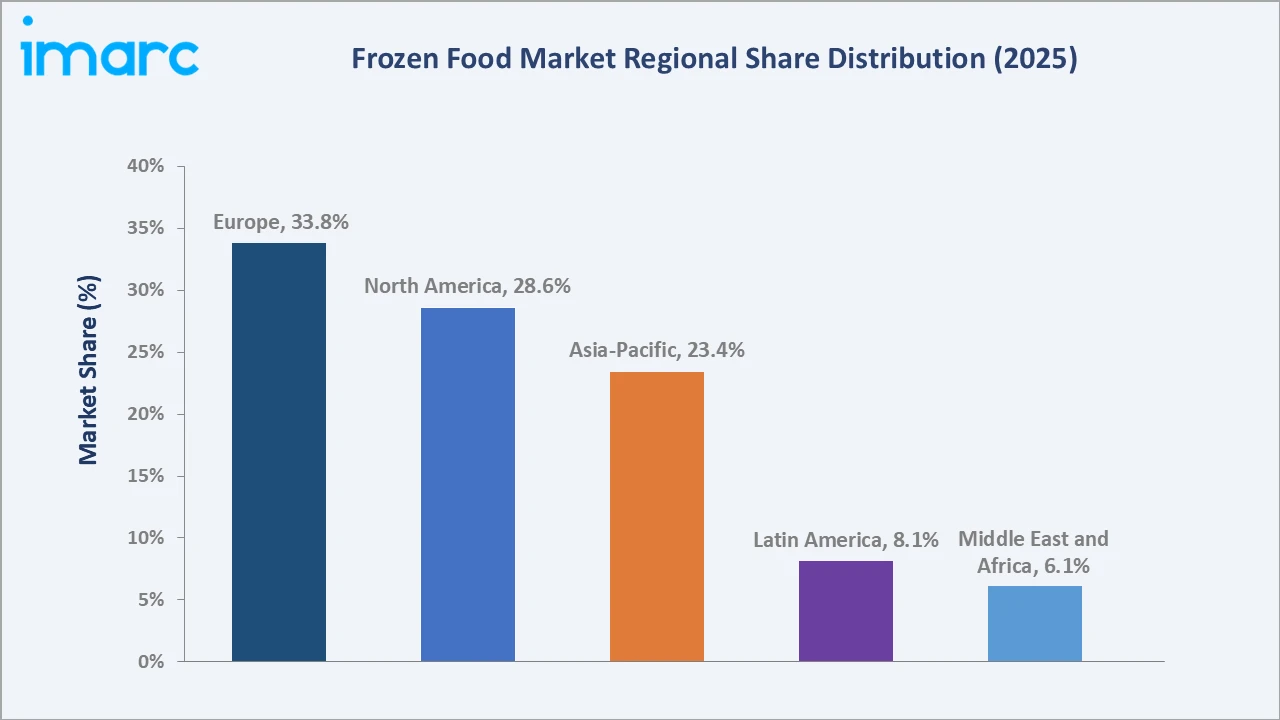
Asia-Pacific, while currently the third-largest region at 23.4%, is expanding at the fastest rate among the major regions, supported by rapid urbanization in China, India, and Southeast Asia, improving cold chain access, and rising middle-class demand for convenient food solutions. The region represents a substantial growth opportunity for manufacturers investing ahead of infrastructure maturity.
Competitive Landscape
The frozen food market is moderately concentrated, with a mix of multinational food conglomerates, specialist frozen food manufacturers, and regional players competing on brand strength, product portfolio breadth, distribution reach, and cold chain capability. Innovation in health-oriented and plant-based frozen formats, alongside premiumization and e-commerce channel development, are the primary competitive differentiators shaping market positioning strategies globally.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Nestlé S.A. | Stouffer's / Lean Cuisine | Leader | Expanding health-oriented frozen meal portfolio and strengthening premium frozen brand presence across retail and foodservice channels globally |
| McCain Foods Limited | McCain | Leader | Expanding global frozen potato and snack manufacturing capacity while developing health-oriented and plant-based frozen product lines |
| Tyson Foods, Inc. | Tyson | Challenger | Growing frozen protein and ready meal offering through brand innovation and expanding retail distribution partnerships |
| JBS N.V. | Seara | Challenger | Scaling frozen meat and processed food portfolio across international markets through vertical integration and brand development |
Key players include Nestlé S.A., McCain Foods Limited, Tyson Foods, Inc., and JBS N.V., among others.
Key Company Profiles
Nestlé S.A.
Nestlé S.A. is a Swiss multinational food and beverage company headquartered in Vevey, Switzerland. It is one of the world's largest food companies and operates a significant frozen food portfolio through brands including Stouffer's and Lean Cuisine, serving both retail consumers and foodservice operators across global markets.
- Product Portfolio: Frozen ready meals, frozen pasta products, frozen pizza, health-oriented frozen entrees, and international cuisine frozen formats across retail and foodservice channels.
- Recent Developments: The company continues to invest in health and wellness-oriented product reformulations, expanding plant-based frozen alternatives and reducing sodium and artificial additive content across its core frozen meal brands.
- Strategic Focus: Strengthening premium and health-oriented frozen meal positioning across key retail markets while expanding digital and e-commerce channel capabilities.
McCain Foods Limited
McCain Foods Limited is a Canadian multinational food company and is among the world's leading producers of frozen potato products. The company operates manufacturing facilities across several countries, supplying frozen French fries, wedges, appetizers, and snacks to retail and foodservice customers globally.
- Product Portfolio: Frozen French fries, wedges, potato specialties, vegetable appetizers, plant-based snacks, and frozen potato products for retail and foodservice channels worldwide.
- Recent Developments: McCain Foods Limited is advancing its sustainability commitments through regenerative agriculture programs and energy efficiency investments at its manufacturing facilities, alongside expanding its plant-based and premium snack product lines.
- Strategic Focus: Expanding global frozen potato and snack manufacturing capacity and developing health-oriented and plant-based product lines to address evolving consumer preferences.
Tyson Foods, Inc.
Tyson Foods, Inc. is a United States-based food company headquartered in Springdale, Arkansas. It is among the world's largest processors and marketers of chicken, beef, and pork, operating a significant frozen protein and convenience food portfolio through its Tyson brand across retail and foodservice channels in the United States and internationally.
- Product Portfolio: Frozen chicken strips, nuggets, wings, frozen breakfast items, frozen entrees, and value-added protein products across retail and institutional foodservice channels.
- Recent Developments: The company continues to scale its frozen protein and ready-to-cook product lines, investing in processing capacity and brand development to address growing consumer demand for convenient frozen protein solutions.
- Strategic Focus: Growing frozen protein and value-added meal offerings through brand innovation, retail distribution expansion, and foodservice partnerships.
Market Concentration Analysis
The frozen food market is moderately concentrated, with leading multinational companies including Nestlé S.A. and McCain Foods Limited maintaining significant market positions through extensive product portfolios, established brand recognition, and broad global distribution infrastructure.
Barriers to entry include substantial capital requirements for manufacturing and cold chain infrastructure, stringent food safety and regulatory compliance across multiple jurisdictions, established brand loyalty in key consumer segments, and the logistical complexity of maintaining temperature-controlled supply chains at scale. These factors favor established operators with existing manufacturing capacity, cold chain networks, and regulatory expertise.
Consolidation activity continues to shape the competitive landscape, with strategic acquisitions targeting regional brands, emerging plant-based frozen food companies, and cold chain logistics capabilities. Partnerships between food manufacturers and retail chains for private-label frozen products are also expanding, creating competitive pressure for mid-tier branded players across multiple market segments.
Investment & Growth Opportunities
Fastest-Growing Segments
Among product type sub-segments, frozen vegetable snacks are expanding faster than the overall market, driven by growing snacking occasions and convenience preferences. Rising demand for quick-to-prepare snack options is encouraging manufacturers to expand their frozen snack portfolios.
Emerging Markets
Asia-Pacific and the Middle East and Africa represent the most significant emerging market opportunities within the frozen food sector. Improving cold chain infrastructure, rising disposable incomes, growing organized retail penetration, and increasing consumer exposure to convenience food formats are creating favorable entry conditions for manufacturers able to localize product offerings and establish distribution partnerships in these regions.
Venture & Investment Trends
Investment activity is concentrated in plant-based frozen food innovation, cold chain technology and IoT monitoring platforms, direct-to-consumer e-commerce frozen delivery solutions, and sustainable packaging for frozen food applications. Capital is also flowing into capacity expansion in emerging markets and into AI-driven quality inspection and processing automation technologies that improve production efficiency and reduce waste.
Future Market Outlook (2026-2034)
The frozen food market is projected to grow from USD 271.3 Billion in 2025 to USD 280.3 Billion in 2026, reaching USD 366.9 Billion by 2034, registering a CAGR of 3.31% during 2026-2034.
Four primary forces will shape the market through 2034 continued expansion of cold chain infrastructure in Asia-Pacific and the Middle East and Africa enabling broader market access; sustained consumer demand for convenient frozen meal and snack solutions driven by urbanization and dual-income household growth; product innovation in plant-based, clean-label, and premium frozen formats addressing evolving dietary preferences; and increasing e-commerce and direct-to-consumer frozen food distribution channel development.
By 2034, the frozen food market is expected to be characterized by a more diversified product landscape integrating health-oriented, sustainably sourced, and culturally diverse frozen food options alongside traditional categories. Continued investment in cold chain technology, manufacturing automation, and packaging sustainability will define competitive advantage among leading market participants through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with frozen food manufacturers, cold chain logistics operators, retail buyers, foodservice distributors, and product development specialists, validating market sizing, segment mix, regional demand patterns, and competitive dynamics across the frozen food ecosystem.
Secondary Research
Secondary sources included industry association publications, regulatory filings from food safety authorities, annual reports and investor disclosures from leading frozen food companies, international trade data, and publicly available market research and industry reports covering frozen food consumption, cold chain infrastructure, and retail channel trends globally.
Forecasting Models
Market forecasts used top-down and bottom-up modeling combining historical consumption data, demographic and urbanization projections, cold chain infrastructure investment trends, category innovation pipeline assessments, and regional retail penetration forecasts. Scenario analysis addressed variations in commodity costs, regulatory developments, and consumer preference shifts across key market segments.
Frozen Food Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Frozen Vegetable Snacks, Frozen Meat Products, Frozen Vegetables and Fruits |
| Frozen Vegetable Snacks Types Covered | French Fries, Bites, Wedges and Smileys, Aloo Tikki, Nuggets, Others |
| Frozen Meat Products Types Covered | Chicken, Fish, Pork, Mutton, Others |
| Frozen Vegetables Types Covered | Green Peas, Corn, Mixed Vegetables, Carrot, Cauliflower, Others |
| Frozen Fruits Types Covered | Strawberries, Berries (Raspberries, Blueberries, Blackberries), Cherries, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Nestlé S.A., McCain Foods Limited, Tyson Foods, Inc., JBS N.V., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the frozen food market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global frozen food market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the frozen food industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Frozen Food Market Report
The frozen food market size is estimated at USD 280.3 Billion in 2026, driven by rising consumer demand for convenient meal solutions, expanding cold chain infrastructure, and growing organized retail penetration worldwide.
The market is projected to grow at a CAGR of 3.31% from 2026-2034, reaching USD 366.9 Billion by 2034, supported by urbanization trends, product innovation, and expanding market access in emerging geographies.
Frozen meat products dominate at 42.6% product type share in 2025, driven by high consumer demand for protein-rich, ready-to-cook protein offerings across retail and foodservice channels globally.
French fries lead the frozen vegetable snacks type segment at 38.4% share in 2025, reflecting its universal consumer appeal and strong demand across quick service restaurants and retail channels worldwide.
Europe commands 33.8% share in 2025, led by mature cold chain infrastructure, high per-capita frozen food consumption, strong organized retail penetration, and established consumer familiarity with frozen food formats.
Asia-Pacific is the fastest-growing region, supported by rapid cold chain development, rising urban populations, increasing disposable incomes, and growing consumer adoption of convenient frozen food products.
Key players include Nestlé S.A., McCain Foods Limited, Tyson Foods, Inc., and JBS N.V., among others.
Key drivers include rising demand for convenient meal solutions, expanding cold chain infrastructure, growing urbanization, dual-income household growth, and increasing organized retail and e-commerce penetration across emerging markets.
Key challenges include maintaining cold chain integrity across extended distribution networks, managing consumer perception versus fresh food alternatives, and meeting stringent food safety compliance requirements across multiple regulatory jurisdictions.
Key emerging trends include plant-based frozen food innovation, clean-label product reformulations, e-commerce channel growth for frozen food delivery, and premiumization through gourmet and restaurant-quality frozen meal formats.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade