
Heat Pumps Market Size, Share, Trends and Forecast by Rated Capacity, Product Type, End Use Sector, and Region, 2026-2034
Heat Pumps Market Size, Share, Trends & Forecast (2026-2034)
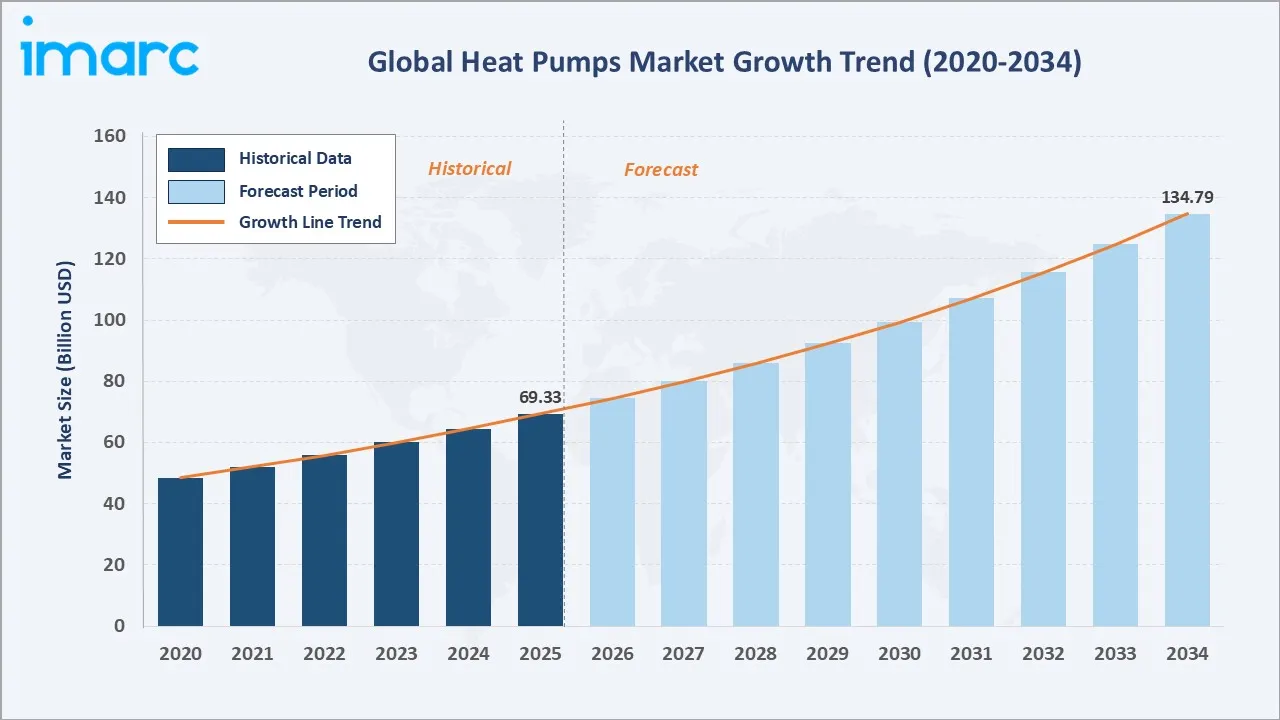
The global heat pumps market grew from USD 69.33 Billion in 2025 to USD 74.48 Billion in 2034 and is projected to reach USD 134.79 Billion by 2034, growing at a CAGR of 7.44% during 2026-2034. Decarbonization policies, government incentives, and rising demand for efficient heating and cooling are driving strong growth across the heat pump industry. Heat pump sales in Germany are expected to reach about 400,000 units in 2026, a significant increase compared with earlier forecasts.
Technology improvements in cold-climate performance, low-GWP refrigerants, and smart connectivity continue to broaden adoption in residential and commercial buildings. Up to 10 kW units dominate at 45.0%. Air source heat pumps lead product types at 80.0%. Asia Pacific commands 35.0% of global market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 69.33 Billion |
|
Market Size (2026) |
USD 74.48 Billion |
|
Forecast Market Size (2034) |
USD 134.79 Billion |
|
CAGR (2026-2034) |
7.44% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Rated Capacity |
Up to 10 kW (45.0%, 2025) |
|
Dominant Product Type |
Air Source Heat Pump (80.0%, 2025) |
|
Leading Region |
Asia Pacific (35.0%, 2025) |
The global heat pump market size increased from USD 48.43 Billion in 2020 to USD 69.33 Billion in 2025 and is estimated to reach USD 74.48 Billion in 2026. The market is further expected to grow to USD 99.24 Billion by 2030 and USD 134.79 Billion by 2034. Growth reflects building electrification, energy efficiency targets, and expanding product availability.
To get more information on this market, Request Sample
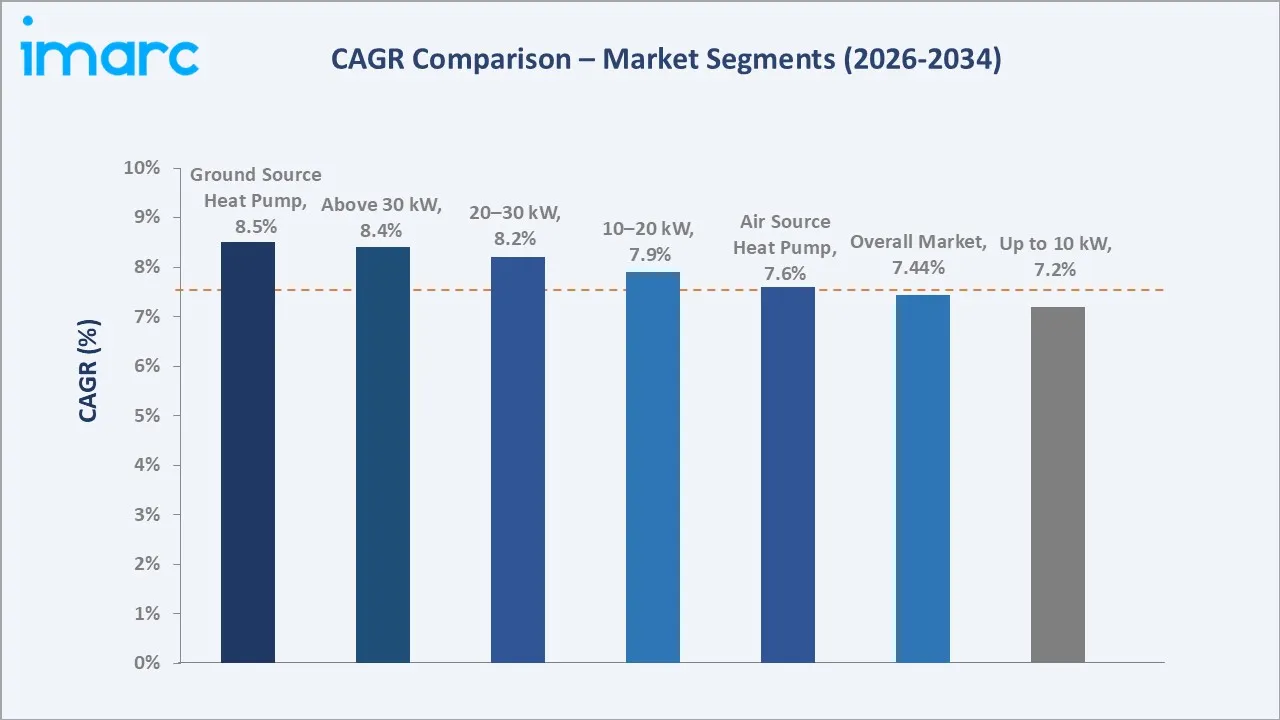
Ground source heat pumps are expected to grow fastest at ~8.5% CAGR, supported by high efficiency and long service life. Above 30 kW systems follow at ~8.4% CAGR as the commercial heat pump market expands in offices, hotels, hospitals, and district heating.
Executive Summary
The global heat pumps market expanded from USD 69.33 Billion in 2025 to an estimated USD 74.48 Billion in 2026. Heat pumps are replacing fossil-fuel boilers and furnaces as governments target net-zero emissions and consumers seek lower energy bills. Manufacturers are expanding production, launching low-GWP and cold-climate models, and adding smart connectivity. The market is projected to reach USD 134.79 Billion by 2034. Up to 10 kW systems at 45.0% lead rated capacity. Air source heat pumps at 80.0% lead product types. Asia Pacific leads regionally at 35.0%.
Key Market Insights
|
Insight |
Data |
|
Dominant Rated Capacity |
Up to 10 kW - 45.0% share (2025) |
|
Dominant Product Type |
Air Source Heat Pump - 80.0% market share (2025) |
|
Leading Region |
Asia Pacific - 35.0% share (2025) |
|
Market Opportunity |
Commercial and large-scale heat pumps; cold-climate models; low-GWP refrigerants; district heating; hybrid and smart connected systems |
Key Analytical Observations Supporting the Above Data:
- Up to 10 kW at 45.0%: Small-capacity units dominate because most residential homes and apartments require up to 10 kW of heating capacity, and these units benefit from subsidies, easy installation, and affordable prices.
- Air Source Heat Pump at 80.0%: Air source heat pumps lead because they are less expensive and easier to install than ground or water source systems and can provide both heating and cooling.
- Asia Pacific at 35.0%: Asia Pacific leads regionally due to large production bases in China and Japan, strong demand for heating and cooling, and government programs promoting clean heating.
Global Heat Pumps Market Overview
Heat pumps transfer heat from air, ground, or water into buildings for space heating, cooling, and hot water. Because they move heat rather than generate it, they can deliver several units of heat for each unit of electricity, making them far more efficient than conventional boilers and electric heaters. They are used in homes, offices, schools, hospitals, hotels, and industrial facilities around the world.
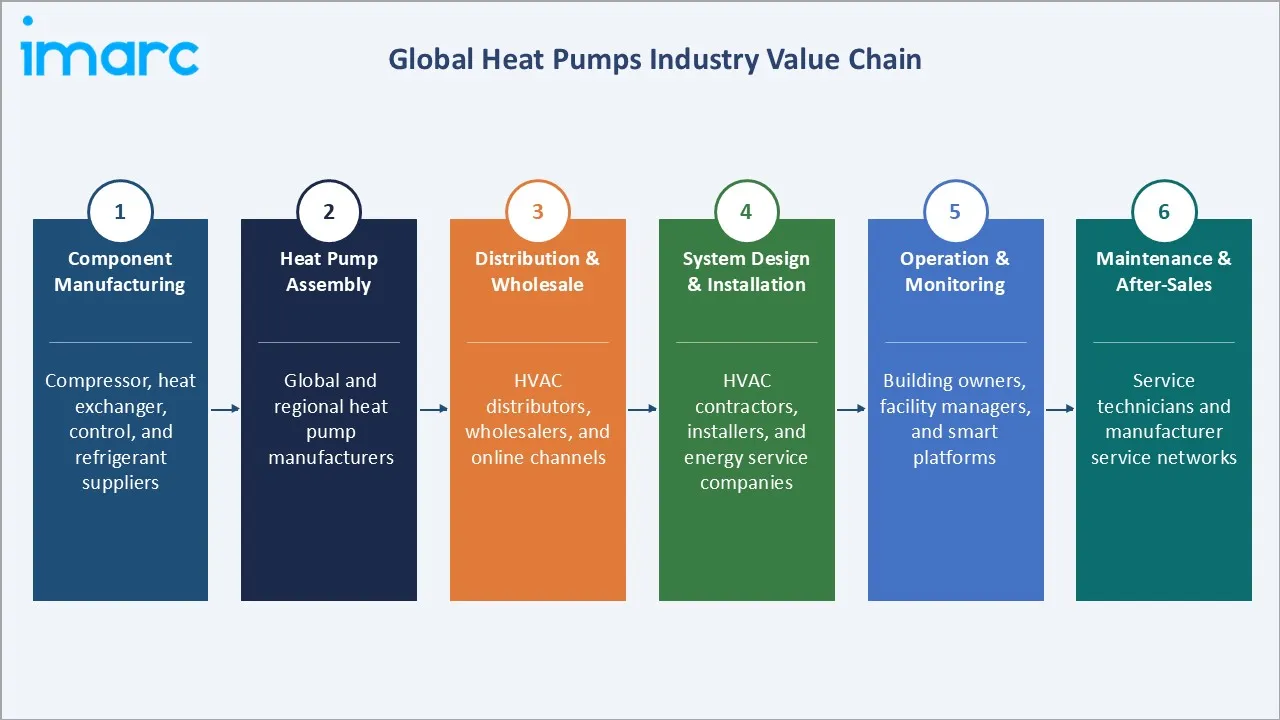
The industry ecosystem links component suppliers, heat pump manufacturers, distributors, installers, utilities, regulators, and end users. Macroeconomic factors include energy prices, construction activity, climate policy, subsidy programs, and electricity grid development, all of which shape demand. Heat pumps also play a key role in national energy security strategies by reducing dependence on imported gas.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
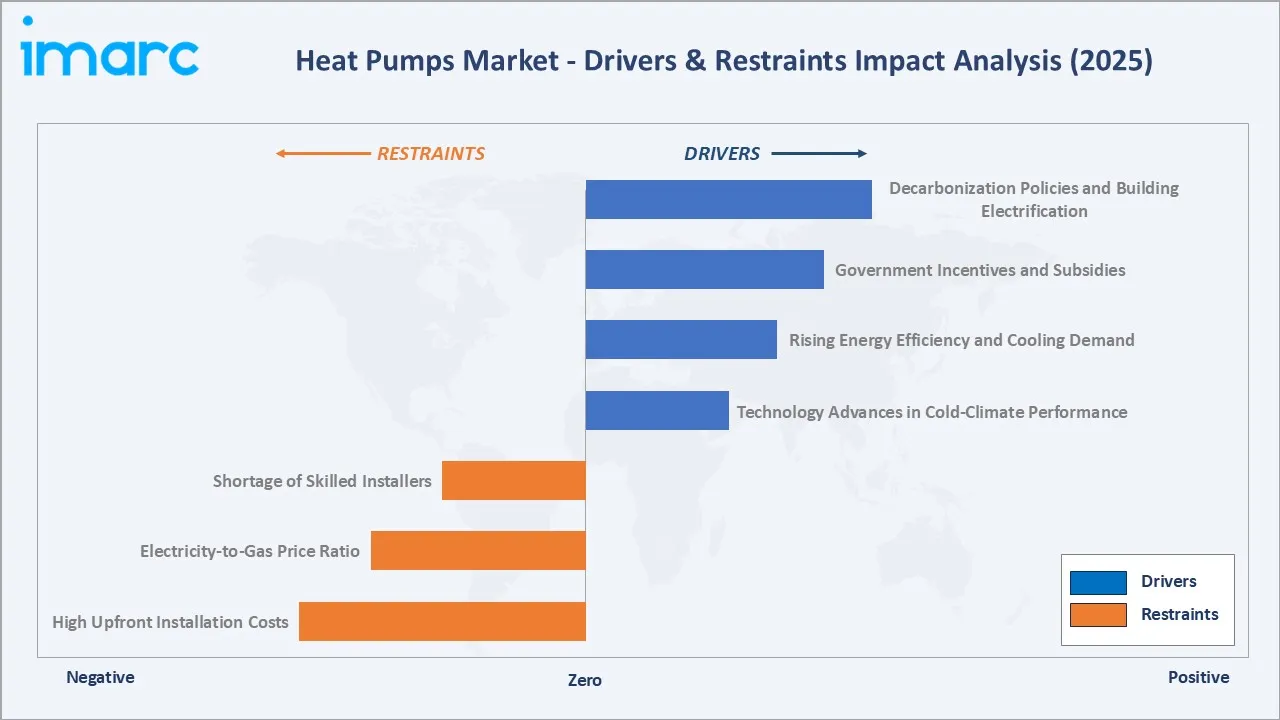
- Decarbonization Policies and Building Electrification: Governments are setting targets to reduce emissions from buildings by phasing out fossil-fuel heating and promoting electric alternatives. Building codes and regulations increasingly favor heat pumps in new construction and renovations, creating strong long-term demand. Several countries have announced bans or restrictions on new fossil-fuel boilers in the coming years, and cities are setting their own building performance standards. Corporate net-zero commitments are also encouraging commercial property owners to replace gas-fired systems with heat pumps during renovations and equipment replacement cycles. Public buildings such as schools and hospitals are often required to lead by example, creating early demand for large-capacity systems. Developers of new housing are increasingly specifying heat pumps as standard equipment to meet energy performance requirements. Social housing providers are also deploying heat pumps at scale to reduce tenant energy bills and meet climate targets.
- Government Incentives and Subsidies: Grants, tax credits, and low-interest financing reduce the upfront cost of heat pumps for households and businesses. Incentive programs in Europe, North America, and Asia have significantly accelerated adoption. Utility rebate programs and special electricity tariffs for heat pump users further improve affordability. In some markets, subsidies cover a large share of installation costs for low-income households, expanding access beyond early adopters and supporting rapid market growth. Clear communication of incentive programs and simplified application processes help increase uptake among homeowners. Public awareness campaigns are also improving consumer understanding of heat pump benefits. Online tools that compare running costs are helping households make informed choices.
- Rising Energy Efficiency and Cooling Demand: Heat pumps provide both heating and cooling, making them attractive in regions with rising summer temperatures. Their high efficiency helps reduce energy bills and supports corporate sustainability goals. Rising global temperatures are increasing cooling needs in regions that previously required only heating, making reversible heat pumps an attractive single solution. Lower operating costs over the system’s life help offset higher upfront investment. Heat pumps also reduce local air pollution compared with combustion-based heating systems. Combined with renewable electricity, heat pumps can deliver near-zero-emission heating. This makes them central to many national climate strategies.
- Technology Advances in Cold-Climate Performance: New compressors, refrigerants, and controls allow heat pumps to perform efficiently in very cold temperatures, expanding their use in northern regions previously dominated by gas and oil heating. Improvements in noise reduction, compact design, and hot water performance are also making heat pumps more suitable for existing homes and apartments. Manufacturers continue to raise seasonal efficiency ratings with each product generation. Better design tools and online calculators are helping installers size systems accurately for different climates. Faster installation methods and pre-assembled units are reducing labor time on site. Monobloc designs that avoid refrigerant handling on site simplify installation further.
Market Restraints
- High Upfront Installation Costs: Heat pumps typically cost more to purchase and install than conventional boilers, particularly ground source systems requiring drilling. High costs can deter adoption without incentives. Retrofitting older buildings may also require upgrades to insulation, radiators, or electrical systems, adding to total project costs. Financing options such as heat-as-a-service and leasing models can help reduce upfront barriers. Supply chain normalization after recent disruptions has improved product availability. Inventory levels have stabilized, helping distributors respond to seasonal demand.
- Electricity-to-Gas Price Ratio: In regions where electricity is expensive relative to gas, operating savings from heat pumps are reduced, weakening the financial case for switching. Energy taxes and levies that favor gas over electricity in some countries further affect the economics of heat pump adoption. Policy reforms that rebalance energy taxes are being discussed in several countries to improve heat pump competitiveness. Volatile gas prices, however, have made heat pumps more attractive in many regions. Energy security concerns continue to encourage diversification away from gas heating.
- Shortage of Skilled Installers: Proper design and installation require trained technicians. Shortages of qualified installers can lead to delays and performance issues. Poorly installed systems can lead to customer dissatisfaction and damage market confidence. Training programs and certification schemes are expanding but may take time to close the skills gap. Manufacturers are running their own training academies to support installer partners. Apprenticeship programs are also being expanded in several countries. Industry associations are developing common standards for installer qualifications. Better training improves installation quality, reduces callbacks, and builds consumer confidence in heat pump performance across all climate zones.
Market Opportunities
- Commercial and Industrial Heat Pumps: Large-capacity and high-temperature heat pumps for offices, hotels, hospitals, and industrial processes represent a fast-growing opportunity. These systems can recover waste heat and supply higher temperatures needed for process heating and hot water. Food processing, chemicals, and paper industries are among early adopters of industrial heat pumps. Government programs are beginning to support industrial heat electrification projects. Industrial heat pumps can deliver temperatures well above 100°C in some applications. This opens new markets in food processing, chemicals, and paper production.
- District Heating and Heat Networks: Large heat pumps using wastewater, rivers, and industrial waste heat can decarbonize district heating systems in cities. Several European cities are already deploying large heat pumps in district heating networks. These projects can supply heat to thousands of homes while reducing emissions significantly. Large heat pumps can also use seawater and sewage as heat sources. Such projects demonstrate the scalability of heat pump technology. Municipal utilities are increasingly planning large heat pump installations as part of long-term heat strategies. Public funding and long-term contracts help de-risk these large infrastructure investments.
Market Challenges
- Policy Uncertainty and Subsidy Changes: Changes to incentive programs can cause sudden shifts in demand, affecting manufacturers and installers. Stable, long-term policy frameworks are important for investment in production capacity and workforce training. Manufacturers have adjusted production plans in response to demand fluctuations in some markets. Long-term demand fundamentals remain strong despite short-term volatility. Manufacturers are using this period to invest in next-generation products. Clear long-term targets help the industry plan capacity and workforce development. Stable incentive schemes also support consumer confidence and steady installation rates. Policy consistency is widely seen as essential for sustained growth in the heat pump industry over the next decade.
- Grid Capacity and Peak Demand: Widespread electrification increases peak electricity demand, requiring grid upgrades and smart control strategies. Demand response programs and thermal storage can help manage peak loads. Utilities are increasingly partnering with manufacturers on smart grid integration. Time-of-use tariffs encourage heat pump operation during off-peak hours. Thermal storage tanks allow heat to be produced when electricity is cheapest. Smart controls can automatically shift operation to periods of low grid demand and high renewable output.
Emerging Market Trends
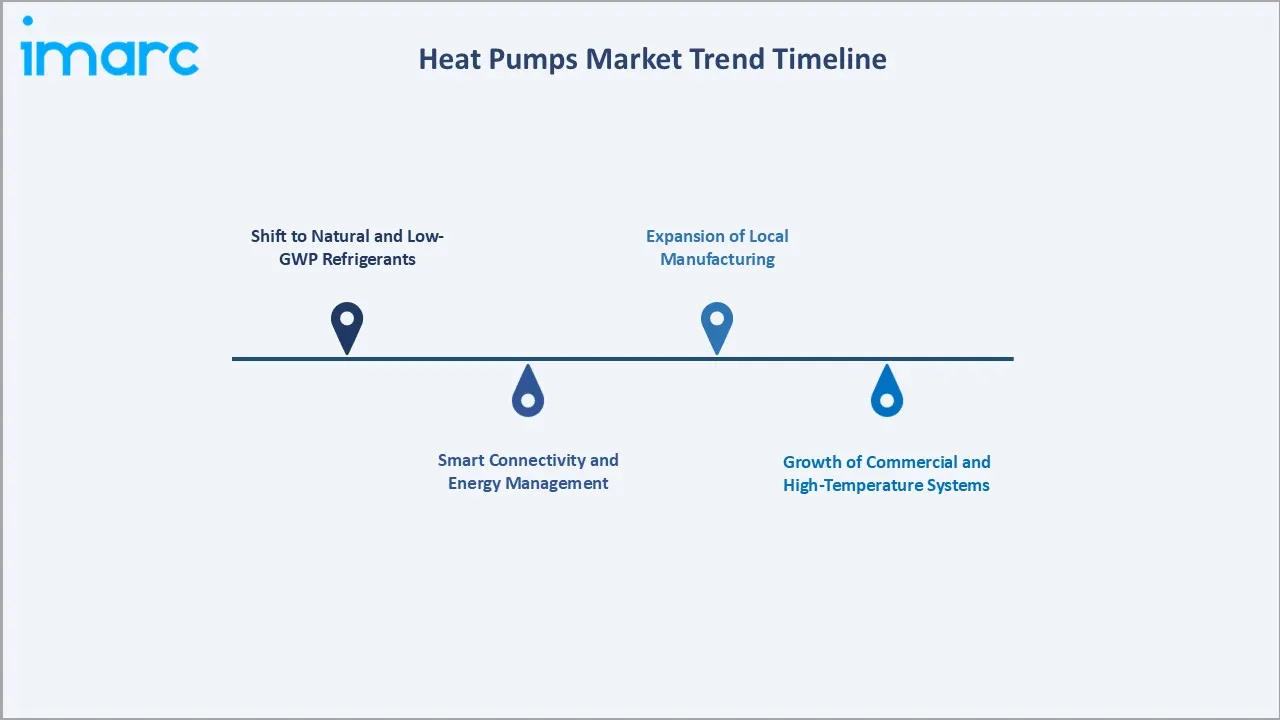
1. Shift to Natural and Low-GWP Refrigerants
Manufacturers are introducing heat pumps using propane (R290) and other low-GWP refrigerants to comply with stricter regulations and reduce environmental impact while improving efficiency. Propane-based models are gaining popularity in Europe as F-gas regulations tighten. CO2-based heat pumps are also gaining traction for commercial hot water applications. Refrigerant transitions require updated training and handling procedures for installers.
2. Smart Connectivity and Energy Management
Connected heat pumps integrate with smart thermostats, solar PV, and batteries, allowing remote control, demand response, and optimized energy use. Manufacturers are adding remote diagnostics and app-based controls as standard features. Integration with home energy management systems allows heat pumps to use excess solar power efficiently. Data from connected systems helps manufacturers improve future product designs. Software updates can also improve performance after installation. Remote commissioning tools also help installers set up systems faster and more accurately. Over-the-air updates allow manufacturers to introduce new features and efficiency improvements throughout the product lifetime.
3. Expansion of Local Manufacturing
Leading manufacturers are building new factories in Europe and North America to shorten supply chains and meet growing regional demand. Local production also helps manufacturers qualify for incentives and respond faster to customer needs. New factories in Poland, the Czech Republic, and the United States illustrate this trend. Regional supply chains also reduce exposure to shipping disruptions.
4. Growth of Commercial and High-Temperature Systems
Modular, high-temperature heat pumps are enabling electrification of commercial buildings, multifamily housing, and industrial hot water applications. These systems support the electrification of larger buildings that were previously difficult to decarbonize. Modular designs allow capacity to be scaled to match building needs. Simultaneous heating and cooling systems improve efficiency in mixed-use buildings.
Industry Value Chain Analysis
The global heat pumps value chain spans component manufacturing, heat pump assembly, distribution and wholesale, system design and installation, operation and monitoring, and maintenance and after-sales. Value is concentrated in manufacturing technology and installation quality. Component innovation, especially in compressors and controls, drives efficiency improvements. Distribution partners provide training, stock, and technical support to installers. Utilities and energy retailers are also entering the market with bundled offerings.
|
Stage |
Key Participants |
|
Component Manufacturing |
Compressor, heat exchanger, control, and refrigerant suppliers |
|
Heat Pump Assembly |
Global and regional heat pump manufacturers |
|
Distribution & Wholesale |
HVAC distributors, wholesalers, and online channels |
|
System Design & Installation |
HVAC contractors, installers, and energy service companies |
|
Operation & Monitoring |
Building owners, facility managers, and smart platforms |
|
Maintenance & After-Sales |
Service technicians and manufacturer service networks |
System design and installation is the most consequential stage of the chain. Correct sizing and installation determine efficiency, comfort, and customer satisfaction, making skilled installers essential to market growth. After-sales service and maintenance also play important roles in ensuring long-term performance and customer satisfaction. Digital monitoring enables predictive maintenance and faster service response. Extended warranties are increasingly offered to build customer confidence.
Technology Landscape in the Global Heat Pumps Industry
Inverter Compressors and Cold-Climate Technology
Variable-speed inverter compressors and vapor injection technology maintain high efficiency across a wide range of outdoor temperatures. These technologies allow heat pumps to provide reliable heating even at temperatures below minus 20°C. Enhanced defrost cycles and improved heat exchangers further support winter performance. Cold-climate certification programs help consumers identify suitable products.
Low-GWP Refrigerants and High-Temperature Systems
Natural refrigerants such as R290 and CO2 enable high flow temperatures suitable for radiators and domestic hot water with lower climate impact. High-temperature heat pumps can replace boilers without changing existing radiators. This makes them particularly attractive for renovating older buildings. High-temperature models are also suitable for commercial hot water applications.
Smart Controls and Hybrid Systems
Smart controls, connectivity, and hybrid systems combining heat pumps with boilers or solar PV optimize performance and energy costs. Hybrid systems are popular in markets where full electrification is not yet practical. Artificial intelligence is beginning to optimize system settings based on weather forecasts and usage patterns. Smart grid-ready labels help consumers choose connected products.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Rated Capacity |
Up to 10 kW |
45.0% |
2025 |
|
Product Type |
Air Source Heat Pump |
80.0% |
2025 |
|
End Use Sector |
Residential |
🔒 |
2025 |
|
Region |
Asia Pacific |
35.0% |
2025 |

By Rated Capacity
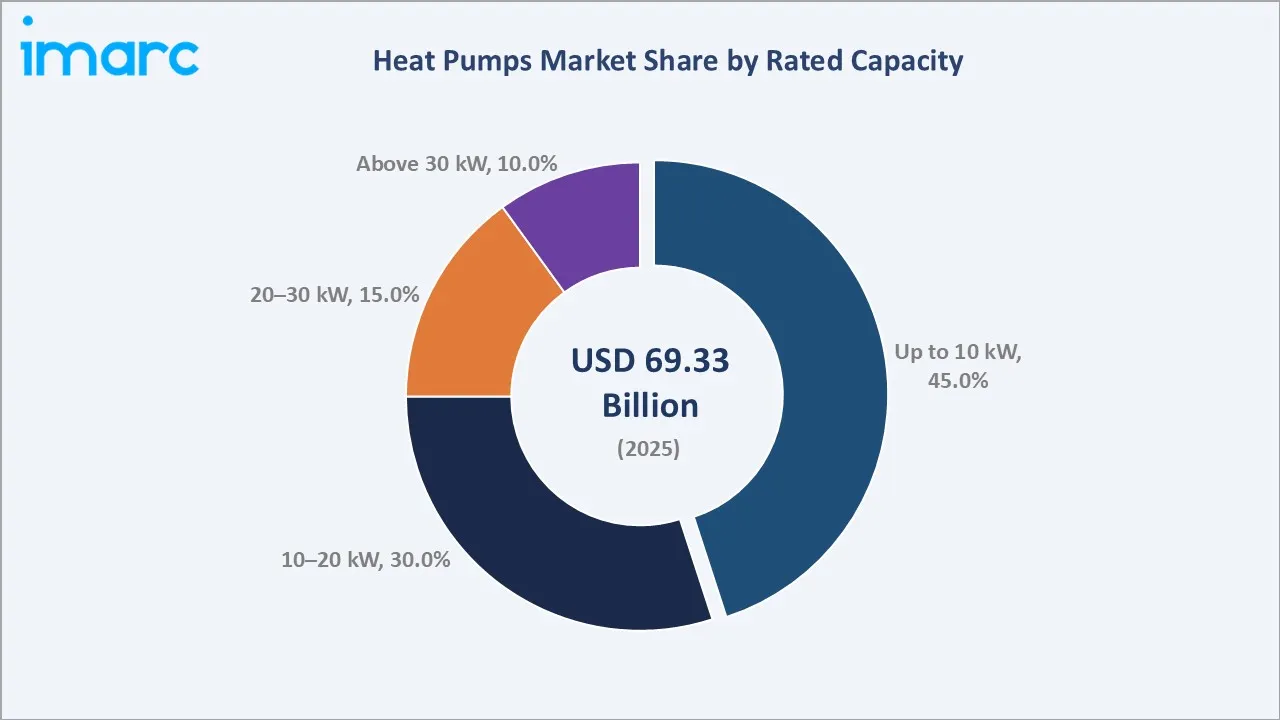
Up to 10 kW units lead at 45.0% (2025). Most residential homes and apartments require small-capacity systems, which benefit from subsidies and easy installation. These units are also widely used in small commercial premises such as shops and offices. Compact designs and quiet operation make these units suitable for dense urban housing. Easy integration with existing radiators and hot water tanks supports replacement demand.
To access detailed market analysis, Request Sample
10–20 kW units at 30.0% grow at ~7.9% CAGR. 20–30 kW at 15.0% grow at ~8.2%, and above 30 kW at 10.0% grow fastest at ~8.4%, supported by commercial demand. Larger systems are increasingly used in multifamily buildings and commercial facilities. The commercial heat pump market is a key growth driver for higher-capacity segments.
By Product Type
Air source heat pumps lead at 80.0% (2025). Lower costs, easy installation, and dual heating and cooling capability make them the most widely used type. Air-to-water and air-to-air variants serve a broad range of residential and commercial applications.
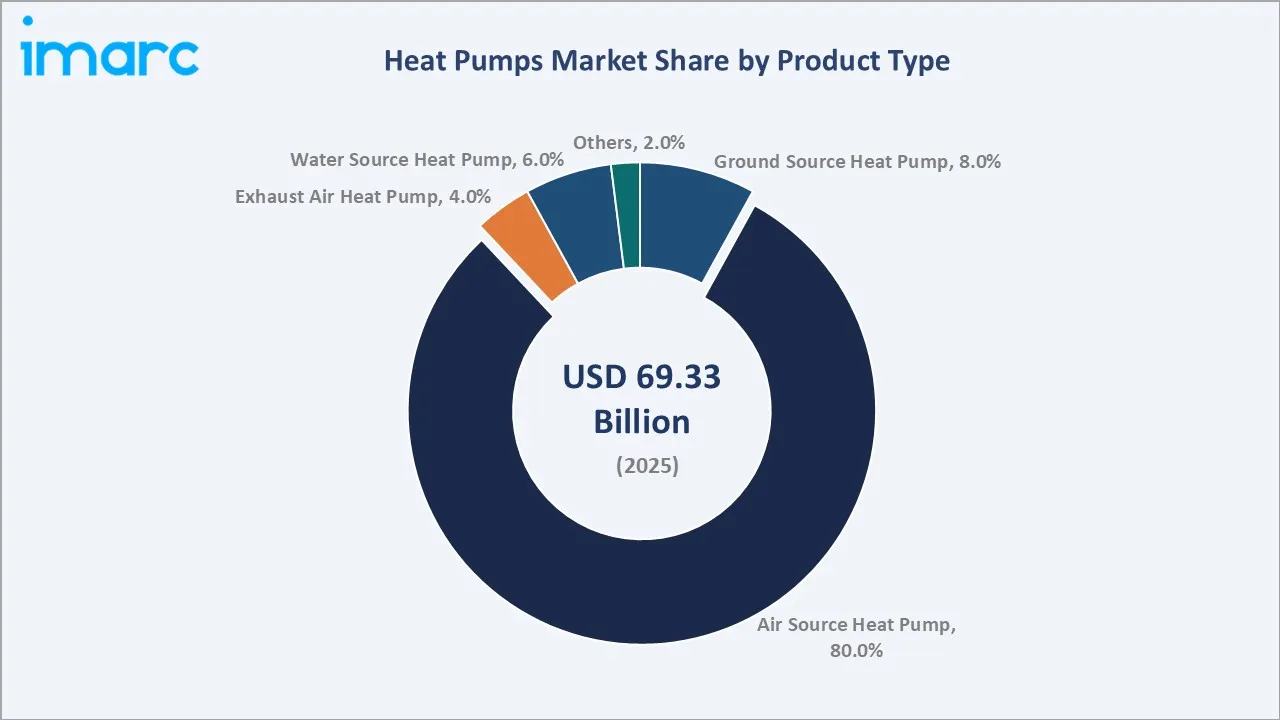
Ground source at 8.0% grows fastest at ~8.5% CAGR. Water source at 6.0%, exhaust air at 4.0%, and others at 2.0% serve specialized applications. Exhaust air heat pumps are common in energy-efficient apartments, particularly in Nordic countries. Ground source systems are favored where long-term efficiency and quiet operation are priorities.
Regional Market Insights
|
Region |
Share (2025) |
Key Global Heat Pumps Market Drivers & Characteristics |
|
Asia Pacific |
35.0% |
Large production base in China and Japan and strong clean-heating programs. |
|
Europe |
30.0% |
Decarbonization policies, subsidies, and fossil-fuel heating phase-outs. |
|
North America |
23.0% |
Tax credits, cold-climate models, and replacement of furnaces. |
|
Middle East and Africa |
7.0% |
Rising cooling demand and efficient building projects. |
|
Latin America |
5.0% |
Growing commercial and residential adoption. |
Asia Pacific's 35.0% market leadership reflects large manufacturing bases and strong clean-heating policies in China, Japan, and South Korea. Europe's 30.0% reflects ambitious decarbonization targets and generous subsidy programs. Germany, France, Italy, and the Nordic countries are among the largest markets in the region. The United Kingdom is also expanding adoption through grants and new-build standards.
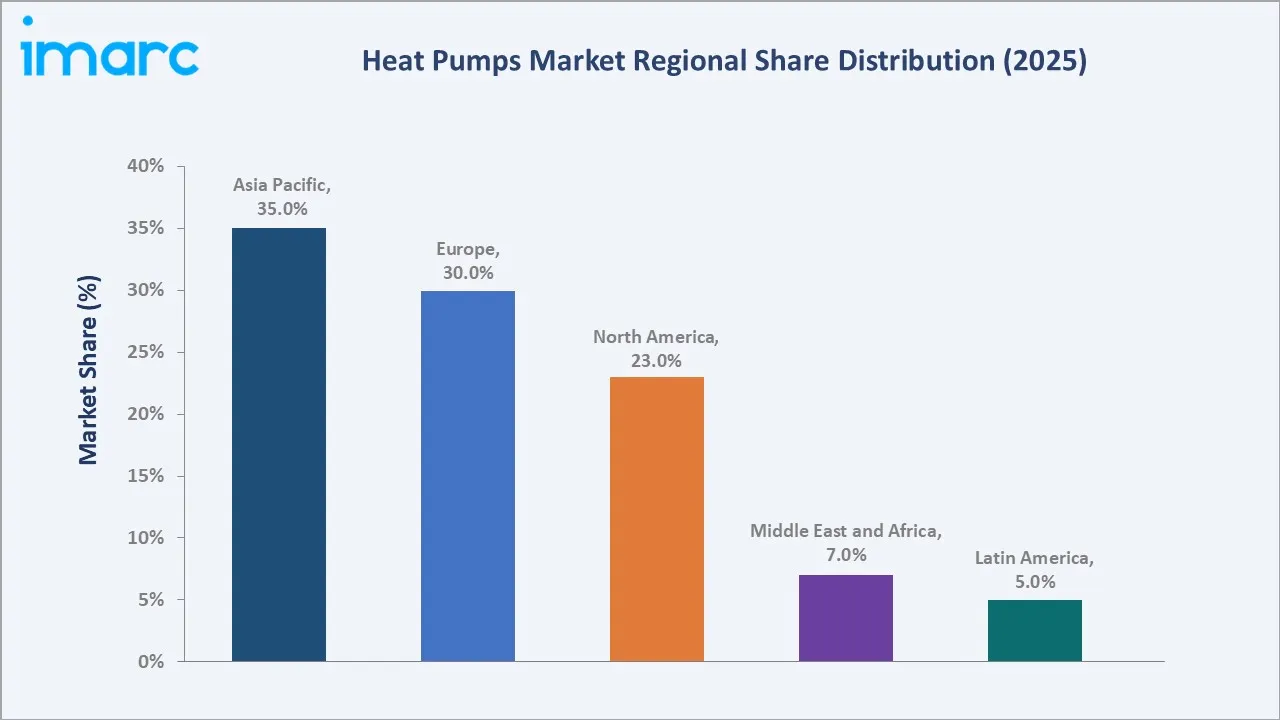
North America's 23.0% reflects tax credits and growing cold-climate adoption. Middle East and Africa at 7.0% and Latin America at 5.0% are smaller but growing with efficiency and cooling demand. Rising awareness of energy efficiency supports gradual adoption across these regions. Large commercial projects and hotels are early adopters in the Gulf region.
Competitive Landscape
The global heat pumps market includes large HVAC manufacturers, heating specialists, and regional producers. Competition centers on efficiency, product range, refrigerant technology, distribution, and installer networks, shaping heat pump market share. Partnerships with utilities and energy service companies also help manufacturers reach customers. Strong brands and service networks remain key differentiators.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Daikin Industries, Ltd. |
Daikin Altherma |
Market Leader |
Global HVAC leader with large heat pump production. |
|
Mitsubishi Electric Corporation |
Ecodan, ecodanPro |
Market Leader |
Cold-climate and air-to-water heat pump expertise. |
|
Midea Group |
Midea, Clivet |
Strong Challenger |
Large-scale manufacturing and broad product range. |
|
Robert Bosch GmbH |
YORK, Hitachi |
Strong Challenger |
Home comfort portfolio with connected heat pumps. |
|
Carrier |
Viessmann, Carrier |
Strong Challenger |
European heating brand with commercial reach. |
|
NIBE Industrier AB |
NIBE |
Innovator |
Ground source and residential heat pump specialist. |
|
Trane Technologies plc |
Trane, Thermo King |
Innovator |
Commercial and high-temperature heat pumps. |
The most important competitive dynamic is the race to expand local manufacturing and launch efficient, low-GWP products while building strong installer networks. Acquisitions are enabling companies to expand their portfolios and geographic presence. Investment in research and development supports continuous product innovation.
Key Company Profiles
Daikin Industries, Ltd.
Daikin Industries is a global leader in heat pump, air conditioning, and air filtration technology, employing more than 104,000 people.
- Key Brands: Daikin Altherma.
- Recent Developments: In May 2026, Daikin Europe inaugurated Daikin Manufacturing Poland, a new heat pump production facility in the Łódź region producing residential heat pump heating systems.
- Strategic Focus: Expanding its European network, which includes 12 HVAC-R manufacturing sites and a heat pump R&D centre in Belgium.
Mitsubishi Electric Corporation
Mitsubishi Electric Corporation offers air-to-water and air-to-air heat pumps, including the Ecodan range, for residential and commercial applications.
- Key Brands: Ecodan, ecodanPro.
- Recent Developments: In March 2026, Mitsubishi Electric Trane HVAC US introduced the ecodan single-phase air-to-water heat pump line for hydronic heating, cooling, and hot water.
- Strategic Focus: Expanding commercial solutions such as the ecodanPro CAHV modular heat pump using low-GWP refrigerant R454C.
Robert Bosch GmbH
The Bosch Home Comfort Group has incorporated the YORK and Hitachi brands into its portfolio, offering heat pumps for residential and light commercial buildings.
- Key Brands: Bosch, Buderus, YORK, Hitachi.
- Recent Developments: In August 2026, Bosch Home Comfort Group released new Evcon and Guardian heat pump and cooling lineups for multifamily buildings.
- Strategic Focus: Connecting all Bosch Home Comfort heat pumps and integrating them with Bosch Smart Home thermostats.
Market Concentration Analysis
The global heat pumps market is moderately concentrated, with leading HVAC manufacturers holding significant shares, while regional and specialist producers compete strongly in local markets.
Market concentration is evolving through acquisitions and new factories by leading players, alongside rapid growth of Asian manufacturers. Competition is intense in residential air source segments, while specialized commercial segments are less crowded. Price competition from Asian manufacturers is increasing in Europe.
Investment & Growth Opportunities
Highest Growth Segments
Ground source (~8.5% CAGR through high efficiency), above 30 kW (~8.4% CAGR through the commercial heat pump market), Asia Pacific (~8.2% CAGR through clean heating), and 20–30 kW (~8.2% CAGR through multifamily demand) represent the highest-growth investment areas through 2034.
Emerging Investment Opportunities
Large-scale commercial and district heating heat pumps are among the most promising opportunities, supporting urban decarbonization. Investment in high-temperature and industrial heat pumps also offers strong returns. Installer training and certification programs are also attractive areas for investment.
Investment Themes
- Local manufacturing: New factories reduce lead times and support regional demand.
- Installer training: Skilled workforce development supports market growth.
Future Market Outlook (2026-2034)
The global heat pumps market is projected to grow from USD 69.33 Billion in 2025 to USD 74.48 Billion in 2026, reaching USD 134.79 Billion by 2034, registering a CAGR of 7.44% during 2026-2034. The anchor value of USD 99.24 Billion in 2030 marks a point at which heat pumps should be mainstream in new buildings. By then, commercial and industrial heat pumps should also account for a larger share of sales. Smart, connected systems are expected to become standard across all segments.
Three structural forces define heat pump industry growth through 2034: decarbonization policy; technology improvement; and expansion into commercial and industrial applications. Together, these forces support strong growth across capacities, product types, and regions over the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including manufacturers, distributors, installers, utilities, and policymakers across all regions.
Secondary Research
Secondary research covered company press releases, energy agency data, trade associations, and industry reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets.
Forecasting Models
Market revenue forecasts were developed using a demand-based model: unit installations by capacity, product type, and region multiplied by average prices, with segment results aggregated to total market value. Assumptions were validated through detailed discussions with experienced industry experts, manufacturers, and installers across all major regions of the world, including Europe, Asia Pacific, and North America.
Heat Pumps Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Rated Capacities Covered | Up To 10 Kw, 10–20 Kw, 20–30 Kw, Above 30 Kw |
| Product Types Covered | Air Source Heat Pump, Ground Source Heat Pump, Water Source Heat Pump, Exhaust Air Heat Pump, Others |
| End Use Sectors Covered | Residential, Commercial, Hospitality, Retail, Education, Food & Beverage, Paper & Pulp, Chemicals & Petrochemicals, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Companies Covered | Daikin Industries, Ltd., Mitsubishi Electric Corporation, Midea Group, Robert Bosch GmbH, Carrier, NIBE Industrier AB, Trane Technologies plc, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the heat pumps market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and market recent opportunities in the global heat pumps market.
- The study maps the leading, as well as the fastest-growing, regional markets.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the heat pumps industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Heat Pumps Market Report
The global heat pump market size is estimated at USD 74.48 Billion in 2026, supported by decarbonization policies and incentives.
The market grows at 7.44% CAGR during 2026-2034, reaching USD 134.79 Billion by 2034.
Up to 10 kW units lead at 45.0%, serving most residential homes.
Air source heat pumps lead at 80.0%, owing to lower costs and easy installation.
Asia Pacific leads at 35.0%, driven by manufacturing and clean-heating programs.
Leading companies include Daikin Industries, Ltd., Mitsubishi Electric Corporation, Midea Group, Robert Bosch GmbH, Carrier, NIBE Industrier AB, and Trane Technologies plc, among others.
The commercial heat pump market is growing quickly as offices, hotels, and hospitals adopt large-capacity and high-temperature systems.
The market is projected to reach approximately USD 99.24 Billion by 2030.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade