India Biodegradable Packaging Market Size, Share, Trends and Forecast by Material Type, Application, and Region, 2026-2034
India Biodegradable Packaging Market Size, Share, Trends & Forecast (2026-2034)
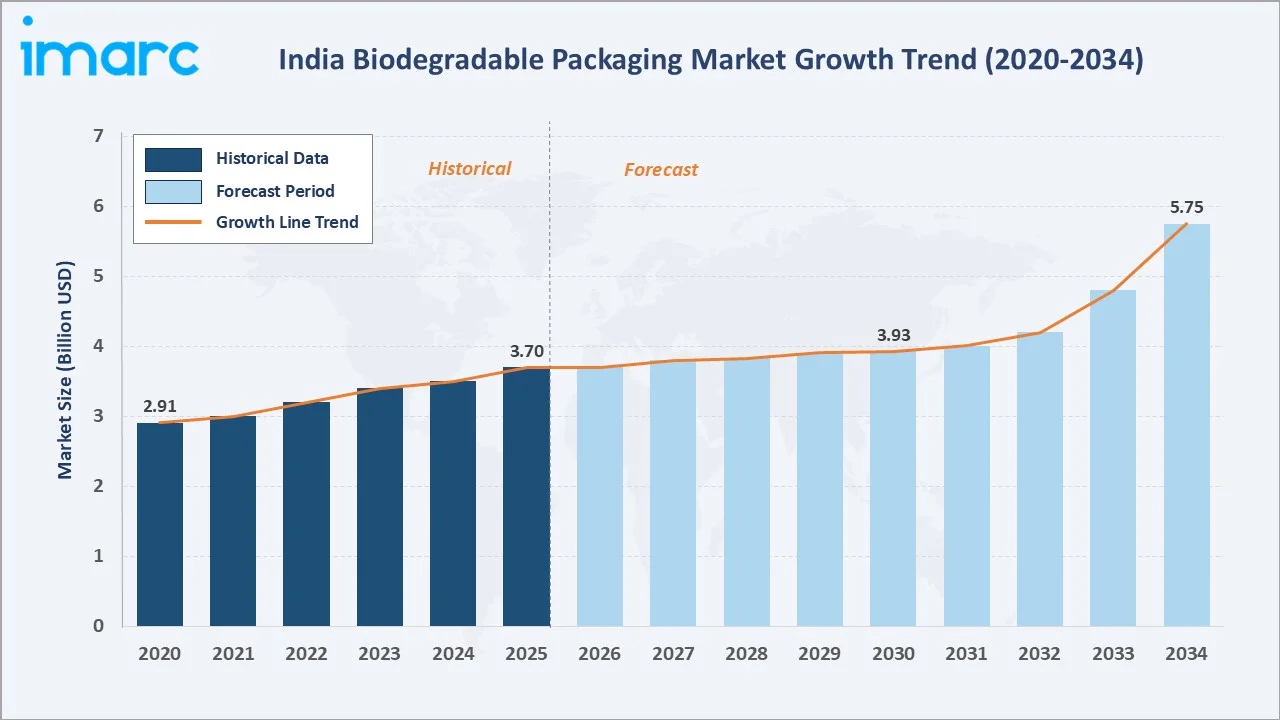
The India biodegradable packaging market grew from USD 3.70 Billion in 2025 to USD 3.93 Billion in 2026 and is projected to reach USD 5.75 Billion by 2034, growing at a CAGR of 4.88% during 2026-2034. The market is driven by regulatory mandates on single-use plastics, rising eco-consciousness, and rapid expansion of food delivery and e-commerce sectors adopting certified compostable packaging.
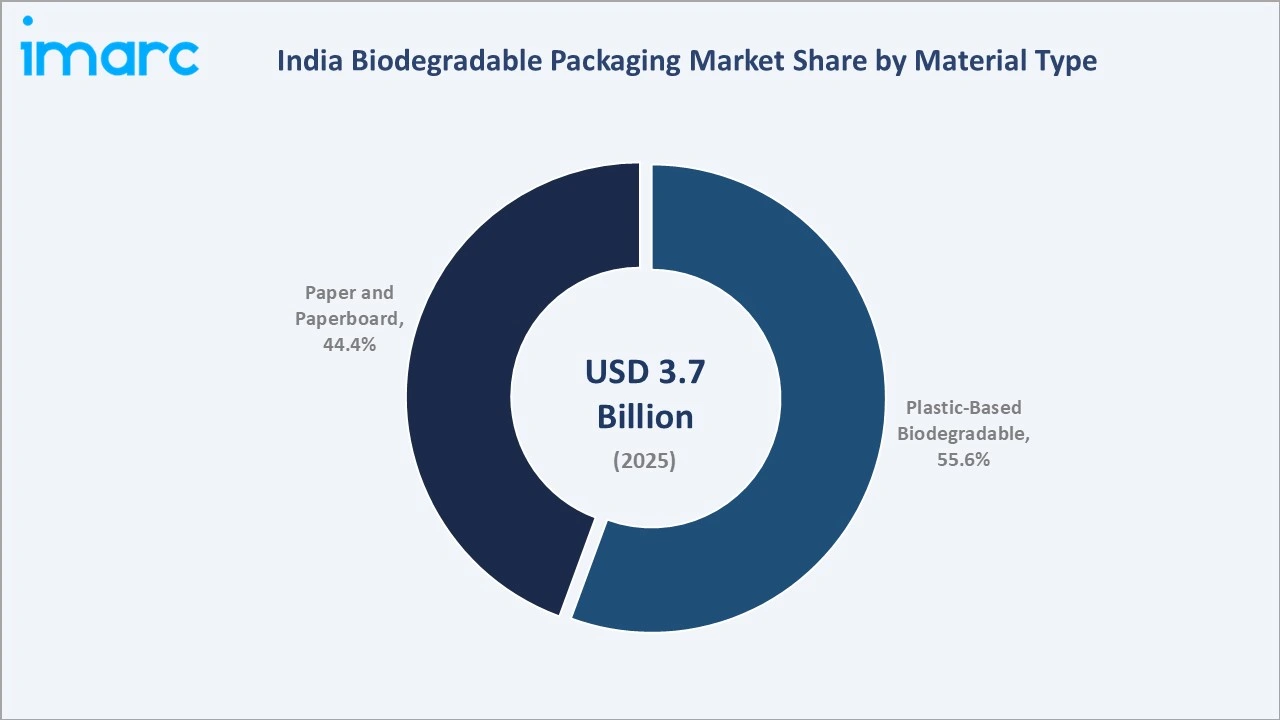
Plastic-based biodegradable materials dominate at 55.6% of the market in 2025, while food packaging leads application segments at 52.7%. West India commands the largest regional share at 32.8%, anchored by concentration of FMCG, pharmaceutical, and export-oriented packaging manufacturers.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 3.70 Billion |
|
Market Size (2026) |
USD 3.93 Billion |
|
Forecast Market Size (2034) |
USD 5.75 Million |
|
CAGR (2026-2034) |
4.88% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Material Type |
Plastic-Based Biodegradable (55.6%, 2025) |
|
Dominant Application |
Food Packaging (52.7%, 2025) |
|
Leading Region |
West India (32.8%, 2025) |
The market grew from USD 2.91 Billion in 2020 to USD 3.70 Billion in 2025 and is estimated at USD 3.93 Billion in 2026, growing further to USD 4.69 Billion by 2030 and USD 5.75 Billion by 2034. India's biodegradable packaging market is structurally positioned at a policy-driven inflection, combining one of Asia's largest packaging consumer bases with accelerating regulatory enforcement and a rapidly maturing domestic biopolymer supply chain.
To get more information on this market, Request Sample
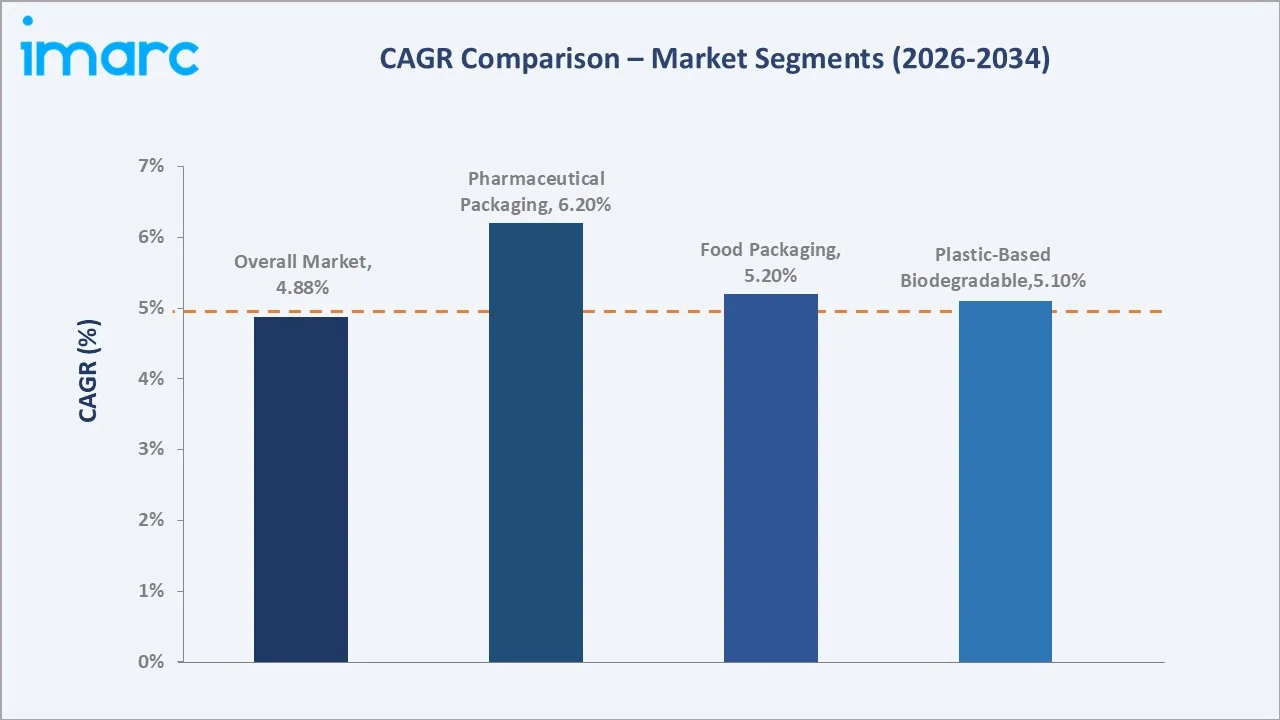
The pharmaceutical segment grows fastest at ~6.2% CAGR through hospital sustainability mandates and export-grade compostable blister pack demand. Plastic-based biodegradable materials grow at ~5.1% CAGR as domestic PLA and PBAT capacity scales and cost differentials with conventional plastics narrow.
Executive Summary
The India biodegradable packaging market expanded from USD 2.91 Billion in 2020 to USD 3.70 Billion in 2025, among Asia-Pacific's most rapidly evolving sustainable packaging markets. Growth is underpinned by India's large FMCG consumer base, decisive enforcement of single-use plastic bans, and rising corporate ESG mandates. The market is projected to reach USD 5.75 Billion by 2034 at a CAGR of 4.88%. Plastic-based biodegradable materials at 55.6% lead through superior barrier properties; food packaging at 52.7% reflects FSSAI-driven compliance demand; West India leads regionally at 32.8%.
Key Market Insights
|
Insight |
Data |
|
Dominant Material Type |
Plastic-Based Biodegradable – 55.6% share (2025) |
|
Dominant Application |
Food Packaging – 52.7% market share (2025) |
|
Leading Region |
West India – 32.8% share (2025) |
|
Market Opportunity |
Agri-feedstock cost reduction; pharma packaging growth; EU export potential; composting infra PPP |
Key Analytical Observations Supporting the Above Data:
- Plastic-Based Biodegradable at 55.6%: This segment dominates due to superior barrier properties, moisture resistance, and compatibility with existing packaging conversion lines using PLA, PBAT, and bio-PE composites.
- Food Packaging at 52.7%: Food packaging leads due to FSSAI compliance mandates, QSR chain sustainability commitments, and rapid growth of cloud kitchens and food delivery platforms.
- West India at 32.8%: West India dominates through the Mumbai-Pune-Ahmedabad-Surat corridor's concentration of FMCG manufacturers, pharmaceutical companies, and packaging converters.
India Biodegradable Packaging Market Overview
India's biodegradable packaging market sits at a unique intersection: one of the world's largest packaging consumer bases by volume, a decisive government mandate to phase out single-use plastics generating structural compliance demand, and a rapidly maturing domestic biopolymer production capability beginning to reduce import dependency and improve cost competitiveness for certified biodegradable packaging materials across all major application segments.
The market ecosystem integrates domestic bio-feedstock producers, biopolymer compounders, packaging converters, brand owners, and post-use composting facilities. India's GDP growth at 6–7% annually, rising urbanisation, and expanding organised retail are collectively accelerating the transition from conventional plastic packaging to certified biodegradable alternatives across FMCG, food service, pharmaceutical, and e-commerce sectors.
Market Dynamics
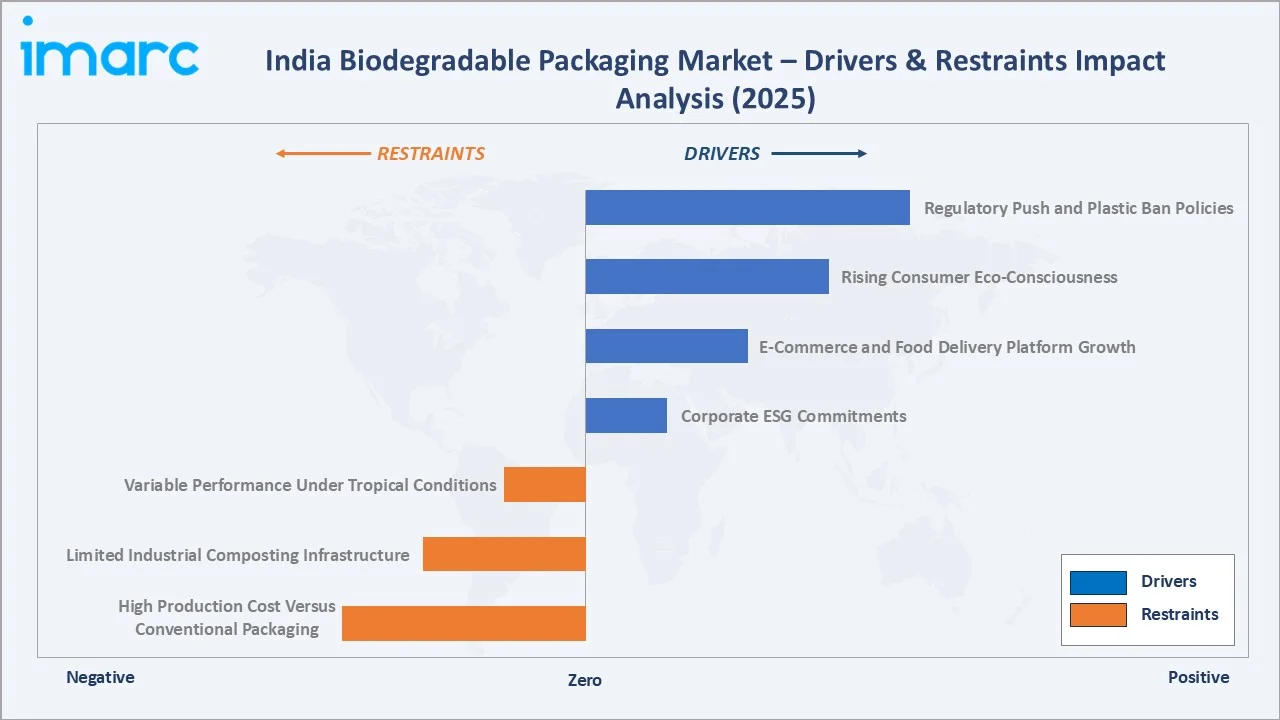
To evaluate market opportunities, Request Sample
Market Drivers
- Regulatory Push and Plastic Ban Policies: The Indian government's enforcement of the Plastic Waste Management (Amendment) Rules, 2021, and Phase II single-use plastic bans have compelled manufacturers and brand owners to seek certified biodegradable alternatives. EPR norms mandate producers to incorporate a defined percentage of compostable material in packaging by 2026–2028, creating a structural compliance demand floor. These regulatory pressures are making biodegradable packaging investment a necessity rather than an ESG aspiration, underpinning the market's baseline growth trajectory.
- Rising Consumer Eco-Consciousness: Indian urban consumers, particularly millennials and Gen Z, are increasingly making purchase decisions based on environmental credentials of brands. Nielsen's 2024 Sustainability Survey revealed that 67% of Indian consumers prefer brands committed to sustainable packaging. This preference is influencing FMCG companies to reformulate packaging strategies, creating pull-through demand for biodegradable solutions. Brand differentiation through eco-labelling and compostability certification has emerged as a key competitive strategy, reinforcing market demand.
- E-Commerce and Food Delivery Platform Growth: In 2024, top food delivery platforms in India like Zomato processed over 753 million orders individually, each requiring sustainable packaging to meet platform-level green commitments. Zomato, Swiggy, and Amazon India have each published biodegradable packaging mandates for partner restaurants and sellers. This channel-driven demand is translating directly into incremental volume uptake of compostable pouches, moulded fibre containers, and paper-based mailers, providing consistent demand growth independent of traditional retail channels.
- Corporate ESG Commitments: Major Indian conglomerates including ITC, Dabur, Hindustan Unilever, and Nestlé India have committed to achieving 100% reusable, recyclable, or compostable packaging by 2030 under their respective sustainability roadmaps. These corporate commitments translate into large-scale procurement programs for certified biodegradable packaging materials with multi-year supply agreements. Revenue visibility from long-term corporate procurement is underpinning capacity expansion decisions by domestic biodegradable packaging manufacturers.
Market Restraints
- High Production Cost Versus Conventional Packaging: Biodegradable packaging materials carry a cost premium of 30–80% over conventional plastic equivalents, due to higher feedstock costs, energy-intensive processing, and limited domestic biopolymer production. While global PLA prices have declined with scale-up, PBAT and starch-blended resins remain expensive in India due to import dependency. This cost differential constrains adoption among price-sensitive SME packagers and discourages MSME food processors from switching despite regulatory pressure, limiting the pace of market penetration in value segments.
- Limited Industrial Composting Infrastructure: The efficacy of compostable packaging depends on industrial composting facilities operating at 58°C or higher, which are scarcely available across Indian cities. As of 2025, fewer than 50 certified industrial composting plants operate nationally, far short of requirements for systemic diversion of biodegradable packaging waste. Without adequate end-of-life infrastructure, biodegradable packaging often ends in landfills or open dumps, undermining its environmental value proposition and creating greenwashing concerns that dampen consumer and regulatory confidence.
- Variable Performance Under Tropical Conditions: India's tropical climate, characterised by high temperature and humidity, accelerates premature degradation of certain biodegradable materials during storage and transit. PLA-based formats are particularly susceptible to heat distortion above 60°C, limiting applicability in hot-fill beverage and retort packaging applications. Addressing this requires heat-resistant bio-composite formulations and multilayer bio-barrier coatings, further elevating costs and extending development timelines for manufacturers serving demanding segments.
Market Opportunities
- Agri-Waste Based Feedstock Development: India generates over 500 million tonnes of agricultural residue annually, including bagasse, wheat straw, rice husk, and banana fibre a large untapped feedstock base for biodegradable packaging. Conversion into pulp, moulded fibre, and bio-composite materials can significantly reduce raw material costs while creating rural livelihood opportunities. Government-backed bio-refinery pilots could materially reduce the cost gap between biodegradable and conventional packaging.
- Export Potential to Stringent-Regulation Markets: The EU's Single-Use Plastics Directive and extended producer responsibility frameworks in Japan and Australia are creating export opportunities for Indian biodegradable packaging producers. India's cost-competitive manufacturing base combined with growing IS 17088 and EN 13432 certification capabilities positions it as a potential leading exporter of compostable packaging to high-value markets.
Market Challenges
- Consumer Confusion Over Biodegradable vs. Compostable Claims: Interchangeable use of "biodegradable," "compostable," and "eco-friendly" without standardised certification has created consumer confusion and regulatory concern. CPCB and BIS have tightened labelling under IS 17088, but enforcement remains inconsistent across states. Addressing this requires industry-wide certification adoption, third-party testing mandates, and consumer education, demanding upfront investment to build market trust for certified biodegradable products.
- Supply Chain Fragmentation: India's biodegradable packaging supply chain remains highly fragmented, with numerous small converters lacking consistent quality systems, certifications, or capital for biopolymer processing equipment. This limits ability to fulfil large-volume, high-specification orders from major FMCG companies. Consolidation through mergers, contract alliances, and cluster-based processing zones is necessary to meet quality standards demanded by multinational brand owners.
Emerging Market Trends
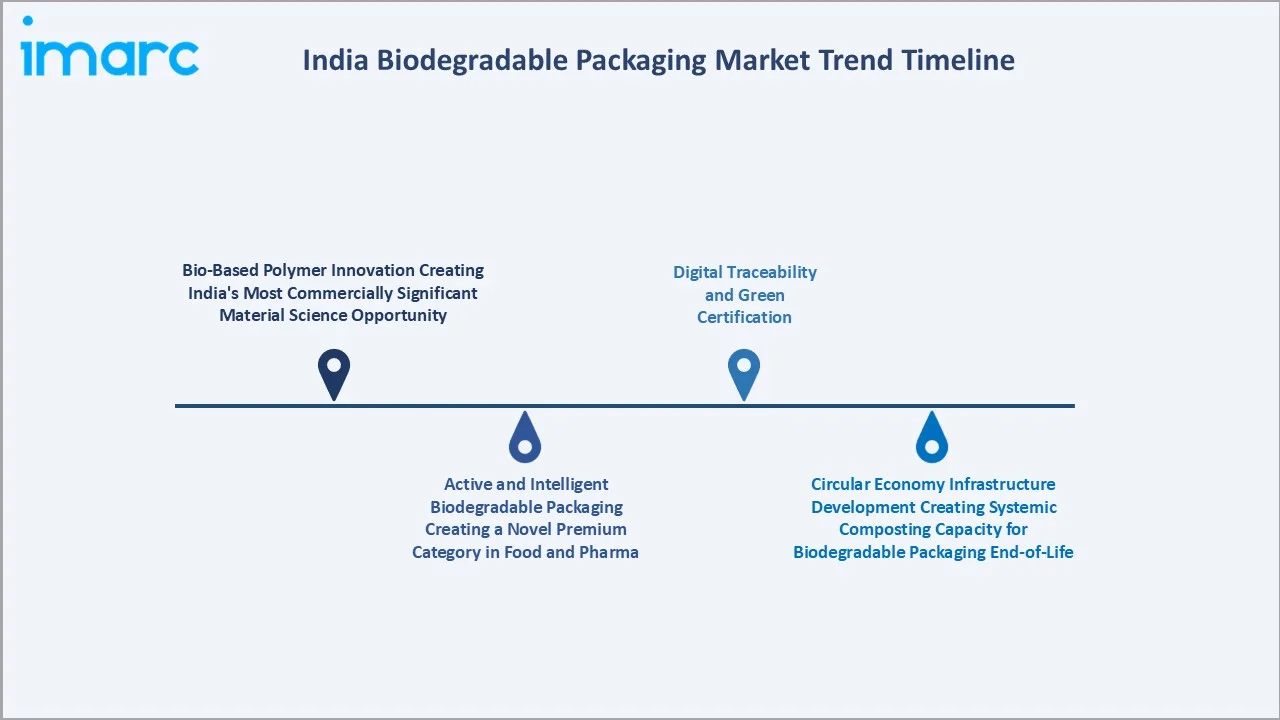
1. Bio-Based Polymer Innovation Creating India's Most Commercially Significant Material Science Opportunity
Next-generation biopolymers such as polyhydroxyalkanoates (PHA) and thermoplastic starch (TPS) composites are gaining research traction, with pilot plants operational in Karnataka and Maharashtra. Commercial scale-up is expected by 2027–2028, with cost parity against PLA projected by 2030. This innovation wave is attracting VC funding and positioning India as a potential Asian hub for advanced biodegradable material production and export to regulated markets.
2. Active and Intelligent Biodegradable Packaging Creating a Novel Premium Category in Food and Pharma
Integration of oxygen scavengers, moisture controllers, and freshness indicators into biodegradable substrates is an emerging frontier for fresh produce and dairy packaging, offering dual-value propositions of shelf-life extension and compostable credentials. CSIR-CFTRI initiated collaborative projects with packaging converters to develop active biodegradable films for the export fresh produce segment.
3. Circular Economy Infrastructure Development Creating Systemic Composting Capacity for Biodegradable Packaging End-of-Life
Industry consortia led by the Packaging Council of India are collaborating with state pollution control boards on certified composting infrastructure pilots in Pune, Hyderabad, and Ahmedabad. These closed-loop systems aim to enable systematic collection and composting of branded biodegradable packaging, strengthening sustainability credentials and supporting credible compostability claims.
4. Digital Traceability and Green Certification
QR code-based traceability systems linking packaging to compostability certifications and material origin data are being piloted by premium FMCG brands, aligning with regulator and investor demand for supply chain transparency. Digital certification integration enables brands to communicate composting instructions and environmental impact credentials directly to end-consumers via smartphone.
Industry Value Chain Analysis
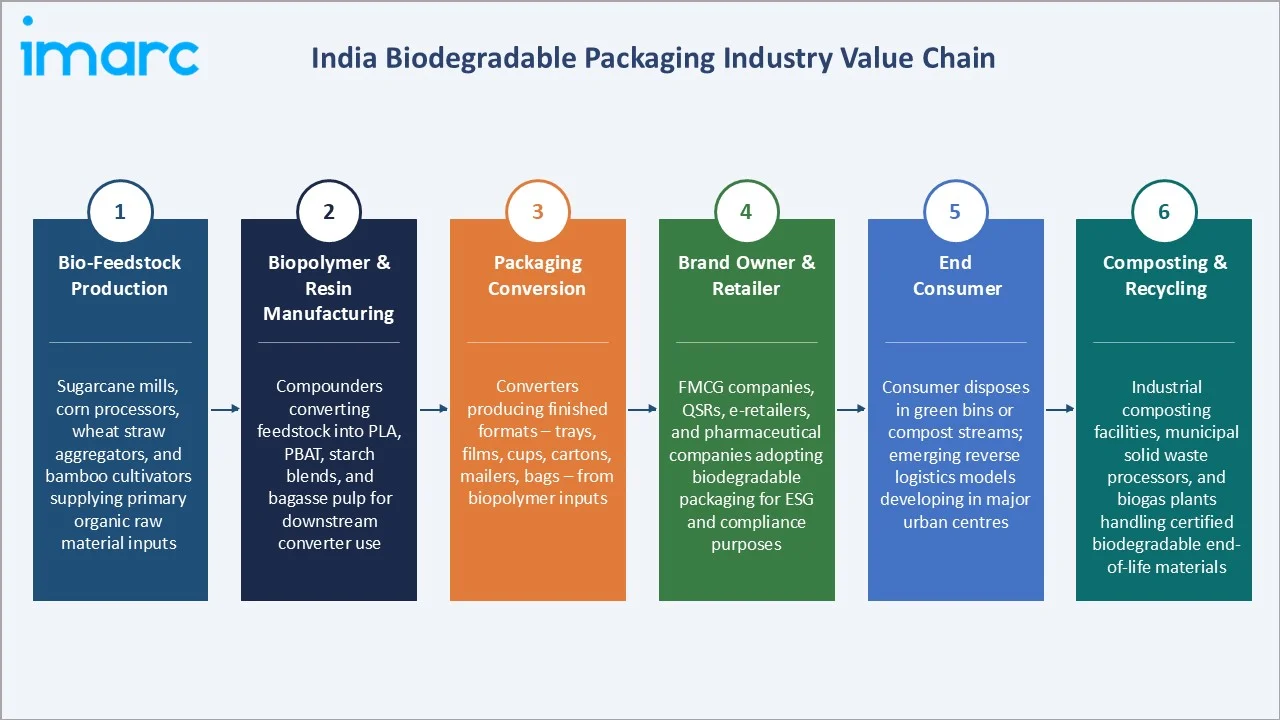
India's biodegradable packaging value chain spans primary bio-feedstock production through certified composting at end-of-life, with each stage presenting distinct cost profiles, strategic entry points, and margin opportunities for participants capitalising on the market's structural growth trajectory through 2034.
|
Stage |
Key Participants |
| Bio-Feedstock Production | Sugarcane mills, corn processors, wheat straw aggregators, and bamboo cultivators supplying primary organic raw material inputs |
| Biopolymer & Resin Manufacturing | Compounders converting feedstock into PLA, PBAT, starch blends, and bagasse pulp for downstream converter use |
| Packaging Conversion | Converters producing finished formats – trays, films, cups, cartons, mailers, bags – from biopolymer inputs |
| Brand Owner & Retailer | FMCG companies, QSRs, e-retailers, and pharmaceutical companies adopting biodegradable packaging for ESG and compliance purposes |
| End Consumer | Consumer disposes in green bins or compost streams; emerging reverse logistics models developing in major urban centres |
| Composting & Recycling | Industrial composting facilities, municipal solid waste processors, and biogas plants handling certified biodegradable end-of-life materials |
Biopolymer resin imports from Europe and China constitute 40–60% of total input cost for Indian converters, making raw material sourcing the most commercially consequential cost driver. Domestic biopolymer production scale-up would transform value chain competitiveness, compressing conversion costs market-wide and creating competitive moats for early domestic resin producers.
Technology Landscape in the India Biodegradable Packaging Industry
Biopolymer Material Technologies
Advances in PLA crystallinity enhancement, PBAT-starch co-extrusion, and nano-cellulose reinforcement are improving barrier properties of biodegradable packaging. IIT Bombay and CSIR-CFTRI are conducting government-funded research in bio-based barrier coatings targeting performance parity with petroleum-based films. Commercial breakthroughs are expected by 2027–2028, supported by PLI scheme funding for specialty biopolymer manufacturing in India.
Moulded Fibre and Thermoforming Technologies
Moulded fibre technology using wet-pressing and thermoforming processes is maturing rapidly in India, enabling high-volume, low-cost production of food containers, trays, and cushion packaging. Thermoforming lines compatible with compostable PLA sheets are expanding product range from rigid to flexible formats, enabling domestic manufacturers to compete with imported biodegradable packaging on quality and price in the organised retail segment.
Digital Integration and Smart Packaging
Embedded NFC and QR code solutions linked to blockchain-based product passports are emerging in premium biodegradable packaging, enabling brands to communicate carbon footprint, composting instructions, and supply chain provenance to consumers via smartphone. This convergence of material science and digital technology creates new premium category opportunities and supports certified biodegradable packaging premium pricing in food and personal care segments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Material Type | Plastic-Based Biodegradable |
55.6% |
2025 |
|
Application |
Food Packaging |
52.7% |
2025 |
|
Region |
West India |
32.8% |
2025 |

By Material Type
Plastic-based biodegradable materials (PLA, PBAT, bio-PE composites) dominated at 55.6% in 2025, driven by superior mechanical performance, moisture resistance, and compatibility with existing packaging lines across food, pharmaceutical, and e-commerce applications where performance requirements preclude simpler paper-based alternatives.
To access detailed market analysis, Request Sample
Paper and paperboard commanded 44.4%, supported by feedstock availability, printability, consumer perception of naturalness, and established supply chains from India's large domestic paper industry. This segment is gaining share in food service and e-commerce packaging as brands seek cost-competitive biodegradable options for high-volume applications.
By Application
Food packaging led at 52.7% in 2025, underpinned by FSSAI-driven compliance and food service sector sustainability commitments. Growth of cloud kitchens, QSR chains, and food delivery platforms creates consistent volume demand for compostable plates, containers, pouches, and certified multi-layer laminates for direct food contact applications.
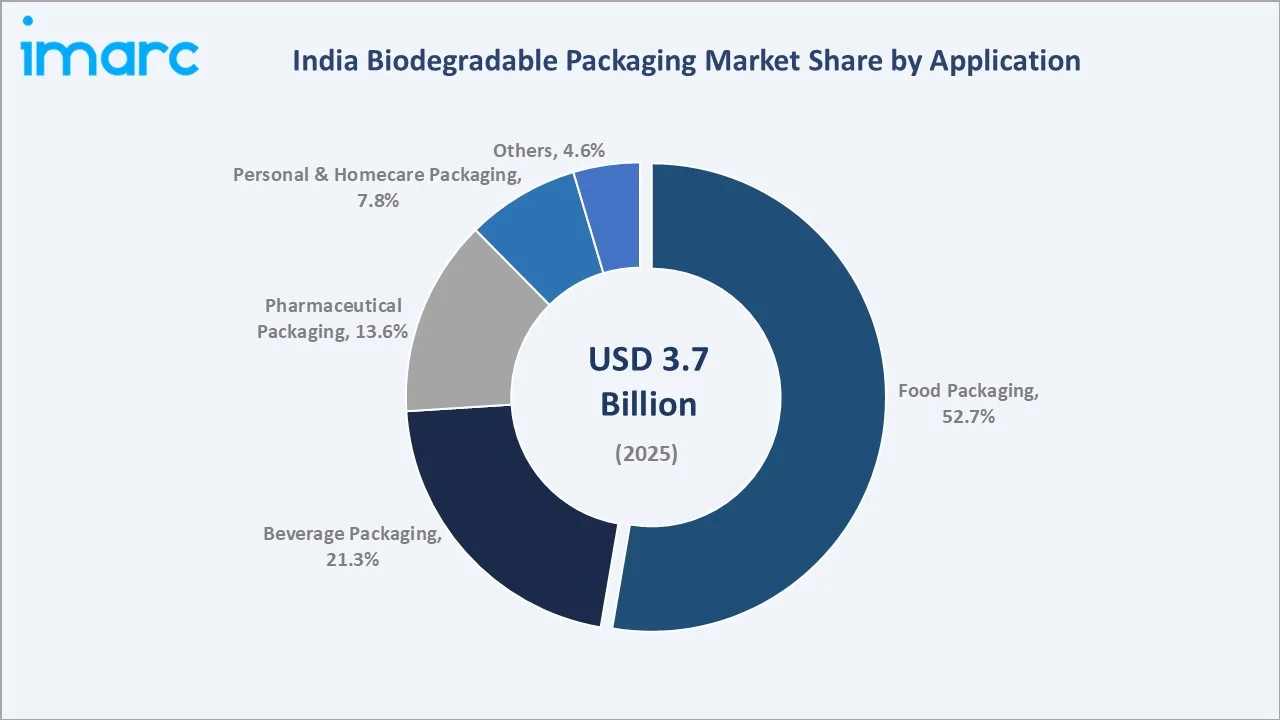
Beverage packaging accounted for 21.3%, with growth in compostable coffee cups. Pharmaceutical packaging at 13.6% is the fastest-growing sub-segment (~6.2% CAGR) driven by hospital sustainability procurement. Personal and homecare packaging holds 7.8%, with all other applications at 4.6% of total market value.
Regional Market Insights
|
Region |
Share (2025) |
Key Biodegradable Packaging Market Drivers & Characteristics |
| West India |
32.8% |
Driven by FMCG, pharma, and packaging converter concentration in Maharashtra and Gujarat; major export hub for certified sustainable packaging. |
| North India |
27.4% |
Supported by agricultural feedstock surplus, NCR-based brand owner demand, and growing food processing sector adopting biodegradable packaging. |
| South India |
23.1% |
Reflects Bengaluru, Hyderabad, and Chennai's tech and FMCG sectors driving premium biodegradable packaging demand and sustainability adoption. |
| East India |
16.7% |
Rising awareness of biodegradable packaging among food processors; untapped jute and bamboo-based packaging potential in Kolkata and Northeast corridor. |
West India's 32.8% leadership reflects the Mumbai-Pune-Ahmedabad-Surat corridor's dense concentration of FMCG companies, pharmaceutical manufacturers, and packaging converters, driven by regulatory compliance and export requirements. North India's 27.4% share is anchored by the NCR's consumer goods procurement market and proximity to major agri-feedstock production belts.
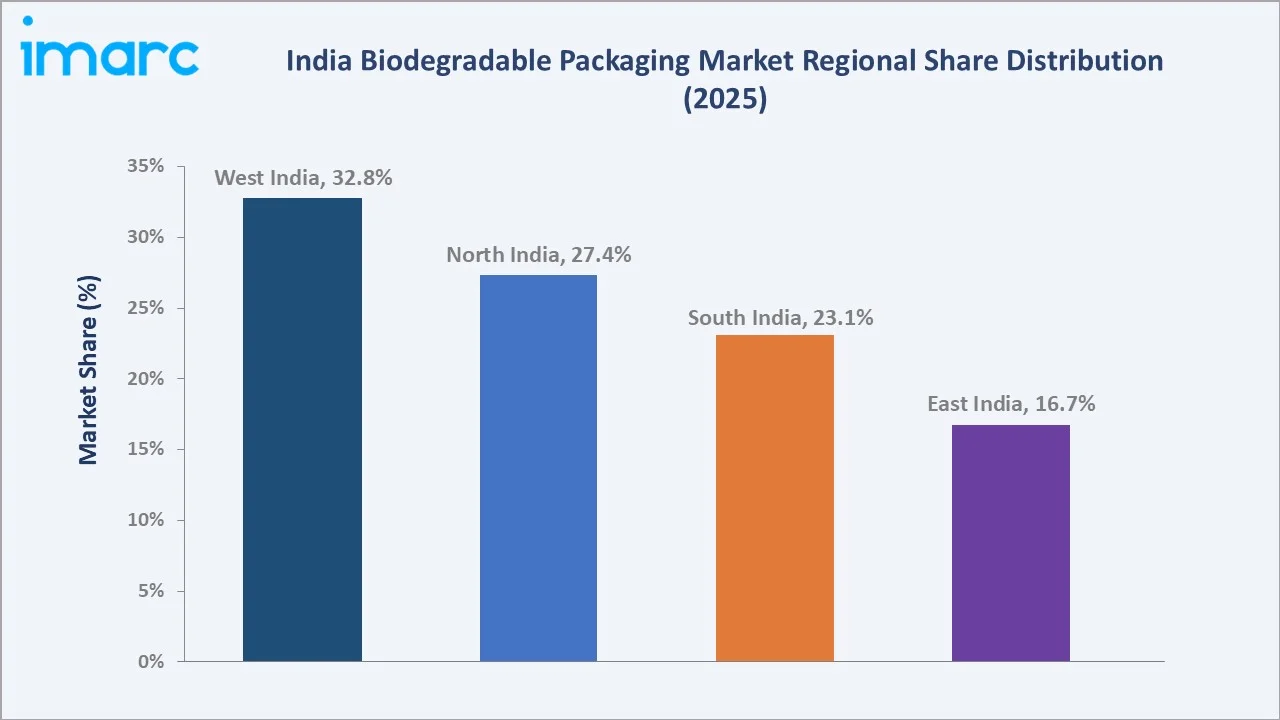
South India's 23.1% reflects Bengaluru's sustainability innovation ecosystem and Chennai's FMCG cluster. East India, at 16.7%, holds untapped potential in bamboo and jute-based packaging, supported by abundant raw materials and government backing for MSME-scale bio-packaging in the Kolkata industrial corridor.
Competitive Landscape
India's biodegradable packaging competitive landscape is moderately concentrated with a mix of dedicated biodegradable specialists, diversified packaging companies, and global players entering domestically. Competition is intensifying through regulatory compliance requirements, rising e-commerce adoption, and consumer demand for certified compostable packaging across food service and consumer goods.
|
Company |
Key Brands |
Market Position |
Core Strength |
| Pakka | Chuk compostable plates, cups, cutlery; flexible compostable laminates |
Market Leader |
Vertically integrated bagasse processing; BPI & OK Compost certified; strong export presence |
| Ecoware | Bagasse food containers, meal trays, bowls; institutional catering packs | Strong Challenger | IS 17088 BIS certification; institutional client base across airlines and government |
| Pappco Greenware | Paper cups, compostable straws, PLA cutlery; cold-chain packaging | Innovator | Export-grade EN 13432 compliant production; strong Middle East and European market access |
| Bambrew | Bamboo-based packaging films, carry bags; plant fibre composites | Niche Innovator | Patented plant fibre composites; differentiates through non-wood sustainable feedstock |
| Greendot Biopak Pvt. Ltd. | PLA cups, compostable cold-chain packaging; pharma secondary packaging | Emerging Player | EN 13432 compliant exports; growing pharmaceutical packaging segment penetration |
Key players include Pakka, Ecoware, Pappco Greenware, Bambrew, Greendot Biopak Pvt. Ltd., and others.
Key Company Profiles
Pakka
Pakka is India's leading manufacturer of compostable packaging under the Chuk brand. Headquartered in Ayodhya, Uttar Pradesh, the company operates integrated sugarcane bagasse processing facilities producing food service items certified under BPI (USA) and OK Compost (Europe) standards.
- Key Products: Chuk brand BPI-certified compostable plates (6–12 inch), bowls, containers, cutlery sets, and flexible compostable laminates (M1, M3, NM1 grades launched September 2024). Products are heat-resistant to 95°C and suitable for both hot and cold food service across QSR, airline catering, and institutional segments.
- Recent Developments: In September 2024, Pakka launched its M1, M3, and NM1 grades of compostable flexible packaging laminates designed for dry goods, confectionery, and fresh produce packaging, meeting European EN 13432 and Indian IS 17088 compostability standards.
- Strategic Focus: Maintaining market leadership in India's certified compostable food service packaging through capacity expansion at the Ayodhya plant targeting doubled output by FY 2026–27, proprietary bio-barrier coating development to reduce imported PLA dependency, and building direct retail export partnerships in Germany, UK, and UAE. The company is piloting QR-based compostability traceability on select SKUs to strengthen sustainability credibility with institutional buyers and export market regulators.
Ecoware
Ecoware, based in New Delhi, is a pioneer in bagasse-based sustainable food packaging. Founded in 2010, the company supplies compostable trays, containers, and bowls to airlines, institutional caterers, FMCG brands, and government food programmes.
- Key Products: Sugarcane bagasse moulded fibre containers, compartmented meal trays, clamshell containers, round and oval dishes, and soup bowls. All products carry IS 17088 (BIS) certification, are heat-resistant to 120°C, microwave-safe, and meet food-grade standards for hot meal delivery and airline in-flight catering.
- Strategic Focus: Expanding manufacturing capacity with a second facility in Rajasthan targeting 120 million units per year by 2026, developing seaweed-composite formulations in collaboration with CSIR-CSMCRI for next-generation marine-based packaging alternatives, and partnering with state pollution control boards in Delhi, Jaipur, and Chandigarh to establish certified composting collection systems that create closed-loop sustainability credentials for its packaging. The company is targeting a stock exchange listing by 2026–27 to fund capacity and geographic expansion.
Market Concentration Analysis
India's biodegradable packaging market is moderately fragmented, with the top five players accounting for an estimated 35–42% of organised market revenues. A large unorganised sector of small-scale paper and agri-fibre converters adds structural fragmentation.
Market concentration is evolving through two opposing forces: increasing quality certification requirements and large-buyer procurement standards that favour larger certified manufacturers, and the entry of technology-backed start-ups challenging incumbents in niche segments such as seaweed packaging and bio-based e-commerce mailers. Strategic M&A and capacity-anchored supply agreements are expected to increase market concentration moderately through 2030.
Investment & Growth Opportunities
Highest Growth Segments
Pharmaceutical packaging (~6.2% CAGR), plastic-based biodegradable materials (~5.1% CAGR), and food packaging (~5.2% CAGR) are India's fastest-growing segments through 2034.
Emerging Investment Opportunities
Domestic biopolymer resin manufacturing represents the highest-value investment opportunity given current 40–60% import dependency on PLA and PBAT from Europe and China. Domestic production at scale would compress conversion costs market-wide and create competitive moats for early movers. Composting infrastructure under public-private partnership models, supported by CPCB guidelines and municipal solid waste contracts, offers viable revenue models.
Investment Themes
- Biopolymer Resin Manufacturing: Domestic PLA and PBAT resin manufacturing capacity investment, targeting India's current import dependency and the 40–60% input cost reduction achievable through local production at scale, creating above-sector-average returns through first-mover material cost advantages across the biodegradable packaging value chain as regulatory-mandated market volumes scale.
- Certified Industrial Composting Infrastructure: Industrial composting facility investment under PPP frameworks with urban local bodies, targeting the systemic end-of-life infrastructure gap that currently limits biodegradable packaging's sustainability claims and creates greenwashing risk for brand owners, with revenue models anchored on tipping fees, compost sales, carbon credit generation, and long-term municipal solid waste processing contracts.
Future Market Outlook (2026-2034)
The India biodegradable packaging market is projected to grow from USD 3.70 Billion in 2025 to USD 3.93 Billion in 2026, reaching USD 4.69 Billion by 2030 and USD 5.75 Billion by 2034 at a CAGR of 4.88%. The USD 4.69 Billion milestone in 2030 marks a structural inflection where regulatory compliance transitions from enforcement pressure to embedded market norm, e-commerce becomes a primary channel driver, and domestic biopolymer production reduces import dependency.
Three structural forces define market growth through 2034: India's regulatory trajectory, among the world's most rapidly enforced packaging sustainability mandates in a large consumer economy; FMCG and food service sector structural commitment to biodegradable packaging beyond discretionary ESG spending; and digital commerce maturation driving sustainability adoption from metro markets into tier-2 and tier-3 city brand owners and consumers across India.
Research Methodology
Primary Research
Primary research comprised structured interviews with biodegradable packaging industry stakeholders, including packaging converter CEOs, FMCG sustainability heads, and regulatory officials from CPCB and BIS, supplemented by consumer survey data across North, West, South, and East India covering food service, pharmaceutical, and e-commerce packaging segments in urban and semi-urban cohorts.
Secondary Research
Secondary research encompassed biodegradable packaging import-export data from DGCI&S, Ministry of Environment publications, CPCB plastic waste management reports, company annual reports, trade publications, patent databases, and certification body licensing records. Over 60 secondary sources were reviewed and cross-validated to ensure data consistency and accuracy.
Forecasting Models
Market forecasts were developed using a bottom-up model: India's packaging consumption by sector multiplied by biodegradable penetration rates per segment, calibrated against EPR compliance timelines and regulatory enforcement schedules. Cross-validation was performed against top-down GDP-correlated models and trade flow triangulation across at least three independent sources per data point.
India Biodegradable Packaging Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Material Types Covered |
|
| Applications Covered | Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal/Homecare Packaging, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Pakka, Ecoware, Pappco Greenware, Bambrew, Greendot Biopak Pvt. Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India biodegradable packaging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India biodegradable packaging market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India biodegradable packaging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Biodegradable Packaging Market Report
India biodegradable packaging market size is estimated at USD 3.93 Billion in 2026, growing from USD 3.70 Billion in 2025, driven by regulatory enforcement of single-use plastic bans, FMCG sustainability commitments, and expansion of food delivery platforms mandating certified compostable packaging.
The India biodegradable packaging market grows at 4.88% CAGR during 2026-2034, reaching USD 5.75 Billion by 2034. Growth is sustained by regulatory tailwinds, corporate ESG mandates, declining biopolymer costs, and rising export demand from EU, Middle East, and Australian markets requiring certified compostable packaging.
Plastic-based biodegradable materials lead at 55.6% due to dominant demand for high-performance certified compostable packaging in food, pharmaceutical, and e-commerce applications where PLA, PBAT, and bio-PE composites offer superior barrier properties over paper-based alternatives.
Food packaging leads at 52.7% through India's large organised food service sector, FSSAI compliance mandates for compostable food contact materials, and food delivery platforms serving over 800 million orders annually, each requiring certified sustainable packaging formats from partner restaurants.
West India leads at 32.8% through Maharashtra and Gujarat's concentration of FMCG manufacturers, pharmaceutical companies, and packaging converters, all significant consumers of certified biodegradable packaging driven by domestic regulatory compliance and international export sustainability requirements.
Leading companies include Pakka, Ecoware, Pappco Greenware, Bambrew, Greendot Biopak Pvt. Ltd., and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade