India Cold Chain Logistics Market Size, Share, Trends and Forecast by Type, Application, and Region, 2026-2034
India Cold Chain Logistics Market Size, Share, Trends & Forecast (2026-2034)
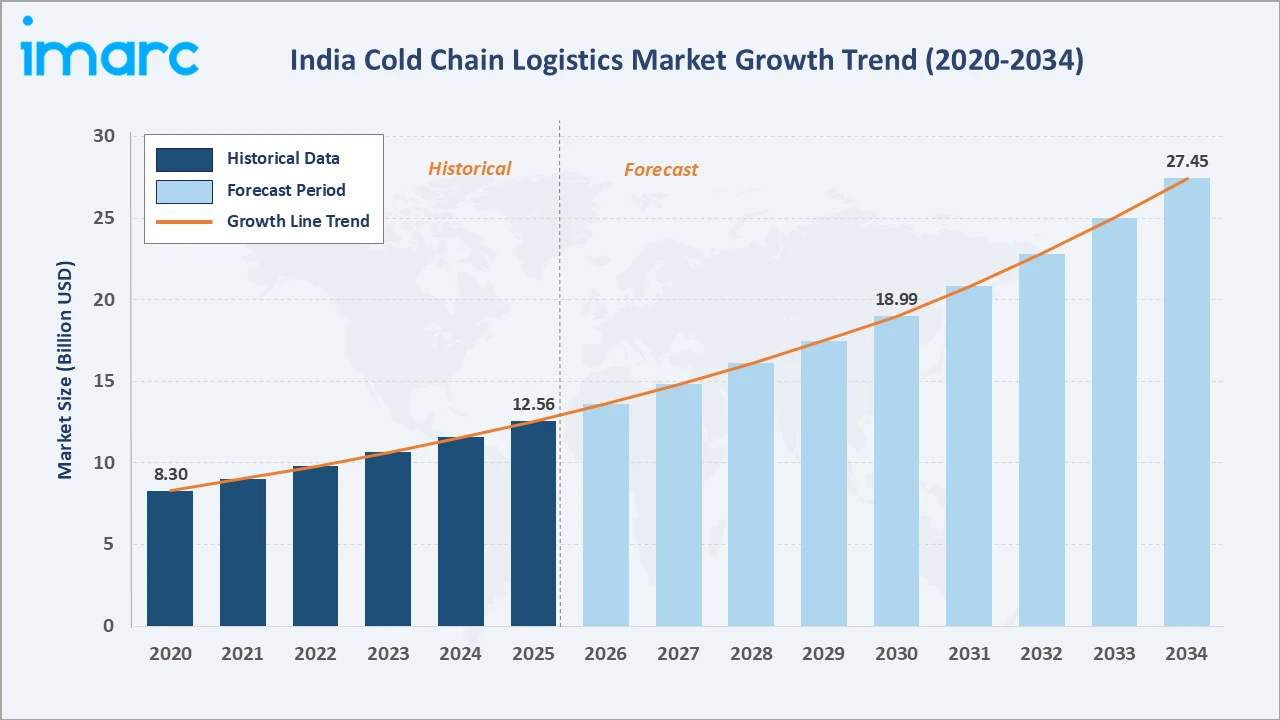
The India cold chain logistics market size increased from USD 12.56 Billion in 2025 to USD 14.16 Billion in 2026 and is projected to reach USD 27.45 Billion by 2034, exhibiting a CAGR of 8.62% during 2026-2034. Rapid expansion of organized food retail and quick-commerce dark stores and rising government support for temperature-controlled infrastructure are the primary drivers shaping the market growth.
Refrigerated warehouses lead the type segment at 57.4%, fruits and vegetables represent the largest application share at 36.8%, and North India commands 33.6% of the regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 12.56 Billion |
| Market Size (2026) | USD 14.16 Billion |
|
Forecast Market Size (2034) |
USD 27.45 Billion |
|
CAGR (2026-2034) |
8.62% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
North India (33.6%, 2025) |
|
Second Largest Region |
West India (28.2%, 2025) |
|
Leading Type |
Refrigerated Warehouses (57.4%, 2025) |
|
Leading Application |
Fruits and Vegetables (36.8%, 2025) |
The India cold chain logistics market expanded from USD 8.30 Billion in 2020 to USD 12.56 Billion in 2025 and an estimated USD 14.16 Billion in 2026, driven by widening organized retail penetration, growing frozen food consumption, and steady investment in warehousing infrastructure across urban and semi-urban regions. Anchored at USD 18.99 Billion in 2030, the forecast to USD 27.45 Billion by 2034 is supported by accelerating pharmaceutical distribution, expanding quick-commerce networks, and a more structured regulatory environment for food safety compliance.
To get more information on this market, Request Sample
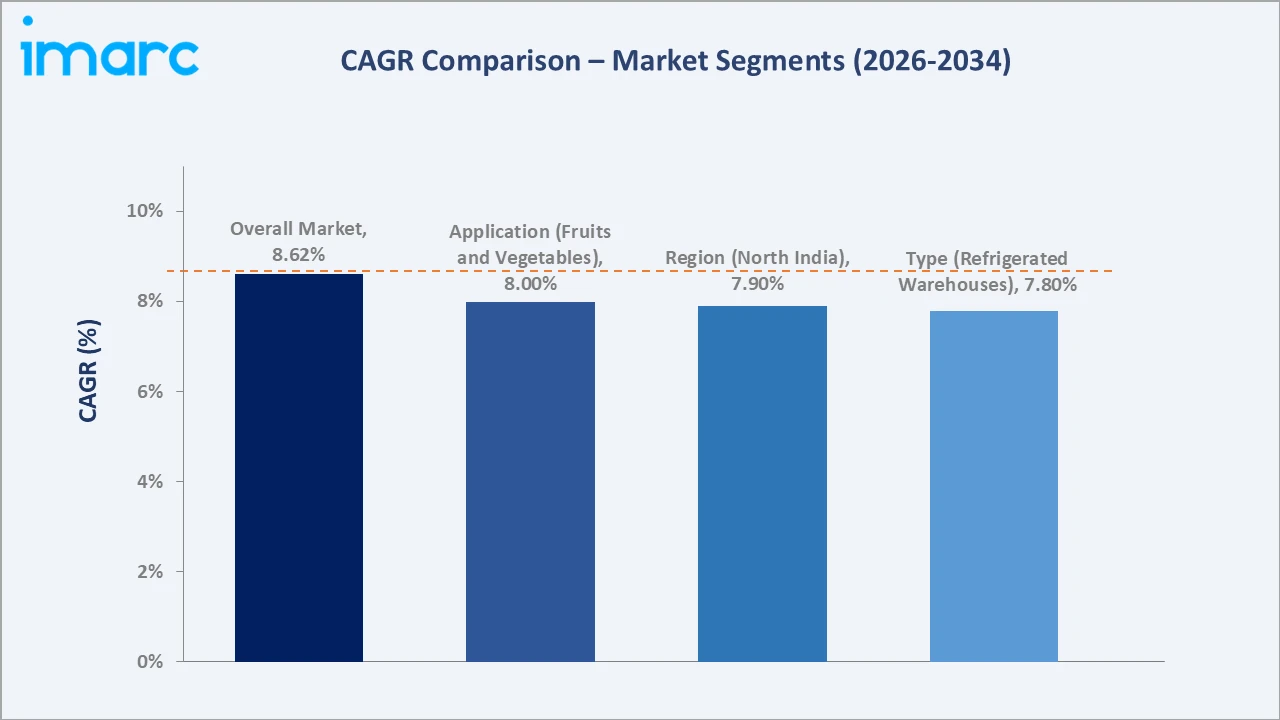
CAGR trajectories across type, application, and regional sub-segments show drugs and pharmaceuticals and refrigerated transportation expanding faster than the overall 8.62% market CAGR, driven by rising temperature-sensitive drug distribution, quick-commerce logistics, and growing multi-city cold storage networks across the country.
Executive Summary
The India cold chain logistics market is on a steady growth trajectory from USD 8.30 Billion in 2020 to an estimated USD 14.16 Billion in 2026, reaching USD 27.45 Billion by 2034. The industry has moved from fragmented, unorganized storage toward integrated, technology-enabled warehousing and refrigerated transportation networks. Rising organized retail penetration, expanding quick-commerce dark stores, and growing food safety compliance requirements are encouraging manufacturers and retailers to formalize their temperature-controlled supply chains.
Refrigerated warehouses dominate the type segment at 57.4% in 2025, supported by rising bulk storage demand from food processors and organized retail chains. Fruits and vegetables lead the application segment at 36.8%, driven by post-harvest loss reduction initiatives and expanding agricultural exports. North India commands 33.6% of the regional share, led by dense agricultural output, strong industrial demand, and a large concentration of organized food processing units in the country.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Refrigerated Warehouses - 57.4% share (2025) |
|
Second Largest Type |
Refrigerated Transportation - 42.6% share (2025) |
|
Leading Application |
Fruits and Vegetables - 36.8% share (2025) |
|
Second Largest Application |
Dairy and Frozen Desserts - 23.4% share (2025) |
|
Leading Region |
North India - 33.6% share (2025) |
|
Second Largest Region |
West India - 28.2% share (2025) |
|
Top Companies |
Gateway Distriparks Limited, Transport Corporation of India Ltd., DHL Group, Gubba Cold Storage Private Limited, Coldman Logistics Private Limited |
Key Analytical Observations Supporting the Above Data:
- Refrigerated warehouses leadership at 57.4% is supported by rising bulk storage requirements from food processors, organized retail chains, and pharmaceutical distributors that need multi-temperature zone facilities close to demand centers.
- Refrigerated transportation at 42.6% is expanding as reefer fleet operators scale up last-mile delivery capacity to serve quick-commerce platforms, modern trade outlets, and export-oriented agricultural supply chains.
- Fruits and vegetables at 36.8% reflect the scale of India's horticultural output and the continued push to reduce post-harvest losses through improved pack-house and cold storage linkages.
- Dairy and frozen desserts share at 23.4% is growing steadily, supported by rising consumption of packaged dairy products and frozen desserts across urban and semi-urban markets. According to PIB, milk production surpassed 239.30 Million Tons in FY 2023-24, sustaining consistent demand for chilled and frozen storage capacity.
- North India at 33.6% leads regional share, anchored by Punjab, Haryana, Uttar Pradesh, and the Delhi-NCR region, supported by dense agricultural production and a large base of organized food processing units.
India Cold Chain Logistics Market Overview
Cold chain logistics refers to the temperature-controlled supply chain encompassing refrigerated warehousing, refrigerated transportation, and value-added handling services required to preserve the quality of perishable and temperature-sensitive goods, including fruits and vegetables, dairy and frozen desserts, meat, fish, and sea food, drugs and pharmaceuticals, and bakery and confectionary, from the point of production to the point of consumption.
The Indian cold chain ecosystem integrates equipment manufacturers, warehouse developers, reefer fleet operators, technology and monitoring platform providers, distribution and logistics partners, and regulatory authorities overseeing food safety and pharmaceutical compliance. Together, these participants support the movement of perishable goods across a geographically diverse and climatically varied country, where macroeconomic factors, such as rising disposable incomes, urbanization, and organized retail expansion, continue to shape infrastructure investment decisions.
Market Dynamics
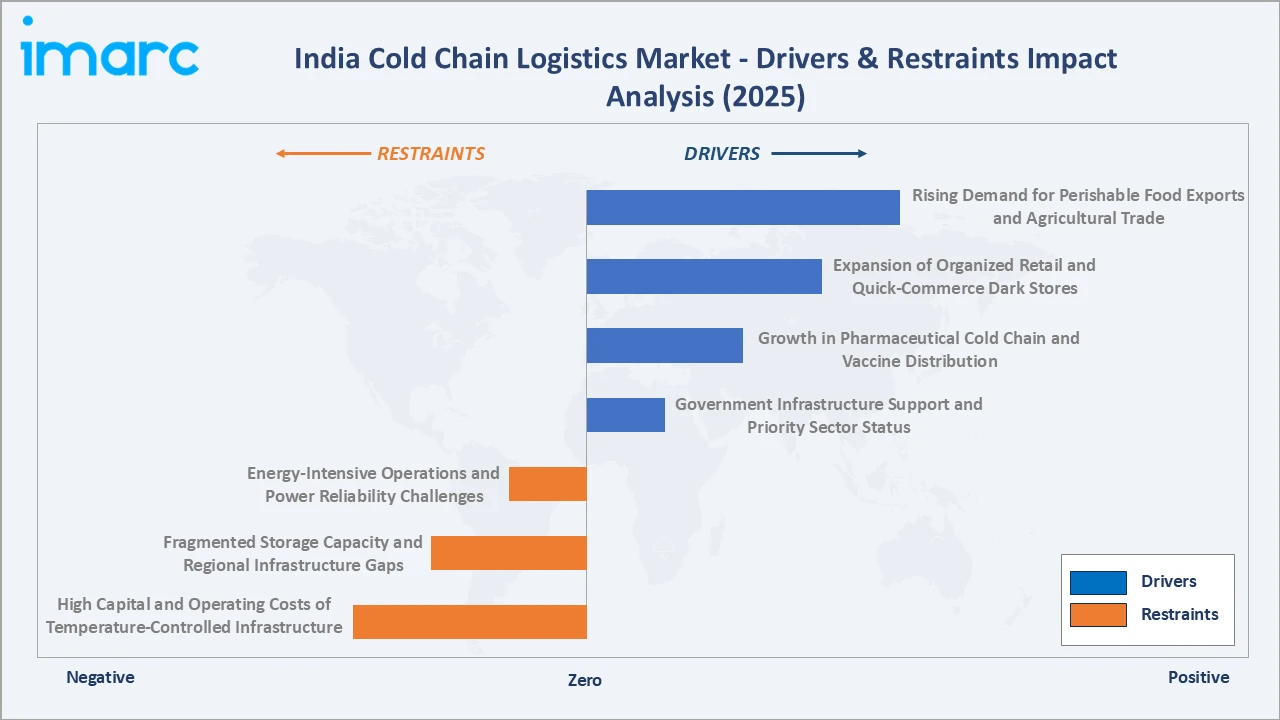
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Demand for Perishable Food Exports and Agricultural Trade: India's growing horticultural and marine exports are increasing the need for certified cold storage and refrigerated transportation infrastructure that meets international quality and traceability standards.
- Expansion of Organized Retail and Quick-Commerce Dark Stores: Rapid growth of supermarket chains and quick-commerce platforms is driving demand for city-level cold storage hubs and last-mile refrigerated delivery fleets. As of March 2026, India's quick-commerce sector was reported to be operating over 5,000 dark stores nationwide, many of which rely on integrated chilled and frozen storage capacity.
- Growth in Pharmaceutical Cold Chain and Vaccine Distribution: Expanding biologics manufacturing, vaccine distribution networks, and stricter temperature-compliance regulations are increasing demand for validated pharmaceutical-grade cold storage and transportation capacity.
- Government Infrastructure Support and Priority Sector Status: Central and state government schemes promoting integrated infrastructure development, along with priority sector lending status for agri-infrastructure projects, are lowering the cost of capital for new warehousing and reefer fleet investments, thus expanded the cold chain logistics market size in India.
Market Restraints
- High Capital and Operating Costs of Temperature-Controlled Infrastructure: Refrigerated warehouses and reefer vehicles require significantly higher upfront investment and ongoing energy expenditure than ambient storage and transportation, constraining smaller operators. Industry estimates place the cost of developing a modern multi-temperature warehouse at several times that of a comparable ambient facility.
- Fragmented Storage Capacity and Regional Infrastructure Gaps: The market remains dominated by a large number of small, regional cold storage operators, resulting in uneven service quality, inconsistent temperature compliance, and limited nationwide network integration.
- Energy-Intensive Operations and Power Reliability Challenges: Frequent power interruptions in several regions increase dependence on diesel backup systems, raising operating costs and limiting the pace of technology upgrades among smaller cold storage operators.
Market Opportunities
- Pharmaceutical and Life Sciences Cold Chain Expansion: Growing biologics, vaccine, and specialty drug distribution needs present significant opportunities for operators able to offer validated, compliant, and traceable pharmaceutical-grade cold storage and transportation.
- Quick-Commerce and Organized Retail Penetration Beyond Metros: Expansion of organized retail and quick-commerce platforms into tier-2 and tier-3 cities creates opportunities for regional cold storage hubs and localized refrigerated distribution networks.
Market Challenges
- Power Supply Reliability and High Energy Costs in Smaller Cities: Inconsistent electricity supply in tier-2 and tier-3 locations continues to raise operating costs and complicate temperature-compliance monitoring for regional cold storage operators.
- Shortage of Skilled Cold Chain Workforce: Limited availability of trained technicians for refrigeration maintenance, temperature monitoring, and reefer fleet management constrains service quality and expansion pace across the industry.
Emerging Market Trends
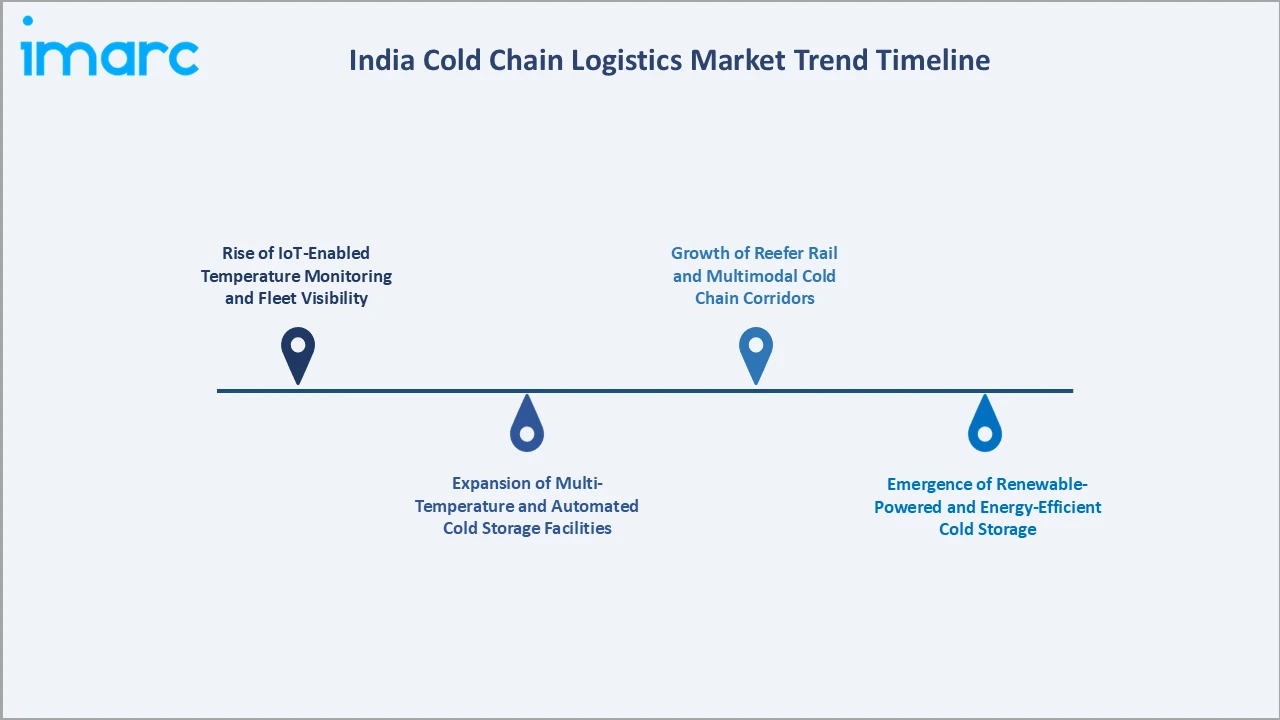
1. Rise of IoT-Enabled Temperature Monitoring and Fleet Visibility
Operators are increasingly deploying IoT-based sensors and real-time tracking platforms across warehouses and reefer fleets to ensure continuous temperature compliance. This shift is improving shipment visibility, reducing spoilage, and enabling faster corrective action during transit disruptions, while strengthening the capabilities of cold chain logistics companies in India.
2. Expansion of Multi-Temperature and Automated Cold Storage Facilities
Newer warehouses are being designed with multiple temperature zones and automated storage and retrieval systems to serve diverse product categories within a single facility. This flexibility is supporting higher throughput and better space utilization for organized retail and food processing clients.
3. Growth of Reefer Rail and Multimodal Cold Chain Corridors
Investment in reefer rail wagons and multimodal logistics corridors is helping reduce long-haul transportation costs for perishable goods moving between production regions and consumption centers.
4. Emergence of Renewable-Powered and Energy-Efficient Cold Storage
Rising energy costs are prompting cold storage operators to adopt solar power, energy-efficient compressors, and natural refrigerants. This transition is gradually lowering operating costs and supporting sustainability commitments across the sector.
Industry Value Chain Analysis
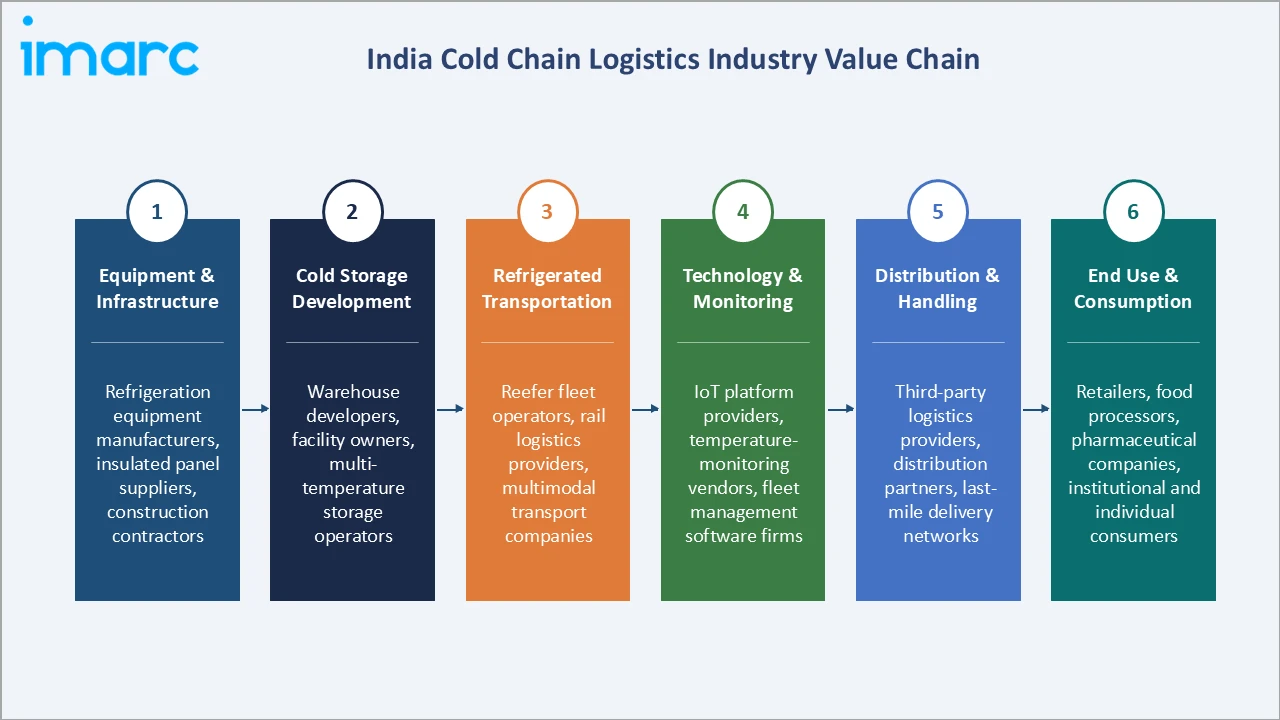
The India cold chain logistics value chain spans six stages, from equipment supply and infrastructure development through end-use consumption. Cold storage development and refrigerated transportation capture the highest value-add, while technology and monitoring capabilities increasingly determine sustainable competitive position across the sector.
|
Stage |
Key Players / Examples |
|
Equipment & Infrastructure |
Refrigeration equipment manufacturers, insulated panel suppliers, and construction contractors |
|
Cold Storage Development |
Warehouse developers, facility owners, and multi-temperature storage operators |
|
Refrigerated Transportation |
Reefer fleet operators, rail logistics providers, and multimodal transport companies |
|
Technology & Monitoring |
IoT platform providers, temperature-monitoring vendors, and fleet management software firms |
|
Distribution & Handling |
Third-party logistics providers, distribution partners, and last-mile delivery networks |
|
End Use & Consumption |
Retailers, food processors, pharmaceutical companies, and institutional and individual consumers |
Vertically integrated players, particularly those owning proprietary warehousing assets, reefer fleets, and technology platforms, are positioned to capture greater value than partners reliant on third-party infrastructure.
Technology Landscape in the India Cold Chain Logistics Industry
IoT Sensors and Real-Time Monitoring Systems
Modern warehouse and fleet operators are deploying wireless temperature and humidity sensors integrated with cloud-based dashboards to maintain continuous visibility across multi-temperature storage zones and refrigerated vehicles. These systems support faster deviation alerts and stronger compliance documentation for food safety and pharmaceutical clients. The growing adoption of these technologies is also supporting the development of the India cold chain monitoring market.
Automation and Robotics in Cold Storage
Automated storage and retrieval systems, robotic palletizers, and conveyor-based sorting are being adopted in larger facilities to reduce manual handling time inside chilled and frozen environments, improving throughput while lowering labor exposure to low-temperature working conditions.
Renewable Energy and Refrigerant Innovation
Solar-powered cold storage units, energy-efficient compressors, and natural refrigerant systems are gaining traction as operators look to reduce electricity costs and align with evolving environmental regulations governing refrigerant use.
Data Analytics and Predictive Maintenance
Analytics platforms are increasingly used to forecast demand, optimize warehouse space utilization, and schedule predictive maintenance for refrigeration equipment, helping operators reduce unplanned downtime and extend asset life across large, distributed facility networks. These capabilities are also enhancing the efficiency and reliability of the cold chain logistics services market.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Refrigerated Warehouses |
57.4% |
2025 |
|
Application |
Fruits and Vegetables |
36.8% |
2025 |
|
Region |
North India |
33.6% |
2025 |

By Type
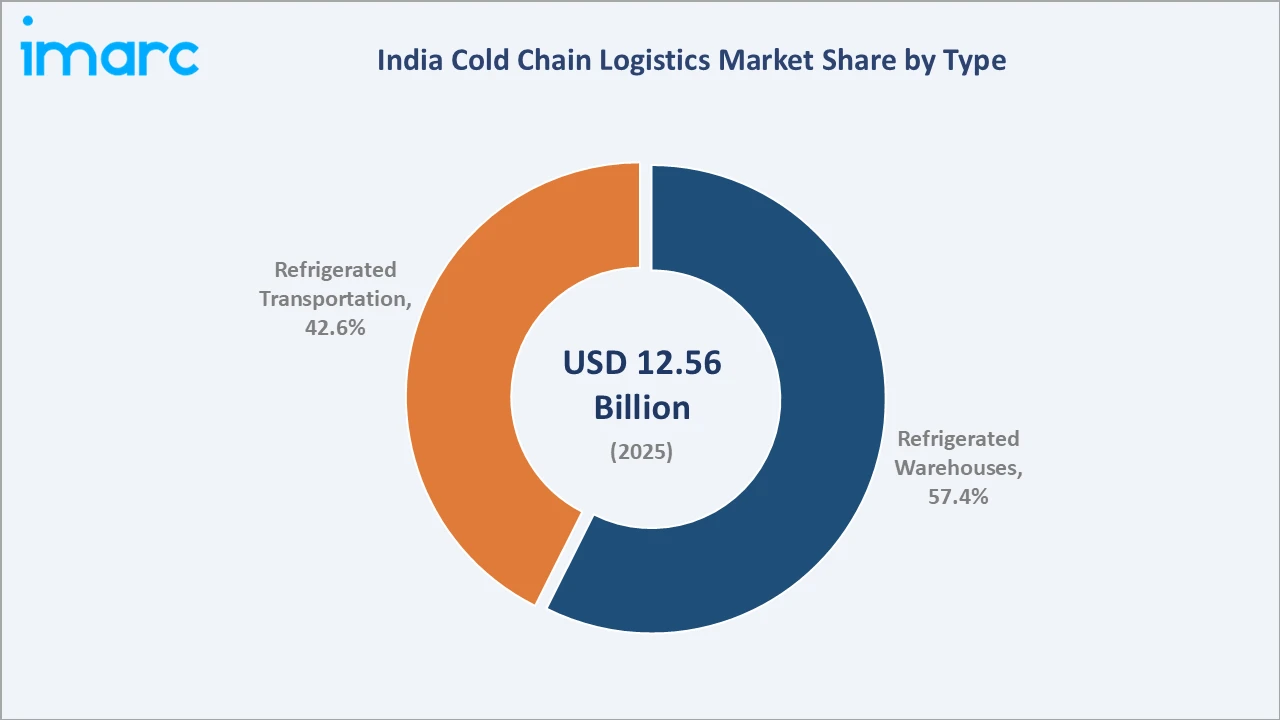
Refrigerated warehouses command a 57.4% majority share in 2025, driven by rising bulk storage requirements from food processors, organized retail chains, and pharmaceutical distributors that need multi-temperature zone facilities near demand centers. The segment benefits from long-term leasing models, economies of scale, and growing institutional investment in modern warehousing assets.
To access detailed market analysis, Request Sample
Refrigerated transportation accounts for 42.6% in 2025, covering reefer trucks, refrigerated rail wagons, and last-mile delivery vehicles. The segment is expanding rapidly alongside quick-commerce and organized retail growth, which increasingly require frequent, smaller-volume temperature-controlled deliveries.
By Application
Fruits and vegetables dominate with 36.8% share in 2025, reflecting the scale of India's horticultural production and continued efforts to reduce post-harvest losses through improved pack-house and cold storage linkages across major growing regions.
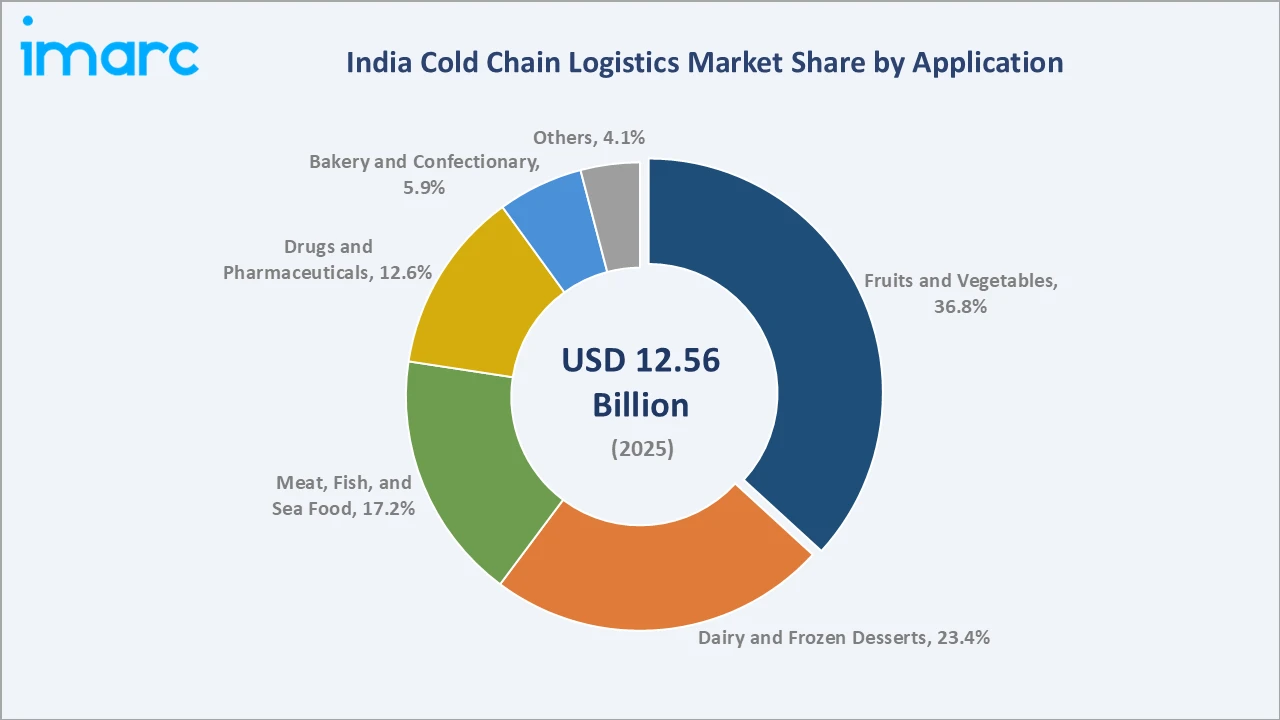
Dairy and frozen desserts follow at 23.4%, supported by rising consumption of packaged milk products, ice cream, and frozen desserts across urban and semi-urban markets.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
North India |
33.6% |
Strong agricultural output, dense industrial base, and expanding organized food processing capacity |
|
West India |
28.2% |
Established port infrastructure, large processed food industry, and strong export-oriented cold chain demand |
|
South India |
24.7% |
Growing agricultural exports, rising quick-commerce penetration, and expanding pharmaceutical manufacturing base |
|
East India |
13.5% |
Emerging cold storage investment, rising agricultural output, and improving regional logistics connectivity |
North India at 33.6% in 2025 leads the regional landscape, anchored by Punjab, Haryana, Uttar Pradesh, and the Delhi-NCR region. Dense agricultural production, a large base of organized food processing units, and proximity to major consumption centers support sustained regional leadership.
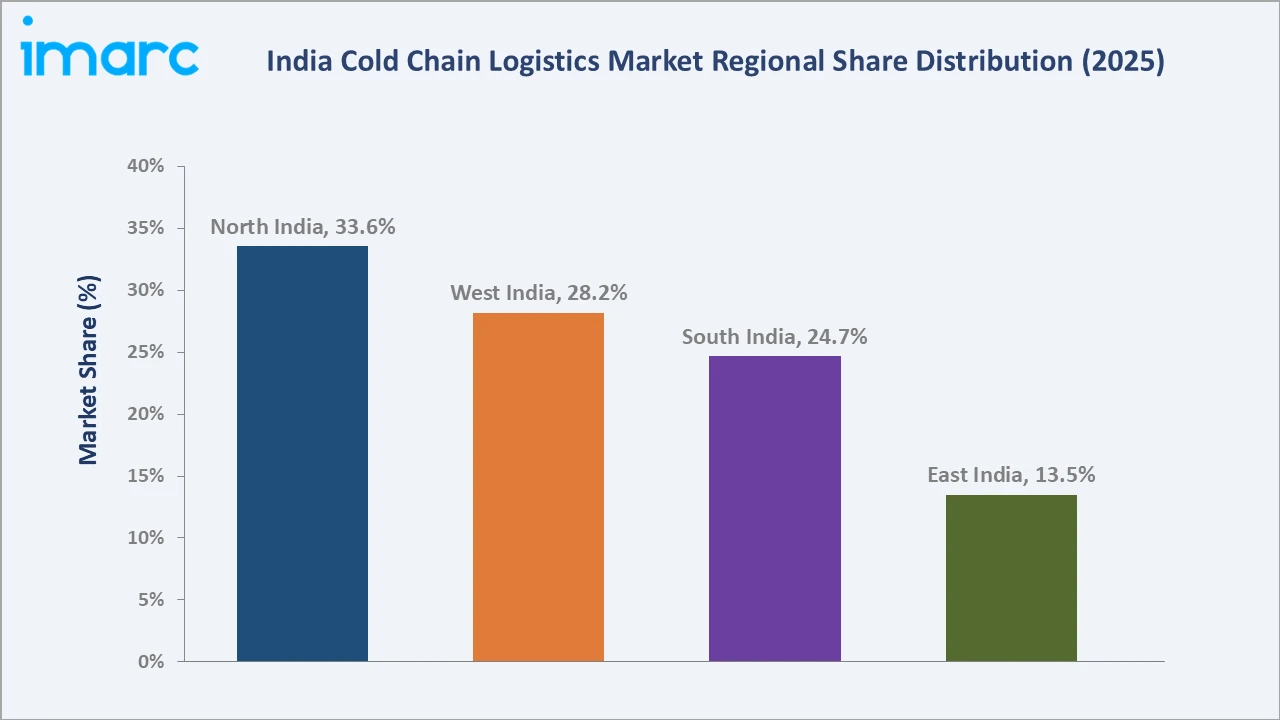
South India, at 24.7%, is the fastest expanding region. Rising agricultural exports, growing pharmaceutical manufacturing clusters, and rapid quick-commerce adoption are accelerating regional cold chain infrastructure investment.
Competitive Landscape
The India cold chain logistics market is moderately fragmented, with established national players competing alongside a large number of regional specialists. Warehousing scale, reefer fleet size, technology adoption, and multi-city network reach form the key competitive differentiators across the sector.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Gateway Distriparks Limited |
Snowman Logistics |
Leader |
Expanding pan-India multi-temperature warehousing and reefer fleet capacity |
|
Transport Corporation of India Ltd. |
TCI Cold Chain |
Leader |
Strengthening multimodal reefer transportation and pharma-focused logistics corridors |
|
DHL Group |
DHL Supply Chain |
Leader |
Investing in automated, technology-enabled cold storage facilities in India |
|
Gubba Cold Storage Private Limited |
Gubba Cold Storage |
Challenger |
Expanding multi-chamber cold storage capacity for agricultural and seed preservation |
|
Coldman Logistics Private Limited |
Coldman Logistics |
Challenger |
Strengthening regional reefer fleet and multi-city warehousing presence |
Key players include Gateway Distriparks Limited, Transport Corporation of India Ltd., DHL Group, Gubba Cold Storage Private Limited, and Coldman Logistics Private Limited, among others.
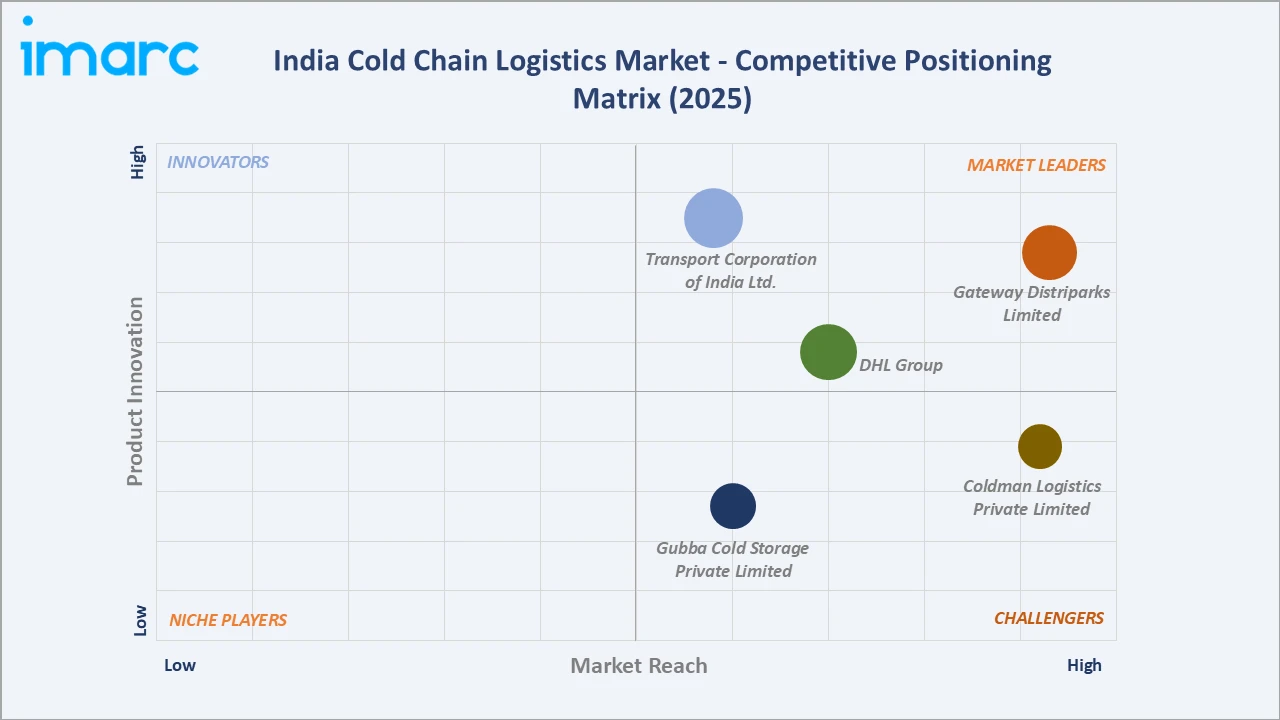
Key Company Profiles
Gateway Distriparks Limited
Gateway Distriparks Limited is an India-based logistics company with operations spanning inter-modal container logistics and temperature-controlled cold chain services through its group operations.
- Product Portfolio: Multi-temperature warehousing and refrigerated transportation services offered through its cold chain logistics operations.
- Recent Developments: The company has continued to strengthen its cold chain logistics capabilities by expanding temperature-controlled infrastructure and enhancing its service network across key markets in India.
- Strategic Focus: Broadening temperature-controlled logistics capabilities through expanded warehousing capacity and distribution coverage.
Transport Corporation of India Ltd.
Transport Corporation of India Ltd. is a diversified logistics company offering multimodal transportation services, including a dedicated cold chain logistics business serving food and pharmaceutical industry clients.
- Product Portfolio: Temperature-controlled road transportation, warehousing, and distribution services for pharmaceutical and perishable food cargo.
- Recent Developments: The company has continued to strengthen its cold chain transportation network and expand its logistics corridors across major manufacturing and distribution hubs.
- Strategic Focus: Enhancing temperature-controlled transportation capabilities and strengthening integrated logistics solutions for pharmaceutical and food supply.
DHL Group
DHL Group is a global logistics company providing temperature-controlled warehousing and distribution services to food, beverage, and pharmaceutical clients through its supply chain operations in India.
- Product Portfolio: Temperature-controlled contract warehousing, distribution management, and value-added logistics services across multiple industry verticals.
- Recent Developments: The company has continued to invest in modern, technology-enabled distribution infrastructure across its India operations.
- Strategic Focus: Advancing technology-driven cold chain infrastructure and strengthening automated temperature-controlled logistics capabilities.
Market Concentration Analysis
The India cold chain logistics market is moderately fragmented, with the leading players, including Gateway Distriparks Limited, Transport Corporation of India Ltd., and DHL Group, together accounting for a meaningful but not dominant share of organized cold storage and refrigerated transportation capacity nationwide.
Barriers to entry include high upfront capital requirements for warehousing and reefer fleet assets, the need for multi-city network scale, and the technical expertise required to maintain consistent temperature compliance. These factors favor well-capitalized incumbents with established client relationships and diversified service portfolios.
Consolidation is gradually accelerating as larger logistics groups acquire regional cold storage operators to expand network reach and service depth. Strategic partnerships with food processors, pharmaceutical companies, and quick-commerce platforms are further reinforcing competitive positioning across the organized segment of the market.
Investment & Growth Opportunities
Fastest-Growing Segments
Drugs and pharmaceuticals expand fastest among application segments, driven by growing biologics and vaccine distribution needs. Refrigerated transportation is the fastest-growing type segment, supported by expanding last-mile delivery requirements from quick-commerce and organized retail channels.
Emerging Markets
South India is the fastest expanding region, supported by rising agricultural exports, growing pharmaceutical manufacturing clusters, and expanding quick-commerce infrastructure. The market represents significant untapped opportunity for operators able to deliver region-specific, technology-enabled cold chain services.
Venture & Investment Trends
Investment is concentrated in technology-enabled warehousing platforms, reefer fleet expansion, and last-mile cold chain delivery startups. Capital is also flowing into renewable-powered cold storage and IoT-based monitoring solutions that align with sustainability and compliance priorities across the sector.
Future Market Outlook (2026-2034)
The India cold chain logistics market is forecast to expand from USD 12.56 Billion in 2025 to USD 14.16 Billion in 2026 and is forecast to reach USD 27.45 Billion by 2034, at a CAGR of 8.62%, adding roughly USD 14.89 Billion in incremental market value over the forecast period.
Four forces will shape the market through 2034: growing pharmaceutical and life sciences cold chain requirements; the rise of quick-commerce and organized retail distribution; deeper integration of IoT-based monitoring and automation; and gradual formalization of regional, unorganized cold storage capacity.
By 2034, the India cold chain logistics sector is expected to be defined by technology-enabled, multi-temperature warehousing and increasingly integrated refrigerated transportation networks. Continued infrastructure investment, regulatory emphasis on food and pharmaceutical safety compliance, and expanding organized retail penetration are expected to further accelerate the formalization of the sector.
Research Methodology
Primary Research
Primary research included structured interviews with cold storage operators, reefer fleet executives, food processing and pharmaceutical supply chain managers, and industry association representatives, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included Ministry of Food Processing Industries publications, National Centre for Cold Chain Development reports, state agricultural marketing board data, and annual reports, press releases, and investor presentations from listed logistics operators.
Forecasting Models
Market forecasts used top-down and bottom-up models combining organized cold storage capacity data, reefer fleet growth trends, application-wise demand patterns, and macroeconomic variables. Scenario analysis addressed infrastructure investment pace, energy cost trends, and regulatory compliance timelines.
India Cold Chain Logistics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered |
|
| Applications Covered | Fruits and Vegetables, Bakery and Confectionary, Dairy and Frozen Desserts, Meat, Fish, and Sea Food, Drugs and Pharmaceuticals, Others |
| Regions Covered | North India, South India, East India, West India |
| Comapnies Covered | Gateway Distriparks Limited, Transport Corporation of India Ltd., DHL Group, Gubba Cold Storage Private Limited, Coldman Logistics Private Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India cold chain logistics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India cold chain logistics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India cold chain logistics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Cold Chain Logistics Market Report
The India cold chain logistics market size is estimated at USD 14.16 Billion in 2026, driven by organized retail expansion, pharmaceutical distribution growth, and rising frozen and dairy food consumption.
The market is projected to grow at a CAGR of 8.62% from 2026-2034, reaching USD 27.45 Billion, supported by expanding quick-commerce networks and pharmaceutical cold chain requirements.
Refrigerated warehouses lead at 57.4% in 2025, driven by bulk storage demand from food processors, organized retail chains, and pharmaceutical distributors requiring multi-temperature zone facilities.
Fruits and vegetables dominate at 36.8% in 2025, supported by India's large horticultural output and continued efforts to reduce post-harvest losses through improved cold storage linkages.
North India commands 33.6% share in 2025, led by dense agricultural production and a large base of organized food processing units across Punjab, Haryana, and Uttar Pradesh.
Leading players include Gateway Distriparks Limited, Transport Corporation of India Ltd., DHL Group, Gubba Cold Storage Private Limited, and Coldman Logistics Private Limited, among others.
South India is the fastest-growing region, supported by rising agricultural exports and expanding pharmaceutical manufacturing clusters.
IoT-based temperature monitoring, automated storage systems, and predictive maintenance analytics are helping operators improve compliance, reduce spoilage, and lower operating costs across the cold chain network.
High capital and energy costs, fragmented regional infrastructure, and power reliability challenges in smaller cities continue to constrain the pace of organized cold chain expansion.
Significant opportunities exist in pharmaceutical cold chain expansion and extending organized retail and quick-commerce cold storage networks into tier-2 and tier-3 cities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade