
India Eye Drop Market Size, Share, Trends and Forecast by Type, Drug Class, Disease Indication, Distribution Channel, and Region, 2026-2034
India Eye Drop Market Size, Share, Trends & Forecast (2026-2034)
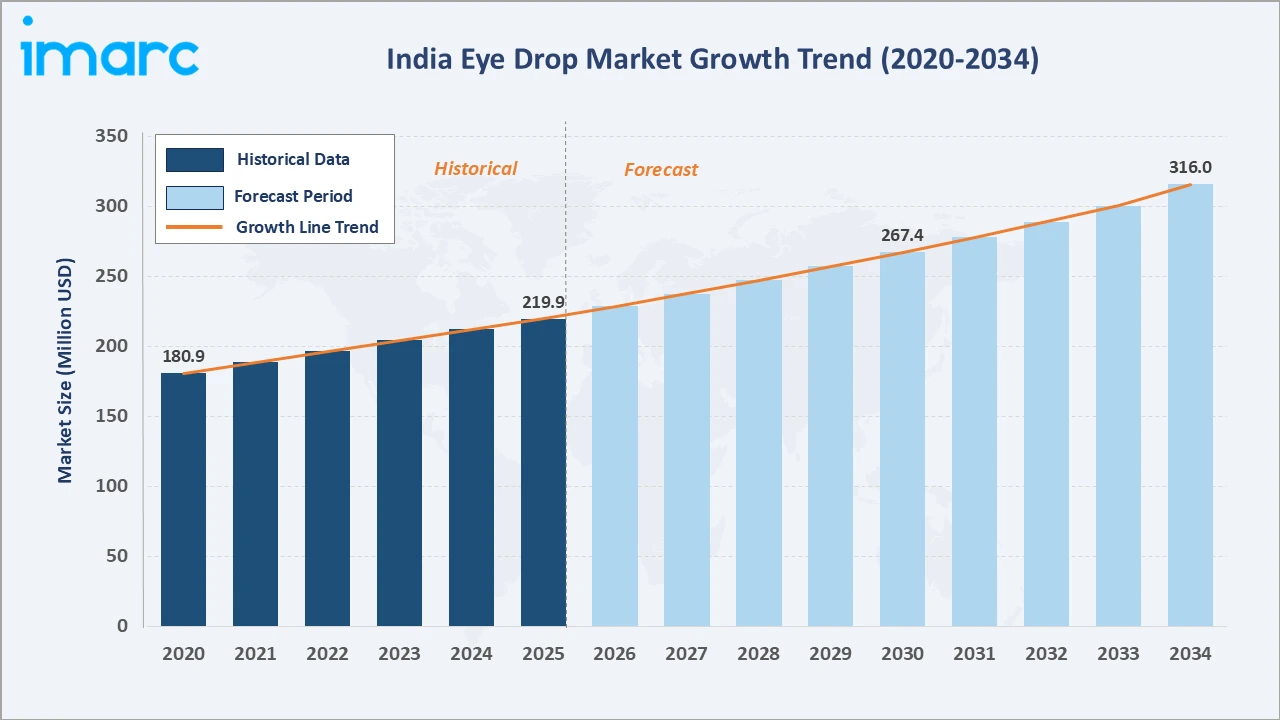
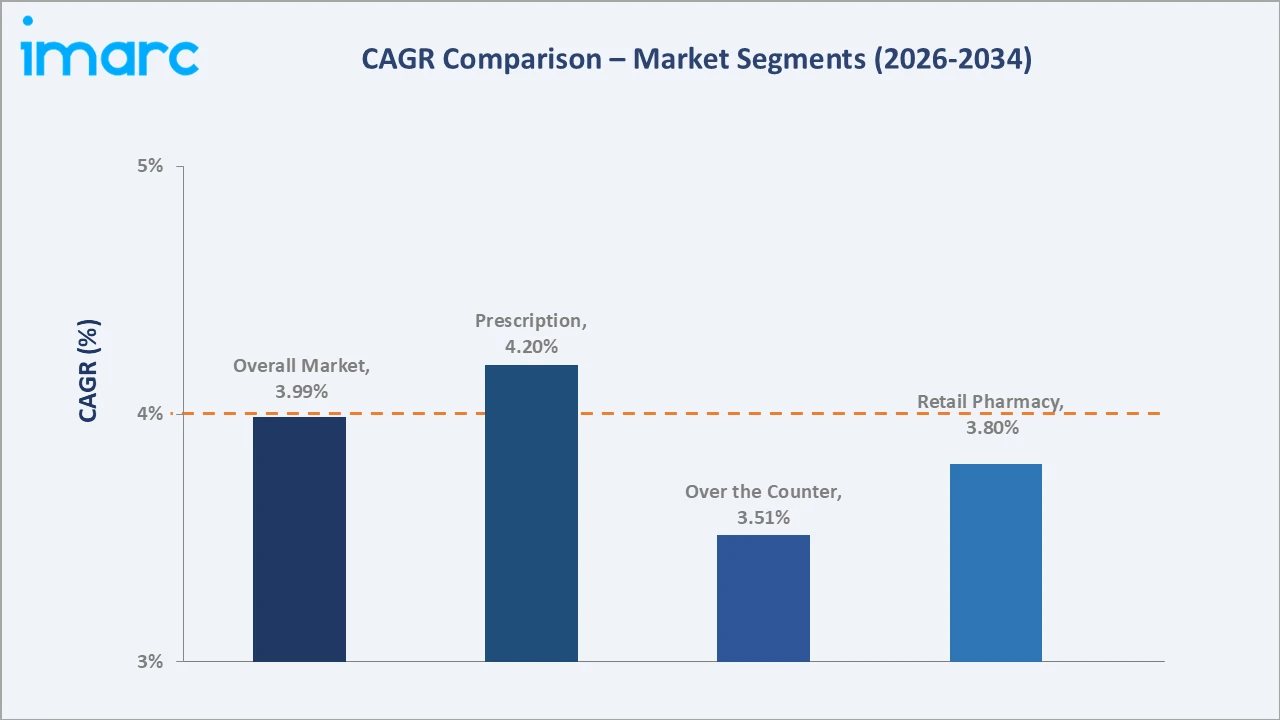
The India eye drop market reached USD 219.9 Million in 2025 and is projected to reach USD 316.0 Million by 2034, growing at a CAGR of 3.99% during 2026-2034. The market is driven by rising eye disorder prevalence, aging demographics, expanding pharmacy infrastructure, and growing awareness of ophthalmic health across India.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 219.9 Million |
|
Forecast Market Size (2034) |
USD 316.0 Million |
|
CAGR (2026-2034) |
3.99% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type Segment |
Prescription (62.7%, 2025) |
|
Dominant Distribution Channel |
Retail Pharmacy (47.8%, 2025) |
|
Leading Region |
North India (27.6%, 2025) |
The India eye drop market expanded from USD 180.9 Million in 2020 to USD 219.9 Million in 2025, anchored at USD 267.4 Million in 2030 and forecast to reach USD 316.0 Million by 2034. Growth is driven by rising ocular disease burden, expanding ophthalmic care access, and increasing pharmacy channel penetration across urban and semi-urban India. The india artificial tears market segment is expanding rapidly as digital device usage rises, contributing meaningfully to OTC lubricant eye drop volumes.
To get more information on this market, Request Sample
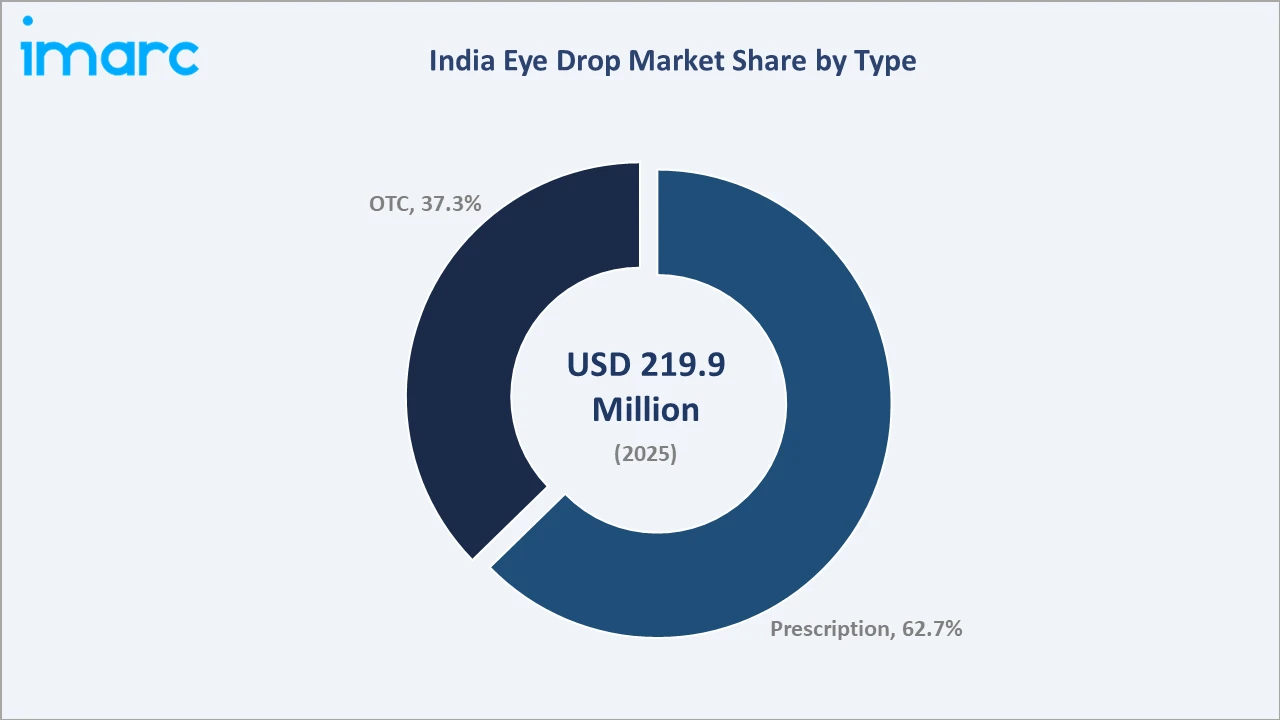
Prescription eye drops led at 62.7% in 2025, driven by clinical management of conditions such as glaucoma, conjunctivitis, and post-surgical care. North India at 27.6% and South India at 26.8% together represent over half the market, underpinned by large urban healthcare infrastructure and high ophthalmic hospital density across major metro centers.
Executive Summary
The India eye drop market reached USD 219.9 Million in 2025, driven by the high prevalence of chronic ophthalmic conditions such as glaucoma, dry eye disease, and cataracts, alongside a growing aging population requiring sustained eye care management. The india artificial tears market is expanding rapidly as digital screen overuse elevates dry eye syndrome prevalence among urban working-age adults, fuelling OTC lubricant formulation demand.
Prescription drops dominated at 62.7%, while over-the-counter formulations at 37.3% expanded with increasing self-medication awareness for dry eye and allergy relief. Retail pharmacy at 47.8% remained the primary dispensing channel. North India led regionally at 27.6%, while South India followed at 26.8% supported by its established ophthalmic hospital networks and high diabetic retinopathy burden.
Key Market Insights
|
Insight |
Data |
|
Dominant Type Segment |
Prescription – 62.7% share (2025) |
|
Dominant Distribution Channel |
Retail Pharmacy – 47.8% market share (2025) |
|
Leading Region |
North India – 27.6% market share (2025) |
|
Key Market Opportunity |
Online pharmacy growth; novel presbyopia drops; generic OTC expansion |
Key Analytical Observations Supporting the Above Data:
- Prescription at 62.7%: The prescription segment dominates as it addresses chronic and acute conditions including glaucoma, post-cataract surgery care, bacterial and viral conjunctivitis, and allergic eye disease. Continued growth in India's diagnosed glaucoma and diabetic retinopathy population will sustain prescription volume expansion through 2034.
- Retail Pharmacy at 47.8%: Retail pharmacy leads distribution through extensive outlet networks in urban and tier-2 cities, enabling easy access to both prescription refills and OTC products, supported by expanding organized chains including Apollo Pharmacy and MedPlus. The channel's strong physician referral linkages reinforce repeat purchase compliance for chronic eye drop users.
- North India at 27.6%: North India leads through the high urban population density of Delhi NCR, elevated pollution-related conjunctivitis and dry eye disease prevalence, and concentration of tertiary ophthalmic hospitals. The region's strong private healthcare ecosystem and high per-capita healthcare spending drive both prescription and OTC eye drop adoption.
India Eye Drop Market Overview
The India eye drop market encompasses the development, manufacturing, and distribution of sterile ophthalmic solutions and suspensions used to treat, prevent, and manage a broad range of eye conditions. Key product categories include anti-infective, anti-inflammatory, antiglaucoma, antiallergic, lubricating, and diagnostic eye drops. The India retinal drugs market is closely linked, as anti-VEGF ophthalmic preparations and retinal disease adjunct therapies represent high-value adjacent prescription segments.
The ecosystem integrates active pharmaceutical ingredient (API) suppliers, ophthalmic formulation manufacturers, contract manufacturing organizations (CMOs), and multi-channel distributors serving retail, hospital, and online pharmacy networks. Regulatory oversight from the Central Drugs Standard Control Organisation (CDSCO) ensures product safety, efficacy, and sterility standards across all market participants.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
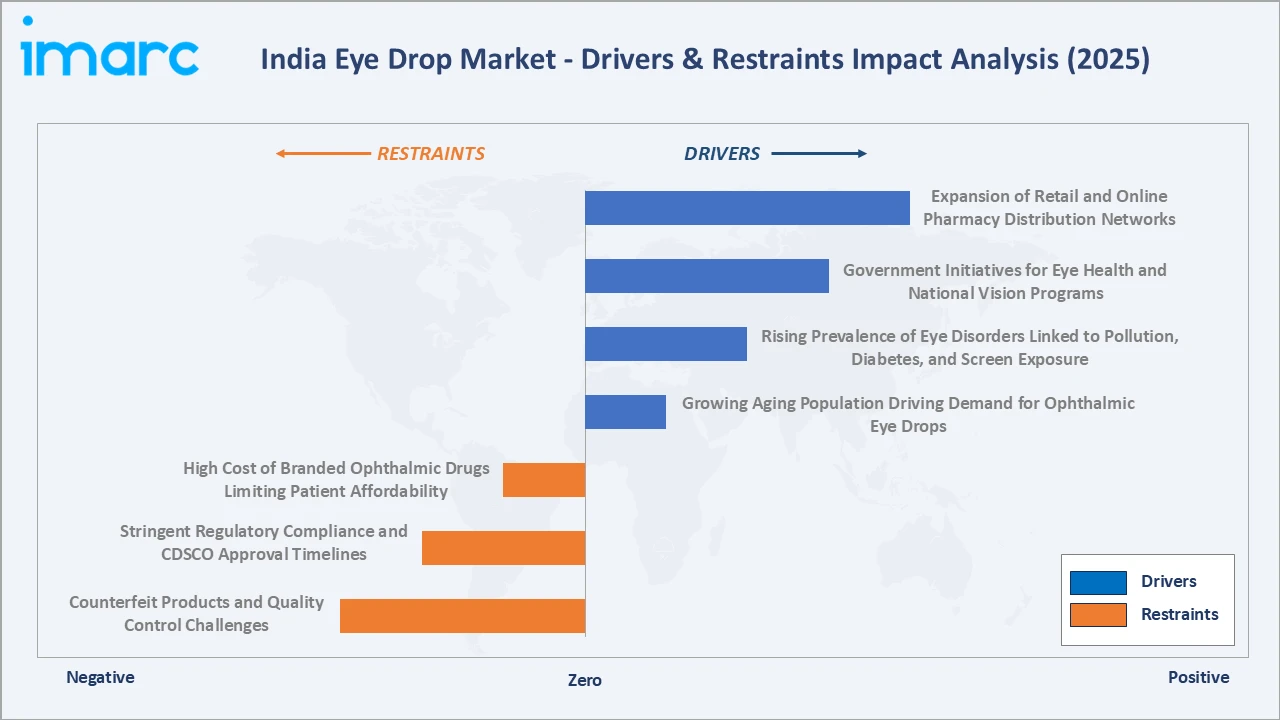
- Growing Aging Population Driving Demand for Ophthalmic Eye Drops: India's elderly population (60+ years) is projected to reach 340 million by 2050, elevating age-related conditions such as cataracts, glaucoma, macular degeneration, and dry eye syndrome, which require continuous ophthalmic therapy. Reduced natural tear production with age further drives demand for lubricant eye drops in India's artificial tears market. Organized healthcare access programs targeting senior citizens across tier-2 cities are expanding first-prescription initiation rates for antiglaucoma and anti-infective eye drops.
- Rising Prevalence of Eye Disorders Linked to Pollution, Diabetes, and Screen Exposure: India has one of the world's highest burdens of diabetic retinopathy, affecting over 18 million people, creating a large addressable patient pool for specialized ophthalmic formulations. Urban air pollution, increasing blue-light screen exposure, and rising diabetes prevalence are compounding annual diagnosis rates for conjunctivitis, dry eye disease, and glaucoma across India. These epidemiological trends collectively underpin the sustained demand growth trajectory for both prescription and OTC eye drops through the forecast period 2026-2034.
- Government Initiatives for Eye Health and National Vision Programs: The National Programme for Control of Blindness and Visual Impairment (NPCBVI) drives rural eye health screening and treatment access, increasing penetration of prescription antiglaucoma and anti-infective eye drops into underserved tier-3 and rural populations. Government subsidy schemes for cataract surgery and glaucoma treatment under Ayushman Bharat indirectly expand the post-surgical eye drop market by increasing the volume of ophthalmological procedures conducted annually. Inclusion of essential ophthalmic formulations in the National List of Essential Medicines (NLEM) improves pricing accessibility and regulatory prioritization for critical eye drop categories.
- Expansion of Retail and Online Pharmacy Distribution Networks: The rapid growth of organized retail pharmacy chains has substantially improved eye drop availability, particularly for recurring OTC lubricant and antiallergy formulations. Online pharmacy platforms are accelerating OTC eye drop accessibility through home delivery, driving above-market CAGR growth for the online distribution channel. Enhanced distribution reach into tier-2 and tier-3 cities through both formats is progressively reducing the historical access gap for prescription eye drops in underserved geographies.
Market Restraints
- High Cost of Branded Ophthalmic Drugs Limiting Patient Affordability: Branded prescription eye drops for chronic conditions such as glaucoma and dry eye impose high recurring costs on Indian patients, many of whom lack comprehensive health insurance coverage for outpatient ophthalmic medications. Cost burden directly impacts patient adherence rates, with a significant proportion of glaucoma patients discontinuing prescribed topical therapy prematurely due to financial constraints, undermining treatment outcomes. Price control under the Drug Price Control Order (DPCO) for some essential ophthalmic categories creates margin pressure on manufacturers, limiting investment in new branded formulation development.
- Stringent Regulatory Compliance and CDSCO Approval Timelines: Ophthalmic products require stringent sterility validation, stability testing, endotoxin testing, and bioequivalence data for regulatory approval, representing a complex and time-intensive compliance pathway for manufacturers. Lengthy CDSCO approval timelines for new formulations and reformulations significantly increase time-to-market, disadvantaging smaller Indian manufacturers with limited regulatory affairs capacity. The requirement for WHO-GMP and Schedule M-compliant cleanroom manufacturing infrastructure imposes high capital expenditure barriers for new entrants to the ophthalmic pharmaceutical segment.
- Counterfeit Products and Quality Control Challenges: The prevalence of substandard and counterfeit ophthalmic products in India's informal market poses significant patient safety risks and erodes brand trust among prescribing ophthalmologists and retail pharmacists. Regulatory enforcement limitations in tier-3 and rural distribution channels enable continued circulation of non-standard ophthalmic preparations that undercut legitimate market pricing while compromising efficacy and sterility. These quality challenges create recurring reputational and liability risks for legitimate market participants and complicate market size tracking across reported and unreported product volumes.
Market Opportunities
- Expansion of Generic Ophthalmic Formulations Post-Patent Expiry: Patent expires on branded antiglaucoma molecules, and anti-infective formulations are creating significant generic market opportunities for Indian pharmaceutical manufacturers, enabling competitive pricing and broader patient access under the NLEM framework. Indian API manufacturers and formulation companies are well-positioned to capture export volumes of generic ophthalmic preparations to regulated markets alongside growing domestic generic demand. Strategic partnerships between domestic manufacturers and global specialty ophthalmic companies for technology licensing represent a key monetization pathway for India's expanding generic ophthalmic capabilities.
- Novel Presbyopia and Advanced Dry Eye Treatment Formulations: Presbyopia treatment drops, following CDSCO approval for the Indian market, represent a new mass-market OTC-adjacent segment targeting India's 550 million people aged 40 and above. Advanced lipid-based and hyaluronic acid lubricant eye drops are gaining rapid share in the Indian retinal drugs market adjacency, expanding the high-margin OTC segment. These novel formulations command premium pricing over commodity lubricants, improving average revenue per unit and overall market value through premiumization.
Market Challenges
- Cold Chain Logistics Requirements for Temperature-Sensitive Ophthalmic Formulations: Many ophthalmic preparations require controlled temperature storage and distribution, creating logistics complexity and incremental cost across India's geographically dispersed pharmacy network. Cold chain infrastructure gaps in tier-3 cities and rural areas constrain the effective distribution reach of temperature-sensitive premium eye drop products, limiting growth in underserved geographies. Investment in cold chain solutions adds operating cost to distributors and retailers, impacting channel profitability and pricing dynamics for temperature-sensitive ophthalmic formulations.
- Patient Non-Compliance with Prescribed Eye Drop Regimens: A significant proportion of Indian glaucoma patients discontinue prescribed topical eye drop therapy within 12 months of initiation, due to side effects, complex dosing schedules, cost burden, and poor understanding of treatment necessity for asymptomatic disease. Non-compliance reduces effective treated-patient volume below the diagnosed population size, creating a gap between potential and realized market demand for antiglaucoma and chronic anti-inflammatory eye drop categories. Behavioural interventions, digital reminder apps, and combination formulations that simplify dosing regimens are critical levers to convert diagnosed patient pools into sustained prescription eye drop users.
Emerging Market Trends
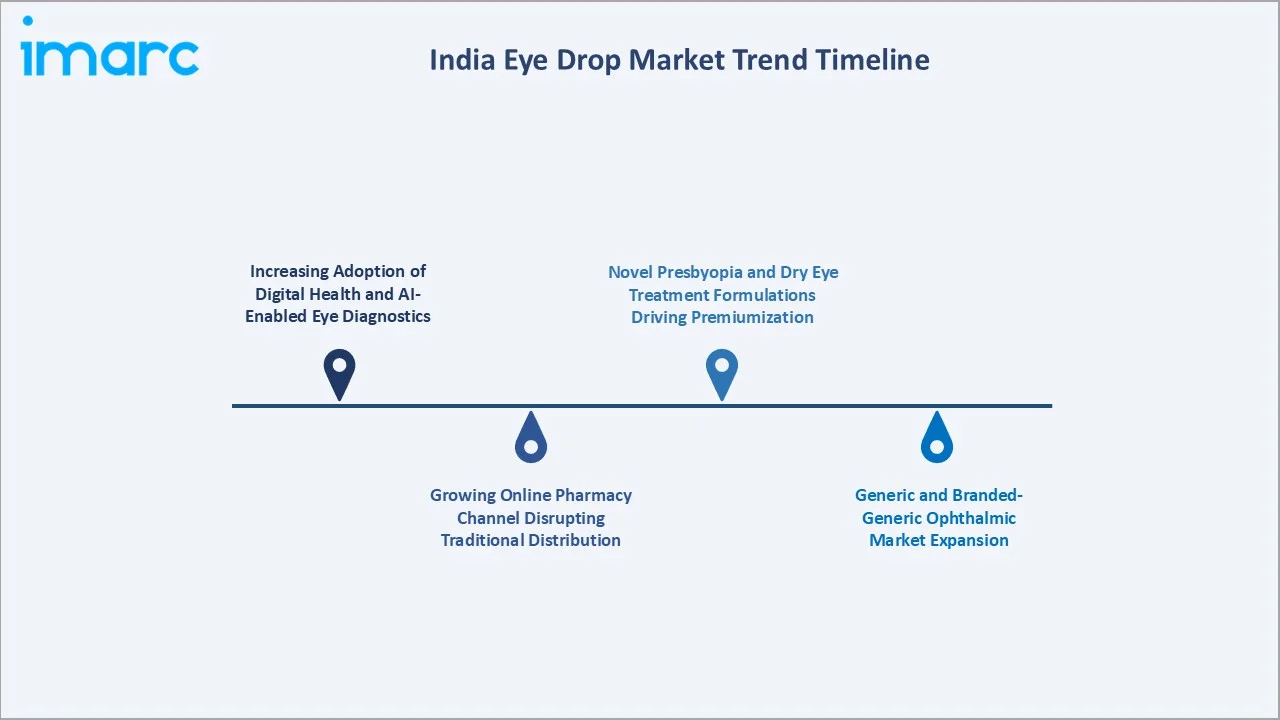
1. Increasing Adoption of Digital Health and AI-Enabled Eye Diagnostics
AI-powered fundus imaging and teleophthalmology platforms are expanding ophthalmic diagnosis reach into rural India, driving early detection of glaucoma, diabetic retinopathy, and dry eye, expanding the diagnosed patient pool and consequently treatment demand for prescription eye drops.
2. Growing Online Pharmacy Channel Disrupting Traditional Distribution
Online pharmacy platforms are accelerating OTC eye drop accessibility through home delivery, particularly for lubricant and antiallergy formulations targeting urban millennials, driving the online channel's above-market growth trajectory through 2034.
3. Generic and Branded-Generic Ophthalmic Market Expansion
Indian manufacturers are aggressively filing ANDAs and domestic CDSCO approvals for generic versions of branded antiglaucoma (prostaglandin analogues), anti-infective, and corticosteroid eye drops, creating a more competitive and price-accessible market for chronic-condition patients across all income levels.
4. Novel Presbyopia and Dry Eye Treatment Formulations Driving Premiumization
Presbyopia treatment drops received CDSCO approval, representing a new OTC-adjacent segment targeting India's large over-40 working population. Advanced lipid-based and hyaluronic acid lubricant formulations are gaining share in the growing dry eye treatment market, enabling premiumization through higher average selling prices.
Industry Value Chain Analysis
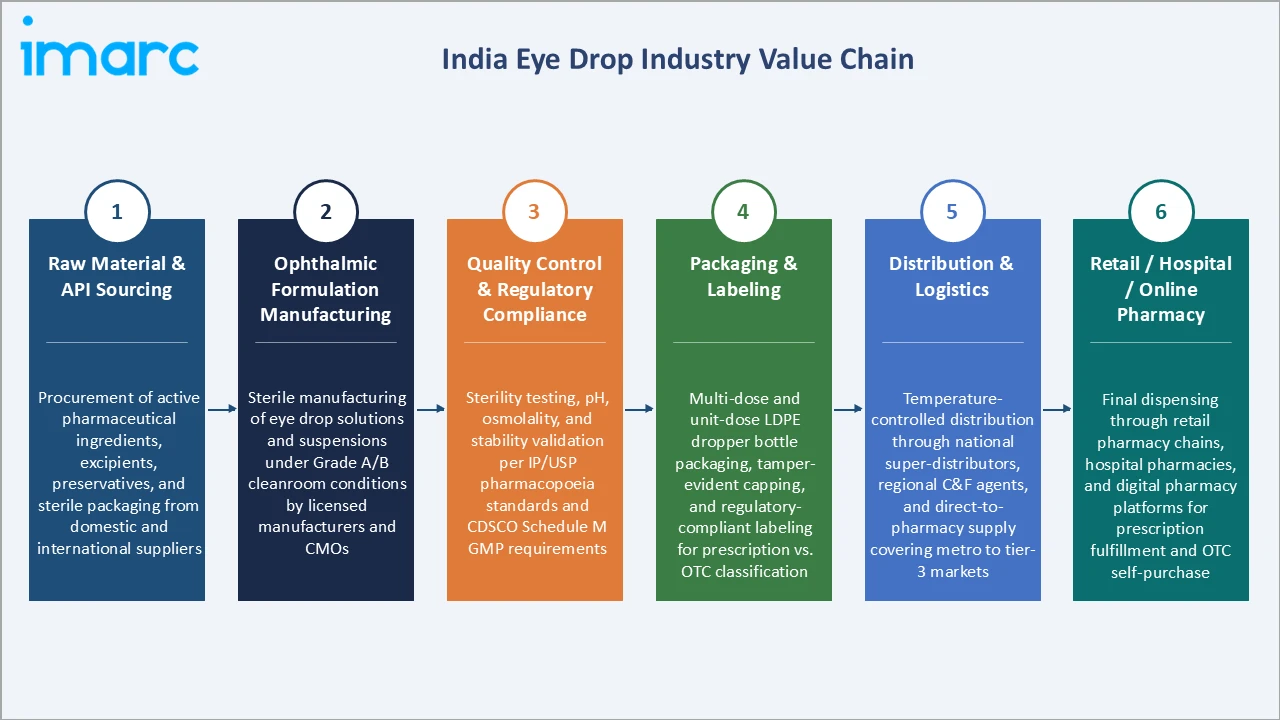
The India eye drop value chain integrates raw material and API sourcing, sterile ophthalmic formulation manufacturing, quality control and regulatory validation, multi-channel distribution, and final patient dispensing. The manufacturing stage is the most compliance-intensive, requiring CDSCO Schedule M-certified cleanroom facilities and rigorous sterility validation.
|
Stage |
Key Activities & Participants |
|
Raw Material & API Sourcing |
Procurement of active pharmaceutical ingredients, excipients, preservatives, and sterile packaging from domestic and international suppliers |
|
Ophthalmic Formulation Manufacturing |
Sterile manufacturing of eye drop solutions and suspensions under Grade A/B cleanroom conditions by licensed manufacturers and CMOs |
|
Quality Control & Regulatory Compliance |
Sterility testing, pH, osmolality, particulate matter, and stability validation per IP/USP pharmacopoeia standards and CDSCO Schedule M GMP requirements |
|
Packaging & Labeling |
Multi-dose and unit-dose LDPE dropper bottle packaging, tamper-evident capping, and regulatory-compliant labeling for prescription vs. OTC classification |
|
Distribution & Logistics |
Temperature-controlled distribution through national super-distributors, regional C&F agents, and direct-to-pharmacy supply covering metro to tier-3 markets |
|
Retail / Hospital / Online Pharmacy |
Final dispensing through retail pharmacy chains, hospital pharmacies, and digital pharmacy platforms for prescription fulfillment and OTC self-purchase |
The distribution and logistics tier is the fastest-evolving segment of the value chain, driven by organized pharmacy expansion and online pharmacy platform growth. Cold chain logistics for temperature-sensitive ophthalmic formulations add structural cost at the distribution tier and create supply chain differentiation for premium manufacturers.
Technology Landscape in the India Eye Drop Industry
Preservative-Free Multi-Dose Delivery Technology
Preservative-free multi-dose ophthalmic containers using airless pump or COMOD delivery systems are gaining adoption in India for chronic dry eye and antiglaucoma therapy, reducing benzalkonium chloride-related ocular surface toxicity and improving long-term patient tolerability and adherence to chronic ophthalmic regimens.
Lipid-Based and Hyaluronic Acid Lubricant Formulations
Advanced ophthalmic emulsion technology using phospholipid-based lipid layer restoration formulations and cross-linked hyaluronic acid polymers is being adopted for high-efficacy dry eye treatment, targeting the premium urban consumer segment experiencing digital-induced eye strain across India's major metros.
Topical Drug Delivery Enhancement Platforms
In April 2024, Entod Pharmaceuticals received CDSCO approval for PresVu (pilocarpine HCl 1.25%), the first presbyopia treatment eye drop approved in India. Nanoemulsion and cyclodextrin-based solubilization technologies are improving bioavailability of poorly soluble ophthalmic APIs, enabling reduced dosing frequency and improved patient adherence for generic ophthalmic formulations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Prescription |
62.7% |
2025 |
|
Drug Class |
🔒 |
🔒 |
2025 |
|
Disease Indication |
🔒 |
🔒 |
2025 |
|
Distribution Channel |
Retail Pharmacy |
47.8% |
2025 |
|
Region |
North India |
27.6% |
2025 |

By Type
Prescription eye drops lead at 62.7% in 2025, encompassing antiglaucoma agents (prostaglandin analogues, beta-blockers), corticosteroids, anti-infectives, anti-VEGF preparations, and post-surgical formulations prescribed by ophthalmologists. The prescription segment commands higher average selling prices and is driven by chronic disease management requirements.
To access detailed market analysis, Request Sample
OTC eye drops at 37.3% encompass lubricants, antihistamines, decongestants, and mild antiseptics. Growth is driven by self-medication for dry eye and allergic conjunctivitis, supported by rising digital health literacy and expanding online pharmacy availability. OTC drops within the india artificial tears market are projected to grow at an above-average CAGR through 2034.
By Distribution Channel
Retail pharmacy at 47.8% remains the dominant distribution channel, leveraging its dense network across urban and semi-urban markets. The organized retail pharmacy segment including Apollo Pharmacy, MedPlus, and Wellness Forever is expanding rapidly, improving product availability and convenience for repeat prescription eye drop purchases across India.
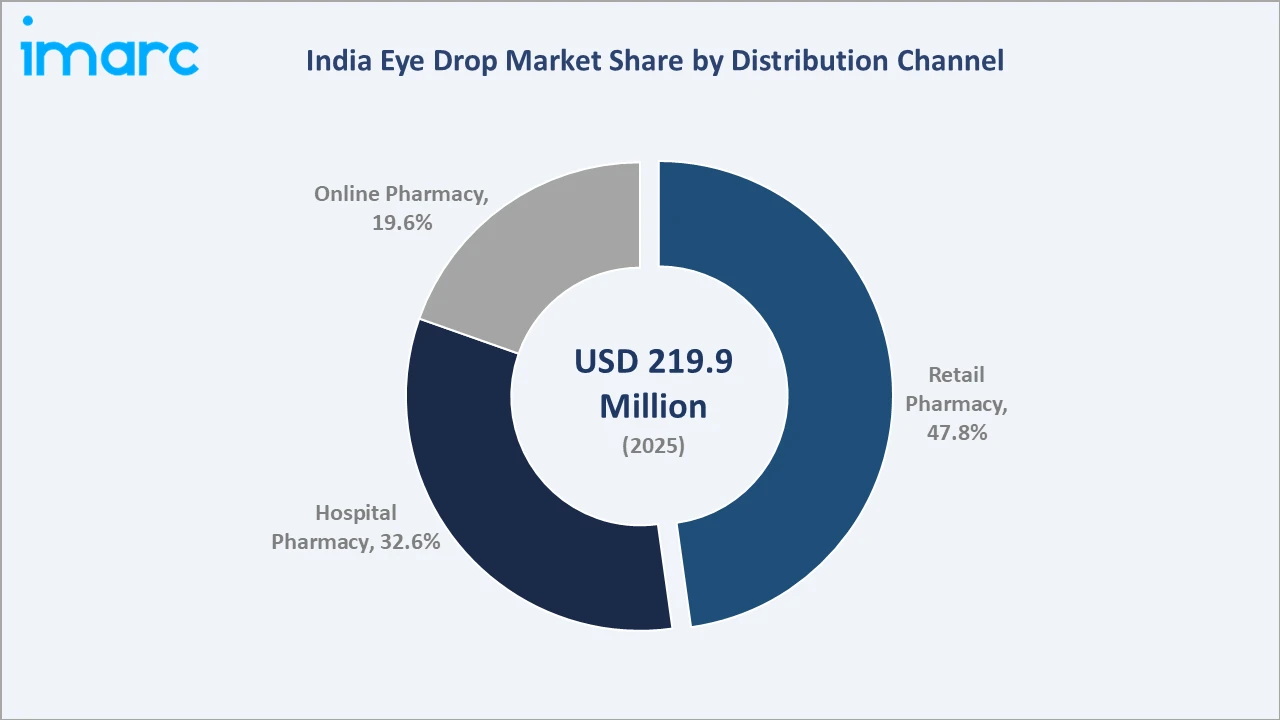
Hospital pharmacy at 32.6% captures the high-value institutional prescription market, particularly for post-surgical eye drops, antiglaucoma therapeutics, and anti-infective preparations dispensed through ophthalmology department channels. Online pharmacy at 19.6% registered the strongest growth rate among all channels, driven by digital adoption and convenience.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
North India |
27.6% |
High urban population density in Delhi NCR, elevated pollution-related eye disorder prevalence, strong tertiary ophthalmic hospital infrastructure, and widespread organized retail pharmacy networks |
|
South India |
26.8% |
Strong ophthalmic hospital density (Aravind Eye Hospitals, Sankara Nethralaya), high diabetic retinopathy burden across Tamil Nadu, Kerala, and Andhra Pradesh, and established ophthalmology practice density |
|
West India |
25.4% |
Maharashtra and Gujarat's large urban healthcare infrastructure, high penetration of private ophthalmology clinics, and Mumbai's position as India's primary pharmaceutical manufacturing and distribution hub |
|
East India |
20.2% |
Growing healthcare infrastructure investment in West Bengal and Odisha, rising awareness of preventable blindness, and increasing government eye health program penetration in rural eastern states |
North India at 27.6% leads the India eye drop market through its high urban density, severe air pollution burden on ocular health, and concentration of tertiary ophthalmic hospitals in Delhi, Noida, and Gurugram. South India at 26.8% reflects the strong ophthalmic care network and high diabetic retinopathy burden across Tamil Nadu, Kerala, and Andhra Pradesh.
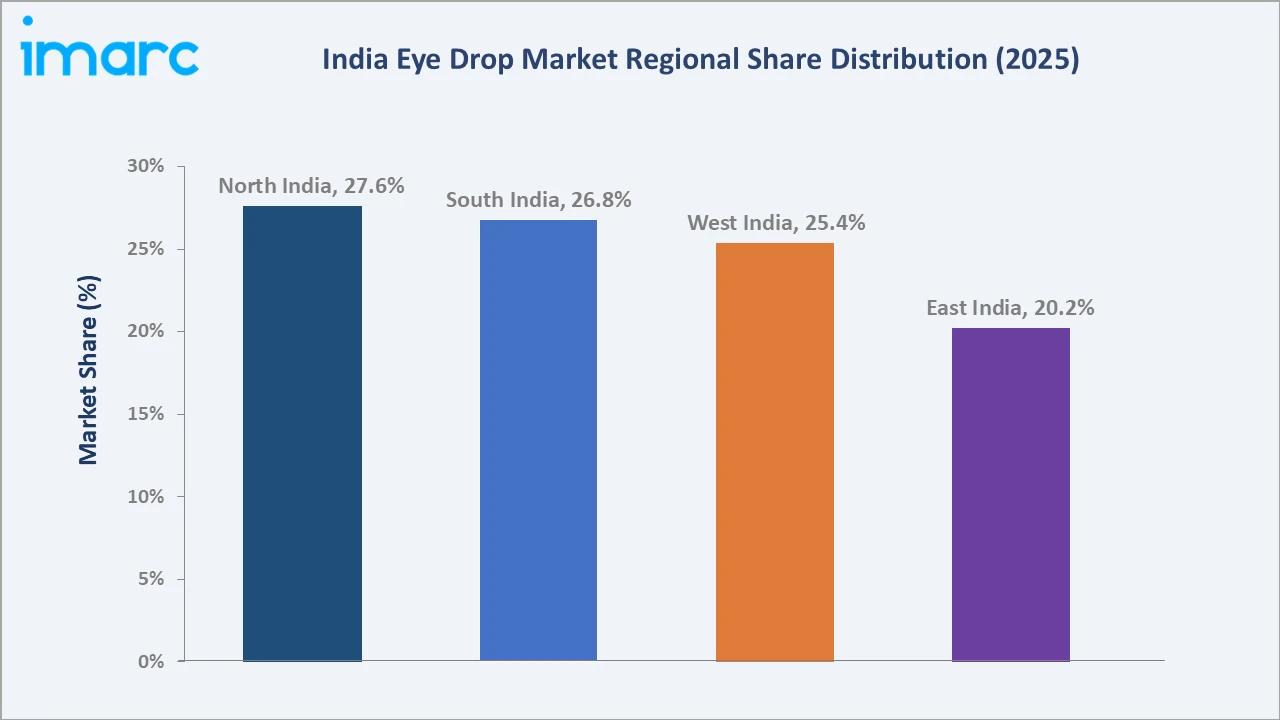
West India at 25.4% benefits from Maharashtra's large ophthalmology practice density, Gujarat's expanding pharmaceutical distribution infrastructure, and Mumbai's role as India's primary pharmaceutical logistics hub. East India at 20.2% represents the market's growth frontier, with increasing government healthcare investment and awareness programs expanding eye care access.
Competitive Landscape
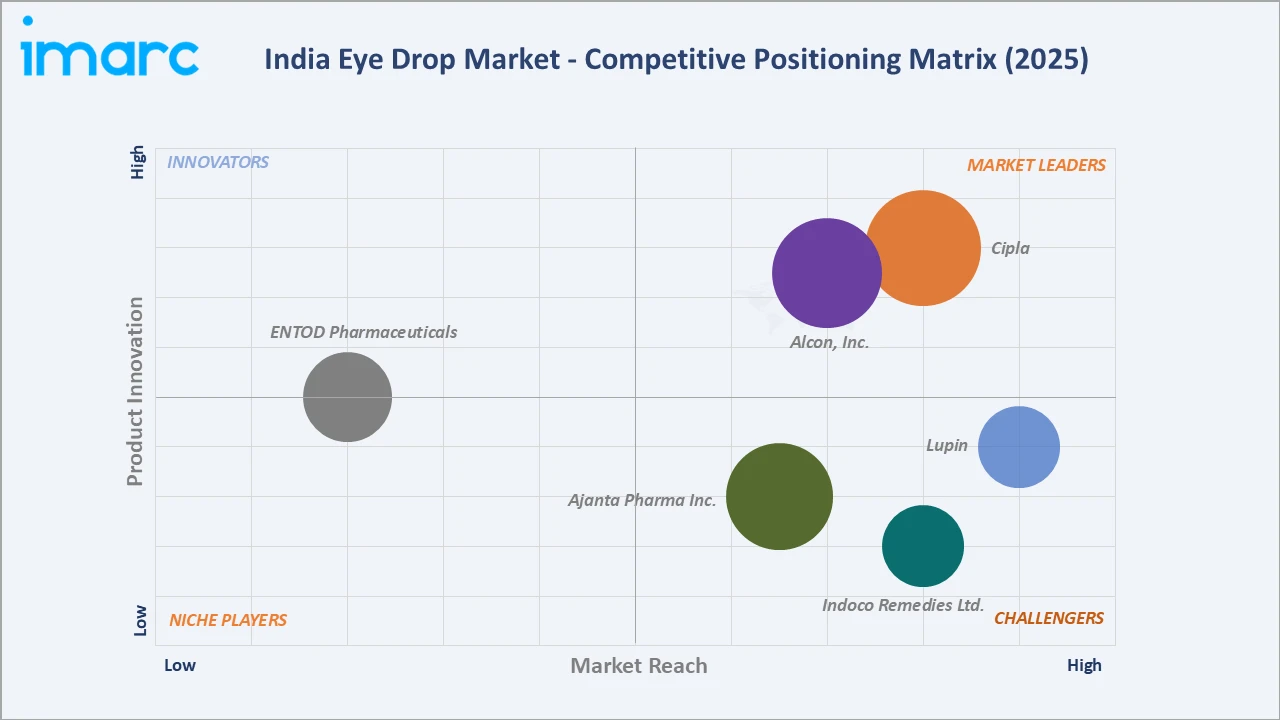
The India eye drop market's competitive landscape is moderately concentrated, with domestic generic manufacturers and multinational specialty ophthalmic companies competing across prescription and OTC segments.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Cipla |
OSMODROPS, IMUDROPS, MOXICIP, NEPCINAC-PRO, ADD TEARS, Gatiquin, LOWPROST, MOXICIP D |
Market Leader |
Strong branded generic ophthalmic portfolio across anti-infective, lubricant, and antiglaucoma categories with wide field force coverage |
|
Alcon Inc. |
Systane Gel Drops, Systane Ultra, Systane HYDRATION, Systane COMPLETE |
Market Leader |
Global ophthalmic leader with premium lubricant and prescription ophthalmic products dominating India's urban specialty market |
|
Lupin |
Autogati, Beipos, Brinzodoc, Hydroeyes – HS, Lacrimos, Lacrimos G |
Strong Challenger |
Growing antiallergy and antiglaucoma ophthalmic product pipeline through domestic CDSCO approvals and ANDA filings |
|
Ajanta Pharma Inc. |
Alcarex, Apdrops, Bidin LS, Brivizac, Bimat |
Strong Challenger |
Specialty ophthalmic manufacturing capability with domestic and export supply for branded generics across anti-infective categories |
|
Indoco Remedies Ltd. |
Latanoprost Eye Drops Solution, Bromfenac Sodium Eye Drops Solution, Travoprost Eye Drops Solution, Azithromycin Eye Drops Solution |
Strong Challenger |
Established ophthalmic manufacturing with a focused product range in anti-infective and anti-inflammatory eye drops |
|
ENTOD Pharmaceuticals |
PresVu, Myatro, Cyclotears, Hyla, Trehatod, Enlube, Megatears |
Emerging Player |
Pioneer of India's first CDSCO-approved presbyopia treatment eye drop with proprietary IP and novel ophthalmic formulation platform |
Key players include Cipla, Alcon Inc., Lupin, Ajanta Pharma Inc., Indoco Remedies Ltd., ENTOD Pharmaceuticals, and others.
Key Company Profiles
Cipla
Cipla is a leading Indian pharmaceutical company with a robust ophthalmic product division addressing anti-infective, antiallergy, lubricant, and antiglaucoma categories under both branded and branded generic strategies across India's retail and institutional pharmacy markets.
- Key Products: OSMODROPS, IMUDROPS, MOXICIP, NEPCINAC-PRO, ADD TEARS, Gatiquin, LOWPROST, MOXICIP D
- Recent Developments: In February 2024, Cipla entered into a collaborative research agreement with CSIR-Central Drug Research Institute (CSIR-CDRI) to jointly develop a novel ophthalmic formulation for the treatment of fungal keratitis. Under the collaboration, Cipla will undertake product scale-up, required studies, and regulatory activities toward potential commercialization.
- Strategic Focus: Strengthening the ophthalmic branded generic portfolio through ongoing CDSCO filings for novel antiglaucoma and dry eye formulations, expanding physician engagement programs in glaucoma and antiallergy segments, and scaling online pharmacy distribution for OTC lubricant and antihistamine eye drops. Cipla is investing in preservative-free formulation technology platforms to differentiate its chronic ophthalmic product range and address the growing patient preference for preservative-free options in antiglaucoma management.
Alcon Inc.
Alcon Inc. is the global leader in eye care, operating a significant India market business in premium lubricant, prescription antiglaucoma, and anti-infective ophthalmic eye drops, with a focus on the urban premium prescription and OTC lubricant segments through retail pharmacy and ophthalmologist referral channels.
- Key Products: Systane Gel Drops, Systane Ultra, Systane HYDRATION, Systane COMPLETE
- Strategic Focus: Premiumization of the dry eye lubricant segment through science-backed product positioning and ophthalmologist recommendation programs, strengthening prescription antiglaucoma market positioning through medical education and clinical data generation, and expanding the ophthalmologist sampling program across India's metro and tier-1 specialty ophthalmic practice networks. Alcon is also evaluating opportunities to expand its India ophthalmic surgical equipment and consumables portfolio in tandem with its eye drop business to create an integrated ophthalmic care commercial presence.
Market Concentration Analysis
The India eye drop market exhibits moderate concentration at the national branded product level. Sun Pharmaceutical Industries Ltd., Cipla Ltd., and Alcon Inc. hold significant market positions in prescription antiglaucoma, anti-infective, and premium lubricant segments, while numerous domestic generic manufacturers compete in commodity ophthalmic categories.
Investment & Growth Opportunities
Highest Growth Segments
Online pharmacy distribution channel, OTC lubricant and antiallergy dry eye category, novel presbyopia treatment eye drops, and preservative-free antiglaucoma formulations represent the highest-growth investment opportunities within the India eye drop market through 2034.
Emerging Investment Opportunities
The presbyopia treatment eye drop segment, following CDSCO approval of pilocarpine HCl 1.25%, represents a large new market opportunity targeting India's 550 million people aged 40 and above. Generic ophthalmic manufacturing for regulated export markets (US FDA, EMA) represents a significant export revenue opportunity for India-based manufacturers leveraging patent cliff timelines.
Investment Themes
- Generic ophthalmic manufacturing capacity expansion: Targeting regulated export markets (US, EU, MENA) alongside growing domestic generic demand post-patent expiry of key antiglaucoma and anti-infective ophthalmic molecules represents a capital-efficient growth strategy for Indian manufacturers with existing sterile manufacturing infrastructure.
- Online pharmacy channel investment and D2C digital marketing: For OTC lubricant and antiallergy eye drops, targeting India's urban millennials experiencing digital eye strain and dry eye symptoms through e-commerce platforms and digital health apps represents a high-ROI channel investment opportunity with scalable reach.
Future Market Outlook (2026-2034)
The India eye drop market is projected to grow from USD 219.9 Million in 2025 to USD 316.0 Million by 2034, delivering a CAGR of 3.99% over the forecast period, with an anchor value of USD 267.4 Million in 2030. Growth will be underpinned by steadily expanding patient pools for chronic eye conditions, increased per-capita ophthalmic care spending, and expanding pharmacy distribution reach into tier-2 and tier-3 cities.
Three structural forces define India eye drop market growth through 2034: rising chronic eye disease diagnosis rates driven by an aging population and increasing diabetes prevalence; digital health and telemedicine infrastructure expanding early ophthalmic diagnosis and treatment initiation; and organized pharmacy expansion improving patient adherence through convenient repeat purchase access across prescription and OTC categories.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders (2025), including ophthalmologists, hospital pharmacy managers, ophthalmic pharmaceutical manufacturers, retail pharmacists, and digital pharmacy buyers, providing direct market intelligence on pricing trends, prescribing patterns, product preferences, and channel dynamics.
Secondary Research
Secondary research encompassed CDSCO drug approval databases, company annual reports and investor presentations, National Programme for Control of Blindness reports, WHO Global Vision 2030 data, IMS Health ophthalmic market data, India diabetes epidemiology reports, and published clinical literature on eye disease prevalence and treatment patterns in India.
Forecasting Models
Market revenue forecasts developed using epidemiology-based bottom-up modelling combining India eye disease patient population estimates, treatment penetration rates by condition, average annual drug cost per treated patient, and pharmacy channel growth projections, validated against historical market size data and cross-checked against industry stakeholder triangulation.
India Eye Drop Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Prescription, Over the Counter |
| Drug Classes Covered | Antiallergy, Anti-Inflammatory, Antiglaucoma, Anti-VEGF, Others |
| Disease Indications Covered | Dry Eye Diseases, Glaucoma, Eye Allergy, Eye Infections, Retinal Disorders, Others |
| Distribution Channels Covered | Hospitals Pharmacy, Retail Pharmacy, Online Pharmacy |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Cipla, Alcon Inc., Lupin, Ajanta Pharma Inc., Indoco Remedies Ltd., ENTOD Pharmaceuticals, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India eye drop market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India eye drop market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India eye drop industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Eye Drop Market Report
The India eye drop market reached USD 219.9 Million in 2025, driven by the prescription segment at 62.7%, retail pharmacy distribution leadership at 47.8%, and North India's regional dominance at 27.6%, supported by rising ocular disease prevalence and expanding pharmacy infrastructure across India.
The India eye drop market grows at a CAGR of 3.99% during 2026-2034, reaching USD 316.0 Million by 2034. This growth reflects aging demographics, rising eye disorder prevalence, pharmacy network expansion, and novel treatment product launches including presbyopia treatment formulations.
Prescription eye drops lead at 62.7% in 2025, driven by chronic condition management requirements including glaucoma, post-cataract surgical care, and severe infective and inflammatory eye disorders that require physician prescription and ongoing clinical monitoring.
Retail pharmacy leads at 47.8% through its extensive urban and semi-urban outlet network, followed by hospital pharmacy at 32.6% and online pharmacy at 19.6%. The online pharmacy channel is growing fastest, driven by digital adoption and home delivery convenience for repeat eye drop purchases.
North India leads at 27.6% through its large urban population, high pollution-related eye disorder prevalence, and strong ophthalmic hospital and retail pharmacy infrastructure, particularly in Delhi NCR, which is India's primary ophthalmic care market.
Key players include Cipla, Alcon Inc., Lupin, Ajanta Pharma Inc., Indoco Remedies Ltd., ENTOD Pharmaceuticals, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade