India Forging Market Size, Share, Trends and Forecast by Technique, Material, Industry, and Region, 2026-2034
India Forging Market Size, Share, Trends & Forecast (2026-2034)
The India forging market grew from USD 5.61 Billion in 2025 to USD 6.12 Billion in 2026 and is projected to reach USD 10.60 Billion by 2034, exhibiting a CAGR of 7.10% during 2026-2034. Rising automotive production and increasing demand for durable metal components are supporting market expansion.
Closed die forging leads the technique segment at 65.0%, steel alloys dominate the material segment at 72.0%, and West India commands 32.0% of regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 5.61 Billion |
|
Market Size (2026) |
USD 6.12 Billion |
|
Forecast Market Size (2034) |
USD 10.60 Billion |
|
CAGR (2026-2034) |
7.10% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
West India (32.0%, 2025) |
|
Second Largest Region |
North India (28.0%, 2025) |
|
Leading Technique |
Closed Die Forging (65.0%, 2025) |
|
Leading Material |
Steel Alloys (72.0%, 2025) |
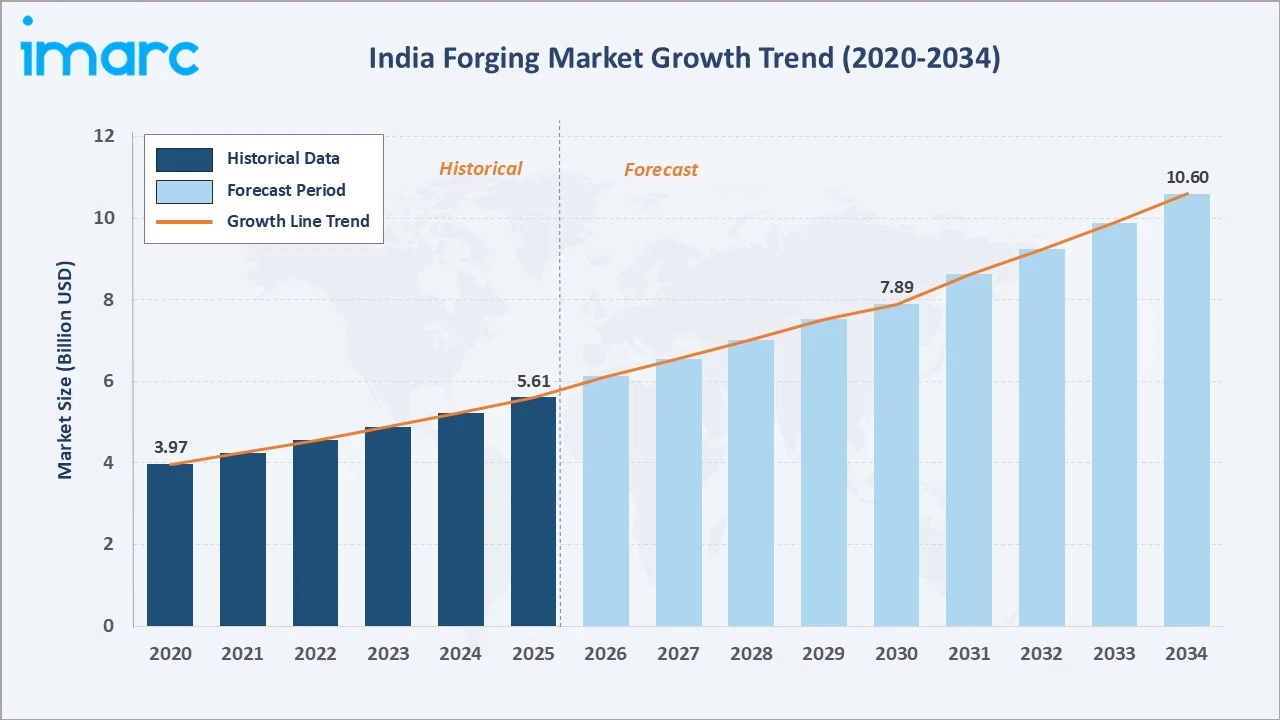
The India forging market size increased from USD 3.97 Billion in 2020 to USD 5.61 Billion in 2025 and is estimated to reach USD 6.12 Billion in 2026. The market is further expected to grow to USD 7.89 Billion by 2030 and USD 10.60 Billion by 2034, as India strengthens its position as a global forging export hub.
To get more information on this market, Request Sample
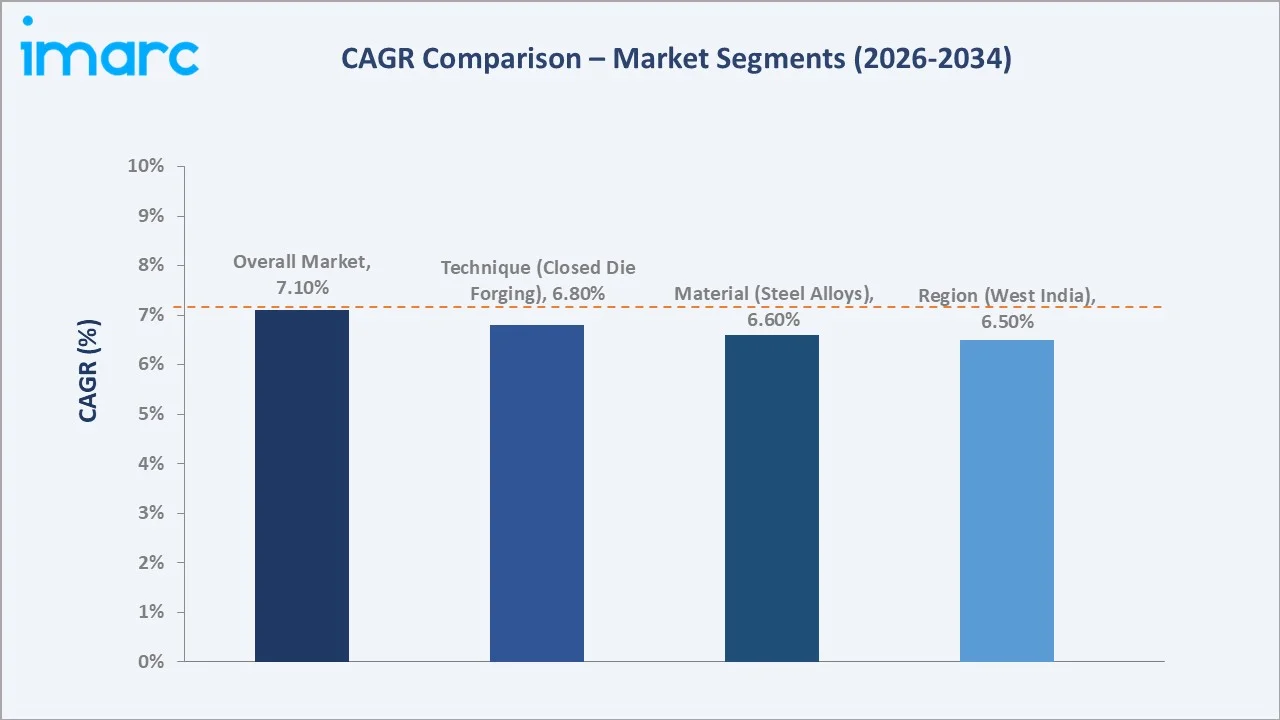
CAGR trajectories across technique and material sub-segments, together with regional patterns, show East India and titanium alloys expanding faster than the overall market rate of 7.10%, driven by increasing industrial activity, infrastructure development, and demand for high-performance forged components across key end-use industries.
Executive Summary
The India forging market expanded from USD 5.61 Billion in 2025 to an estimated USD 6.12 Billion in 2026, positioning it among the largest forging markets in Asia-Pacific by value. The industry has witnessed broad-based expansion, propelled by surging automotive production, large-scale infrastructure investment, and a growing presence in defense and aerospace manufacturing.
Closed die forging leads at 65.0% within the technique segment, driven by its ability to produce complex, high-precision components with consistent quality and material efficiency. Steel alloys retain a commanding 72.0% material share, propelled by their high strength, durability, cost effectiveness, and broad use across automotive and industrial applications. West India accounts for 32.0% of the market, supported by the region’s established automotive and industrial manufacturing base.
Key Market Insights
|
Insight |
Data |
|
Leading Technique |
Closed Die Forging - 65.0% share (2025) |
|
Second Largest Technique |
Open Die Forging - 25.0% share (2025) |
|
Leading Material |
Steel Alloys - 72.0% share (2025) |
|
Second Largest Material |
Aluminum Alloys - 15.0% share (2025) |
|
Leading Region |
West India - 32.0% share (2025) |
|
Second Largest Region |
North India - 28.0% share (2025) |
|
Top Companies |
Bharat Forge Limited, Ramkrishna Forgings Limited, MM Forgings Limited, Happy Forgings Limited |
Key Analytical Observations Expanding On the Data Above:
- Closed die forging dominance at 65.0% reflects widespread adoption in automotive component manufacturing, where tight dimensional tolerances and material efficiency are essential.
- Open die forging at 25.0% remains critical for large industrial components used in oil and gas, power generation, and heavy engineering, where custom geometries and large part sizes exceed closed die press capability.
- Steel alloys at 72.0% underpin the market due to cost efficiency, wide availability, and suitability across automotive, construction, and energy applications.
- Aluminum alloys share at 15.0% reflects growing use in lightweight automotive and transportation components, where weight reduction, corrosion resistance, and favorable strength-to-weight ratios are important.
- West India at 32.0% leads regional share, anchored by Pune’s established auto-component and heavy forging cluster and proximity to major automotive OEMs, Tier-1 suppliers, and western port export infrastructure.
India Forging Market Overview
Forging is a metal-shaping process that uses compressive forces to deform and shape metal workpieces into predetermined forms, producing components with superior mechanical strength compared to casting or machining. The process encompasses closed die, open die, and seamless ring forging techniques, applied across steel, aluminum, nickel, and titanium alloys.
The India forging ecosystem integrates raw material suppliers, billet processors, forging OEMs, machining and finishing units, quality certifiers, and end-use industries spanning automotive, aerospace, oil and gas, power, and construction. The sector is supported by increasing demand for high-strength, lightweight, and precision-engineered components across automotive, aerospace, and industrial applications.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
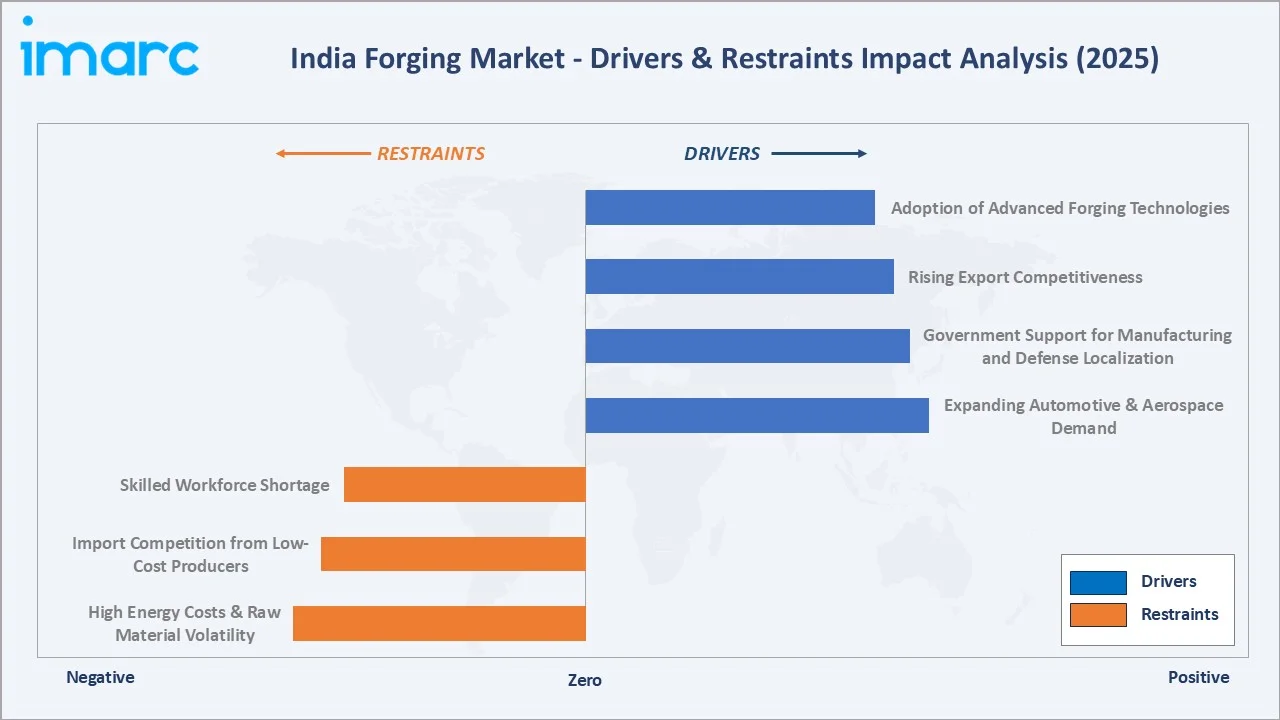
- Expanding Automotive and Aerospace Demand: The forging market in India is benefiting from rising demand across the automotive and aerospace sectors. Rising domestic vehicle production, combined with sourcing from global OEMs, is sustaining strong volume offtake for closed die-forged drivetrain, suspension, and engine components. In March 2026, the combined output of passenger vehicles, three wheelers, two wheelers, and quadricycle reached approximately 2.98 Million units, resulting in a total production of 34.71 Million units for FY26.
- Government Support for Manufacturing and Defense Localization: Government initiatives promoting domestic manufacturing, infrastructure development, and defense indigenization are encouraging investments in forging capacity and supporting local production of critical components.
- Rising Export Competitiveness: Indian forging exporters are capitalizing on cost advantages, improving quality certifications, and greater alignment with global supply chain requirements. Expanding trade relationships with Europe, the United States, and the Middle East are opening new export avenues for precision-forged components.
- Adoption of Advanced Forging Technologies: Growing investment in isothermal forging, CNC-controlled die manufacturing, and simulation-based forging design is enabling Indian manufacturers to produce more complex, tighter-tolerance components, expanding addressable markets in defense and medical devices.
Market Restraints
- High Energy Costs and Raw Material Volatility: Forging is an energy-intensive process requiring high-temperature billet heating. Volatility in electricity tariffs and fuel costs, alongside swings in steel and aluminum prices, compresses margins for small and mid-sized units that lack backward integration or long-term supply contracts.
- Import Competition from Low-Cost Producers: Competition from Chinese and other Asian forging exporters offering lower-priced alternatives, particularly in standard open die and commodity-grade components, limits pricing power for unspecialized Indian manufacturers.
- Skilled Workforce Shortage: Trained forging engineers and die-design specialists remain scarce outside major industrial clusters. This limits rapid capacity expansion and the adoption of advanced forging techniques in smaller manufacturing centers.
Market Opportunities
- EV Component Manufacturing: The transition to EVs is creating demand for new forged component categories, including battery enclosure structures, motor housings, and lightweight suspension parts. Indian forgers with closed die capabilities are well-positioned to supply EV-specific requirements as domestic EV assembly scales.
- Defense and Aerospace Indigenization: Increasing emphasis on domestic defense production and aerospace manufacturing is creating opportunities for Indian forging companies to supply high-strength components for aircraft structures, engines, missiles, and military vehicles. Growing localization of critical components is encouraging investment in advanced forging capabilities and specialized alloy processing.
Market Challenges
- Environmental Compliance and Emission Norms: Stricter emission norms and environmental compliance obligations for forging furnaces and heat treatment facilities are increasing capital expenditure requirements, particularly for older manufacturing units needing upgrades to meet current standards.
- Consolidation Pressure on Smaller Units: Larger OEM customers are consolidating their forging vendor base, preferring suppliers with full-system manufacturing capability, quality certification, and global delivery. This challenges smaller units that lack the scale and certification infrastructure to participate in premium supply chains.
Emerging Market Trends
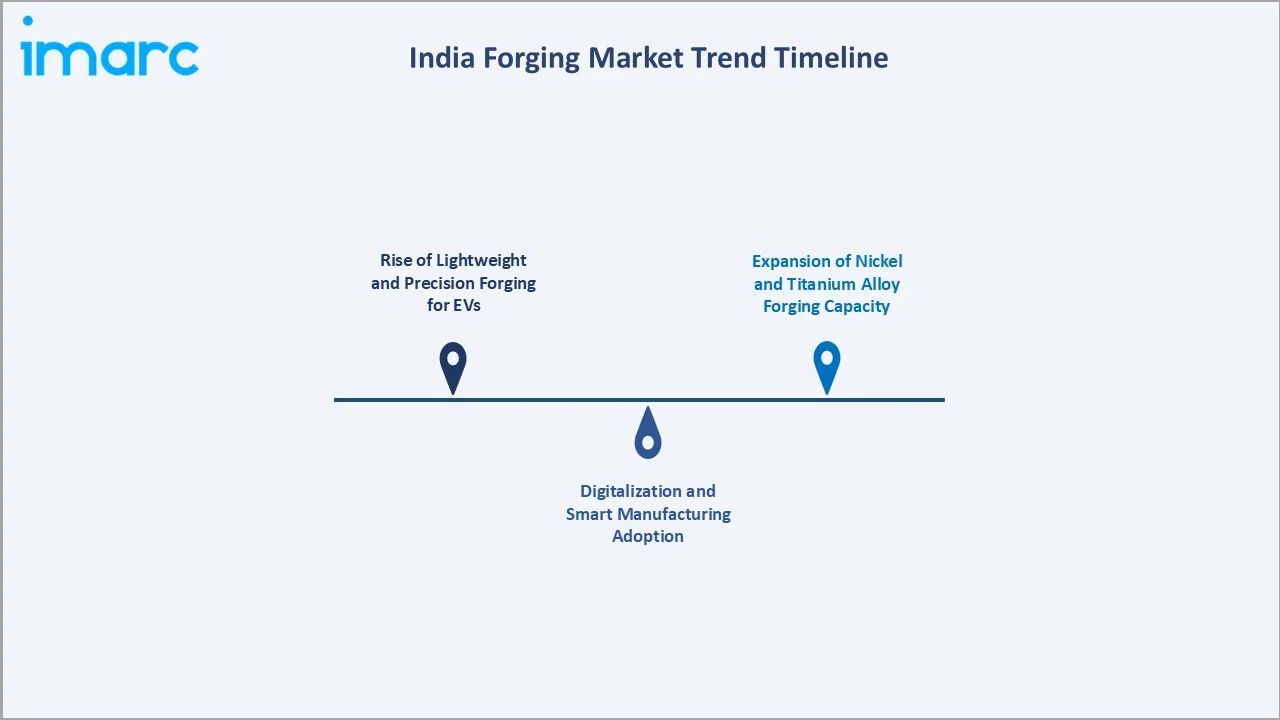
1. Rise of Lightweight and Precision Forging for EVs
The EV transition is prompting a fundamental shift in forging demand from heavy, iron-based powertrain components to lightweight aluminum and titanium forged parts for battery structures and chassis systems. Indian manufacturers are investing in warm and cold forging lines to meet EV platform tolerances.
2. Digitalization and Smart Manufacturing Adoption
Large Indian forging manufacturers are deploying digital forging simulation tools, real-time press monitoring systems, and CNC-controlled die manufacturing equipment to improve process precision and reduce material waste. Adoption of Industry 4.0 practices is accelerating, with leading players integrating manufacturing execution systems and quality data loops to meet the traceability requirements that define competitiveness in the India forging industry.
3. Expansion of Nickel and Titanium Alloy Forging Capacity
Growing demand from aerospace, defense, and high-performance industrial applications is encouraging Indian forging manufacturers to expand capabilities for nickel-based superalloys and titanium alloys. Investments in specialized forging presses, controlled heating systems, and precision process monitoring are enabling production of complex, high-strength components for engines, airframes, and defense platforms. This capacity expansion is also supporting greater domestic sourcing of critical alloy components.
Industry Value Chain Analysis
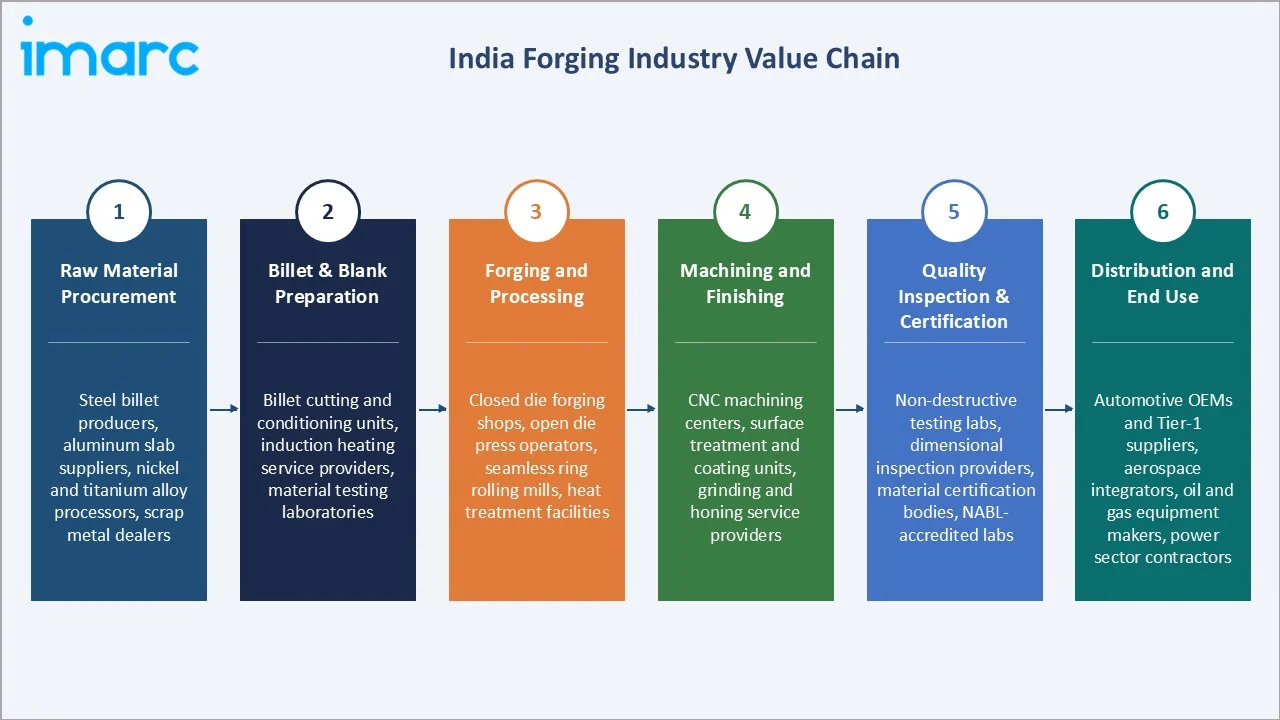
The India forging industry value chain spans six core stages, from upstream raw material procurement through end-use delivery and lifecycle management. Integration across these stages determines a manufacturer’s ability to control costs, ensure quality, and respond to OEM requirements with speed and flexibility.
|
Stage |
Key Players / Examples |
|
Raw Material Procurement |
Steel billet producers, aluminum slab suppliers, nickel and titanium alloy processors, scrap metal dealers |
|
Billet and Blank Preparation |
Billet cutting and conditioning units, induction heating service providers, material testing laboratories |
|
Forging and Processing |
Closed die forging shops, open die press operators, seamless ring rolling mills, heat treatment facilities |
|
Machining and Finishing |
CNC machining centers, surface treatment and coating units, grinding and honing service providers |
|
Quality Inspection and Certification |
Non-destructive testing labs, dimensional inspection providers, material certification bodies, NABL-accredited labs |
|
Distribution and End Use |
Automotive OEMs and Tier-1 suppliers, aerospace integrators, oil and gas equipment makers, power sector contractors |
Vertically integrated forging manufacturers, particularly those managing raw material sourcing, forging, and in-house machining, capture more margin across the chain and respond better to OEM just-in-time requirements. India’s top forging groups are progressively moving toward full-service supply capability.
Technology Landscape in the India Forging Industry
Closed Die and Precision Forging Technology
Advanced closed die forging lines with high-tonnage mechanical and hydraulic presses are enabling Indian manufacturers to produce near-net-shape components with tighter tolerances and lower post-forging machining requirements. Computer-controlled die-sink EDM and forging simulation software are being adopted to reduce die design cycles and improve first-time-right production rates.
Isothermal and Warm Forging
Isothermal forging, which maintains workpiece temperature throughout deformation to enable forging of difficult alloys, is being adopted by manufacturers supplying aerospace-grade titanium and nickel-based components. Warm forging is gaining use in aluminum alloy component production for automotive and EV applications requiring complex geometries with high dimensional consistency, a trend that is directly expanding the forging market size in India.
Automation and Process Control
Robotic billet handling, automated die lubrication systems, and in-line quality monitoring using vision-based inspection and laser measurement are being deployed across high-volume forging lines. These technologies reduce operator dependency, lower scrap rates, and support the quality traceability requirements of global Tier-1 customers.
Digital Forging Simulation
Finite element analysis and digital twin-based forging simulation tools allow manufacturers to optimize die geometry, process parameters, and material flow before committing to physical die production. This reduces die design iterations, shortens new product development timelines, and improves die life, lowering unit tooling costs.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Technique | Closed Die Forging | 65.0% |
2025 |
| Material | Steel Alloys | 72.0% |
2025 |
| Industry | 🔒 | 🔒 | 2025 |
|
Region |
West India | 32.0% |
2025 |

By Technique
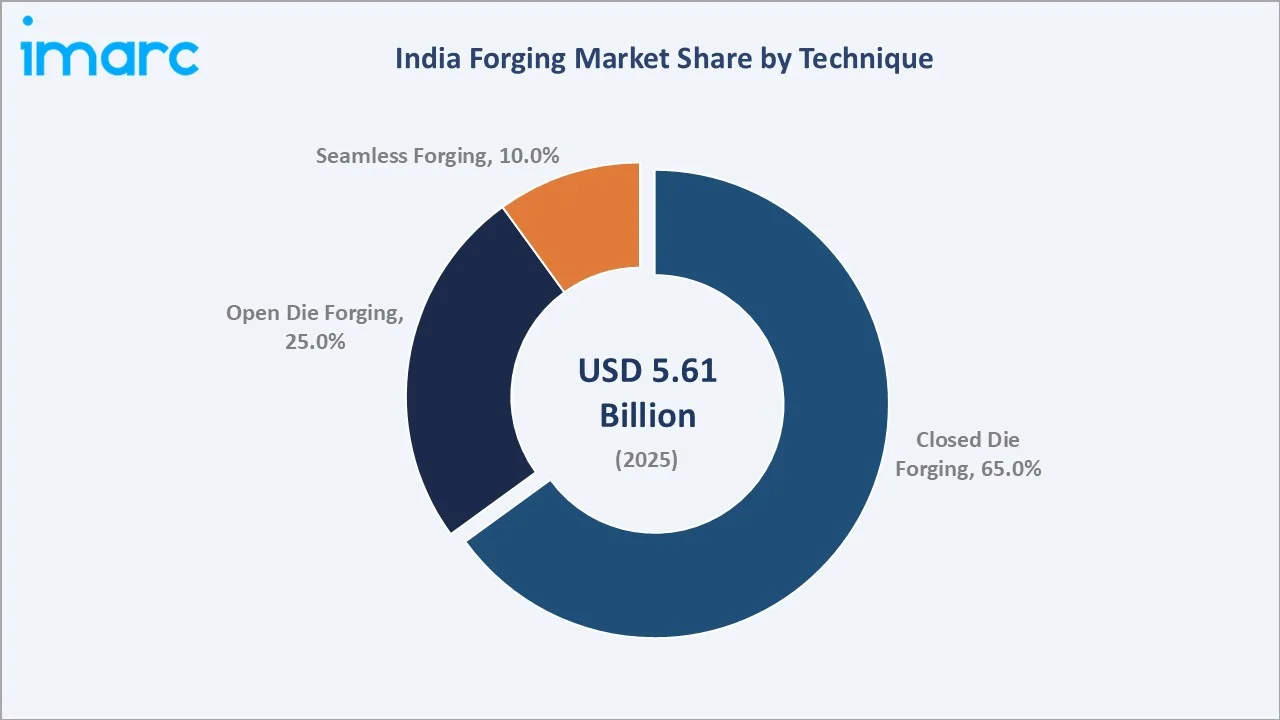
Closed die forging commands a 65.0% majority share in 2025, driven by high-volume production of automotive crankshafts, connecting rods, gears, and steering knuckles, where dimensional precision and material strength are essential. The process delivers superior material utilization and repeatability compared to open die methods.
To access detailed market analysis, Request Sample
Open die forging at 25.0% in 2025 serves large industrial and energy-sector requirements including turbine shafts, pressure vessel flanges, mill rolls, and marine propulsion components, where part sizes exceed closed die press capability.
By Material
Steel alloys retain a 72.0% dominant share in 2025, reflecting their cost effectiveness, wide alloy availability, and suitability for high-stress structural and mechanical applications.
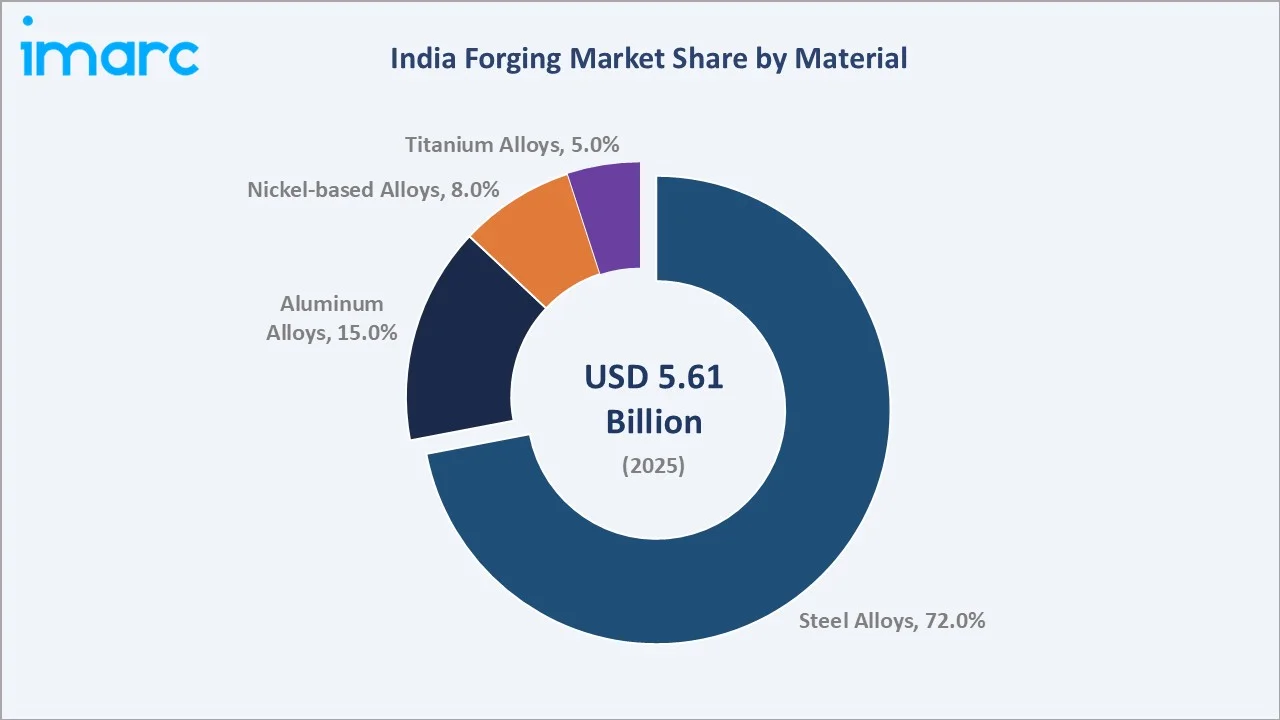
Aluminum alloys at 15.0% represent the second largest segment, driven by lightweighting mandates in automotive and rising EV-specific structural component volumes.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| West India | 32.0% | Dense automotive OEM and Tier-1 supplier base, established forging cluster in Pune, strong export linkages through western ports |
| North India | 28.0% | Large tractor, commercial vehicle, and industrial equipment manufacturing base in Ludhiana and Faridabad |
| South India | 25.0% | Expanding automotive and aerospace manufacturing in Chennai and Bengaluru, rising defense component demand |
| East India | 15.0% | Growing steel production capacity, new industrial corridors, state manufacturing incentives, emerging forging cluster development |
West India at 32.0% in 2025 leads the regional landscape, anchored by Pune’s status as India’s premier auto-component manufacturing hub and home to a high concentration of closed die forging specialists supplying both domestic OEMs and export markets. Mumbai’s port infrastructure and industrial linkages further strengthen the region’s supply chain efficiency.
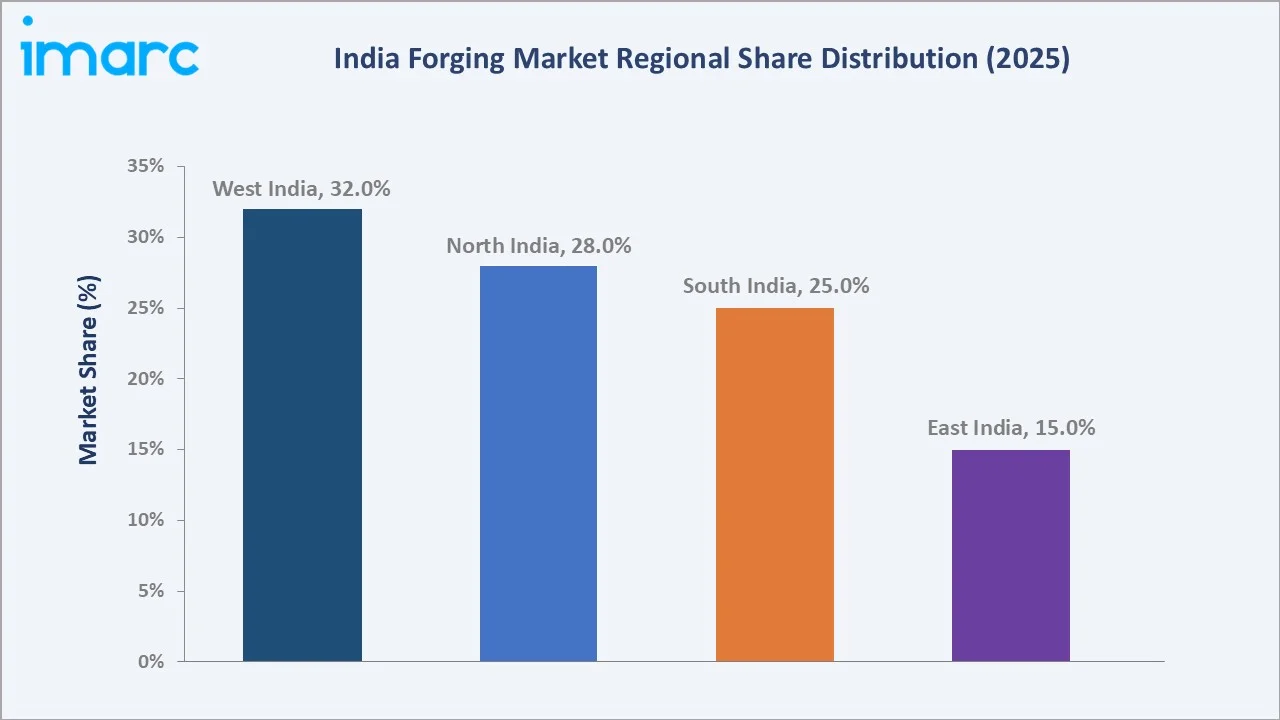
North India at 28.0% is supported by Ludhiana and Faridabad, which house large open die and alloy steel forging clusters serving tractor, commercial vehicle, and industrial equipment manufacturers.
Competitive Landscape
The India forging market is moderately concentrated, with a small number of large integrated manufacturers holding significant market share while a large population of small and mid-sized units serve niche and regional requirements. Leading players compete on forging press capacity, material and technique diversification, quality certifications, and global customer relationships.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| Bharat Forge Limited | Front Axle Beams & Crankshafts | Leader | Expanding precision forging capabilities across automotive, aerospace, and defense through technology investment and global partnerships |
| Ramkrishna Forgings Limited | RKFL | Leader | Strengthening closed die forging capacity for automotive and railway component supply to domestic and export markets |
| MM Forgings Limited | Closed Die Hot Forgings | Leader | Expanding closed die forging capacity for heavier components and deepening export relationships with North American and European OEMs |
| Happy Forgings Limited | Happy Forgings | Challenger | Scaling forging capacity in commercial vehicle and farm equipment segments through targeted capacity addition |
Key players include Bharat Forge Limited, Ramkrishna Forgings Limited, MM Forgings Limited, and Happy Forgings Limited, among others.
Key Company Profiles
Bharat Forge Limited
Bharat Forge Limited is a Pune, Maharashtra-based manufacturer specializing in forged and machined components for automotive, aerospace, defense, and industrial applications. The company operates integrated forging and machining facilities and supplies engineered components to domestic and international customers.
- Product Portfolio: Forged crankshafts and aerospace structural components in steel and aluminum alloys.
- Recent Developments: The company has undertaken capacity expansion initiatives across its manufacturing facilities and broadened its product range to serve both domestic and international customers across multiple end-use sectors.
- Strategic Focus: Advancing high-value forging capabilities across aerospace, defense, and EV component segments while broadening global original equipment manufacturer supply partnerships.
Ramkrishna Forgings Limited
Ramkrishna Forgings Limited is an Indian manufacturer of forged components for the commercial vehicle, passenger car, and industrial sectors, headquartered in Kolkata, West Bengal. The company operates closed die and open die forging facilities, supplying domestic and international automotive OEMs and Tier-1 suppliers.
- Product Portfolio: Closed die-forged axle shafts, crankshafts, connecting rods, and railway wheel and axle components in carbon and alloy steels.
- Recent Developments: The company has been progressively expanding its manufacturing capacity and strengthening its customer base across domestic and international markets.
- Strategic Focus: Reinforcing closed die forging output for commercial vehicle and railway component supply while intensifying penetration into international export markets.
MM Forgings Limited
MM Forgings Limited is a Chennai-based manufacturer of closed die hot forgings, supplying domestic and international customers in the automotive, commercial vehicle, agriculture, off-highway, oil and gas, and industrial machinery sectors.
- Product Portfolio: Closed die hot forgings including crankshafts, axle beams, steering knuckles, yokes, sprockets, and high-pressure valve bodies in carbon, alloy, micro-alloy, and stainless steel grades.
- Recent Developments: The company has been investing in manufacturing infrastructure and adding new production capabilities to serve a growing range of domestic and export customers.
- Strategic Focus: Scaling closed die hot forging capacity for progressively heavier and more complex components while strengthening long-term supply relationships with North American and European automotive OEMs.
Market Concentration Analysis
The India forging market exhibits a moderate level of concentration. Established manufacturers benefit from long-standing OEM relationships, established production infrastructure, and technical capabilities across multiple forging processes and material grades.
Barriers to entry include the capital intensity of forging press installation, the expertise required for die design and metallurgical process management, and the certification requirements of key end-use sectors such as automotive, aerospace, and defense. These factors limit new entrant competition at the premium end of the market.
Consolidation is gradually increasing as larger manufacturers acquire or establish joint ventures with smaller regional units to access new geographies, product niches, or customer bases. Export pressure and OEM vendor rationalization are further accelerating market concentration at the organized sector level.
Investment & Growth Opportunities
Fastest-Growing Segments
Titanium alloys represent the highest-growth material segment, driven by expanding aerospace and defense procurement programs. Among techniques, seamless forging is emerging as a high-growth niche due to expanding oil and gas and nuclear power infrastructure requirements.
Emerging Markets
East India is the fastest growing regional market, with state-level manufacturing incentives, new steel production capacity, and emerging industrial corridor development creating new forging demand centers beyond the established clusters in West and North India. The region’s growth is also supported by proximity to eastern port infrastructure, which supports export logistics.
Venture & Investment Trends
Investment is concentrated in high-tonnage precision press lines, automation and robotics for material handling, and simulation-based die design infrastructure. Capital is also flowing into material diversification, particularly non-ferrous and specialty alloy forging capacity, to serve the growing aerospace, EV, and defense segments. PLI scheme disbursements are de-risking capacity investment for qualifying manufacturers.
Future Market Outlook (2026-2034)
The India forging market is projected to grow from USD 5.61 Billion in 2025 to USD 6.12 Billion in 2026, reaching USD 10.60 Billion by 2034, registering a CAGR of 7.10% during 2026-2034. The market is set to add roughly USD 5 Billion in incremental value over the forecast period.
Four forces will shape the market through 2034: continued automotive platform expansion including EVs; rising defense and aerospace localization demand; government-backed manufacturing incentives supporting capacity investment; and growing global supply chain interest in India as a cost-competitive, high-quality forging source.
By 2034, forging in India is expected to be defined by a higher mix of precision closed die and lightweight alloy components, a larger share of export revenue in total output, and greater integration of digital manufacturing tools. Manufacturers investing now in technology, quality systems, and product diversification are best positioned to capture disproportionate growth.
Research Methodology
Primary Research
Primary research included structured interviews with forging industry executives, die design engineers, automotive OEM procurement managers, and export market development specialists. Insights from forging equipment suppliers, metallurgical testing laboratories, and industry association representatives were incorporated to validate market sizing estimates and sector trend assessments.
Secondary Research
Secondary sources included Ministry of Steel publications, Commerce Ministry export statistics, SIAM automotive production data, DRDO and HAL annual reports, company filings, and trade publication data from forging industry journals and technical conferences.
Forecasting Models
Market forecasts used top-down and bottom-up models combining automotive production volume projections, infrastructure investment pipeline data, export order trends, capacity utilization estimates, and macroeconomic indicators. Both demand-side and supply-side inputs were cross-validated against historical growth trajectories and sector-specific investment data.
India Forging Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Techniques Covered | Closed Die Forging, Open Die Forging, Seamless Forging |
| Materials Covered | Nickel-based Alloys, Titanium Alloys, Aluminum Alloys, Steel Alloys |
| Industries Covered | Automotive, Aerospace, Railway, Heavy Equipment, Wind Power |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Bharat Forge Limited, Ramkrishna Forgings Limited, MM Forgings Limited, Happy Forgings Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India forging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India forging market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India forging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Forging Market Report
The India forging market size is estimated at USD 6.12 Billion in 2026, driven by strong automotive demand, infrastructure investment, and growing defense and aerospace procurement.
The market is projected to grow at a CAGR of 7.10% from 2026-2034, reaching USD 10.60 Billion, supported by automotive production growth, EV component demand, and rising export volumes.
Closed die forging leads with 65.0% share in 2025, driven by high-volume automotive and precision engineering component manufacturing where dimensional consistency is critical.
Steel alloys dominate with 72.0% share in 2025, reflecting their cost efficiency and wide applicability across automotive, construction, and industrial end-use segments.
West India commands 32.0% share in 2025, led by Pune’s concentration of automotive and forging manufacturers and strong export linkages through western port infrastructure.
Leading players include Bharat Forge Limited, Ramkrishna Forgings Limited, MM Forgings Limited, and Happy Forgings Limited, among others.
Key drivers include expanding automotive production, government PLI incentives, rising export orders, infrastructure investment, and increasing aerospace and defense localization requirements.
EV growth is shifting forging demand toward lightweight aluminum and titanium alloy components for battery structures and chassis systems, creating new product opportunities for manufacturers with non-ferrous forging capability.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade