India Geotextiles Market Size, Share, Trends and Forecast by Type, Material, Application, and Region, 2026-2034
India Geotextiles Market Size, Share, Trends & Forecast (2026-2034)
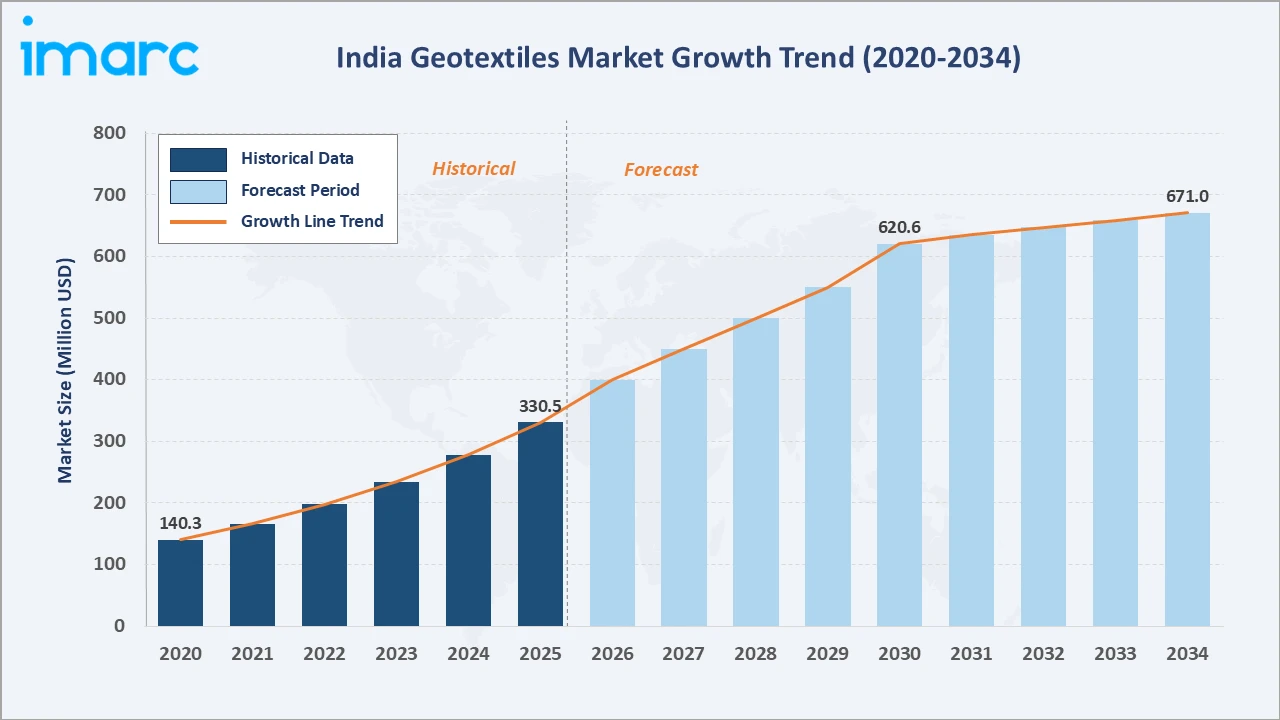
The India geotextiles market grew from USD 330.5 Million in 2025 to USD 364.1 Million in 2026 and is projected to reach USD 671.0 Million by 2034, growing at a CAGR of 7.94% during 2026-2034. India allocated approximately USD 133 Billion (INR 11 lakh crore) to infrastructure development in the Union Budget 2024-25, driving sustained demand for geotextiles across road construction, erosion control, drainage, and soil stabilization applications. Non-woven geotextiles lead at 52.8% in 2025, polypropylene dominates the material segment at 58.4%, and North India commands the largest regional share at 30.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 330.5 Million |
|
Market Size (2026) |
USD 364.1 Million |
|
Forecast Market Size (2034) |
USD 671.0 Million |
|
CAGR (2026-2034) |
7.94% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Non-Woven (52.8%, 2025) |
|
Dominant Material |
Polypropylene (58.4%, 2025) |
|
Leading Region |
North India (30.8%, 2025) |
The India geotextiles market grew from USD 140.3 Million in 2020 to USD 330.5 Million in 2025 to USD 364.1 Million in 2026, driven by accelerating infrastructure investment, expanding road construction programs, and growing awareness of geotextile benefits in erosion control and drainage management across civil engineering projects. The market is projected to reach USD 620.6 Million by 2030 before reaching USD 671.0 Million by 2034.
To get more information on this market, Request Sample
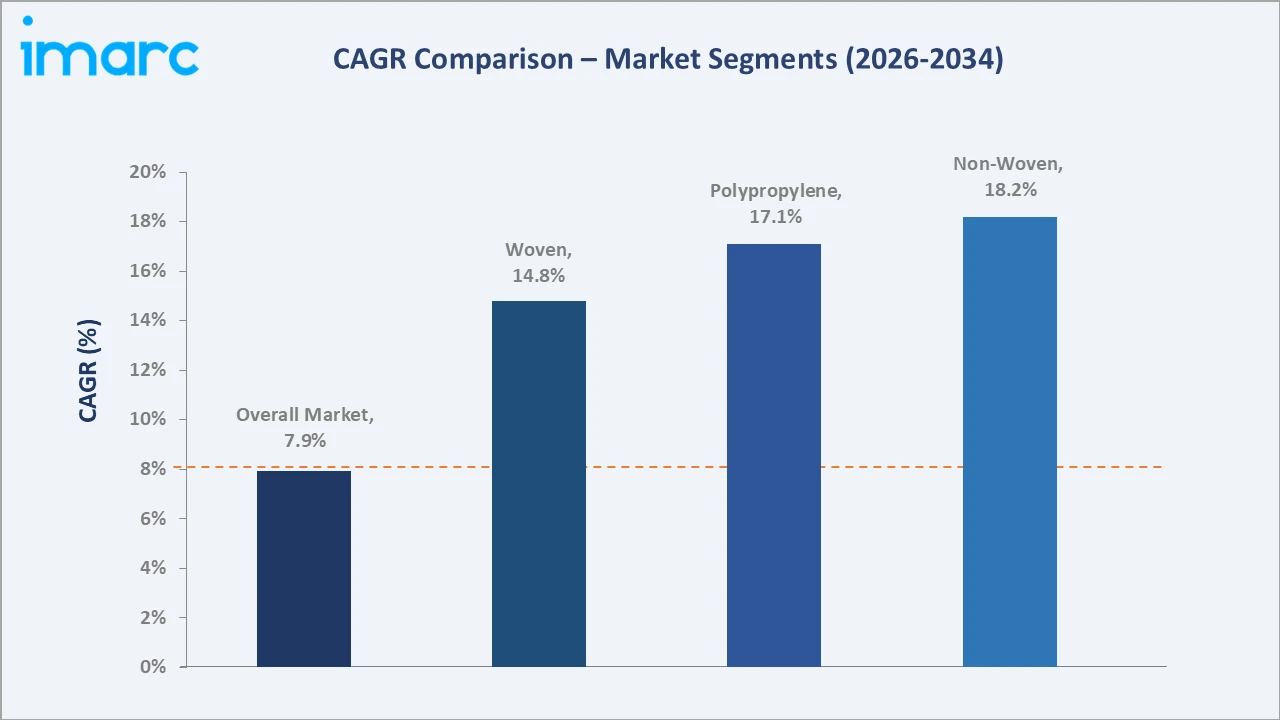
Non-woven geotextiles grow at 18.2% CAGR as the preferred solution for road subgrade separation and filtration in infrastructure projects. Polypropylene-based products grow at 17.1% CAGR, driven by their cost-effectiveness and chemical resistance across road and drainage applications. Woven geotextiles at a 14.8% CAGR, supported by their tensile reinforcement properties in steep slope stabilization and retaining wall applications.
Executive Summary
The India geotextiles market is on a high-growth trajectory, driven by one of the most ambitious infrastructure construction programs. Government programs including Bharatmala Pariyojana, Smart Cities Mission, and the National Technical Textiles Mission (NTTM) provide strong institutional demand, while growing private sector awareness of geotextile performance benefits is expanding beyond traditional road applications.
Non-woven geotextiles lead at 52.8% in 2025, reflecting their versatility across separation, filtration, and drainage applications in road and civil construction. Polypropylene dominates the material segment at 58.4%, supported by cost advantages and availability. North India at 30.8% represents the largest regional market, driven by the high density of national highway construction activity.
Key Market Insights
|
Insight |
Data |
|
Largest Type |
Non-Woven – 52.8% share (2025) |
|
Dominant Material |
Polypropylene – 58.4% share (2025) |
|
Leading Region |
North India – 30.8% (2025) |
|
Key Market Opportunity |
Smart Cities Mission and railway expansion programs are generating multi-billion-dollar infrastructure investment that directly drives geotextile procurement across road, drainage, erosion control, and slope stabilization applications through 2034. |
Key Analytical Observations Supporting the Above Data:
- Non-Woven at 52.8%: Non-woven geotextiles dominate because they offer a cost-effective, versatile solution for the separation, filtration, and drainage functions most commonly required in road subgrade construction. Their ease of installation and availability in a wide range of weights and permeabilities make them the default specification for most highway and urban road projects.
- Polypropylene at 58.4%: Polypropylene dominates the material segment due to its combination of competitive cost, chemical inertness, resistance to biological degradation, and wide availability from India's established PP polymer production base. It meets the performance requirements of the majority of standard road and drainage geotextile applications.
- North India at 30.8%: North India's leadership reflects the high concentration of highway construction activity, generating sustained demand for road geotextiles alongside growing urban infrastructure investment in metro rail and smart city projects.
India Geotextiles Market Overview
Geotextiles are permeable, synthetic or natural textile materials used in geotechnical and civil engineering applications to stabilize, separate, filter, drain, or reinforce soil. The India geotextiles market encompasses non-woven, woven, and knitted products manufactured from polypropylene, polyester, and natural fibers serving road construction, erosion control, drainage, and slope stabilization applications.
The market ecosystem spans raw material and fiber suppliers, geotextile manufacturers, distributors, project contractors, and end-use infrastructure operators across North, South, East, and West India. India's infrastructure spending commitment of approximately USD 133 Billion in FY2024-25, combined with a national focus on road connectivity, flood control, and urban development, positions geotextiles as a strategically important materials category with government-backed demand visibility through 2034.
Market Dynamics
To evaluate market opportunities, Request Sample
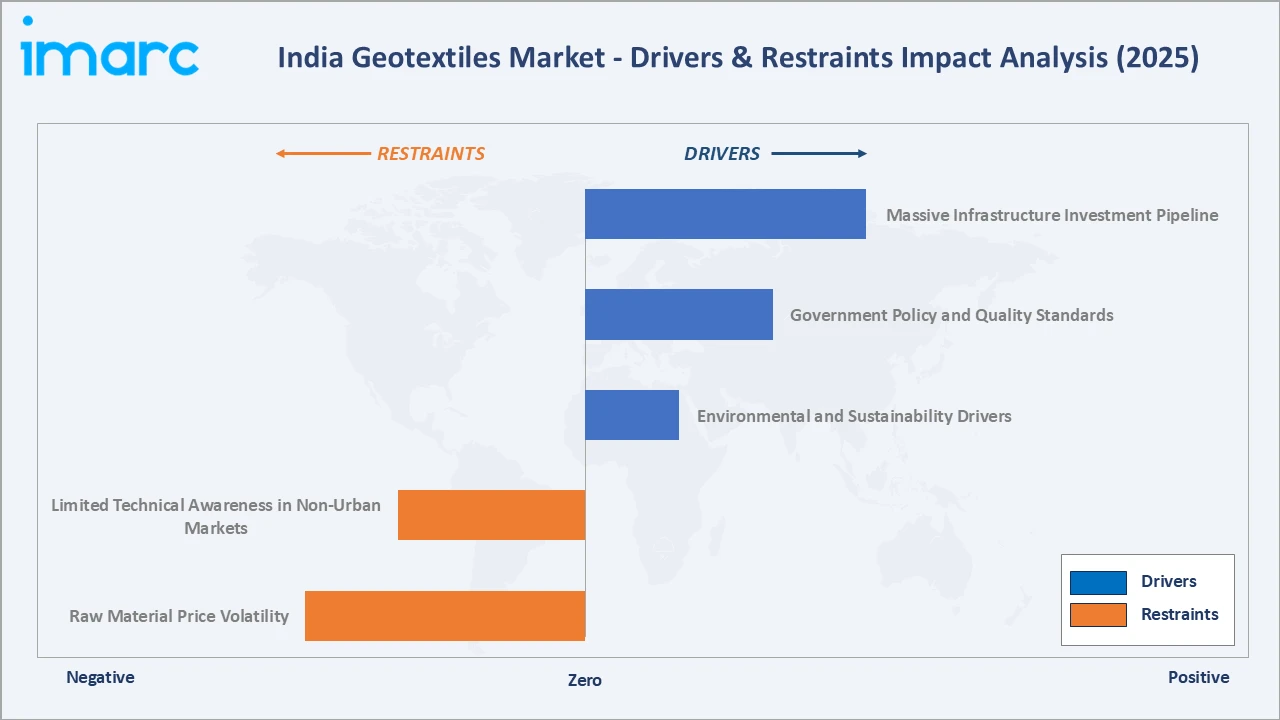
Market Drivers
- Massive Infrastructure Investment Pipeline: India's Union Budget 2024-25 allocated approximately USD 133 Billion (INR 11 lakh crore), which is 3.4% of the GDP, to infrastructure, generating direct geotextile demand. Bharatmala Pariyojana Phase 1 targets 34,800 km of national highways, with geotextile use specified for subgrade separation, drainage filtration, and slope protection across project corridors, creating a large and sustained institutional demand base through the forecast period.
- Government Policy and Quality Standards: The Ministry of Textiles introduced mandatory quality control orders for geotextiles in infrastructure applications, driving specification of certified products in government-funded projects. The National Technical Textiles Mission (2020-2026) with INR 1,480 Crore outlay supports geotextile R&D, testing infrastructure, and industry capability development, accelerating market formalization.
- Environmental and Sustainability Drivers: Growing regulatory pressure on erosion control, slope stabilization, and landfill lining is increasing geotextile specification across environmental management projects. Biodegradable jute and coir-based geotextiles receive government support for eco-sensitive applications including stream bank protection and agricultural land conservation, expanding the addressable market beyond traditional civil engineering applications.
Market Restraints
- Limited Technical Awareness in Non-Urban Markets: Geotextile specification remains concentrated in centrally funded highway and urban projects, with limited penetration into state and rural road construction budgets where awareness of performance benefits and correct installation practices is still developing among engineering staff and contractors.
- Raw Material Price Volatility: Geotextile manufacturing is exposed to polypropylene and polyester feedstock price cycles that track crude oil prices, creating margin volatility for manufacturers and occasional project cost uncertainty for geotextile procurement in price-sensitive government tender processes.
Market Opportunities
- Railway and Metro Expansion: The Union Budget 2024–25 allocated a record ₹2,62,200 crore in capital expenditure to the Indian Railways, with track bed geotextiles specified for railway subgrade rehabilitation and new line construction. Most of the Indian cities have metro rail projects in operation or under construction, generating consistent geotextile demand for tunnel lining, embankment stabilization, and drainage applications through the forecast period.
- Smart Cities and Urban Drainage: The Smart Cities Mission encompassing 100 cities drives urban drainage modernization that requires high-performance filtration and drainage geotextiles in stormwater management systems, road subgrade layers, and green infrastructure installations, creating a growing urban application segment beyond traditional highway use.
Market Challenges
- Quality Standardization and Enforcement: Ensuring consistent product quality across a fragmented manufacturing base and diverse project application contexts remains a structural challenge. Inconsistent testing and inspection practices in smaller projects allow substandard products to enter the market, affecting overall performance perceptions and inhibiting specification uptake in cost-sensitive segments.
- Installation Skill and Contractor Awareness: Geotextile performance is highly sensitive to correct installation practices, including proper seaming, overlap dimensions, and protection from construction traffic. A shortage of trained contractors familiar with geotextile installation specifications creates a performance gap that limits confidence among specifying engineers in new application segments.
Emerging Market Trends
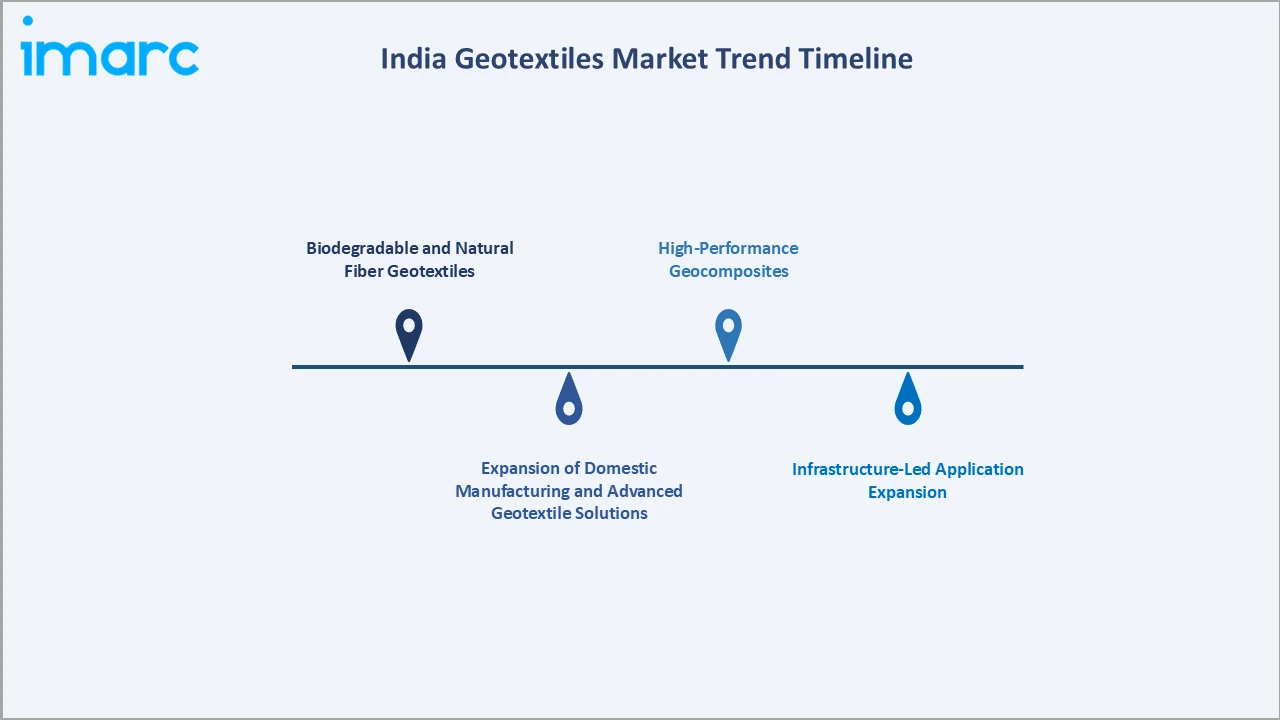
1. Biodegradable and Natural Fiber Geotextiles
Jute and coir-based geotextiles are gaining regulatory and commercial momentum as eco-friendly alternatives for slope protection, stream bank stabilization, and agricultural applications. Government procurement mandates for natural fiber geotextiles in specific environmental applications and export demand from Europe and North America are driving capacity expansion among Indian manufacturers of biodegradable geotextile products.
2. Expansion of Domestic Manufacturing and Advanced Geotextile Solutions
Acquisitions, infrastructure development, and growing demand for durable materials in road construction, railways, drainage, and soil stabilization are encouraging manufacturers to expand their product portfolios and technical capabilities. In February 2026, Strata Geosystems acquired India-based Venus Interlinings, expanding its portfolio into non-woven geotextiles. The acquisition strengthens its manufacturing capabilities, technical expertise, and innovation potential in geosynthetic and engineered textile solutions.
3. High-Performance Geocomposites
Growing adoption of geocomposite products combining drainage cores with non-woven filter geotextiles is expanding the addressable application range beyond traditional single-function products. Geocomposites offer installation efficiency advantages in complex drainage and containment applications, attracting specification from advanced infrastructure projects including metro rail, elevated highway, and port construction.
4. Infrastructure-Led Application Expansion
Bharatmala Pariyojana's focus on road construction in challenging terrain, including steep gradients, waterlogged areas, and weak subgrade conditions, is driving adoption of technically advanced geotextile systems beyond simple separation fabrics. Demand for woven geogrids, erosion control mats, and drainage composites is growing as contractors encounter progressively more challenging site conditions across the program.
Industry Value Chain Analysis
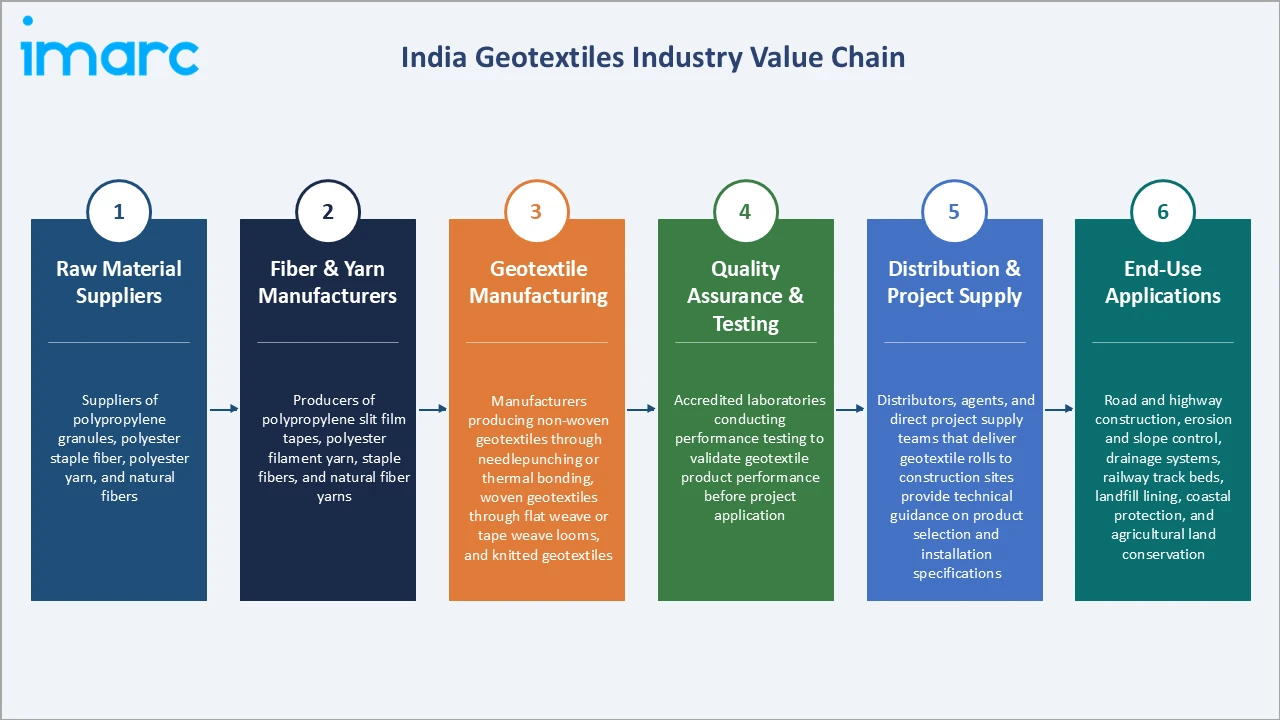
The India geotextiles value chain is structured across six integrated stages from raw material supply through end-use application in infrastructure projects. Value addition increases progressively from upstream commodity polymer supply toward downstream manufactured geotextile products, with the highest margin concentration at the geotextile manufacturing and quality assurance stages where engineering expertise, certified performance, and brand reputation create meaningful competitive differentiation in government-specified procurement.
| Stage | Key Activities |
|---|---|
| Raw Material Suppliers | Suppliers of polypropylene granules, polyester staple fiber, polyester yarn, and natural fibers. |
| Fiber & Yarn Manufacturers | Producers of polypropylene slit film tapes, polyester filament yarn, staple fibers, and natural fiber yarns. |
| Geotextile Manufacturing | Manufacturers producing non-woven geotextiles through needlepunching or thermal bonding, woven geotextiles through flat weave or tape weave looms, and knitted geotextiles. |
| Quality Assurance & Testing | Accredited laboratories conducting performance testing to validate geotextile product performance before project application. |
| Distribution & Project Supply | Distributors, agents, and direct project supply teams that deliver geotextile rolls to construction sites provide technical guidance on product selection and installation specifications. |
| End-Use Applications | Road and highway construction, erosion and slope control, drainage systems, railway track beds, landfill lining, coastal protection, and agricultural land conservation. |
The geotextile manufacturing stage holds the highest strategic value, as manufacturers combine polymer processing expertise with civil engineering performance knowledge and certification to create differentiated product portfolios. Distribution and project technical support are progressively critical as geotextile projects grow in scale and technical complexity, with specifiers increasingly selecting suppliers based on their application engineering capability and on-site installation support.
Technology Landscape in the India Geotextiles Industry
Non-Woven Manufacturing Technology
Non-woven geotextile manufacturing in India primarily employs needlepunching technology, which mechanically entangles staple fibers to produce permeable fabrics with isotropic mechanical properties suited for separation and filtration applications. Spunbond technology is growing, offering continuous filament non-woven geotextiles with higher tensile strength and uniformity for premium infrastructure applications including metro rail and airport construction.
Woven Manufacturing Technology
Woven geotextiles are produced using flat weave or tape weave loom technology, processing polypropylene slit film tapes or polyester yarns into fabrics with high directional tensile strength. Advanced shuttleless rapier and air-jet loom technology enables production of wider, more uniform fabrics at higher productivity, reducing per-unit costs and enabling competitive supply to large-scale infrastructure projects across the country.
Biodegradable and Natural Fiber Processing
Jute and coir geotextile manufacturing employs traditional weaving and mat-forming processes enhanced by modern engineering to achieve consistent performance across erosion control applications. Government-supported processing upgrades and standardization are improving natural fiber geotextile product consistency, while export market demand is encouraging capacity investment in higher-quality biodegradable geotextile production.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Non-Woven | 52.8% | 2025 |
| Material | Polypropylene | 58.4% | 2025 |
| Application | 🔒 | 🔒 | 2025 |
| Region | North India | 30.8% | 2025 |

By Type
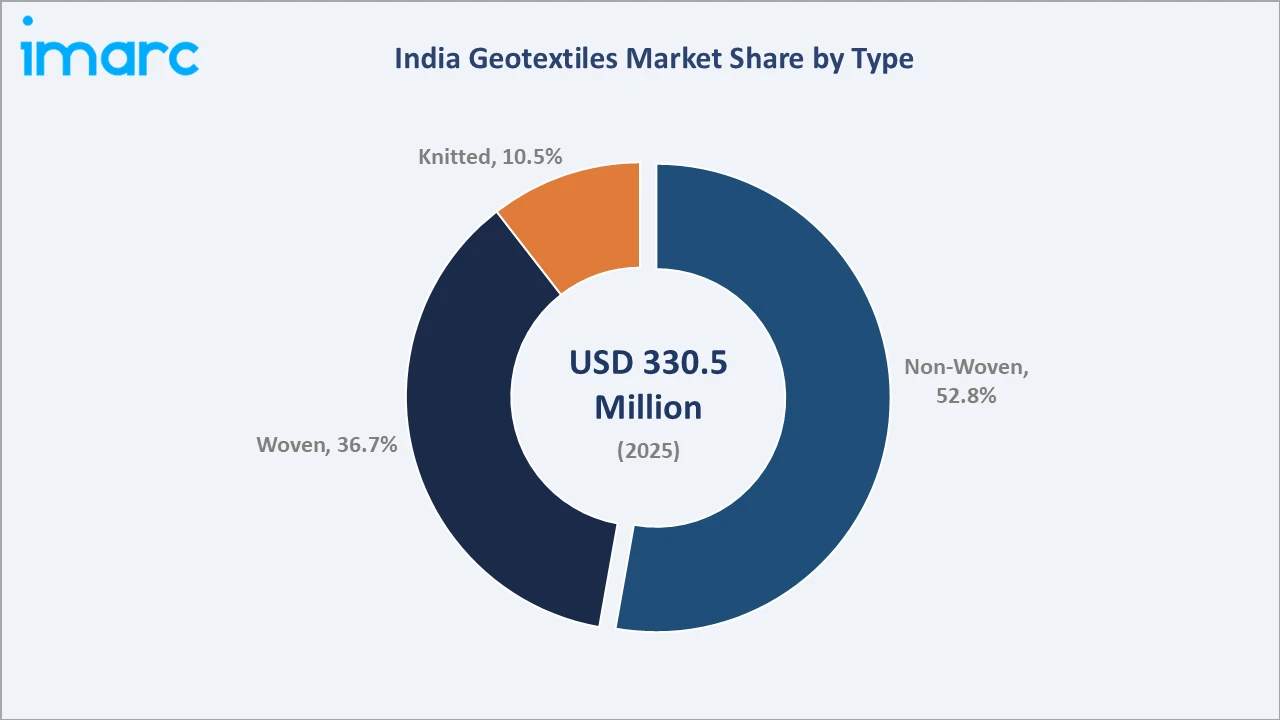
Non-woven geotextiles lead at 52.8% in 2025, reflecting their dominant position in road construction. Non-woven geotextiles function as separation layers between subgrade soils and aggregate road base layers, preventing particle migration while allowing water drainage, a critical function in India's road construction program across varied soil and climate conditions.
To access detailed market analysis, Request Sample
Woven geotextiles at 36.7% serve reinforcement and high-tensile applications including embankment stabilization, retaining structures, and steep slope protection where directional tensile load bearing is required. Knitted geotextiles at 10.5% serve specialized applications including erosion control mats and composite geosynthetic products where extensibility and conformance to irregular surfaces provide performance advantages over non-woven or woven alternatives.
By Material
Polypropylene dominates at 58.4% in 2025, driven by its competitive cost, chemical resistance, and wide availability from domestic polymer producers. PP-based geotextiles are the standard specification for the majority of road construction and drainage applications, where their resistance to soil chemistry and biological degradation ensures a long service life in embedded applications.
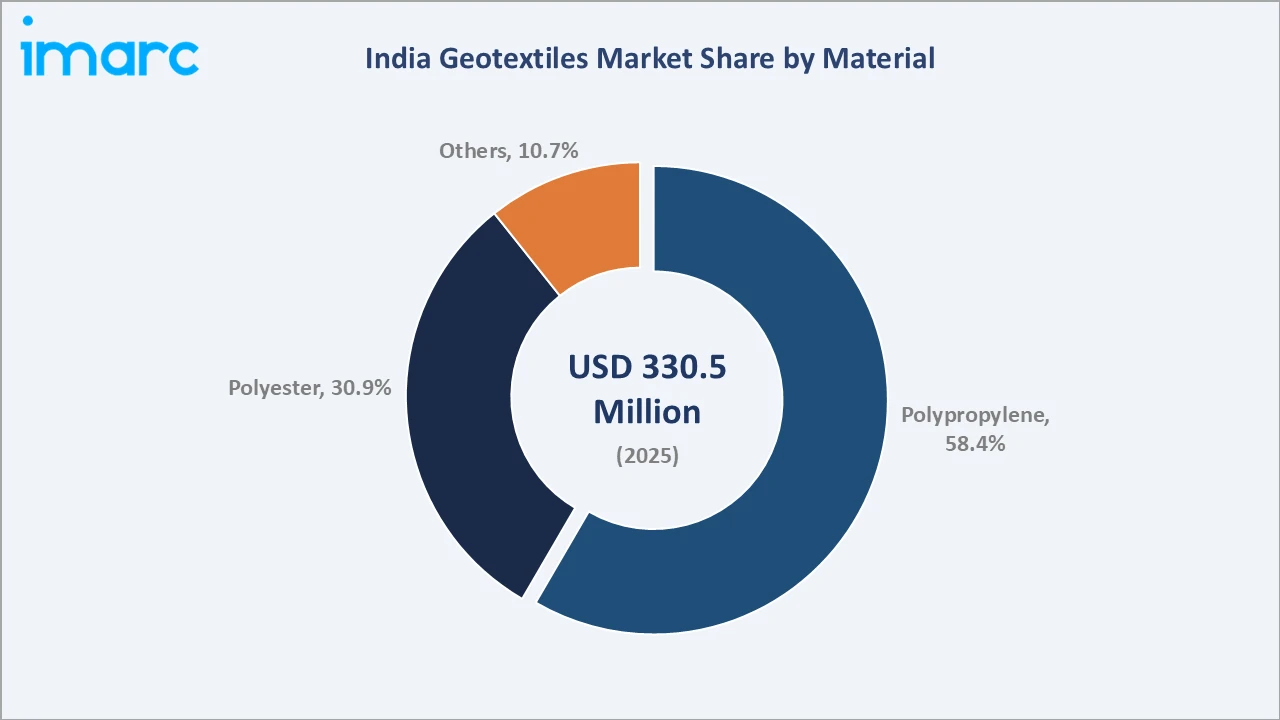
Polyester at 30.9% is preferred for applications requiring higher stiffness and lower creep under sustained load, including woven geogrids and high-strength geotextiles for reinforced soil structures. Others at 10.7% include natural fiber products, jute and coir, supported by government mandates for environmentally sensitive applications and growing export demand from sustainable construction markets.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
North India |
30.8% |
The largest regional market, driven by the high concentration of highway construction. Metro rail expansion and smart city projects in Delhi-NCR supplement highway demand. |
|
West India |
28.7% |
Maharashtra and Gujarat drive demand through major roads, ports, coastal protection, and urban infrastructure projects. Mumbai Metropolitan Region metro expansion and port modernization programs generate consistent high-volume geotextile procurement. |
|
South India |
24.1% |
Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana generate demand through highway construction, metro rail projects in Chennai, Bengaluru, and Hyderabad, and coastal erosion control applications along the extensive southern coastline. |
|
East India |
16.4% |
The smallest but high-potential region, driven by Northeast connectivity road programs, riverbank erosion control, and growing infrastructure investments. |
North India commands the largest regional share at 30.8% in 2025, reflecting the high density of national highway construction. West India holds a 28.7% share in 2025, driven by strong infrastructure investment pipelines.
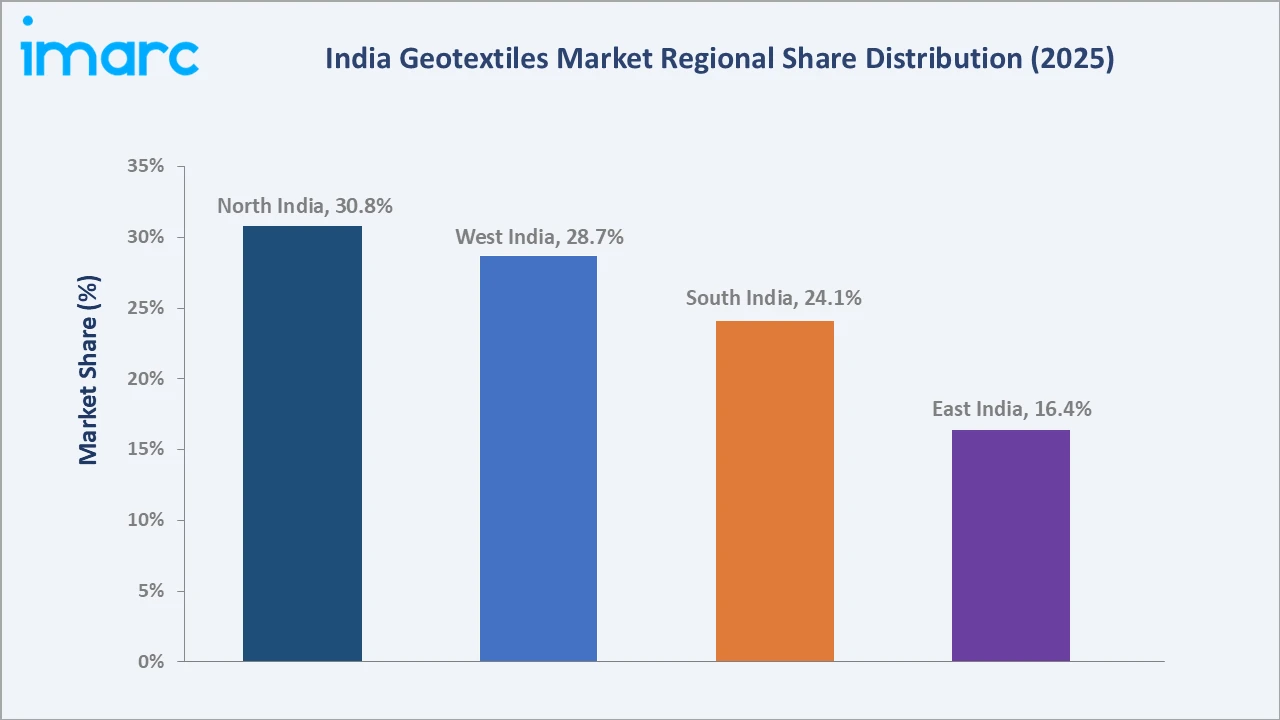
South India accounts for 24.1% in 2025, with demand distributed across Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana. Metro rail projects, national highway construction requiring slope protection geotextiles, and coastal erosion control collectively sustain a broad and diversified regional demand base. East India represents 16.4% of the market in 2025, the smallest regional share but with the highest growth potential.
Competitive Landscape
The India geotextiles market features a mix of domestic manufacturers and international players with India manufacturing or distribution presence. Domestic companies hold leading positions through established manufacturing capacity and deep project supply relationships. International players contribute specialized engineering-grade products for technically demanding infrastructure applications.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Garware Technical Fibres Ltd. | Woven Geotextiles, Non Woven Geotextiles | Market Leader | Garware Technical Fibres Ltd. is a leading Indian technical textiles manufacturer that plays a vital role in India's civil engineering, infrastructure, and environmental protection sectors through its advanced geosynthetic and geotextile solutions. |
| TechFab India Industries Ltd. | TechFab PP Woven Geotextile 1000 Series, TechGeo PP Nonwoven Geotextiles | Market Leader | TechFab India Industries Ltd. is India's largest geosynthetics manufacturer, playing a pioneering role in the country's geotextiles and geohazard mitigation sector. |
| Gayatri Polymers & Geosynthetics | Nonwoven Geotextiles, Woven Geotextiles, Coir Geotextiles, Jute Geotextiles | Established Player | Gayatri Polymers & Geosynthetics plays a specialized role as a manufacturer, exporter, importer, and service provider of civil engineering and environmental solutions in India's geosynthetics industry. |
| Thrace Group | Nonwoven Geotextiles, Woven Geotextiles | Niche Player | The Thrace Group plays a role as a prominent international supplier and technology benchmark in the Indian geotextiles and geosynthetics market. |
Competition in the mid-range non-woven segment is intensifying as domestic manufacturers expand capacity to serve Bharatmala project demand. Technical differentiation through certified product performance, application engineering capability, and project supply reliability is the primary competitive strategy for market leaders, while mid-tier producers compete on price and regional proximity to construction sites.
Key Company Profiles
Garware Technical Fibres Ltd.
Garware Technical Fibres Ltd. is India's leading technical fiber manufacturer, producing a broad portfolio of high-performance synthetic fiber products including geotextiles, fishing nets, aquaculture systems, and sports netting. The company serves civil engineering, marine, agriculture, and sports infrastructure markets in India and internationally, with established manufacturing facilities and a long track record of supplying geotextile products to major infrastructure projects across the country.
- Key Products: Woven Geotextiles, Non Woven Geotextiles.
- Strategic Focus: Focuses on technical fiber innovation and expanding its geotextile product range to address growing specification demand from infrastructure project agencies. The company is investing in manufacturing capacity and technical marketing to strengthen its position in the Bharatmala highway construction supply chain and emerging applications in railway and coastal infrastructure projects.
TechFab India Industries Ltd.
TechFab India Industries Ltd. is a pioneering Indian geosynthetics manufacturer with one of the broadest geotextile and geogrid product portfolios in the domestic market. The company serves road construction, railway, erosion control, and drainage infrastructure applications across India, with manufacturing facilities and a technical marketing team providing product specification and application engineering support to infrastructure project agencies, consultants, and contractors across the country.
- Key Offerings: TechFab PP Woven Geotextile 1000 Series, TechGeo PP Nonwoven Geotextiles.
- Strategic Focus: Expanding its non-woven geotextile production capacity to capture growing Bharatmala highway project demand. The company is investing in technical specification resources and laboratory testing capability to support product certification under quality control orders and strengthen its position in government-specified infrastructure project procurement.
Market Concentration Analysis
The India geotextiles market is moderately fragmented, with established domestic manufacturers and international players operating alongside a significant unorganized sector that serves the lower end of the price-sensitive domestic market. The organized segment is led by a small number of companies with certified manufacturing capability, technical marketing infrastructure, and established project supply relationships that provide meaningful competitive advantages in government-specified infrastructure procurement.
Consolidation opportunities exist as mandatory quality control orders progressively constrain the unorganized sector and raise compliance barriers for smaller producers. Organized players with certified product portfolios, application engineering capability, and the scale to supply large-scale infrastructure project volumes are positioned to gain market share as the formal segment of the market expands and quality standardization becomes an enforced prerequisite for government project participation through 2034.
Investment & Growth Opportunities
Fastest Growing Segments
Non-woven geotextiles at 18.2% CAGR represent the highest-growth segment, driven by road construction volumes under Bharatmala Pariyojana and national highway expansion programs. Polypropylene-based products at 17.1% CAGR offer the strongest material segment growth, aligned with cost-competitive road project supply requirements.
Emerging Market Investment Themes
- Infrastructure Project Pipeline: India's infrastructure investment commitment provides a USD 133 Billion annual spending base that directly sustains geotextile demand. Bharatmala Phase 1, railway electrification and capacity expansion, metro rail in major cities, and smart city drainage upgrades represent individually significant demand sources through the forecast period, providing investment visibility for manufacturing capacity expansion decisions.
- Natural Fiber Geotextile Exports: India's jute and coir processing heritage positions domestic manufacturers advantageously for growing global demand for biodegradable geotextiles in environmentally sensitive applications. Export to European and North American sustainable construction markets represents a high-value growth opportunity beyond the domestic infrastructure demand base.
- Agricultural and Environmental Applications: India's large agricultural land base and river system management requirements represent a significantly underpenetrated geotextile application market. Government watershed development, flood management, and agricultural land conservation programs create addressable market opportunities that expand geotextile demand beyond the primary infrastructure application base.
Future Market Outlook (2026-2034)
The India geotextiles market grew from USD 330.5 Million in 2025 to USD 364.1 Million in 2026 and is projected to reach USD 671.0 Million by 2034, exhibiting a CAGR of 7.94% during 2026-2034. The market is expected to reach an intermediate milestone of USD 620.6 Million by 2030, as Bharatmala Pariyojana highway construction reaches peak completion rates and Smart Cities Mission drainage and road upgrades generate broad-based geotextile procurement across all major regional markets.
Three structural forces will define India's geotextiles market through 2034. First, the government's sustained infrastructure investment commitment will remain the primary demand driver. Second, progressive quality control enforcement will formalize the market, shifting demand toward certified organized sector manufacturers and supporting margin improvement across the value chain. Third, the expansion of geotextile application from highway construction into railway track beds, metro construction, coastal protection, and agricultural land management will broaden the demand base and reduce concentration risk in a single application category, supporting the sustained high-CAGR growth trajectory through the forecast period.
Research Methodology
Primary Research
Primary research comprised structured consultations with geotextile manufacturing executives, procurement managers at road and civil engineering contractors, project engineers at government infrastructure agencies, and geotextile distributors and traders across North, South, East, and West India. These discussions validated market sizing estimates, assessed segment demand dynamics, and provided insights into competitive positioning, application expansion drivers, and project supply chain dynamics across the India geotextiles industry.
Secondary Research
Secondary research drew on Ministry of Road Transport & Highways project data, National Technical Textiles Mission program documentation, quality control order publications, geotextile industry association reports, company annual reports and investor presentations, trade data from customs authorities, and market intelligence from civil engineering and technical textile publications. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources to ensure consistency and accuracy.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical market growth rates, infrastructure project pipeline analysis, government budget allocation trends, end-use industry capital expenditure projections, geotextile specification adoption curve modeling, and macroeconomic indicators including India's GDP growth outlook, manufacturing sector investment trends, and infrastructure policy commitment benchmarks across the 2026-2034 forecast period.
India Geotextiles Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Non-Woven, Woven, Knitted |
| Materials Covered | Polypropylene, Polyester, Others |
| Applications Covered | Erosion Control, Road, Drainage, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Garware Technical Fibres Ltd., TechFab India Industries Ltd., Gayatri Polymers & Geosynthetics, Thrace Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India geotextiles market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India geotextiles market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India geotextiles industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Geotextiles Market Report
The India geotextiles market reached USD 364.1 Million in 2026, driven by highway construction, government infrastructure programs, and growing adoption in erosion control and drainage applications across the country.
The market is projected to grow at a CAGR of 7.94% during 2026-2034, supported by Bharatmala Pariyojana, Smart Cities Mission, railway expansion, and the National Technical Textiles Mission driving sustained geotextile demand.
The market is projected to reach USD 620.6 Million by 2030, driven by peak Bharatmala construction activity, metro rail expansion, and progressive geotextile adoption in railway and coastal protection applications across India.
Non-woven geotextiles lead with a 52.8% share in 2025, reflecting their dominant role in road subgrade separation and filtration applications across India's national highway and urban road construction programs.
Polypropylene dominates at 58.4% in 2025, driven by its cost-competitiveness, chemical resistance, and wide availability from India's domestic polymer production base for standard road and drainage geotextile applications.
North India leads with a 30.8% share in 2025, driven by high national highway construction density and metro and urban infrastructure development.
Key players include Garware Technical Fibres Ltd., TechFab India Industries Ltd., Gayatri Polymers & Geosynthetics, and Thrace Group, among others.
The market is projected to reach USD 671.0 Million by 2034, driven by continued infrastructure investment, expanding application scope in railway and coastal protection, and progressive adoption of geotextiles in agricultural and environmental management.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade