
India Golf Equipment Market Size, Share, Trends and Forecast by Type, Distribution Channel, and Region, 2026-2034
India Golf Equipment Market Size, Share, Trends & Forecast (2026-2034)
The India golf equipment market grew from USD 278.7 Million in 2025 to USD 292.4 Million in 2026 and is projected to reach USD 395.4 Million by 2034, growing at a CAGR of 3.84% during 2026-2034. India has over 250 operational golf courses, with the sport gaining consistent traction among urban professionals, corporate players, and a growing base of youth and women participants. Golf clubs lead at 38.6% by type, specialty stores account for 29.7% of distribution, and North India commands the largest regional share at 32.8% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 278.7 Million |
|
Market Size (2026) |
USD 292.4 Million |
|
Forecast Market Size (2034) |
USD 395.4 Million |
|
CAGR (2026-2034) |
3.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Golf Clubs (38.6%, 2025) |
|
Dominant Distribution Channel |
Specialty Stores (29.7%, 2025) |
|
Leading Region |
North India (32.8%, 2025) |
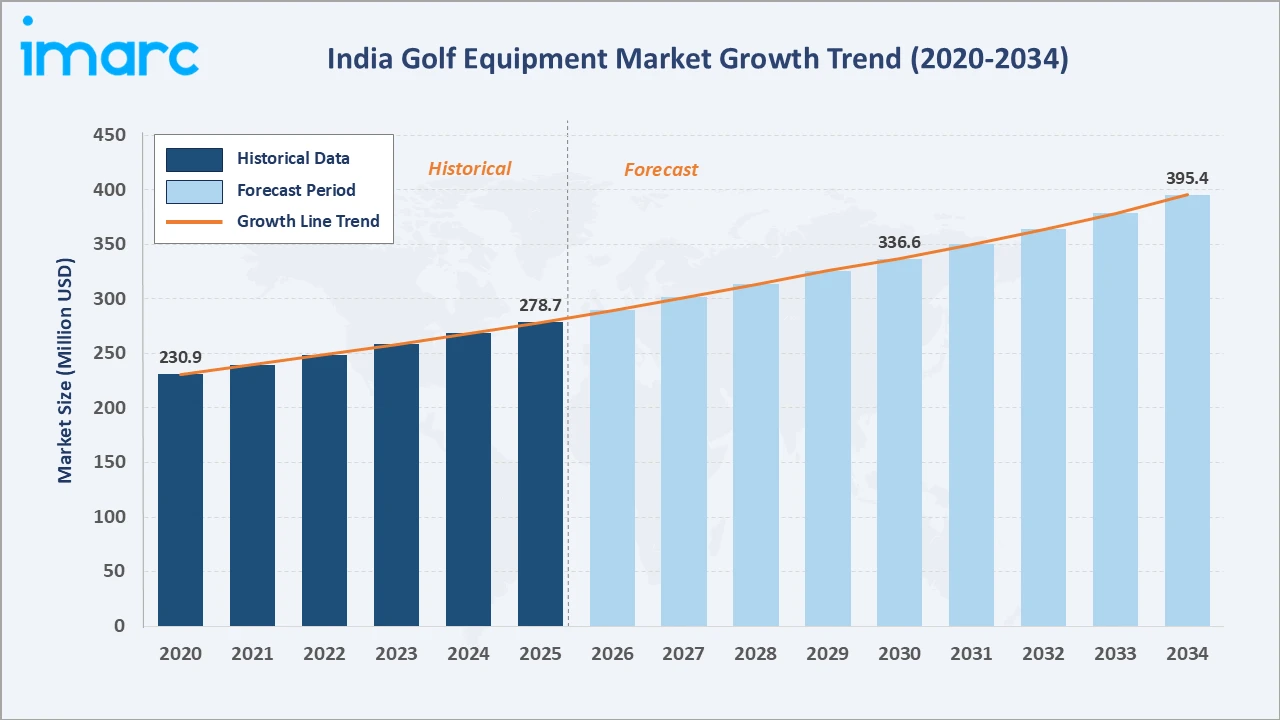
The India golf equipment market grew from USD 230.9 Million in 2020 to USD 278.7 Million in 2025, and further to USD 292.4 Million in 2026, reflecting steady expansion driven by rising golf participation and growing infrastructure. The market is projected to reach USD 336.6 Million by 2030 before reaching USD 395.4 Million by 2034.
To get more information on this market, Request Sample
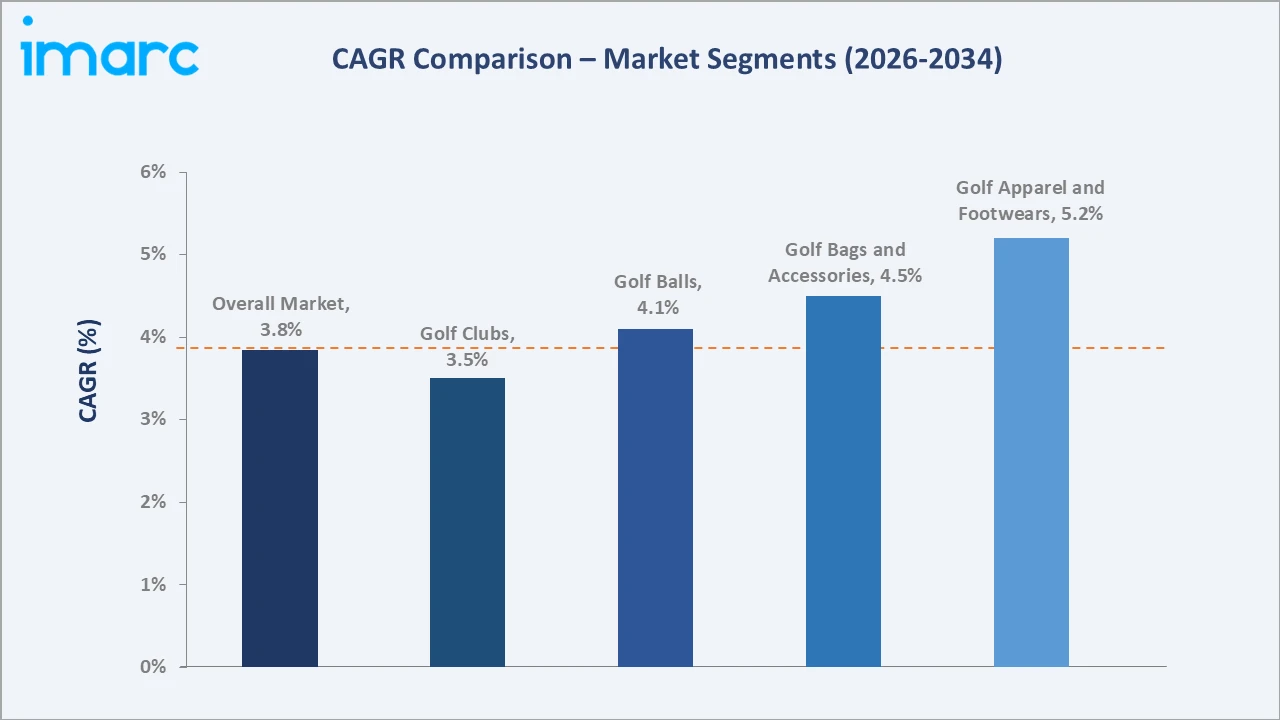
Golf apparel and footwear lead at approximately 5.2% CAGR, driven by rising lifestyle spending and branded fashion demand. Golf bags and accessories follow at 4.5% CAGR, supported by growing participation. Golf balls expand at 4.1%, while golf clubs, the largest type segment at 38.6%, grow at 3.5% CAGR through the forecast period.
Executive Summary
The India golf equipment market is on a sustained growth trajectory, underpinned by rising urban affluence, rapid expansion of golf course and resort infrastructure, and growing corporate and lifestyle association with the sport. The market growth is driven by increasing participation in professional and amateur tournaments, new golf resort developments in metro and tourist destinations, and expanding online retail channels improving product accessibility.
Golf clubs lead at 38.6%, reflecting the primacy of core playing equipment. Specialty stores dominate distribution at 29.7%, though online stores at 26.8% represent the fastest-growing channel, driven by smartphone penetration and competitive pricing. North India leads regionally at 32.8%, underpinned by a high concentration of established golf clubs, corporate memberships, and organized golf tournaments in the Delhi NCR region and surrounding areas.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Type | Golf Clubs – 38.6% share (2025) |
| Dominant Distribution Channel | Specialty Stores – 29.7% share (2025) |
| Leading Region | North India – 32.8% (2025) |
| Key Market Opportunity | Rising participation among women, youth, and tier-2 city residents presents a large addressable market for both premium and entry-level golf equipment. |
Key Analytical Observations Supporting the Above Data:
- Golf Clubs at 38.6%: Golf Clubs dominate the market as the primary and highest-value equipment category. Demand is sustained by regular performance upgrades among active golfers and growing adoption of custom-fitted club sets.
- Specialty Stores at 29.7%: Specialty stores lead distribution by offering expert fitting services, brand-authorized product ranges, and personalized consultation, making them the preferred purchase channel for premium buyers across metro cities.
- North India at 32.8%: North India leads regionally due to the highest concentration of established golf clubs, corporate memberships, and organized golf events in Delhi NCR and the north Indian plains, generating consistent premium equipment demand.
India Golf Equipment Market Overview
The India golf equipment market encompasses the manufacture, import, distribution, and retail of all primary playing equipment and accessories used across golf courses, resorts, and recreational golf facilities. Core product categories include clubs, balls, bags, apparel, and footwear, serving professional and amateur golfers. The market operates through a multi-channel distribution ecosystem spanning global manufacturers, specialized importers, specialty retail stores, online platforms, and on-course pro shops.
India's golf industry serves an estimated player base of registered golfers, with a broader recreational and resort-based segment growing steadily. The sport's association with corporate culture, premium lifestyle, and international tourism continues to attract new participants in metro and tier-1 cities, supporting consistent demand growth across all equipment categories.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
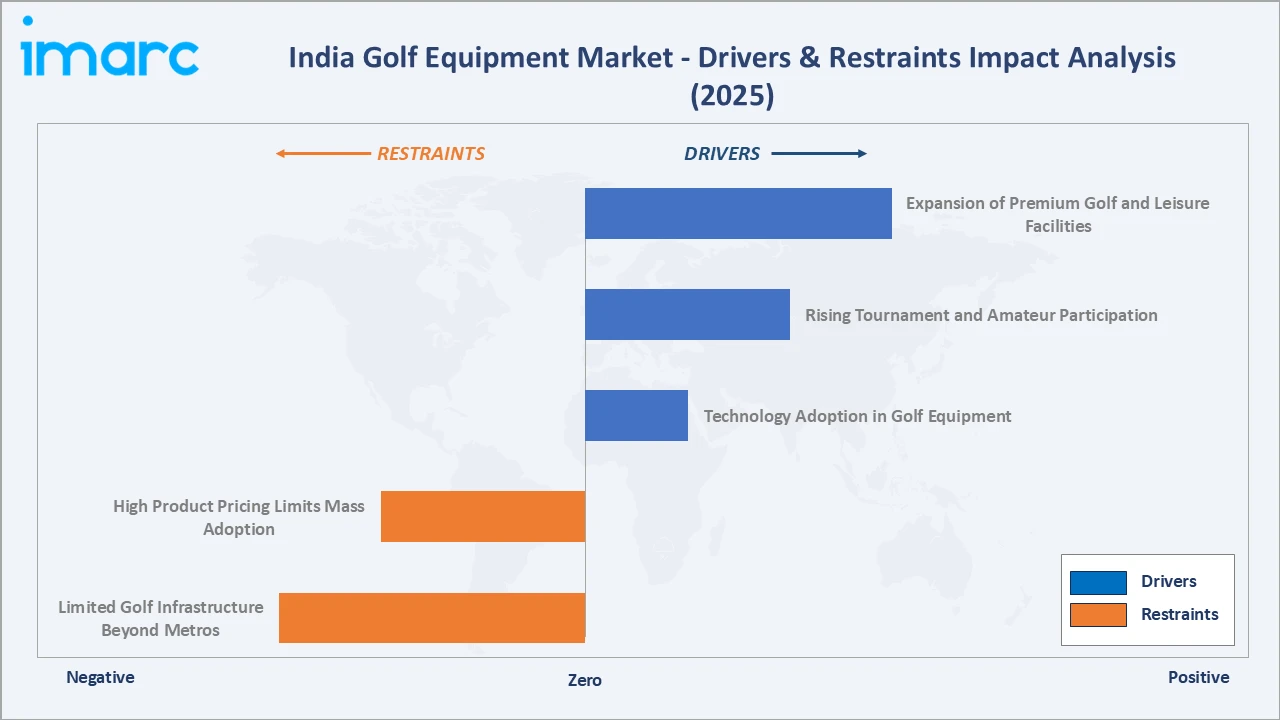
- Expansion of Premium Golf and Leisure Facilities: In October 2026, DreamFolks Services Limited introduced DreamFolks Club Nagavalli Wilderness Estate, a private club situated in the Eastern Ghats along the Odisha–Andhra Pradesh border. Spanning around 30 acres, including a 25-acre golf course, the estate offers a blend of golf, nature, adventure, and regional cultural experiences. The growing availability of integrated golf, leisure, and lifestyle facilities is encouraging greater participation in the sport and creating new opportunities for golf equipment brands.
- Rising Tournament and Amateur Participation: Growing participation in golf tournaments at professional and amateur levels encourages golfers to invest in higher-quality, performance-grade equipment, including premium clubs, balls, and accessories across all segments.
- Technology Adoption in Golf Equipment: Integration of smart sensors, GPS rangefinders, launch monitors, and data-driven club fitting is driving demand for premium, technology-enabled equipment, particularly among urban professionals seeking measurable performance improvement.
Market Restraints
- High Product Pricing Limits Mass Adoption: Premium golf equipment pricing positions the market as aspirational, restricting the active player base to affluent urban consumers and limiting volume growth potential in price-sensitive markets and smaller cities.
- Limited Golf Infrastructure Beyond Metros: Golf courses and practice facilities remain concentrated in major urban centers, limiting market development in regions where infrastructure, coaching access, and sport awareness are insufficient to drive consistent equipment demand.
Market Opportunities
- Women and Youth Golf Participation Growth: Growing women's golf adoption and structured junior development programs are generating demand for gender-specific and youth-segment equipment, representing an underpenetrated opportunity for specialized product launches and targeted marketing.
- Premium and Custom-Fit Equipment Demand: Increasing demand from serious amateur golfers for professional custom-fitted clubs is driving higher per-unit revenue and margin opportunity for brands investing in fitting centers and advisory retail services in India.
Market Challenges
- High Import Duties on Golf Equipment: Significant import levies on golf equipment and accessories increase landed costs, constraining price competitiveness and accessibility of international brands for mid-market and entry-level consumer segments.
- Fragmented Retail Distribution Outside Metros: Golf equipment distribution beyond major cities relies on fragmented dealer networks with limited brand representation, inconsistent product availability, and reduced post-sale service quality.
Emerging Market Trends
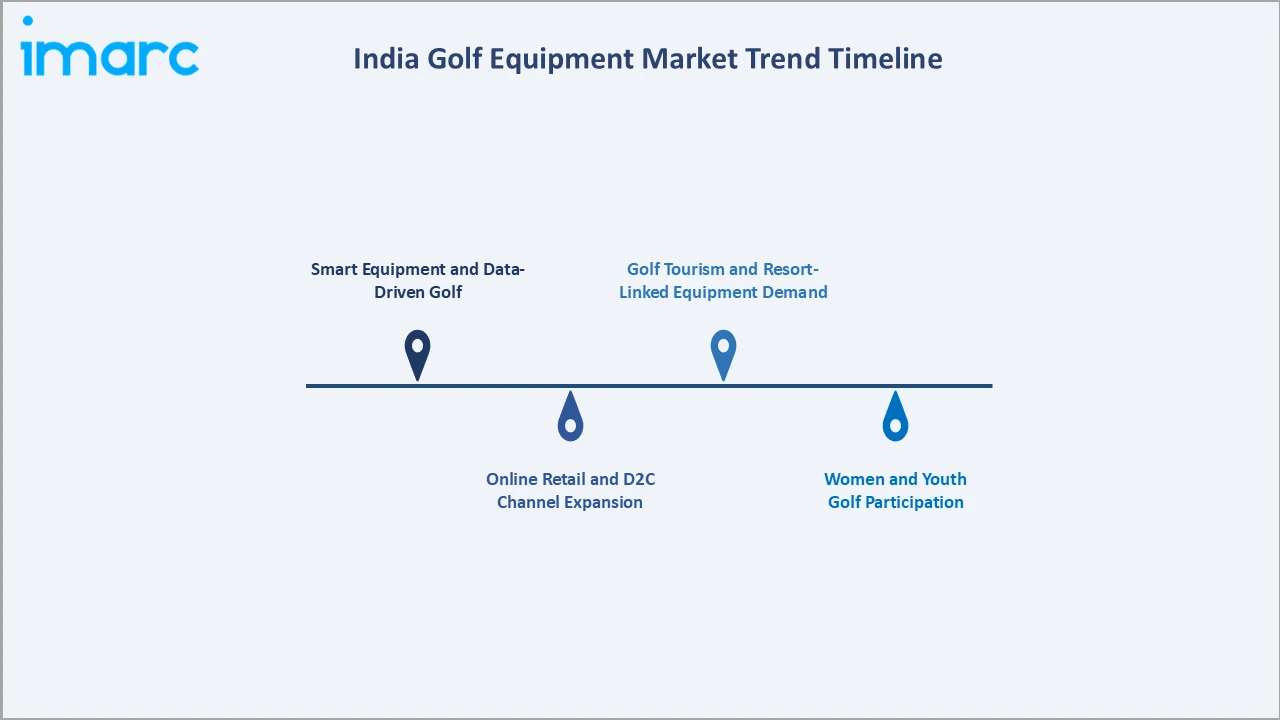
1. Smart Equipment and Data-Driven Golf
Golf equipment is increasingly integrating smart sensor technology, GPS systems, and shot-tracking capabilities. Smart clubs, GPS rangefinders, and launch monitors are gaining adoption among serious amateur golfers, driving demand for premium technology-enabled equipment.
2. Online Retail and D2C Channel Expansion
Online retail is the fastest-growing distribution channel, with global golf brands launching India-specific collections on e-commerce platforms. In November 2024, Luxury golf apparel and accessories brand G/Fore partnered with Brandman Retail to expand its presence in India. The collaboration aims to strengthen the brand’s reach, particularly across Tier-2 and Tier-3 cities, while targeting golfers and fashion-conscious consumers. Direct-to-consumer platforms are improving product authenticity, pricing transparency, and delivery reach to non-metro geographies.
3. Golf Tourism and Resort-Linked Equipment Demand
Golf tourism is expanding across India's resort destinations, with courses integrated into luxury hotel and real estate developments. In March 2025, iGolf Pune launched as a high-tech golf entertainment venue using InRange ball-tracking technology, reflecting growing demand for immersive, technology-enhanced golf experiences outside traditional club environments.
4. Women and Youth Golf Participation
Structured junior golf programs and growing women's golf events are driving demand for gender-specific and youth-segment equipment across India. Brands are increasingly launching India-focused collections for these segments, creating new product development and revenue diversification opportunities expected to scale through 2034.
Industry Value Chain Analysis
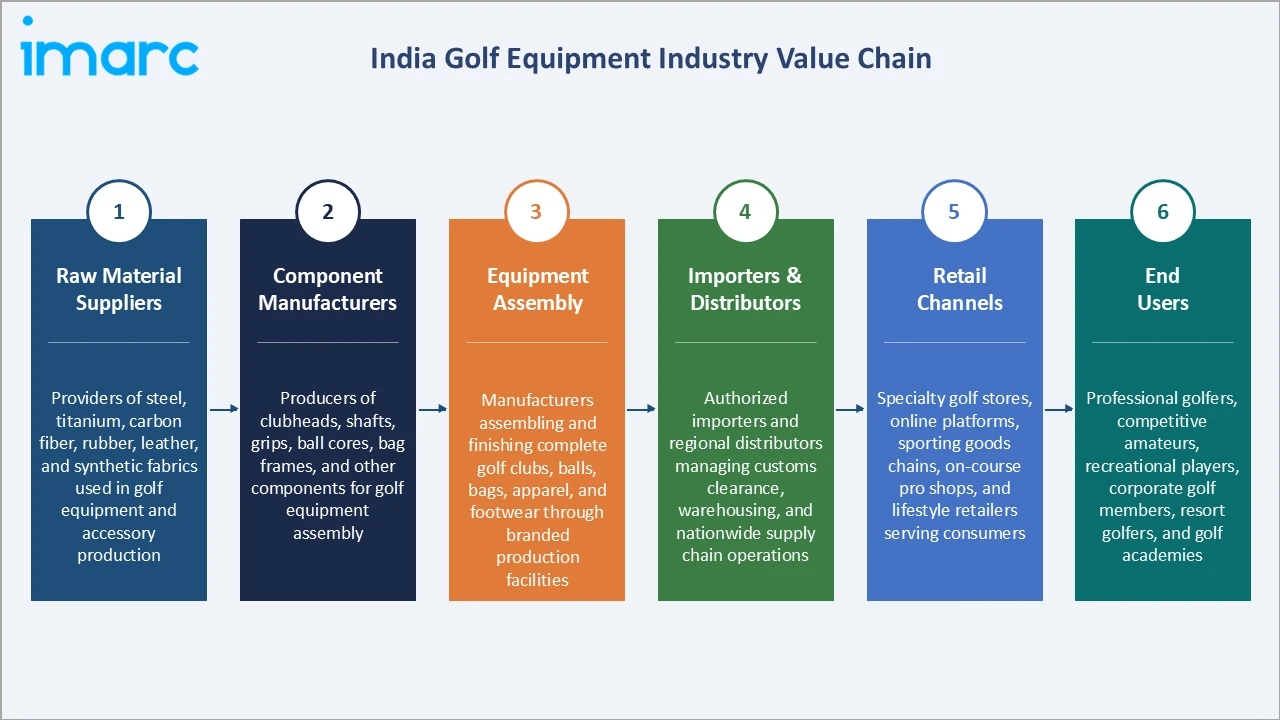
The India golf equipment value chain spans six integrated stages from raw material sourcing through end-user purchase. Each stage contributes distinct value through material processing, precision manufacturing, import logistics, multi-channel distribution, and specialized retail services.
| Stage | Key Participants |
|---|---|
| Raw Material Suppliers | Providers of steel, titanium, carbon fiber, rubber, leather, and synthetic fabrics used in golf equipment and accessory production. |
| Component Manufacturers | Producers of clubheads, shafts, grips, ball cores, bag frames, and other components for golf equipment assembly. |
| Equipment Assembly | Manufacturers assembling and finishing complete golf clubs, balls, bags, apparel, and footwear through branded production facilities. |
| Importers & Distributors | Authorized importers and regional distributors managing customs clearance, warehousing, and nationwide supply chain operations. |
| Retail Channels | Specialty golf stores, online platforms, sporting goods chains, on-course pro shops, and lifestyle retailers serving consumers. |
| End Users | Professional golfers, competitive amateurs, recreational players, corporate golf members, resort golfers, and golf academies. |
The retail distribution stage is evolving rapidly as online platforms gain market share from traditional specialty stores. Multi-channel retail strategies combining specialist stores with digital commerce are emerging as the most effective distribution approach for global golf equipment brands operating across India's diverse and geographically dispersed market.
Technology Landscape in the India Golf Equipment Industry
Smart Sensors and GPS Integration
GPS rangefinders, swing-analysis sensors, and shot-tracking devices embedded in clubs and gloves are creating a premium technology tier that drives upgrade cycles among performance-focused golfers. These tools provide real-time feedback, enabling data-driven improvement and increasing long-term equipment spend per player.
Advanced Materials in Club Manufacturing
Carbon composite crowns, titanium alloy faces, and forged steel bodies are enabling manufacturers to optimize club weight distribution, launch angles, and forgiveness. Multi-material construction is now standard across premium driver and iron categories, supporting innovation-led pricing and differentiation.
Custom Fitting Technology
Professional launch monitors and digital ball-flight tracking systems are enabling data-driven custom fitting services at specialty retail centers. Custom fitting improves player performance outcomes and drives per-unit revenue uplift, as players invest in purpose-built club specifications rather than standard off-the-shelf configurations.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Golf Clubs | 38.6% | 2025 |
| Distribution Channel | Specialty Stores | 29.7% | 2025 |
| Region | North India | 32.8% | 2025 |

By Type
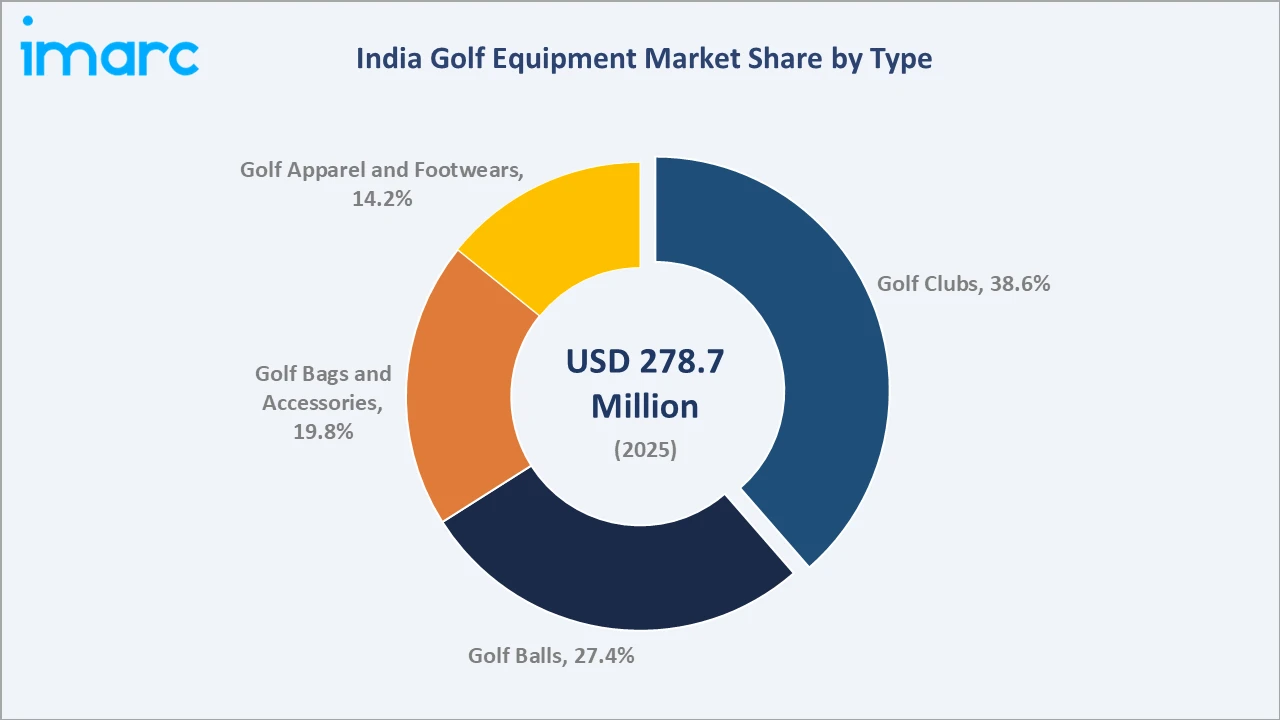
Golf clubs lead at 38.6% in 2025, reflecting their role as the core and highest-value playing equipment category. Demand is driven by regular performance upgrades among active players and growing adoption of professional custom-fitted club sets, particularly among urban amateur golfers seeking competitive performance improvement.
To access detailed market analysis, Request Sample
Golf balls at 27.4% represent a high-frequency consumable category delivering consistent repeat purchase revenue. Golf bags and accessories at 19.8% serve a growing lifestyle and functionality market, while golf apparel and footwear at 14.2% is the fastest-growing type segment, driven by branded golf fashion demand among urban professionals and resort golfers.
By Distribution Channel
Specialty stores lead at 29.7% in 2025, supported by expert fitting consultation and comprehensive branded assortments. Online stores at 26.8% represent the fastest-growing channel, driven by smartphone adoption, competitive pricing, and expanding e-commerce reach connecting international golf brands with India's tier-1 and tier-2 consumer base.
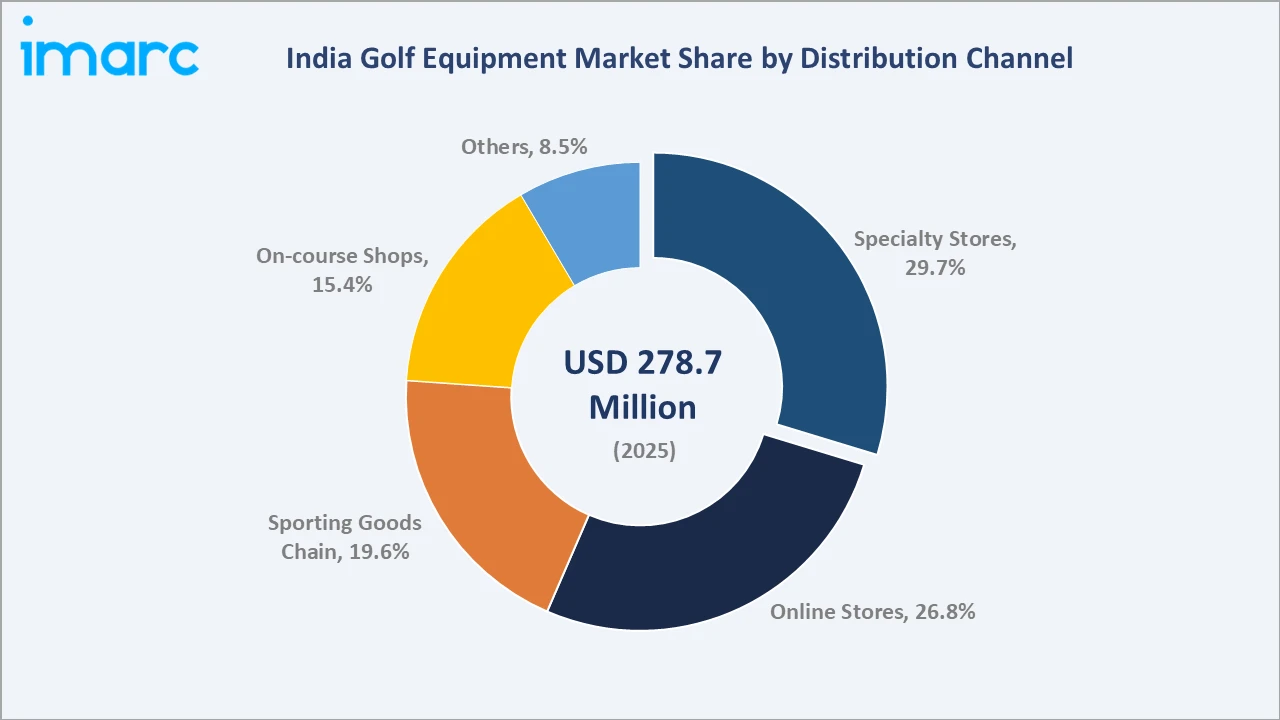
Sporting goods chains at 19.6% serve multi-sport retail environments, while on-course shops at 15.4% capture convenience purchases at golf clubs and resort pro shops. Others at 8.5% include multi-brand lifestyle outlets and department stores reaching occasional and entry-level golfers.
Regional Market Insights
|
Region |
Share (2025) |
Key India Golf Equipment Market Drivers & Characteristics |
|
North India |
32.8% |
Reflecting the highest concentration of established golf clubs, corporate memberships, and organized tournament activity, generating consistent premium equipment demand. |
|
West India |
27.6% |
Reflecting a strong golf club membership base, growing resort-linked golf activity, and high urban affluence levels driving premium equipment adoption. |
|
South India |
24.7% |
Reflecting growing golf infrastructure investment, expanding golf resort developments in tourist destinations, and rising professional tournament activity. |
|
East India |
14.9% |
Reflecting emerging golf participation driven by sport tourism, new course developments, and growing urban professional interest in the sport. |
North India leads the India golf equipment market at 32.8% in 2025, reflecting the highest concentration of established golf clubs, corporate golf memberships, and organized tournament activity. West India holds 27.6% of the India golf equipment market in 2025, anchored by strong club membership networks, growing luxury golf resort developments across high urban affluence levels, and supporting consistent premium equipment spend.
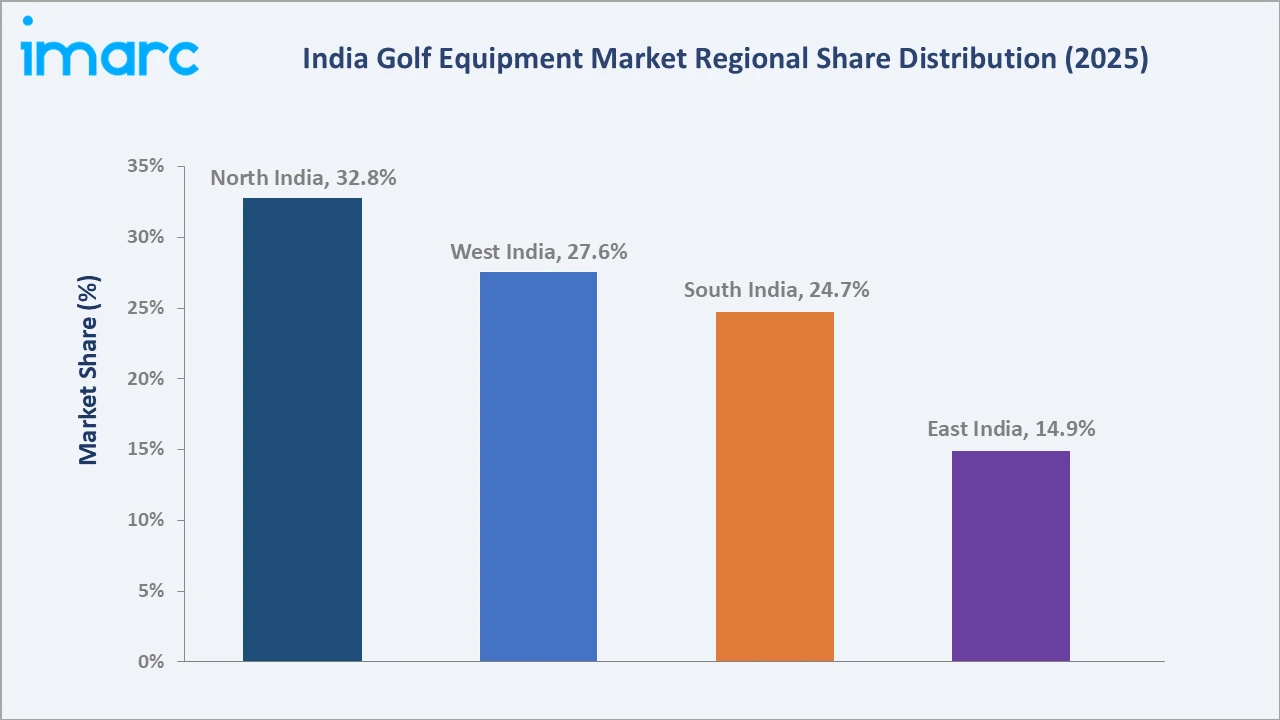
South India accounts for 24.7% of the India golf equipment market in 2025, driven by expanding golf infrastructure investment, growing resort-linked golf tourism, and rising professional tournament activity supported by state golf associations and private club development. East India represents 14.9% of the India golf equipment market in 2025 and is the smallest regional contributor.
Competitive Landscape
The India golf equipment market is moderately concentrated, with global brands holding dominant positions across premium product categories. The top players compete on the basis of technology differentiation, brand strength, fitting expertise, and distribution reach. Emerging players and regional distributors compete in the mid-market and lifestyle segments.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Callaway Golf Company | Golf Clubs, Balls, Accessories | Market Leader | Callaway Golf Company plays a major role in shaping India's golf equipment and technology landscape through direct retail presence, custom fitting facilities, and a global tech center. |
| PING | Golf Clubs | Established Player | PING plays a major role in the Indian golf equipment market by delivering high-precision engineering, custom-fit options, and industry-standard golf clubs to local players through authorized channels. |
| Mizuno Golf | Golf Clubs, Balls, Accessories | Innovator | Mizuno Golf occupies a premium, purist-focused niche in the Indian golf equipment market. |
| adidas Group | Golf Apparel, Shoes and Accessories | Established Player | The adidas Group plays a distinct, focused role in the Indian golf market by providing high-performance golf footwear, apparel, and lifestyle gear. |
Competition in the India golf equipment market is intensifying as global brands invest in India-specific retail expansion, fitting centers, and tournament sponsorships. Market leaders are differentiating through technology investment and custom fitting capabilities, while emerging players target the lifestyle and fashion segments to build brand presence among younger urban golfers.
Key Company Profiles
Callaway Golf Company
Callaway Golf Company is a leading manufacturer of premium golf equipment, offering a comprehensive portfolio of clubs, balls, and accessories serving professional tour players and serious amateur golfers. The company is recognized for its consistent technology innovation and broad global distribution network serving multiple geographies, including India.
- Key Products: Golf Clubs, Balls, Accessories.
- Strategic Focus: Expanding India market presence through premium custom fitting services, technology-led product innovation, and strategic retail partnerships with specialty golf stores and online channels to serve performance-oriented golfers.
PING
PING is a manufacturer of premium custom-fit golf clubs, recognized for its engineering precision and personalized fitting approach. The company serves serious amateur and professional golfers seeking equipment optimized for their individual swing characteristics and performance requirements.
- Key Products: Golf Clubs.
- Strategic Focus: Expanding custom fitting services and personalized equipment consultation in India, building authorized dealer networks, and reinforcing precision engineering brand values among performance-oriented urban golfers.
Market Concentration Analysis
The India golf equipment market exhibits moderate concentration at the premium segment level, where leading global brands hold dominant positions through established distribution networks, brand equity, and technology differentiation. The top players collectively account for a significant proportion of organized sector premium equipment sales, maintaining leadership positions reinforced by consistent product innovation and marketing investment.
The broader market, including mid-range and lifestyle equipment categories, is more fragmented, with regional distributors, multi-brand sporting goods chains, and emerging local brands competing for share in price-sensitive consumer segments. This fragmentation creates ongoing opportunities for organized premium brands to deepen retail penetration and formalize distribution channels across underserved geographic markets.
Investment & Growth Opportunities
Highest Growth Segments
Golf apparel and footwear at a 5.2% CAGR represents the highest-growth opportunity within the India golf equipment market, driven by the growing lifestyle and fashion appeal of the sport among urban professionals. Online stores at 26.8% share represent the most dynamic channel investment opportunity, with digital platforms enabling cost-effective national reach at scale.
Investment Themes
- Golf Retail Infrastructure: Investment in specialty golf stores, custom fitting centers, and on-course retail infrastructure across metro and emerging tier-2 markets represents a high-return opportunity as participation volumes expand and premium equipment demand grows.
- Digital and E-commerce Distribution: Building online retail capabilities, direct-to-consumer platforms, and digital product discovery tools offers scalable investment return as India's golf consumer base increasingly purchases premium equipment online.
- Women and Junior Golf Equipment: Dedicated product development and distribution for women's and junior golf segments offers first-mover advantage in an underpenetrated market with strong long-term participation growth potential through 2034.
Future Market Outlook (2026-2034)
The India golf equipment market grew from USD 278.7 Million in 2025 to USD 292.4 Million in 2026, reaching USD 395.4 Million by 2034 at a CAGR of 3.84% during 2026-2034. The market is expected to reach USD 336.6 Million by 2030, as growing golf course completions, expanding tournament activity, and broadening online distribution collectively sustain above-average demand growth across all equipment segments.
Three structural forces will define the India golf equipment market through 2034. First, continued golf infrastructure investment and course development will expand the active player base, sustaining broad-based equipment demand. Second, technology-driven product differentiation in smart equipment, GPS tools, and custom fitting will gradually shift value toward higher-margin, performance-led product categories. Third, the progressive adoption of online retail and direct-to-consumer channels will improve market accessibility, enabling global brands to serve India's geographically dispersed golfer base more efficiently and cost-effectively through the forecast period.
Research Methodology
Primary Research
Primary research comprised structured consultations with golf equipment distributors, specialty store operators, golf club management executives, tournament organizers, and premium golf equipment brand representatives in India. These discussions validated market sizing estimates, assessed distribution channel dynamics, and provided competitive positioning insights across the India golf equipment sector.
Secondary Research
Secondary research drew on published industry data including golf association membership records, corporate annual reports and investor presentations, e-commerce platform sales trend data, golf course development project databases, and trade publications covering Indian sports and leisure equipment markets. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical market growth rates, golf participation trajectory analysis, golf course development pipeline data, e-commerce channel penetration projections, premium lifestyle expenditure trends, macroeconomic indicators including GDP growth and urban household income growth, and competitive capacity investment signals from leading global golf equipment manufacturers.
India Golf Equipment Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Golf Clubs, Golf Balls, Golf Bags and Accessories, Golf Apparel and Footwear |
| Distribution Channels Covered | Specialty Stores, Sporting Goods Chains, On-Course Shops, Online Stores, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Callaway Golf Company, PING, Mizuno Golf, adidas Group, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India golf equipment market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India golf equipment market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India golf equipment industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Golf Equipment Market Report
The India golf equipment market reached USD 292.4 Million in 2026, driven by growing golf participation, rising urban affluence, and expanding golf course and resort infrastructure across India.
The market is projected to grow at a CAGR of 3.84% during 2026-2034, supported by rising golf participation, online retail expansion, smart equipment adoption, and premium lifestyle spending.
The market is projected to reach approximately USD 336.6 Million by 2030, supported by growing golf course completions, expanding tournament participation, and broadening online distribution channels.
Golf clubs lead with a 38.6% share in 2025, driven by regular performance upgrades among active golfers and increasing adoption of custom-fitted premium club sets across metro cities.
Specialty stores lead with a 29.7% share in 2025, supported by expert fitting services and authorized product ranges.
North India leads with a 32.8% share in 2025, reflecting the highest concentration of established golf clubs, corporate memberships, and organized tournament activity in Delhi NCR and surrounding areas.
Key players include Callaway Golf Company, PING, Mizuno Golf, and adidas Group, among others.
The market is projected to reach USD 395.4 Million by 2034, driven by sustained golf participation growth, technology-led equipment innovation, premium lifestyle spending, and expanding online retail distribution.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade