India Metal Forging Market Size, Share, Trends and Forecast by Material, Technique, Installation Capacity, End User, and Region, 2026-2034
India Metal Forging Market Size, Share, Trends & Forecast (2026-2034)
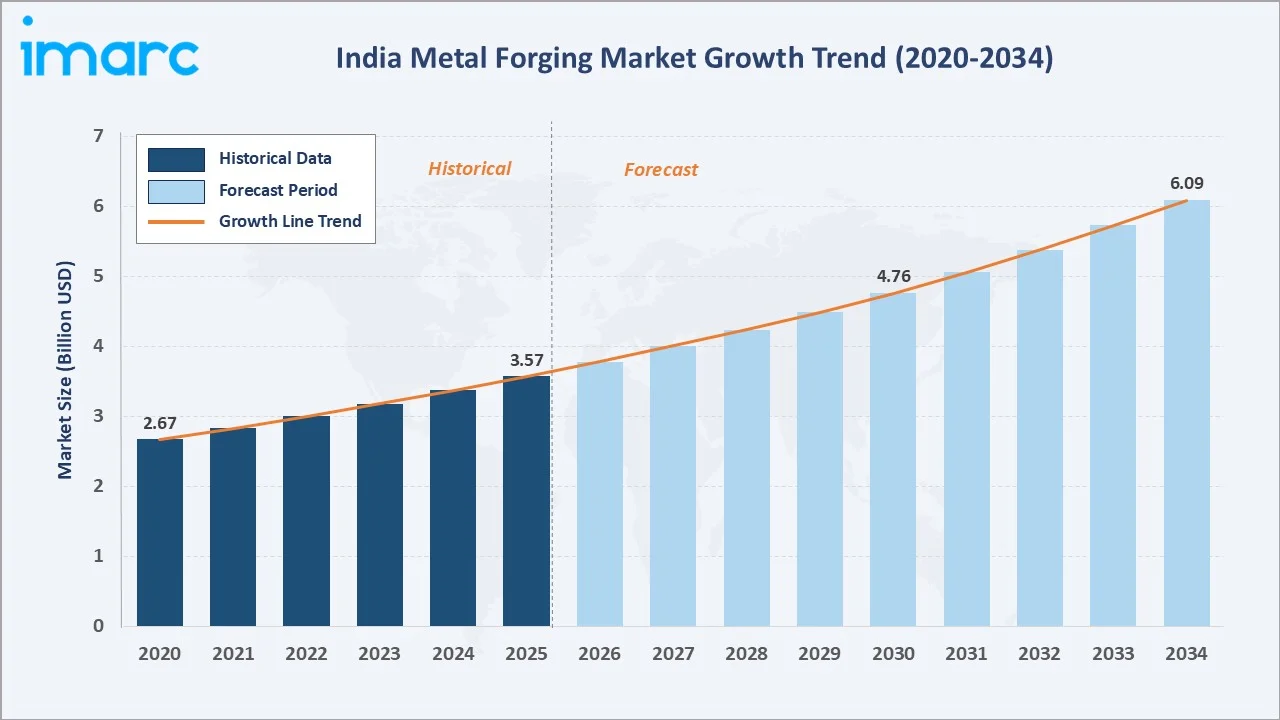
The India metal forging market reached USD 3.57 Billion in 2025 and is projected to reach USD 6.09 Billion by 2034, growing at a CAGR of 5.93% during 2026-2034. Growth is driven by rising automotive production, infrastructure investment under the National Infrastructure Pipeline, and aerospace and defense indigenization. India's automotive industry, the third-largest in the world by volume, continues to generate sustained demand for forged crankshafts, connecting rods, and axle components, while government-backed manufacturing programmes are expanding the addressable base for domestic forging capacity.
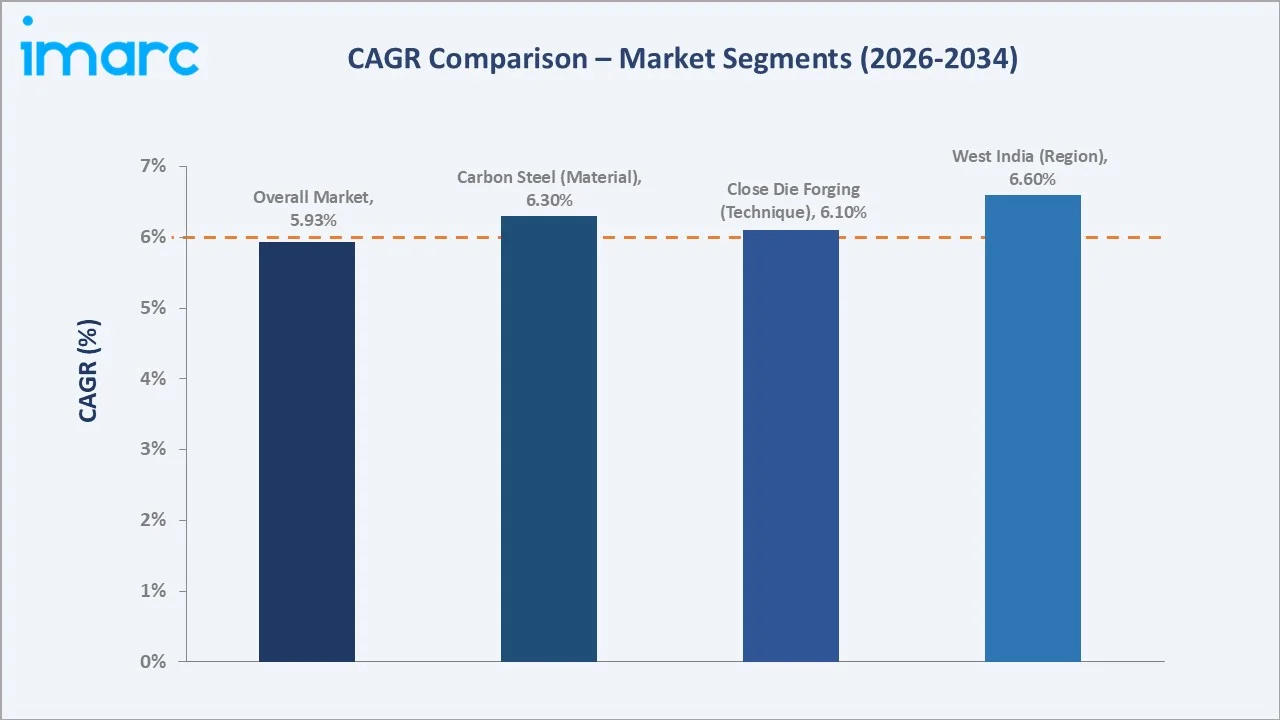
Carbon steel leads the material segment at 46.8%, reflecting its strength-to-cost advantage in high-volume automotive and structural applications, while West India commands 38.7% of regional share, anchored by an established forging manufacturing base.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 3.57 Billion |
|
Forecast Market Size (2034) |
USD 6.09 Billion |
|
CAGR (2026-2034) |
5.93% |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Material |
Carbon Steel (46.8%, 2025) |
|
Dominant Technique |
Close Die Forging (58.7%, 2025) |
|
Leading Region |
West India (38.7%, 2025) |
The market expanded from an estimated USD 2.67 Billion in 2020 to USD 3.57 Billion in 2025, supported by post-pandemic industrial recovery and steady automotive output growth, and is anchored at USD 6.09 Billion by 2034.
To get more information on this market, Request Sample
Year-on-year growth is expected to remain broadly consistent across the forecast period, without the sharp cyclical disruptions that characterized the early part of the historical period.
Executive Summary
The India metal forging market reached USD 3.57 Billion in 2025 and is forecast to reach USD 6.09 Billion by 2034 at a 5.93% CAGR, driven by automotive, infrastructure, and aerospace and defense demand. Carbon steel dominates the material mix at 46.8% on cost-effectiveness and strength for automotive and structural applications, followed by alloy steel at 28.4% and stainless steel at 17.9%.
West India leads regionally at 38.7% on an established forging manufacturing base, followed by South India at 29.6%, North India at 19.4%, and East India at 12.3%.
Key Market Insights
|
Insight |
Data |
|
Dominant Material |
Carbon Steel - 46.8% share (2025) |
|
Dominant Technique |
Close Die Forging - 58.7% share (2025) |
|
Leading Region |
West India - 38.7% market share (2025) |
|
Market Opportunity |
Aluminium forgings for EV lightweighting; aerospace and defense forgings; precision automated forging capacity |
Key Analytical Observations Supporting the Above Data:
- Carbon Steel at 46.8%: Carbon steel dominates on its strength-to-cost ratio and wide use in automotive powertrain and chassis components, reinforced by high-volume production for domestic and export original equipment manufacturers. Its cost stability and broad process compatibility keep it the default specification across most volume automotive programmes.
- Close Die Forging at 58.7%: Close die forging dominates the technique segment on its ability to deliver high dimensional accuracy and strong repeatability at scale, making it the default process for automotive crankshafts, connecting rods, and axle components produced in high volumes. Its efficient material utilization and minimal secondary machining requirement keep production costs competitive relative to open die and ring forging alternatives.
- West India at 38.7%: West India leads through an established forging cluster with proximity to automotive original equipment manufacturers and port-based export infrastructure, which together support faster turnaround for both domestic supply and overseas shipments.
India Metal Forging Market Overview
The India metal forging market encompasses the design, manufacture, and supply of forged metal components used across automotive, aerospace and defense, railway, industrial machinery, marine, and other end-use industries. Forging processes shape heated or cold metal billets using compressive force through pressing, hammering, or rolling, producing components with superior strength, durability, and structural integrity compared with cast or machined alternatives. This structural advantage makes forged components the preferred choice for safety-critical and high-stress applications, including powertrain, chassis, and landing gear parts, where failure tolerance is minimal.
The ecosystem integrates raw material and alloy suppliers, forging and machining manufacturers, tooling and equipment suppliers, quality testing and certification bodies, original equipment manufacturers and end-use industries, and distributors and aftermarket suppliers.
Market Dynamics
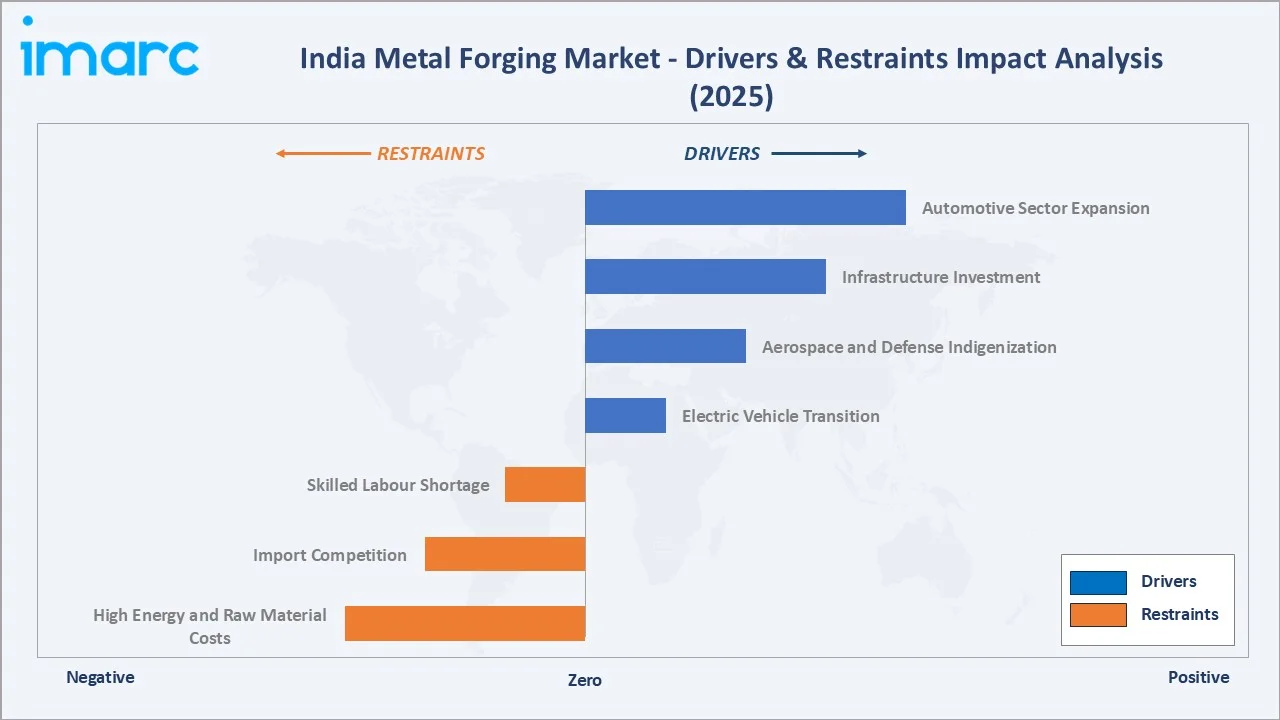
To evaluate market opportunities, Request Sample
Market Drivers
- Automotive Sector Expansion: India's position as the world's third-largest automobile market drives sustained demand for forged crankshafts, connecting rods, and axle components across passenger, commercial, and two-wheeler vehicles. Rising domestic vehicle ownership and export-oriented vehicle manufacturing both contribute to this sustained order volume. Growing localization of component sourcing by global automakers operating in India is further reinforcing demand for domestically forged powertrain and chassis parts. As vehicle platforms diversify across fuel types, forging suppliers with flexible tooling capability are best positioned to capture this broadening order base.
- Infrastructure Investment: Government programmes such as the National Infrastructure Pipeline and Make in India are expanding demand for forged components in construction machinery, railways, and industrial equipment, as large-scale capital projects increase procurement of heavy-duty forged parts. Sustained public capital expenditure across roads, ports, and rail networks is creating multi-year visibility for forging suppliers serving construction and industrial equipment manufacturers. This visibility is encouraging capacity investment decisions that would otherwise be deferred under shorter-cycle demand assumptions.
- Aerospace and Defense Indigenization: Rising domestic defense procurement and aerospace localization, including landing gear and artillery system components, are creating high-value forging opportunities for manufacturers able to meet stringent qualification and certification requirements. Defense indigenization policy is actively steering procurement toward domestic suppliers, reducing reliance on imported forged components for critical defense platforms. Manufacturers that secure early qualification on these programmes typically retain preferred-supplier status for multiple subsequent procurement cycles.
- Electric Vehicle Transition: Growing EV production is boosting demand for lightweight aluminium forgings for drivetrain and structural applications, diversifying the traditional carbon steel-led product mix and creating new specialization opportunities for forward-looking manufacturers. As EV platforms mature, motor housings, suspension components, and battery enclosure supports are emerging as new forged component categories. Suppliers that develop aluminium forging expertise ahead of broader industry adoption stand to capture disproportionate early-mover share.
Market Restraints
- High Energy and Raw Material Costs: Energy-intensive forging processes and volatile steel and alloy prices raise production costs and compress margins, particularly for smaller MSME forging units that lack the scale to hedge input cost exposure. Electricity and furnace fuel costs represent a substantial share of total production expense, leaving margins exposed to broader energy market volatility. Manufacturers without long-term supply contracts for key alloy inputs are especially vulnerable to sudden price swings that erode already thin margins.
- Import Competition: Low-cost forged component imports, particularly from China, exert pricing pressure on domestic manufacturers and limit share gains for smaller players competing primarily on price rather than quality certification. This competitive pressure is most acute in standardized, lower-complexity component categories where differentiation on quality or lead time is difficult to sustain. Domestic manufacturers are increasingly required to compete on total cost of ownership rather than unit price alone to retain share against import competition.
- Skilled Labour Shortage: Limited availability of skilled labour for precision and automated forging processes constrains capacity utilization and slows technology adoption among mid-tier manufacturers, extending qualification timelines for new equipment investments. Training pipelines for specialized forging and metallurgical skills have not kept pace with industry modernization, leaving a persistent gap between available talent and evolving technical requirements. This shortage is particularly pronounced for roles combining traditional forging expertise with newer automation and quality-system skills.
Market Opportunities
- Aluminium and Lightweight Alloy Forging Development: Growing electric vehicle production is creating opportunities for manufacturers to develop lightweight aluminium and alloy forging capabilities, addressing a segment currently underrepresented relative to traditional carbon steel forgings and positioning early movers ahead of broader industry adoption. Manufacturers that build this capability now are likely to secure preferred-supplier status as automakers finalize next-generation EV platform sourcing decisions. Cross-training existing steel forging teams on aluminium-specific processes can accelerate this transition without requiring entirely new workforce recruitment.
- Export Market Expansion: Competitive labour costs and improving quality standards are supporting India's position as an export base for forged automotive and industrial components to North American and European original equipment manufacturers seeking to diversify their supplier base. Ongoing global supply chain diversification away from single-country sourcing concentration is creating incremental opportunities for Indian manufacturers with proven export quality track records. Manufacturers that invest in internationally recognized certifications are best positioned to convert this structural shift into long-term export contracts.
Market Challenges
- Technology Upgradation Costs: Transitioning from manual to automated, precision forging equipment requires significant capital outlay, which can be difficult for smaller manufacturers to justify against uncertain near-term order visibility and longer equipment payback periods. Financing constraints faced by smaller and mid-tier manufacturers further limit their ability to fund large upfront automation investments without external capital support. This dynamic risks widening the competitive gap between well-capitalized integrated players and smaller regional forging units over time.
- Raw Material Price Volatility: Fluctuations in steel and alloy input prices complicate long-term pricing agreements with original equipment manufacturers and create margin pressure during periods of rapid input cost inflation, particularly for fixed-price supply contracts. Manufacturers with limited pricing pass-through mechanisms in existing contracts bear a disproportionate share of this risk during periods of sustained input cost escalation. Building more flexible, indexed pricing arrangements with key customers is becoming an increasingly important risk mitigation strategy.
Emerging Market Trends
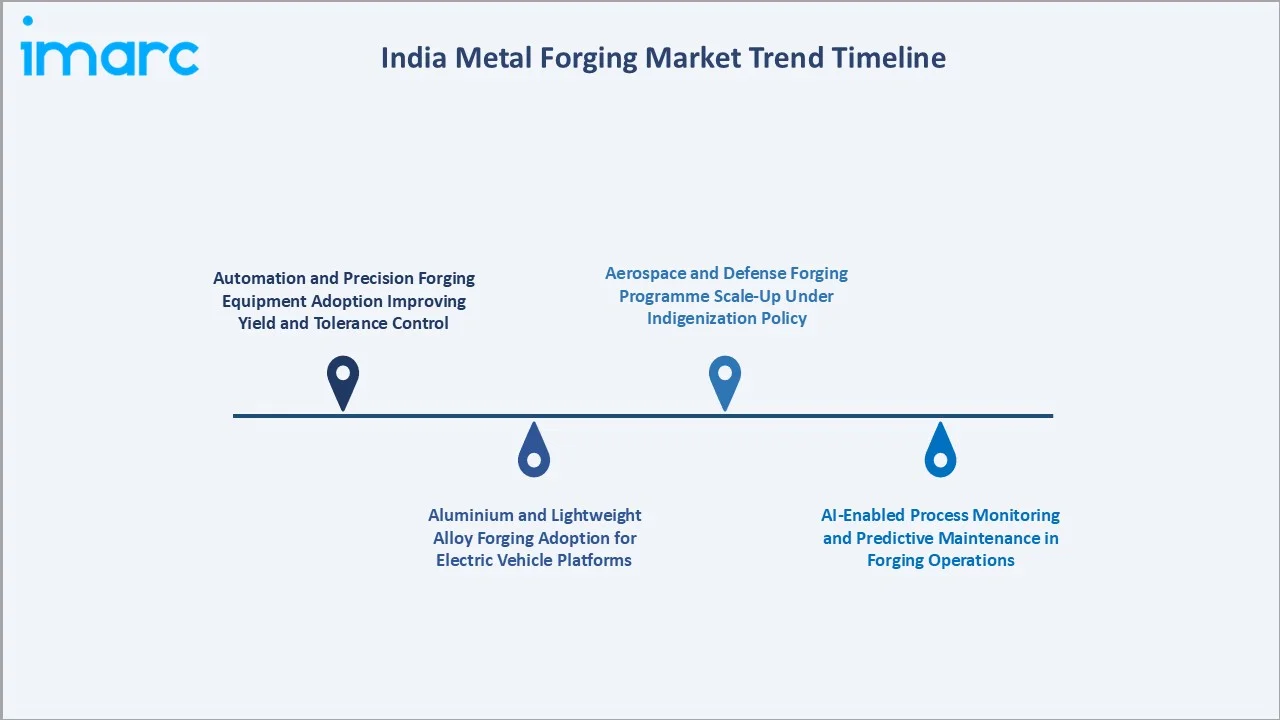
1. Automation and Precision Forging Equipment Adoption Improving Yield and Tolerance Control
Adoption of automated forging presses, robotic material handling, and in-line dimensional inspection is progressively displacing conventional manual processes across mid-to-large manufacturing facilities. This shift improves material yield, reduces scrap rates, and supports tighter dimensional tolerance compliance demanded by automotive and aerospace customers. Compact, sensor-integrated forging lines also reduce cycle times and labour dependency, increasing demand for manufacturers capable of financing and operating advanced equipment. As original equipment manufacturers tighten quality and traceability requirements across their supplier base, automated process monitoring is becoming a qualifying criterion rather than a differentiator, accelerating adoption timelines across the mid-tier manufacturing segment.
2. Aluminium and Lightweight Alloy Forging Adoption for Electric Vehicle Platforms
Aluminium and lightweight alloy forging adoption is emerging as automakers pursue electric vehicle powertrain weight reduction to extend battery range and improve efficiency. This shift is creating demand for forging capability beyond traditional carbon steel processing, particularly for motor housings, suspension components, and structural battery enclosure supports. As electric vehicle platforms scale, manufacturers developing early aluminium forging expertise are positioning themselves for long-term platform sourcing relationships.
3. Aerospace and Defense Forging Programme Scale-Up Under Indigenization Policy
Aerospace and defense forging programme scale-up is emerging as domestic indigenization policy steers procurement toward qualified local suppliers for landing gear, structural, and artillery system components. These programmes demand tighter tolerances, extensive material traceability, and rigorous certification compared with standard automotive forgings. As defense procurement budgets continue to prioritize domestic sourcing, manufacturers that secure early qualification are positioned to capture multi-year, high-value order commitments.
4. AI-Enabled Process Monitoring and Predictive Maintenance in Forging Operations
Artificial intelligence-enabled process monitoring and predictive maintenance are emerging as manufacturers seek to reduce unplanned downtime and improve first-pass yield across forging and machining operations. Sensor-driven analytics can flag die wear, temperature deviation, and material defects earlier than manual inspection, reducing scrap and rework costs. As adoption expands across larger manufacturers, predictive maintenance capability is expected to become an increasingly important differentiator for suppliers competing on total cost of ownership rather than unit price alone.
Industry Value Chain Analysis
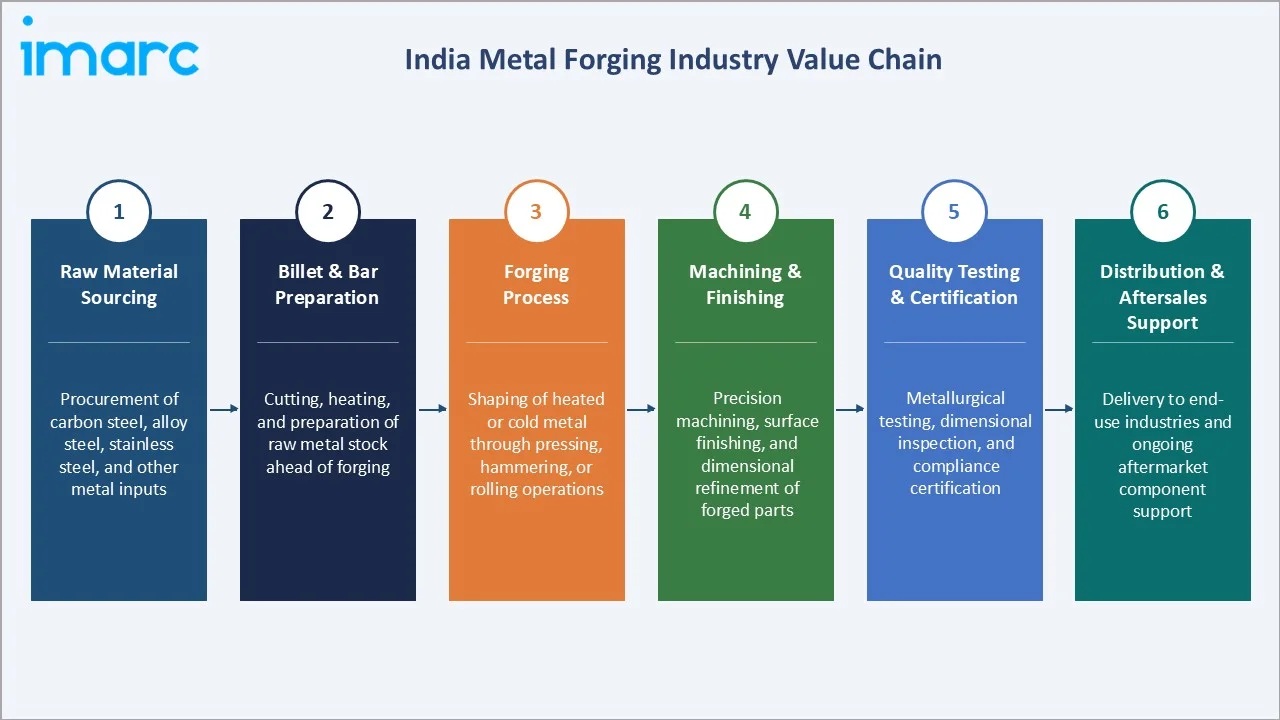
The India metal forging value chain spans raw material sourcing, billet and bar preparation, the core forging process, machining and finishing, quality testing and certification, and distribution and aftersales support. Each stage requires distinct technical capability, and integration across stages is increasingly valued by original equipment manufacturers seeking consolidated, quality-assured supply relationships. Manufacturers that control multiple adjacent stages, particularly forging through machining, are generally better positioned to offer shorter lead times and tighter quality control than single-stage suppliers reliant on external subcontracting.
|
Stage |
Description |
|
Raw Material Sourcing |
Procurement of carbon steel, alloy steel, stainless steel, and other metal inputs |
|
Billet & Bar Preparation |
Cutting, heating, and preparation of raw metal stock ahead of forging |
|
Forging Process |
Shaping of heated or cold metal through pressing, hammering, or rolling operations |
|
Machining & Finishing |
Precision machining, surface finishing, and dimensional refinement of forged parts |
|
Quality Testing & Certification |
Metallurgical testing, dimensional inspection, and compliance certification |
|
Distribution & Aftersales Support |
Delivery to end-use industries and ongoing aftermarket component support |
Technology Landscape in the India Metal Forging Industry
Close Die Forging Technology
Close die forging offers high dimensional accuracy, strong repeatability, and efficient material utilization for components produced at scale. The technique confines heated metal within matched dies under compressive force, producing near-net-shape parts that require minimal secondary machining. Its widespread adoption across automotive crankshaft, connecting rod, and axle component manufacturing reflects the technique's cost efficiency at high production volumes.
Open Die Forging Technology
Open die forging support larger, lower-volume components such as shafts, rollers, and heavy industrial parts where flexibility in size and shape outweighs the need for tight dimensional tolerances. The technique shapes metal between flat or simple-contour dies without fully enclosing the workpiece, making it well suited to custom and low-volume industrial and marine applications.
Ring Forging Technology
Ring forging serves applications such as bearing races, flanges, and railway wheel blanks, where seamless circular geometry provides structural advantages over welded or cast alternatives. Rising railway wheel manufacturing investment and bearing component demand from industrial machinery are supporting steady growth in this technique segment.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Material |
Carbon Steel |
46.8% |
2025 |
|
Technique |
Close Die Forging |
58.7% |
2025 |
|
Installation Capacity |
🔒 |
🔒 |
2025 |
|
End-User |
🔒 |
🔒 |
2025 |
|
Region |
West India |
38.7% |
2025 |

By Material
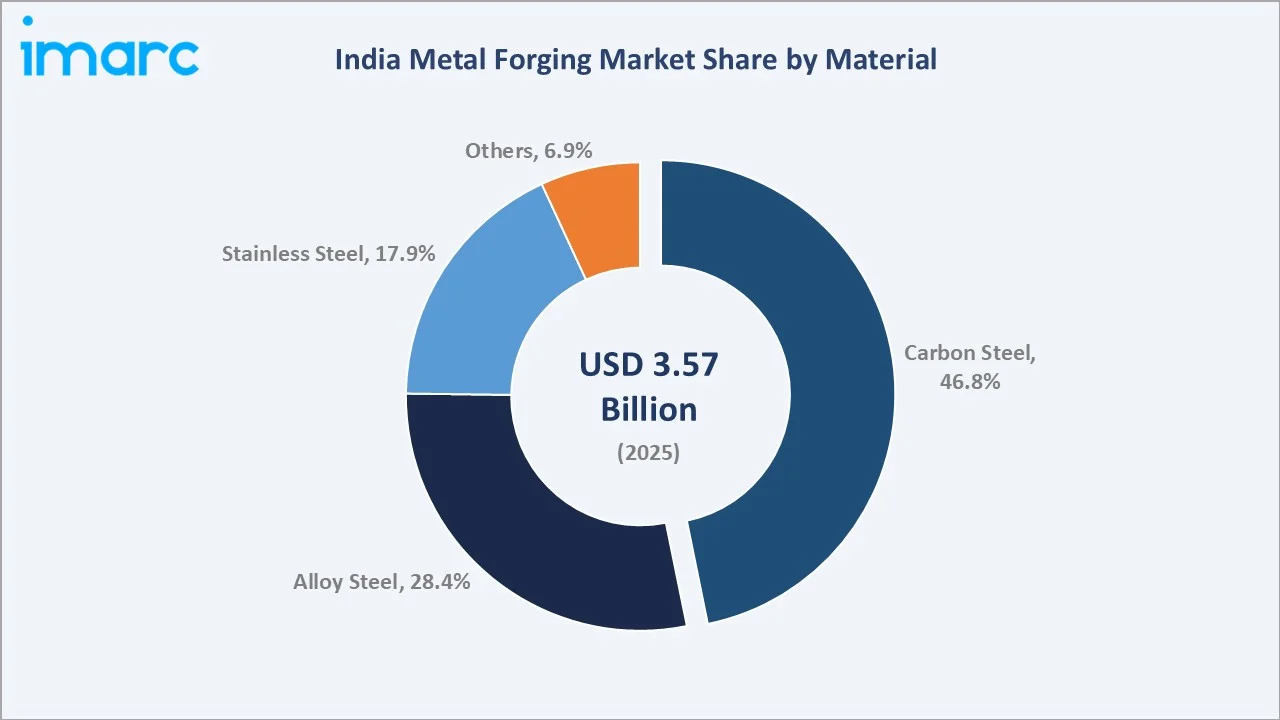
To access detailed market analysis, Request Sample
Carbon steel leads the material segment at 46.8% in 2025, reflecting its dominant use in automotive and structural forgings. Alloy steel follows at 28.4%, driven by demand for high-strength components in commercial vehicles and industrial machinery. Stainless steel holds 17.9%, used in corrosion-resistant aerospace and marine applications, while other materials, including aluminium and titanium, account for 6.9%, led by EV lightweighting demand.
By Technique
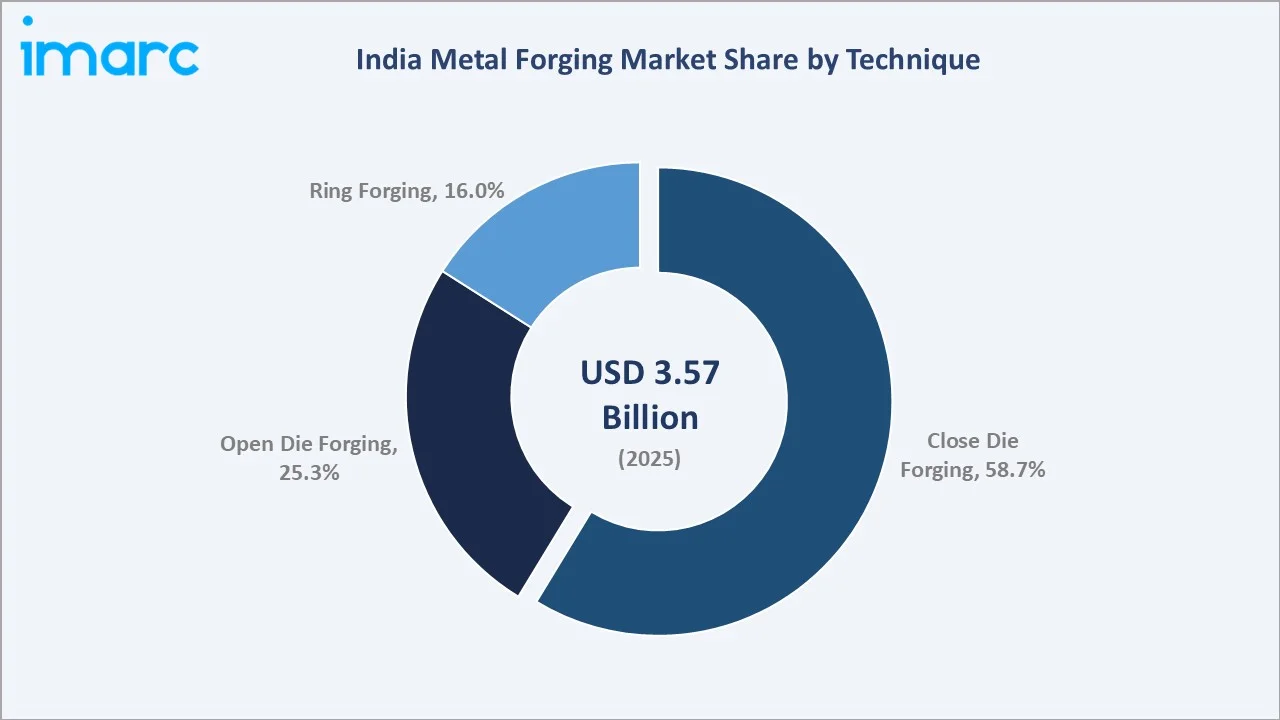
Close die forging leads the technique segment at 58.7%, reflecting its dominant use in high-volume automotive and industrial component production. Open die forging follows at 25.3%, serving larger, lower-volume industrial parts, while ring forging accounts for 16.0%, driven by bearing, flange, and railway wheel blank demand.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
West India |
38.7% |
Supported by an established forging manufacturing base, automotive original equipment manufacturer proximity, and export-oriented infrastructure |
|
South India |
29.6% |
Driven by automotive and industrial manufacturing activity and a growing base of component exporters |
|
North India |
19.4% |
Backed by expanding manufacturing activity and growing defense and railway procurement |
|
East India |
12.3% |
Driven by railway wheel and heavy engineering forging demand, and expanding industrial machinery output |
West India's automotive-heavy base gives it the most direct exposure to passenger and commercial vehicle production cycles, while East India's railway and heavy engineering orientation provides a comparatively steadier, infrastructure-linked demand profile less sensitive to short-term automotive fluctuations.
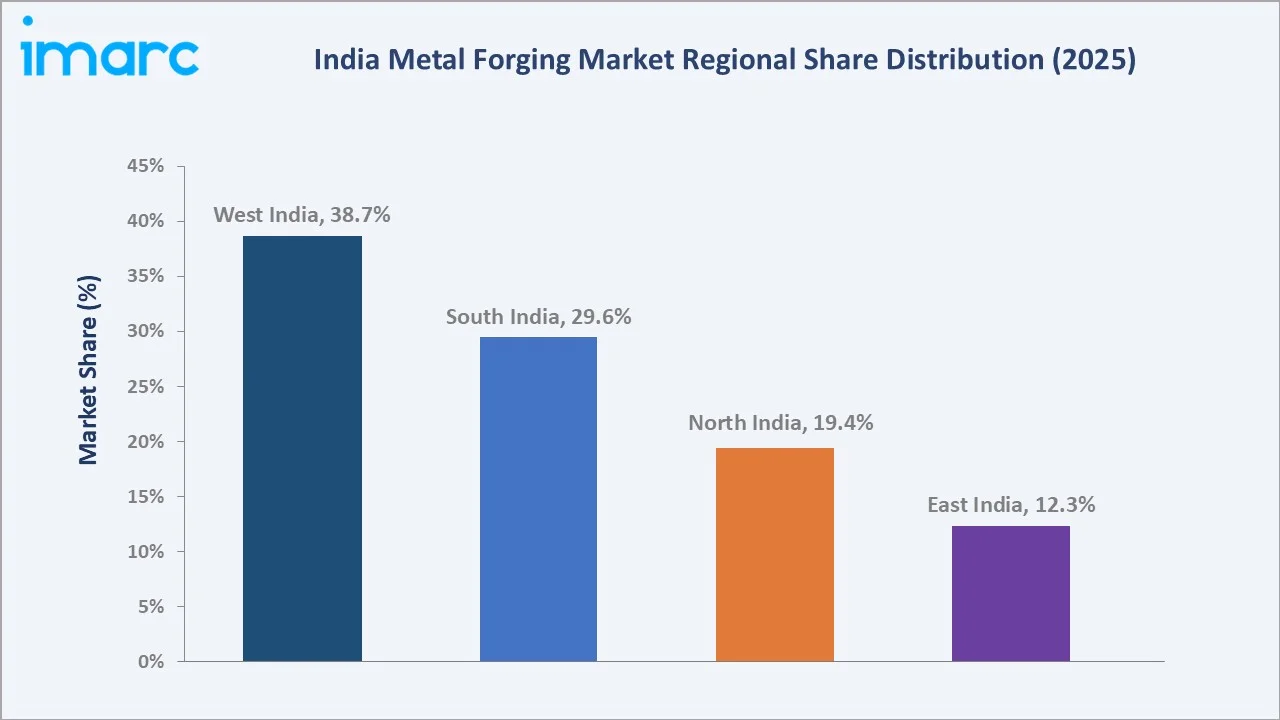
West India's leadership reflects a long-established forging manufacturing base, while South India's growth stems from automotive and industrial diversification. North and East India are gaining share as defense indigenization and railway modernization programmes expand forged component demand outside the traditional western hub.
Competitive Landscape
The India metal forging market is moderately concentrated, led by integrated forging majors alongside regional and mid-tier component specialists serving automotive, railway, and industrial end users. Competitive differentiation increasingly rests on process automation, quality certification breadth, and the ability to service export and defense-linked programmes in addition to core domestic automotive demand.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Bharat Forge |
Close Die Forging, Open Die Forging |
Market Leader |
Largest Indian forging player with global manufacturing footprint and automotive-to-defense diversification |
|
Ramkrishna Forgings LTD. |
Hammer & Upsetter Forgings, Ring Rolling, Cold Forging, Warm Forging, Aluminium Forging |
Strong Challenger |
High-volume automotive forgings with expanding EV and railway wheel manufacturing capacity |
|
CIE Automotive |
Forged & Machined Auto Components |
Strong Challenger |
Integrated forging-to-machining capability serving domestic and export OEMs |
|
M M Forgings Limited |
Precision Automotive & Industrial Forgings |
Established Player |
Export-oriented precision forging with diversified end-user base |
|
ISGEC Heavy Engineering Ltd. |
Heavy Forgings for Industrial Equipment |
Niche Player |
Specialization in heavy and open-die forgings for industrial machinery |
Key players include Bharat Forge, Ramkrishna Forgings LTD., CIE Automotive, M M Forgings Limited, ISGEC Heavy Engineering Ltd., and others.
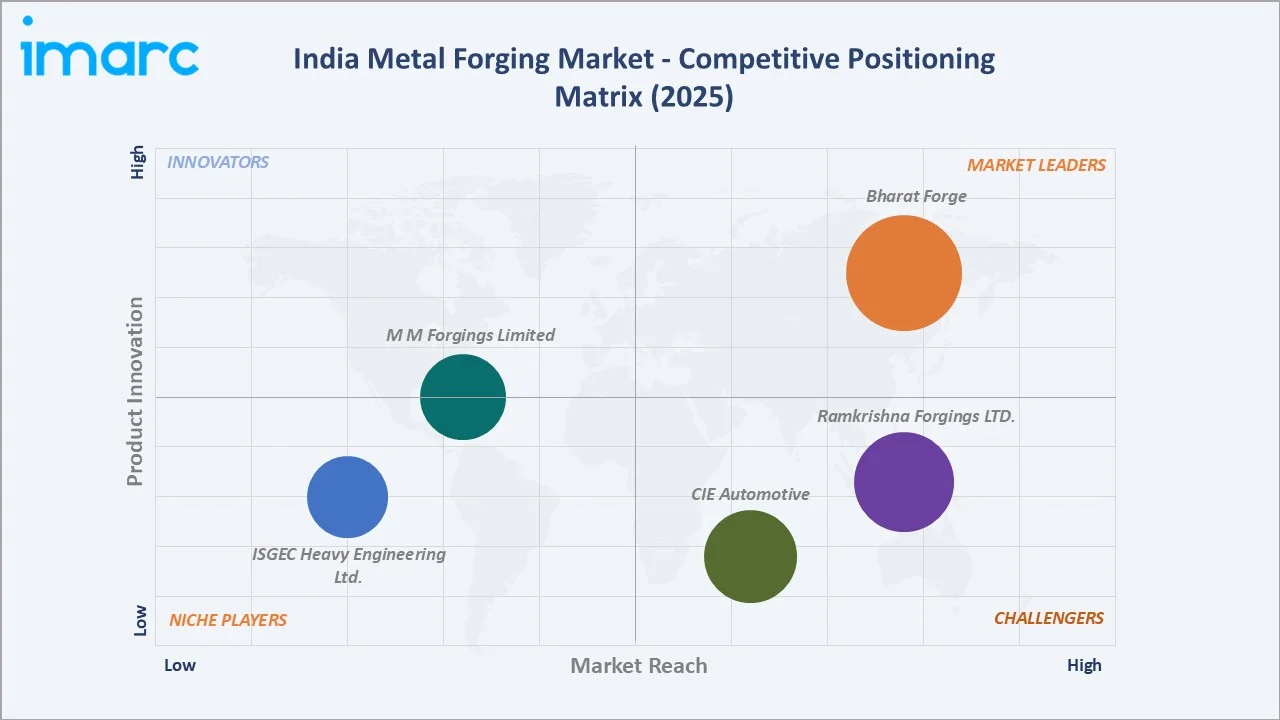
Key Company Profiles
Bharat Forge
Bharat Forge is a Pune-headquartered forging company with manufacturing operations across India, Germany, Sweden, and North America, serving automotive, industrial, aerospace, and defense customers worldwide. Its scale and geographic diversification give it a broader end-market base than most domestic peers.
- Key Products: Close Die Forging, Open Die Forging
- Recent Developments: In May 2026, Bharat Forge secured a long-term contract with Embraer to manufacture and supply critical landing gear forgings for the aircraft manufacturer's commercial and defense aircraft programs. With this agreement, Bharat Forge becomes the first Indian company to join Embraer’s global aerospace supply chain as a supplier of forged components.
- Strategic Focus: Diversifying from automotive forging into aerospace, defense, and electric vehicle components, while continuing to expand its global manufacturing and customer base. The company is prioritizing capacity investment in high-precision, tight-tolerance forging lines to serve premium aerospace and defense programmes alongside its core automotive business. It is also pursuing selective acquisitions and partnerships to accelerate entry into adjacent component categories, including axle and drivetrain systems for electric commercial vehicles.
Ramkrishna Forgings LTD.
Ramkrishna Forgings is a Kolkata-headquartered forging company supplying cold and hot forged components to automotive and railway customers in India and overseas, with a growing footprint in export markets.
- Key Products: Hammer & Upsetter Forgings, Ring Rolling, Cold Forging, Warm Forging, Aluminium Forging
- Recent Developments: In May 2026, Ramkrishna Forgings started commercial production of forged wheels at its Chennai manufacturing facility, marking the company's entry into the forged wheel manufacturing segment.
- Strategic Focus: Expanding railway wheel capacity and electric vehicle powertrain component exports, alongside continued investment in automated forging capacity. The company is scaling its cold forging operations to serve growing international demand for precision powertrain components, while its railway joint venture positions it to capture a larger share of domestic wheel replacement and new rolling stock manufacturing programmes over the coming years.
Market Concentration Analysis
The India metal forging market is moderately concentrated at the Tier-1 automotive supply level, with the leading integrated forging manufacturers collectively accounting for a substantial share of domestic automotive and industrial forging revenue. Mid-tier and regional forging units continue to serve price-sensitive segments and localized industrial demand, while consolidation is gradually occurring as larger players expand capacity and pursue backward integration into machining and aftersales support. Smaller manufacturers that cannot fund automation upgrades face growing pressure to specialize in niche geometries or low-volume runs where larger competitors have less cost advantage.
Investment & Growth Opportunities
Highest Growth Segments
Aluminium and lightweight alloy forgings for electric vehicle applications, aerospace and defense forgings, and precision automated forging capacity represent the highest-growth investment vectors through 2034, supported by structural shifts in automotive powertrain design and rising domestic defense procurement. Manufacturers positioned across more than one of these vectors are likely to see the most resilient order books through cyclical automotive demand swings.
Emerging Investment Opportunities
Aerospace and defense forging programmes represent the market's highest per-unit-value emerging opportunity, as landing gear, structural, and artillery system components command significantly higher per-unit revenue than standard automotive forgings, supported by sustained government indigenization commitments through the forecast period. Railway wheel and axle forging capacity is a related opportunity, benefiting from ongoing network modernization and rolling stock expansion programmes.
Investment Themes
- Automated and precision forging capacity expansion to meet rising quality and tolerance requirements from automotive and aerospace original equipment manufacturers, reducing dependence on manual, labour-intensive processes and improving production consistency.
- Aluminium and lightweight alloy forging capability development to capture growing electric vehicle powertrain demand, positioning manufacturers ahead of the broader industry shift away from traditional carbon steel components toward mixed-material platforms.
Future Market Outlook (2026-2034)
The India metal forging market is projected to grow from USD 3.57 Billion in 2025 to USD 6.09 Billion by 2034, delivering a 5.93% CAGR over the forecast period. The market's anchor value of USD 4.76 Billion in 2030 represents a forging industry in steady structural expansion, supported by automotive production growth, infrastructure investment, and aerospace and defense indigenization. Carbon steel forgings are expected to retain material leadership through the forecast period, while aluminium and alloy forgings gain incremental share as electric vehicle platforms scale, and precision automated forging lines become more prevalent among mid-to-large manufacturers.
Three structural forces define market growth through 2034. Automotive production growth creates a self-reinforcing demand cycle for forged powertrain and chassis components, as rising domestic vehicle output and export demand jointly support order volumes. Infrastructure and defense indigenization programmes are expanding forged component demand beyond traditional automotive applications, opening higher-value revenue pools for manufacturers able to meet stricter qualification standards. Regional diversification toward South, North, and East India is broadening the market's manufacturing base beyond its traditional western concentration, gradually reducing single-region supply concentration risk for original equipment manufacturer customers.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including manufacturing executives, procurement leads at original equipment manufacturers, and industry association representatives, supplemented by discussions with equipment suppliers and quality certification bodies to validate technology adoption trends.
Secondary Research
Secondary research encompassed company annual reports, government infrastructure and defense procurement data, industry association publications, and trade and manufacturing databases covering the India metal forging industry, along with published material on automotive production trends and export shipment data.
Forecasting Models
Market revenue forecasts were developed using a production-based bottom-up model incorporating end-use industry production forecasts, average forged component value by material and region, and technology and capacity utilization adjustments across the forecast period, cross-checked against historical market growth patterns for consistency.
India Metal Forging Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Materials Covered | Carbon Steel, Alloy Steel, Stainless Steel, Others |
| Techniques Covered | Close Die Forging, Open Die Forging, Ring Forging |
| Installation Capacities Covered | Small (100 MT to 12,500 MT), Medium (12,500 MT to 30,000 MT), Heavy (Above 30,000 MT) |
| End Users Covered | Automotive, Aerospace and Defense, Railway, Industrial Machinery, Marine, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Bharat Forge, Ramkrishna Forgings LTD., CIE Automotive, M M Forgings Limited, ISGEC Heavy Engineering Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India metal forging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India metal forging market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India metal forging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Metal Forging Market Report
The India metal forging market reached USD 3.57 Billion in 2025, driven by carbon steel forgings dominant at 46.8%, West India leading regionally at 38.7%, and sustained demand from the automotive, infrastructure, and aerospace and defense sectors. Continued automotive production growth and expanding infrastructure investment are expected to keep underlying demand on a steady upward trajectory through the remainder of the decade.
The India metal forging market grows at a 5.93% CAGR during 2026-2034, reaching USD 6.09 Billion by 2034, driven by automotive production growth, infrastructure investment, and aerospace and defense indigenization. This growth rate reflects a market transitioning from a primarily automotive-led demand base toward a more diversified mix of end-use industries.
Carbon steel leads at 46.8%, reflecting its strength-to-cost advantage in automotive and structural forgings, followed by alloy steel at 28.4%, stainless steel at 17.9%, and other materials at 6.9%. Aluminium and other lightweight alloys within the 'other materials' category are expected to gain incremental share as electric vehicle production scales.
West India leads at 38.7% through its established forging manufacturing base, followed by South India at 29.6%, North India at 19.4%, and East India at 12.3%. Regional share is expected to gradually rebalance as manufacturing investment expands into newer industrial corridors.
Leading companies include Bharat Forge, Ramkrishna Forgings LTD., CIE Automotive, M M Forgings Limited, ISGEC Heavy Engineering Ltd., and others.
The India metal forging market is projected to reach approximately USD 4.76 Billion by 2030, supported by continued automotive, infrastructure, and defense indigenization demand, with aluminium and alloy forgings beginning to capture a larger share of incremental market growth.
Key drivers include automotive sector expansion, infrastructure investment under the National Infrastructure Pipeline, aerospace and defense indigenization, and the electric vehicle transition boosting demand for lightweight aluminium forgings. High energy costs, import competition, and skilled labour shortages remain the primary restraints on faster growth.
Priority investment opportunities include automated and precision forging capacity expansion, aluminium and lightweight alloy forging capability development, and aerospace and defense forging programme participation, with railway wheel and axle manufacturing representing a related adjacent opportunity.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade