India Potato Chips Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034
India Potato Chips Market Size, Share, Trends & Forecast (2026-2034)
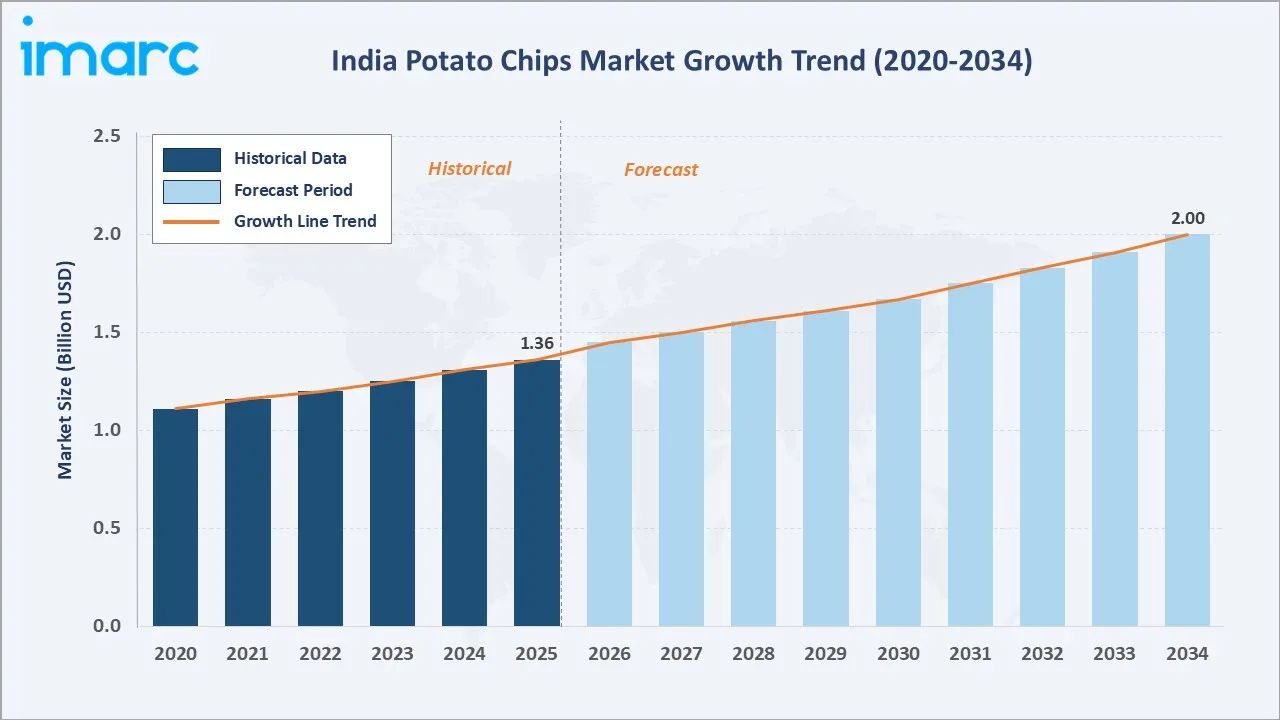
The India potato chips market grew from USD 1.36 Billion in 2025 to USD 1.45 Billion in 2026 and is projected to reach USD 2.00 Billion by 2034, growing at a CAGR of 4.13% during 2026-2034. Demand rests on one of the world's largest snack-consuming populations, where rising disposable incomes, modern retail penetration, and preference for packaged convenience foods are expanding the consumer base. Growth is supported by rapid urbanization and the spread of organized food retail and e-commerce across Tier I, II, and III cities. Flavor and format innovation, including health-oriented variants, is attracting new consumer segments. Regional flavor profiles, such as masala, spicy tomato, and tangy chutney-style seasonings, are resonating strongly with local palates, while baked, air-popped, and reduced-oil formats are broadening appeal among health-conscious urban shoppers.
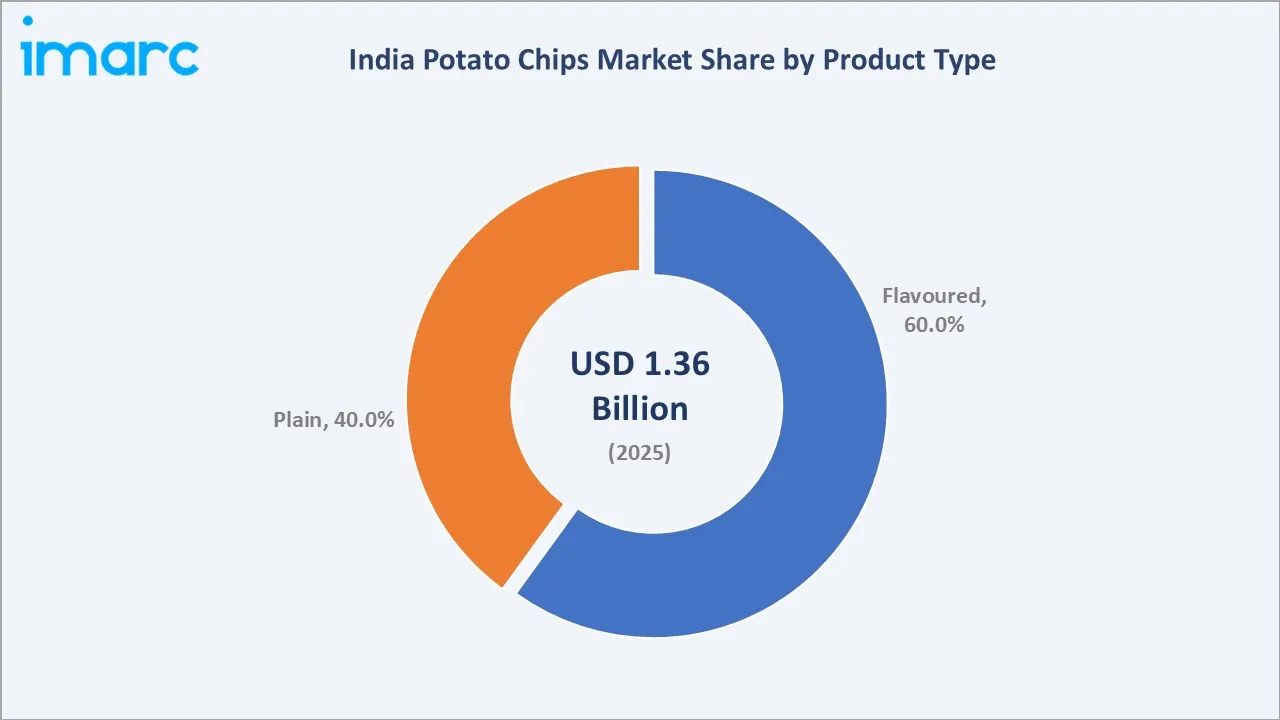
Flavoured potato chips dominate at 60.0%, driven by the strong consumer preference for spiced and masala variants that align with Indian taste profiles. Convenience Stores lead distribution at 40.0%, reflecting the dense network of kirana stores and modern trade outlets across urban and semi-urban India.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.36 Billion |
|
Market Size (2026) |
USD 1.45 Billion |
|
Forecast Market Size (2034) |
USD 2.00 Billion |
|
CAGR (2026-2034) |
4.13% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Flavoured (60.0%, 2025) |
|
Dominant Distribution Channel |
Convenience Stores (40.0%, 2025) |
|
Leading Region |
West India (32.0%, 2025) |
The India potato chips market size increased from USD 1.11 Billion in 2020 to USD 1.36 Billion in 2025 and is estimated to reach USD 1.45 Billion in 2026. The market is further expected to grow to USD 1.67 Billion by 2030 and USD 2.00 Billion by 2034. India's market is commercially distinctive because a youthful, urban-skewing consumer base and an extensive informal retail network create simultaneous demand across premium branded and value-tier segments, sustaining broad volume and revenue growth across the forecast period.
To get more information on this market, Request Sample
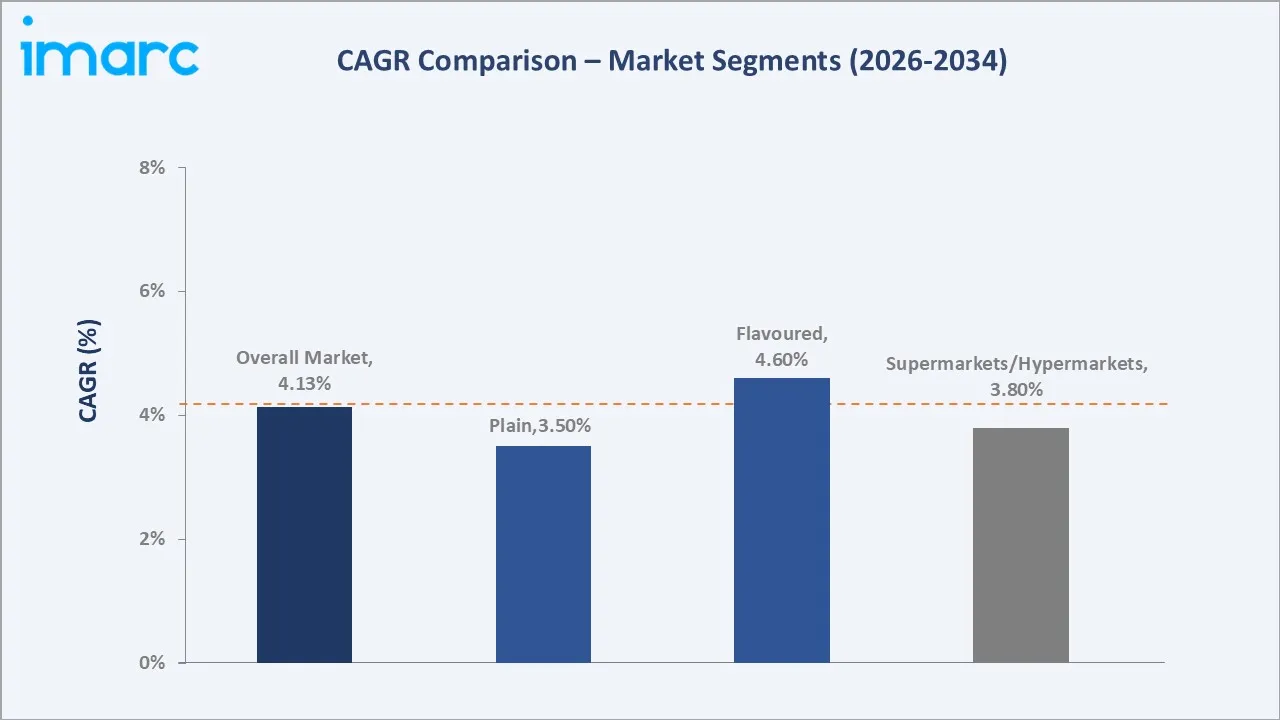
Online Stores within the Distribution Channel segment are growing at ~5.8% CAGR, supported by quick-commerce adoption and digital-native snack brands expanding into e-commerce. Within the Product Type segment, Flavoured potato chips are growing fastest at ~4.6% CAGR through continuous regional taste innovation and premium flavor extensions driving repeat purchase.
Executive Summary
The India potato chips market expanded from USD 1.36 Billion in 2025 to an estimated USD 1.45 Billion in 2026, with demand anchored in a large, young consumer population, expanding organized retail infrastructure, and growing penetration of packaged snacks across urban and semi-urban geographies. The fastest-developing areas are flavored variants with regional taste profiles, online and quick-commerce distribution, and premium health-positioned formats, each outpacing the overall market. Rising snack occasion frequency, improved logistics capability, and digital marketing investment by organized players are reinforcing the market's commercial foundation. In parallel, quick-commerce platforms are shortening delivery times to urban households and widening shelf access for new launches, while premium formats such as baked, air-popped, and lower-oil chips are attracting health-conscious consumers willing to pay higher price points.The market is projected to reach USD 2.00 Billion by 2034. Flavoured at 60.0% leads through continuous product innovation and strong brand investment across mass and premium tiers. Convenience Stores at 40.0% anchor volume distribution through deep neighborhood penetration. West India leads regionally at 32.0% through its concentration of urban consumers and retail density.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Flavoured - 60.0% share (2025) |
|
Dominant Distribution Channel |
Convenience Stores - 40.0% market share (2025) |
|
Leading Region |
West India - 32.0% share (2025) |
|
Market Opportunity |
Premium and health-oriented variants, online and quick-commerce channels, regional flavor innovation, single-serve and portion-control formats |
Key Analytical Observations Supporting the Above Data:
- Flavoured at 60.0%: Flavoured potato chips command dominant share because continuous innovation in regional, international, and fusion taste profiles drives repeat purchase and trial, while mass-market affordability sustains broad cross-demographic consumption across both urban and rural channels. Regional flavours such as masala, tangy tomato, and chaat-inspired variants resonate strongly with Indian palates, giving manufacturers a reliable platform for line extensions and limited-edition launches tied to local festivals and cricket seasons.
- Convenience Stores at 40.0%: Convenience stores lead distribution through their dense neighborhood-level presence across Indian cities and towns, enabling high-frequency impulse purchase occasions that align closely with the on-the-go snacking behavior that drives most potato chips volume.
- West India at 32.0%: West India leads through Maharashtra and Gujarat's combined urban consumer density, higher per-capita packaged food spending, well-developed modern retail networks, and gateway status for both domestic brand expansion and international product entry into the India potato chips market.
India Potato Chips Market Overview
The India potato chips market sits at the intersection of a vast snack consumption base, a rapidly modernizing food retail environment, and an intensely competitive branded manufacturing landscape. The market integrates large organized players with national manufacturing footprints, regional brands with strong local flavor knowledge, and a growing cohort of premium and health-oriented entrants targeting urban millennials. Distribution spans traditional trade, modern retail, institutional channels, and fast-growing e-commerce and quick-commerce platforms. Demand is shaped by urbanization, rising incomes, changing lifestyles, and wider availability of innovative variants at accessible price points. The market benefits from a large potato-growing base that supports competitive raw material sourcing, while food processing policy encourages manufacturing investment and domestic value addition. Flavor localization is a central competitive lever, with classic salted and masala profiles sitting alongside regional tastes and newer international-style seasonings, while entry-level single-serve packs at low price points, drive trial and rural penetration. Premiumization, the expansion of single-serve formats, and health-driven reformulation are gradually reshaping the product mix and competitive dynamics.
Market Dynamics
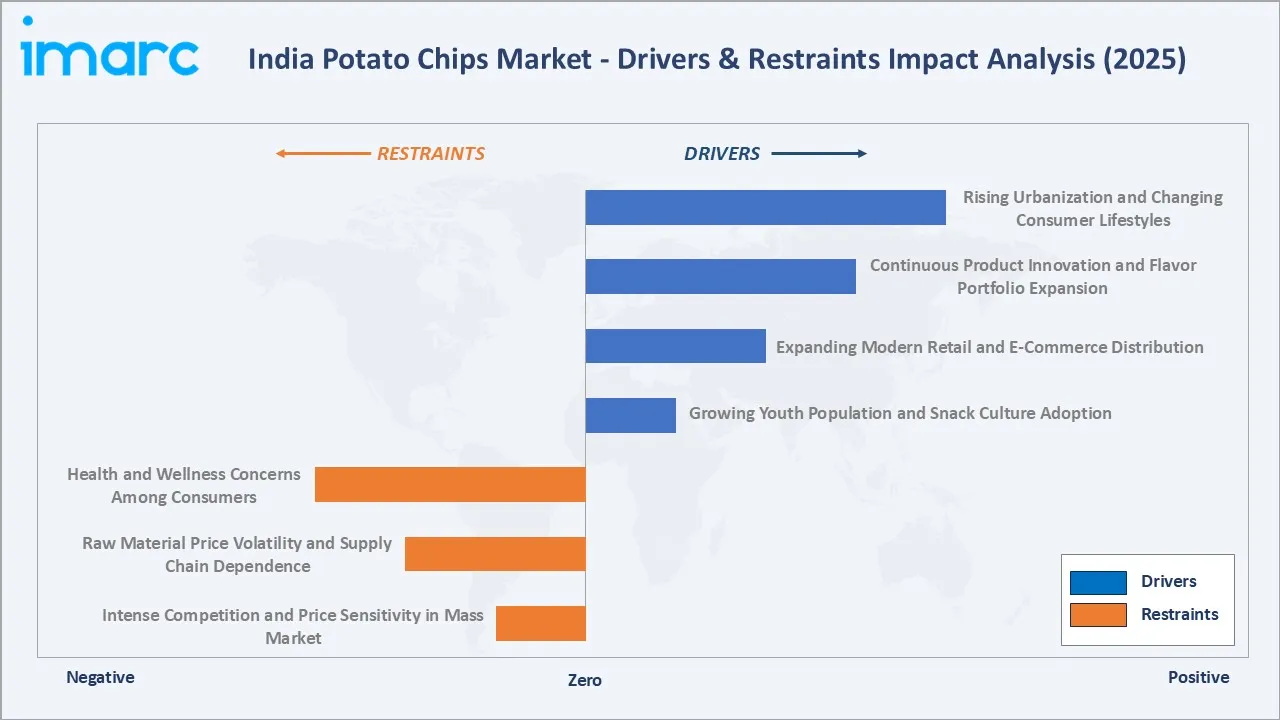
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Urbanization and Changing Consumer Lifestyles: India's urban expansion is reshaping food consumption, with city households replacing home-prepared snacks with packaged options due to time constraints. Modern retail and quick-commerce platforms across Tier I and II cities make branded chips accessible to more consumers. Rising dual-income households and disposable incomes support more frequent, higher-value snack purchases, sustaining volume and revenue growth. Quick-commerce platforms in particular have shortened delivery windows to minutes, encouraging impulse purchases of chips alongside beverages and other convenience items during evening and weekend consumption occasions.
- Continuous Product Innovation and Flavor Portfolio Expansion: Manufacturers invest heavily in flavor development, drawing on regional taste preferences, international cuisine trends, and health-oriented reformulation. Limited-edition flavors, regional masala variants, baked and low-fat formats, and premium ingredient lines expand engagement beyond the mass segment. This cycle shortens repurchase intervals and creates trial-driven volume uplift, while packaging innovation and portion-control formats raise average selling prices.
- Expanding Modern Retail and E-Commerce Distribution: Rapid growth in organized food retail, convenience store chains, supermarkets, and e-commerce platforms is broadening the reach of branded chips. Online grocery and quick-commerce create high-frequency impulse occasions that bypass traditional distribution constraints. Digital discoverability, targeted promotions, and subscription-linked snack categories drive customer acquisition, and organized retailers increasingly allocate shelf space to chips as a high-turnover category.
- Growing Youth Population and Snack Culture Adoption: India's large young demographic, exposed to global snacking trends through social media and international brands, creates a favorable demand environment. Youth-centric marketing, gaming-linked promotions, and vending expansion sustain strong volume in the under-30 cohort.
Market Restraints
- Health and Wellness Concerns Among Consumers: Growing awareness of the caloric, sodium, and fat content of conventional chips prompts some health-conscious consumers to reduce or substitute purchases. Media coverage of diet-related disease and official nutritional guidance influence parental buying decisions and drive trial of alternative snacks. The trend is strongest in urban premium segments but is spreading, compelling investment in baked variants and cleaner labels.
- Raw Material Price Volatility and Supply Chain Dependence: Potato prices in India fluctuate seasonally with monsoon performance, pest pressure, and cold-storage availability. These cycles directly affect input costs, compressing margins when prices spike and complicating procurement planning. Manufacturers without long-term procurement agreements or backward integration face periodic margin pressure that limits their ability to hold stable consumer pricing, especially in the price-elastic mass tier.
- Intense Competition and Price Sensitivity in Mass Market: The market is highly competitive at mass and value tiers, where national and regional brands compete on price, promotions, and distribution breadth. Consumer price sensitivity, particularly in Tier II, III, and rural markets, limits the ability of organized players to pass through cost increases. Private labels add pricing pressure, constraining margin expansion.
Market Opportunities
- Premium and Health-Oriented Variant Development: A growing urban segment will pay a premium for baked, air-popped, multigrain, reduced-sodium, and organic variants that align with wellness aspirations. Brands that bridge the taste and health trade-off capture higher average selling prices and build loyalty in the urban premium tier. Certified health claims, cleaner ingredient decks, and international sourcing enable differentiation that sustains margin expansion.
- Quick-Commerce and Direct-to-Consumer Channel Growth: The expansion of 10-to-30-minute delivery platforms across Indian cities has created a structurally new, high-frequency snack channel that suits impulsive potato chips buying. Brands that optimize for quick-commerce discovery, packaging, and minimum-order economics capture incremental volume at favorable margins. D2C brand websites and subscription snack boxes add direct consumer relationships, enabling personalized flavor sampling, loyalty integration, and faster new product launches.
- Tier II and III City Market Penetration: Rising aspirations and improving packaged food retail infrastructure in smaller Indian cities represent significant untapped growth for organized brands. As modern trade, branded convenience stores, and logistics connectivity expand into non-metro markets, branded products can displace unorganized local alternatives and capture first-time organized snack buyers. Affordable pack sizes, regional flavor localization, and distributor expansion build durable volume bases.
Market Challenges
- Regulatory Compliance and Labeling Requirements: India's food safety rules, including FSSAI nutrition disclosure and proposed front-of-pack warning labels, create compliance costs and packaging redesign work. The evolving environment demands continuous monitoring, and mandatory warnings could shift buying behavior. Smaller manufacturers face disproportionate burdens.
- Waste Management and Sustainability Pressures: Consumer and regulatory attention to plastic packaging waste is pushing manufacturers toward recyclable laminates and reduced-plastic formats. Moving away from multi-layer flexible packaging, which provides the barrier properties essential for shelf life, is technically and economically difficult. Sustainable alternatives cost more and compress margins.
- Cold Chain and Freshness Management Complexity: Maintaining freshness, shelf life, and quality consistency across India's geographically diverse and climatically variable distribution network is an ongoing challenge. Inadequate cold-chain infrastructure in some Tier III and rural markets accelerates product degradation, causing quality complaints and returns that damage brand reputation. Shelf-life compliance across a fragmented traditional trade network requires distributor training and merchandising investment.
Emerging Market Trends
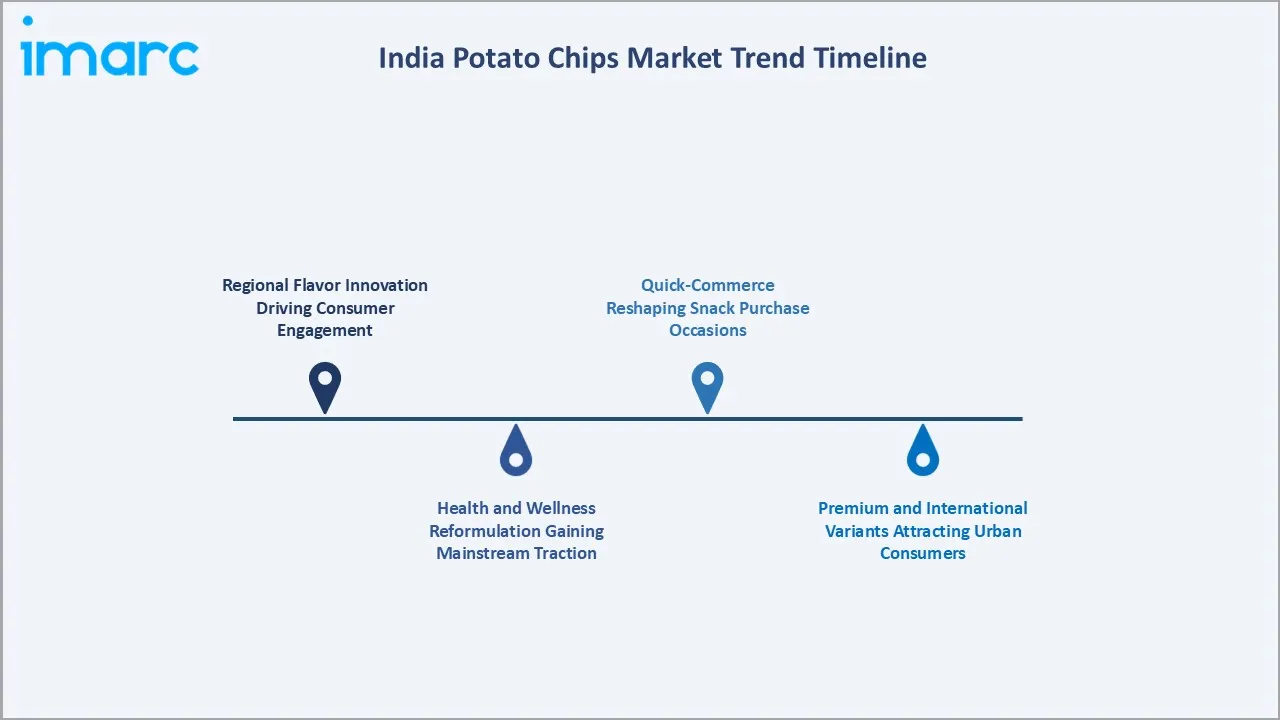
1. Regional Flavor Innovation Driving Consumer Engagement
Indian consumers show growing enthusiasm for hyper-local and regionally inspired potato chip flavors, moving beyond national standard variants toward taste profiles drawn from specific regional cuisines. Manufacturers use ethnographic consumer research and social media listening to identify and launch regionally resonant flavors such as Peri-Peri, Achari, Schezwan, and local street-food profiles. These launches generate trial, social sharing, and media attention at disproportionately low marketing cost. The trend reflects premiumization, where flavor authenticity and novelty become key purchase drivers alongside price, and innovation cycles shorten as players build agile development pipelines.
2. Health and Wellness Reformulation Gaining Mainstream Traction
Demand for baked, air-fried, reduced-fat, and multigrain potato chip variants is moving from niche urban health-food positioning toward mainstream availability across organized and e-commerce channels. Manufacturers are reformulating to reduce sodium, eliminate artificial colors, and introduce clean-label ingredient decks aligned with consumer wellness narratives. Marketing increasingly highlights portion control, calorie transparency, and ingredient provenance. The convergence of wellness awareness, digital health content consumption, and rising urban health spending is accelerating premiumization within the India potato chips market, creating a commercially significant better-for-you tier alongside the dominant mass-market segment.
3. Quick-Commerce Reshaping Snack Purchase Occasions
The explosive growth of instant-delivery platforms is reshaping how Indian urban consumers purchase potato chips, shifting significant impulse snack volume from neighborhood stores to digital platforms offering 10-to-30-minute delivery. This channel shift creates new competitive dynamics, as discoverability on quick-commerce apps, promotional placement, and digital shelf optimization become as commercially critical as traditional trade distribution. Brands are adapting packaging and SKU assortments for quick-commerce compatibility, and new direct-to-consumer snack brands are building primarily digital businesses, intensifying competition in the India potato chips market across volume and premium tiers.
4. Premium and International Variants Attracting Urban Consumers
India's expanding urban upper-middle-income consumer segment is driving demand for imported and premium domestic potato chip brands with sophisticated flavor profiles, higher quality oil and ingredient sourcing, and distinctive packaging. Kettle-cooked, hand-cooked, and artisanal-positioned chips are gaining shelf space in modern trade and specialty food retail. International brands entering through licensing, import, or domestic manufacturing partnerships are elevating the premium benchmark. This premiumization is raising average unit prices at the high end of the India potato chips market, expanding revenue per consumer and creating a distinct premium tier that coexists with the dominant mass-market base.
Industry Value Chain Analysis
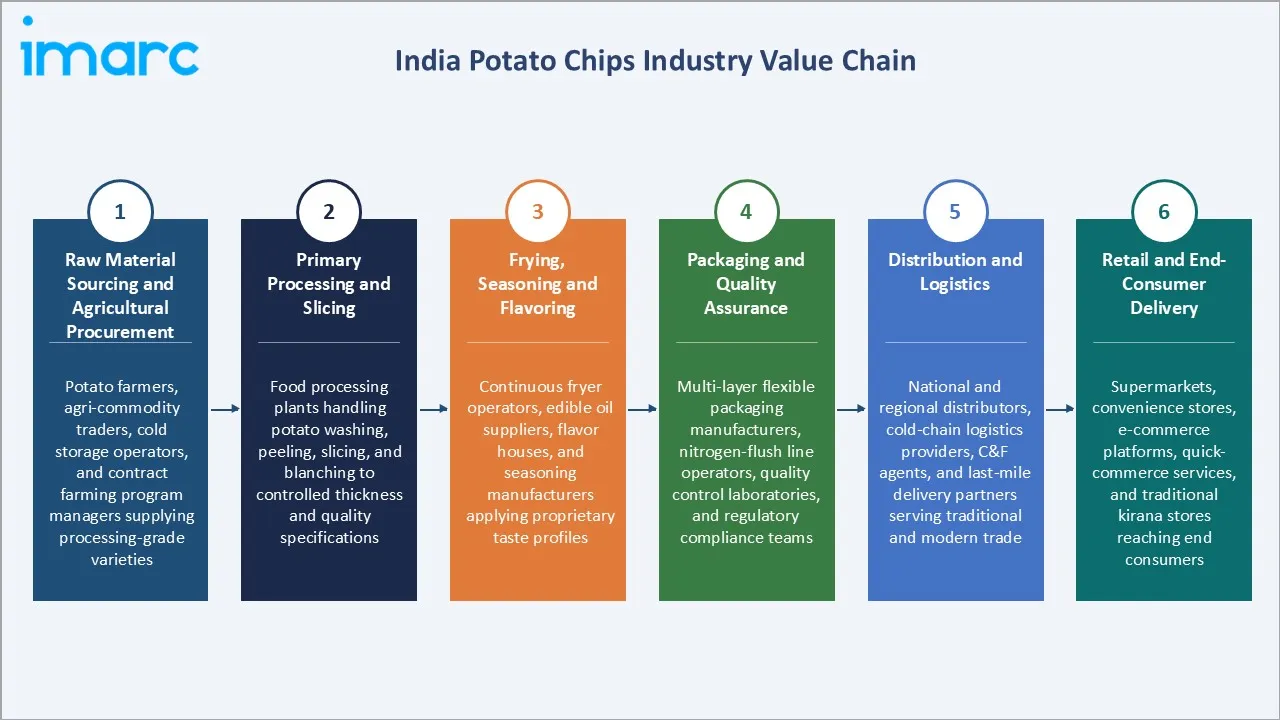
The industry value chain spans raw material sourcing and agricultural procurement, primary potato processing and slicing, frying and flavoring operations, packaging and quality assurance, distribution and logistics, and retail and end-consumer delivery. Each stage adds value as raw agricultural produce is transformed into a shelf-stable, branded consumer product delivered through multi-channel retail networks, with quality control and traceability requirements tightening at every handoff.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing and Agricultural Procurement | Potato farmers, agri-commodity traders, cold storage operators, and contract farming program managers supplying processing-grade varieties |
| Primary Processing and Slicing | Food processing plants handling potato washing, peeling, slicing, and blanching to controlled thickness and quality specifications |
| Frying, Seasoning and Flavoring | Continuous fryer operators, edible oil suppliers, flavor houses, and seasoning manufacturers applying proprietary taste profiles |
| Packaging and Quality Assurance | Multi-layer flexible packaging manufacturers, nitrogen-flush line operators, quality control laboratories, and regulatory compliance teams |
| Distribution and Logistics | National and regional distributors, cold-chain logistics providers, C&F agents, and last-mile delivery partners serving traditional and modern trade |
| Retail and End-Consumer Delivery | Supermarkets, convenience stores, e-commerce platforms, quick-commerce services, and traditional kirana stores reaching end consumers |
Frying, seasoning and flavoring is the most commercially critical stage, because it determines the product's taste profile, texture, and differentiation, fixes the majority of variable cost through oil consumption and flavor input, and establishes the brand's sensory proposition that drives consumer loyalty and repeat purchase across all distribution channels, and it links brand equity most directly to manufacturing efficiency.
Technology Landscape in the India Potato Chips Industry
Continuous Frying and Oil Management Technology
Modern continuous fryer systems with precise temperature zoning, oil turnover control, and automated filtration are replacing batch-frying operations across organized Indian manufacturers. These systems deliver consistent texture, uniform color, and controlled oil uptake at scale. Closed-loop oil management and high-oleic sunflower oil adoption reduce oxidation and extend shelf life. Advanced fryer technology also improves energy efficiency and cuts oil waste, lowering cost per kilogram. Leading manufacturers report oil consumption reductions of 15–20% compared to conventional batch systems, with throughput capacities exceeding 500 kilograms per hour in large-format lines.
Automated Flavoring and Seasoning Application Systems
Precision seasoning drum systems with gravimetric dosing and in-line flavor adhesion enable consistent application across large batch volumes, reducing giveaway and waste. Microencapsulation and spray-coating let manufacturers apply complex multi-layered flavor profiles that resist moisture and hold taste intensity. These systems support rapid flavor changeovers on shared lines, enabling high SKU diversity.
Modified Atmosphere Packaging and Barrier Film Innovation
Multi-layer flexible packaging with nitrogen flushing, high-barrier metallized films, and laser-scored easy-open features extends potato chips shelf life and preserves crunch across India's climatically challenging distribution environment. Film innovation focuses on cutting plastic weight per pack while maintaining barrier performance, responding to sustainability regulation. Reclosable packs and portion-control formats gain traction in premium and health-oriented SKUs.
Digital Supply Chain and Demand Forecasting Platforms
Indian manufacturers are adopting integrated enterprise resource planning and AI-driven demand forecasting to improve raw material procurement, cut inventory waste, and optimize production scheduling across multi-plant networks. Real-time distributor inventory visibility and van-sales automation improve replenishment accuracy in traditional trade. E-commerce and quick-commerce data integration enables faster launch decisions and promotional measurement. These investments compress time from consumer insight to shelf, a competitive advantage in a fast-innovating market.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Flavoured |
60.0% |
2025 |
|
Distribution Channel |
Convenience Stores |
40.0% |
2025 |
|
Region |
West India |
32.0% |
2025 |

By Product Type
Flavoured potato chips lead at 60.0% (2025). The flavoured segment dominates because continuous innovation in regional, fusion, and international taste profiles generates consumer trial and repeat purchase, while mass-market affordability sustains broad cross-demographic demand. The segment spans entry-level masala and spice variants to premium artisanal and globally-inspired flavors, covering a wide price range and consumer base.
To access detailed market analysis, Request Sample
Flavoured is also the fastest-growing product type at ~4.6% CAGR, as the volume of new flavor launches accelerates through organized brand innovation pipelines and regional taste preferences continue to fragment the category into distinct consumer occasions. Rising premiumization, global flavor exposure through digital media, and the brand marketing investment concentrated in the flavoured tier sustain its above-market growth through the forecast period.
By Distribution Channel
Convenience Stores lead at 40.0% (2025). The segment's leadership reflects the dense neighborhood-level presence of convenience stores across Indian cities and towns, which aligns perfectly with the impulse-driven, high-frequency purchase behavior that characterizes potato chips consumption. Convenience store proximity enables repeat purchase occasions that no other channel format can replicate at comparable density across the country.
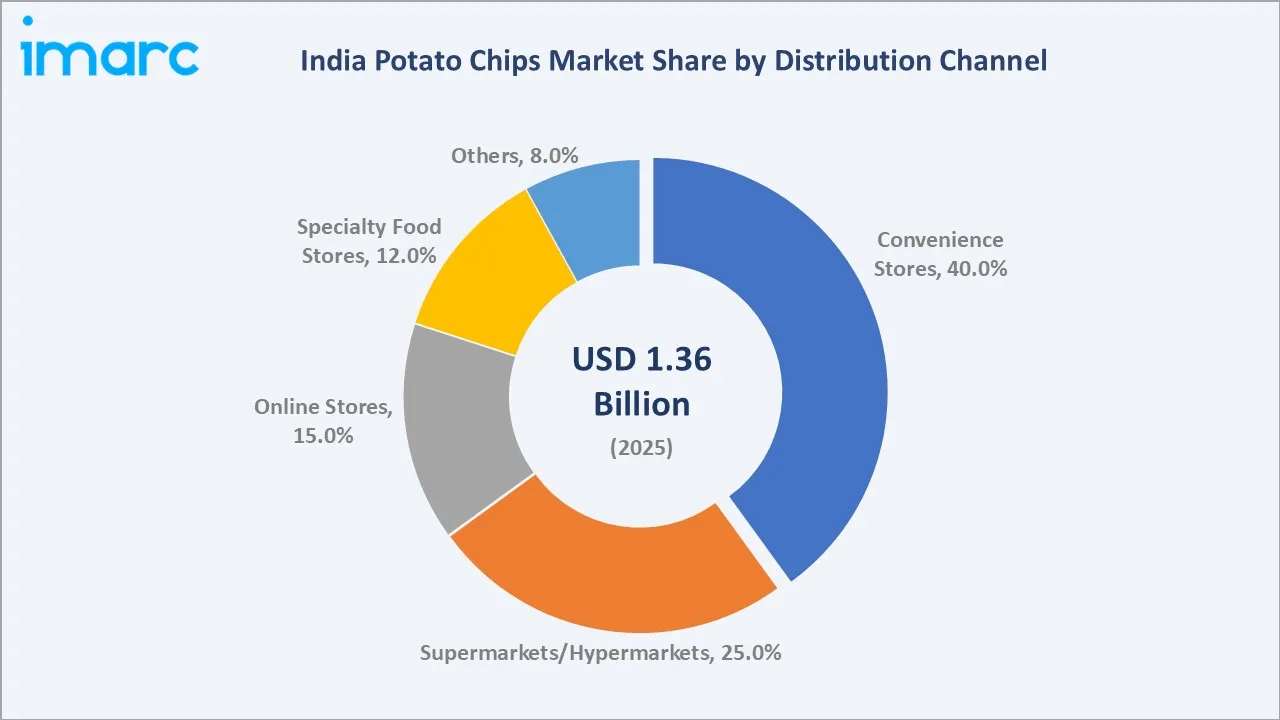
Online Stores are the fastest-growing distribution channel at ~5.8% CAGR, driven by the rapid expansion of quick-commerce and grocery delivery platforms that have created new high-frequency snack purchase occasions. Increasing smartphone penetration, digital payment adoption, and platform-driven promotional discoverability are accelerating online channel growth, particularly for premium and innovative SKUs where digital shelf visibility enables trial among urban consumers.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
West India |
32.0% |
High urban consumer density in Maharashtra and Gujarat, strong modern retail infrastructure, and gateway status for premium brand launches |
|
North India |
28.0% |
Large urban population in Delhi-NCR and Punjab, strong snacking culture, and deep traditional trade distribution networks |
|
South India |
25.0% |
Growing IT-sector wealth in Bengaluru and Hyderabad, strong regional flavor preferences, and expanding organized retail |
|
East India |
15.0% |
Rising consumer incomes in Kolkata and Odisha, improving retail infrastructure, and growing brand penetration in emerging urban centers |
West India accounts for 32.0% of the India potato chips market, supported by Maharashtra and Gujarat's combined urban consumer density, well-developed modern retail and convenience store networks, and strong e-commerce and quick-commerce penetration across Mumbai, Pune, and Ahmedabad. North India holds 28.0%, where Delhi-NCR's large urban population, robust traditional trade networks, and strong snacking culture across Punjab and Uttar Pradesh generate consistent high-volume demand for both mass-market and premium potato chips.
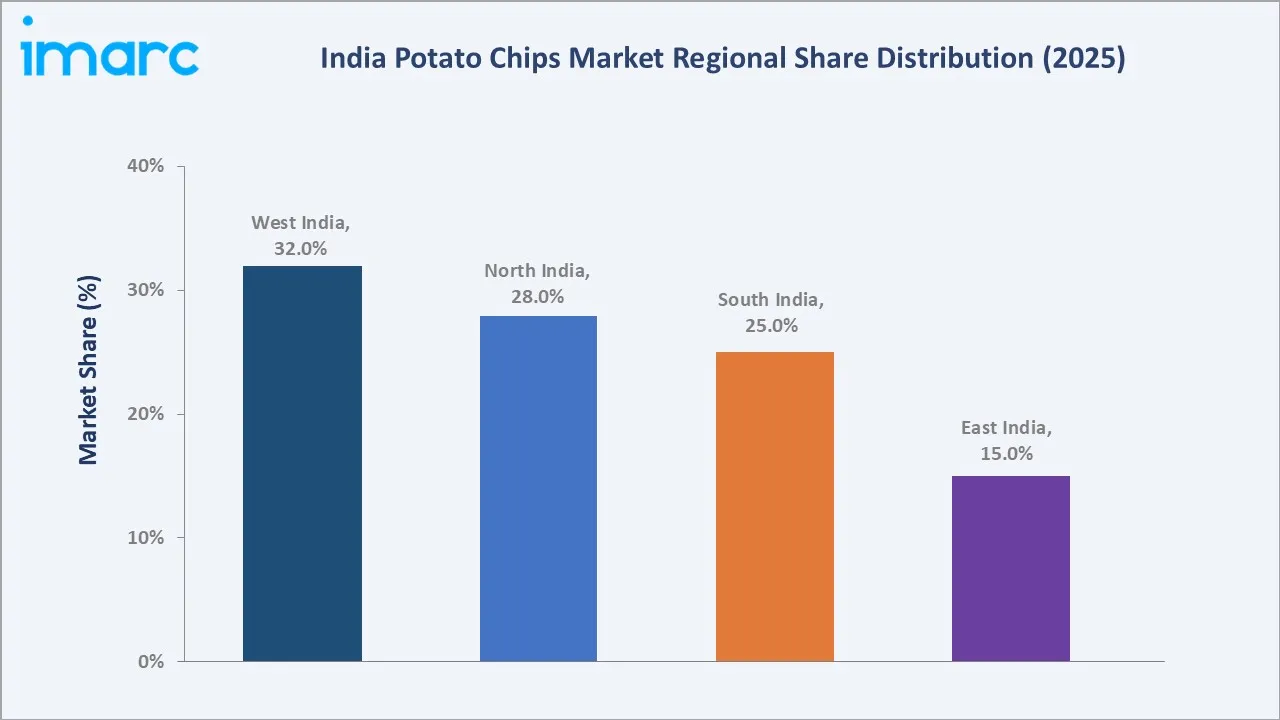
South India contributes 25.0%, shaped by the IT sector wealth concentrated in Bengaluru and Hyderabad, which supports premium variant adoption, alongside strong regional flavor preferences that sustain demand for locally-tailored product ranges across Tamil Nadu, Kerala, and Andhra Pradesh. East India accounts for 15.0%, where improving retail infrastructure in Kolkata and rising consumer aspirations across Odisha and West Bengal are supporting above-average brand penetration growth, though the region remains underpenetrated relative to its population base.
Competitive Landscape
The India potato chips market is moderately consolidated at the national branded tier, with a small group of large organized players controlling the majority of modern retail and e-commerce shelf space, while a large number of regional and local manufacturers compete effectively in traditional trade and value segments. Competition is primarily waged through flavor innovation, distribution breadth, brand marketing investment, and pricing strategy across mass and premium tiers.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| PepsiCo, Inc. | Lay's, Kurkure, Uncle Chipps | Market Leader | Unmatched national distribution, iconic brand equity, and continuous flavor innovation across mass and premium tiers |
| ITC Limited | Bingo!, Bingo! Mad Angles | Strong Challenger | Aggressive distribution leverage through ITC's FMCG network and strong regional flavor development capability |
| Haldiram Snacks Pvt. Ltd. | Haldiram's potato chips, Haldiram's namkeen | Strong Challenger | Deep consumer trust in Indian snack authenticity and wide traditional trade distribution across North and Central India |
| Prataap Snacks Limited | Yellow Diamond, Rich Feast | Established Player | Value-tier strength in Tier II and III markets and an expanding modern trade and e-commerce distribution footprint |
| Balaji Wafers Pvt. Ltd. | Balaji Wafers, Balaji potato chips | Established Player | Dominant regional brand equity in Gujarat and Western India with competitive mass-market pricing and strong traditional trade reach |
| Bikaji Foods International Limited | Bikaji potato chips, Bikaji snacks | Established Player | Strong Rajasthan and North India heritage brand with growing pan-India distribution and IPO-funded capacity expansion |
The most commercially significant competitive dynamic in the India potato chips market is the structural contest between PepsiCo India's incumbent brand and distribution leadership and a cohort of domestic challengers particularly ITC and Haldiram's that are leveraging complementary FMCG distribution infrastructure and deep regional consumer affinity to close the gap. PepsiCo's scale advantage in modern retail and e-commerce is being tested by the rapid growth of quick-commerce channels, where discovery algorithms can level the playing field for well-funded domestic challengers and new digital-native entrants. Regional players such as Balaji and Prataap retain durable cost advantages in their home geographies by operating leaner supply chains and maintaining stronger traditional trade relationships, limiting the pace at which national brands can convert volume in price-sensitive non-metro markets.
Key Company Profiles
PepsiCo, Inc.
PepsiCo, Inc. is the Indian subsidiary of PepsiCo Inc. and the market leader in the India potato chips market, operating manufacturing plants across multiple states and distributing through a national network that spans modern trade, traditional trade, e-commerce, and foodservice channels. Its portfolio spans entry-level to premium snack positions.
- Key Brands: Lay's, Uncle Chipps, Kurkure.
- Recent Developments: In 2026, PepsiCo Foods announced a seasonal portfolio of five limited-time Lay’s potato chip flavours, including Cheddar Scalloped-Style Potatoes, Roasted Holiday Turkey, Maple Bacon, Wavy Milk Chocolate and Wavy Dubai-Style Dark Chocolate. The launch demonstrates product innovation and flavour diversification in the potato chips segment.
- Strategic Focus: PepsiCo India is prioritizing flavor localization, digital channel growth including quick-commerce partnerships, and health-oriented product development across its Lay's portfolio. The company is also investing in manufacturing capacity modernization and sustainable packaging initiatives to align with evolving regulatory and consumer sustainability expectations.
ITC Limited
ITC Limited is one of India's largest diversified conglomerates, with a significant and growing presence in the packaged foods category through its Bingo! brand, which competes directly in the India potato chips market. ITC leverages its extensive FMCG distribution infrastructure, shared with its market-leading cigarettes and agri businesses, to drive rapid distribution scale for its snacks portfolio.
- Key Brands: Bingo!, Bingo! Mad Angles.
- Recent Developments: In 2026, ITC introduced two flavour innovations under its Bingo! potato chips portfolio: Himalayan Pink Salt and Butter & Garlic. The launches were highlighted in the company's FY2026 financial results announcement, reflecting its focus on product differentiation and expanding flavour choices in the Indian potato chips market.
- Strategic Focus: ITC is focused on expanding Bingo!'s national distribution reach through its unparalleled multi-category FMCG network, increasing investment in flavor innovation and regional taste development, and scaling its digital commerce presence. Sustainability and responsible sourcing credentials are being embedded into the Bingo! brand communication strategy.
Bikaji Foods International Limited
Bikaji Foods International Limited is a leading Indian ethnic snack brand with deep roots in Rajasthan and growing pan-India relevance, operating in the India potato chips market alongside its traditional namkeen and snack categories. The company has used its 2022 IPO proceeds to fund capacity expansion and national distribution investment.
- Key Brands: Bikaji potato chips, Bikaji snacks.
- Strategic Focus: Bikaji is prioritizing geographic diversification beyond its traditional North and East India strongholds, investing in modern trade and e-commerce distribution, and broadening its potato chips flavor portfolio to compete more directly with national brands in organized retail channels. Export market expansion is a secondary strategic pillar.
Market Concentration Analysis
The India potato chips market is moderately concentrated at the national branded tier but structurally fragmented once regional and local manufacturers are included. PepsiCo India, through its Lay's and Uncle Chipps brands, is the leading national player, estimated to hold a revenue share of 30% to 38% of the organized branded market. ITC's Bingo! and Haldiram's hold meaningful secondary positions, while regional players including Balaji, Prataap, Bikaji, and local manufacturers account for a significant portion of total volume, particularly in Tier II, III, and rural markets where national brand penetration is lower. Two opposing forces are actively reshaping concentration. National players are consolidating through distribution scale, marketing investment, and e-commerce prioritization, raising competitive barriers in modern trade and digital channels. Meanwhile, regional brands backed by IPO funding and cost-competitive manufacturing are expanding nationally, and digital-native snack brands are entering through quick-commerce and D2C channels, fragmenting value at the premium end.
Investment & Growth Opportunities
Highest Growth Segments
Online Stores at ~5.8% CAGR and Flavoured potato chips at ~4.6% CAGR are the primary investment vectors through 2034, followed by Convenience Stores at ~4.1%, Supermarkets/Hypermarkets at ~3.8%, Plain potato chips at ~3.5%, Specialty Food Stores at ~3.3%, and Others at ~2.9%. These segments grow fastest where demand pull is strongest: quick-commerce driven digital acceleration and flavor innovation lifting volume in the dominant tier. Capacity investment and digital shelf optimization convert that demand into revenue. On the digital side, quick-commerce platforms compress delivery windows to minutes, which favors impulse-led snacking occasions and rewards brands that secure prominent placement within in-app search results and category pages.
Emerging Investment Opportunities
The most dynamic emerging opportunity is the premium and health-oriented potato chips segment, where better-for-you positioning, clean-label ingredients, and portion-control formats command higher prices and attract the fastest-growing urban consumer cohort. This opportunity scales most rapidly in metro and Tier I cities through modern retail, specialty food channels, and quick-commerce platforms, where health-aware consumers are most concentrated and willing to pay a price premium.
Investment Themes
- Online and quick-commerce channel infrastructure: Investment in digital shelf optimization, quick-commerce SKU design, and direct-to-consumer platform capability captures the fastest-growing distribution channel and builds first-mover advantages in high-frequency urban snack purchase occasions through 2034.
- Regional flavor and product innovation capability: Building agile flavor development pipelines that respond to regional taste preferences and global trend signals drives consumer trial, media attention, and repeat purchase across the dominant Flavoured segment at above-market CAGR.
- Health-oriented and premium variant development: Reformulating and launching baked, reduced-fat, and clean-label potato chip variants captures the fastest-growing consumer segment by value and supports margin expansion through premium positioning in organized and digital retail channels.
Future Market Outlook (2026-2034)
The India potato chips market is projected to grow from USD 1.36 Billion in 2025 to USD 1.45 Billion in 2026, reaching USD 2.00 Billion by 2034, registering a CAGR of 4.13% during 2026-2034. The market's anchor value of USD 1.67 Billion in 2030 reflects durable consumer demand underpinned by urbanization, rising snack occasion frequency, and continuous product innovation. Forward growth rests on digital channel expansion, premium segment development, and broader geographic penetration, with West India and North India sustaining leadership as organized retail and quick-commerce infrastructure deepens in their respective markets. On the digital front, quick-commerce platforms and e-commerce marketplaces are widening access to a larger range of pack sizes and flavors, particularly in metro and Tier 1 cities where impulse and convenience purchases are rising. In the premium segment, manufacturers are introducing kettle-cooked, baked, and gourmet-flavored variants, along with healthier-positioning options such as lower-oil and alternative-ingredient chips, to attract urban, health-conscious, and higher-income consumers.
Manufacturers are increasingly relying on kirana stores, village-level wholesalers and van-based distribution networks to reach outlets that were previously underserved by organized snack suppliers.
Research Methodology
Primary Research
Primary research for the India potato chips market involved discussions with manufacturers, brand managers, organized retail category heads, distribution partners, and food industry consultants across key consumption geographies, focused on consumer demand trends, packaging and format preferences, channel dynamics, pricing strategy, and competitive positioning.
Secondary Research
Secondary research drew on company annual reports, FSSAI regulatory publications, food processing industry association materials, organized retail trade press, and e-commerce platform category data, triangulated to establish product type and distribution channel splits and the regional distribution of potato chips consumption across India, with all figures cross-validated against published industry benchmarks.
Forecasting Models
Forecasting combined consumer volume modeling by product type and distribution channel with penetration curves for organized retail and digital channels in India, applying flavor innovation and premiumization adjustment factors to reconcile yearly market values and segment growth paths to the overall market CAGR of 4.13% during 2026-2034.
India Potato Chips Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Plain, Flavoured |
| Distribution Channels Covered | Supermarkets/Hypermarkets, Convenience Stores, Specialty Food Stores, Online Stores, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | PepsiCo Inc., ITC Limited, Haldiram Snacks Pvt. Ltd., Prataap Snacks Limited, Balaji Wafers Pvt. Ltd., Bikaji Foods International Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India potato chips market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India potato chips market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India potato chips industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Potato Chips Market Report
The India potato chips market reached USD 1.36 Billion in 2025 and is estimated at USD 1.45 Billion in 2026. Growth is supported by urbanization, frequent snacking, organized retail expansion, and product innovation across flavored and plain chips. This represents an increase of approximately USD 0.09 Billion, or 6.6%, year-on-year, reflecting steady demand in metropolitan and emerging urban markets.
The market is projected to grow at a CAGR of 4.13% during 2026-2034, increasing from USD 1.45 Billion in 2026 to USD 2.00 Billion by 2034. Growth is expected from digital retail, flavor innovation, and urban snacking habits. Online retail, quick-commerce platforms, regional and fusion flavors, and on-the-go consumption are likely to contribute.
Flavoured potato chips lead the product type segment, accounting for 60.0% of the market in 2025. Their position reflects flavor innovation, brand marketing, and consumer preference for variety across mass-market and premium snacking occasions.
Convenience Stores lead the distribution channel segment with a 40.0% share in 2025. Their neighborhood presence across cities and towns supports impulse purchases and on-the-go snacking.
West India leads the regional segment with a 32.0% share in 2025. Maharashtra and Gujarat benefit from urban consumer density, developed retail networks, and e-commerce and quick-commerce penetration in Mumbai, Pune, and Ahmedabad. Rising packaged-snack spending further supports demand.
Leading companies include PepsiCo, Inc., ITC Limited, Haldiram Snacks Pvt. Ltd., Prataap Snacks Limited, Balaji Wafers Pvt. Ltd., and Bikaji Foods International Limited. Competition is shaped by flavor innovation, distribution reach, brand strength, and digital channel investment.
Online Stores, growing at approximately 5.8% CAGR, and flavoured potato chips, at approximately 4.6% CAGR, are the fastest-growing segments. Other opportunities include health-oriented and premium products, quick-commerce infrastructure, and regional flavor innovation. These areas offer potential through 2034. This reflects evolving consumer preferences and purchasing channels.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade