Indonesia Diaper Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, and Region, 2026-2034
Indonesia Diaper Market Size, Share, Trends & Forecast (2026-2034)
The Indonesia diaper market reached USD 1.25 Billion in 2025 and is projected to reach USD 2.16 Billion by 2034, growing at a CAGR of 6.24% during 2026-2034. The market is driven by Indonesia's high birth rate and large young population sustaining baby diaper demand, rising disposable incomes, and rapid e-commerce penetration expanding market accessibility. Indonesia records approximately 4.4 million births annually, with a crude birth rate of around 15.4 births per 1,000 people. This large newborn population creates a substantial and recurring consumer base for baby diapers, supporting steady demand for disposable, affordable, and premium diaper products. Baby diapers lead at 78.6% by product type, Supermarkets and hypermarkets dominate at 31.6% by distribution channel, and Java holds the largest regional share at 48.7%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.25 Billion |
|
Forecast Market Size (2034) |
USD 2.16 Billion |
|
CAGR (2026-2034) |
6.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Baby Diaper (78.6%, 2025) |
|
Leading Distribution Channel |
Supermarkets & Hypermarkets (31.6%, 2025) |
|
Leading Region |
Java (48.7%, 2025) |
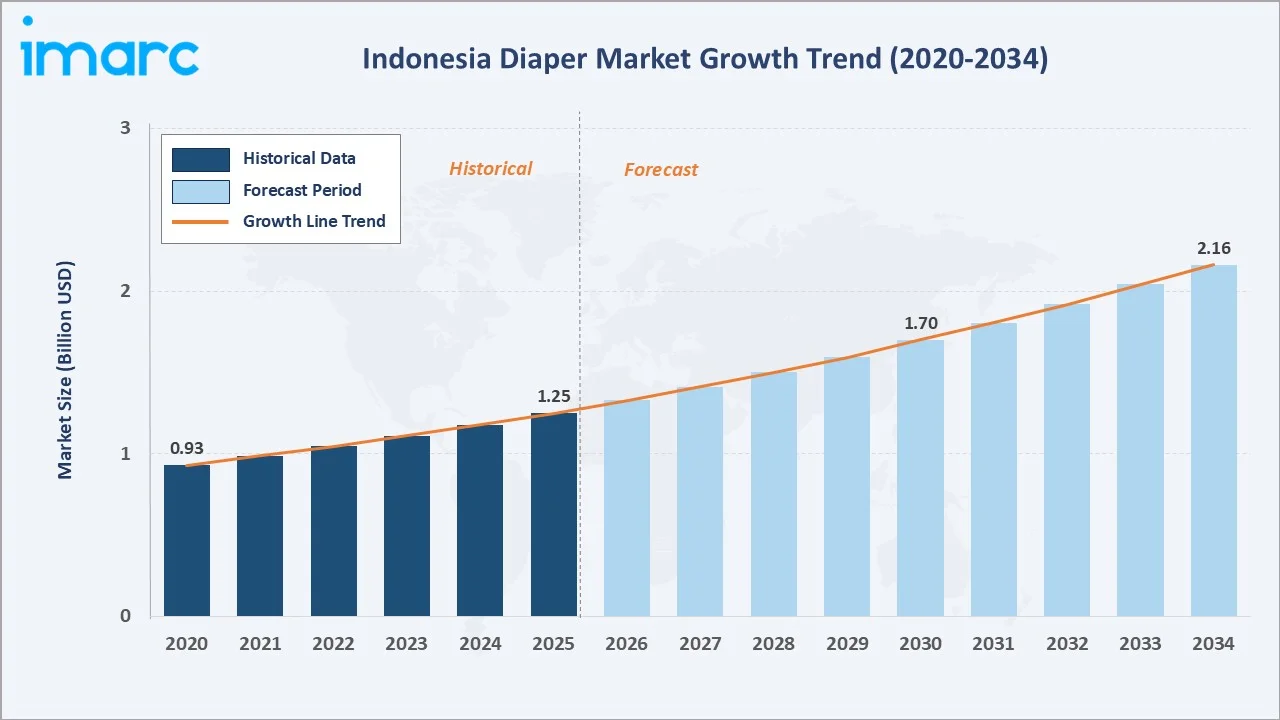
The Indonesia diaper market has grown from USD 0.93 billion in 2020 to USD 1.25 billion in 2025, reflecting robust demand driven by one of Southeast Asia's largest and youngest populations. The market is projected to reach USD 1.70 billion by 2030 and USD 2.16 billion by 2034.
To get more information on this market, Request Sample
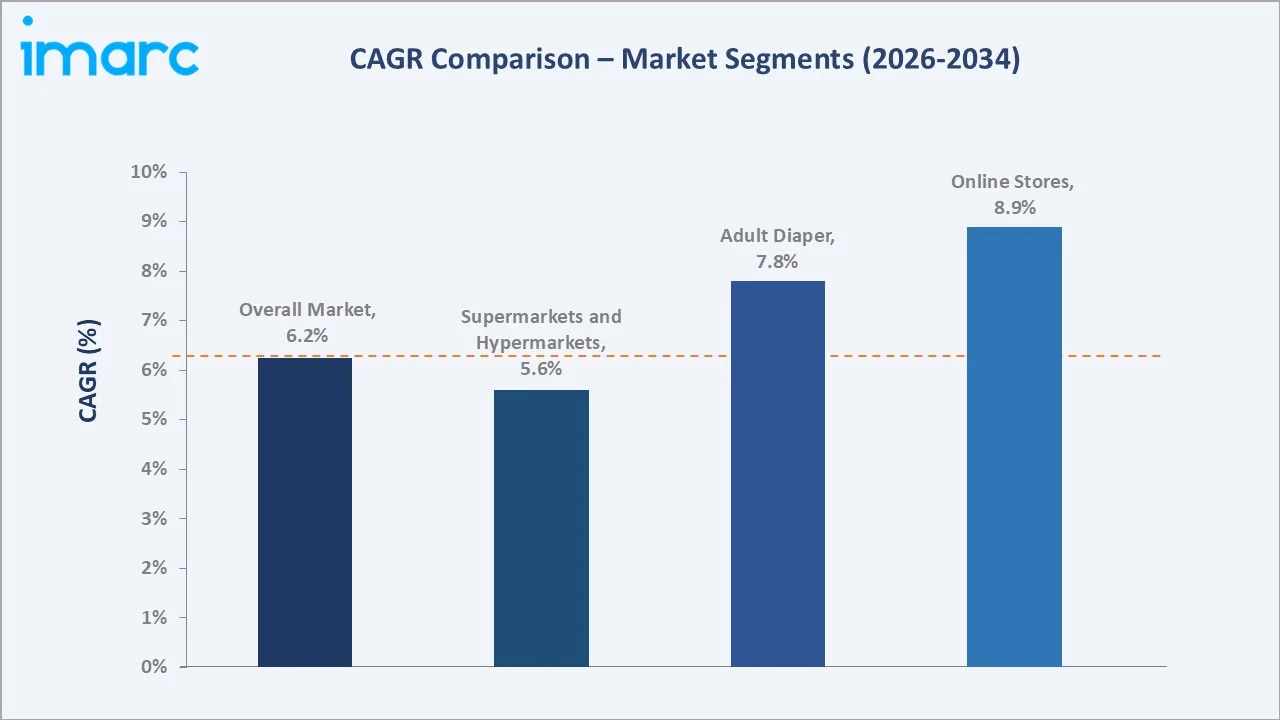
Online stores grow at ~8.9% CAGR through e-commerce adoption. Adult diapers grow at ~7.8% CAGR through aging population and healthcare expansion. Supermarkets and hypermarkets grow at ~5.6% CAGR, sustaining offline channel leadership.
Executive Summary
The Indonesia diaper market is witnessing sustained and accelerating growth, anchored by the nation's demographic advantage as one of the most populous countries with a large and growing young population. Indonesia's population reached approximately 287.2 million people by mid-2026, and newborns create a structurally strong and recurring demand foundation for baby diapers.
Rising household incomes, particularly within Indonesia's expanding urban middle class, are enabling a progressive shift from cloth diapers to premium disposable formats featuring enhanced absorbency, skin-care technologies, and eco-friendly materials. Baby diapers lead at 78.6% through newborn and infant population demand. Supermarkets & hypermarkets lead at 31.6% by distribution channel through mass retail reach. Java leads regionally at 48.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Baby Diaper - 78.6% share (2025) |
|
Leading Distribution Channel |
Supermarkets & Hypermarkets - 31.6% (2025) |
|
Leading Region |
Java - 48.7% share (2025) |
|
Market Opportunities |
Rising demand for premium diapers, eco-friendly products, affordable mass-market variants, e-commerce distribution, and products tailored to infants’ skin comfort and hygiene needs. |
Key Analytical Observations Supporting the Above Data:
- Baby Diaper at 78.6%: Baby diapers dominate through Indonesia's large birth cohort of newborns requiring daily diaper consumption from birth through toddler stages. Rising working-mother participation in urban centers is accelerating the shift from reusable cloth diapers to convenient disposable formats, with premium sub-segments featuring wetness indicators, skin-care lotions, and ultra-thin profiles gaining rapid market share among higher-income Indonesian households.
- Supermarkets & Hypermarkets at 31.6%: Supermarkets and hypermarkets lead distribution through their combination of broad product range, competitive pricing, and convenience for regular bulk purchasing.
- Java at 48.7%: Java dominates due to its concentration of Indonesia's population, highest urban household density, most developed modern retail infrastructure, highest per-capita income levels, and greatest penetration of working-mother households driving consistent premium diaper adoption across metropolitan areas.
Indonesia Diaper Market Overview
The Indonesia diaper market encompasses baby diapers (disposable, training pants, cloth, swim pants, and biodegradable variants) and adult diapers (pad type, flat type, and pant type) distributed through supermarkets and hypermarkets, convenience stores, online platforms, pharmacies, and specialty retail channels. The market is defined by Indonesia's demographic profile combined with an aging cohort driving adult diaper growth. Urbanization, rising working-mother participation, e-commerce expansion, and product premiumization are the primary market evolution forces.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
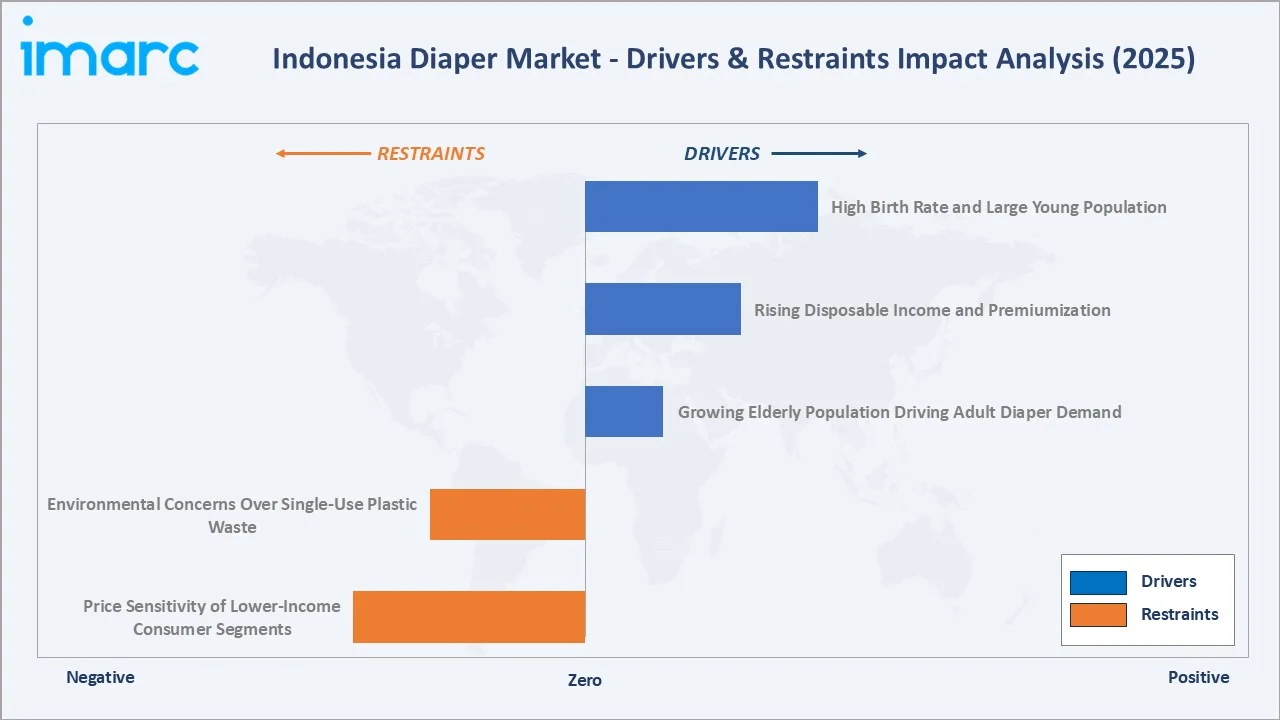
- High Birth Rate and Large Young Population: Indonesia records approximately 4.4 million births annually, corresponding to a crude birth rate of around 15.4 births per 1,000 people, creating a structurally large and recurring diaper demand base. The country's total fertility rate ensures sustained baby diaper consumption through the forecast period. As mothers increasingly adopt disposable diapers over traditional cloth alternatives, supported by rising incomes and urbanization, the addressable market expands progressively.
- Rising Disposable Income and Premiumization: Indonesia's expanding middle class, projected to reach 90 million households by 2030, is driving progressive premiumization of diaper purchasing decisions. Higher-income Indonesian consumers are adopting premium diaper brands featuring ultra-thin profiles, multi-layered absorbency, dermatologically tested materials, aloe vera and vitamin E skin-care enhancements, and wetness indicators. Unicharm's MamyPoko and Kimberly-Clark's premium ranges are experiencing strong demand growth among urban middle-class Indonesian households.
- Growing Elderly Population Driving Adult Diaper Demand: By 2050, Indonesians aged 60 years and above are projected to account for approximately 25% of the population, equivalent to nearly 74 million elderly people, creating substantial structural demand for adult incontinence products. Expanding private hospital networks, home healthcare services, and growing caregiver awareness of dignity and hygiene management for elderly patients are accelerating adult diaper adoption.
Market Restraints
- Environmental Concerns Over Single-Use Plastic Waste: Indonesia is among the largest producers of plastic waste, and disposable diapers are a significant contributor to household solid waste. Growing environmental consciousness, particularly among educated urban Indonesian consumers, is creating preference pressure toward eco-friendly, biodegradable, and reduced-packaging alternatives. This environmental sensitivity constrains volume growth in conventional disposable segments while creating premium opportunity for sustainable alternatives.
- Price Sensitivity of Lower-Income Consumer Segments: A substantial proportion of Indonesian households remain in lower-income segments where the per-unit cost of premium disposable diapers represents a significant household budget component. Price sensitivity limits full market penetration in rural Java, Sumatra, and eastern Indonesian provinces, where cloth diaper alternatives remain prevalent. Government-subsidized diaper programs are absent, unlike in some developed markets, creating reliance on market-rate pricing.
Market Opportunities
- Biodegradable and Eco-Friendly Diaper Innovation: Indonesia's growing environmental awareness and the government's expanding plastic waste reduction regulations create market opportunity for plant-based, biodegradable, and reduced-SAP diaper formulations. Brands that establish credible eco-friendly credentials through certified biodegradable materials, reduced carbon footprints, and take-back recycling programs will capture premium-paying environmentally conscious Indonesian consumers.
- Rural Market Penetration Through Modern Trade Expansion: The progressive expansion of convenience store networks into secondary cities and rural Indonesian areas is creating new distribution touchpoints for diaper brands beyond traditional urban concentrated sales. As modern trade penetration deepens, previously underserved rural consumer segments become accessible to branded disposable diaper products.
Market Challenges
- Counterfeit and Substandard Product Infiltration: The Indonesian diaper market is affected by the presence of counterfeit and substandard products, particularly in price-sensitive segments and informal retail channels. Counterfeit products undermine legitimate manufacturer revenues, expose infant consumers to potential hygiene and safety risks, and create regulatory compliance challenges. Addressing this requires sustained brand authentication investment and enforcement collaboration.
- Raw Material Import Dependency and Cost Volatility: Key diaper raw materials, including superabsorbent polymer (SAP), fluff pulp, and specialty nonwoven fabrics, are predominantly imported, exposing Indonesian manufacturers to global commodity price fluctuations and currency exchange rate risk. SAP price volatility particularly affects manufacturing cost structures, as it represents the highest-cost diaper component.
Emerging Market Trends
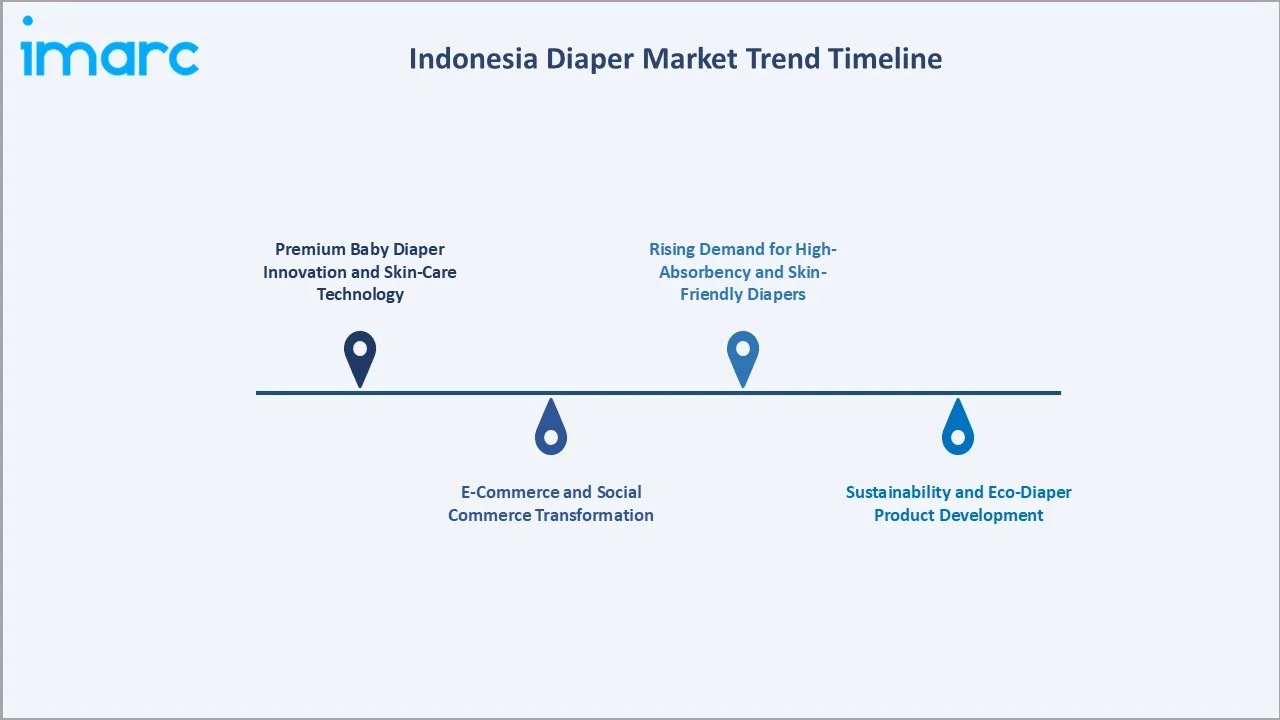
1. Premium Baby Diaper Innovation and Skin-Care Technology
Indonesian consumers are increasingly demanding premium baby diaper formats featuring advanced skin-care technologies, ultra-soft nonwoven cover layers, aloe vera and vitamin E moisturizing coatings, dermatologist-tested hypoallergenic materials, and enhanced leakage protection systems. Wetness indicator technology, baby skin pH-balanced materials, and 3D stretch waistbands are becoming standard expectations among urban middle-class Indonesian parents who view diaper quality as a direct reflection of infant health investment.
2. E-Commerce and Social Commerce Transformation
E-commerce platforms including Shopee, Tokopedia, and Lazada have fundamentally transformed Indonesia's diaper distribution landscape, enabling subscription purchase models, multi-pack bulk buying discounts, and direct-to-consumer brand engagement. Social commerce through TikTok Shop and Instagram Shopping allows diaper brands to reach new parents through peer parenting community influence. Live streaming commerce events featuring diaper brand promotions and product demonstrations attract millions of Indonesian viewers, creating powerful real-time purchase conversion opportunities that are reshaping how diaper brands allocate marketing investment.
3. Rising Demand for High-Absorbency and Skin-Friendly Diapers
In July 2024, Sweety introduced its Dry X-Pert diaper featuring X-Zone technology in Indonesia. The product is designed to absorb liquid up to five times faster, keep babies’ skin dry for as long as 12 hours, and provide a flexible fit that helps reduce rashes and irritation. This launch highlights growing demand for diapers with faster absorption, longer-lasting dryness, and improved skin protection. Consumers are increasingly favoring products that combine comfort, flexible fit, and rash-prevention features, encouraging further innovation in Indonesia’s diaper market.
4. Sustainability and Eco-Diaper Product Development
Environmental sustainability is emerging as a meaningful product differentiation axis in Indonesia's premium diaper segment. Plant-based biopolymer cover layers, reduced SAP content through advanced distribution layer technologies, and certified sustainable sourcing of fluff pulp are becoming marketing differentiators for premium-positioned brands. Bamboo-based diaper products are gaining trial among eco-conscious Indonesian parents.
Industry Value Chain Analysis
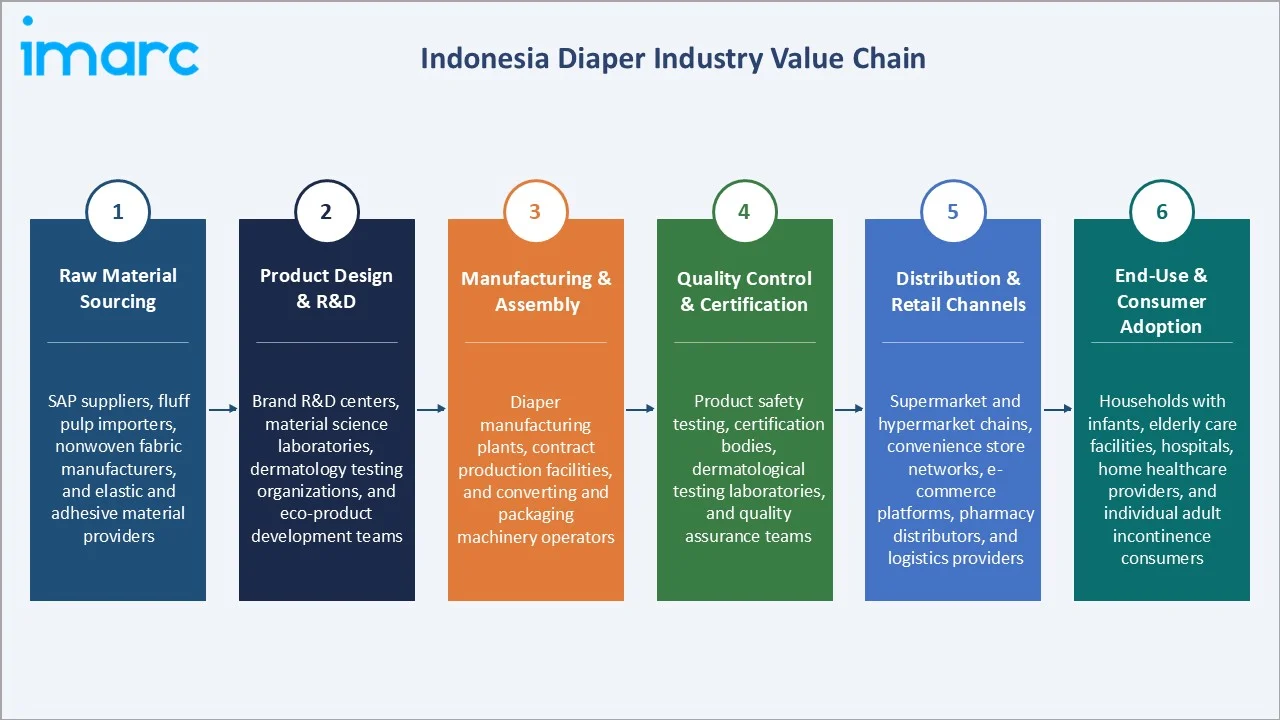
The Indonesia diaper value chain integrates raw material sourcing, product design and R&D, manufacturing and assembly, quality control and certification, distribution and retail channels, and end-use consumer adoption across baby and adult diaper categories.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
SAP suppliers, fluff pulp importers, nonwoven fabric manufacturers, and elastic and adhesive material providers. |
|
Product Design & R&D |
Brand R&D centers, material science laboratories, dermatology testing organizations, and eco-product development teams. |
|
Manufacturing & Assembly |
Diaper manufacturing plants, contract production facilities, and converting and packaging machinery operators. |
|
Quality Control & Certification |
Product safety testing, certification bodies, dermatological testing laboratories, and quality assurance teams. |
|
Distribution & Retail Channels |
Supermarket and hypermarket chains, convenience store networks, e-commerce platforms, pharmacy distributors, and logistics providers. |
|
End-Use & Consumer Adoption |
Households with infants, elderly care facilities, hospitals, home healthcare providers, and individual adult incontinence consumers. |
Manufacturing and assembly represent the most capital-intensive stage in the Indonesia diaper value chain, requiring sophisticated converting equipment, cleanroom production environments, and continuous quality monitoring to deliver consistent absorbency performance, leak protection, and skin-contact material safety. Leading manufacturers invest in advanced multi-layer diaper construction technology, high-speed production lines, and automated quality inspection systems that enable scale efficiencies while maintaining the product consistency that builds Indonesian consumer brand loyalty.
Technology Landscape in the Indonesia Diaper Industry
Advanced Absorbency and Material Technology
Modern diaper manufacturing incorporates multi-layer superabsorbent polymer (SAP) distribution systems that achieve high absorption capacity by weight in liquid while maintaining ultra-thin panel profiles. Acquisition and distribution layer (ADL) technology ensures rapid liquid transfer from the skin contact layer to the SAP core, reducing surface wetness and skin irritation. Nonwoven cover sheet innovations using spunbond-meltblown-spunbond (SMS) technology deliver softness, breathability, and structural integrity. Leading Indonesian manufacturers are adopting airlaid pulp composite core technology that enables thinner, lighter diapers with equivalent or superior absorbency performance.
E-Commerce Technology and Direct-to-Consumer Platforms
Indonesia's diaper market leaders are investing heavily in e-commerce technology capabilities, including subscription management systems, personalized recommendation algorithms, and digital loyalty programs. Brand-owned direct-to-consumer apps are enabling data-rich consumer engagement through newborn tracking features, diaper fit guides, and parenting community integration. Live commerce technology is enabling real-time product demonstration with one-click purchase integration, dramatically reducing the consideration-to-purchase journey for Indonesian diaper consumers.
Sustainable Materials and Biodegradable Technology
R&D investment in biodegradable diaper technologies is expanding as Indonesian consumer and regulatory pressure for environmentally responsible products intensifies. Plant-based polylactic acid (PLA) nonwoven cover layers, organic cotton cover materials, and certified sustainable bamboo fiber integration are at various stages of commercial development and launch in the Indonesian premium market. Waterless manufacturing processes and reduced packaging innovations are also being adopted to minimize the environmental footprint of diaper production and distribution operations in Indonesia.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Baby Diaper |
78.6% |
2025 |
|
Distribution Channel |
Supermarkets and Hypermarkets |
31.6% |
2025 |
|
Region |
Java |
48.7% |
2025 |

By Product Type
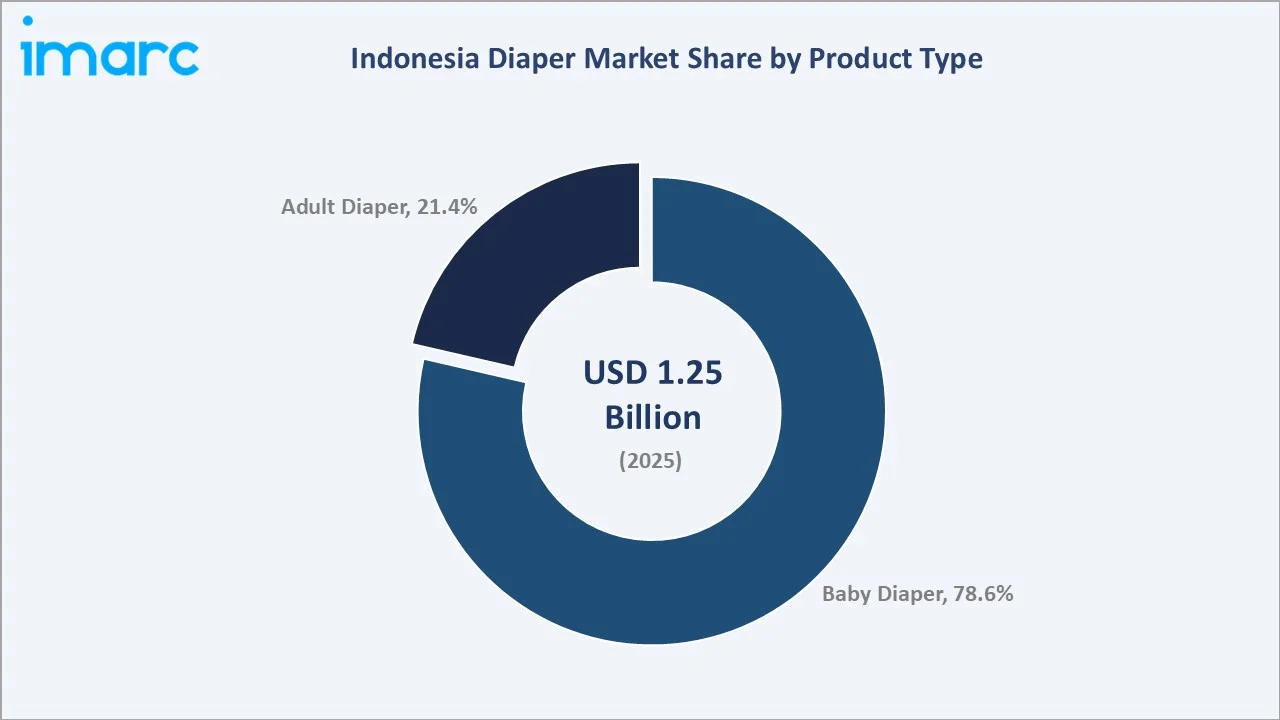
Baby diapers lead at 78.6% (2025), driven by Indonesia's large annual birth cohort, rising disposable diaper adoption rates among working mothers, and progressive premiumization toward skincare-enhanced and ultra-thin disposable formats.
To access detailed market analysis, Request Sample
Adult diapers at 21.4% represent the fastest-growing product type segment at ~7.8% CAGR, driven by Indonesia's aging demographic, expanding elderly care institutions, and growing caregiver awareness of continence management solutions. The pant-type adult diaper sub-segment is gaining rapid adoption for its discretion and ease of use.
By Distribution Channel
Supermarkets and hypermarkets lead at 31.6% (2025), providing broad product range access, competitive pricing through promotional offers, and convenient weekly household shopping integration across Indonesia's major retail chains.
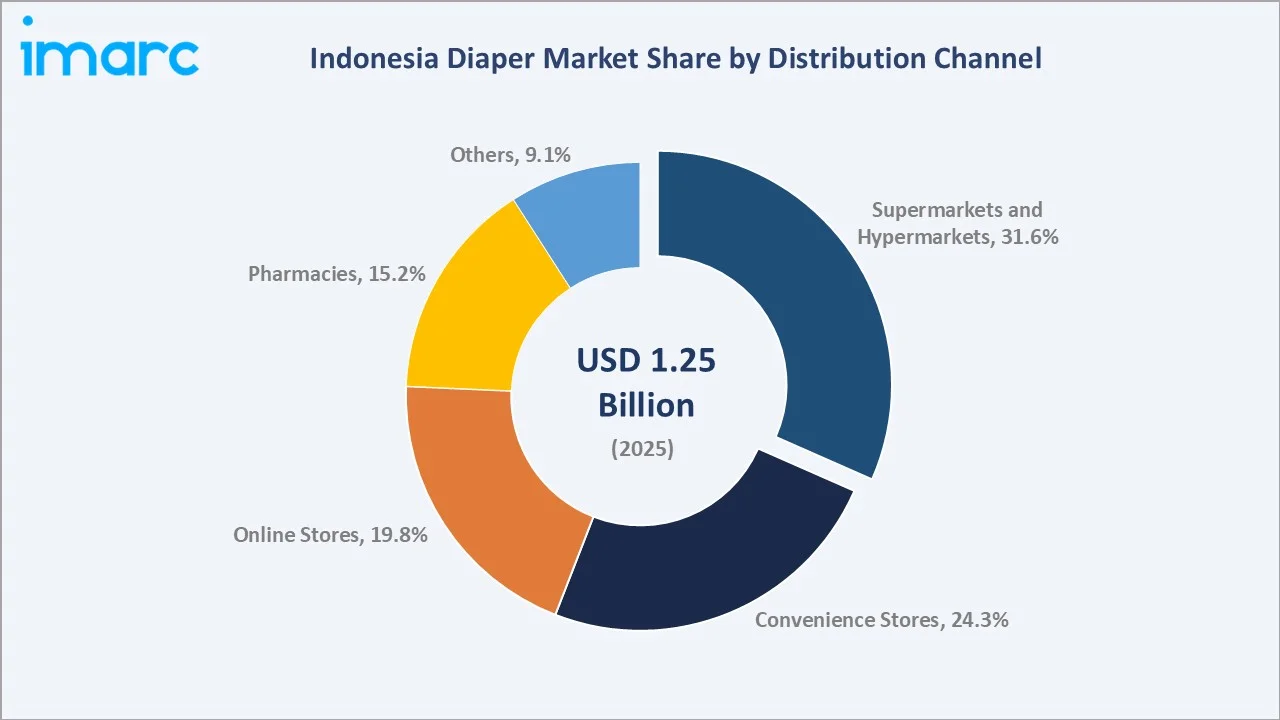
Convenience stores at 24.3% reflect extensive nationwide networks serving emergency and top-up diaper purchases. Online stores at 19.8% represent the fastest-growing channel at ~8.9% CAGR through subscription convenience and e-commerce platform promotions. Pharmacies at 15.2% serve both baby and adult diaper categories with health-oriented positioning.
Regional Market Insights
|
Region |
Share (2025) |
Key Indonesia Diaper Market Drivers & Characteristics |
|
Java |
48.7% |
Reflecting the highest population concentration, strongest urban middle-class penetration, most developed modern retail infrastructure, and highest working-mother participation rates driving premium diaper adoption. |
|
Sumatra |
21.4% |
Reflecting a large and growing urban population base, expanding modern trade retail penetration, rising household incomes, and increasing diaper brand awareness through e-commerce platform growth. |
|
Kalimantan |
11.2% |
Reflecting growing urbanization from resource sector employment, expanding convenience store networks, and rising disposable incomes driving progressive diaper adoption beyond major cities. |
|
Sulawesi |
8.3% |
Reflecting a younger demographic profile, growing urban centers including Makassar, and expanding retail infrastructure supporting increasing diaper brand accessibility across the island. |
|
Others |
10.4% |
Reflecting Papua, Maluku, Nusa Tenggara, and Bali regions with growing modern trade presence, rising incomes in tourism-dependent areas, and government infrastructure investment supporting distribution network expansion. |
Java's 48.7% dominance reflects its concentration of high population alongside the most mature modern retail and e-commerce distribution infrastructure. Sumatra's 21.4% reflects the island's large urban population centers, where modern retail penetration and rising incomes are accelerating the cloth-to-disposable transition.
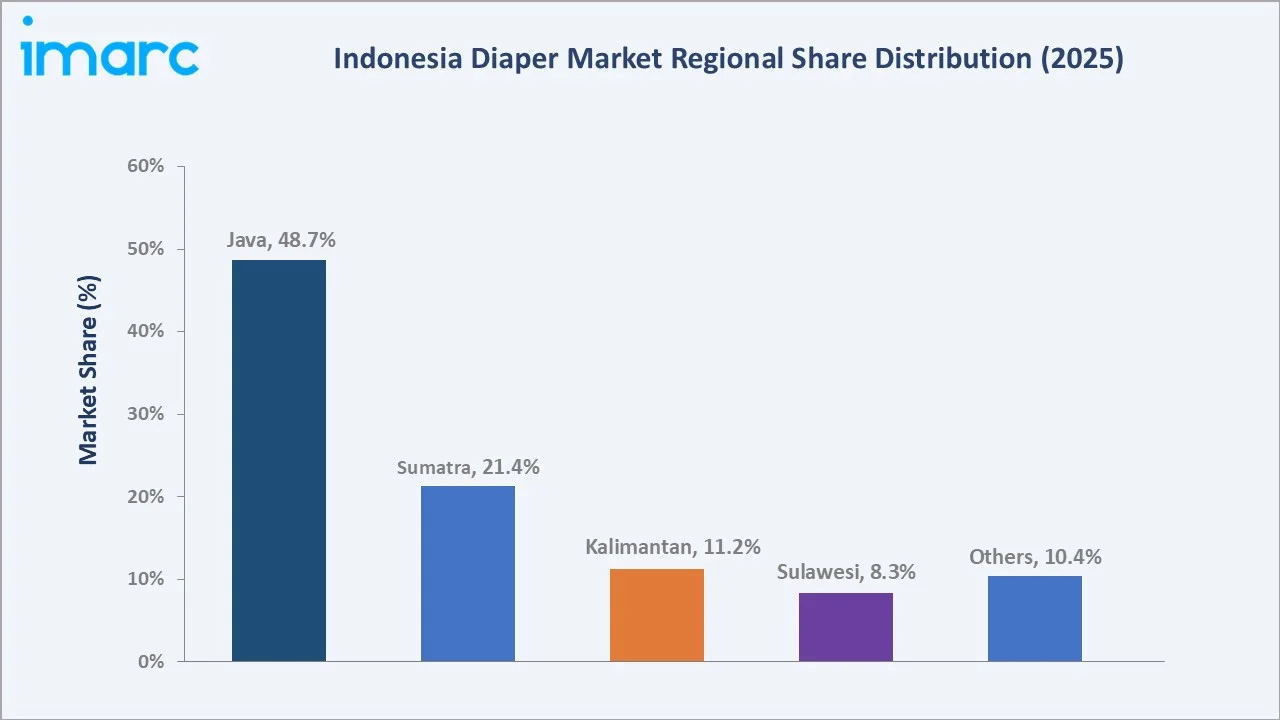
Kalimantan's 11.2% reflects the island's growing urban workforce in mining and plantation sectors, where rising disposable incomes and expanding network coverage are increasing diaper brand accessibility. Sulawesi at 8.3% is driven by Makassar's role as eastern Indonesia's commercial hub and growing retail modernization. The others at 10.4% encompass diverse markets from Bali's tourism-driven premium consumer base to Papua's government investment-backed development areas where diaper market penetration is early but growing.
Competitive Landscape
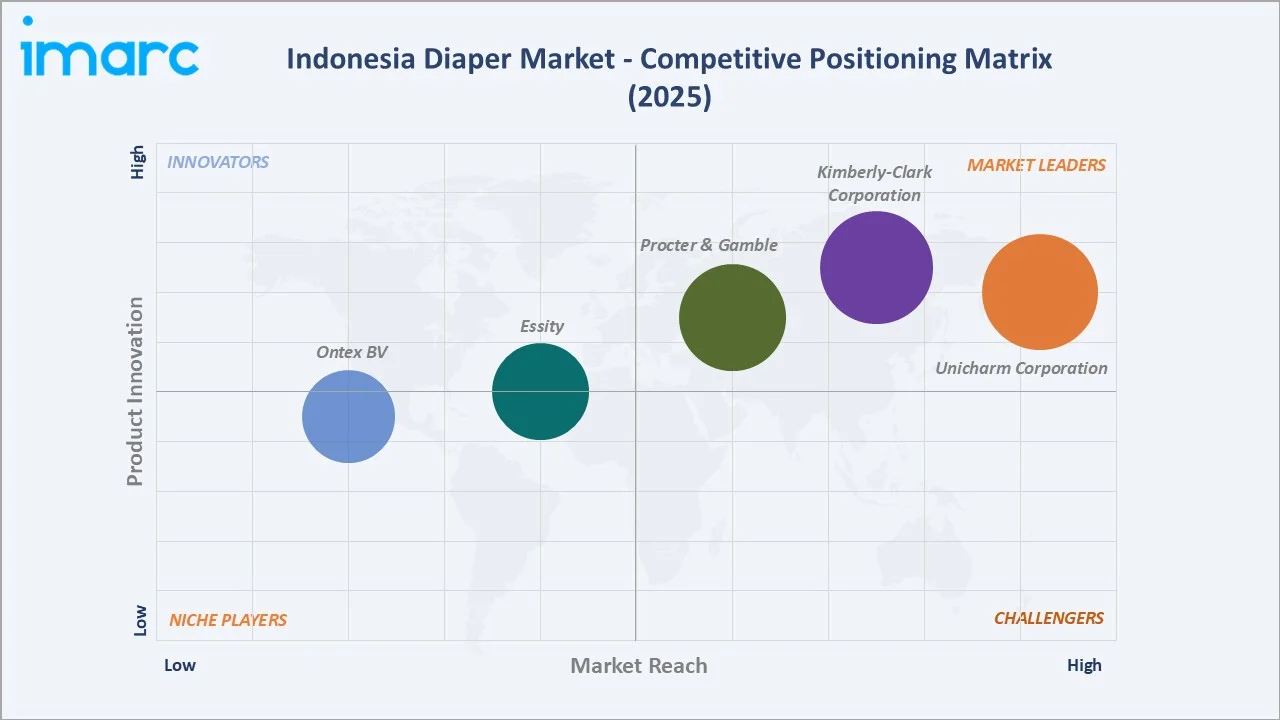
The Indonesia diaper market is moderately concentrated. Competitive dynamics are driven by brand equity, product innovation, distribution network depth, promotional spending, and pricing strategy. The rise of e-commerce has intensified competition by reducing barriers to national brand exposure and enabling smaller specialty brands to compete alongside multinational incumbents through digital marketing and subscription models.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Unicharm Corporation |
MamyPoko, Lifree, Fitti Pants, Certainty |
Market Leader |
Unicharm Indonesia leads the market through the MamyPoko brand franchise, which spans value, mid-range, and premium diaper tiers. |
|
Kimberly-Clark Corporation |
Sweety, Happy Nappy, Confidence |
Market Leader |
Kimberly-Clark Corporation plays a major role in the Indonesian diaper market through its acquisition and expansion of Softex Indonesia. |
|
Procter & Gamble |
Pampers |
Market Leader |
Procter & Gamble (P&G) plays a major role in the Indonesian baby diaper market through localized manufacturing and the distribution of its flagship Pampers brand. |
|
Essity |
Libero, TENA |
Established Player |
Essity serves the adult incontinence market through TENA, the recognized adult dignity care brand, and baby hygiene through Libero. |
|
Ontex BV |
Moltex Pure & Nature, Freelife |
Established Player |
Ontex BV plays a critical role as a major international competitor and contract manufacturer in the rapidly expanding Indonesian diaper market |
Companies across the competitive landscape are investing in e-commerce subscription model development, influencer marketing partnerships with Indonesian parenting communities, sustainability certification, and product innovation in premium and eco-friendly diaper segments. The market is expected to see further competition intensification as international brands seek to expand Indonesian presence, and domestic players strengthen manufacturing and distribution capabilities.
Key Company Profiles
Unicharm Corporation
Unicharm Corporation, a leading personal care company, operates Unicharm Indonesia as one of its most significant Asian manufacturing and commercial operations. The company's MamyPoko brand is Indonesia's most widely recognized baby diaper franchise, available across value, mid-range, and premium product tiers that collectively address Indonesia's diverse household income landscape. Unicharm Indonesia operates domestic manufacturing facilities that provide supply chain efficiency, rapid product adaptation for local preferences, and localized pricing advantages over purely import-dependent competitors. The Lifree adult diaper brand positions Unicharm strongly in the fastest-growing market segment.
- Key Brands: MamyPoko, Lifree, Fitti Pants, Certainty.
- Strategic Focus: Expanding MamyPoko premium tier penetration through digital marketing and e-commerce subscription models, accelerating Lifree adult diaper market development through healthcare institution partnerships and caregiver awareness campaigns, and advancing sustainable material integration in diaper formulations to address growing Indonesian environmental consciousness.
Kimberly-Clark Corporation
Kimberly-Clark Corporation operates its Indonesian business through baby diapers and a growing adult care portfolio, targeting the premium end of the Indonesian baby diaper market. The variants are positioned as the dermatologically superior choices for health-conscious Indonesian parents who prioritize infant skin health above price considerations. Kimberly-Clark's parenting content marketing strategy, delivered through the loyalty platform and social media parenting community partnerships, builds brand advocacy among Indonesian new parents and expectant mothers. Strong e-commerce performance supports the brand's premium pricing through subscription convenience and exclusive online bundle offers.
- Key Brands: Sweety, Happy Nappy, Confidence.
- Strategic Focus: Strengthening premium tier brand positioning through dermatologist endorsement marketing and hospital partnership programs, expanding e-commerce subscription and direct-to-consumer engagement channels, and developing sustainability-positioned diaper variants to capture Indonesian eco-conscious parent segments.
Market Concentration Analysis
The Indonesia diaper market exhibits moderate concentration. Unicharm's MamyPoko franchise commands the broadest market coverage across all income tiers, while Kimberly-Clark leads in the premium segment. Market concentration is expected to remain moderate through 2034, with the rapid growth of online channels creating opportunities for both incumbent brands to strengthen direct consumer relationships and new eco-positioned entrants to establish niche premium positions.
Investment & Growth Opportunities
Highest Growth Segments
Adult diapers (~7.8% CAGR), online store distribution channel (~8.9% CAGR), eco-friendly and biodegradable baby diapers, premium skin-care enhanced baby diaper formats, and institutional adult care product sales represent the highest-growth investment vectors in the Indonesia diaper market through 2034.
Investment Themes
- Adult diaper market development: Indonesia's aging demographic creates a structurally growing adult diaper market with current low penetration rates offering significant volume growth headroom. Investment in healthcare institution partnerships, caregiver education programs, and retail pharmacy distribution expansion will capture disproportionate market share as Indonesian adult diaper awareness and adoption accelerates through 2034.
- E-commerce subscription platform investment: Building robust direct-to-consumer subscription infrastructure and brand-owned platforms enables consistent recurring revenue streams, consumer data-rich personalization, and reduced customer acquisition costs. Subscription diaper models also reduce consumer price sensitivity, supporting premium product positioning and loyalty.
Future Market Outlook (2026-2034)
The Indonesia diaper market is projected to grow from USD 1.25 Billion in 2025 to USD 2.16 Billion by 2034, exhibiting a CAGR of 6.24% during 2026-2034. The market is projected to reach an anchor value of USD 1.70 Billion by 2030, representing the mid-period milestone at which e-commerce channels approach channel share parity with convenience stores and adult diapers demonstrate measurable mainstream consumer adoption.
Three structural forces will define the Indonesia diaper market through 2034. First, Indonesia's demographic fundamentals will sustain robust baby diaper demand. Second, the adult diaper segment's accelerating growth trajectory will reshape Indonesia's diaper market mix through 2034. Third, digital commerce transformation will continue to reshape distribution economics. These combined forces position Indonesia as one of Southeast Asia's most attractive and fastest-growing diaper markets through the forecast horizon of 2034.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with diaper brand executives, retail category managers, e-commerce platform representatives, healthcare institution procurement officers, and consumer behavior analysts. These discussions validated market size estimates, assessed product segment growth dynamics, evaluated channel evolution trends, and provided insights into competitive strategies and future innovation priorities in the Indonesia diaper market.
Secondary Research
Secondary research encompassed Indonesia population and birth rate statistics, product registration databases, retail chain annual reports, e-commerce platform category data, investor disclosures, consumer behavior surveys, and industry publications covering the Southeast Asian personal care and hygiene product markets.
Forecasting Models
Forecasting models incorporated historical diaper market revenue trends, demographic projections, household income growth scenarios, e-commerce adoption curves, and competitive market share dynamics. Both top-down approaches using Indonesia personal care market sizing and bottom-up segment volume and pricing models were applied and cross-validated to ensure forecast robustness across product type and distribution channel dimensions.
Indonesia Diaper Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered |
|
| Distribution Channels Covered | Supermarkets and Hypermarkets, Pharmacies, Convenience Stores, Online Stores, Others |
| Regions Covered | Java, Sumatra, Kalimantan, Sulawesi, Others |
| Companies Covered | Unicharm Corporation, Kimberly-Clark Corporation, Procter & Gamble, Essity, Ontex BV, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Indonesia diaper market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Indonesia diaper market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Indonesia diaper industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Indonesia Diaper Market Report
The Indonesia diaper market reached USD 1.25 Billion in 2025, driven by the country's large annual birth cohort, rising disposable incomes enabling premium product adoption, rapid e-commerce penetration, and growing adult diaper consumption from Indonesia's aging demographic.
The Indonesia diaper market is projected to grow at a CAGR of 6.24% during 2026-2034, sustained by demographic growth, income-driven premiumization, adult diaper segment expansion, and e-commerce distribution channel growth.
The market is projected to reach approximately USD 1.70 Billion by 2030, representing the mid-period milestone at which e-commerce channels approach parity with convenience stores and adult diapers achieve mainstream consumer adoption beyond institutional channels.
Baby diapers lead with a 78.6% share in 2025, driven by Indonesia's large annual birth cohort, rising disposable diaper adoption rates among urban working mothers, and progressive premiumization toward enhanced skincare and ultra-thin formats.
Supermarkets and hypermarkets lead with a 31.6% share in 2025, providing a broad product range, competitive promotional pricing, and convenient integration with regular household shopping patterns across Indonesia's major retail chains.
Java leads with a 48.7% share in 2025, driven by its concentration of Indonesia's population, highest urban household income levels, most developed modern retail infrastructure, and greatest penetration of working-mother households driving premium diaper adoption.
Key players include Unicharm Corporation, Kimberly-Clark Corporation, Procter & Gamble, Essity, and Ontex BV, among others.
The Indonesia diaper market is projected to reach USD 2.16 Billion by 2034, driven by sustained baby diaper demand, significant adult diaper segment growth, premium product mix expansion, and digital channel transformation.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade