
Japan Adhesives and Sealants Market Size, Share, Trends and Forecast by Adhesive Type, Sealant Type, Technology, Application, and Region, 2026-2034
Japan Adhesives and Sealants Market Size, Share, Trends & Forecast (2026-2034)
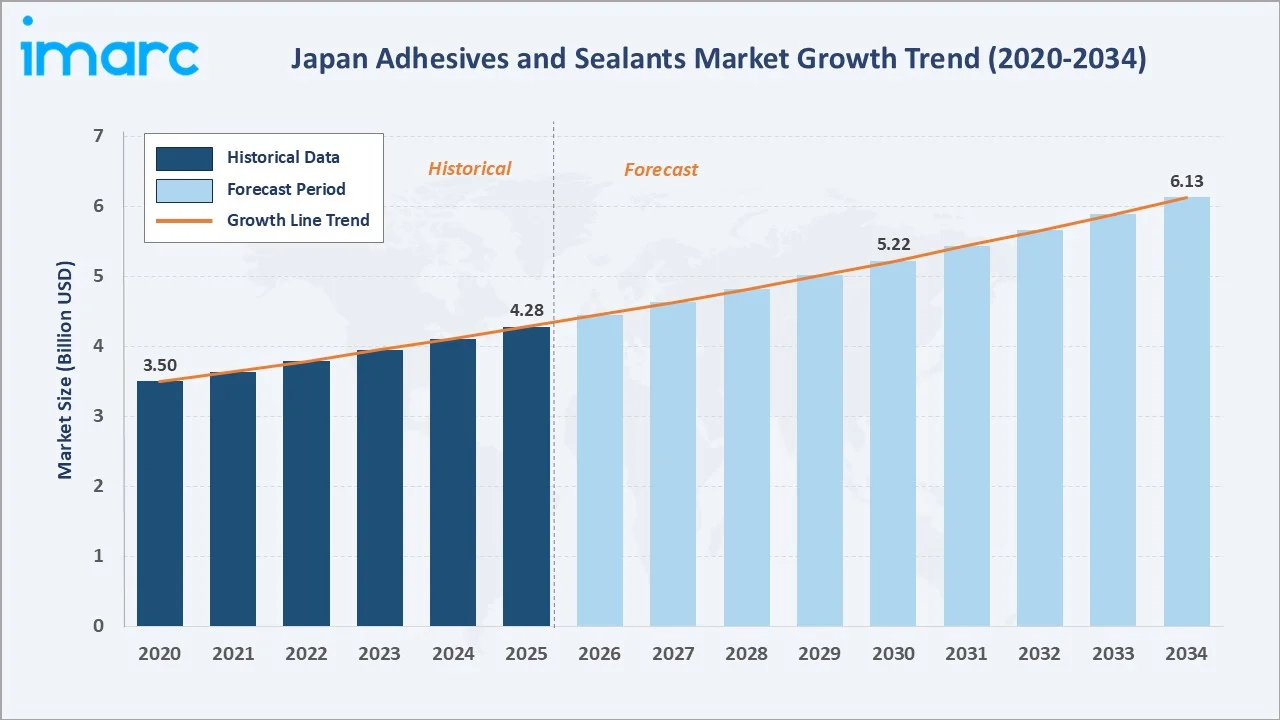
The Japan adhesives and sealants market grew from USD 4.28 Billion in 2025 to USD 4.45 Billion in 2026 and is projected to reach USD 6.13 Billion by 2034, growing at a CAGR of 4.09% during 2026-2034. The market is driven by rapid growth in automotive lightweighting, EV production, construction sector expansion, and electronics manufacturing demand for advanced bonding technologies across industrial applications. Acrylic leads adhesive types at 23.0%. Silicone dominates sealant types at 38.0%. Kanto Region commands 34.0% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 4.28 Billion |
|
Market Size (2026) |
USD 4.45 Billion |
|
Forecast Market Size (2034) |
USD 6.13 Billion |
|
CAGR (2026-2034) |
4.09% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Adhesive Type |
Acrylic (23.0%, 2025) |
|
Dominant Sealant Type |
Silicone (38.0%, 2025) |
|
Leading Region |
Kanto Region (34.0%, 2025) |
The Japan adhesives and sealants market size increased from USD 3.50 Billion in 2020 to USD 4.28 Billion in 2025 and is estimated to reach USD 4.45 Billion in 2026. The market is further expected to grow to USD 5.22 Billion by 2030 and USD 6.13 Billion by 2034. Japan adhesives and sealants market is commercially significant among Asia-Pacific specialty chemical markets, combining one of the most advanced industrial manufacturing bases with stringent quality and sustainability requirements driving premium adhesive adoption.
To get more information on this market, Request Sample
The acrylic segment leads adhesive types at 23.0%, driven by versatility across automotive, packaging, and construction. Silicone sealants dominate at 38.0% through high-temperature resistance and weatherproofing performance in electronics and construction applications.
Executive Summary
The Japan adhesives and sealants market expanded from USD 4.28 Billion in 2025 to an estimated USD 4.45 Billion in 2026, positioning it as one of Asia-Pacific's leading specialty adhesive markets. The market's scale is underpinned by Japan's advanced manufacturing ecosystem, automotive EV transition, and construction sector renewal. The market is projected to reach USD 6.13 Billion by 2034. Acrylic at 23.0% leads through versatility and VOC compliance. Silicone sealants at 38.0% reflect weatherproofing and electronics demand. Kanto Region leads regionally at 34.0%.
Key Market Insights
|
Insight |
Data |
|
Dominant Adhesive Type |
Acrylic – 23.0% share (2025) |
|
Dominant Sealant Type |
Silicone – 38.0% market share (2025) |
|
Leading Region |
Kanto Region – 34.0% share (2025) |
|
Market Opportunity |
EV battery & lightweight assembly bonding; eco-friendly water-based adhesives; electronics semiconductor bonding; construction sealants |
Key Analytical Observations Supporting the Above Data:
- Acrylic at 23.0%: Acrylic adhesives dominate due to versatility across substrates, UV resistance, and compliance with Japan's stringent VOC reduction guidelines across automotive, electronics, and packaging manufacturing sectors.
- Silicone at 38.0%: Silicone sealants lead through superior thermal stability, weatherproofing capability, and flexibility requirements in Japan's electronics and architectural construction markets demanding long-term durability.
- Kanto Region at 34.0%: Kanto Region dominates through Tokyo-Yokohama industrial concentration, Japan's highest density of automotive Tier-1 suppliers, electronics manufacturers, and construction activity requiring precision adhesive applications.
Japan Adhesives and Sealants Market Overview
Japan adhesives and sealants market is positioned at a unique intersection of advanced industrial manufacturing, stringent environmental compliance requirements, and growing demand from EV production, semiconductor manufacturing, and infrastructure renewal. The market's commercial structure reflects Japan's precision manufacturing culture and zero-defect quality standards across automotive, electronics, and construction sectors.
Japan adhesives and sealants ecosystem integrates domestic resin producers, international specialty chemical suppliers, formulation manufacturers, and end-use industries including automotive OEMs, electronics brands, construction contractors, and packaging manufacturers. Macroeconomic drivers include green chemistry mandates, automotive electrification, and aging infrastructure renewal programs.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
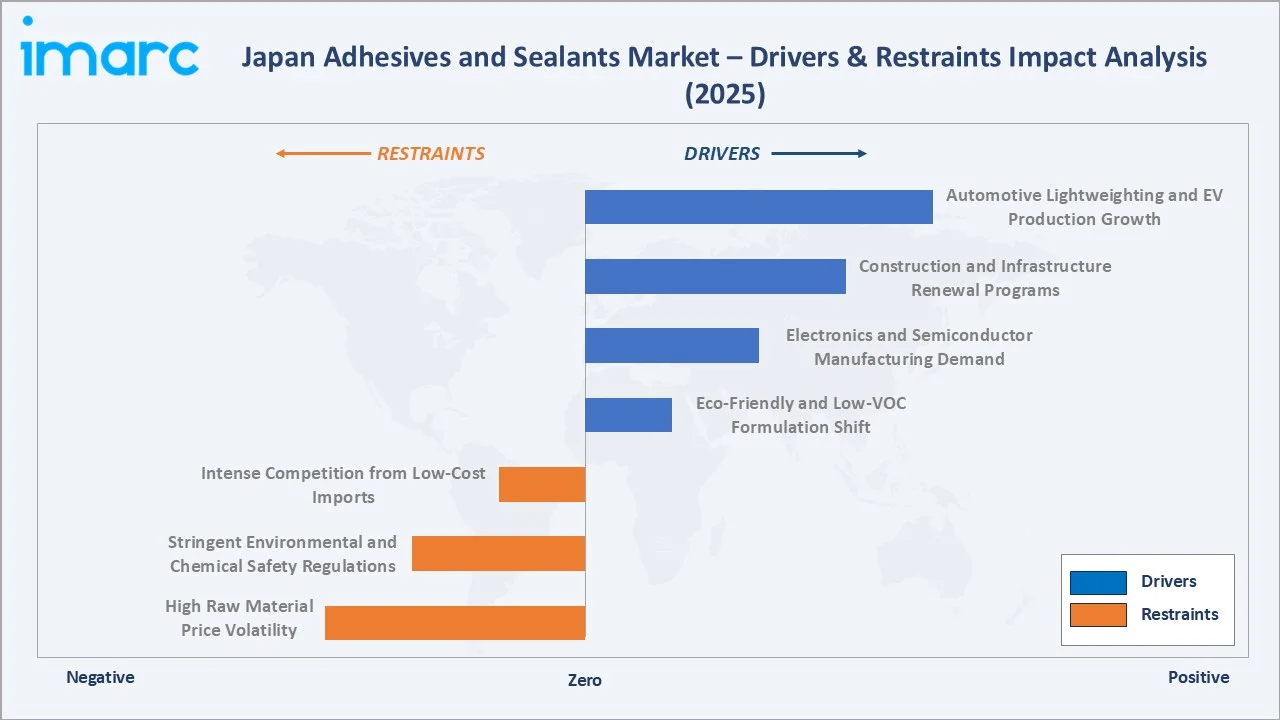
- Automotive Lightweighting and EV Production Growth: Japan's automotive industry transition to battery electric vehicles drives significant demand for high-performance structural adhesives that bond dissimilar materials including aluminum, CFRP, and high-strength steel. Adhesives replace mechanical fasteners in EV battery pack assembly, reducing weight by up to 20% while improving structural rigidity. Japan's major OEMs including Toyota, Honda, and Nissan are specifying advanced polyurethane and epoxy adhesive systems across EV platforms, creating sustained demand growth for premium adhesive products throughout the forecast period.
- Construction and Infrastructure Renewal Programs: Japan's aging infrastructure including highways, bridges, and public buildings requires extensive renovation using advanced sealants and structural adhesives that meet earthquake resistance and weatherproofing standards. Government investment in urban renewal and disaster-resilient construction drives adoption of silicone and polyurethane sealants in curtain wall systems, façade bonding, and joint sealing applications. Post-earthquake reconstruction programs across Tohoku and other regions create sustained demand for construction-grade adhesives and structural sealants with seismic performance certification.
- Electronics and Semiconductor Manufacturing Demand: Japan's advanced electronics manufacturing sector including semiconductor fabrication, printed circuit board assembly, and display manufacturing demands precision adhesives with ultra-low outgassing, thermal management, and electrical insulation properties. The expansion of domestic semiconductor production capacity through TSMC Kumamoto and Rapidus facilities creates incremental demand for specialty epoxy underfills, thermal interface adhesives, and die-attach materials. Japan's position as a global supplier of electronic components amplifies domestic adhesive consumption across the semiconductor supply chain.
- Eco-Friendly and Low-VOC Formulation Shift: Japan's Air Pollution Prevention Act and workplace chemical safety regulations drive systematic replacement of solvent-based adhesives with water-based, hot-melt, and reactive adhesive systems. Manufacturers are reformulating product lines to meet evolving VOC emission limits and achieve Eco Mark certification requirements. Growing procurement emphasis on green chemistry credentials from automotive and electronics OEM customers accelerates adoption of sustainable adhesive technologies, benefiting suppliers with established waterborne and UV-cure product portfolios across multiple application segments.
Market Restraints
- High Raw Material Price Volatility: Adhesive and sealant formulations depend heavily on petrochemical-derived resins including acrylic acid, MDI, TDI, and epoxy precursors whose prices fluctuate with crude oil markets and global chemical supply dynamics. Price spikes of 15-30% in key polymer feedstocks during supply disruption cycles compress manufacturer margins and create pricing instability that makes long-term customer contracts difficult to maintain. Specialty monomers sourced from limited global suppliers create additional vulnerability to supply chain disruptions affecting production scheduling and delivery commitments.
- Stringent Environmental and Chemical Safety Regulations: Japan's Chemical Substances Control Law (CSCL), Act on the Evaluation of Chemical Substances and Regulation of Their Manufacture, and workplace hazardous substance regulations create complex compliance burdens for adhesive formulators. Registration requirements for new chemical substances, restricted substance lists from automotive OEM customers, and evolving REACH-aligned regulations require continuous product reformulation investment. Compliance costs for certification, testing, and documentation increase barriers to product innovation and slow the introduction of new adhesive technologies to the Japanese market.
- Intense Competition from Low-Cost Imports: Chinese adhesive manufacturers with significantly lower production costs are increasingly penetrating Japan's commodity adhesive segments for packaging, construction, and general industrial applications. Import price pressure in lower-specification product categories erodes margins for domestic and international suppliers serving Japan's price-sensitive industrial customers. The growing availability of certified and tested Chinese adhesive products meeting JIS standards reduces the traditional quality premium that domestic suppliers commanded, intensifying competitive pressure in mid-market adhesive categories.
Market Opportunities
- EV Battery Assembly and Thermal Management Adhesives: Japan's EV production ramp creates demand for specialty thermally conductive adhesives, battery cell potting compounds, and structural bonding systems for battery module assembly. These specialty adhesive systems command significant price premiums and represent a high-growth segment aligned with Japan's automotive industry transformation priorities.
- Bio-Based and Sustainable Adhesive Formulations: Development of bio-derived adhesive resins from plant-based feedstocks enables formulators to address Japan's growing corporate sustainability commitments and circular economy legislation. Bio-based adhesives with competitive performance properties represent a differentiated market position for Japanese manufacturers seeking to strengthen ESG credentials across supply chains.
Market Challenges
- Technical Performance Requirements in Precision Applications: Japan's advanced manufacturing sectors require adhesive systems meeting extreme performance specifications for bond strength, thermal cycling resistance, chemical resistance, and process compatibility. Meeting these specifications requires sustained R&D investment and sophisticated formulation expertise that creates high barriers for smaller adhesive suppliers seeking entry into premium automotive and electronics segments.
- Substrate Diversification in Lightweighting Applications: Expanding use of CFRP, glass fiber composites, and multi-material assemblies in automotive and aerospace applications requires adhesive systems capable of bonding dissimilar materials with differing thermal expansion coefficients. Developing qualified adhesive solutions for new substrate combinations requires extensive application testing and OEM approval processes that slow product commercialization timelines.
Emerging Market Trends
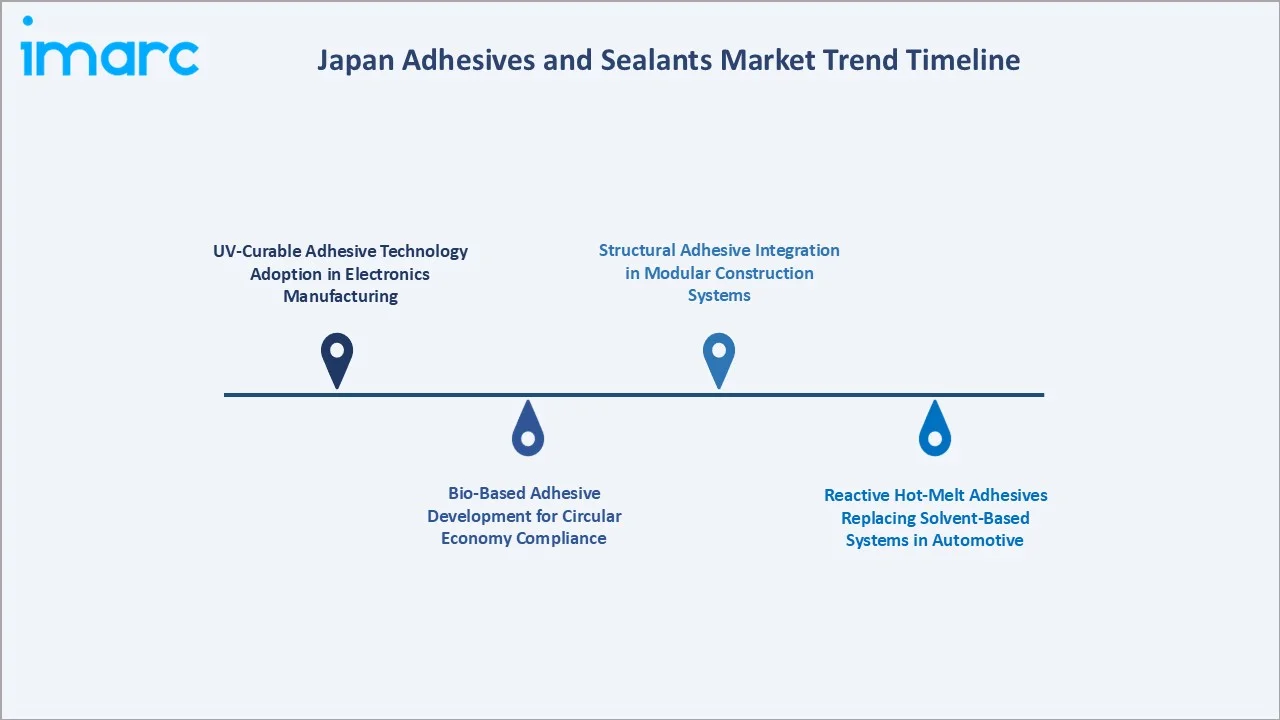
1. UV-Curable Adhesive Technology Adoption in Electronics Manufacturing
UV-curable adhesives are displacing traditional heat-cure systems in Japan's precision electronics manufacturing for display bonding, component encapsulation, and FPC assembly. Instant cure capability, energy efficiency, and compatibility with heat-sensitive substrates drive adoption across smartphone, automotive display, and IoT device manufacturing.
2. Reactive Hot-Melt Adhesives Replacing Solvent-Based Systems in Automotive
Reactive polyurethane hot-melt adhesives are rapidly replacing solvent-based systems in Japan's automotive trim, headliner, and door panel assembly. VOC elimination, improved bond performance, and compatibility with automated application systems drive their adoption across Toyota, Honda, and Nissan supply chains.
3. Structural Adhesive Integration in Modular Construction Systems
Japan's growing modular and prefabricated construction sector is integrating structural adhesives for façade panel bonding, floor system assembly, and curtain wall fabrication. Performance-certified structural adhesive systems replace mechanical fasteners in seismically designed building components, creating demand for high-strength, flexible sealant and bonding systems.
4. Bio-Based Adhesive Development for Circular Economy Compliance
Japan's leading adhesive manufacturers are investing in bio-based resin platforms derived from succinic acid, rosin esters, and soy protein to address corporate carbon neutrality commitments by 2050. Bio-based adhesives with mechanical properties matching petroleum-based alternatives represent a growing premium segment attracting R&D investment across the industry.
Industry Value Chain Analysis
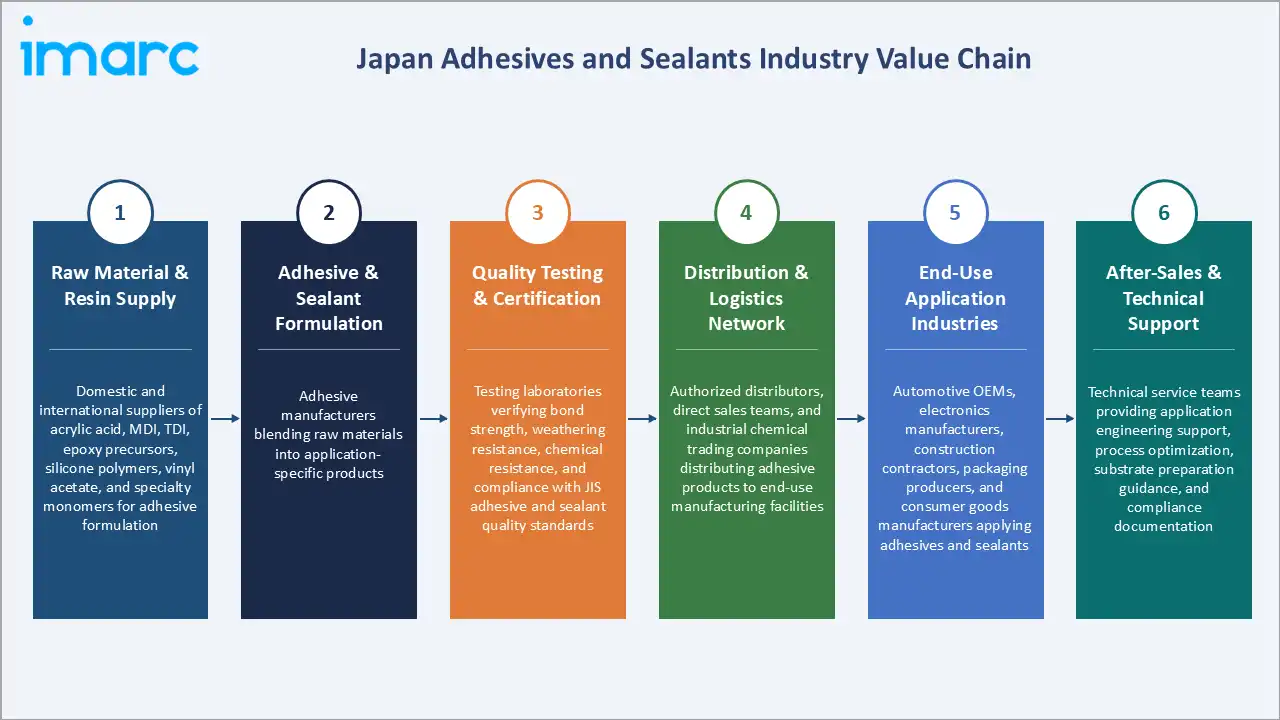
Japan adhesives and sealants value chain is one of the most technically sophisticated in Asia-Pacific, combining world-class resin and polymer production, precision formulation expertise, and integration with Japan's advanced automotive, electronics, and construction manufacturing ecosystems through direct supply relationships and technical collaboration programs.
|
Stage |
Key Participants |
|
Raw Material & Resin Supply |
Domestic and international suppliers of acrylic acid, MDI, TDI, epoxy precursors, silicone polymers, vinyl acetate, and specialty monomers for adhesive formulation |
|
Adhesive & Sealant Formulation |
Adhesive manufacturers blending raw materials into application-specific products |
|
Quality Testing & Certification |
Testing laboratories verifying bond strength, weathering resistance, chemical resistance, and compliance with JIS adhesive and sealant quality standards |
|
Distribution & Logistics Network |
Authorized distributors, direct sales teams, and industrial chemical trading companies distributing adhesive products to end-use manufacturing facilities |
|
End-Use Application Industries |
Automotive OEMs, electronics manufacturers, construction contractors, packaging producers, and consumer goods manufacturers applying adhesives and sealants |
|
After-Sales & Technical Support |
Technical service teams providing application engineering support, process optimization, substrate preparation guidance, and compliance documentation |
The formulation and quality testing stages are Japan adhesives value chain's most commercially significant, where manufacturers invest significantly in application-specific formulation development and OEM qualification processes to secure long-term supply agreements with Japan's automotive, electronics, and construction customers.
Technology Landscape in the Japan Adhesives and Sealants Industry
Water-Based Adhesive Technology
Water-based adhesive systems represent Japan's fastest-growing technology segment, driven by VOC reduction mandates and green chemistry adoption across packaging, paper, and construction applications. Acrylic emulsion and polyvinyl acetate (PVA) water-based formulations achieve performance parity with solvent-based systems in key applications while meeting Japan's evolving workplace safety and environmental compliance requirements.
Reactive Adhesive and Sealant Technology
Reactive polyurethane, epoxy, and silicone systems represent Japan's highest-value technology segment, serving precision automotive, electronics, and aerospace applications requiring structural bond strength and thermal stability. Two-component and moisture-cure reactive systems provide irreversible crosslinked bonds that meet stringent automotive OEM specifications for crash-load bearing joints and seismic-resistant construction assemblies.
Hot-Melt and UV-Cure Technology
Hot-melt adhesive technology serves Japan's high-throughput packaging, bookbinding, and product assembly markets with instant bond formation and process efficiency advantages. UV-cure systems are the preferred technology for Japan's electronics precision bonding applications, enabling instant curing at ambient temperature without thermal damage to heat-sensitive components in display panel, semiconductor, and PCB assembly operations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Adhesive Type |
Acrylic |
23.0% |
2025 |
|
Sealant Type |
Silicone |
38.0% |
2025 |
|
Technology |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
34.0% |
2025 |

By Adhesive Type
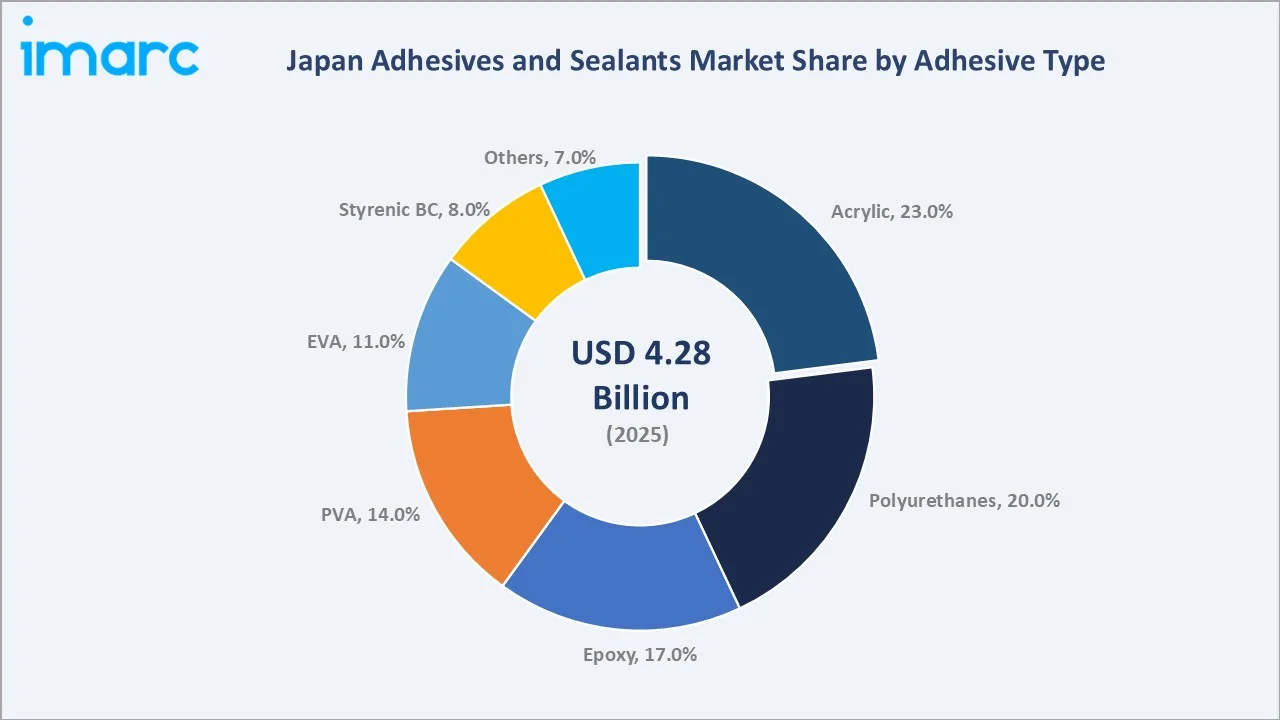
Acrylic leads at 23.0% (2025). The acrylic adhesive segment encompasses the broadest application range in Japan's adhesive market, spanning pressure-sensitive tapes, structural assembly adhesives, and waterborne formulations. Acrylic's UV stability, versatility across substrates, and reformulation flexibility for water-based systems position it as the preferred adhesive chemistry across automotive, electronics, and packaging applications.
To access detailed market analysis, Request Sample
Polyurethanes at 20.0% are growing through EV battery assembly and automotive interior bonding applications. Epoxy at 17.0% serves structural and electronics applications requiring maximum bond strength. PVA at 14.0% dominates woodworking and paper applications. EVA at 11.0% serves hot-melt packaging and bookbinding, while Styrenic Block Copolymers at 8.0% address pressure-sensitive and hygiene product applications.
By Sealant Type
Silicone leads at 38.0% (2025). The silicone sealant segment commands a dominant position in Japan's sealant market through unmatched high-temperature resistance, UV stability, and flexibility across temperature cycling environments in electronics encapsulation, automotive glazing, and architectural construction sealing applications requiring 20-plus-year service life.
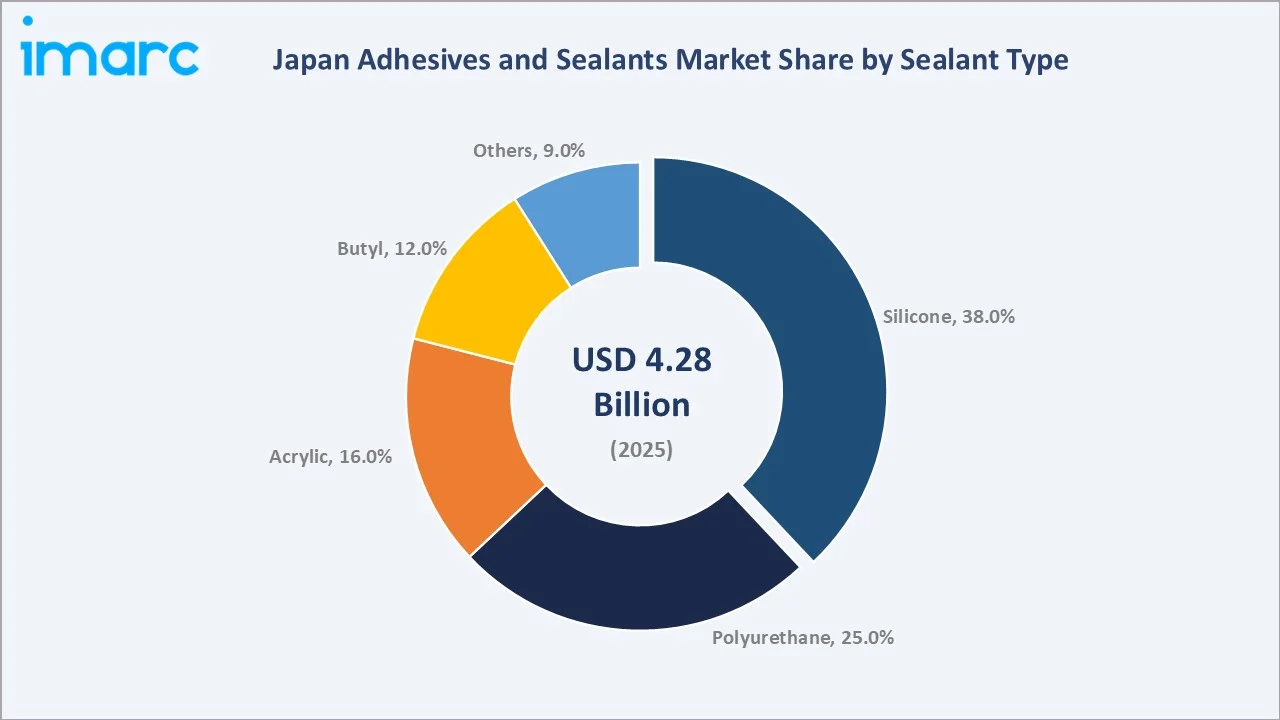
Polyurethane sealants at 25.0% serve automotive body sealing and construction joint applications requiring paintability and mechanical flexibility. Acrylic sealants at 16.0% serve general construction and consumer markets. Butyl at 12.0% provides waterproofing in roofing, window glazing, and HVAC system sealing. Others at 9.0% include specialty polysulfide and hybrid MS-polymer formulations.
Regional Market Insights
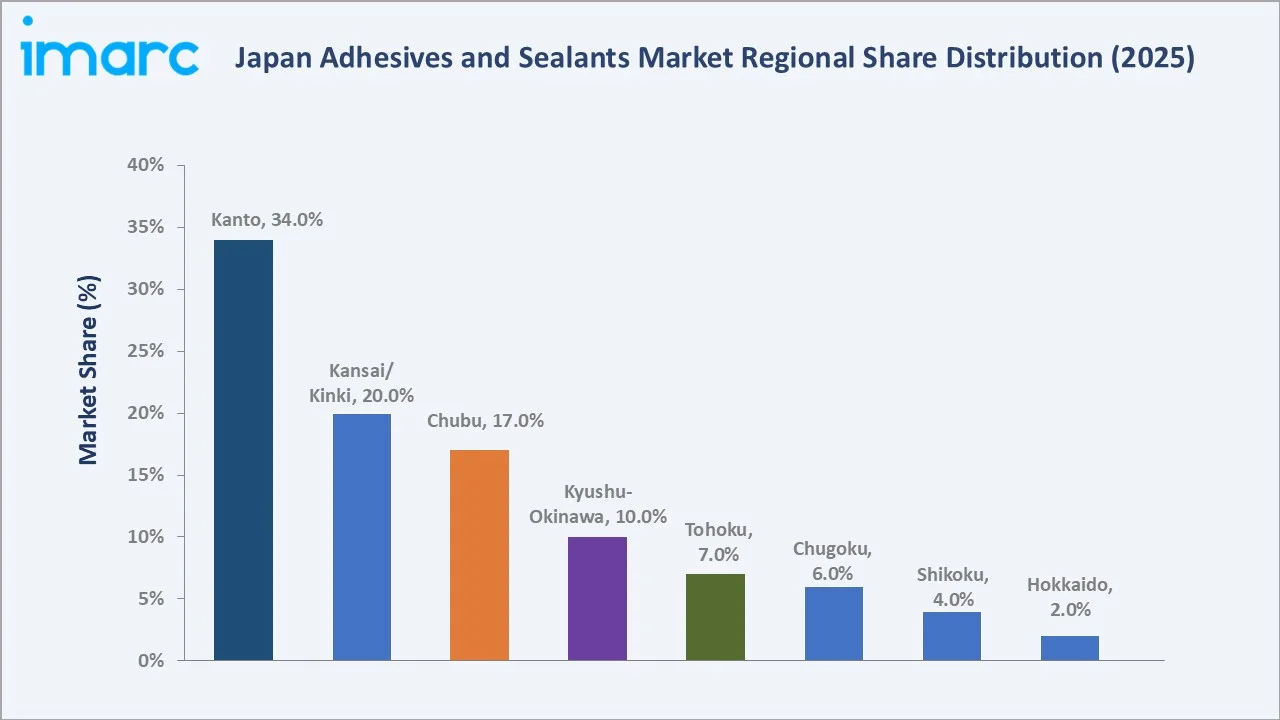
|
Region |
Share (2025) |
Key Japan Adhesives and Sealants Market Drivers & Characteristics |
|
Kanto Region |
34.0% |
Driven by Tokyo-Yokohama industrial cluster, electronics manufacturing density, and Japan's highest concentration of automotive Tier-1 suppliers and construction activity. |
|
Kansai/Kinki Region |
20.0% |
Reflects Osaka-Kobe manufacturing and chemical industry clusters, supporting automotive, packaging, and industrial adhesive and sealant demand. |
|
Central/Chubu Region |
17.0% |
Nagoya automotive corridor anchors demand, with Toyota and supplier network creating sustained adhesive volumes for vehicle assembly and component manufacturing. |
|
Kyushu-Okinawa Region |
10.0% |
Semiconductor and automotive assembly manufacturing in Fukuoka and Kumamoto support adhesive demand in electronics and automotive components. |
|
Tohoku Region |
7.0% |
Post-disaster reconstruction and infrastructure renewal investments support structural adhesive and waterproofing sealant demand in building and civil engineering. |
|
Chugoku Region |
6.0% |
Hiroshima automotive and shipbuilding industries provide industrial adhesive demand for vehicle body assembly and marine waterproofing applications. |
|
Shikoku Region |
4.0% |
Chemical processing and paper industry machinery requirements supported by specialty adhesive demand for industrial equipment manufacturing and maintenance. |
|
Hokkaido Region |
2.0% |
Construction and food processing sectors support adhesive and sealant demand for cold-climate building applications and food-grade packaging bonding. |
Kanto Region's 34.0% market leadership reflects Japan's industrial center of gravity, with Tokyo-Yokohama manufacturing belts concentrating automotive OEM supply chains, electronics assembly facilities, and major construction activity requiring high-specification adhesive and sealant products across application segments.Chubu Region's 17.0% reflects Nagoya's automotive manufacturing dominance, where Toyota's global production engineering drives precision adhesive specification and volume across the Tier-1 and Tier-2 supply base. Kyushu-Okinawa at 10.0% is growing above the national average as semiconductor and automotive investment expands adhesive demand from previously lighter industrial regions.
Competitive Landscape
Japan adhesives and sealants market competitive landscape combines global chemical majors and established domestic manufacturers competing on formulation technology, OEM qualification credentials, and technical service capability. Japan's precision quality standards and long-term customer relationship culture create high barriers to entry for new suppliers.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Henkel AG & Co. KGaA |
Loctite, Technomelt, Bonderite, Aquence, Pritt |
Market Leader |
Global adhesive technology leader with comprehensive product portfolio across automotive, electronics, and industrial applications in Japan. |
|
HB Fuller Company |
Swift series |
Global Player |
Strong hot-melt and reactive adhesive portfolio for packaging, hygiene, and industrial assembly markets across Japan. |
|
Konishi Co., Ltd. |
Bond series, MOS7 |
Specialist |
Well-established Japanese consumer and industrial adhesive brand with strong construction, woodworking, and DIY channel distribution. |
|
Toagosei Co., Ltd. |
ARON ALPHA, Aronix, Aronbond |
Innovator |
Leading cyanoacrylate and UV-cure specialist with globally recognized ARON ALPHA instant adhesive brand and electronics segment expertise. |
|
3M |
Scotch-Weld, VHB, 3M Adhesive |
Technology Player |
Broad adhesive tape, structural adhesive, and specialty bonding product portfolio serving Japanese automotive, electronics, and industrial markets. |
Key players include Henkel AG & Co. KGaA, HB Fuller Company, Konishi Co., Ltd., Toagosei Co., Ltd., 3M, and others.
Key Company Profiles
Henkel AG & Co. KGaA
Henkel AG & Co. KGaA is the world's largest adhesives manufacturer and a market leader in Japan's adhesives and sealants market, operating through Henkel Japan Ltd. with a comprehensive product portfolio serving automotive, electronics, industrial, and consumer markets.
- Key Products: Loctite structural adhesives, Technomelt hot-melt adhesives, Bonderite surface treatment systems, Aquence automotive sealants, and Teroson sealing compounds for automotive body-in-white applications.
- Strategic Focus: Strengthening automotive EV adhesive systems portfolio, expanding semiconductor and electronics bonding technology offerings, and developing low-carbon adhesive formulations aligned with Japan's corporate carbon neutrality targets and OEM sustainability procurement requirements.
3M
3M Company is a global science and technology leader with a broad and well-established adhesives and sealants portfolio serving Japan's automotive, electronics, industrial, and consumer markets through 3M Japan Ltd., leveraging its materials science platform across more than 60,000 products to deliver bonding, sealing, and surface protection solutions.
- Key Products: Scotch-Weld structural adhesives including one-part epoxy adhesives 6101 and 6102, VHB acrylic foam bonding tapes for automotive and electronics assembly, Scotch masking and packaging tapes, 3M Structural Adhesive Film series, and specialty adhesive solutions for EV battery thermal management and electronics encapsulation applications.
- Strategic Focus: Expanding adhesive tape and structural bonding solutions for Japan's EV battery assembly and automotive lightweighting market, deepening electronics adhesive and display film capabilities aligned with Japan's semiconductor and consumer electronics manufacturing sectors, and leveraging 3M Japan Ltd.'s established domestic manufacturing and distribution network to grow share in precision industrial bonding applications across automotive OEM and electronics Tier-1 supply chains.
Market Concentration Analysis
Japan adhesives and sealants market is moderately concentrated, with global leaders commanding estimated combined shares of 25-30% of the organized market by value, alongside strong domestic players collectively holding approximately 20-25%. The market's high OEM qualification barriers and technical service intensity support incumbent supplier positions.
Market concentration is evolving through multinational supplier acquisitions of domestic Japanese companies, exemplified by Sika's Hamatite acquisition, creating hybrid entities with both global technology access and established domestic OEM supply relationships. Domestic players are responding by accelerating specialty product development in EV and electronics adhesive segments where proprietary technology provides competitive protection.
Investment & Growth Opportunities
Highest Growth Segments
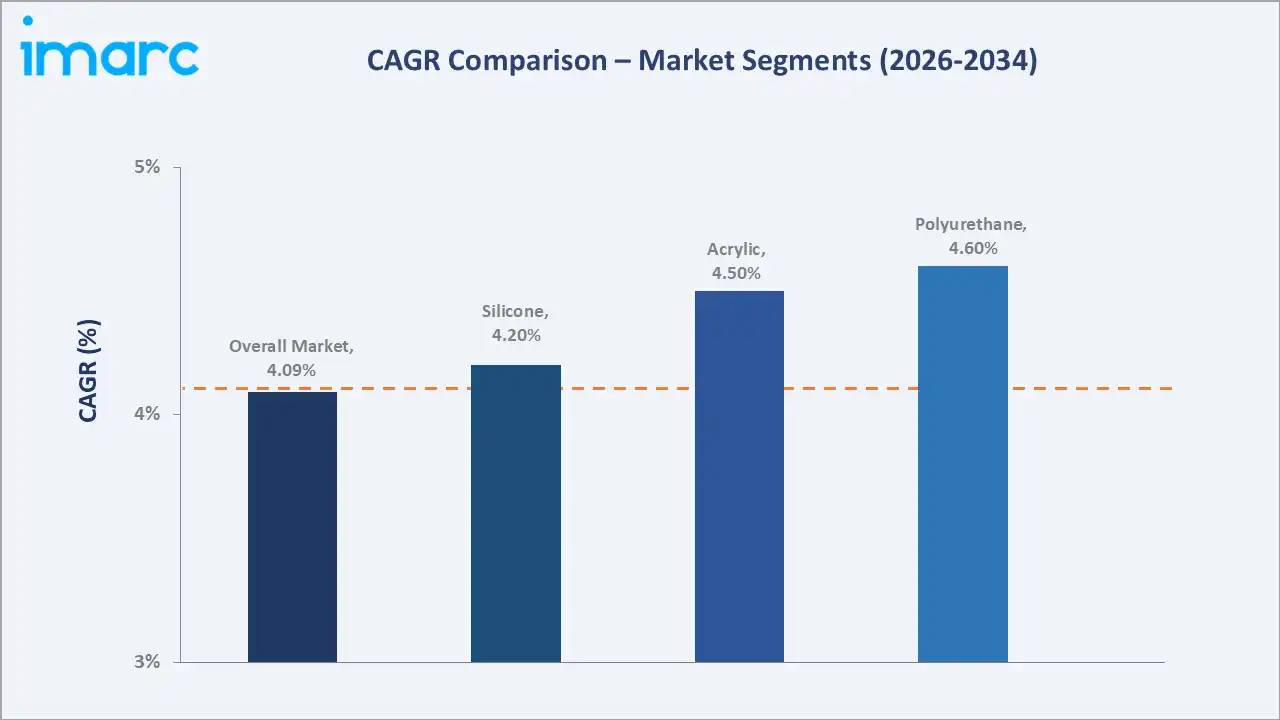
Kanto Region adhesive and sealant supply (~4.7% CAGR), polyurethane sealants (~4.6% CAGR), and silicone sealants (~4.2% CAGR) represent Japan's highest-growth adhesives and sealants investment vectors through 2034.
Emerging Investment Opportunities
Japan's EV-specific adhesive segment represents the market's most commercially significant emerging growth opportunity, with battery module assembly, power electronics potting, and lightweight structural bonding creating a USD 200-300 million incremental market by 2030. Thermally conductive adhesive formulations enabling heat dissipation in battery enclosures command 3-5x price premiums over conventional structural adhesives.
Investment Themes
- EV battery and power electronics specialty adhesive development: Japan's automotive electrification creates demand for thermally conductive, electrically insulating, and flame-retardant adhesive systems with OEM qualification credentials representing the highest-value specialty adhesive investment theme.
- Bio-based and sustainable adhesive platform development: Japan's corporate carbon neutrality commitments create growing procurement preference for bio-derived adhesive systems, providing differentiation opportunity for suppliers investing in plant-based resin technology platforms meeting performance parity with petroleum-based alternatives.
Future Market Outlook (2026-2034)
The Japan adhesives and sealants market is projected to grow from USD 4.28 Billion in 2025 to USD 4.45 Billion in 2026, reaching USD 6.13 Billion by 2034, registering a CAGR of 4.09% during 2026-2034. The market's anchor value of USD 5.22 Billion in 2030 reflects Japan's adhesive market at a structural growth inflection driven by EV production scale-up and semiconductor manufacturing expansion.
Three structural forces define Japan adhesives and sealants market growth through 2034: automotive EV transition creating incremental demand for specialty bonding systems; semiconductor and electronics manufacturing expansion requiring precision adhesive materials; and Japan's aging infrastructure renewal creating sustained construction adhesive and sealant demand above the historical market growth rate.
Research Methodology
Primary Research
Primary research comprised structured interviews with Japan adhesives and sealants industry stakeholders including Technical Directors, Procurement Managers, Application Engineers, OEM Specification Teams, and regulatory compliance specialists across automotive, electronics, construction, and packaging end-use segments supplemented by adhesive formulator and distributor expert consultations.
Secondary Research
Secondary research encompassed Japan Ministry of Economy Trade and Industry (METI) chemical industry statistics, Japan Adhesive Industry Association (JAIA) market data, company annual reports, JIS adhesive standard documentation, patent analysis databases, industry trade publications, and sustainability reporting frameworks. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using an end-use sector demand model: Japan industrial production output by sector multiplied by adhesive and sealant consumption intensity coefficients, creating total market revenue by segment aggregation. Regulatory compliance transition timelines and EV production ramp multipliers applied across relevant segments.
Japan Adhesives And Sealants Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Adhesive Types Covered | Acrylic, PVA, Polyurethanes, Styrenic Block Copolymers, Epoxy, EVA, Others |
| Sealant Types Covered | Acrylic, Silicone, Polyurethane, Butyl, Others |
| Technologies Covered | Water-Based, Solvent-Based, Hot Melt, Reactive, Others |
| Applications Covered | Paperboard and Packaging, Building and Construction, Transportation, Leather and Footwear, Furniture, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Henkel AG & Co. KGaA, HB Fuller Company, Konishi Co., Ltd., Toagosei Co., Ltd., 3M, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan adhesives and sealants market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Japan adhesives and sealants market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan adhesives and sealants industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Adhesives and Sealants Market Report
Japan adhesives and sealants market size is estimated at USD 4.45 Billion in 2026, driven by automotive EV transition, electronics manufacturing demand, construction sector renewal, and eco-friendly formulation adoption across Japan's advanced industrial manufacturing sectors.
Japan adhesives and sealants market grows at 4.09% CAGR during 2026-2034, reaching USD 6.13 Billion by 2034. Growth is sustained by EV adhesive demand, semiconductor manufacturing expansion, infrastructure renewal investment, and waterborne adhesive technology adoption.
Acrylic leads at 23.0% through versatility across substrates, UV stability, and reformulation flexibility for water-based VOC-compliant systems serving automotive, electronics, packaging, and construction applications across Japan's manufacturing sectors.
Silicone leads at 38.0% through superior thermal stability, UV resistance, and flexibility across temperature cycling environments serving electronics encapsulation, automotive glazing, and architectural construction sealing requiring long-term weatherproofing performance.
Kanto Region leads at 34.0% through Tokyo-Yokohama industrial concentration, Japan's highest electronics and automotive Tier-1 supplier density, and major construction activity requiring precision adhesive and sealant product applications.
Leading companies include Henkel AG & Co. KGaA, HB Fuller Company, Konishi Co., Ltd., Toagosei Co., Ltd., 3M, and others.
Japan adhesives and sealants market is projected to reach approximately USD 5.22 Billion by 2030, with EV battery assembly adhesive growth, semiconductor manufacturing expansion, and construction sealant demand from Japan's infrastructure renewal programs driving above-average segment growth rates.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade