Japan Biochar Market Size, Share, Trends and Forecast by Feedstock Type, Technology Type, Product Form, Application, and Region, 2026-2034
Japan Biochar Market Size, Share, Trends & Forecast (2026-2034)
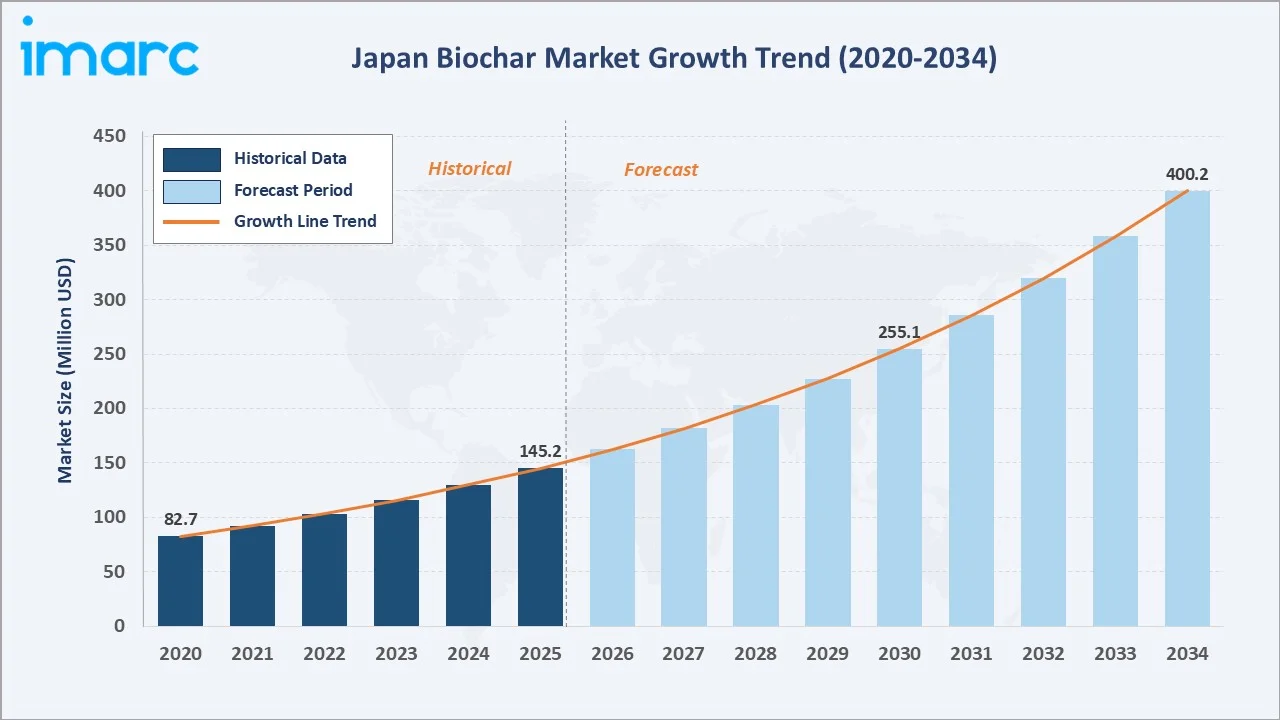
The Japan biochar market was valued at USD 145.2 Million in 2025 and is projected to reach USD 400.2 Million by 2034, exhibiting a CAGR of 11.92% during 2026-2034. The market is driven by growing demand for sustainable soil management, carbon sequestration, and agricultural waste utilization.
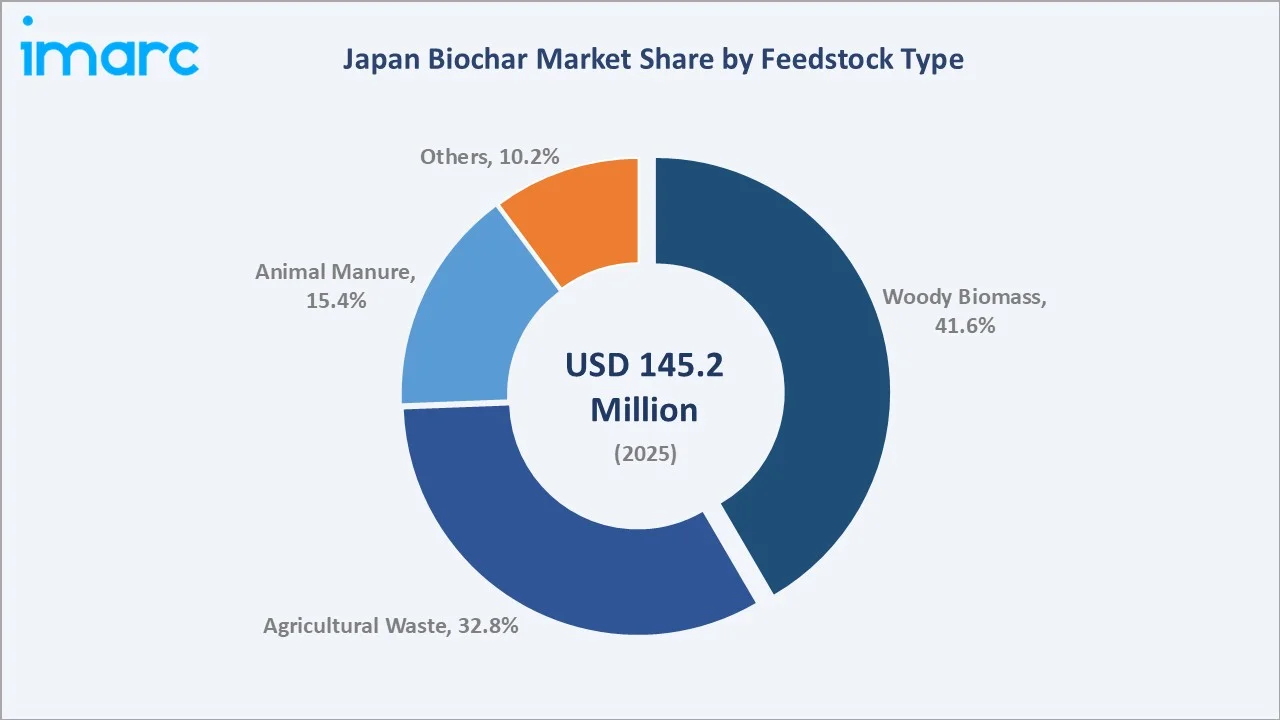
Woody biomass leads the feedstock type segment at 41.6%, slow pyrolysis commands 38.7% of the technology type segment, and Kanto Region accounts for 30.6% regional share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 145.2 Million |
|
Forecast Market Size (2034) |
USD 400.2 Million |
|
CAGR (2026-2034) |
11.92% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Kanto Region (30.6%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (17.8%, 2025) |
|
Leading Feedstock Type |
Woody Biomass (41.6%, 2025) |
|
Leading Technology Type |
Slow Pyrolysis (38.7%, 2025) |
The Japan biochar market expanded from USD 82.7 Million in 2020 to USD 145.2 Million in 2025, supported by growing awareness of soil carbon sequestration, rising demand for sustainable agricultural amendments, and expanding government policy support. Anchored at USD 255.1 Million in 2030, the forecast to USD 400.2 Million by 2034 is underpinned by accelerating adoption in precision agriculture, increasing carbon credit monetization, and maturing pyrolysis and gasification technology ecosystems.
To get more information on this market, Request Sample
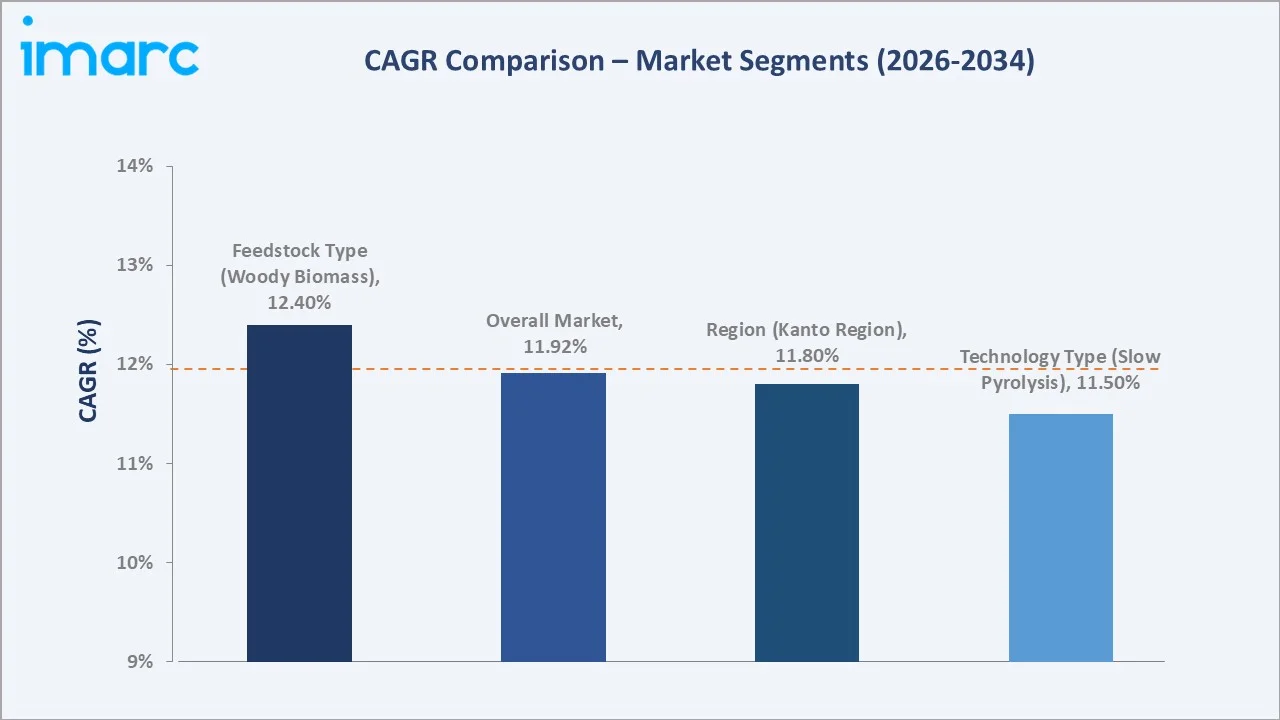
CAGR trajectories across feedstock type and technology type sub-segments, together with regional patterns, indicate that agricultural waste and fast pyrolysis are expanding faster than the overall 11.92% market CAGR, driven by rising crop residue utilization programs and growing investment in advanced conversion technologies.
Executive Summary
The Japan biochar market is on a sustained growth trajectory, rising from USD 82.7 Million in 2020 to USD 400.2 Million by 2034. The industry has evolved from a niche soil amendment application to a broadly integrated component of Japan's sustainable agriculture and carbon management ecosystems.
Woody biomass dominates the feedstock type segment at 41.6% in 2025, supported by abundant forest residue supply and strong alignment with national biomass energy policies. Slow pyrolysis leads the technology type segment at 38.7%, reflecting its cost efficiency and proven track record in rural agricultural applications. Kanto Region commands 30.6% of regional share, anchored by proximity to major agricultural markets and strong prefectural-level biochar promotion programs.
Key Market Insights
|
Insight |
Data |
|
Leading Feedstock Type |
Woody Biomass – 41.6% share (2025) |
|
Second Largest Feedstock Type |
Agricultural Waste – 32.8% share (2025) |
|
Leading Technology Type |
Slow Pyrolysis – 38.7% share (2025) |
|
Second Largest Technology Type |
Fast Pyrolysis – 22.6% share (2025) |
|
Leading Region |
Kanto Region – 30.6% share (2025) |
|
Second Largest Region |
Kansai/Kinki Region – 17.8% share (2025) |
|
Top Companies |
Osaka Gas Co., Ltd., Mitsui & Co., Ltd., Sumitomo Corporation |
Key Analytical Observations Expanding On the Data Above:
- Woody biomass dominance at 41.6% is supported by the widespread availability of forestry residues, sawmill by-products, and lumber waste streams that provide reliable, high-carbon feedstock for slow and fast pyrolysis operations across rural Japan.
- Agricultural waste at 32.8% reflects growing utilization of rice husks, straw, and crop residues as cost-effective biochar feedstocks, driven by Japan's active crop residue reduction policies and expanding biochar-composting integration programs.
- Slow pyrolysis leadership at 38.7% is driven by its energy efficiency, lower capital requirements, and ability to produce high-quality biochar with stable carbon content, making it the preferred technology for agricultural and forestry biochar producers across rural regions.
- Fast pyrolysis at 22.6% is expanding rapidly as industrial-scale biochar producers invest in higher-throughput conversion systems that co-produce bio-oil and syngas alongside biochar, creating additional revenue diversification opportunities.
- Kanto Region at 30.6% leads regional share, anchored by the region's large agricultural land base, dense network of biochar distribution cooperatives, and active prefectural-level carbon sequestration funding programs centered in Ibaraki and Tochigi prefectures.
Japan Biochar Market Overview
Biochar is a carbon-rich solid material produced through the thermochemical conversion of organic biomass under limited or zero oxygen conditions, primarily through pyrolysis, gasification, or hydrothermal carbonization. When applied to soil, biochar improves water retention, nutrient cycling, and microbial activity while sequestering carbon for centuries, offering dual benefits for agricultural productivity and climate mitigation.
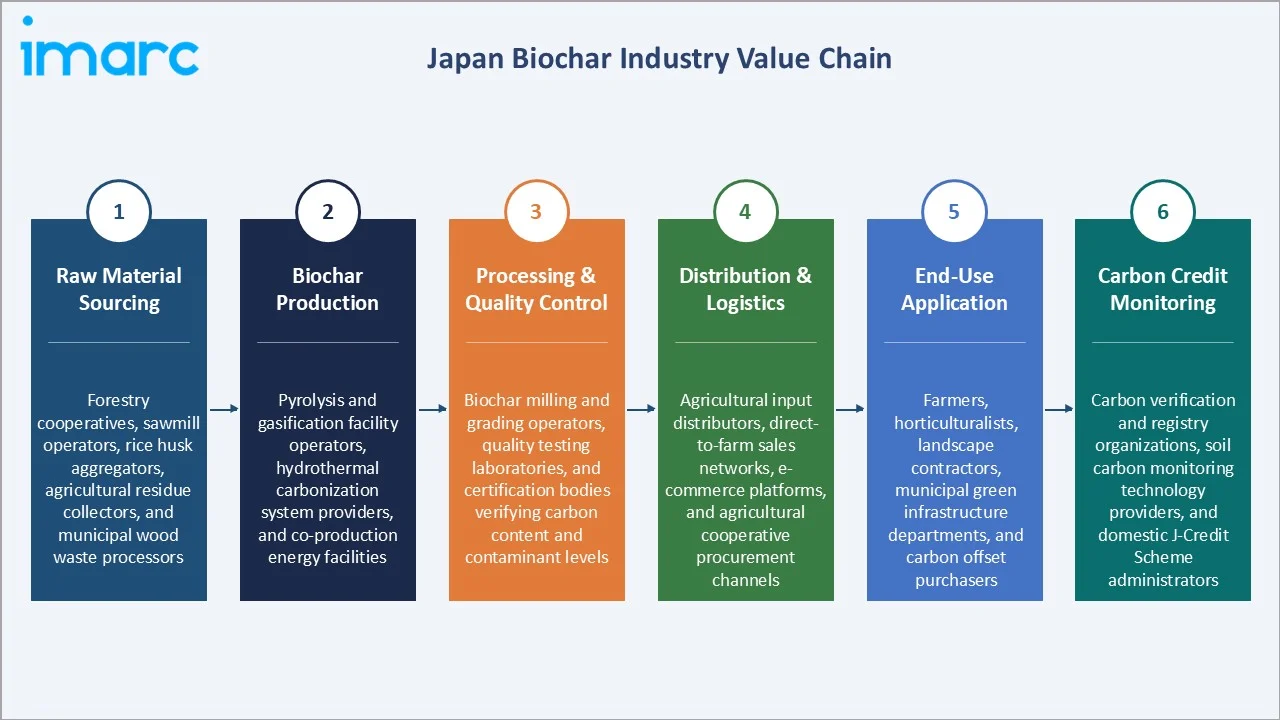
The Japanese biochar ecosystem integrates raw material suppliers including forestry cooperatives, agricultural residue aggregators, and wood processing companies; production facilities utilizing slow pyrolysis, fast pyrolysis, and gasification technologies; distribution networks spanning agricultural cooperatives and direct sales channels; and end users encompassing farmers, horticulturalists, carbon credit market participants, and urban green infrastructure developers. Government agencies, research universities, and carbon verification bodies play enabling roles across the value chain.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
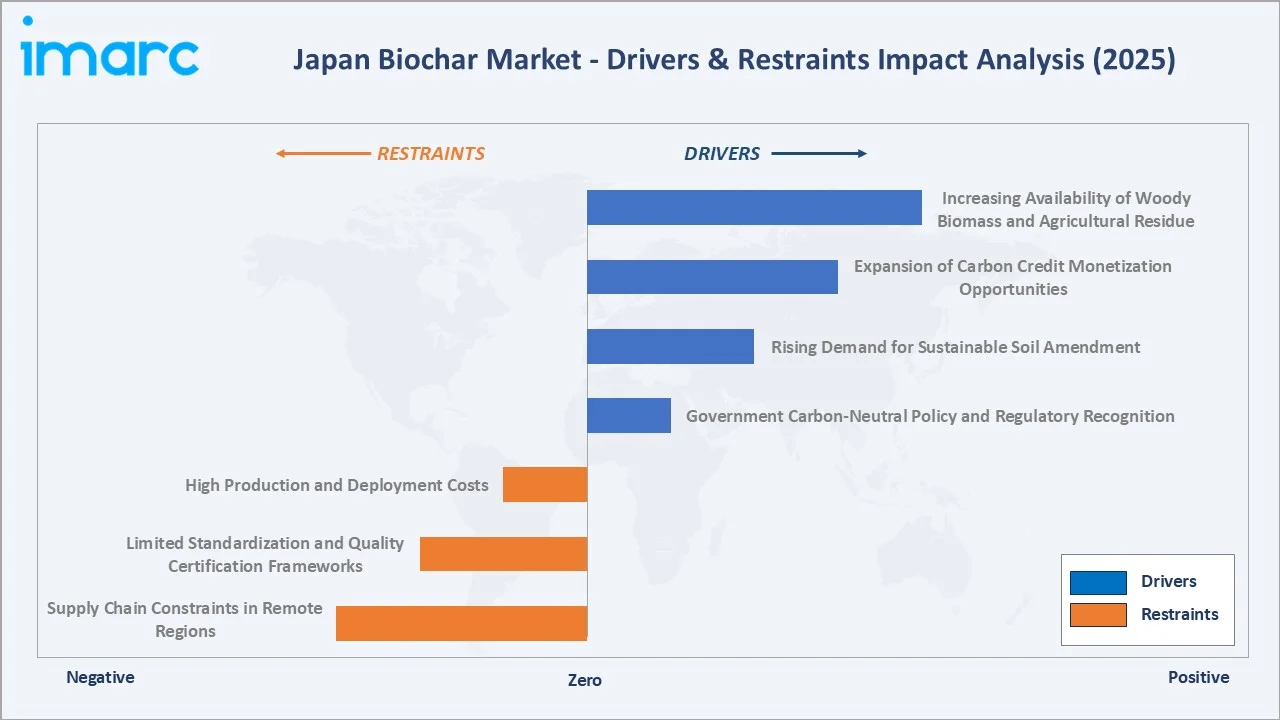
- Government Carbon-Neutral Policy and Regulatory Recognition: Japan's 2050 carbon-neutral pledge has positioned biochar as a formally recognized soil carbon sequestration method, encouraging investment across production, application, and monitoring segments. Policy-driven incentives for biochar adoption in rice cultivation and vegetable farming are accelerating commercial uptake.
- Rising Demand for Sustainable Soil Amendment: Japanese farmers and agricultural cooperatives are increasingly adopting biochar as a complementary soil conditioner alongside conventional fertilizers, driven by documented improvements in crop yield, soil water retention, and reduced fertilizer leaching.
- Expansion of Carbon Credit Monetization Opportunities: Japan's growing carbon credit ecosystem is creating additional revenue opportunities for biochar producers and agricultural users by enabling verified carbon removal from biochar applications to generate tradable environmental credits. This improves the economic viability of biochar projects and encourages investment in scalable production and distribution infrastructure.
- Increasing Availability of Woody Biomass and Agricultural Residue: Japan's forestry activities, agricultural operations, and biomass utilization initiatives provide a growing supply of woody residues, rice husks, and other organic feedstocks suitable for biochar production. Converting these residues into biochar supports resource circularity while creating additional value from locally available biomass.
Market Restraints
- High Production and Deployment Costs: Biochar production remains capital-intensive relative to conventional soil amendments, with pyrolysis equipment, biomass logistics, and quality certification costs limiting adoption among smaller-scale farmers and rural cooperatives in regions outside major agricultural clusters.
- Limited Standardization and Quality Certification Frameworks: Limited standardization across biochar production, feedstock selection, quality assessment, and certification creates uncertainty regarding product performance and safety. Variations in biochar characteristics can make it difficult for farmers and agricultural stakeholders to compare products, assess their suitability for specific applications, and build confidence in long-term use.
- Supply Chain Constraints in Remote Regions: Biomass feedstock collection and biochar distribution logistics remain underdeveloped in remote rural regions, increasing transportation costs and reducing the economic viability of biochar deployment in lower-density agricultural areas outside major regional hubs.
Market Opportunities
- Integration with Carbon Credit and Environmental Markets: The formalization of biochar as an eligible carbon dioxide removal method under Japan's domestic carbon credit frameworks is creating new revenue streams for producers and incentivizing large-scale investment from energy companies and trading houses seeking carbon offset portfolios.
- Precision Agriculture and Smart Biochar Application Systems: Growing adoption of precision agriculture tools, including soil sensors, GIS mapping, and variable-rate application equipment, is enabling more targeted and effective biochar deployment, improving return on investment for farmers and expanding the addressable market.
Market Challenges
- Knowledge Gaps and Farmer Education Barriers: Limited awareness of biochar's long-term agronomic benefits among traditional farming communities continues to slow adoption outside early-adopter agricultural networks.
- Long Payback Periods for Agricultural Adopters: Biochar's benefits in soil health and crop yield improvement typically manifest over multiple growing seasons, making it difficult for farmers with limited capital to justify the upfront investment relative to immediately effective conventional soil amendments.
Emerging Market Trends
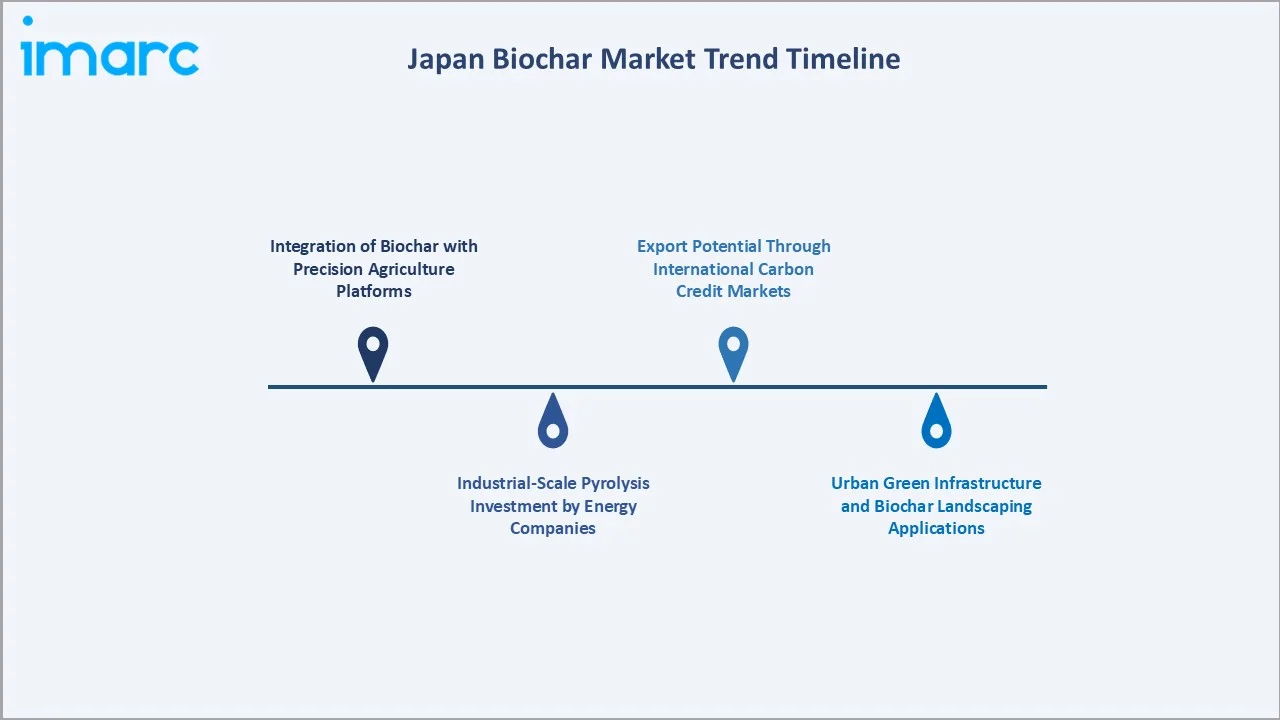
1. Integration of Biochar with Precision Agriculture Platforms
Japanese agritech companies and agricultural cooperatives are integrating biochar into precision farming workflows, combining soil health data from IoT sensors with targeted biochar application recommendations. This convergence is improving application efficiency and providing farmers with measurable return-on-investment data across growing cycles.
2. Industrial-Scale Pyrolysis Investment by Energy Companies
Major Japanese energy companies are investing in large-scale biochar production facilities that co-produce bio-oil and syngas alongside biochar, improving overall conversion economics and supporting the transition toward circular biomass utilization models.
3. Urban Green Infrastructure and Biochar Landscaping Applications
Municipal governments in Tokyo, Osaka, and Nagoya are incorporating biochar into urban tree planting initiatives, stormwater management systems, and green rooftop programs, expanding the addressable market beyond traditional agricultural applications and creating new demand channels for specialty biochar products.
4. Export Potential Through International Carbon Credit Markets
Japanese biochar producers are exploring cross-border carbon credit export opportunities through voluntary carbon markets and emerging bilateral carbon trading frameworks with Southeast Asian nations, diversifying revenue streams and incentivizing production scale-up beyond domestic demand.
Industry Value Chain Analysis
The Japan biochar value chain spans six stages, from raw material sourcing and biomass aggregation through biochar production, processing, distribution, end-use application, and carbon credit monitoring. Production, quality control, and agronomic integration capture the highest value-add, while carbon verification and monitoring are emerging as critical differentiators for producers targeting premium carbon credit markets.
|
Stage |
Key Players / Examples |
|
Raw Material Sourcing |
Forestry cooperatives, sawmill operators, rice husk aggregators, agricultural residue collectors, and municipal wood waste processors |
|
Biochar Production |
Pyrolysis and gasification facility operators, hydrothermal carbonization system providers, and co-production energy facilities |
|
Processing & Quality Control |
Biochar milling and grading operators, quality testing laboratories, and certification bodies verifying carbon content and contaminant levels |
|
Distribution & Logistics |
Agricultural input distributors, direct-to-farm sales networks, e-commerce platforms, and agricultural cooperative procurement channels |
|
End-Use Application |
Farmers, horticulturalists, landscape contractors, municipal green infrastructure departments, and carbon offset purchasers |
|
Carbon Credit Monitoring |
Carbon verification and registry organizations, soil carbon monitoring technology providers, and domestic J-Credit Scheme administrators |
Vertically integrated producers, particularly those combining biomass sourcing, biochar production, and carbon credit monetization within a single operating model, are positioned to capture greater value than producers reliant on third-party distribution and external certification bodies.
Technology Landscape in the Japan Biochar Industry
Slow Pyrolysis Systems
Slow pyrolysis remains the dominant technology type, operating at lower temperatures over extended residence times to produce high-carbon-content biochar with stable aromatic structures suited for long-term soil carbon sequestration. The technology's relatively lower capital cost and established operational expertise make it the preferred choice for agricultural-scale biochar production across Japan's rural regions.
Fast Pyrolysis and Bio-Oil Co-Production
Fast pyrolysis systems operating at higher temperatures with shorter residence times are gaining adoption among industrial-scale producers seeking to co-produce bio-oil and syngas alongside biochar. This multi-product approach improves overall conversion economics and is attracting investment from energy companies seeking to diversify their biomass utilization models.
Hydrothermal Carbonization
Hydrothermal carbonization processes wet biomass feedstocks including food waste, sewage sludge, and aquatic biomass under pressurized water conditions, producing a hydrochar product suited for specific soil and industrial applications. The technology is expanding as Japan increases its focus on wet organic waste valorization and circular economy integration.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Feedstock Type |
Woody Biomass |
41.6% |
2025 |
|
Technology Type |
Slow Pyrolysis |
38.7% |
2025 |
|
Product Form |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
30.6% |
2025 |

By Feedstock Type
Woody biomass commands a 41.6% majority share in 2025, driven by abundant forestry residue supply from Japan's extensive timber sector, high carbon content of wood-derived feedstocks, and strong alignment with existing biomass energy supply chains that provide consistent raw material access for pyrolysis facility operators.
To access detailed market analysis, Request Sample
Agricultural waste at 32.8% in 2025 includes rice husks, straw, bamboo, and crop residues, benefiting from Japan's agricultural residue management policies that incentivize thermal conversion over open-field burning.
By Technology Type
Slow pyrolysis leads with 38.7% share in 2025, reflecting the technology's cost efficiency, established operational track record, and ability to produce high-quality, stable biochar at scales suited to Japan's predominantly small-to-medium agricultural operations.
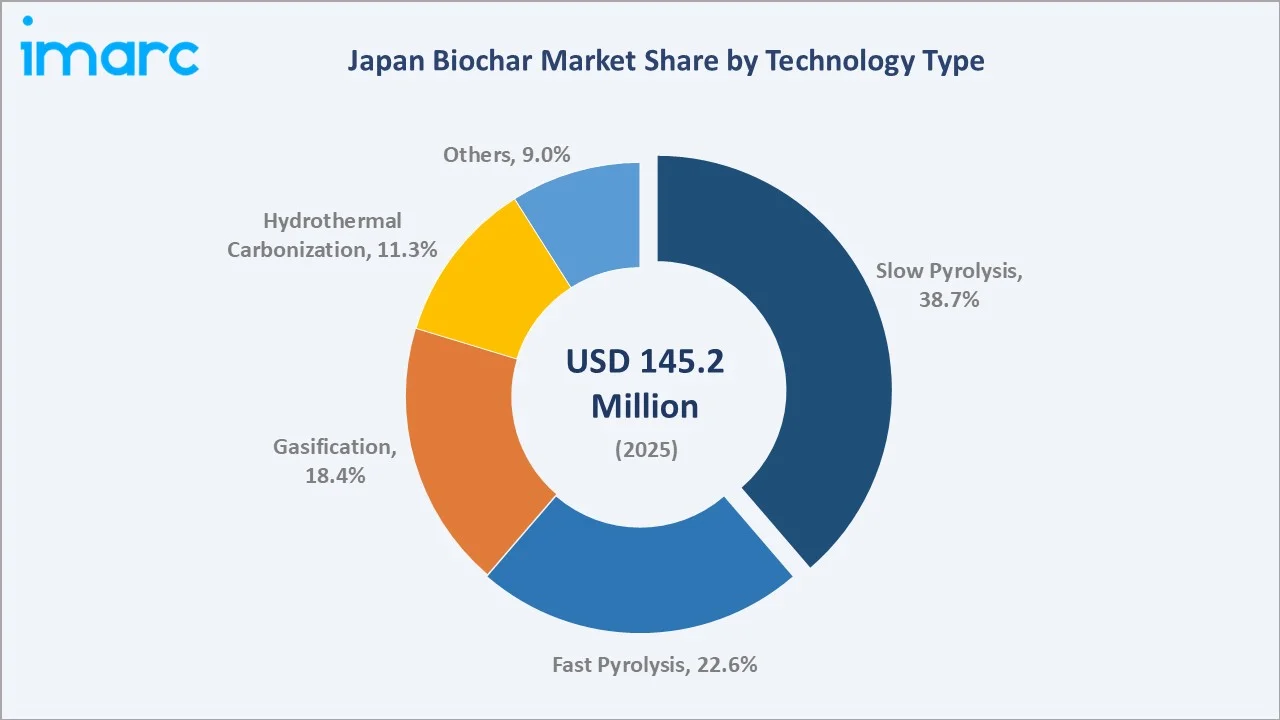
Fast pyrolysis at 22.6% in 2025 is the fastest-growing technology segment, driven by growing industrial investment in multi-product conversion systems that generate bio-oil and syngas co-products alongside biochar.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
30.6% |
Large agricultural land base, active prefectural biochar promotion programs, strong carbon credit market participation, and proximity to major urban distribution networks |
|
Kansai/Kinki Region |
17.8% |
Growing industrial biochar production investment, strong university research partnerships, and expanding organic farming sector adoption |
|
Central/Chubu Region |
15.4% |
Active forestry sector providing abundant woody biomass feedstock, growing precision agriculture integration, and expanding biochar composting programs |
|
Kyushu-Okinawa Region |
11.2% |
Livestock sector driving animal manure biochar co-composting adoption, subtropical crop residue availability, and active regional sustainability programs |
|
Tohoku Region |
9.1% |
Post-disaster agricultural recovery programs incorporating biochar for soil restoration, rice cultivation integration, and expanding prefectural funding support |
|
Chugoku Region |
6.8% |
Forestry residue utilization programs, growing rural biochar cooperatives, and expanding regional carbon credit participation |
|
Hokkaido Region |
5.2% |
Large-scale agricultural operations providing high-volume feedstock, expanding dairy sector biochar co-composting, and growing carbon sequestration awareness |
|
Shikoku Region |
3.9% |
Small-scale specialty crop farming adoption, expanding sustainable agriculture certification programs, and growing local biochar production cooperatives |
Kanto Region at 30.6% in 2025 leads the regional landscape, anchored by its large agricultural land area, active prefectural carbon sequestration incentive programs in Ibaraki, Tochigi, and Gunma prefectures, and strong access to biochar distribution networks serving the greater Tokyo metropolitan area.
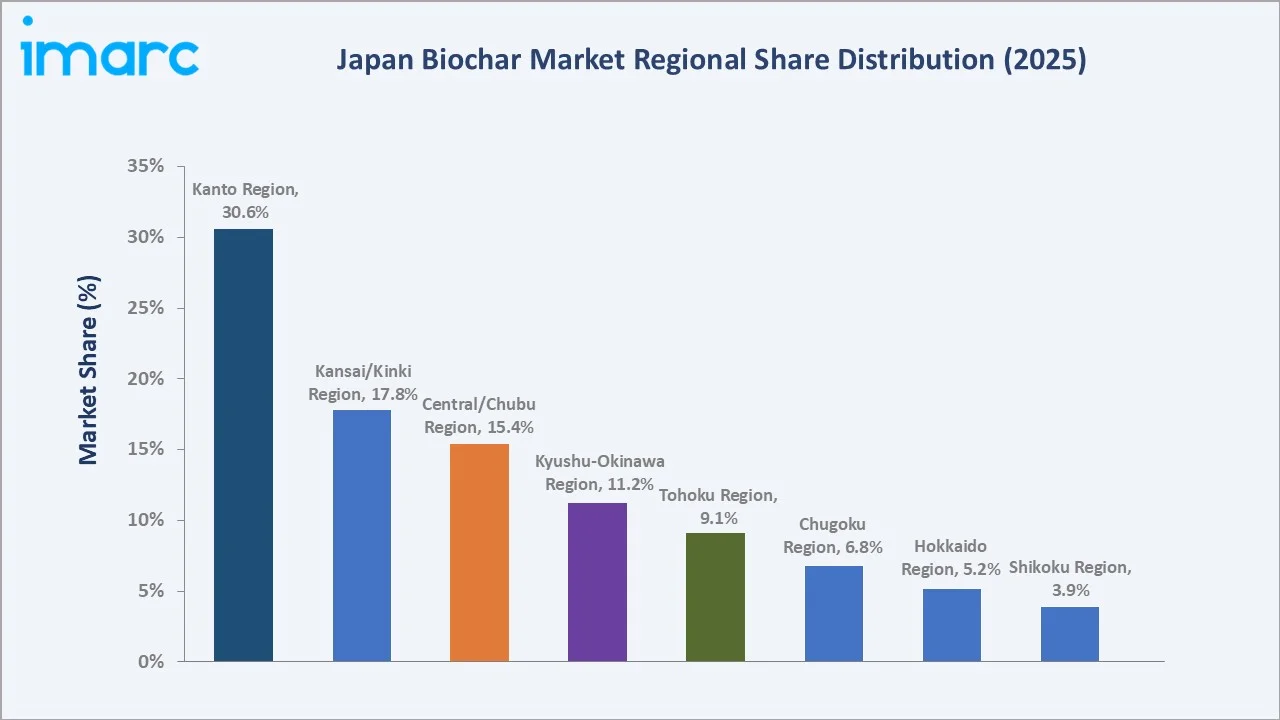
Kansai/Kinki Region at 17.8% represents the second-largest market, supported by active university research programs at Kyoto University and Osaka University, growing organic and sustainable farming sector adoption, and increasing industrial biochar production investment by major energy companies headquartered in the region.
Competitive Landscape
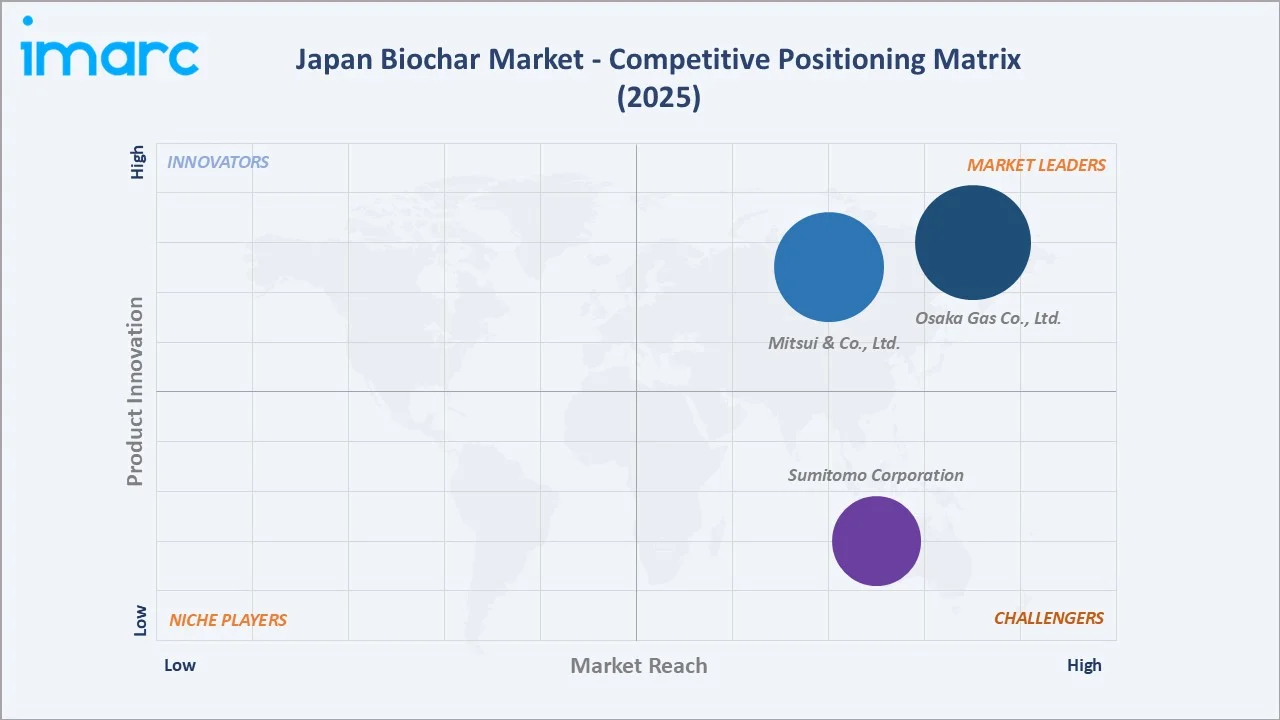
The Japan biochar market is moderately fragmented, with established energy companies, trading houses, and specialty biochar producers competing alongside a growing number of regional and cooperative-scale producers. Technology depth, feedstock sourcing capabilities, carbon credit certification expertise, and established agricultural distribution networks form the key competitive differentiators across the industry.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Osaka Gas Co., Ltd. |
Osaka Gas |
Leader |
Expanding biochar co-production from biomass energy operations and growing carbon credit market participation |
|
Mitsui & Co., Ltd. |
Mitsui |
Leader |
Building integrated biochar supply chains and expanding carbon offset portfolio through domestic and international partnerships |
|
Sumitomo Corporation |
Sumitomo |
Challenger |
Expanding biochar trading and carbon credit monetization capabilities through sustainable agriculture and forestry sector partnerships |
Key players include Osaka Gas Co., Ltd., Mitsui & Co., Ltd., and Sumitomo Corporation, among others.
Key Company Profiles
Osaka Gas Co., Ltd.
Osaka Gas Co., Ltd. is a Japanese energy company headquartered in Osaka, operating in city gas supply, power generation, and energy services. The company is engaged in biomass energy operations and carbon neutrality initiatives across the domestic and international market.
- Product Portfolio: City gas supply, biomass energy co-products, and carbon credit evaluation services for biochar and other nature-based credit projects.
- Recent Developments: The company continues to strengthen its renewable energy and carbon neutrality initiatives, including the development of biomass-related projects and participation in emerging carbon management opportunities.
- Strategic Focus: Expanding biochar co-production from biomass energy operations and growing carbon credit market participation through domestic partnerships.
Mitsui & Co., Ltd.
Mitsui & Co., Ltd. is a global general trading company headquartered in Tokyo, with diversified business operations spanning energy, chemicals, food, infrastructure, and carbon solutions. The company is actively engaged in building carbon credit supply chains and supporting Japan's decarbonization goals.
- Product Portfolio: Carbon credit origination and trading, forest J-credit generation, carbon offset marketplace services, and biomass-related energy solutions across domestic and international markets.
- Recent Developments: Mitsui & Co., Ltd. has been actively expanding its carbon credit portfolio, including agreements to supply forest-based J-credits to major Japanese companies on a multi-year basis.
- Strategic Focus: Building integrated biochar supply chains and expanding carbon offset portfolio through domestic and international partnerships.
Sumitomo Corporation
Sumitomo Corporation is one of Japan's largest general trading companies headquartered in Tokyo, with global business activities spanning metals, infrastructure, media, chemicals, and energy. The company has established a significant presence in the carbon dioxide removal market as both a buyer and seller of CDR credits.
- Product Portfolio: Carbon dioxide removal credits, biomass carbon removal and storage solutions, and CDR project development and trading services across global and Japanese markets.
- Recent Developments: Sumitomo Corporation continues to expand its carbon removal activities through investments, project development, credit procurement, and partnerships across emerging carbon removal pathways.
- Strategic Focus: Expanding biochar trading and carbon credit monetization capabilities through sustainable agriculture and forestry sector partnerships.
Market Concentration Analysis
The Japan biochar market is moderately fragmented, with large energy companies and trading houses accounting for a significant portion of production capacity while a long tail of regional cooperatives, agricultural biochar producers, and specialty technology firms capture the remainder.
Barriers to entry include capital requirements for pyrolysis and gasification equipment, expertise in carbon certification and credit registration, and established biomass feedstock procurement relationships. These factors favor larger energy companies and trading houses with existing biomass infrastructure and financial resources.
Consolidation is gradually increasing as larger players acquire or partner with regional biochar producers, specialty technology firms, and carbon credit aggregators to broaden their capabilities. Strategic partnerships between energy companies, agricultural cooperatives, and carbon market participants are further shaping competitive positioning.
Investment & Growth Opportunities
Fastest-Growing Segments
Agricultural waste is expanding fastest among feedstock type categories, driven by rising crop residue utilization incentives and growing biochar-composting integration programs across Japan's rice and vegetable farming regions. Fast pyrolysis is the fastest-growing technology type segment, supported by growing industrial investment in multi-product conversion systems that generate bio-oil and syngas alongside biochar.
Emerging Markets
Kansai/Kinki Region and Central/Chubu Region are the fastest-growing regional markets, supported by expanding university research partnerships, growing industrial biochar production investment, and active prefectural-level adoption programs.
Venture & Investment Trends
Investment activity is concentrated in large-scale pyrolysis infrastructure, carbon credit certification and registry services, and biochar-precision agriculture integration platforms. Capital is also flowing into hydrothermal carbonization technology development and into international carbon market frameworks that could enable Japanese biochar producers to export carbon removal credits across Asia and Europe.
Future Market Outlook (2026-2034)
The Japan biochar market is forecast to expand from USD 145.2 Million in 2025 to USD 400.2 Million by 2034 at a CAGR of 11.92%, adding approximately USD 255.0 Million in incremental market value over the forecast period.
Four forces will shape the market through 2034: continued government policy support under Japan's carbon-neutral frameworks; growing industrial investment in large-scale pyrolysis and gasification infrastructure; deeper integration of biochar into precision agriculture and carbon monitoring platforms; and expanding international carbon credit monetization opportunities linking Japanese producers to global voluntary carbon markets.
By 2034, the Japan biochar market is expected to be characterized by greater industrial-scale production, more formalized quality and certification standards, and a broader application base spanning traditional agriculture, urban green infrastructure, and industrial carbon removal.
Research Methodology
Primary Research
Primary research included structured interviews with biochar producers, agricultural cooperative managers, carbon credit market specialists, technology vendors, and regulatory officials in Japan, validating market sizing, segment mix, regional demand patterns, and competitive positioning across key market participants.
Secondary Research
Secondary sources included Japan's Ministry of Agriculture, Forestry and Fisheries publications, Ministry of the Environment carbon credit framework documentation, Japan Biochar Association technical reports, annual reports and investor presentations from listed energy companies and trading houses, and academic research from leading Japanese universities.
Forecasting Models
Market forecasts used top-down and bottom-up models combining biochar production capacity data, feedstock availability trends, agricultural adoption rates, carbon credit market growth trajectories, and macroeconomic variables. Scenario analysis addressed regulatory developments, technology cost curves, feedstock supply dynamics, and carbon market price evolution.
Japan Biochar Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Feedstock Types Covered | Woody Biomass, Agricultural Waste, Animal Manure, Others |
| Technology Types Covered | Slow Pyrolysis, Fast Pyrolysis, Gasification, Hydrothermal Carbonization, Others |
| Product Forms Covered | Coarse and Fine Chips, Fine Powder, Pellets, Granules and Prills, Liquid Suspension |
| Applications Covered | Farming, Gardening, Livestock Feed, Soil, Water and Air Treatment, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Osaka Gas Co., Ltd., Mitsui & Co., Ltd., Sumitomo Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan biochar market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan biochar market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan biochar industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Biochar Market Report
The Japan biochar market was valued at USD 145.2 Million in 2025, driven by government carbon-neutral policy support, growing agricultural adoption, and expanding carbon credit market integration across the country.
The market is projected to grow at a CAGR of 11.92% from 2026 to 2034, reaching USD 400.2 Million, supported by policy-driven adoption, industrial-scale production investment, and expanding carbon credit monetization opportunities.
Woody biomass leads the feedstock type segment at 41.6% in 2025, driven by abundant forestry residue availability, high carbon content, and strong alignment with existing biomass supply chains across Japan's timber sector.
Slow pyrolysis dominates the technology type segment at 38.7% in 2025, reflecting its cost efficiency, operational simplicity, and ability to produce high-quality, stable biochar suited for agricultural soil amendment applications.
Kanto Region commands 30.6% share in 2025, led by its large agricultural land base, active prefectural biochar promotion programs, and strong access to carbon credit market networks and agricultural distribution channels.
Leading players include Osaka Gas Co., Ltd., Mitsui & Co., Ltd., and Sumitomo Corporation, among others.
Biochar is primarily applied in agricultural soil amendment to improve water retention, nutrient cycling, and crop yield. Emerging applications include urban green infrastructure, stormwater management, carbon sequestration programs, and industrial carbon removal credit generation.
Key challenges include high production costs relative to conventional soil amendments, limited standardization and quality certification frameworks, supply chain constraints in remote rural regions, and knowledge gaps among traditional farming communities outside major agricultural hubs.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade