
Japan Bioplastics Market Size, Share, Trends and Forecast by Product, Application, Distribution Channel, and Region, 2026-2034
Japan Bioplastics Market Size, Share, Trends & Forecast (2026-2034)
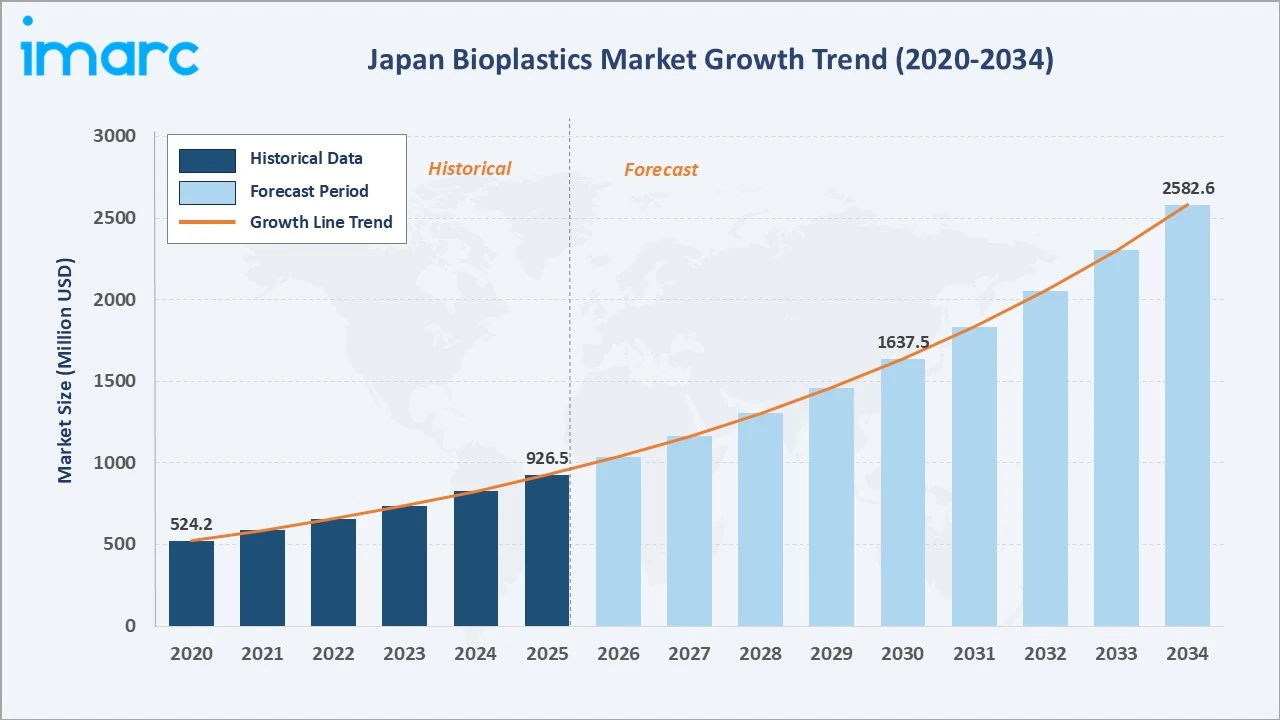
The Japan bioplastics market grew from USD 926.5 Million in 2025 to USD 1,038.2 Million in 2026 and is projected to reach USD 2,582.6 Million by 2034, growing at a CAGR of 12.07% during 2026-2034. The market is driven by rising corporate sustainability commitments and expanding adoption of biodegradable materials across the packaging, agricultural, and industrial sectors.
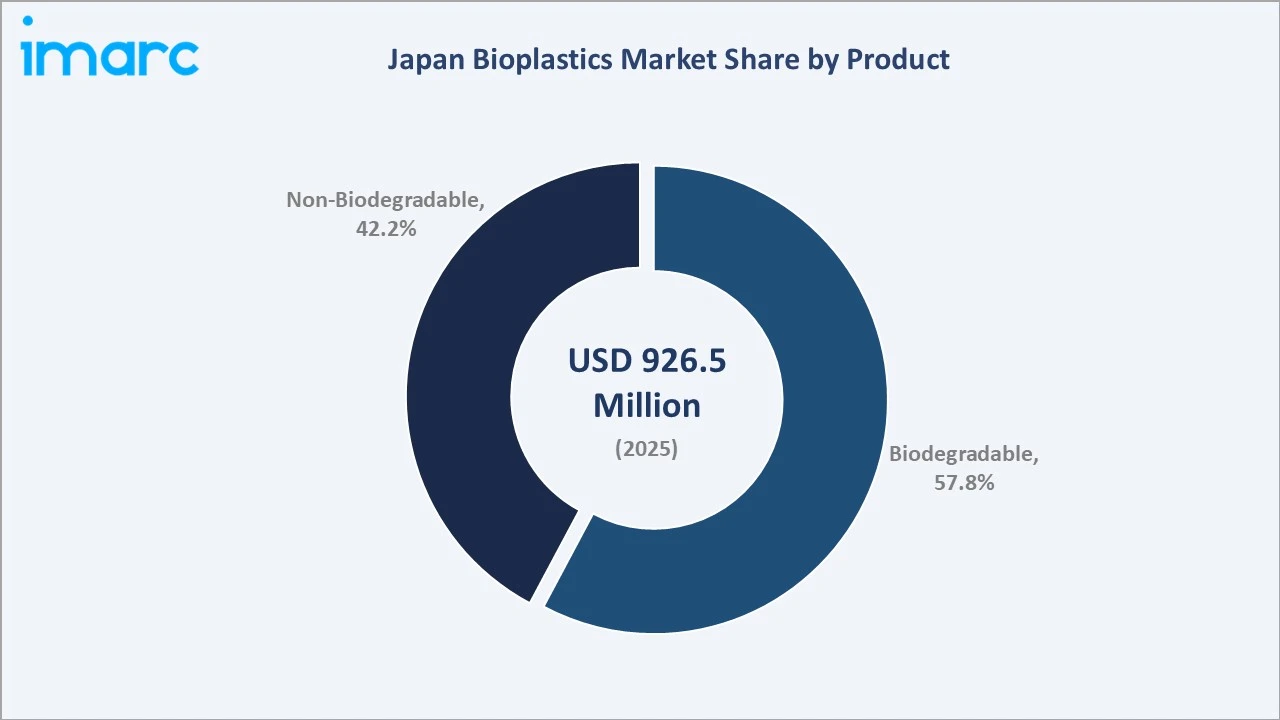
Biodegradable leads the product segment at 57.8%, while flexible packaging dominates application demand at 31.6%. Kanto Region commands the largest regional share at 34.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 926.5 Million |
|
Market Size (2026) |
USD 1,038.2 Million |
|
Forecast Market Size (2034) |
USD 2,582.6 Million |
|
CAGR (2026-2034) |
12.07% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
| Largest Region | Kanto Region (34.8%, 2025) |
| Second Largest Region |
Kansai/Kinki Region (19.7%, 2025) |
| Leading Product |
Biodegradable (57.8%, 2025) |
| Leading Application |
Flexible Packaging (31.6%, 2025) |
The Japan bioplastics market size increased from USD 524.2 Million in 2020 to USD 926.5 Million in 2025 and is estimated to reach USD 1,038.2 Million in 2026. The market is further expected to grow to USD 1,637.5 Million by 2030 and USD 2,582.6 Million by 2034. The market is commercially significant within Asia-Pacific, underpinned by Japan's advanced polymer manufacturing ecosystem, strong regulatory mandates for plastics reduction, and growing end-use demand for sustainable materials across packaging, automotive, agriculture, and consumer goods industries.
To get more information on this market, Request Sample
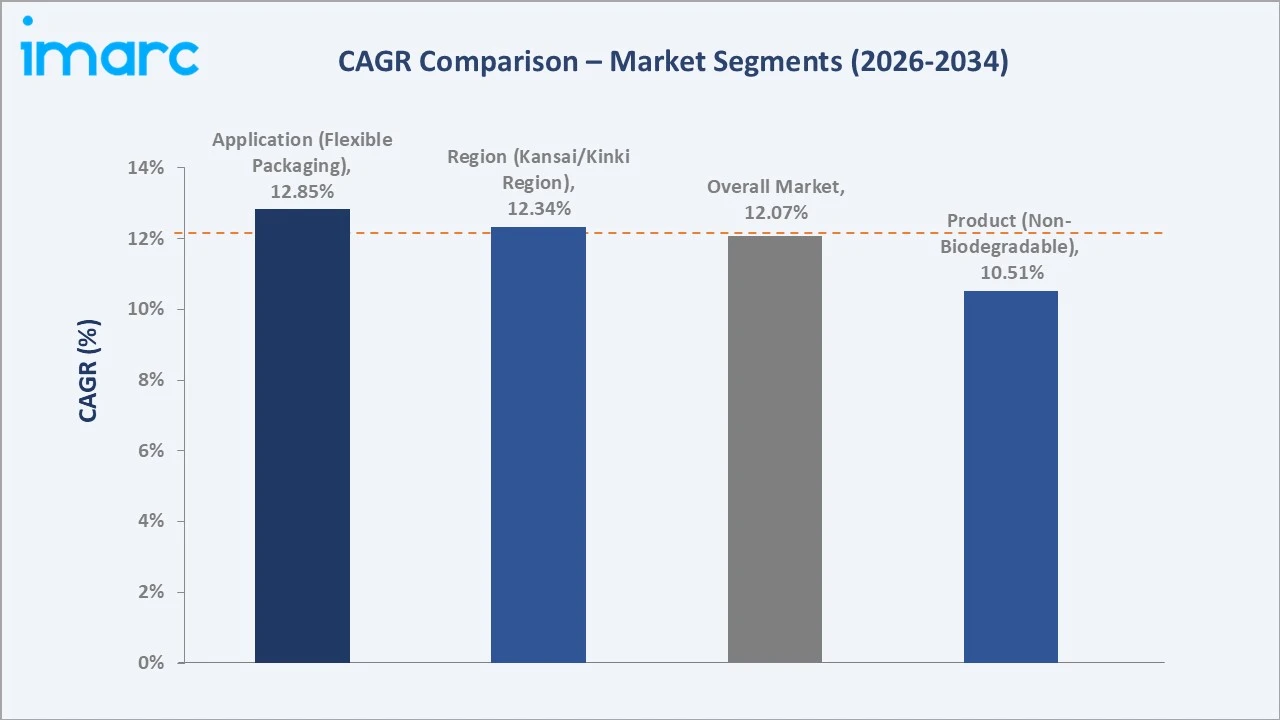
CAGR trajectories across product, application, and regional sub-segments show automotive and transportation and Kyushu-Okinawa Region expanding faster than the overall 12.07% market CAGR, driven by lightweighting demand, government sustainability mandates, and growing industrial investment in bioplastic processing infrastructure.
Executive Summary
The Japan bioplastics market expanded from USD 926.5 Million in 2025 to an estimated USD 1038.2 Million in 2026, positioning it among Asia-Pacific's fastest-growing sustainable materials markets. The market's scale is underpinned by Japan's advanced polymer manufacturing ecosystem, strong regulatory mandates, and rising end-use demand for compostable and bio-based materials across packaging, automotive, and consumer goods sectors.
Biodegradable at 57.8% leads through regulatory mandates, composting infrastructure expansion, and widespread adoption in flexible packaging and agricultural film applications. Flexible packaging at 31.6% reflects Japan's large food processing sector and strong retail and foodservice demand for compostable packaging materials. Kanto Region leads regionally at 34.8%, driven by its concentration of manufacturing facilities, major consumer markets, established packaging industries, and strong demand for sustainable material solutions.
Key Market Insights
|
Insight |
Data |
| Leading Product |
Biodegradable – 57.8% share (2025) |
| Second Largest Product | Non-Biodegradable – 42.2% share (2025) |
| Leading Application | Flexible Packaging – 31.6% share (2025) |
| Second Largest Application |
Rigid Packaging – 21.8% share (2025) |
|
Leading Region |
Kanto Region – 34.8% sharere (2025) |
| Second Largest Region | Kansai/Kinki Region – 19.7% share (2025) |
| Top Companies | Mitsui Chemicals, Inc., Toray Industries, Inc., Kaneka Corporation, Unitika Ltd., NEC Corporation |
Key Analytical Observations Expanding On the Data Above:
- Biodegradable dominance at 57.8% reflects stringent Japanese government mandates targeting single-use plastic reduction, expanding composting infrastructure across urban centers, and increasing adoption in food packaging and consumer goods sectors.
- Non-biodegradable share at 42.2% is supported by demand for durable, high-performance bio-based materials in automotive components, electronics housings, and industrial applications where compostability is less critical than mechanical properties.
- Flexible packaging leadership at 31.6% is driven by Japan's large food processing sector, growing demand from convenience retail and e-commerce for compostable packaging, and brand-owner sustainability commitments across major consumer goods companies.
- Rigid packaging share at 21.8% reflects demand for sustainable containers, trays, and protective packaging across food, beverage, and consumer goods industries.
- Kanto Region at 34.8% indicates its concentration of manufacturing facilities, major consumer markets, established packaging industries, and growing demand for sustainable material solutions.
Japan Bioplastics Market Overview
Bioplastics are polymers derived from biological sources, such as corn starch, sugarcane, cassava, cellulose, and organic plant oils. They encompass both biodegradable variants such as polylactic acid (PLA) and polyhydroxyalkanoates (PHA), and bio-based non-biodegradable variants such as bio-based polyethylene.
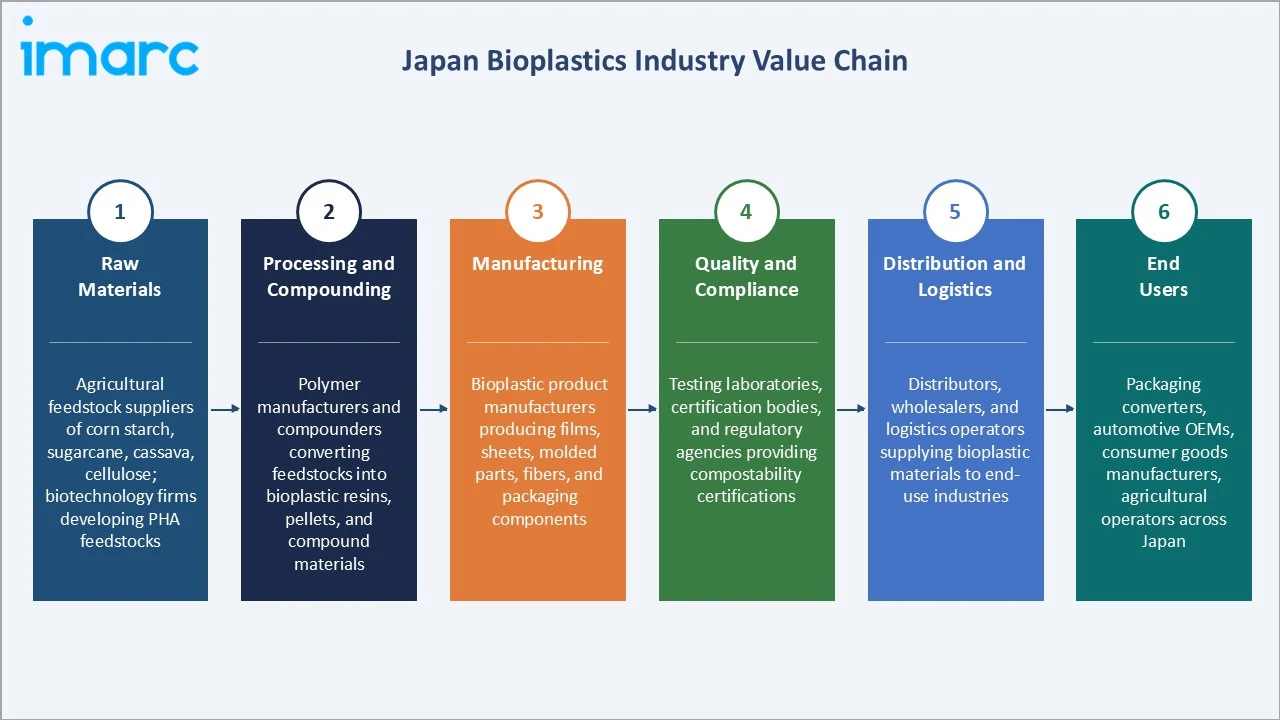
The Japan bioplastics ecosystem integrates agricultural feedstock suppliers, polymer manufacturers and compounders, downstream processors and converters, distribution networks, and end-use industries. Government bodies, research institutions, and certification bodies form the supporting infrastructure governing standards, environmental compliance, and compostability certification.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
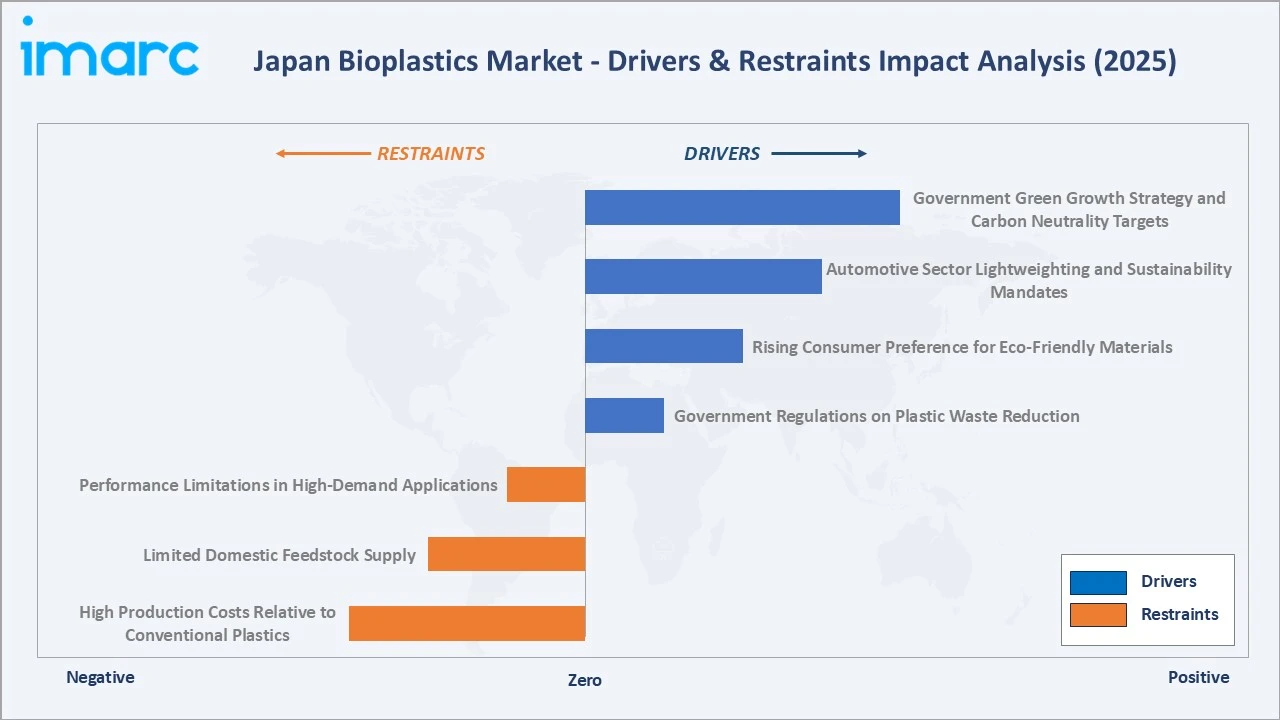
- Government Regulations on Plastic Waste Reduction: Japan's efforts to reduce unnecessary use of disposable plastic items are accelerating the substitution of conventional plastics with bioplastic alternatives across retail, foodservice, and packaging sectors.
- Rising Consumer Preference for Eco-Friendly Materials: Japanese consumers demonstrate strong environmental consciousness, encouraging brand owners and retailers to transition toward compostable and bio-based packaging. Retail-led sustainability commitments from major supermarket chains and convenience store operators are expanding bioplastic adoption across flexible packaging and consumer goods segments.
- Automotive Sector Lightweighting and Sustainability Mandates: Japanese automakers are integrating bio-based plastics into interior components and exterior trim to reduce vehicle weight and meet carbon footprint targets. The automotive sector offers growth opportunities for bioplastics as manufacturers increasingly prioritize lightweight materials and sustainable vehicle production.
- Government Green Growth Strategy and Carbon Neutrality Targets: Japan's Green Growth Strategy and commitment to carbon neutrality by 2050 identify bioplastics as important enabling materials. Public procurement initiatives, research and development subsidies, and industrial policy frameworks are encouraging domestic bioplastic production capacity expansion and technological advancement.
Market Restraints
- High Production Costs Relative to Conventional Plastics: Bioplastics typically carry a significant price premium over petroleum-based equivalents, limiting adoption to applications where sustainability credentials justify the cost differential or where regulatory mandates compel transition.
- Limited Domestic Feedstock Supply: Japan's limited agricultural land constrains domestic production of plant-based feedstocks such as corn starch, sugarcane, and cassava, increasing reliance on imported raw materials and exposing manufacturers to supply chain and pricing volatility.
- Performance Limitations in High-Demand Applications: Certain bioplastic variants exhibit lower mechanical strength, heat resistance, and moisture barrier properties than petroleum-based alternatives, restricting adoption in high-performance applications and requiring ongoing material innovation to close the performance gap.
Market Opportunities
- Scale-Up of PHA Manufacturing for Premium Biodegradable Applications: PHA offer superior biodegradability across marine and soil environments, positioning them as a premium bioplastic for agricultural films, medical devices, and food contact packaging.
- Integration with Agricultural and Composting Value Chains: Japan's growing urban composting infrastructure and expanding agricultural bioplastic film adoption create a circular value chain opportunity, linking bioplastic manufacturers with end-of-life recovery systems and reinforcing the sustainability credentials of biodegradable material adoption.
Market Challenges
- Consumer and Industry Awareness Gaps: Despite strong environmental awareness, confusion between bio-based and biodegradable bioplastics, inconsistent compostability labeling, and limited composting access in certain regions reduce consumer confidence and complicate end-of-life material management.
- Competing Recycling Priorities: Japan's established plastics recycling infrastructure and high recycling rates create competitive pressure against composting-dependent biodegradable bioplastics, requiring clear end-of-life infrastructure alignment and public communication to support effective bioplastic adoption.
Emerging Market Trends
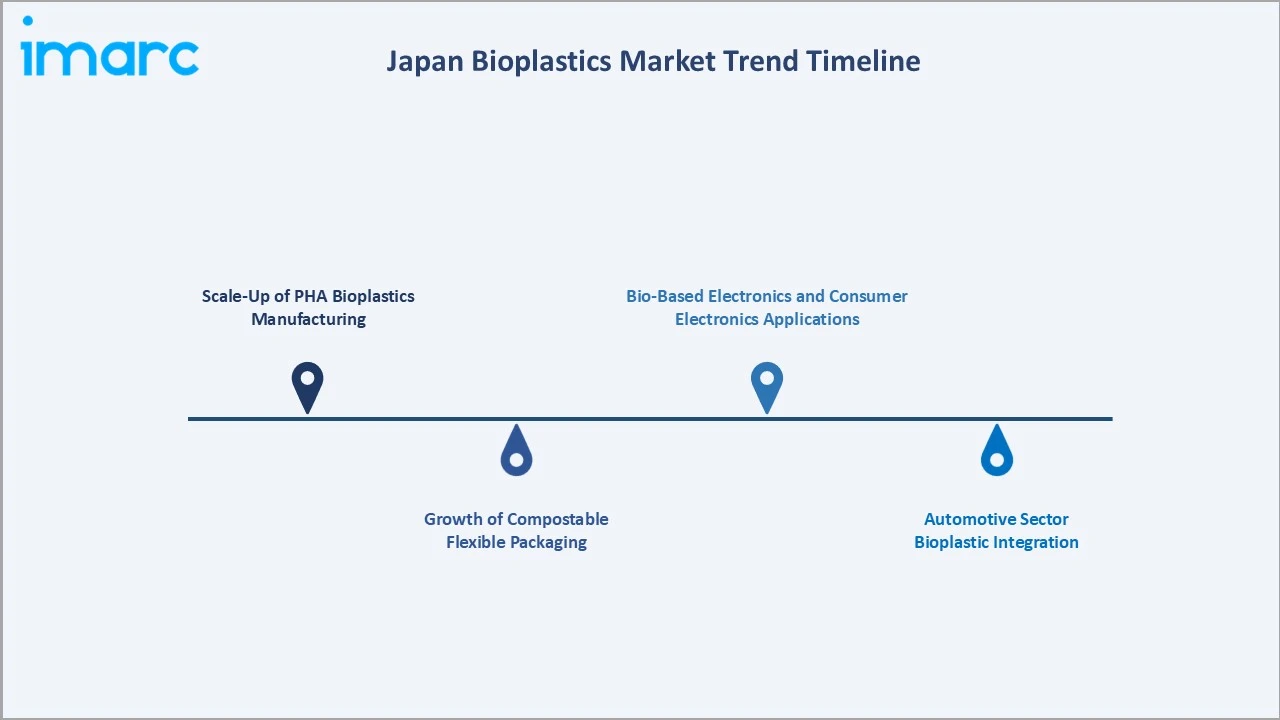
1. Scale-Up of PHA Bioplastics Manufacturing
PHAs are gaining commercial traction in Japan due to their biodegradability in marine and soil environments. Their distinctive environmental properties create opportunities for adoption in agriculture, marine applications, and food-contact materials where conventional biodegradable plastics may face performance limitations. Ongoing research is also improving material performance and expanding potential industrial applications.
2. Growth of Compostable Flexible Packaging
Japanese retailers and foodservice operators are increasingly transitioning to certified compostable flexible packaging, driven by brand sustainability commitments and government plastic reduction targets. Demand for PLA-based and starch-blend compostable films, bags, and wrapping materials is expanding alongside urban composting infrastructure development, creating a reinforcing demand cycle for biodegradable bioplastics.
3. Automotive Sector Bioplastic Integration
Japan's automotive manufacturers are integrating bio-based engineering plastics into interior components, door trims, and instrument panels as part of vehicle carbon footprint reduction programs. Toyota and other domestic original equipment manufacturers are establishing bioplastic content targets for new vehicle platforms, creating a sustained demand trajectory for durable bio-based polymers.
4. Bio-Based Electronics and Consumer Electronics Applications
Bio-based materials in electronics reduce device carbon footprints, align with manufacturer sustainability reporting requirements, and address growing consumer demand for environmentally responsible consumer technology products. Their integration into device housings, internal components, and packaging is creating new opportunities for sustainable material innovation across electronics manufacturing.
Industry Value Chain Analysis
The Japan bioplastics value chain spans six stages, from feedstock sourcing through material recovery and secondary market integration. Processing and compounding stages capture the highest value-add, while certification, composting infrastructure, and end-of-life management systems are increasingly determining competitive positioning in Japan's regulation-driven bioplastics market.
|
Stage |
Key Players / Examples |
| Raw Materials | Agricultural feedstock suppliers of corn starch, sugarcane, cassava, cellulose, and plant oils; biotechnology firms developing PHA feedstocks |
| Processing and Compounding | Polymer manufacturers and compounders converting feedstocks into bioplastic resins, pellets, and compound materials |
| Manufacturing | Bioplastic product manufacturers and converters producing films, sheets, molded parts, fibers, and packaging components |
| Quality and Compliance | Testing laboratories, certification bodies, and regulatory agencies providing compostability and biodegradability certifications |
| Distribution and Logistics | Distributors, wholesalers, and logistics operators supplying bioplastic materials and products to end-use industries |
| End Users | Packaging converters, automotive OEMs, consumer goods manufacturers, agricultural operators, and textile producers across Japan |
Vertically integrated operators controlling feedstock sourcing, compounding, and downstream product manufacturing are positioned to capture greater margin than single-stage participants, while certification and composting infrastructure investment increasingly determines long-term competitive advantage in end-user application markets.
Technology Landscape in the Japan Bioplastics Industry
PLA Technology
PLA remains the most commercially scaled bioplastic in Japan, produced from fermented corn starch or sugarcane. Processing advances are improving heat resistance through stereocomplex PLA blends and nucleating agents, expanding adoption into hot-fill packaging and automotive applications previously limited by thermal constraints.
Cellulose and Plant-Derived Engineering Plastics
Cellulose-based bioplastics and other plant-derived materials are advancing the development of sustainable engineering polymers in Japan. These materials target electronics, automotive, and consumer goods applications where durability, heat resistance, and reliable performance are required alongside sustainability benefits.
Smart Blending and Compatibilization
Advanced blending technologies enable the combination of bioplastics with conventional polymers and other bio-based materials to optimize performance, processability, and cost efficiency. These solutions improve compatibility between different materials and enhance the functional properties of blended bioplastic formulations used in packaging, agricultural films, and other industrial applications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Product | Biodegradable |
57.8% |
2025 |
|
Application |
Flexible Packaging |
31.6% |
2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
|
Region |
Kanto Region |
34.8% |
2025 |

By Product
Biodegradable commands a 57.8% majority share in 2025, driven by Japan's regulatory mandates for single-use plastic reduction, growing composting infrastructure in urban centers, and rising adoption across flexible packaging and agricultural film applications.
To access detailed market analysis, Request Sample
Non-biodegradable represents 42.2% of product share in 2025, supported by demand for durable bio-based engineering materials in automotive, electronics, and industrial applications.
By Application
Flexible packaging leads the application segment at 31.6% in 2025, reflecting Japan's large food processing and convenience retail sectors and the strong regulatory push for compostable packaging. Compostable films, bags, and wrapping materials are the primary product forms driving flexible packaging bioplastic demand.
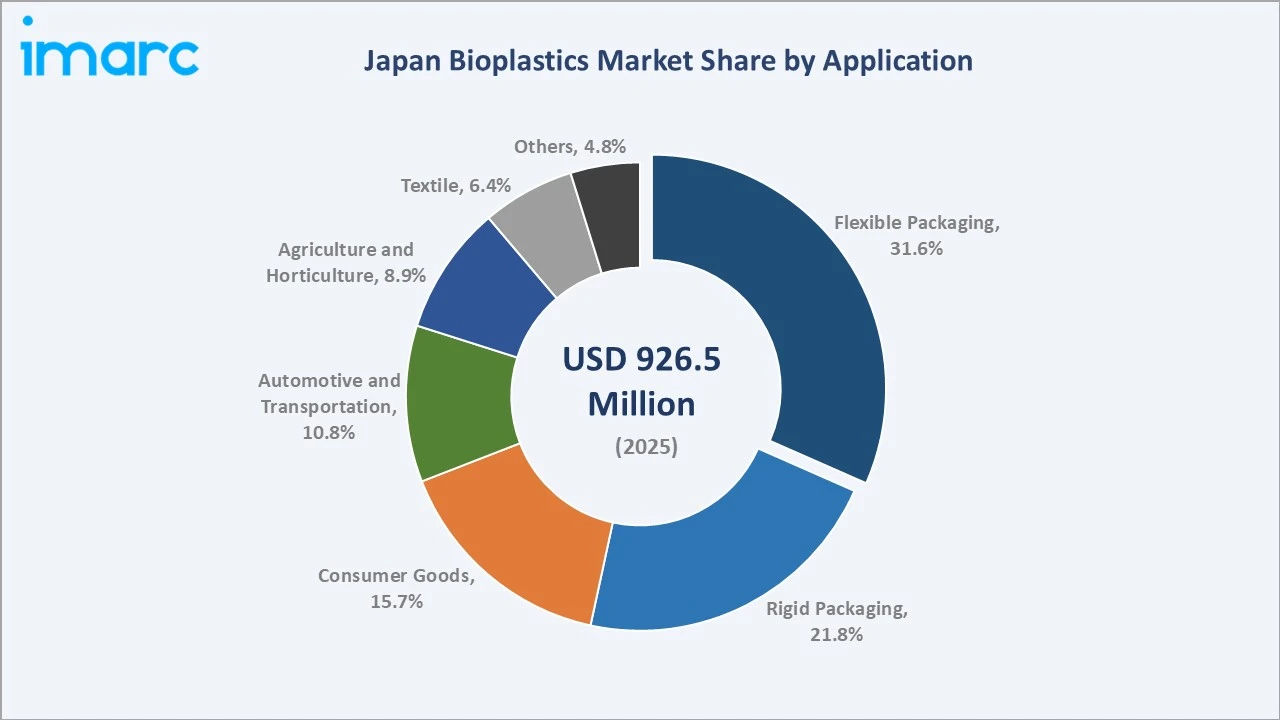
Rigid packaging at 21.8% is the second-largest application segment, driven by adoption of PLA-based trays, containers, and bottles across food retail and convenience sectors.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Kanto Region | 34.8% | Large manufacturing base, dense packaging converter network, concentration of corporate headquarters, and highest consumer goods demand in Japan |
| Kansai/Kinki Region | 19.7% | Chemical manufacturing clusters in Osaka, strong packaging and electronics producer base, growing sustainability commitments from regional corporates |
| Central/Chubu Region | 15.6% | Automotive manufacturing hub centered on Nagoya, growing adoption of bio-based engineering plastics by original equipment manufacturers and Tier 1 suppliers |
| Kyushu-Okinawa Region | 9.8% | Agricultural bioplastic film adoption, food processing sector growth, expanding composting infrastructure, and government sustainability programs |
| Tohoku Region |
6.8% |
Agricultural applications, food processing industry, government-led circular economy initiatives, and growing regional sustainability investment |
| Chugoku Region |
6.1% |
Industrial manufacturing base, packaging sector demand, government sustainability mandates, and growing corporate environmental commitment |
| Hokkaido Region |
4.3% |
Agricultural bioplastic film demand, food packaging adoption, dairy and agricultural sector sustainability initiatives |
| Shikoku Region |
2.9% |
Agricultural applications, food processing sector, growing awareness of compostable materials, regional government sustainability programs |
Kanto Region leads the regional landscape at 34.8% in 2025, anchored by Tokyo's concentration of packaging converters, automotive suppliers, consumer goods companies, and corporate sustainability programs.
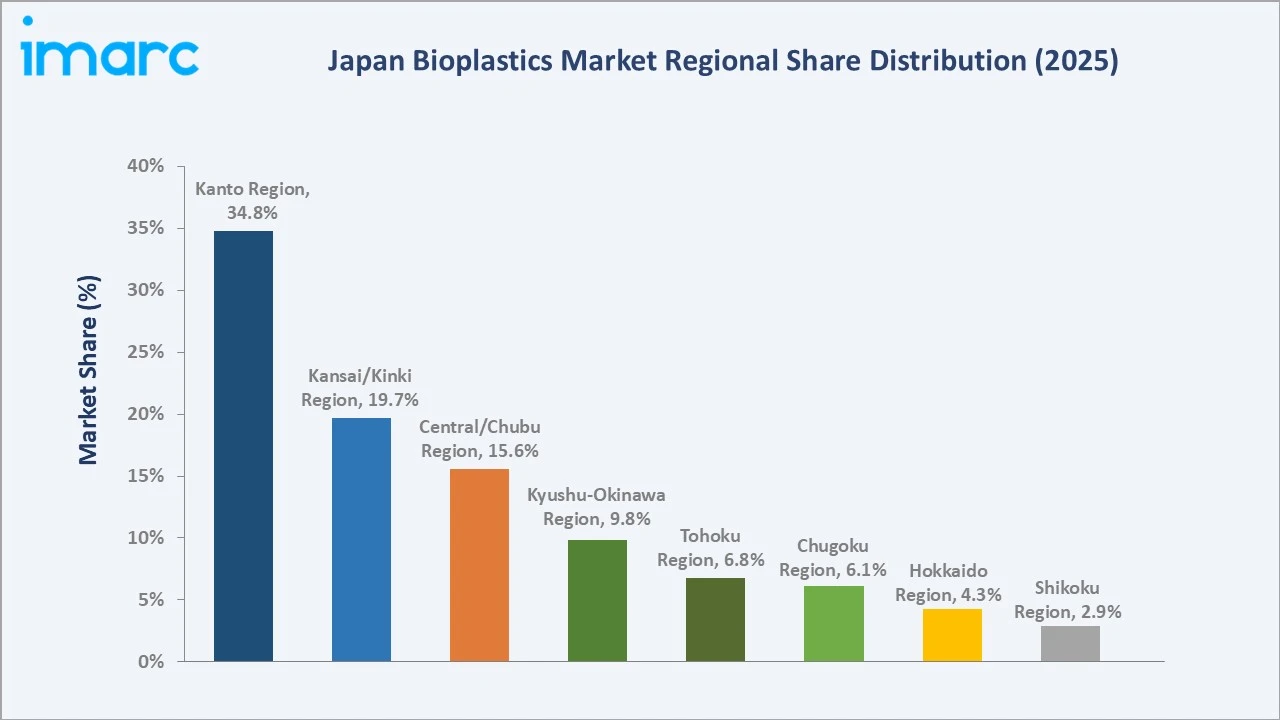
Kyushu-Okinawa Region at 9.8% is the fastest-growing regional market among smaller regions, supported by expanding agricultural bioplastic film adoption, food processing sector growth, and government investment in composting and circular economy infrastructure.
Competitive Landscape
The Japan bioplastics market features a mix of diversified chemical conglomerates, specialty polymer manufacturers, and industrial companies with emerging bioplastics divisions. Technology differentiation, production scale, feedstock access, and regulatory certification capability form the primary competitive differentiators.
|
Company |
Key Brands |
Market Position |
Core Strength |
| Mitsui Chemicals, Inc. | Bio-based Polymer Solutions | Leader | Expanding bio-based polymer production capacity and sustainable material solutions across packaging and industrial markets |
| Toray Industries, Inc. | Ecodear | Leader | Advancing bio-based polymer solutions and integrating sustainable materials across fiber, film, and engineering polymer platforms |
| Kaneka Corporation | KANEKA Biodegradable Polymer Green Planet™ |
Challenger |
Scaling PHA biodegradable polymer manufacturing and expanding global partnerships for high-value bioplastic applications |
| Unitika Ltd. | Terramac | Challenger | Growing PLA-based bioplastic portfolio across packaging, fiber, and industrial application segments |
| NEC Corporation | NECycle | Emerging | Developing cellulose and kenaf-based bioplastics for electronics housings and industrial component applications |
Key players include Mitsui Chemicals, Inc., Toray Industries, Inc., Kaneka Corporation, Unitika Ltd., and NEC Corporation, among others.
Key Company Profiles
Mitsui Chemicals, Inc.
Mitsui Chemicals, Inc. is a Japan-based integrated chemical company headquartered in Tokyo. The company develops and commercializes bio-based polymer solutions targeting packaging, agricultural, and industrial applications, leveraging its advanced materials and chemical synthesis capabilities to support Japan's transition toward sustainable plastics.
- Product Portfolio: Bio-based polymer solutions including bio-based polyesters, polymer blends, and sustainable resin compounds for packaging, agricultural films, and consumer goods applications.
- Recent Developments: The company continues to develop its bio-based polymer materials and expand its sustainable product offerings across key end-use markets.
- Strategic Focus: Broadening its materials portfolio into high-performance bio-based compounds and reinforcing supply chain partnerships to serve Japan's evolving packaging and industrial material requirements.
Toray Industries, Inc.
Toray Industries, Inc. is a Japan-based advanced materials manufacturer headquartered in Tokyo. The company develops bio-based polymer materials including its Ecodear line of plant-derived PET and PLA-based materials, targeting fiber, film, and engineering polymer applications.
- Product Portfolio: Ecodear bio-based polymer materials including plant-derived PET fibers, PLA-based films, and bio-based engineering plastics for fiber, packaging, and industrial applications.
- Recent Developments: The company continues to advance its Ecodear bio-based materials line and broaden application development across fiber, film, and polymer segments.
- Strategic Focus: Widening commercial adoption of plant-derived performance materials across fiber, film, and specialty engineering polymer applications through continued product innovation.
Kaneka Corporation
Kaneka Corporation is a Japan-based specialty chemicals and materials company. The company produces KANEKA Biodegradable Polymer Green Planet™, a PHA-based material that biodegrades in marine and soil environments and targets food packaging, agricultural, and single-use product applications.
- Product Portfolio: KANEKA Biodegradable Polymer Green Planet™ PHA biodegradable polymer for food packaging, agricultural film, medical device, and single-use product applications.
- Recent Developments: The company continues to develop its Green Planet™ PHA polymer capabilities and work toward broader commercial adoption across application markets.
- Strategic Focus: Commercializing marine-biodegradable PHA polymers at industrial scale and deepening collaborative value chain development across food contact, agricultural, and industrial application markets.
Market Concentration Analysis
The Japan bioplastics market exhibits moderate fragmentation, with large diversified chemical groups and specialty polymer manufacturers competing alongside automotive and electronics companies developing proprietary bio-based material programs. The top players, including Mitsui Chemicals, Inc. and Toray Industries, Inc., account for a significant share of domestic bioplastic production volume, while specialty producers like Kaneka Corporation hold leading positions in specific polymer categories.
Barriers to competitive entry include capital requirements for bioplastic manufacturing facilities, access to agricultural feedstock supply chains, expertise in fermentation and polymer processing technologies, and certification costs for compostability and biodegradability standards. These factors favor established chemical groups and companies with existing polymer manufacturing infrastructure.
Consolidation is advancing through joint ventures, supply agreements, and technology partnerships linking feedstock producers, polymer manufacturers, and end-use industry partners. Strategic alliances between Japanese bioplastic producers and global material technology companies are emerging as a key structure for scaling production and accelerating application development.
Investment & Growth Opportunities
Fastest-Growing Segments
Automotive and transportation are expanding fastest among application segments, driven by OEM bio-based content targets and carbon footprint reduction programs. Growing interest in lightweight components and sustainable interior materials is further creating opportunities for bioplastics adoption across vehicle manufacturing and mobility applications.
Emerging Markets
Kyushu-Okinawa Region is the fastest-growing regional opportunity, supported by agricultural sector bioplastic adoption, food processing industry growth, and government circular economy investment. Expanding industrial activity and rising demand for sustainable packaging solutions are further creating opportunities for bioplastics manufacturers across the region.
Venture & Investment Trends
Investment activity is concentrated in PHA production capacity expansion, bio-based engineering polymer development, and composting infrastructure supporting circular bioplastic end-of-life systems. Government grants and subsidies are catalyzing private investment in domestic bioplastic manufacturing and feedstock technology development.
Future Market Outlook (2026-2034)
The Japan bioplastics market is projected to grow from USD 926.5 Million in 2025 to USD 1,038.2 Million in 2026, reaching USD 2,582.6 Million by 2034, registering a CAGR of 12.07% during 2026-2034. Four forces will shape the Japan bioplastics market through 2034: an increasingly stringent national regulatory framework for plastic reduction and producer responsibility; accelerating cost reduction in PLA and PHA manufacturing driven by domestic polymer innovation; deepening integration of bio-based materials across automotive, packaging, and agricultural value chains; and the steady displacement of conventional plastics through composting infrastructure expansion and retailer eco-packaging commitments.
By 2034, the Japan bioplastics market is expected to be characterized by commercially mature biodegradable packaging segments, scaled PHA production for premium applications, and substantial automotive sector adoption of bio-based engineering plastics. Continued government policy support and increasing corporate sustainability commitments will sustain strong demand growth through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with bioplastic manufacturers, packaging converters, automotive material engineers, agricultural operators, and regulatory officials, validating market sizing, segment mix, and regional demand patterns across Japan's bioplastics ecosystem.
Secondary Research
Secondary sources included Japan Bioplastics Association publications, Ministry of Economy, Trade and Industry reports, Ministry of the Environment plastic regulation documents, corporate sustainability disclosures from listed manufacturers, and government Green Growth Strategy materials.
Forecasting Models
Market forecasts used top-down and bottom-up models combining domestic plastic consumption data, bioplastic penetration rate assumptions, regulatory implementation timelines, and technology adoption trajectories. Scenario analysis addressed regulatory enforcement pace, feedstock price trends, and manufacturing capacity investment plans.
Japan Bioplastics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Products Covered |
|
| Applications Covered | Flexible Packaging, Rigid Packaging, Agriculture and Horticulture, Consumer Goods, Textile, Automotive and Transportation, Others |
| Distribution Channels Covered | Online, Offline |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Mitsui Chemicals, Inc., Toray Industries, Inc., Kaneka Corporation, Unitika Ltd., NEC Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan bioplastics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan bioplastics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan bioplastics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Bioplastics Market Report
The Japan bioplastics market size is estimated at USD 1,038.2 Million in 2026, driven by rising corporate sustainability commitments and expanding industrial adoption across packaging, agricultural, and automotive sectors, which are boosting demand for biodegradable polymers, PLA, PHA, and bio-based resins.
The market is projected to grow at a CAGR of 12.07% from 2026-2034, reaching USD 2,582.6 Million by 2034, supported by rising demand for sustainable materials, government initiatives to reduce plastic waste, and expanding applications across packaging, automotive, and consumer goods industries.
Biodegradable dominates at 57.8% share in 2025, driven by regulatory mandates for single-use plastic reduction, expanding composting infrastructure, and widespread adoption in flexible packaging and consumer goods applications.
Flexible packaging leads at 31.6% application share in 2025, driven by Japan's large food processing and convenience retail sectors and strong regulatory push for compostable packaging materials across foodservice and consumer goods channels.
Kanto Region commands 34.8% regional share in 2025, led by Tokyo's concentration of packaging manufacturers, automotive suppliers, and consumer goods companies with strong bioplastic demand and processing capacity.
Kyushu-Okinawa Region is among the fastest-growing regions, supported by expanding agricultural bioplastic film adoption, food processing industry growth, and government investment in composting and circular economy infrastructure.
Key players include Mitsui Chemicals, Inc., Toray Industries, Inc., Kaneka Corporation, Unitika Ltd., and NEC Corporation, among others.
Key drivers include rising consumer eco-preference, automotive lightweighting programs, government carbon neutrality targets, and expanding composting infrastructure supporting biodegradable bioplastic end-of-life management.
Key challenges include high production costs relative to conventional plastics, limited domestic agricultural feedstock supply, performance limitations in high-demand applications, and consumer confusion between bio-based and biodegradable bioplastic categories.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade