
Japan Coal Market Size, Share, Trends and Forecast by End User, and Region 2026-2034
Japan Coal Market Size, Share, Trends & Forecast (2026-2034)
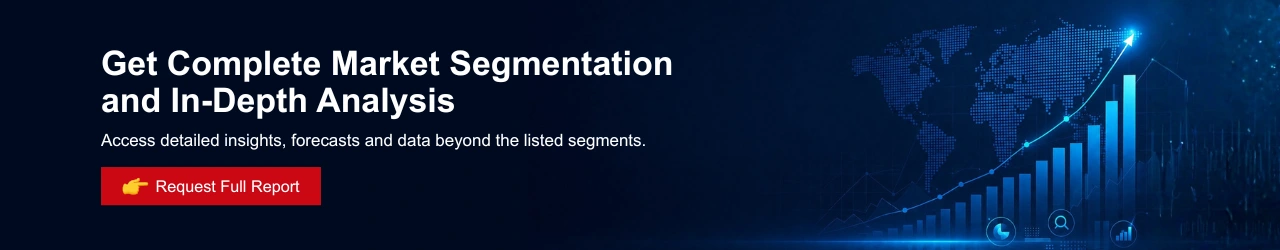
The Japan coal market reached 666.2 Thousand Tons in 2025, growing to 687.3 Thousand Tons in 2026, and is projected to reach 882.1 Thousand Tons by 2034, growing at a CAGR of 3.17% during 2026-2034. The market is driven by Japan's energy security strategy, which mandates coal as a critical baseload electricity source in the Strategic Energy Plan. Japan is one of the world's largest coal importers, sourcing primarily from Australia, Indonesia, Russia, and Canada through long-term procurement agreements managed by major sogo shosha (general trading companies). Power Station (Thermal Coal) dominates end-user demand at 65.0%, reflecting coal's central role in Japan's electricity grid stability. Coking Feedstock (Coking Coal) accounts for 30.0%, sustained by Japan's integrated steel industry. Kanto Region commands 25.0% of Japan's coal market, driven by the highest concentration of coal-fired power plants and industrial facilities in the Tokyo metropolitan area.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
666.2 Thousand Tons |
|
Market Size (2026) |
687.3 Thousand Tons |
|
Forecast Market Size (2034) |
882.1 Thousand Tons |
|
CAGR (2026-2034) |
3.17% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant End User |
Power Station (Thermal Coal) (65.0%, 2025) |
|
Leading Region |
Kanto Region (25.0%, 2025) |
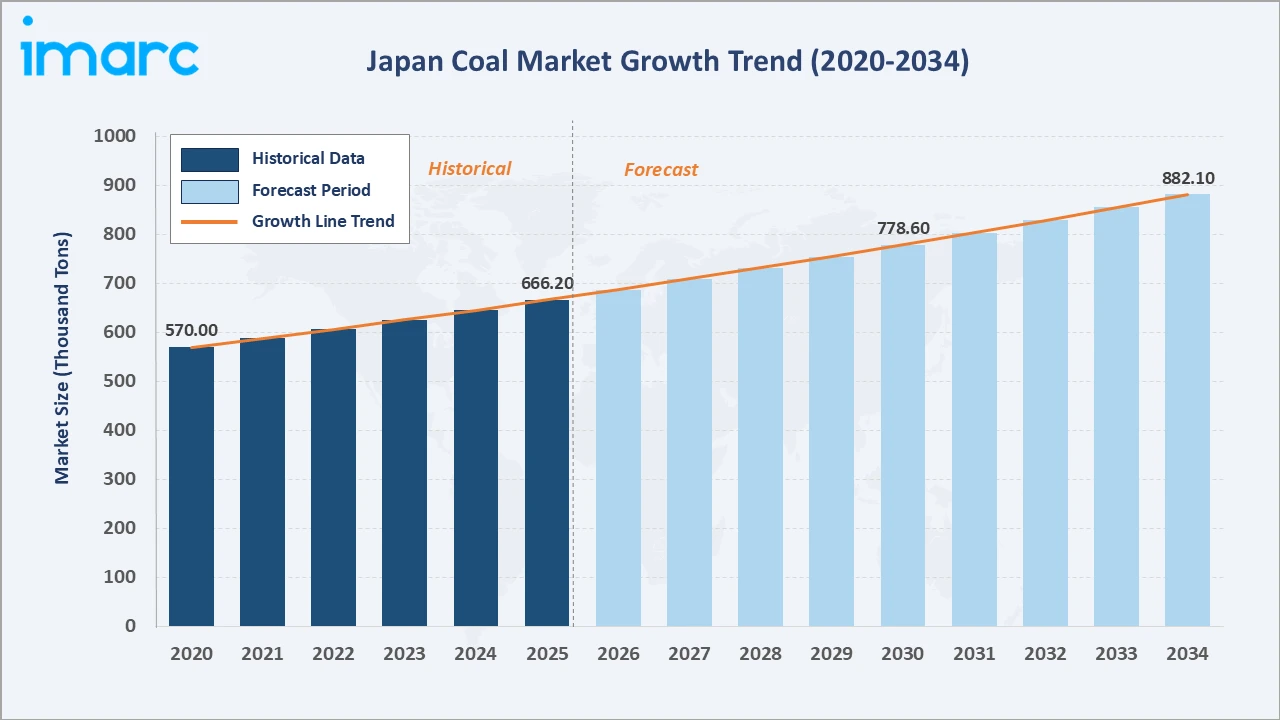
The Japan coal market expanded from 570.0 Thousand Tons in 2020 to 666.2 Thousand Tons in 2025, anchored at 778.6 Thousand Tons in 2030, and forecast to reach 882.1 Thousand Tons by 2034. The 2026 market is projected at 687.3 Thousand Tons. Japan's coal imports remained anchored by consistent power utility procurement and steel industry coking coal requirements throughout the 2020-2025 historical period, with COVID-19 supply chain disruptions in 2020 contributing to temporary demand moderation before recovery through 2021-2025.
To get more information on this market, Request Sample
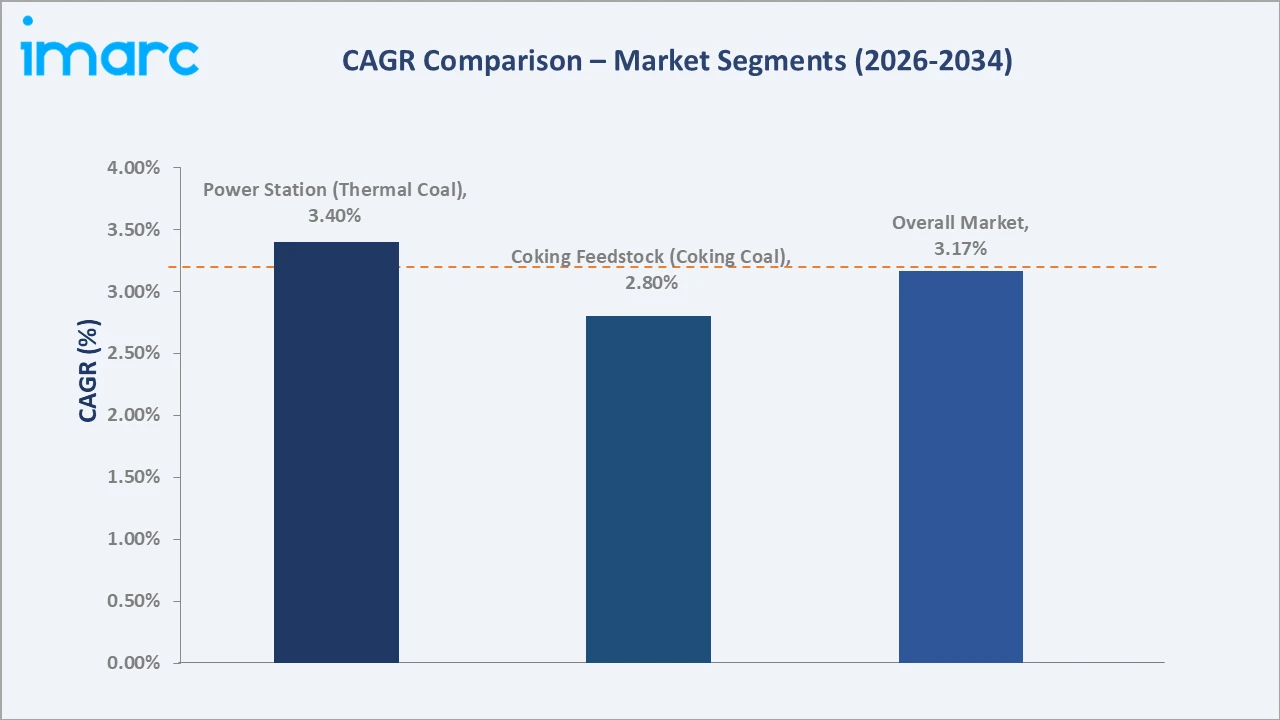
Power Station (Thermal Coal) grows at ~3.4% CAGR through 2026-2034, driven by Japan's coal fleet baseload commitments and ammonia co-firing programs extending plant operational life. Coking Feedstock (Coking Coal) grows at ~2.8% CAGR through stable blast furnace steelmaking demand. Kanto Region leads regional CAGR at ~3.5%, reflecting Tokyo metropolitan industrial growth and coal power capacity concentration.
Executive Summary
The Japan coal market reached 666.2 Thousand Tons in 2025, growing to an estimated 687.3 Thousand Tons in 2026, representing a critical energy commodity underpinning Japan's electricity grid stability and steel production capacity. The market encompasses thermal coal for power generation, metallurgical (coking) coal for blast furnace steelmaking, and specialty industrial coal applications across cement, chemicals, and other manufacturing sectors.
Power Station (Thermal Coal) at 65.0% dominates through Japan's coal-fired power fleet, which contributes approximately one-third of national electricity generation and provides essential baseload capacity during Japan's multi-decade energy transition. Coking Feedstock (Coking Coal) at 30.0% reflects Japan's position as a world-leading steel producer with major integrated steelmakers Nippon Steel and JFE Steel operating large blast furnace complexes. Kanto Region, at 25.0%, leads through its concentration of major coal power plants and dense industrial base centered around the Tokyo metropolitan area.
Key Market Insights
|
Insight |
Data |
|
Dominant End User |
Power Station (Thermal Coal) – 65.0% share (2025) |
|
Second End User |
Coking Feedstock (Coking Coal) – 30.0% share (2025) |
|
Leading Region |
Kanto Region – 25.0% market share |
|
Market Opportunity |
Ammonia co-firing infrastructure; coking coal quality upgrade; energy security stockpiling; USC technology investment; green steel transition support |
Key Analytical Observations Supporting the Above Data:
- Power Station (Thermal Coal) at 65.0%: Thermal coal dominates due to Japan's continued reliance on coal-fired power plants for stable, cost-effective baseload electricity generation. Despite renewable energy expansion, coal plants provide approximately one-third of national electricity output, with JERA and J-POWER operating major coal generation fleets across Japan's industrial regions.
- Coking Feedstock (Coking Coal) at 30.0%: Coking coal demand is sustained by Japan's major integrated steelmakers—Nippon Steel and JFE Steel—who import premium-grade metallurgical coal from Australia's Queensland mines for blast furnace operations producing high-quality steel for automotive, shipbuilding, and construction applications.
- Kanto Region at 25.0%: Kanto Region leads due to Japan's highest concentration of coal-fired power plants and industrial facilities centered around the Tokyo metropolitan area, where electricity consumption density requires substantial coal-based baseload power capacity complementing variable renewables.
Japan Coal Market Overview
The Japan coal market encompasses the import, port handling, distribution, and consumption of thermal coal for power generation and metallurgical coal for steel production. Japan is one of the world's largest coal importers at approximately 180-200 million tonnes annually, sourcing predominantly from Australia (60-65%), Indonesia, Russia, and Canada through long-term supply agreements managed by major trading companies including Mitsubishi Corporation, Mitsui & Co., Marubeni Corporation, and Sumitomo Corporation.
Macroeconomic factors include Japan's Strategic Energy Plan targets, industrial production requirements, international coal price dynamics, and carbon emission commitments. Government energy security imperatives, environmental regulations, and steel industry output volumes collectively drive coal market demand trajectories. Japan's 2050 carbon neutrality target and 2030 emission reduction commitments create structural demand moderation pressure while near-term energy security considerations sustain coal import volumes.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
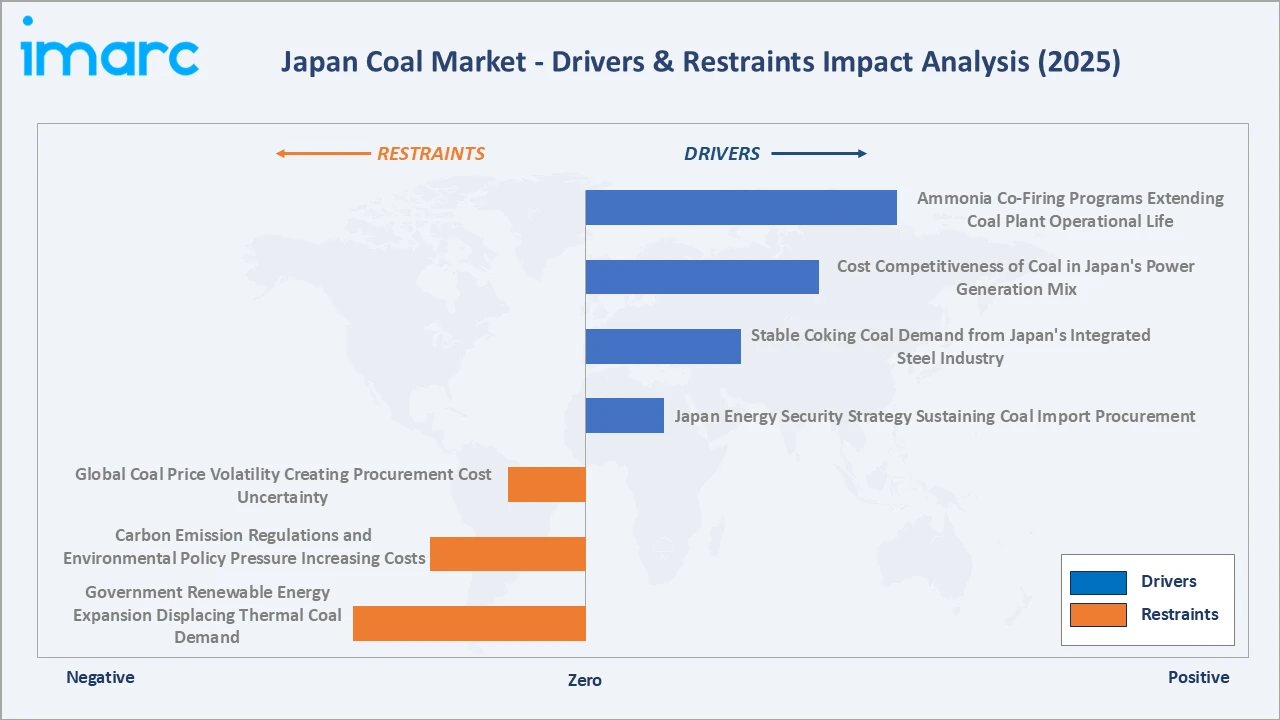
- Japan Energy Security Strategy Sustaining Coal Import Procurement: Japan's Strategic Energy Plan prioritizes energy source diversification to ensure stable supply, with coal designated as a critical baseload resource. Coal accounts for approximately one-third of Japan's power generation, reflecting the government's balanced approach to energy security, cost stability, and gradual decarbonization. The Ministry of Economy, Trade and Industry (METI) continues to support long-term coal procurement agreements with major exporters, ensuring supply security during Japan's multi-decade energy transition to renewables.
- Stable Coking Coal Demand from Japan's Integrated Steel Industry: Japan's major steelmakers—including Nippon Steel and JFE Steel—rely on high-quality coking coal for blast furnace operations producing approximately 85-90 million tonnes of crude steel annually. The high-grade steel manufactured at Japan's coastal integrated mill complexes serves premium automotive, shipbuilding, and infrastructure applications, underpinning consistent metallurgical coal import demand with limited substitution risk in the near-to-medium term.
- Cost Competitiveness of Coal in Japan's Power Generation Mix: Coal remains one of the most cost-effective options for large-scale baseload power generation relative to LNG alternatives, particularly during periods of high LNG price volatility. Japan's power utilities continue operating existing coal fleet assets to maintain economic generation portfolios while managing energy transition costs, supporting coal demand from the power sector through the 2026-2034 forecast period.
- Ammonia Co-Firing Programs Extending Coal Plant Operational Life: Japan's government-initiated ammonia co-firing programs at coal power plants create a transition pathway extending coal infrastructure operational life while reducing per-unit emissions. JERA's commercial ammonia co-firing at Hekinan Thermal Power Station—achieving 20% ammonia co-firing ratio—demonstrates Japan's commitment to clean coal technology as a bridging energy solution, sustaining coal consumption volumes during the energy transition period.
Market Restraints
- Government Renewable Energy Expansion Displacing Thermal Coal Demand: Japan's 2030 energy mix targets 36-38% from renewables, which will structurally reduce coal's power generation share from current levels. Expanding solar, offshore wind, and battery storage capacity is progressively displacing coal-fired generation, and utility-scale renewable projects commissioned through 2025-2030 will create structural thermal coal demand reduction pressure over the forecast period.
- Carbon Emission Regulations and Environmental Policy Pressure Increasing Costs: Japan's commitment to carbon neutrality by 2050 and 46% greenhouse gas emission reduction by 2030 creates regulatory pressure on coal utilization. Carbon pricing mechanisms, emissions trading, and environmental compliance standards increase operational costs for coal-intensive power operators, reducing coal's long-term economic competitiveness against lower-emission generation alternatives.
- Global Coal Price Volatility Creating Procurement Cost Uncertainty: Japan's complete dependence on coal imports exposes the market to international price volatility from geopolitical developments, exporter policy changes, shipping cost fluctuations, and weather-related supply disruptions. High coal price episodes reduce the economic competitiveness of coal-fired generation relative to LNG and renewables, creating demand-side cost management pressure for utilities.
Market Opportunities
- Green Steel Transition Supporting Premium Coking Coal Quality Demand: Japan's steel industry gradual decarbonization pathway creates demand for premium coking coal grades enabling efficient, lower-emission blast furnace operations as an interim measure while hydrogen direct reduction technology matures commercially. High-quality coking coal enabling optimal coke production supports the steel sector's interim carbon intensity reduction pathway.
- Energy Security Coal Stockpiling Programs Creating Stable Demand: Japan's strategic coal stockpiling infrastructure and reserve management programs create stable procurement demand independent of immediate consumption requirements, supporting market volume stability during energy transition uncertainty and geopolitical supply disruption risk management.
Market Challenges
- Nuclear Restart Delays Extending Coal Dependence and Creating Demand Uncertainty: Japan's nuclear restart program has proceeded slower than planned following Fukushima safety review requirements. When nuclear capacity returns at commercial scale, coal generation displacement will accelerate, creating structural thermal coal demand reduction risk within the forecast period's later years.
- Import Concentration Risk with Key Exporter Nations: Japan's coal import base is concentrated, with Australia supplying approximately 60-65% of total imports. Exporter policy changes, labor disruptions, or geopolitical developments create substantial supply procurement risk, requiring diversification investment and complex contract management across multiple alternative source nations.
Emerging Market Trends
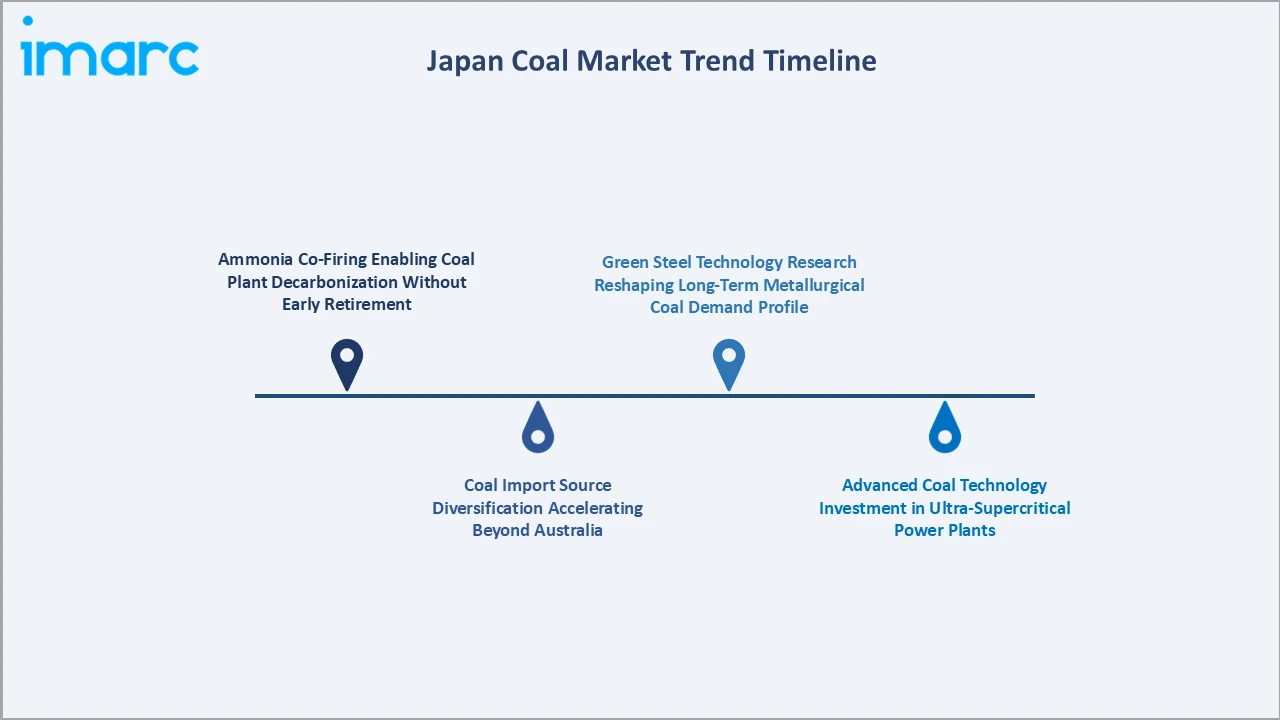
1. Ammonia Co-Firing Enabling Coal Plant Decarbonization Without Early Retirement
Japan is pioneering commercial-scale ammonia co-firing at coal power plants, with JERA achieving 20% ammonia co-firing at Hekinan Thermal Power Station—a globally significant milestone in large-scale clean energy co-firing technology. JERA and J-POWER are leading commercial-scale program development targeting higher ammonia substitution ratios. This trend extends coal plant operational life while reducing per-unit carbon emissions, sustaining coal consumption volumes during Japan's managed energy transition through the forecast period.
2. Coal Import Source Diversification Accelerating Beyond Australia
Japan's major trading companies are strategically diversifying coal sourcing beyond Australia to manage geopolitical and supply chain concentration risk. Canadian, Colombian, and South African coal sources are receiving increased evaluation alongside existing Australian, Indonesian, and Russian supply relationships. Mitsubishi Corporation, Mitsui & Co., and Marubeni Corporation are advancing long-term supply agreements across multiple geographies, systematically reducing dependence on single-source procurement for both thermal and metallurgical coal categories.
3. Advanced Coal Technology Investment in Ultra-Supercritical Power Plants
Japan continues significant investment in Ultra-Supercritical (USC) and Advanced Ultra-Supercritical (A-USC) coal power technology, achieving 45-50% plant efficiencies versus 35-40% for conventional plants. USC technology upgrades by JERA and J-POWER reduce coal consumption per unit of electricity generated and lower per-unit CO₂ emissions while maintaining coal's baseload generation role during Japan's energy transition, making each tonne of imported coal contribute more effectively to electricity output.
4. Green Steel Technology Research Reshaping Long-Term Metallurgical Coal Demand Profile
Japan's steel producers—led by Nippon Steel and JFE Steel—are investing in hydrogen direct reduction iron (DRI) and electric arc furnace (EAF) technologies as long-term alternatives to blast furnace steelmaking. While commercial-scale transitions extend beyond the 2034 forecast horizon, these research programs signal structural metallurgical coal demand evolution and are already influencing long-term procurement strategy, with premium coking coal quality demand potentially sustained even as longer-term volume trajectories moderate.
Industry Value Chain Analysis
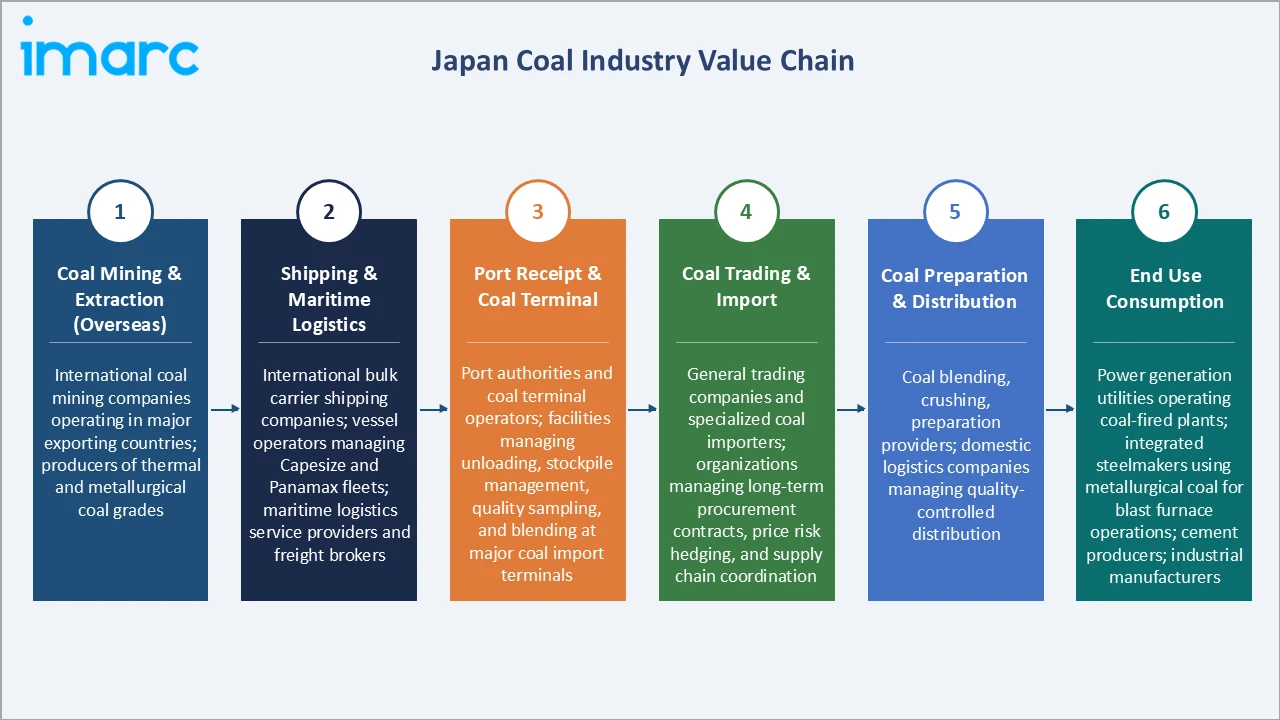
The Japan coal market value chain integrates overseas coal mining and extraction, bulk maritime shipping, port receipt and terminal handling, domestic coal trading and distribution, coal preparation and quality blending, and final consumption at power utilities and steel manufacturers. Each value chain stage involves specialized infrastructure, expertise, and commercial relationships managed across complex international and domestic supply networks.
|
Stage |
Key Participants |
|
Coal Mining & Extraction (Overseas) |
International coal mining companies operating in major exporting countries; producers of thermal and metallurgical coal grades |
|
Shipping & Maritime Logistics |
International bulk carrier shipping companies; vessel operators managing Capesize and Panamax fleets; maritime logistics service providers and freight brokers |
|
Port Receipt & Coal Terminal |
Port authorities and coal terminal operators; facilities managing unloading, stockpile management, quality sampling, and blending at major coal import terminals |
|
Coal Trading & Import |
General trading companies and specialized coal importers; organizations managing long-term procurement contracts, price risk hedging, and supply chain coordination |
|
Coal Preparation & Distribution |
Coal blending, crushing, and preparation service providers; domestic logistics companies managing quality-controlled distribution from port storage to end-user consumption facilities |
|
End Use Consumption |
Power generation utilities operating coal-fired plants; integrated steelmakers using metallurgical coal for blast furnace operations; cement producers; industrial manufacturers |
The coal trading and import stage represents the most commercially differentiated phase of Japan's coal market value chain. Japan's major sogo shosha leverage mine equity positions in Australia and Canada, long-term procurement agreements, and integrated logistics infrastructure to provide supply security and price risk management services. Quality management through coal preparation and blending at terminal facilities is critical for matching imported coal specifications to end-user combustion and coking requirements across power generation and steel production applications.
Technology Landscape in the Japan Coal Industry
Ultra-Supercritical and Advanced USC Coal Power Technology
Ultra-Supercritical (USC) and Advanced USC coal power technology enables higher steam temperatures and pressures—achieving 45-50% plant efficiencies versus 35-40% for conventional plants—reducing coal consumption per unit of electricity generated. Japanese utilities including JERA and J-POWER have invested in USC technology upgrades at major coal power stations, reducing both coal input requirements and per-unit CO₂ emissions while maintaining coal's essential baseload power generation role during Japan's extended energy transition period.
Coal Blending and Quality Management Technology
Advanced coal blending technology enables Japanese coal consumers to optimize combustion efficiency and coking quality by combining coals from different geographic origins with complementary quality characteristics. Automated blending systems, real-time quality sensors, and advanced analytical laboratory infrastructure ensure consistent coal performance despite inherent variability in imported coal characteristics. This technology supports procurement cost optimization by enabling use of lower-cost coal grades in quality-compliant blends, improving overall import economics.
Ammonia Co-Firing Combustion Technology
Ammonia co-firing combustion technology modifies existing coal boiler systems to combust ammonia alongside coal, reducing per-unit carbon emissions proportionate to the ammonia substitution ratio applied. Japan leads globally in commercial-scale ammonia co-firing development through JERA's Hekinan Thermal Power Station program achieving 20% co-firing, with J-POWER's Matsushima Power Station also conducting co-firing research. Combustion burner modification hardware, ammonia handling and storage infrastructure, and advanced safety management systems represent the core technology investment requirements for large-scale co-firing deployment.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
End User |
Power Station (Thermal Coal) |
65.0% |
2025 |
|
Region |
Kanto Region |
25.0% |
2025 |
By End User
Power Station (Thermal Coal) leads at 65.0% (2025), growing at ~3.4% CAGR during 2026-2034. The power station segment encompasses Japan's coal-fired power plants operated by JERA—the world's largest LNG buyer and a dominant coal power operator—J-POWER, and regional utilities. Thermal coal imports are governed by long-term supply agreements with Australian and Indonesian producers, ensuring stable procurement volumes despite short-term price fluctuations. Power stations consume predominantly sub-bituminous and bituminous thermal coal grades suited for high-efficiency USC and conventional pulverized coal boiler combustion.
To access detailed market analysis, Request Sample
Coking Feedstock (Coking Coal) at 30.0% grows at ~2.8% CAGR, encompassing metallurgical coal imported for Japan's blast furnace steelmaking operations at Nippon Steel and JFE Steel facilities. Japan imports premium-grade hard coking coal (HCC) primarily from Australia's Queensland mines, with semi-soft coking coal and pulverized coal injection (PCI) coal sourced from diverse origins including Canada and the United States. Others at 5.0% (~2.1% CAGR) includes coal for cement kilns, chemical manufacturing processes, and specialized industrial heating applications with stable but modest demand volumes.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Coal Market Drivers & Characteristics |
|
Kanto Region |
25.0% |
Driven by Japan's largest concentration of coal power plants and industrial facilities in the Tokyo metropolitan area, including major JERA and J-POWER generation assets requiring substantial coal-based baseload electricity. |
|
Kinki Region |
20.0% |
Supported by major industrial clusters in Osaka and Kobe including integrated steelmaking operations at Nippon Steel and JFE Steel facilities and coal-based power generation infrastructure. |
|
Central/Chubu Region |
17.0% |
Anchored by JERA's Hekinan Thermal Power Station—one of Japan's largest coal power plants—and Toyota Group automotive manufacturing energy demand for industrial coal consumption. |
|
Kyushu-Okinawa Region |
12.0% |
Sustained by regional power utilities, semiconductor manufacturing facilities, and chemical industry operations with consistent coal-based electricity and process energy requirements. |
|
Chugoku Region |
10.0% |
Supported by major coal-fired power stations and integrated steel production facilities in Hiroshima and Yamaguchi prefectures with stable industrial coal demand. |
|
Tohoku Region |
7.0% |
Driven by regional power generation needs and food processing industries with stable coal consumption patterns and moderate manufacturing industrial base. |
|
Hokkaido Region |
5.0% |
Supported by heating energy demand, food processing, and local coal-fired power generation with moderate but stable year-round coal consumption requirements. |
|
Shikoku Region |
4.0% |
Sustained by local utility coal power plants and chemical manufacturing with Japan's smallest regional share reflecting limited heavy industrial concentration. |
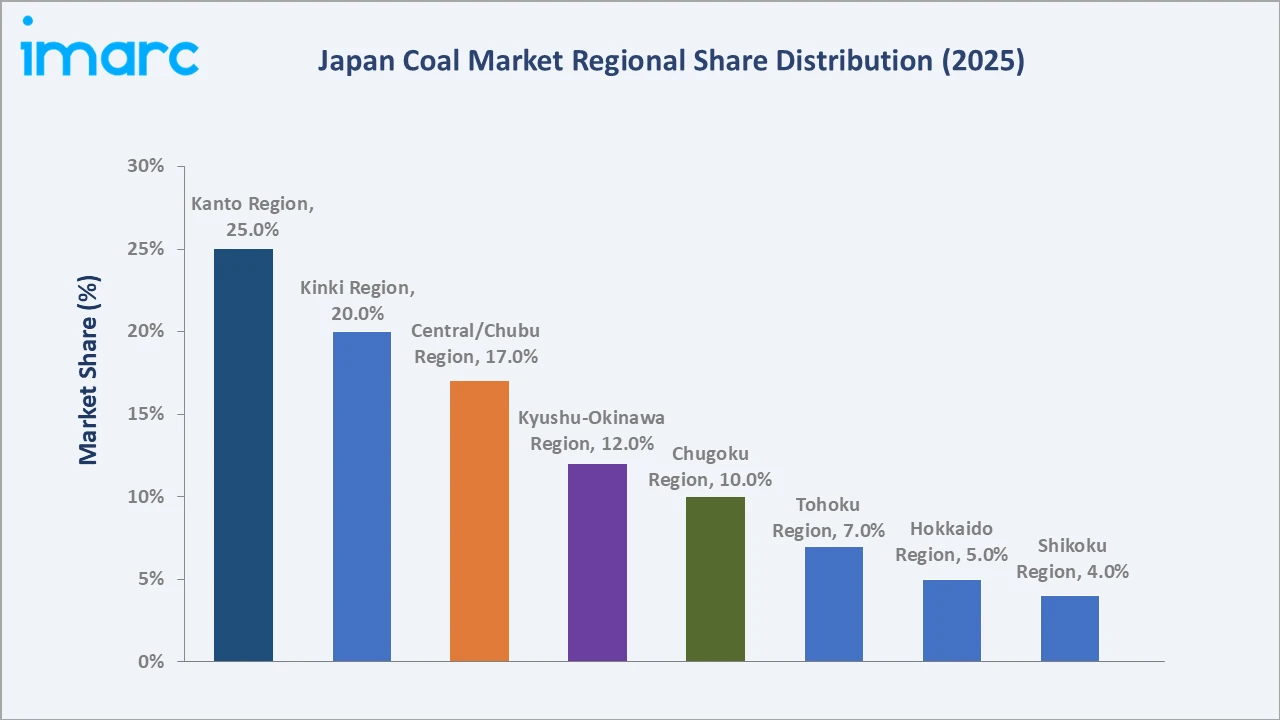
Kanto Region's 25.0% market leadership reflects the Tokyo metropolitan area's position as Japan's largest electricity consumption zone, anchored by major coal-fired power capacity operated by JERA and supplementary generation from J-POWER assets. Kinki Region's 20.0% reflects both coal-based power generation and steel production at major Kobe and Osaka coastal integrated mill complexes operated by Nippon Steel and JFE Steel. Central/Chubu Region's 17.0% is anchored by JERA's Hekinan Thermal Power Station—one of Japan's largest coal power plants and the site of Japan's landmark commercial ammonia co-firing program—and Toyota Group's extensive automotive manufacturing energy demand. Chugoku Region at 10.0% sustains demand through major coal power stations and steel production in Hiroshima and Yamaguchi prefectures.
Competitive Landscape
The Japan coal market competitive landscape encompasses major general trading companies (sogo shosha) managing coal procurement and supply chain integration, power utilities operating coal-fired generation fleets, and specialized coal importers managing logistics and quality control infrastructure. Japan's five major sogo shosha dominate coal procurement through vertically integrated operations including mine equity ownership, long-term supply agreements, and logistics coordination across international coal supply chains.
|
Company Name |
Key Products/Activities |
Market Position |
Core Strength |
|
J-POWER (Electric Power Development Co., Ltd.) |
Coal-fired power generation, IGCC clean coal technology, |
Market Leader |
J-POWER plays a central role as Japan's leading wholesale coal power generator and clean coal technology pioneer, operating major USC coal stations and advancing IGCC commercialization for low-emission baseload generation. |
|
JERA Co., Inc. |
Coal-fired power generation; global coal and LNG procurement; |
Market Leader |
JERA operates Japan's largest coal-fired power portfolio and is Asia's largest coal procurement organization, leading commercial ammonia co-firing at Hekinan Thermal Power Station in a globally significant energy transition milestone. |
|
Mitsubishi Corporation |
Thermal and metallurgical coal trading |
Established Player |
Mitsubishi Corporation is Japan's leading coal trading company with substantial mine equity in Australia and Canada, providing vertically integrated supply chain management from mine ownership to customer delivery. |
|
Mitsui & Co., Ltd. |
Coal trading |
Established Player |
Mitsui & Co. maintains significant coal mine ownership in Australia and manages integrated supply chains serving Japanese power utilities and steel manufacturers through established long-term procurement frameworks. |
|
Marubeni Corporation |
Coal trading |
Established Player |
Marubeni Corporation operates coal trading activities with mine equity investments supporting utility supply, with established procurement relationships spanning Australia, Indonesia, and other major exporting nations. |
Japan's sogo shosha concentration creates a differentiated market structure where procurement, logistics, and price risk management are consolidated in vertically integrated commercial organizations with mine equity positions. Their supply security advantages, built on decades of Australian and Canadian mine investment, sustain dominant procurement positions despite ongoing energy transition pressure and sustainability-driven portfolio optimization.
Key Company Profiles
J-POWER (Electric Power Development Co., Ltd.)
J-POWER is Japan's leading wholesale electricity generator and a pioneering clean coal technology developer, operating major coal-fired power stations and holding equity stakes in overseas coal mining operations while advancing next-generation coal combustion technologies including IGCC and ammonia co-firing.
- Key Products: Coal-fired power generation at USC and IGCC-technology plants; Osaki CoolGen IGCC demonstration plant; overseas coal mine equity in Australia; ammonia co-firing research and demonstration programs.
- Recent Developments: In March 2026, J-POWER conducted Japan’s first co-firing test using Erianthus, an energy crop, at one of its coal-fired power plants. The trial is part of the company’s efforts to reduce fossil-fuel use and advance carbon-neutral fuel options for its thermal power generation facilities. J-POWER stated that the biomass fuel was domestically grown and the initiative is aimed at developing practical biomass co-firing applications.
- Strategic Focus: Clean coal technology commercialization including IGCC and ammonia co-firing programs, overseas resource investment in coal mining equity, maintaining coal baseload generation capability during Japan's energy transition, and exporting clean coal technology solutions to emerging Asian markets.
JERA Co., Inc.
JERA Co., Inc. is Japan's largest electricity generating company, formed through a joint venture between Tokyo Electric Power Company (TEPCO) and Chubu Electric Power Company, operating one of Asia's largest thermal power portfolios and managing extensive global coal and LNG procurement with pioneering commercial ammonia co-firing programs.
- Key Products: Coal-fired power generation across multiple major Japanese facilities; global coal procurement from Australia, Indonesia, and Russia; LNG supply management; commercial ammonia co-firing at Hekinan; fuel price risk management and trading.
- Recent Developments: In 2026, JERA commenced commercial-scale 20% ammonia co-firing at Hekinan Thermal Power Station Unit 4 in Aichi Prefecture—a globally significant milestone representing the world's first large-scale commercial ammonia co-firing operation at a major coal power plant, demonstrating Japan's leadership in clean energy transition technology.
- Strategic Focus: Large-scale ammonia and hydrogen co-firing deployment to systematically reduce coal power carbon intensity; energy security through diversified global fuel procurement portfolios; decarbonized thermal power generation innovation for domestic application and technology export to Asian energy markets.
Mitsubishi Corporation
Mitsubishi Corporation is Japan's premier sogo shosha (general trading company) with extensive coal mining equity investments and integrated trading operations across Australia, Canada, and other major coal producing regions, serving Japan's power and steel sectors through vertically integrated supply chain management from mine to consumer.
- Key Products: Thermal and metallurgical coal mine equity investments in BHP Mitsubishi Alliance (BMA) and other Australian and Canadian operations; coal trading and supply chain management; logistics coordination; long-term supply agreements with Japanese utilities and steel manufacturers.
- Strategic Focus: Balancing coal supply security for Japanese customers through the energy transition with long-term portfolio decarbonization commitments; investing in premium coking coal assets with stronger long-term sustainability outlook; developing alternative clean energy supply chain capabilities including LNG, hydrogen, and ammonia supply infrastructure.
Market Concentration Analysis
The Japan coal market is moderately concentrated at the trading and procurement tier, with Japan's five major sogo shosha collectively managing the large majority of coal import volumes through mine equity positions and long-term supply agreements. Power generation is concentrated among JERA, J-POWER, and regional utilities with limited market fragmentation. End-use consumption is diversified across Power Station (Thermal Coal) (65.0%) and Coking Feedstock (Coking Coal) (30.0%) sectors with no single-user concentration risk within either segment.
Investment & Growth Opportunities
Highest Growth Segments
Power Station (Thermal Coal) (~3.4% CAGR), Coking Feedstock (Coking Coal) (~2.8% CAGR), USC technology retrofit investment, coal terminal modernization and automation, energy security strategic stockpiling programs, and premium metallurgical coal supply chain optimization represent the highest-growth coal market investment vectors through 2034.
Emerging Investment Opportunities
Ammonia co-firing infrastructure at Japan's coal power plants represents the largest near-term capital deployment opportunity within the energy transition framework. Suppliers of ammonia handling technology, burner modification systems, ammonia storage infrastructure, and co-firing management systems are positioned for significant capex capture from JERA, J-POWER, and regional utility coal fleet operators over the 2026-2030 investment cycle.
Investment Themes
- Ammonia and Hydrogen Co-Firing Infrastructure Supply and Engineering Services: Coal plant operators' ammonia and hydrogen co-firing programs require substantial capital investment in fuel handling, storage, combustion modification, safety management, and monitoring infrastructure. Technology suppliers and engineering firms positioned in Japan's co-firing supply chain are set for growth as the coal fleet undergoes systematic transition-technology investment through 2030.
- Premium Coking Coal Quality Management Technology and Supply Chain Optimization: Japan's steel industry demand for premium hard coking coal creates investment opportunity in quality management technology, blending infrastructure, and supply chain optimization capabilities. As steelmakers optimize blast furnace operations for interim decarbonization, premium coking coal supply security and grade consistency become key commercial differentiators for coal trading organizations.
Future Market Outlook (2026-2034)
The Japan coal market is projected to grow from 666.2 Thousand Tons in 2025 to 882.1 Thousand Tons by 2034, delivering a 3.17% CAGR over the forecast period. The market's 2026 anchor at 687.3 Thousand Tons and 2030 milestone at 778.6 Thousand Tons reflect continued coal consumption supported by Japan's baseload power requirements and steel industry metallurgical coal demand throughout Japan's managed energy transition.
Three structural forces define Japan's coal market through 2034 with high confidence. Energy security policy commitment sustains coal procurement frameworks despite decarbonization pressure, with Japan's Strategic Energy Plan ensuring coal remains in the generation mix through the forecast period. Steel industry metallurgical coal demand remains anchored by blast furnace steelmaking operations, with commercial-scale hydrogen DRI transitions extending beyond the forecast horizon at meaningful volume scale. Ammonia co-firing technology commercialization—pioneered by JERA at Hekinan—creates a transition pathway extending coal plant operational life while reducing per-unit emissions, supporting coal volume stability during Japan's energy transition.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ Japan coal market stakeholders (2025) including METI energy policy specialists, coal import operations directors at major sogo shosha, power utility procurement managers, steel company raw material purchasing executives, coal terminal operators, and Japan Coal Energy Center (JCOAL) industry specialists.
Secondary Research
Secondary research encompassed Japan's Strategic Energy Plan documentation, METI energy statistics annual reports, IEA Coal Market Update and Coal 2025 reports, Japan Coal Energy Center (JCOAL) data publications, Australian coal mining company annual reports, maritime bulk shipping statistics, and Japanese utility financial disclosures. Over 55 secondary sources reviewed and cross-referenced.
Forecasting Models
Market volume forecasts developed using a segment bottom-up model: (i) power generation thermal coal demand component calibrated against Japan's electricity generation targets; (ii) metallurgical coal demand component calibrated against Japanese steel production forecasts; (iii) industrial and other coal demand component; totals cross-checked against METI's Long-term Energy Supply and Demand Outlook scenarios with policy-driven demand moderation adjustments.
Japan Coal Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Thousand Tons |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| End Users Covered | Power Station (Thermal Coal), Coking Feedstock (Coking Coal), Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | J-POWER (Electric Power Development Co., Ltd.), JERA Co., Inc., Mitsubishi Corporation, Mitsui & Co., Ltd. Marubeni Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan coal market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan coal market.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan coal industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Coal Market Report
The Japan coal market size is estimated at 687.3 Thousand Tons in 2026, growing from 666.2 Thousand Tons in 2025, driven by coal's essential role in baseload power generation accounting for approximately one-third of Japan's electricity output, stable coking coal demand from integrated steelmakers, and Japan's energy security procurement strategy ensuring consistent import volumes from Australia, Indonesia, and other major exporting nations.
The market grows at 3.17% CAGR during 2026-2034, reaching 882.1 Thousand Tons by 2034. Power Station (Thermal Coal) grows at ~3.4% CAGR through ammonia co-firing program adoption. Coking Feedstock (Coking Coal) grows at ~2.8% CAGR anchored by blast furnace steelmaking demand. Others grow at ~2.1% CAGR from stable industrial coal consumption.
Power Station (Thermal Coal) leads at 65.0% through Japan's coal-fired power generation fleet operated by JERA, J-POWER, and regional utilities, which collectively contribute approximately one-third of national electricity generation output and provide essential baseload capacity supporting grid stability during Japan's renewable energy expansion.
Kanto Region leads at 25.0% through the Tokyo metropolitan area's concentration of coal-fired power plants, industrial manufacturing facilities, and Japan's highest electricity consumption density, requiring substantial coal-based baseload generation capacity to complement variable renewable sources and nuclear plants undergoing restart approvals.
Leading companies include J-POWER (Electric Power Development Co., Ltd.), JERA Co., Inc., Mitsubishi Corporation, Mitsui & Co., Ltd. and Marubeni Corporation, among others.
The Japan coal market is projected to reach 687.3 Thousand Tons in 2026, with continued demand from coal-fired power generation and metallurgical coal for steel production supported by Japan's energy security procurement commitments, partially offset by incremental renewable energy capacity additions improving the overall generation mix.
The market is projected to reach 778.6 Thousand Tons by 2030, supported by stable coking coal demand from Japan's steel industry and continued coal baseload power operation, with ammonia co-firing programs at JERA's Hekinan and other major coal plants moderating per-unit emission intensity while sustaining overall coal consumption volumes.
Ammonia co-firing involves combusting ammonia alongside coal in existing power plant boilers, reducing per-unit carbon emissions proportionate to the ammonia substitution ratio applied. Japan leads globally in commercial-scale ammonia co-firing, with JERA achieving 20% ammonia co-firing at Hekinan Thermal Power Station—the world's first large-scale commercial coal-ammonia co-firing operation. This technology extends coal plant operational life during Japan's energy transition, sustaining coal demand while systematically reducing the carbon emission intensity of coal-based electricity generation.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade