Japan Debt Collection Software Market Size, Share, Trends and Forecast by Component, Deployment Mode, Organization Size, End User, and Region, 2026-2034
Japan Debt Collection Software Market Size, Share, Trends & Forecast (2026-2034)
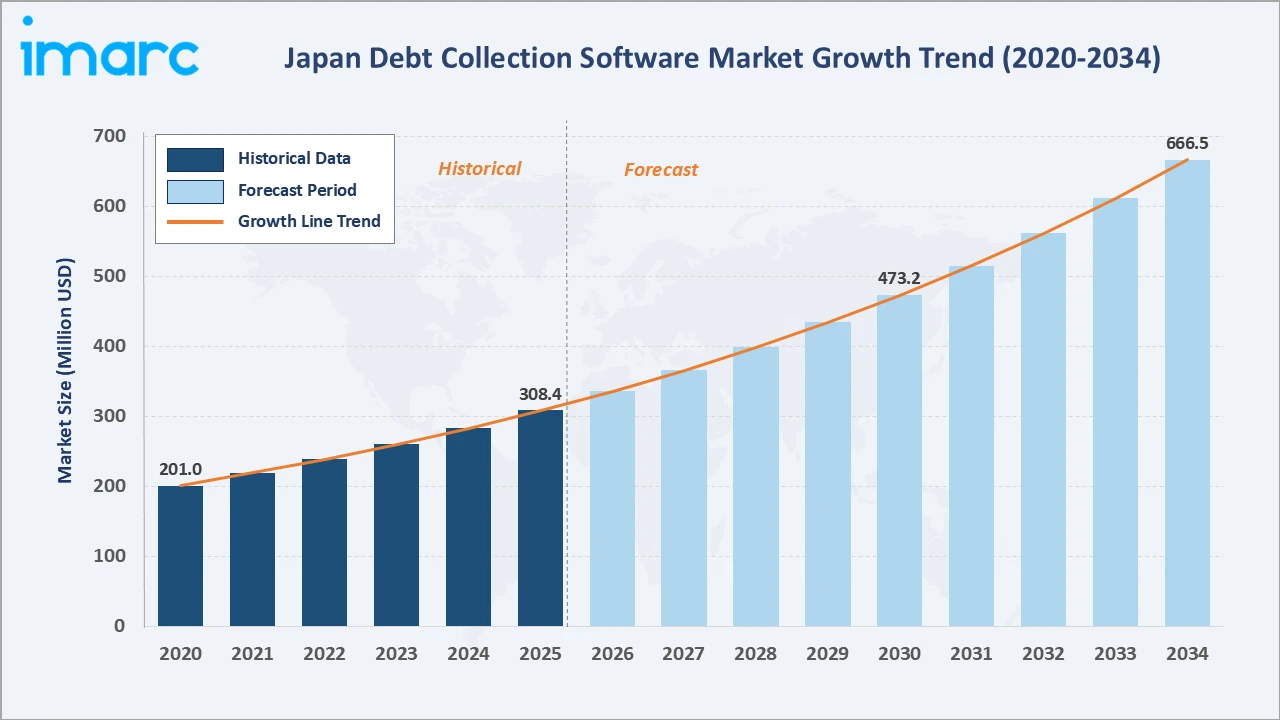
The Japan debt collection software market grew from USD 308.4 Million in 2025 to USD 336.0 Million in 2026 and is projected to reach USD 666.5 Million by 2034, growing at a CAGR of 8.94% during 2026-2034. Digital transformation in financial services, rising consumer credit, and the adoption of AI-driven automation are supporting strong growth. Financial institutions across Japan are increasingly replacing manual, phone-based processes with digital collection platforms, reflecting growing demand for automated receivables management.
Labor shortages, cashless payment growth, and pressure to improve recovery rates while treating customers fairly continue to broaden demand. Software dominates at 64.7%. Large enterprises lead organization size at 58.6%. The Kanto Region commands 38.5% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 308.4 Million |
|
Market Size (2026) |
USD 336.0 Million |
|
Forecast Market Size (2034) |
USD 666.5 Million |
|
CAGR (2026-2034) |
8.94% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Component |
Software (64.7%, 2025) |
|
Dominant Organization Size |
Large Enterprises (58.6%, 2025) |
|
Leading Region |
Kanto Region (38.5%, 2025) |
The Japan debt collection software market size increased from USD 201.0 Million in 2020 to USD 308.4 Million in 2025 and is estimated to reach USD 336.0 Million in 2026. The market is further expected to grow to USD 473.2 Million by 2030 and USD 666.5 Million by 2034. Growth reflec ts a steady shift from manual and legacy collection processes to cloud-based, automated platforms.
To get more information on this market, Request Sample
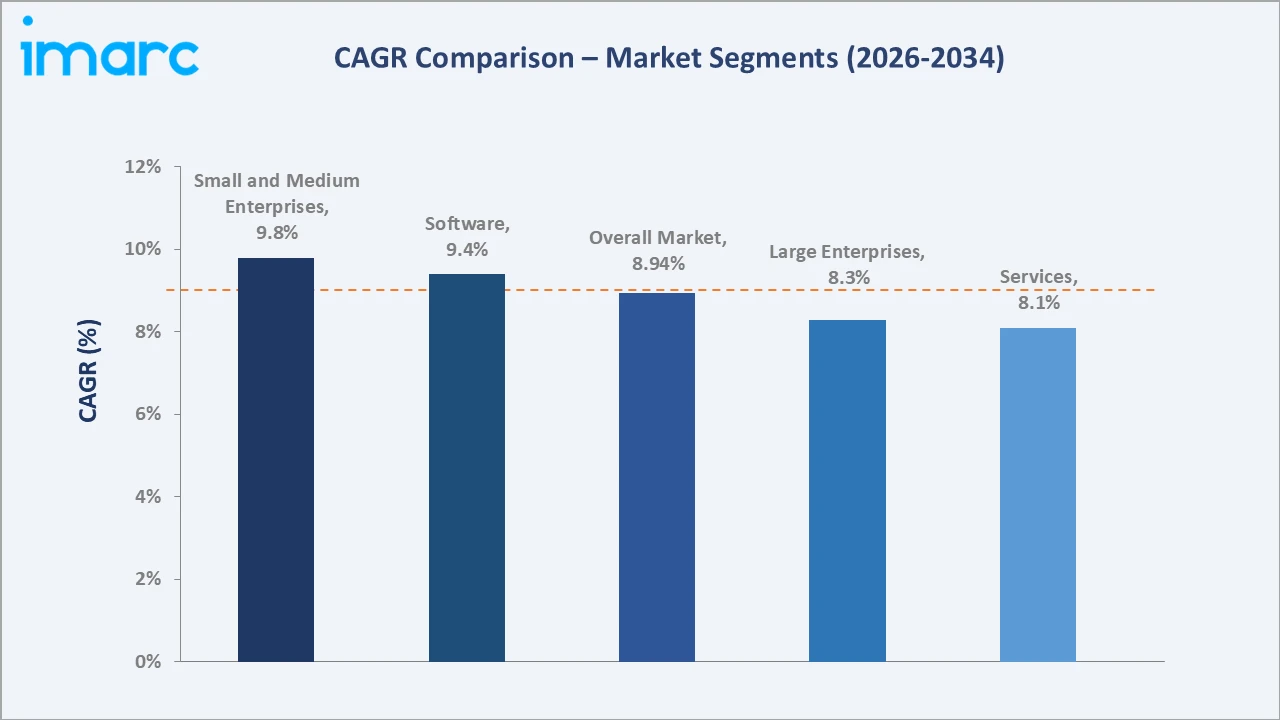
Small and medium enterprises are expected to grow fastest at ~9.8% CAGR, supported by affordable cloud and SaaS solutions. Software follows at ~9.4% CAGR as lenders and businesses replace legacy systems with automated, AI-enabled collection platforms.
Executive Summary
The Japan debt collection software market expanded from USD 308.4 Million in 2025 to an estimated USD 336.0 Million in 2026. Banks, card issuers, consumer lenders, servicers, and utilities are moving from paper-based and phone-heavy collection processes toward digital platforms that automate reminders, segment debtors, and offer self-service repayment options. Generative AI and analytics are improving efficiency while supporting fair and compliant customer treatment. The market is projected to reach USD 666.5 Million by 2034. Software at 64.7% leads as institutions invest in core platforms. Large enterprises at 58.6% lead adoption. The Kanto Region leads at 38.5%.
Key Market Insights
|
Insight |
Data |
|
Dominant Component |
Software - 64.7% share (2025) |
|
Dominant Organization Size |
Large Enterprises - 58.6% market share (2025) |
|
Leading Region |
Kanto Region - 38.5% share (2025) |
|
Market Opportunity |
Cloud and SaaS collection platforms for SMEs; generative AI negotiation tools; digital self-service repayment portals; integration with cashless payment ecosystems |
Key Analytical Observations Supporting the Above Data:
- Software at 64.7%: Software dominates because collection platforms, decision engines, and workflow tools form the core of every digital collection operation. Institutions are replacing legacy in-house systems with configurable platforms that automate communication, prioritize accounts, and integrate payment options.
- Large Enterprises at 58.6%: Large enterprises lead because major banks, card companies, consumer finance firms, and telecom operators manage large volumes of receivables and have the budgets to invest in comprehensive, integrated collection solutions.
- Kanto Region at 38.5%: The Kanto Region leads due to the concentration of financial institutions, fintech companies, and corporate headquarters in Tokyo and surrounding prefectures.
Japan Debt Collection Software Market Overview
Debt collection software helps organizations manage overdue receivables by automating reminders, scheduling, segmentation, payment arrangements, and reporting. In Japan, users include banks, credit card companies, consumer finance companies, servicers, utilities, telecom operators, and businesses managing trade receivables.
The industry ecosystem links software vendors, system integrators, data and payment partners, cloud and AI providers, regulators, and end users. Macroeconomic factors include consumer credit growth, interest rates, household finances, cashless payment adoption, and labor availability, all of which shape demand for automated collection tools.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
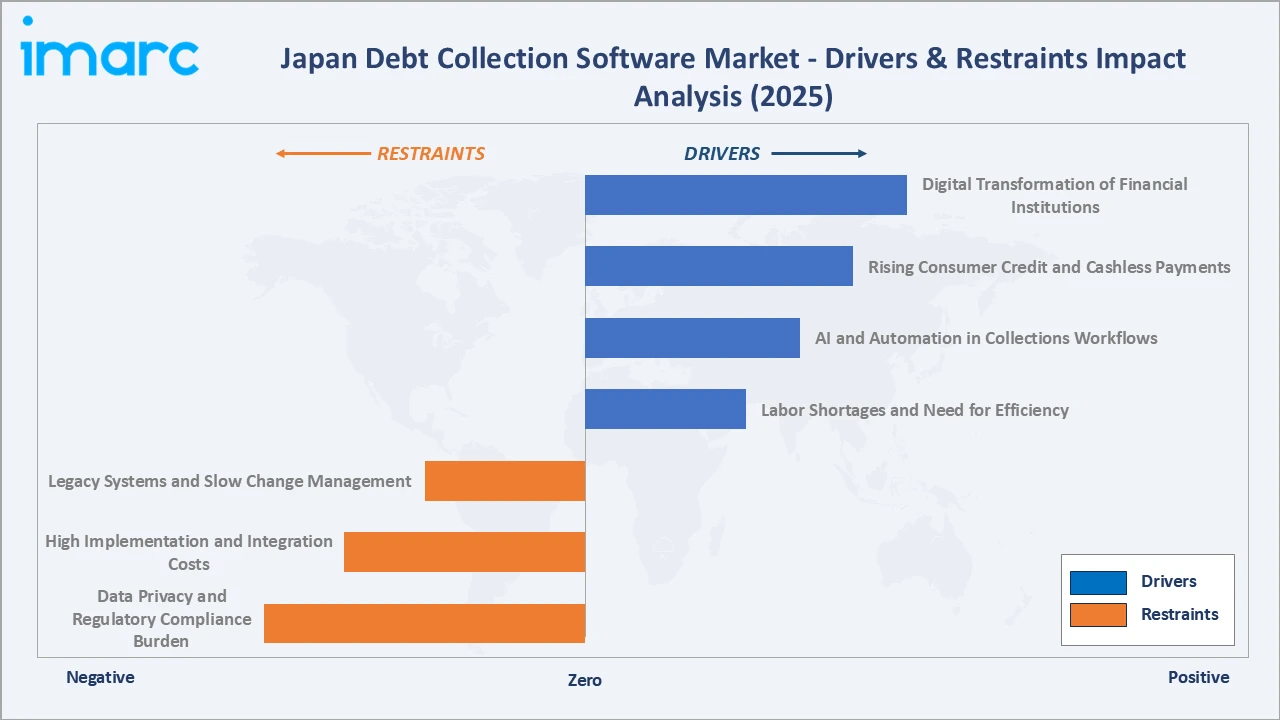
- Digital Transformation of Financial Institutions: Japanese banks, credit card companies, and consumer lenders are modernizing legacy systems and moving core processes to digital platforms. Collection operations are a priority area because manual, paper-based, and phone-heavy processes are costly and slow. Modern software allows institutions to automate routine tasks, standardize workflows, and gain real-time visibility into overdue accounts. Government initiatives promoting digital finance and paperless operations are also encouraging institutions to modernize back-office processes, and collections teams increasingly need dashboards that link delinquency data with customer service, risk, and finance functions.
- Rising Consumer Credit and Cashless Payments: The growth of credit cards, buy-now-pay-later services, smartphone payments, and online lending is increasing the number of accounts that require monitoring and collection. Higher transaction volumes and more diverse credit products create demand for scalable software that can manage large portfolios efficiently. Rising use of installment payments for smartphones, appliances, and online purchases also expands the base of small-balance accounts that are costly to manage manually. Fintech lenders entering the market need modern collection tools from day one. Growth in corporate trade credit and subscription-based business models is also increasing demand for automated receivables management outside the financial sector.
- AI and Automation in Collections Workflows: Artificial intelligence, machine learning, and generative AI are helping organizations predict which customers are likely to miss payments, choose the best contact channel and timing, and automate repayment conversations. These capabilities improve recovery rates while reducing the workload on collection staff. AI-supported quality monitoring also helps managers review conversations, detect compliance risks, and coach staff more effectively. As models improve, organizations expect further gains in accuracy and efficiency. Speech analytics in call centers is also helping organizations understand customer situations and improve conversation outcomes.
- Labor Shortages and Need for Efficiency: Japan’s shrinking working-age population makes it harder for financial institutions and servicers to staff collection teams. Automation, self-service portals, and digital communication help organizations maintain service levels and recovery performance with fewer staff. Remote work options supported by cloud platforms also help organizations retain experienced staff and access talent across regions. Automation of routine reminders allows remaining staff to focus on complex and sensitive cases. Aging collection staff and retirements are adding urgency to capture expertise in standardized digital workflows.
Market Restraints
- Data Privacy and Regulatory Compliance Burden: Collection activities in Japan are governed by strict rules on lending, servicing, and personal information protection. Software must support compliant communication practices, consent management, and secure data handling, which increases development and implementation costs. Organizations must also keep detailed records of communications, which requires robust audit trails and reporting features. Changes to regulations can require frequent system updates. Vendors with deep knowledge of Japanese rules and practices therefore have an advantage over new entrants.
- High Implementation and Integration Costs: Integrating new collection platforms with core banking, card, and accounting systems can be complex and expensive. Smaller organizations may lack the budgets and in-house expertise needed for large implementations. Long project timelines and the need to migrate historical data can delay benefits, making some organizations cautious about large-scale replacements. Customization requirements unique to each institution can further raise costs and limit the use of standard products.
- Legacy Systems and Slow Change Management: Many Japanese institutions rely on long-established mainframe and custom-built systems. Organizational caution, approval processes, and staff habits can slow the replacement of these systems with modern platforms. Concerns about operational risk during system transitions often lead institutions to adopt phased approaches that extend implementation timelines. Limited availability of skilled IT staff in some regions also slows modernization efforts.
Market Opportunities
- Cloud and SaaS Platforms for SMEs: Affordable cloud-based collection tools allow small and medium businesses, regional banks, and new lenders to automate receivables management without large upfront investment. Subscription pricing and standardized templates make it easier for smaller organizations to start with core features and expand over time. Partnerships with accounting software and payment providers can extend reach to thousands of smaller businesses.
- Digital Self-Service and Customer-Centric Collections: Online portals, chat, and app-based repayment options allow customers to resolve overdue balances discreetly and at their convenience, improving recovery and customer experience. Customers who prefer not to speak with collectors are more likely to engage through digital channels, increasing contact rates and promised payments. Self-service options also support customers facing temporary financial difficulty by offering flexible repayment plans.
Market Challenges
- Balancing Automation with Fair Treatment: Organizations must ensure that automated communications are respectful, accurate, and compliant, especially when dealing with vulnerable customers. Poorly designed automation can damage customer relationships and brand reputation. Clear guidelines, human oversight, and regular review of automated messages are essential to maintain trust and compliance. Training staff to work alongside AI tools is equally important for consistent customer outcomes.
- Data Quality and System Fragmentation: Collection performance depends on accurate, up-to-date customer and account data. Fragmented systems and inconsistent data across departments can limit the effectiveness of analytics and automation. Investments in data governance and integration are therefore becoming a prerequisite for advanced collection strategies. Cleaner data also supports better regulatory reporting and management decision-making.
Emerging Market Trends
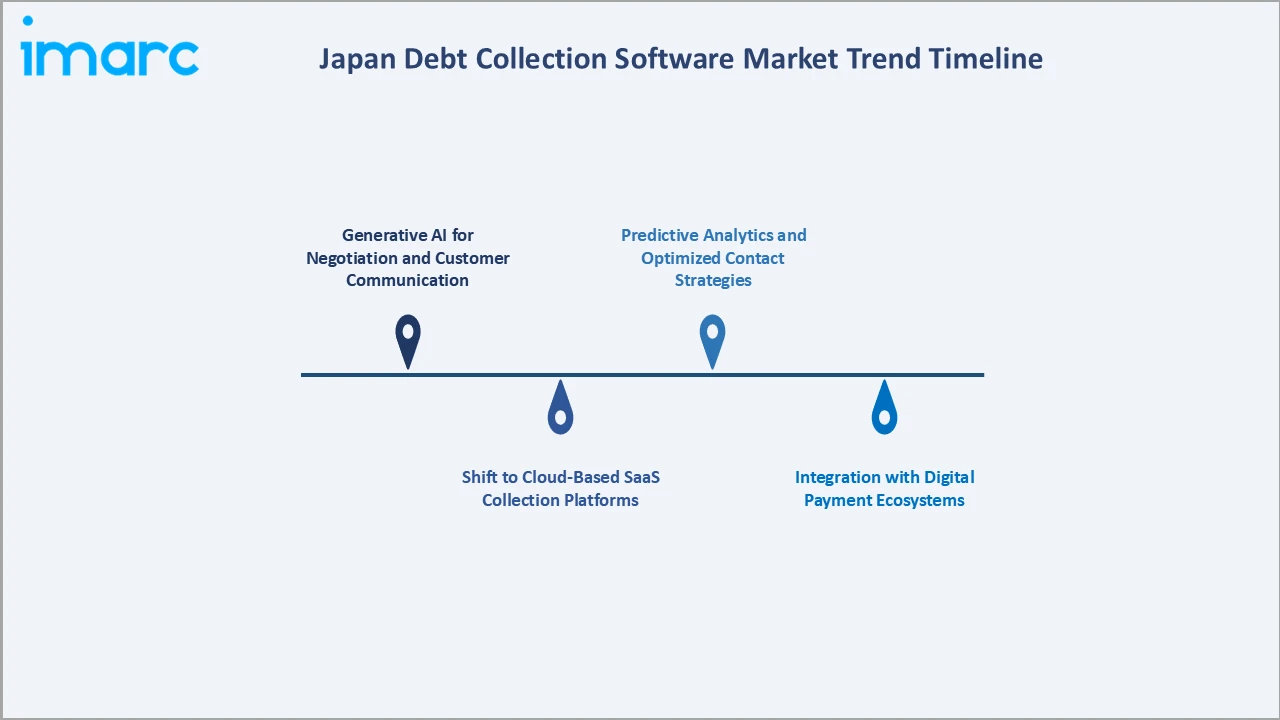
1. Generative AI for Negotiation and Customer Communication
Collection platforms are adding generative AI to draft personalized messages, answer debtor questions, and support repayment consultations through chat. These tools help organizations handle large volumes of conversations consistently while freeing staff to focus on complex cases. Japanese language capabilities and culturally appropriate communication styles are important factors in selecting AI solutions for the domestic market. Integration with existing call center systems allows smooth handover from AI to human agents when needed.
2. Shift to Cloud-Based SaaS Collection Platforms
Organizations are moving from on-premise systems to cloud-based platforms that can be deployed quickly, updated continuously, and scaled as portfolios grow. SaaS models lower upfront costs and make advanced capabilities accessible to regional banks, fintech lenders, and smaller businesses. Continuous updates also allow users to benefit quickly from new features such as AI tools and payment integrations. Cloud adoption in Japan’s financial sector has accelerated as security standards and regulatory guidance have matured.
3. Predictive Analytics and Optimized Contact Strategies
Predictive models are being used to segment debtors, estimate the likelihood of repayment, and automatically generate optimized dunning schedules. Organizations can focus resources on accounts where intervention is most effective and reduce unnecessary contact. Organizations can also test different strategies and measure their impact, gradually improving collection outcomes over time. Early-stage intervention strategies also help customers avoid serious delinquency and preserve long-term relationships.
4. Integration with Digital Payment Ecosystems
Collection software is increasingly connected to smartphone payment apps, online banking, and convenience store payment networks, allowing customers to repay instantly from a reminder message. Seamless payment integration shortens recovery times and improves the customer experience. Real-time payment confirmation also allows systems to stop further reminders immediately, avoiding customer frustration. Integration with convenience store payment networks remains particularly important in Japan for customers who prefer cash payments.
Industry Value Chain Analysis
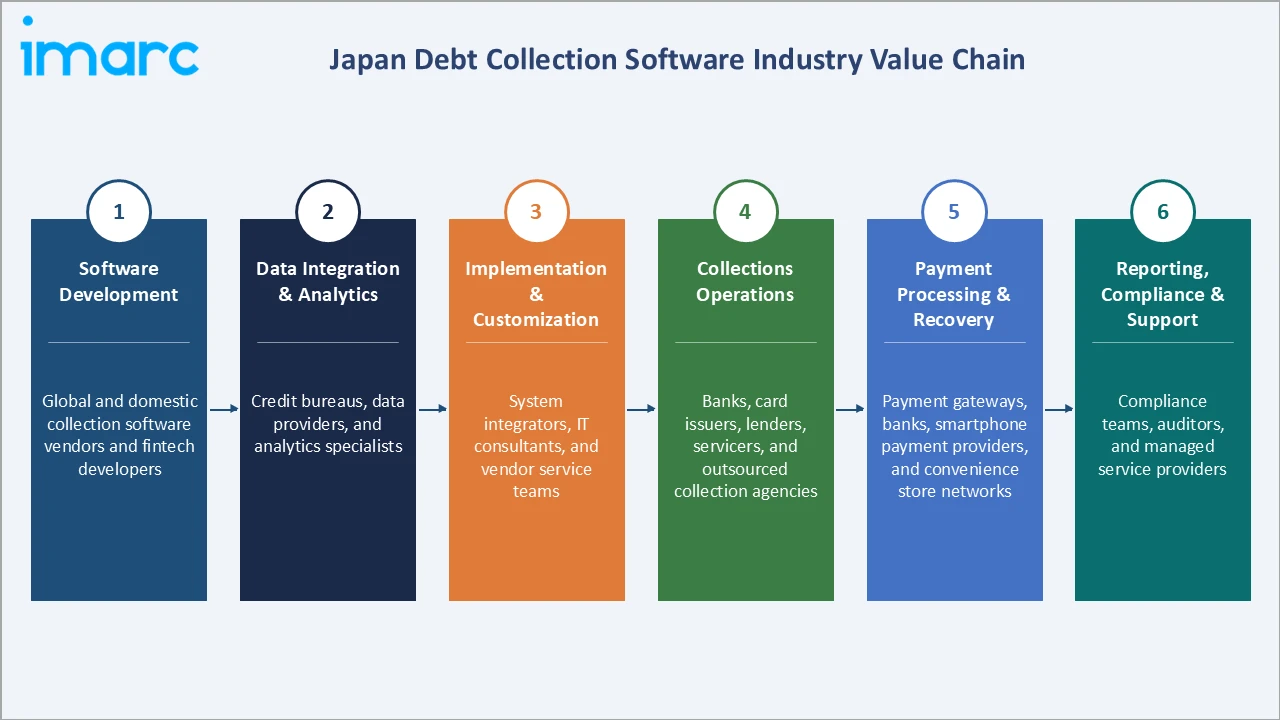
The Japan debt collection software value chain spans software development, data integration and analytics, implementation and customization, collections operations, payment processing and recovery, and reporting, compliance, and support. Value is concentrated in platform capabilities, data, and integration expertise. Long-term service and support relationships also generate recurring revenue for vendors and integrators. Payment and data partners also play a growing role as collection journeys become more digital and connected.
|
Stage |
Key Participants |
|
Software Development |
Global and domestic collection software vendors and fintech developers |
|
Data Integration & Analytics |
Credit bureaus, data providers, and analytics specialists |
|
Implementation & Customization |
System integrators, IT consultants, and vendor service teams |
|
Collections Operations |
Banks, card issuers, lenders, servicers, and outsourced collection agencies |
|
Payment Processing & Recovery |
Payment gateways, banks, smartphone payment providers, and convenience store networks |
|
Reporting, Compliance & Support |
Compliance teams, auditors, and managed service providers |
Implementation and customization is the most consequential stage of the chain. Successful integration with core banking, card, and accounting systems determines how quickly organizations realize the benefits of new software, making system integrators and experienced vendor teams critical partners. Clear project governance and experienced vendor teams help reduce risks during migration from legacy systems. Post-implementation optimization services help organizations continuously improve strategies and results.
Technology Landscape in the Japan Debt Collection Software Industry
Cloud-Based Collection Platforms
Cloud platforms deliver collection workflows, debtor management, and reporting through secure online environments. They support rapid deployment, automatic updates, and flexible scaling, and they enable remote access for collection teams. Strong security certifications and data residency options within Japan are important for winning financial sector customers.
Artificial Intelligence and Machine Learning
AI and machine learning models predict payment behavior, prioritize accounts, and recommend actions. Generative AI supports chat-based negotiation, automated message drafting, and quality monitoring of customer interactions. Explainable models help organizations meet internal governance and regulatory expectations for automated decisions.
Omnichannel Communication and Payment Integration
Modern platforms coordinate communication across email, SMS, messaging apps, voice, and web portals, and link directly to payment services. This allows customers to receive reminders and complete repayments in a single, convenient journey. Secure identity verification and electronic agreements allow customers to set up repayment plans online without visiting branches or mailing documents. Unified communication histories give collectors a complete view of each customer interaction across channels.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Component | Software | 64.7% | 2025 |
| Deployment Mode | 🔒 | 🔒 | 2025 |
| Organization Size | Large Enterprises | 58.6% | 2025 |
| End User | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 38.5% | 2025 |

By Component
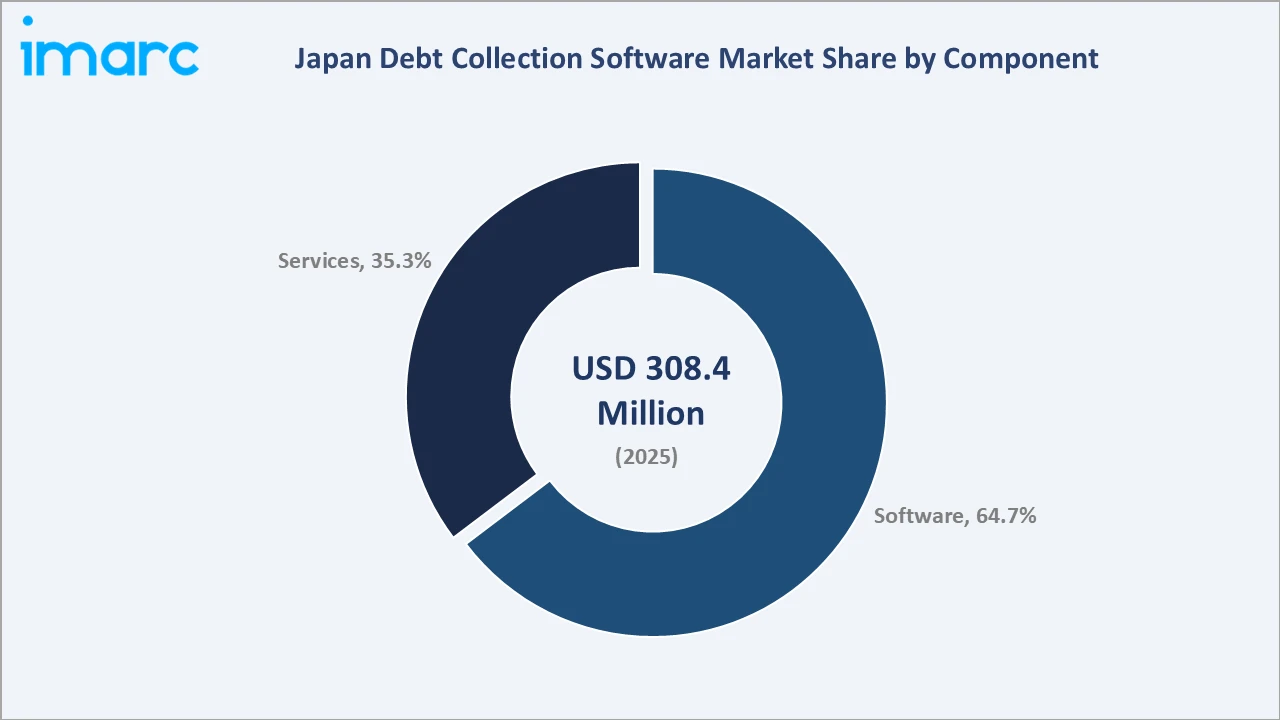
Software leads at 64.7% (2025). Collection platforms, decision engines, and workflow tools form the core of digital collection operations, and institutions are investing in configurable, cloud-ready software to replace legacy systems. Modular platforms allow organizations to add new capabilities, such as AI or self-service portals, without replacing entire systems. Configurable rules engines also allow business users to update collection strategies without extensive IT support.
To access detailed market analysis, Request Sample
Services at 35.3% are growing at ~8.1% CAGR, supported by implementation, integration, consulting, training, and managed services that help organizations deploy and optimize collection platforms. Ongoing support and managed services are growing as organizations seek to maximize returns from their software investments.
By Organization Size
Large enterprises lead at 58.6% (2025). Major banks, card issuers, consumer lenders, and telecom operators manage large receivable portfolios and invest in comprehensive, integrated collection platforms with advanced analytics. These organizations also tend to adopt AI tools earlier because of their large data volumes and dedicated technology teams. Large enterprises also require strong security, scalability, and integration with multiple internal systems, favoring established vendors.
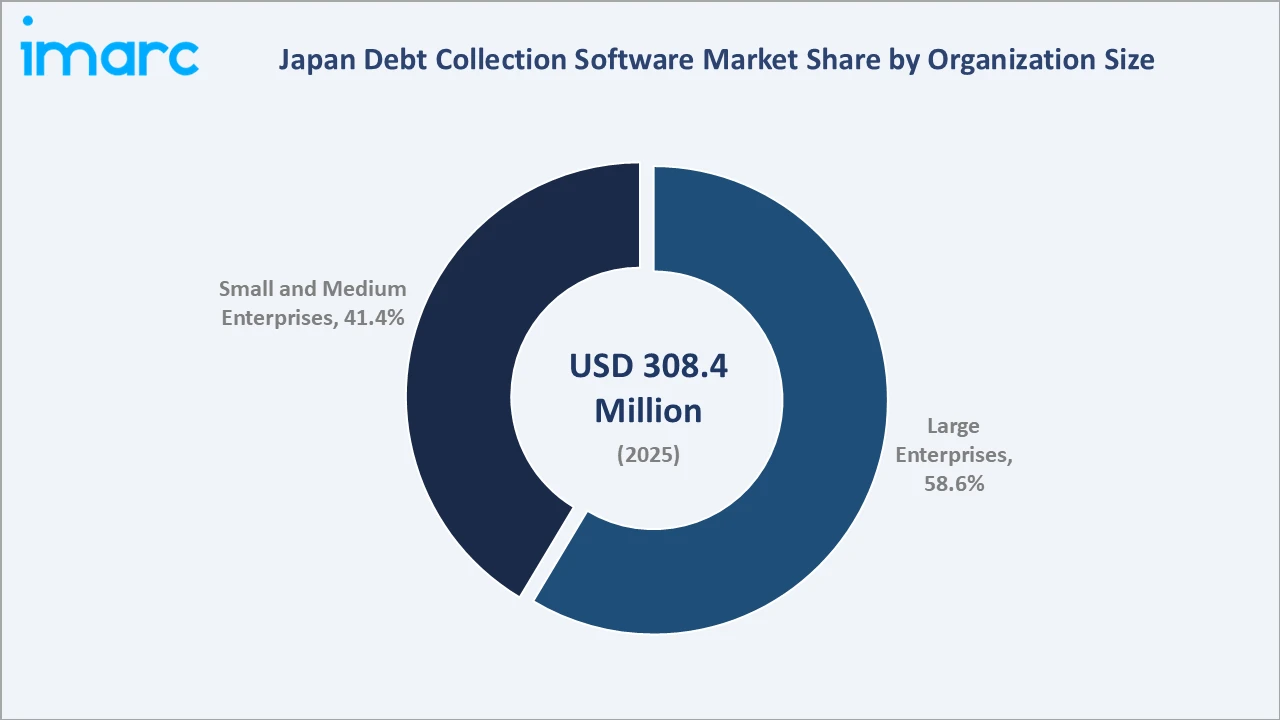
Small and medium enterprises at 41.4% are growing fastest at ~9.8% CAGR, as affordable SaaS tools make automated receivables management accessible to regional banks, fintech lenders, and smaller businesses. Simple user interfaces and quick deployment make these tools attractive to organizations with limited IT resources. Many SMEs are moving from spreadsheets and manual reminders to automated platforms for the first time.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Debt Collection Software Market Drivers & Characteristics |
|
Kanto Region |
38.5% |
Headquarters of major banks, card companies, and fintech firms in Tokyo. |
|
Kansai/Kinki Region |
18.7% |
Large financial and commercial base in Osaka, Kyoto, and Kobe. |
|
Central/Chubu Region |
14.2% |
Strong manufacturing economy and regional banks around Nagoya. |
|
Kyushu-Okinawa Region |
9.6% |
Growing regional banks and fintech adoption in Fukuoka. |
|
Tohoku Region |
6.8% |
Regional banks modernizing systems across Sendai and surrounding areas. |
|
Chugoku Region |
5.1% |
Regional financial institutions in Hiroshima and Okayama. |
|
Hokkaido Region |
4.2% |
Regional banks and credit unions centered in Sapporo. |
|
Shikoku Region |
2.9% |
Smaller regional banks gradually adopting digital tools. |
The Kanto Region's 38.5% market leadership reflects the concentration of banks, card issuers, consumer lenders, and fintech companies in Tokyo. The Kansai/Kinki Region's 18.7% reflects a large financial and commercial base in Osaka, Kyoto, and Kobe, and the Central/Chubu Region's 14.2% reflects strong regional banks around Nagoya. Many regional institutions in these areas are actively modernizing systems to improve efficiency and customer service. Strong economic activity in these regions supports demand from consumer finance companies, utilities, and businesses managing trade receivables.
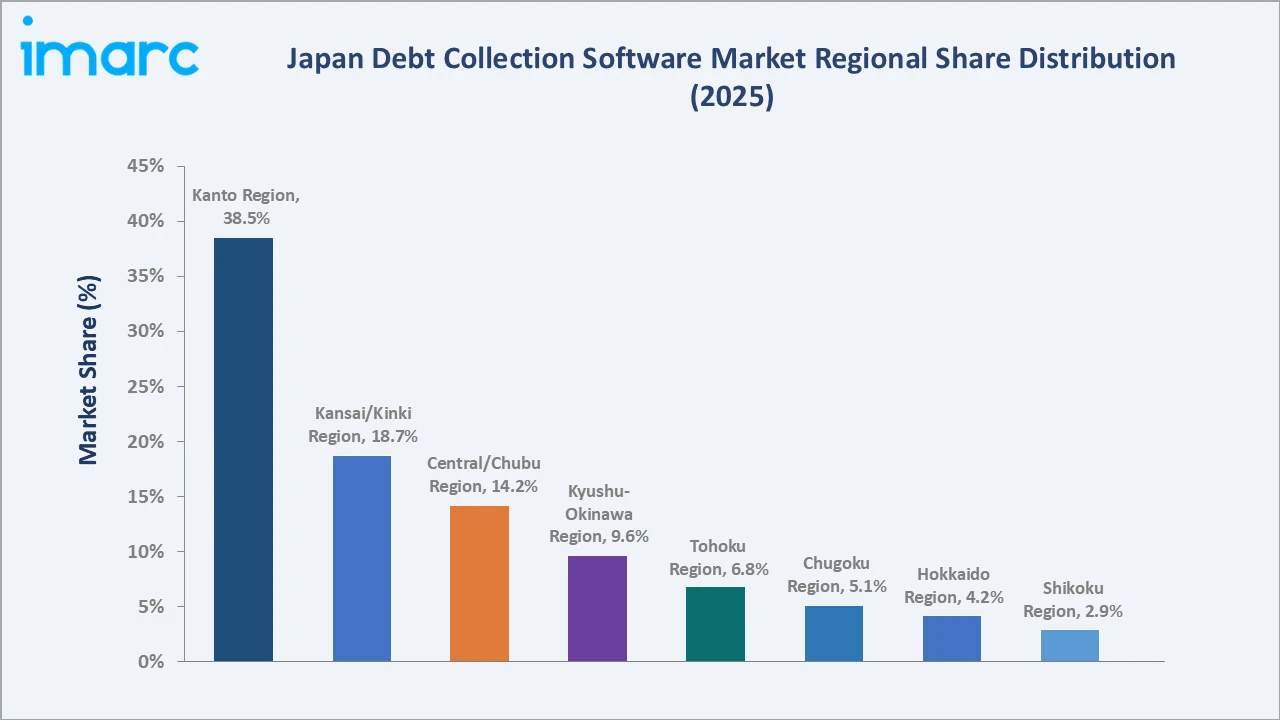
The Kyushu-Okinawa Region at 9.6% and the Tohoku Region at 6.8% are growing as regional banks modernize. The Chugoku Region at 5.1%, Hokkaido Region at 4.2%, and Shikoku Region at 2.9% are smaller but adopting cloud-based tools. Regional bank consolidation and digitalization programs are expected to support steady growth across these regions over the forecast period.
Competitive Landscape
The Japan debt collection software market includes global collection and decisioning software providers, large Japanese IT service companies, and domestic fintech firms. Competition centers on platform capabilities, AI and analytics, integration with core systems, regulatory compliance, and local support. Partnerships between global vendors and Japanese system integrators are common, combining international technology with local implementation expertise. Domestic fintech firms differentiate with Japanese-specific features, quick deployment, and close integration with local payment networks. Service quality, Japanese-language support, and responsiveness remain decisive in vendor selection.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Credit Engine, Inc. | Credit Engine Collection Service | Innovator | Japan-focused digital collection SaaS with AI features. |
| Experian | PowerCurve Collections, Tallyman, Experian | Market Leader | Data-driven decisioning and analytics for collections. |
| Robot Payment Inc. | Debt Collection Robot | Strong Challenger | Automated multi-channel dunning for businesses and lenders. |
| Pegasystems Inc. | Pega Collections | Innovator | AI-driven workflow and collections orchestration. |
| Hitachi Systems, Ltd. | Digital Credit Management System (DCMS), Digital Collection and Recovery System | Strong Challenger | AI-driven dunning optimization for credit card companies. |
| CGI Inc. | CGI Credit Studio for Collections | Strong Challenger | Established collections software for lenders. |
The most important competitive dynamic is the shift from on-premise, custom-built systems to cloud-based, AI-enabled platforms. Vendors with strong local implementation partners and compliance expertise are best placed to win projects with Japanese financial institutions.
Key Company Profiles
Credit Engine, Inc.
Credit Engine, Inc. is a financial technology company specialising in digital lending and debt management solutions. The company develops software platforms that help financial institutions, businesses, and law firms streamline loan management, debt collection, and related financial operations.
- Key Brands: Credit Engine Collection Service
- Recent Developments: In January 2026, Credit Engine added a new feature to CE Collection that allows individual emails to be sent to and received from debtors.
- Strategic Focus: Expanding adoption among banks, including PayPay Bank’s selection of CE Collection and CE Loan Personal in October 2025.
Pegasystems Inc.
Pegasystems Inc. offers Pega Collections, which uses AI-driven workflows and engagement strategies to help organizations resolve collections across assisted and digital channels.
- Key Brands: Pega Collections.
- Recent Developments: In July 2026, Pegasystems made Pega Infinity 26 generally available, adding agentic AI capabilities that allow companies to orchestrate AI agents within governed workflows.
- Strategic Focus: Combining predictable AI agents with workflow automation for collections and customer service.
Experian
Experian offers PowerCurve Collections, which uses data and analytics to personalize the collections process and recover debt while preserving customer relationships.
- Key Brands: PowerCurve Collections, Tallyman, Experian
- Recent Developments: In October 2026, Experian launched Experian Cashflow Data Bureau, a consumer reporting agency designed to expand access to credit.
- Strategic Focus: Expanding data-driven decisioning across the credit lifecycle, from origination to collections.
Market Concentration Analysis
The Japan debt collection software market is moderately fragmented. Large Japanese IT service providers hold strong positions with major banks, global software vendors compete for advanced analytics and decisioning projects, and domestic fintech firms are gaining share with cloud-based solutions.
Market concentration is evolving through two opposing forces: large institutions consolidate spending with established partners, while affordable SaaS platforms and fintech entrants expand competition among small and medium organizations. Partnerships and acquisitions, such as the integration of fintech firms into larger payment groups, are also reshaping the competitive landscape. Vendors that combine strong local partnerships with modern cloud and AI capabilities are expected to gain the most share.
Investment & Growth Opportunities
Highest Growth Segments
Small and medium enterprises (~9.8% CAGR through SaaS adoption), software (~9.4% CAGR through platform modernization), Kyushu-Okinawa Region (~9.6% CAGR through regional bank digitalization), and Hokkaido Region (~9.2% CAGR through cloud adoption) represent the highest-growth investment areas through 2034.
Emerging Investment Opportunities
Generative AI tools for collections communication are among the most promising opportunities. Solutions that automate respectful, compliant conversations and integrate instant payment options can significantly improve recovery efficiency. Analytics services that help organizations benchmark and optimize performance also offer attractive recurring revenue potential.
Investment Themes
- Cloud collection platforms for regional banks: Regional institutions need affordable, compliant tools to modernize legacy systems.
- Payment-integrated self-service: Linking reminders to smartphone payments improves recovery and customer experience.
Future Market Outlook (2026-2034)
The Japan debt collection software market is projected to grow from USD 308.4 Million in 2025 to USD 336.0 Million in 2026, reaching USD 666.5 Million by 2034, registering a CAGR of 8.94% during 2026-2034. The anchor value of USD 473.2 Million in 2030 marks a point at which cloud and AI-enabled platforms should be standard across major lenders. By then, generative AI communication and payment-integrated self-service should also be widely used across the market.
Three structural forces define Japan debt collection software market growth through 2034 digital transformation of financial services; growth in consumer credit and cashless payments; and the need to automate operations amid labor shortages. Together, these forces support steady growth across components, organization sizes, and regions over the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including software vendors, system integrators, bank and card company collection managers, servicers, and fintech executives, along with inputs from all major regions of Japan.
Secondary Research
Secondary research covered company websites and press releases, financial regulator publications, consumer credit statistics, and industry reports. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets.
Forecasting Models
Market revenue forecasts were developed using a demand-based model: number of organizations by size and region multiplied by adoption rates and average spending on software and services, with segment results aggregated to total market value. Assumptions were validated through detailed discussions with experienced industry experts, vendors, system integrators, and collection managers across all major regions of Japan today.
Japan Debt Collection Software Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Software, Services |
| Deployment Modes Covered | On-Premises, Cloud-Based |
| Organization Sizes Covered | Small and Medium Enterprises, Large Enterprises |
| End Users Covered | Financial Institutions, Collection Agencies, Healthcare, Government, Telecom and Utilities, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Credit Engine, Inc., Experian, Robot Payment Inc., Pegasystems Inc., Hitachi Systems, Ltd., CGI Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan debt collection software market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan debt collection software market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan debt collection software industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Debt Collection Software Market Report
The Japan debt collection software market size is estimated at USD 336.0 Million in 2026, supported by digital transformation and AI adoption in collections.
The market grows at 8.94% CAGR during 2026-2034, reaching USD 666.5 Million by 2034.
Software leads at 64.7%, as institutions invest in core collection platforms.
Large enterprises lead at 58.6%, owing to large receivable portfolios and larger technology budgets.
The Kanto Region leads at 38.5%, driven by the concentration of financial institutions in Tokyo.
Leading companies include Credit Engine, Inc., Experian, Robot Payment Inc., Pegasystems Inc., Hitachi Systems, Ltd., and CGI Inc., among others.
The market is projected to reach approximately USD 473.2 Million by 2030.
Key trends include generative AI for debtor communication, cloud SaaS platforms, predictive contact strategies, and payment ecosystem integration.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade