
Japan Golf Cart Market Size, Share, Trends and Forecast by Product Type, Seating Capacity, Application, and Region, 2026-2034
Japan Golf Cart Market Size, Share, Trends & Forecast (2026-2034)
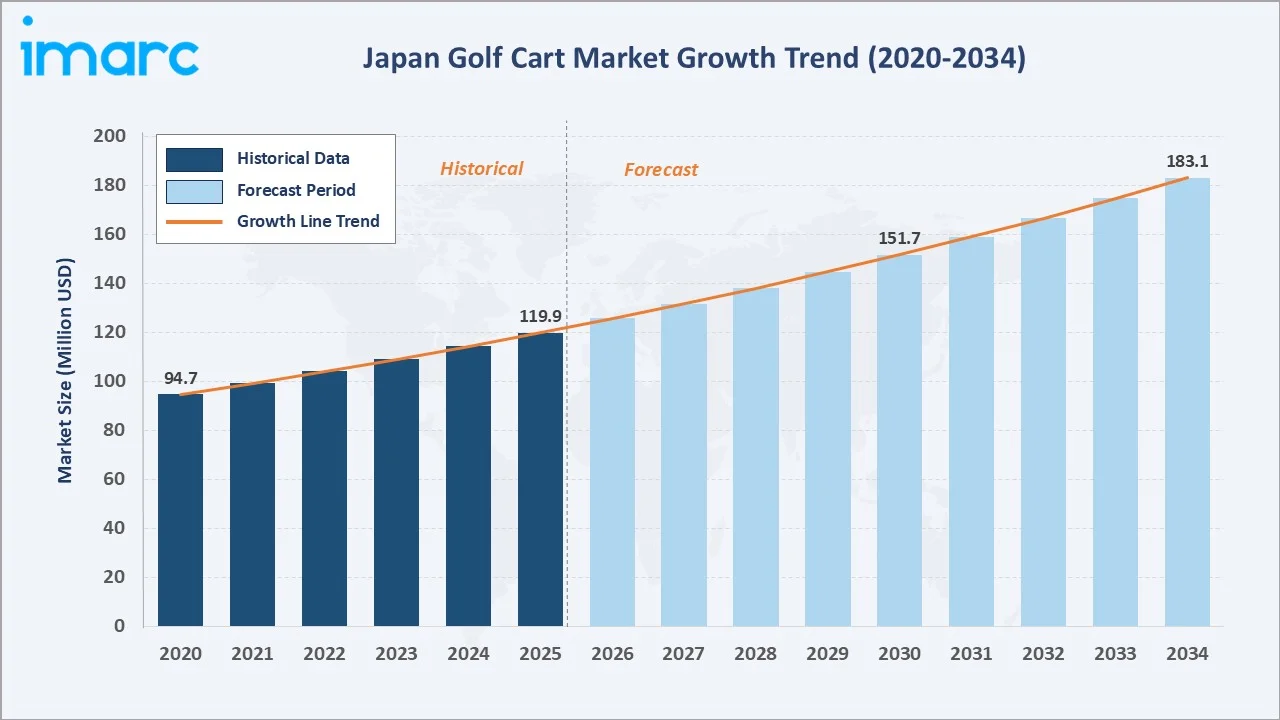
The Japan golf cart market grew from USD 119.9 Million in 2025 to USD 125.7 Million in 2026 and is projected to reach USD 183.1 Million by 2034, expanding at a CAGR of 4.82% during 2026-2034. Accelerating fleet electrification driven by government clean mobility incentives and sustainability mandates from golf course operators is reshaping product demand across the market.
Electric golf cart dominates the product type segment at 72.8%, golf course leads the application segment at 63.5%, and Kanto Region commands 34.7% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 119.9 Million |
|
Market Size (2026) |
USD 125.7 Million |
|
Forecast Market Size (2034) |
USD 183.1 Million |
|
CAGR (2026-2034) |
4.82% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Kanto Region (34.7%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (21.6%, 2025) |
|
Leading Product Type |
Electric Golf Cart (72.8%, 2025) |
|
Leading Application |
Golf Course (63.5%, 2025) |
The Japan golf cart market size increased from USD 94.7 Million in 2020 to USD 119.9 Million in 2025 and is estimated to reach USD 125.7 Million in 2026. The market is further expected to grow to USD 151.7 Million by 2030 and USD 183.1 Million by 2034, supported by fleet electrification, government green mobility programs, and rising demand from the hospitality and resort sectors across Japan.
To get more information on this market, Request Sample
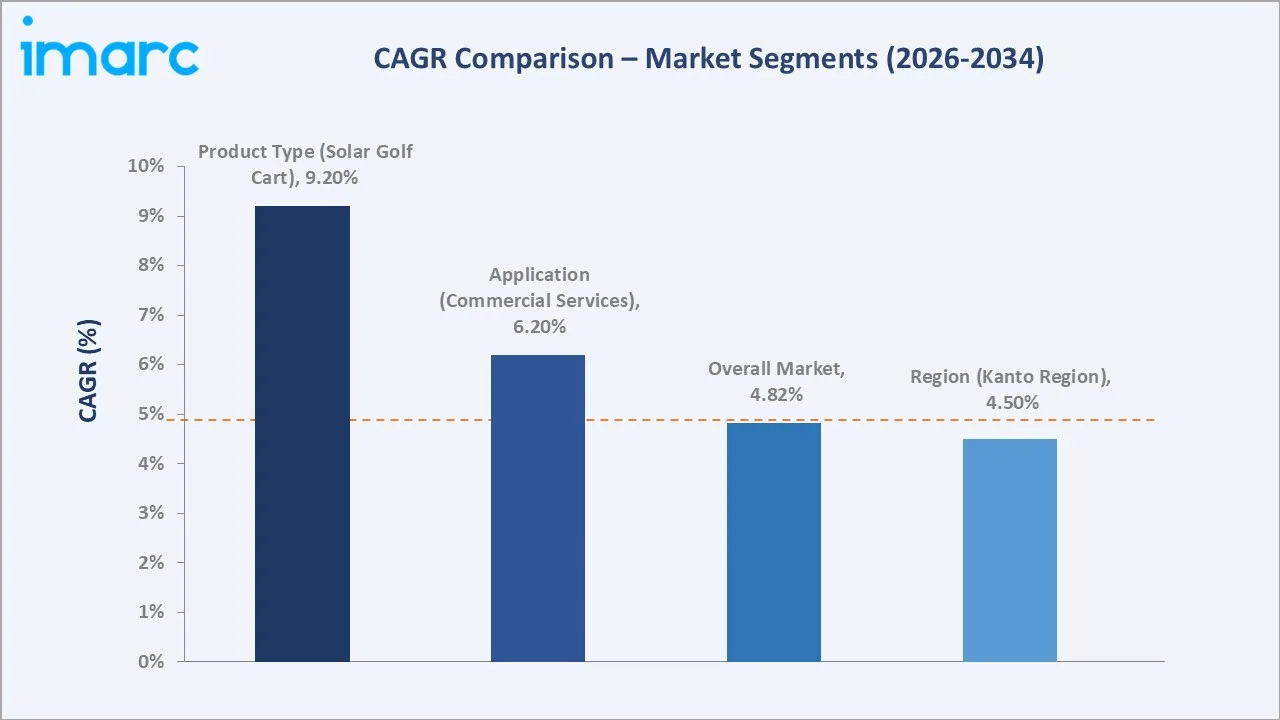
CAGR trajectories across product type and application sub-segments, together with regional patterns, show solar golf cart and commercial services expanding faster than the overall 4.82% market CAGR. This trend is driven by evolving mobility requirements, sustainability initiatives, and the growing use of golf carts across recreational and commercial settings.
Executive Summary
The Japan golf cart market expanded steadily from USD 119.9 Million in 2025 to an estimated USD 125.7 Million in 2026, positioning it among Asia's most structured and mature golf cart markets. A deeply rooted golf culture, competitive domestic manufacturers, and rising recreational demand are reshaping the industry.
Based on product type, electric golf cart commands a 72.8% share in 2025, driven by lower operating costs and growing demand for energy efficient mobility. Golf course retains a 63.5% application share, fueled by widespread golf course infrastructure and consistent demand for golf course transportation. Kanto Region leads regionally with 34.7%, supported by its strong concentration of golf facilities and established recreational infrastructure.
Key Market Insights
|
Insight |
Data |
|
Leading Product Type |
Electric Golf Cart – 72.8% share (2025) |
|
Second Largest Product Type |
Gasoline Golf Cart – 21.4% share (2025) |
|
Leading Application |
Golf Course – 63.5% share (2025) |
|
Second Largest Application |
Commercial Services – 23.4% share (2025) |
|
Leading Region |
Kanto Region – 34.7% share (2025) |
|
Second Largest Region |
Kansai/Kinki Region – 21.6% share (2025) |
|
Top Companies |
Yamaha Motor Co., Ltd., Textron Inc., Club Car LLC |
Key Analytical Observations Expanding On the Data Above:
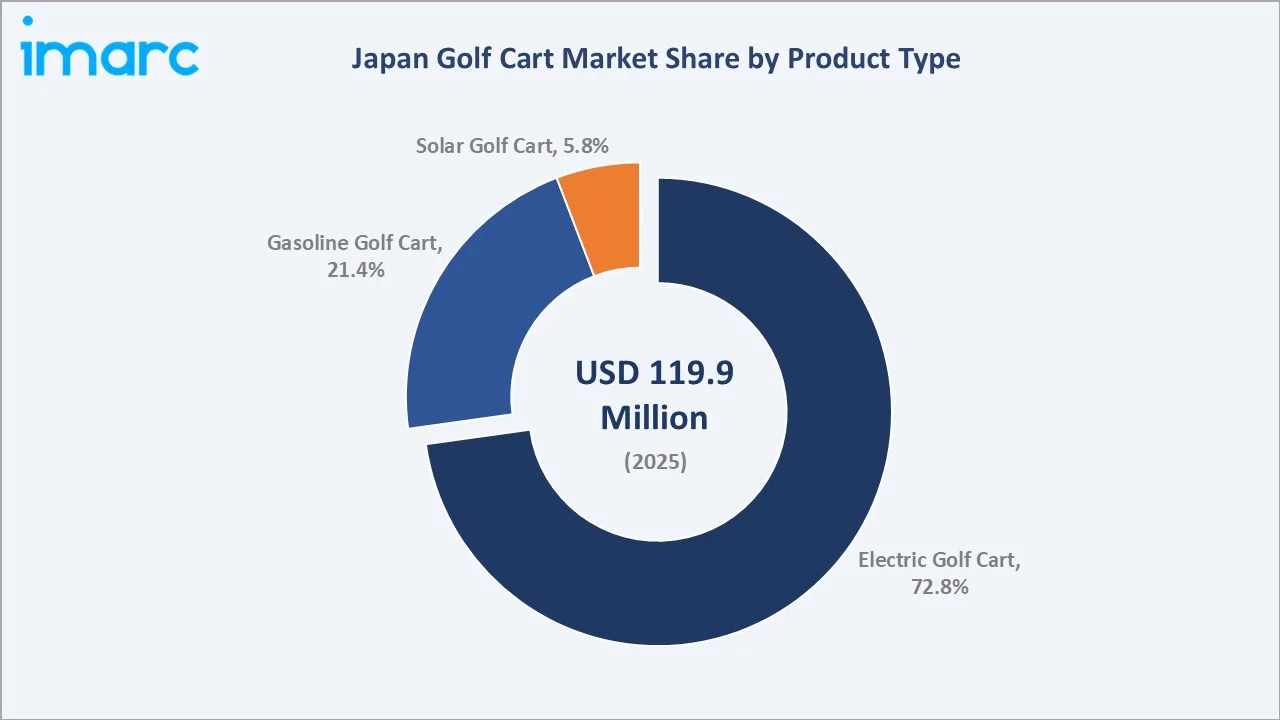
- Electric golf cart dominance at 72.8% reflects Japan's progressive fleet electrification across golf courses and commercial operators, supported by government incentive programs and declining battery acquisition costs.
- Gasoline golf cart at 21.4% highlights continued demand for conventional powertrains among users prioritizing established refueling infrastructure and operational flexibility. These models remain suitable for applications requiring extended usage periods and dependable performance.
- Golf course leadership at 63.5% stems from the regular use of golf carts for player transportation, equipment movement, and course maintenance. Consistent demand for convenient mobility supports daily operations and enhances visitor experiences across golf facilities.
- Commercial services at 23.4% benefit from demand for convenient transportation across resorts, hospitality facilities, and commercial properties. Golf carts provide practical mobility for staff, visitors, and maintenance teams within large premises.
- Kanto Region share at 34.7% is linked to its concentration of recreational facilities, commercial establishments, and tourism infrastructure. Demand across golf courses, resorts, and commercial properties contributes to regional market activity.
Japan Golf Cart Market Overview
Golf carts are motorized, low-speed vehicles designed for short-distance transport across golf courses, resorts, commercial facilities, and hospitality settings. The market encompasses electric, gasoline, and solar-powered variants, supported by a sophisticated ecosystem spanning vehicle design, component manufacturing, fleet distribution, and after-sales service.
The market is shaped by demographic trends, government emission policies, Japan's dense golf course infrastructure, and evolving sustainability commitments across the leisure and hospitality sectors. Technological shifts toward battery electrification and smart fleet connectivity are progressively redefining product and service models across the value chain.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
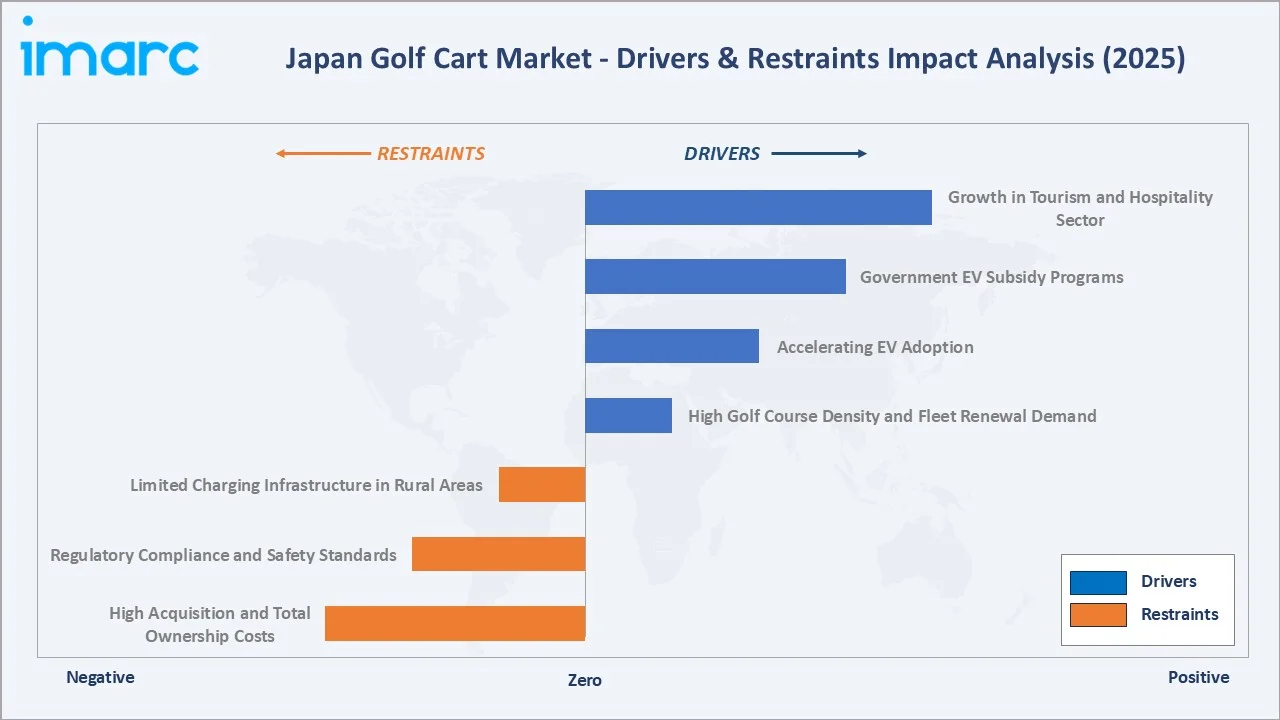
- High Golf Course Density and Fleet Renewal Demand: Japan's extensive network of golf facilities creates sustained structural demand for golf cart procurement, fleet replacement, and periodic electrification upgrades across all regions.
- Accelerating EV Adoption: Growing interest in electric mobility and low-emission transportation encourages golf course operators, resorts, and commercial establishments to adopt electric golf carts. As per IMARC Group, the Japan EVs market reached USD 73.2 Billion in 2025. Improvements in battery performance, charging convenience, and operating efficiency further support the transition from gasoline-powered models.
- Government EV Subsidy Programs: Government-backed clean energy vehicle subsidies reduce acquisition costs for electric golf carts, lowering barriers for golf course operators and commercial fleet managers considering electrification.
- Growth in Tourism and Hospitality Sector: Expanding domestic and inbound tourism, resort development, and hospitality sector investment is fueling demand for golf cart fleets in hotels, resorts, and recreational facilities across Japan. As reported by the Japan National Tourism Organization (JNTO) and the Japan Tourism Agency (JTA), approximately 36.9 Million international visitors traveled to Japan in 2024, exceeding the former high of 31.9 Million in 2019 by around 16%.
Market Restraints
- High Acquisition and Total Ownership Costs: Premium electric golf carts carry elevated purchase prices, and battery replacement costs for lithium-ion packs, creating significant recurring lifecycle expenditure for golf course operators managing large fleets. This cost structure limits adoption among smaller and budget-constrained facilities.
- Regulatory Compliance and Safety Standards: Japan's stringent vehicle safety and road certification requirements increase compliance costs for manufacturers and restrict deployment of golf carts beyond designated course and private facility environments.
- Limited Charging Infrastructure in Rural Areas: Inadequate public and facility-level charging infrastructure in rural prefectures constrains adoption of electric golf carts, particularly for operators in regions without reliable grid access or charging investment capacity.
Market Opportunities
- Government Incentive Programs for Zero-Emission Fleets: Government subsidy programs for zero-emission commercial vehicles, including electric golf carts, create commercial opportunity for OEMs and fleet operators investing in battery-electric platform transitions.
- Resort and Hospitality Sector Expansion: Japan's growing luxury resort and eco-tourism sector presents new demand for premium electric and solar golf cart fleets, particularly in scenic regional destinations.
Market Challenges
- Supply Chain Volatility for Battery Components: Global lithium-ion battery supply chain disruptions and semiconductor availability constraints continue to affect vehicle production timelines and parts availability.
- Rising Competition from Low-Cost Imports: Increasing imports of lower-cost electric golf carts from Southeast Asian manufacturers introduce pricing pressure on entry-level domestic models.
Emerging Market Trends
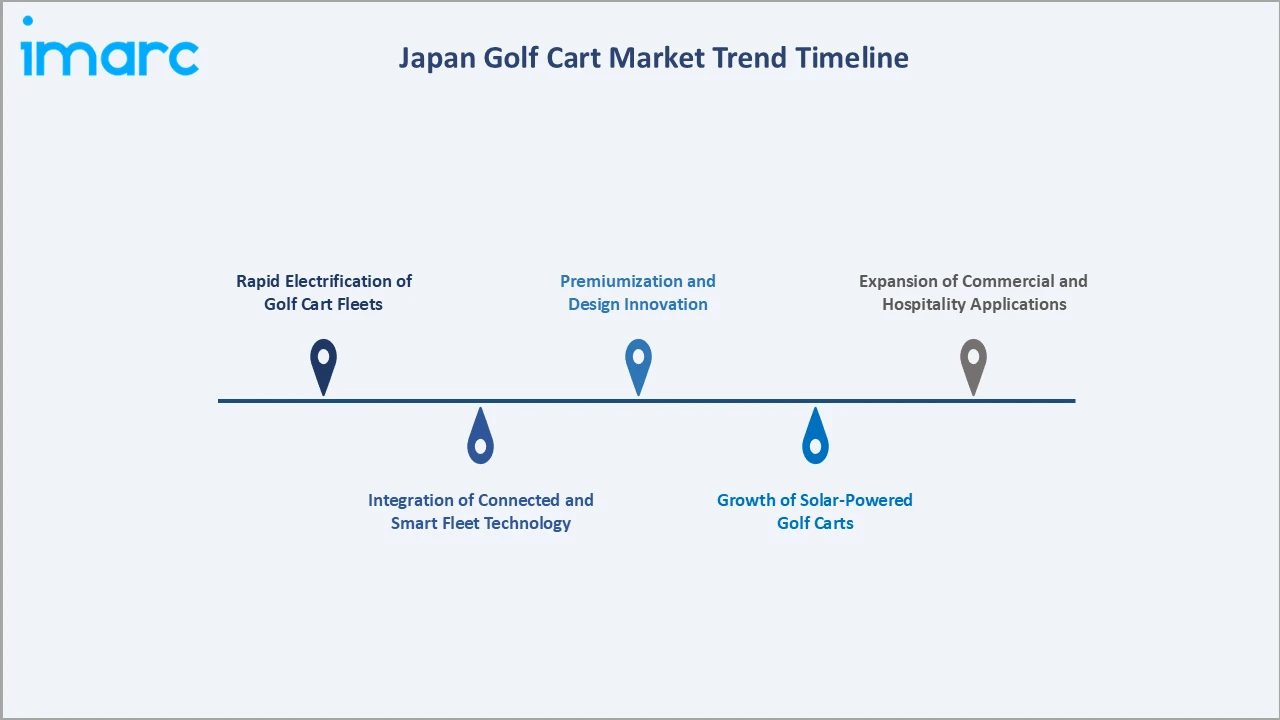
1. Rapid Electrification of Golf Cart Fleets
Japan's golf course operators and commercial fleet managers are accelerating the transition from gasoline to electric golf carts. This shift is driven by sustainability mandates, declining battery costs, and supportive government incentive programs targeting zero-emission commercial mobility.
2. Integration of Connected and Smart Fleet Technology
IoT connectivity, GPS fleet tracking, ride analytics, and smartphone interfaces are increasingly embedded in mid-range and premium golf carts. Smart fleet management platforms allow golf course operators to monitor cart utilization, schedule maintenance, and optimize deployment across large facilities.
3. Growth of Solar-Powered Golf Carts
Solar golf carts are gaining traction across Japan's sunnier southern prefectures. Solar-assisted charging also helps reduce electricity consumption and supports the adoption of energy-efficient mobility solutions across golf courses and resorts.
4. Premiumization and Design Innovation
Rising consumer expectations from hospitality and resort operators are driving demand for premium golf cart designs with enhanced comfort features, custom aesthetics, and advanced suspension systems. Manufacturers are expanding premium product lines to serve Japan's high-end resort and golf club market.
5. Expansion of Commercial and Hospitality Applications
Golf carts are increasingly adopted beyond traditional golf course use, with resorts, airports, hospitals, and large commercial facilities deploying them for last-mile passenger and cargo transport, expanding the addressable market significantly beyond core golf applications.
Industry Value Chain Analysis
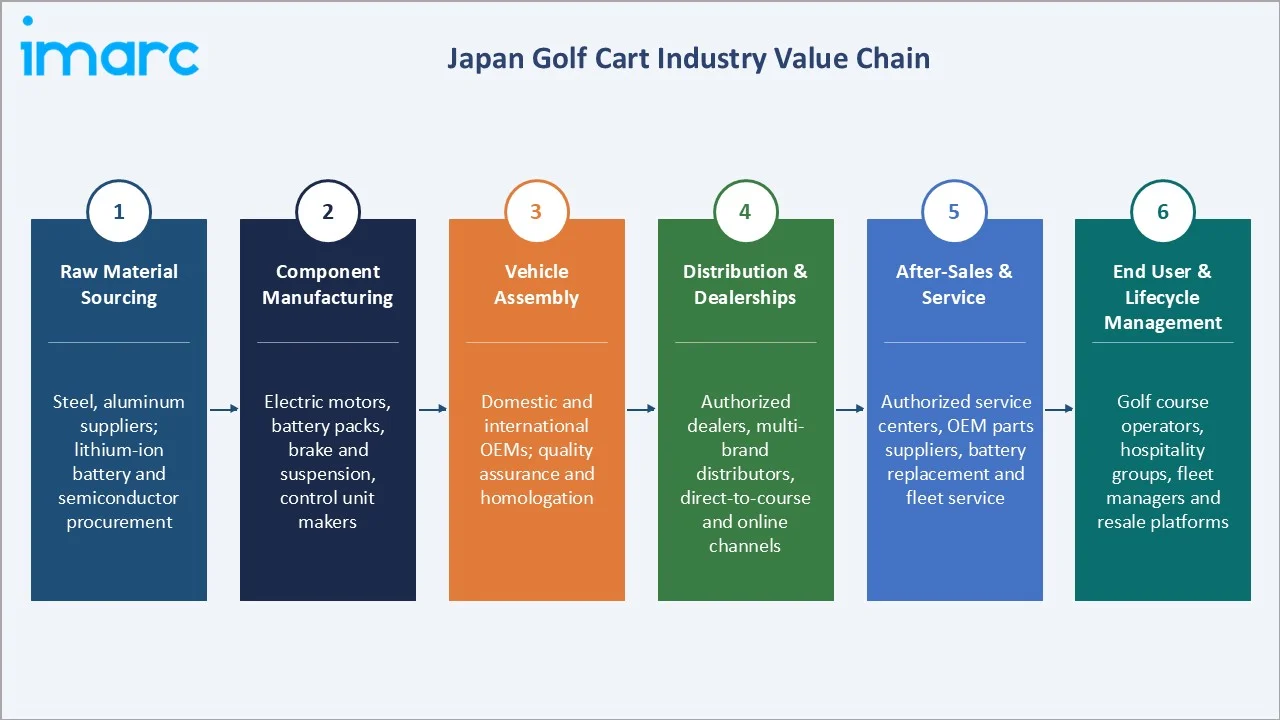
The Japan golf cart value chain spans six key stages, from raw material sourcing and component manufacturing through vehicle assembly, distribution, after-sales servicing, and end-user lifecycle management. OEM assembly and distribution capture the highest value-add, while battery technology and after-sales service networks increasingly determine competitive position and customer retention.
|
Stage |
Key Players / Examples |
|
Raw Material Sourcing |
Steel, aluminum, and composite material suppliers; lithium-ion battery material and semiconductor procurement networks |
|
Component Manufacturing |
Electric motor and drive system specialists, battery pack assemblers, brake and suspension suppliers, electronic control unit manufacturers |
|
Vehicle Assembly |
Domestic and international OEMs performing final assembly, quality assurance testing, and regulatory homologation |
|
Distribution & Dealerships |
Authorized brand dealers, multi-brand golf equipment distributors, direct-to-golf-course sales channels, and online retail platforms |
|
After-Sales & Service |
Authorized service centers, independent repair workshops, OEM parts suppliers, battery replacement networks, and fleet management service providers |
|
End User & Lifecycle Management |
Golf course operators, commercial fleet managers, hospitality groups, insurance providers, and trade-in and resale platforms |
Vertically integrated OEMs that control manufacturing and distribution are positioned to capture greater value than specialist component suppliers. Growing importance of after-sales services and digital fleet management creates new value capture opportunities for OEMs with subscription-based service capabilities.
Technology Landscape in the Japan Golf Cart Industry
Electric Drivetrain and Battery Technology
Japanese and international golf cart OEMs are investing in lithium-ion and next-generation solid-state battery technologies to improve energy density, charging speed, and cycle life. Battery standardization initiatives are reducing costs and supporting broader electric golf cart adoption across fleet operators.
Connected Vehicle Technology and IoT Integration
Advanced GPS fleet tracking, ride-mode customization, and real-time diagnostics are being integrated into golf carts to enable data-driven fleet management. These systems allow operators to track usage, schedule maintenance, and optimize charging schedules across large fleets.
Solar Energy Integration
Solar panel integration into golf cart rooftops is evolving from a novelty into a viable commercial option. Improvements in flexible photovoltaic modules and battery storage systems are extending the operational range of solar carts, particularly in Japan's sunny central and southern prefectures.
Lightweight Material Engineering
OEMs are incorporating high-strength aluminum alloys and advanced polymer components to reduce vehicle weight, improve efficiency, and extend electric range. These materials reduce both manufacturing costs and operational energy consumption.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Electric Golf Cart |
72.8% |
2025 |
|
Seating Capacity |
🔒 |
🔒 |
2025 |
|
Application |
Golf Course |
63.5% |
2025 |
|
Region |
Kanto Region |
34.7% |
2025 |

By Product Type
Electric golf cart commands a 72.8% majority share in 2025, driven by Japan's comprehensive electrification push, government subsidy programs, and the strong sustainability commitments of golf course operators transitioning their fleets. The segment benefits from improving battery cost trajectories and expanding charging infrastructure at golf facilities.
To access detailed market analysis, Request Sample
Gasoline golf cart retains a 21.4% share, supported by established refueling infrastructure and wide model availability across rural and semi-urban golf facilities.
By Application
Golf course leads with a 63.5% share in 2025, supported by Japan's high-density golf course network and consistent fleet replacement demand. Golf facilities maintain dedicated cart fleets to support daily operations, creating recurring procurement and replacement demand for manufacturers and distributors.
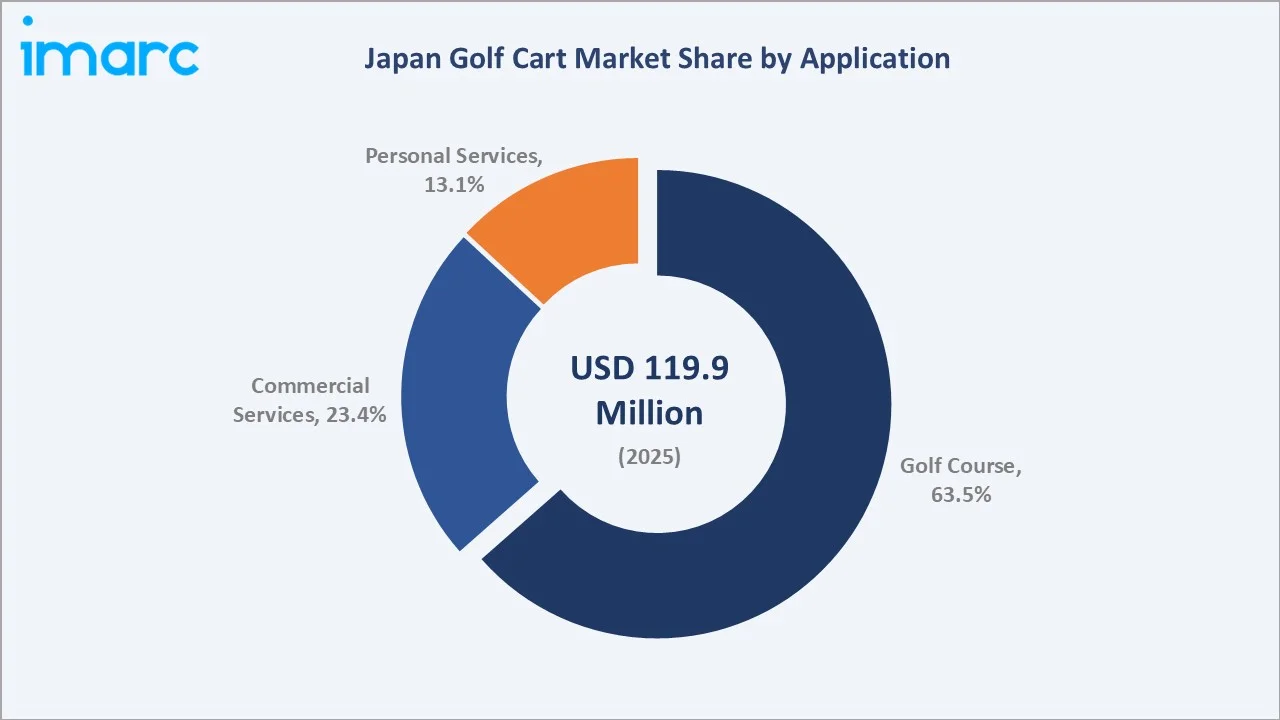
Commercial services hold a 23.4% application share in 2025, driven by resort operators, hospitality groups, airports, and large commercial facilities deploying golf carts for intra-facility transport.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
34.7% |
High population density, mature dealer network, strong leisure demand, and concentration of golf courses and fleet operators |
|
Kansai/Kinki Region |
21.6% |
Large urban population, established golf culture, growing tourism activity, and expanding commercial fleet demand in Osaka and Kyoto |
|
Central/Chubu Region |
14.8% |
Strong industrial base, growing recreational golf participation, established dealer and service infrastructure, and resort golf demand |
|
Kyushu-Okinawa Region |
9.8% |
Expanding tourism sector, warm climate supporting year-round golf, growing resort development, and rising commercial golf cart fleet demand |
|
Tohoku Region |
7.2% |
Rugged terrain driving utility cart demand, expanding regional golf infrastructure, and growing adoption of electric carts in rural golf facilities |
|
Chugoku Region |
5.8% |
Coastal tourism supporting golf resort activity, rising recreational golf participation, and growing commercial fleet demand in regional hotels |
|
Hokkaido Region |
3.7% |
Scenic golf resort landscape, growing inbound tourism, expanding commercial hospitality sector, and seasonal golf course fleet demand |
|
Shikoku Region |
2.4% |
Rural leisure tourism, scenic golf course routes, growing regional participation, and rising adoption of electric golf carts in rural facilities |
Kanto Region leads national market demand at 34.7% in 2025, anchored by greater Tokyo's dense population, high per-capita recreational spending, and a mature ecosystem of golf courses, fleet operators, and dealer networks. The region benefits from both strong leisure and commercial cart deployment.
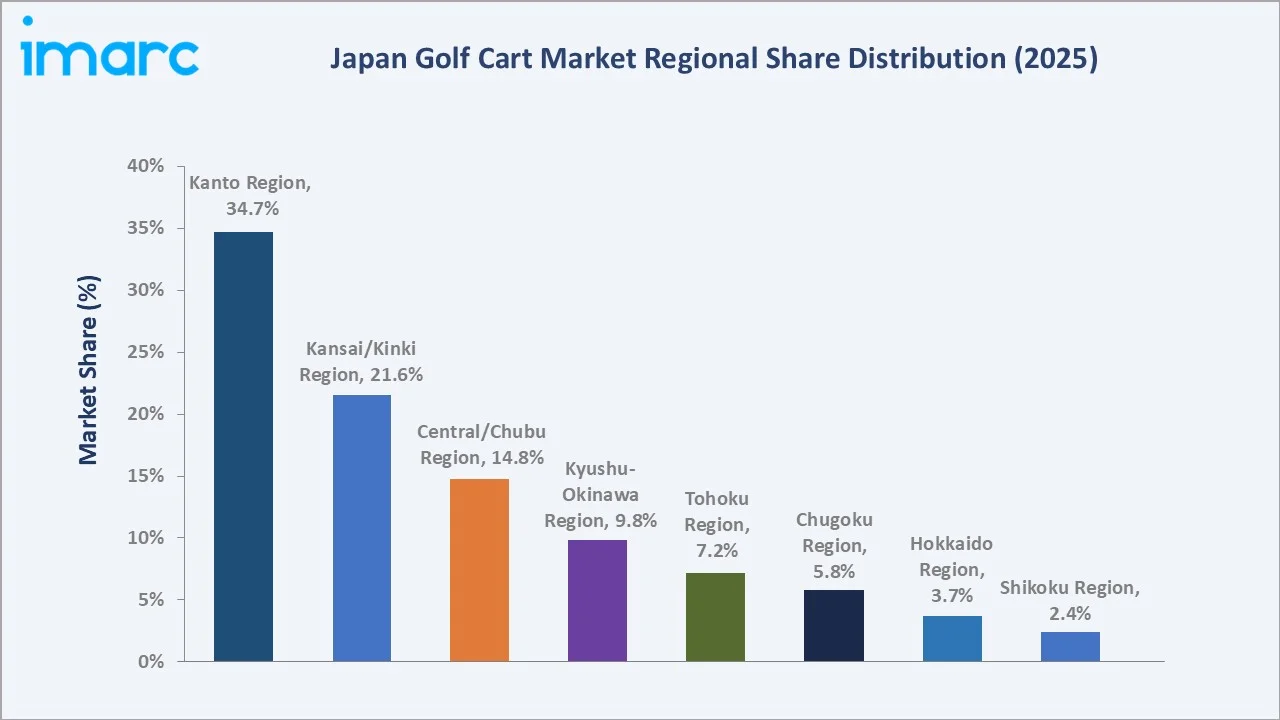
Kansai/Kinki Region at 21.6% maintains significant regional share, supported by Osaka and Kyoto's large urban populations, established golf culture, and growing tourism demand for resort-based golf cart services.
Competitive Landscape
The Japan golf cart market is moderately concentrated, with a small number of globally competitive manufacturers holding the majority of market share alongside established international brands. Brand heritage, technology leadership, dealer network depth, and product range breadth form the key competitive differentiators.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Yamaha Motor Co., Ltd. | Yamaha Golf Car | Leader | Expanding electric golf cart portfolio and strengthening domestic distribution infrastructure |
| Textron Inc. | E-Z-GO | Leader | Broadening commercial fleet offering and advancing battery technology integration across product lines |
| Club Car LLC | Club Car | Challenger | Reinforcing premium segment positioning and expanding smart connectivity features across the range |
Key players include Yamaha Motor Co., Ltd., Textron Inc., and Club Car LLC, among others.
Key Company Profiles
Yamaha Motor Co., Ltd.
Yamaha Motor Co., Ltd. is a Japanese multinational corporation headquartered in Iwata, Shizuoka, Japan, and one of the world's foremost manufacturers of golf carts and mobility vehicles. The firm's golf car division is one of Japan's most established producers of purpose-built electric and gasoline golf carts distributed across domestic and international markets.
- Product Portfolio: Yamaha Golf Car electric and gasoline golf carts designed for golf course, resort, and commercial fleet applications.
- Recent Developments: Yamaha Motor Co., Ltd. continues to advance its golf car product and technology programs in line with evolving market and operator requirements.
- Strategic Focus: Scaling electric golf car development programs and deepening domestic dealer network coverage to strengthen fleet supply capabilities across Japan's golf course and resort sectors.
Textron Inc.
Textron Inc. is a United States-based multinational industrial conglomerate. Its E-Z-GO division is a leading manufacturer of golf carts and personal utility vehicles, with a broad global distribution presence including Japan's commercial and golf course market.
- Product Portfolio: E-Z-GO electric and fleet golf carts designed for golf course, commercial service, and personal transport applications.
- Recent Developments: Textron Inc. continues to invest in its E-Z-GO product program and distribution capabilities to support evolving golf cart fleet market requirements globally.
- Strategic Focus: Driving fleet electrification through advanced battery platform investment and broadening E-Z-GO's distribution reach across golf course and commercial service operators worldwide.
Club Car LLC
Club Car LLC is a United States-based manufacturer of golf carts and personal utility vehicles, recognized for its premium product positioning and broad commercial fleet offerings. Club Car LLC distributes its vehicles across global markets, including Japan's golf and commercial sectors.
- Product Portfolio: Club Car electric and fleet golf carts and utility vehicles designed for golf course, hospitality, and commercial fleet operations.
- Recent Developments: Club Car LLC continues to develop its product and technology portfolio, with ongoing focus on fleet electrification and commercial operator capabilities.
- Strategic Focus: Elevating its premium fleet positioning by embedding smart connectivity and remote management technologies into its golf cart and utility vehicle lineup for hospitality and commercial operators.
Market Concentration Analysis
The Japan golf cart market is moderately concentrated, with Yamaha Motor Co., Ltd., Textron Inc., and Club Car LLC holding the majority of domestic fleet sales across golf course, commercial service, and personal segments.
Barriers to entry are high, encompassing capital-intensive manufacturing requirements, comprehensive vehicle homologation and certification costs, nationwide dealer service infrastructure, and significant brand recognition requirements. These factors strongly favor established incumbents over new entrants.
Strategic collaboration in battery standardization and EV development reflects the industry's collective approach to managing the transition to electric mobility while maintaining competitive independence in product design and marketing.
Investment & Growth Opportunities
Fastest-Growing Segments
Solar golf cart is the fastest-growing product type, driven by increasing adoption at eco-conscious golf facilities, resort operators, and hospitality venues seeking zero-emission fleet solutions. Commercial services represent the fastest-growing application segment, supported by expanding resort, hospitality, airport, and facility transport demand.
Emerging Markets
Kyushu-Okinawa Region is the fastest-growing regional market, supported by expanding domestic and international tourism, active resort development, and rising commercial fleet deployment across Okinawa's hospitality sector.
Venture & Investment Trends
Investment activity is concentrated in battery EV platform development, smart fleet management software, and solar integration technology. Strategic alliances between golf cart OEMs and battery technology firms are attracting increasing R&D capital across Japan's green mobility ecosystem.
Future Market Outlook (2026-2034)
The Japan golf cart market is projected to grow from USD 119.9 Million in 2025 to USD 125.7 Million in 2026, reaching USD 183.1 Million by 2034, registering a CAGR of 4.82% during 2026-2034.
Four forces will shape the market through 2034: continued electrification of golf cart fleets across OEMs; deepening integration of smart fleet management and IoT connectivity; expansion of commercial and hospitality applications beyond golf courses; and evolving sustainability mandates from corporate and institutional fleet operators.
By 2034, the Japan golf cart market is expected to be characterized by a substantially larger electric cart share, broader solar adoption, and wider deployment across non-golf commercial settings. This transformation will be supported by improving battery economics, expanded charging infrastructure, and growing institutional acceptance of electric fleet mobility.
Research Methodology
Primary Research
Primary research included structured interviews with golf cart industry executives, OEM product managers, golf course fleet operators, and regulatory specialists. These interviews validated market sizing, segment mix assumptions, and regional demand patterns across Japan's golf and commercial sectors.
Secondary Research
Secondary sources included Japan Golf Association records, Japan Automobile Manufacturers Association publications, Ministry of Economy, Trade and Industry (METI) data, OEM annual reports and investor presentations, and Japan Tourism Agency data on leisure and hospitality sector growth trends.
Forecasting Models
Market forecasts combined top-down and bottom-up models incorporating fleet procurement data, OEM sales volume trends, consumer spending patterns, EV adoption trajectories, and macroeconomic variables. Scenario analysis addressed regulatory developments, battery cost curves, and solar technology adoption timelines.
Japan Golf Cart Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Electric Golf Cart, Gasoline Golf Cart, Solar Golf Cart |
| Seating Capacities Covered | Small (2 - 4 Seater), Medium (6 - 8 Seater), Large (Above 8 Seats) |
| Applications Covered | Golf Course, Personal Services, Commercial Services |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Yamaha Motor Co., Ltd., Textron Inc., Club Car LLC, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan golf cart market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan golf cart market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan golf cart industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Golf Cart Market Report
The Japan golf cart market size is estimated at USD 125.7 Million in 2026, driven by fleet electrification and rising demand from golf courses and commercial operators.
The market is projected to grow at a CAGR of 4.82% from 2026-2034, reaching USD 183.1 Million by 2034, supported by electric adoption, government incentives, and expanding commercial applications.
Electric golf cart leads the product type segment at 72.8% in 2025, supported by government EV incentives, fleet sustainability mandates, and declining battery acquisition costs across Japan.
Golf course dominates with 63.5% application share in 2025, driven by Japan's extensive course network and consistent fleet renewal demand from established golf facility operators.
Kanto Region commands 34.7% share in 2025, led by greater Tokyo's high population density, mature golf infrastructure, and strong per-capita leisure spending on golf-related activities.
Leading players include Yamaha Motor Co., Ltd., Textron Inc., and Club Car LLC, among others.
Key trends include fleet electrification, solar golf cart adoption, smart fleet management integration, commercial application expansion beyond golf courses, and premiumization of resort cart products.
High acquisition and battery replacement costs, regulatory compliance requirements, limited rural charging infrastructure, and rising import competition from low-cost manufacturers represent primary market challenges.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade