Japan Powersports Market Size, Share, Trends and Forecast by Vehicle Type, Propulsion Type, Application, and Region 2026-2034
Japan Powersports Market Size, Share, Trends & Forecast (2026-2034)
The Japan powersports market grew from USD 2.23 Billion in 2025 to USD 2.37 Billion in 2026 and is projected to reach USD 3.77 Billion by 2034, exhibiting a CAGR of 5.99% during 2026-2034. Japan's strong motorsports culture, globally competitive domestic manufacturers, and rising interest in recreational off-road activities are key forces supporting market expansion.
Gasoline dominates the propulsion type segment at 71.6% share, on-road prevails over the application segment at 64.3%, and Kanto Region leads with 34.8% market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 2.23 Billion |
|
Market Size (2026) |
USD 2.37 Billion |
|
Forecast Market Size (2034) |
USD 3.77 Billion |
|
CAGR (2026-2034) |
5.99% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Kanto Region (34.8%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (19.7%, 2025) |
|
Leading Propulsion Type |
Gasoline (71.6%, 2025) |
|
Leading Application |
On-Road (64.3%, 2025) |
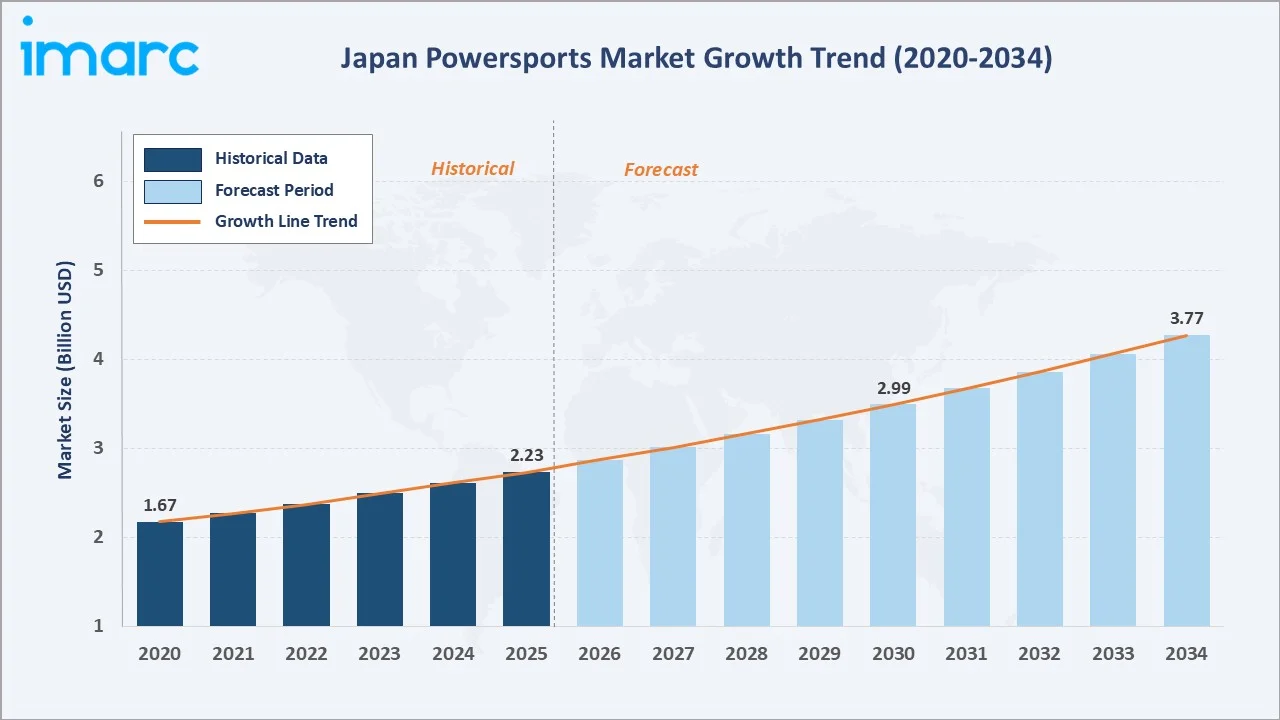
The Japan powersports market size increased from USD 1.67 Billion in 2020 to USD 2.23 Billion in 2025 and is estimated to reach USD 2.37 Billion in 2026. The market is further expected to grow to USD 2.99 Billion by 2030 and USD 3.77 Billion by 2034, supported by accelerating electrification, government clean-mobility incentives, and expanding off-road recreational infrastructure across Japan.
To get more information on this market, Request Sample
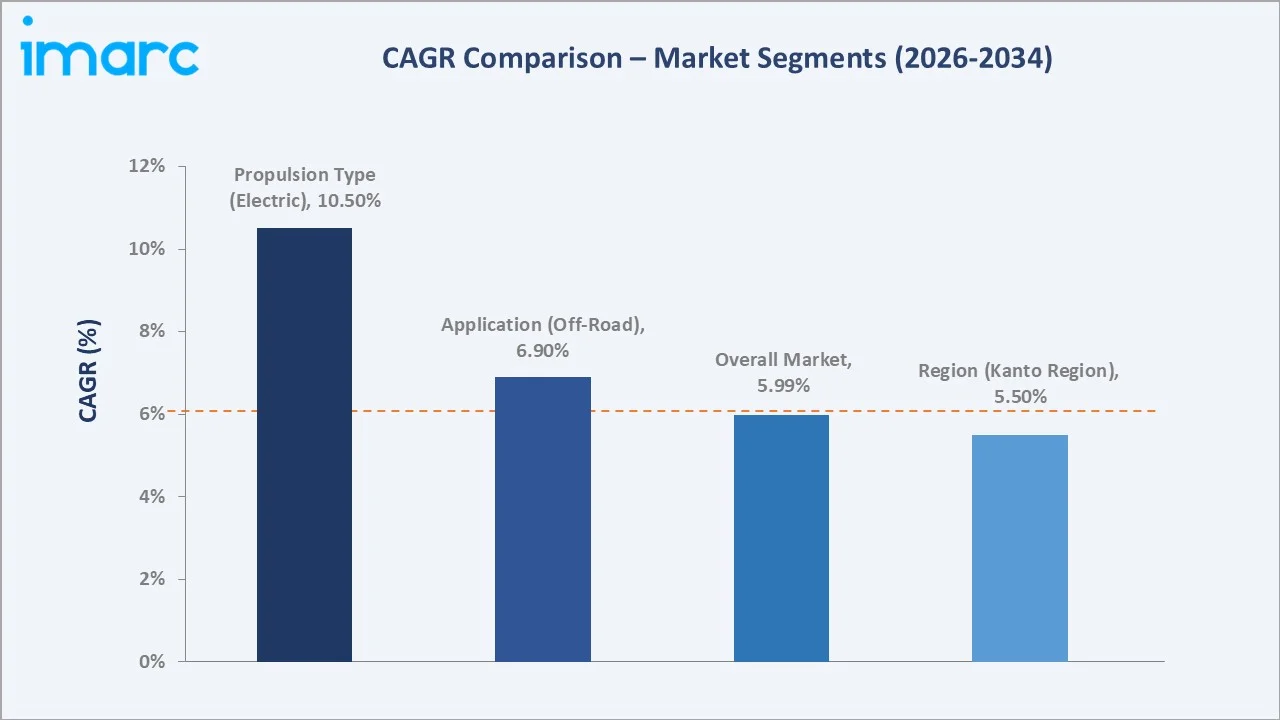
CAGR trajectories across propulsion type and application sub-segments, together with regional patterns, show electric and off-road expanding faster than the overall 5.99% market CAGR, driven by rising environmental awareness, government EV incentive schemes, and growing demand for adventure riding across Japan's diverse terrain.
Executive Summary
The Japan powersports market expanded from USD 2.23 Billion in 2025 to an estimated USD 2.37 Billion in 2026, positioning it among Asia-Pacific's most mature and innovative powersports markets. The industry encompasses motorcycles, scooters, all-terrain vehicles (ATVs), side-by-sides, and personal watercraft. A deeply rooted motorsports culture, globally competitive domestic manufacturers, and rising recreational demand are collectively reshaping the industry landscape.
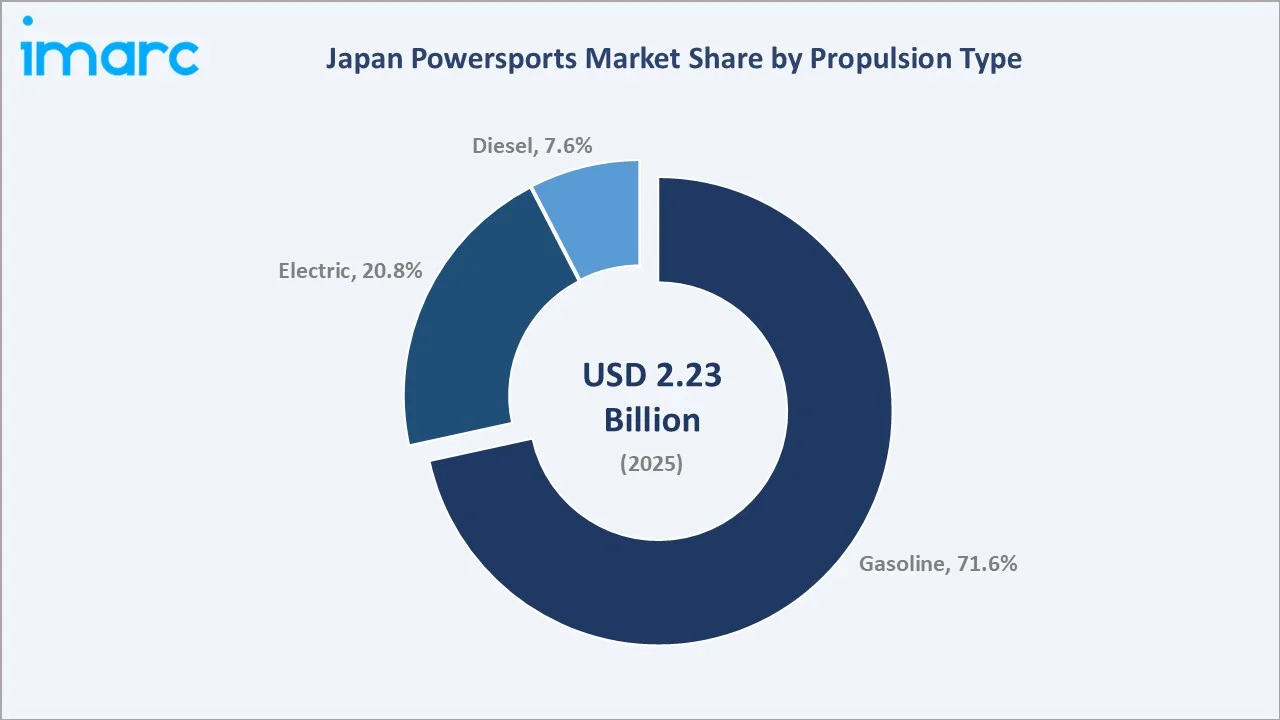
Gasoline dominates the propulsion type segment at 71.6% in 2025, supported by an established refueling infrastructure, broad consumer familiarity, and wide model availability across price segments. On-road leads the application segment at 64.3%, fueled by extensive motorcycle and scooter usage for commuting, personal mobility, and leisure activities. Kanto Region prevails over the market with 34.8% share, benefiting from high population density, well-developed road infrastructure, and a concentration of powersports dealerships.
Key Market Insights
|
Insight |
Data |
| Leading Propulsion Type | Gasoline – 71.6% share (2025) |
| Second Largest Propulsion Type | Electric – 20.8% share (2025) |
| Leading Application | On-Road – 64.3% share (2025) |
| Second Largest Application | Off-Road – 35.7% share (2025) |
| Leading Region | Kanto Region – 34.8% share (2025) |
| Second Largest Region | Kansai/Kinki Region – 19.7% share (2025) |
| Top Companies | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Harley-Davidson, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Gasoline dominance at 71.6% reflects Japan's extensive petrol refueling network, wide model range from domestic OEMs, and established consumer preference for combustion-powered performance across touring, sport, and commuter segments.
- Electric share at 20.8% is underpinned by accelerating OEM EV launches, growing urban adoption of electric scooters, and expanding government incentive programs targeting clean personal mobility.
- On-road leadership at 64.3% is supported by Japan's dense urban road network, commuter motorcycle culture, and strong demand for fuel-efficient scooters and light motorcycles in metro areas.
- Off-road at 35.7% reflects a structurally growing segment driven by expanding adventure tourism, ATV adoption, and growing rural utility applications across Japan's mountainous interior.
- Kanto Region at 34.8% leads due to greater population concentration, higher disposable income, a dense dealer network, and proximity to major powersports event venues and motorsport communities.
Japan Powersports Market Overview
Powersports refers to motorized recreational and utility vehicles designed for performance, adventure, and off-road use, encompassing motorcycles, scooters, ATVs, side-by-side vehicles, snowmobiles, and personal watercraft. Japan is home to several of the world's largest powersports OEMs and maintains a sophisticated ecosystem spanning vehicle design, component manufacturing, distribution, and after-sales services.
The market is influenced by demographic trends, regulatory frameworks on emissions and road safety, evolving consumer lifestyles, and technological shifts toward electrification and connectivity. Japan's mountainous terrain, island geography, and deep motorsports culture create a uniquely diverse demand environment across both on-road commuting and off-road recreational segments.
Market Dynamics
To evaluate market opportunities, Request Sample
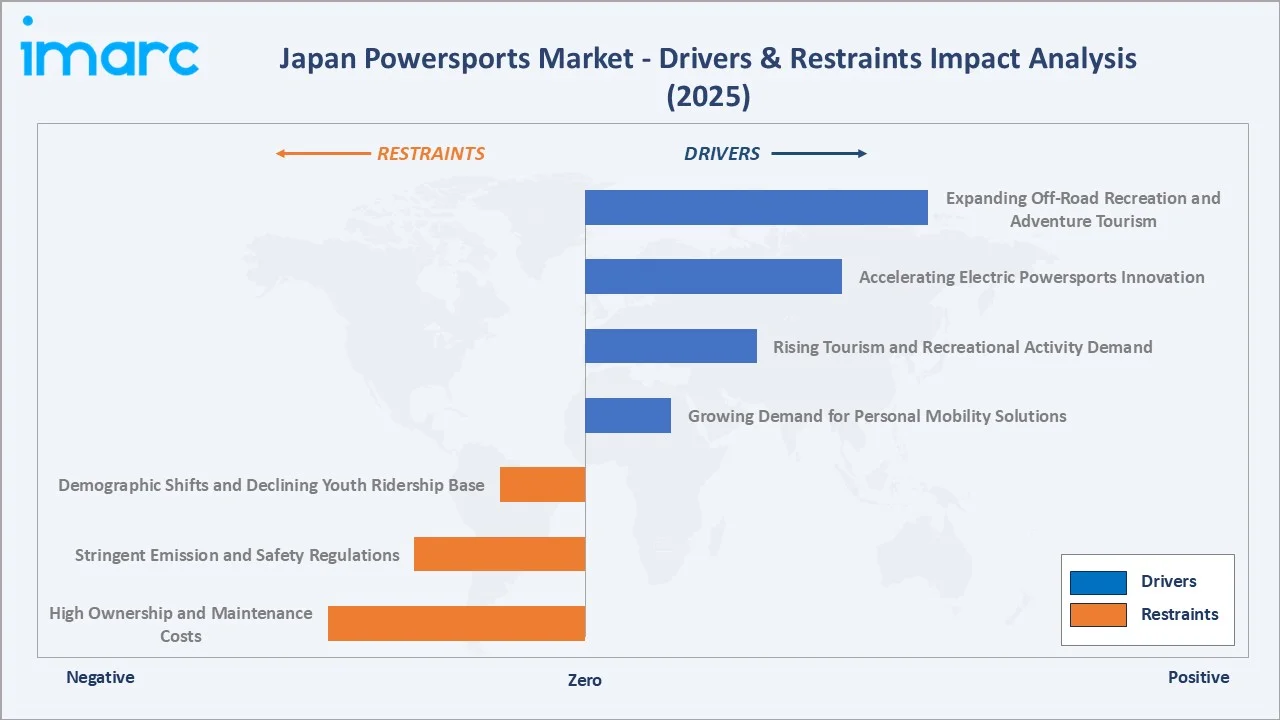
Market Drivers
- Growing Demand for Personal Mobility Solutions: Japan's urbanized population increasingly favors motorcycles and scooters for flexible, cost-effective personal mobility, particularly for short-to-medium commutes in congested metropolitan areas. This preference for individualized transport continues to support strong on-road powersports demand.
- Rising Tourism and Recreational Activity Demand: Rising domestic and inbound tourism focused on adventure activities, including trail riding, ATV tours, and off-road experiences, is fueling demand for recreational powersports vehicles across rural and mountainous prefectures. The Japan National Tourism Organization (JNTO) estimated that 3,442,100 international visitors were set to travel to Japan in July 2026, reflecting a 0.1% increase from 2025.
- Accelerating Electric Powersports Innovation: Major Japanese OEMs are accelerating electric powersports product development, supported by government clean-energy incentive programs.
- Expanding Off-Road Recreation and Adventure Tourism: Growing interest in outdoor lifestyles, motorsports clubs, and off-road trail development is creating sustained incremental demand for ATVs, side-by-sides, and adventure motorcycles across Japan's regional prefectures.
Market Restraints
- High Ownership and Maintenance Costs: Premium powersports vehicles carry high purchase prices, and ongoing costs including insurance, maintenance, and registration fees present barriers to new user entry, limiting market expansion among younger consumers and moderate-income segments.
- Stringent Emission and Safety Regulations: Japan's progressive tightening of exhaust emission standards increases manufacturing costs for gasoline-powered vehicles and requires OEMs to invest significantly in engine technology upgrades to maintain regulatory compliance.
- Demographic Shifts and Declining Youth Ridership Base: Japan's rapidly aging population and declining proportion of young adults reduces the long-term addressable consumer base for performance-oriented powersports vehicles, requiring industry-wide efforts to attract new rider demographics.
Market Opportunities
- Government EV Incentives and Green Mobility Programs: Government subsidy programs for zero-emission vehicles, including electric motorcycles and ATVs, create significant commercial opportunity for OEMs investing in battery technology and EV product lines, directly reducing consumer acquisition costs.
- Expansion of Off-Road Parks and Recreational Infrastructure: Japan's regional prefectures, particularly Hokkaido, Tohoku, and Shikoku, are actively developing dedicated off-road parks and trail networks, creating new demand centers for ATVs, trail bikes, and off-road utility vehicles.
Market Challenges
- Supply Chain Disruptions and Component Availability: Global semiconductor and battery supply chain disruptions continue to affect vehicle production timelines and parts availability, creating uncertainty in inventory planning and retail delivery schedules.
- Rising Import Competition and Pricing Pressure: Increasing competition from imported low-cost powersports brands from Southeast Asian manufacturers introduces pricing pressure on entry-level domestic models, challenging Japanese OEMs to maintain competitiveness.
Emerging Market Trends
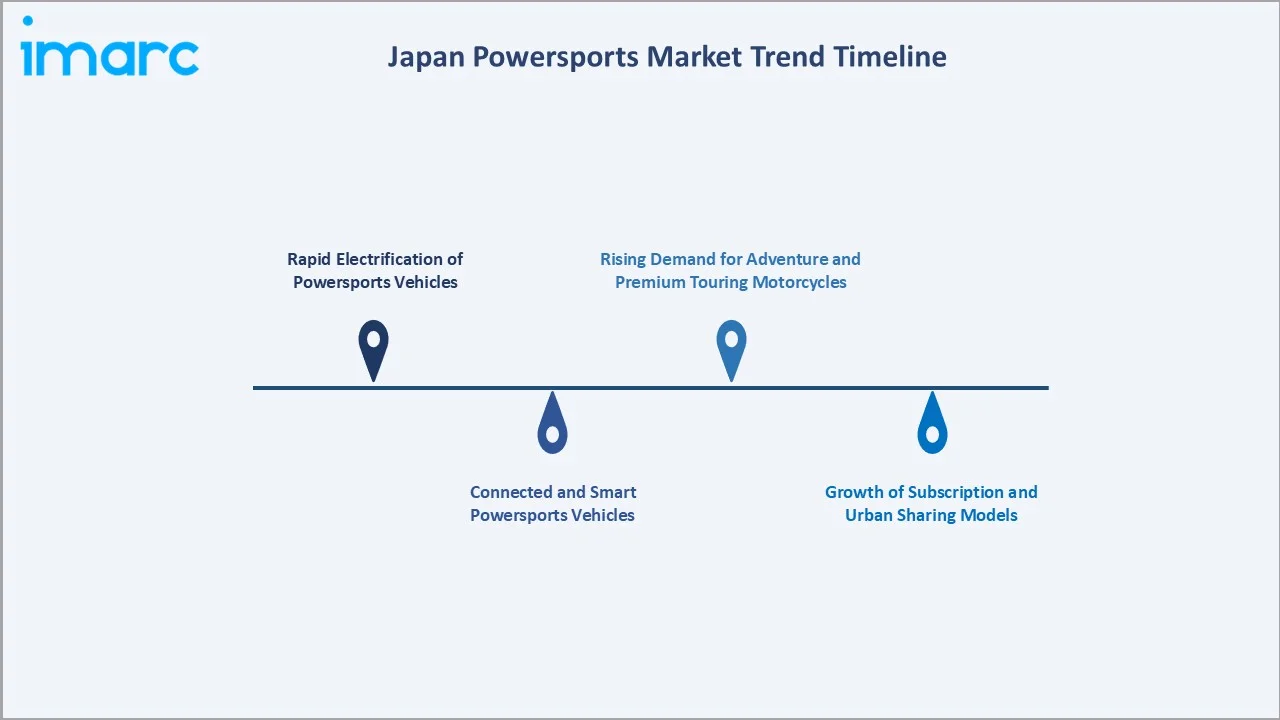
1. Rapid Electrification of Powersports Vehicles
Japan's major powersports OEMs are accelerating EV development across motorcycle, scooter, and ATV categories. This trend is reshaping product roadmaps, dealer service capabilities, and consumer purchase decisions across the market.
2. Connected and Smart Powersports Vehicles
Integration of IoT connectivity, GPS tracking, smartphone interfaces, and ride analytics into powersports vehicles is becoming a key differentiator for premium models. Japanese OEMs and technology partners are embedding telemetry, navigation, and over-the-air update capabilities into motorcycles and ATVs, enhancing rider experience and enabling new service and subscription models.
3. Rising Demand for Adventure and Premium Touring Motorcycles
Growing interest in long-distance motorcycle touring and adventure riding is driving demand for premium, feature-rich models with advanced suspension, navigation, and comfort systems. This supports premiumization across the on-road powersports segment, with consumers investing in higher-specification models for enhanced touring capability and riding comfort.
4. Growth of Subscription and Urban Sharing Models
Emerging motorcycle and scooter sharing platforms in urban areas are expanding access to powersports vehicles without the cost of ownership. These services are particularly relevant in major metropolitan areas, attracting younger urban consumers who value flexibility over ownership and contributing to incremental market volume growth.
Industry Value Chain Analysis
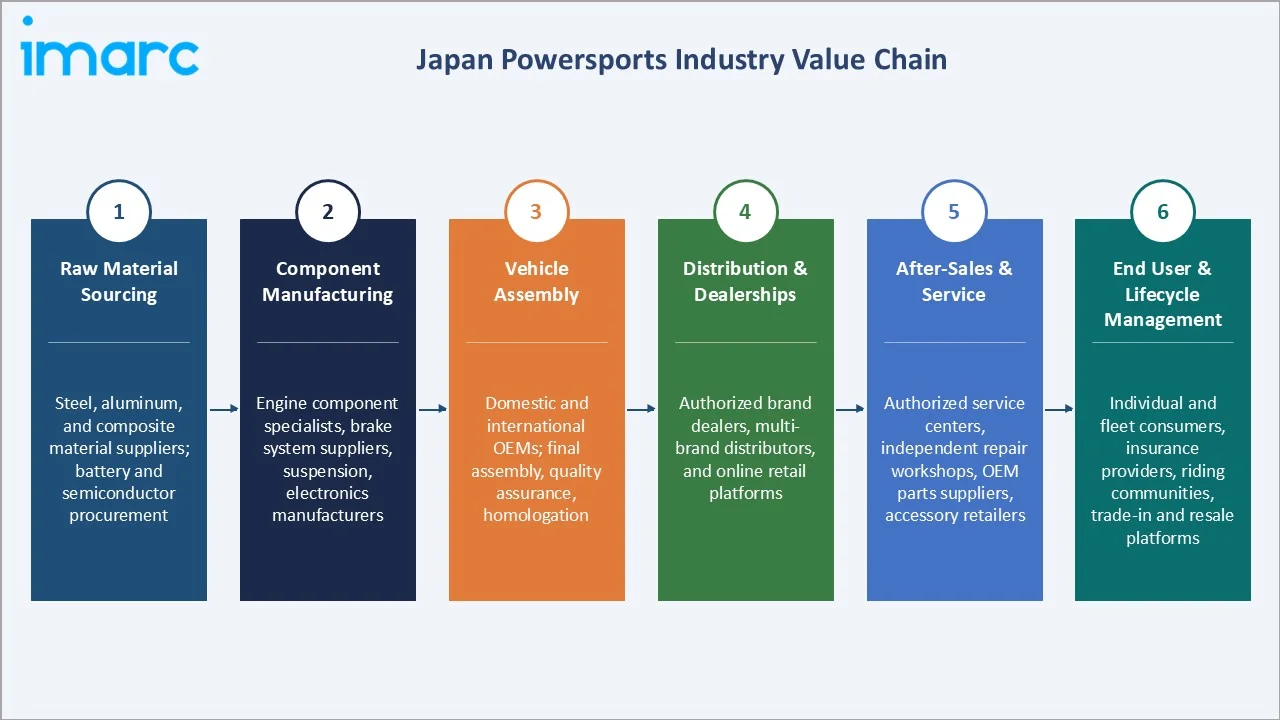
The Japan powersports value chain spans six key stages, from raw material sourcing and component manufacturing through vehicle assembly, distribution, after-sales servicing, and end-user lifecycle management. OEM assembly and distribution capture the highest value-add, while component quality and after-sales service networks increasingly determine competitive position and customer retention.
|
Stage |
Key Players / Examples |
| Raw Material Sourcing | Steel, aluminum, and composite material suppliers; battery and semiconductor procurement networks |
| Component Manufacturing | Engine component specialists, brake system suppliers, suspension system developers, and electronics manufacturers |
| Vehicle Assembly | Domestic and international OEMs performing final assembly, quality assurance, and homologation |
| Distribution & Dealerships | Authorized brand dealers, multi-brand distributors, and online retail platforms managing vehicle distribution |
| After-Sales & Service | Authorized service centers, independent repair workshops, OEM parts suppliers, and accessory retailers |
| End User & Lifecycle Management | Individual and fleet consumers, insurance providers, riding communities, and trade-in and resale platforms |
Vertically integrated Japanese OEMs that control both manufacturing and distribution are positioned to capture greater value than specialist component suppliers. The growing importance of after-sales services and digital connectivity creates new value capture opportunities for OEMs with subscription-based service capabilities.
Technology Landscape in the Japan Powersports Industry
Electric Drivetrain and Battery Technology
Japanese OEMs are investing heavily in lithium-ion and next-generation solid-state battery technologies to improve energy density, charging speed, and cycle life for electric powersports vehicles. Major OEMs have formed collaborative battery standardization initiatives to support interchangeable swappable battery systems for urban electric motorcycles and scooters.
Connected Vehicle Technology and IoT Integration
Advanced telemetry, GPS navigation, ride-mode customization, and smartphone integration systems are being embedded into mid-range and premium powersports models. Over-the-air software update capability is emerging as a standard feature in flagship models, enabling ongoing performance optimization and new feature delivery after purchase.
Lightweight Material Engineering
OEMs are incorporating carbon fiber composites, high-strength aluminum alloys, and advanced polymer components to reduce vehicle weight, improve power-to-weight ratios, and extend EV range. These innovations are especially prominent in performance motorcycles, premium ATVs, and electric powersports platforms.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Vehicle Type | 🔒 | 🔒 | 2025 |
| Propulsion Type | Gasoline | 71.6% | 2025 |
| Application | On-Road | 64.3% | 2025 |
| Region | Kanto Region | 34.8% | 2025 |

By Propulsion Type
Gasoline commands a 71.6% majority share in 2025, driven by Japan's comprehensive petrol refueling infrastructure, diverse model availability across sport, touring, adventure, and commuter categories, and strong established consumer preference for internal combustion performance. The segment benefits from mature manufacturing efficiency and broad dealer service support.
To access detailed market analysis, Request Sample
Electric at 20.8% in 2025 is expanding rapidly as OEMs launch purpose-built electric models and government subsidies lower acquisition costs.
By Application
On-road leads with 64.3% share in 2025, supported by high urban motorcycle penetration in commuter and touring segments. Japan's dense road network, strong culture of motorcycle commuting, and premium touring market drive sustained on-road demand across diverse consumer segments.
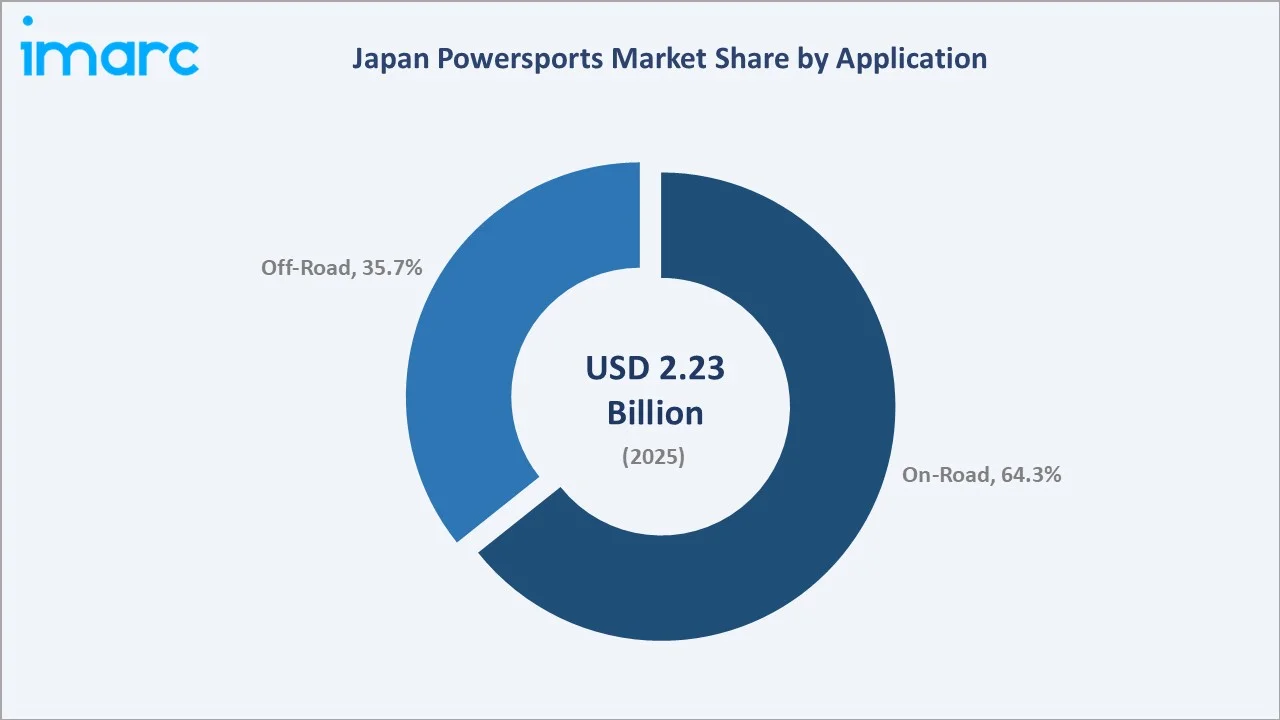
Off-road at 35.7% in 2025 is growing as adventure recreational riding gains popularity. Demand for ATVs and side-by-sides in rural utility applications, combined with expanding trail networks and adventure tourism infrastructure, is forecast to sustain above-market growth through the forecast period.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Kanto Region | 34.8% | High population density, mature dealer network, strong commuter motorcycle demand, and concentration of OEM corporate and R&D operations |
| Kansai/Kinki Region | 19.7% | Large urban population in Osaka and Kyoto, growing touring motorcycle culture, expanding adventure sports participation |
| Central/Chubu Region | 14.8% | Industrial base supporting domestic OEM supply chains, strong motorsport heritage, and growing recreational powersports interest |
| Kyushu-Okinawa Region | 9.1% | Expanding adventure tourism, warm climate supporting year-round riding, and growing regional off-road recreational infrastructure |
| Tohoku Region | 7.8% | Rugged terrain supporting off-road vehicle demand, expanding rural utility ATV adoption, and growing snow sports powersports activity |
| Chugoku Region | 6.3% | Coastal and inland tourism driving scooter and ATV demand, rising recreational riding activity in rural areas |
| Hokkaido Region | 4.9% | Snowmobile and cold-weather powersports demand, extensive open terrain for off-road use, growing adventure tourism infrastructure |
| Shikoku Region | 2.6% | Rural utility vehicle demand, scenic touring routes attracting motorcycle tourism, expanding local off-road trail networks |
Kanto Region at 34.8% in 2025 leads the national landscape, anchored by greater Tokyo's dense population, high per-capita vehicle ownership, and a mature ecosystem of powersports dealerships, service centers, and riding communities. The region benefits from strong both commuter and recreational demand segments.
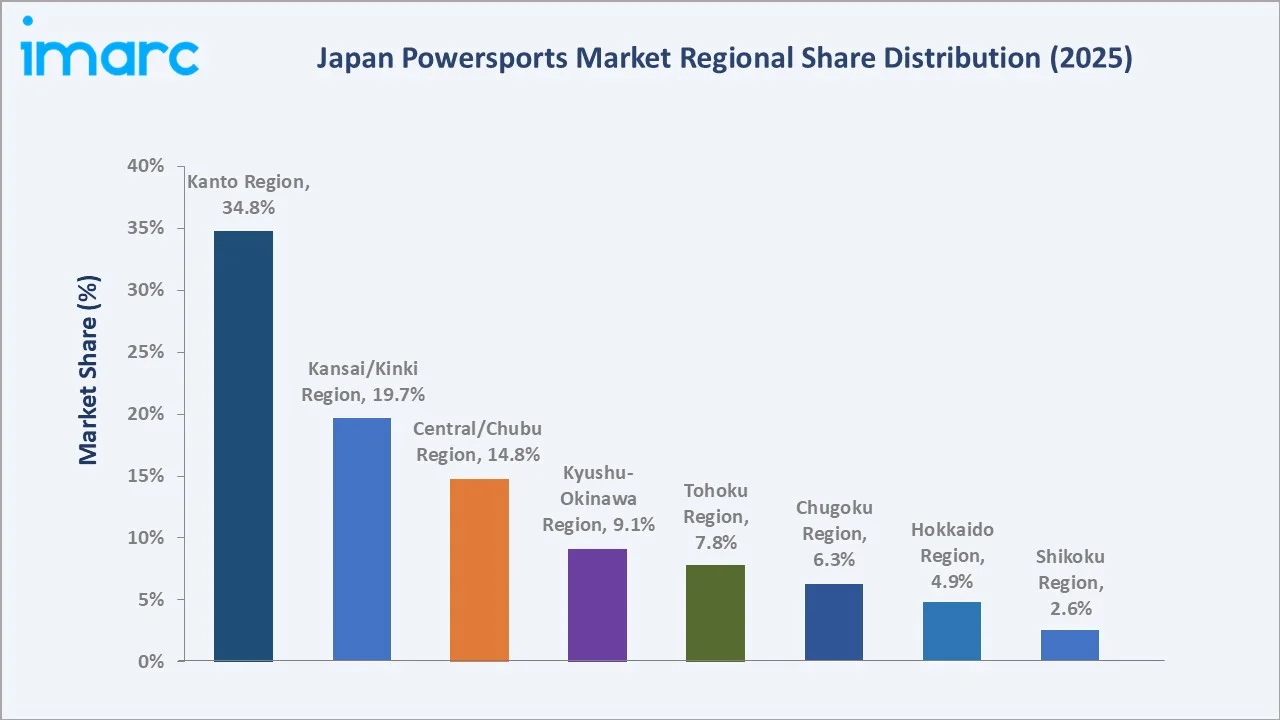
Kansai/Kinki Region at 19.7% maintains a significant regional share, supported by its large urban population, established transportation infrastructure, and strong consumer demand for recreational mobility.
Competitive Landscape
The Japan powersports market is highly concentrated, with a small number of globally dominant Japanese OEMs holding the majority of market share alongside established international competitors. Brand heritage, technology leadership, dealer network depth, and product range breadth form the key competitive differentiators.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| Honda Motor Co., Ltd. | Honda Powersports | Leader | Expanding electric powersports product portfolio and deepening global distribution partnerships |
| Yamaha Motor Co., Ltd. | Yamaha | Leader | Accelerating EV model launches and strengthening connected vehicle technology integration |
| Suzuki Motor Corporation | Suzuki | Challenger | Expanding accessible mid-range powersports offering and strengthening emerging market presence |
| Harley-Davidson, Inc. | Harley-Davidson | Challenger | Strengthening premium cruiser and touring motorcycle positioning and expanding electric motorcycle portfolio |
Key players include Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, and Harley-Davidson, Inc., among others.
Key Company Profiles
Honda Motor Co., Ltd.
Honda Motor Co., Ltd. is a Japanese multinational corporation headquartered in Minato, Tokyo, Japan, and one of the world's largest powersports vehicle manufacturers. Honda's powersports division produces motorcycles, scooters, ATVs, side-by-sides, and personal watercraft distributed across global markets.
- Product Portfolio: Comprehensive powersports range spanning the Super Cub commuter series, Africa Twin adventure motorcycle, Gold Wing touring motorcycle, CRF off-road series, and Pioneer SxS lineup.
- Recent Developments: Honda Motor Co., Ltd. continues to advance its product development programs and technology initiatives, focusing on expanding its global powersports portfolio and strengthening its long-term mobility strategy.
- Strategic Focus: Broadening its EV lineup and reinforcing distribution reach across key global markets while advancing connected mobility capabilities.
Yamaha Motor Co., Ltd.
Yamaha Motor Co., Ltd. is a Japanese manufacturer headquartered in Iwata, Shizuoka, Japan, producing motorcycles, scooters, ATVs, side-by-sides, personal watercraft, and marine products. Yamaha is among the top global powersports OEMs by volume and revenue.
- Product Portfolio: Diversified range including the MT naked motorcycle series, Ténéré adventure bikes, YZF-R sportbikes, Grizzly ATV, and Viking SxS lineup.
- Recent Developments: Yamaha Motor Co., Ltd. continues to invest in product innovation and technology development across its powersports lineup, with ongoing initiatives to advance its broader mobility and sustainability goals.
- Strategic Focus: Driving electrification across its powersports range and deepening integration of digital and connected features throughout its vehicle portfolio.
Suzuki Motor Corporation
Suzuki Motor Corporation is a Japanese multinational manufacturer headquartered in Hamamatsu, Shizuoka, Japan. Suzuki's motorcycle and powersports division produces a broad range of motorcycles, scooters, and ATVs serving both domestic and international markets.
- Product Portfolio: Broad range including the GSX-S sportbike series, V-Strom adventure bikes, and Burgman scooters.
- Recent Developments: The firm continues to develop its motorcycle and powersports lineup, with ongoing focus on product improvement, clean mobility investment, and market expansion across domestic and international segments.
- Strategic Focus: Broadening its mid-range vehicle lineup and reinforcing commercial presence in key international growth markets while advancing clean mobility initiatives.
Market Concentration Analysis
The Japan powersports market is highly concentrated, with Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., and Suzuki Motor Corporation collectively commanding the majority of domestic vehicle sales across motorcycle, scooter, and ATV categories.
Barriers to entry are high and include capital-intensive manufacturing requirements, the need for comprehensive homologation and safety certification, the cost of establishing nationwide dealer service infrastructure, and the brand recognition required to compete in a market with deeply loyal consumer bases. These factors strongly favor established incumbents over new market entrants.
Strategic consolidation continues at the supply chain level, with OEMs forming alliances for shared battery standardization and EV development. Cross-brand collaboration reflects the industry's collective approach to managing the transition to electric mobility while maintaining competitive independence in vehicle design and marketing.
Investment & Growth Opportunities
Fastest-Growing Segments
Electric is expanding fastest among propulsion type categories, driven by OEM product investment, government EV subsidies, and rising consumer environmental awareness. Off-road is the fastest-growing application segment, supported by expanding recreational infrastructure and growing adventure tourism demand across Japan's regional prefectures.
Emerging Markets
Kyushu-Okinawa Region and Tohoku Region are among the faster-growing regional markets, supported by expanding off-road park infrastructure, growing adventure tourism activity, and rising rural utility vehicle demand. These regions represent significant opportunity for OEMs and distributors able to develop targeted retail and service network presence.
Venture & Investment Trends
Investment activity in Japan's powersports sector is concentrated in battery and EV platform development, connected vehicle technology, and lightweight material engineering. Government and private capital is also flowing into off-road recreational infrastructure including ATV parks and adventure trail networks. Strategic alliances between OEMs and technology companies for advanced rider assistance systems are attracting increasing R&D investment.
Future Market Outlook (2026-2034)
The Japan powersports market is projected to grow from USD 2.23 Billion in 2025 to USD 2.37 Billion in 2026, reaching USD 3.77 Billion by 2034, registering a CAGR of 5.99% during 2026-2034.
Four forces will shape the market through 2034: continued electrification of the powersports product portfolio across all major OEMs; deepening integration of connectivity and advanced rider assistance technology; expansion of recreational off-road infrastructure in regional Japan; and evolving consumer lifestyles that increasingly prioritize experiential, adventure-oriented personal mobility.
By 2034, the Japan powersports market is expected to be characterized by a significantly larger EV share. This transition will be supported by broader model availability, improving charging infrastructure, and growing consumer acceptance of electric mobility.
Research Methodology
Primary Research
Primary research included structured interviews with powersports industry executives, OEM product managers, dealership network operators, and regulatory specialists from MLIT and the Japan Automobile Manufacturers Association. These interviews validated market sizing, segment mix assumptions, and regional demand patterns.
Secondary Research
Secondary sources included Japan Automobile Manufacturers Association (JAMA) reports, MLIT vehicle registration statistics, Japan Automotive Federation data, OEM annual reports and investor presentations, Ministry of Economy, Trade and Industry (METI) publications, and Japan Tourism Agency data on adventure and recreational tourism trends.
Forecasting Models
Market forecasts combined top-down and bottom-up models incorporating vehicle registration data, OEM production volume trends, consumer spending patterns, EV adoption trajectory analysis, and macroeconomic variables. Scenario analysis addressed regulatory developments, EV technology cost curves, and infrastructure investment timelines.
Japan Powersports Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Vehicle Types Covered | All-Terrain Vehicles (ATV), Side-By-Side Vehicles, Snowmobiles, Personal Watercraft, Heavyweight Motorcycle |
| Propulsion Types Covered | Gasoline, Electric, Diesel |
| Applications Covered | On-Road, Off-Road |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Harley-Davidson, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan powersports market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan powersports market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan powersports industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Powersports Market Report
The Japan powersports market size is estimated at USD 2.37 Billion in 2026, driven by strong domestic OEM activity, commuter motorcycle demand, and growing recreational powersports adoption.
The market is projected to grow at a CAGR of 5.99% from 2026-2034, reaching USD 3.77 Billion, driven by electrification and expanding off-road recreational demand.
Gasoline leads the propulsion type segment at 71.6% in 2025, supported by wide model availability, established refueling infrastructure, and strong consumer preference for combustion-powered performance.
On-road leads the application segment at 64.3% in 2025, driven by Japan's high urban motorcycle penetration, strong commuter demand, and a well-developed premium touring motorcycle culture.
Kanto Region commands 34.8% share in 2025, led by greater Tokyo's population density, mature dealer infrastructure, and high per-capita powersports vehicle ownership.
Leading players include Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, and Harley-Davidson, Inc., among others.
Government EV subsidies, OEM product launches, and expanding charging infrastructure are the primary drivers of electric powersports growth in Japan.
Key trends include vehicle electrification, connected vehicle technology integration, premiumization of touring and adventure motorcycles, and expansion of off-road recreational infrastructure.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade