Japan Smart Parking Market Size, Share, Trends and Forecast by System, Technology, Component, Solution, Vertical Type, Parking Site, and Region, 2026-2034
Japan Smart Parking Market Size, Share, Trends & Forecast (2026-2034)
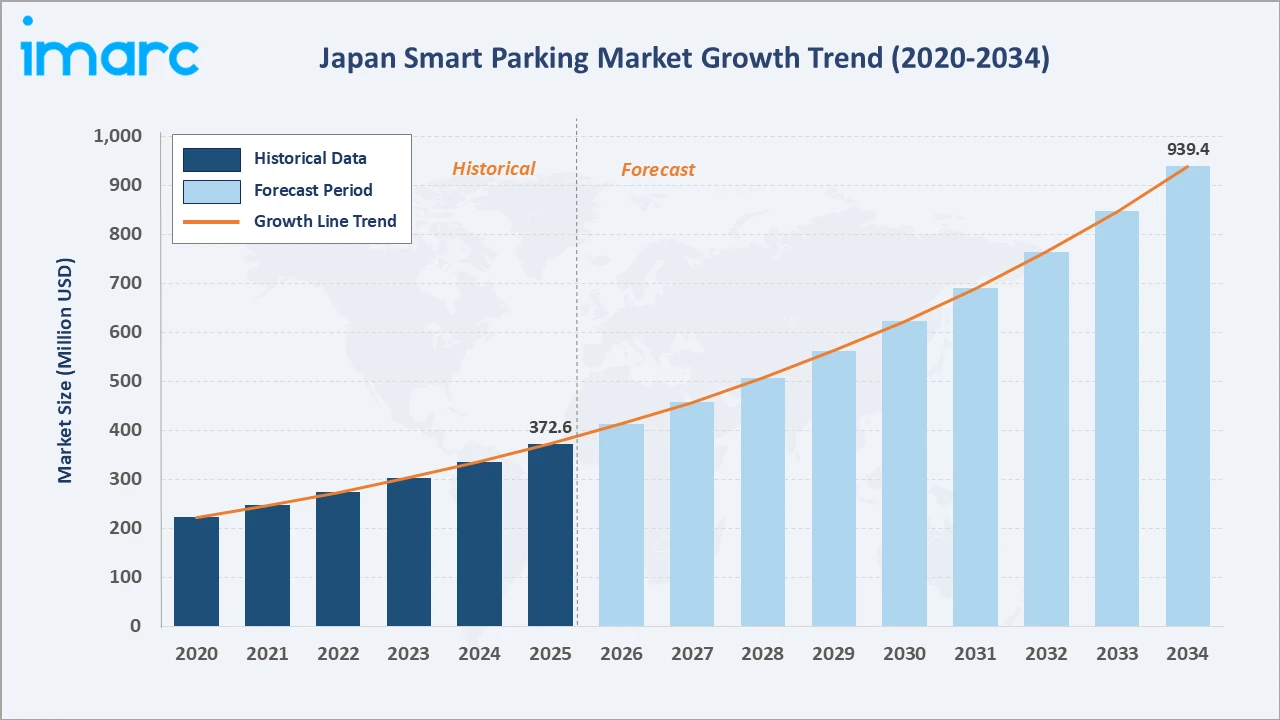
The Japan smart parking market reached USD 372.6 Million in 2025 and is estimated at USD 412.9 Million in 2026. It is projected to reach USD 939.4 Million by 2034, growing at a CAGR of 10.82% during 2026-2034, supported by urban congestion and rising adoption of connected parking technologies.
Smart city initiatives, cashless payment adoption, and growing integration of park assist systems in vehicles are further supporting market growth. Guided park assist system leads systems at 58.3%. Hardware leads components at 49.7%. The Kanto Region commands 36.7% of the national market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 372.6 Million |
| Market Size (2026) | USD 412.9 Million |
| Forecast Market Size (2034) | USD 939.4 Million |
| CAGR (2026-2034) | 10.82% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant System | Guided Park Assist System (58.3%, 2025) |
| Dominant Component | Hardware (49.7%, 2025) |
| Leading Region | Kanto Region (36.7%, 2025) |
The Japan smart parking market size increased from USD 222.9 Million in 2020 to USD 372.6 Million in 2025 and is estimated to reach USD 412.9 Million in 2026. The market is further expected to grow to USD 622.8 Million by 2030 and USD 939.4 Million by 2034.
To get more information on this market, Request Sample
The Japan smart parking market combines a dense network of unmanned coin parking facilities, advanced automotive electronics, and a strong culture of technology adoption. Parking operators, equipment manufacturers, automotive suppliers, and platform providers are digitalizing parking across cities, commercial facilities, and transport hubs.
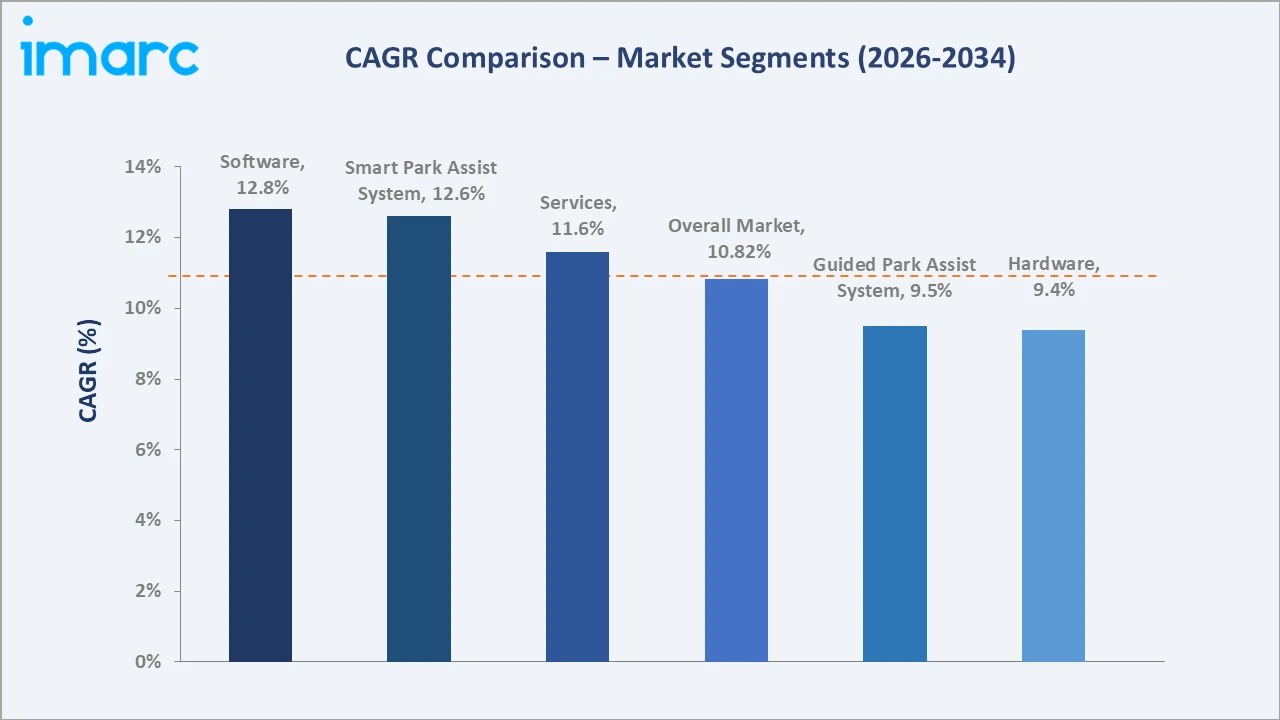
Software grows fastest at ~12.8% CAGR as parking operators adopt cloud platforms, reservation systems, and data analytics. Smart park assist systems advance at ~12.6% CAGR through automated parking features in new vehicles, while services grow at ~11.6% CAGR through system integration and managed operations.
Guided park assist systems grow at ~9.5% CAGR from a large installed base of parking guidance and sensor systems. Hardware advances at ~9.4% CAGR, supported by replacement of legacy gates and lock plates with cameras, license plate recognition units, and cashless payment terminals.
Executive Summary
The Japan smart parking market expanded from USD 372.6 Million in 2025 to an estimated USD 412.9 Million in 2026, reflecting strong demand for efficient and convenient parking in dense urban areas. Smart parking solutions help reduce congestion, improve space utilization, and enhance the driver experience.
Market growth is underpinned by limited urban space, high vehicle density in metropolitan areas, government smart city programs, and rapid adoption of cashless payments. Drivers increasingly value real-time space availability, reservation services, ticketless entry, and in-vehicle assistance that simplifies parking in tight spaces.
The market is projected to reach USD 939.4 Million by 2034. Guided park assist system at 58.3% leads through widespread parking guidance deployments. Hardware at 49.7% reflects investment in sensors, cameras, and terminals. The Kanto Region leads regionally at 36.7%.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant System | Guided Park Assist System - 58.3% share (2025) |
| Dominant Component | Hardware - 49.7% market share (2025) |
| Leading Region | Kanto Region - 36.7% share (2025) |
| Market Opportunity | Ticketless license plate recognition parking; reservation and parking sharing platforms; automated valet parking; EV charging integration at parking facilities |
Key Analytical Observations Supporting the Above Data:
- Guided Park Assist System at 58.3%: Guided park assist systems dominate as they are widely deployed in commercial garages, shopping centers, and transport hubs. Sensors, indicator lights, and digital signage guide drivers to available spaces, reducing search time, congestion, and emissions in busy parking facilities.
- Hardware at 49.7%: Hardware dominates as smart parking deployments require ultrasonic sensors, cameras, license plate recognition units, gates, payment terminals, and signage. Continuous upgrades of Japan’s extensive coin parking and garage networks sustain strong demand for advanced parking equipment.
- Kanto Region at 36.7%: The Kanto Region dominates due to the dense population and vehicle traffic of Tokyo, Kanagawa, Saitama, and Chiba. Limited urban space, a large concentration of commercial facilities, and early adoption of digital parking services sustain strong smart parking demand.
Japan Smart Parking Market Overview
The Japan smart parking market sits at the intersection of urban mobility, automotive innovation, and digital payment adoption. Smart parking solutions combine sensors, cameras, software platforms, and payment systems to help drivers find, reserve, and pay for parking while enabling operators to optimize space utilization.
Solutions differ across applications. Parking facilities use guidance systems, license plate recognition, and cashless terminals, while vehicles increasingly feature park assist systems that use ultrasonic sensors and cameras to help drivers maneuver and park in narrow spaces.
Japan's smart parking ecosystem integrates hardware manufacturers, automotive suppliers, software developers, parking operators, payment providers, system integrators, and municipalities. Macroeconomic factors include urban density, an ageing driver population, tourism recovery, and investment in smart city and mobility-as-a-service initiatives.
The market operates within a framework of parking regulations, road traffic rules, vehicle garage certificate requirements, and personal data protection laws. Government programs promoting smart cities and digital transformation encourage municipalities and operators to adopt connected parking technologies.
Market Dynamics
To evaluate market opportunities, Request Sample
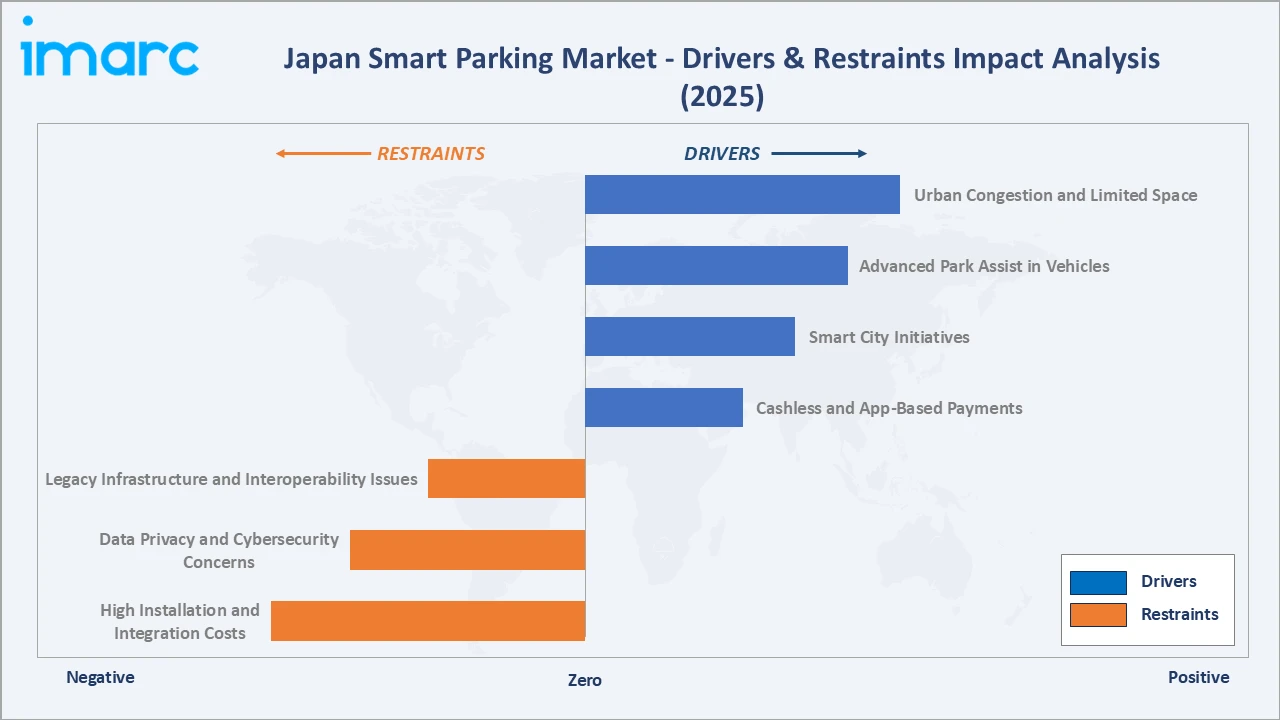
Market Drivers
- Urban Congestion and Limited Parking Space: Dense metropolitan areas face severe space constraints and high demand for parking. Smart parking solutions improve space utilization, reduce time spent searching for spaces, and ease traffic congestion, making them attractive for operators, commercial facilities, and municipalities.
- Growing Adoption of Advanced Park Assist in Vehicles: Automakers are increasingly equipping vehicles with park assist systems that use sensors and cameras to support parking maneuvers. Rising consumer demand for safety and convenience, especially among older drivers, supports adoption of guided and automated parking features.
- Smart City Initiatives and Government Digitalization: National and local government programs promoting smart cities, digital transformation, and mobility services encourage investment in connected parking infrastructure. Municipal projects integrate parking data with traffic management and public transport to improve urban mobility.
- Shift to Cashless and App-Based Parking Payments: Consumers are increasingly using QR codes, electronic money, credit cards, and mobile apps for payments. Parking operators are adopting cashless and ticketless systems that streamline entry and exit, reduce operating costs, and enable reservation and dynamic pricing services.
Market Restraints
- High Installation and Integration Costs: Deploying sensors, cameras, payment systems, and software platforms requires significant upfront investment. Smaller parking operators and facilities in less congested areas may delay upgrades due to cost concerns and uncertain returns.
- Data Privacy and Cybersecurity Concerns: Smart parking systems collect license plate data, payment information, and location data. Ensuring compliance with personal information protection rules and securing connected systems against cyber threats increases complexity and costs for providers and operators.
- Legacy Infrastructure and Interoperability Issues: Many parking facilities use older equipment that is difficult to integrate with new digital platforms. Lack of standardized interfaces among systems from different vendors can slow upgrades and limit seamless data sharing across parking networks.
Market Opportunities
- Automated Valet Parking: Advances in vehicle automation and infrastructure-based guidance create opportunities for automated valet parking, where vehicles park themselves in designated facilities. Early deployments in commercial and logistics facilities can establish new service models for operators and technology providers.
- EV Charging Integration: Growing electric vehicle adoption creates opportunities to integrate charging stations with smart parking systems. Combined parking and charging reservations, payment, and space management can improve utilization and create new revenue streams for parking operators.
Market Challenges
- Ageing Workforce and Maintenance Needs: Maintaining large networks of unmanned parking facilities requires skilled technicians and reliable remote monitoring. Labor shortages in maintenance and field services can challenge operators as system complexity increases.
- Lower Adoption in Rural Areas: Smaller cities and rural regions often have lower parking pressure and limited budgets for digital infrastructure. Slower adoption outside major metropolitan areas can limit market expansion and create uneven technology availability across regions.
Emerging Market Trends
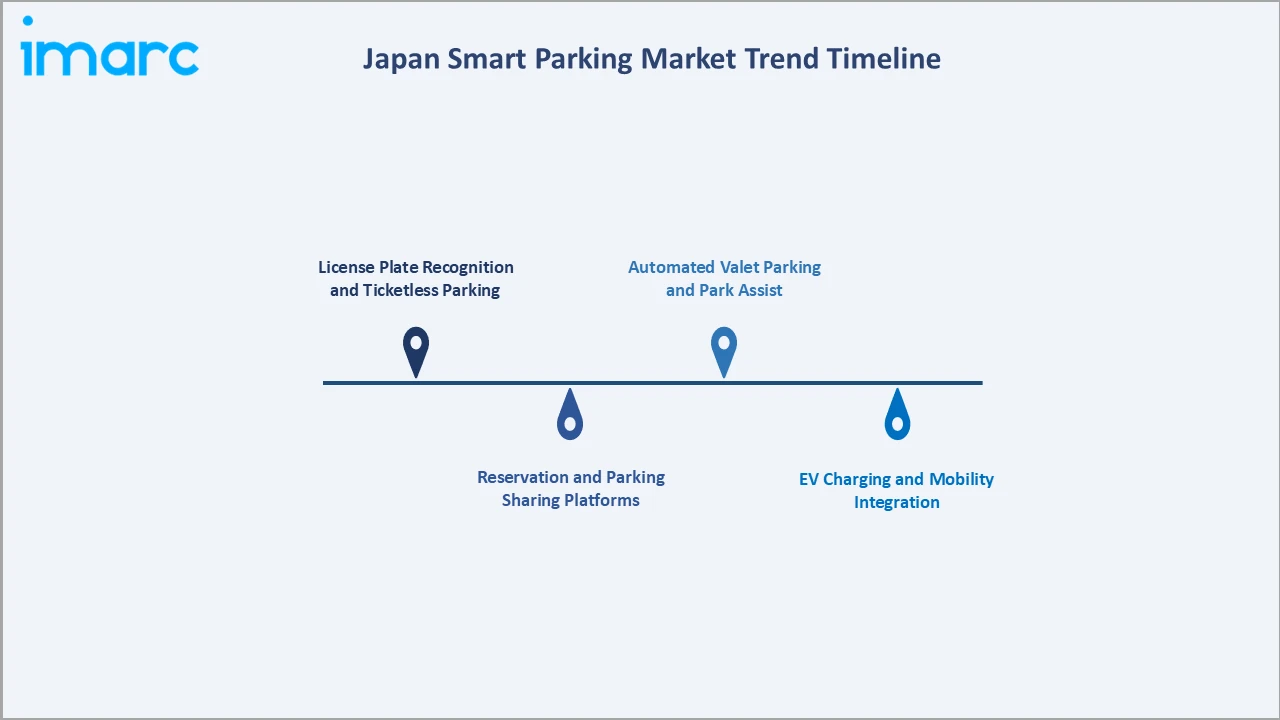
1. License Plate Recognition and Ticketless Parking
Parking operators are replacing ticket machines and lock plates with license plate recognition cameras and ticketless systems. These solutions enable smoother entry and exit, automatic payment through registered accounts, and better detection of unpaid use, improving convenience and operating efficiency.
2. Reservation and Parking Sharing Platforms
Mobile apps that allow drivers to reserve parking spaces in advance and platforms that let owners share unused private spaces are gaining popularity. These services improve space availability during events and peak periods and help monetize underused parking assets.
3. Automated Valet Parking and Advanced Park Assist
Automotive suppliers and parking operators are developing automated parking functions, from in-vehicle park assist to infrastructure-supported valet parking. International standards and demonstration projects are supporting gradual commercialization of driverless parking in controlled facilities.
4. Integration with EV Charging and Mobility Services
Smart parking platforms are increasingly integrated with electric vehicle charging, car sharing, and mobility-as-a-service applications. This integration allows drivers to find, reserve, charge, and pay in one service, while operators gain new ways to utilize parking assets.
Industry Value Chain Analysis
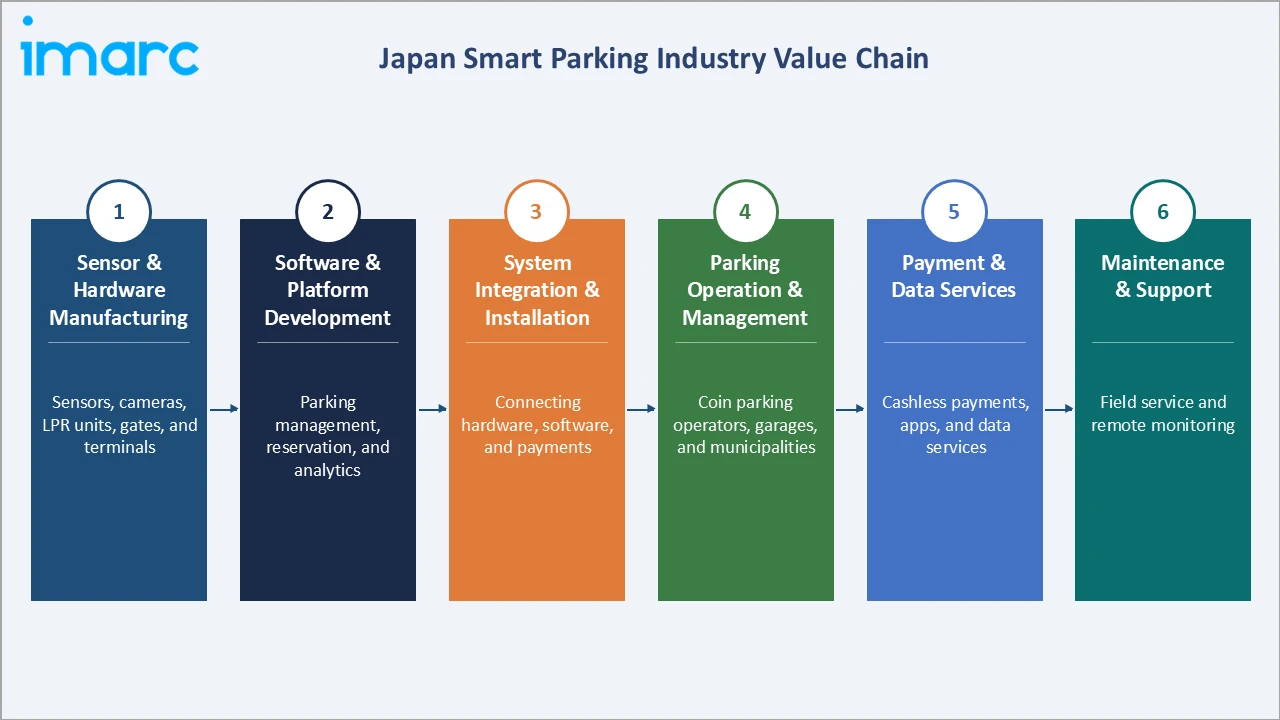
The Japan smart parking market value chain spans sensor and hardware manufacturing, software and platform development, system integration, parking operation, payment and data services, and maintenance. Each stage requires coordination between manufacturers, software developers, operators, and payment providers to deliver seamless parking experiences.
| Stage | Key Participants |
|---|---|
| Sensor & Hardware Manufacturing | Producers of ultrasonic sensors, cameras, LPR units, gates, payment terminals, and signage |
| Software & Platform Development | Developers of parking management, reservation, guidance, and analytics platforms |
| System Integration & Installation | Integrators installing and connecting hardware, software, and payment systems at facilities |
| Parking Operation & Management | Coin parking operators, garage managers, commercial facilities, and municipalities |
| Payment & Data Services | Cashless payment providers, app platforms, and data service companies |
| Maintenance & Support | Field service teams and remote monitoring centers ensuring system uptime |
Software and platform development is the most strategically consequential stage, as reservation, payment, and data analytics capabilities determine service quality and operator efficiency. Hardware manufacturing adds value through sensor accuracy and durability, while parking operation shapes customer experience and space utilization.
Maintenance and support also play a decisive role, as unmanned facilities depend on reliable equipment and rapid issue resolution. Remote monitoring centers and predictive maintenance help operators manage large parking networks efficiently across urban and regional locations.
Technology Landscape in the Japan Smart Parking Industry
Sensors, Cameras and License Plate Recognition
Ultrasonic sensors, image sensors, and AI-enabled cameras detect vehicle presence, guide drivers to available spaces, and recognize license plates. Improved recognition accuracy under varied lighting and weather conditions enables ticketless entry, automated payment, and real-time occupancy monitoring across facilities.
Cloud Platforms, IoT and Data Analytics
Cloud-based parking management platforms connect IoT devices across multiple sites, enabling centralized monitoring, dynamic pricing, and reservation services. Data analytics help operators forecast demand, optimize pricing and space allocation, and integrate parking information with navigation and mobility applications.
Vehicle Park Assist and Automated Valet Technologies
In-vehicle park assist systems use ultrasonic sensors, surround-view cameras, and steering control to guide or automate parking maneuvers. Automated valet parking combines vehicle automation with infrastructure sensors and communication systems, allowing vehicles to park themselves in equipped facilities.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| System | Guided Park Assist System | 58.3% | 2025 |
| Technology | 🔒 | 🔒 | 2025 |
| Component | Hardware | 49.7% | 2025 |
| Solution | 🔒 | 🔒 | 2025 |
| Vertical Type | 🔒 | 🔒 | 2025 |
| Parking Site | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 36.7% | 2025 |

By System
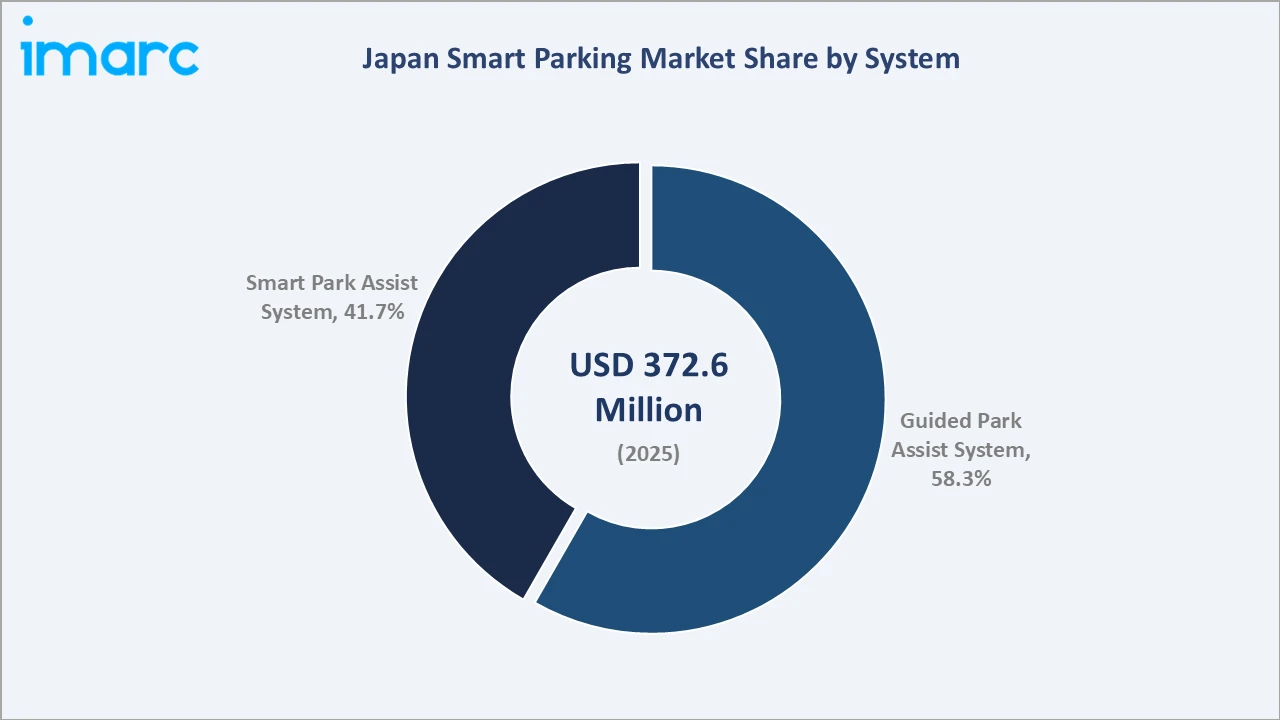
Guided park assist system leads at 58.3% (2025). The segment benefits from widespread deployment in commercial garages, shopping centers, airports, and stations. Space detection sensors, indicator lights, and digital signage reduce search time and congestion, improving facility efficiency and driver satisfaction.
To access detailed market analysis, Request Sample
Guided systems are also being upgraded with camera-based detection and app integration, allowing drivers to check space availability before arrival. These upgrades extend the value of existing installations and support operators seeking better utilization data.
Smart park assist system holds 41.7% and grows faster at ~12.6% CAGR, supported by automated parking features in new vehicles and infrastructure-supported valet parking initiatives. These systems assist or control steering, acceleration, and braking during parking maneuvers.
System adoption differs by user. Facility operators primarily invest in guidance infrastructure, while automakers and suppliers drive smart park assist adoption in vehicles, creating complementary growth paths that together improve parking efficiency and safety.
By Component
Hardware leads at 49.7% (2025). Sensors, cameras, license plate recognition units, gates, payment terminals, and signage form the foundation of smart parking systems. Replacement of legacy equipment across Japan’s large network of parking facilities sustains strong hardware demand.
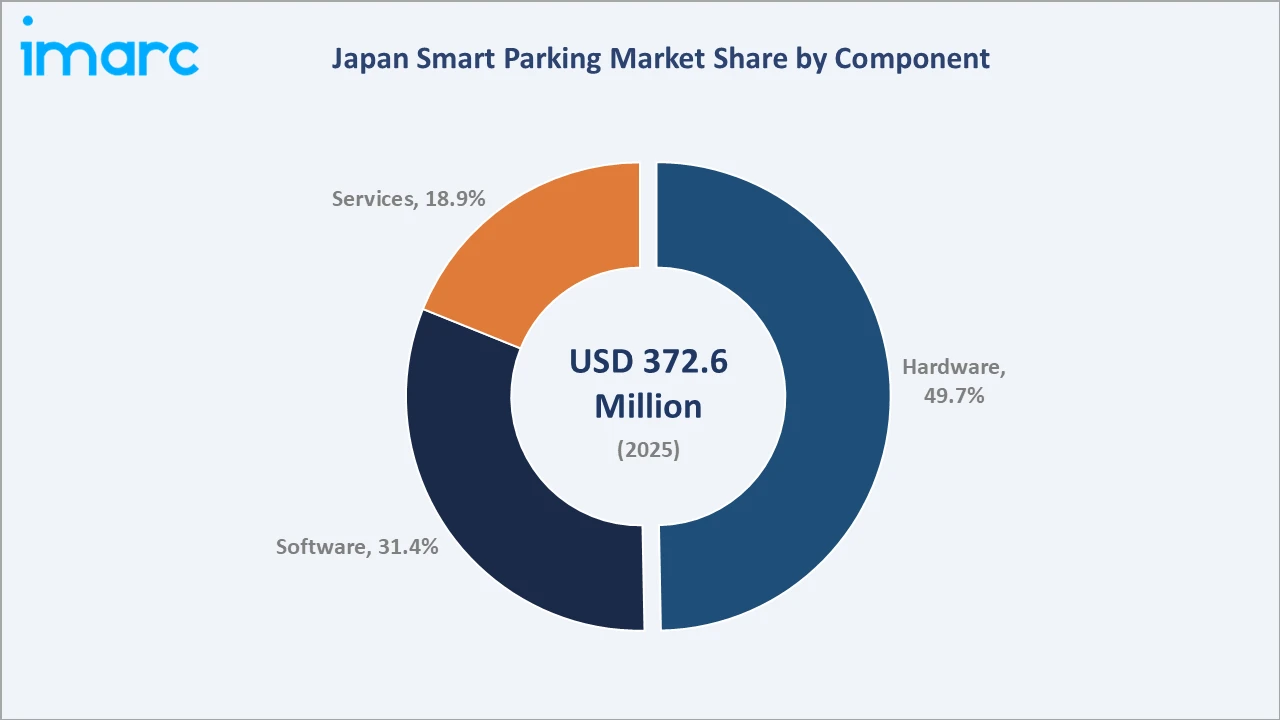
Hardware demand is further supported by the shift toward cashless and ticketless operations, which requires new cameras, terminals, and connectivity devices. Durable, weather-resistant equipment is important for outdoor coin parking lots across diverse climatic conditions.
Software holds 31.4% and grows fastest at ~12.8% CAGR through cloud parking management, reservation, and analytics platforms. Services account for 18.9%, including system integration, installation, maintenance, and managed operations that support reliable performance of smart parking networks.
The component mix is gradually shifting toward software and services as operators move to subscription-based platforms, remote monitoring, and data-driven management. This transition increases recurring revenue opportunities for technology providers over the forecast period.
Regional Market Insights
| Region | Share (2025) | Key Japan Smart Parking Market Drivers & Characteristics |
|---|---|---|
| Kanto Region | 36.7% | Driven by Tokyo metropolitan density, limited space, and extensive coin parking and garage networks. |
| Kansai/Kinki Region | 19.8% | Supported by Osaka, Kyoto, and Kobe urban centers, tourism, and commercial facility upgrades. |
| Central/Chubu Region | 16.4% | Driven by Nagoya’s automotive industry, high car ownership, and commercial parking demand. |
| Kyushu-Okinawa Region | 9.6% | Supported by Fukuoka’s urban growth, tourism, and airport and station parking upgrades. |
| Tohoku Region | 6.9% | Gradual adoption in Sendai and regional cities through municipal and commercial projects. |
| Chugoku Region | 5.8% | Supported by Hiroshima and Okayama urban centers and commercial facility parking upgrades. |
| Hokkaido Region | 3.0% | Driven by Sapporo urban parking, tourism demand, and winter-resistant parking solutions. |
| Shikoku Region | 1.8% | Gradual adoption supported by regional cities and tourism-related parking facilities. |
The Kanto Region's 36.7% market leadership reflects Tokyo’s dense population, high parking demand, and concentration of parking operators and technology providers. The Kansai/Kinki Region's 19.8% reflects strong urban activity in Osaka, Kyoto, and Kobe, along with tourism-driven parking demand.
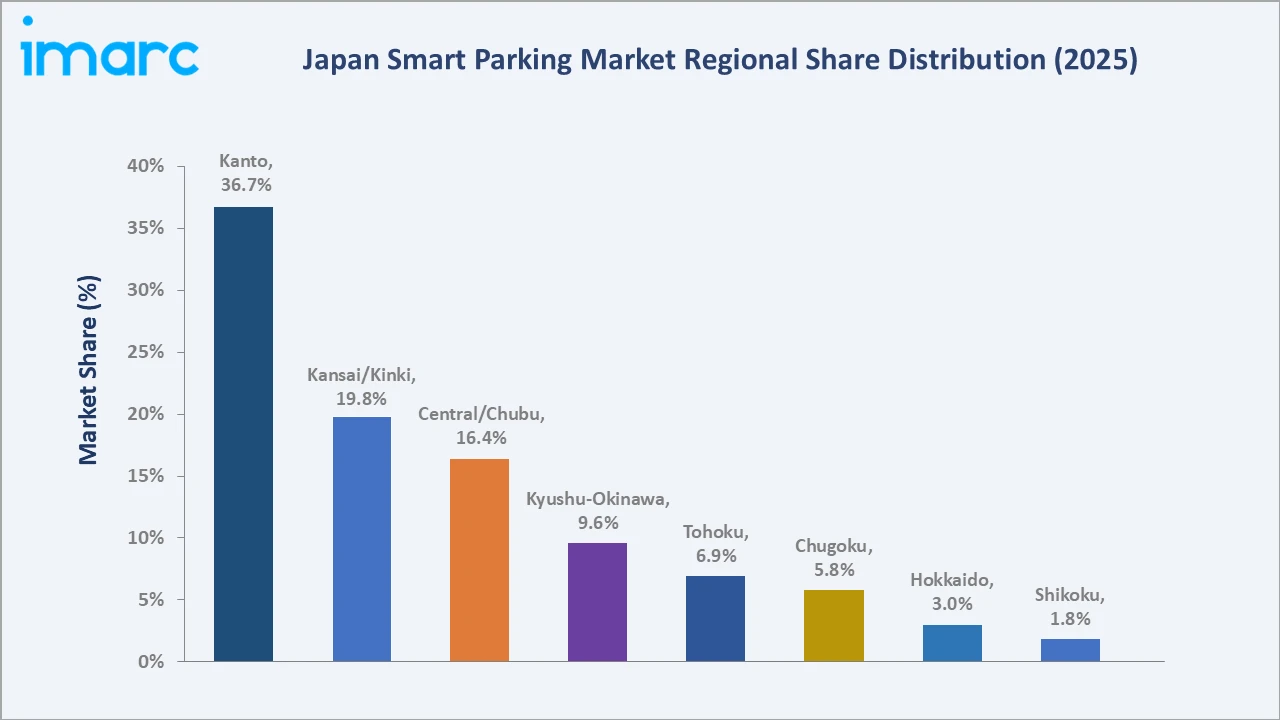
Regional adoption is also shaped by car dependency and urban density. Metropolitan areas lead in ticketless and reservation-based parking, while regions with higher car ownership show strong demand for commercial facility parking systems and in-vehicle park assist technologies.
The Central/Chubu Region's 16.4% is supported by Nagoya’s automotive industry and high car ownership, while Kyushu-Okinawa at 9.6% benefits from Fukuoka’s growth and tourism. Tohoku (6.9%), Chugoku (5.8%), Hokkaido (3.0%), and Shikoku (1.8%) show gradual adoption through municipal and commercial projects.
Regional cities are expected to adopt smart parking more widely over the forecast period as municipalities pursue smart city programs, tourism destinations upgrade visitor parking, and operators extend cloud-based management platforms beyond major metropolitan areas.
Competitive Landscape
The Japan smart parking market competitive landscape is moderately concentrated, combining major parking operators, parking equipment manufacturers, automotive suppliers, and parking sharing platforms. Competition is intensifying through cashless and ticketless systems, license plate recognition, reservation services, and advanced park assist technologies.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| PARK24 Co., Ltd. | Times PARKING, Times CAR, Times PAY | Market Leader | Japan’s largest hourly parking network with integrated mobility services. |
| Amano Corporation | Amano Parking Systems | Market Leader | Long-established parking equipment maker with ticketless LPR solutions. |
| Robert Bosch GmbH | Bosch | Market Leader | Automotive sensors and park assist technologies, including automated parking. |
| The Nippon Signal Co., Ltd. | Nippon Signal Parking Systems | Strong Challenger | Parking equipment and transport systems for operators and municipalities. |
| Aisin Corporation | Automated Parking System | Innovator | Pioneer of automatic parking assist and automated valet parking development. |
| Denso Corporation | DENSO | Innovator | Advanced driver assistance sensors supporting vehicle park assist systems. |
| akippa Inc. | akippa | Niche Player | Parking sharing and reservation platform using unused private spaces. |
The competitive landscape's most significant dynamic is the convergence of parking infrastructure and vehicle technologies. Parking operators and equipment makers compete on cashless, ticketless, and reservation services, while automotive suppliers compete on sensor performance and automated parking capabilities.
Strategic priorities across leading participants include expanding license plate recognition and cashless systems, developing cloud parking platforms, advancing automated valet parking, integrating EV charging and car sharing, and partnering with municipalities and mobility service providers.
Key Company Profiles
PARK24 Co., Ltd.
PARK24 Co., Ltd. is a Japanese parking and mobility services company operating the Times PARKING network of unmanned hourly parking facilities nationwide, along with Times CAR car sharing, payment services, and platform services for other parking operators.
- Key Brands: Times PARKING, Times CAR, Times PAY, Times CLUB, among others.
- Recent Developments: In March 2026, Times Mobility Co., Ltd., a PARK24 Group company, partnered with Tobu Railway Co., Ltd. to introduce the Tobu Car Share service along the Tobu Railway line, linking car sharing with rail stations and parking.
- Strategic Focus: Expanding cashless, camera-based next-generation parking facilities and integrating parking with car sharing and mobility services.
Amano Corporation
Amano Corporation is a Japanese manufacturer of time information, parking, environmental, and cleaning systems. Its parking business offers gate and flap-lock systems, vehicle guidance, license plate recognition, and parking management solutions in Japan and overseas.
- Key Brands: Amano parking systems, Amano ONE.
- Recent Developments: In September 2026, Amano McGann, Amano Corporation’s US subsidiary, introduced ONEflex Ticketless LPR, a new Amano ONE feature that uses license plate recognition to create a virtual ticket at entry while retaining traditional ticket options when needed.
- Strategic Focus: Advancing ticketless license plate recognition and cloud-based parking management solutions across global markets.
Robert Bosch GmbH
Robert Bosch GmbH is a global technology and automotive supplier operating in Japan through Bosch Corporation. It develops sensors, driver assistance systems, park assist solutions, and automated parking technologies for automakers and parking infrastructure.
- Key Brands: Bosch.
- Recent Developments: In June 2025, Bosch in Japan introduced a parking assist system tailored to Japan’s unique parking environment, developed by its Japanese engineering team, which starts automated parking upon driver instruction using images captured by near-range cameras.
- Strategic Focus: Developing park assist and automated parking technologies adapted to Japanese vehicles and parking conditions.
Market Concentration Analysis
The Japan smart parking market is moderately concentrated, with a few large parking operators and equipment manufacturers accounting for a significant share of facility-based solutions. Automotive park assist technologies are supplied by a concentrated group of global and domestic suppliers, while parking apps remain more fragmented.
Market concentration is evolving through two opposing forces. Leading operators and equipment makers are consolidating positions through nationwide networks and integrated platforms. At the same time, app-based reservation and sharing services increase fragmentation by enabling new entrants to monetize private parking spaces.
Entry barriers remain moderate to high in equipment and automotive segments due to technology, reliability, and certification requirements. In app-based services, barriers are lower, although building user bases and partnerships with operators remains essential for success.
Investment & Growth Opportunities
Highest Growth Segments
Software (~12.8% CAGR through cloud platforms), smart park assist systems (~12.6% CAGR through vehicle automation), services (~11.6% CAGR through integration and managed operations), and guided park assist systems (~9.5% CAGR through facility upgrades) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Ticketless parking represents an emerging opportunity, as operators replace legacy equipment with license plate recognition and cashless systems. Providers offering integrated hardware, software, and payment solutions can capture significant upgrade demand across Japan.
EV charging and mobility integration add further potential. Parking facilities equipped with chargers, car sharing, and reservation services can attract more users, while integrated platforms create new revenue streams for operators and technology providers.
Investment Themes
- Ticketless parking upgrades in Kanto and Kansai: Investing in license plate recognition, cashless terminals, and cloud management for high-traffic urban facilities can improve throughput, reduce operating costs, and enhance driver convenience in the largest parking markets.
- Automated valet and EV-ready parking facilities: Developing facilities that support automated parking and integrated EV charging can position operators and suppliers for future vehicle technologies and growing electric vehicle adoption.
Future Market Outlook (2026-2034)
The Japan smart parking market is projected to grow from USD 372.6 Million in 2025 to USD 412.9 Million in 2026, reaching USD 939.4 Million by 2034, registering a CAGR of 10.82% during 2026-2034. The anchor value of USD 622.8 Million in 2030 marks a structural inflection point.
By 2030, ticketless and cashless parking is expected to become standard in major cities, software platforms will account for a growing share of value, and automated parking features will be more common in new vehicles and equipped facilities.
Three structural forces define market growth through 2034 urban congestion and limited space increasing demand for efficient parking, digital payments and cloud platforms transforming facility operations, and vehicle automation expanding park assist and automated valet capabilities.
Over the forecast period, companies that combine reliable hardware with cloud platforms, payment integration, and mobility partnerships are expected to gain share. Investments in data analytics, EV charging integration, and automated parking will be critical for long-term competitiveness.
Research Methodology
Primary Research
Primary research comprised structured interviews with Japan smart parking industry stakeholders, including parking operators, equipment manufacturers, automotive suppliers, software developers, system integrators, payment providers, and municipal officials across Kanto, Kansai, Chubu, and other regions.
Secondary Research
Secondary research encompassed government statistics, vehicle registration data, smart city program documents, company websites, press releases, annual reports, industry association publications, and trade press coverage. Over 50 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a demand-side model combining parking facility counts, equipment upgrade cycles, vehicle park assist penetration, and average solution values by component. Regional facility data and operator investment plans were used to validate the aggregated forecast.
Japan Smart Parking Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Systems Covered | Guided Park Assist System, Smart Park Assist System |
| Technologies Covered | Ultrasonic, RFID, IoT |
| Components Covered | Hardware, Software, Services |
| Solutions Covered | Security and Surveillance, Valet and Parking Reservation, License Plate Recognition |
| Vertical Types Covered | Government and Municipalities, Commercial Institutions, Transport Facilities |
| Parking Sites Covered | Off-Street Parking, On-Street Parking |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | PARK24 Co., Ltd., Amano Corporation, Robert Bosch GmbH, The Nippon Signal Co., Ltd., Aisin Corporation, Denso Corporation, akippa Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan smart parking market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan smart parking market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan smart parking industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Smart Parking Market Report
The Japan smart parking market size is estimated at USD 412.9 Million in 2026, driven by urban congestion, cashless payment adoption, and smart city initiatives. Growing integration of park assist systems in vehicles further supports market expansion.
The Japan smart parking market grows at a 10.82% CAGR during 2026-2034, reaching USD 939.4 Million by 2034. Growth is sustained by ticketless parking upgrades, cloud platforms, vehicle automation, and EV charging integration.
Guided park assist system leads at 58.3% through widespread deployment in commercial garages, shopping centers, airports, and stations. Camera-based upgrades and app integration further extend the value of these installations.
Hardware leads at 49.7% through demand for sensors, cameras, license plate recognition units, gates, and payment terminals. Replacement of legacy equipment with cashless and ticketless systems sustains this demand.
The Kanto Region leads at 36.7% through Tokyo’s dense population, high parking demand, and extensive parking networks. Early adoption of reservation and ticketless services further strengthens regional leadership.
Leading companies include PARK24 Co., Ltd., Amano Corporation, Robert Bosch GmbH, The Nippon Signal Co., Ltd., Aisin Corporation, DENSO CORPORATION, and akippa Inc., among others.
The Japan smart parking market is projected to reach approximately USD 622.8 Million by 2030, with ticketless parking becoming standard, software gaining share, and automated parking features expanding.
Three priority investment opportunities include ticketless parking upgrades in Kanto and Kansai, automated valet and EV-ready parking facilities, and cloud-based parking management platforms.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade