
Japan Two-Wheeler Market Size, Share, Trends and Forecast by Type, Technology, Transmission, Engine Capacity, Fuel Type, Distribution Channel, End User, and Region, 2026-2034
Japan Two-Wheeler Market Size, Share, Trends & Forecast (2026-2034)
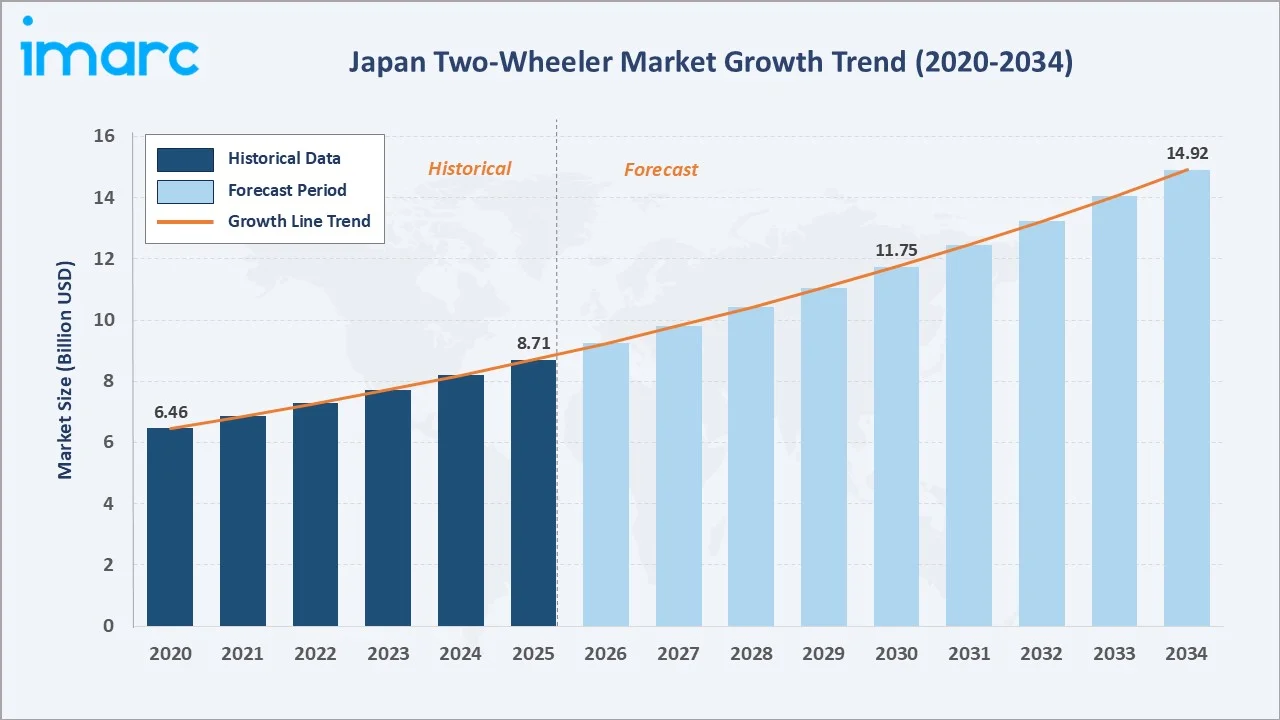
The Japan two-wheeler market grew from USD 8.71 Billion in 2025 to USD 9.24 Billion in 2026 and is projected to reach USD 14.92 Billion by 2034, growing at a CAGR of 6.17% during 2026-2034. The market is driven by robust domestic demand for scooters, rising electric two-wheeler adoption, strong OEM innovation from various manufacturers and government incentives promoting zero-emission vehicles. Japan's aging population and urban commuter culture sustain scooter dominance, while motorcycle tourism and enthusiast culture drive premium segment growth.
Growing EV infrastructure, rising fuel costs, and Japan's decarbonisation commitments are accelerating electric two-wheeler adoption. Automatic transmission leads at 61.8%. Scooters dominate type-wise at 38.7%. Kanto Region commands 32.7% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 8.71 Billion |
|
Market Size (2026) |
USD 9.24 Billion |
|
Forecast Market Size (2034) |
USD 14.92 Billion |
|
CAGR (2026-2034) |
6.17% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Transmission |
Automatic (61.8%, 2025) |
|
Dominant Type |
Scooters (38.7%, 2025) |
|
Leading Region |
Kanto Region (32.7%, 2025) |
The Japan two-wheeler market size increased from USD 6.46 Billion in 2020 to USD 8.71 Billion in 2025 and is estimated to reach USD 9.24 Billion in 2026. The market is further expected to grow to USD 11.75 Billion by 2030 and USD 14.92 Billion by 2034. Japan two-wheeler market uniquely combines one of the world's most sophisticated OEM production ecosystems with a mature domestic commuter base, a rapidly electrifying urban mobility segment, and a growing premium motorcycle culture underpinned by motorcycle tourism and enthusiast culture.
To get more information on this market, Request Sample
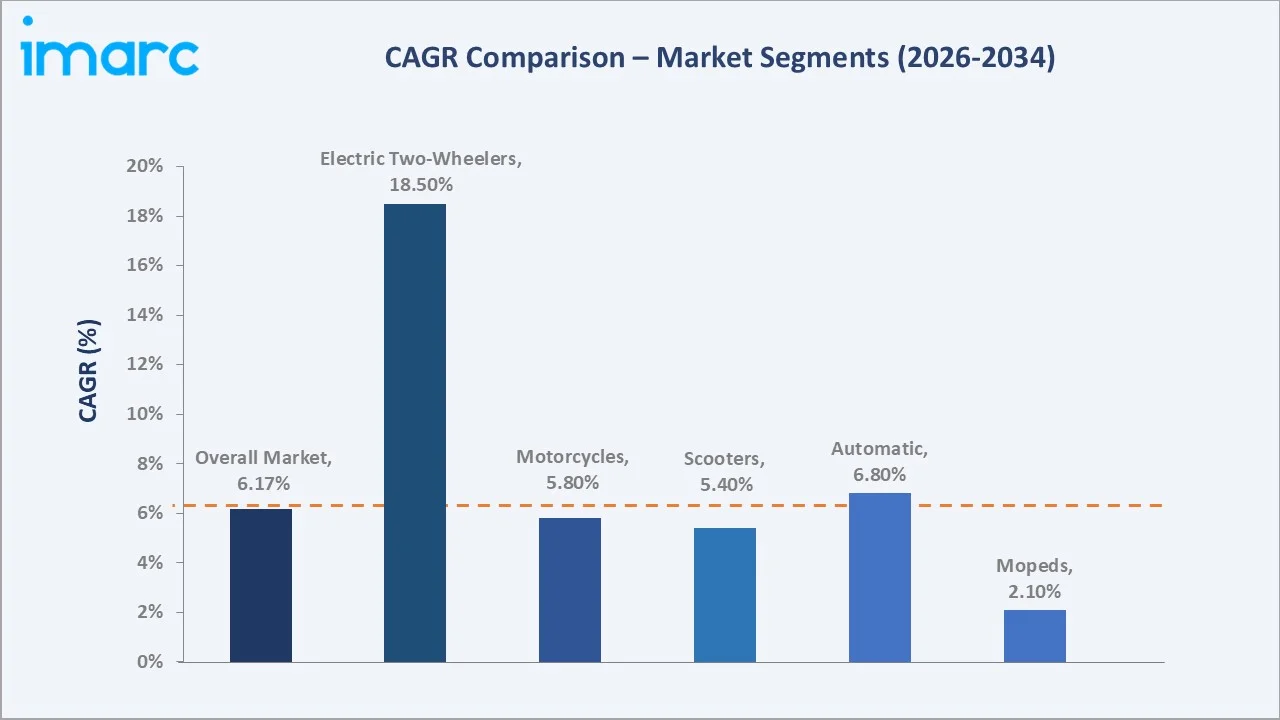
Electric two-wheelers are the fastest-growing segment at approximately 18.5% CAGR, propelled by government subsidies, the Honda-Yamaha-Suzuki-Kawasaki-KTM battery swap consortium, and growing commercial delivery fleet electrification. Automatic transmission gains share as scooter volumes expand and rider demographics broaden toward older and urban commuter profiles.
Executive Summary
The Japan two-wheeler market expanded from USD 8.71 Billion in 2025 to an estimated USD 9.24 Billion in 2026, positioning Japan as Asia's third-largest two-wheeler market by value. The market is projected to reach USD 14.92 Billion by 2034. Automatic transmission leads at 61.8%, scooters at 38.7%, and Kanto Region at 32.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Transmission |
Automatic – 61.8% share (2025) |
|
Dominant Type |
Scooters – 38.7% market share (2025) |
|
Leading Region |
Kanto Region – 32.7% share (2025) |
|
Market Opportunity |
Electric two-wheeler infrastructure; premium motorcycle tourism; export-linked domestic demand; subscription-based urban commuter mobility services |
Key Analytical Observations Supporting the Above Data:
- Automatic at 61.8%: Scooter dominance and aging rider demographics drive automatic preference. Low-maintenance, fuel-efficient automatic scooters appeal to urban commuters and older riders transitioning from manual motorcycles to easy-to-operate platforms across Japan's dense metropolitan areas.
- Scooters at 38.7%: Urban commuting culture, compact road infrastructure, and economic efficiency of 50-125cc scooters sustain volume leadership. Japan's food delivery platform boom has further accelerated commercial scooter demand from Uber Eats and Demae-can fleet operators.
- Kanto Region at 32.7%: Tokyo-Yokohama metropolitan density, Japan's largest authorised dealership network concentration, and the highest commercial delivery fleet operator density create the strongest two-wheeler demand cluster nationally, reinforced by the highest EV subsidy utilisation rates.
Japan Two-Wheeler Market Overview
Japan two-wheeler market is commercially positioned at a globally unique intersection: the world's most technically advanced two-wheeler OEM production base, a mature domestic market with high per-capita ownership, a rapidly transitioning electric mobility adoption curve, and a growing premium motorcycle culture that creates above-average export demand from Japanese brands serving global enthusiast markets.
Japan two-wheeler ecosystem integrates domestic OEM manufacturing, sophisticated dealership networks, government-supported EV infrastructure, and export logistics. Macroeconomic factors include Japan's carbon neutrality goal for 2050, urban mobility policy favouring light vehicles, and demographic ageing increasing demand for easy-to-operate automatic scooters.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
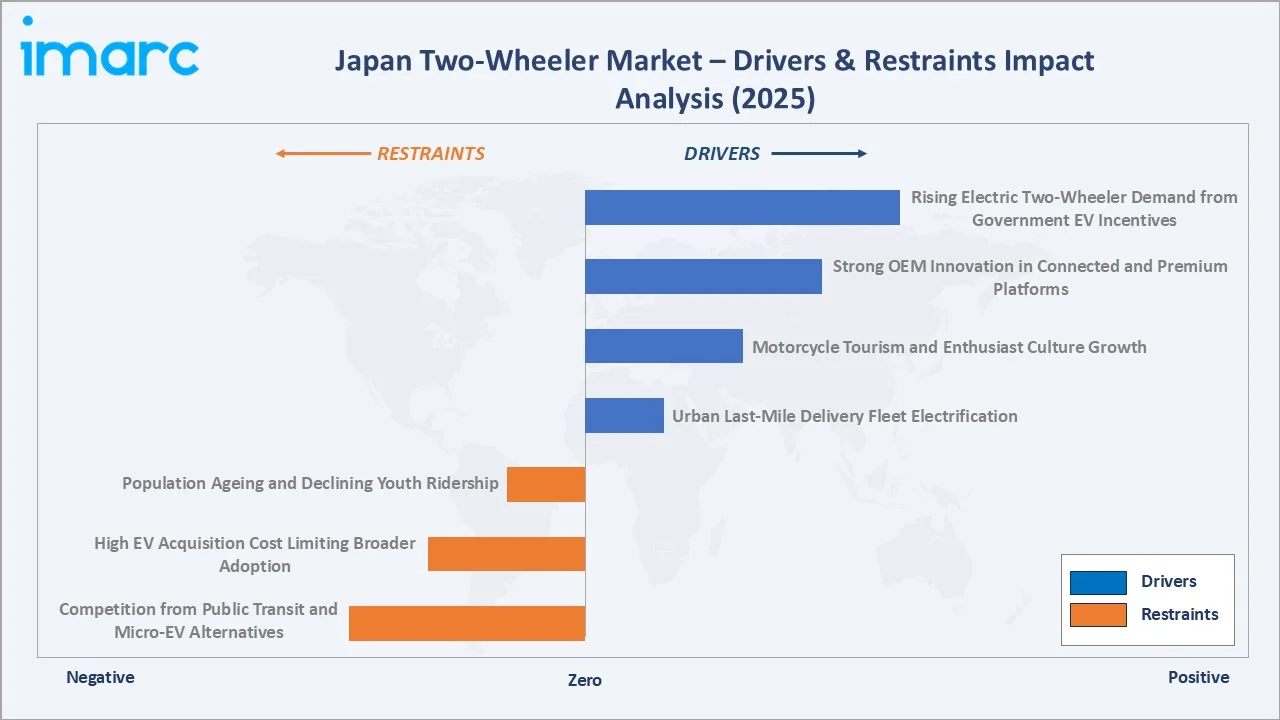
- Rising Electric Two-Wheeler Demand from Government EV Incentives: Japan's Ministry of the Environment and METI provide purchase subsidies and infrastructure grants supporting electric motorcycle and scooter adoption. Various companies have entered mass consumer market pricing through government subsidy programmes, driving EV category. The electric two-wheeler segment is further supported by the eMC battery consortium developing standardised swappable batteries. Commercial delivery fleet operators are accelerating EV scooter procurement as total cost of ownership achieves ICE parity in urban environments with subsidy support applied.
- Strong OEM Innovation in Connected and Premium Platforms: Companies are integrating smartphone connectivity, ride-by-wire throttle, cornering ABS, and semi-active suspension into mid-premium and premium motorcycle categories. The premium motorcycle segment above 500cc grows at above-market CAGR through Japan's experienced rider demographic upgrading. Connected platform investment creates above-mechanical-specification commercial differentiation, supporting premium pricing. Japan's OEM technology leadership drives brand premium globally and strengthens domestic consumer preference for home-brand models across all segments.
- Motorcycle Tourism and Enthusiast Culture Growth: Japan's motorcycle tourism market, including Hokkaido's summer touring circuit, Mt. Fuji road networks, and organised club riding events, creates structured above-average demand for large-displacement touring and adventure motorcycles. Japan's domestic motorcycle club registrations are increasing, creating a commercial enthusiast ecosystem that supports premium brand sales and aftermarket parts demand. Motorcycle tourism investment by prefectural governments in rural Japan further institutionalises long-distance riding routes that catalyse premium two-wheeler demand.
- Urban Last-Mile Delivery Fleet Electrification: Japan's e-commerce logistics expansion, food delivery platform growth, and courier service proliferation have created above-market growth for commercial scooter and electric moped segments. Delivery operators are transitioning fleet procurement toward electric models, driven by operational cost savings and urban low-emission zone compliance. Platform operators are formally piloting electric scooter fleet incentive programmes to reduce delivery carbon footprints and operational fuel costs simultaneously.
Market Restraints
- Population Ageing and Declining Youth Ridership: Japan's demographic decline reduces the youth motorcycle purchasing cohort that historically drives entry-level and mid-range two-wheeler sales volume. The 18-24 age group's declining population share, combined with higher urban youth preference for public transit and shared mobility, creates structural volume compression in the mass-market two-wheeler segment. This pressure particularly affects 50-125cc entry-level motorcycles and youth-oriented scooter categories. Japan's total new two-wheeler registrations have declined from peak levels, with demographic factors cited as the primary structural driver of below-peak unit volume.
- High EV Acquisition Cost Limiting Broader Adoption: Honda's electric scooter lineup is priced at JPY 300,000-500,000 even after subsidies, with Kawasaki's Ninja e-1 exceeding JPY 700,000, limiting mainstream adoption outside urban higher-income demographics. High battery replacement costs and limited EV charging infrastructure outside major cities constrain total cost of ownership competitiveness against ICE alternatives in rural regions. Subsidy programme complexity and annual budget caps create uncertainty for consumers planning EV purchases. The premium acquisition cost barrier is particularly significant for commercial delivery operators with large fleet transition investment requirements.
- Competition from Public Transit and Micro-EV Alternatives: Japan's extensive Shinkansen, metro, and bus networks provide direct substitutes for personal two-wheeler commuting in metropolitan areas. The emergence of compact EV kei-cars and e-bikes further segments the urban short-distance mobility market, reducing the addressable commuter opportunity for traditional two-wheelers. E-bike adoption is growing in Japan, directly competing with low-displacement scooters and mopeds for urban short-distance mobility occasions. Public transit reliability and density in Tokyo and Osaka are significantly above global norms, creating high substitutability between rail commuting and personal two-wheeler ownership.
Market Opportunities
- Electric Two-Wheeler Ecosystem Investment: Japan's standardised battery swap initiative, developed through the various consortium, creates infrastructure investment opportunities in charging and swap station networks. Standardised swappable batteries reduce per-charge wait time to under 60 seconds, removing the most commercially significant barrier to EV scooter adoption for commercial delivery operators. Swap station deployment along Japan's urban commuter corridors represents a first-mover infrastructure opportunity. The consortium's standardised battery format potentially enables future export of the swap infrastructure model to other Asian EV two-wheeler markets.
- Premium Motorcycle and Aftermarket Segment Expansion: Japan's adventure touring, premium sport, and cruiser segments are growing at above-domestic-GDP CAGR, creating expanding aftermarket accessories, riding apparel, and motorcycle lifestyle product demand. The increasing registered motorcycle club members represent a high-spending enthusiast consumer base underserved by current retail infrastructure. Premium motorcycle tourism infrastructure investment by rural prefectures creates ancillary revenue streams. Export-oriented premium motorcycle production expansion creates parallel domestic premium model availability that strengthens Japan's domestic premium motorcycle market supply diversity.
Market Challenges
- EV Technology Transition Managing ICE-to-Electric Fleet Shift: Japan's two-wheeler OEMs face simultaneous ICE optimisation and EV platform development investment requirements, compressing margins and R&D allocation across technology generations. Dealer network EV service capability development requires technician training, EV-specific diagnostic equipment, and battery service infrastructure investment exceeding typical ICE service upgrade timelines. The transition period creates operational complexity for dealerships simultaneously servicing ICE, hybrid, and full-EV platforms. Consumer uncertainty about EV technology maturity and resale value further slows adoption beyond early-adopter commercial segments, requiring sustained OEM investment in consumer education programmes.
- Rural-Urban Infrastructure Disparity for EV Adoption: Japan's EV charging infrastructure is concentrated in urban prefectures, creating significant EV adoption barriers in rural regions including Hokkaido, Tohoku, and Shikoku, where longer inter-city distances make electric two-wheelers commercially uncompetitive. Motorcycle tourism's commercial importance in rural Japan creates a structural contradiction where the highest-growth premium motorcycle market depends on ICE long-range capability. Rural prefectural governments face budget constraints limiting EV infrastructure investment in low-population-density areas. Seasonal riding restriction in northern Japan further reduces EV infrastructure utilisation rates in regions where motorcycle use is concentrated in 5-7 months annually.
Emerging Market Trends
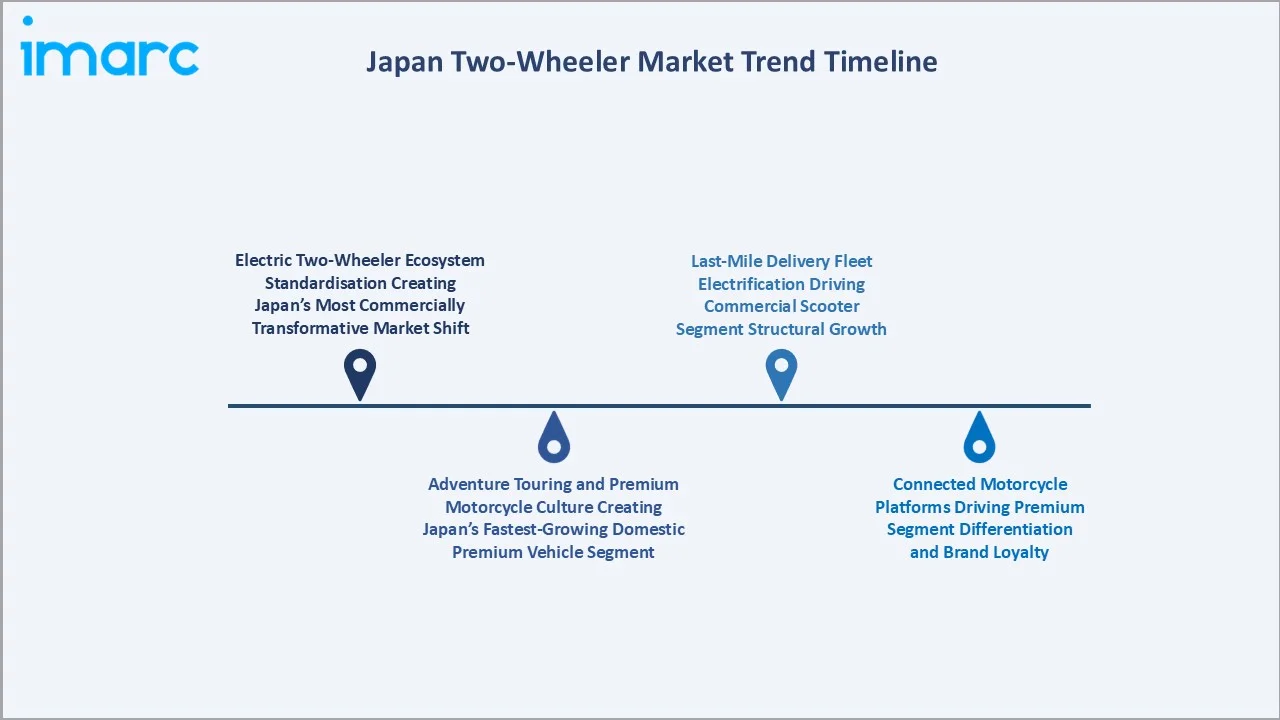
1. Electric Two-Wheeler Ecosystem Standardisation Creating Japan's Most Commercially Transformative Market Shift
The four-OEM battery swap consortium represents Japan's most commercially consequential two-wheeler market development. Standardised swappable batteries eliminate range anxiety and charging time barriers, enabling electric scooters to achieve commercial delivery fleet total cost of ownership parity with ICE alternatives within Japan's urban environments. The consortium's commercial deployment timeline targets Tokyo, Osaka, and Nagoya urban commercial corridors as initial anchor swap station markets before national expansion.
2. Adventure Touring and Premium Motorcycle Culture Creating Japan's Fastest-Growing Domestic Premium Vehicle Segment
Japan's adventure touring motorcycle segment is growing, driven by motorcycle tourism cultural growth, Hokkaido and rural Japan touring circuit popularity, and Japan's experienced rider demographic upgrade pattern.
3. Connected Motorcycle Platforms Driving Premium Segment Differentiation and Brand Loyalty
Leading motorcycle manufacturers are increasingly integrating connected technologies such as smartphone connectivity, navigation, digital displays, ride tracking, and vehicle-management applications across premium and mid-to-premium models. These connected features enhance the overall riding experience while providing manufacturers with additional opportunities for product differentiation and customer engagement. Greater integration of software and digital services can strengthen brand loyalty, support premium pricing, and create recurring aftermarket and digital-service opportunities beyond traditional mechanical features.
4. Last-Mile Delivery Fleet Electrification Driving Commercial Scooter Segment Structural Growth
The continued expansion of e-commerce, food delivery, and on-demand logistics is increasing demand for two-wheelers used in last-mile delivery operations. Fleet operators are increasingly evaluating electric scooters and motorcycles due to their lower operating and maintenance costs, suitability for urban routes, and growing emissions-related requirements. This transition is supporting structural growth in the commercial electric two-wheeler segment and is expected to remain an important demand driver alongside consumer-led EV adoption.
Industry Value Chain Analysis
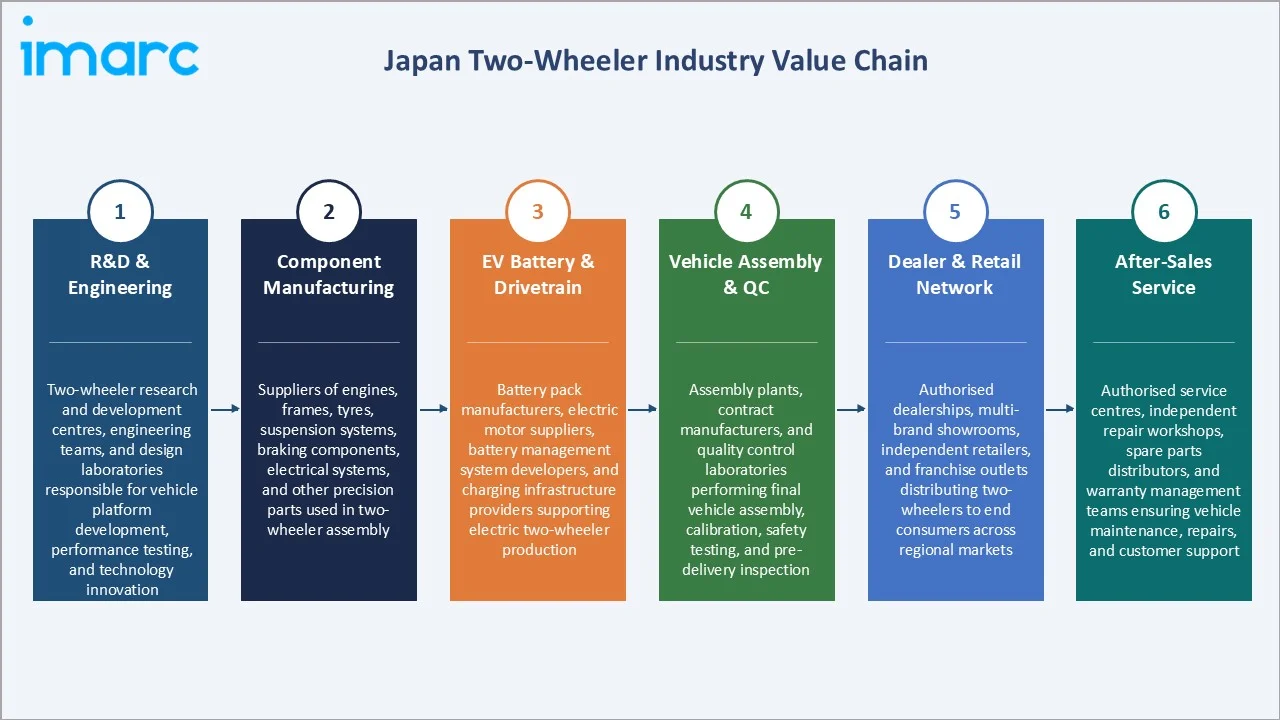
Japan two-wheeler value chain is the most technically integrated of any national two-wheeler market, with Japan's four major OEMs controlling design, engineering, and key component manufacturing across a co-located supplier base. This vertical integration creates above-global-average innovation speed and product quality, sustaining Japan's premium commercial positioning in global export markets.
|
Stage |
Key Participants |
|
R&D & Engineering |
Two-wheeler research and development centres, engineering teams, and design laboratories responsible for vehicle platform development, performance testing, and technology innovation |
|
Component Manufacturing |
Suppliers of engines, frames, tyres, suspension systems, braking components, electrical systems, and other precision parts used in two-wheeler assembly |
|
EV Battery & Drivetrain |
Battery pack manufacturers, electric motor suppliers, battery management system developers, and charging infrastructure providers supporting electric two-wheeler production |
|
Vehicle Assembly & QC |
Assembly plants, contract manufacturers, and quality control laboratories performing final vehicle assembly, calibration, safety testing, and pre-delivery inspection |
|
Dealer & Retail Network |
Authorised dealerships, multi-brand showrooms, independent retailers, and franchise outlets distributing two-wheelers to end consumers across regional markets |
|
After-Sales Service |
Authorised service centres, independent repair workshops, spare parts distributors, and warranty management teams ensuring vehicle maintenance, repairs, and customer support |
The component supply and EV battery & drivetrain stages are the two most commercially consequential stages for Japan's two-wheeler market transformation through 2034, as the eMC battery consortium's standardisation reduces OEM-specific battery lock-in and enables Japan's commercial EV scooter ecosystem to scale across multiple OEM platforms simultaneously.
Technology Landscape in the Japan Two-Wheeler Industry
Internal Combustion Engine (ICE) Technology
Internal combustion engines, particularly fuel-injected four-stroke engines across a broad range of displacement categories, continue to account for a significant share of Japan's two-wheeler market. Improvements in fuel efficiency, emissions performance, reliability, and engine refinement are helping ICE-powered motorcycles and scooters remain competitive, particularly for long-distance, touring, and applications where refueling convenience and established infrastructure remain important. These factors are expected to support the continued relevance of ICE technology alongside the gradual adoption of electric two-wheelers.
Electric Vehicle (EV) Drivetrain and Battery Technology
Advancements in electric drivetrains, lithium-ion batteries, battery management systems, and charging solutions are supporting the gradual expansion of electric two-wheelers in Japan. Manufacturers are introducing electric scooters and motorcycles across urban commuting, personal mobility, and commercial applications, with product development increasingly focused on improving driving range, charging convenience, battery life, and overall performance. Battery-swapping solutions and improved energy density are also helping address range and charging-related limitations, supporting wider adoption of electric two-wheelers over the forecast period.
Connected Motorcycle and Advanced Rider Assistance Systems (ARAS)
Connected technologies and advanced rider assistance systems are becoming increasingly important differentiators in Japan's two-wheeler market. Features such as smartphone connectivity, navigation, digital instrumentation, traction control, cornering ABS, ride modes, and other electronic assistance systems are being incorporated across mid-range and premium motorcycles. These technologies enhance safety, convenience, and riding experience while enabling manufacturers to differentiate products beyond conventional mechanical specifications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Scooters |
38.7% |
2025 |
|
Technology |
🔒 |
🔒 |
2025 |
|
Transmission |
Automatic |
61.8% |
2025 |
|
Engine Capacity |
🔒 |
🔒 |
2025 |
|
Fuel Type |
🔒 |
🔒 |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
32.7% |
2025 |

By Transmission
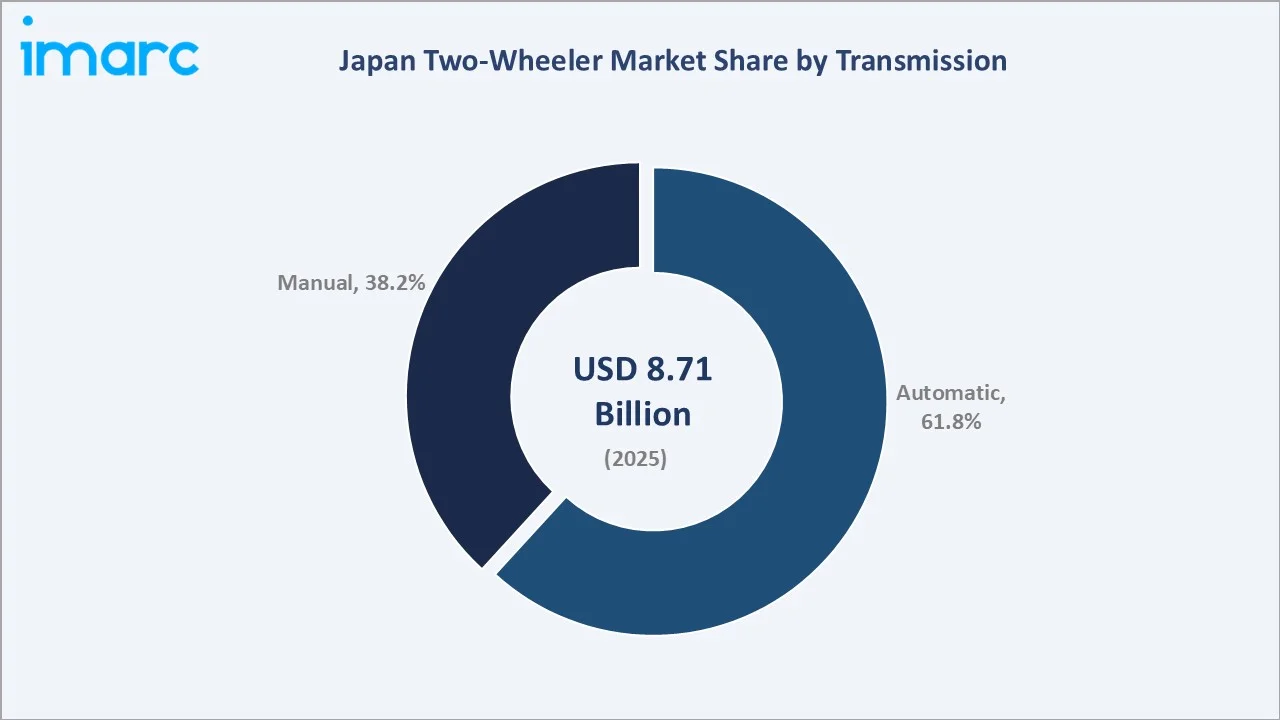
Automatic leads at 61.8% (2025). The automatic transmission segment encompasses Japan's dominant scooter volume and represents the preferred choice of urban commuters, older riders, and commercial delivery fleet operators who value low operating complexity and reduced rider fatigue in stop-start urban traffic.
To access detailed market analysis, Request Sample
Manual transmission at 38.2% serves Japan's motorcycle enthusiast and performance-oriented rider demographics, covering sport motorcycles, adventure tourers, and large-displacement cruisers where driver engagement and mechanical control are core product attributes.
By Type
Scooters lead at 38.7% (2025). Japan's scooter segment is the commercial cornerstone of domestic two-wheeler demand, covering various platforms. Scooters dominate urban commuting, food delivery, and small business logistics use cases across Japan's metropolitan areas.
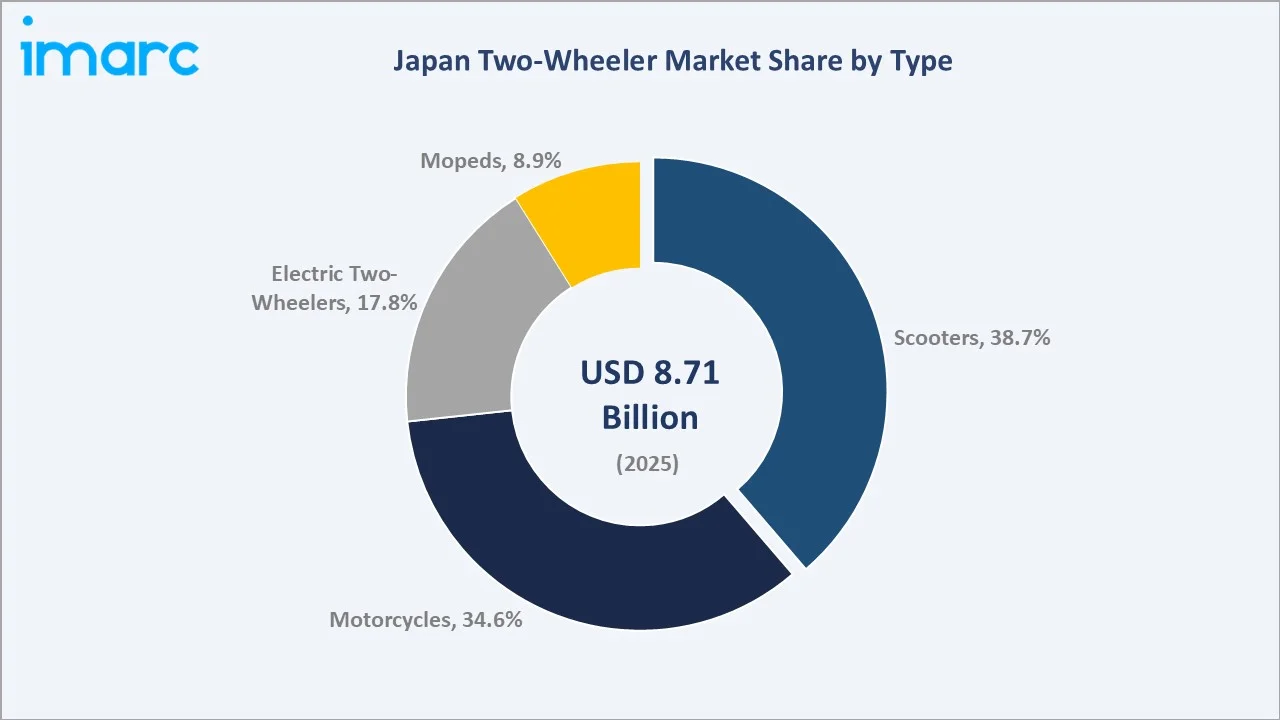
Motorcycles at 34.6% serve Japan's performance, touring, and enthusiast segments. Electric two-wheelers at 17.8% are the fastest-growing category at approximately 18.5% CAGR. Mopeds at 8.9% serve sub-50cc utility and entry-level commuter use cases, though this segment faces structural volume decline from e-bike competition and demographic contraction in the youth cohort.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Two-Wheeler Market Drivers & Characteristics |
|
Kanto Region |
32.7% |
Tokyo-Yokohama metro commuter density, largest authorised dealer network, delivery fleet concentration, and highest EV subsidy uptake rates drive the dominant regional market position. |
|
Kansai/Kinki Region |
20.4% |
Osaka-Kobe-Kyoto metropolitan corridor supporting urban scooter commuting, premium motorcycle retail, and growing e-commerce delivery fleet demand across Japan's second-largest metro economy. |
|
Central/Chubu Region |
16.8% |
Nagoya-Toyota City industrial proximity creates strong OEM employee and supplier community two-wheeler demand; manufacturing heritage drives local consumer preference for domestic brands. |
|
Kyushu-Okinawa Region |
9.8% |
Okinawa's year-round mild climate sustains above-national per-capita scooter ownership; Fukuoka and Kumamoto urban commuter demand and Honda Kumamoto factory proximity support local market. |
|
Tohoku Region |
7.4% |
Sendai and Morioka urban commuter segments support scooter demand; rural agricultural use sustains utility bike sales; seasonal riding limits premium motorcycle CAGR below national average. |
|
Chugoku Region |
6.1% |
Hiroshima's manufacturing workforce and medium-density urban commuter base sustains entry and mid-range scooter demand; regional touring routes support motorcycle segment above unit volume share. |
|
Hokkaido Region |
4.5% |
Japan's premier motorcycle tourism destination; summer touring circuit creates seasonal premium demand spike; long winter season compresses annual unit registrations below tourism-economy potential. |
|
Shikoku Region |
2.3% |
Smallest regional market; rural commuter utility demand for small-displacement scooters and agricultural bikes; limited premium and EV market development below national penetration rates. |
Kanto Region's 32.7% market leadership reflects Tokyo's unmatched commercial density, Japan's largest authorised two-wheeler dealership cluster in Tokyo, Saitama, and Kanagawa prefectures. Kansai/Kinki Region's 20.4% reflects Osaka's commercial hub status and the Kyoto-Kobe combined urban professional commuter base.
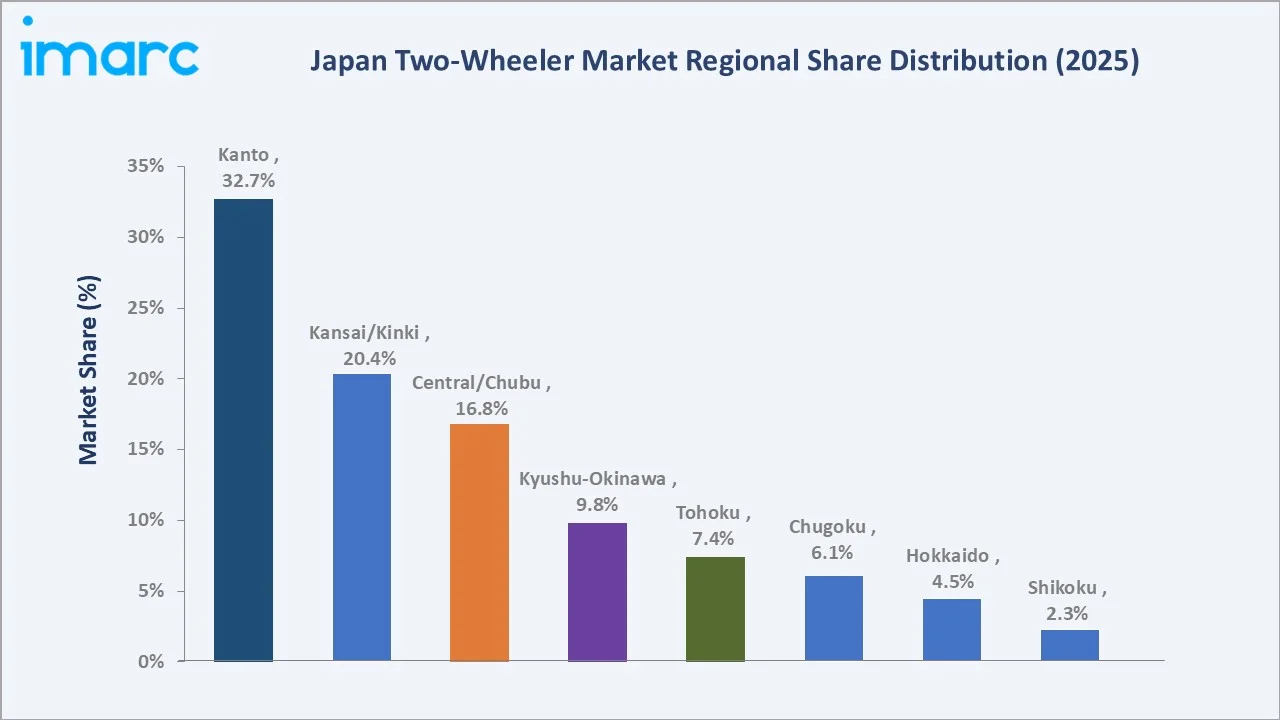
Central/Chubu Region's 16.8% reflects Nagoya's industrial base and Japan's manufacturing corridor two-wheeler commuter culture. Kyushu-Okinawa's 9.8% is commercially supported by Okinawa's year-round climate and Honda's Kumamoto manufacturing hub creating strong local brand affinity and OEM community demand from factory and supplier employees.
Competitive Landscape
Japan two-wheeler market competitive landscape is the most globally concentrated of any national two-wheeler market by OEM headquarters density. Competition is intensifying at the electric and connected vehicle segments as international brands establish Japan distribution and EV product entries.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Honda Motor Co., Ltd. | Gold Wing Tour, CB1300, NT1100, Rebel 1100, Rebel 1100T, CRF1100L, NC750X, X-ADV, CBR650R, CBR600RR | Market Leader | Dominant domestic and global OEM with broadest product range from 50cc mopeds to 1800cc touring bikes and EV platforms. |
| Yamaha Motor Co., Ltd. | N-Max, MT Series, YZF Series, TMAX560, Tracer Series, XSR Series, Tenere700, Aerox, Tricity-155 | Strong Challenger | Technology leadership in connected platforms, three-wheel LMW technology, and design-forward premium motorcycle positioning. |
| Suzuki Motor Corporation | Address, Burgman, V-Strom, GSX Series, Hayabusa | Innovator | Engineering-heritage brand; Hayabusa premium brand equity sustains above-average ASP in Japanese and global markets. |
| Kawasaki Motors Co., Ltd. | Ninja Series, Z Series, Versys, Eliminator | Established Player | Performance motorcycle leadership; first-mover in commercial electric motorcycle with Ninja e-1 and Z e-1 platforms. |
| BMW AG | R1250GS, S1000RR, F-Series, CE 04 Electric | Premium Innovator | Luxury motorcycle and electric scooter brand growing Japan dealer network in premium and adventure touring categories. |
| Harley-Davidson | Sportster, Softail, Pan America | Specialty Challenger | Lifestyle and culture brand with dedicated Japan cruiser community; LiveWire EV platform addresses Japan's EV enthusiast segment. |
Key players include Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Kawasaki Motors Co., Ltd., BMW AG, Harley-Davidson, and others.
Key Company Profiles
Honda Motor Co., Ltd.
Honda Motor Co., Ltd. is Japan's largest two-wheeler manufacturer and the world's largest by volume, headquartered in Minato, Tokyo. Honda dominates Japan's domestic market across all segments from 50cc Super Cub utility scooters to the Gold Wing 1800cc touring flagship, while pioneering commercial EV deployment through the EM1 e: platform and Honda Mobile Power Pack battery ecosystem.
- Key Brands: Gold Wing Tour, CB1300, NT1100, Rebel 1100, Rebel 1100T, CRF1100L, NC750X, X-ADV, CBR650R, CBR600RR, and others.
- Strategic Focus: Maintaining domestic market leadership through EV platform commercialisation and global scooter volume growth. Honda is investing heavily in the eMC consortium battery standardisation, leveraging its position as the world's largest two-wheeler OEM to drive adoption of swappable battery infrastructure. Expanding Honda Rider Education Programme and premium motorcycle lifestyle brand building further strengthens long-term consumer loyalty and market leadership across Japan's diverse two-wheeler demand segments.
Yamaha Motor Co., Ltd.
Yamaha Motor Co., Ltd. is Japan's second-largest two-wheeler manufacturer, headquartered in Iwata, Shizuoka Prefecture. Yamaha is known for engineering innovation in connected motorcycle platforms, three-wheel Leaning Multi-Wheel (LMW) technology, and design leadership across sport, premium, and urban mobility categories. Yamaha's MT and R-series motorcycles command premium pricing in Japan's performance segment.
- Key Brands: N-Max, MT Series, YZF Series, TMAX560, Tracer Series, XSR Series, Tenere700, Aerox, Tricity-155, and others.
- Recent Developments: In May 2026, Yamaha introduced an updated version of the XSR155 in Japan, featuring a new black colour scheme with contrasting gold detailing and bronze-finished alloy wheels. The refreshed styling gives the neo-retro motorcycle a more premium and distinctive appearance, while additional design elements such as block-pattern tyres further enhance its roadster character.
- Strategic Focus: Technology leadership in LMW platforms and connected motorcycle ecosystem development. Yamaha is advancing electric two-wheeler platform expansion through E-Vino lineup extension and new 125cc electric commuter scooter development targeting urban commercial delivery applications. Investment in Y-Connect digital connectivity infrastructure positions Yamaha to monetise aftermarket digital content and subscription services alongside physical vehicle sales, creating a new revenue stream independent of unit volume growth.
Market Concentration Analysis
Japan two-wheeler market is highly concentrated among four domestic OEMs collectively commanding an estimated 85%+ of domestic unit sales. Honda alone holds an estimated 50-55% domestic market share by unit volume, creating Japan's most commercially dominant single-OEM national market position globally. International brands hold combined share below 3% of domestic unit volume but command above-proportional revenue share through premium average selling prices.
Market concentration is evolving through two opposing forces: Japan's domestic OEMs' continued product portfolio breadth and technological leadership consolidating domestic volume leadership, while international premium brands' growing Japan dealer network incrementally builds international premium market share against Japan's domestic premium motorcycle platforms over the forecast period.
Investment & Growth Opportunities
Highest Growth Segments
Electric two-wheelers (~18.5% CAGR), manual transmission (~4.9% CAGR), scooters (~5.4% CAGR), motorcycle (~5.8% CAGR from near-zero base), and mopeds (~2.1% CAGR) represent Japan's highest-growth two-wheeler investment vectors through 2034.
Emerging Investment Opportunities
Japan's standardised battery swap network represents the highest-upside two-wheeler adjacent infrastructure investment opportunity. Swap station deployment along Japan's major urban commuter corridors and national highway rest areas creates first-mover infrastructure advantage. The consortium's standardised battery format enables potential export of the swap infrastructure model to other Asian EV two-wheeler markets where Japan-brand scooters hold dominant market positions.
Investment Themes
- EV battery swap station network deployment for urban commercial and personal electric scooter operators, targeting Tokyo-Osaka corridor initial density before national scale-up with commercial delivery fleet operators as anchor tenants.
- Premium motorcycle accessories, apparel, and aftermarket parts retail expansion targeting registered motorcycle club members and growing adventure touring enthusiast demographic with above-national spending per rider.
Future Market Outlook (2026-2034)
The Japan two-wheeler market is projected to grow from USD 8.71 Billion in 2025 to USD 9.24 Billion in 2026, reaching USD 14.92 Billion by 2034, registering a CAGR of 6.17% during 2026-2034. The market's anchor value of USD 11.75 Billion in 2030 represents Japan's two-wheeler industry at a structural EV transition inflection where electric scooter and commercial delivery fleet electrification transitions from early-adopter to mainstream adoption phase.
Three structural forces define Japan two-wheeler market growth through 2034: Japan's government carbon neutrality commitment accelerating EV two-wheeler adoption beyond commercial demand-pull; motorcycle tourism's structural growth creating above-domestic-GDP premium market demand; and Japan's ageing population creating paradoxical scooter demand growth as older riders transition from manual motorcycles to automatic scooters at higher average selling prices.
Research Methodology
Primary Research
Primary research comprised structured interviews with Japan two-wheeler industry stakeholders, including dealership owners and sales managers, OEM regional sales directors, fleet procurement managers at delivery platform operators, EV infrastructure executives, and consumer intercept survey data from two-wheeler owners across Kanto, Kansai, Chubu, and Kyushu prefectures covering commuter, enthusiast, and commercial rider segments.
Secondary Research
Secondary research encompassed Japan Automobile Manufacturers Association (JAMA) two-wheeler registration statistics, Ministry of Land Infrastructure Transport and Tourism (MLIT) vehicle type approval data, company annual reports for Honda, Yamaha, Suzuki, and Kawasaki, METI EV subsidy programme data, Japan motorcycle industry trade publications, and investor presentations. Over 60 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a segment-disaggregated bottom-up model: Japan domestic two-wheeler unit registration forecast by category multiplied by estimated average selling price per segment, summed across domestic volume and adjusted for OEM Japan-export-linked domestic market premium activity and commercial fleet segment value contribution.
Japan Two-Wheeler Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Scooters, Mopeds, Motorcycle, Electric Two-Wheeler |
| Technologies Covered | ICE, Electric |
| Transmissions Covered | Manual, Automatic |
| Engine Capacities Covered | <100cc, 100-125cc, 126-180cc, 181-250cc, 251-500cc, 501-800cc, 801-1600cc, >1600cc |
| Fuel Types Covered | Gasoline, Petrol, Diesel, LPG/CNG, Battery |
| Distribution Channel Covered | Offline Channels, Online Channels |
| End Users Covered | Personal, Commercial |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Kawasaki Motors Co., Ltd., BMW AG, Harley-Davidson, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan two-wheeler market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan two-wheeler market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan two-wheeler industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Two-Wheeler Market Report
Japan two-wheeler market size is estimated at USD 9.24 Billion in 2026, driven by rising EV adoption supported by government subsidies, resilient urban commuter scooter demand, a growing premium motorcycle segment, and Japan's four major OEM technology innovation pipelines. Commercial delivery fleet electrification and motorcycle tourism further support market expansion across urban and regional segments.
Japan two-wheeler market grows at a CAGR of 6.17% during 2026-2034, reaching USD 14.92 Billion by 2034. Growth is driven by electric two-wheeler adoption acceleration, premium motorcycle segment expansion through motorcycle tourism, and commercial delivery fleet electrification creating above-consumer-CAGR commercial EV demand within the domestic market.
Automatic transmission leads at 61.8% through Japan's scooter volume dominance, urban commuter preference for low-complexity operation, ageing rider demographic transitioning from manual to automatic platforms, and commercial delivery fleet operator preference for reduced operator training requirements and lower fatigue in stop-start urban delivery routing.
Scooters lead at 38.7% through Japan's urban commuter culture, Honda Super Cub and PCX volume dominance, food delivery fleet adoption, and the economic efficiency advantage of 50-125cc automatic scooters in Japan's congested metropolitan commuter environments. Motorcycles at 34.6% and Electric Two-Wheelers at 17.8% represent the next largest segments.
Kanto Region leads at 32.7% through Tokyo-Yokohama metropolitan density, Japan's highest concentration of authorised two-wheeler dealerships, the largest commercial delivery fleet operator concentration, and highest EV subsidy utilisation rate nationally, creating above-average electric scooter adoption ahead of other regions.
Leading companies include Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Kawasaki Motors Co., Ltd., BMW AG, Harley-Davidson, and others.
Japan two-wheeler market is projected to reach approximately USD 11.75 Billion by 2030, with electric two-wheelers transitioning to mainstream commercial adoption through battery swap network maturation, the premium motorcycle segment driving through motorcycle tourism growth.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade