
Japan Video Surveillance Systems Market Size, Share, Trends and Forecast by System Type, Component, Application, Enterprise Size, Customer Type, and Region, 2026-2034
Japan Video Surveillance Systems Market Size, Share, Trends & Forecast (2026-2034)
The Japan video surveillance systems market reached USD 4.98 Billion in 2025 and is projected to reach USD 14.27 Billion by 2034, growing at a CAGR of 12.42% during 2026-2034. The market is driven by rising public safety concerns, accelerating smart city development, and AI-powered video analytics adoption. Japan's aging population, declining workforce, and government-mandated security standards are reinforcing sustained demand. IP Surveillance dominates at 61.8%. Hardware leads component at 48.6%. Kanto Region commands 34.8% of the market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 4.98 Billion |
|
Forecast Market Size (2034) |
USD 14.27 Billion |
|
CAGR (2026-2034) |
12.42% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant System Type |
IP Surveillance (61.8%, 2025) |
|
Dominant Component |
Hardware (48.6%, 2025) |
|
Leading Region |
Kanto Region (34.8%, 2025) |
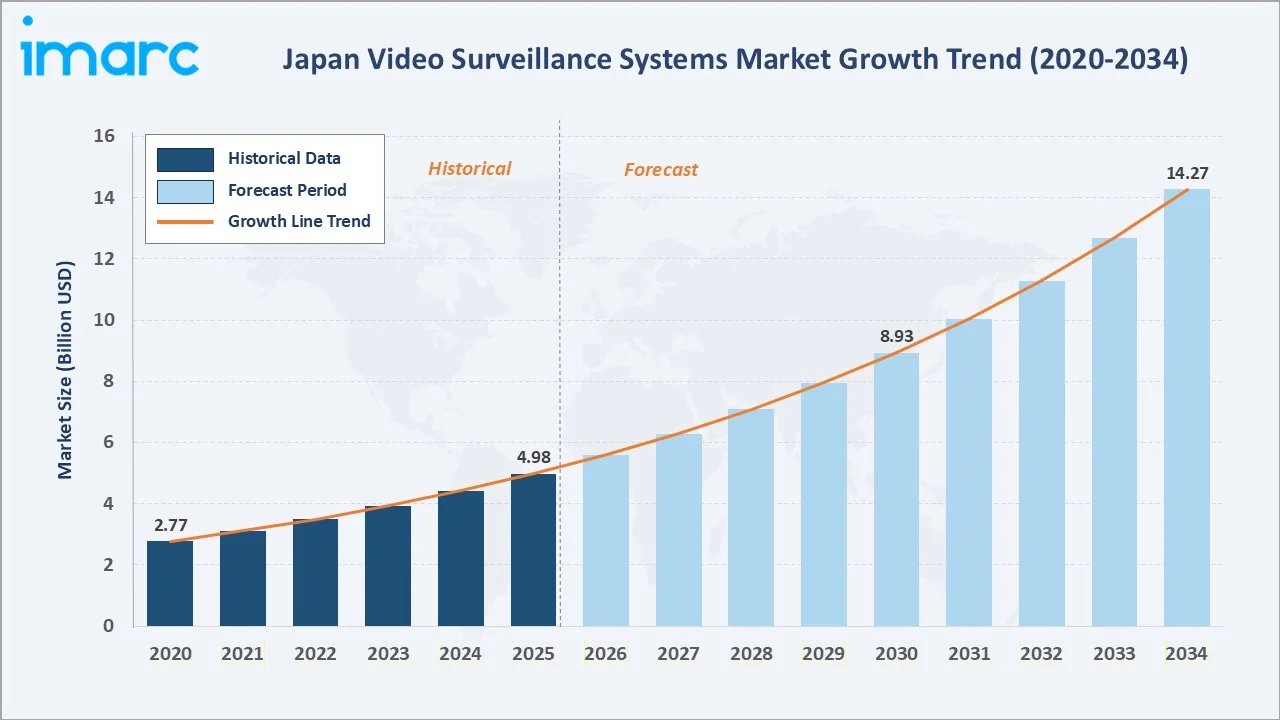
The Japan video surveillance systems market expanded from USD 2.77 Billion in 2020 to USD 4.98 Billion in 2025, anchored at USD 8.93 Billion in 2030, and forecast to reach USD 14.27 Billion by 2034. COVID-19 accelerated contactless monitoring adoption in 2020, triggering government and private sector investment in AI-powered video surveillance infrastructure. Post-pandemic smart city and public safety investment sustained above-trend market growth through 2022-2025.
To get more information on this market, Request Sample
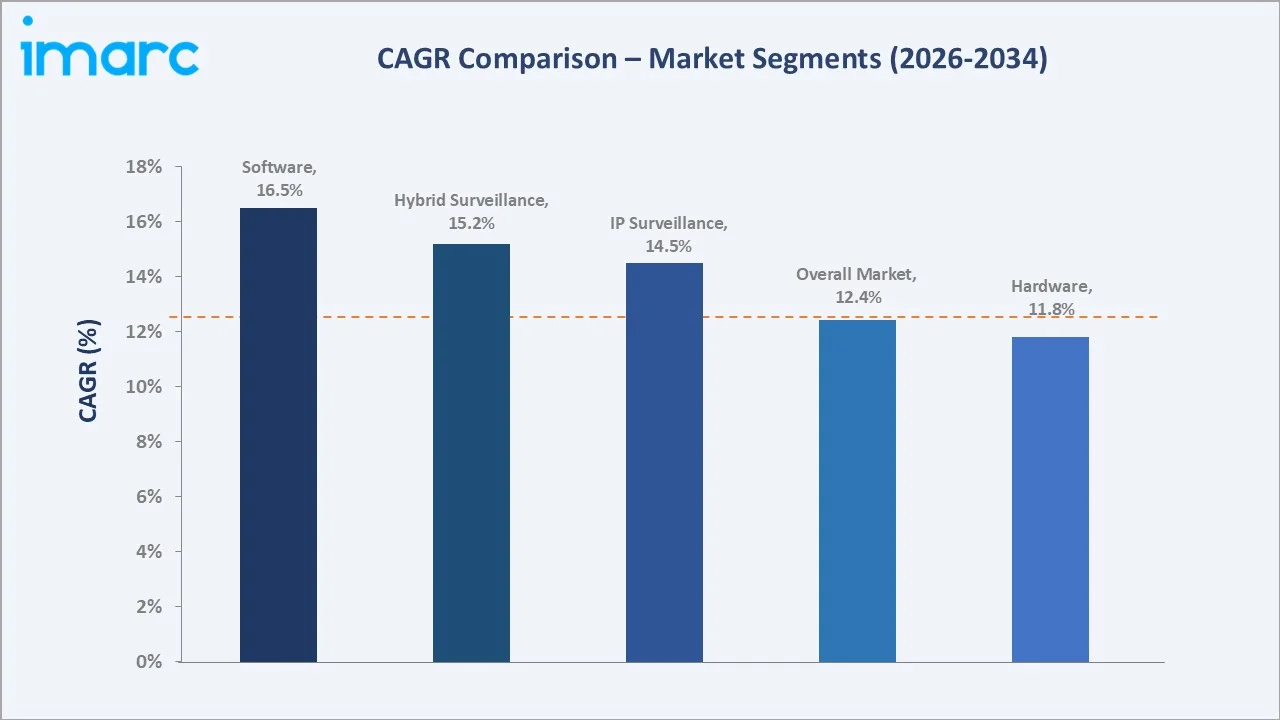
AI video analytics and edge computing integration are growing fastest at ~15%+ CAGR as Japan deploys intelligent surveillance across transportation, retail, and government facilities. IP surveillance systems grow at ~14.5% CAGR through large-scale smart city infrastructure contracts.
Executive Summary
The Japan video surveillance systems market reached USD 4.98 Billion in 2025, representing one of Asia's most advanced and rapidly evolving security technology ecosystems. The market encompasses IP cameras, analog and hybrid systems, video management software, AI analytics platforms, and associated professional installation and managed services.
IP surveillance at 61.8% dominates through superior image resolution, remote access, and AI integration advantages. Hardware at 48.6% leads components through the capital-intensive camera and recording infrastructure foundation. Kanto Region, at 34.8%, leads through Tokyo's mega-urban surveillance density and government digital transformation initiatives.
Key Market Insights
|
Insight |
Data |
|
Dominant System Type |
IP Surveillance - 61.8% share (2025) |
|
Dominant Component |
Hardware - 48.6% market share (2025) |
|
Leading Region |
Kanto Region - 34.8% market share |
|
Market Opportunity |
AI-powered analytics; cloud-based VSaaS; smart city projects; edge computing integration; 5G-enabled cameras |
Key Analytical Observations Supporting the Above Data:
- IP Surveillance at 61.8%: IP surveillance dominates due to its high-definition imaging capabilities, network integration, remote accessibility, and compatibility with AI analytics platforms. These systems are widely preferred for smart city, commercial, and critical infrastructure deployments.
- Hardware at 48.6%: Hardware components dominate because physical cameras, NVRs, and storage infrastructure represent the foundational capital investment in any surveillance deployment. Japan's aging installed base drives ongoing hardware refresh cycles.
- Kanto Region at 34.8%: Kanto Region leads through Tokyo's concentrated urban surveillance demand, government smart city contracts, and the highest density of commercial and transit security installations in Japan.
Japan Video Surveillance Systems Market Overview
The Japan video surveillance systems market encompasses the design, supply, installation, and operation of camera systems, recording infrastructure, AI-based video analytics, and integrated security management platforms across commercial, government, infrastructure, and residential end-use sectors.
Macroeconomic factors include Japan's aging society creating labor-efficient security solutions demand, government digital transformation budgets supporting smart city surveillance, and rising corporate governance standards driving enterprise security investment.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
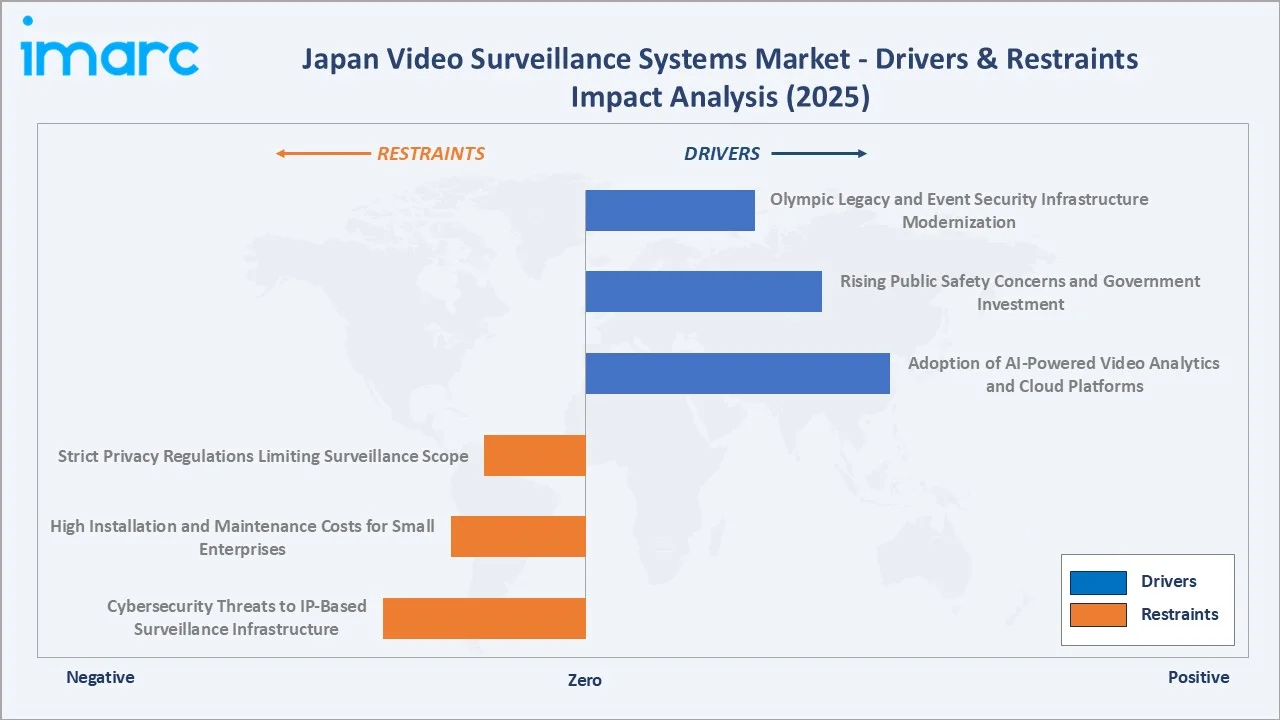
- Rising Public Safety Concerns and Government Investment: Public safety concerns are increasing government funding for advanced video surveillance infrastructure. Japan's National Police Agency and municipal governments are deploying large-scale IP camera networks in urban areas, transportation hubs, and public spaces. The 2025 Osaka Expo and ongoing Tokyo smart city programs have accelerated investment in high-definition surveillance networks. Government mandates for critical infrastructure protection under Japan's Cybersecurity Strategy are further driving procurement of integrated surveillance and analytics systems.
- Smart City and Urban Surveillance Expansion: Japan's Smart City initiative is driving systematic deployment of surveillance infrastructure across major metropolitan areas. AI-powered cameras integrated with urban management platforms are being deployed for traffic monitoring, crowd management, and public safety. These systems support Japan's Society 5.0 vision of a data-driven urban environment. Municipalities are investing in interoperable surveillance platforms that connect police, transportation, and emergency services into unified security command centers.
- Adoption of AI-Powered Video Analytics and Cloud Platforms: AI-powered analytics are transforming Japan's surveillance market from passive recording to active threat detection and behavioral analysis. Deep learning algorithms enable real-time face recognition, license plate reading, and anomaly detection across existing camera infrastructure. Cloud-based video surveillance as a service (VSaaS) is gaining traction among small and medium enterprises unable to invest in on-premise NVR infrastructure. These platforms reduce upfront capital expenditure while enabling advanced analytics capabilities.
- Olympic Legacy and Event Security Infrastructure Modernization: The legacy of the Tokyo 2020 Olympics and preparations for the 2025 Osaka Expo created permanent high-density surveillance infrastructure upgrades. Stadium-grade multi-camera deployments, AI crowd analytics, and integrated command platforms built for event security are transitioning to permanent city-wide operations. This event-driven investment cycle creates a sustained base of modern, AI-capable surveillance infrastructure for broader commercial and government utilization.
Market Restraints
- Strict Privacy Regulations Limiting Surveillance Scope: Japan's Act on the Protection of Personal Information (APPI) and evolving data privacy regulations create compliance requirements that limit aggressive surveillance expansion in public and semi-public spaces. Organizations must obtain consent, limit retention periods, and manage access controls for biometric and facial recognition data. These restrictions slow adoption in retail and hospitality sectors and increase compliance costs for enterprise deployments.
- High Installation and Maintenance Costs for Small Enterprises: Comprehensive IP surveillance system deployment requires significant capital investment in cameras, NVRs, network infrastructure, cabling, and professional integration services. Small and medium-sized enterprises in Japan often cannot justify the per-site economics of high-specification systems. Ongoing maintenance, firmware updates, and cybersecurity patching add recurring costs that reduce ROI for price-sensitive segments.
- Cybersecurity Threats to IP-Based Surveillance Infrastructure: The network connectivity of IP surveillance systems creates cybersecurity vulnerabilities that are exploited by threat actors targeting both the surveillance infrastructure and the data it collects. Japan's Critical Infrastructure Protection guidelines impose stringent network security requirements that increase system complexity and deployment costs. High-profile incidents involving compromised surveillance cameras have created procurement hesitancy among security-conscious government and enterprise buyers.
Market Opportunities
- 5G-Enabled Ultra-HD Smart Camera Networks: 5G network rollout is enabling deployment of ultra-high-definition cameras streaming uncompressed video for AI analysis at the edge and cloud. Japan's advanced 5G infrastructure creates a platform for next-generation video surveillance systems with sub-second latency analytics. These capabilities are particularly valuable for traffic management, crowd analytics, and real-time threat response applications.
- Edge AI Integration for Real-Time On-Camera Processing: Edge AI chips embedded directly in cameras enable real-time analytics processing without cloud dependency. This addresses latency, bandwidth, and data privacy concerns while enabling deployment in locations with limited connectivity. Japan's advanced semiconductor ecosystem positions domestic manufacturers to lead edge AI camera development.
Market Challenges
- Interoperability Between Legacy Analog and Modern IP Systems: Japan's large installed base of analog surveillance equipment creates integration complexity as organizations transition to IP-based systems. Hybrid systems managing both analog and IP cameras across fragmented networks require specialized middleware and skilled integration expertise. This migration complexity extends deployment timelines and increases total cost of ownership.
- Skilled Workforce Shortage for Advanced System Integration: Japan's aging workforce and declining technical education pipeline create shortages of qualified surveillance system engineers and integrators. The increasing complexity of AI-powered systems requires specialized skills combining networking, cybersecurity, and AI platform expertise that are scarce in the domestic labor market.
Emerging Market Trends
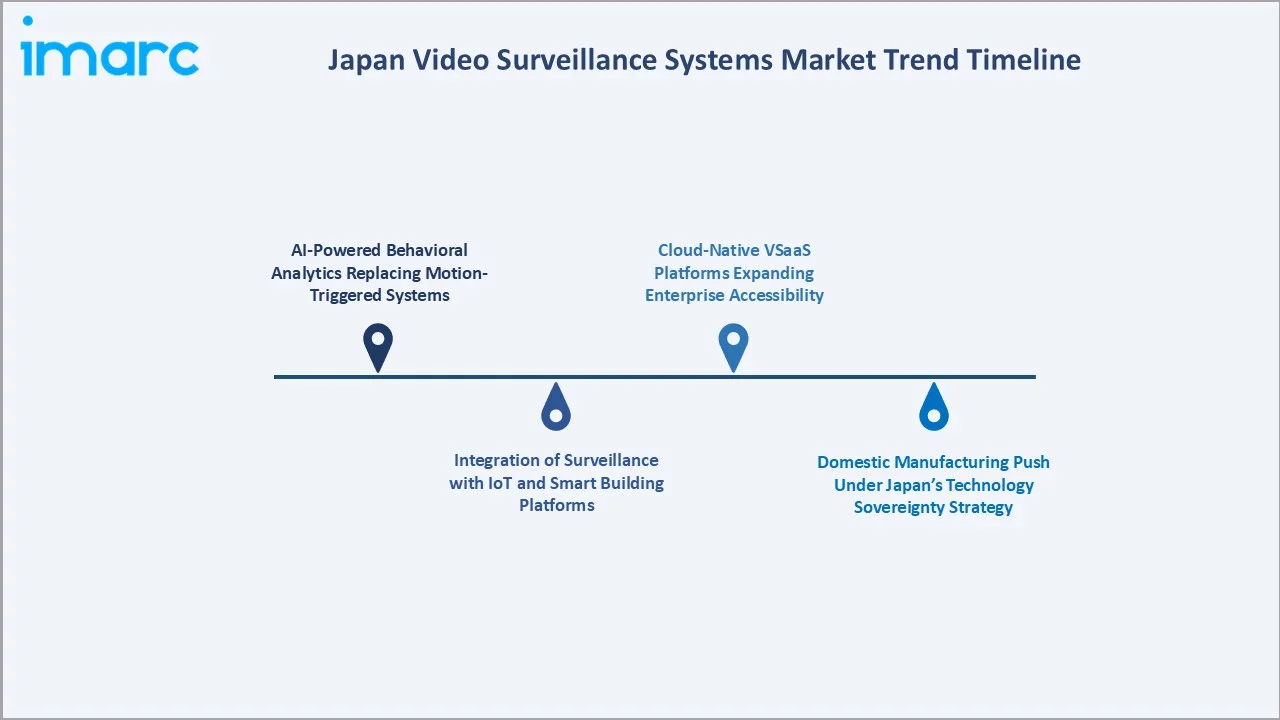
1. AI-Powered Behavioral Analytics Replacing Motion-Triggered Systems
AI behavioral analytics is replacing basic motion detection as the standard intelligence layer for video surveillance systems in Japan. Deep learning models trained on Japan-specific behavioral patterns enable detection of loitering, crowd surge, prohibited zone intrusion, and abnormal movement in real time. These capabilities are being deployed at transportation hubs, retail centers, and public events. The shift from passive recording to active intelligence is increasing the operational value of surveillance infrastructure.
2. Cloud-Native VSaaS Platforms Expanding Enterprise Accessibility
Cloud-native Video Surveillance as a Service platforms are democratizing advanced analytics for Japanese small and medium enterprises. Subscription-based models eliminate upfront NVR infrastructure investment while providing AI analytics, remote access, and managed storage. Japan's enterprise digital transformation momentum is accelerating VSaaS adoption in retail, hospitality, and multi-site commercial operations.
3. Integration of Surveillance with IoT and Smart Building Platforms
Surveillance systems are being integrated with building management, access control, and IoT sensor networks into unified security platforms. AI cameras that communicate with smart building systems enable automated responses to security events, reducing human operator dependency. This convergence is driving larger, more complex system deployments with higher per-site value in Japan's commercial real estate sector.
4. Domestic Manufacturing Push Under Japan's Technology Sovereignty Strategy
Japan's government is actively promoting domestic surveillance technology manufacturing under its economic security and technology sovereignty framework. Incentives for domestic production of AI chips, camera sensors, and VMS platforms are creating opportunities for Japanese technology companies to capture market share previously dominated by Chinese manufacturers. This policy trend is reshaping the competitive landscape.
Industry Value Chain Analysis
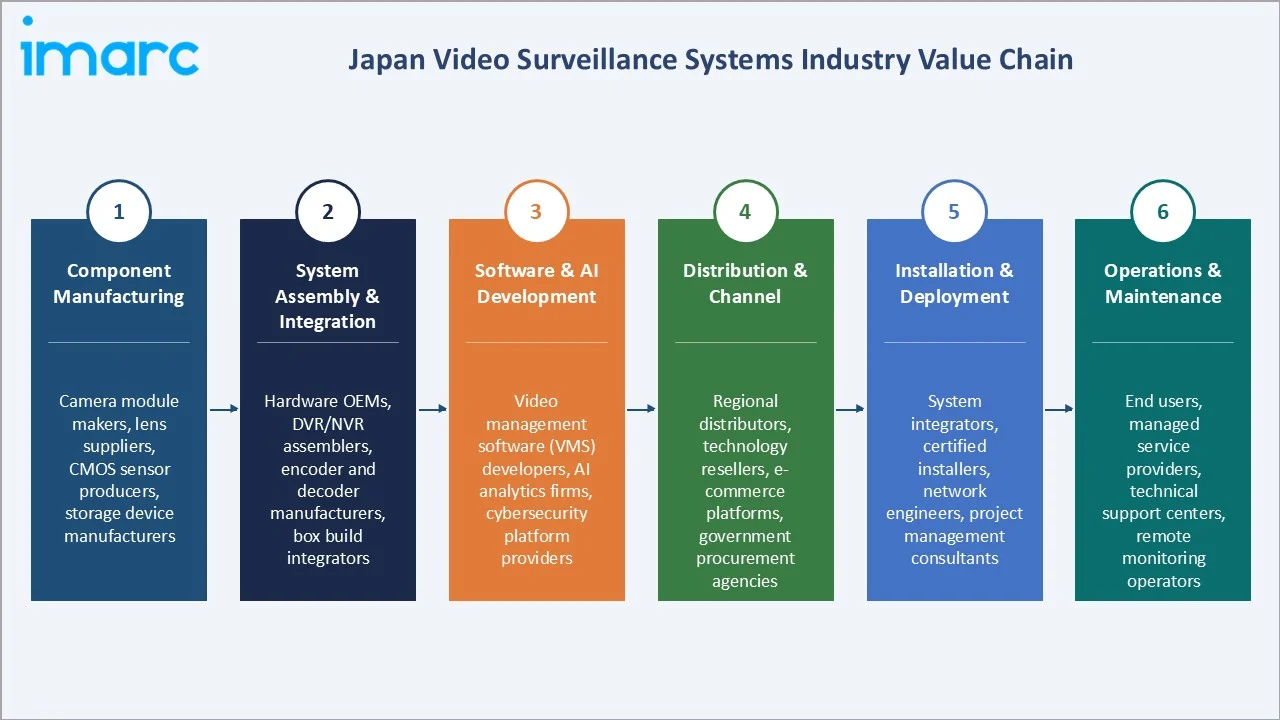
The Japan video surveillance systems value chain integrates component manufacturing, system assembly, software and AI development, distribution, professional installation, and ongoing operations and maintenance support.
|
Stage |
Key Participants |
|
Component Manufacturing |
Camera module makers, lens suppliers, CMOS sensor producers, storage device manufacturers |
|
System Assembly & Integration |
Hardware OEMs, DVR/NVR assemblers, encoder and decoder manufacturers, box build integrators |
|
Software & AI Development |
Video management software (VMS) developers, AI analytics firms, cybersecurity platform providers |
|
Distribution & Channel |
Regional distributors, technology resellers, e-commerce platforms, government procurement agencies |
|
Installation & Deployment |
System integrators, certified installers, network engineers, project management consultants |
|
Operations & Maintenance |
End users, managed service providers, technical support centers, remote monitoring operators |
The software and AI development stage is the value chain's fastest-growing and highest-margin phase. The distribution and installation layer is being consolidated as system integrators expand into managed service models. Post-installation operations and maintenance is the most recurring revenue-generating stage for service-oriented players.
Technology Landscape in the Japan Video Surveillance Systems Industry
AI-Powered Deep Learning Video Analytics
AI-powered deep learning analytics enable real-time object recognition, behavioral analysis, and anomaly detection from standard IP camera streams. These platforms are replacing rules-based motion detection with intelligent threat identification capable of operating continuously without human oversight. Growing deployment across Japan's transportation and retail sectors reflects the technology's proven operational ROI.
Edge Computing Integration in Surveillance Cameras
Edge computing-enabled cameras perform AI inference locally without transmitting raw video to centralized servers. This architecture reduces bandwidth consumption, latency, and cloud storage costs while maintaining analytical capabilities at distributed locations. Japan's dense urban camera networks particularly benefit from edge processing that enables local decision-making at traffic intersections and transit hubs.
Cloud-Based Video Management and VSaaS Platforms
Cloud-based video management platforms provide centralized access to distributed camera networks through secure internet connections. VSaaS models enable enterprise organizations to manage multi-site surveillance deployments from unified dashboards with AI analytics, automated alerts, and remote playback. These platforms are reducing the dependency on on-premise IT infrastructure for surveillance operations.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
System Type |
IP Surveillance |
61.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Enterprise Size |
🔒 |
🔒 |
2025 |
|
Component |
Hardware |
48.6% |
2025 |
|
Customer Type |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
34.8% |
2025 |

By System Type
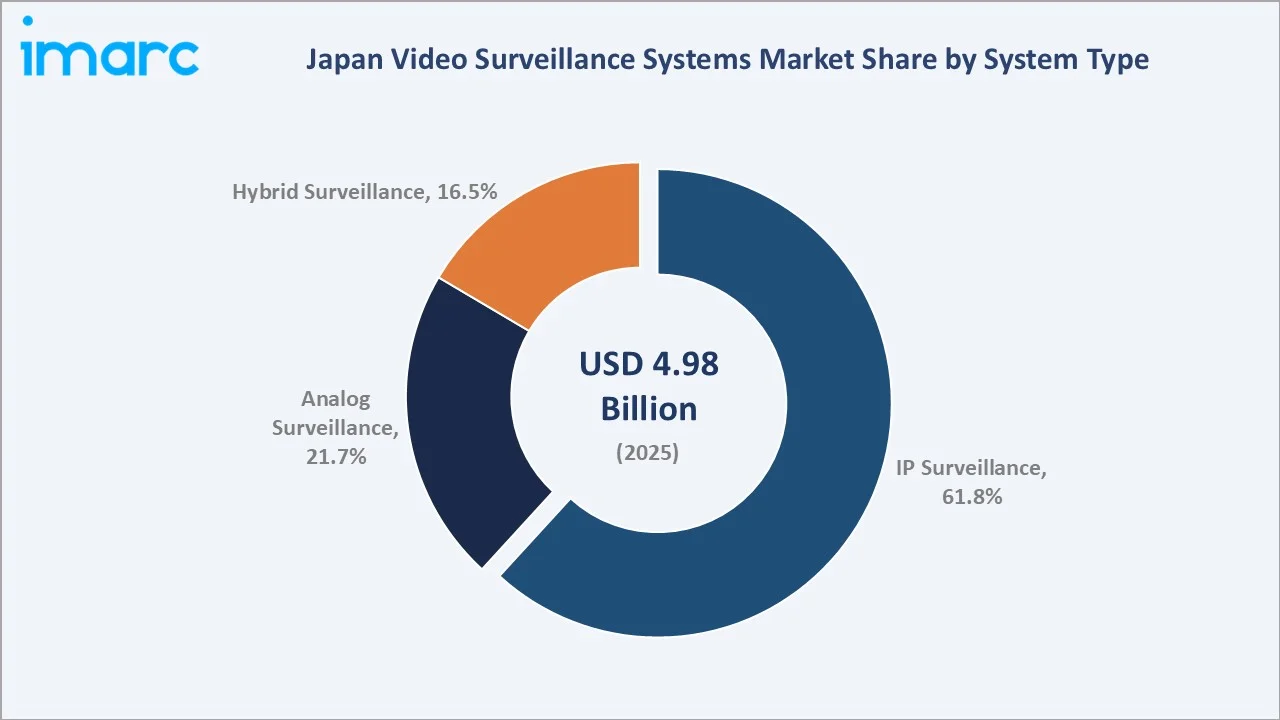
IP Surveillance leads at 61.8% (2025). The IP surveillance segment encompasses high-definition network cameras, PTZ systems, fisheye panoramic cameras, and multi-sensor platforms connected through standard network infrastructure. IP surveillance's dominance reflects Japan's advanced network infrastructure enabling seamless camera connectivity across complex deployments.
To access detailed market analysis, Request Sample
Analog Surveillance at 21.7% encompasses the large installed base of CCTV systems in older commercial and residential buildings undergoing gradual IP migration. Hybrid Surveillance at 16.5% serves the transitional segment bridging analog-legacy and IP-modern infrastructure through encoding hardware and hybrid NVR platforms.
By Component
Hardware leads at 48.6% (2025). The hardware segment encompasses network cameras, analog cameras, DVRs, NVRs, encoders, decoders, and physical transmission and mounting infrastructure. Hardware dominance reflects the capital-intensive physical layer investment required for surveillance system deployment across Japan's extensive urban and facility landscape.
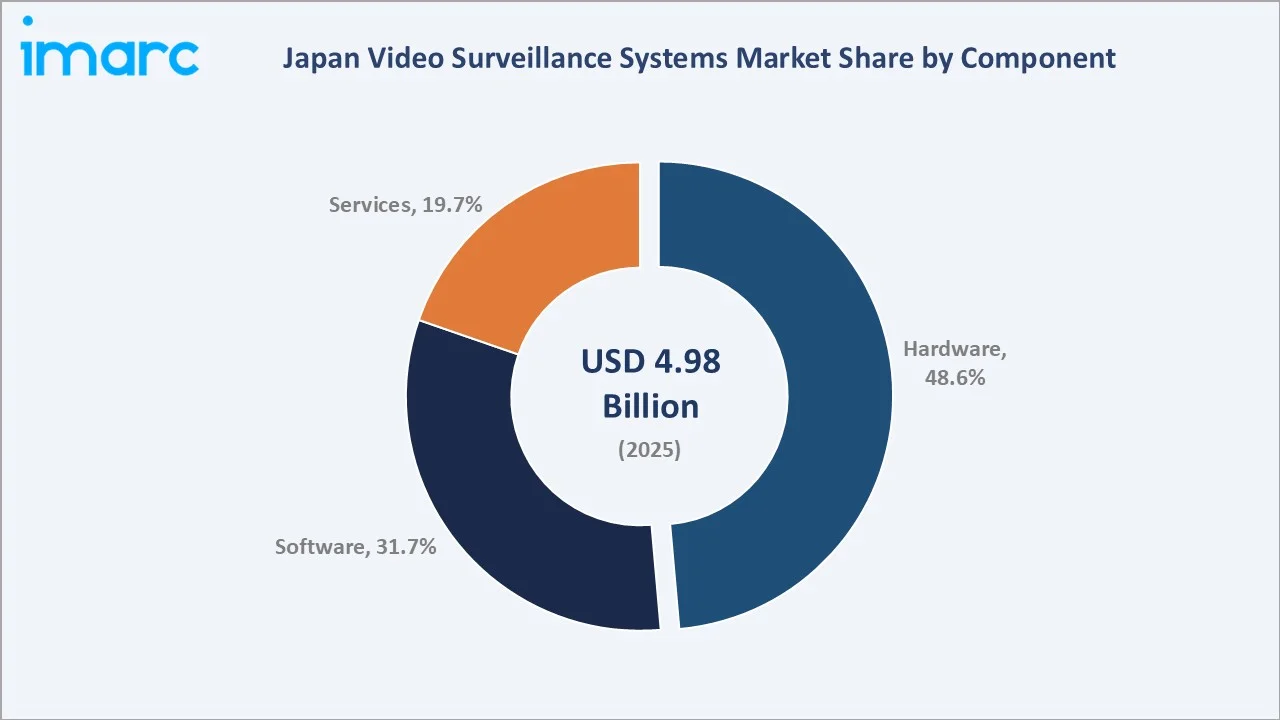
Software at 31.7% encompasses video management software, AI analytics platforms, cloud VMS, and cybersecurity management tools. Software's rapid growth reflects AI analytics adoption and VSaaS transition. Services at 19.7% encompasses professional installation, system integration, maintenance contracts, and managed security services.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan Video Surveillance Market Drivers & Characteristics |
|
Kanto Region |
34.8% |
Driven by highest urban density, government smart city programs, extensive commercial and transit surveillance networks. |
|
Kansai/Kinki Region |
18.9% |
Supported by manufacturing hub security needs, commercial district surveillance, and expo-related infrastructure upgrades. |
|
Central/Chubu Region |
14.7% |
Driven by automotive and industrial facility security requirements and growing urban surveillance deployments. |
|
Kyushu-Okinawa Region |
9.8% |
Supported by military base perimeter security, port surveillance, and expanding smart city pilots. |
|
Tohoku Region |
7.4% |
Driven by disaster recovery infrastructure, critical facility monitoring, and post-earthquake security modernization. |
|
Chugoku Region |
6.2% |
Supported by port and logistics hub security, industrial facility monitoring, and municipal safety programs. |
|
Hokkaido Region |
5.1% |
Driven by border security, tourism infrastructure monitoring, and expanding smart agriculture surveillance. |
|
Shikoku Region |
3.1% |
Supported by small-scale commercial surveillance adoption and municipal safety initiatives. |
Kanto Region's 34.8% market leadership is anchored by Tokyo's world-highest commercial camera density, government smart city procurement, and the concentration of Japan's largest corporate headquarters requiring enterprise-grade surveillance. Kansai/Kinki Region's 18.9% reflects Osaka's Expo 2025 infrastructure legacy.
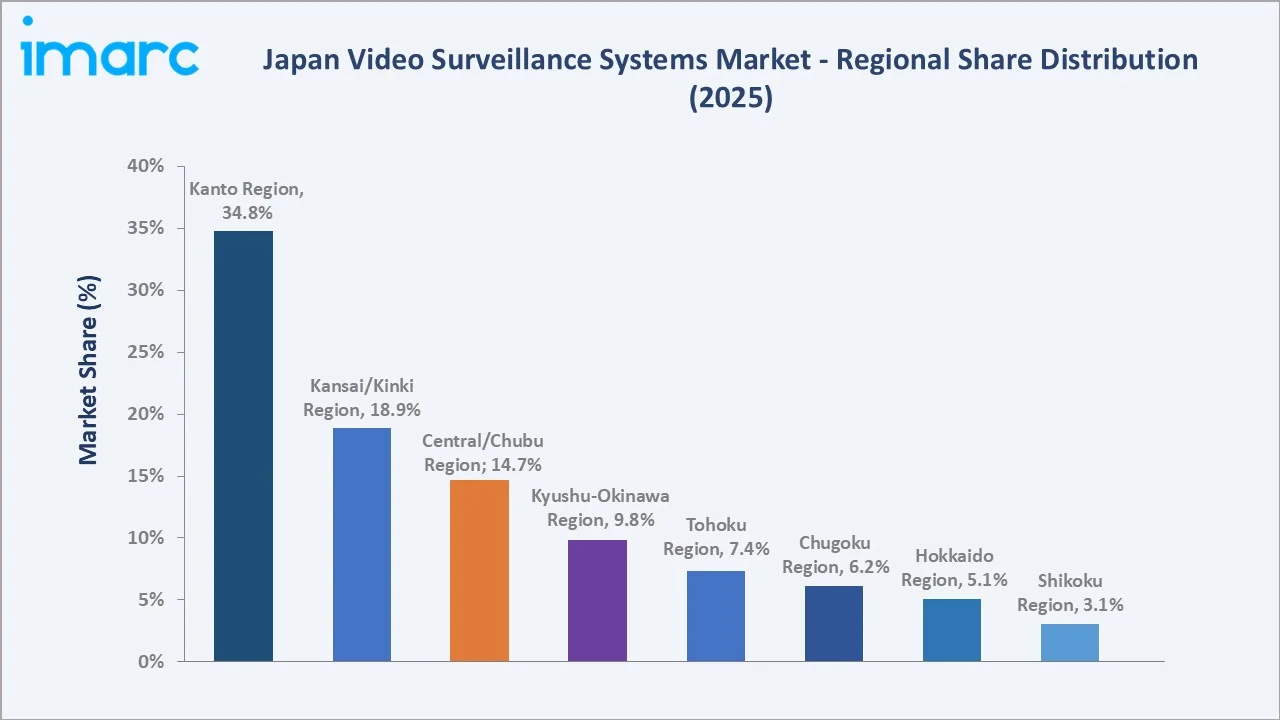
Central/Chubu Region's 14.7% encompasses Toyota City's automotive manufacturing facility security requirements. Shikoku Region at 3.1% represents the smallest share, driven by lower urbanization density and slower smart city investment relative to Japan's major metropolitan corridors.
Competitive Landscape
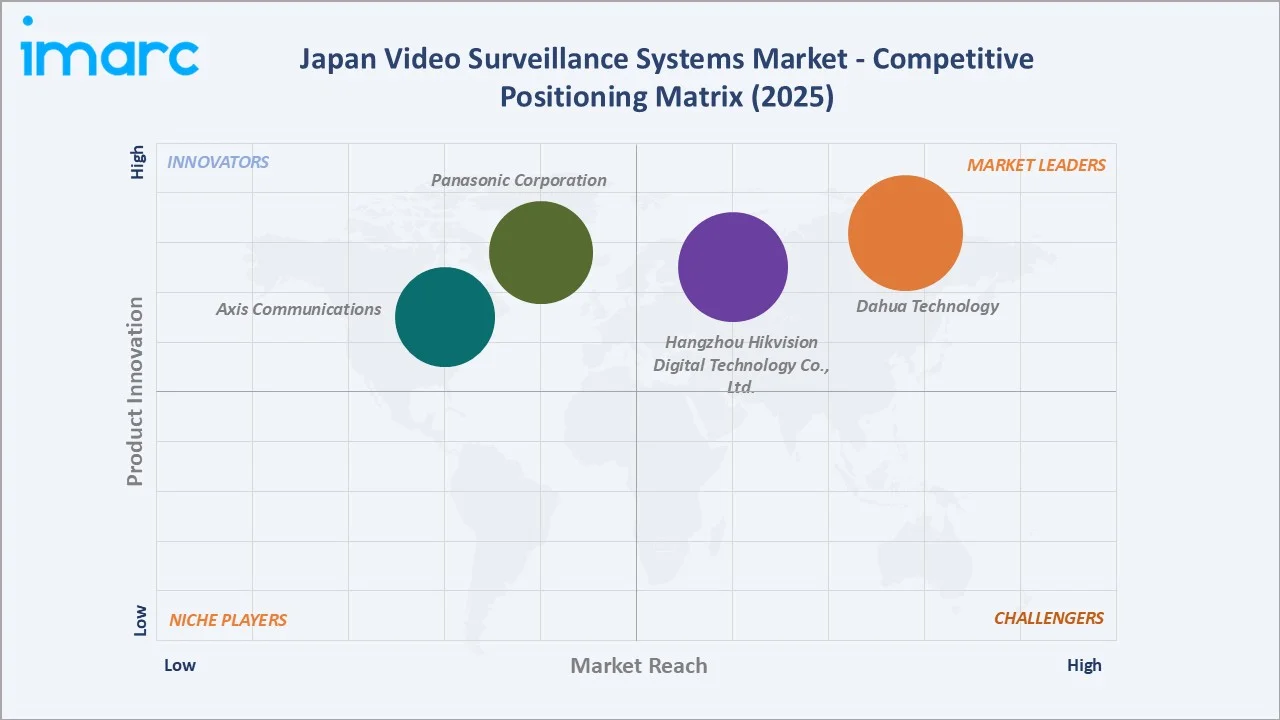
The Japan video surveillance systems market competitive landscape encompasses multinational hardware manufacturers, Japanese domestic electronics conglomerates, managed security service providers, and AI analytics software specialists.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Hangzhou Hikvision Digital Technology Co., Ltd. |
DS-2CD Series, DeepinView, AcuSense Cameras |
Market Leader |
Hangzhou Hikvision Digital Technology Co., Ltd. delivers integrated AI-powered cameras and NVR solutions enabling large-scale surveillance deployments across Japan's commercial and government sectors. |
|
Dahua Technology |
Lite Series IP Cameras, WizSense, HDCVI Systems |
Market Leader |
Dahua provides cost-effective, AI-integrated surveillance hardware and software platforms supporting Japan's public safety and infrastructure projects. |
|
Axis Communications |
AXIS Q Series, AXIS P Series, AXIS Camera Station |
Established Player |
Axis brings premium IP camera technology with advanced analytics and cybersecurity features, widely adopted in Japanese enterprise and critical infrastructure. |
|
Panasonic Corporation |
i-PRO Series, WV-Series IP Cameras, Security Management Software |
Established Player |
Panasonic offers domestically trusted surveillance cameras and integrated security management systems for commercial, industrial, and public sector applications. |
Chinese manufacturers, particularly Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua, hold significant hardware market share in Japan despite ongoing security scrutiny. Japanese domestic players including Panasonic, Sony, Secom, and Mitsubishi Electric are leveraging government preference and trusted brand recognition.
Key Company Profiles
Hangzhou Hikvision Digital Technology Co., Ltd.
Hangzhou Hikvision Digital Technology Co., Ltd. is a leading global provider of innovative security products and solutions, specializing in IP cameras, AI-powered video analytics, and integrated surveillance systems for the Japan market.
- Key Products: DS-2CD Series IP Cameras, DeepinView AI Analytics Cameras, AcuSense Motion Detection Systems.
- Recent Developments: In 2025, Hangzhou Hikvision Digital Technology Co., Ltd. launched its next-generation edge AI camera lineup featuring on-device deep learning for behavioral analytics without cloud dependency, targeting Japan's smart city and transit deployments.
- Strategic Focus: Expanding AI-integrated product portfolio for smart city applications, deepening partnerships with Japanese system integrators, and developing compliance solutions for Japan's data privacy frameworks.
Axis Communications
Axis Communications is a global pioneer in network video surveillance, providing IP cameras, video management software, and analytics platforms widely adopted across Japan's commercial and infrastructure sectors.
- Key Products: AXIS Q Series PTZ Cameras, AXIS P Series Fixed Cameras, AXIS Camera Station VMS.
- Strategic Focus: Centered on open-platform camera ecosystems, cybersecurity-hardened network surveillance, and deep integration with Japanese smart building and IoT management platforms.
Panasonic Corporation
Panasonic Corporation is a trusted Japanese electronics conglomerate providing i-PRO professional security cameras and integrated security management solutions for commercial, industrial, and public sector customers.
- Key Products: i-PRO Series AI Cameras, WV-Series Network Cameras, Security Management Software platforms.
- Recent Developments: In 2026, Panasonic's i-PRO division launched its AI-Edge camera series with embedded machine learning chips enabling on-device analytics for Japanese municipal and transportation authority deployments.
- Strategic Focus: Focused on AI-integrated domestic manufacturing advantage, government and critical infrastructure procurement, and trusted brand positioning against Chinese competitors in Japan's security-sensitive sectors.
Market Concentration Analysis
The Japan video surveillance systems market is moderately concentrated at the hardware tier, with global leaders Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua holding significant volume share alongside established Japanese domestic players. The analytics software tier is fragmented with numerous AI startup entrants. System integration services are highly fragmented across thousands of regional certified integrators. Market concentration is increasing at the platform tier through VMS consolidation.
Investment & Growth Opportunities
Highest Growth Segments
AI-powered behavioral analytics (~18% CAGR), cloud-native VSaaS platforms (~16% CAGR), edge computing cameras (~15% CAGR), smart city government procurement (~14% CAGR), managed security services (~13% CAGR), and 5G-integrated ultra-HD surveillance (~17% CAGR) represent the highest-growth investment vectors in Japan's video surveillance market through 2034.
Emerging Investment Opportunities
Japan's government digital transformation budget allocations for smart city surveillance represent the largest near-term procurement opportunity. System integrators and software vendors who establish preferred supplier status with Japan's municipal procurement offices and Ministry of Land, Infrastructure, Transport and Tourism are positioned for contracted revenue growth as smart city programs accelerate.
Investment Themes
- AI Analytics Platform Development for Japanese Smart City Subscription Revenue: AI surveillance analytics has documented a measurable benefit of 30-40% reduction in security staffing costs through automated detection. A Japan-localized cloud AI analytics subscription platform creates high-margin recurring revenue as the camera fleet grows across smart city programs.
- Domestic Edge AI Camera Manufacturing Under Japan Technology Sovereignty Programs: Japan's economic security initiatives include incentives for domestic production of surveillance technology components. Investment in edge AI chip-integrated camera manufacturing aligned with Japan's technology sovereignty strategy positions companies for government procurement preference and export opportunities to allied nations.
Future Market Outlook (2026-2034)
The Japan video surveillance systems market is projected to grow from USD 4.98 Billion in 2025 to USD 14.27 Billion by 2034, delivering a 12.42% CAGR over the forecast period. The market's anchor value of USD 8.93 Billion in 2030 represents Japan's surveillance infrastructure at a pivotal transformation stage where AI-native systems will have displaced legacy analog infrastructure in all major metropolitan deployments.
Three structural forces define Japan's video surveillance market growth through 2034. Public safety as a government policy priority, Japan's declining workforce creating demand for AI-automated security operations, and smart city infrastructure investment creating permanent demand for integrated surveillance platforms. These forces create compounding growth dynamics that sustain above-regional-average market expansion through 2034.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders including Chief Security Officers, System Integration Directors, Municipal Smart City Program Managers, AI Analytics platform executives, and regional market specialists across Japan's major metropolitan areas.
Secondary Research
Secondary research encompassed Japan Security Industry Association publications, National Police Agency statistics, municipal smart city program reports, company annual reports, and AI surveillance technology journals. Over 55 secondary sources reviewed.
Forecasting Models
Market revenue forecasts developed using a segment bottom-up model: (i) hardware component; (ii) software and analytics component; (iii) services component. Regional forecasts validated against prefecture-level government procurement data and population density indices.
Japan Video Surveillance Systems Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| System Types Covered | Surveillance, IP Surveillance, Hybrid Surveillance |
| Components Covered | Hardware, Software, Services |
| Applications Covered | Commercial, Military and Defense, Infrastructure, Residential, Others |
| Enterprise Sizes Covered | Small Scale Enterprise, Medium Scale Enterprise, Large Scale Enterprise |
| Customer Types Covered | B2B, B2C |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology, Axis Communications, Panasonic Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan video surveillance systems market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan video surveillance systems market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan video surveillance systems industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Video Surveillance Systems Market Report
The Japan video surveillance systems market reached USD 4.98 Billion in 2025. The market is driven by public safety investment, smart city development, and AI analytics adoption across commercial, government, and infrastructure sectors.
The market grows at 12.42% CAGR during 2026-2034, reaching USD 14.27 Billion by 2034. AI analytics and cloud VSaaS platforms grow fastest above the overall market average through the forecast period.
IP surveillance leads at 61.8% through network connectivity advantages, AI analytics integration capability, and superior image resolution enabling smart city deployment at scale.
Hardware leads at 48.6% through the foundational capital investment in cameras, NVRs, and storage infrastructure required for surveillance system deployment across Japan's extensive commercial and public facility landscape.
Kanto Region leads at 34.8% through Tokyo's world-highest commercial surveillance density, government smart city procurement, and concentration of enterprise headquarters security deployments.
Leading companies include Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology, Axis Communications, and Panasonic Corporation, among others.
The market is projected to reach approximately USD 8.93 Billion by 2030, with AI-native surveillance achieving mainstream commercial deployment in Japan's major metropolitan areas, VSaaS platforms reaching mass-market penetration among small and medium enterprises, and smart city programs creating permanent surveillance infrastructure across Japan's top 20 cities.
Video Surveillance as a Service (VSaaS) delivers surveillance infrastructure, recording, and AI analytics through cloud subscription models, eliminating on-premise NVR infrastructure. In Japan, VSaaS is expanding accessibility to AI-powered surveillance for the large SME segment that cannot justify capital-intensive traditional deployments, creating a high-growth recurring revenue stream.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade