
Japan Virtual Events Market Size, Share, Trends and Forecast by Type, Solution Type, Application, End Use, and Region, 2026-2034
Japan Virtual Events Market Size, Share, Trends & Forecast (2026-2034)
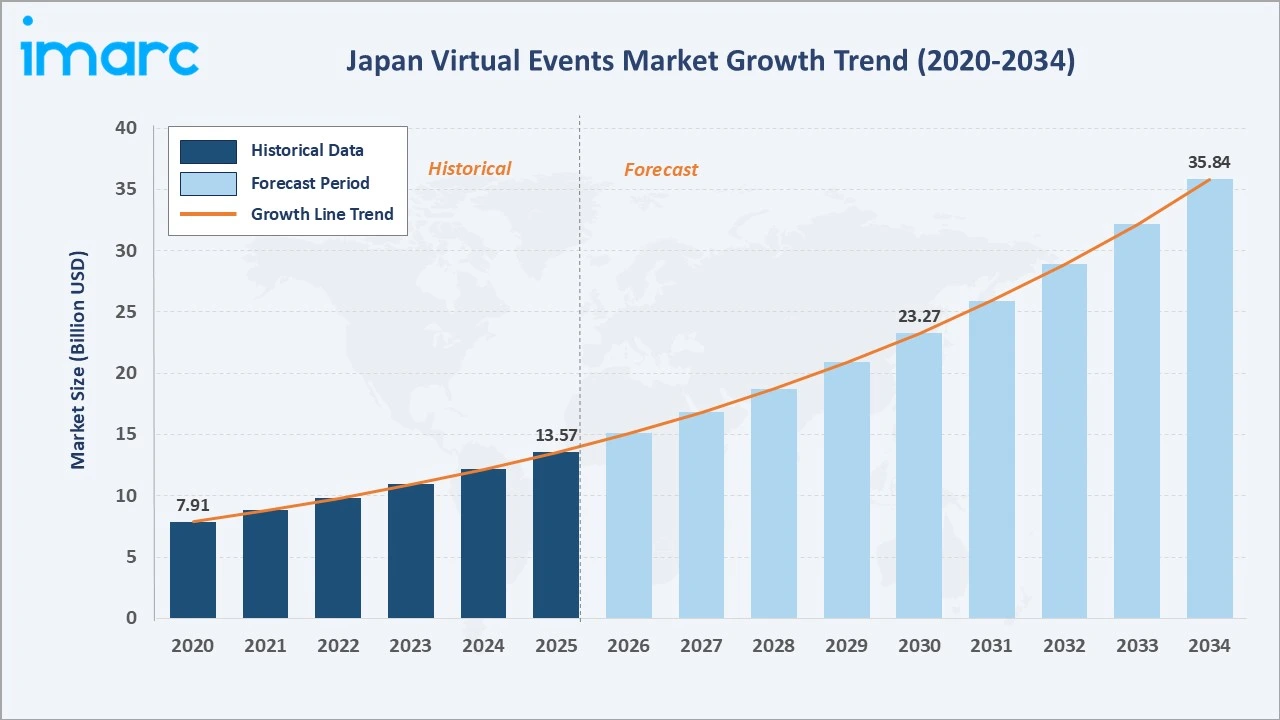
The Japan virtual events market grew from USD 13.57 Billion in 2025 to USD 15.11 Billion in 2026 and is projected to reach USD 35.84 Billion by 2034, growing at a CAGR of 11.40% during 2026-2034. Digital transformation across Japan's corporate, education, government, and healthcare sectors is the primary growth engine. Video conferencing and unified communications and collaborations lead by type at 61.8%, Webinars and enterprise streaming lead by solution type at 28.6%, and the Kanto region commands the largest regional share at 36.8% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 13.57 Billion |
|
Market Size (2026) |
USD 15.11 Billion |
|
Forecast Market Size (2034) |
USD 35.84 Billion |
|
CAGR (2026-2034) |
11.40% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Video Conferencing and Unified Communications and Collaborations (61.8%, 2025) |
|
Dominant Solution Type |
Webinars and Enterprise Streaming (28.6%, 2025) |
|
Leading Region |
Kanto Region (36.8%, 2025) |
The Japan virtual events market expanded from USD 7.91 Billion in 2020 to USD 13.57 Billion in 2025, and further to USD 15.11 Billion in 2026, reflecting accelerated enterprise adoption of cloud-based collaboration platforms, webinar infrastructure, and virtual event management solutions across Japan's leading industries. The market is projected to reach USD 23.27 Billion by 2030 before reaching USD 35.84 Billion by 2034.
To get more information on this market, Request Sample
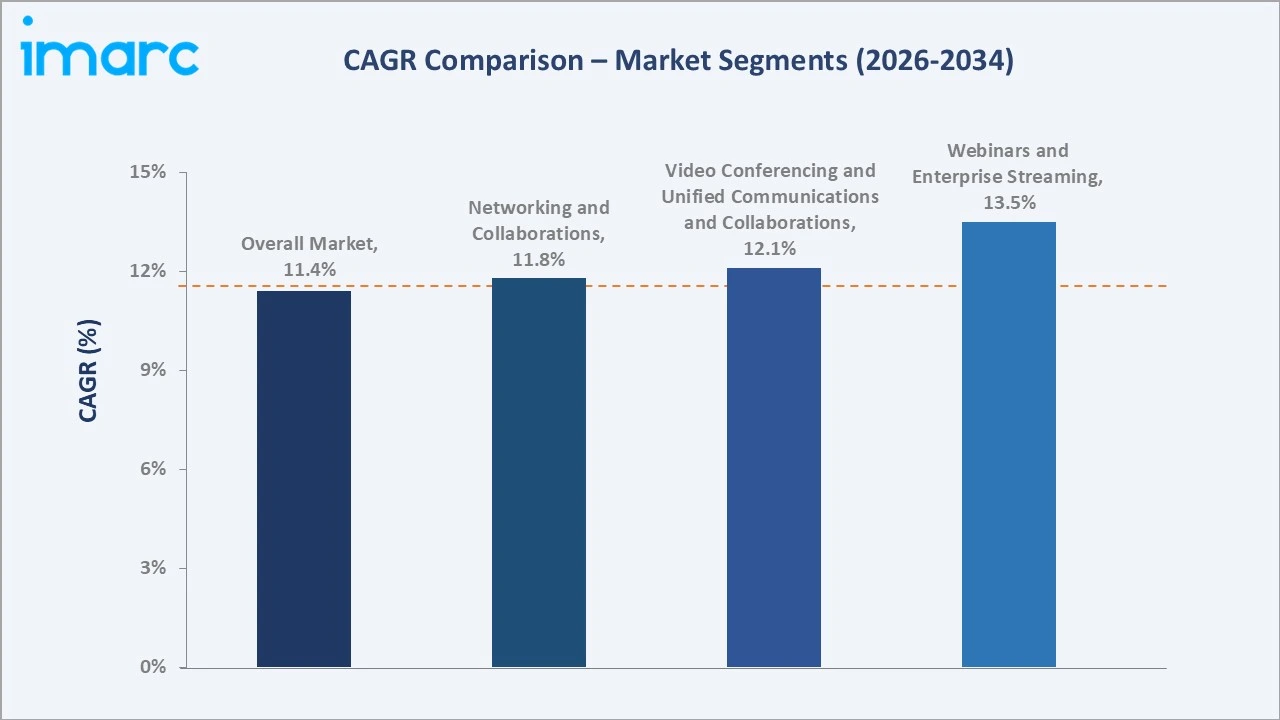
Webinars and enterprise streaming are the fastest-growing at 13.5% CAGR, driven by Japan's corporate demand for large-scale interactive broadcast events, investor relations webinars, and enterprise all-hands platforms. Video conferencing and unified communications and collaborations lead at 12.1% CAGR, reflecting deep enterprise penetration of collaborative platforms across Japan's major industrial and financial sectors.
Executive Summary
The Japan virtual events market is undergoing sustained structural expansion, underpinned by accelerating enterprise digital transformation, the normalization of hybrid work and distributed team collaboration, and increasing corporate investment in virtual event infrastructure. Platform sophistication, including AI-driven personalization, advanced analytics, and immersive VR-based event experiences, is progressively elevating the value proposition of virtual events for Japanese enterprises, education institutions, government agencies, and healthcare organizations.
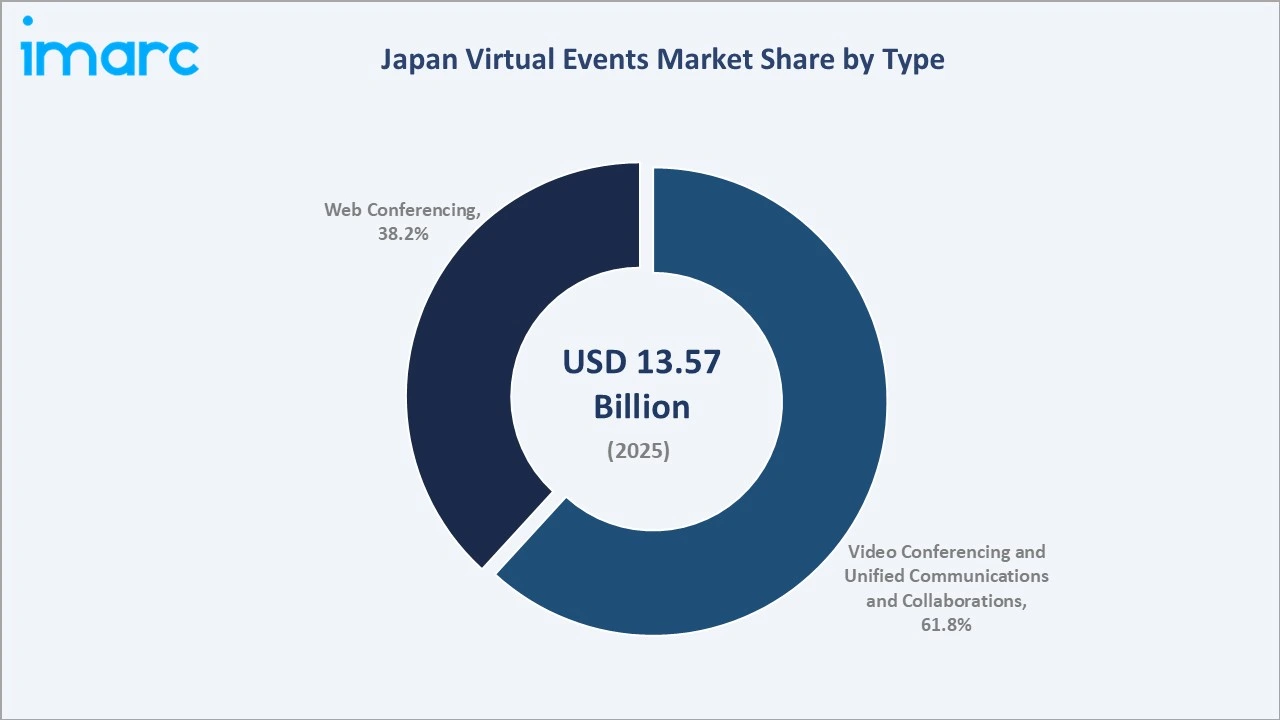
Video conferencing and unified communications and collaborations at 61.8% lead the type segmentation in 2025, driven by the deep penetration of enterprise-grade collaboration platforms across Japan's corporate and government sectors. Webinars and enterprise streaming at 28.6% represent the dominant solution type, supported by growing B2B marketing investment in interactive broadcast platforms. The Kanto region commands 36.8% of the market, concentrated in the Greater Tokyo Metropolitan Area's dense corporate and technology ecosystem.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Video Conferencing and Unified Communications and Collaborations – 61.8% share (2025) |
|
Dominant Solution Type |
Webinars and Enterprise Streaming – 28.6% share (2025) |
|
Leading Region |
Kanto Region – 36.8% (2025) |
|
Key Market Opportunity |
Hybrid event model development, VR/AR immersive experience platforms, AI-driven event analytics, and vertical expansion into healthcare, government, and education sectors. |
Key Analytical Observations Supporting the Above Data:
- Video Conferencing and Unified Communications and Collaborations at 61.8%: The dominance reflects Japan's strong enterprise adoption of integrated collaboration platforms that unify video meetings, persistent team messaging, file sharing, and workflow integration under a single platform architecture.
- Webinars and Enterprise Streaming at 28.6%: Webinars and enterprise streaming lead as Japan's B2B marketing, investor relations, and internal enterprise communication functions increasingly rely on scalable virtual broadcast formats. Large-audience interactive webinars have become a primary channel for product launches, analyst briefings, and employee-wide communications in Japan's leading listed companies.
- Kanto Region at 36.8%: The Kanto region's market leadership reflects its concentration of Japan's largest corporate headquarters, financial institutions, technology companies, and government ministries, all representing high per-organization virtual event spend. The Greater Tokyo Metropolitan Area alone hosts approximately 50% of Japan's Fortune-equivalent large enterprises, creating the densest virtual event demand cluster.
Japan Virtual Events Market Overview
The Japan virtual events market encompasses the full range of technology platforms, software solutions, and professional services enabling organizations to plan, deliver, and manage events, meetings, conferences, webinars, trade shows, and training programs in fully virtual or hybrid formats. The market spans two primary technology types: video conferencing and unified communications and collaboration solutions for real-time collaboration, and web conferencing platforms for structured event delivery, across five solution categories including webinars, networking tools, content sharing, event marketing, and integrated services.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
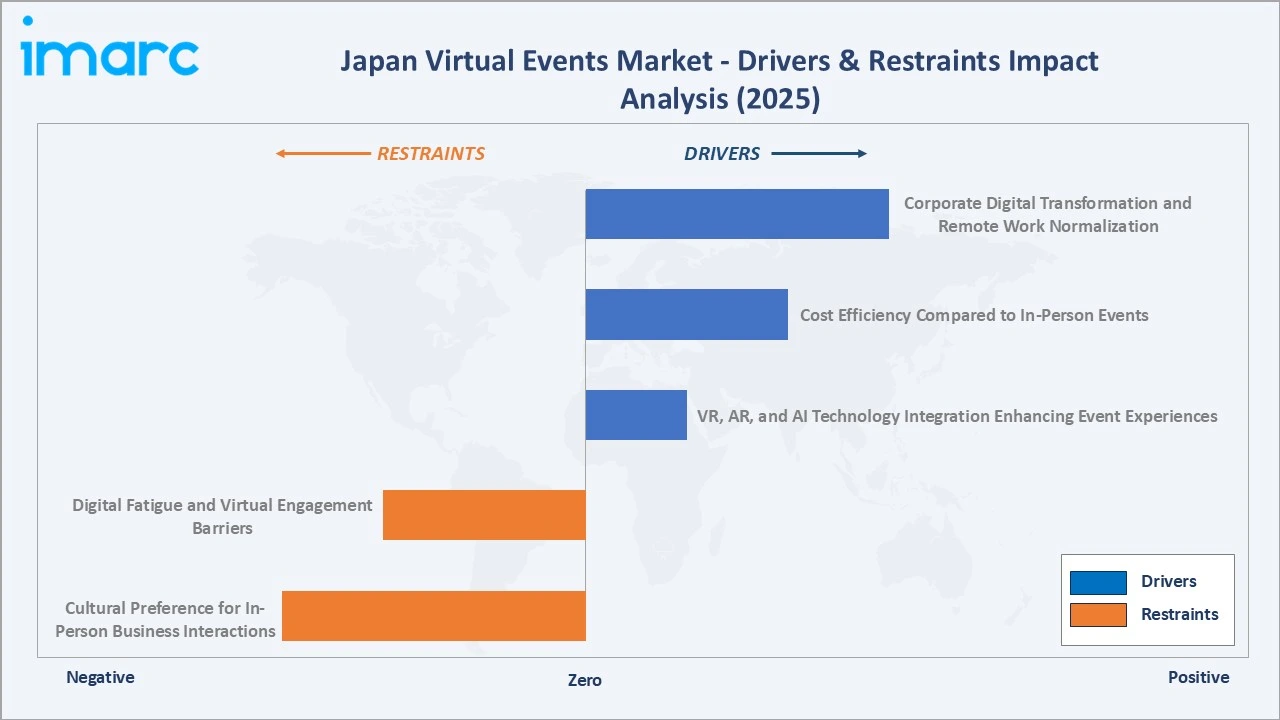
- Corporate Digital Transformation and Remote Work Normalization: Remote work adoption in Japan increased from around 40% before February 2020 to over 75% by April 2025. Japan's enterprise sector accelerated digital transformation investment following the widespread shift to distributed work, with virtual collaboration and event platforms becoming embedded in standard corporate operating models across financial services, manufacturing, technology, and government sectors.
- Cost Efficiency Compared to In-Person Events: Virtual and hybrid events eliminate venue, travel, accommodation, and logistics costs, offering Japan's large corporate event organizers a significantly lower per-attendee cost compared to traditional in-person formats. This economic advantage sustains platform adoption, particularly for high-frequency internal events and broad-audience external broadcasts where in-person alternatives are cost-prohibitive.
- VR, AR, and AI Technology Integration Enhancing Event Experiences: The progressive integration of artificial intelligence for real-time translation, automated attendee matching, content recommendations, and post-event analytics is increasing the engagement value of virtual events, expanding use case adoption across Japan's corporate, education, and government sectors.
Market Restraints
- Digital Fatigue and Virtual Engagement Barriers: Prolonged reliance on virtual event formats has generated audience fatigue among Japan's corporate and professional communities, reducing average attendee engagement rates and completion metrics for virtual sessions compared to in-person equivalents. This engagement challenge constrains the premium pricing power of virtual event platforms and limits the willingness of some organizations to fully transition high-value relationship-dependent events to virtual formats.
- Cultural Preference for In-Person Business Interactions: Japan's deeply rooted business culture values face-to-face relationship-building and formal interpersonal protocols that are difficult to replicate in virtual formats. This cultural preference limits the full migration of high-value business development events, executive forums, and formal industry conferences to virtual-only formats, preserving a structural ceiling on virtual-only event adoption rates in certain industry segments.
Market Opportunities
- Immersive Virtual Reality Event Platform Development: The emerging VR and metaverse-based virtual event segment represents an early-stage but rapidly growing opportunity in Japan, as technology companies and event organizers explore fully immersive 3D virtual conference environments, virtual trade show floors, and interactive product showrooms. In March 2026, HYBE JAPAN introduced “HYBE JAPAN VR NEXT STAGE 2026,” a year-round virtual reality concert initiative that represents a major expansion of its immersive entertainment business.
- AI-Powered Event Personalization and Analytics: The integration of large language model-based real-time translation, AI-driven attendee-to-attendee networking matching, and predictive content recommendation engines into virtual event platforms creates a high-value differentiation opportunity in Japan's enterprise market, where personalization and measurable ROI from event spend are increasingly evaluated during procurement decisions.
Market Challenges
- Replicating Authentic Networking in Virtual Formats: Creating meaningful virtual networking experiences that generate the relationship quality and spontaneous interaction of in-person professional events remains a persistent challenge for platform providers in Japan.
- Platform Reliability, Scalability, and Latency Requirements: Large-scale virtual events with thousands of simultaneous participants require enterprise-grade cloud infrastructure guaranteeing low latency, high-definition video transmission, and near-zero downtime, which remains operationally demanding for platforms serving Japan's geographically distributed attendee base.
Emerging Market Trends
1. Growing Adoption of Hybrid and Digitally Accessible Events
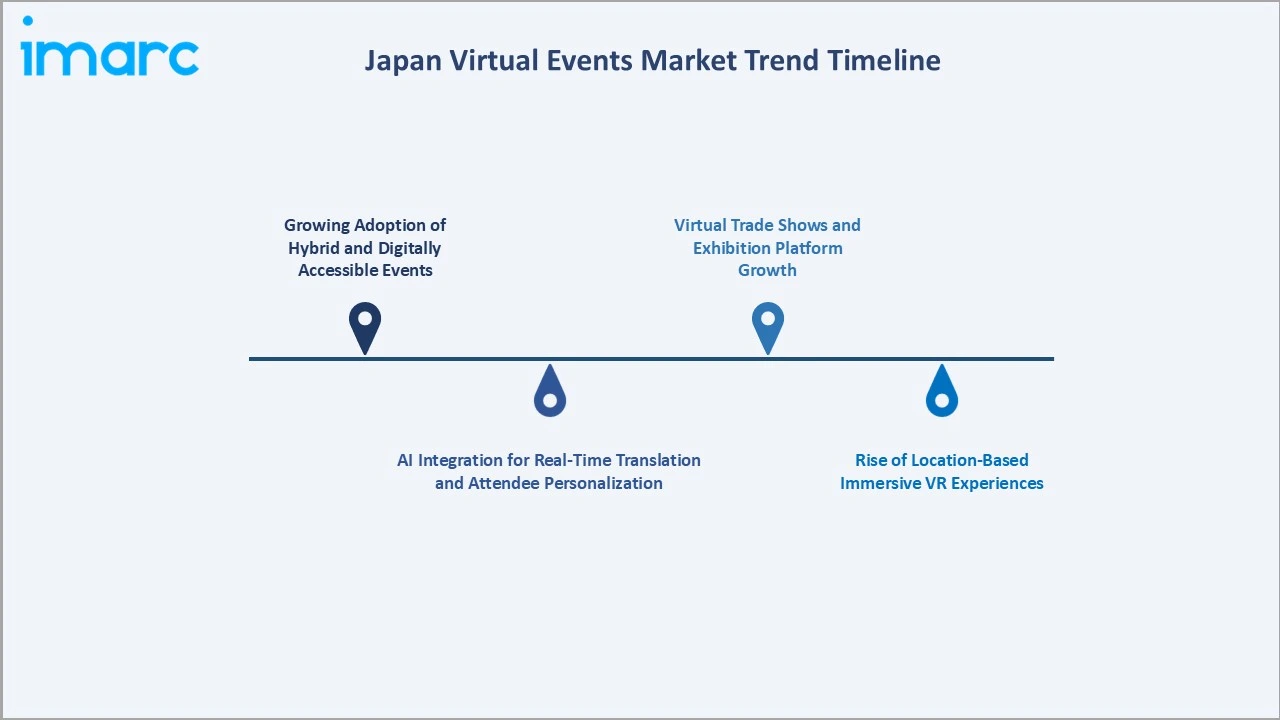
In April 2026, SusHi Tech Tokyo 2026 featured a record 770 startup exhibitors, up from 607 in 2025, with total attendance projected at 60,000, including 10,000 online participants. Held April 27–29 at Tokyo Big Sight, the event highlighted AI, robotics, and other advanced technologies, offering remote participation options for international audiences. These formats enable international audiences to engage with conferences remotely, broadening event reach and supporting demand for virtual event platforms and digital engagement solutions.
2. AI Integration for Real-Time Translation and Attendee Personalization
Artificial intelligence capabilities are being embedded across Japan's leading virtual event platforms, delivering real-time multilingual translation that removes language barriers for international attendees, AI-driven session recommendations that personalize event agendas, and intelligent attendee matching for structured networking. These capabilities significantly elevate event engagement metrics, extend geographic reach to global participants, and provide organizers with granular behavioral analytics that quantify event ROI and inform content investment decisions.
3. Virtual Trade Shows and Exhibition Platform Growth
Japan's large trade show and exhibition industry is progressively adopting virtual and hybrid exhibition platforms that replicate physical booth experiences through 3D virtual showrooms, live product demonstration streams, and digital catalog integration. These platforms allow exhibitors to reach nationally and internationally distributed buyer audiences without geographic or logistical constraints, while providing measurable attendee engagement data that surpasses traditional lead capture methods used at physical trade shows.
4. Rise of Location-Based Immersive VR Experiences
In March 2026, VIVERSE announced the global premiere of Samurai’s Dream: The Ghosts of Osaka Castle, an immersive free-roam virtual reality and location-based entertainment experience that allows visitors to explore a digital recreation of Osaka Castle during Japan’s Sengoku period. These experiences combine digital storytelling with interactive environments, creating new opportunities for immersive events across the tourism, cultural, and entertainment sectors.
Industry Value Chain Analysis
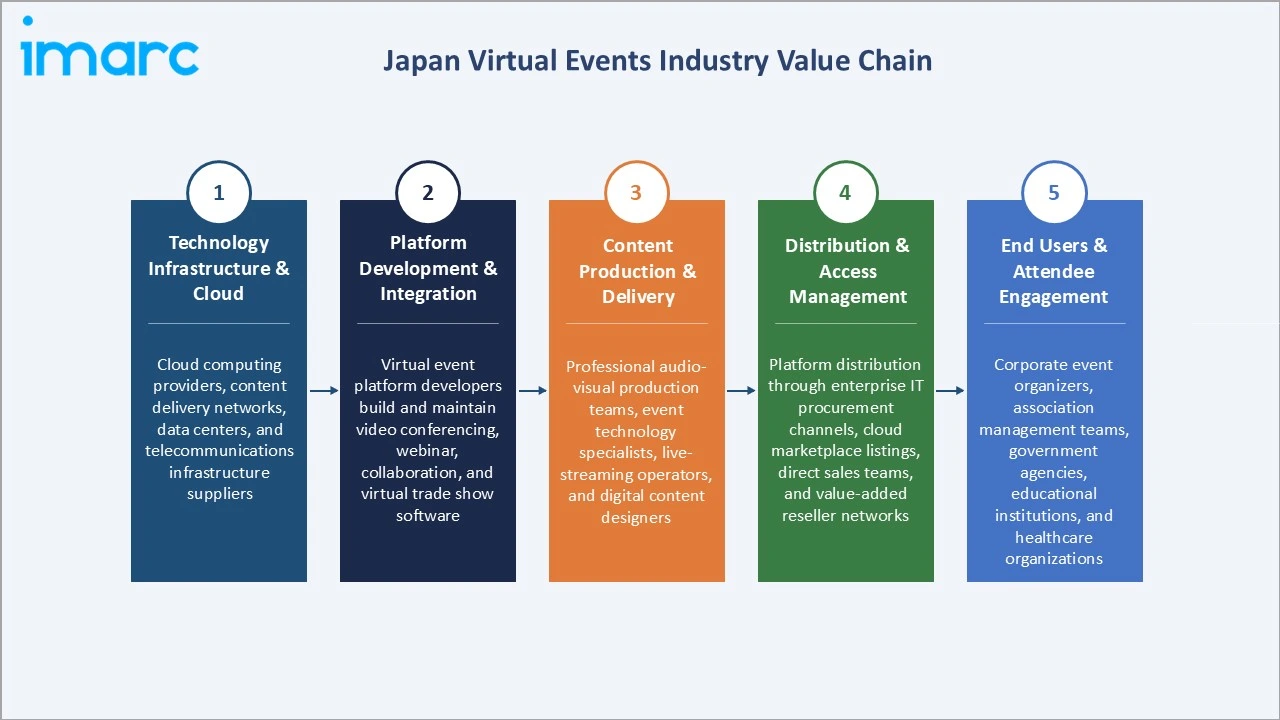
The Japan virtual events market value chain spans five integrated stages from foundational technology infrastructure and cloud services through to end-user attendee engagement and post-event analytics.
|
Stage |
Description |
|
Technology Infrastructure & Cloud |
Cloud computing providers, content delivery networks, data centers, and telecommunications infrastructure suppliers. |
|
Platform Development & Integration |
Virtual event platform developers build and maintain video conferencing, webinar, collaboration, and virtual trade show software. |
|
Content Production & Delivery |
Professional audio-visual production teams, event technology specialists, live-streaming operators, and digital content designers. |
|
Distribution & Access Management |
Platform distribution through enterprise IT procurement channels, cloud marketplace listings, direct sales teams, and value-added reseller networks. |
|
End Users & Attendee Engagement |
Corporate event organizers, association management teams, government agencies, educational institutions, and healthcare organizations. |
The platform development and integration stage commands the highest value concentration in Japan's virtual events value chain. Providers that invest in proprietary AI translation, advanced analytics, and VR integration capabilities capture significant pricing premiums and multi-year enterprise contracts that sustain commercial leadership in Japan's increasingly sophisticated virtual event procurement environment.
Technology Landscape in the Japan Virtual Events Industry
Cloud Infrastructure and Video Streaming Technologies
Cloud-native virtual event platforms leverage elastic compute resources, content delivery networks, and adaptive bitrate streaming to deliver high-definition video experiences to thousands of simultaneous attendees across Japan's diverse network environments. Low-latency streaming protocols and WebRTC-based real-time communication technologies form the foundational technical architecture enabling sub-second interactive collaboration in video conferencing and large-scale virtual broadcast events.
Virtual Reality and Immersive Event Technologies
VR headsets, 3D avatar-based virtual environments, and spatial audio technologies are enabling next-generation virtual event experiences that replicate the spatial and social dimensions of physical events. Immersive virtual trade show floors, 3D conference halls, and interactive product demonstration spaces are entering commercial deployment among Japan's technology and gaming industry event organizers, representing the leading edge of a broader shift toward experiential virtual event formats that address the engagement and networking limitations of traditional video-based platforms.
Data Analytics and Event Intelligence Platforms
Advanced analytics platforms embedded in virtual event solutions provide real-time attendee behavior tracking, session engagement heatmaps, lead scoring integration, audience segmentation, and post-event ROI measurement dashboards that exceed the data capture capabilities of in-person events. Japan's enterprise marketing and event organizations are increasingly prioritizing platforms with deep analytics capabilities, driving demand for virtual event solutions that deliver granular event intelligence integrating with CRM, marketing automation, and enterprise data platforms.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Video Conferencing and Unified Communications and Collaborations |
61.8% |
2025 |
|
Solution Type |
Webinars and Enterprise Streaming |
28.6% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End Use |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
36.8% |
2025 |

By Type
Video conferencing and unified communications and collaborations lead at 61.8% in 2025. This type encompasses enterprise-grade platforms that unify real-time video meetings, persistent team messaging channels, file collaboration, workflow integrations, and virtual event broadcast capabilities under a single platform architecture.
To access detailed market analysis, Request Sample
Web conferencing at 38.2% captures the segment of Japan's virtual events market focused on structured virtual meetings, online seminars, client presentations, and small-to-mid-scale virtual events that require reliable browser-based or lightweight application access.
By Solution Type
Webinars and enterprise streaming lead at 28.6% in 2025, reflecting the broad adoption of scalable virtual broadcast platforms across Japan's corporate investor relations, B2B marketing, and internal enterprise communication functions. This solution type enables organizations to reach hundreds or thousands of attendees simultaneously with interactive Q&A, polling, and on-demand replay capabilities.
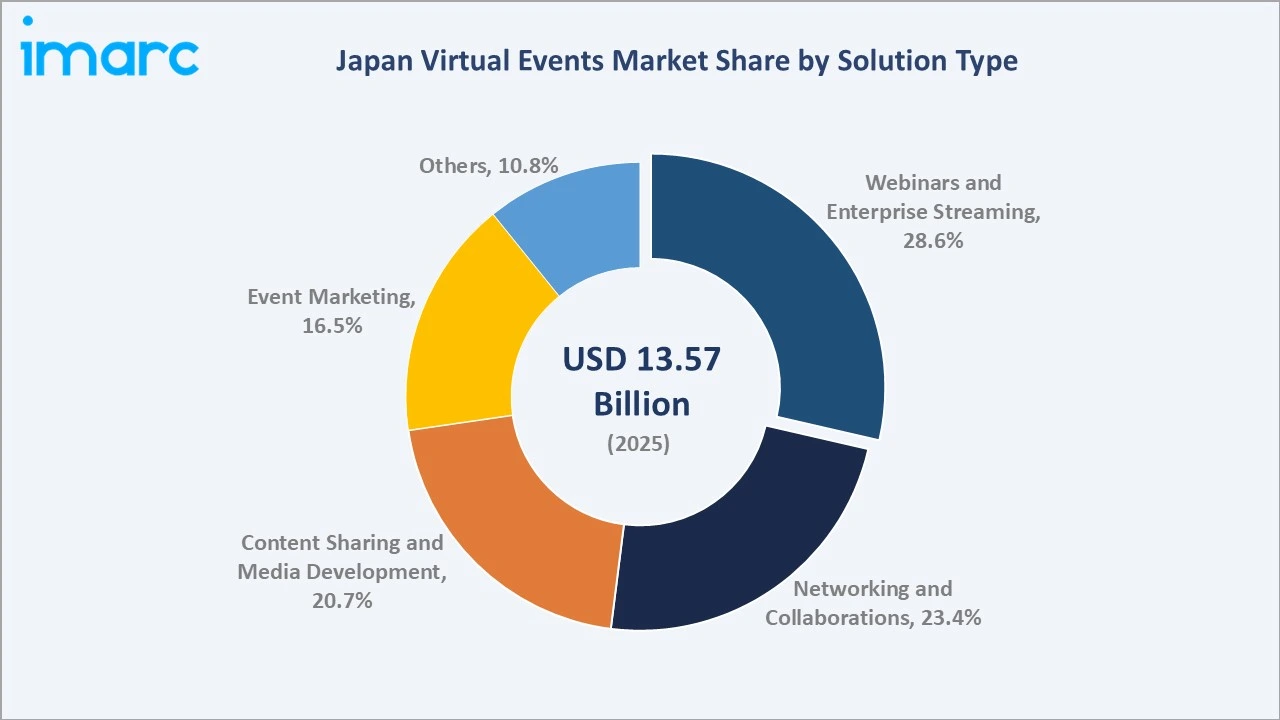
Networking and collaborations at 23.4% captures demand for virtual tools that enable structured professional networking, including attendee matching, one-on-one session scheduling, and virtual roundtable coordination. Content sharing and media development at 20.7% supports the production, distribution, and on-demand accessibility of virtual event content assets. Event marketing at 16.5% integrates virtual event data into demand generation workflows, providing lead capture, behavioral scoring, and marketing automation connectivity. Others at 10.8% include specialized tools for virtual exhibitions, digital sponsor activations, and niche event vertical applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
Kanto Region |
36.8% |
Largest virtual events market, driven by the highest concentration of Japan's corporate headquarters, financial institutions, technology companies, and government ministries in the Greater Tokyo Metropolitan Area. |
|
Kansai/Kinki Region |
20.4% |
Strong enterprise and SME virtual event adoption across commercial and manufacturing sectors, technology and academic institutions, and trade and logistics industries. |
|
Central/Chubu Region |
13.8% |
Demand driven by the automotive and manufacturing industry ecosystem, including virtual supplier conferences, engineering training programs, and cross-company collaboration platforms. |
|
Kyushu-Okinawa Region |
9.4% |
Growing virtual events adoption supported by expanding startup and technology ecosystem, regional government digital service initiatives, and cross-island virtual connectivity needs in the Okinawa prefecture. |
|
Tohoku Region |
6.7% |
Virtual event adoption driven by regional enterprise connectivity needs, academic institution virtual lecture and conference programs, and government-supported digital infrastructure investment programs. |
|
Chugoku Region |
5.4% |
Moderate market supported by manufacturing and automotive supplier base, with growing adoption of virtual training programs, inter-company collaboration platforms, and regional trade association events. |
|
Hokkaido Region |
4.6% |
Growing virtual event adoption in enterprise and public sector, with demand driven by geographic distance from mainland Japan's major commercial centers making virtual collaboration particularly cost-effective. |
|
Shikoku Region |
2.9% |
Smallest regional share, with demand concentrated in the enterprise base. Virtual event adoption is supported by regional government digital transformation programs and cross-regional business connectivity needs. |
Japan's virtual events market is highly concentrated in the Kanto region at 36.8%, reflecting the Tokyo metropolitan area's unrivaled density of corporate event organizers and enterprise technology buyers. The Kansai/Kinki region holds 20.4%, supported by commercial, technology, and academic sectors. The Central/Chubu region at 13.8% benefits from industrial and automotive industry virtual event demand.
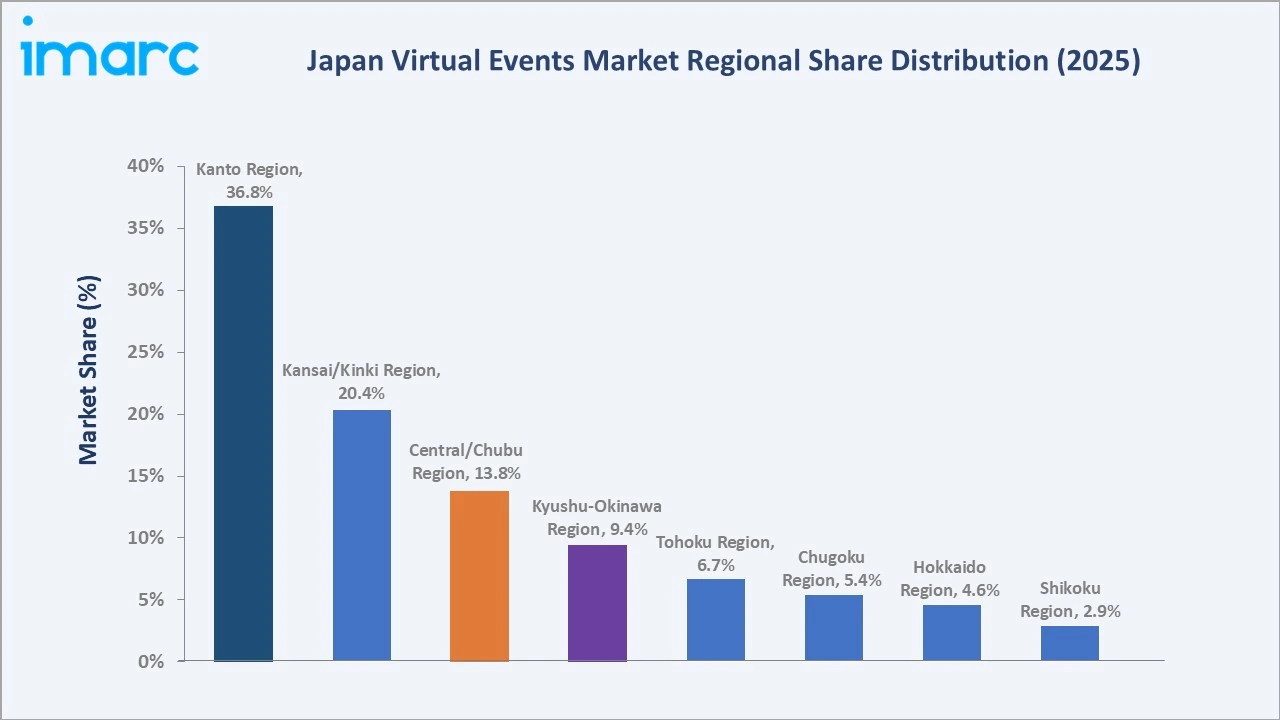
Kyushu-Okinawa contributes 9.4%, driven by a growing technology startup ecosystem. The Tohoku region represents 6.7%, with academic and government sector demand anchoring virtual event adoption. Chugoku accounts for 5.4%, Hokkaido 4.6%, and Shikoku 2.9%, with demand in each region constrained by smaller enterprise concentrations relative to Japan's major metropolitan markets.
Competitive Landscape
The Japan virtual events market is characterized by a three-tier competitive structure. Global UC&C platform leaders dominate the enterprise collaboration segment through deep corporate penetration and integrated platform ecosystems. Specialized virtual event platform providers compete on event management functionality, analytics depth, and enterprise customization capabilities. Japanese domestic technology companies leverage installed enterprise relationships and domestic brand trust to compete in collaboration and virtual event hosting segments.
|
Company |
Key Platforms |
Market Position |
Core Strength |
|
Zoom Communications, Inc. |
Zoom |
Market Leader |
Zoom Communications, Inc. plays a major infrastructure and platform role in Japan's virtual, hybrid, and large-scale corporate event landscape. |
|
Microsoft |
Microsoft Teams |
Market Leader |
Microsoft plays a central role in powering, hosting, and localizing virtual and hybrid events in Japan, utilizing tools like Microsoft Teams. |
|
Cisco Systems, Inc. |
Webex Events |
Established Player |
Cisco Systems, Inc. plays a foundational role in Japan's virtual events, remote collaboration, and digital transformation initiatives through its enterprise platforms. |
|
|
Google Meet, Google Workspace |
Established Player |
Google supports and powers virtual, hybrid, and large-scale digital events in Japan through its cloud infrastructure, collaboration suites, and XR partnerships. |
|
RingCentral, Inc. |
Hopin Events |
Innovator |
RingCentral, Inc. plays a major role in Japan's virtual events market primarily through its comprehensive, AI-powered platform Hopin Events. |
Competitive dynamics in Japan's virtual events market are being reshaped by AI feature differentiation, hybrid event platform capabilities, and the growing enterprise focus on data analytics and measurable event ROI. Platforms that invest in Japan-specific localization, data governance, and deep enterprise system integration are positioned to expand their share in Japan's high-value corporate events segment.
Key Company Profiles
Zoom Communications, Inc.
Zoom Communications, Inc. is the leader in video-first cloud communications, with Zoom Meetings, Zoom Webinars, and Zoom Events forming the dominant virtual event platform in Japan's enterprise, SME, and education sectors. Zoom's Japan operations are supported by a dedicated localization team, Japanese-language product interfaces, and enterprise support infrastructure aligned with Japan's corporate procurement and compliance requirements.
- Key Platforms: Zoom.
- Strategic Focus: Deepening AI-powered event intelligence capabilities for Japan's enterprise market, expanding Zoom Events platform functionality for large-scale virtual trade show and conference applications, and strengthening data management capabilities to address Japan's corporate data governance requirements.
Microsoft
Microsoft Teams platform is deeply embedded in Japan's corporate digital workplace as the dominant platform for the country's largest enterprises, government agencies, and educational institutions. Teams Live Events and Teams Meetings provide the primary virtual event infrastructure for a significant portion of Japan's large corporate events, investor relations broadcasts, and internal all-hands communications, integrated within Microsoft's productivity ecosystem that is deployed at organizational scale across Japan's enterprise sector.
- Key Platforms: Microsoft Teams.
- Strategic Focus: Deepening Teams' position as Japan's enterprise virtual event backbone through M365 ecosystem integration, advancing AI capabilities for Japanese-language event intelligence, and expanding Teams Rooms and hybrid event infrastructure to capture Japan's growing hybrid corporate event market.
Market Concentration Analysis
The Japan virtual events market is moderately concentrated, with the top five platform providers collectively accounting for an estimated 60-65% of total market revenue in 2025. These leaders command dominant shares in the enterprise UC&C and webinar segments through their deeply embedded platform ecosystems, long-term enterprise license agreements, and continuous AI-driven feature investment that raises competitive switching costs.
Japanese domestic providers hold their positions primarily through integrated IT service relationships rather than platform differentiation, maintaining stable but constrained share in a market where platforms feature velocity is high. Market concentration is expected to remain stable through the forecast period, with AI differentiation becoming the primary competitive axis reshaping relative positioning within the established leader tier.
Investment & Growth Opportunities
Highest Growth Segments
Webinars and enterprise streaming represent Japan's fastest-growing solution type at approximately 13.5% CAGR, driven by expanding corporate investment in interactive broadcast platforms for investor relations, product launches, and large-scale internal communications.
Investment Themes
- AI-Powered Event Platform Development for Japan Localization: Investment in large language model-based real-time Japanese translation, culturally adapted AI networking recommendation engines, and bilingual event analytics dashboards addresses Japan's critical language and cultural localization requirements, creating a high-value competitive differentiation that generic platforms features do not fully address in Japan's enterprise market.
- Hybrid Event Infrastructure and AV Production Services: Investment in enterprise-grade hybrid event technology infrastructure, including broadcast-quality streaming systems, virtual-physical attendance synchronization platforms, and professional AV production services tailored to Japan's corporate event quality standards, captures the growing hybrid event format adoption that is the dominant enterprise event model driving platform upgrade cycles.
- Healthcare and Government Sector Virtual Event Platforms: Dedicated virtual event platform investment targeting Japan's healthcare and government sectors addresses underserved, high-value verticals with growing regulatory mandates for digital service delivery.
Future Market Outlook (2026-2034)
The Japan virtual events market stood at USD 13.57 Billion in 2025 and is projected to grow from USD 15.11 Billion in 2026 to USD 35.84 Billion by 2034, exhibiting a CAGR of 11.40% during the forecast period. The market is projected to reach an intermediate milestone of approximately USD 23.27 Billion by 2030, as expanding AI platform capabilities, maturing hybrid event models, and progressive VR event adoption accelerate enterprise event technology spend across Japan's major industries and public sector verticals.
Three structural forces will define Japan's virtual events market through 2034. First, the AI transformation of virtual event platforms will progressively elevate the functional value of virtual and hybrid events through intelligent personalization, real-time translation, and predictive engagement analytics, converting virtual events from cost-efficient substitutes into high-value enterprise engagement channels that justify expanding platform investment.
Second, the immersive event transition will create a new high-growth platform category within Japan's virtual events market as hardware accessibility expands and enterprise adoption of metaverse-based event environments gains commercial validation in technology, gaming, and automotive sectors. Third, Japan's sustained digital transformation investment in public administration, healthcare, and education will expand the institutional virtual event market beyond corporate enterprise, diversifying demand generation and supporting nationwide virtual event infrastructure development through 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with enterprise IT and procurement managers at Japan's leading corporations and financial institutions, virtual event platform product managers and sales executives at Japan subsidiaries of major technology companies, and education technology administrators at Japanese universities and government digital transformation program officers. These consultations validated platform market share estimates, assessed adoption trends for AI and hybrid event capabilities, and provided competitive intelligence on enterprise purchasing priorities.
Secondary Research
Secondary research drew on IMARC Group's Japan virtual events market database, digital transformation statistical publications, event market reports, regulatory compliance guidance publications, and public financial disclosures and investor presentations from major virtual event platform providers operating in Japan.
Forecasting Models
Market forecasts incorporated Japan enterprise cloud software adoption trajectory modeling, corporate event budget allocation trend analysis, AI platform feature release timeline projections, VR hardware penetration rate modeling for Japan's consumer and enterprise segments, government digital transformation program investment pipeline assessment, and macroeconomic indicators including Japan GDP growth, enterprise IT expenditure forecasts, and hybrid work normalization trends through 2034.
Japan Virtual Events Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Video Conferencing and Unified Communications and Collaborations, Web Conferencing |
| Solution Types Covered | Webinars and Enterprise Streaming, Networking and Collaborations, Content Sharing and Media Development, Event Marketing, Others |
| Applications Covered | Virtual Conferences, Virtual Tradeshows, Online Education Programs, Virtual Reality Exhibitions, Others |
| End Uses Covered | Corporate, Education, Healthcare, Finance and Banking, Government, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Zoom Communications, Inc., Microsoft, Cisco Systems, Inc., Google, RingCentral, Inc.,etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan virtual events market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan virtual events market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan virtual events industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Virtual Events Market Report
The Japan virtual events market reached USD 15.11 Billion in 2026, driven by enterprise digital transformation, hybrid event model adoption, and expanding AI-powered platform capabilities across corporate and institutional sectors.
The market is projected to grow at a CAGR of 11.40% during 2026-2034, driven by AI feature adoption, hybrid event normalization, VR experience integration, and expanding demand across corporate, government, and education verticals.
The Japan virtual events market is projected to reach approximately USD 23.27 Billion by 2030, supported by enterprise platform upgrades, growing hybrid event adoption, and expanding virtual trade show and conference market development.
Video conferencing and unified communications and collaborations lead with a 61.8% share in 2025, driven by deep enterprise adoption of integrated collaboration platforms across Japan's financial, manufacturing, government, and technology sectors.
Webinars and enterprise streaming lead at 28.6% share in 2025, supported by corporate demand for large-scale interactive broadcast platforms for investor relations, B2B marketing, and enterprise-wide communications.
The Kanto region leads with a 36.8% share in 2025, reflecting the Greater Tokyo Metropolitan Area's unrivaled concentration of corporate headquarters, financial institutions, and enterprise technology buyers.
Key players include Zoom Communications, Inc., Microsoft, Cisco Systems, Inc., Google, and RingCentral, Inc., among others.
The market is projected to reach USD 35.84 Billion by 2034, driven by AI platform investment, VR event adoption, hybrid event model maturity, and expansion into healthcare, government, and education verticals.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade