
Leather Goods Market Size, Share, Trends and Forecast by Product, Material, Price, Distribution Channel, and Region, 2026-2034
Leather Goods Market Size, Share, Trends & Forecast (2026-2034)
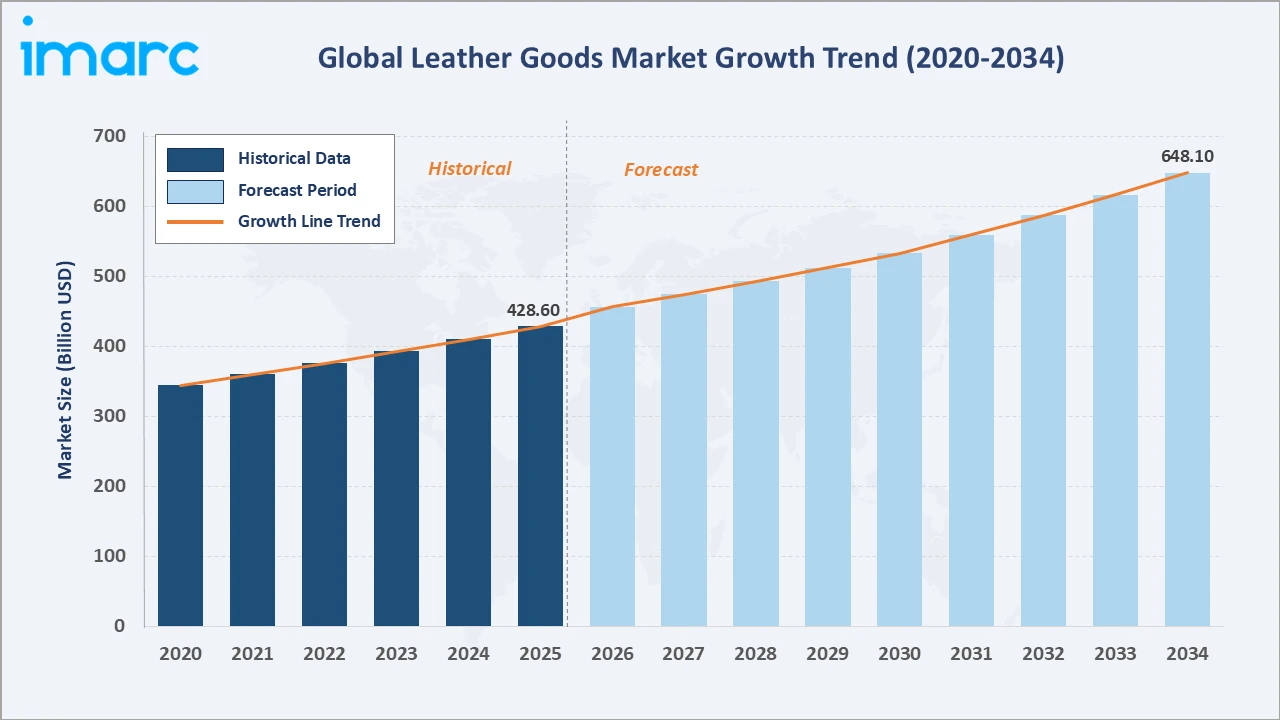
The global leather goods market grew from USD 428.6 Billion in 2025 to USD 456.9 Billion in 2026 and is projected to reach USD 648.1 Billion by 2034, growing at a CAGR of 4.47% during 2026-2034. The market is driven by rising disposable incomes, growing fashion-consciousness, and increasing consumer demand for premium leather accessories globally.
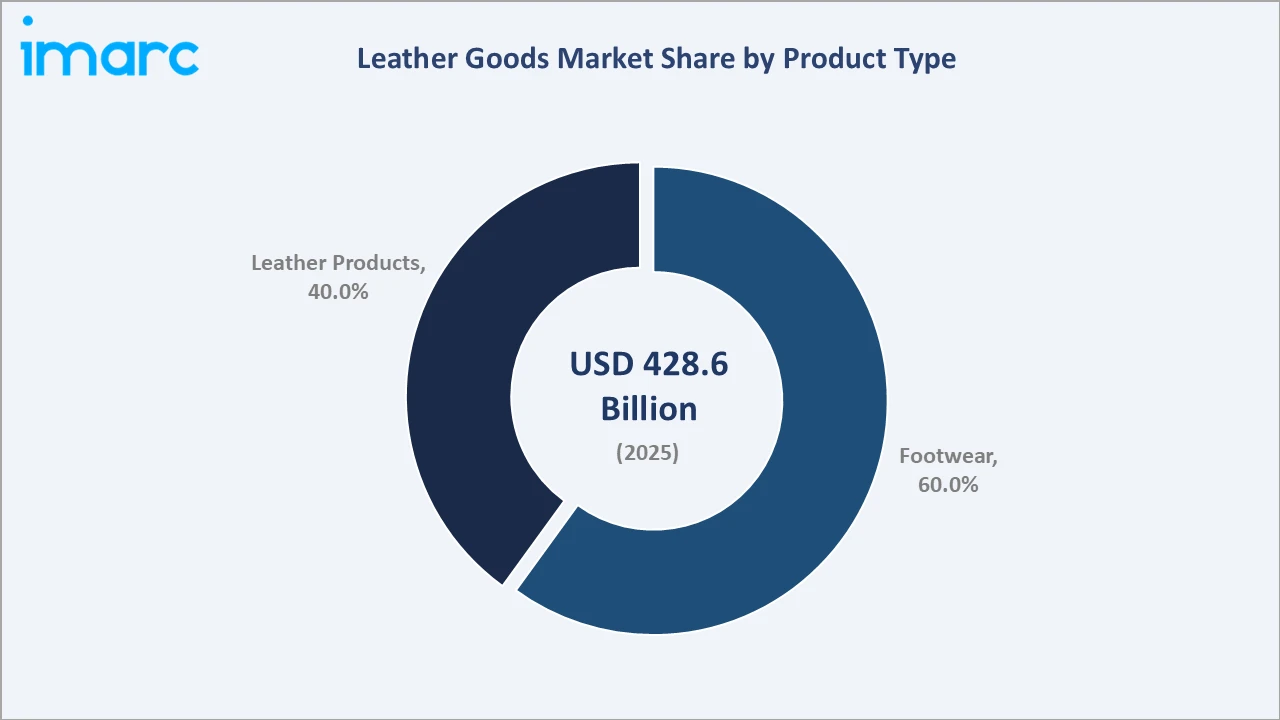
Expanding e-commerce, rising gifting culture, and youth preference for branded and stylish leather goods are further supporting market growth. Footwear dominates at 60.0%. Genuine leather leads material segments at 55.0%. North America commands 35.0% of the global market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 428.6 Billion |
| Market Size (2026) | USD 456.9 Billion |
| Forecast Market Size (2034) | USD 648.1 Billion |
| CAGR (2026-2034) | 4.47% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Product Segment | Footwear (60.0%, 2025) |
| Dominant Material Segment | Genuine Leather (55.0%, 2025) |
| Leading Region | North America (35.0%, 2025) |
The global leather goods market size increased from USD 344.5 Billion in 2020 to USD 428.6 Billion in 2025 and is estimated to reach USD 456.9 Billion in 2026. The market is further expected to grow to USD 533.3 Billion by 2030 and USD 648.1 Billion by 2034. The global leather goods market is commercially unique among consumer goods categories for its extraordinary price stratification, spanning mass-market everyday footwear to ultra-luxury heritage handbags at the highest price tiers.
To get more information on this market, Request Sample
Growing consumer preference for premium and branded leather accessories, supported by rising disposable incomes and aspirational lifestyles, is a primary structural driver sustaining long-term demand across footwear, handbags, and accessories segments globally.
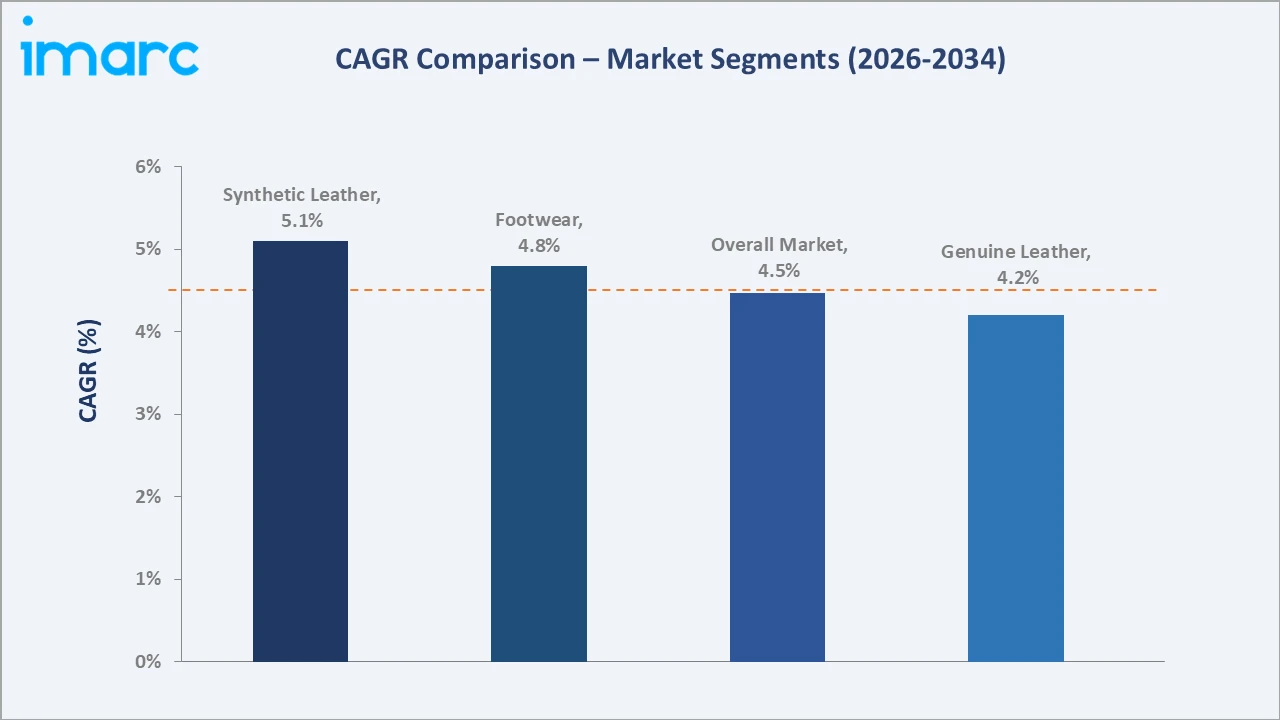
Across segments, synthetic leather is the fastest-growing material category, expanding at ~5.1% CAGR through 2034, driven by rising vegan consumer preferences, cost competitiveness versus genuine leather, and continuous technological improvements in PU-based and bio-based polymer manufacturing. The footwear segment leads product growth at ~4.8% CAGR, supported by high purchase frequency across casual, formal, and athletic categories. Genuine leather maintains a steady ~4.2% CAGR underpinned by its durability, premium positioning, and persistent consumer preference in luxury segments.
Executive Summary
The global leather goods market expanded from USD 428.6 Billion in 2025 to an estimated USD 456.9 Billion in 2026, positioning it among the world's largest and most commercially significant consumer goods markets by value. The market's scale is underpinned by a broad global consumer base, the enduring cultural significance of leather goods as status symbols and gifting items, and rising consumer aspirations for internationally recognized premium and luxury leather brands. These structural demand drivers are supporting the expansion of the luxury leather segment at a rate that outpaces overall consumer goods market growth in most key geographies. The market is projected to reach USD 648.1 Billion by 2034. Footwear at 60.0% leads through commercial breadth and high purchase frequency across casual, formal, and athletic categories. Genuine leather at 55.0% reflects persistent consumer preference for premium, durable, and status-signaling materials. North America leads regionally at 35.0%, driven by high household spending and a concentrated luxury retail ecosystem.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Product Segment | Footwear – 60.0% share (2025) |
| Dominant Material Segment | Genuine Leather – 55.0% market share (2025) |
| Leading Region | North America – 35.0% share (2025) |
| Market Opportunity | Expanding e-commerce leather retail in Asia Pacific; premiumization of accessories in emerging markets |
Key Analytical Observations Supporting the Above Data:
- Footwear at 60.0%: The footwear segment dominates due to its high purchase frequency, wide consumer appeal, and commercial breadth spanning casual, formal, athletic, and specialty categories across all price tiers and geographies. Its dominance reflects the universal nature of footwear demand.
- Genuine Leather at 55.0%: Genuine leather leads the material segment through its premium quality perception, longevity, and alignment with the luxury branding strategies of established global fashion houses. Its established tanning infrastructure further supports supply-side resilience.
- North America at 35.0%: North America's 35.0% regional share reflects the region's high household discretionary spending, a dense luxury retail ecosystem, and the concentration of globally recognized leather goods brands with strong domestic and international consumer followings.
Global Leather Goods Market Overview
The global leather goods market is commercially positioned at a unique intersection of fashion, functionality, and cultural heritage. With USD 456.9 Billion in 2026, the market spans footwear, handbags, wallets, belts, luggage, and apparel segments across premium and mass tiers, serving a diverse global consumer base from mass-market buyers to ultra-high-net-worth luxury collectors.
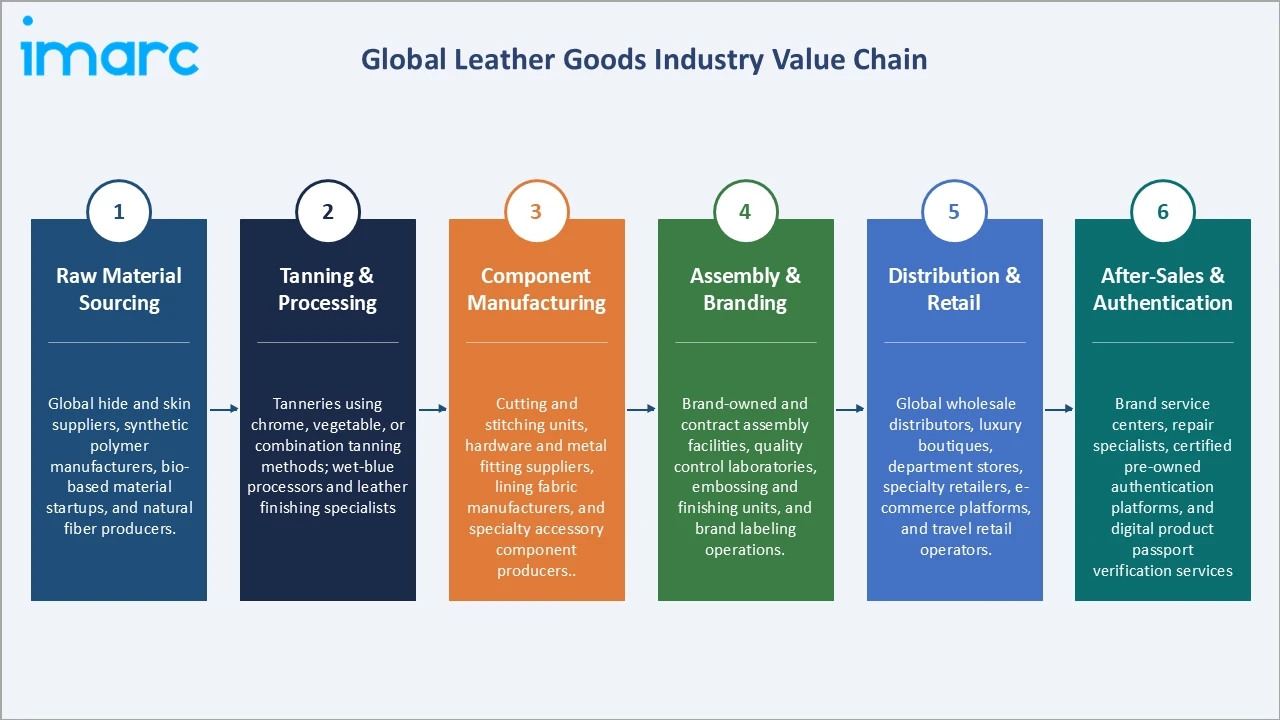
The leather goods ecosystem integrates raw material sourcing, tanning, component manufacturing, brand marketing, and multi-channel distribution. Macroeconomic factors including income growth, tourism recovery, and digital commerce expansion are collectively driving sustained market growth across all key geographies and consumer segments.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
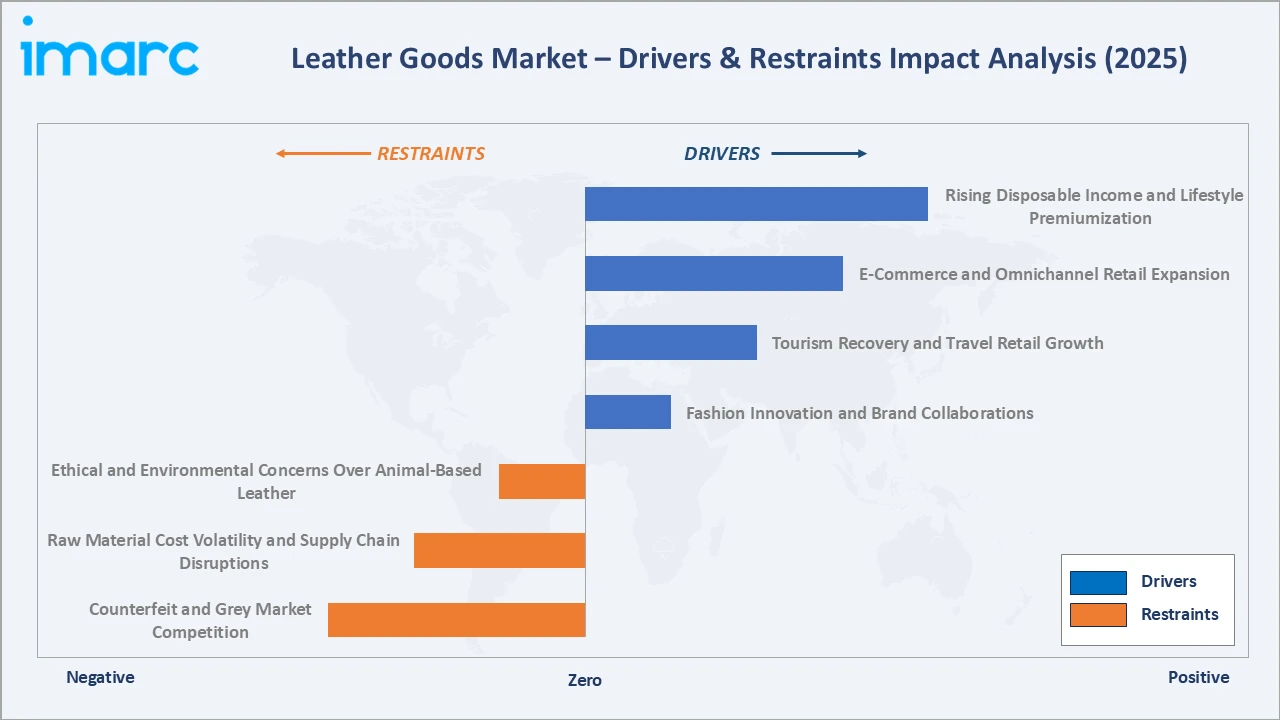
- Rising Disposable Income and Lifestyle Premiumization: Rising disposable income and lifestyle premiumization are driving market demand as consumers increasingly allocate budgets toward premium and branded leather accessories. Growing purchasing power among urban and middle-class populations is boosting demand for higher-quality leather goods across footwear, handbags, and accessories globally.
- E-Commerce and Omnichannel Retail Expansion: E-commerce and omnichannel retail expansion are providing consumers with convenient access to global leather goods brands across all price tiers. Online platforms, direct-to-consumer channels, and social commerce are reducing geographic barriers and enabling brand discovery across both established and emerging markets.
- Tourism Recovery and Travel Retail Growth: International tourism recovery and expanding travel retail networks are driving impulse purchases of leather goods in airports, luxury malls, and destination retail outlets. Travel retail's leather goods sales are growing particularly strongly in Europe and Asia Pacific following post-pandemic recovery.
- Fashion Innovation and Brand Collaborations: Fashion industry innovation, including limited-edition designer collaborations, influencer marketing, and celebrity brand partnerships, is generating aspirational consumer demand and sustaining premium pricing power for established leather goods brands globally.
Market Restraints
- Ethical and Environmental Concerns Over Animal-Based Leather: Growing consumer and regulatory awareness about the environmental and ethical implications of animal-based leather production is creating reputational challenges for brands and limiting expansion in ethically conscious consumer segments across key markets globally.
- Raw Material Cost Volatility and Supply Chain Disruptions: Fluctuating raw material costs, including hide price volatility and supply chain disruptions, create significant margin pressures across the leather goods value chain, particularly affecting mid-market manufacturers and smaller independent brands.
- Counterfeit and Grey Market Competition: The persistent presence of counterfeit leather goods and grey market products continues to undermine brand equity, erode authorized retail revenues, and create pricing reference distortions that challenge legitimate brand positioning across major consumer markets.
Market Opportunities
- Sustainable and Vegan Leather Material Innovation: Consumer demand for ethical and sustainable products is accelerating the development of plant-based, mushroom-derived, and bio-based leather alternatives, creating a high-growth product opportunity as brands invest in next-generation sustainable material platforms.
- Emerging Market Retail and E-Commerce Expansion: Emerging markets in Southeast Asia, India, and Africa present significant untapped growth opportunities, as rising urbanization, income growth, and brand awareness drive leather goods adoption among new consumer demographics.
Market Challenges
- Rapid Changes in Fashion Trends and Consumer Preferences: Fast-evolving fashion cycles and shifting consumer preferences create inventory management challenges and require continuous product innovation investment, increasing operational complexity and costs for brands across all price tiers.
- Supply Chain Complexity and Geopolitical Vulnerabilities: The global leather goods supply chain's complexity spanning tanneries, component suppliers, and manufacturers across multiple continents creates structural vulnerabilities during geopolitical disruptions, trade policy changes, or pandemic-related supply shocks.
Emerging Market Trends
1. Sustainable and Vegan Leather Adoption Creating the Leather Goods Market's Most Commercially Disruptive Material Innovation Trend
Consumer demand for ethical and sustainable products is accelerating the commercialization of plant-based, mushroom-derived, and bio-based synthetic leather alternatives across multiple product categories. Leading brands including Stella McCartney, Gucci, and Adidas are integrating sustainable materials such as Mylo, Piñatex, and Desserto into core product lines, signaling a strategic industry shift rather than a niche positioning exercise. Regulatory pressure from the European Union's Green Deal, incoming deforestation regulations, and extended producer responsibility frameworks are accelerating mandatory sustainability compliance across supply chains. Brand investment in sustainable material R&D is expanding, with multiple venture-backed bio-material startups reaching Series B and C funding rounds. Consumer willingness-to-pay premiums for certified sustainable leather goods is increasing, particularly among Millennial and Gen Z demographics in North America and Western Europe, creating commercially viable addressable markets for sustainably positioned leather goods brands.
2. Luxury Resale and Certified Pre-Owned Leather Goods Market Creating a Novel High-Growth Revenue Stream
The certified pre-owned luxury leather goods market is expanding at a double-digit CAGR, driven by younger consumers seeking accessible luxury entry points and sustainability-conscious purchasing behavior that values circularity over first-hand ownership. Dedicated platforms including The RealReal, Vestiaire Collective, and Rebag are formalizing authentication, dynamic pricing, and logistics infrastructure for this segment, transforming what was once an informal grey market into a structured, high-margin business category. Brand-owned resale programs, such as those piloted by Balenciaga and Burberry, indicate growing recognition among heritage brands that controlled participation in the resale market protects brand equity and captures value that would otherwise accrue entirely to third-party platforms. The institutionalization of resale also strengthens the investment thesis for new luxury leather goods purchases by enhancing perceived residual value and reducing total cost of ownership for premium consumers, thereby stimulating primary market demand in a reinforcing cycle.
3. Digital-First and Direct-to-Consumer Brand Strategy Transformation Reshaping Distribution Economics
Leather goods brands across luxury, affordable luxury, and accessible segments are investing heavily in direct-to-consumer digital channels, systematically reducing dependence on traditional wholesale distribution models that dilute margins and diminish brand control. Social commerce through Instagram, TikTok Shop, and WeChat mini-programs is enabling brands to convert aspirational engagement directly into purchasing transactions, compressing the traditional consideration-to-conversion funnel. Influencer and creator partnerships are reshaping brand discovery dynamics, with nano and micro-influencer networks delivering higher engagement and conversion efficiency than traditional celebrity endorsement models. Data captured through DTC channels is enabling increasingly personalized product recommendations, loyalty programming, and demand forecasting, creating compounding competitive advantages for brands that have invested earlier and more deeply in first-party consumer data infrastructure. Brands that structurally favor DTC distribution are demonstrating superior gross margin profiles and inventory management outcomes compared to wholesale-dependent peers.
4. Smart and Technology-Integrated Leather Accessories Emerging as a Premium Differentiator
Technology integration in leather accessories, including NFC-enabled product authentication chips embedded in handbags and wallets, GPS-tracked luxury bags, and QR-code-based supply chain transparency labels, is transitioning from experimental pilots to commercially scaled product features at premium brands. Digital product passports, mandated under evolving EU circular economy regulation, are accelerating the embedding of unique digital identifiers into leather goods, creating a structural compliance and brand differentiation driver simultaneously. Blockchain-based provenance tracking is being adopted by leading luxury houses to provide immutable, consumer-verifiable records of material origin, manufacturing history, and ownership chain, directly addressing counterfeiting and grey-market diversion concerns. Wearable technology integration, including RFID payment capabilities and biometric sensor compatibility in smart leather accessories, is opening new product categories at the intersection of fashion and consumer electronics, attracting both fashion-forward consumers and technology-savvy demographics seeking multifunctional premium accessories.
Industry Value Chain Analysis
The global leather goods value chain is one of the most geographically distributed of any consumer goods category. The value chain's commercial structure creates unique market dynamics, where raw material sourcing regions, tanning clusters, and finished goods manufacturers operate across separate geographies with distinct labor, regulatory, and cost profiles that collectively shape end-market pricing and brand profitability.
| Stage | Key Participants |
|---|---|
| Raw Material Sourcing | Global hide and skin suppliers, synthetic polymer manufacturers, bio-based material startups, and natural fiber producers. |
| Tanning & Processing | Tanneries using chrome, vegetable, or combination tanning methods; wet-blue processors and leather finishing specialists. |
| Component Manufacturing | Cutting and stitching units, hardware and metal fitting suppliers, lining fabric manufacturers, and specialty accessory component producers. |
| Assembly & Branding | Brand-owned and contract assembly facilities, quality control laboratories, embossing and finishing units, and brand labeling operations. |
| Distribution & Retail | Global wholesale distributors, luxury boutiques, department stores, specialty retailers, e-commerce platforms, and travel retail operators. |
| After-Sales & Authentication | Brand service centers, repair specialists, certified pre-owned authentication platforms, and digital product passport verification services. |
The assembly and branding stage represents the leather goods value chain's most commercially consequential and highest value-added stage, where brand equity, design differentiation, and quality certification collectively determine consumer willingness-to-pay and establish the pricing authority that separates luxury brands from mass-market competitors.
Technology Landscape in the Leather Goods Industry
Advanced Tanning and Sustainable Processing Technologies
Advanced tanning technologies, including enzymatic tanning, chrome-free processing, and waterless tanning methods, are fundamentally reducing the environmental footprint of leather production while maintaining the material quality standards required for premium and luxury applications. Enzymatic tanning processes eliminate hazardous chemical inputs, reduce water consumption by up to 50%, and produce leathers with superior softness and breathability characteristics that command pricing premiums in performance footwear and luxury handbag segments. Chrome-free tanning technologies, including vegetable, aldehyde, and metal-free synthetic tanning systems, are gaining regulatory-driven adoption as the EU and key importing markets impose stricter limits on hexavalent chromium residues in finished leather goods. Waterless and low-water tanning innovations, including CO2-based supercritical fluid processing, are emerging from pilot scale to commercial deployment, addressing water scarcity constraints at major tanning clusters in Italy, India, and China. Industry investment in closed-loop water recycling systems and zero-discharge tannery operations is accelerating, driven by both regulatory compliance requirements and cost reduction imperatives in water-stressed manufacturing regions.
Bio-Based and Synthetic Leather Material Innovation
Bio-based leather materials derived from fungi mycelia, pineapple leaf fibers, cactus pulp, apple pomace, and grape skin waste are progressing from laboratory development to commercial production scale, supported by dedicated brand investment, specialized manufacturing partnerships, and growing consumer willingness-to-pay for non-animal-derived luxury goods. Bolt Threads' Mylo material, Ananas Anam's Piñatex, Desserto's cactus leather, and Vegea's grape-based material represent commercially deployed alternatives that have secured brand partnerships with Hermès, Adidas, H&M, and Stella McCartney respectively, validating the market development trajectory for bio-based leather at scale. Synthetic leather advancements in high-performance polyurethane, bio-based PU formulations, and microfiber composite materials are delivering improved durability, weather resistance, and texture consistency that are closing the performance gap with genuine leather in multiple product categories. The convergence of bio-based raw materials with advanced polymer processing technologies is enabling the development of hybrid materials that combine the aesthetic properties of genuine leather with the sustainability credentials of bio-based inputs, creating a new material category positioned at the intersection of luxury and environmental responsibility.
Digital Manufacturing and Industry 4.0 Integration
Digital pattern cutting systems utilizing AI-optimized nesting algorithms are reducing leather hide waste by 15–25% compared to traditional manual cutting methods, delivering significant raw material cost savings while simultaneously improving sustainability metrics for leather goods manufacturers across production scales. Automated stitching and assembly systems are enabling precision manufacturing at higher speeds with consistent quality outputs, reducing dependence on specialized skilled labor and enabling geographic diversification of production operations away from traditional craft manufacturing clusters. AI-driven quality control systems utilizing computer vision are achieving defect detection accuracy rates that match or exceed human inspection performance while delivering significantly higher throughput and consistent documentation of quality standards for regulatory and brand compliance purposes. Mass customization capabilities enabled by digital manufacturing infrastructure are opening new commercial models including made-to-order and bespoke leather goods at accessible price points, expanding the addressable market for personalized leather products beyond the traditional luxury custom segment.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product | Footwear | 60.0% | 2025 |
| Price | 🔒 | 🔒 | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| Material | Genuine Leather | 55.0% | 2025 |
| Region | North America | 35.0% | 2025 |

By Product
Footwear leads at 60.0% (2025). The footwear segment encompasses the leather goods market's most commercially diverse and highest-volume category, spanning military, casual, formal, sports, and specialty footwear. Its dominance reflects ubiquitous consumer demand, high annual purchase frequency, and the segment's commercial breadth across mass-market, fashion, and luxury price tiers in all major geographies.
To access detailed market analysis, Request Sample
Leather Products at 40.0% includes upholstery, luggage, accessories, clothing and apparel, bags, wallets, and purses. This segment grows at ~3.9% CAGR through premiumization in luxury handbags, growing luggage demand from international travel recovery, and the expanding global accessories market among fashion-conscious consumers through 2034.
By Material
Genuine leather leads at 55.0% (2025). This segment encompasses top-grain and split-grain leathers, commanding premium market positions across footwear and accessories. Its dominance reflects established consumer preference for authentic, durable, and status-signaling materials, supported by robust tanning industry infrastructure in Italy, Brazil, India, and China.
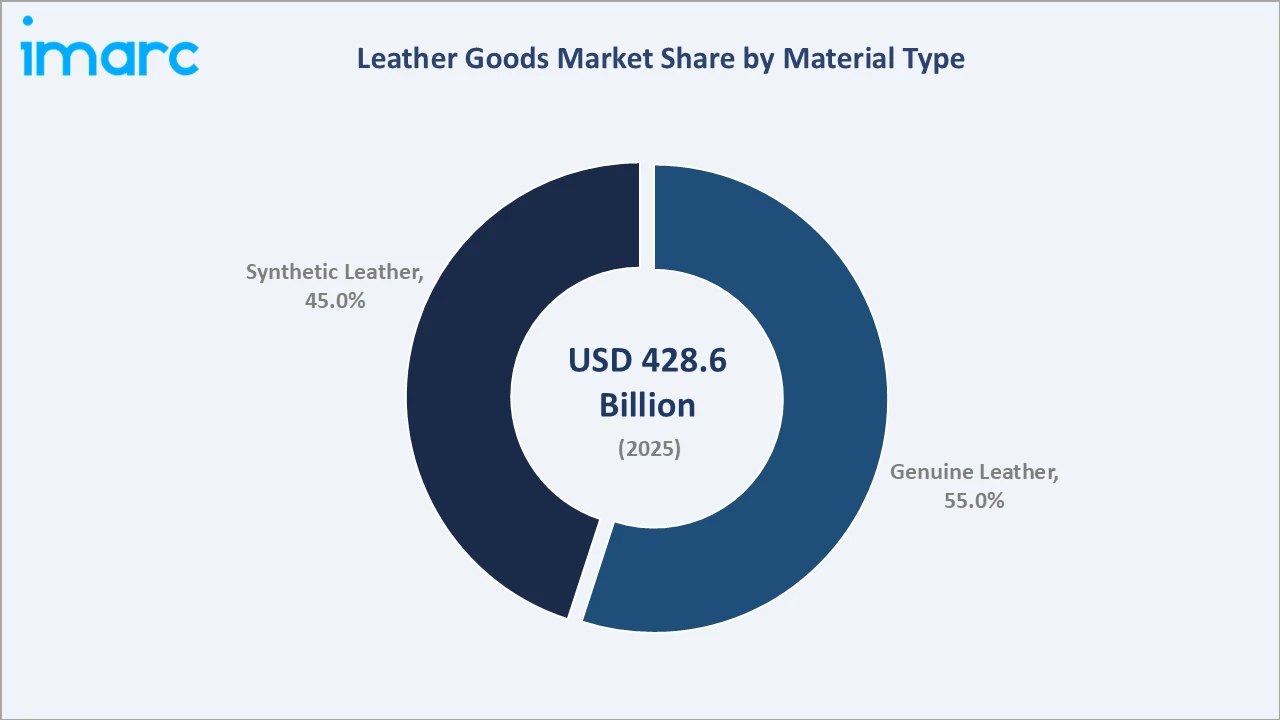
Synthetic leather at 45.0% grows fastest at ~5.1% CAGR through vegan lifestyle adoption, cost advantages over genuine leather, and significant technological performance improvements. PU-based, PVC-based, and bio-based variants are capturing increasing market share across mass-market and mid-range categories as performance parity with genuine leather improves.
Regional Market Insights
| Region | Share (2025) | Key Leather Goods Market Drivers & Characteristics |
|---|---|---|
| North America | 35.0% | Driven by high per-capita discretionary spending, concentrated luxury retail networks, and strong domestic brand ecosystems for leather footwear and accessories. |
| Asia Pacific | 30.0% | Fastest-growing region supported by China's luxury consumption growth, India's expanding middle class, and rising fashion aspiration across Southeast Asian markets. |
| Europe | 22.0% | Heritage luxury brands, Italy's world-leading tanning industry, and strong domestic and tourist-driven demand for authentic European leather goods. |
| Latin America | 7.0% | Growing domestic leather manufacturing in Brazil and Argentina, rising brand-conscious consumer class, and increasing e-commerce leather goods penetration. |
| Middle East & Africa | 6.0% | Gulf Cooperation Council luxury demand, growing African urbanization, and rising disposable incomes driving leather goods adoption across the region. |
North America's 35.0% market leadership reflects the United States' dominant luxury retail density, high household discretionary spending on fashion and accessories, and the concentration of globally recognized leather goods brands. The region also benefits from a well-developed e-commerce infrastructure that broadens access to premium leather goods.
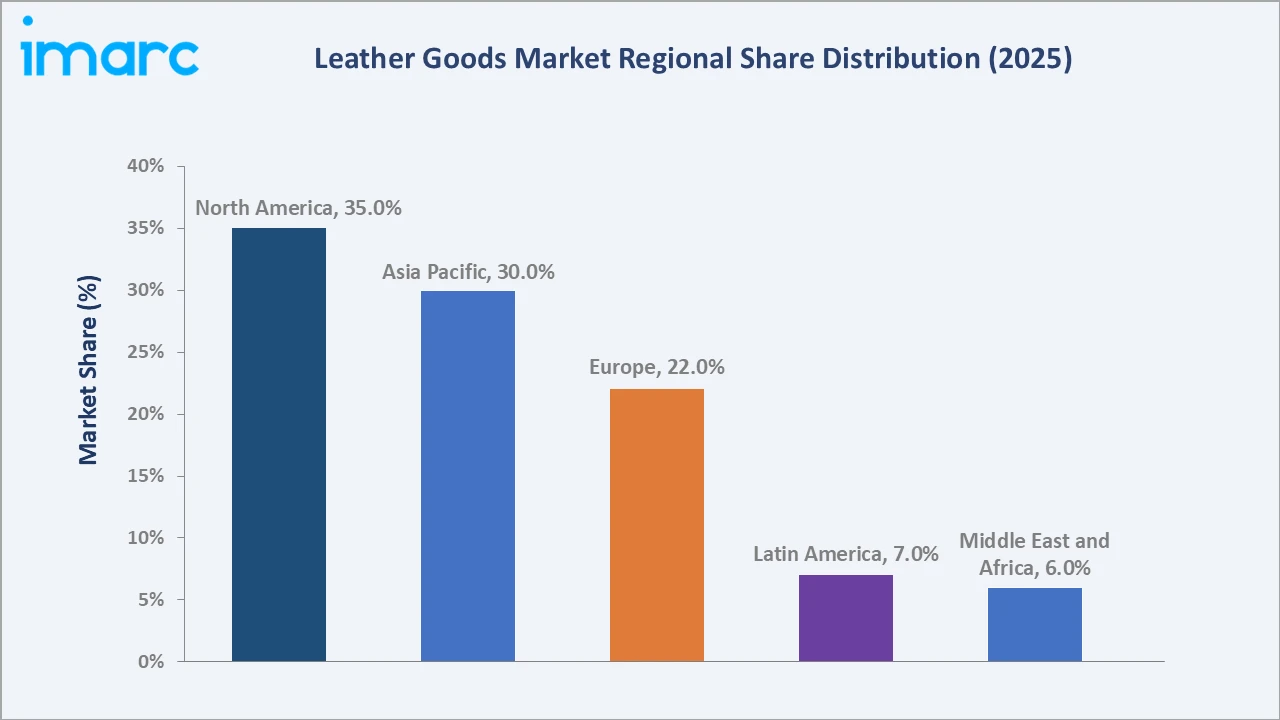
Asia Pacific's 30.0% share reflects China's dominant luxury leather goods consumption, India's rapidly expanding organized retail and e-commerce sector, and Japan's established premium leather goods culture. Regional digital commerce growth is further accelerating market penetration across younger demographics in emerging Southeast Asian markets.
Europe's 22.0% share reflects the region's role as the global epicenter of luxury leather heritage brands, with Italy and France hosting world-leading tanneries and fashion houses. Latin America's 7.0% and Middle East & Africa's 6.0% represent emerging growth frontiers driven by urbanization, income growth, and expanding brand awareness among aspirational consumer segments.
Competitive Landscape
The global leather goods market competitive landscape spans luxury conglomerates, specialized luxury heritage houses, and mass-market sportswear and accessories brands. Competition is intense across all price tiers, with brand equity, global distribution reach, design innovation, and sustainability credentials as the primary competitive differentiators across both established and emerging consumer markets.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Adidas AG | Athletic footwear, leather sports goods | Mass-premium leader | Global brand equity, sports marketing, and widespread distribution reach |
| American Leather Holdings LLC | Premium leather furniture, custom leather accessories | Specialty player | Custom manufacturing capability and premium quality craftsmanship |
| Capri Holdings Limited | Michael Kors, Versace, Jimmy Choo leather goods | Premium challenger | Diversified multi-brand portfolio across accessible and luxury tiers |
| Hermès International S.A. | Birkin bags, Kelly bags, luxury leather goods | Luxury leader | Artisanal heritage, deliberate scarcity model, and extreme brand pricing power |
| Kering S.A. | Gucci, Saint Laurent, Balenciaga leather goods | Luxury conglomerate | Diversified luxury brand portfolio with strong sustainability leadership |
The competitive landscape's most commercially significant dynamic is the growing divide between consolidated luxury conglomerates commanding superior pricing power and global retail distribution and independent specialty brands that seek to differentiate through craftsmanship heritage, sustainability positioning, and niche consumer community building.
Key Company Profiles
Kering S.A.
Kering S.A. is a global luxury goods group managing a prestigious portfolio of leather goods and fashion brands. The group is internationally recognized for its pioneering commitment to sustainability and Environmental Profit & Loss accounting methodology.
- Key Products: Gucci, Saint Laurent, Bottega Veneta, Balenciaga, and Alexander McQueen leather handbags, footwear, belts, small leather goods, and fashion accessories.
- Recent Developments: In 2026, Kering S.A.’s Bottega Veneta launched a limited collection of six small leather goods made using Ephea, a mycelium-based material developed by Italian startup Sqim. The material replaces bovine leather in the brand’s signature Intrecciato woven design and features in its Fall 2026 men’s collection. The initiative combines traditional leather-working craftsmanship with alternative material innovation, supporting Kering’s efforts to diversify its raw materials and develop lower-impact options for luxury leather products.
- Strategic Focus: Balancing luxury brand creativity and commercial performance with industry-leading sustainability commitments to attract premium consumers and institutional investors aligned with responsible business practice standards.
Hermès International S.A.
Hermès International S.A. is a French luxury goods manufacturer celebrated for exceptional artisanal craftsmanship, deliberate scarcity-driven brand positioning, and its globally iconic leather goods portfolio commanding the industry's highest price points.
- Key Products: Birkin and Kelly handbags, leather belts, wallets, agenda covers, footwear, saddlery, and small leather goods crafted with proprietary tanning and artisanal production methods.
- Recent Developments: In 2026, Hermès International S.A. announced plans to establish a new leather goods manufacturing workshop in Les Andelys, in France’s Eure department. The facility is expected to create 260 artisan jobs and strengthen the company’s production capabilities for its leather goods and saddlery collections. The project will redevelop a former industrial site and complement Hermès’ existing workshops in Normandy. The company will recruit and train artisans through its École Hermès des savoir-faire, supporting the preservation of traditional leatherworking skills while expanding long-term manufacturing capacity.
- Strategic Focus: Sustaining artisanal heritage and deliberate supply scarcity model to command category-leading pricing power, while selectively exploring sustainable material innovation to future-proof brand positioning for next-generation luxury consumers.
Market Concentration Analysis
The global leather goods market exhibits a moderately concentrated competitive structure at the premium and luxury tiers, where a small number of large conglomerates collectively command significant revenue share through their diversified brand portfolios and global distribution capabilities. Mass-market and mid-range segments remain considerably more fragmented, with a large number of regional and local brands competing on price and design.
Market concentration is evolving through two opposing structural forces: consolidation among luxury conglomerates extending their brand portfolios and retail distribution footprints, and the simultaneous emergence of independent, digitally native brands that target niche consumer segments through sustainability, craftsmanship heritage, and personalization differentiation, creating a structurally dual-track competitive market.
Investment & Growth Opportunities
Highest Growth Segments
Synthetic leather segment (~5.1% CAGR through sustainable material adoption and vegan consumer demand), footwear category (~4.8% CAGR through casual and athletic expansion), Asia Pacific regional market (~5.5% CAGR through income growth and urbanization), certified pre-owned luxury leather goods platforms (~15–20% CAGR from emerging base), and e-commerce leather goods channel growth (~8–10% CAGR through digital retail expansion).
Emerging Investment Opportunities
The certified pre-owned luxury leather goods market, growing at 15–20% annually, represents the highest-CAGR investment opportunity in the leather goods space. Growth is driven by sustainability-conscious purchasing behavior, accessibility premium demand among younger luxury consumers, and the scalability of digital authentication and logistics platforms.
Investment Themes
- Sustainable Leather Material Innovation Platforms: Bio-based and vegan leather material startups addressing growing ethical consumer demand, with investment in platforms that serve multiple product categories footwear, handbags, and accessories creating diversified revenue streams from a single sustainable material base.
- Asia Pacific Leather Goods Retail and E-Commerce Expansion: Asia Pacific leather goods retail investment, capitalizing on rising disposable incomes, fashion aspiration, and digital commerce infrastructure development across China, India, Southeast Asia, and emerging ASEAN markets where brand penetration remains commercially underdeveloped.
Future Market Outlook (2026-2034)
The global leather goods market is projected to grow from USD 428.6 Billion in 2025 to USD 456.9 Billion in 2026, reaching USD 648.1 Billion by 2034, registering a CAGR of 4.47% during 2026-2034. The market's anchor value of USD 533.3 Billion in 2030 represents the leather goods industry at a structural inflection, where synthetic and bio-based material adoption begins materially reshaping the competitive material landscape.
Three structural forces define leather goods market growth through 2034 rising affluence in Asia Pacific, creating the fastest-growing regional leather goods consumer base; sustainability mandates driving material innovation and brand repositioning across all price tiers; and digital commerce permanently expanding the addressable market reach of both global luxury brands and independent specialty leather goods manufacturers.
Research Methodology
Primary Research
Primary research comprised structured interviews with leather goods industry stakeholders, including retail directors, brand managers, tannery operators, distribution executives, and consumer survey data from leather goods buyers across North America, Europe, and Asia Pacific. Insights from trade associations, industry exhibitions, and expert consultations informed qualitative market dynamics and competitive landscape assessments.
Secondary Research
Secondary research encompassed company annual reports, trade publications, leather goods import-export data, fashion industry databases, luxury market studies, and government statistical sources across major markets. Global retail analytics, consumer behavior surveys, e-commerce platform data, and sustainability certification reports supplemented quantitative market sizing, segment analysis, and regional market intelligence.
Forecasting Models
Market revenue forecasts were developed using a consumer income stratification model: regional affluent and middle-class population segments multiplied by category purchase frequency and average transaction values per segment, creating total market revenue by segment aggregation. A sustainability adoption multiplier was applied across material segments to account for the accelerating shift toward synthetic and bio-based leathers through 2034, cross-validated against historical revenue trends and macroeconomic projections.
Leather Goods Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered |
|
| Materials Covered |
|
| Prices Covered | Premium Products, Mass Products |
| Distribution Channels Covered | Clothing and Sportswear Retailers, Departmental Stores, Supermarkets and Hypermarkets, Online Stores, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Adidas AG, American Leather Holdings LLC, Capri Holdings Limited, Hermès International S.A., Kering S.A., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the global leather goods market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the leather goods market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the leather goods industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Leather Goods Market Report
The global leather goods market size is estimated at USD 456.9 Billion in 2026, driven by rising disposable incomes, premiumization, e-commerce expansion, and growing demand for branded leather footwear and accessories across key global markets.
The leather goods market grows at a CAGR of 4.47% during 2026-2034, reaching USD 648.1 Billion by 2034. Growth is sustained by Asia Pacific expansion, synthetic leather adoption, e-commerce development, and luxury premiumization trends globally.
Footwear leads at 60.0% through ubiquitous consumer demand across casual, formal, sports, and specialty footwear categories at all price tiers, reflecting the segment's commercial breadth and high annual purchase frequency.
Genuine leather leads at 55.0% through durability perception, luxury positioning, and established tanning industry infrastructure, while synthetic leather grows fastest at ~5.1% CAGR through vegan adoption and material performance improvements.
North America leads at 35.0% through high per-capita spending, luxury retail density, and strong domestic and international brand presence, followed by Asia Pacific at 30.0%, which is the fastest-growing regional market.
Leading companies include Adidas AG, American Leather Holdings LLC, Capri Holdings Limited, Hermès International S.A., and Kering S.A., among others.
The leather goods market is projected to reach approximately USD 533.3 Billion by 2030, with Asia Pacific and synthetic leather segments driving incremental growth as e-commerce infrastructure and sustainable material adoption accelerate.
Top investment opportunities include synthetic and bio-based leather material platforms, Asia Pacific retail and e-commerce expansion, certified pre-owned luxury leather goods platforms, and digital personalization and authentication technology investments.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade