
RFID Market Size, Share, Trends and Forecast by Type, Product, Frequency, End Use, and Region, 2026-2034
RFID Market Size, Share, Trends & Forecast (2026-2034)
The global RFID market grew from USD 16.10 Billion in 2025 to USD 18.09 Billion in 2026 and is projected to reach USD 47.41 Billion by 2034, growing at a CAGR of 12.37% during 2026-2034. Demand is fueled by expanding IoT ecosystems, real-time asset tracking requirements across retail, healthcare, and logistics, and growing regulatory mandates for product traceability. Passive RFID dominates at 72.6% by type in 2025, and tags lead at 58.7% by product. North America holds the largest regional share at 28.7%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 16.10 Billion |
|
Market Size (2026) |
USD 18.09 Billion |
|
Forecast Market Size (2034) |
USD 47.41 Billion |
|
CAGR (2026-2034) |
12.37% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Passive RFID (72.6%, 2025) |
|
Dominant Product |
Tags (58.7%, 2025) |
|
Leading Region |
North America (28.7%, 2025) |
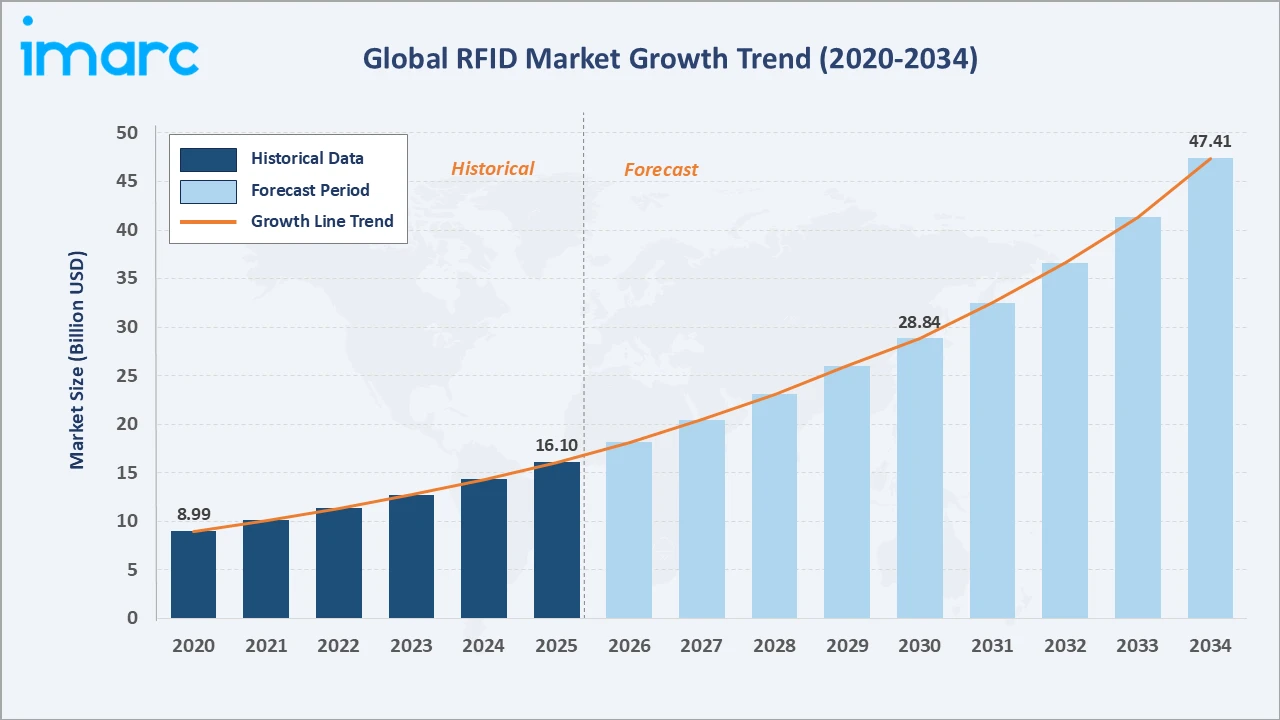
The global RFID market expanded from USD 8.99 Billion in 2020 to USD 16.10 Billion in 2025, and further to USD 18.09 Billion in 2026, reflecting robust adoption across supply chain, retail inventory, and healthcare asset management. The market is projected to reach USD 28.84 Billion by 2030 before reaching USD 47.41 Billion by 2034.
To get more information on this market, Request Sample
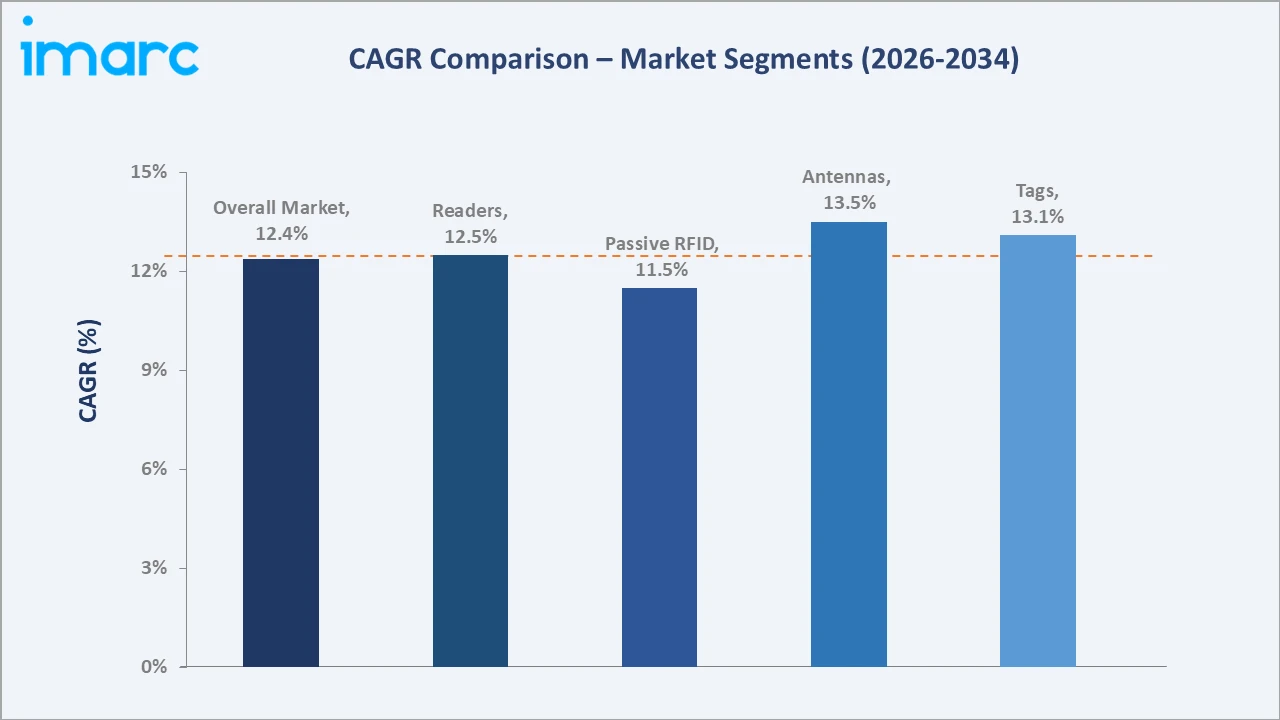
Tags grow at approximately 13.1% CAGR, driven by increasing deployment volumes in retail and logistics. Antennas, at 13.5% CAGR, benefit from expanding multi-reader infrastructure. Passive RFID grows at 11.5% as cost efficiencies widen its applicability. Readers record a 12.5% CAGR, supported by enterprise-grade fixed and handheld reader deployments.
Executive Summary
The RFID market is on a sustained high-growth trajectory, supported by converging technology advancements, growing enterprise demand for real-time visibility, and expanding regulatory frameworks requiring product authentication and traceability. The market grew from USD 16.10 Billion in 2025 to USD 18.09 Billion in 2026 and is projected to reach USD 47.41 Billion by 2034, growing at a CAGR of 12.37% during 2026–2034.
Passive RFID technology, commanding 72.6% of the market in 2025, continues to dominate due to low cost, ease of deployment, and suitability for high-volume retail and supply chain applications. Tags remain the highest-revenue product segment at 58.7%, underpinned by continuous growth in item-level tagging across apparel, pharmaceuticals, and fast-moving consumer goods. North America leads regionally at 28.7%, driven by advanced logistics infrastructure and early enterprise adoption.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Passive RFID – 72.6% share (2025) |
|
Dominant Product |
Tags – 58.7% share (2025) |
|
Leading Region |
North America – 28.7% (2025) |
|
Key Market Opportunity |
IoT integration and cloud-based RFID platforms are creating scalable, cross-industry deployment opportunities, particularly in manufacturing and healthcare. |
Key Analytical Observations Supporting the Above Data:
- Passive RFID at 72.6%: Passive RFID tags require no internal power source and are significantly cheaper to produce than active variants, making them the preferred choice for mass-scale item-level tagging across retail, logistics, and consumer goods industries.
- Tags at 58.7%: RFID tags are the primary data-carrying element in every RFID system. As item-level tagging mandates expand across pharma, apparel, and food sectors, tag volumes and revenue continue to grow at double-digit rates.
- North America at 28.7%: North America benefits from high enterprise IT spending, advanced logistics networks, and early adoption of RFID across retail supply chains and healthcare asset management, sustaining its global leadership through the forecast period.
Global RFID Market Overview
Radio Frequency Identification (RFID) is a wireless data capture technology that uses electromagnetic fields to automatically identify and track tags attached to objects. The global RFID ecosystem spans semiconductor manufacturers producing chips and inlays, hardware suppliers providing tags, readers, and antennas, and software vendors offering middleware, analytics, and cloud management platforms.
RFID finds application across retail inventory management, pharmaceutical serialization, livestock and food traceability, access control, library management, manufacturing work-in-progress tracking, and baggage handling in aviation. The market's macroeconomic underpinnings include the global push toward supply chain digitalization, the expansion of e-commerce requiring warehouse automation, and the rise of Industry 4.0 environments where real-time data is essential.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
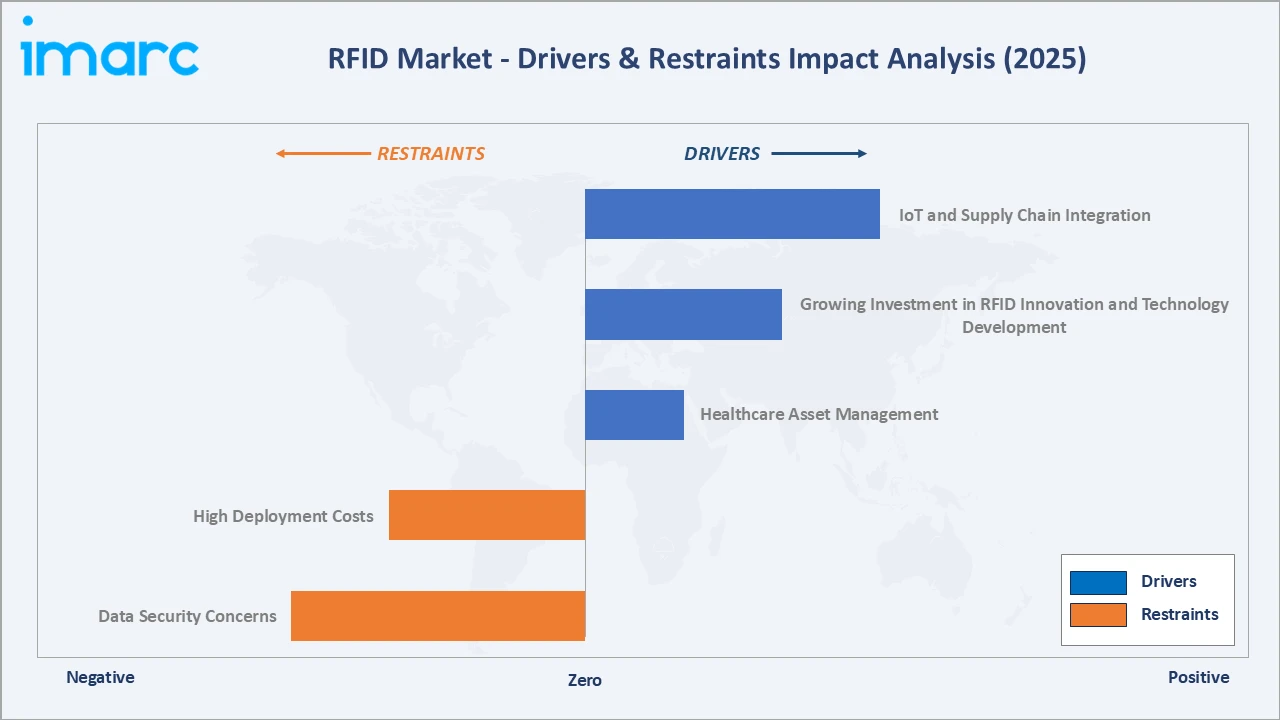
- IoT and Supply Chain Integration: The convergence of RFID with IoT networks is enabling real-time, automated asset visibility across extended supply chains, reducing manual intervention and improving operational efficiency in warehouse environments, driving broad enterprise adoption.
- Growing Investment in RFID Innovation and Technology Development: Increasing investments in research and development are driving advancements in RFID technology, improving its performance, reliability, and integration with Internet of Things (IoT) solutions. In December 2025, Murata ID Solutions launched an RFID Experience & Innovation Hub in Parma, Italy, dedicated to advancing IoT and RFID technologies through research, testing, demonstrations, and workshops.
- Healthcare Asset Management: RFID is increasingly deployed in hospitals and healthcare facilities to track medical equipment, pharmaceutical inventory, and patient identification, with adoption accelerating as healthcare systems prioritize operational efficiency and patient safety.
Market Restraints
- High Deployment Costs: The upfront investment required for RFID infrastructure, including readers, antennas, middleware, and enterprise system integration, can be significant for small and mid-sized organizations, creating a barrier to adoption particularly in cost-sensitive markets.
- Data Security Concerns: The wireless nature of RFID data transmission raises concerns around unauthorized data interception and privacy risks, particularly in consumer-facing applications, requiring additional investment in encryption and security protocols that increase total system costs.
Market Opportunities
- Cloud RFID Platforms: Cloud-native RFID management platforms enable scalable, software-as-a-service deployments that lower the total cost of RFID adoption, creating new demand from small and medium enterprises and emerging market organizations.
- Sensor-Fused Smart Tags: Advances in RFID chip miniaturization and sensor-fused smart tags capable of capturing temperature, humidity, and shock data are opening high-value applications in pharmaceutical cold-chain, food freshness monitoring, and precision industrial asset tracking.
Market Challenges
- RF Performance in Harsh Environments: RFID read performance can be degraded by metal surfaces, liquids, and electromagnetic interference, requiring specialized tag and reader configurations for applications in pharmaceutical labs, food processing, and metal manufacturing environments.
- System Integration Complexity: Integrating RFID infrastructure with existing enterprise resource planning, warehouse management, and supply chain management systems requires significant technical effort, increasing total implementation time and cost and extending the payback period.
Emerging Market Trends
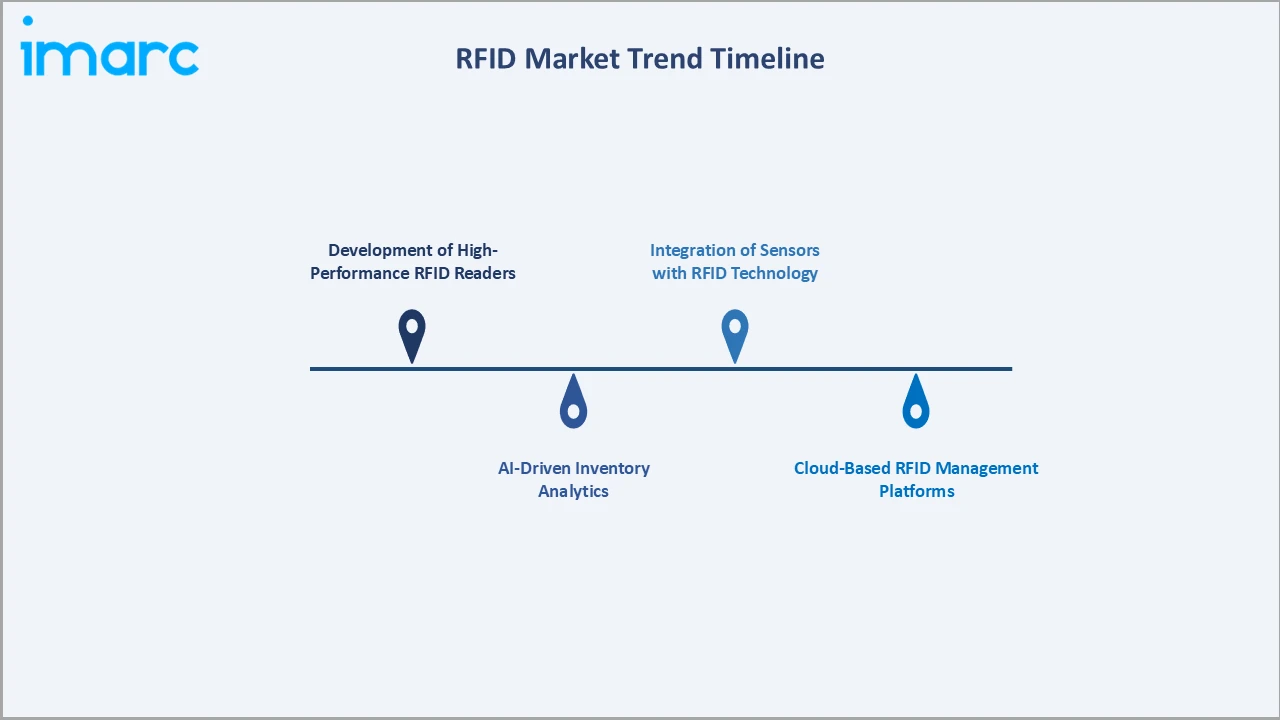
1. Development of High-Performance RFID Readers
RFID manufacturers are introducing advanced fixed readers with longer reading ranges and faster tag processing capabilities to meet the needs of high-throughput industrial and enterprise applications. In August 2026, Newland AIDC EMEA launched the URF520 Solea, its first fixed UHF RFID reader, designed for enterprise and industrial applications. Powered by an Impinj E710 chip, the device offers a reading range of up to 14 meters and supports high-speed scanning of up to 900 tags per second.
2. AI-Driven Inventory Analytics
Artificial intelligence is being applied to RFID-generated data streams to enable predictive inventory replenishment, demand forecasting, and loss prevention. AI algorithms analyze real-time tag read patterns to identify anomalies, optimize stock placement, and automate reorder processes, improving operational ROI across retail and distribution applications.
3. Integration of Sensors with RFID Technology
The integration of sensors with RFID is creating new opportunities for real-time monitoring, asset management, and industrial IoT applications. In August 2026, the RAIN Alliance launched an RFID Sensor Working Group to accelerate the development and adoption of sensor-enabled RAIN RFID technologies. The initiative brings together industry stakeholders to address applications, deployment challenges, and standards for industrial IoT, asset management, and digital product passports.
4. Cloud-Based RFID Management Platforms
SaaS-based RFID platforms are lowering the barrier to enterprise RFID adoption by eliminating on-premises server infrastructure and enabling subscription-based pricing. Cloud platforms enable multi-site visibility and data aggregation across global supply chains, making enterprise-scale RFID accessible to mid-market organizations with limited IT resources.
Industry Value Chain Analysis
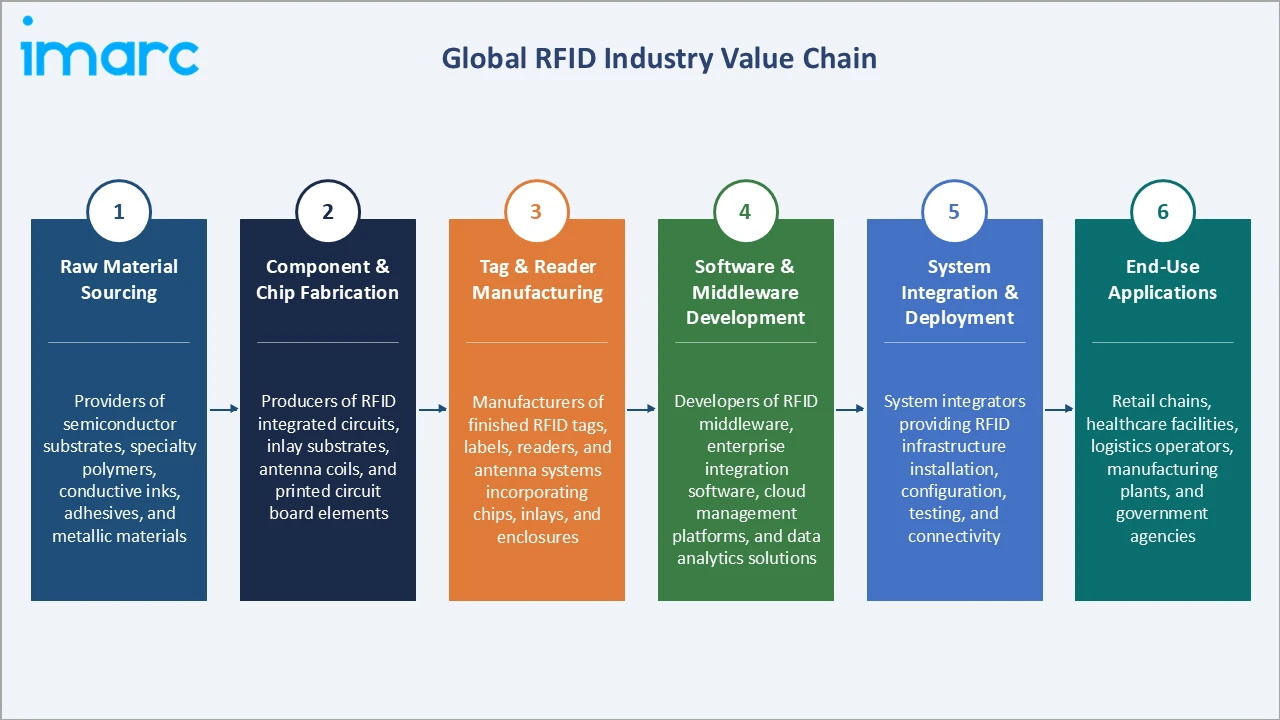
The RFID market value chain operates across six distinct stages, from upstream raw material sourcing through to end-user application deployment. Each stage contributes incremental value through processing, assembly, and software integration, with the highest value concentration at the system manufacturing and integration stages where proprietary technology creates lasting competitive advantages.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Providers of semiconductor substrates, specialty polymers, conductive inks, adhesives, and metallic materials. |
|
Component & Chip Fabrication |
Producers of RFID integrated circuits, inlay substrates, antenna coils, and printed circuit board elements. |
|
Tag & Reader Manufacturing |
Manufacturers of finished RFID tags, labels, readers, and antenna systems incorporating chips, inlays, and enclosures. |
|
Software & Middleware Development |
Developers of RFID middleware, enterprise integration software, cloud management platforms, and data analytics solutions. |
|
System Integration & Deployment |
System integrators providing RFID infrastructure installation, configuration, testing, and connectivity. |
|
End-Use Applications |
Retail chains, healthcare facilities, logistics operators, manufacturing plants, and government agencies. |
The tag & reader manufacturing stages hold the greatest strategic value in the RFID value chain. Chip and inlay manufacturers benefit from significant scale economies and proprietary silicon design. System integrators and software vendors differentiate through vertical-specific expertise and cloud platform capabilities that drive customer lock-in and recurring revenue streams.
Technology Landscape in the RFID Industry
Miniaturization and Advanced Chip Design
Continuous advances in CMOS semiconductor processes have enabled RFID chip areas to shrink below 0.15 mm², reducing material cost per tag and enabling integration into substrates previously impractical for RFID. Advanced chip designs also deliver improved read sensitivity, supporting longer read ranges and better performance in challenging RF environments.
Sensor-Integrated Smart Tags
Next-generation RFID tags incorporate environmental sensors for temperature, humidity, pressure, and light exposure alongside the identification function, enabling condition monitoring without separate sensor hardware. These smart tags are particularly valuable in pharmaceutical cold-chain, perishable food logistics, and precision industrial asset tracking applications.
Cloud-Based RFID Middleware and Analytics
Cloud-native RFID middleware platforms aggregate and process read events from distributed deployments, providing real-time dashboards, API integrations with ERP and WMS systems, and machine learning-driven analytics. Cloud deployment eliminates on-premises server requirements and enables scalable, multi-site visibility, accelerating enterprise RFID adoption.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Passive RFID | 72.6% | 2025 |
| Product | Tags | 58.7% | 2025 |
| Frequency | 🔒 | 🔒 | 2025 |
| End Use | 🔒 | 🔒 | 2025 |
| Region | North America | 28.7% | 2025 |

By Type
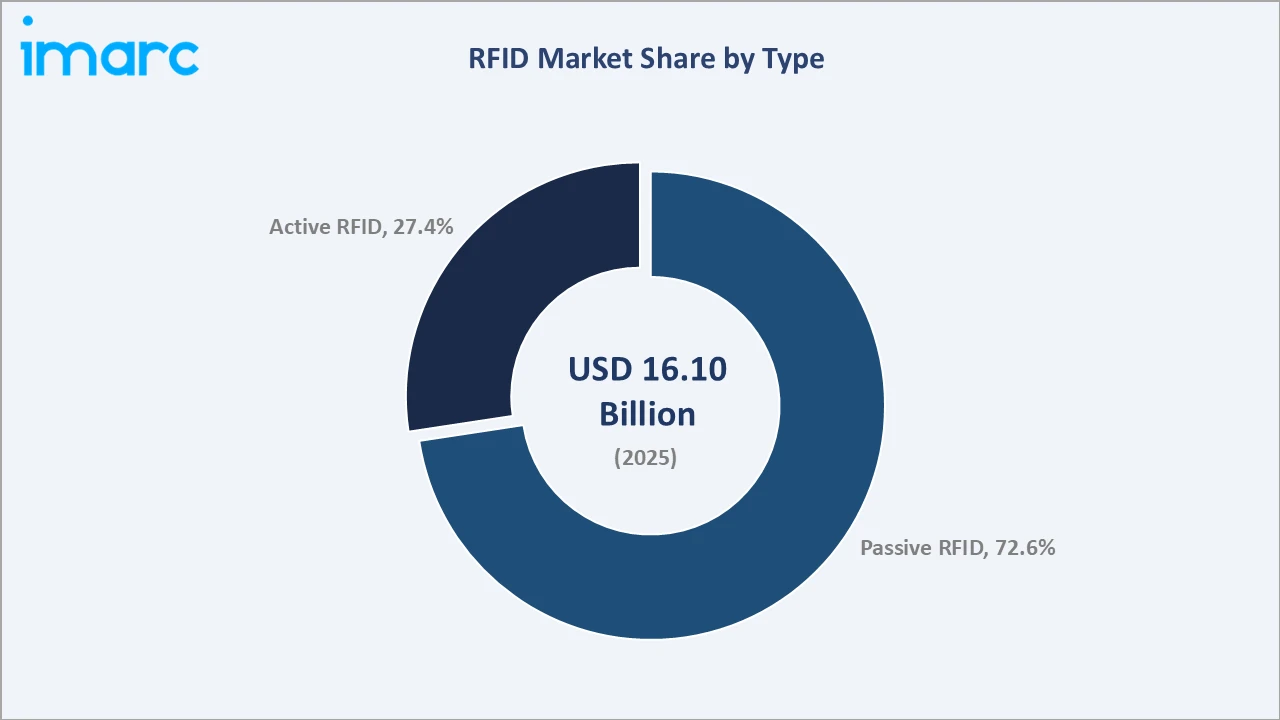
Passive RFID leads with a 72.6% share in 2025, driven by its significantly lower unit cost relative to active RFID, the absence of internal battery requirements, and its versatility across retail, logistics, pharmaceutical, and access control applications.
To access detailed market analysis, Request Sample
Active RFID, at 27.4%, holds a meaningful position in applications requiring longer read ranges, real-time location tracking, or operation in challenging RF environments. Active tags with embedded batteries support high ranges and are deployed in vehicle tracking, mining asset monitoring, and large-area logistics facilities.
By Product
Tags dominate with a 58.7% share in 2025, reflecting the fundamental role of the tag as the data-carrying element in every RFID deployment. Demand is driven by the rapid growth of item-level tagging in apparel, where major retailers require billions of individual tags, and by pharmaceutical serialization programs mandating unique RFID identification on individual drug packages.
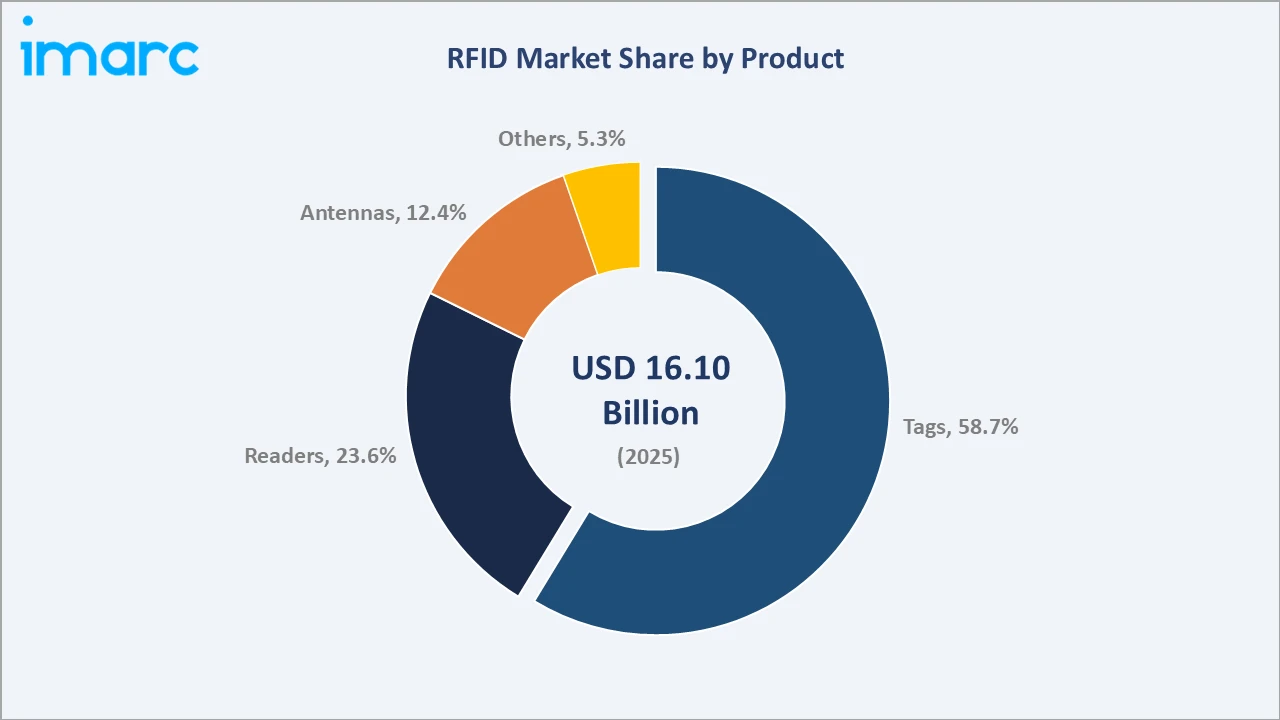
Readers at 23.6% are supported by expanding fixed reader deployments at retail checkouts, warehouse docks, and manufacturing lines, as well as growing adoption of handheld readers for stocktaking and inventory verification. Antennas at 12.4% grow in proportion with reader deployments, as each installation typically requires multiple antennas for comprehensive coverage. Others at 5.3% include cables, connectors, power-over-Ethernet components, and RFID middleware software.
Regional Market Insights
|
Region |
Share (2025) |
Key RFID Market Drivers & Characteristics |
|
North America |
28.7% |
Reflecting advanced logistics and retail infrastructure, strong enterprise IT budgets, and established regulatory frameworks for pharmaceutical serialization and food safety traceability. |
|
Asia Pacific |
28.1% |
Reflecting rapid manufacturing expansion, accelerating retail modernization, and growing government-backed digitalization programs in China, Japan, India, and South Korea. |
|
Europe |
24.6% |
Reflecting mature retail and manufacturing adoption, driven by supply chain transparency regulations and strong demand in automotive and pharmaceutical traceability applications. |
|
Latin America |
9.7% |
Reflecting growing adoption in retail and logistics modernization, supported by increasing foreign investment in supply chain digitalization and expanding domestic manufacturing activity. |
|
Middle East |
5.1% |
Reflecting adoption in government smart city initiatives, asset tracking in oil and gas, and growing retail and logistics infrastructure investment. |
|
Africa |
3.8% |
Reflecting early-stage adoption in agricultural traceability, retail modernization, and government identity management programs, with growth supported by increasing mobile infrastructure investment. |
The North American region held the largest share of the RFID market at 28.7% in 2025, supported by advanced logistics and retail infrastructure and strong enterprise adoption. Asia Pacific followed closely with a 28.1% share, driven by rapid manufacturing expansion, retail modernization, and government-led digitalization initiatives.
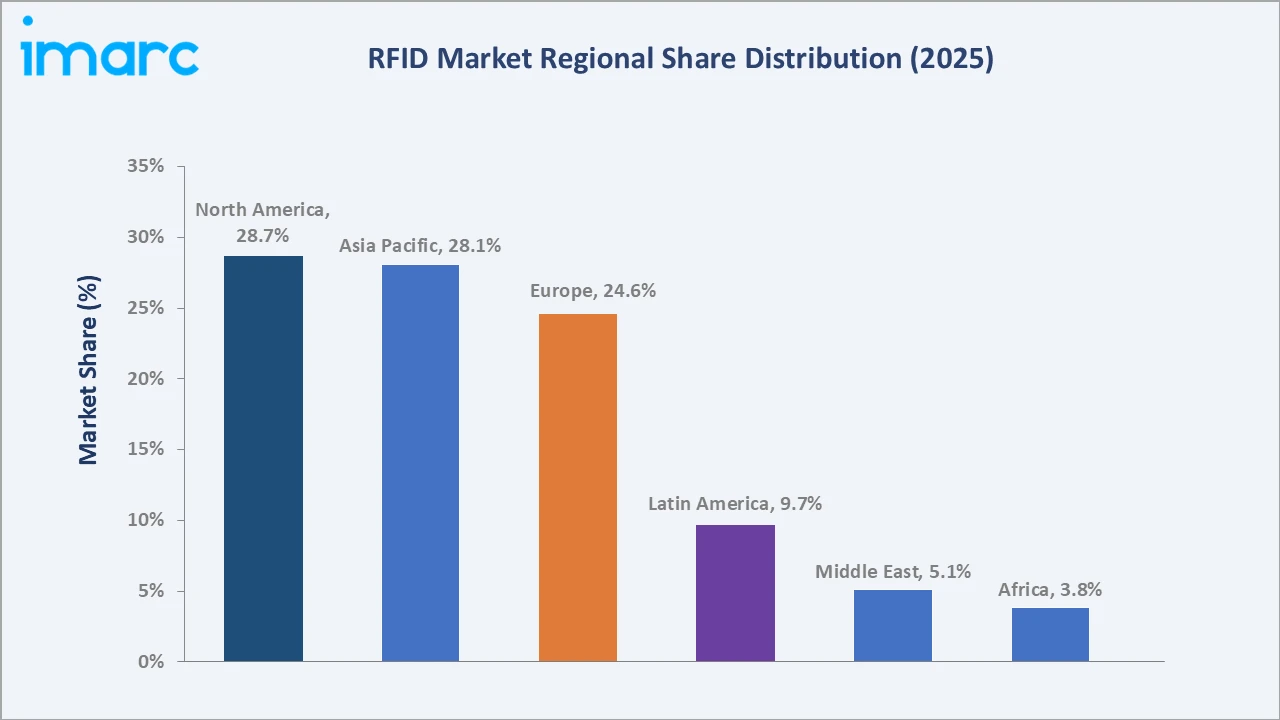
Europe accounted for 24.6%, reflecting mature adoption across retail and manufacturing and increasing demand for traceability solutions. Latin America represented 9.7%, supported by supply chain digitalization, foreign investment, and expanding manufacturing activity. The Middle East held a 5.1% share, driven by smart city initiatives and growing investment in logistics and asset tracking. Africa, with a 3.8% share, remained an emerging market with increasing adoption across agriculture, retail, and government applications.
Competitive Landscape
The global RFID market is moderately concentrated at the technology and hardware layer, with a handful of integrated providers commanding significant shares across chip supply, hardware, and software. The broader market remains fragmented, with hundreds of regional systems integrators and tag converters serving localized demand.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| AVERY DENNISON CORPORATION | AD Pure Line, RAIN RFID (UHF) inlays, AD TexTrace | Market Leader | AVERY DENNISON CORPORATION is a global leader in RFID and digital identification solutions, transforming physical products into connected assets through embedded microchips and antennas. |
| Zebra Technologies Corp. | Handheld RFID Readers, RFID-Enabled Products, RFID Antennas | Market Leader | Zebra Technologies Corp. plays a leading, end-to-end role in radio frequency identification (RFID) by providing a complete hardware, software, and supplies stack designed to automate data capture, enhance real-time asset visibility, and streamline workflows across multiple industries. |
| Impinj, Inc. | Impinj RAIN RFID endpoint ICs, Impinj Reader ICs, Impinj RAIN RFID readers | Market Leader | Impinj, Inc. is a pioneer and leading global provider of RAIN RFID that connects everyday physical items to the Internet of Things (IoT). |
| NXP Semiconductors | UCODE RAIN RFID | Established Player | NXP Semiconductors is a major provider of RFID and NFC integrated circuits (ICs), powering supply chain, retail, automotive, and healthcare applications. |
| Honeywell International Inc | IH45 RFID Handheld Reader, IH40 RFID Handheld Reader, IP30 RFID Handheld Reader, IF2B Fixed RFID Reader | Established Player | Honeywell International Inc. provides RFID readers designed to track and manage inventory, assets, and workflows across logistics, manufacturing, retail, aerospace, and healthcare. |
Companies are increasingly focusing on cost-effective products, improved read accuracy, enhanced security, and compatibility with IoT and cloud-based platforms. Strategic partnerships, mergers, acquisitions, and investments in research and development are also shaping market competition.
Key Company Profiles
AVERY DENNISON CORPORATION
AVERY DENNISON CORPORATION is a materials science and manufacturing company with a significant presence in the RFID industry, primarily through its Intelligent Labels division. The company serves retail, healthcare, logistics, and industrial markets with an extensive portfolio of RFID inlays, labels, and digital identification solutions. Its global manufacturing footprint and digital service platforms support large-scale, omnichannel RFID deployments.
- Key Offerings: AD Pure Line, RAIN RFID (UHF) inlays, AD TexTrace.
- Strategic Focus: Expanding its intelligent labels and RFID capabilities through manufacturing capacity investment, digital services growth, and sustainability-aligned product innovation. It also emphasizes strategic partnerships with brand owners and retailers to drive item-level RFID adoption at scale.
Zebra Technologies Corp.
Zebra Technologies Corp. is an enterprise technology company providing hardware, software, and services for tracking, printing, and real-time visibility solutions. The company serves retail, manufacturing, transportation, logistics, and healthcare markets with an integrated RFID ecosystem spanning fixed readers, handheld mobile computers, RFID printers, and software platforms.
- Key Offerings: Handheld RFID Readers, RFID-Enabled Products, RFID Antennas.
- Strategic Focus: Broadening its enterprise mobility and RFID solutions through product innovation, software platform development, and expanding its services portfolio. It also emphasizes vertical-specific RFID solutions for retail inventory management, healthcare asset tracking, and manufacturing production visibility.
Market Concentration Analysis
The global RFID market exhibits moderate concentration at the technology and hardware layer, where a small number of chip manufacturers, reader suppliers, and integrated solutions providers hold disproportionate influence over industry standards, pricing, and technology direction. The top players benefit from significant intellectual property portfolios, established customer relationships with global enterprises, and scale-driven cost advantages that create high barriers to new entrants at the component and platform level.
The broader market, encompassing tag converters, regional systems integrators, and vertical-specific software providers, is significantly more fragmented, with hundreds of specialized participants serving niche geographies and application segments. This fragmentation at the services and integration layer creates ongoing consolidation opportunities as larger players seek to expand their full-stack capabilities and geographic reach, driving progressive market concentration over the forecast period through 2034.
Investment & Growth Opportunities
Highest Growth Segments
Tags grow at 13.1% CAGR, antennas at 13.5% CAGR, passive RFID grows at 11.5%, and readers record a 12.5% CAGR. Sensor-integrated smart tags represent the highest-value per-unit opportunity in pharmaceutical cold-chain and precision industrial monitoring.
Investment Themes
- Healthcare and Pharmaceutical RFID: Expanding pharmaceutical serialization regulations, hospital asset management programs, and patient safety initiatives are creating non-discretionary RFID demand with multi-year implementation cycles, offering stable, high-value growth for specialized healthcare RFID providers.
- Asia Pacific Expansion: Government-supported Industry 4.0 adoption, expanding organized retail, and growing cold-chain logistics in Asia Pacific represent the largest geographic growth opportunity, with market participants able to capture first-mover advantages in underpenetrated markets across Southeast Asia and India.
Future Market Outlook (2026-2034)
The global RFID market grew from USD 16.10 Billion in 2025 to USD 18.09 Billion in 2026 and is projected to reach USD 47.41 Billion by 2034, exhibiting a CAGR of 12.37% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 28.84 Billion by 2030, as item-level tagging mandates in apparel and pharmaceuticals reach broad implementation and IoT-integrated RFID deployments scale across manufacturing and logistics.
Three structural forces will define the RFID market through 2034. First, the convergence of RFID with IoT, cloud computing, and artificial intelligence will transform RFID from a point-in-time identification tool into a continuous, intelligent data platform, expanding the market's addressable use cases and increasing average deployment value. Second, expanding regulatory mandates for product traceability in pharmaceuticals, food, and electronics will create policy-backed demand that sustains growth independent of broader economic cycles. Third, the progressive reduction in passive RFID tag unit costs, driven by scale manufacturing and chip miniaturization, will enable RFID adoption in lower-value item categories and emerging market geographies, significantly expanding the total addressable market through 2034 and beyond.
Research Methodology
Primary Research
Primary research comprised structured interviews with RFID technology executives, supply chain managers, retail operations directors, healthcare IT leaders, and government procurement officials. These consultations validated market sizing, assessed regional demand dynamics, identified regulatory drivers, and provided insights into competitive positioning and technology adoption trajectories across the global RFID market.
Secondary Research
Secondary research drew on published data from industry associations, government trade statistics, company annual reports, investor presentations, standards body publications, and peer-reviewed research on RFID technology and market adoption. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical RFID market growth rates, tag volume shipment data, enterprise technology spending forecasts, regulatory mandate timelines, IoT adoption curves, and macroeconomic indicators including industrial production indices and retail sales growth across key geographic markets.
RFID Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Active RFID, Passive RFID |
| Products Covered | Tags, Readers, Antennas, Others |
| Frequencies Covered | Low Frequency, High Frequency, Ultra-High Frequency |
| End Uses Covered | Retail, Financial Services, Healthcare, Industrial, Transportation & Logistics, Government, Others |
| Regions Covered | North America, Asia Pacific, Europe, Latin America, Middle East, Africa |
| Countries Covered | United States, China, Japan, India, South Korea, Australia, Indonesia, Canada, Germany, France, United Kingdom, Italy, Spain, Brazil, Mexico |
| Companies Covered | AVERY DENNISON CORPORATION, Zebra Technologies Corp., Impinj, Inc., NXP Semiconductors, Honeywell International Inc, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the RFID market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the global RFID market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the RFID industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the RFID Market Report
The global RFID market reached USD 18.09 Billion in 2026, driven by growing enterprise adoption across retail, healthcare, and logistics sectors, and expanding regulatory requirements for product traceability.
The market is projected to grow at a CAGR of 12.37% during 2026-2034, supported by IoT integration, expanding item-level tagging, and cloud-based RFID platform adoption.
The market is projected to reach USD 47.41 Billion by 2034, driven by pharmaceutical serialization mandates, retail inventory automation, and expanding industrial IoT deployments.
Passive RFID holds the dominant share at 72.6% in 2025, due to lower cost and broad applicability across retail, logistics, and consumer goods tagging applications.
Tags lead with a 58.7% share in 2025, driven by high-volume item-level tagging requirements in apparel, pharmaceuticals, and food and beverage sectors globally.
North America leads with a 28.7% share in 2025, reflecting advanced enterprise RFID adoption in retail, logistics, and healthcare sectors.
Key players include AVERY DENNISON CORPORATION, Zebra Technologies Corp., Impinj, Inc., NXP Semiconductors, and Honeywell International Inc., among others.
The market is projected to reach approximately USD 28.84 Billion by 2030, driven by scaling item-level tagging and growing cloud-connected RFID platform deployments.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade