
Risk Management Market Size, Share, Trends and Forecast by Component, Deployment Mode, Enterprise Size, Industry Vertical and Region, 2026-2034
Risk Management Market Size, Share, Trends & Forecast (2026-2034)
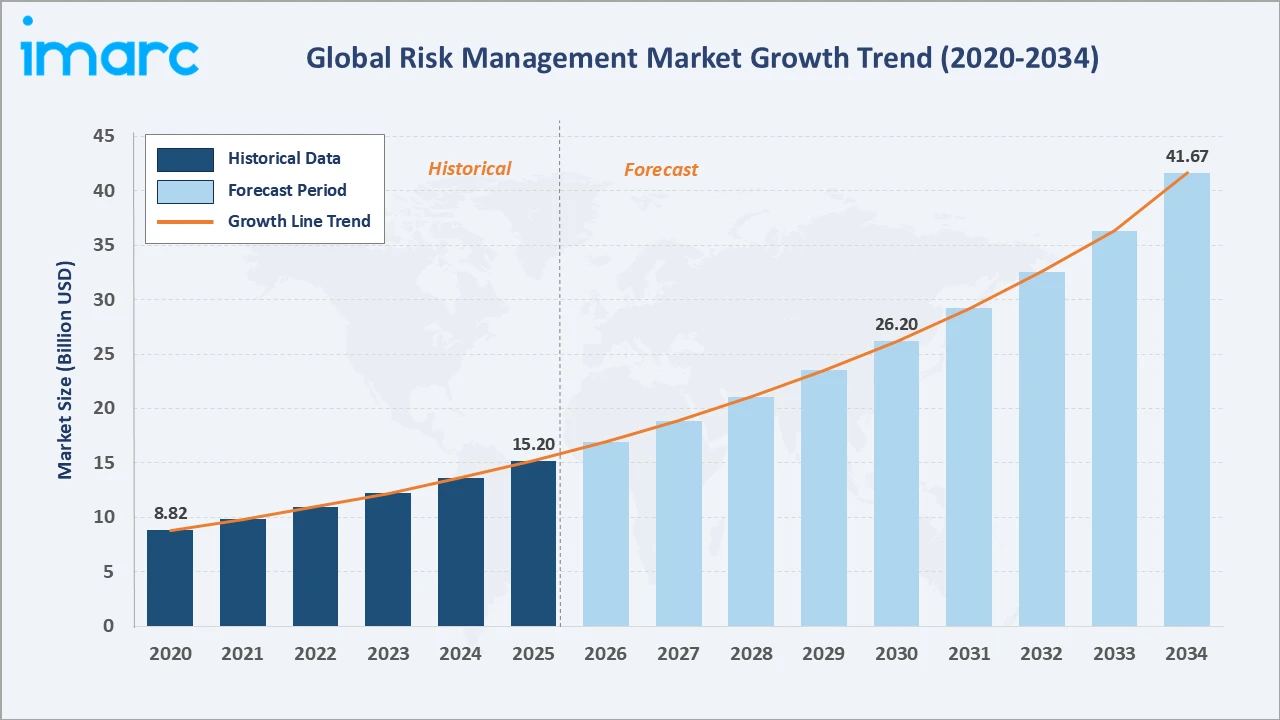
The global risk management market grew from USD 15.20 Billion in 2025 to USD 16.95 Billion in 2026 and is projected to reach USD 41.67 Billion by 2034, growing at a CAGR of 11.50% during 2026-2034, driven by rising regulatory requirements and cyber threat proliferation. Organizations across industries are increasingly prioritizing proactive risk identification and mitigation strategies to safeguard operational continuity, financial stability, and regulatory compliance in an evolving threat environment. The convergence of advanced analytics, automation, and integrated governance frameworks is reshaping how enterprises assess, monitor, and respond to risk—enabling more agile, data-driven decision-making across all functional levels of the organization.
Expanding digital transformation, cloud adoption, and growing enterprise risk awareness are further accelerating risk management market growth. Risk management market data confirms Software leads at 62.8%, On-Premises at 54.6%, and North America commands 36.4% of the global market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 15.20 Billion |
|
Market Size (2026) |
USD 16.95 Billion |
|
Forecast Market Size (2034) |
USD 41.67 Billion |
|
CAGR (2026-2034) |
11.50% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Component |
Software (62.8%, 2025) |
|
Dominant Deployment Mode |
On-Premises (54.6%, 2025) |
|
Leading Region |
North America (36.4%, 2025) |
The risk management market size expanded consistently from USD 8.82 Billion in 2020 to USD 15.20 Billion in 2025, with growth projected through USD 26.20 Billion in 2030 to USD 41.67 Billion by 2034. Risk management market outlook 2026 reflects robust demand momentum driven by digital risk proliferation. Escalating regulatory compliance mandates, rising cyber threat complexity, and rapid AI integration into enterprise risk platforms are primary drivers propelling sustained market expansion across financial services, healthcare, and technology sectors.
To get more information on this market, Request Sample
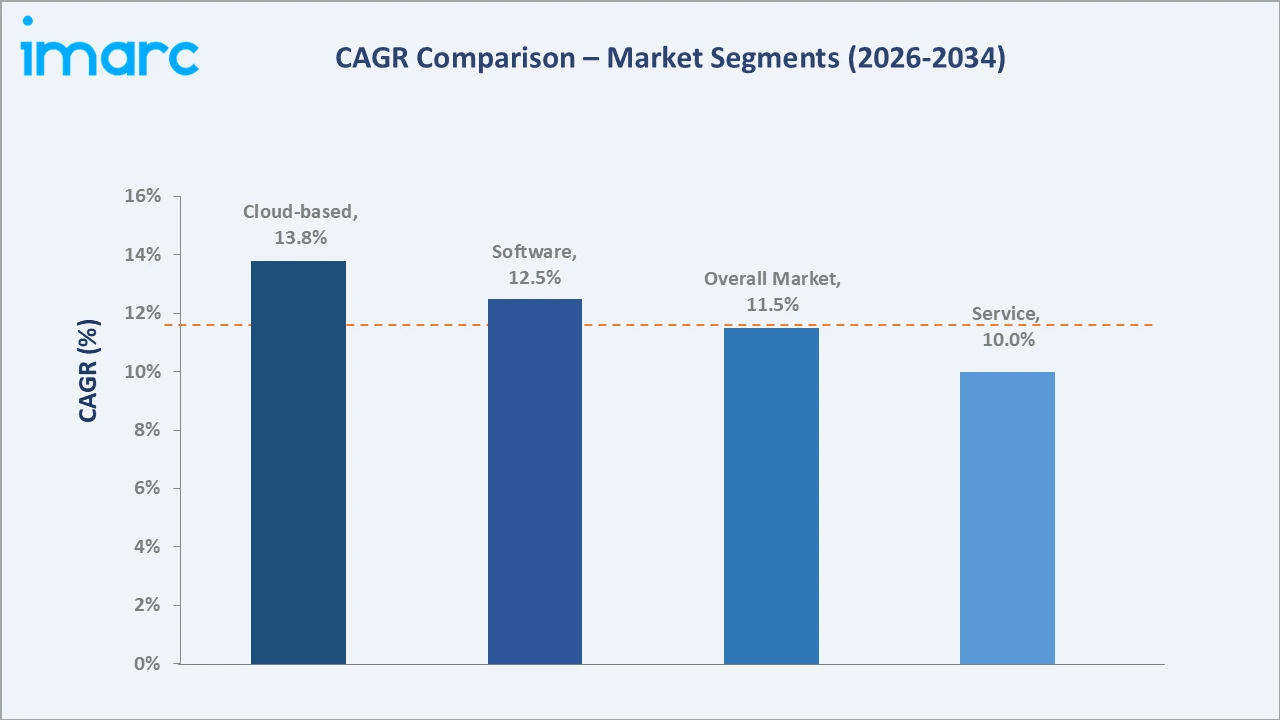
Risk management market research confirms Cloud-based solutions register the highest CAGR at 13.8%, followed by Software at 12.5%, reflecting strong risk management industry trends toward digital and cloud-native risk frameworks across enterprises globally.
Executive Summary
The global risk management market expanded from USD 15.20 Billion in 2025 to an estimated USD 16.95 Billion in 2026, establishing it as a high-priority technology investment vertical. Risk management market outlook 2026 reflects unprecedented demand across BFSI, healthcare, IT, and manufacturing sectors.
Tightening regulatory frameworks across major economies are compelling organizations to invest in structured, auditable risk management systems. The escalating frequency of cyber threats has elevated risk governance to a board-level strategic priority across all sectors. Rapid advancements in AI and machine learning are enabling predictive risk analytics, transforming how enterprises anticipate and respond to emerging exposures.
The market is underpinned by mounting regulatory obligations, escalating cyber threats, and the integration of AI-powered analytics into enterprise risk frameworks. Risk management market research indicates Software commanding 62.8% market share in 2025, reflecting broad platform adoption.
North America leads with 36.4% market share, supported by stringent compliance mandates and mature vendor ecosystems. The market is projected to reach USD 41.67 Billion by 2034, growing at 11.50% CAGR. On-Premises deployments retain 54.6% share while cloud adoption accelerates.
Key Market Insights
|
Insight |
Data |
|
Dominant Component |
Software – 62.8% share (2025) |
|
Dominant Deployment Mode |
On-Premises – 54.6% market share (2025) |
|
Leading Region |
North America – 36.4% share (2025) |
|
Market Opportunity |
AI/ML risk analytics integration; cloud-based RM for SMEs; ESG risk compliance; cybersecurity risk automation |
Key Analytical Observations Supporting the Above Risk Management Market Data:
- Software at 62.8%: Driven by regulatory mandates such as GDPR, SOX, and Basel III requiring comprehensive digital compliance platforms capable of real-time monitoring, automated reporting, and risk-score computation across enterprise operations.
- On-Premises at 54.6%: Industries handling sensitive data prefer on-premises deployments for greater security control, data sovereignty assurance, and customized infrastructure management compliant with sector-specific regulatory standards.
- North America at 36.4%: Driven by concentration of key vendors, robust regulatory environment, and strong enterprise adoption of integrated risk management platforms that automate compliance, cyber risk assessment, and operational risk workflows.
Risk Management Market Overview
The global risk management market is positioned at the intersection of regulatory compliance, digital transformation, and enterprise resilience strategy. Organizations across all sectors are adopting integrated platforms to identify, assess, and mitigate financial, operational, and cyber risks at scale.
Risk management industry trends include AI-driven risk scoring, cloud-native platform deployment, and enterprise-wide risk frameworks integrating operational, strategic, and compliance risk dimensions. Risk management market data confirms accelerating adoption among large enterprises and SMEs alike across North America, Europe, and Asia Pacific.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
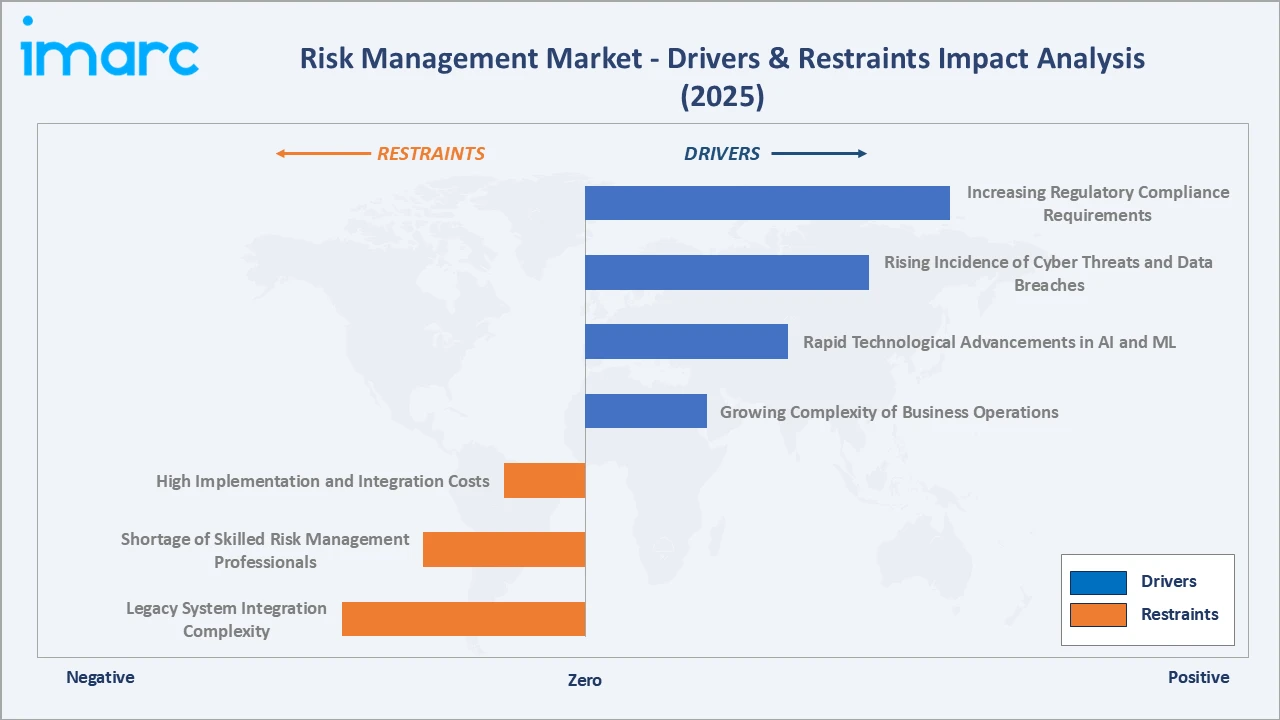
- Increasing Regulatory Compliance Requirements: Regulatory bodies across major economies continue to expand and tighten compliance frameworks governing how organizations identify, document, and report risk exposures. Enterprises operating in regulated industries are compelled to deploy structured risk management systems that ensure continuous compliance monitoring, audit-ready documentation, and timely regulatory reporting. The growing frequency of regulatory updates across financial, healthcare, and technology sectors further elevates the ongoing demand for adaptable, configurable risk management platforms capable of absorbing new compliance requirements as they emerge.
- Rising Incidence of Cyber Threats and Data Breaches: The rising sophistication and frequency of cyber incidents across industries have made cybersecurity risk management a board-level strategic imperative for organizations of all sizes. Enterprises are investing in dedicated cyber risk assessment tools that provide real-time threat monitoring, vulnerability scoring, and incident response planning capabilities. The expanding attack surface driven by digital transformation, remote work adoption, and cloud migration amplifies the need for integrated risk platforms that can quantify cyber exposure and align it with broader enterprise risk tolerance frameworks.
- Growing Complexity of Business Operations: Modern enterprises operate across increasingly complex ecosystems involving global supply chains, multi-jurisdictional regulatory environments, and interconnected third-party relationships. This operational complexity multiplies the volume and variety of risk exposures that organizations must monitor and manage simultaneously. Integrated risk management platforms that unify operational, financial, strategic, and compliance risk data into a single governance layer are becoming essential tools for leadership teams seeking to maintain visibility and control across all dimensions of enterprise risk.
- Rapid Technological Advancements in AI and ML: The integration of artificial intelligence and machine learning capabilities into risk management platforms is enabling a fundamental shift from reactive to predictive risk management. These technologies allow organizations to detect anomalies, forecast risk events, and automate risk-scoring processes with greater speed and accuracy than traditional methods permit. Continuous learning algorithms improve risk model performance over time, reducing false positives and enabling risk teams to prioritize resources toward the highest-impact exposures, thereby improving overall risk governance efficiency across the enterprise.
Market Restraints
- High Implementation and Integration Costs: Deploying a comprehensive risk management platform requires significant upfront capital investment covering software licensing, infrastructure provisioning, system customization, data migration, and ongoing maintenance. For many mid-sized and smaller organizations, these costs represent a meaningful financial barrier that delays or limits full-scale adoption. Budget constraints force some organizations to rely on partial implementations or manual processes, reducing the effectiveness of their risk management posture and creating gaps in governance coverage that expose them to unaddressed risk accumulation over time.
- Shortage of Skilled Risk Management Professionals: Effective deployment and operation of advanced risk management systems requires professionals with multidisciplinary expertise spanning data analytics, regulatory knowledge, technology integration, and enterprise governance frameworks. The availability of such qualified professionals remains limited relative to market demand, creating staffing challenges that slow platform adoption and reduce operational effectiveness after deployment. Organizations that lack sufficient internal expertise often face prolonged implementation cycles and reduced utilization of platform capabilities, limiting the return on their risk management technology investments.
- Legacy System Integration Complexity: A significant proportion of enterprises continue to rely on legacy information systems built on aging architectures that were not designed to interface with modern risk management platforms. Integrating contemporary risk tools with these environments requires extensive custom development, API bridging, and data transformation work that extends project timelines and inflates total implementation costs. The technical complexity and resource intensity of these integration efforts often deters organizations from pursuing full-scale modernization, resulting in siloed risk data and fragmented governance visibility that limits the strategic value of their risk management investments.
Market Opportunities
- Cloud-Based Solutions for SME Adoption: Small and medium enterprises represent a large and largely underserved segment of the global risk management market, as many have historically lacked access to affordable, easy-to-deploy risk management solutions. The proliferation of cloud-delivered, subscription-based risk platforms is lowering entry barriers and making enterprise-grade risk management accessible to organizations with constrained IT budgets. As awareness of risk management value grows among smaller enterprises, solution providers capable of offering scalable, configurable platforms tailored to SME needs are positioned to capture a substantial and rapidly expanding addressable market opportunity.
- ESG and Climate Risk Management Expansion: Growing stakeholder expectations and evolving regulatory requirements around Environmental, Social, and Governance performance are creating new demand for risk management capabilities that extend beyond traditional financial and operational domains. Organizations across industries are seeking platforms that can incorporate climate-related risk scenarios, social impact assessments, and governance compliance tracking into their enterprise risk frameworks. This integration creates meaningful expansion opportunities for risk management solution providers capable of delivering ESG risk quantification, scenario modeling, and disclosure-ready reporting as part of a unified platform.
Market Challenges
- Rapidly Evolving Risk Landscape: The risk environment facing organizations continues to evolve at an accelerating pace, driven by technological disruption, geopolitical instability, supply chain volatility, and the emergence of entirely new categories of risk. Maintaining risk frameworks that remain current, comprehensive, and actionable in the face of this constant change requires sustained investment in risk model refinement, regulatory monitoring, and platform capability enhancement. Organizations that fail to keep pace with an evolving risk landscape risk making governance decisions based on outdated assumptions, potentially exposing themselves to undetected accumulations of strategic or operational risk.
- Managing Cross-Jurisdictional Compliance Complexity: Enterprises with operations spanning multiple countries must simultaneously navigate a diverse and often conflicting set of regulatory obligations governing risk disclosure, data handling, financial reporting, and operational governance. Building a unified risk management platform capable of accommodating jurisdiction-specific requirements while maintaining a consistent enterprise-wide governance framework presents considerable technical and organizational complexity. The ongoing evolution of local regulations across key markets further compounds this challenge, requiring organizations to continuously update their compliance configurations and risk reporting processes to avoid exposure to regulatory penalties and reputational risk.
Emerging Market Trends
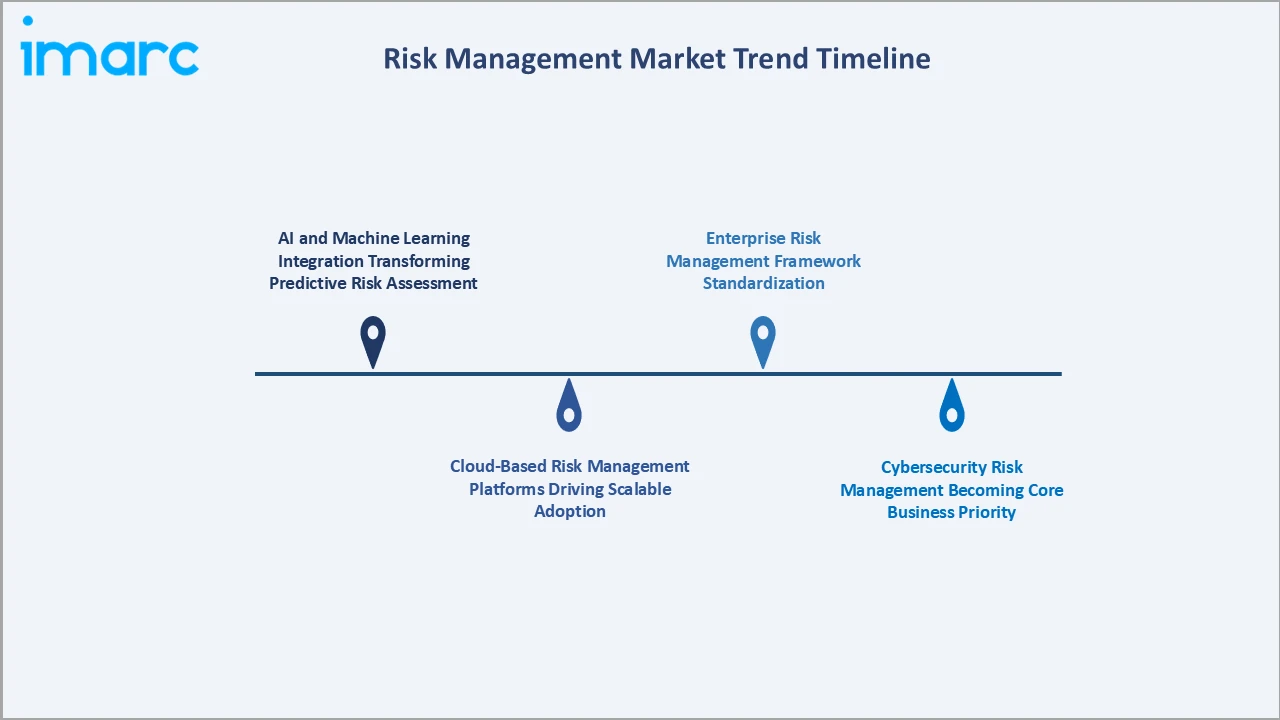
1. AI and Machine Learning Integration Transforming Predictive Risk Assessment
The integration of artificial intelligence and machine learning into enterprise risk management platforms is reshaping how organizations identify, evaluate, and respond to risk exposures across all business functions. These technologies enable continuous analysis of structured and unstructured data streams, allowing risk teams to detect early warning signals and emerging risk patterns that traditional rule-based systems would miss. Predictive risk scoring models built on machine learning algorithms improve in accuracy over time as they process more organizational and market data, enabling risk functions to shift from periodic reporting cycles to real-time, always-on risk intelligence that supports faster and more informed decision-making at the enterprise level.
2. Cloud-Based Risk Management Platforms Driving Scalable Adoption
Cloud-native deployment has emerged as the dominant model for organizations seeking to modernize their risk management infrastructure without incurring the capital expenditure and maintenance burden associated with traditional on-premises installations. Cloud-based platforms offer elastic scalability, allowing organizations to expand their risk management capabilities in line with business growth without significant incremental IT investment. The subscription-based pricing models common to cloud platforms also lower barriers to adoption for mid-sized organizations, while centralized updates ensure that all users benefit from the latest risk models, compliance frameworks, and security enhancements without requiring manual patch management or system downtime.
3. Enterprise Risk Management Framework Standardization
Organizations across industries are moving away from siloed, function-specific risk management approaches toward integrated enterprise risk management frameworks that provide a unified view of risk exposure across operational, financial, strategic, and compliance dimensions. Standardized ERM frameworks establish common risk taxonomies, assessment methodologies, and reporting structures that enable consistent risk communication from front-line business units to executive leadership and board-level governance bodies. This consolidation improves the quality and comparability of risk information, supports more effective capital allocation and risk prioritization decisions, and strengthens the overall governance posture of the enterprise in the eyes of regulators and investors.
4. Cybersecurity Risk Management Becoming Core Business Priority
Cybersecurity risk has evolved from a narrowly defined technical concern into a strategic business risk that demands attention and investment at the highest organizational levels. Enterprises are increasingly embedding cyber risk quantification methodologies into their broader enterprise risk frameworks, enabling leadership teams to assess the potential financial and reputational impact of cyber incidents alongside other categories of business risk. This integration facilitates more rational resource allocation toward cyber resilience capabilities, supports insurance and risk transfer decisions, and enables organizations to communicate cyber risk exposure to boards, investors, and regulators in business-relevant terms that drive accountability and action.
Industry Value Chain Analysis
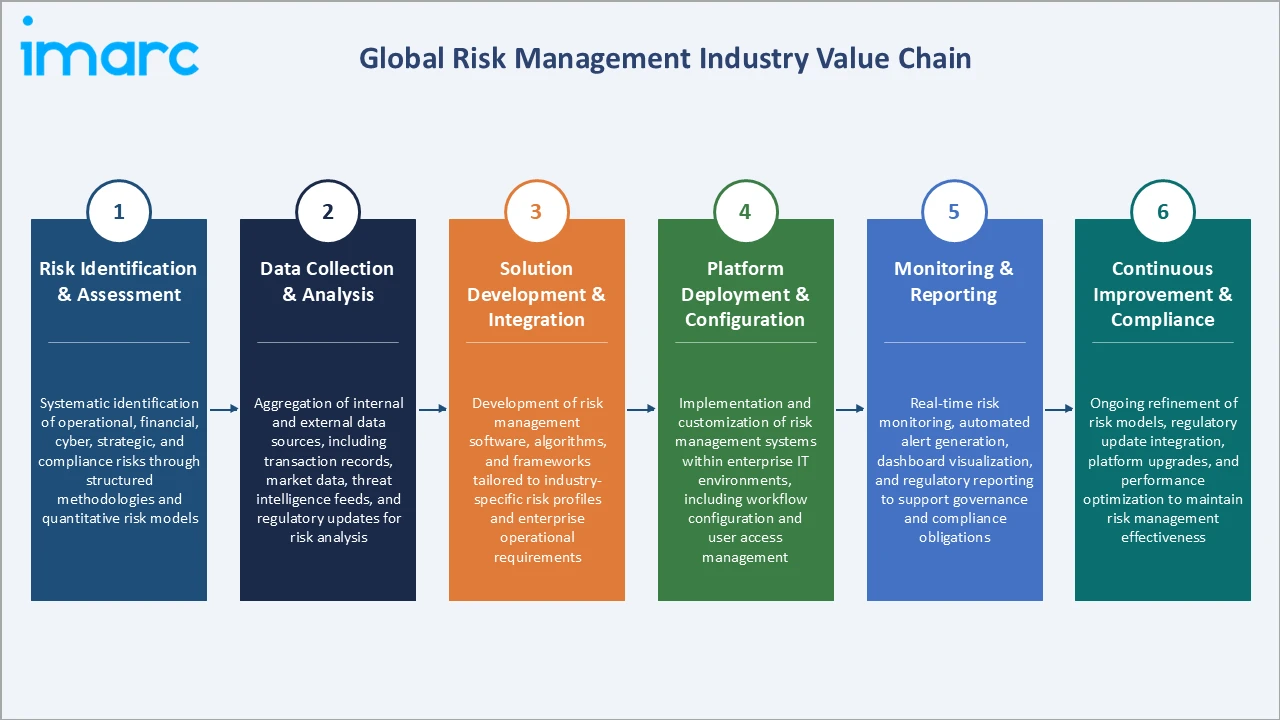
The risk management industry value chain encompasses six core stages, from initial risk identification through continuous improvement. Each stage creates incremental value through specialized processes, technologies, and services that collectively deliver comprehensive enterprise risk management capabilities.
|
Stage |
Key Activities |
|
Risk Identification & Assessment |
Systematic identification of operational, financial, cyber, strategic, and compliance risks through structured methodologies and quantitative risk models |
|
Data Collection & Analysis |
Aggregation of internal and external data sources, including transaction records, market data, threat intelligence feeds, and regulatory updates for risk analysis |
|
Solution Development & Integration |
Development of risk management software, algorithms, and frameworks tailored to industry-specific risk profiles and enterprise operational requirements |
|
Platform Deployment & Configuration |
Implementation and customization of risk management systems within enterprise IT environments, including workflow configuration and user access management |
|
Monitoring & Reporting |
Real-time risk monitoring, automated alert generation, dashboard visualization, and regulatory reporting to support governance and compliance obligations |
|
Continuous Improvement & Compliance |
Ongoing refinement of risk models, regulatory update integration, platform upgrades, and performance optimization to maintain risk management effectiveness |
The solution development and integration stage represents the highest value-added component of the risk management value chain. Vendors in this stage invest heavily in R&D, regulatory expertise, and technology innovation to develop differentiated platforms that address complex enterprise risk management requirements across multiple sectors.
Technology Landscape in the Risk Management Industry
Artificial Intelligence and Machine Learning Platforms
AI and ML platforms are revolutionizing risk detection, assessment, and mitigation capabilities. Predictive algorithms analyze historical risk patterns and real-time data to forecast potential risk events, enabling proactive intervention. These technologies are driving adoption of next-generation risk management software across financial services, healthcare, and manufacturing sectors with measurable ROI improvements.
Cloud-Native Risk Management Architecture
Cloud-native architectures enable scalable, resilient risk management deployments with reduced infrastructure costs. Microservices-based platforms offer flexible risk module deployment, API integration capabilities, and continuous update delivery, supporting rapid adaptation to evolving regulatory requirements and risk environments.
Big Data Analytics and Real-Time Processing
Big data platforms enable processing of large-scale structured and unstructured data streams for comprehensive risk intelligence. Real-time analytics capabilities provide instant risk visibility across enterprise operations, supply chains, and financial portfolios, enabling immediate response to emerging risk indicators.
Blockchain and Distributed Ledger Technology
Blockchain technology is being integrated into risk management platforms to enhance audit trail integrity, transaction transparency, and data immutability. These capabilities are particularly valuable in financial risk management, compliance verification, and supply chain risk monitoring applications.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Component | Software | 62.8% | 2025 |
| Deployment Mode | On-Premises | 54.6% | 2025 |
| Enterprise Size | Large Enterprise | 🔒 | 2025 |
| Industry Vertical | BFSI | 🔒 | 2025 |
| Region | North America | 36.4% | 2025 |

By Component
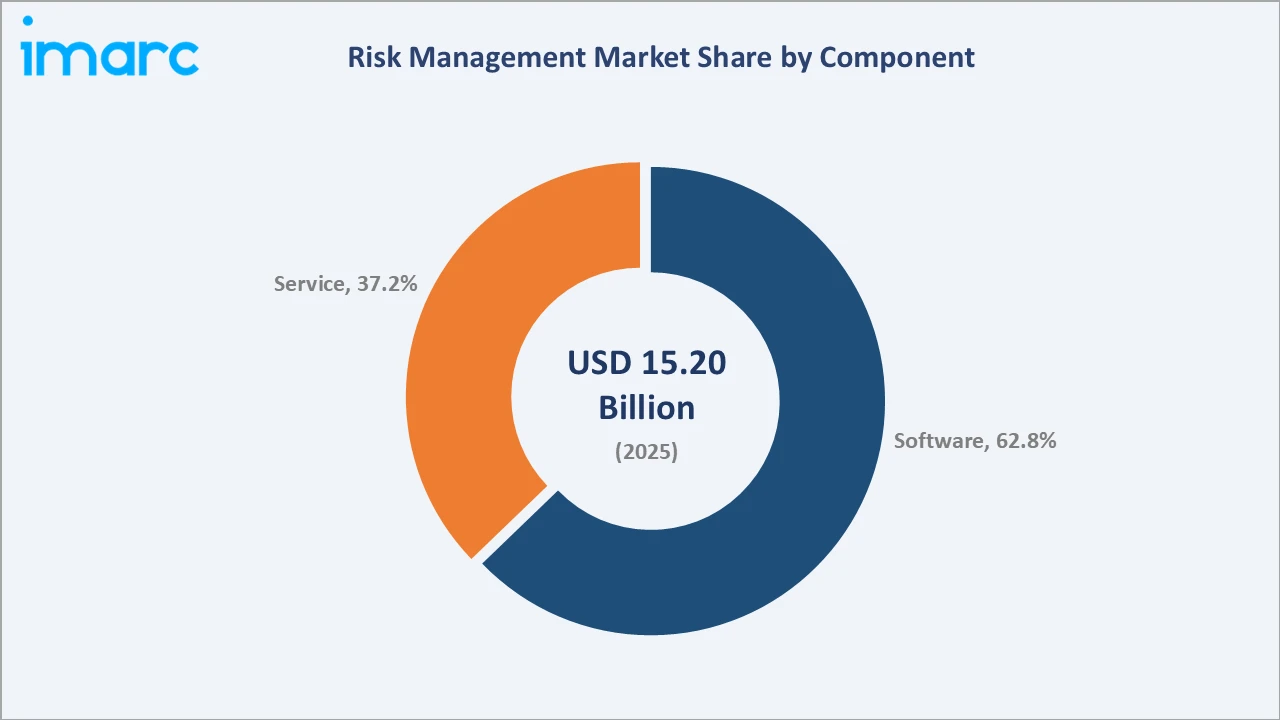
The Software sub-segment accounts for 62.8% of the risk management market in 2025 and is projected to grow at a CAGR of 12.5% during 2026-2034, driven by enterprise demand for integrated platforms that automate compliance monitoring, cyber risk assessment, and operational risk reporting. The increasing volume and complexity of regulatory requirements across industries is accelerating software adoption as organizations seek scalable, configurable solutions capable of managing multiple risk domains within a unified governance architecture.
To access detailed market analysis, Request Sample
The Service sub-segment holds 37.2% market share in 2025 and is expected to expand at a CAGR of 10.0% through 2034, encompassing consulting, implementation, training, and managed risk services. Growth is driven by organizations outsourcing risk management functions to specialized providers who deliver domain expertise, regulatory knowledge, and operational efficiency improvements. Demand for managed services is particularly strong among mid-sized enterprises that lack the internal capacity to deploy and maintain comprehensive risk management capabilities independently.
By Deployment Mode
On-Premises deployments account for 54.6% of the risk management market in 2025 and are projected to grow at a CAGR of 9.5% during 2026-2034, favored by highly regulated industries including BFSI, healthcare, and government that prioritize data sovereignty, security control, and customized compliance configurations. Organizations in sectors with strict data residency obligations continue to prefer on-premises architectures as they provide greater control over sensitive risk data and allow tailored integration with legacy enterprise systems and sector-specific regulatory reporting requirements.
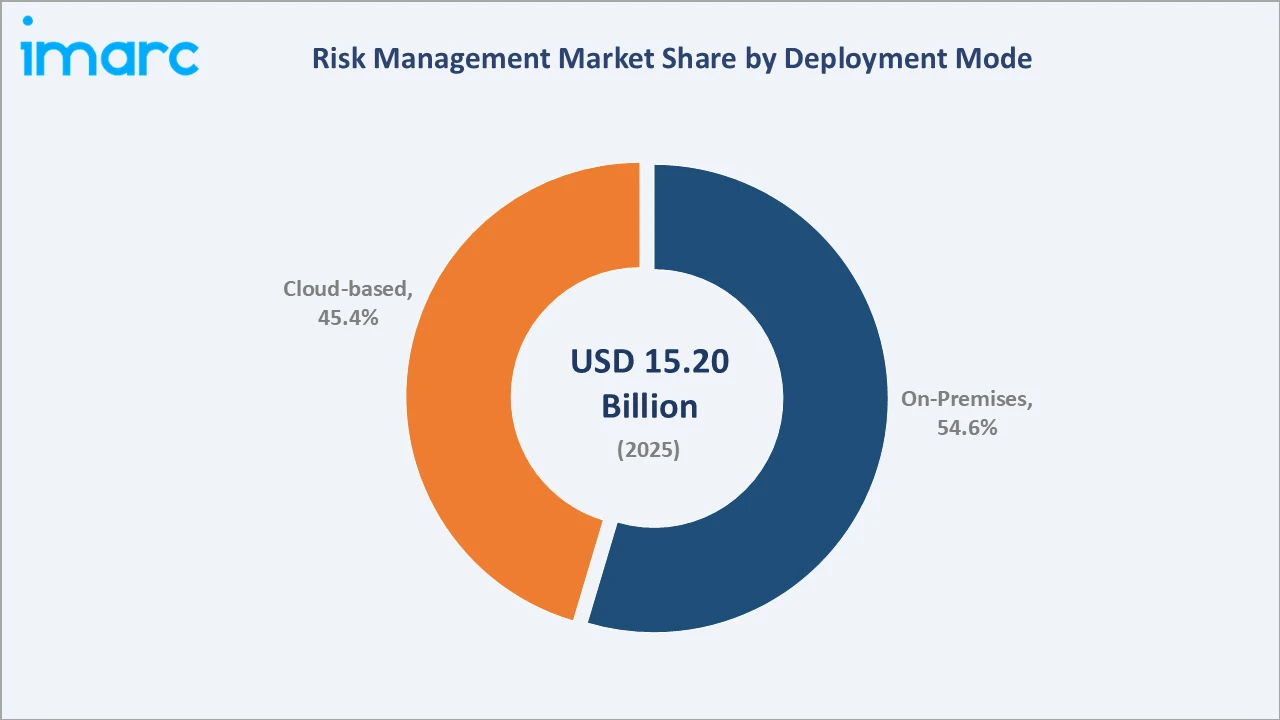
Cloud-based deployments hold 45.4% market share in 2025 and represent the fastest-growing sub-segment, expanding at a CAGR of 13.8% during 2026-2034. Scalability, cost-efficiency, and remote accessibility advantages are accelerating cloud adoption, particularly among mid-sized enterprises seeking rapid deployment without significant infrastructure investment. The shift toward subscription-based pricing models and the availability of pre-configured compliance modules are further lowering barriers to cloud-based risk management adoption across diverse industry verticals globally.
Regional Market Insights
|
Region |
Share (2025) |
Key Risk Management Market Drivers & Characteristics |
|
North America |
36.4% |
Largest market driven by robust regulatory environment, high technology adoption, and concentration of leading risk management solution vendors |
|
Europe |
27.3% |
Strong demand driven by GDPR compliance requirements, financial sector risk management mandates, and enterprise digital transformation initiatives |
|
Asia Pacific |
23.6% |
Fastest-growing region as digital infrastructure expansion, rising cyber threats, and increasing regulatory awareness accelerate platform adoption |
|
Latin America |
7.4% |
Growing market supported by expanding financial sector regulation, increasing corporate governance requirements, and digital transformation adoption |
|
Middle East & Africa |
5.3% |
Emerging market with growing adoption driven by Vision 2030 initiatives, financial sector development, and increasing cybersecurity risk awareness |
North America leads with 36.4% share, supported by a stringent regulatory environment and high enterprise adoption of integrated risk management platforms. Europe holds 27.3% share, driven by data protection mandates and strong financial sector compliance requirements across the United Kingdom, Germany, and France.
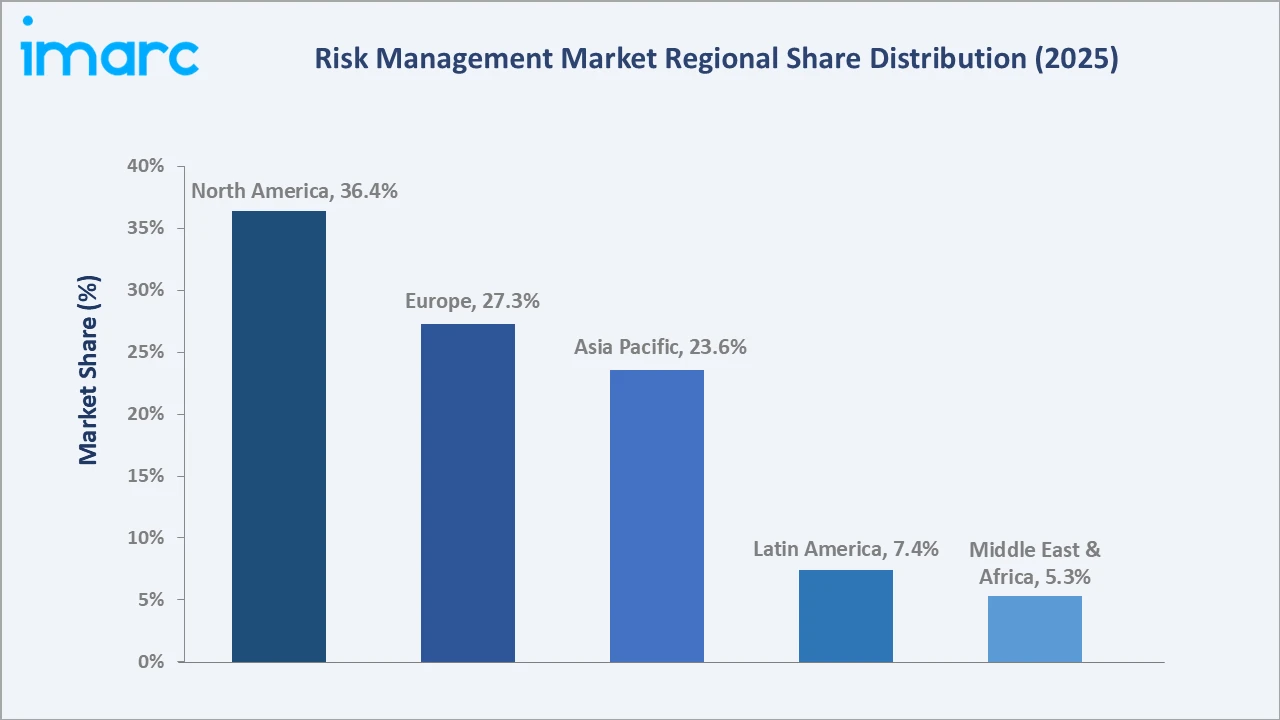
Asia Pacific accounts for 23.6% share and registers the fastest regional growth, fueled by digital infrastructure expansion, rising cyber incidents, and evolving regulatory frameworks. Latin America holds 7.4% share, while Middle East and Africa accounts for 5.3%, both driven by financial sector development, digitalization programs, and increasing cybersecurity risk awareness.
Competitive Landscape
The global risk management market features a highly competitive landscape with established technology conglomerates, specialized risk management software vendors, and emerging AI-native platforms. Key risk management companies are investing in platform integration, AI capabilities, and regulatory compliance updates.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| International Business Machines Corporation | IBM OpenPages, AI-powered GRC platforms | Market Leader | End-to-end GRC platform with deep AI integration, regulatory mapping, and enterprise-scale deployment capabilities |
| Oracle Corporation | Oracle Risk Management Cloud, Financial Services Risk | Market Leader | Comprehensive cloud-native risk and compliance platform integrated with ERP and financial management systems |
| SAP SE | SAP GRC Suite, SAP Risk Management | Market Leader | Integrated risk management embedded within enterprise ERP, enabling unified risk visibility across business processes |
| ServiceNow | ServiceNow GRC, IT Risk Management | Strong Challenger | Workflow-driven risk management platform with strong IT governance integration and process automation capabilities |
| Thomson Reuters Corporation | Risk & Compliance Platform, Regulatory Intelligence | Strong Challenger | Deep regulatory intelligence and compliance content embedded in risk management workflow platforms |
Key players in the risk management market are actively developing AI-driven risk analytics capabilities, expanding cloud-native platform offerings, and forging strategic partnerships to address evolving enterprise risk management requirements across financial services, healthcare, and technology sectors.
Key Company Profiles
International Business Machines Corporation
International Business Machines Corporation is a global technology and consulting enterprise with a comprehensive portfolio of risk management and governance, risk, and compliance (GRC) solutions. The company serves large enterprises across financial services, healthcare, and government sectors.
- Key Offerings: IBM OpenPages GRC Platform, IBM Financial Crimes Insight, AI-powered risk analytics, regulatory change management, and enterprise risk reporting solutions.
- Recent Developments: In October 21, 2026, International Business Machines Corporation (IBM) announced the release of OpenPages 9.2.2, introducing AI-powered recommendations, expanded document analysis, and enhanced workflow automation to help organizations improve risk identification, assessment, and compliance management. The update enables risk teams to connect related risks, controls, issues, and audit records while automating routine governance processes. These enhancements support informed risk-based decisions, strengthen oversight, and improve operational efficiency across enterprise risk management activities.
- Strategic Focus: International Business Machines Corporation focuses on deepening AI integration within its GRC platform ecosystem, expanding cloud-native risk management offerings, and strengthening regulatory compliance content libraries to maintain leadership across enterprise risk management verticals.
Oracle Corporation
Oracle Corporation is a leading global technology company providing cloud-based enterprise risk management and financial compliance solutions. Its integrated risk management platform serves financial services, manufacturing, healthcare, and public sector organizations worldwide.
- Key Offerings: Oracle Risk Management Cloud, Oracle Financial Services Analytical Applications, GRC platform, compliance management, and financial crime and compliance management solutions.
- Key Developments: On September 29, 2026, Oracle Corporation announced the availability of Oracle Nexus Case Flow and Oracle Nexus Reach, introducing agentic AI capabilities to its financial crime and compliance management portfolio. The solutions help financial institutions streamline investigations by gathering relevant evidence, identifying suspicious activities, analyzing adverse media, and generating investigation narratives. With human oversight integrated into investigative workflows, these capabilities aim to improve risk identification, reduce false positives, strengthen compliance controls, and help financial institutions manage financial crime risks more efficiently.
- Strategic Focus: Oracle Corporation prioritizes cloud-first risk management platform expansion, embedding advanced analytics and AI capabilities into its enterprise applications suite, enabling seamless risk management integration across ERP, finance, and supply chain management functions.
SAP SE
SAP SE is a global enterprise software leader offering integrated risk management and GRC solutions embedded within its comprehensive ERP ecosystem. SAP serves large enterprises across manufacturing, financial services, retail, and public sector verticals with end-to-end risk management capabilities.
- Key Offerings: SAP GRC Suite, SAP Risk Management, SAP Audit Management, SAP Process Control, SAP Business Integrity Screening, and integrated compliance management modules.
- Recent Developments: On October 6, 2026, SAP SE announced a new partnership with Moody’s Corporation to integrate supplier risk monitoring intelligence into SAP Ariba Supplier Lifecycle and Performance. The integration is designed to provide procurement teams with continuously updated insights into suppliers’ financial health, operational risks, and regulatory status directly within procurement workflows. By enabling earlier identification of potential supplier disruptions and supporting proactive risk mitigation, the collaboration aims to strengthen supply chain resilience, improve procurement decisions, and enhance enterprise risk management.
- Strategic Focus: SAP SE focuses on embedding risk management capabilities natively within its core ERP and cloud platform ecosystem, enabling organizations to achieve unified risk visibility across all business processes and regulatory compliance domains without additional third-party integration requirements.
Market Concentration Analysis
The global risk management market exhibits moderate-to-high concentration at the enterprise segment level, with established technology conglomerates maintaining competitive advantages through integrated platform ecosystems, deep regulatory compliance content libraries, and long-term enterprise relationships.
Market concentration is evolving through dual forces of consolidation and fragmentation. Strategic acquisitions are enabling established vendors to expand capabilities, while AI-native startups and specialized GRC platforms are creating competitive fragmentation in niche risk management categories and emerging market segments.
Investment & Growth Opportunities
Highest Growth Segments
Cloud-based risk management solutions growing at 13.8% CAGR and AI-powered risk analytics expanding at 12.5%+ CAGR represent the highest-growth investment segments through 2034. Cybersecurity risk management platforms are attracting substantial capital as enterprises prioritize real-time threat monitoring and cyber risk quantification capabilities. ESG risk management frameworks are emerging as a rapidly expanding category, driven by regulatory disclosure mandates and investor-driven sustainability reporting requirements. SME-targeted risk management applications represent a largely underpenetrated segment with considerable addressable market potential as awareness and affordability of risk solutions improve across smaller enterprises.
Emerging Investment Opportunities
AI-native risk management platforms delivering autonomous risk detection, quantification, and mitigation capabilities represent the most commercially dynamic emerging investment opportunity in the market. The integration of generative AI into regulatory compliance and audit management is creating significant new revenue streams for solution providers capable of automating complex, high-frequency compliance tasks. Embedded risk management capabilities within enterprise workflow platforms are gaining investor attention as organizations seek seamlessly integrated risk intelligence rather than standalone point solutions. Cross-border risk management solutions addressing multi-jurisdictional compliance complexity are also attracting investment as globally operating enterprises require unified governance platforms.
Investment Themes
- Cloud and SaaS Risk Platform Investment: Cloud-native risk management platform investment targeting SMEs and mid-market enterprises seeking affordable, scalable solutions without significant infrastructure investment requirements presents the largest addressable market expansion opportunity through 2034. Subscription-based models lower adoption barriers and accelerate market penetration across diverse industry verticals globally.
- AI-Powered Risk Analytics: AI and ML risk analytics investment enabling predictive risk modeling, automated regulatory change management, and real-time cyber risk quantification creates high-value differentiation opportunities for platform vendors targeting large enterprise and financial services clients. Continuous learning models that improve risk accuracy over time represent a compelling long-term competitive advantage and a strong driver of enterprise platform stickiness and recurring revenue growth.
Future Market Outlook (2026-2034)
The global risk management market is projected to grow from USD 15.20 Billion in 2025 to USD 16.95 Billion in 2026, reaching USD 26.20 Billion by 2030 and USD 41.67 Billion by 2034, registering a CAGR of 11.50% during 2026-2034. Risk management market outlook 2026 confirms strong structural growth drivers.
Three structural forces define market growth through 2034 accelerating regulatory complexity requiring continuous compliance platform evolution; AI and automation integration enabling next-generation risk intelligence; and expanding cloud adoption democratizing risk management capabilities across enterprise sizes.
The market anchor value of USD 26.20 Billion in 2030 represents a structural inflection driven by widespread cloud-native platform adoption, AI-powered risk automation maturation, and ESG risk management becoming a regulatory and investor-mandated enterprise priority across all major global markets.
Research Methodology
Primary Research
Primary research comprised structured interviews with risk management industry stakeholders, including Chief Risk Officers, GRC platform implementation directors, compliance technology managers, and enterprise risk consultants across North America, Europe, Asia Pacific, and emerging markets.
Secondary Research
Secondary research encompassed company annual reports, regulatory body publications, industry association reports, technology analyst publications, patent databases, and risk management software vendor investor presentations. Over 60 secondary sources were reviewed across all market segments.
Forecasting Models
Market revenue forecasts were developed using a bottom-up segmentation model aggregating platform adoption rates by enterprise size, industry vertical, and geographic region. AI adoption multipliers and regulatory compliance investment indices were applied to refine segment-level growth projections through 2034.
Risk Management Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Software, Service |
| Deployment Modes Covered | On-premises, Cloud-based |
| Enterprise Sizes Covered | Large Enterprises, Small and Medium-sized Enterprises |
| Industry Verticals Covered | BFSI, IT and Telecom, Retail, Healthcare, Energy and Utilities, Manufacturing, Government and Defense, Others |
| Regions Covered | North America, Asia Pacific, Europe, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | International Business Machines Corporation, Oracle Corporation, SAP SE, ServiceNow, Thomson Reuters Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the risk management market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the global risk management market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the risk management industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Risk Management Market Report
The risk management market size reached USD 15.20 Billion in 2025, driven by regulatory compliance requirements, cyber threat proliferation, and enterprise digital transformation initiatives.
The market grows at 11.50% CAGR during 2026-2034, projected to reach USD 41.67 Billion by 2034 from USD 16.95 Billion in 2026.
Software leads at 62.8% (2025) through enterprise demand for integrated platforms automating compliance monitoring, cyber risk assessment, and reporting.
On-Premises leads at 54.6% (2025) driven by data sovereignty requirements, security control preferences, and regulatory mandates in financial services and healthcare.
North America leads at 36.4% (2025) through stringent regulatory frameworks, high technology adoption rates, and concentration of leading solution providers.
Leading companies include International Business Machines Corporation, Oracle Corporation, SAP SE, ServiceNow, and Thomson Reuters Corporation, among others.
The market is projected to reach approximately USD 26.20 Billion by 2030, driven by cloud-native platform adoption, AI integration, and expanding regulatory compliance requirements.
Key trends include AI-driven predictive risk analytics, cloud-based GRC platform adoption, ESG risk integration, cybersecurity risk management prioritization, and ERM framework standardization.
Cloud-native SME-focused platforms, AI-powered risk analytics, ESG risk compliance solutions, and cybersecurity risk quantification tools represent the highest-ROI investment opportunities.
Risk management market outlook 2026 is driven by escalating cyber threats, tightening regulatory mandates, AI platform maturation, and increased board-level risk governance prioritization.
Risk management market research covers Component, Deployment Mode, Enterprise Size, and Industry Vertical segments across North America, Europe, Asia Pacific, Latin America, and Middle East and Africa.
Cloud-based deployment grows at 13.8% CAGR, the fastest segment, driven by scalability, cost efficiency, and rapid implementation advantages over on-premises alternatives.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade