Saudi Arabia Battery Recycling Market Size, Share, Trends and Forecast by Type, Source, Material, End-Use, and Region, 2026-2034
Saudi Arabia Battery Recycling Market Size, Share, Trends & Forecast (2026-2034)
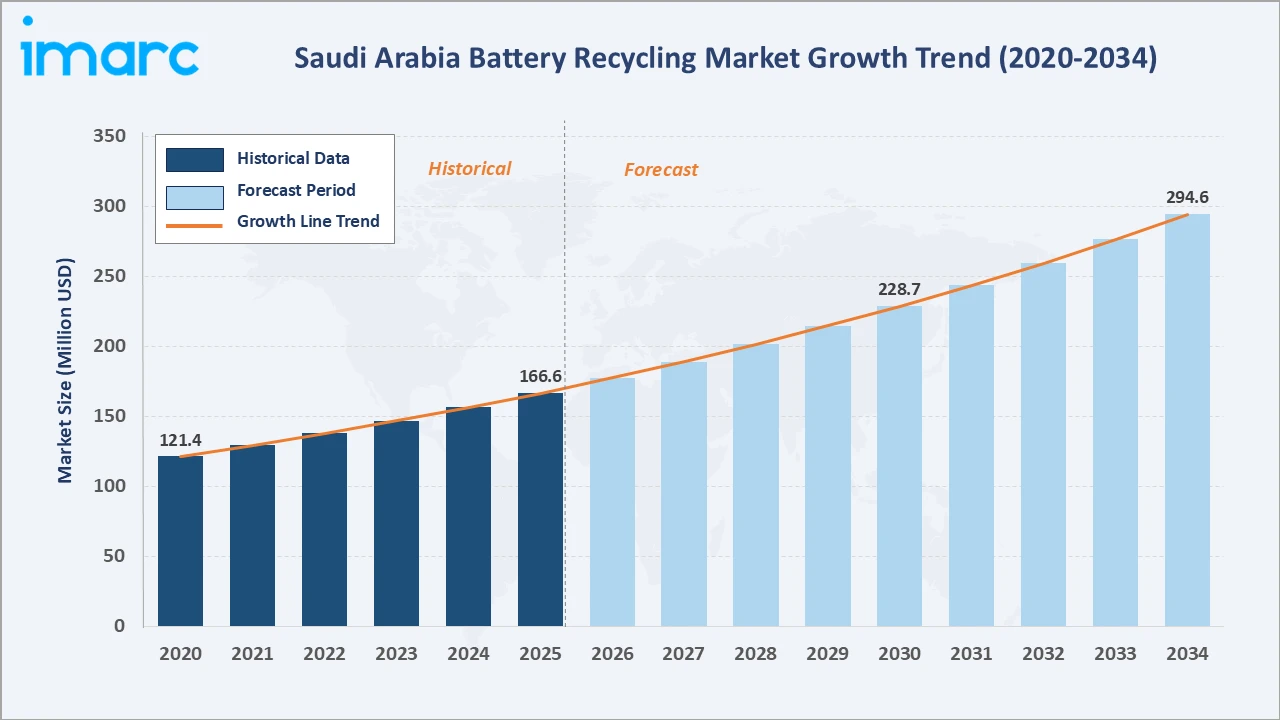
The Saudi Arabia battery recycling market size increased from USD 166.6 Million in 2025 to USD 177.5 Million in 2026 and is projected to reach USD 294.6 Million by 2034, exhibiting a CAGR of 6.54% during 2026-2034. Expanding automotive and industrial battery volumes, Vision 2030's circular economy initiatives, and tightening hazardous waste regulations are the primary drivers shaping the market growth.
Lead-acid batteries lead the type segment at 54.6%, automotive dominates the source segment at 46.3%, and Northern and Central Region commands 46.9% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 166.6 Million |
| Market Size (2026) | USD 177.5 Million |
|
Forecast Market Size (2034) |
USD 294.6 Million |
|
CAGR (2026-2034) |
6.54% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern and Central Region (46.9%, 2025) |
|
Second Largest Region |
Western Region (24.3%, 2025) |
|
Leading Type |
Lead-acid Batteries (54.6%, 2025) |
|
Leading Source |
Automotive (46.3%, 2025) |
The Saudi Arabia battery recycling market expanded from USD 121.4 Million in 2020 to USD 166.6 Million in 2025 and is estimated to reach USD 177.5 Million in 2026, driven by a rising vehicle parc, growing industrial battery backup demand, and stricter hazardous waste handling requirements. Anchored at USD 228.7 Million in 2030, the forecast to USD 294.6 Million by 2034 is supported by accelerating lithium-based battery volumes, expanding domestic smelting capacity, and a maturing formal collection network across the Kingdom.
To get more information on this market, Request Sample
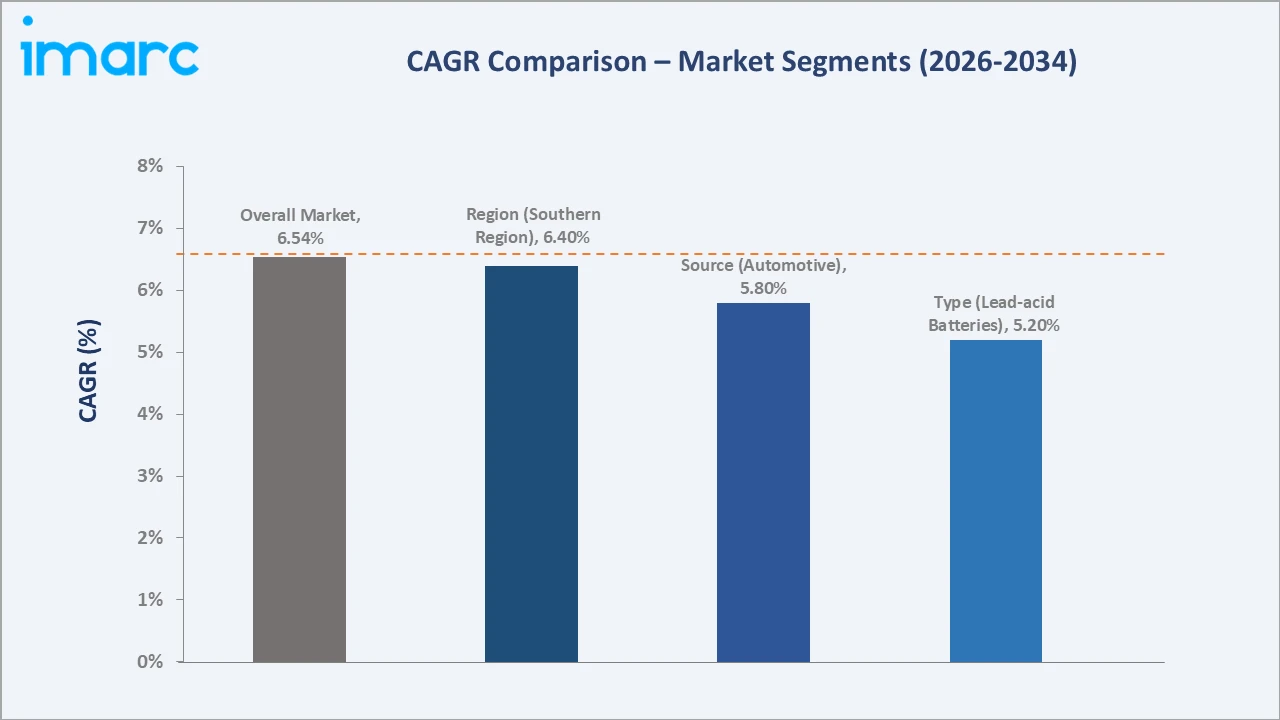
CAGR trajectories across type, source, and regional segments show lithium-based batteries and Western Region expanding faster than the overall 6.54% market CAGR, driven by rising energy storage deployment, EV-linked feedstock growth, and industrial diversification outside the traditional northern and central hub.
Executive Summary
The Saudi Arabia battery recycling market is on a steady growth trajectory from USD 121.4 Million in 2020 to an estimated USD 177.5 Million in 2026, reaching USD 294.6 Million by 2034. The industry has moved from informal scrap collection to a more formalized, regulation-led recycling ecosystem spanning automotive, industrial, and consumer battery streams. Rising vehicle ownership, expanding renewable energy storage deployment, and Vision 2030's circular economy initiatives are encouraging manufacturers and recyclers to scale compliant processing capacity.
Lead-acid batteries dominate the type segment at 54.6% in 2025, supported by the country's large automotive fleet and dense industrial backup power base. Automotive leads the source segment at 46.3%, driven by steady vehicle ownership, routine battery replacement demand, and a well-established aftermarket network. Northern and Central Region commands 46.9% of the regional share, anchored by Riyadh's industrial base and vehicle density.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Lead-acid Batteries - 54.6% share (2025) |
|
Second Largest Type |
Lithium-based Batteries - 23.4% share (2025) |
|
Leading Source |
Automotive - 46.3% share (2025) |
|
Second Largest Source |
Industrial - 27.5% share (2025) |
|
Leading Region |
Northern and Central Region - 46.9% share (2025) |
|
Second Largest Region |
Western Region - 24.3% share (2025) |
|
Top Companies |
National Industrialization Company (TASNEE), Saudi Investment Recycling Company (SIRC), Veolia Environnement S.A., MEBCO, Averda |
Key Analytical Observations Supporting the Above Data:
- Lead-acid batteries leadership at 54.6% is anchored by the Kingdom's large automotive fleet, industrial UPS and backup power systems, and telecom tower installations, supported by well-established collection channels through distributors and scrap dealers.
- Lithium-based batteries at 23.4% form the fastest-growing type segment, propelled by expanding utility-scale battery energy storage systems and early-stage EV adoption generating a rising pool of end-of-life cells.
- Automotive dominance at 46.3% reflects the country's expanding vehicle parc and frequent lead-acid battery replacement cycles in a high-temperature operating environment that shortens average battery lifespan.
- Industrial share at 27.5% is expanding as data centers, telecom infrastructure, and solar-plus-storage installations generate steady volumes of end-of-life industrial batteries requiring specialized processing.
- Northern and Central Region at 46.9% dominates regional share, supported by the concentration of industrial facilities, automotive activity, and battery collection infrastructure centered around Riyadh and surrounding economic hubs.
Saudi Arabia Battery Recycling Market Overview
Battery recycling refers to the collection, dismantling, and processing of end-of-life batteries to recover reusable materials such as lead, lithium, nickel, plastics, and electrolytes, diverting hazardous waste from landfills while supplying secondary raw materials to manufacturers. In Saudi Arabia, the market spans lead-acid, lithium-based, nickel-based, and other battery chemistries collected from automotive, industrial, consumer product, and electronic appliance sources.
The Kingdom's recycling ecosystem integrates scrap collectors and distributors, licensed smelting and refining operators, technology providers, environmental regulators, battery manufacturers, and logistics and compliance service providers. Together, they support a value chain shaped by Vision 2030's circular economy agenda and tightening hazardous waste rules.
Market Dynamics
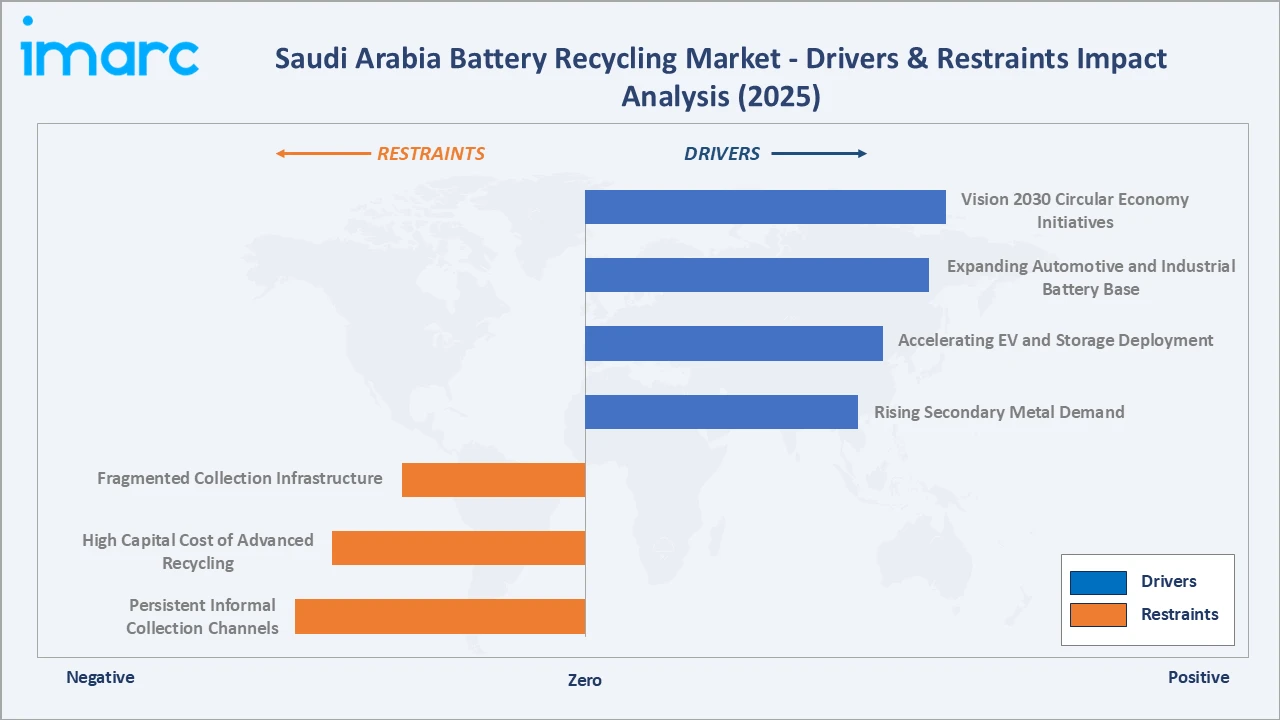
To evaluate market opportunities, Request Sample
Market Drivers
- Vision 2030 Circular Economy Initiatives: National sustainability targets under Vision 2030 are pushing manufacturers, importers, and municipalities toward formal collection and licensed recycling, replacing informal scrap channels with traceable, regulated material recovery streams.
- Expanding Automotive and Industrial Battery Base: A growing vehicle parc combined with dense telecom, data center, and industrial backup power infrastructure is generating a steadily rising volume of end-of-life lead-acid and industrial batteries each year.
- Accelerating EV and Storage Deployment: The government targets 30% EV penetration by 2030, supported by the planned rollout of 5,000 public charging points, a shift that is expanding the pool of lithium-based batteries entering the recycling stream.
- Rising Secondary Metal Demand: Domestic battery manufacturers are increasingly sourcing recycled lead and lithium to reduce import dependence, supporting steady offtake for licensed smelting and refining operators.
Market Restraints
- Persistent Informal Collection Channels: A significant share of used batteries still moves through unlicensed scrap dealers operating outside formal reporting and environmental compliance frameworks, limiting traceability of hazardous material flows.
- High Capital Cost of Advanced Recycling: Establishing hydrometallurgical or advanced pyrometallurgical processing capacity requires substantial upfront investment, restraining smaller operators from upgrading beyond basic smelting operations.
- Fragmented Collection Infrastructure: Limited drop-off and take-back coverage outside major industrial cities constrains consistent feedstock supply for licensed recyclers in less urbanized regions.
Market Opportunities
- Lithium-based Battery Recovery Technology: Rising utility-scale storage and early EV adoption create an emerging opportunity for hydrometallurgical recovery of lithium, nickel, and cobalt from end-of-life cells.
- Domestic Secondary Lead Supply Chains: Expanding smelting and refining capacity presents an opportunity to reduce reliance on imported lead by supplying battery manufacturers with locally recovered material.
Market Challenges
- Feedstock Traceability Across the Supply Chain: Inconsistent battery collection reporting between formal and informal channels complicates efforts to build a fully traceable circular material flow.
- Technical Workforce and Processing Capability Gaps: Scaling advanced recycling technologies requires specialized technical expertise that remains limited domestically, slowing capacity expansion at some facilities.
Emerging Market Trends
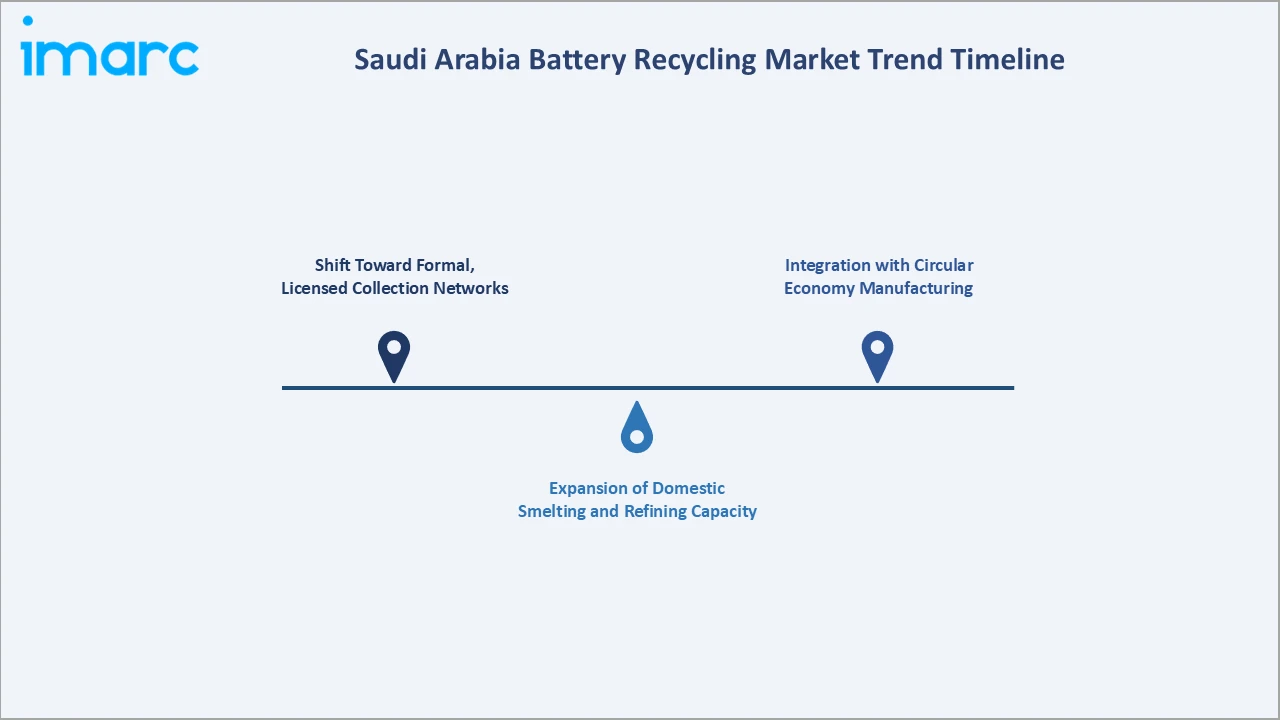
1. Shift Toward Formal, Licensed Collection Networks
Operators are replacing informal scrap channels with structured take-back and drop-off programs aligned with the Waste Management Law, improving traceability of hazardous battery waste across the Kingdom.
2. Expansion of Domestic Smelting and Refining Capacity
Licensed lead smelters are scaling refining capacity to meet growing demand for secondary lead from domestic battery manufacturers, reducing reliance on imported raw material.
3. Integration with Circular Economy Manufacturing
Battery producers are increasingly sourcing recycled lead and other recovered materials directly from domestic recyclers, tightening the loop between end-of-life collection and new battery production.
Industry Value Chain Analysis
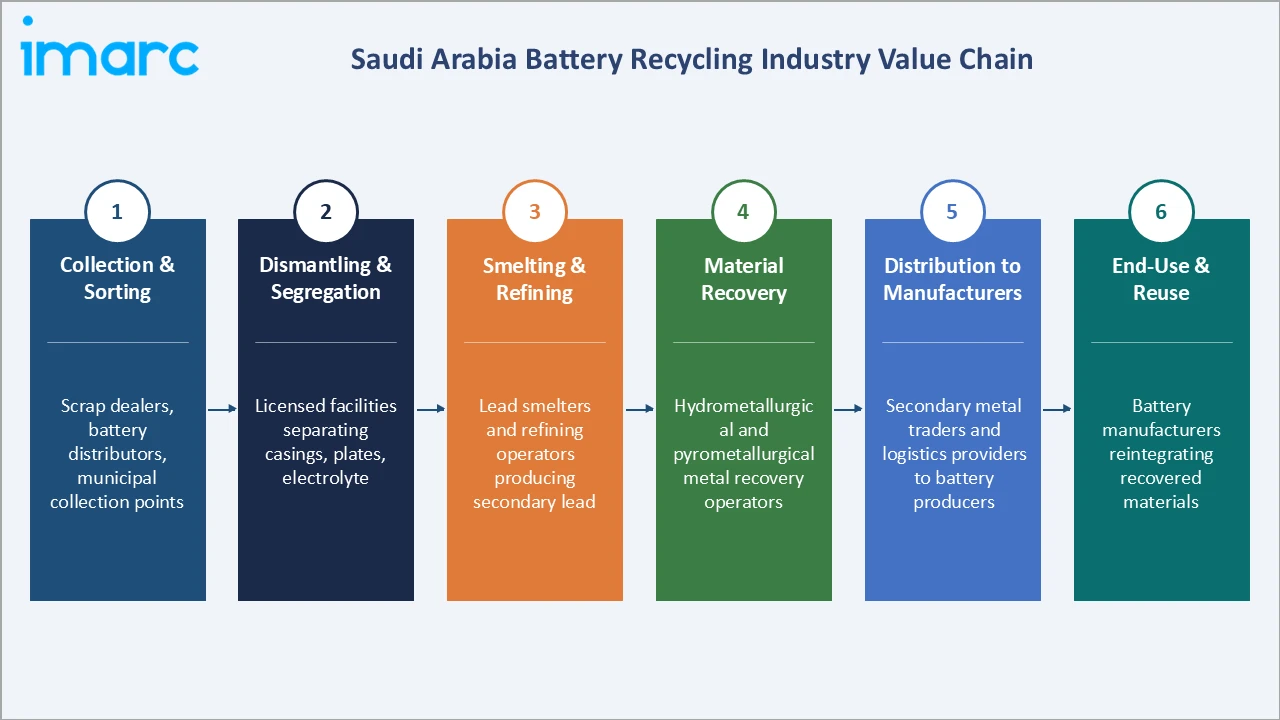
The Saudi Arabia battery recycling value chain spans six stages, from feedstock collection through end-use reintegration. Smelting and refining, along with material recovery, capture the highest value-add, while collection and compliance capabilities increasingly determine sustainable competitive position within this regulated category.
|
Stage |
Key Players / Examples |
|
Collection & Sorting |
Scrap dealers, battery distributors, and municipal collection points gathering end-of-life batteries from automotive and industrial sources |
|
Dismantling & Segregation |
Licensed processing facilities separating casings, plates, and electrolyte materials ahead of thermal or chemical processing |
|
Smelting & Refining |
Lead smelters and refining operators producing high-purity secondary lead ingots and alloys |
|
Material Recovery |
Hydrometallurgical and pyrometallurgical operators recovering lead, lithium, nickel, and other battery-grade metals |
|
Distribution to Manufacturers |
Secondary metal traders and logistics providers supplying recovered material to domestic and regional battery producers |
|
End-Use & Reuse |
Battery manufacturers and industrial users reintegrating recovered materials into new battery production |
Vertically integrated operators that combine collection, smelting, and refining capabilities are positioned to capture greater value than partners reliant on third-party feedstock aggregation.
Technology Landscape in the Saudi Arabia Battery Recycling Industry
Battery Recycling Technology & Processing
Licensed recyclers in Saudi Arabia rely primarily on pyrometallurgical smelting for lead-acid battery processing, given the country's mature lead smelting infrastructure and abundant, low-cost energy supply. Hydrometallurgical processes, which use chemical solutions rather than high-temperature smelting, are gaining traction for lithium-based battery recovery due to lower emissions and more selective metal extraction.
Materials Innovation
Recyclers are investing in improved sorting and pre-processing technology to separate mixed battery chemistries more accurately before downstream treatment, supporting higher material recovery rates and reducing cross-contamination between lead and lithium streams.
Smart Connectivity
Digital tracking systems are being piloted to log battery collection, transport, and processing data, supporting compliance with take-back mandates and improving visibility into feedstock volumes across the value chain.
Automation
Automated battery breaking, separation, and material sorting equipment is being adopted to increase throughput, reduce manual handling of hazardous materials, and improve worker safety at processing facilities across Riyadh, Jeddah, and Dammam.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Lead-acid Batteries |
54.6% |
2025 |
|
Source |
Automotive |
46.3% |
2025 |
|
Material |
🔒 |
🔒 |
2025 |
|
End Use |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
46.9% |
2025 |

By Type
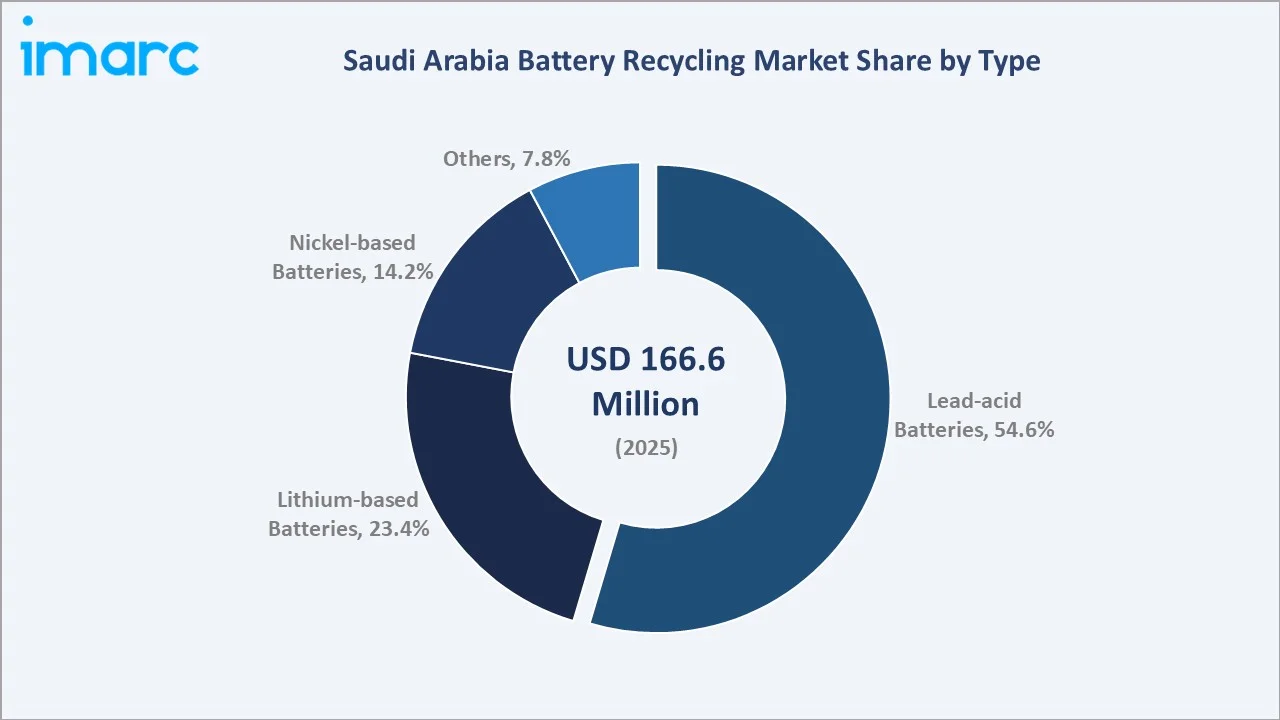
Lead-acid batteries command a 54.6% majority share in 2025, driven by their widespread use in automotive starting, lighting, and ignition systems, as well as industrial uninterruptible power and backup applications. The segment benefits from mature collection networks and well-established smelting infrastructure across the Kingdom.
To access detailed market analysis, Request Sample
Lithium-based batteries hold 23.4% share in 2025, expanding fastest among type segments as utility-scale energy storage and early EV adoption generate a growing pool of end-of-life cells requiring specialized hydrometallurgical processing.
By Source
Automotive leads the source segment with 46.3% share in 2025, reflecting the country's large and growing vehicle parc and the shorter average battery lifespan associated with high ambient temperatures.
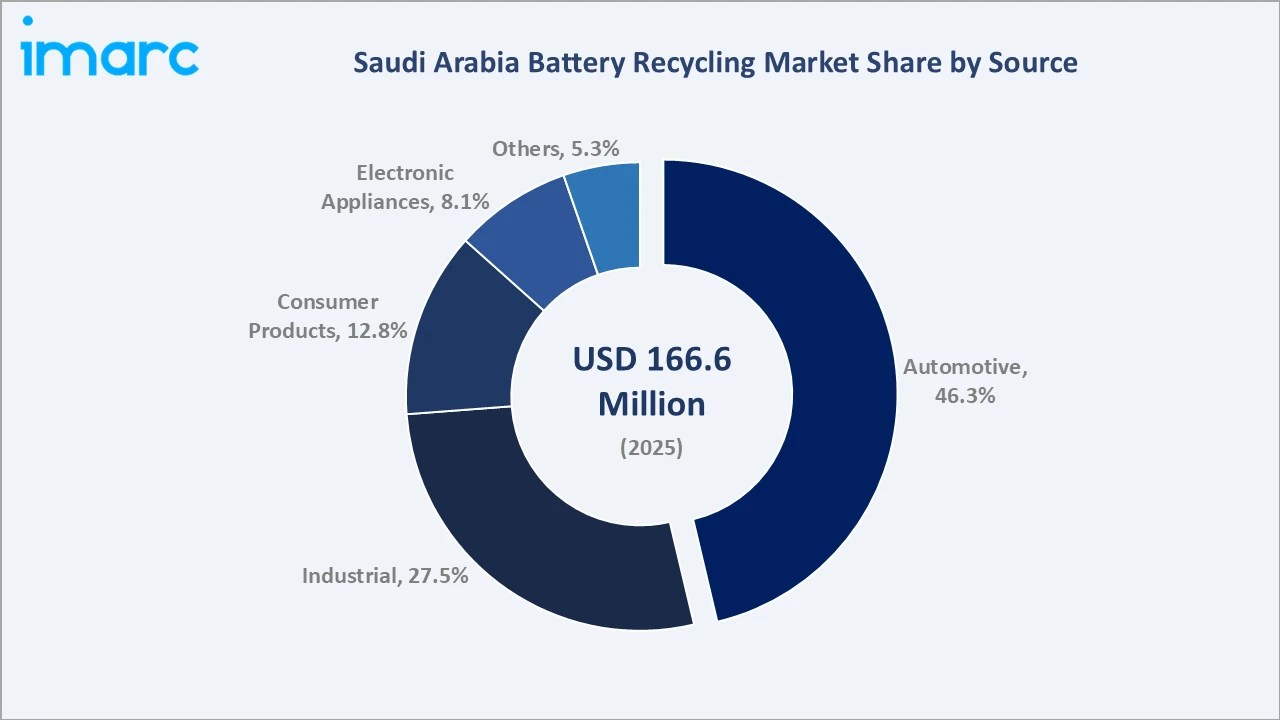
Industrial accounts for 27.5% share in 2025, supported by expanding telecommunications infrastructure, data centers, manufacturing facilities, and renewable energy storage systems that generate a steady stream of end-of-life industrial batteries for recycling.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
46.9% |
Large urban population, dense automotive and industrial base, established lead smelting infrastructure, and strong regulatory enforcement presence |
|
Western Region |
24.3% |
Port-linked logistics infrastructure, growing industrial diversification, expanding manufacturing base, and rising urban vehicle ownership |
|
Eastern Region |
17.8% |
Concentrated industrial and petrochemical infrastructure, strong backup power demand, and established scrap collection networks |
|
Southern Region |
11.0% |
Emerging industrial development, expanding urban infrastructure, and gradual formalization of local collection channels |
Northern and Central Region at 46.9% in 2025 leads the regional landscape, anchored by Riyadh's industrial base, dense vehicle ownership, and the concentration of large lead smelting and refining facilities. Established regulatory presence and mature collection networks support sustained regional leadership.
Western Region at 24.3% is expanding fastest, with growth supported by Jeddah's port-linked import-export infrastructure, rising industrial diversification, and expanding formal collection coverage beyond the traditional Riyadh-Dammam corridor.
Competitive Landscape
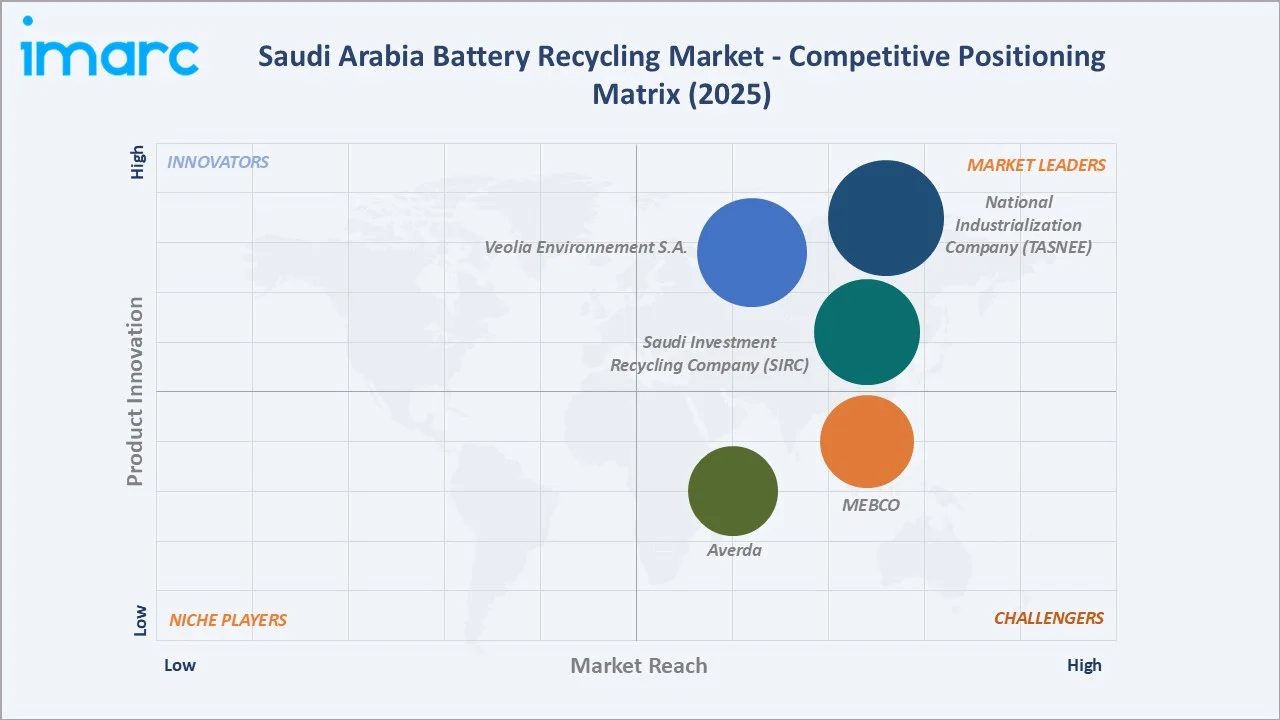
The Saudi Arabia battery recycling market is moderately concentrated, with a mix of state-backed national recyclers, dedicated lead smelters, and international waste management groups leading collection and processing capacity. Technology depth, licensing status, and integration with domestic battery manufacturing form the key competitive differentiators following the tightening of hazardous waste regulations.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| National Industrialization Company (TASNEE) |
RASASS |
Leader |
Expanding domestic lead smelting and refining capacity to strengthen secondary material supply |
| Saudi Investment Recycling Company (SIRC) |
Reviva (formerly GEMS) |
Leader |
Scaling national hazardous waste infrastructure across multiple recycling streams including batteries |
|
Veolia Environnement S.A. |
Veolia Near & Middle East |
Leader |
Growing hazardous and industrial waste treatment capacity in partnership with national operators |
|
MEBCO |
MEBCO |
Challenger |
Strengthening take-back and collection coordination alongside battery manufacturing operations |
|
Averda |
Averda |
Challenger |
Expanding hazardous and e-waste collection infrastructure to support formal battery take-back |
Key players include National Industrialization Company (TASNEE), Saudi Investment Recycling Company (SIRC), Veolia Environnement S.A., MEBCO, and Averda, among others.
Key Company Profiles
National Industrialization Company (TASNEE)
National Industrialization Company (TASNEE) is a diversified Saudi industrial group active in petrochemicals and industrial manufacturing. The company supports the Kingdom's industrial sustainability initiatives through investments in resource efficiency, waste management, and circular economy practices across its manufacturing operations.
- Product Portfolio: Lead alloys recovered from end-of-life lead-acid batteries through its RASASS subsidiary.
- Recent Developments: The company continues to strengthen its recycling operations by enhancing lead recovery efficiency and supporting the domestic supply of recycled lead for industrial and automotive battery applications.
- Strategic Focus: Maintaining RASASS's position as a leading lead recycling facility in Saudi Arabia while supporting the country's secondary metals supply chain.
Saudi Investment Recycling Company (SIRC)
Saudi Investment Recycling Company (SIRC) is a Saudi government-owned environmental services company established to develop recycling and waste management infrastructure across the Kingdom as part of Vision 2030. The company provides integrated solutions for municipal, industrial, hazardous, and specialized waste streams through its subsidiaries and strategic partnerships.
- Product Portfolio: Battery and hazardous waste treatment services delivered through its subsidiary, Reviva.
- Recent Developments: The firm continues to expand its national recycling and hazardous waste treatment infrastructure across Saudi Arabia.
- Strategic Focus: Building national recycling infrastructure and supporting Saudi Arabia's circular economy goals.
Veolia Environnement S.A.
Veolia Environnement S.A. is a French multinational group providing water, waste, and energy management services worldwide, operating in Saudi Arabia through its regional division, Veolia Near & Middle East.
- Product Portfolio: Hazardous and industrial waste treatment services, including battery-related waste handling, as part of its broader environmental services portfolio.
- Recent Developments: The company continues to strengthen its hazardous waste treatment partnerships and operations across Saudi Arabia.
- Strategic Focus: Expanding its regional waste treatment capacity in partnership with national operators in Saudi Arabia.
Market Concentration Analysis
The Saudi Arabia battery recycling market is moderately concentrated, with established recycling companies and industrial waste management firms competing alongside regional players through collection networks, processing capabilities, regulatory compliance, and partnerships with automotive, industrial, and energy-sector stakeholders.
Barriers to entry include the high capital cost of smelting and hydrometallurgical infrastructure, the need for environmental licensing and compliance capability, and the logistics required to secure consistent feedstock from a still-fragmented collection base. These factors favor established operators with existing smelting assets and government-linked backing.
Consolidation is gradually advancing as international waste management groups form partnerships with national recyclers, while technology providers license hydrometallurgical processes to expand domestic lithium-based recovery capacity. Strategic partnerships between battery manufacturers and recyclers are expected to further reinforce competitive positioning across the formal segment of the market.
Investment & Growth Opportunities
Fastest-Growing Segments
Lithium-based batteries are expanding the fastest among type segments, driven by rising energy storage deployment and early EV adoption. Growing investments in utility-scale renewable energy projects and battery energy storage systems are expected to further increase the volume of end-of-life lithium-ion batteries available for recycling over the forecast period.
Emerging Markets
Eastern Region represents significant untapped opportunity for operators able to expand formal collection coverage and licensed processing capacity beyond the traditional Riyadh-Dammam industrial corridor.
Venture & Investment Trends
Investment is concentrated in hydrometallurgical technology licensing, smelting capacity expansion, and partnerships between international waste management groups and national recyclers, aligning with Vision 2030's circular economy and hazardous waste management priorities.
Future Market Outlook (2026-2034)
The Saudi Arabia battery recycling market is projected to grow from USD 166.6 Million in 2025 to USD 177.5 Million in 2026, reaching USD 294.6 Million by 2034, at a CAGR of 6.54%, adding roughly USD 128.0 Million in incremental market value over the forecast period.
Three forces will shape the market through 2034: continued formalization of collection and take-back infrastructure under the Waste Management Law; expanding hydrometallurgical capacity to serve growing lithium-based battery volumes; and deeper integration between domestic battery manufacturers and licensed recyclers.
By 2034, battery recycling in Saudi Arabia is expected to be defined by compliant, formally licensed processing, with lithium-based recovery accounting for a meaningfully higher share of overall activity as utility-scale storage and EV adoption continue to expand.
Research Methodology
Primary Research
Primary research included structured interviews with recycling plant operators, battery manufacturers, environmental regulators, and logistics providers, validating market sizing, segment shares, and regional demand patterns.
Secondary Research
Secondary sources included Ministry of Environment, Water and Agriculture publications, the Waste Management Law and related regulatory texts, company disclosures from listed and private recyclers, and industry association reports.
Forecasting Models
Market forecasts used top-down and bottom-up models combining battery installed base, average replacement cycles, collection rate assumptions, and regulatory transition scenarios. Scenario analysis addressed licensing pace, feedstock formalization, and technology adoption timelines.
Saudi Arabia Battery Recycling Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Lead-acid Batteries, Nickel-based Batteries, Lithium-based Batteries, Others |
| Sources Covered | Industrial, Automotive, Consumer Products, Electronic Appliances, Others |
| Materials Covered | Manganese, Iron, Lithium, Nickel, Cobalt, Lead, Aluminum, Others |
| End-Uses Covered | Reuse, Repackaging, Extraction, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | National Industrialization Company (TASNEE), Saudi Investment Recycling Company (SIRC), Veolia Environnement S.A., MEBCO, Averda, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia battery recycling market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia battery recycling market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia battery recycling industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Battery Recycling Market Report
The market size is estimated at USD 177.5 Million in 2026, driven by expanding automotive and industrial battery volumes and tightening hazardous waste recycling regulations across the Kingdom.
The market is projected to grow at a CAGR of 6.54% from 2026-2034, reaching USD 294.6 Million, supported by rising lithium-based battery recovery and expanding smelting capacity.
Lead-acid batteries lead at 54.6% share in 2025, supported by the Kingdom's large automotive fleet and industrial backup power base.
Automotive leads at 46.3% share in 2025, reflecting the country's expanding vehicle parc. The segment is further supported by frequent lead-acid battery replacement cycles and a well-established collection network across dealerships, workshops, and scrap dealers.
Northern and Central Region commands 46.9% share in 2025, anchored by Riyadh's industrial base, dense vehicle ownership, and concentration of large lead smelting facilities.
Leading players include National Industrialization Company (TASNEE), Saudi Investment Recycling Company (SIRC), Veolia Environnement S.A., MEBCO, and Averda, among others.
Hydrometallurgical processing is gaining adoption for lithium-based battery recovery, while automated sorting and separation equipment is improving throughput and safety at licensed processing facilities.
Persistent informal collection channels, high capital costs for advanced recycling infrastructure, and fragmented collection coverage outside major industrial cities continue to restrain formal market expansion.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade