
Saudi Arabia Commercial Drones Market Size, Share, Trends and Forecast by System, Product, Mode of Operation, Weight, Application, End User, and Region, 2026-2034
Saudi Arabia Commercial Drones Market Size, Share, Trends & Forecast (2026-2034)
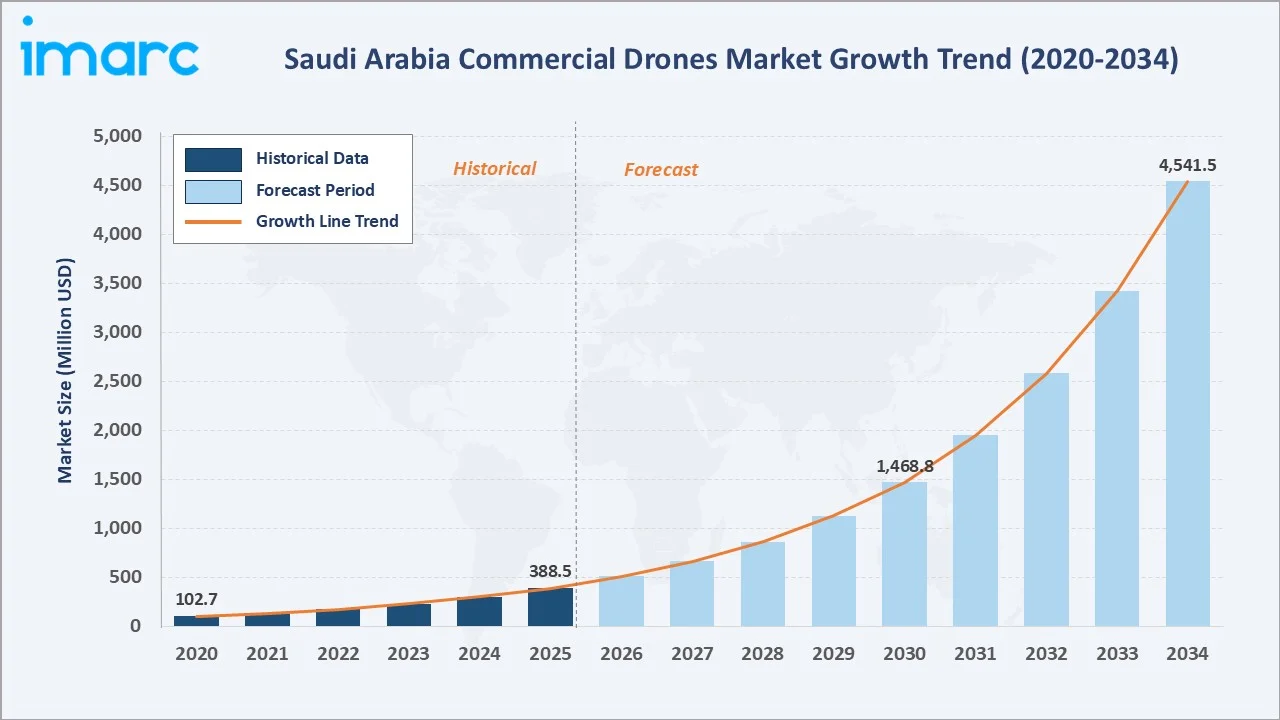
The Saudi Arabia commercial drones market reached USD 388.5 Million in 2025 and is projected to reach USD 4,541.5 Million by 2034, growing at a CAGR of 30.47% during 2026-2034.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 388.5 Million |
|
Forecast Market Size (2034) |
USD 4,541.5 Million |
|
CAGR (2026-2034) |
30.47% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Weight Segment |
<2 Kg (46.8%, 2025) |
|
Dominant Application |
Inspection & Maintenance (24.7%, 2025) |
|
Leading Region |
Northern and Central Region (36.5%, 2025) |
The Saudi Arabia commercial drones market expanded from USD 102.7 Million in 2020 to USD 388.5 Million in 2025 anchored at USD 1,468.8 Million by 2030 and USD 4,541.5 Million by 2034, driven by Vision 2030 initiatives, oil and gas sector digital transformation, and rapid AI integration across commercial drone applications.
To get more information on this market, Request Sample
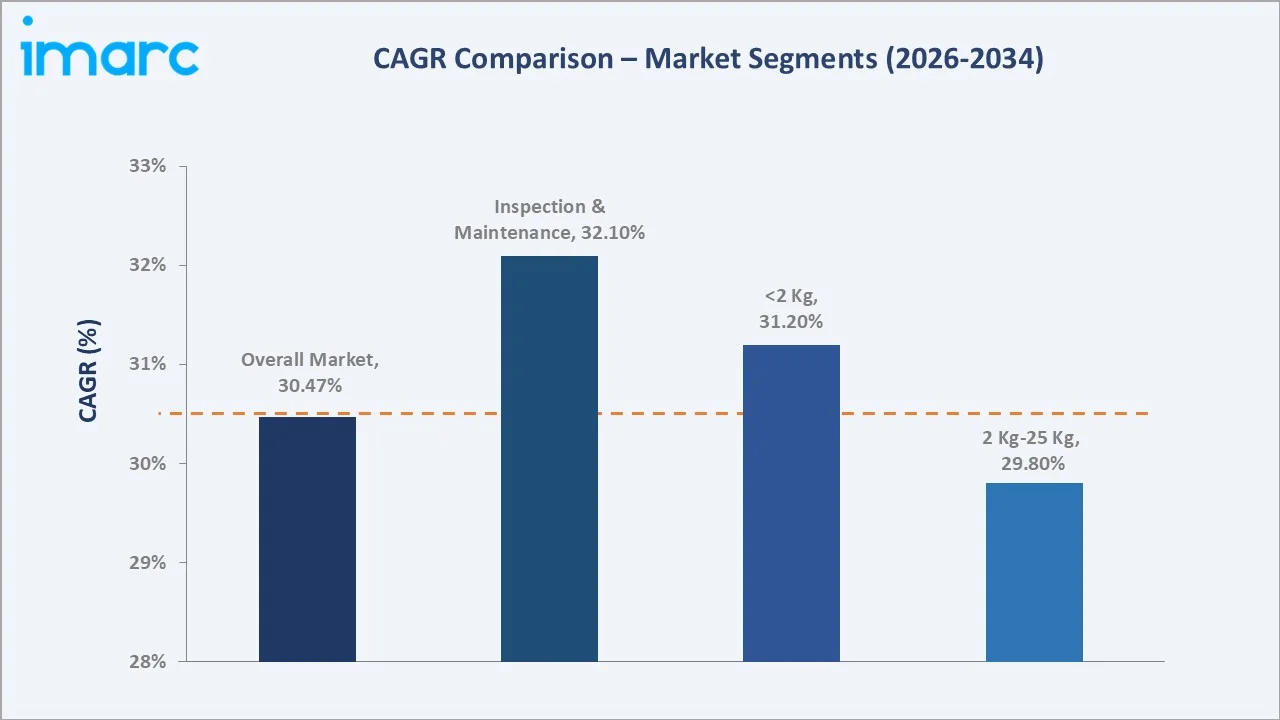
Inspection and maintenance leads application at 24.7% as Saudi Arabia's extensive oil, gas, and infrastructure assets create sustained aerial surveillance demand. The <2 Kg weight class commands 46.8% share driven by regulatory accessibility and multi-sector deployability across commercial segments.
Executive Summary
The Saudi Arabia commercial drones market reached USD 388.5 Million in 2025, representing one of the Middle East's highest-growth technology sectors. Saudi Arabia's Vision 2030 program, mega-infrastructure projects, and energy sector modernization are primary growth catalysts driving the market toward USD 4,541.5 Million by 2034.
The <2 Kg weight class at 46.8% dominates by enabling flexible, cost-effective deployment across industries. Inspection and maintenance at 24.7% leads application share driven by oil and gas infrastructure monitoring, while the Northern and Central Region at 36.5% anchors market growth through Riyadh's commercial and government procurement concentration.
Key Market Insights
|
Insight |
Data |
|
Dominant Weight Segment |
<2 Kg — 46.8% share (2025) |
|
Dominant Application |
Inspection & Maintenance — 24.7% market share (2025) |
|
Leading Region |
Northern and Central Region — 36.5% market share (2025) |
|
Market Opportunity |
BVLOS operations, smart city drones, precision agriculture AI platforms |
Key Analytical Observations Supporting the Above Data:
- <2 Kg at 46.8%: The lightweight drone segment dominates due to ease of deployment, lower regulatory barriers, and multi-sector applicability across filming, mapping, and inspection in urban and semi-urban areas. This segment benefits from accessible price points and broad commercial adoption across SME and enterprise operators. The regulatory simplicity of sub-2 Kg drones under GACA's framework continues to drive market growth.
- Inspection & Maintenance at 24.7%: Saudi Arabia's extensive oil, gas, and infrastructure assets create sustained demand for drone-based inspection, reducing personnel exposure to hazardous environments. The Eastern Province's oil fields and pipeline networks represent the Kingdom's largest concentration of inspection demand.
- Northern & Central Region at 36.5%: Riyadh and surrounding areas drive market growth through government procurement, giga-project construction activity, and the expanding commercial drone service provider ecosystem. The concentration of Vision 2030 administrative and development infrastructure further reinforces the region's market leadership.
Saudi Arabia Commercial Drones Market Overview
The Saudi Arabia commercial drones market encompasses the design, manufacture, supply, and deployment of unmanned aerial vehicles across commercial, industrial, and public sector applications. The ecosystem integrates drone hardware manufacturers, software and AI platform providers, regulatory bodies such as GACA, and end-users across oil and gas, agriculture, construction, and logistics.
The ecosystem integrates drone hardware manufacturers, software and AI platform providers, regulatory certification bodies such as GACA, commercial service operators, and end-users across oil and gas, agriculture, construction, and logistics. Saudi Arabia's geographic diversity, from expansive desert terrain to dense urban centers, drives a wide variety of drone use cases.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
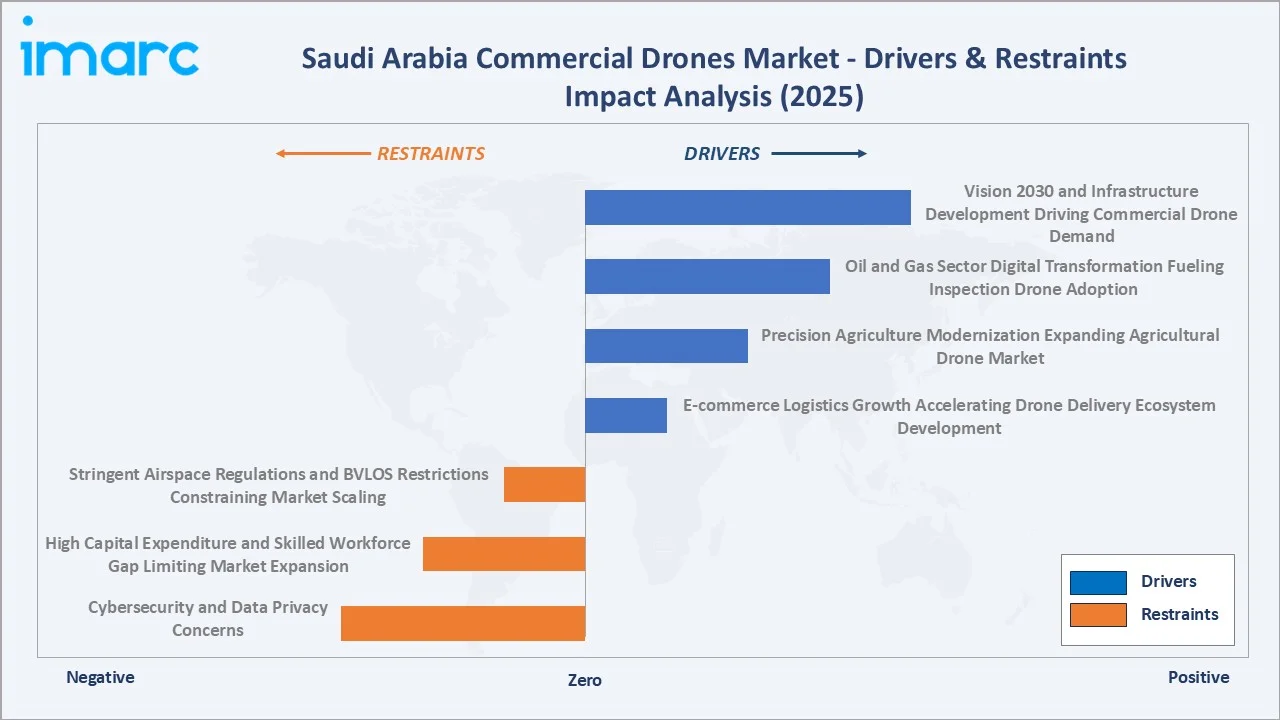
- Vision 2030 and Infrastructure Development Driving Commercial Drone Demand: Saudi Arabia's Vision 2030 program is driving unprecedented infrastructure investment across NEOM, The Red Sea Project, and Qiddiya, creating sustained demand for drone-based construction monitoring, mapping, and safety inspection services. Construction companies are utilizing drones to produce real-time aerial mapping, 3D models, and volumetric analysis, thus optimizing project efficiency and cutting costs. Governments are introducing programs that support R&D in unmanned aerial systems, creating a favorable environment for commercial drone adoption across key sectors.
- Oil and Gas Sector Digital Transformation Fueling Inspection Drone Adoption: Saudi Aramco and other energy operators are deploying drones for pipeline inspection, offshore rig monitoring, and thermal leak detection, reflecting institutional commitment to aerial surveillance technology. Energy firms are employing thermal imaging-enabled drones to find gas leaks and corrosion in real time, greatly enhancing operational safety while minimizing downtime. Being one of the world's largest producers of crude oil, Saudi Arabia's demand for inspection drone solutions is steadily rising across its extensive Eastern Province energy infrastructure.
- Precision Agriculture Modernization Expanding Agricultural Drone Market: Saudi Arabia's agriculture industry is progressively embracing drone technology to overcome conventional constraints related to water usage, land yield, and crop monitoring difficulties. Farmers are employing drones to spray crops, map irrigation, and manage pests, greatly enhancing resource use efficiency and production under conditions of drought and scarce arable land. Government departments are facilitating the shift to smart agricultural methods, with precision agriculture becoming critical to the Kingdom's national food security strategy.
- E-commerce Logistics Growth Accelerating Drone Delivery Ecosystem Development: Logistics operators are testing drone deliveries to bypass traffic congestion limitations, access remote locations, and reduce high delivery expenses, creating new commercial drone market demand. As consumer expectations move toward same-day delivery, drones are proving to be a potential technological solution for the rapidly expanding Saudi e-commerce ecosystem.
Market Restraints
- Stringent Airspace Regulations and BVLOS Restrictions Constraining Market Scaling: While GACA continues to evolve drone regulations, airspace restrictions, mandatory registration, and limited beyond-visual-line-of-sight approvals continue to constrain commercial drone scaling across complex operational environments. The regulatory approval timeline for new drone operational categories remains lengthy, creating barriers for commercial operators seeking to expand service portfolios. Pilot programs and sandbox approvals represent progress, but systematic commercial BVLOS authorization remains a near-term market constraint.
- High Capital Expenditure and Skilled Workforce Gap Limiting Market Expansion: Procurement of advanced commercial drones, sensors, and data processing platforms requires significant capital investment, while the shortage of trained drone operators and data analysts limits rapid market expansion across Saudi Arabia. The technical complexity of advanced drone systems requires specialized training programs that remain underdeveloped relative to the pace of market demand growth. High initial investment costs create barriers for SME market entry, concentrating commercial drone operations among larger enterprises.
- Cybersecurity and Data Privacy Concerns: Commercial drones collecting sensitive aerial imagery and operational data across critical infrastructure sites present cybersecurity risks and data privacy challenges, requiring robust protection frameworks. Saudi Arabia's energy and defense infrastructure creates heightened sensitivity around aerial data collection, necessitating comprehensive data governance frameworks. Regulatory clarity on data localization requirements and permitted imagery capture zones adds compliance complexity for commercial drone operators.
Market Opportunities
- BVLOS Operations and Beyond-Visual-Line-of-Sight Expansion: Regulatory evolution toward BVLOS approvals, enabled by Skyports' Saudi Arabia market entry in partnership with IoT Squared, creates significant commercial opportunities for large-scale infrastructure inspection and giga-project monitoring. The strategic partnership provides a pathway for building BVLOS infrastructure across Saudi Arabia's extensive and varied terrain. Scaling BVLOS operations enables commercial drone services to address inspection needs across remote energy and agricultural assets with significant efficiency gains.
- Smart City and Urban Air Mobility Integration Across Giga-Projects: NEOM and other smart city developments provide ideal environments for integrating drone delivery networks, aerial surveillance platforms, and urban air mobility solutions, positioning Saudi Arabia as a regional drone innovation hub. The Saudi government's proactive stance on emerging technology adoption within giga-project developments accelerates the establishment of enabling infrastructure for advanced commercial drone operations.
Market Challenges
- Limited Local Manufacturing Capability Creating Supply Chain Vulnerability: Saudi Arabia's commercial drone ecosystem remains heavily reliant on imported hardware, primarily from global manufacturers, creating supply chain vulnerabilities and limiting localization targets under Vision 2030. Building domestic drone manufacturing capacity requires significant investment in specialized engineering talent, production facilities, and supply chain infrastructure that takes years to develop.
- Desert Environmental Conditions Requiring Specialized Equipment Specifications: Extreme heat, sandstorms, and high UV exposure in Saudi Arabia's desert environment create specialized operational challenges for drone hardware durability, battery performance, and sensor reliability. Standard commercial drone platforms designed for temperate climates often experience accelerated degradation in Saudi Arabia's harsh conditions, increasing maintenance costs and operational downtime.
Emerging Market Trends
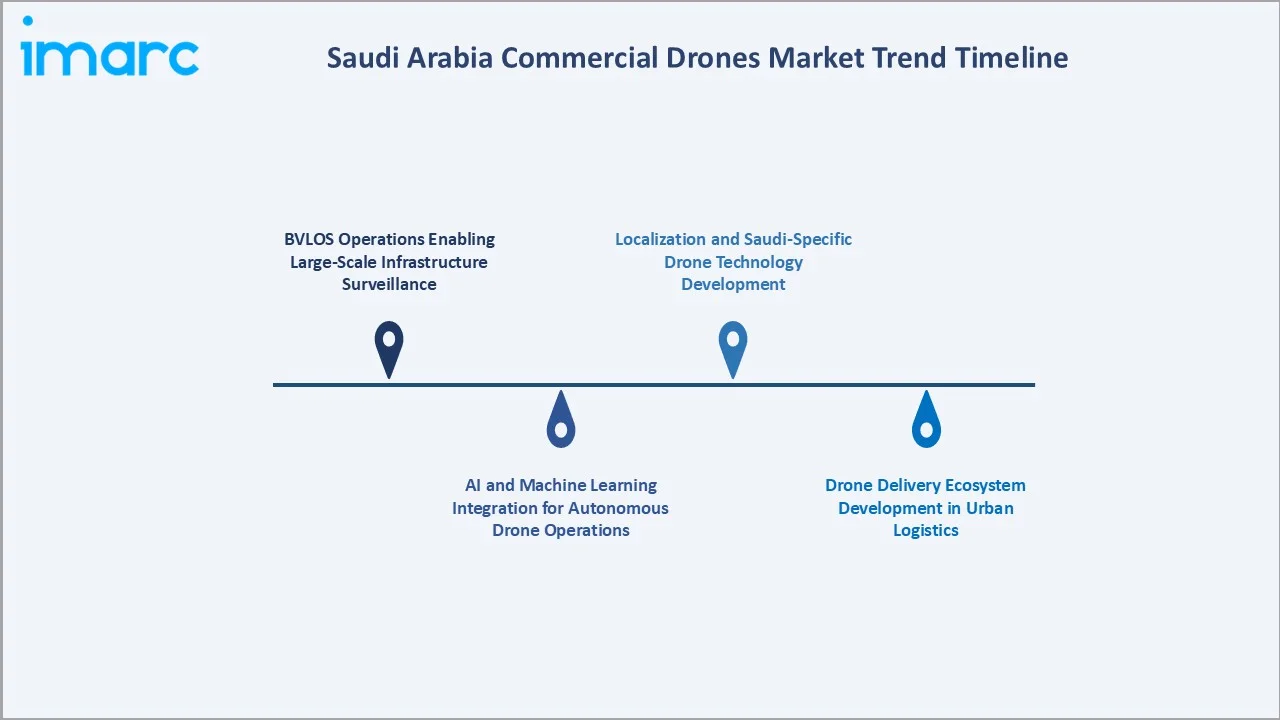
1. BVLOS Operations Enabling Large-Scale Infrastructure Surveillance
Beyond-visual-line-of-sight operations are becoming a key growth frontier, with Skyports' 2025 entry into Saudi Arabia demonstrating growing institutional interest in large-scale infrastructure monitoring across giga-projects. The partnership with iot squared reflects a broader strategic shift toward professional drone service operator ecosystems.
2. AI and Machine Learning Integration for Autonomous Drone Operations
AI-powered autonomous drones are enabling real-time object recognition, predictive maintenance, and automated inspection reporting, redefining commercial drone capability across Saudi Arabia's industrial sectors.
3. Drone Delivery Ecosystem Development in Urban Logistics
Matternet's GACA approval for the M2 drone marks a pivotal regulatory milestone for commercial drone delivery in Saudi Arabia. Saudi Arabia's June 2025 drone-based medicine delivery pilot during the Hajj season further validated institutional demand for unmanned aerial delivery in high-density, time-critical operational environments.
4. Localization and Saudi-Specific Drone Technology Development
Saudi Arabia's focus on localizing advanced technologies is encouraging the development and deployment of drone solutions adapted to the country's specific operating conditions. Partnerships between international drone technology providers and local energy, infrastructure, and industrial companies are supporting technology transfer, local expertise, and the development of customized commercial drone applications. This trend aligns with the broader Vision 2030 localization agenda and is expected to strengthen the domestic commercial drone ecosystem.
Industry Value Chain Analysis
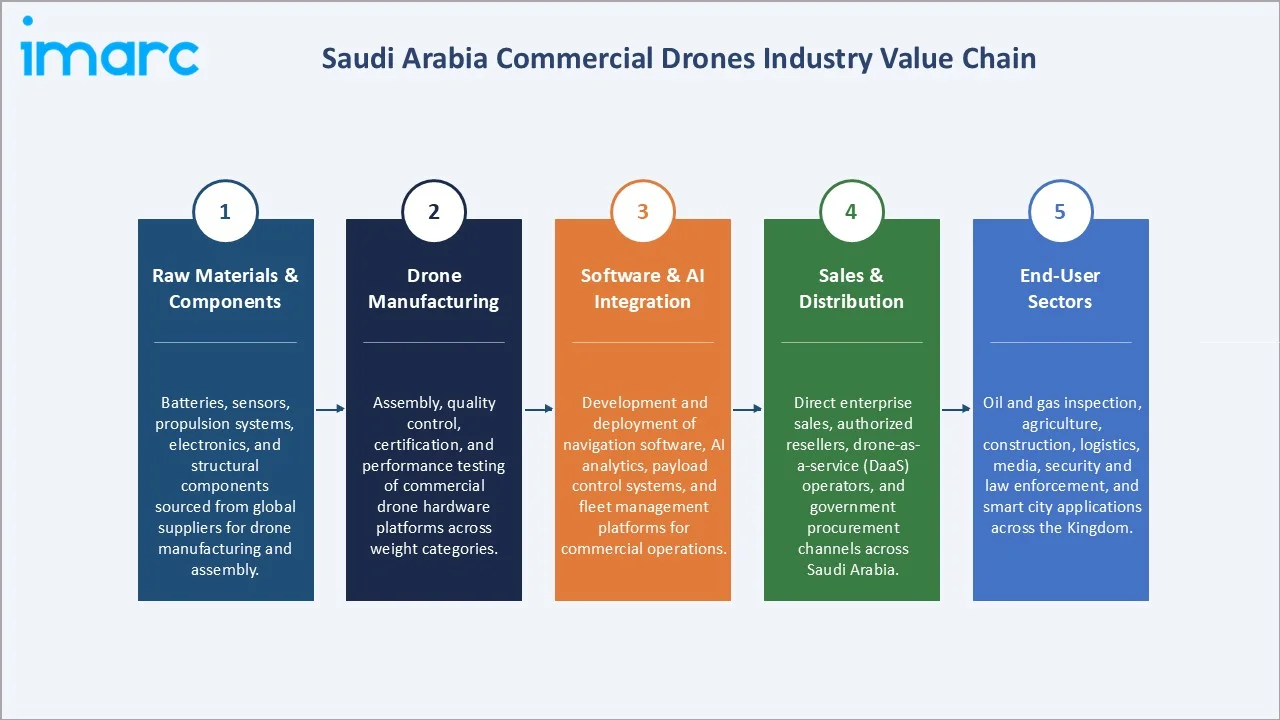
The Saudi Arabia commercial drones value chain integrates raw material and component sourcing, drone manufacturing and assembly, software and AI platform development, distribution and service provision, and end-user deployment across oil and gas, agriculture, construction, and logistics sectors.
|
Stage |
Key Participants |
|
Raw Materials & Components |
Batteries, sensors, propulsion systems, electronics, and structural components sourced from global suppliers for drone manufacturing and assembly. |
|
Drone Manufacturing |
Assembly, quality control, certification, and performance testing of commercial drone hardware platforms across weight categories. |
|
Software & AI Integration |
Development and deployment of navigation software, AI analytics, payload control systems, and fleet management platforms for commercial operations. |
|
Sales & Distribution |
Direct enterprise sales, authorized resellers, drone-as-a-service (DaaS) operators, and government procurement channels across Saudi Arabia. |
|
End-User Sectors |
Oil and gas inspection, agriculture, construction, logistics, media, security and law enforcement, and smart city applications across the Kingdom. |
The regulatory and certification tier, anchored by GACA's evolving drone framework, represents a critical commercial enabler across the value chain. Distribution and service layers, including drone-as-a-service operators and fleet management platforms, are emerging as high-growth intermediary segments with significant margin potential in the Saudi market.
Technology Landscape in the Saudi Arabia Commercial Drones Industry
Fixed-Wing Drone Technology
Fixed-wing drones offer extended flight range and endurance, making them suitable for large-scale mapping, surveying, and agricultural monitoring across Saudi Arabia's expansive territory. These platforms are increasingly integrated with multispectral sensors and AI-powered data analysis tools for precision agriculture and infrastructure surveillance applications across remote locations.
Rotary-Wing (Multirotor) Drone Technology
Multirotor drones dominate the <2 Kg segment by offering vertical takeoff and landing capability, maneuverability, and accessibility for urban inspection, filming, and monitoring applications. Their versatility, ease of operation, and declining cost profile have driven broad commercial adoption across Saudi Arabia's real estate, construction, and media sectors.
AI-Powered Autonomous Navigation Technology
AI-driven autonomous navigation systems, enabling obstacle avoidance, real-time route optimization, and automated mission execution, are redefining commercial drone capability across Saudi Arabia's industrial sectors. In June 2025, Saudi Arabia's drone-based Hajj medicine delivery program demonstrated practical autonomous drone deployment at institutional scale, validating AI navigation technology for complex, high-density operational environments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
System |
🔒 |
🔒 |
2025 |
|
Product |
🔒 |
🔒 |
2025 |
|
Mode of Operation |
🔒 |
🔒 |
2025 |
|
Weight |
<2 Kg |
46.8% |
2025 |
|
Application |
Inspection and maintenance |
24.7% |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
Northern & Central Region |
36.5% |
2025 |

By Weight
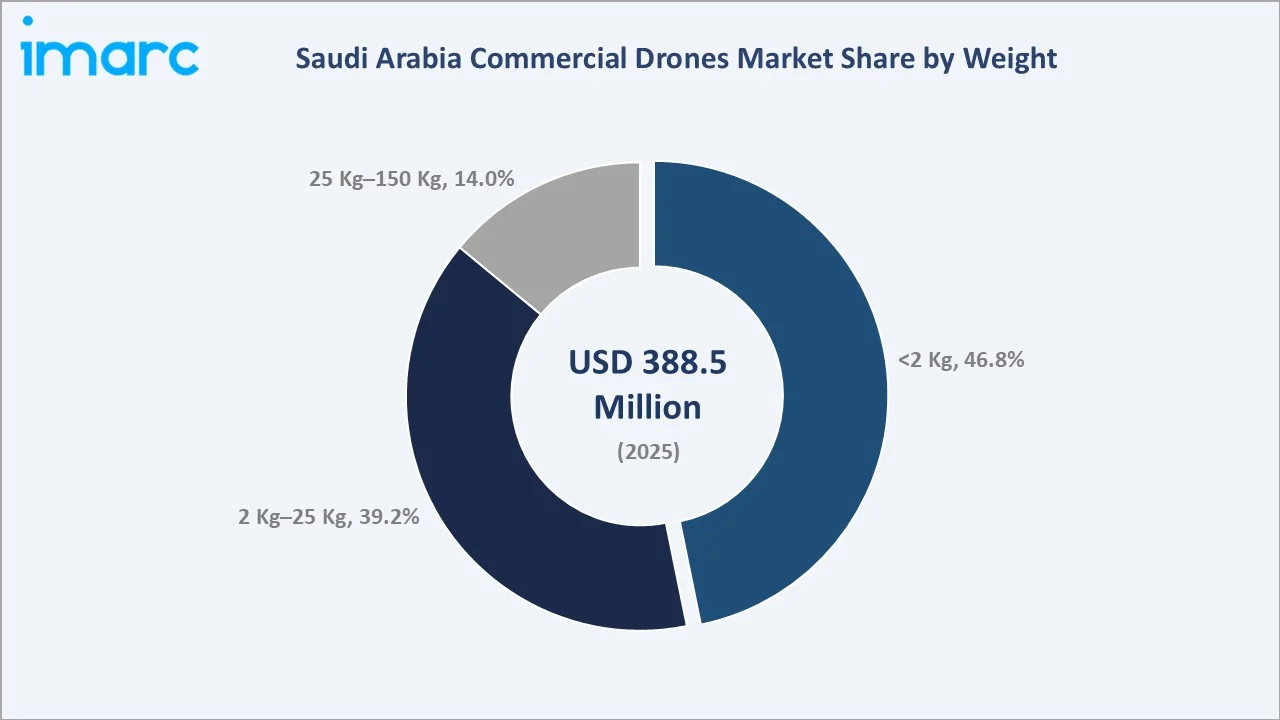
The <2 Kg segment leads at 46.8% in 2025, capturing the broadest commercial application range including mapping, filming, and inspection drones. The accessible price point, regulatory simplicity, and multi-sector deployability drive adoption across SMEs and large enterprises throughout Saudi Arabia's commercial drone market.
To access detailed market analysis, Request Sample
The 2 Kg–25 Kg segment at 39.2% encompasses professional-grade commercial drones serving oil and gas inspection, mapping, and agricultural applications requiring higher payload capacity and longer endurance. The 25 Kg–150 Kg segment at 14.0% serves heavy-lift delivery and specialized industrial applications, including cargo delivery across giga-project construction sites.
By Application
Inspection and maintenance leads at 24.7% through Saudi Arabia's extensive oil and gas pipeline networks, refineries, and infrastructure assets requiring regular aerial surveillance. The Eastern Province's energy infrastructure concentration creates a persistent institutional inspection market that underpins this segment's dominant position through 2034.
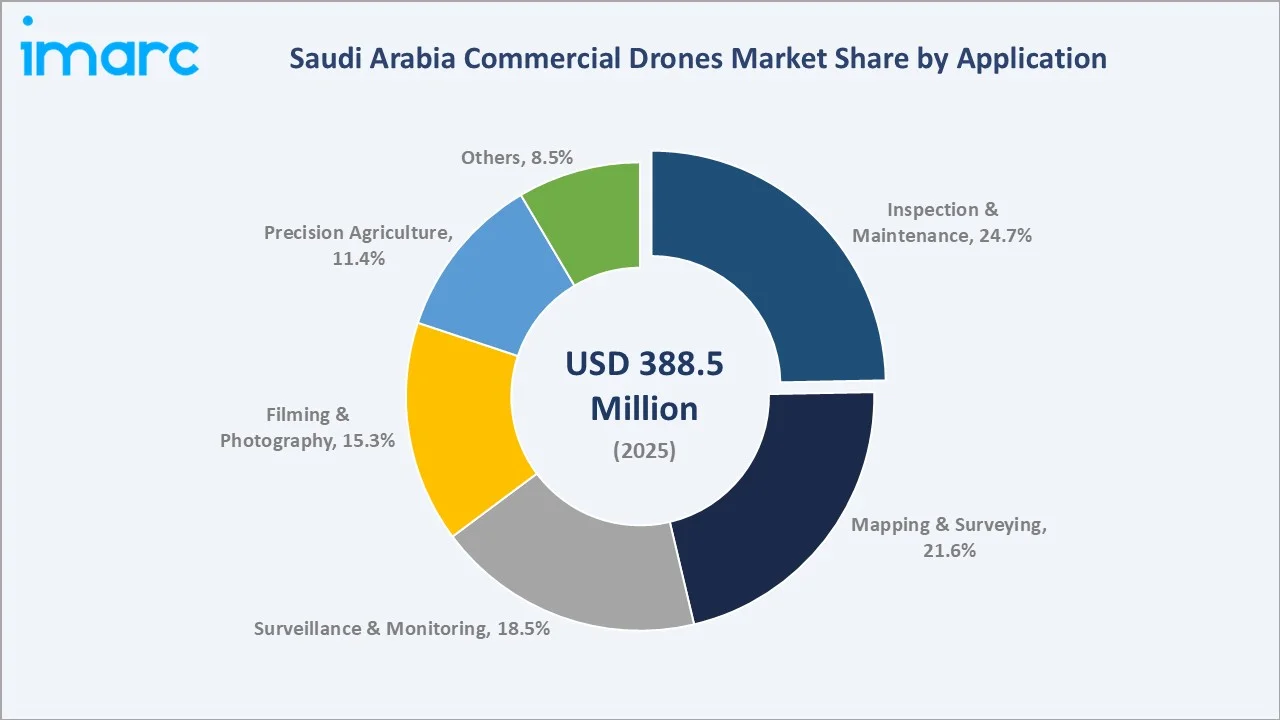
Mapping and surveying at 21.6% is driven by giga-project planning demands, with drones providing real-time 3D modeling and volumetric analysis for NEOM, The Red Sea Project, and Qiddiya. Surveillance and monitoring at 18.5% reflects security and law enforcement demand, while filming and photography at 15.3% serves Saudi Arabia's expanding media, entertainment, and real estate marketing sectors.
Regional Market Insights
|
Region |
Share (2025) |
Key Drone Market Drivers & Characteristics |
|
Northern & Central Region |
36.5% |
Anchored by Riyadh's government procurement, smart city initiatives, and commercial sector growth; highest concentration of drone service providers in the Kingdom. |
|
Western Region |
30.4% |
Driven by Jeddah's logistics sector, tourism and Hajj season operations, and Red Sea coastal infrastructure surveillance requirements. |
|
Eastern Region |
21.8% |
Dominated by oil and gas drone adoption; Saudi Aramco's extensive Eastern Province operations create sustained inspection and monitoring demand. |
|
Southern Region |
11.3% |
Emerging market driven by agricultural modernization, border surveillance, and infrastructure development along key transportation corridors. |
The Northern and Central Region at 36.5% leads through Riyadh's concentration of government entities, commercial enterprises, and Vision 2030 mega-project activity driving drone procurement. The Western Region at 30.4% reflects Jeddah's logistics and tourism-driven drone demand alongside the Red Sea Project's coastal surveillance requirements.
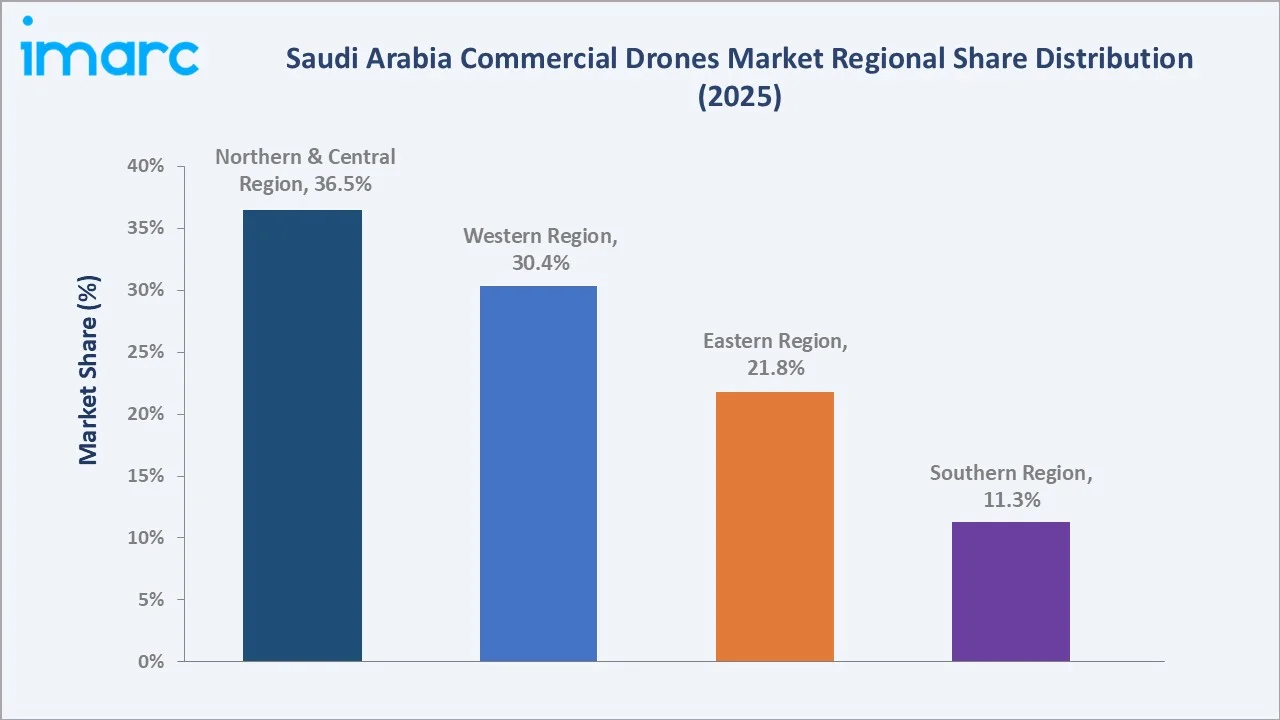
The Eastern Region at 21.8% is the primary oil and gas drone adoption zone, with Saudi Aramco's extensive Eastern Province operational infrastructure driving sustained inspection, pipeline monitoring, and thermal imaging drone deployment. The Southern Region at 11.3% represents an emerging growth corridor anchored by agricultural modernization and border security surveillance requirements.
Competitive Landscape
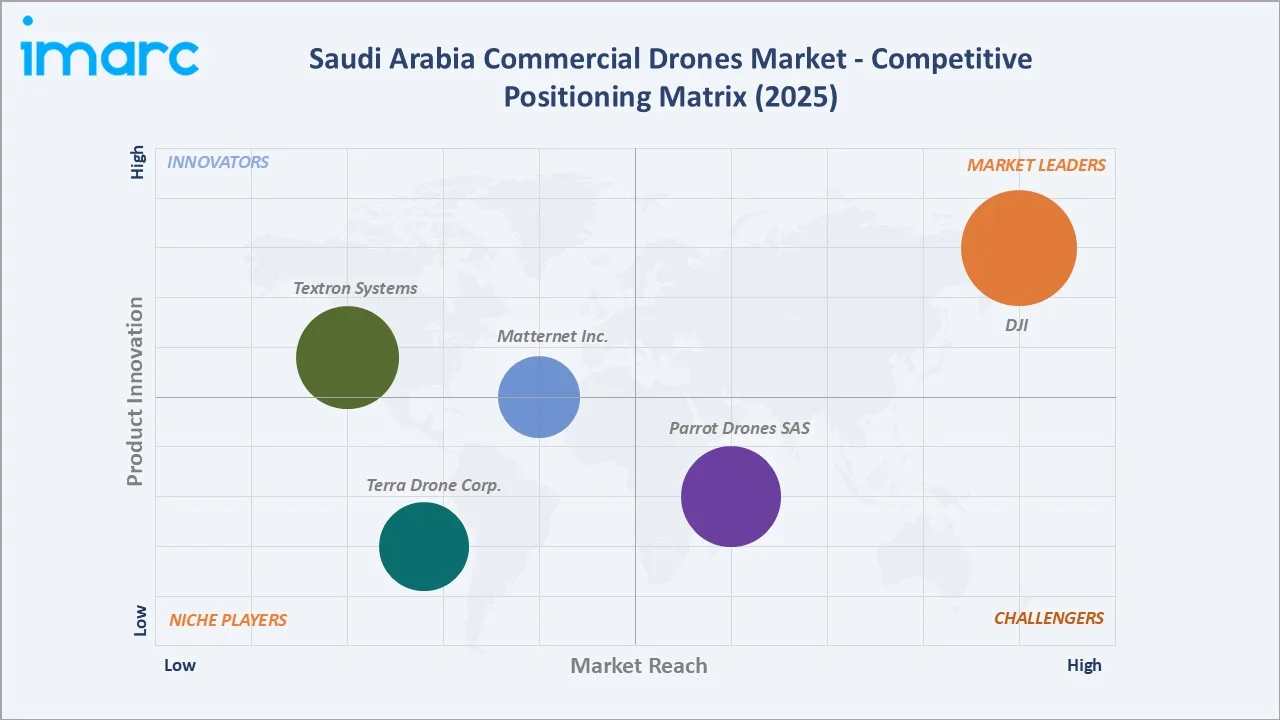
The Saudi Arabia commercial drones market competitive landscape is moderately fragmented, with global hardware leaders dominating alongside specialized service operators entering through regulatory milestones and strategic partnerships with Saudi entities.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
DJI |
LITO Series, MAVIC 4 PRO, MINI 5 PRO, AVATA 360, NEO 2 |
Market Leader |
Leading global drone manufacturer with the widest product portfolio spanning consumer, enterprise, and industrial applications. |
|
Parrot Drones SAS |
ANAFI USA, ANAFI AI, ANAFI UKR |
Strong Challenger |
European drone specialist focused on secure, AI-powered platforms for enterprise, defense, and inspection use cases. |
|
Textron Systems |
Aerosonde, Shadow UAV |
Established Player |
Defense and industrial UAV provider offering integrated surveillance, reconnaissance, and commercial drone systems. |
|
Terra Drone Corp. |
Industrial Inspection Drones, UTM |
Niche Player |
Drone services and technology company specializing in industrial inspection, survey, and unmanned traffic management solutions. |
|
Matternet Inc. |
M2 Drone Delivery System |
Emerging Player |
Urban drone delivery pioneer offering autonomous last-mile delivery solutions for healthcare and logistics sectors. |
Key players include DJI, Parrot Drones SAS, Textron Systems, Terra Drone Corp., Matternet Inc., and others.
Key Company Profiles
DJI
DJI is a China-based global leader in consumer and commercial drone manufacturing with a dominant market presence in the Saudi Arabia commercial drones’ market through its Matrice industrial series and Phantom professional platforms designed for enterprise-grade aerial operations.
- Key Products: LITO Series, MAVIC 4 PRO, MINI 5 PRO, AVATA 360, NEO 2
- Strategic Focus: Expanding AI-integrated industrial drone platforms for infrastructure inspection, precision agriculture, and mapping applications aligned with Saudi Arabia's Vision 2030 infrastructure priorities. The company is investing in specialized technical support infrastructure across GCC markets to maintain its dominant commercial hardware position and drive enterprise adoption of its latest Matrice enterprise platform across key Saudi sectors.
Parrot Drones SAS
Parrot Drones SAS is a France-based commercial drone manufacturer with a growing presence in the Saudi Arabia market through AI-powered inspection and mapping drone solutions designed for professional operators and enterprise clients requiring European-manufactured drone hardware for sensitive government and energy applications.
- Key Products: ANAFI USA, ANAFI AI, ANAFI UKR
- Strategic Focus: Developing AI-native drone platforms for enterprise inspection, mapping, and surveillance, targeting high-value industrial clients across Saudi Arabia's energy and infrastructure sectors. The company's strategic emphasis on data security and European manufacturing origin addresses growing government and enterprise sensitivity around data sovereignty, positioning Parrot as a preferred alternative in security-sensitive commercial applications.
Market Concentration Analysis
The Saudi Arabia commercial drones market is moderately fragmented at the hardware level, with the key players holding significant commercial share through their broad product portfolio and established enterprise partnerships. Specialized services are establishing distinct niches through regulatory certifications and strategic Saudi entity partnerships.
Market concentration is expected to moderate as Saudi Arabia's localization agenda under Vision 2030 incentivizes domestic drone manufacturing investment, creating opportunities for regional players to establish competitive positions alongside global technology leaders across the rapidly expanding commercial drone ecosystem.
Investment & Growth Opportunities
Highest Growth Segments
Inspection and maintenance (~32% CAGR), mapping and surveying (~31% CAGR), <2 Kg commercial drone platforms (~31% CAGR), BVLOS-certified operators, and AI-powered autonomous drone platforms represent the highest commercial growth opportunities through 2034 in Saudi Arabia's expanding drone market.
Emerging Investment Opportunities
BVLOS drone infrastructure development, including command-and-control networks and UTM systems, represents the Saudi commercial drone market's most critical enabling investment. Healthcare and emergency response drone delivery, validated by the 2025 Hajj medicine delivery pilot, signals an institutional market with significant scaling potential across Saudi Arabia's healthcare and emergency management sectors.
Investment Themes
- Drone localization manufacturing aligned with Vision 2030 industrial development goals: reducing Saudi Arabia's dependence on imported commercial drone hardware and creating domestic aerospace manufacturing capacity for the Kingdom's expanding commercial drone ecosystem.
- AI and analytics platform investment enabling autonomous drone inspection: real-time data analysis, and predictive maintenance across Saudi Arabia's extensive oil and gas infrastructure, construction sites, and smart city environments through the 2034 forecast period.
Future Market Outlook (2026-2034)
The Saudi Arabia commercial drones market is projected to grow from USD 388.5 Million in 2025 to USD 4,541.5 Million by 2034, delivering a 30.47% CAGR and passing through USD 1,468.8 Million by 2030. This represents one of the highest commercial drone market growth rates among emerging global drone markets.
Three structural forces define market growth through 2034: Vision 2030's infrastructure investment pipeline sustaining drone demand across giga-projects, oil and gas sector digital transformation creating institutional aerial inspection markets, and GACA's progressive regulatory evolution enabling BVLOS and urban air mobility operations at commercial scale across Saudi Arabia.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders (2025), including GACA regulatory officials, Vision 2030 project managers, oil and gas drone procurement leads, commercial drone service operators, and agricultural technology specialists across Saudi Arabia's key commercial regions.
Secondary Research
Secondary research encompassed GACA regulatory publications, Saudi Aramco annual reports, Vision 2030 project documentation, industry association reports from AUVSI and GUTMA, company press releases and investor presentations, and trade data from Saudi Arabia's commerce and investment authorities covering the historical period 2020-2025.
Forecasting Models
Market revenue forecasts developed using a sector-based bottom-up model incorporating: (i) drone unit shipment estimates by weight class and application segment, (ii) average selling price trend analysis by product category, (iii) commercial service revenue estimation from drone-as-a-service operators, and (iv) regulatory milestone impact assessments on adoption timing across all commercial drone segments.
Saudi Arabia Commercial Drones Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Systems Covered |
|
| Products Covered | Fixed Wing, Rotary Blade, Hybrid |
| Mode of Operations Covered | Remotely Operated, Semi-Autonomous, Autonomous |
| Weights Covered | <2 Kg, 2 Kg-25 Kg, 25 Kg-150 Kg |
| Applications Covered | Filming and Photography, Inspection and Maintenance, Mapping and Surveying, Precision Agriculture, Surveillance and Monitoring, Others |
| End Users Covered | Agriculture, Delivery and Logistics, Energy, Media and Entertainment, Real Estate and Construction, Security and Law Enforcement, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | DJI, Parrot Drones SAS, Textron Systems, Terra Drone Corp., Matternet Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia commercial drones market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia commercial drones market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia commercial drones industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Commercial Drones Market Report
The Saudi Arabia commercial drones market reached USD 388.5 Million in 2025, driven by inspection and maintenance application at 24.7%, the <2 Kg weight segment at 46.8%, and the Northern and Central Region at 36.5%. The market expanded from USD 102.7 Million in 2020, reflecting a strong five-year historical growth trajectory.
The market grows at a CAGR of 30.47% during 2026-2034, reaching USD 4,541.5 Million by 2034. This growth reflects Vision 2030 infrastructure investment, oil and gas sector digital transformation, AI integration, and GACA's progressive regulatory framework enabling expanded commercial drone operations across Saudi Arabia.
The <2 Kg segment leads at 46.8%, capturing the broadest commercial application range across mapping, filming, inspection, and monitoring use cases. This segment benefits from lower regulatory barriers and accessible pricing enabling wide multi-sector deployment across SME and enterprise operators throughout the Kingdom.
Inspection and maintenance leads at 24.7% through Saudi Arabia's extensive oil and gas infrastructure monitoring requirements, with mapping and surveying at 21.6% driven by giga-project planning and geospatial data demand across NEOM, The Red Sea Project, and Qiddiya construction activities.
The Northern and Central Region leads at 36.5% through Riyadh's concentration of government procurement, commercial drone operators, and Vision 2030 mega-project activity. The Western Region at 30.4% and Eastern Region at 21.8% follow as key commercial hubs anchored by logistics, tourism, and oil and gas industry demand.
Leading companies include DJI, Parrot Drones SAS, Textron Systems, Terra Drone Corp., Matternet Inc., and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade