Saudi Arabia Farm Implements Market Size, Share, Trends and Forecast by Type, Application, and Region, 2026-2034
Saudi Arabia Farm Implements Market Size, Share, Trends & Forecast (2026-2034)
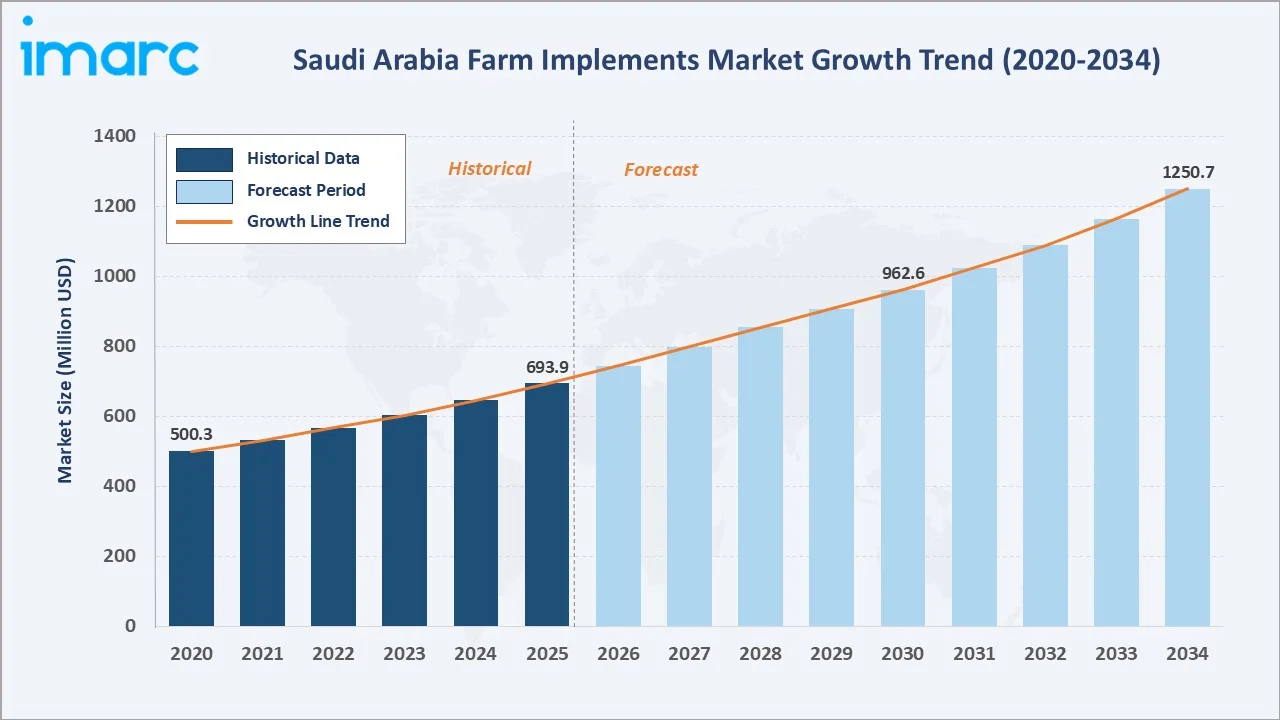
The Saudi Arabia farm implements market was valued at USD 693.9 Million in 2025 and is projected to reach USD 1,250.7 Million by 2034, exhibiting a CAGR of 6.76% during 2026-2034. Rising food security initiatives, expanding irrigation infrastructure, and the shift from manual to mechanized farming operations are the primary drivers shaping market growth.
Sprayers lead the type segment at 28.7%, plant protection and fertilizing commands 30.6% of application share, and Northern and Central Region holds the largest regional share at 37.2%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 693.9 Million |
|
Forecast Market Size (2034) |
USD 1,250.7 Million |
|
CAGR (2026-2034) |
6.76% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern and Central Region (37.2%, 2025) |
|
Second Largest Region |
Western Region (26.8%, 2025) |
|
Leading Type |
Sprayers (28.7%, 2025) |
|
Leading Application |
Plant Protection and Fertilizing (30.6%, 2025) |
The Saudi Arabia farm implements market expanded from USD 500.3 Million in 2020 to USD 693.9 Million in 2025, supported by widening adoption of sprayers and cultivators, growing mechanization of cereal and vegetable cultivation, and government-led agricultural investment programs under Vision 2030. Anchored at USD 962.6 Million in 2030, the forecast to USD 1,250.7 Million by 2034 is supported by accelerating adoption of precision agriculture tools, expanding smart irrigation-linked implement usage, and a more favorable regulatory environment for agricultural equipment imports.
To get more information on this market, Request Sample
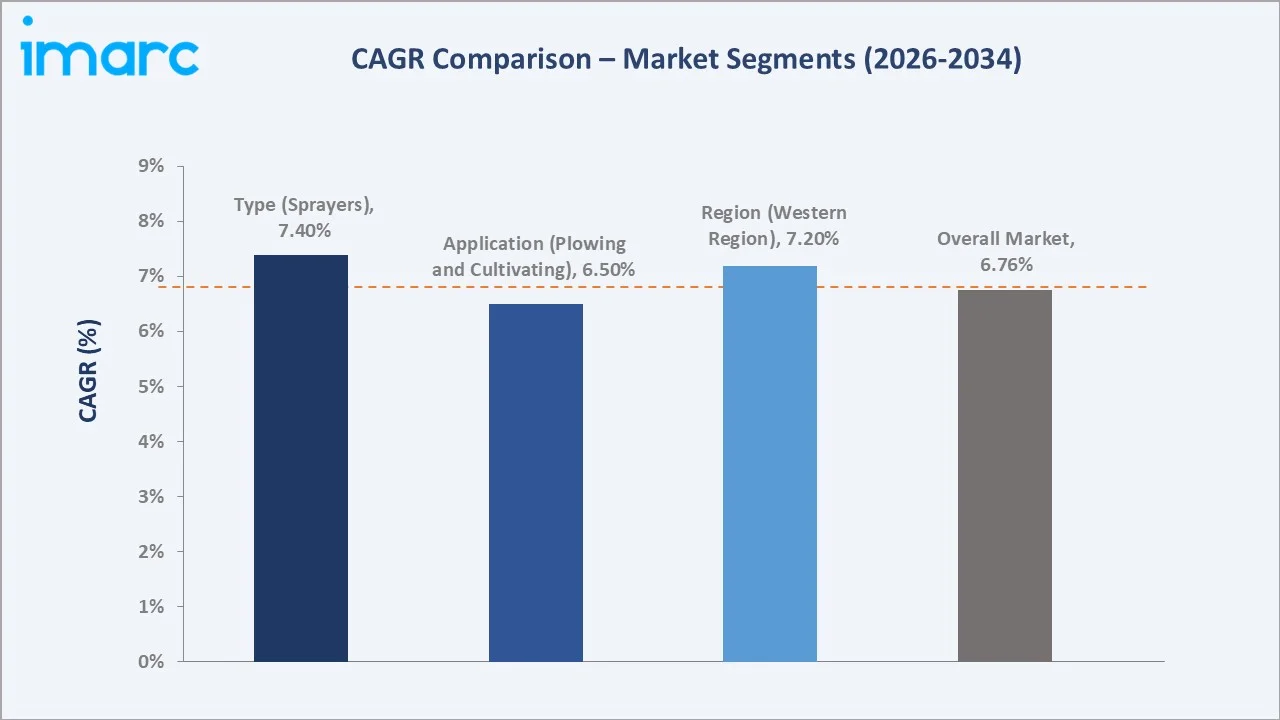
CAGR trajectories across type and application sub-segments, together with regional patterns, show Western Region and sprayers expanding faster than the overall 6.76% market CAGR, driven by rising agri-tech investments, growing adoption of precision farming, and increasing non-traditional crop cultivation in irrigated regions.
Executive Summary
The Saudi Arabia farm implements market is on a steady growth trajectory, rising from USD 500.3 Million in 2020 to USD 1,250.7 Million by 2034. The market has evolved from basic tractor-mounted tools to a sophisticated ecosystem of precision-engineered sprayers, seed drills, cultivators, and threshers that support large-scale cereal, date, and vegetable cultivation across the Kingdom.
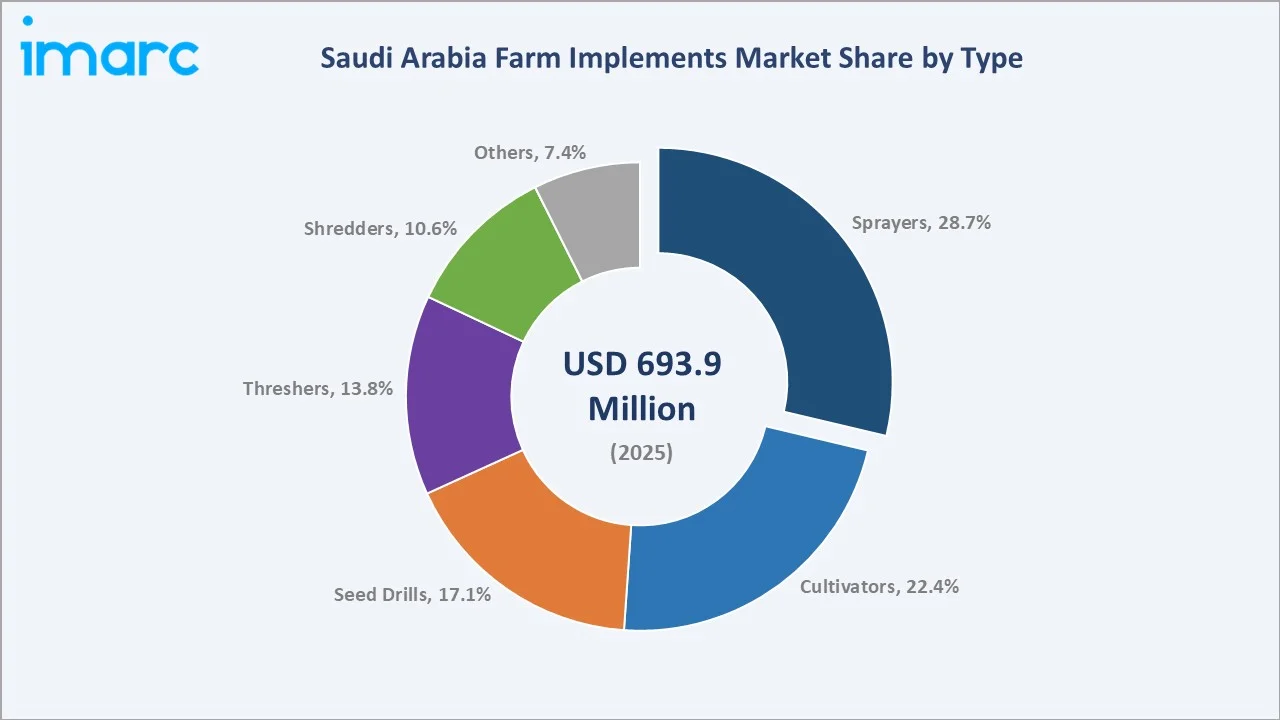
Sprayers lead the type segment at 28.7% in 2025, supported by high-frequency pest control and fertilizer application across cereal and horticulture operations. Plant protection and fertilizing commands the largest application share at 30.6%, fueled by increasing crop protection needs and the adoption of mechanized farming practices. Northern and Central Region commands 37.2% of regional share, anchored by the Kingdom's primary grain-producing corridors and active agri-investment projects.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Sprayers - 28.7% share (2025) |
|
Second Largest Type |
Cultivators - 22.4% share (2025) |
|
Leading Application |
Plant Protection and Fertilizing - 30.6% share (2025) |
|
Second Largest Application |
Plowing and Cultivating - 26.8% share (2025) |
|
Leading Region |
Northern and Central Region - 37.2% share (2025) |
|
Second Largest Region |
Western Region - 26.8% share (2025) |
|
Top Companies |
AGCO Corporation, Deere & Company, CNH Industrial N.V., Kubota Corporation, YANMAR HOLDINGS CO., LTD. |
Key Analytical Observations Expanding On the Data Above:
- Sprayers leadership at 28.7% is driven by the high-frequency need for crop protection and precision fertilizer application across Saudi Arabia's irrigated cereal and horticulture zones, where chemical use per hectare continues to rise with growing cultivation intensity.
- Cultivators share at 22.4% reflects strong demand from dryland and irrigated farms for soil preparation equipment ahead of each planting cycle, particularly across wheat, barley, and date palm plantations.
- Plant protection and fertilizing at 30.6% is supported by government-mandated integrated pest management programs and precision fertilizer application initiatives across large-scale farming operations.
- Plowing and cultivating at 26.8% remains the second-largest application category, underpinned by expanding area under cultivation and growing mechanization of soil preparation activities across the Kingdom.
- Northern and Central Region at 37.2% leads regional share, anchored by major cereal-producing corridors around Al-Qassim and Ha'il, where state-supported irrigation projects and farm mechanization programs are most active.
Saudi Arabia Farm Implements Market Overview
Farm implements refer to the broad category of equipment attached to or drawn by tractors and other prime movers to perform specific agricultural tasks, including soil preparation, seeding, crop protection, and harvesting. The Saudi Arabia market encompasses sprayers, cultivators, seed drills, threshers, shredders, and related equipment used across cereal, horticulture, date palm, and vegetable production systems.
The market ecosystem integrates raw material and steel suppliers, global and regional equipment manufacturers, import and distribution channels, authorized dealerships, government agricultural agencies, and end users spanning commercial farms, smallholders, and cooperative farming enterprises. Together, they support the delivery, financing, and after-sales servicing of a growing implement base across the Kingdom's diverse agri-climatic zones.
Market Dynamics
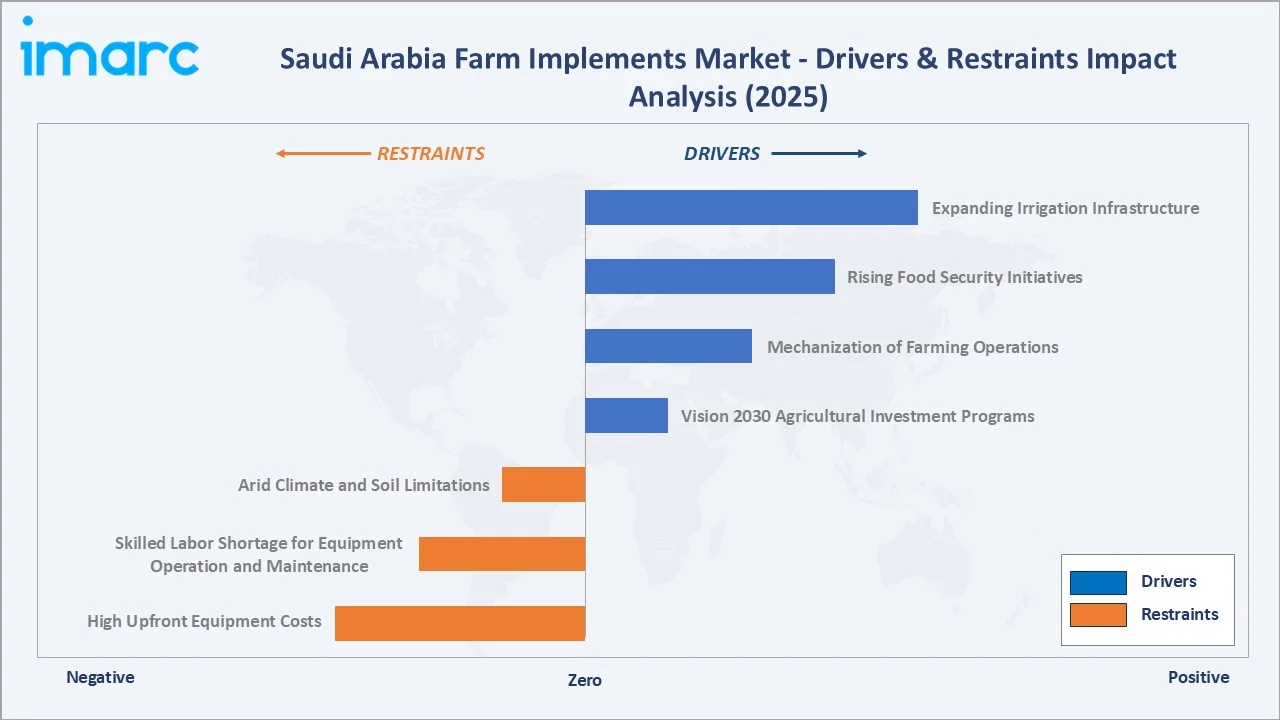
To evaluate market opportunities, Request Sample
Market Drivers
- Vision 2030 Agricultural Investment Programs: Government-led initiatives under Vision 2030 are channeling substantial public capital into farm mechanization, irrigation infrastructure, and agricultural productivity programs, directly expanding the addressable market for implement suppliers and dealerships across the Kingdom.
- Mechanization of Farming Operations: Growing recognition among Saudi farmers and agri-enterprises of the productivity and cost advantages of mechanized implement use over manual and semi-mechanized methods is accelerating adoption across cereal, horticulture, and date palm cultivation segments.
- Rising Food Security Initiatives: Population growth and rising food demand are encouraging the government to strengthen domestic agricultural production and improve food security, supporting investment in modern farming practices and farm implements. As per Macrotrends, the total population of Saudi Arabia in 2025 was 37,989,969, marking a 1.38% rise from 2024.
- Expanding Irrigation Infrastructure: Continued development of drip and center-pivot irrigation networks is enabling year-round crop production across arid regions, creating sustained demand for soil preparation, seeding, and protection implements across previously uncultivated land.
Market Restraints
- High Upfront Equipment Costs: The significant capital investment required for modern farm implements remains a barrier for smallholder and subsistence farmers in Saudi Arabia, slowing the pace of adoption outside large-scale commercial operations.
- Skilled Labor Shortage for Equipment Operation and Maintenance: A limited supply of trained tractor operators and equipment technicians in rural and semi-urban agricultural areas constrains effective implement utilization and increases breakdown-related productivity losses.
- Arid Climate and Soil Limitations: Saudi Arabia's predominantly arid and rocky terrain in certain regions reduces the effectiveness of standard implement designs, requiring specialized adaptations that add cost and limit the range of equipment that can be profitably deployed.
Market Opportunities
- Precision Agriculture and Smart Implement Integration: Growing interest in GPS-guided seeding, variable-rate spraying, and sensor-enabled soil management is creating demand for next-generation implement solutions that deliver measurable productivity and resource efficiency gains.
- Expansion of Contract Farming and Agri-Enterprise Models: Rising adoption of corporate farming structures and cooperative agri-enterprise models is driving bulk equipment procurement and creating opportunities for long-term implement supply and service partnerships.
Market Challenges
- Dependence on Imported Equipment and Components: The Saudi Arabia farm implements market is significantly reliant on imported products, exposing buyers and distributors to currency fluctuations, supply chain disruptions, and import duty variability that can affect equipment availability and pricing.
- Seasonal Demand Concentration: Implement demand in Saudi Arabia is concentrated around key planting and harvesting windows, creating inventory management challenges for dealers and cash flow pressures for smaller market participants outside peak seasons.
Emerging Market Trends
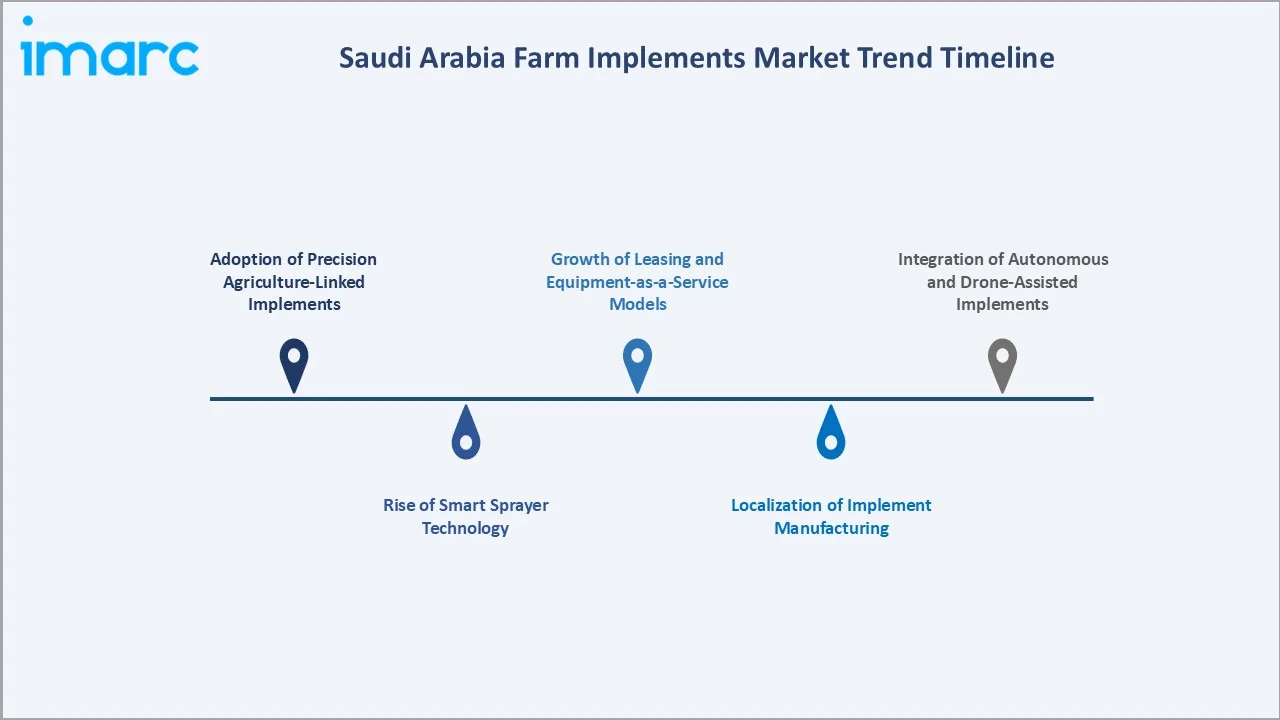
1. Adoption of Precision Agriculture-Linked Implements
Farmers and agri-enterprises across Saudi Arabia are increasingly investing in GPS-enabled seed drills, variable-rate sprayers, and sensor-integrated cultivators that reduce input waste and improve yield consistency. This trend is being accelerated by government-supported digital farming programs and the growing commercial viability of precision agri-technology solutions in the Kingdom.
2. Rise of Smart Sprayer Technology
AI-powered and IoT-connected sprayers capable of real-time crop detection and targeted chemical application are gaining traction in Saudi Arabia's large-scale cereal and horticulture operations. These systems improve application accuracy while reducing chemical use and operational costs.
3. Localization of Implement Manufacturing
Saudi Arabia's Vision 2030 industrial localization agenda is encouraging global implement manufacturers to establish local assembly, customization, and after-sales service operations within the Kingdom. This shift is improving equipment availability, reducing lead times, and creating opportunities for domestic supply chain development.
4. Growth of Leasing and Equipment-as-a-Service Models
Implement leasing and service-based procurement models are gaining adoption among smallholder and mid-scale farmers who face capital constraints but require access to modern equipment. Agricultural cooperatives and equipment dealers are increasingly offering flexible financing and lease arrangements to expand their customer base.
5. Integration of Autonomous and Drone-Assisted Implements
Pilot programs using autonomous tractors, drone-mounted sprayers, and remote-controlled seeding implements are emerging across large commercial farms in Saudi Arabia's key agricultural regions. These technologies are expected to move toward wider commercial adoption by 2030 as operational costs decline and regulatory frameworks mature.
Industry Value Chain Analysis
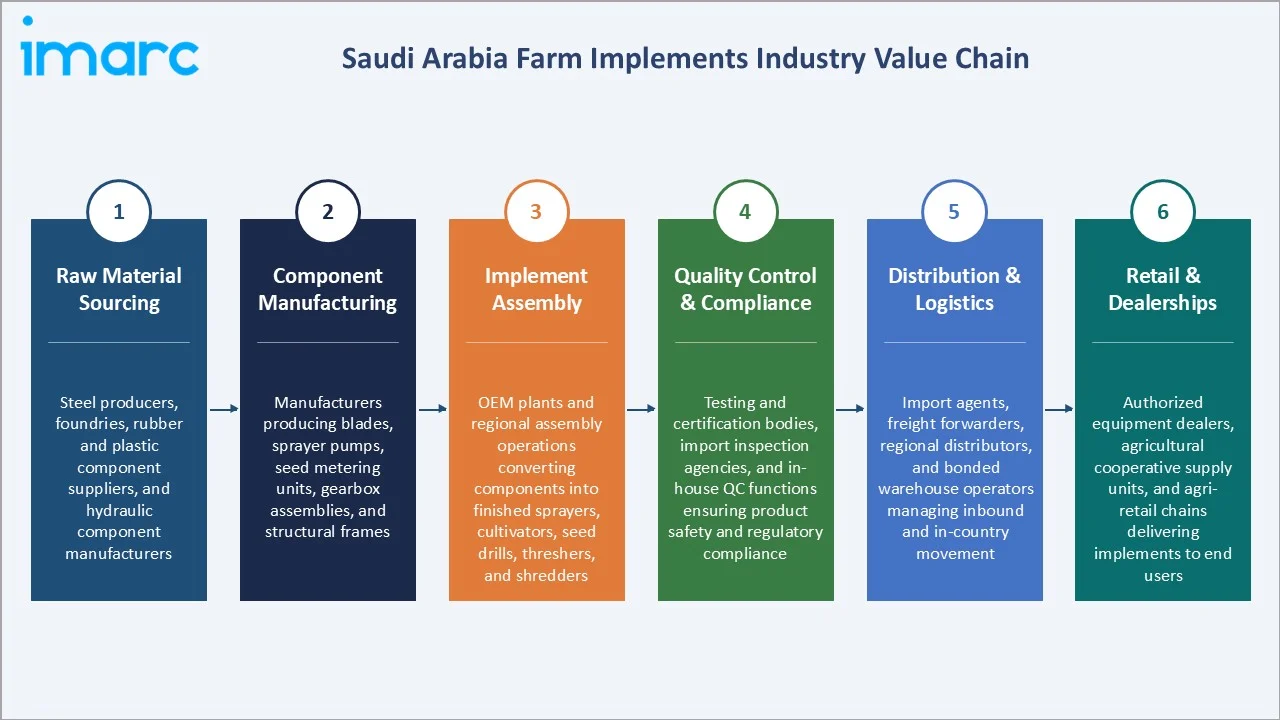
The Saudi Arabia farm implements value chain spans six stages, from raw material sourcing and component manufacturing through end-user deployment and after-sales service. Assembly, distribution, and retail dealerships capture significant value-add in the Saudi context, where import-based supply chains and specialized dealer networks are the dominant go-to-market model for international implement brands.
|
Stage |
Key Players / Examples |
| Raw Material Sourcing | Steel producers, foundries, rubber and plastic component suppliers, and hydraulic component manufacturers providing inputs to implement production facilities |
| Component Manufacturing | Manufacturers producing blades, sprayer pumps, seed metering units, gearbox assemblies, and structural frames used across implement product categories |
| Implement Assembly | OEM plants and regional assembly operations converting components into finished sprayers, cultivators, seed drills, threshers, and shredders |
| Quality Control & Compliance | Testing and certification bodies, import inspection agencies, and in-house QC functions ensuring product safety and regulatory compliance |
| Distribution & Logistics | Import agents, freight forwarders, regional distributors, and bonded warehouse operators managing inbound and in-country movement of equipment |
| Retail & Dealerships | Authorized equipment dealers, agricultural cooperative supply units, and agri-retail chains delivering implements to end users with financing and after-sales support |
Vertically integrated international manufacturers with direct dealer partnerships in Saudi Arabia are positioned to capture greater value than those relying on multi-tier distribution chains, given the importance of after-sales service quality and parts availability in sustaining long-term customer relationships in this market.
Technology Landscape in the Saudi Arabia Farm Implements Industry
Precision Agriculture and GPS-Guided Implement Systems
GPS and RTK-guided implement systems are being adopted across large Saudi commercial farms to enable precise row alignment for seeding, uniform soil preparation, and targeted application of inputs, reducing overlap, minimizing waste, and improving field efficiency.
IoT Sensors and Telematics
Farm implements are increasingly equipped with embedded sensors and telematics units that transmit real-time performance data to farm management platforms, enabling remote diagnostics, predictive maintenance scheduling, and data-driven implement utilization optimization across multi-field operations.
Smart Sprayer and Variable-Rate Application Technology
Variable-rate application systems integrated into sprayers and fertilizer broadcasters allow operators to adjust input delivery rates based on soil maps and crop condition data, improving agronomic outcomes and reducing chemical input costs across high-value horticulture and cereal operations.
Automation and Robotics in Implement Design
Emerging implement designs incorporating robotic actuation, automated depth control, and autonomous guidance systems are being piloted on large commercial farms in Saudi Arabia, with broader adoption expected as technology costs decline and agronomic outcomes are validated across a range of soil and crop types present in the Kingdom.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Sprayers |
28.7% |
2025 |
|
Application |
Plant Protection and Fertilizing |
30.6% |
2025 |
|
Region |
Northern and Central Region |
37.2% |
2025 |

By Type
Sprayers command a 28.7% majority share in 2025, driven by the high-frequency application of pesticides, herbicides, and liquid fertilizers across cereal, vegetable, and date palm operations in Saudi Arabia. Growing use of boom sprayers, airblast sprayers, and precision drone sprayers across commercial farms is reinforcing segment leadership.
To access detailed market analysis, Request Sample
Cultivators hold 22.4% share in 2025, supported by broad demand for primary and secondary tillage equipment across wheat, barley, and vegetable cultivation zones.
By Application
Plant protection and fertilizing lead the application segment at 30.6% in 2025, supported by the high input-intensity nature of Saudi Arabia's irrigated crop production and the growing adoption of integrated pest management approaches that rely on regular and precise chemical application schedules.
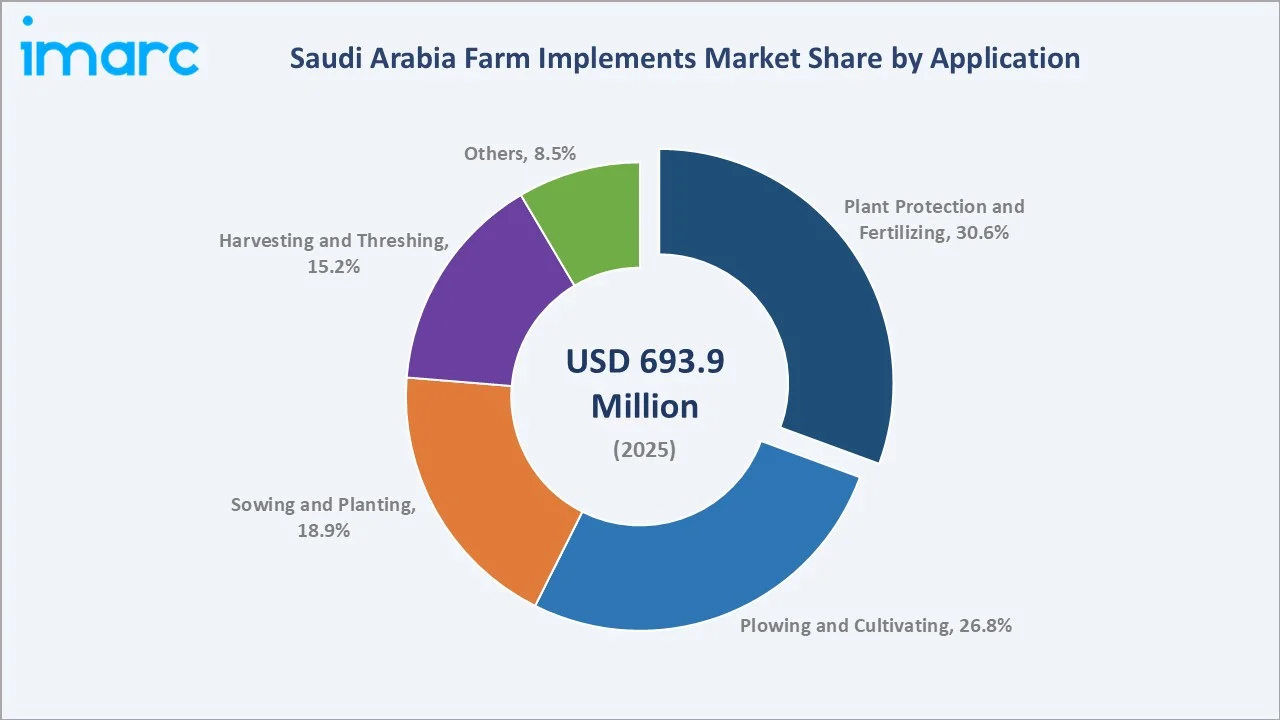
Plowing and cultivating at 26.8% reflects sustained demand for soil preparation equipment across primary and secondary tillage operations ahead of each planting cycle.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
37.2% |
Concentration of major grain-producing zones, active government irrigation and farm mechanization projects, and proximity to key agricultural research and extension services |
|
Western Region |
26.8% |
Expanding horticulture and vegetable cultivation, growing agri-enterprise investment, and rising adoption of precision farming tools in Makkah and Madinah agricultural corridors |
|
Eastern Region |
22.5% |
Presence of large commercial date palm and cereal operations, expanding agri-infrastructure investment, and growing corporate farming activity in Al-Ahsa |
|
Southern Region |
13.5% |
Diverse crop production including coffee, fruits, and vegetables in the Asir and Jizan highlands, growing demand for specialized implements suited to highland farming conditions |
Northern and Central Region at 37.2% in 2025 leads the regional landscape, anchored by Saudi Arabia's primary cereal-producing corridors in Al-Qassim and Ha'il. State-supported irrigation and farm mechanization programs are most active in these regions, sustaining robust demand for sprayers, cultivators, and seed drills.
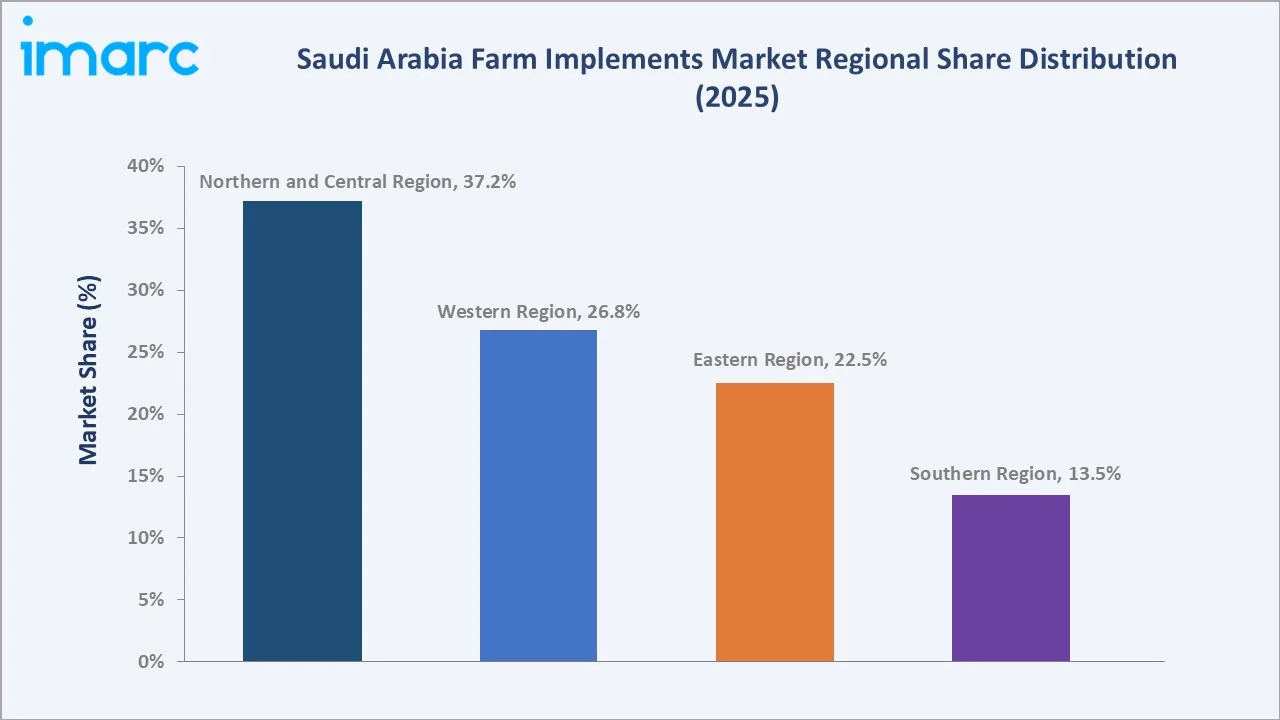
Southern Region, while currently the smallest contributor at 13.5%, offers growing potential as expanding road infrastructure, improved market access, and specialized implement availability open new cultivation areas in the Asir and Jizan highland farming zones.
Competitive Landscape
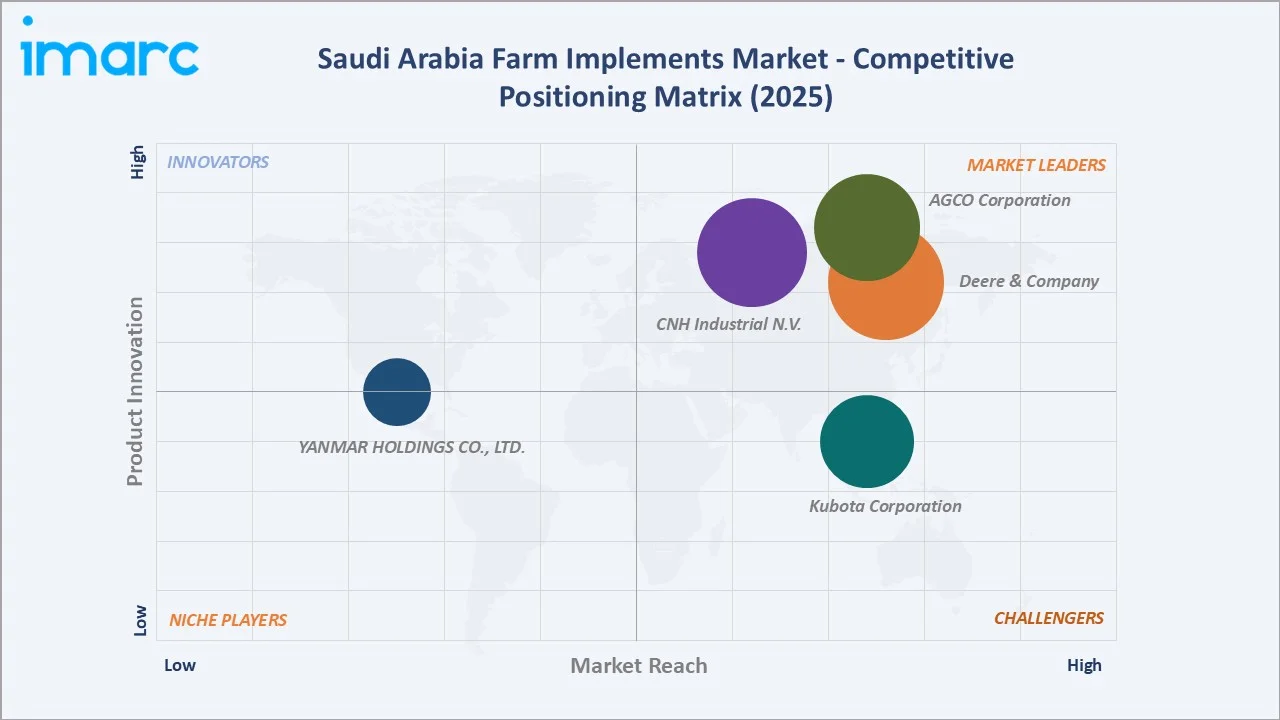
The Saudi Arabia farm implements market is moderately consolidated, with established global equipment manufacturers operating through authorized dealer networks and regional players competing on equipment localization, after-sales service depth, and value-for-money positioning. Product reliability, compatibility with Saudi Arabia's soil and climate conditions, and availability of parts and trained technicians form the key competitive differentiators across the market.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| AGCO Corporation | Fendt |
Leader |
Expanding premium implement portfolio and dealer network across major agri-regions in Saudi Arabia |
| Deere & Company | John Deere Farm Implements |
Leader |
Strengthening precision agriculture-linked implement offerings and growing service infrastructure across the Kingdom |
| CNH Industrial N.V. | Case IH | Leader | Growing presence in Saudi Arabia through expanded dealer partnerships and localized product adaptation |
| Kubota Corporation | Kverneland | Challenger | Expanding precision implement adoption across cereal and horticulture operations through the Kverneland Group subsidiary |
| YANMAR HOLDINGS CO., LTD. | Yanmar Tractors & Implements | Emerging | Growing compact tractor and implement adoption among smallholder and niche farming operations in the Kingdom |
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| AGCO Corporation | Fendt |
Leader |
Expanding premium implement portfolio and dealer network across major agri-regions in Saudi Arabia |
| Deere & Company | John Deere Farm Implements |
Leader |
Strengthening precision agriculture-linked implement offerings and growing service infrastructure across the Kingdom |
| CNH Industrial N.V. | Case IH | Leader | Growing presence in Saudi Arabia through expanded dealer partnerships and localized product adaptation |
| Kubota Corporation | Kverneland | Challenger | Expanding precision implement adoption across cereal and horticulture operations through the Kverneland Group subsidiary |
| YANMAR HOLDINGS CO., LTD. | Yanmar Tractors & Implements | Emerging | Growing compact tractor and implement adoption among smallholder and niche farming operations in the Kingdom |
Key players include AGCO Corporation, Deere & Company, CNH Industrial N.V., Kubota Corporation, and YANMAR HOLDINGS CO., LTD., among others.
Key Company Profiles
AGCO Corporation
AGCO Corporation is a global agricultural equipment manufacturer headquartered in Duluth, Georgia, United States. The company designs, manufactures, and distributes a broad portfolio of agricultural machinery and precision agriculture technology through its network of dealers and distributors worldwide.
- Product Portfolio: Farm implement portfolio marketed under the Fendt brand, serving cereal, horticulture, and specialty crop operations across global markets.
- Recent Developments: The company continues to expand its Fendt product and technology portfolio, with an emphasis on advanced agricultural machinery, precision farming solutions, and connected equipment.
- Strategic Focus: Broadening the implement range under the Fendt brand and deepening its authorized dealer reach across key farming regions in Saudi Arabia.
Deere & Company
Deere & Company is a global manufacturer of agricultural, construction, and forestry equipment headquartered in Moline, Illinois, United States. The company markets its agricultural products and implements globally under the John Deere brand through an extensive authorized dealer and distributor network.
- Product Portfolio: John Deere Farm Implements suited to a wide range of crop and soil types, designed to integrate seamlessly with John Deere tractor platforms across diverse farming operations.
- Recent Developments: Deere & Company continues to expand its precision agriculture capabilities, with ongoing investments in GPS-guided implement systems, autonomous tillage, and smart sprayer technology suited to large-scale commercial farm operations.
- Strategic Focus: Enhancing its technology-integrated implement lineup and reinforcing its service and support network for farm operators across the Kingdom.
CNH Industrial N.V.
CNH Industrial N.V. is a global leader in agricultural and construction equipment headquartered in Basildon, United Kingdom. The company designs, manufactures, and distributes agricultural machinery through its Case IH and New Holland Agriculture brands, serving farmers across several countries.
- Product Portfolio: Case IH agricultural implement range adapted for diverse crop and soil conditions across commercial and smallholder farming operations globally.
- Recent Developments: CNH Industrial N.V. continues to invest in expanding its dealer network and introduce locally adapted product configurations across Middle East and African markets, improving equipment availability and after-sales service depth.
- Strategic Focus: Strengthening its on-ground presence in Saudi Arabia by building closer dealer relationships and tailoring its product offering to local farming requirements.
Market Concentration Analysis
The Saudi Arabia farm implements market is moderately consolidated, with the top players accounting for a significant share of total equipment procurement across commercial farms, government agricultural projects, and dealer networks. Global manufacturers with established Saudi Arabian distributor relationships hold structural advantages in product availability, financing partnerships, and after-sales service coverage.
Barriers to entry include the need for established dealer and service networks across geographically dispersed agricultural regions, familiarity with import regulations and standards compliance requirements, and the scale required to offer competitive financing and warranty programs. These factors favor established players with proven market presence and existing relationships with Saudi agricultural enterprises and government procurement agencies.
Consolidation is gradually increasing as global agricultural equipment manufacturers invest in dealer network strengthening and local after-sales capability development. Strategic partnerships between implement manufacturers, local dealers, and Saudi agricultural cooperatives are further shaping competitive positioning in this market.
Investment & Growth Opportunities
Fastest-Growing Segments
Sprayers are expanding the fastest within the type segment, driven by rising demand for precision chemical application across cereal and horticulture operations. Plant protection and fertilizing grow consistently, as input-intensity increases across commercial farming operations.
Emerging Markets
Western Region is the fastest growing regional market, supported by expanding agri-enterprise investment in Makkah and Madinah agricultural corridors, growing horticulture and vegetable cultivation, and rising adoption of precision farming tools. Southern Region offers significant untapped potential as infrastructure investment opens highland farming areas to greater mechanization.
Venture & Investment Trends
Investment activity is concentrated in precision agriculture-integrated implement solutions, smart sprayer technology, and IoT-enabled farm implement management platforms. Capital is also flowing into local manufacturing and assembly capacity development under Vision 2030's industrial localization program, and into agri-fintech solutions that make equipment financing more accessible to smallholder and mid-scale farm operators.
Future Market Outlook (2026-2034)
The Saudi Arabia farm implements market is forecast to expand from USD 693.9 Million in 2025 to USD 1,250.7 Million by 2034 at a CAGR of 6.76%, adding roughly USD 556.8 Million in incremental market value over the forecast period.
Four forces will shape the market through 2034: continued government investment in agricultural mechanization under Vision 2030; deeper integration of precision agriculture technology across implement categories; expansion of locally assembled and customized implement solutions; and growing adoption of leasing and service-based procurement models that widen the addressable farmer base.
By 2034, the Saudi Arabia farm implements market is expected to be defined by precision-enabled, IoT-connected equipment across all major product categories, with locally assembled products accounting for a growing share of total market supply. Continued regulatory support for food security investment and agricultural modernization is expected to further accelerate the evolution of the farm implements ecosystem through the forecast period.
Research Methodology
Primary Research
Primary research included structured interviews with farm equipment dealers, agri-enterprise procurement managers, agricultural cooperative representatives, and industry specialists in Saudi Arabia, validating market sizing, segment mix, and regional demand patterns.
Secondary Research
Secondary sources included Saudi Ministry of Environment, Water and Agriculture publications, Agricultural Development Fund annual reports, Saudi General Authority for Statistics data, and annual reports and press releases from leading agricultural equipment manufacturers and distributors active in the Saudi Arabia market.
Forecasting Models
Market forecasts used top-down and bottom-up models combining implement sales volume trends, agricultural area under cultivation data, mechanization rate estimates, and macroeconomic variables including government agricultural spending and food import dependency targets. Scenario analysis addressed policy developments, technology adoption pace, and infrastructure investment trends across Saudi Arabia's diverse agricultural regions.
Saudi Arabia Farm Implements Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Cultivators, Seed Drills, Threshers, Shredders, Sprayers, Others |
| Applications Covered | Plowing and Cultivating, Sowing and Planting, Plant Protection and Fertilizing, Harvesting and Threshing, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | AGCO Corporation, Deere & Company, CNH Industrial N.V., Kubota Corporation, YANMAR HOLDINGS CO., LTD., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia farm implements market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia farm implements market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia farm implements industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Farm Implements Market Report
The Saudi Arabia farm implements market was valued at USD 693.9 Million in 2025, driven by government-led agricultural mechanization programs, rising food security investments, and expanding irrigation infrastructure under Vision 2030.
The market is projected to grow at a CAGR of 6.76% from 2026 to 2034, reaching USD 1,250.7 Million, supported by accelerating mechanization adoption and precision agriculture integration.
Sprayers lead the type segment at 28.7% in 2025, driven by high-frequency pesticide, herbicide, and liquid fertilizer application across cereal, horticulture, and date palm operations.
Plant protection and fertilizing commands the largest application share at 30.6% in 2025, reflecting the high input-intensity nature of Saudi Arabia's irrigated commercial crop production and the widespread adoption of scheduled crop protection programs.
Northern and Central Region commands 37.2% share in 2025, anchored by the Kingdom's primary cereal-producing zones in Al-Qassim and Ha'il and active government farm mechanization programs.
Leading players include AGCO Corporation, Deere & Company, CNH Industrial N.V., Kubota Corporation, and YANMAR HOLDINGS CO., LTD., among others.
Precision agriculture tools including GPS-guided seed drills, variable-rate sprayers, and IoT-enabled implements are gaining adoption, improving input efficiency and yield consistency on commercial Saudi farms.
Key challenges include high upfront equipment costs for smallholders, dependence on imported products, a shortage of skilled operators and technicians, and seasonal demand concentration that creates inventory management pressures.
Key opportunities include smart implement technology adoption, expansion of leasing and equipment-as-a-service models, local manufacturing development under Vision 2030, and growing demand in the Western and Southern regions.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade