Saudi Arabia Luxury Interior Design Market Size, Share, Trends and Forecast by Type, Material, Style, Distribution Channel, Application, and Region, 2026-2034
Saudi Arabia Luxury Interior Design Market Size, Share, Trends & Forecast (2026-2034)
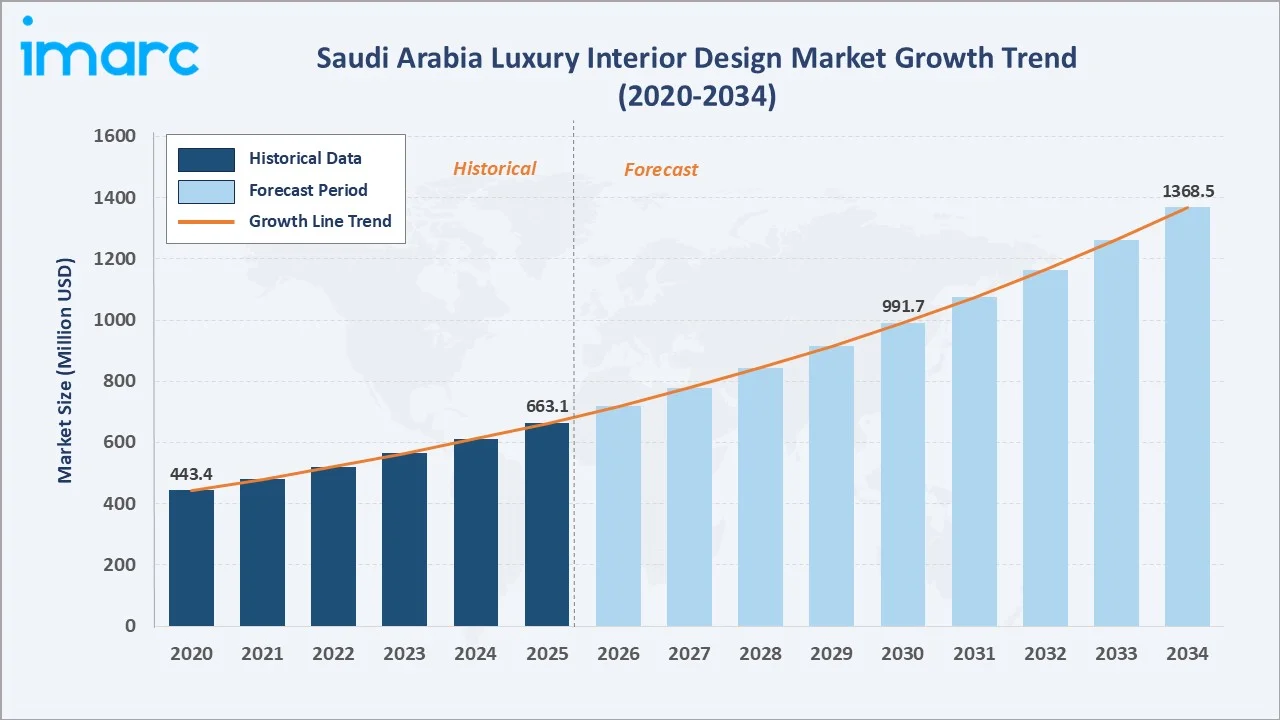
The Saudi Arabia luxury interior design market grew from USD 663.1 Million in 2025 to USD 718.7 Million in 2026 and is projected to reach USD 1,368.5 Million by 2034, exhibiting a CAGR of 8.38% during 2026-2034. The market is being driven by rising demand for premium residential and hospitality spaces, along with increasing investment in high-end real estate and luxury developments across the Kingdom.
Renovation leads the type segment at 42.6%, offline dominates distribution channel with 72.4% share, and Northern and Central Region holds a dominant 46.3% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 663.1 Million |
|
Market Size (2026) |
USD 718.7 Million |
|
Forecast Market Size (2034) |
USD 1,368.5 Million |
|
CAGR (2026-2034) |
8.38% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern and Central Region (46.3%, 2025) |
|
Second Largest Region |
Western Region (25.8%, 2025) |
|
Leading Type |
Renovation (42.6%, 2025) |
|
Leading Distribution Channel |
Offline (72.4%, 2025) |
The Saudi Arabia luxury interior design market size increased from USD 443.4 Million in 2020 to USD 663.1 Million in 2025 and is estimated to reach USD 718.7 Million in 2026. The market is further expected to grow to USD 991.7 Million by 2030 and USD 1,368.5 Million by 2034. The market is commercially distinguished by its integration of regional heritage with international luxury standards, combining a large high-net-worth residential renovation base and a growing recurring decorated segment among the Kingdom's ultra-high-net-worth clientele.
To get more information on this market, Request Sample
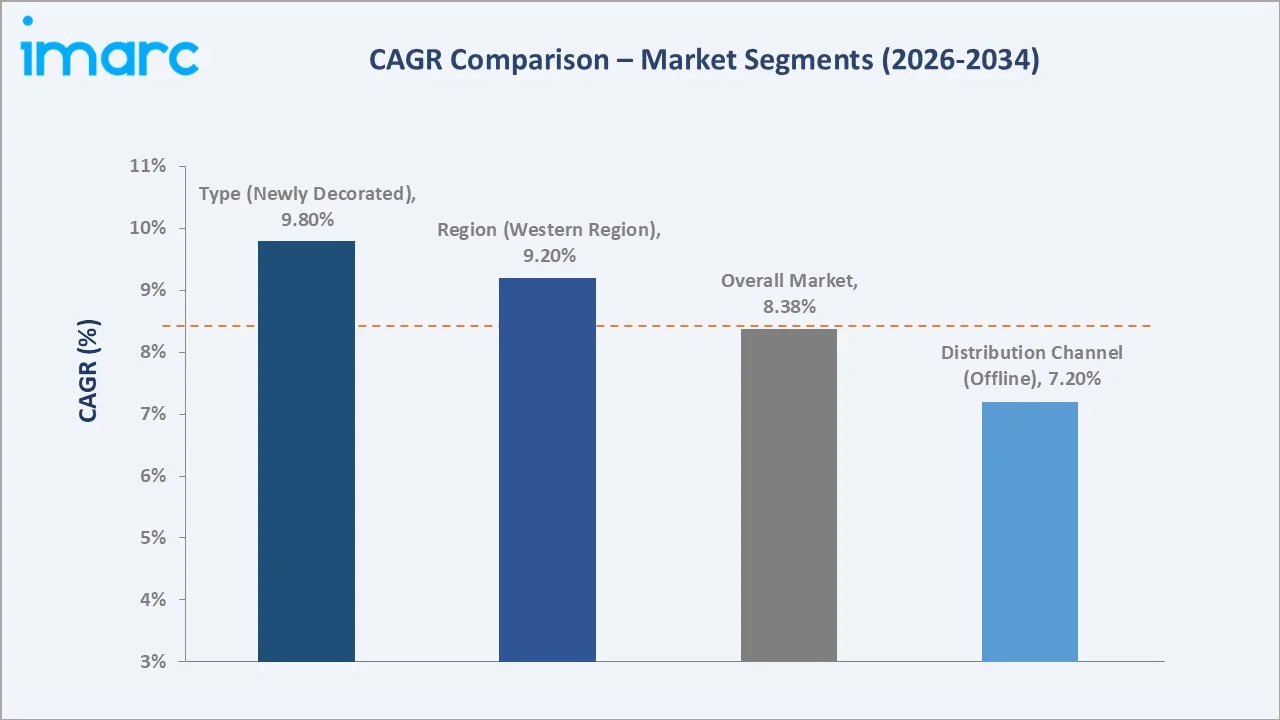
CAGR trajectories across type and distribution channel sub-segments, together with regional patterns, show online and newly decorated expanding faster than the overall 8.38% market CAGR, reflecting a broadening consumer and digital channel appetite for luxury interiors.
Executive Summary
The Saudi Arabia luxury interior design market expanded from USD 663.1 Million in 2025 to an estimated USD 718.7 Million in 2026. The industry has evolved from traditional craftsmanship-led engagements into a sophisticated ecosystem combining high-end design studios, premium imported materials, and technology-driven project delivery.
Renovation at 42.6% leads the type segment, driven by growing affluent homeowner upgrades. Offline retains 72.4% distribution share, reflecting the high-touch and consultation-intensive nature of luxury interior design engagements. Northern and Central Region commands 46.3% regional share, anchored by Riyadh's concentration of luxury residential towers, premium hospitality facilities, and royal-estate projects.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Renovation – 42.6% share (2025) |
|
Second Largest Type |
Newly Decorated – 35.8% share (2025) |
|
Leading Distribution Channel |
Offline – 72.4% share (2025) |
|
Second Largest Distribution Channel |
Online – 27.6% share (2025) |
|
Leading Region |
Northern and Central Region – 46.3% share (2025) |
|
Second Largest Region |
Western Region – 25.8% share (2025) |
|
Top Companies |
Depa PLC, Dar Al Riyadh, Havelock One Interiors, Dewan Architects + Engineers |
Key Analytical Observations Expanding On the Data Above:
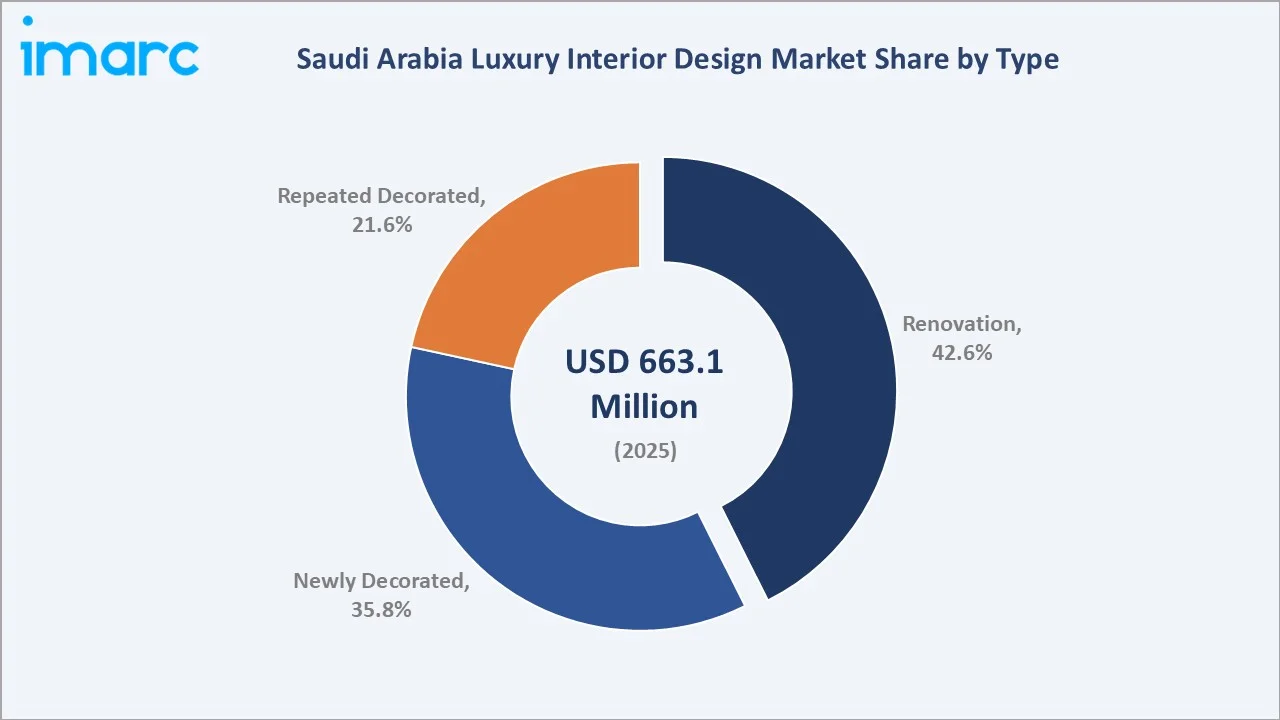
- Renovation dominance at 42.6% reflects the large base of aging luxury villas and apartments in Riyadh and Jeddah, where affluent owners are upgrading interiors to reflect evolving premium lifestyle aspirations.
- Newly decorated at 35.8% is supported by rapid new luxury residential development under Vision 2030 mega-projects such as NEOM, The Red Sea Project, and Diriyah Gate, where first-time luxury interior installations are occurring at scale.
- Offline leadership at 72.4% is driven by the high-touch, consultation-intensive nature of luxury interior design, where clients prefer in-person material selection, showroom visits, and bespoke design presentations.
- Online share at 27.6% reflects growing adoption of digital design consultations, virtual project presentations, online material catalogues, and remote collaboration tools, particularly among tech-savvy luxury consumers.
- Northern and Central Region at 46.3% reflects Riyadh's position as the Kingdom's administrative and commercial capital, hosting a high concentration of luxury residential towers, government buildings, and premium hospitality facilities.
Saudi Arabia Luxury Interior Design Market Overview
Luxury interior design refers to the planning, design, and execution of premium residential, commercial, and hospitality spaces using high-quality materials, bespoke furnishings, and skilled craftsmanship. It encompasses architecture-led interior design, custom furniture procurement, decorative lighting, flooring solutions, and specialized finishing services delivered to high-net-worth and ultra-high-net-worth clients.
The Saudi ecosystem integrates design studios, luxury material importers, skilled artisans, fit-out contractors, and regulatory bodies operating under the Saudi Council of Engineers and the Ministry of Municipal and Rural Affairs. Rising oil revenues, expanding expatriate populations, tourism investment under Vision 2030, and increased government spending on iconic buildings are key macroeconomic forces driving sustained demand.
Market Dynamics
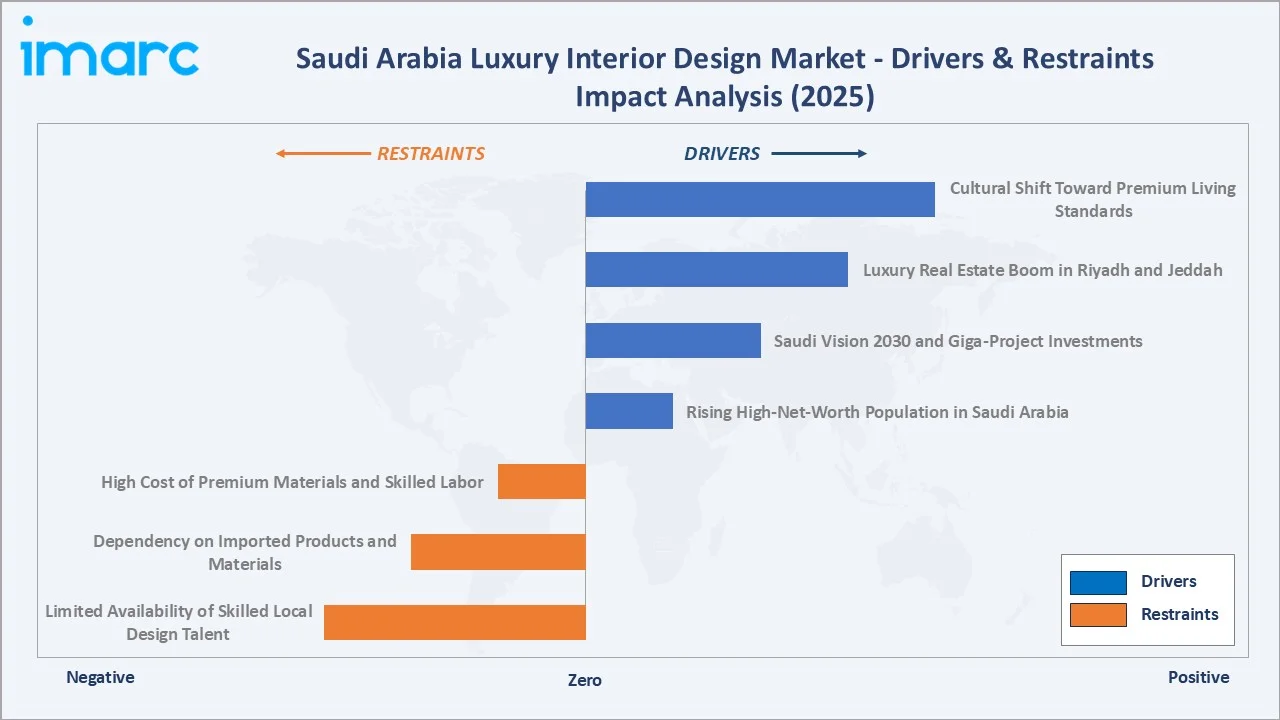
To evaluate market opportunities, Request Sample
Market Drivers
- Rising High-Net-Worth Population in Saudi Arabia: Growth in the Kingdom's high-net-worth and ultra-high-net-worth individual base is generating sustained demand for bespoke luxury interior design. This demographic is increasingly spending on private residences, investment properties, and hospitality assets that demand premium interior solutions.
- Saudi Vision 2030 and Giga-Project Investments: Landmark government-backed projects including NEOM, The Red Sea Project, Diriyah Gate, and Qiddiya are creating unprecedented demand for luxury interior design and fit-out services. Each project mandates world-class interior finishes, attracting international design firms and elevating quality benchmarks across the market.
- Luxury Real Estate Boom in Riyadh and Jeddah: Rapid development of premium residential compounds, branded residences, and five-star hotel properties across Riyadh and Jeddah is fueling high-volume demand for luxury interior solutions. In September 2026, Emaar Properties introduced three new ultra-luxury, high-rise projects in the Gulf region. The latest developments from the leading real estate firm would be located in the heart of Dubai Harbour, Diriyah in Riyadh, and Ras Al Khaimah.
- Cultural Shift Toward Premium Living Standards: Evolving lifestyle preferences among Saudi nationals and expatriates are driving demand for contemporary luxury interiors blending traditional Arabic design elements with modern aesthetics. Social media influence and international travel exposure are accelerating this shift toward premium home environments.
Market Restraints
- High Cost of Premium Materials and Skilled Labor: Luxury interior projects depend heavily on imported premium materials including Italian marble, European furniture, and custom-crafted decorative elements, which carry substantial import costs and longer procurement lead times.
- Dependency on Imported Products and Materials: The Kingdom's luxury interior design sector relies significantly on imports from Italy, France, and Spain for premium furnishings and finishing materials. Exchange rate volatility, global supply chain disruptions, and logistics costs can affect project timelines and cost structures.
- Limited Availability of Skilled Local Design Talent: A shortage of Saudi-national interior designers with international luxury design credentials constrains project delivery capacity and increases dependence on expatriate professionals, adding cost and regulatory complexity to staffing luxury design firms.
Market Opportunities
- Expansion of Luxury Hospitality and Tourism Infrastructure: Vision 2030's target of 150 Million annual visitors by 2030 is driving large-scale construction and renovation of luxury hotels, resorts, and entertainment venues across the Kingdom, creating a sustained pipeline of high-value interior design contracts.
- Growing Online Luxury Interior Design Platforms and E-Commerce: Digital channels are opening new avenues for showcasing and selling premium interior design products and consultation services, especially among younger affluent Saudi consumers comfortable engaging with brands through online platforms and virtual design tools.
Market Challenges
- Project Execution Complexity in Mega-Development Environments: Managing large-scale luxury interior design projects within fast-paced mega-project developments requires sophisticated coordination between multiple design disciplines, contractors, and material suppliers under tight delivery timelines.
- Regulatory and Localization Requirements Under Saudization: Luxury interior design firms must navigate evolving regulatory requirements while increasing the employment and development of Saudi nationals, which can add complexity to staffing and project execution.
Emerging Market Trends
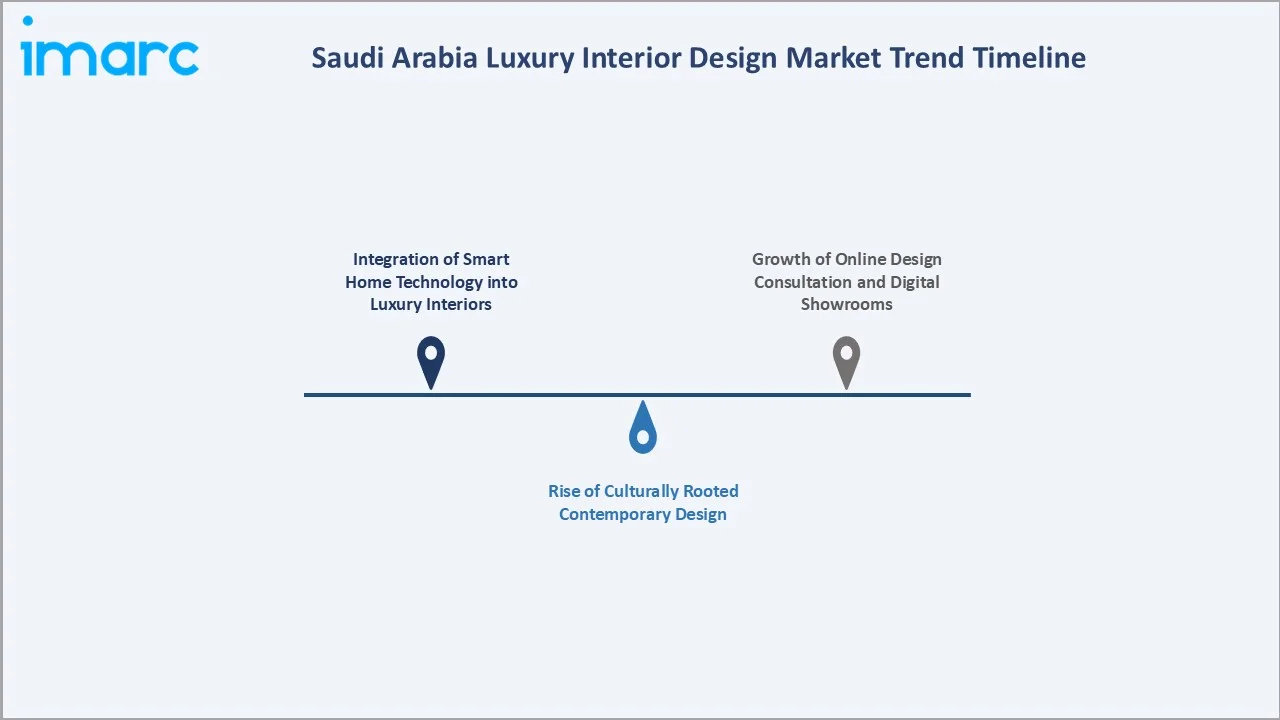
1. Integration of Smart Home Technology into Luxury Interiors
Saudi luxury interior design projects are increasingly incorporating integrated smart home systems covering lighting automation, climate control, security, and audio-visual management. High-net-worth clients commission interior designers to embed these technologies seamlessly into premium aesthetics, adding new technical complexity and value to projects.
2. Rise of Culturally Rooted Contemporary Design
A growing trend among Saudi clients is commissioning designs that blend modern luxury aesthetics with authentic Arabic and Islamic architectural motifs. This movement drives demand for skilled designers capable of interpreting traditional geometric patterns, arabesque detailing, and local material traditions within contemporary luxury environments.
3. Growth of Online Design Consultation and Digital Showrooms
Digital platforms enabling virtual walkthroughs, augmented reality (AR) material visualization, and online design consultation are transforming client engagement models. Interior design firms are investing in digital experience capabilities to serve a new generation of tech-savvy luxury consumers who research and initiate projects online before committing to in-person engagements.
Industry Value Chain Analysis
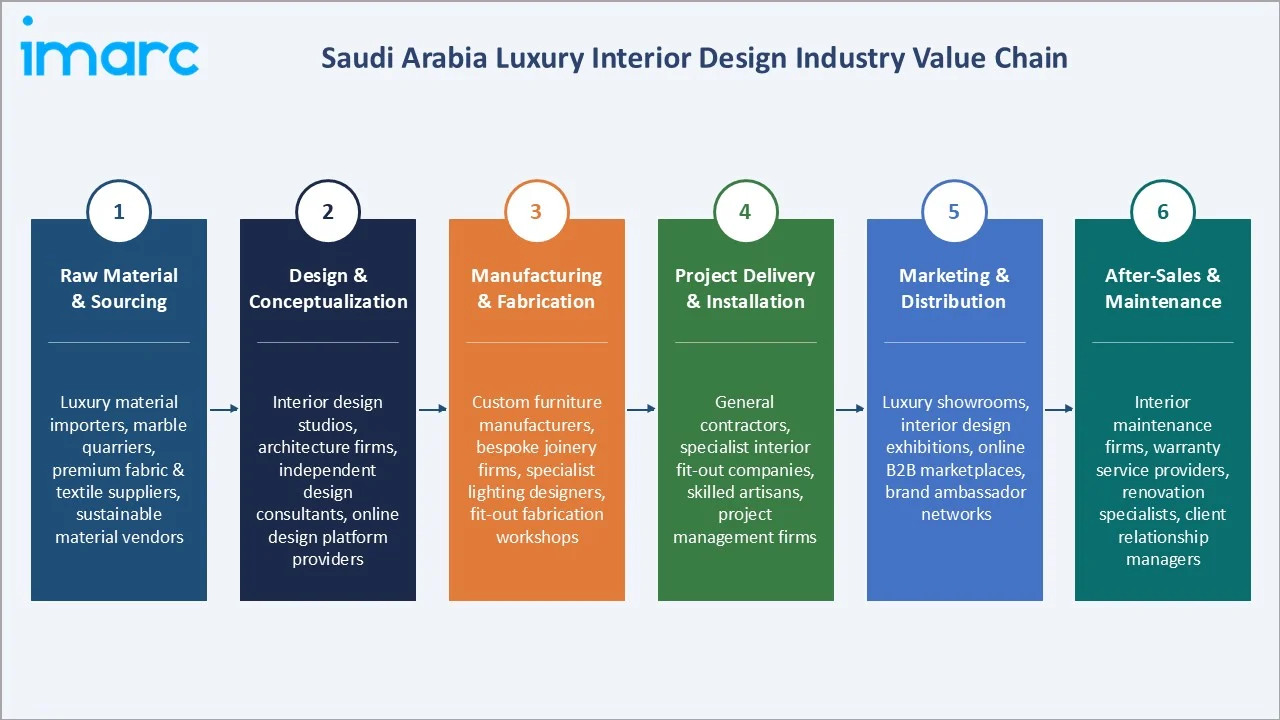
The Saudi Arabia luxury interior design value chain spans six integrated stages, from raw material sourcing through after-sales and maintenance. Premium material suppliers, bespoke designers, and specialist contractors form the backbone of project delivery, while regulatory compliance and client relationship management run throughout the chain.
|
Stage |
Key Players / Examples |
| Raw Material & Sourcing | Luxury material importers, marble quarriers, premium fabric and textile suppliers, and sustainable material vendors |
| Design & Conceptualization | Interior design studios, architecture firms, independent design consultants, and online design platform providers |
| Manufacturing & Fabrication | Custom furniture manufacturers, bespoke joinery firms, specialist lighting designers, and fit-out fabrication workshops |
| Project Delivery & Installation | General contractors, specialist interior fit-out companies, skilled artisans, and project management firms |
| Marketing & Distribution | Luxury showrooms, interior design exhibitions, online B2B marketplaces, and brand ambassador networks |
| After-Sales & Maintenance | Interior maintenance firms, warranty service providers, renovation specialists, and client relationship managers |
Vertically integrated design firms controlling both conceptualization and installation stages capture greater project margins, eliminating sub-contractor markups and maintaining consistent quality throughout delivery.
Technology Landscape in the Saudi Arabia Luxury Interior Design Industry
Building Information Modelling (BIM) and 3D Visualization
BIM platforms and photorealistic 3D rendering tools are becoming standard in luxury interior design project delivery, enabling clients to review and approve design concepts before physical work commences. These technologies reduce change-order costs and improve client satisfaction in high-value projects.
Smart Home and Building Automation Integration
Advanced smart home systems integrating lighting, climate, security, and entertainment controls are increasingly embedded into luxury interior design specifications. Saudi clients demand seamless integration of these systems within premium aesthetic frameworks.
AR and Virtual Reality (VR) Design Tools
AR and VR platforms allow clients to virtually walk through completed interior design concepts before construction begins, enabling real-time design modifications and reducing approval cycles. These tools are particularly valued in high-budget projects where design changes at execution stage carry significant cost implications.
Sustainable Material Technologies
Innovations in low-emission coatings, recycled luxury materials, energy-efficient lighting systems, and certified sustainable wood products are reshaping material specifications in premium interior design, aligning luxury design with growing client demand for environmentally responsible interiors.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Renovation |
42.6% |
2025 |
|
Material |
🔒 |
🔒 |
2025 |
|
Style |
🔒 |
🔒 |
2025 |
|
Distribution Channel |
Offline |
72.4% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
46.3% |
2025 |

By Type
Renovation commands a 42.6% majority share in 2025, driven by high demand from affluent Saudi homeowners upgrading existing luxury villas, apartments, and royal estate properties to reflect contemporary design trends and integrate modern smart home features.
To access detailed market analysis, Request Sample
Newly decorated at 35.8% in 2025 reflects the strong pipeline of new luxury residential and commercial developments, particularly in Riyadh's expanding premium real estate districts and Vision 2030-linked tourism and entertainment destinations.
By Distribution Channel
Offline leads with 72.4% share in 2025, reflecting the high-touch consultation model that characterizes luxury interior design. Clients engaging in premium design projects typically prefer in-person material selection at showrooms, site visits, and direct engagement with principal designers over extended project timelines.
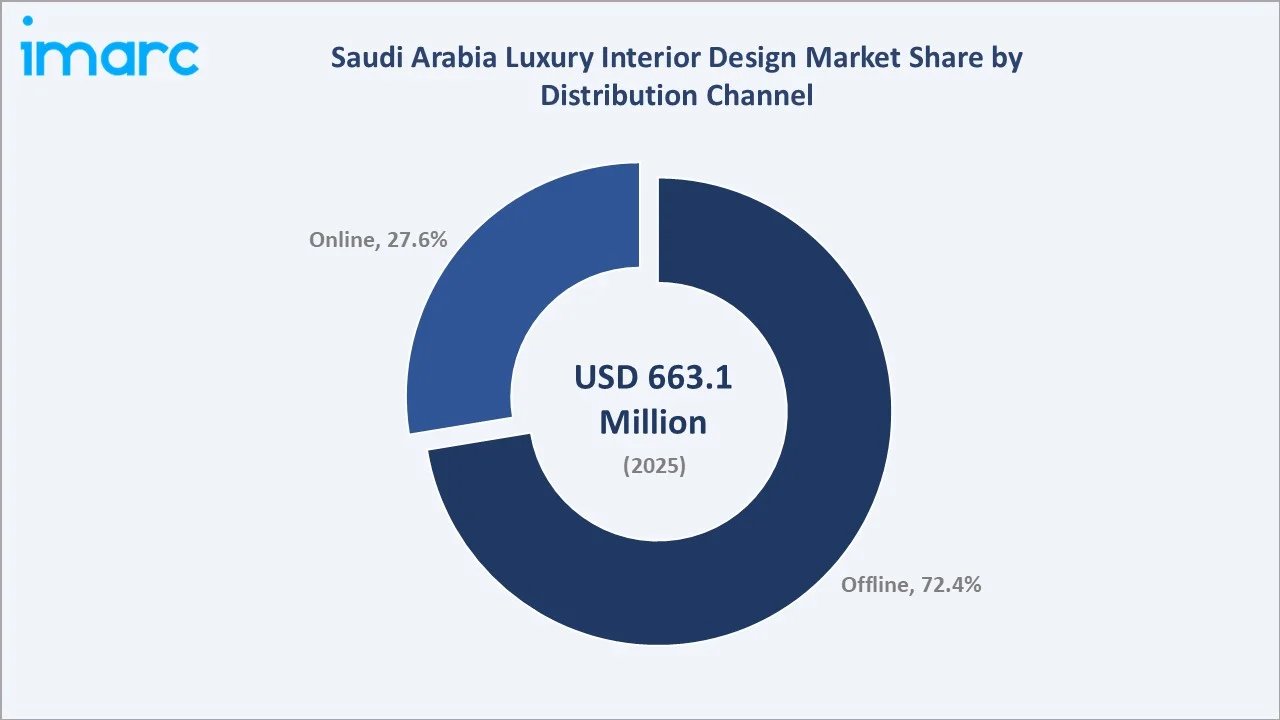
Online at 27.6% in 2025 is a growing channel, driven by younger affluent clients discovering design studios, products, and inspiration through social media platforms and digital showrooms.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
| Northern and Central Region | 46.3% | High concentration of luxury real estate, government and royal estate projects, and premium hospitality development in and around Riyadh. |
| Western Region | 25.8% | Strong luxury residential and commercial activity in Jeddah, Red Sea tourism infrastructure investment, and growing international design firm presence. |
| Eastern Region | 18.7% | Expanding luxury corporate and residential demand in Dhahran, Dammam, and Al Khobar driven by oil sector wealth and a growing expatriate population. |
| Southern Region | 9.2% | Emerging heritage tourism and eco-luxury resort development in Asir and Jizan, supported by Vision 2030 regional development initiatives. |
Northern and Central Region at 46.3% in 2025 leads the regional landscape, anchored by Riyadh's position as Saudi Arabia's administrative and economic capital and home to a dense concentration of luxury residential compounds, government buildings, royal estates, and premium hospitality facilities.
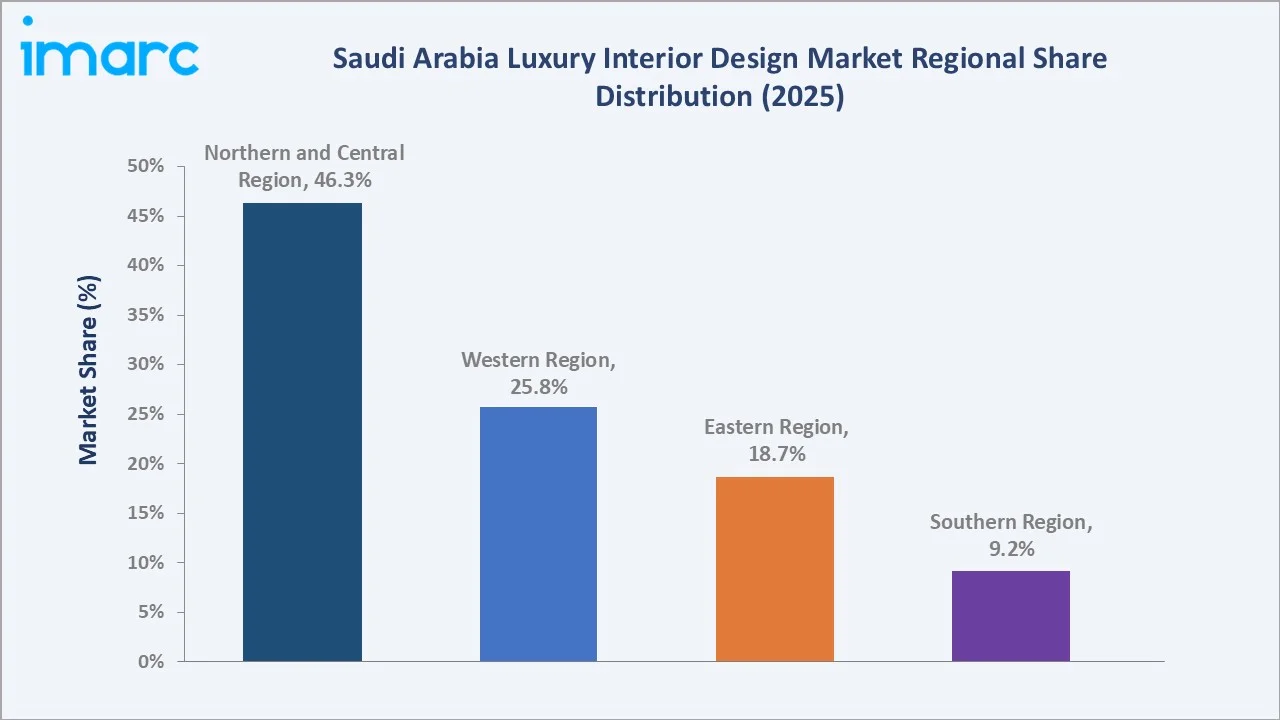
Western Region at 25.8% is the second largest region, supported by strong luxury residential, hospitality, and commercial development across Jeddah, Makkah, and Madinah.
Competitive Landscape
The Saudi Arabia luxury interior design market is moderately fragmented, with a mix of established conglomerates and integrated fit-out groups, international luxury hospitality design specialists, and locally rooted architecture and engineering firms. Larger players leverage brand equity, project management scale, and premium supplier relationships, while boutique studios compete on design creativity and personalized client service.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
| Depa PLC | Depa Interiors |
Leader |
Expanding luxury hospitality and residential fit-out project pipeline across Saudi giga-project developments. |
| Dar Al Riyadh | Dar Design | Leader | Growing interior design and engineering integration capability for premium public-sector and mixed-use developments. |
| Havelock One Interiors |
Havelock One | Challenger | Expanding luxury hotel and high-end residential fit-out coverage across Vision 2030 hospitality developments. |
| Dewan Architects + Engineers |
Dewan Design | Challenger | Growing interior design capability alongside architecture services for premium mixed-use developments. |
Key players include Depa PLC, Dar Al Riyadh, Havelock One Interiors, and Dewan Architects + Engineers, among others.
Key Company Profiles
Depa PLC
Depa PLC is a publicly listed, UAE-headquartered interior solutions group operating across hospitality, residential, commercial, and transport sectors.
- Product Portfolio: Luxury hotel fit-outs, premium hospitality interiors, high-end residential fit-outs, transport infrastructure interior works, and customized furniture, fixtures, and equipment procurement across Saudi Arabia and the broader GCC.
- Recent Developments: Depa PLC has continued to expand its project portfolio in Saudi Arabia, securing new interior fit-out contracts across luxury hospitality and giga-project destinations in the Kingdom.
- Strategic Focus: Deepening its luxury hospitality and giga-project fit-out pipeline in Saudi Arabia by leveraging Depa Interiors' established client relationships and specialist delivery capabilities across the Kingdom.
Dar Al Riyadh
Dar Al Riyadh is a fully integrated Saudi engineering and design consultancy with over four decades of experience, offering master planning, architecture, engineering, interior design, and project supervision services. The firm operates a nationwide presence and is actively involved in major public-sector, hospitality, and infrastructure developments across the Kingdom.
- Product Portfolio: Interior design for airport terminals and VIP lounges, luxury hospitality fit-outs, premium office and institutional interiors, large-scale public infrastructure projects, and high-end mixed-use development interiors.
- Recent Developments: Dar Al Riyadh has continued to grow its interior design practice, reinforcing its design team and broadening its interior design capability in support of Vision 2030-linked infrastructure and hospitality projects across Saudi Arabia.
- Strategic Focus: Strengthening its integrated interior design and engineering offer for premium airport, hospitality, and institutional projects by leveraging its full lifecycle consultancy model across Saudi Arabia.
Havelock One Interiors
Havelock One Interiors is a GCC-based turnkey fit-out contractor and custom manufacturer, with a fully established subsidiary in Saudi Arabia. The company specializes in delivering high-quality interior contracting and bespoke manufacturing for the hospitality, retail, entertainment, and residential sectors.
- Product Portfolio: Luxury hotel and resort fit-outs, high-end retail and flagship brand fit-outs, entertainment venue interiors, premium residential fit-outs, and bespoke joinery and decorative metalwork manufacturing for the Saudi Arabia market.
- Recent Developments: Havelock One Interiors has continued to expand its Saudi Arabia project portfolio, securing new fit-out contracts and receiving industry recognition for the quality of its delivery across major luxury developments in the Kingdom.
- Strategic Focus: Scaling its luxury hotel and premium residential fit-out delivery in Saudi Arabia by building on its established regional manufacturing capability and its track record across Vision 2030 giga-project destinations.
Market Concentration Analysis
The Saudi Arabia luxury interior design market is moderately fragmented, with no single player holding a dominant market share. The top players, Depa PLC and Dar Al Riyadh, collectively account for a meaningful share of overall project value, given the large-scale and project-based nature of luxury design engagements.
Barriers to entry include high design talent acquisition costs, the need for extensive premium supplier relationships, strong client referral networks, and the capital required to operate showrooms and large project delivery teams. These factors limit rapid new entrant disruption while allowing established firms to maintain client loyalty.
Consolidation trends are emerging at a modest pace, with larger conglomerates acquiring boutique design studios to access niche client bases and specialized design talent. Strategic partnerships between regional design firms and international luxury brands are also broadening the product offering of established players.
Investment & Growth Opportunities
Fastest-Growing Segments
Newly decorated is expanding fastest among type categories, driven by the surge in new luxury residential and commercial completions across Vision 2030 development zones. Online is the fastest-growing distribution channel, supported by rising digital engagement among affluent Saudi consumers.
Emerging Markets
Western Region is poised for accelerating growth, driven by Red Sea tourism project completions, expanding luxury hotel and resort infrastructure, and Jeddah's growing profile as a premium residential destination.
Venture & Investment Trends
Investment activity is concentrated in premium design studio establishment, digital visualization technology adoption, and sustainable luxury material supply chains. Capital is also flowing into smart home integration capabilities. International luxury furniture brands are entering the Saudi Arabia market through exclusive distribution partnerships with local interior design firms.
Future Market Outlook (2026-2034)
The Saudi Arabia luxury interior design market is projected to grow from USD 663.1 Million in 2025 to USD 718.7 Million in 2026, reaching USD 1,368.5 Million by 2034, registering a CAGR of 8.38% during 2026–2034.
Four forces will shape the market through 2034: continued luxury real estate development under Vision 2030 mega-projects; deeper integration of smart home and digital design technologies; growing domestic design talent through Saudi design schools and international partnerships; and expanding renovation cycles among the Kingdom's growing luxury residential stock.
By 2034, the Saudi Arabia luxury interior design industry is expected to be defined by a stronger domestic design identity that blends contemporary global aesthetics with culturally authentic Saudi and Arabic design heritage, supported by a maturing local ecosystem of skilled designers, premium material suppliers, and technology-enabled project delivery platforms.
Research Methodology
Primary Research
Primary research included structured interviews with luxury interior design firm principals, premium material suppliers, luxury real estate developers, and procurement specialists at hospitality groups, validating market size estimates, segment shares, and competitive dynamics across the Kingdom.
Secondary Research
Secondary sources included Saudi Council of Engineers publications, Ministry of Municipal and Rural Affairs data, Saudi Vision 2030 project documentation, Saudi General Authority for Statistics reports, and annual reports and press releases from leading interior design firms and real estate developers operating in the Kingdom.
Forecasting Models
Market forecasts used top-down and bottom-up models combining luxury residential construction completion data, hospitality and commercial project pipeline analysis, consumer expenditure trends, and macroeconomic variables including oil revenues and government capital expenditure. Scenario analysis was conducted to assess upside and downside risks from giga-project execution timelines and global material supply chain conditions.
Saudi Arabia Luxury Interior Design Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Newly Decorated, Repeated Decorated, Renovation |
| Materials Covered | Textiles, Wood, Metals, Glass, Ceramics, Plastics, Others |
| Styles Covered | Modern, Traditional, Rustic, Vintage, Classical, Others |
| Distribution Channels Covered | Online, Offline |
| Applications Covered | Residential, Commercial, Hospitality, Retail, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Depa PLC, Dar Al Riyadh, Havelock One Interiors, Dewan Architects + Engineers, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia luxury interior design market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia luxury interior design market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia luxury interior design industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Luxury Interior Design Market Report
The Saudi Arabia luxury interior design market size is estimated at USD 718.7 Million in 2026, driven by Vision 2030-backed real estate development and a luxury hospitality expansion pipeline.
The market is projected to grow at a CAGR of 8.38% from 2026-2034, reaching USD 1,368.5 Million, supported by mega-project development and increasing affluent consumer demand.
Renovation leads the type segment at 42.6% in 2025, driven by affluent homeowners upgrading luxury villas and apartments across Riyadh and Jeddah.
Offline dominates at 72.4% in 2025, reflecting the high-touch consultation model typical of luxury interior design client engagements in the Kingdom.
Northern and Central Region commands 46.3% share in 2025, anchored by Riyadh's concentration of luxury residences, government buildings, and premium hospitality facilities.
Leading players include Depa PLC, Dar Al Riyadh, Havelock One Interiors, and Dewan Architects + Engineers, among others.
Vision 2030 mega-projects including NEOM, The Red Sea Project, and Diriyah Gate are creating large-scale demand for world-class luxury interior design and fit-out services across the Kingdom.
Key restraints include high dependency on imported premium materials, the high cost of skilled design labor, and limited availability of Saudi-national luxury design professionals with international credentials.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade