Saudi Arabia Membrane Bioreactor (MBR) Market Size, Share, Trends and Forecast by System Configuration, Membrane Type, Application, and Region, 2026-2034
Saudi Arabia Membrane Bioreactor (MBR) Market Size, Share, Trends & Forecast (2026-2034)
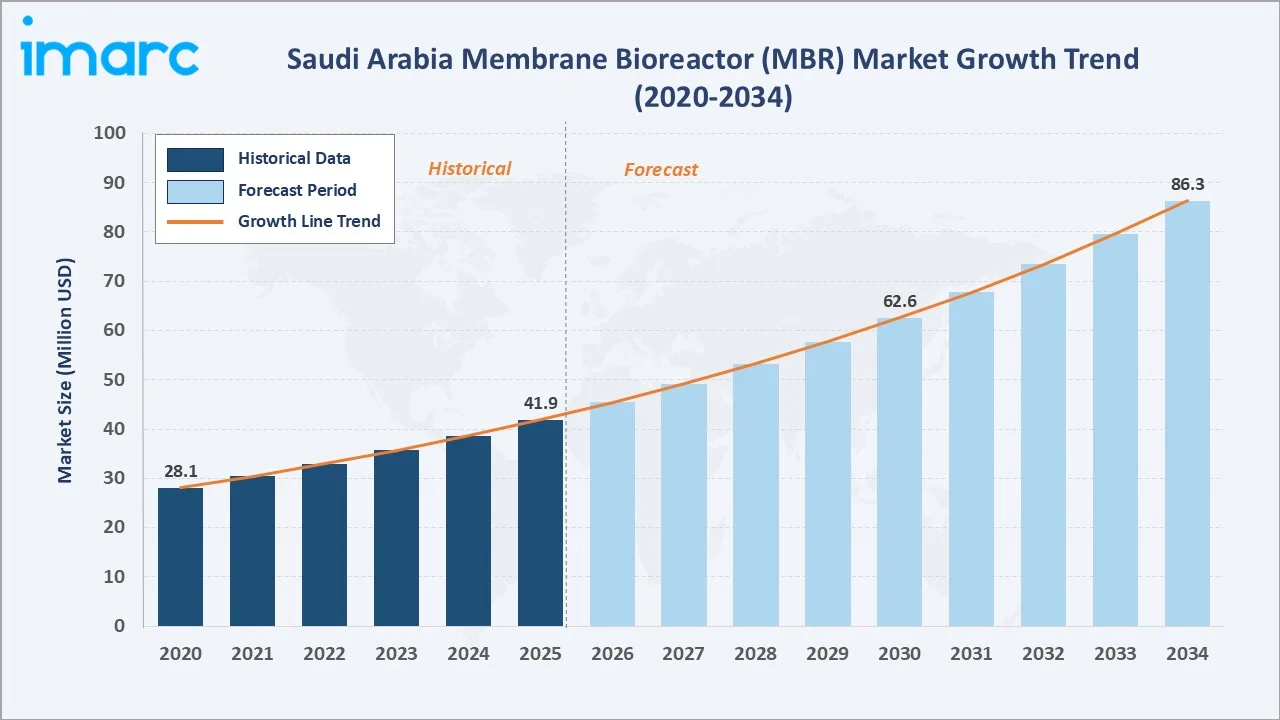
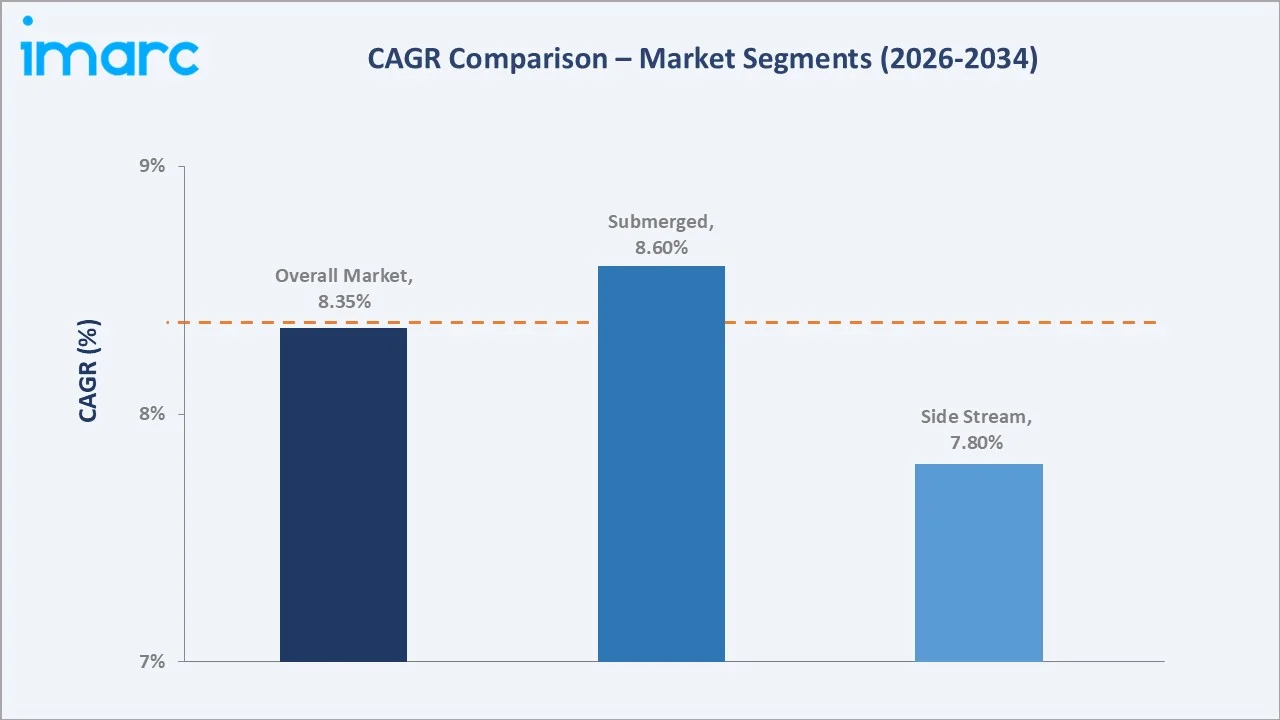
The Saudi Arabia membrane bioreactor (MBR) market reached USD 41.9 Million in 2025 and is projected to reach USD 86.3 Million by 2034, growing at a CAGR of 8.35% during 2026-2034. The market is driven by rising water scarcity, stringent wastewater regulations, urbanization, increasing water reuse, and growing demand from municipal and industrial sectors for efficient and environmentally sustainable treatment technologies. Submerged configuration dominates at 74.6%. Municipal Waste-Water Treatment leads applications at 57.8%. Western Region commands 34.8% of the market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 41.9 Million |
|
Forecast Market Size (2034) |
USD 86.3 Million |
|
CAGR (2026-2034) |
8.35% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant System Configuration |
Submerged (74.6%, 2025) |
|
Dominant Application |
Municipal Waste-Water Treatment (57.8%, 2025) |
|
Leading Region |
Western Region (34.8%, 2025) |
The market expanded from USD 28.1 Million in 2020 to USD 41.9 Million in 2025, anchored at USD 62.6 Million in 2030 and forecast to reach USD 86.3 Million by 2034. Saudi Arabia's National Water Company contracts worth SAR 3.2 Billion for seven strategic MBR projects anchored the demand trajectory, which sustained growth through 2023-2025 as Vision 2030 infrastructure spending accelerated across Makkah, Riyadh, and Eastern Region industrial zones.
To get more information on this market, Request Sample
Submerged MBR grows fastest through energy efficiency advantages and compact design suitability for municipal-scale treatment. Municipal Waste-Water Treatment application grows at the market CAGR as the National Water Company expands decentralized treatment capacity, while industrial applications grow above the market CAGR as Eastern Region ZLD compliance requirements accelerate industrial MBR adoption across petrochemical and manufacturing facilities.
Executive Summary
The Saudi Arabia Membrane Bioreactor (MBR) Market reached USD 41.9 Million in 2025, representing one of the region's highest-growth water treatment technology markets driven by Vision 2030 sustainability targets, critical water scarcity, and the Kingdom's national mandate for advanced wastewater reclamation. The MBR system is the defining water treatment technology of Saudi Arabia's sustainability agenda, delivering the high-quality reuse-grade effluent that the Kingdom's arid conditions and regulatory framework demand. The market is projected to reach USD 86.3 Million by 2034.
Submerged configuration at 74.6% dominates by delivering energy-efficient, compact treatment suited to Saudi Arabia's large-scale municipal wastewater treatment facilities. Municipal Waste-Water Treatment at 57.8% leads through Vision 2030's large-scale national water infrastructure rollout and the National Water Company's sustained capital deployment into MBR-based treatment capacity. Western Region at 34.8% leads through Makkah and Jeddah's extensive treatment infrastructure expansion and the Kingdom's highest concentration of large-scale NWC-contracted MBR projects.
Key Market Insights
|
Insight |
Data |
|
Dominant System Configuration |
Submerged – 74.6% share (2025) |
|
Dominant Application |
Municipal Waste-Water Treatment – 57.8% market share (2025) |
|
Leading Region |
Western Region – 34.8% market share (2025) |
|
Market Opportunity |
AI-driven MBR monitoring; decentralized treatment; industrial ZLD compliance; agricultural water reuse for Vision 2030 food security |
Key Analytical Observations Supporting the Above Data:
- Submerged at 74.6%: The Submerged MBR configuration dominates as membranes immersed directly in the bioreactor reduce energy consumption, space requirements, and capital costs versus side-stream systems.
- Municipal Waste-Water Treatment at 57.8%: The municipal sector leads through the Saudi government's large-scale treatment and reuse infrastructure mandated under Vision 2030.
- Western Region at 34.8%: The Western Region leads through Makkah and Jeddah's high population density and infrastructure investment concentration. The region hosts the Kingdom's largest planned and operational wastewater treatment facilities, with pilgrimage infrastructure management and NWC's concentrated capital allocation driving the highest MBR project volume of any Saudi administrative region.
Saudi Arabia Membrane Bioreactor (MBR) Market Overview
The Saudi Arabia Membrane Bioreactor (MBR) Market encompasses the design, manufacture, supply, installation, and operation of all membrane bioreactor systems used in municipal and industrial wastewater treatment across the Kingdom's four administrative regions, serving municipal utilities, petrochemical complexes, food and beverage manufacturers, pharmaceutical producers, and agricultural reuse programs.
The ecosystem integrates MBR system manufacturers, membrane module suppliers, biological process engineers, EPC contractors, utility operators under NWC and SWPC, and regulatory bodies setting effluent quality standards. Macroeconomic factors include Vision 2030 water security targets, rising urbanization, oil and gas industrial expansion, and government reuse mandates requiring treated water quality standards achievable only through advanced MBR technology.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
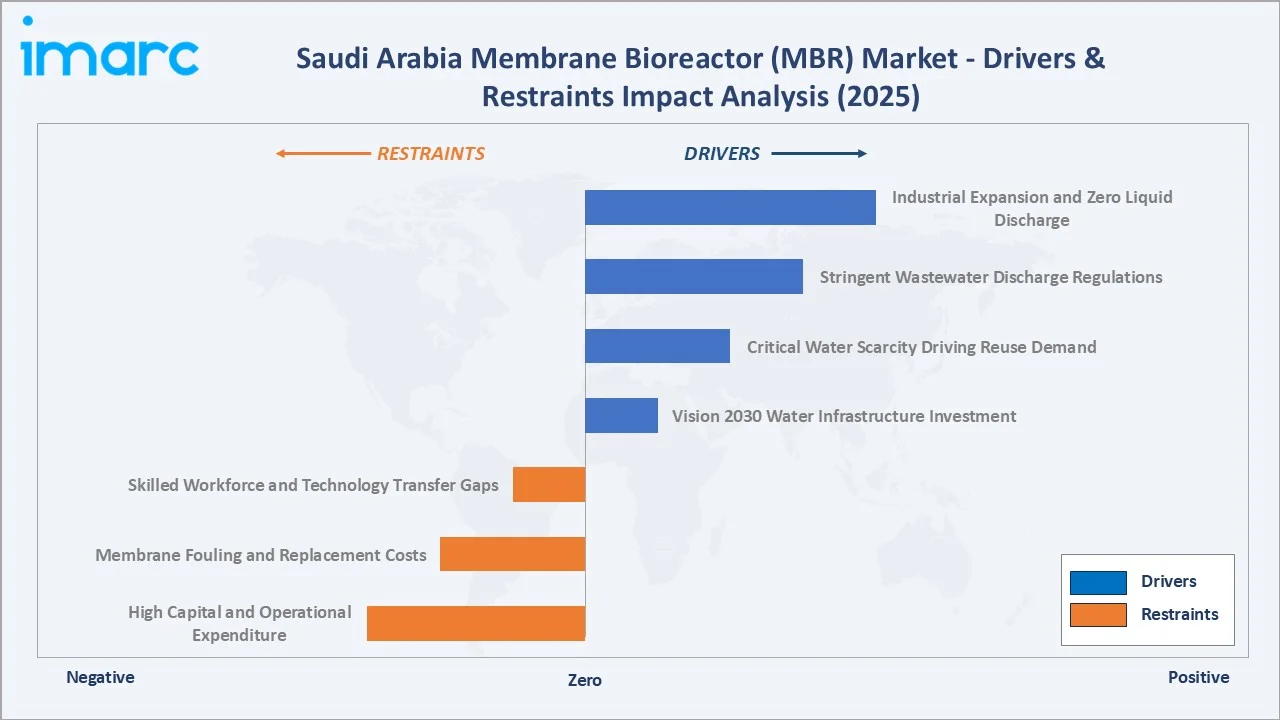
- Vision 2030 Water Infrastructure Investment: Saudi Arabia's Vision 2030 mandates substantial investment in water reuse and advanced treatment capacity, positioning MBR as the preferred technology for compact, high-quality effluent production. Government contracts and public-private partnerships are creating a sustained pipeline of large-scale MBR projects across municipal and industrial segments through 2034.
- Critical Water Scarcity Driving Reuse Demand: Saudi Arabia's arid climate and near-zero natural freshwater availability create structural non-discretionary demand for advanced wastewater reclamation. MBR systems produce consistently high-quality reuse water suitable for agricultural irrigation, industrial process water, and groundwater recharge, directly addressing the Kingdom's national water security priorities.
- Stringent Wastewater Discharge Regulations: Saudi Arabia's increasingly stringent effluent quality standards from the Ministry of Environment, Water and Agriculture compel municipalities and industries to upgrade conventional activated sludge systems to MBR technology, which delivers superior effluent quality. Regulatory pressure is accelerating plant retrofits and greenfield MBR adoptions across both municipal and industrial segments, creating a regulatory-driven procurement pipeline largely independent of economic cycle fluctuations. The Kingdom's zero liquid discharge mandate for Eastern Region petrochemical complexes creates an industrial MBR adoption wave that adds to the already robust municipal segment demand through 2034.
- Industrial Expansion and Zero Liquid Discharge Requirements: Rapid expansion of oil and gas, petrochemical, food processing, and pharmaceutical industries in the Eastern and Western Regions generates significant industrial wastewater volumes requiring advanced treatment. Zero liquid discharge mandates and high-quality process water requirements are driving industrial MBR adoption as a technically superior alternative to conventional biological treatment systems across NEOM, Jubail Industrial City, and Yanbu Industrial City projects. SABIC and Saudi Aramco's expanding industrial footprint in the Eastern Region is creating an accelerating industrial MBR procurement pipeline that grows above the overall market CAGR through the forecast period.
Market Restraints
- High Capital and Operational Expenditure: MBR systems require substantially higher capital investment than conventional biological treatment due to precision membrane modules, air scouring systems, and specialized control equipment that command significant cost premiums. Elevated energy consumption for aeration and membrane maintenance further increases operational costs, creating adoption barriers for smaller municipalities and industrial facilities with constrained capital budgets. The premium capital cost of MBR over conventional treatment limits market penetration in Southern Region municipalities and smaller industrial operators without mandated ZLD compliance requirements, moderating overall market growth below the level that Saudi Arabia's water scarcity fundamentals would otherwise support.
- Membrane Fouling and Replacement Costs: Membrane fouling caused by biological cake layer formation and scaling in Saudi Arabia's high-salinity and high-temperature wastewater environments is a persistent operational challenge that increases lifecycle costs. Frequent membrane cleaning cycles, chemical dosing requirements, and periodic module replacement add significant ongoing operating costs that reduce financial attractiveness of MBR relative to conventional options for cost-sensitive operators. The accelerated membrane degradation caused by Saudi Arabia's extreme ambient temperatures and high-salinity industrial effluents reduces effective membrane lifespan, increasing replacement frequency and total cost of ownership compared to temperate climate MBR deployments.
- Skilled Workforce and Technology Transfer Gaps: Advanced MBR operation and maintenance requires specialized technical expertise in membrane management, biological process control, and SCADA-integrated monitoring that remains scarce in Saudi Arabia's domestic workforce despite Vision 2030's Saudization objectives. Dependency on expatriate technical staff and international vendors for system commissioning, troubleshooting, and maintenance creates operational vulnerabilities and cost premiums. The domestic skill gap is particularly acute for AI-integrated MBR monitoring systems and anaerobic MBR configurations, limiting the adoption pace of next-generation MBR technologies and constraining efficiency gains these advanced configurations offer.
Market Opportunities
- AI-Powered MBR Monitoring and Predictive Maintenance: Integration of AI-based monitoring systems that analyze real-time membrane performance data to prevent fouling, optimize aeration intensity, and extend membrane lifespan creates significant operational cost reduction opportunities. AI monitoring platforms reduce unplanned membrane replacement events by enabling proactive intervention before fouling becomes critical, lowering total lifecycle costs and improving system reliability. The combination of AI monitoring with IoT sensor networks and SCADA integration positions Saudi Arabia's MBR operators for next-generation intelligent water management, aligning with the Kingdom's smart city and digital infrastructure objectives.
- Decentralized and Package MBR Systems for Remote Installations: Saudi Arabia's dispersed industrial sites, pilgrimage facilities in the Makkah region, and agricultural communities in the Southern Region represent an underserved market for compact, containerized MBR package systems. Package MBR units offer scalable, modular treatment capacity that conventional centralized wastewater treatment plants cannot provide for the highly variable hydraulic loading created by Hajj and Umrah pilgrimage peak seasons. The growing NEOM and Giga-project industrial zones represent a high-value decentralized MBR opportunity, as their remote locations and advanced water quality requirements favour modular systems that can be expanded incrementally alongside industrial zone development.
Market Challenges
- Integration Complexity with Existing Infrastructure: Retrofitting MBR technology into aging conventional activated sludge treatment plants requires extensive civil engineering modifications, process re-engineering, and operational downtime management that create project complexity and cost overruns. The civil infrastructure investment required to adapt existing clarifier-based treatment plants for membrane cassette installation significantly increases total project cost above greenfield MBR construction, reducing financial viability of retrofit projects for budget-constrained municipal operators. The coordination challenge between MBR system suppliers, local EPC contractors, NWC project managers, and MEWA regulatory compliance teams further extends project timelines.
- Supply Chain Dependencies for Membrane Modules: Saudi Arabia's MBR market relies on 100% imported membrane modules from Japan, Europe, and North America, creating supply chain vulnerabilities that can delay project implementation and increase total system costs. Supply chain disruptions, currency fluctuations, extended lead times for specialty hollow fiber and flat sheet membrane modules, and import logistics challenges create procurement uncertainties affecting project planning and lifecycle maintenance budgeting. The absence of domestic membrane manufacturing capability creates a structural dependency on international suppliers that conflicts with Vision 2030's local content Iktva objectives and exposes the Saudi MBR market to geopolitical supply disruption risks.
Emerging Market Trends
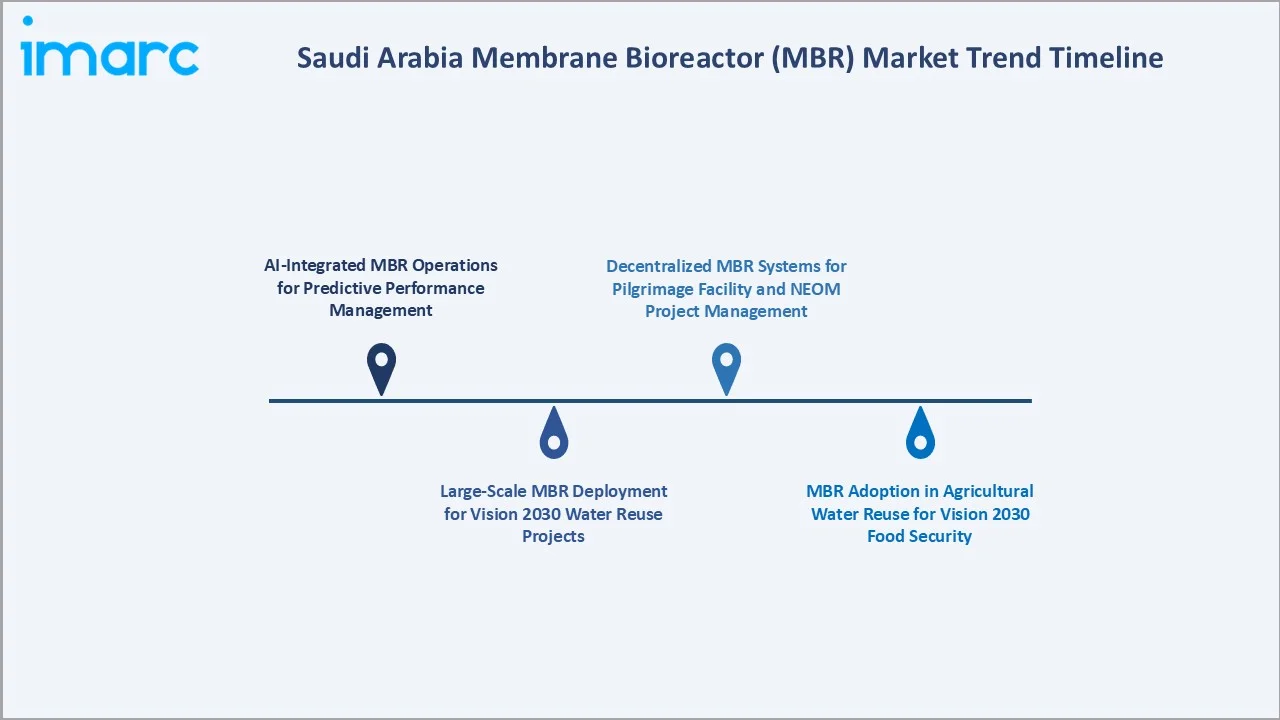
1. AI-Integrated MBR Operations for Predictive Performance Management
Saudi Arabia's adoption of AI-powered monitoring systems for MBR operations represents a transformative trend enabling real-time membrane fouling prevention, aeration energy optimization, and predictive maintenance scheduling. AI monitoring platforms analyze continuous sensor data streams from membrane modules, biological reactors, and effluent quality meters to identify fouling precursors and trigger preventive cleaning cycles before performance deterioration occurs, reducing unplanned downtime and extending membrane operational life.
2. Large-Scale MBR Deployment for Vision 2030 Water Reuse Projects
Saudi Arabia's National Water Company and government utilities are deploying large-scale MBR infrastructure as the primary treatment technology for Vision 2030's water reuse mandate, creating a sustained multi-year MBR construction and commissioning pipeline.
3. MBR Adoption in Agricultural Water Reuse for Vision 2030 Food Security
Saudi Arabia's Vision 2030 food security objectives are driving MBR adoption for agricultural wastewater reuse, particularly in hydroponic and controlled environment agriculture requiring consistently high-quality irrigation water.
4. Decentralized MBR Systems for Pilgrimage Facility and NEOM Project Management
The unique demands of Makkah and Madinah's annual Hajj and Umrah pilgrimage seasons, accommodating millions of visitors in compressed timeframes, are driving adoption of modular and decentralized MBR systems that can handle highly variable hydraulic loads. NEOM's gigaproject industrial zones and The Line's advanced urban infrastructure requirements are also driving MBR adoption for high-quality water reuse, with decentralized containerized systems offering operational flexibility that large-scale centralized treatment plants cannot provide.
Industry Value Chain Analysis
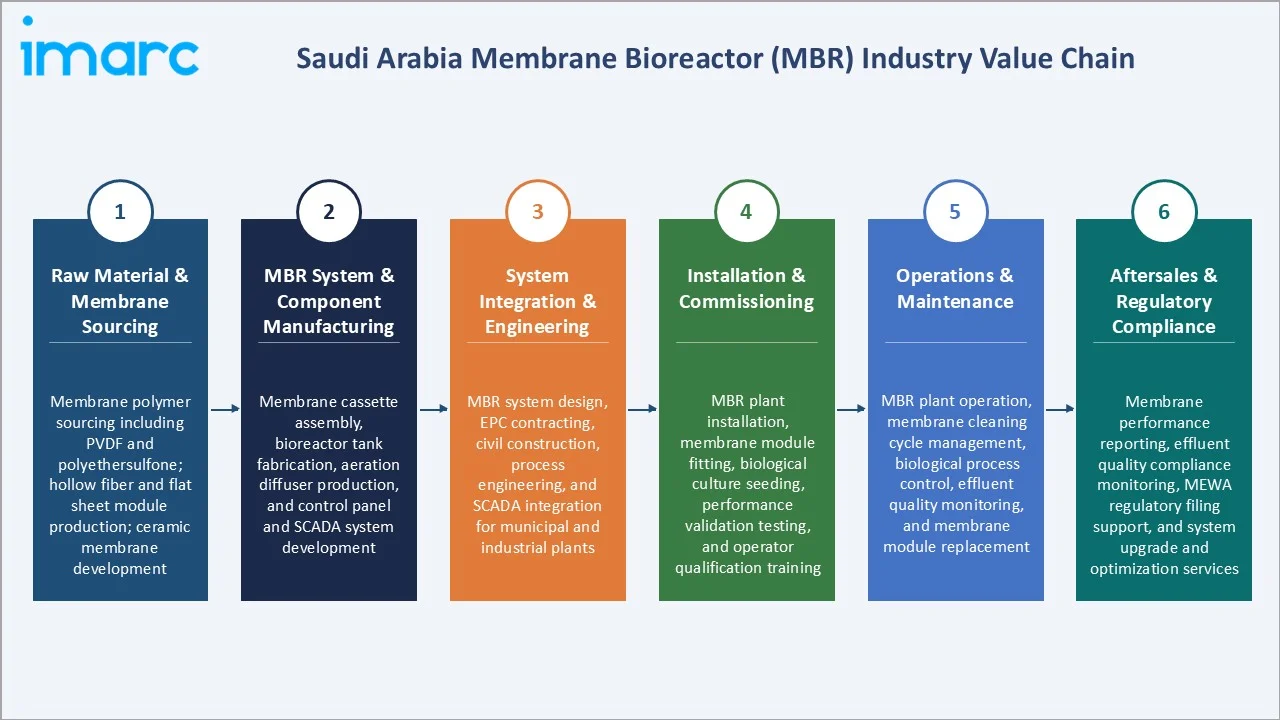
The MBR value chain integrates raw membrane material and polymer procurement, MBR system and component manufacturing, system integration and EPC engineering, plant installation and commissioning, and ongoing operations and maintenance services across Saudi Arabia's municipal and industrial treatment facilities. The value chain's commercial architecture is progressively consolidating toward integrated system procurement as the primary commercial format, as NWC and industrial clients prefer single-source MBR system suppliers over fragmented component procurement.
|
Stage |
Key Participants |
|
Raw Material & Membrane Sourcing |
Membrane polymer sourcing including PVDF and polyethersulfone; hollow fiber and flat sheet module production; ceramic membrane development |
|
MBR System & Component Manufacturing |
Membrane cassette assembly, bioreactor tank fabrication, aeration diffuser production, and control panel and SCADA system development |
|
System Integration & Engineering |
MBR system design, EPC contracting, civil construction, process engineering, and SCADA integration for municipal and industrial plants |
|
Installation & Commissioning |
MBR plant installation, membrane module fitting, biological culture seeding, performance validation testing, and operator qualification training |
|
Operations & Maintenance |
MBR plant operation, membrane cleaning cycle management, biological process control, effluent quality monitoring, and membrane module replacement |
|
Aftersales & Regulatory Compliance |
Membrane performance reporting, effluent quality compliance monitoring, MEWA regulatory filing support, and system upgrade and optimization services |
The membrane module manufacturing tier is the value chain's most commercially critical stage, with Japan-based KUBOTA and Toray and France-based Veolia/SUEZ controlling dominant global membrane technology positions. The operations and maintenance tier is experiencing the most rapid technology transition as AI-based monitoring systems replace manual membrane management protocols across Saudi Arabia's large-scale MBR installations.
Technology Landscape in the Saudi Arabia Membrane Bioreactor (MBR) Industry
Hollow Fiber Membrane Technology
Hollow fiber membrane technology offers high packing density, efficient backwashing capability, and robust fouling resistance in submerged MBR configurations, making it the dominant membrane technology for Saudi Arabia's large-scale municipal wastewater treatment projects. Hollow fiber membranes deliver high surface area per unit volume, enabling compact treatment footprints suited to Saudi Arabia's urban site constraints and achieving consistently high effluent quality that meets NWC reuse standards.
Flat Sheet Membrane Technology
Flat sheet membrane technology provides superior fouling resistance in high-solids industrial wastewater environments and enables individual cassette replacement without system shutdown, making it particularly suited to Saudi Arabia's petrochemical and food processing industrial applications. Flat sheet configurations from KUBOTA and other suppliers are gaining traction in Eastern Region industrial MBR applications where variable feed quality and high suspended solids challenge hollow fiber system performance and longevity.
Anaerobic MBR (AnMBR) Technology
Anaerobic MBR technology combines anaerobic biological digestion with membrane separation to produce high-quality effluent while generating recoverable biogas as a valuable energy byproduct. KAUST's March 2025 initiative using anaerobic MBR with UV disinfection for agricultural wastewater reuse demonstrates the technology's growing relevance to Saudi Arabia's water-energy-food nexus sustainability agenda and positions AnMBR as the next-generation MBR platform for agricultural reuse applications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
System Configuration |
Submerged |
74.6% |
2025 |
|
Membrane Type |
🔒 |
🔒 |
2025 |
|
Application |
Municipal Waste-Water Treatment |
57.8% |
2025 |
|
Region |
Western Region |
34.8% |
2025 |

By System Configuration
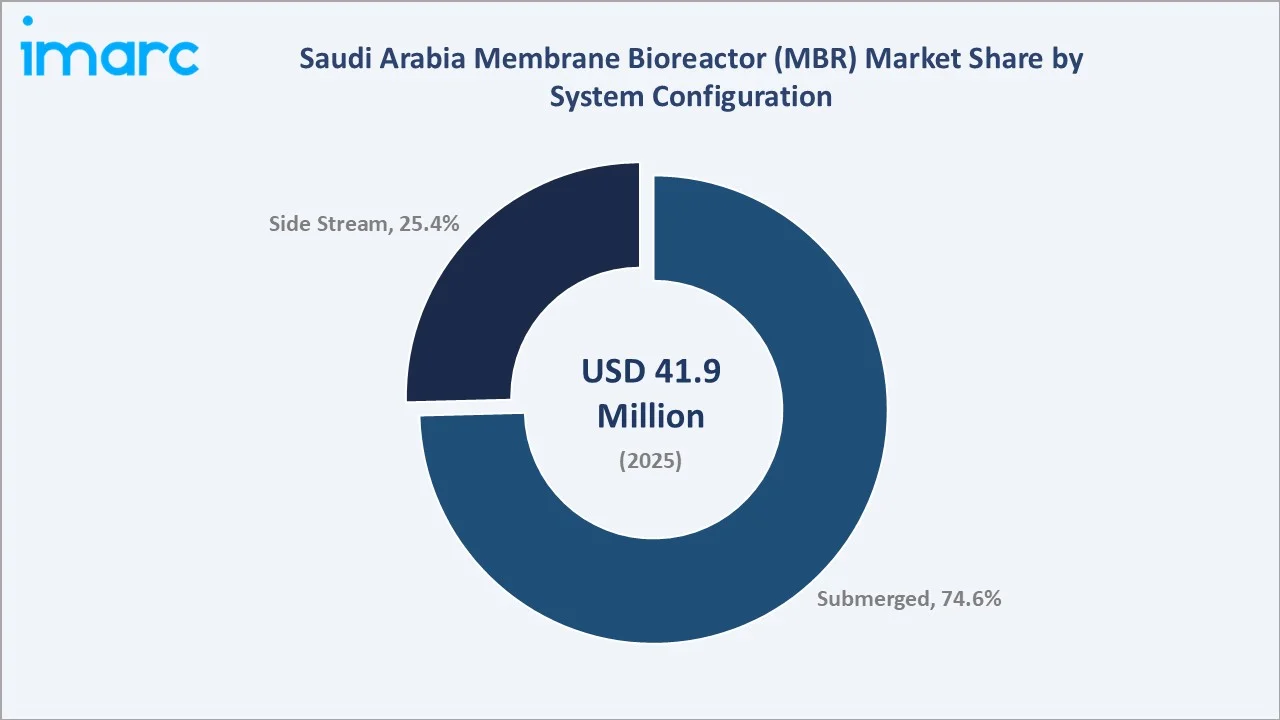
The Submerged segment leads at 74.6% in 2025, encompassing the dominant MBR configuration for Saudi Arabia's municipal and industrial wastewater treatment, positioned as the commercially preferred, operationally efficient, and energy-cost-optimized system design for the Kingdom's large-scale treatment projects.
To access detailed market analysis, Request Sample
The Side Stream segment at 25.4% captures applications requiring robust cross-flow membrane filtration for high-viscosity or high-solids industrial effluents. Side-stream MBR systems are specifically favored in oil and gas processing, petrochemical sector effluent treatment, and food and beverage manufacturing applications across Saudi Arabia's Eastern Region and Western Region industrial zones.
By Application
Municipal Waste-Water Treatment leads at 57.8% in 2025, driven by Saudi Arabia's large-scale national water infrastructure expansion under Vision 2030 and the National Water Company's sustained capital deployment into MBR-based treatment capacity across all four administrative regions of the Kingdom.
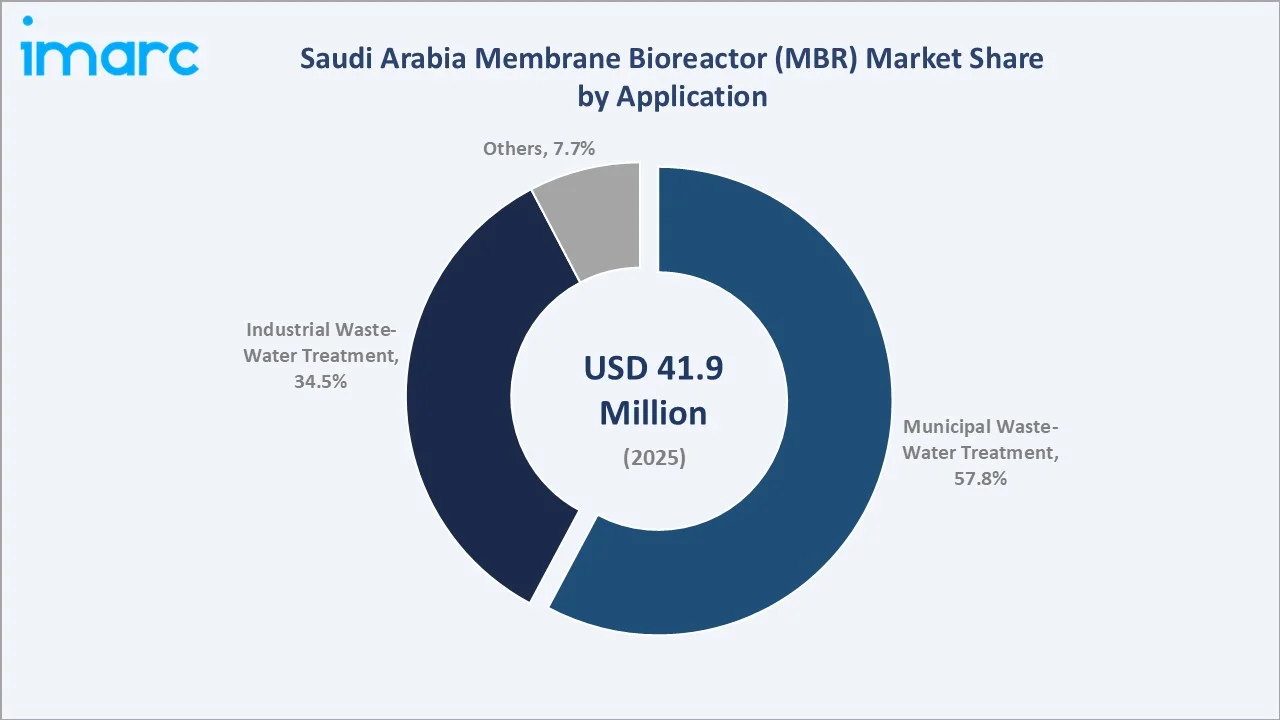
Industrial Waste-Water Treatment at 34.5% is the market's fastest-growing application as Eastern Region petrochemical complexes, NEOM industrial zones, and expanding food and beverage manufacturing require advanced high-quality effluent treatment compliant with increasingly stringent zero liquid discharge standards. Others at 7.7% includes agricultural wastewater reuse, research and development installations, and hospitality sector treatment applications.
Regional Market Insights
|
Region |
Share (2025) |
Key MBR Market Drivers & Characteristics |
|
Western Region |
34.8% |
Driven by Makkah and Jeddah large-scale municipal treatment infrastructure, pilgrimage facility wastewater management, and the National Water Company's highest capital investment concentration |
|
Northern and Central Region |
31.7% |
Driven by Riyadh's metropolitan expansion, Vision 2030 urban development projects, and the capital region's rapidly increasing municipal wastewater treatment capacity requirements |
|
Eastern Region |
22.4% |
Supported by oil and gas industrial wastewater treatment, petrochemical sector zero liquid discharge requirements, and SABIC and Saudi Aramco advanced industrial effluent programs |
|
Southern Region |
11.1% |
Emerging with growing agricultural water reuse initiatives, rural municipal treatment upgrades, and increasing groundwater protection and environmental compliance enforcement |
Western Region, at 34.8%, leads through Makkah and Jeddah's high population density and the Kingdom's largest wastewater treatment infrastructure investment concentration, hosting the NWC's highest-value project pipeline. Northern and Central Region, at 31.7%, reflects Riyadh's metropolitan expansion and the capital's Vision 2030 urban development pipeline.
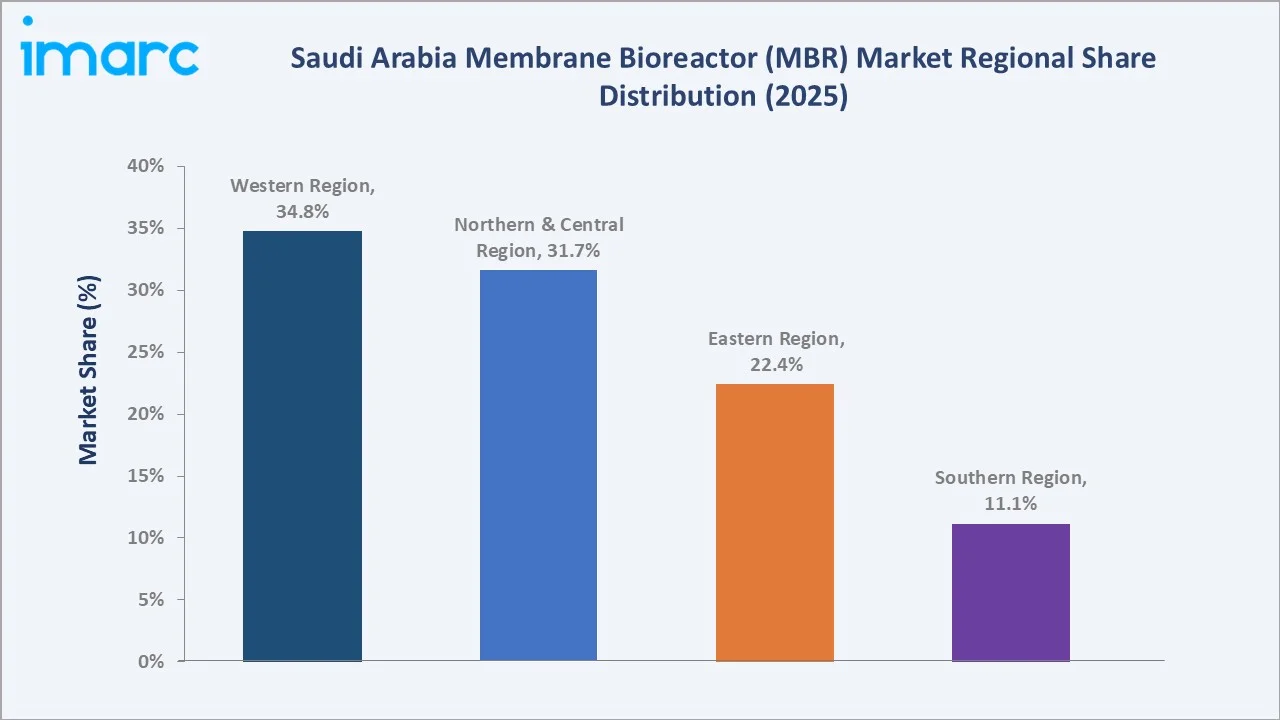
Eastern Region, at 22.4%, reflects the oil and gas industrial sector's growing MBR adoption for zero liquid discharge compliance and high-quality process water requirements across Jubail and Yanbu industrial cities. Southern Region, at 11.1%, represents the early-stage but emerging market segment driven by agricultural water reuse and rural municipal treatment modernization programs aligned with Vision 2030.
Competitive Landscape
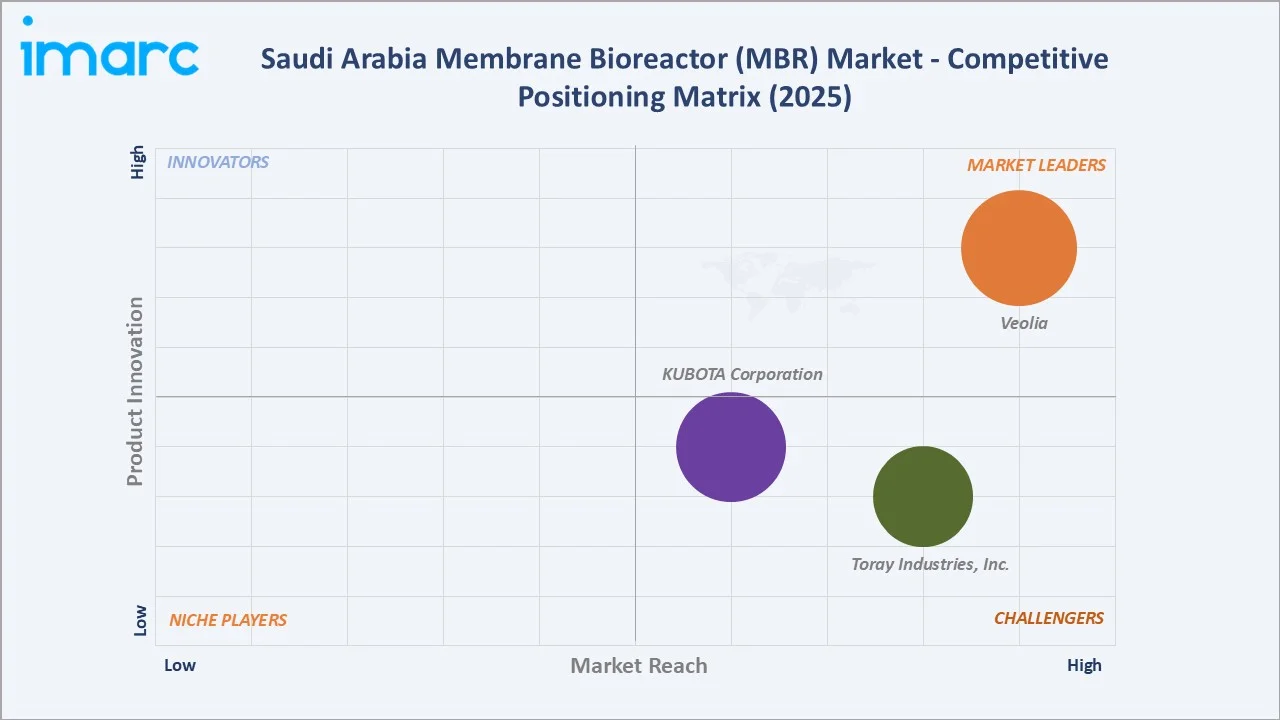
The Saudi Arabia Membrane Bioreactor (MBR) Market competitive landscape is moderately concentrated with two distinct competitive tiers: global integrated MBR system leaders and specialized membrane technology companies competing through technology differentiation and project-specific engineering capabilities.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Veolia |
Biosep MBR Systems, AnoxKaldnes MBBR, Aquamem Modules |
Market Leader |
Veolia is a global water treatment leader delivering integrated MBR solutions for Saudi Arabia's largest municipal and industrial wastewater projects under NWC and SWPC contracts. |
|
KUBOTA Corporation |
Kubota MBR Membrane Units, Flat Sheet Modules |
Strong Challenger |
KUBOTA Corporation specializes in flat sheet membrane modules for MBR wastewater treatment with a strong Middle East project track record and long-life membrane performance in high-temperature environments. |
|
Toray Industries, Inc. |
Toray MBR Membranes, Hollow Fiber Modules |
Strong Challenger |
Toray Industries, Inc. provides high-performance hollow fiber membranes for MBR wastewater treatment and water reuse applications with advanced fouling resistance in industrial and municipal settings. |
Key players include Veolia, KUBOTA Corporation, Toray Industries, Inc., and others.
Key Company Profiles
Veolia
Veolia is a global leader in water treatment technology with a strong presence in the Saudi Arabia Membrane Bioreactor (MBR) Market through its integrated Biosep and AnoxKaldnes MBR solutions for municipal and industrial wastewater treatment under major NWC and SWPC framework contracts.
- Key Products: Biosep MBR Systems, AnoxKaldnes MBBR, Aquamem MBR Modules.
- Strategic Focus: Expanding integrated water cycle management services combining MBR membrane technology with AI-based digital monitoring platforms, energy recovery systems, and advanced water reuse optimization for Saudi Arabia's large-scale municipal and industrial treatment facilities. Veolia is investing in AnMBR technology development for Saudi Arabia's agricultural reuse applications to capitalize on Vision 2030 food security investments, positioning the company at the intersection of water treatment, energy recovery, and sustainable agriculture in the Kingdom's long-term infrastructure strategy.
KUBOTA Corporation
KUBOTA Corporation is a Japan-based industrial manufacturer with a strong competitive position in the Saudi Arabia Membrane Bioreactor (MBR) Market through its proven flat sheet membrane modules for municipal and industrial wastewater applications across the Middle East and Arabian Gulf region.
- Key Products: Kubota MBR Membrane Units, Flat Sheet Submerged Membrane Modules for municipal and industrial wastewater treatment applications.
- Strategic Focus: Providing reliable, long-life flat sheet membrane solutions specifically optimized for Saudi Arabia's high-temperature and high-salinity wastewater environments, supporting the region's growing water reuse requirements with membrane systems that maintain consistent performance under the Kingdom's extreme operational conditions. KUBOTA is developing next-generation membrane materials with enhanced fouling resistance and extended operational lifespan to reduce total lifecycle costs for Saudi Arabia's large-scale municipal MBR operators and improve the competitive economics of MBR versus conventional treatment across the market.
Market Concentration Analysis
The Saudi Arabia Membrane Bioreactor (MBR) Market is moderately concentrated at the membrane technology and integrated system level, with the key players collectively accounting for approximately 55-65% of the Kingdom's MBR system and membrane module revenue. International EPC contractors and Saudi utility operators hold significant procurement influence as gatekeepers to the Kingdom's large government-contracted treatment project pipeline. Market concentration is declining over the forecast period as Evoqua, Koch Separation Solutions, and emerging regional suppliers gain NWC qualification and industrial sector project access through competitive tendering.
Investment & Growth Opportunities
Highest Growth Segments
Industrial Waste-Water Treatment (~9.5% CAGR), AI-integrated MBR monitoring platforms (~15% CAGR from early commercial base), decentralized package MBR systems (~12% CAGR), anaerobic MBR for agricultural reuse and biogas recovery (~18% CAGR from small base), and NEOM Giga-project advanced water treatment (~20%+ CAGR from near-zero) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
NEOM and Giga-project water infrastructure represents the Saudi Arabia Membrane Bioreactor (MBR) Market's highest-value emerging opportunity, with multi-billion riyal advanced water treatment contracts being tendered for transformational urban development projects including The Line, Sindalah, and Oxagon that require zero-liquid-discharge and high-quality reuse-grade effluent standards achievable only through advanced MBR technology deployments.
Investment Themes
- Domestic MBR membrane manufacturing capability development as a Vision 2030 Iktva strategic investment: Saudi Arabia's current 100% import dependency for MBR membrane modules creates a strategic domestic manufacturing investment opportunity aligned with Vision 2030's local content requirements and industrial diversification objectives, offering first-mover advantage to investors who establish PVDF hollow fiber or flat sheet membrane manufacturing capacity within the Kingdom.
- AI-integrated digital water management platforms for MBR performance optimization across NWC's distributed network: Saudi Arabia's smart city initiatives, NWC's digital transformation program, and the Kingdom's ambition for world-leading water management infrastructure create demand for integrated AI and IoT platforms that can optimize MBR performance, reduce energy consumption, and enable remote predictive maintenance across the distributed network of Saudi Arabia's municipal and industrial treatment facilities.
Future Market Outlook (2026-2034)
The Saudi Arabia Membrane Bioreactor (MBR) Market is projected to grow from USD 41.9 Million in 2025 to USD 86.3 Million by 2034, delivering an 8.35% CAGR over the forecast period. The market's anchor value of USD 62.6 Million in 2030 represents the MBR industry at its Vision 2030 infrastructure delivery peak, with the bulk of NWC-contracted MBR capacity commissioned and operational. Submerged MBR will remain the dominant system configuration, AI-integrated monitoring will achieve mainstream adoption, and anaerobic MBR will begin its commercial scaling in agricultural reuse applications.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025), including National Water Company project managers; municipal wastewater treatment plant operators; industrial EHS and water management directors; MBR system suppliers and regional sales managers; and membrane technology specialists active in the Saudi Arabia and broader Arabian Gulf market with expertise in Saudi Arabia's Vision 2030 water reuse infrastructure strategy.
Secondary Research
Secondary research encompassed NWC annual reports and project tender announcements; Saudi Arabian Ministry of Environment, Water and Agriculture water strategy publications and effluent quality standards; Vision 2030 water reuse program documentation; KAUST water research publications; MBR technology supplier product literature and case studies; global membrane bioreactor market studies 2024-2025; and Saudi Arabia industrial expansion data from SABIC, Saudi Aramco, and NEOM. Over 50 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a bottom-up model: (i) municipal MBR capacity expansion pipeline from NWC project database and Ministry of Environment tender announcements; (ii) industrial sector wastewater volume projections by subsector based on production capacity expansion plans; (iii) MBR system cost per cubic meter of daily treatment capacity by configuration; (iv) membrane replacement and service revenue as a percentage of cumulative installed base; (v) regional allocation based on historical infrastructure investment distribution and forward project pipeline.
Saudi Arabia Membrane Bioreactor (MBR) Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| System Configurations Covered | Submerged, Side Stream |
| Membrane Types Covered | Hollow Fiber, Flat Sheet, Multi-Tubular, Others |
| Applications Covered | Municipal Waste-Water Treatment, Industrial Waste-Water Treatment, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Veolia, KUBOTA Corporation, Toray Industries, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia membrane bioreactor (MBR) market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia membrane bioreactor (MBR) market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia membrane bioreactor (MBR) industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Membrane Bioreactor (MBR) Market Report
The Saudi Arabia Membrane Bioreactor (MBR) Market reached USD 41.9 Million in 2025, driven by Submerged configuration dominant at 74.6%, Municipal Waste-Water Treatment application leading at 57.8%, Vision 2030 water infrastructure investment, Western Region commanding 34.8% market share through Makkah and Jeddah's large-scale NWC-contracted treatment projects, and the National Water Company's SAR 3.2 Billion December 2024 contract awards for seven strategic MBR-incorporating water projects.
The Saudi Arabia Membrane Bioreactor (MBR) Market grows at 8.35% CAGR during 2026-2034, reaching USD 86.3 Million by 2034. This growth reflects sustained Vision 2030 water infrastructure investment commitment, growing industrial sector zero liquid discharge compliance requirements, expanding agricultural water reuse adoption, and the commissioning of NEOM and Giga-project advanced water treatment infrastructure through the forecast period.
Submerged configuration leads at 74.6%, capturing Saudi Arabia's municipal MBR market as the energy-efficient, compact design suited to high-volume centralized treatment plants operated by the National Water Company. Submerged MBR grows at the market CAGR as municipal sector capacity expansion through Vision 2030 NWC projects remains the primary demand driver, while side-stream configurations grow above the market CAGR in industrial applications.
Municipal Waste-Water Treatment leads at 57.8% through Vision 2030's large-scale treatment and reuse infrastructure rollout under NWC and SWPC framework programs. Industrial Waste-Water Treatment is the fastest-growing application at 34.5% as Eastern Region petrochemical complexes, NEOM industrial zones, and the expanding food and beverage manufacturing sector face zero liquid discharge compliance requirements that are accelerating industrial MBR adoption above the overall market CAGR.
Western Region leads at 34.8% through Makkah and Jeddah's large municipal treatment infrastructure and NWC investment concentration, hosting the highest volume of large-scale MBR project contracts. Northern and Central Region at 31.7% reflects Riyadh's metropolitan expansion and Vision 2030 urban development pipeline, while Eastern Region at 22.4% reflects the oil and gas industrial sector's MBR adoption for zero liquid discharge compliance.
Leading companies include Veolia, KUBOTA Corporation, Toray Industries, Inc., and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade