
Saudi Arabia Oxygen Concentrator Market Size, Share, Trends and Forecast by Type, Technology, Application, End User, and Region, 2026-2034
Saudi Arabia Oxygen Concentrator Market Size, Share, Trends & Forecast (2026-2034)
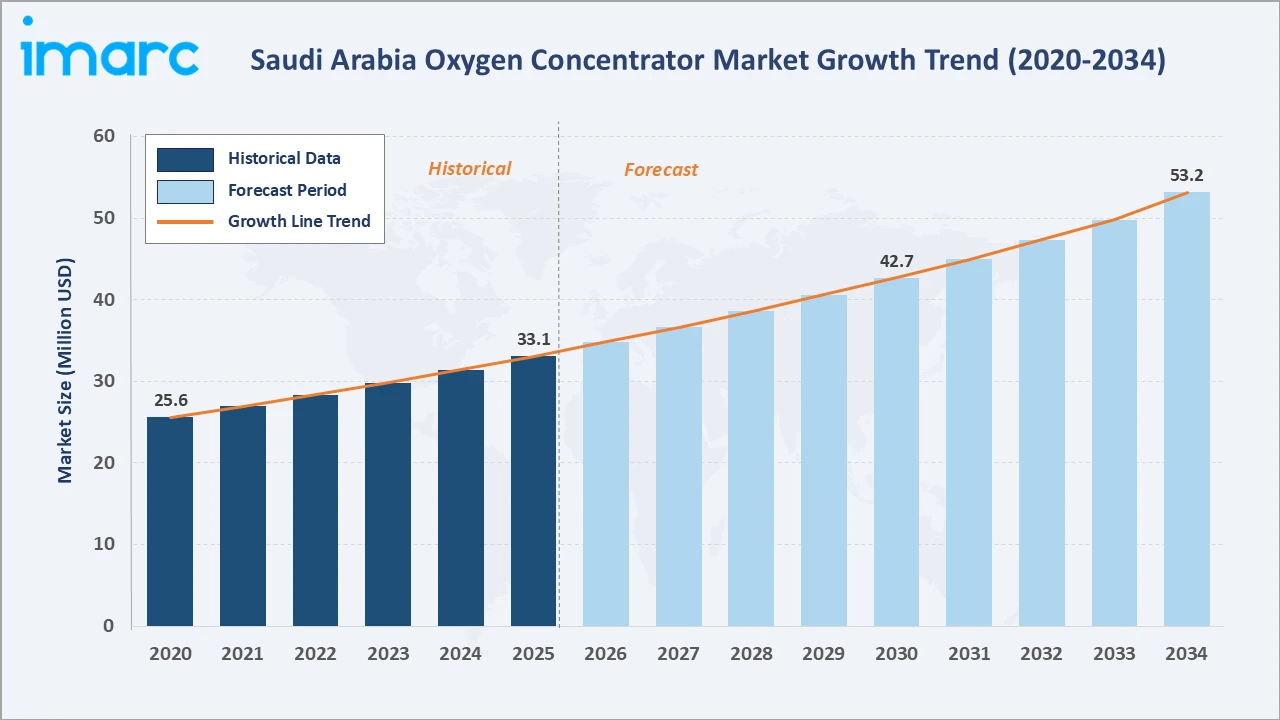
The Saudi Arabia oxygen concentrator market reached USD 33.1 Million in 2025 and is projected to reach USD 53.2 Million by 2034, growing at a CAGR of 5.24% during 2026-2034. The market is driven by rising chronic respiratory disease prevalence, Vision 2030 healthcare infrastructure investment, aging population growth, and expanding home care demand. Portable devices lead at 58.7%. Continuous Flow leads technology at 62.8%. Western Region commands 35.4% share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 33.1 Million |
|
Forecast Market Size (2034) |
USD 53.2 Million |
|
CAGR (2026-2034) |
5.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Portable (58.7%, 2025) |
|
Dominant Technology |
Continuous Flow (62.8%, 2025) |
|
Leading Region |
Western Region (35.4%, 2025) |
The market expanded from USD 25.6 Million in 2020 to USD 33.1 Million in 2025, anchored at USD 42.7 Million in 2030 and forecast to reach USD 53.2 Million by 2034. The COVID-19 pandemic created a structural baseline elevation in 2020-2022; Vision 2030 hospital expansions and home care program growth sustained demand through 2023-2025.
To get more information on this market, Request Sample
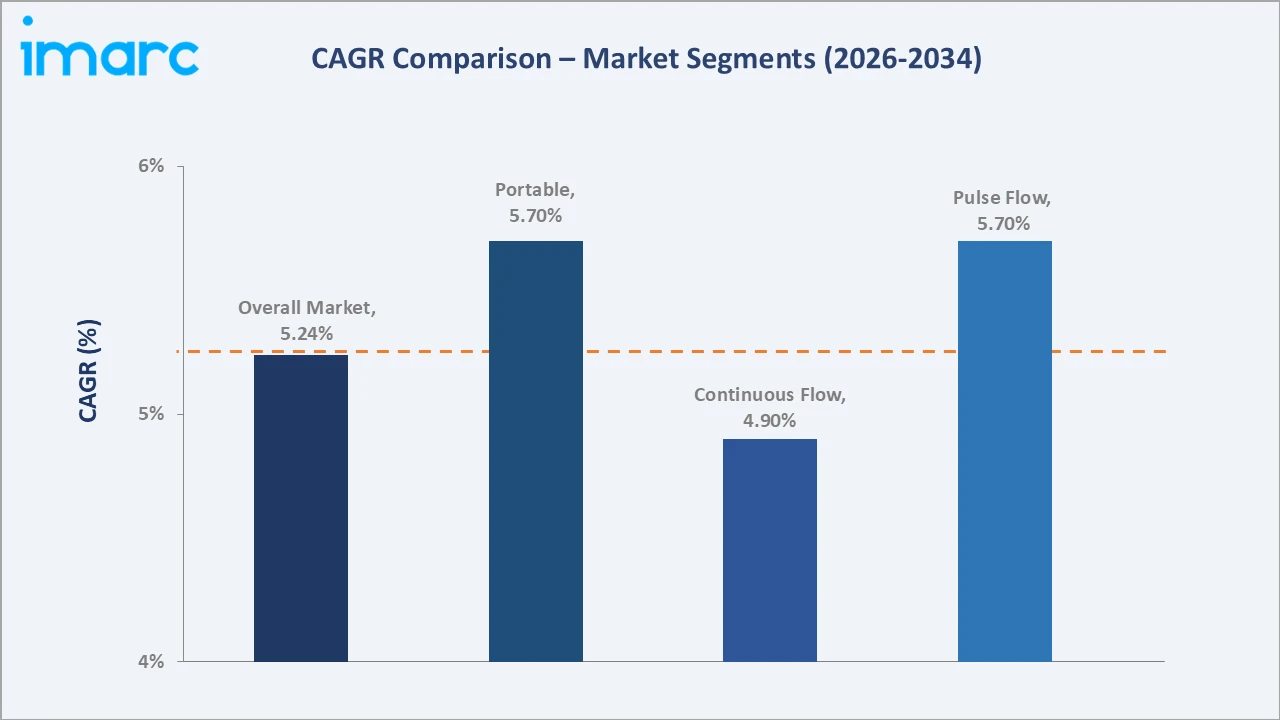
Portable concentrators grow fastest at ~5.7% CAGR as home care programs expand and aging patients adopt mobility-enabling devices. Continuous flow technology grows at ~4.9% CAGR through sustained hospital deployment, while pulse flow advances at ~5.7% CAGR through improved home-care suitability.
Executive Summary
The Saudi Arabia oxygen concentrator market reached USD 33.1 Million in 2025, representing one of the Kingdom's fastest-growing medical device markets driven by Vision 2030 healthcare modernization, rising chronic respiratory disease burden, and expanding home-based oxygen therapy. The market is projected to reach USD 53.2 Million by 2034.
Portable type at 58.7% dominates through home care independence and patient mobility requirements. Continuous Flow at 62.8% leads through widespread hospital deployment for acute respiratory care. Western Region at 35.4% leads through Makkah and Jeddah's high hospital density and pilgrimage-related respiratory health demands.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Portable – 58.7% share (2025) |
|
Dominant Technology |
Continuous Flow – 62.8% market share (2025) |
|
Leading Region |
Western Region – 35.4% market share (2025) |
|
Market Opportunity |
Smart POC with telemedicine; home care expansion; CCHI insurance coverage; Vision 2030 hospital procurement |
Key Analytical Observations Supporting the Above Data:
- Portable at 58.7%: The Portable segment dominates as lightweight, battery-powered concentrators enable home-based oxygen therapy and patient mobility, aligned with the MOH's strategic shift toward decentralized care. Rising COPD and asthma diagnosis rates combined with CCHI insurance coverage for home medical equipment are accelerating portable device adoption across all regions.
- Continuous Flow at 62.8%: Continuous Flow technology leads through widespread deployment in Saudi Arabia's tertiary hospitals and specialized respiratory care centers, delivering uninterrupted oxygen output essential for acute and severe respiratory patient management. Vision 2030 hospital expansion projects across all four regions are directly increasing institutional procurement of continuous flow concentrators.
- Western Region at 35.4%: The Western Region leads through Makkah and Jeddah's high population density and the Kingdom's highest concentration of tertiary hospitals. Pilgrimage-related respiratory health demands during Hajj and Umrah create additional cyclical procurement demand, reinforcing the region's market leadership.
Saudi Arabia Oxygen Concentrator Market Overview
The Saudi Arabia oxygen concentrator market encompasses the procurement, distribution, and deployment of portable and stationary oxygen concentrating devices used across hospitals, clinics, home care settings, and ambulatory surgical centers to deliver supplemental oxygen therapy for patients with chronic and acute respiratory conditions.
The ecosystem integrates device manufacturers, SFDA-registered importers, hospital procurement departments, home healthcare service providers, CCHI-covered insurance payers, and MOH regulatory oversight. Macroeconomic drivers include Vision 2030 healthcare capital investment, aging population growth, rising COPD and asthma prevalence, and expanding private health insurance coverage.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
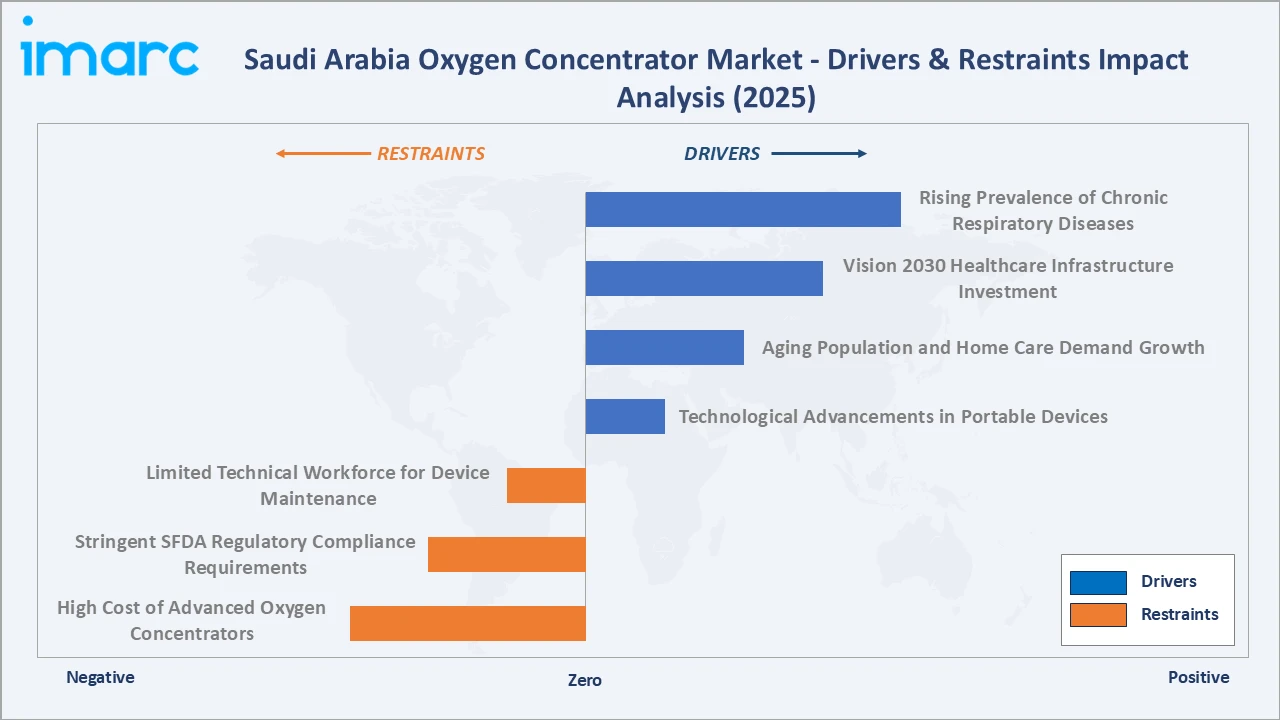
- Rising Prevalence of Chronic Respiratory Diseases: Saudi Arabia continues to experience a significant burden of chronic respiratory conditions, including COPD, asthma, and sleep-related breathing disorders. Factors such as tobacco consumption, exposure to dust and air pollutants, and changing lifestyles contribute to respiratory health risks. Increasing awareness, improved diagnostic capabilities, and greater access to healthcare services are resulting in more patients being identified and treated for chronic respiratory conditions. This expanding patient pool is supporting demand for oxygen concentrators across hospitals, clinics, and home-care settings.
- Vision 2030 Healthcare Infrastructure Investment: Healthcare infrastructure development under Saudi Arabia's Vision 2030 is supporting the expansion and modernization of medical facilities across the country. Investments in hospitals, primary healthcare centers, specialized treatment facilities, and digital healthcare infrastructure are increasing the need for medical equipment. The expansion of healthcare capacity is creating additional procurement opportunities for oxygen concentrators and other respiratory-care devices, while public-private partnerships and healthcare-sector reforms are further supporting equipment modernization.
- Aging Population and Home Care Demand Growth: Saudi Arabia's gradually aging population is expected to increase demand for healthcare services associated with chronic and age-related conditions, including respiratory diseases. At the same time, healthcare providers are placing greater emphasis on home-based care and the management of stable chronic patients outside hospital settings. Improvements in home healthcare services, insurance coverage, and availability of respiratory-care equipment are encouraging the use of oxygen concentrators in residential settings. This shift toward decentralized care is expected to support demand for both stationary and portable oxygen-concentrator systems.
- Technological Advancements in Portable Devices: Technological improvements are making portable oxygen concentrators increasingly compact, lightweight, energy-efficient, and user-friendly. Manufacturers are incorporating features such as improved oxygen delivery algorithms, longer battery life, quieter operation, digital interfaces, and connectivity capabilities to enhance patient mobility and treatment convenience. These developments are reducing some of the limitations associated with conventional oxygen therapy equipment and supporting greater adoption of portable devices for home care, travel, and other non-hospital applications.
Market Restraints
- High Cost of Advanced Oxygen Concentrators: Premium portable oxygen concentrators from leading international manufacturers carry per-unit prices of USD 2,000–5,000, representing significant financial barriers for patients without comprehensive insurance or government subsidies. High device costs limit penetration in Southern Region municipalities and lower-income segments, constraining growth below what Saudi Arabia's respiratory disease burden would otherwise support.
- Stringent SFDA Regulatory Compliance Requirements: Saudi Food and Drug Authority regulations require comprehensive device registration, clinical evidence submission, and post-market surveillance, creating significant compliance costs and extended market entry timelines for new suppliers. Regulatory complexity limits competitive alternatives and sustains price premiums that reduce affordability.
- Limited Technical Workforce for Device Maintenance: Saudi Arabia's medical device maintenance sector faces a shortage of certified biomedical engineers qualified to service advanced oxygen concentrator systems, particularly models requiring manufacturer-specific diagnostics. The gap is most acute in Southern Region and secondary cities distant from Riyadh and Jeddah's biomedical services hubs, creating extended downtime periods and service cost premiums.
Market Opportunities
- Smart POC Integration with Telemedicine: Integration of AI-driven adaptive oxygen delivery and cloud-based monitoring into POC devices creates substantial growth opportunity as Vision 2030's digital health agenda drives remote patient monitoring platform adoption. Smart POC devices transmitting real-time therapy compliance and oxygen saturation data to clinicians improve outcomes and reduce hospital readmissions, creating premium device demand across Saudi Arabia's expanding home care oxygen therapy patient base.
- Home Healthcare Oxygen Therapy Program Expansion: Saudi Arabia's MOH home healthcare strategy creates structured procurement pathways for portable oxygen concentrators beyond hospital channels. CCHI coverage expansion for home medical equipment progressively reduces financial barriers, while approximately 150,000+ undiagnosed or undertreated COPD patients represent a substantial addressable market for systematic home oxygen therapy program development by device manufacturers and distributors.
Market Challenges
- Patient Awareness and Therapy Adherence Gaps: Suboptimal patient awareness of chronic respiratory disease management and cultural barriers to home-based medical device therapy constrain market expansion below clinical prevalence levels. Low therapy adherence due to social stigma, discomfort, or misunderstanding of long-term therapy benefits reduces effective device utilization and limits market potential realization, requiring manufacturer-led patient education investment to close the gap between clinical need and actual device adoption rates.
- Supply Chain Dependencies and Import Logistics: Saudi Arabia's oxygen concentrator market relies entirely on imported devices from the United States, Europe, and Japan, creating supply chain vulnerability to geopolitical disruptions and shipping delays. Extended import lead times of 4–8 weeks require significant inventory buffer investment throughout the distribution chain. The absence of domestic manufacturing conflicts with Vision 2030's local content objectives and exposes the market to concentrated supply disruption risks.
Emerging Market Trends
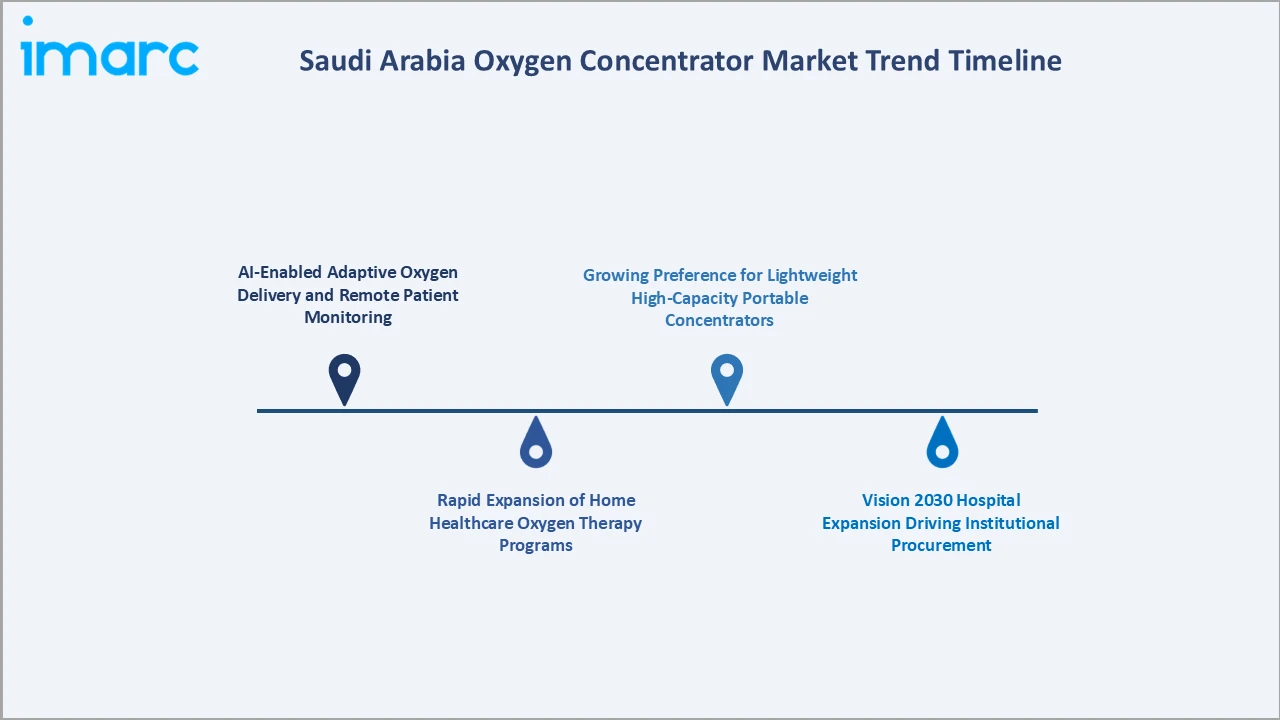
1. AI-Enabled Adaptive Oxygen Delivery and Remote Patient Monitoring
Advanced concentrators incorporating AI-driven adaptive delivery algorithms are emerging as next-generation standards, optimizing oxygen flow based on real-time patient respiratory pattern analysis. Integration with Saudi Arabia's telemedicine infrastructure enables remote therapy compliance monitoring and oxygen saturation tracking, improving clinical outcomes and reducing unnecessary hospital visits for stable home oxygen therapy patients.
2. Rapid Expansion of Home Healthcare Oxygen Therapy Programs
Saudi Arabia's MOH home healthcare expansion strategy creates structured pathways for stable respiratory patients to transition from hospital to home-based oxygen therapy, supported by portable concentrator procurement through CCHI-covered home medical equipment programs. According to government data, Saudi Arabia allocates significant healthcare budget toward chronic disease home management, directly expanding the addressable portable concentrator market.
3. Vision 2030 Hospital Expansion Driving Institutional Procurement
Saudi Arabia's Vision 2030 healthcare program is delivering a multi-year wave of new tertiary hospital commissioning across all four regions, each requiring comprehensive medical equipment including stationary oxygen concentrators. The MOH target of 2.5 beds per 1,000 population creates a predictable institutional procurement pipeline sustaining stationary concentrator demand through the forecast period across all administrative regions.
4. Growing Preference for Lightweight High-Capacity Portable Concentrators
Patient demand for POCs combining clinical-grade oxygen purity with progressively lighter weights and extended battery duration is driving manufacturer innovation toward compact next-generation designs. In June 2025, Inogen, Inc. launched the Voxi 5 stationary concentrator, combining affordability with durability and setting new standards that influence purchasing across Saudi Arabia's institutional and home care channels.
Industry Value Chain Analysis
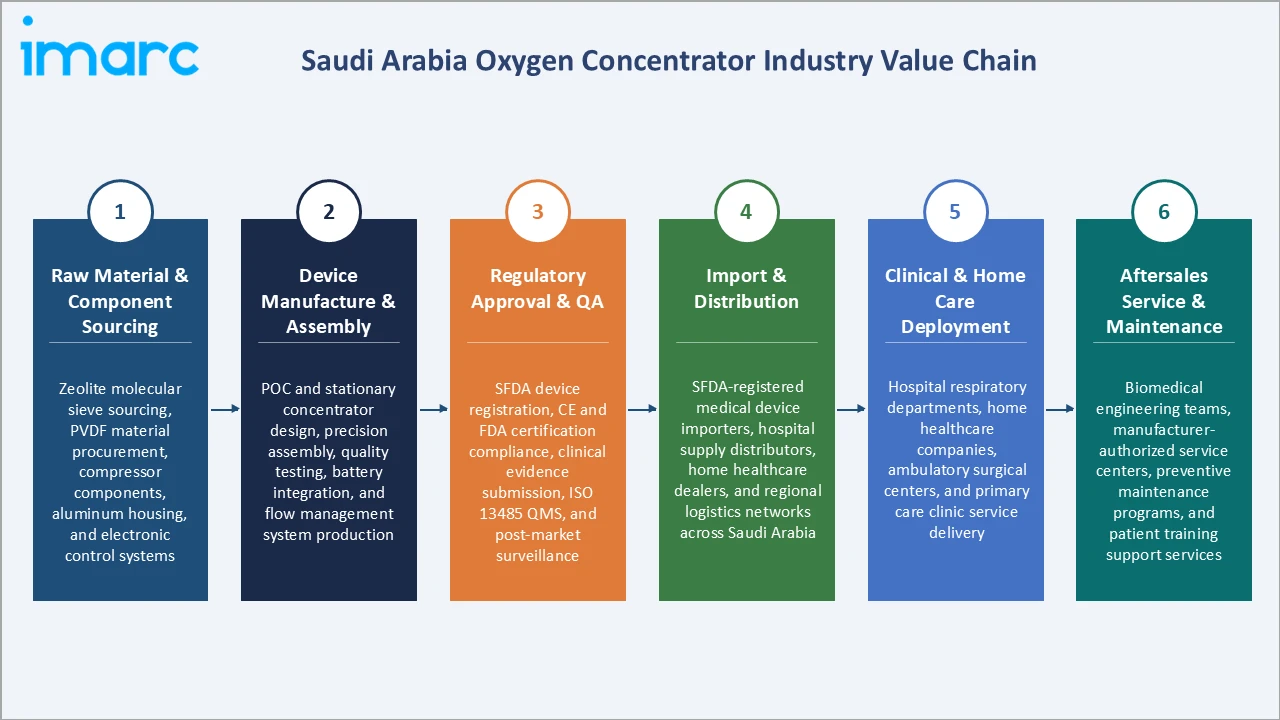
The oxygen concentrator value chain integrates raw material and zeolite sourcing, device manufacturing and quality testing, SFDA regulatory approval, import and regional distribution, clinical and home care deployment, and ongoing maintenance services across Saudi Arabia's healthcare network. The value chain is progressively consolidating toward integrated device-service contracts as NWC and hospital groups prefer turnkey respiratory care supply arrangements.
|
Stage |
Key Participants |
|
Raw Material & Component Sourcing |
Zeolite molecular sieve sourcing, PVDF material procurement, compressor components, aluminum housing, and electronic control systems |
|
Device Manufacture & Assembly |
POC and stationary concentrator design, precision assembly, quality testing, battery integration, and flow management system production |
|
Regulatory Approval & QA |
SFDA device registration, CE and FDA certification compliance, clinical evidence submission, ISO 13485 QMS, and post-market surveillance |
|
Import & Distribution |
SFDA-registered medical device importers, hospital supply distributors, home healthcare dealers, and regional logistics networks across Saudi Arabia |
|
Clinical & Home Care Deployment |
Hospital respiratory departments, home healthcare companies, ambulatory surgical centers, and primary care clinic service delivery |
|
Aftersales Service & Maintenance |
Biomedical engineering teams, manufacturer-authorized service centers, preventive maintenance programs, and patient training support services |
The device manufacture and assembly tier is the value chain's most commercially critical stage, with the key players controlling dominant technology positions. The import and distribution tier is evolving most rapidly as direct-to-patient home care channels reshape traditional distributor-led supply structures.
Technology Landscape in the Saudi Arabia Oxygen Concentrator Industry
Pressure Swing Adsorption (PSA) Technology
PSA technology is the dominant oxygen concentration method across portable and stationary concentrators, using zeolite molecular sieves to selectively adsorb nitrogen and produce oxygen-enriched output at 87–96% purity. PSA delivers reliable continuous-duty performance for both hospital systems and home-based portable units. Advances in zeolite formulation by leading manufacturers are progressively improving PSA energy efficiency by up to 20% in next-generation product lines.
Pulse Dose Delivery Technology
Pulse dose delivery technology represents the most significant recent advance in POC design, using breath-detection sensors and adaptive algorithms to deliver precisely calibrated oxygen boluses synchronized with patient inhalation cycles, significantly reducing energy consumption versus continuous flow.
Continuous Flow Technology
Continuous flow technology remains the dominant delivery method in hospital and clinical settings, providing constant-rate oxygen output suited to acute respiratory patient management, post-surgical recovery, and ICU applications. Continuous flow stationary concentrators dominate Saudi Arabia's hospital procurement, with newer high-efficiency models reducing per-liter oxygen delivery energy costs across large-volume institutional deployments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Portable |
58.7% |
2025 |
|
Technology |
Continuous Flow |
62.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End User |
🔒 |
🔒 |
2025 |
|
Region |
Western Region |
35.4% |
2025 |
By Type
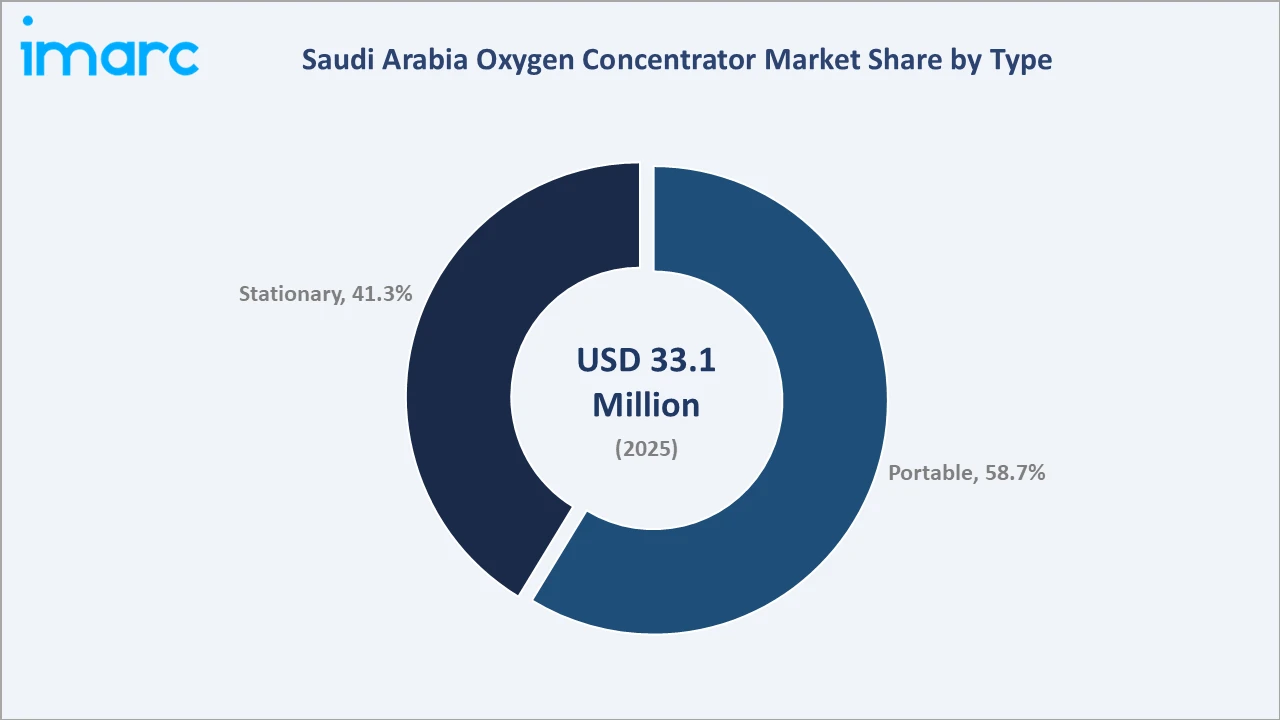
The Portable segment leads at 58.7% in 2025, encompassing the dominant oxygen concentrator configuration for Saudi Arabia's expanding home care and mobile patient population, positioned as the commercially preferred device type for both institutional discharge programs and direct home care oxygen therapy prescriptions.
To access detailed market analysis, Request Sample
The Stationary segment at 41.3% maintains significant market presence through sustained hospital and clinical facility procurement, where continuous-duty operation requirements, higher flow rate capability, and lower per-unit cost make stationary concentrators the preferred choice. Stationary concentrators dominate in intensive care, emergency departments, and surgical recovery settings requiring consistent high-flow oxygen delivery.
By Technology
Continuous Flow technology leads at 62.8% in 2025, driven by widespread deployment across Saudi Arabia's tertiary hospitals and specialized care centers where consistent, uninterrupted oxygen delivery is required for acute and severe respiratory patient management under clinical supervision and hospital protocol.
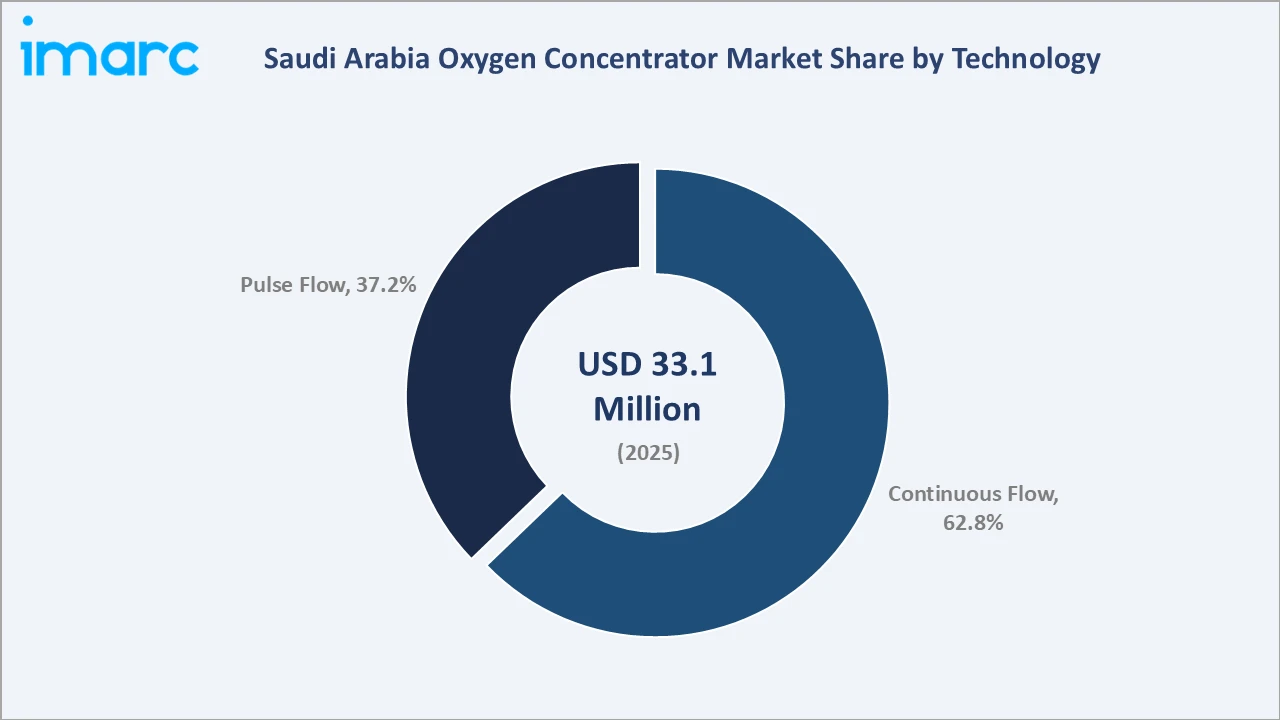
Pulse Flow technology at 37.2% is the fastest-growing segment as portable concentrator adoption accelerates in home care settings, where pulse dose delivery's superior battery efficiency and patient-responsive output provide clinical advantages. Improving pulse flow detection accuracy is progressively expanding clinical suitability to higher acuity patient categories, broadening the addressable home care market.
Regional Market Insights
|
Region |
Share (2025) |
Key Oxygen Concentrator Market Drivers & Characteristics |
|
Western Region |
35.4% |
Driven by Makkah and Jeddah's large tertiary hospital network, high pilgrimage-related respiratory health demands, and the Kingdom's highest concentration of specialized respiratory care centers |
|
Northern and Central Region |
32.1% |
Driven by Riyadh's metropolitan healthcare infrastructure, Vision 2030 National Guard and MOH hospital expansion programs, and the capital's large aging and COPD patient population |
|
Eastern Region |
20.6% |
Supported by industrial workforce respiratory health demands from oil and gas sector exposure, ARAMCO employee healthcare facilities, and Dammam's expanding private hospital network |
|
Southern Region |
11.9% |
Emerging with MOH primary care network expansion, rising COPD diagnosis rates, and government initiatives to improve rural healthcare equipment access and home care services |
Western Region, at 35.4%, leads through Makkah and Jeddah's high population density and the Kingdom's highest hospital investment concentration. Northern and Central Region, at 32.1%, reflects Riyadh's metropolitan healthcare expansion and Vision 2030's capital region hospital development program.
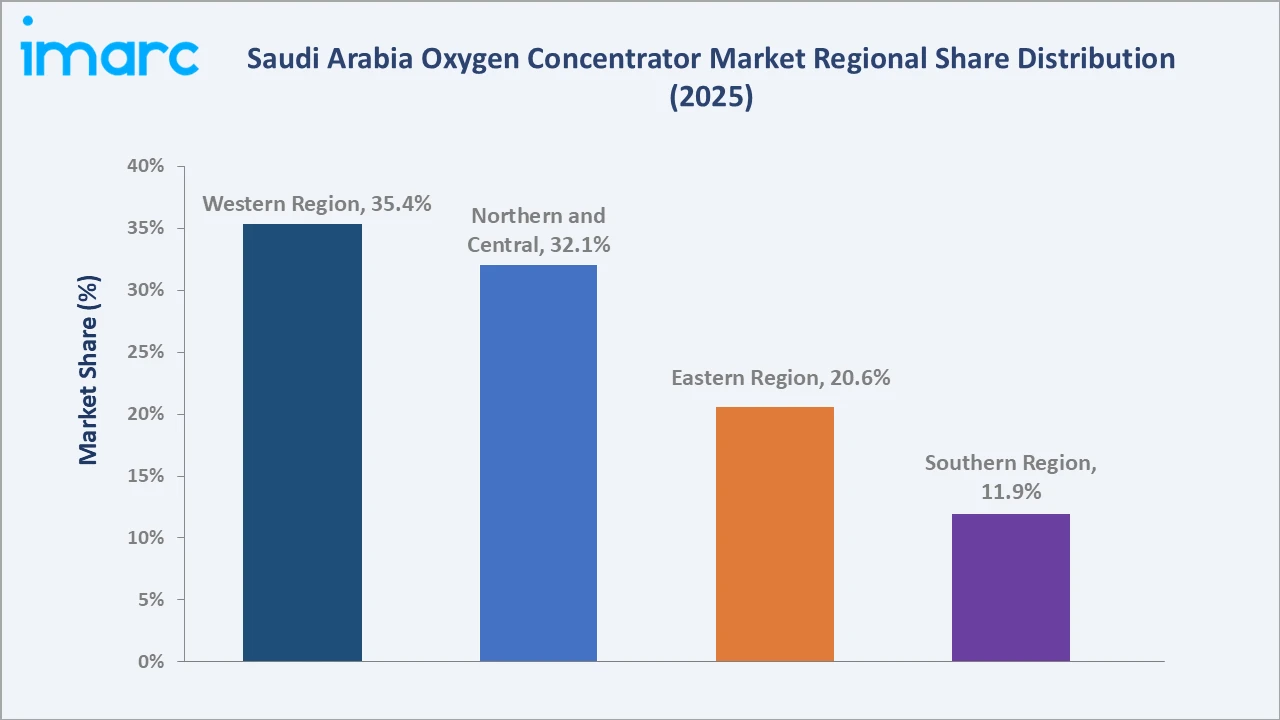
Eastern Region, at 20.6%, reflects the oil and gas industrial sector's occupational respiratory health demands and ARAMCO's extensive employee healthcare system driving institutional concentrator procurement. Southern Region, at 11.9%, represents the early-stage market supported by MOH rural healthcare equipment programs and rising respiratory disease awareness.
Competitive Landscape
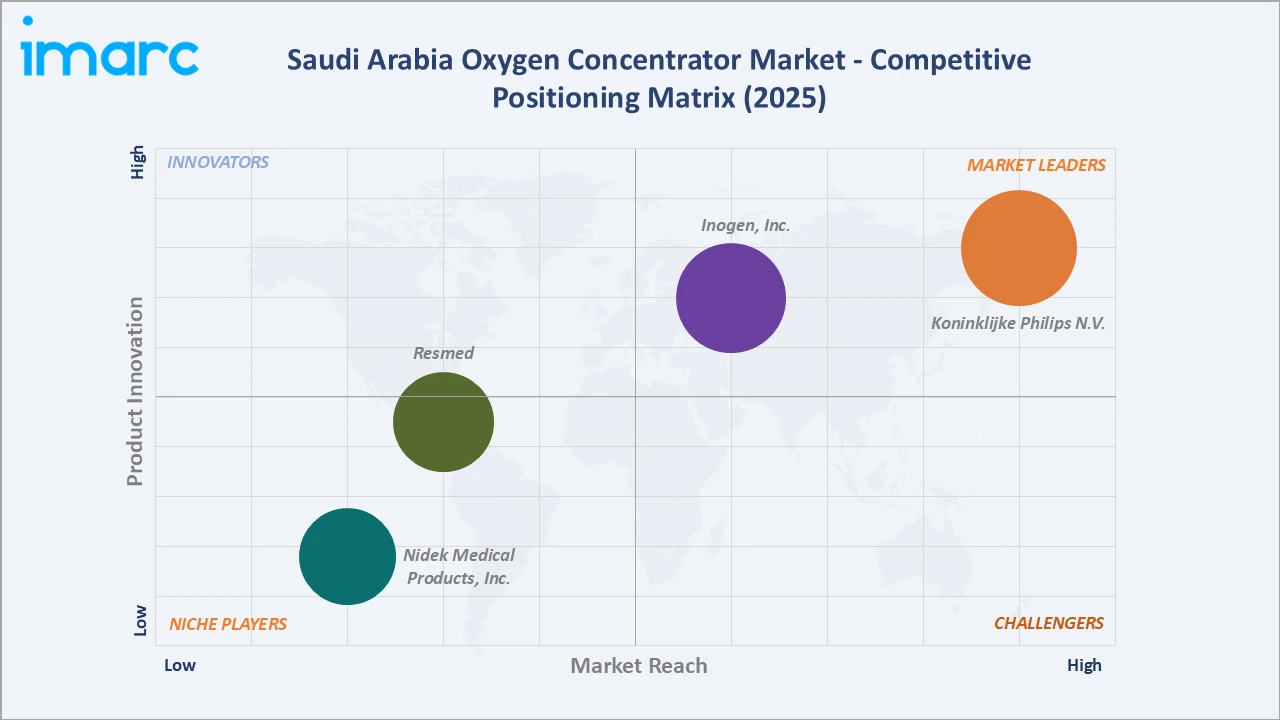
The Saudi Arabia oxygen concentrator market competitive landscape is moderately concentrated, led by global respiratory device specialists alongside established medical device companies competing through clinical performance, SFDA compliance positioning, and distribution network strength.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Koninklijke Philips N.V. |
SimplyFlo |
Market Leader |
Koninklijke Philips N.V. is a Netherlands-based medical device leader providing comprehensive stationary and portable oxygen concentrators with established clinical trust across Saudi Arabia's hospital and home care segments. |
|
Inogen, Inc. |
Rove 4, Rove 6 |
Market Leader |
Inogen, Inc. is a US-based portable oxygen concentrator specialist known for lightweight, high-performance POC devices targeting Saudi Arabia's growing home care and ambulatory oxygen therapy segments. |
|
Resmed |
Mobi POC |
Emerging Player |
ResMed is a respiratory device company supplying advanced portable oxygen and ventilation therapy solutions with growing presence in Saudi Arabia's private hospital and home care channels. |
|
Nidek Medical Products, Inc. |
Nuvo Lite Mark 5, Nuvo 8 |
Niche Player |
Nidek Medical Products, Inc. is a US-based oxygen concentrator manufacturer providing reliable stationary concentrators at competitive price points serving Saudi Arabia's government hospital procurement programs. |
Key players include Koninklijke Philips N.V., Inogen, Inc., Resmed, Nidek Medical Products, Inc., and others.
Key Company Profiles
Koninklijke Philips N.V.
Koninklijke Philips N.V. is a Netherlands-based global medical device leader with a strong presence in the Saudi Arabia oxygen concentrator market through its stationary and portable POC product lines deployed across hospital and home care channels.
- Key Products: SimplyFlo Lightweight Concentrator, DreamStation Portable Oxygen Concentrator.
- Strategic Focus: Expanding integrated respiratory care solutions combining oxygen concentrator hardware with connected patient monitoring platforms and clinical data management systems, aligned with Saudi Arabia's Vision 2030 digital health agenda and the MOH's telemedicine infrastructure investment program for home-based chronic disease management.
Inogen, Inc.
Inogen, Inc. is a US-based portable oxygen concentrator specialist with a growing presence in the Saudi Arabia market through its Inogen One G5 and Rove 4 lightweight portable devices targeting home care and ambulatory respiratory therapy patients.
- Key Products: Inogen Rove 4 POC, Inogen At Home G5 Stationary, Voxi 5 Stationary Oxygen Concentrator.
- Strategic Focus: Advancing POC technology toward lighter device weights, extended battery duration, and integrated smart monitoring, addressing the clinical and lifestyle requirements of Saudi Arabia's growing home oxygen therapy patient population while expanding direct-to-patient and home care partnership channels to accelerate POC adoption beyond the traditional hospital prescription pathway.
Market Concentration Analysis
The Saudi Arabia oxygen concentrator market is moderately concentrated at the premium clinical device level, with the key players collectively accounting for approximately 50-60% of the Kingdom's total oxygen concentrator revenue. International device manufacturers control the entire market through import channels, as no domestic manufacturing exists.
Investment & Growth Opportunities
Highest Growth Segments
Pulse Flow portable concentrators (~5.7% CAGR), smart POC with telemedicine connectivity (~12% CAGR), home care oxygen therapy programs (~8% CAGR), AI-adaptive respiratory monitoring devices (~15% CAGR from early base), and Southern Region market penetration programs (~7.5% CAGR from low base) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's planned home healthcare infrastructure expansion under Vision 2030 represents the highest-value emerging opportunity, with MOH home care programs targeting the transition of 500,000+ stable chronic disease patients from hospital to home settings, creating structured procurement demand for portable concentrators across a patient population currently lacking systematic access to home oxygen therapy.
Investment Themes
- Local assembly and SFDA manufacturing approval for oxygen concentrators under Vision 2030 local content framework: Saudi Arabia's 100% import dependency for oxygen concentrators creates a domestic manufacturing opportunity aligned with Vision 2030's medical device localization strategy, offering potential import duty advantages and procurement preference under government hospital tender programs prioritizing locally manufactured medical equipment.
- Integrated respiratory care service platform combining POC devices with remote monitoring and telemedicine clinical support: Vision 2030's digital health investment and MOH telemedicine infrastructure program create demand for integrated platforms combining SFDA-compliant oxygen concentrators with connected monitoring apps, remote therapy adjustment capability, and AI-driven clinical decision support for managing Saudi Arabia's large and growing COPD home therapy patient population.
Future Market Outlook (2026-2034)
The Saudi Arabia oxygen concentrator market is projected to grow from USD 33.1 Million in 2025 to USD 53.2 Million by 2034, delivering a 5.24% CAGR over the forecast period. The market anchor of approximately USD 42.7 Million in 2030 represents the sector at its Vision 2030 healthcare modernization delivery peak, with substantial hospital capacity additions commissioned and home care programs reaching operational scale.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders (2025), including MOH procurement officials, hospital respiratory department heads, home care equipment distributors, SFDA-registered medical device importers, CCHI reimbursement specialists, and respiratory therapy clinicians active in Saudi Arabia's major healthcare centers.
Secondary Research
Secondary research encompassed MOH annual healthcare reports; Vision 2030 healthcare program documentation; SFDA medical device registration databases; WHO respiratory disease prevalence data for Saudi Arabia; global oxygen concentrator manufacturer annual reports and product literature; GCC healthcare market research publications 2024-2025; and Saudi Arabia private hospital sector expansion announcements. Over 45 secondary sources reviewed.
Forecasting Models
Market revenue forecasts developed using a bottom-up model: (i) Saudi Arabia respiratory disease patient population requiring supplemental oxygen; (ii) hospital bed expansion pipeline from MOH capital project database; (iii) average concentrator procurement value per hospital bed and home care patient; (iv) device replacement cycle revenue; (v) regional allocation based on population distribution and healthcare infrastructure investment weighting.
Saudi Arabia Oxygen Concentrator Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Portable, Stationary |
| Technologies Covered | Continuous Flow, Pulse Flow |
| Applications Covered | Chronic Obstructive Pulmonary Disease (COPD), Asthma, Respiratory Distress, Others |
| End Users Covered | Hospitals and Clinics, Home Care Settings, Ambulatory Surgical Centers and Physician Offices |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Comapnies Covered | Koninklijke Philips N.V., Inogen, Inc., Resmed, Nidek Medical Products, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia oxygen concentrator market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia oxygen concentrator market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia oxygen concentrator industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Oxygen Concentrator Market Report
The Saudi Arabia oxygen concentrator market reached USD 33.1 Million in 2025, driven by Portable type dominant at 58.7%, Continuous Flow technology leading at 62.8%, Vision 2030 healthcare investment, and Western Region commanding 35.4% through Makkah and Jeddah's high hospital density and pilgrimage-related respiratory health demands.
The Saudi Arabia oxygen concentrator market grows at 5.24% CAGR during 2026-2034, reaching USD 53.2 Million by 2034. This reflects sustained Vision 2030 hospital expansion procurement, growing home care oxygen therapy adoption, rising COPD and respiratory disease burden, and expanding CCHI insurance coverage for home oxygen therapy equipment.
Portable type leads at 58.7%, capturing the expanding home care and ambulatory patient market as lightweight, battery-powered devices enable patient mobility and home-based oxygen therapy independence. Portable concentrators grow at approximately 5.7% CAGR through MOH home healthcare expansion and growing physician prescription rates.
Continuous Flow technology leads at 62.8% through widespread deployment across Saudi Arabia's hospital and clinical facility network where consistent oxygen delivery is required for acute patient management. Pulse Flow is the fastest-growing segment at approximately 5.7% CAGR as home care portable concentrator adoption accelerates.
Western Region leads at 35.4% through Makkah and Jeddah's high population density and the Kingdom's highest concentration of tertiary hospitals. Northern and Central Region at 32.1% reflects Riyadh's metropolitan healthcare expansion, while Eastern Region at 20.6% reflects oil and gas industrial sector respiratory health demands.
Leading companies include Koninklijke Philips N.V., Inogen, Inc., Resmed, Nidek Medical Products, Inc., and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade