
Small Drones Market Size, Share, Trends and Forecast by Size, Type, Application, and Region, 2026-2034
Small Drones Market Size, Share, Trends & Forecast (2026-2034)
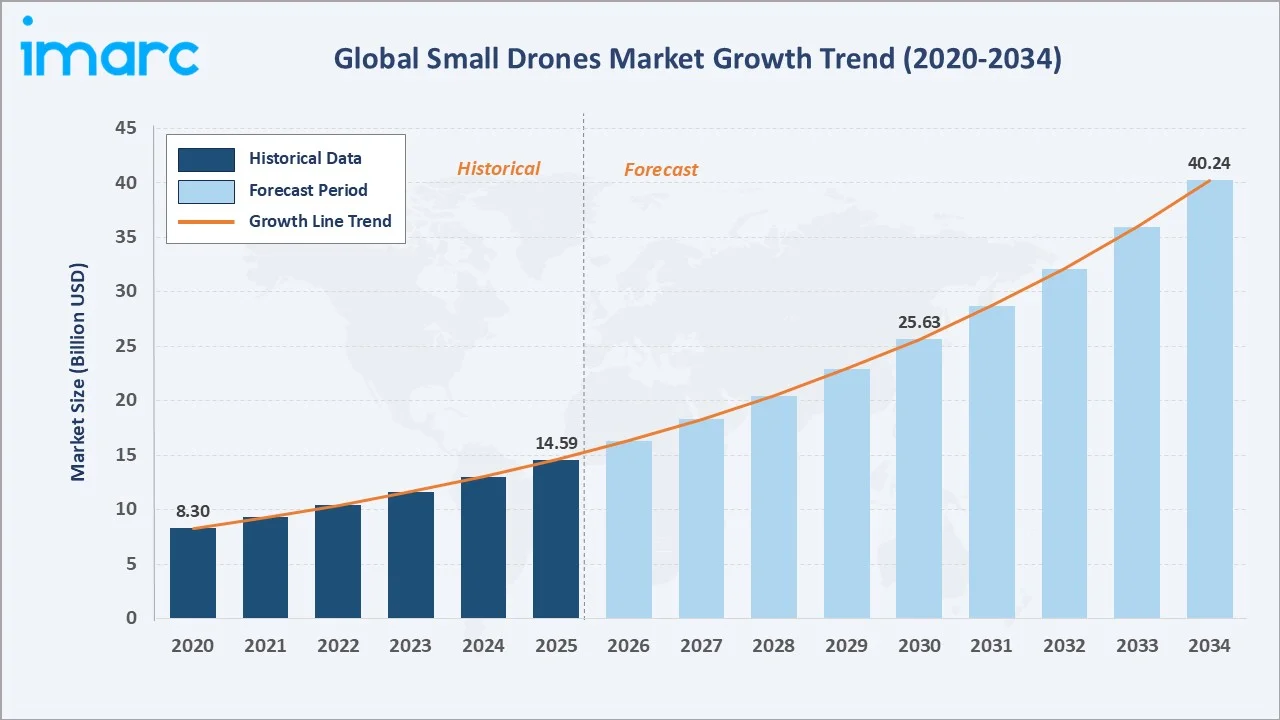
The small drones market grew from USD 14.59 Billion in 2025 to USD 16.33 Billion in 2026 and is projected to reach USD 40.24 Billion by 2034, growing at a CAGR of 11.93% during 2026-2034. The market is driven by escalating defense procurement, rapid AI-powered autonomy integration, and expanding commercial applications across agriculture, infrastructure inspection, and public safety. Micro drones lead at 65.0% by size, rotary wing dominates at 53.8% by type, and North America commands the largest regional share at 32.4% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 14.59 Billion |
|
Market Size (2026) |
USD 16.33 Billion |
|
Forecast Market Size (2034) |
USD 40.24 Billion |
|
CAGR (2026-2034) |
11.93% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Size |
Micro Drones (65.0%, 2025) |
|
Dominant Type |
Rotary Wing (53.8%, 2025) |
|
Leading Region |
North America (32.4%, 2025) |
The small drones market grew from USD 8.30 Billion in 2020 to USD 14.59 Billion in 2025, and further to USD 16.33 Billion in 2026, reflecting accelerating demand across defense, commercial, and industrial segments driven by AI-enabled autonomy, regulatory evolution enabling BVLOS operations, and the structural shift in US defense procurement away from Chinese-manufactured platforms. The market is projected to reach USD 25.63 Billion by 2030 before reaching USD 40.24 Billion by 2034.
To get more information on this market, Request Sample
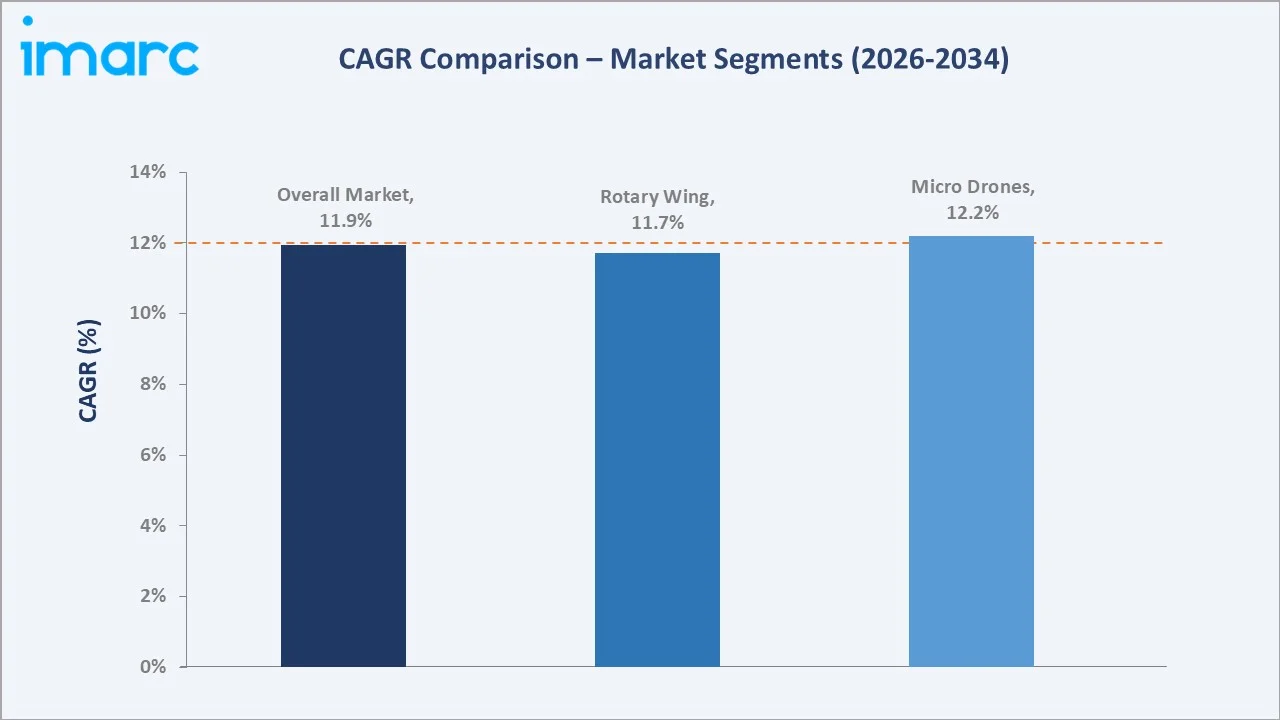
Micro drones are growing at a 12.2% CAGR as their versatility across both military tactical operations and commercial inspection applications drives sustained adoption. Rotary wing drones at 11.7% CAGR reflect their dominance in both military short-range reconnaissance missions and commercial sectors where hover capability and precision landing are operationally critical.
Executive Summary
The small drones market is experiencing structural acceleration driven by three concurrent forces: unprecedented defense procurement expansion as conflicts in Ukraine and beyond have validated small unmanned aerial systems as decisive tactical assets; regulatory evolution enabling commercial operations that unlock new enterprise use cases; and a geopolitical market restructuring, creating a demand void that domestic US manufacturers are racing to fill.
Micro drones lead at 65.0% by size, serving both the military squad-level reconnaissance role and the commercial precision agriculture and industrial inspection markets where compact platforms with advanced imaging sensors provide the best cost-to-capability ratio. Rotary wing at 53.8% leads by type, reflecting the operational superiority of multirotor platforms for hover-dependent tasks including surveillance, inspection, and search and rescue operations where fixed wing platforms cannot operate. North America at 32.4% leads regionally, anchored by the US defense procurement surge, domestic drone vendor program, and favorable regulatory evolution.
Key Market Insights
|
Insight |
Data |
|
Dominant Size |
Micro Drones - 65.0% share (2025) |
|
Dominant Type |
Rotary Wing - 53.8% share (2025) |
|
Leading Region |
North America - 32.4% (2025) |
|
Key Market Opportunity |
Defense and security applications, commercial surveillance, aerial mapping and surveying, precision agriculture, infrastructure inspection, logistics and delivery, disaster management, media and entertainment, construction monitoring, environmental monitoring, and integration of AI, automation, and advanced sensing technologies. |
Key Analytical Observations Supporting the Above Data:
- Micro Drones at 65.0%: Micro drones dominate because the sub-25 kilogram class accounts for the largest market segment by volume and value, serving the broadest range of military and commercial applications. Micro drones span military squad-level ISR, commercial mapping and precision agriculture, infrastructure inspection, first responder operations, and media production, collectively representing the largest addressable market within the small drone category.
- Rotary Wing at 53.8%: Rotary wing drones lead because multirotor and single-rotor platforms provide hover capability that is operationally essential across the majority of commercial and tactical military applications. For commercial applications including bridge inspection, power line inspection, and precision agricultural imaging, hover capability enables data collection precision impossible with fixed-wing platforms.
- North America at 32.4%: North America leads because the United States maintains the largest defense drone procurement budget, with Trump’s USD 1.5 Trillion defense budget request for fiscal year 2027 and is concentrating commercial procurement toward domestic and allied-nation manufacturers that are primarily US-headquartered.
Small Drones Market Overview
The small drones market encompasses all unmanned aerial vehicles in the micro (1-25 kg) and nano (under 1 kg) weight categories, operating across military, commercial, and recreational applications. Key product categories within the small drones market include man-portable military reconnaissance systems; tactical loitering munitions; commercial multirotor platforms for aerial photography, precision agriculture, and infrastructure inspection; autonomous AI-powered platforms for public safety; fixed-wing mapping drones for large-area surveying; and miniaturized nano drones for indoor surveillance and confined space inspection.
The market operates across two primary demand categories: military and defense, where small drones serve intelligence, surveillance, and reconnaissance roles; direct attack through loitering munitions; electronic warfare; and logistics; and commercial, industrial, and public safety, where drones serve precision agriculture, infrastructure inspection, emergency response, delivery, mapping, and security applications.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
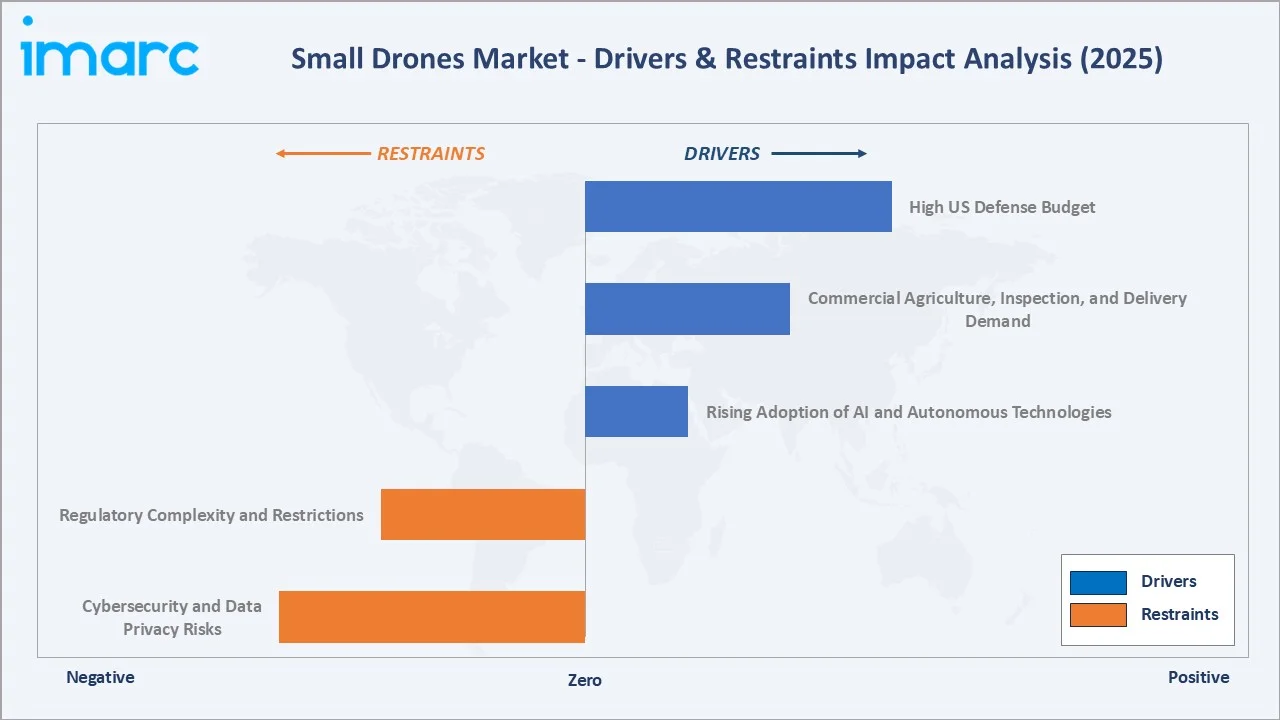
- High US Defense Budget: Trump’s USD 1.5 Trillion defense budget request for fiscal year 2027, an unprecedented dedicated budget line that signals a structural, long-term defense procurement commitment to unmanned systems. Higher US defense spending is supporting increased procurement and deployment of small drones for intelligence, surveillance, reconnaissance, border security, and tactical operations. Growing investments in autonomous and unmanned systems are encouraging technological development and expanding demand for advanced small drone solutions
- Commercial Agriculture, Inspection, and Delivery Demand: The expansion of commercial drone applications across agriculture, infrastructure inspection, construction site monitoring, and last-mile logistics is diversifying the small drones demand base beyond pure defense procurement. Agricultural drones, including fixed-wing spraying platforms and multirotor precision imaging systems, are becoming standard input tools for crop management, with adoption accelerating in India, Brazil, and Southeast Asia.
- Rising Adoption of AI and Autonomous Technologies: Advancements in artificial intelligence, computer vision, navigation, and onboard processing are enhancing small drone capabilities. AI-enabled drones can increasingly support automated object detection, route planning, tracking, and data analysis. Improved autonomy also reduces dependence on continuous manual control during certain operations. These technological developments are broadening the applications and commercial potential of small drones.
Market Restraints
- Cybersecurity and Data Privacy Risks: Small drones increasingly rely on wireless communications, GPS, cloud platforms, and connected control systems. These technologies can expose drone operations to hacking, signal interference, data theft, and unauthorized access. Concerns are particularly significant for defense, surveillance, infrastructure, and sensitive commercial applications. Manufacturers therefore face growing pressure to strengthen cybersecurity and data-protection capabilities.
- Regulatory Complexity and Restrictions: The regulatory frameworks governing small drone operations create compliance complexity for commercial operators seeking to scale drone operations across multiple markets. Restricted airspace around airports, urban areas, critical infrastructure, and temporary flight restrictions create operational gaps that limit commercial use case viability in high-density areas where drone applications would otherwise generate the highest value.
Market Opportunities
- High-Altitude Tactical Drone Deployment: In September 2026, Zenith Unmanned Systems successfully operated its Vijay-Z1 tactical drone at 14,000 feet for 1 hour and 18 minutes during high-altitude trials with the Indian Army’s Eastern Command in Arunachal Pradesh. The drone demonstrated reliable performance in low-density air and challenging weather conditions, including heavy rain and fog, supporting its use in reconnaissance, search and rescue, and continuous surveillance missions. The successful high-altitude performance creates opportunities for small tactical drones in mountainous border surveillance, reconnaissance, search and rescue, and disaster-response missions.
- Last-Mile Logistics and Urban Air Mobility Applications: Drone delivery services for medical supply, e-commerce last-mile fulfillment, and emergency logistics are advancing from pilot programs toward commercial-scale operations, representing a large addressable market opportunity that requires specifically designed small fixed-wing and hybrid VTOL platforms optimized for payload capacity, range, and regulatory compliance with emerging urban air mobility frameworks.
Market Challenges
- Signal Interference and Connectivity Issues: Small drones often depend on reliable communication links and navigation signals for safe and effective operation. Interference, signal blockage, and limited connectivity can affect control, positioning, and data transmission. Urban environments, mountainous terrain, and remote areas can create additional communication challenges. These issues can restrict the reliability of drones during long-range or mission-critical operations.
- High Technology and Development Costs: Advanced small drones require sophisticated sensors, navigation systems, communication technologies, and autonomous capabilities. Research and development expenses can increase the cost of developing and commercializing advanced platforms. Integration of AI, imaging systems, secure communications, and specialized payloads can further raise production costs. This may create adoption barriers for smaller organizations and price-sensitive customers.
Emerging Market Trends
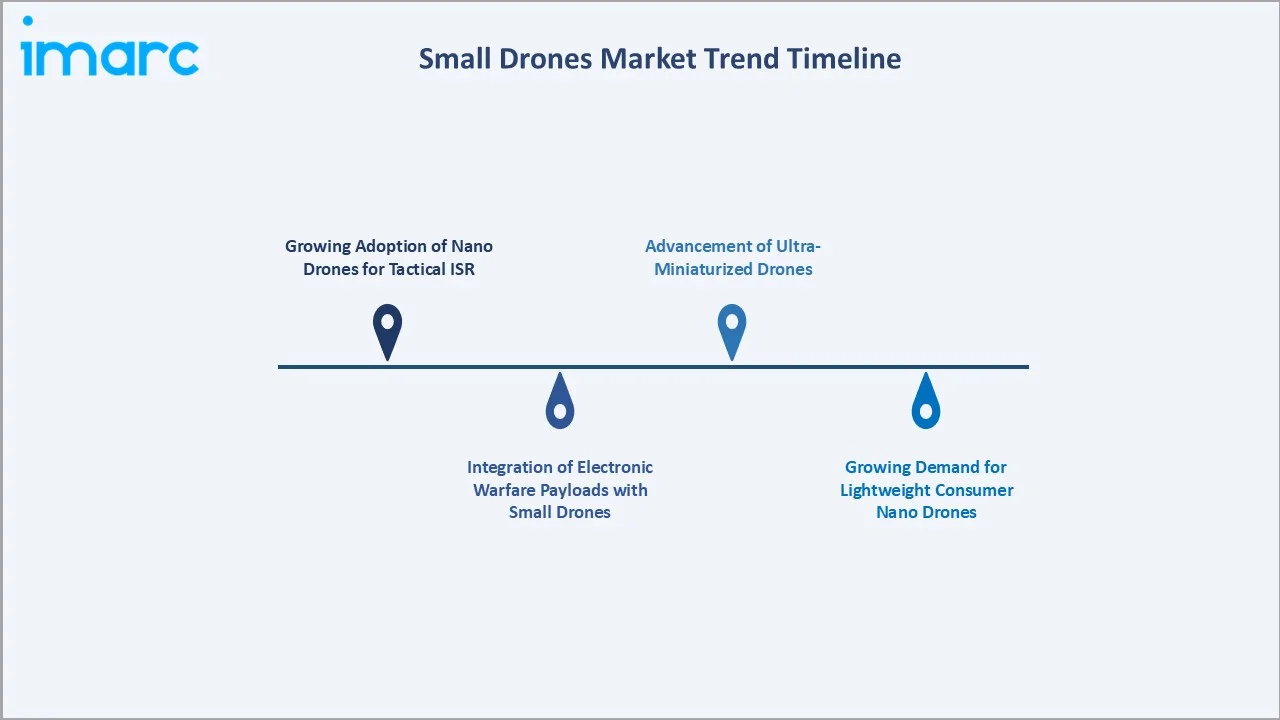
1. Growing Adoption of Nano Drones for Tactical ISR
In May 2026, Vayudh introduced Atri, a nano surveillance drone designed to enhance compact tactical intelligence, surveillance, and reconnaissance (ISR) capabilities. The drone is engineered for aerial monitoring and situational awareness in high-risk operational environments. The launch highlights an emerging trend toward highly compact nano drones designed for intelligence, surveillance, and reconnaissance (ISR) missions. Their small size and portability enable discreet aerial monitoring and deployment in high-risk and challenging operational environments.
2. Integration of Electronic Warfare Payloads with Small Drones
In June 2025, Thales introduced a lightweight electronic warfare payload for small drones that can detect and locate radio signals. Designed for easy deployment without specialized operator training, the system provides military units with portable, discreet, and adaptable electromagnetic intelligence capabilities. The launch highlights a growing trend toward equipping small drones with lightweight electronic warfare sensors for real-time signal detection and intelligence gathering. This enables more agile, discreet, and rapidly deployable electromagnetic surveillance capabilities for frontline military operations.
3. Advancement of Ultra-Miniaturized Drones
In July 2025, China’s National University of Defense Technology (NUDT) developed a mosquito-sized micro aerial vehicle designed to closely replicate the appearance and movement of a real mosquito. The development highlights advances in drone miniaturization, micro-robotics, and stealth-oriented aerial technology. Such technologies could expand small drone applications in covert surveillance, reconnaissance, and intelligence-gathering missions.
4. Growing Demand for Lightweight Consumer Nano Drones
In January 2024, IZI launched the MINI X, a 249-gram 4K nano drone available in Standalone and Fly More Combo variants. The launch expands India’s consumer drone offerings with advanced aerial features and a starting price of Rs 29,999. Increasing portability, ease of use, and accessible pricing are supporting broader adoption of nano drones for photography, recreation, and content creation.
Industry Value Chain Analysis
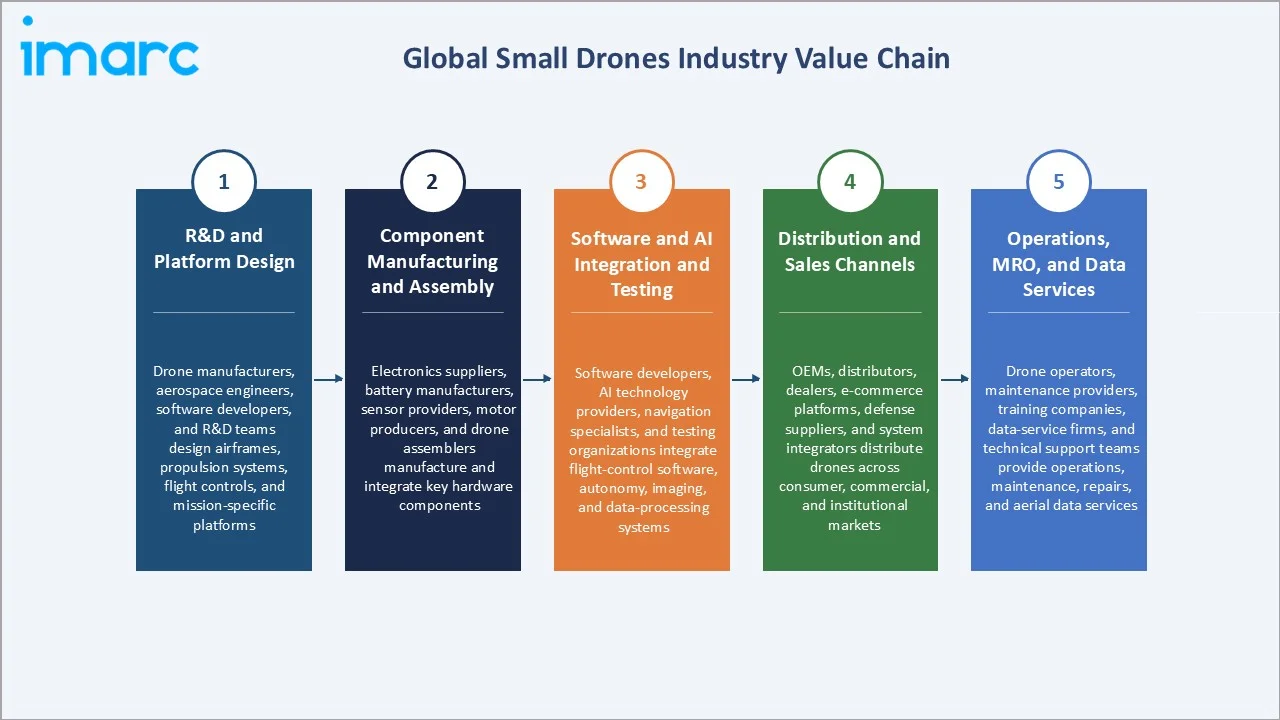
The small drones market value chain spans five integrated stages from R&D and platform design through operational services. The software, AI integration, and testing stage captures the highest per-unit value addition, as artificial intelligence, mission management software, encrypted communications, and autonomous navigation represent the primary technical differentiation and intellectual property concentration in modern small drone platforms.
|
Stage |
Key Participants |
|
R&D and Platform Design |
Drone manufacturers, aerospace engineers, software developers, and R&D teams design airframes, propulsion systems, flight controls, and mission-specific platforms. |
|
Component Manufacturing and Assembly |
Electronics suppliers, battery manufacturers, sensor providers, motor producers, and drone assemblers manufacture and integrate key hardware components. |
|
Software and AI Integration and Testing |
Software developers, AI technology providers, navigation specialists, and testing organizations integrate flight-control software, autonomy, imaging, and data-processing systems. |
|
Distribution and Sales Channels |
OEMs, distributors, dealers, e-commerce platforms, defense suppliers, and system integrators distribute drones across consumer, commercial, and institutional markets. |
|
Operations, MRO, and Data Services |
Drone operators, maintenance providers, training companies, data-service firms, and technical support teams provide operations, maintenance, repairs, and aerial data services. |
The software and AI integration stage is the highest value-added stage in the small drones value chain. Drone platforms that incorporate superior AI-powered obstacle avoidance, autonomous mission execution, encrypted communications, and cloud-based fleet management software command significant price premiums and retention advantages over hardware-equivalent competitors.
Technology Landscape in the Small Drones Industry
AI-Powered Autonomous Navigation and Obstacle Avoidance
Onboard AI processing enabling real-time autonomous obstacle avoidance, terrain following, and target tracking without ground control input is the defining technology differentiator in modern small drone platforms. The convergence of miniaturized AI processors with advanced imaging sensors is enabling autonomous capabilities in platforms under 5 kg that previously required aircraft-scale computing resources.
Extended Battery Technology and Hybrid Propulsion
Battery energy density improvements and the emergence of hydrogen fuel cell and hybrid propulsion systems are progressively extending small drone endurance from the 20-30 minute limitation of current battery-electric multirotor platforms toward 1-4 hour endurance capabilities that enable enterprise operational use cases including perimeter security monitoring and agricultural field inspection without mid-mission battery swaps. Solid-state battery development by manufacturers is expected to deliver 2-3 times the energy density of current lithium polymer cells, directly enabling proportional endurance extension for small drone platforms.
Miniaturized Multi-Spectral and Thermal Sensor Integration
Advanced imaging payload miniaturization is enabling small drones below 2 kg to carry multi-spectral, thermal infrared, LiDAR, and hyperspectral sensor payloads that were previously limited to much larger platforms. Agricultural multi-spectral sensors enabling crop health index analysis are driving adoption of dedicated agricultural micro-drone platforms that combine precision imaging with automated flight path planning for whole-field coverage.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Size |
Micro Drones |
65.0% |
2025 |
|
Type |
Rotary Wing |
53.8% |
2025 |
|
Application |
Military and Defense |
🔒 |
2025 |
|
Region |
North America |
32.4% |
2025 |

By Size
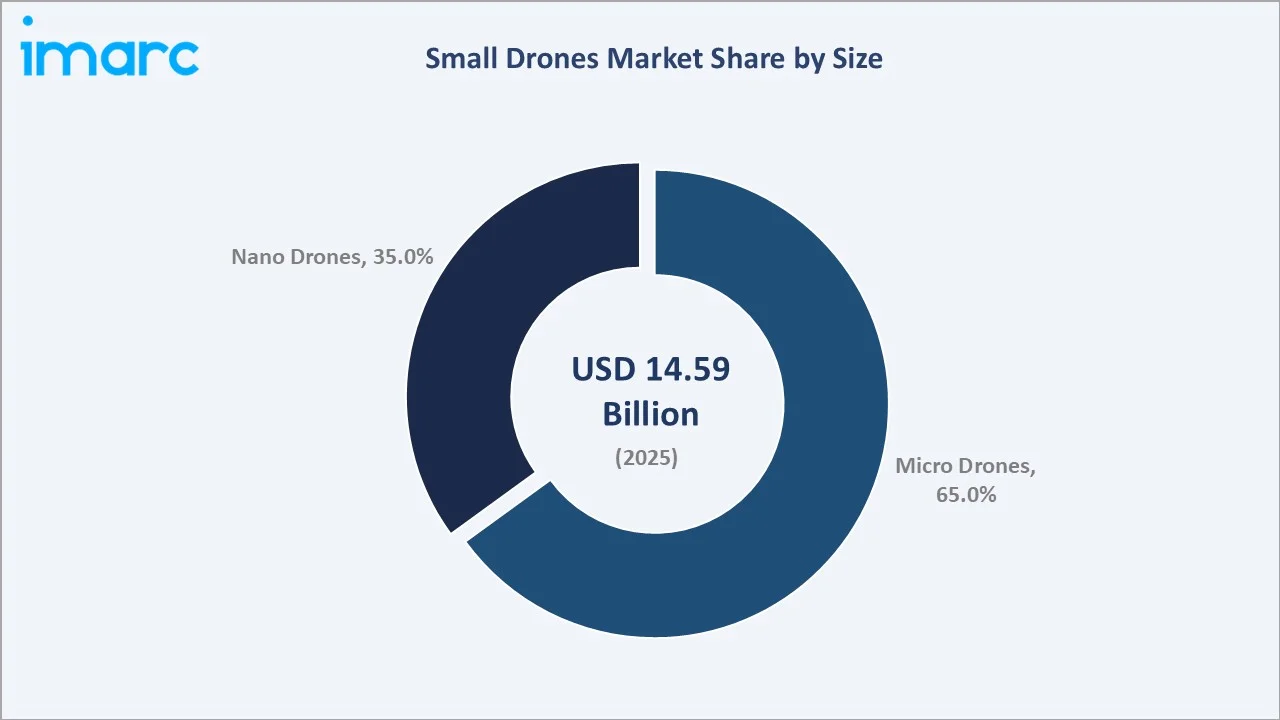
Micro drones lead at 65.0% in 2025, encompassing platforms in the 1-25 kg weight class that represent the broadest category of unmanned aerial vehicles by both volume and application diversity. Micro drones serve the military tactical reconnaissance role alongside the commercial agriculture, infrastructure inspection, mapping, and public safety sectors where sub-25 kg platforms can be legally operated.
To access detailed market analysis, Request Sample
Nano drones at 35.0% serve specialized applications where extreme miniaturization is operationally critical, including indoor reconnaissance, confined space inspection within industrial facilities, proximity inspection of structural components where larger drones cannot safely operate, and consumer recreational use where regulatory weight thresholds below 250 grams exempt platforms from registration requirements in many jurisdictions.
By Type
Rotary wing drones lead at 53.8% in 2025, reflecting the operational primacy of multirotor and single-rotor designs across both military and commercial applications where hover capability, VTOL operation without runway infrastructure, and precise maneuverability in confined spaces are operationally essential.
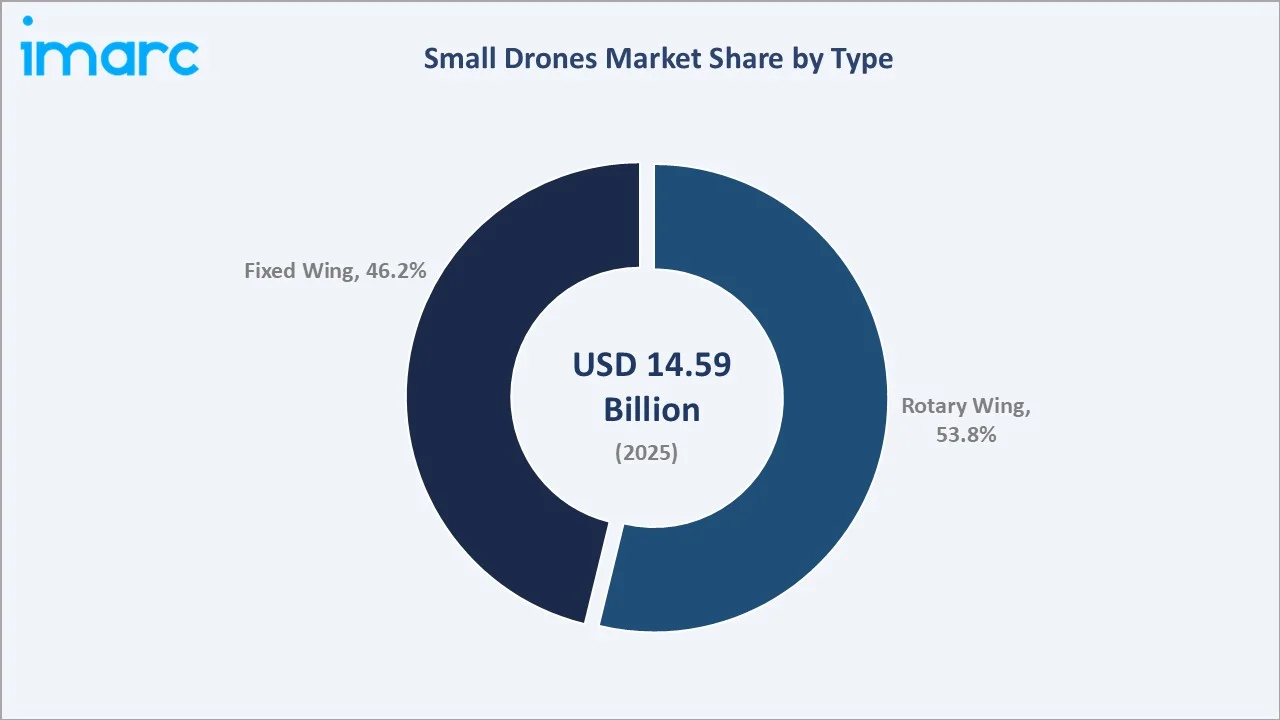
Fixed wing drones at 46.2% serve applications where aerodynamic efficiency enables substantially longer endurance and higher cruising speed than equivalent rotary wing platforms, including large-area mapping and surveying, agricultural precision spraying over extensive field areas, military persistent area surveillance, and coastal border patrol.
Regional Market Insights
|
Region |
Share (2025) |
Key Small Drones Market Drivers & Characteristics |
|
North America |
32.4% |
Strong defense and security demand, commercial adoption, and technological advancements in autonomous and AI-enabled small drones support regional market growth. |
|
Asia-Pacific |
29.8% |
Expanding defense applications, consumer drone adoption, manufacturing capabilities, and growing use in agriculture and infrastructure are driving demand. |
|
Europe |
23.6% |
Increasing adoption across defense, surveillance, infrastructure inspection, and commercial applications, supported by advancements in drone technologies. |
|
Latin America |
8.1% |
Growing use of small drones for agriculture, security, mapping, and infrastructure monitoring is supporting market development across the region. |
|
Middle East and Africa |
6.1% |
Rising defense, border surveillance, infrastructure, and security requirements are creating opportunities for small drone deployment. |
North America held the largest share of the small drones market at 32.4% in 2025, supported by strong defense, security, and commercial applications. Asia-Pacific accounted for 29.8%, driven by expanding drone manufacturing, defense programs, agriculture, and infrastructure applications. Europe represented 23.6%, with demand supported by surveillance, defense, inspection, and commercial drone use.
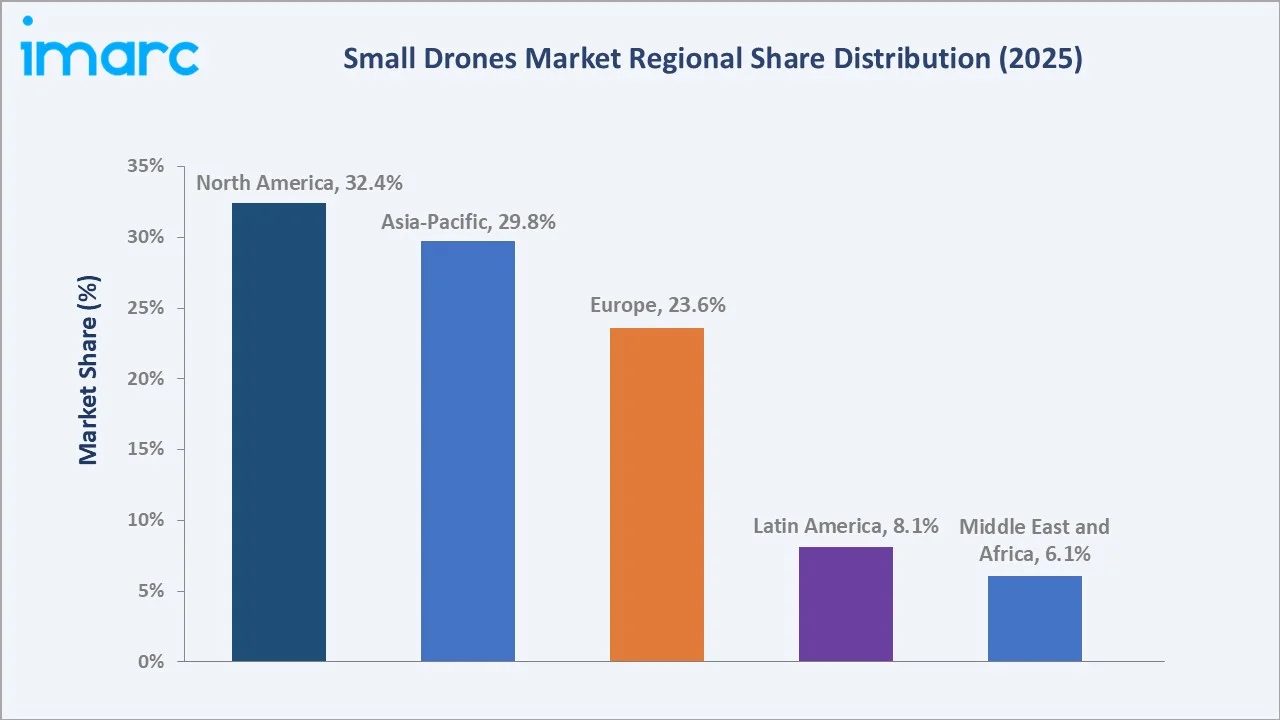
Latin America captured 8.1%, with increasing adoption in agriculture, security, mapping, and infrastructure monitoring. The Middle East and Africa accounted for 6.1%, supported by defense, border surveillance, and infrastructure requirements.
Competitive Landscape
The small drones market is characterized by the presence of established aerospace and defense companies, specialized drone manufacturers, and emerging technology providers. Companies are focusing on product innovation, lightweight designs, autonomous flight capabilities, advanced sensors, and AI-enabled systems to strengthen their market position. Strategic partnerships, product launches, technological development, and expansion into defense, commercial, and industrial applications remain key competitive strategies.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Skydio, Inc. |
Skydio X10, Skydio R10 |
Market Leader |
Skydio, Inc. plays a leading role by shifting the market away from manual consumer-grade photography devices toward AI-driven, autonomous flying robots used in defense, public safety, and enterprise infrastructure. |
|
DJI |
DJI Lito SERIES, DJI MAVIC 4 PRO, DJI MINI 5 PRO, DJI NEO 2, DJI AVATA 360 |
Market Leader |
DJI dominates the small and ultra-lightweight drone market by combining pro-grade imaging, intelligent automation, and ultra-portable designs into consumer-friendly packages. |
|
Vayudh |
ATRI Tactical Nano Drone |
Established Player |
Vayudh develops indigenous, full-stack hardware, software, and artificial intelligence for small and nano-class military drones. |
|
IZI |
IZI Mini X Nano 4K Drone |
Innovator |
IZI plays a significant role in the small and sub-250g drone market by offering affordable, compliant, and feature-rich compact UAVs tailored for creators, beginners, and commercial applications. |
The competitive landscape bifurcation between US-approved platforms and the globally dominant commercial platforms facing US regulatory restrictions is the defining structural feature of the current market. This regulatory bifurcation is accelerating domestic US manufacturer investment while creating market share preservation opportunity.
Key Company Profiles
Skydio, Inc.
Skydio, Inc. is a US-based drone technology company specializing in autonomous aerial systems and small unmanned aircraft. The company develops drones equipped with advanced navigation, imaging, and autonomous flight capabilities for commercial, industrial, public safety, and defense applications. Its product portfolio focuses on simplifying drone operations while enabling reliable aerial data collection and situational awareness. Skydio serves organizations across sectors such as infrastructure inspection, public safety, defense, and industrial operations.
- Key Offerings: Skydio X10, Skydio R10.
- Strategic Focus: Focuses on advancing autonomous small drone technologies by integrating intelligent navigation, imaging, and flight-control capabilities. The company emphasizes expanding applications across defense, public safety, infrastructure inspection, and other commercial and industrial sectors.
DJI
DJI is a global drone technology company specializing in unmanned aerial systems, aerial imaging platforms, and related equipment. The company offers a broad portfolio of small drones designed for consumer, commercial, industrial, and professional applications. Its products integrate advanced imaging, flight-control, navigation, and stabilization technologies to support diverse aerial operations. DJI serves applications including photography, videography, surveying, inspection, agriculture, public safety, and other professional use cases.
- Key Offerings: DJI Lito SERIES, DJI MAVIC 4 PRO, DJI MINI 5 PRO, DJI NEO 2, DJI AVATA 360.
- Strategic Focus: Focuses on strengthening its small drone portfolio through advancements in aerial imaging, intelligent flight control, navigation, and automation technologies. The company emphasizes expanding drone applications across consumer, commercial, industrial, agriculture, and professional markets.
Market Concentration Analysis
The small drones market has moderate concentration at the military procurement tier but is experiencing significant competitive restructuring at the commercial premium enterprise tier driven by procurement requirements and AI autonomy as a new competitive dimension beyond hardware specifications. The commercial market is experiencing progressive de-concentration from DJI monopoly toward a more fragmented landscape in North America, while DJI maintains concentrated dominance in Asia-Pacific and other international commercial markets unaffected by US regulatory restrictions.
Investment & Growth Opportunities
Highest Growth Segments
AI-autonomous tactical small UAS for GPS-denied military operations represents the highest near-term defense contract revenue opportunity. Last-mile drone delivery represents the largest long-term addressable market expansion as urban and rural delivery economics improve with regulatory maturity.
Investment Themes
- AI Autonomy and Swarm Technology: Investment in AI-powered autonomous navigation, multi-drone coordination, and swarm operation software creates the technical differentiation that determines competitive outcomes in both military procurement (GPS-denied operation requirement) and enterprise commercial markets (pilot scarcity and operational efficiency requirement).
- Agricultural Drone Market in Emerging Economies: The large-scale agricultural markets of India, Brazil, Indonesia, and Africa represent structurally expanding demand bases for fixed-wing precision agriculture mapping and multirotor precision spraying drones, growing in parallel with national government programs to improve agricultural productivity through precision technology adoption.
Future Market Outlook (2026-2034)
The small drones market stood at USD 14.59 Billion in 2025 and is projected to grow from USD 16.33 Billion in 2026 to USD 40.24 Billion by 2034, exhibiting a CAGR of 11.93% during the forecast period. The market is expected to reach an intermediate milestone of approximately USD 25.63 Billion by 2030, as US defense procurement programs reach full expenditure, commercial operations scale to enterprise volume in North America and Europe, agricultural drone adoption reaches commercial saturation in Asia-Pacific large-scale farming markets, and the platform investments drive the production scale that reduces per-unit costs and enables volume procurement programs.
Three structural forces will define the small drones market through 2034. First, the defense spending acceleration creates a policy-backed demand foundation that grows independently of commercial market development. Second, AI autonomy and regulatory evolution are jointly unlocking enterprise commercial use cases that currently do not exist at commercial scale. Third, the geopolitical market restructuring is creating a sustained competitive window for domestic and allied-nation manufacturers to build installed base, software ecosystem lock-in, and institutional procurement relationships that will compound through the forecast period as the supply chain security requirements embedded in US defense and government procurement become a permanent baseline rather than a temporary regulatory intervention.
Research Methodology
Primary Research
Primary research comprised structured consultations with military drone program managers and defense procurement officers, commercial drone enterprise operators across agriculture, inspection, and public safety verticals, drone manufacturer product and business development executives, venture capital investors tracking the drone sector, airspace regulatory specialists, and national aviation authorities, and defense technology analysts specializing in unmanned systems. These discussions validated market sizing, assessed the commercial impact, identified technology adoption trends, and provided competitive intelligence on contract award dynamics and platform selection criteria.
Secondary Research
Secondary research drew on IMARC Group market data, drone market weekly analysis, regulations impact on US commercial drone manufacturers, small drone market size and company share data, small drones market company profiles, and investor relations materials. Historical market data spanning 2020 through 2025 was cross-validated across multiple commercial and government data sources.
Forecasting Models
Market forecasts incorporated US defense drone procurement trajectory, commercial regulatory evolution timeline and associated use case unlocking projections, agricultural drone adoption rate modeling by region, AI autonomy cost reduction impact on commercial enterprise adoption rates, and macroeconomic indicators including global defense spending trajectory and commercial technology adoption rates across key verticals through 2034.
Small Drones Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Sizes Covered | Nano drones, Micro Drones |
| Types Covered | Fixed Wing, Rotary Wing |
| Applications Covered | Military and Defense, Consumer, and Consumer and Civil |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Skydio, Inc., DJI, Vayudh, IZI, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the small drones market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global small drones market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the small drones industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Small Drones Market Report
The small drones market reached USD 16.33 Billion in 2026, driven by US defense procurement and commercial enterprise adoption expanding across agriculture, infrastructure inspection, and public safety sectors.
The market is projected to grow at a CAGR of 11.93% during 2026-2034, driven by US defense procurement acceleration, military rearmament, AI autonomy enabling commercial operations, commercial agriculture and inspection market expansion, and structural market demand.
The market is projected to reach approximately USD 25.63 Billion by 2030, as US defense drone budget allocation reaches peak expenditure, BVLOS commercial operations scale to enterprise volume in North America and Europe, and agricultural drone adoption reaches commercial maturity in Asia-Pacific and Latin American large-scale farming markets.
Micro drones lead with a 65.0% share in 2025, reflecting the dominance of the 1-25 kg weight class across military tactical ISR, commercial agriculture and inspection, and public safety applications where this weight class provides the optimal balance of payload capacity, flight endurance, and regulatory operational freedom across the broadest range of use cases.
Rotary wing drones lead with a 53.8% share in 2025, reflecting the operational primacy of hover-capable multirotor platforms across military ISR loitering requirements and commercial inspection applications where vertical takeoff, precise hover, and confined space maneuverability are operationally essential performance attributes.
North America leads with a 32.4% share in 2025, anchored by the US defense procurement surge with drone-specific budget allocation, demand for domestic alternatives, and favorable regulatory framework development enabling commercial autonomous drone operations at enterprise scale.
Key players include Skydio, Inc., DJI, Vayudh, and IZI, among others.
The market is projected to reach USD 40.24 Billion by 2034, driven by structural defense procurement expansion across all military tiers, AI autonomy scaling commercial use cases from inspection to logistics, agricultural drone adoption reaching commercial maturity in emerging economy markets, and geopolitical supply chain restructuring creating permanent domestic manufacturing investment in North America and allied nations.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade