
Smart Lighting Market Size, Share, Trends and Forecast by Offering, Communication Technology, Installation Type, Light Source, Application, and Region, 2026-2034
Smart Lighting Market Size, Share, Trends & Forecast (2026-2034)
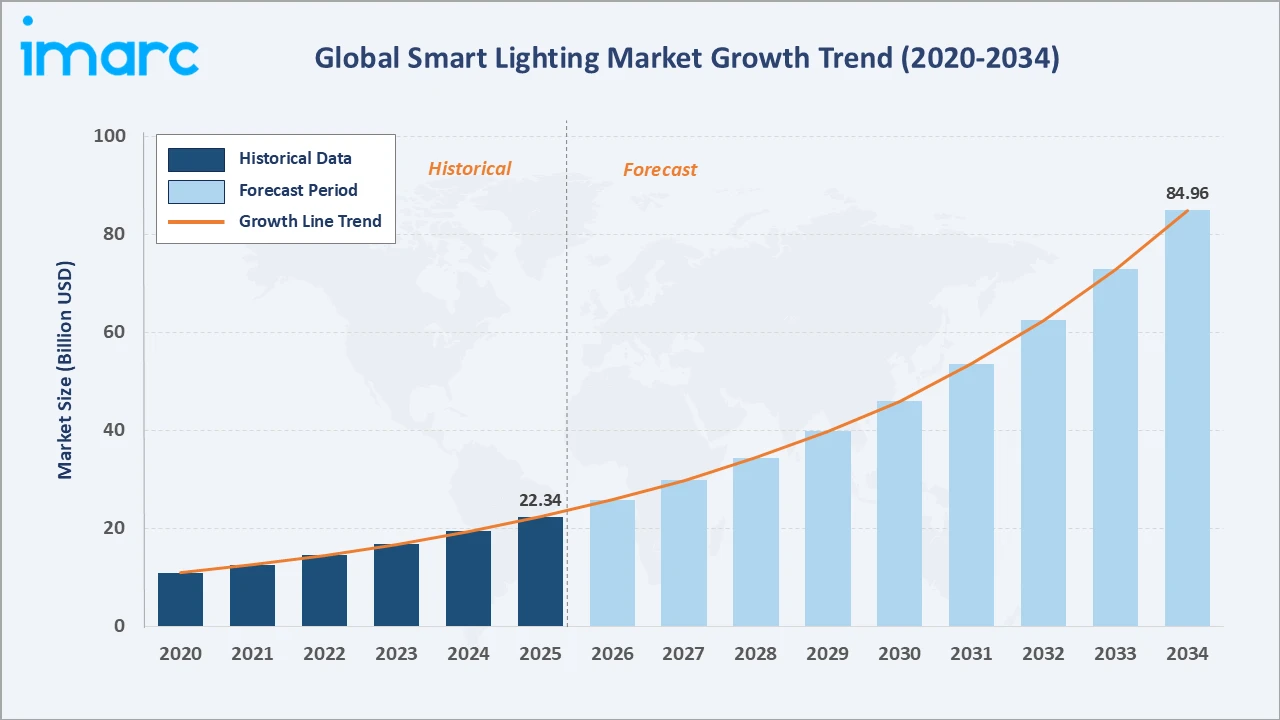
The global smart lighting market grew from USD 22.34 Billion in 2025 to USD 25.80 Billion in 2026 and will reach USD 84.96 Billion by 2034, at a CAGR of 15.52%. Lighting accounts for about 12% of global electricity use.
Energy efficiency rules, smart home adoption, and connected city infrastructure are reshaping the smart lighting industry. Hardware dominates offerings at 58.0%. Wired technology leads communication technologies at 55.0%. Europe commands 35.0% of global smart lighting market share, supported by strict efficiency regulations and building renovation programs.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 22.34 Billion |
|
Market Size (2026) |
USD 25.80 Billion |
|
Forecast Market Size (2034) |
USD 84.96 Billion |
|
CAGR (2026-2034) |
15.52% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Offering |
Hardware (58.0%, 2025) |
|
Dominant Communication Technology |
Wired Technology (55.0%, 2025) |
|
Leading Region |
Europe (35.0%, 2025) |
The smart lighting market size increased from USD 10.86 Billion in 2020 to USD 22.34 Billion in 2025 and is estimated to reach USD 25.80 Billion in 2026. It is expected to reach USD 45.96 Billion by 2030 and USD 84.96 Billion by 2034, reflecting rapid connected lighting adoption.
To get more information on this market, Request Sample
Asia-Pacific is expected to grow fastest at ~18.9% CAGR, supported by smart city projects and rising smart home adoption. Wireless technology follows at ~18.6% CAGR as Wi-Fi, Bluetooth, Zigbee, and Matter devices simplify installation, while software grows at ~18.4% with cloud and analytics platforms.
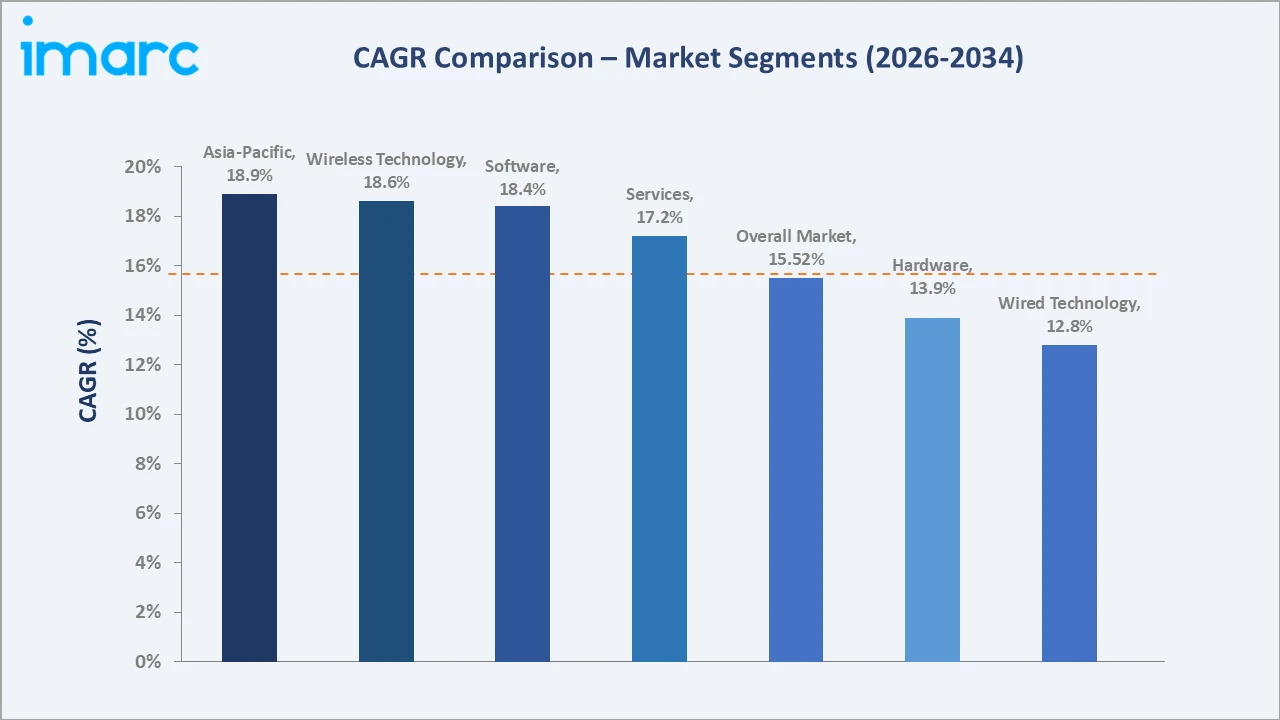
Hardware grows more slowly at ~13.9% CAGR as unit prices decline, while software and services steadily gain share.
Executive Summary
The smart lighting market expanded from USD 22.34 Billion in 2025 to USD 25.80 Billion in 2026 and is projected to reach USD 84.96 Billion by 2034. Companies are launching connected bulbs, controls, and platforms. Hardware leads at 58.0%, wired technology at 55.0%, and Europe at 35.0%.
Global lighting leaders continue to expand connected portfolios, while consumer brands compete strongly in smart bulbs and accessories. Rising smart city investments, building retrofits, and Matter-enabled products signal a broader and more interoperable global smart lighting market over the forecast period.
Key Market Insights
|
Insight |
Data |
|
Dominant Offering |
Hardware - 58.0% share (2025) |
|
Dominant Communication Technology |
Wired Technology - 55.0% market share (2025) |
|
Leading Region |
Europe - 35.0% share (2025) |
|
Market Opportunity |
Connected street lighting; smart building controls; Matter-enabled smart home lighting; lighting analytics software; retrofit installations |
Key Analytical Observations Supporting the Above Data:
- Hardware at 58.0%: Hardware dominates because every smart lighting system requires LED luminaires, smart bulbs, sensors, drivers, gateways, and switches. Large replacement volumes in homes, offices, and street lighting keep hardware spending well ahead of software and services.
- Wired Technology at 55.0%: Wired technology leads because commercial buildings and large facilities rely on proven systems such as DALI, Power over Ethernet, and wired lighting control networks that offer high reliability, security, and integration with building management systems.
- Europe at 35.0%: Europe leads due to strict energy efficiency regulations, the phase-out of fluorescent lamps, building renovation programs, and strong adoption of connected street lighting. Leading lighting companies and smart city projects further support regional market growth.
Smart Lighting Market Overview
Smart lighting refers to lighting systems that can be controlled remotely or automatically through sensors, apps, voice assistants, or building management software. These systems combine LED light sources with connectivity, controls, and software to adjust brightness, color, and schedules for comfort and efficiency.
The smart lighting industry links component suppliers, luminaire and smart bulb manufacturers, control system providers, software platforms, distributors, installers, and end users. Energy prices, building codes, smart home ecosystems, interoperability standards, and public infrastructure budgets shape demand across residential, commercial, and outdoor applications.
Smart lighting also supports climate goals by reducing electricity use in buildings and cities. It increasingly serves as a data platform, with sensors embedded in luminaires providing information on occupancy, air quality, and space utilization for building and city managers.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
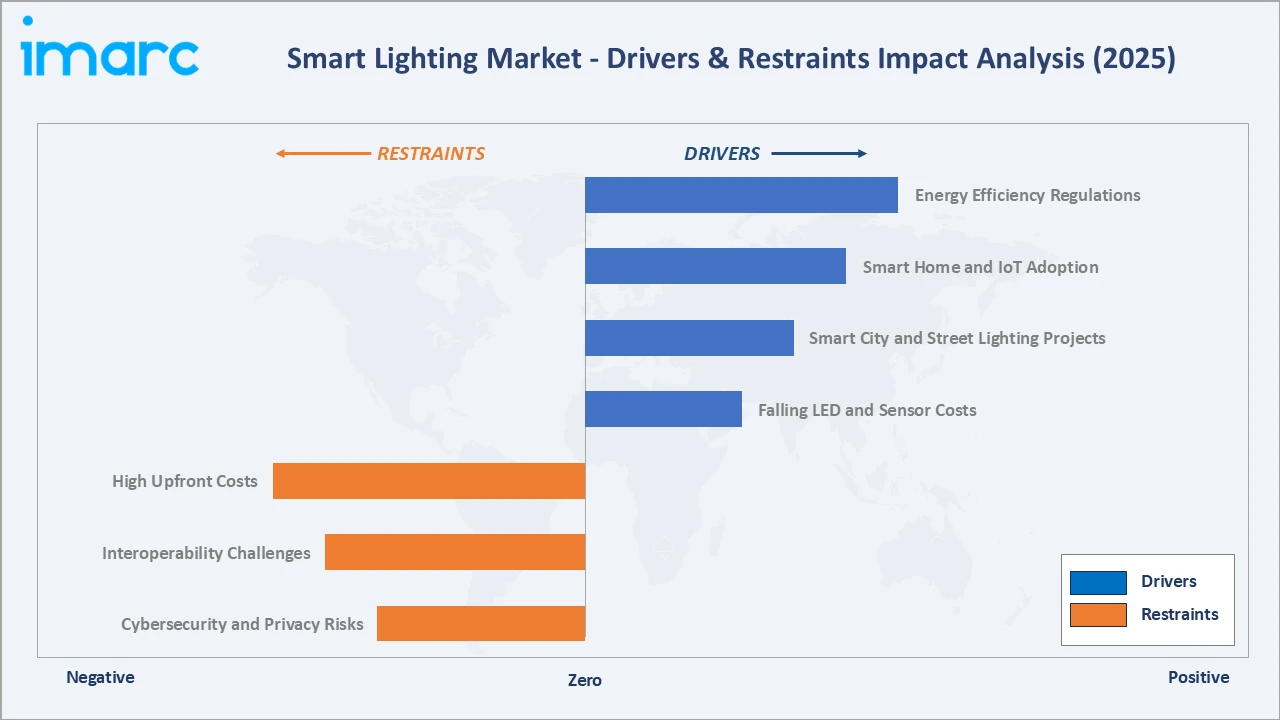
- Energy Efficiency Regulations: Governments are tightening building energy codes and phasing out inefficient lamps. Smart lighting with occupancy sensors, daylight harvesting, and scheduling helps buildings meet these rules while significantly reducing electricity consumption and operating costs.
- Lighting controls are increasingly mandatory in new commercial buildings under energy codes in Europe and North America. Utility rebate programs for networked lighting controls further improve project economics and encourage adoption.
- Smart Home and IoT Adoption: Growing use of voice assistants, smartphones, and smart home hubs is increasing demand for connected bulbs, light strips, and switches. The Matter standard is making it easier for consumers to combine lighting products from different brands.
- Consumers are using smart lighting for convenience, security, and ambiance, with schedules, away modes, and voice control. Integration with security systems and smart speakers is increasing the value of connected lighting in modern homes.
- Smart City and Street Lighting Projects: Cities are replacing conventional street lights with connected LED systems that can be monitored and dimmed remotely. These projects reduce energy and maintenance costs and provide a platform for sensors, cameras, and other smart city services.
- Connected street lighting can cut energy use significantly through adaptive dimming and fault detection. Many cities are using lighting poles as infrastructure for air quality sensors, traffic monitoring, and public Wi-Fi.
- Falling LED and Sensor Costs: Declining prices of LED chips, wireless modules, and sensors are making smart lighting more affordable. Lower hardware costs allow manufacturers to add connectivity to mainstream products, expanding adoption across homes, offices, and public spaces.
- Wireless chips supporting multiple protocols are now embedded in low-cost bulbs and fixtures. As component prices fall, smart features are moving from premium to mainstream products, widening the customer base.
Market Restraints
- High Upfront Costs: Smart lighting systems cost more than conventional LED lighting, especially when controls, sensors, gateways, and installation are included. Higher initial investment can discourage price-sensitive consumers and small businesses, despite long-term energy savings.
- Manufacturers are introducing affordable starter kits, plug-and-play products, and financing options to reduce cost barriers. Energy savings and utility incentives can also shorten payback periods for commercial customers.
- Interoperability Challenges: Different communication protocols, apps, and ecosystems can make it difficult to combine products from multiple brands. Compatibility issues complicate installation and use, although new standards such as Matter are gradually improving interoperability.
- Industry alliances are promoting shared standards, certification programs, and open interfaces. Products that work across multiple ecosystems are gaining preference among consumers and building owners seeking flexibility.
- Cybersecurity and Privacy Risks: Connected lighting devices can create entry points for cyberattacks if not properly secured. Concerns about data privacy and network security can slow adoption, particularly in commercial buildings, government facilities, and critical infrastructure.
- Manufacturers are adding encryption, secure boot, regular firmware updates, and compliance with new cybersecurity rules. Strong security practices are becoming an important purchasing criterion for commercial and government customers.
Market Opportunities
- Smart Buildings and Retrofits: Large numbers of existing commercial buildings still use basic lighting. Retrofitting them with wireless controls and connected luminaires offers strong opportunities, as these systems reduce energy use and provide occupancy and space utilization data.
- Wireless controls reduce installation time and disruption, making retrofits more attractive. Lighting data can also support heating, ventilation, and space management decisions, increasing the value of smart lighting investments.
- Human-Centric and Entertainment Lighting: Tunable white and color-changing lighting that supports well-being, productivity, and entertainment is gaining popularity. Lighting that syncs with televisions, music, and games creates premium opportunities in the smart LED lighting market.
- Hospitals, schools, and offices are adopting tunable lighting to support circadian rhythms. Consumers are spending on entertainment lighting for televisions, gaming setups, and outdoor spaces, supporting higher average selling prices.
Market Challenges
- Complex Installation and Commissioning: Large smart lighting projects require careful design, network setup, and commissioning. Shortages of skilled installers and integrators can delay projects and increase costs, particularly for advanced building-wide control systems.
- Manufacturers are developing simpler commissioning tools, mobile apps, and pre-configured systems to reduce installation complexity. Training programs for electricians and integrators are also expanding to address skill gaps.
- Standby Power and Product Longevity: Connected lamps consume standby power, and electronics may become outdated faster than LED light sources. Ensuring long-term software support and energy efficiency is important to maintain customer trust and regulatory compliance.
- New regulations are addressing standby power limits for connected lamps. Manufacturers are improving power efficiency and offering long-term software support to strengthen product reliability and customer confidence.
Emerging Market Trends
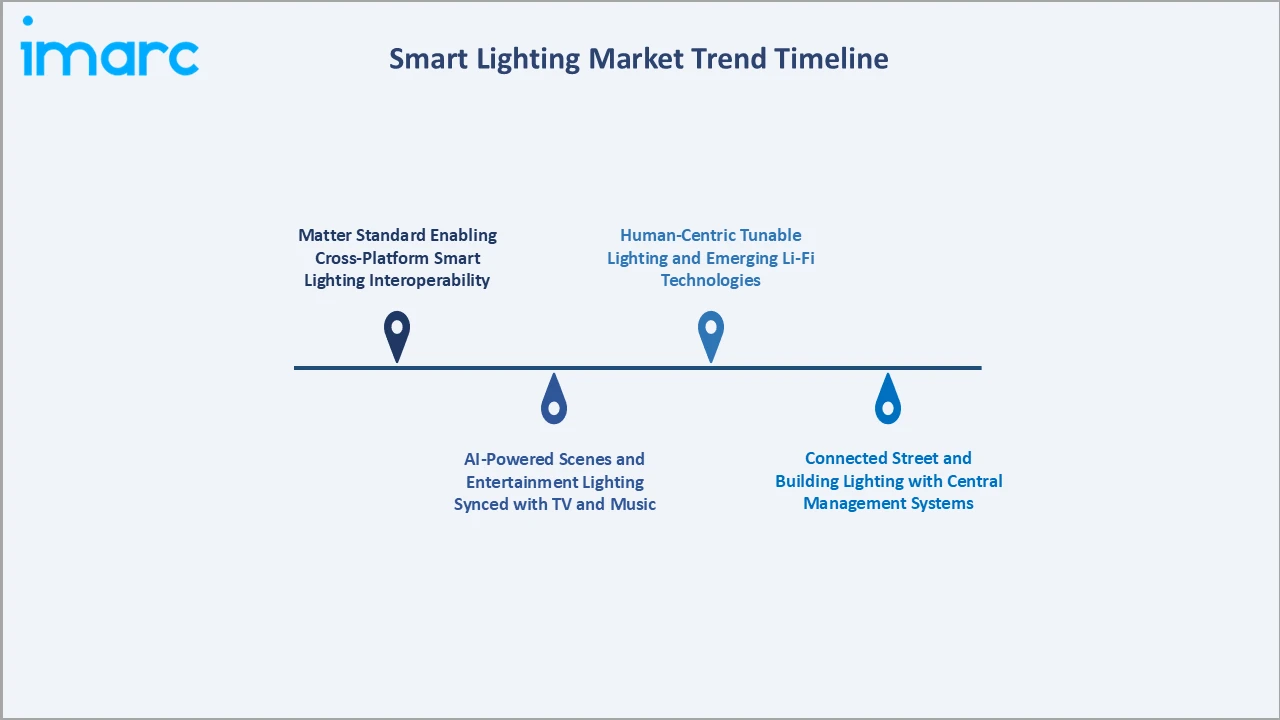
1. Matter and Cross-Platform Interoperability
Manufacturers are adopting the Matter standard so smart lights work across Apple, Google, Amazon, and Samsung ecosystems. Smart lighting market trends show new bulbs supporting both Matter and Zigbee, making setup easier and expanding consumer choice.
Matter compatibility reduces dependence on single ecosystems and simplifies setup for consumers. Retailers and brands expect interoperability to accelerate adoption among first-time smart home buyers.
2. AI and Entertainment Lighting
Brands are introducing AI-powered scene creation, screen sync devices, and lighting that responds to music, games, and live sports. These features turn smart lighting into an entertainment experience and support premium product sales.
Software updates allow companies to add features over time, improving customer engagement and loyalty. Partnerships with entertainment and audio brands are expanding integrated home experiences.
3. Connected Street and Building Lighting
Cities and building owners are deploying connected lighting platforms with central management systems, adaptive dimming, and sensor integration. These systems reduce energy use and maintenance while supporting smart city and intelligent building strategies.
Cellular and hybrid connectivity options simplify outdoor deployments without complex wiring. Building platforms combine lighting data with other systems to improve energy management and occupant comfort.
4. Human-Centric and Li-Fi Technologies
Tunable lighting that follows natural daylight patterns is being adopted in offices, schools, and hospitals. Emerging technologies such as Li-Fi, which uses light for data transmission, highlight growth in the emerging lighting technology market.
Human-centric lighting is supported by growing research on the effects of light on health and productivity. Li-Fi remains at an early stage but offers potential for secure, high-speed wireless data in specialized environments.
Industry Value Chain Analysis
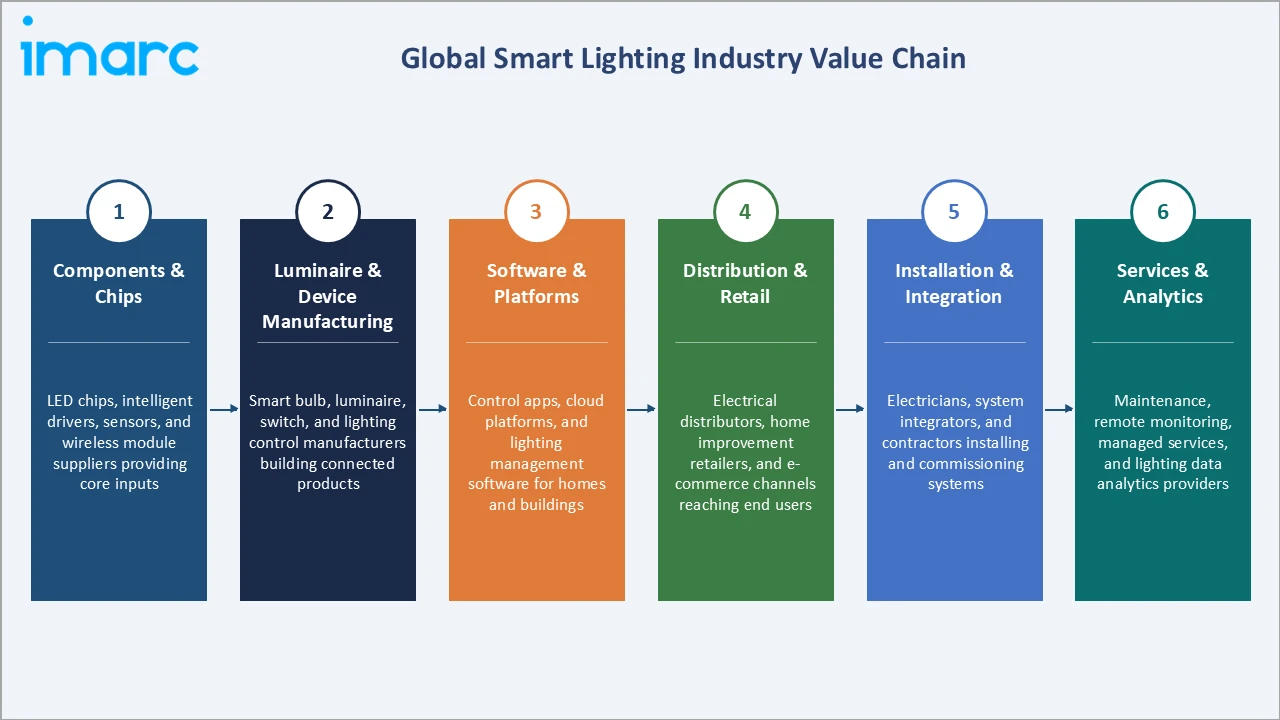
The smart lighting value chain spans components and chips, luminaire and device manufacturing, software and platforms, distribution and retail, installation and integration, and services and analytics. Value is concentrated in software, controls, and brand ecosystems, which shape customer loyalty and recurring revenue.
|
Stage |
Key Participants |
|
Components & Chips |
LED chips, drivers, sensors, and wireless module suppliers |
|
Luminaire & Device Manufacturing |
Smart bulb, luminaire, switch, and control makers |
|
Software & Platforms |
Apps, cloud platforms, and lighting management software |
|
Distribution & Retail |
Electrical distributors, retailers, and e-commerce |
|
Installation & Integration |
Electricians, system integrators, and contractors |
|
Services & Analytics |
Maintenance, monitoring, and data analytics providers |
Software and platforms are the most consequential stage, as control apps, cloud services, and integration with smart home and building systems determine user experience and lock-in. Installation and integration also matter greatly because proper commissioning determines system performance and energy savings.
Component suppliers add value through efficient LED chips, intelligent drivers, and multi-protocol wireless modules. Distribution partners and online retailers are important for consumer products, while specialized integrators drive professional projects and long-term service contracts.
Technology Landscape in the Smart Lighting Industry
LED Light Sources and Intelligent Drivers
LED light sources with intelligent drivers enable dimming, color tuning, and power monitoring. Advanced drivers support standards such as DALI-2 and D4i, allowing luminaires to report energy use and operating data to control systems and maintenance platforms.
Efficient LED drivers also reduce standby power in connected products. Driver and luminaire manufacturers are collaborating on standard interfaces that make it easier to add sensors and wireless modules.
Wired and Wireless Connectivity
Wired systems such as DALI and Power over Ethernet provide reliable control in large buildings, while wireless technologies including Wi-Fi, Bluetooth Mesh, Zigbee, and Thread simplify installation in homes and retrofit projects. Matter is improving cross-brand compatibility.
Hybrid systems combining wired backbones with wireless devices are common in large projects. Mesh networking improves reliability by allowing devices to relay signals across buildings and outdoor areas.
Sensors, Software, and Analytics
Occupancy, daylight, and environmental sensors embedded in luminaires collect data on space use and conditions. Cloud and edge software analyze this data to optimize energy use, schedule maintenance, and support space planning in smart buildings.
Artificial intelligence is increasingly used to learn usage patterns and adjust lighting automatically. Open application interfaces allow lighting data to be shared with building management and workplace software.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Offering | Hardware | 58.0% | 2025 |
| Communication Technology | Wired Technology | 55.0% | 2025 |
| Installation Type | New Installation | 🔒 | 2025 |
| Light Source | LED Lamps | 🔒 | 2025 |
| Application | Commercial | 🔒 | 2025 |
| Region | Europe | 35.0% | 2025 |

By Offering
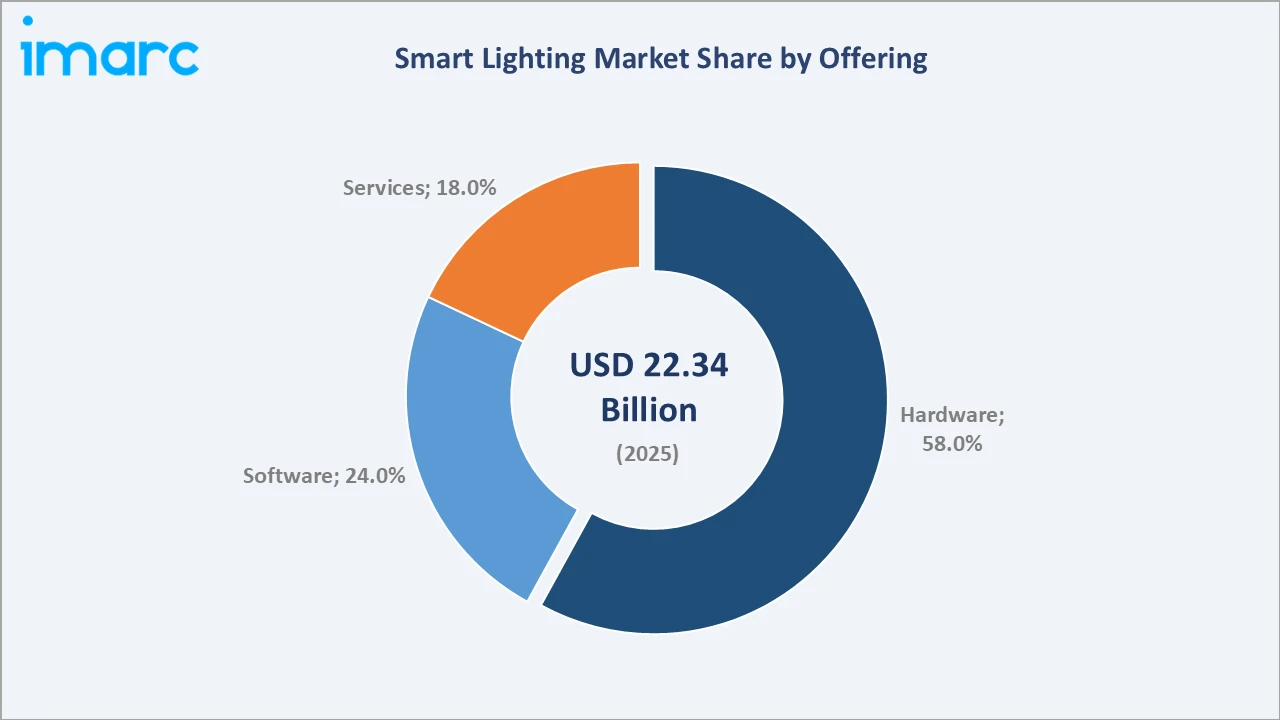
Hardware leads at 58.0% (2025). LED luminaires, smart bulbs, sensors, switches, drivers, and gateways form the physical foundation of every smart lighting system. High replacement volumes in homes, offices, and street lighting support hardware leadership.
To access detailed market analysis, Request Sample
Smart bulbs and light strips dominate residential hardware sales, while connected luminaires, sensors, and gateways lead commercial projects. Outdoor luminaires with integrated controllers support growth in street and area lighting.
Software at 24.0% grows fastest at ~18.4% CAGR, supported by cloud platforms, analytics, and smart home apps. Services at 18.0% grow at ~17.2%, driven by installation, commissioning, and managed services, while hardware grows at ~13.9%.
Hardware demand remains strong as existing lighting is replaced with connected LED products, but value is shifting toward software subscriptions, analytics, and managed services that provide recurring revenue for lighting companies and system integrators.
By Communication Technology
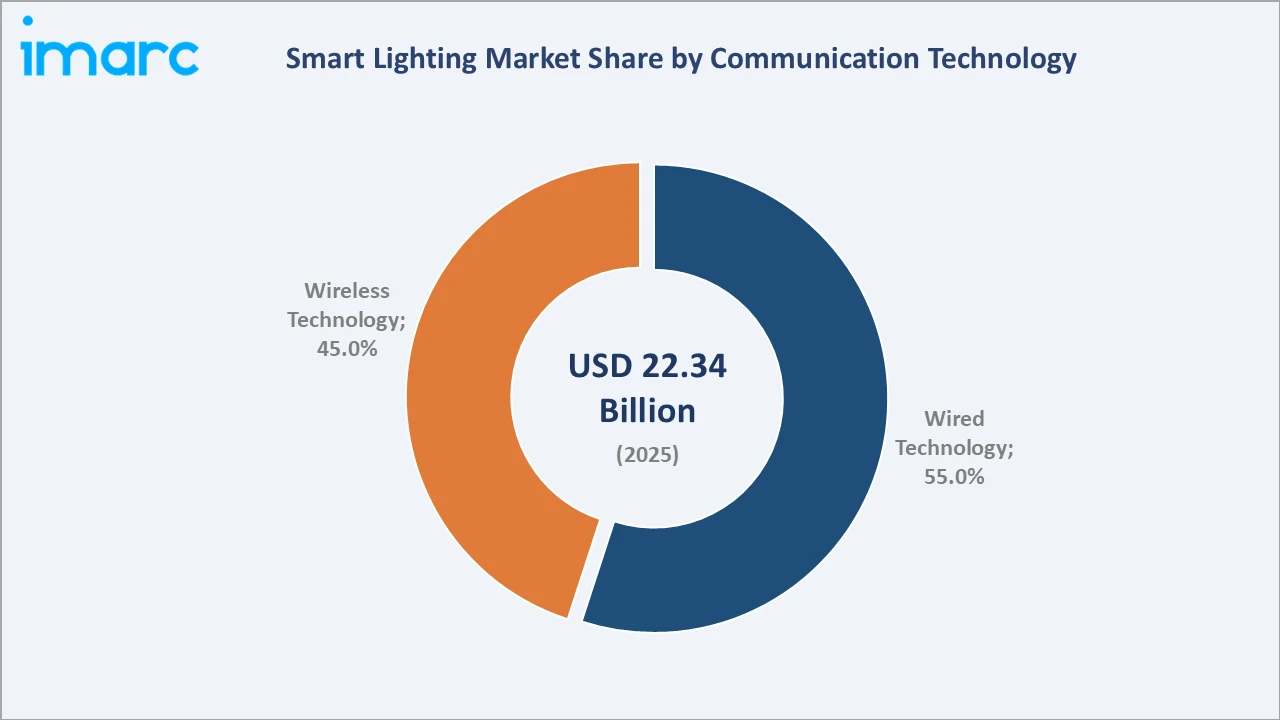
Wired technology leads at 55.0% (2025). DALI, Power over Ethernet, and wired control networks remain preferred in large commercial buildings, hospitals, and industrial facilities, where reliability, security, and integration with building management systems are critical.
Power over Ethernet lighting is gaining attention in modern offices because it combines power and data on a single cable. Wired systems are also preferred where security and reliability requirements are high.
Wireless technology at 45.0% grows faster at ~18.6% CAGR, compared with ~12.8% for wired technology. Easy installation, lower retrofit costs, and Matter-enabled smart home devices are driving rapid wireless adoption in homes, offices, and outdoor projects.
Wireless systems are especially popular in residential and retrofit projects, while wired systems remain dominant in new commercial construction. Hybrid architectures combining both technologies are increasingly common in large buildings and campuses.
Regional Market Insights
| Region | Share (2025) | Key Smart Lighting Market Drivers & Characteristics |
|---|---|---|
| Europe | 35.0% | Strict efficiency rules, renovations, and connected street lights. |
| Asia-Pacific | 25.0% | Smart city projects and rising smart home adoption. |
| North America | 22.0% | Smart homes, energy codes, and commercial retrofits. |
| Middle East and Africa | 10.0% | New smart cities and large infrastructure projects. |
| Latin America | 8.0% | Street lighting upgrades and urban modernization. |
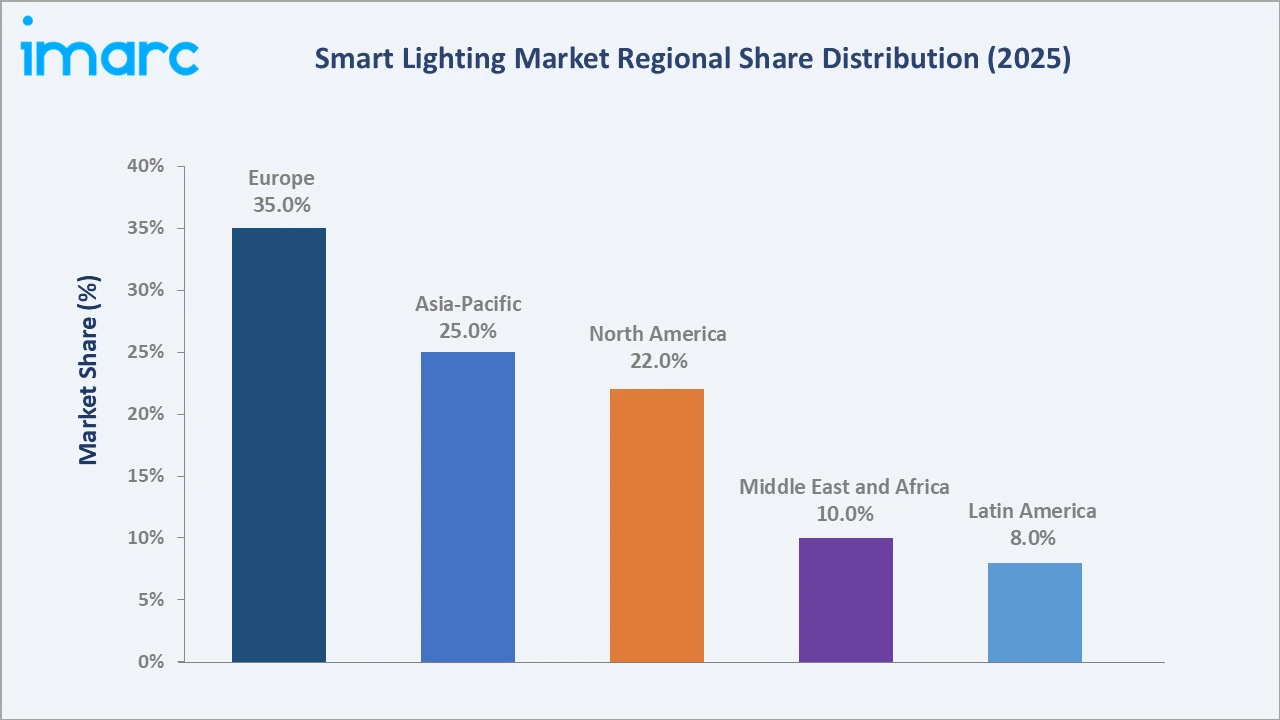
Europe's 35.0% market leadership reflects strict energy efficiency regulations, building renovation programs, and widespread connected street lighting. Asia-Pacific's 25.0% is supported by smart city projects in China, India, and Southeast Asia, while North America's 22.0% reflects strong smart home adoption and commercial retrofits.
The European Union's building renovation and ecodesign policies continue to drive connected lighting upgrades. China and India are investing heavily in smart city infrastructure, while the United States benefits from strong consumer smart home adoption.
The Middle East and Africa at 10.0% grows at ~16.8% CAGR, driven by new smart cities and infrastructure projects in Saudi Arabia and the UAE. Latin America at 8.0% grows at ~16.1%, while Asia-Pacific grows fastest at ~18.9%.
Europe's growth is supported by public lighting upgrades and building renovation, while North America benefits from energy codes and utility incentives. Emerging markets are adopting connected lighting as part of new urban developments.
Competitive Landscape
The smart lighting market includes global lighting manufacturers, lighting control specialists, electrical equipment companies, and consumer smart home brands. Competition centers on product range, connectivity, software, ecosystem compatibility, and channel reach, shaping smart lighting market share across regions.
Leading companies compete through broad product portfolios, strong brands, partnerships with smart home platforms, and extensive distribution networks. Professional players also offer design, commissioning, and managed services to large customers.
| Company | Key Brands | Market Position | Core Strength |
|---|---|---|---|
| Signify Holding | Philips Hue, Interact | Market Leader | World leader in connected lighting. |
| Acuity Inc. | nLight, Lithonia Lighting | Market Leader | Lighting and building controls leader. |
| Lutron | Caséta, RadioRA, Ketra | Strong Challenger | Lighting control and shading systems. |
| Legrand | Arteor IoT, MyHOME+, Living Now | Strong Challenger | Electrical and lighting control solutions. |
| GE Lighting, a Savant company | Cync, GE Lighting | Strong Challenger | Smart home bulbs and fixtures. |
| Nanoleaf | Nanoleaf | Innovator | Design-led smart light panels. |
| Yeelight | Yeelight | Innovator | Affordable smart bulbs and light strips. |
The most important competitive dynamic is the shift from selling lighting hardware to providing connected systems, software, and services. Leading players are investing in Matter compatibility, AI features, and building management integration, while expanding through new product launches and acquisitions.
Consumer brands focus on design, ease of use, and attractive pricing, often selling through online channels. Professional lighting companies emphasize reliability, certification, and integration with building systems for large projects.
Key Company Profiles
Signify Holding
Signify Holding is the world leader in lighting for professionals and consumers, and its installed base of connected light points increased to 171 million in Q1 2026.
- Key Brands: Philips Hue, WiZ, Interact, Dynalite.
- Recent Developments: In September 2026, Philips Hue introduced new AI, entertainment, and design innovations, including Screen Sync and the Philips Hue Play HDMI sync box 4K.
- Strategic Focus: Expanding next-generation Interact solutions for intelligent buildings and cities, including EasyConnect outdoor light management and a Central Management System.
Acuity Inc.
Acuity Inc. is a market-leading industrial technology company operating through Acuity Brands Lighting and Acuity Intelligent Spaces, offering lighting, lighting controls, building management solutions, and an audio, video, and control platform.
- Key Brands: Lithonia Lighting, nLight, Distech Controls, Atrius.
- Recent Developments: In October 2026, Acuity agreed to acquire Parameter Technologies, adding sensing, detection, and monitoring technology to Distech Controls within Acuity Intelligent Spaces.
- Strategic Focus: Scaling nLight networked lighting controls that connect luminaires and sensors into one intelligent architecture from a single room to an entire campus.
Lutron
Lutron, founded in 1961, is a leader in lighting control and automated shading, offering more than 15,000 energy-saving products sold in over 100 countries.
- Key Brands: Caséta, RadioRA, HomeWorks, Athena, Ketra.
- Recent Developments: In February 2026, Lutron unveiled its Intelligent Lighting portfolio at Integrated Systems Europe, introducing Ketra and Orluna product families for luxury residential spaces.
- Strategic Focus: Enhancing its Athena and Vive commercial systems with native fixture integration, upgraded platforms, and stronger security measures.
Market Concentration Analysis
The smart lighting market is moderately fragmented, with a few global lighting and control companies holding strong positions in professional and premium segments, while many consumer brands and regional manufacturers compete in smart bulbs and accessories.
Global lighting leaders benefit from scale, brand recognition, and extensive channel partnerships. Smaller brands differentiate through design, niche features, and online marketing to attract younger, tech-savvy consumers.
Market concentration is higher in professional lighting controls and connected street lighting, where certification, project experience, and integration capabilities create barriers to entry. Competition is intense in consumer smart bulbs, where low prices and online sales attract many brands.
Partnerships with smart home platforms, chipmakers, and building automation companies are shaping competitive positions. Companies with broad ecosystems and strong software capabilities are best placed to increase their market presence.
Investment & Growth Opportunities
Highest Growth Segments
Asia-Pacific (~18.9% CAGR through smart cities), wireless technology (~18.6% CAGR through easy retrofits), software (~18.4% CAGR through cloud and analytics), and services (~17.2% CAGR through managed lighting) represent the highest-growth investment areas through 2034.
Hardware will remain the largest revenue segment, but software and services will gain share as customers prioritize analytics, remote management, and long-term support. Emerging markets also offer strong growth potential through new infrastructure projects.
Emerging Investment Opportunities
Connected street lighting, smart building retrofits, and lighting analytics software are among the most promising opportunities, supporting growth in the smart lighting industry. Investment in Matter-enabled consumer products and human-centric lighting also offers attractive long-term returns.
Lighting-as-a-service business models, where customers pay for lighting performance instead of equipment, are also gaining interest. These models reduce upfront costs for customers and create stable recurring revenue for providers.
Investment Themes
- Smart city lighting: Connected street lights cut energy and maintenance costs.
- Building controls: Wireless retrofits deliver fast energy savings and data insights.
Future Market Outlook (2026-2034)
The smart lighting market is projected to grow from USD 22.34 Billion in 2025 to USD 25.80 Billion in 2026, reaching USD 84.96 Billion by 2034 at a CAGR of 15.52%. The 2030 value of USD 45.96 Billion marks mainstream connected lighting adoption.
Three structural forces define smart lighting industry growth through 2034 energy efficiency regulations; smart home and IoT adoption; and smart city investment. Together, these forces support strong growth across offerings, communication technologies, and regions, while costs, interoperability, and cybersecurity remain key factors.
Companies that combine reliable hardware, open interoperability, strong cybersecurity, and intelligent software are best positioned to capture growth. Partnerships across the smart home and building automation ecosystems will continue to shape long-term competitive success.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including lighting manufacturers, control system providers, software companies, distributors, system integrators, facility managers, and city officials across all major regions. Interviews covered demand, pricing, technology, and adoption trends.
Secondary Research
Secondary research covered company press releases, annual reports, IEA and government energy data, industry associations, and trade publications. Over 50 credible secondary sources were reviewed, compared, and cross-checked for accuracy and consistency across datasets and regions.
Forecasting Models
Market revenue forecasts were developed using a demand-based model: smart lighting installations by offering, communication technology, and region multiplied by average system values, then aggregated to total market value. Assumptions were validated through discussions with industry experts.
Smart Lighting Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Offerings Covered |
|
| Communication Technologies Covered | Wired Technology, Wireless Technology |
| Installation Types Covered | New Installation, Retrofit Installation |
| Light Sources Covered | LED Lamps, Fluorescent Lamps, Compact Fluorescent Lamps, High Intensity Discharge Lamps, Others |
| Applications Covered | Commercial, Residential, Public Infrastructure, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Signify Holding, Acuity Inc., Lutron, Legrand, GE Lighting, a Savant company, Nanoleaf, Yeelight, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the smart lighting market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the global smart lighting market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the smart lighting industry and its attractiveness.
- The competitive landscape allows stakeholders to understand their competitive environment and provides insight into the current positions of key players in the market.
Frequently Asked Questions About the Smart Lighting Market Report
The smart lighting market size is estimated at USD 25.80 Billion in 2026, supported by energy efficiency regulations, growing smart home adoption, connected street lighting projects, and falling LED and sensor costs worldwide.
The market grows at a 15.52% CAGR during 2026-2034, reaching USD 84.96 Billion by 2034, driven by smart homes, intelligent buildings, and smart city lighting projects.
Hardware leads at 58.0%, owing to strong demand for LED luminaires, smart bulbs, sensors, switches, and gateways that form the foundation of smart lighting systems.
Wired technology leads at 55.0%, supported by DALI, Power over Ethernet, and wired control networks widely used in large commercial and industrial buildings.
Europe leads at 35.0%, driven by strict energy efficiency regulations, building renovation programs, and widespread adoption of connected street lighting.
Leading companies include Signify Holding, Acuity Inc., Lutron, Legrand, GE Lighting, a Savant company, Nanoleaf, and Yeelight, among others.
The smart LED lighting market is evolving through Matter-enabled products, AI and entertainment features, tunable human-centric lighting, and connected building and street lighting platforms.
The market is projected to reach approximately USD 45.96 Billion by 2030, supported by strong growth in wireless systems, software, and connected outdoor lighting.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade