
United States B2B Payments Market Size, Share, Trends and Forecast by Payment Type, Payment Mode, Enterprise Size, Industry Vertical, and Region, 2026-2034
United States B2B Payments Market Size, Share, Trends & Forecast (2026-2034)
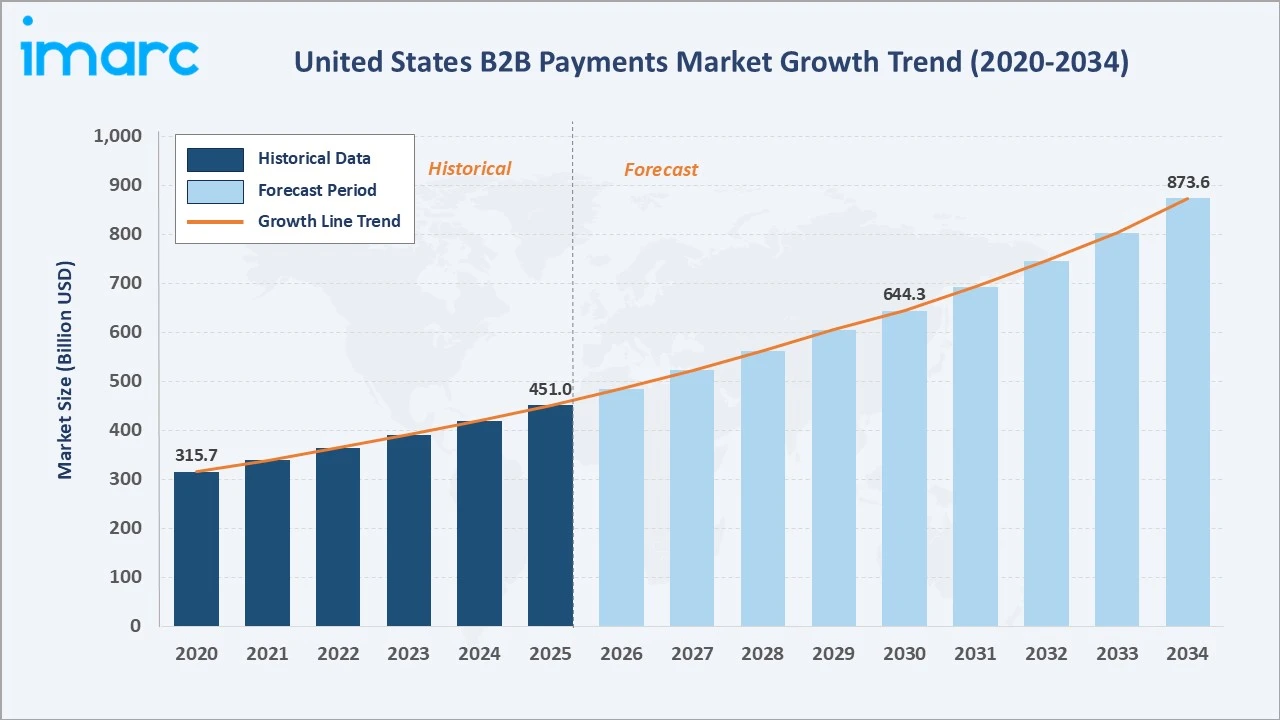
The United States B2B payments market size reached USD 451.0 Billion in 2025 and is estimated at USD 484.3 Billion in 2026. The market is projected to reach USD 873.6 Billion by 2034, growing at a CAGR of 7.39% during 2026-2034. Growth is driven by accelerating digital transformation, AI-driven automation of accounts payable and receivable, cross-border trade expansion, and widespread adoption of cloud-based payment platforms across US enterprises.
The market is characterized by rapid digital payment adoption, growing real-time payment infrastructure, and increasing integration of AI and automation into corporate treasury operations. Digital payments lead at 62.8% by payment mode. Domestic payments dominate at 68.7% by payment type. The South region commands 31.4% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 451.0 Billion |
|
Market Size (2026) |
USD 484.3 Billion |
|
Forecast Market Size (2034) |
USD 873.6 Billion |
|
CAGR (2026-2034) |
7.39% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Payment Mode |
Digital (62.8%, 2025) |
|
Dominant Payment Type |
Domestic Payments (68.7%, 2025) |
|
Leading Region |
South (31.4%, 2025) |
The United States B2B payments market size increased from USD 315.7 Billion in 2020 to USD 451.0 Billion in 2025 and is estimated to reach USD 484.3 Billion in 2026. The market is further projected to reach USD 644.3 Billion by 2030 and USD 873.6 Billion by 2034, supported by accelerating enterprise digital payment adoption, real-time payment infrastructure expansion, and AI-driven automation of corporate financial workflows.
To get more information on this market, Request Sample
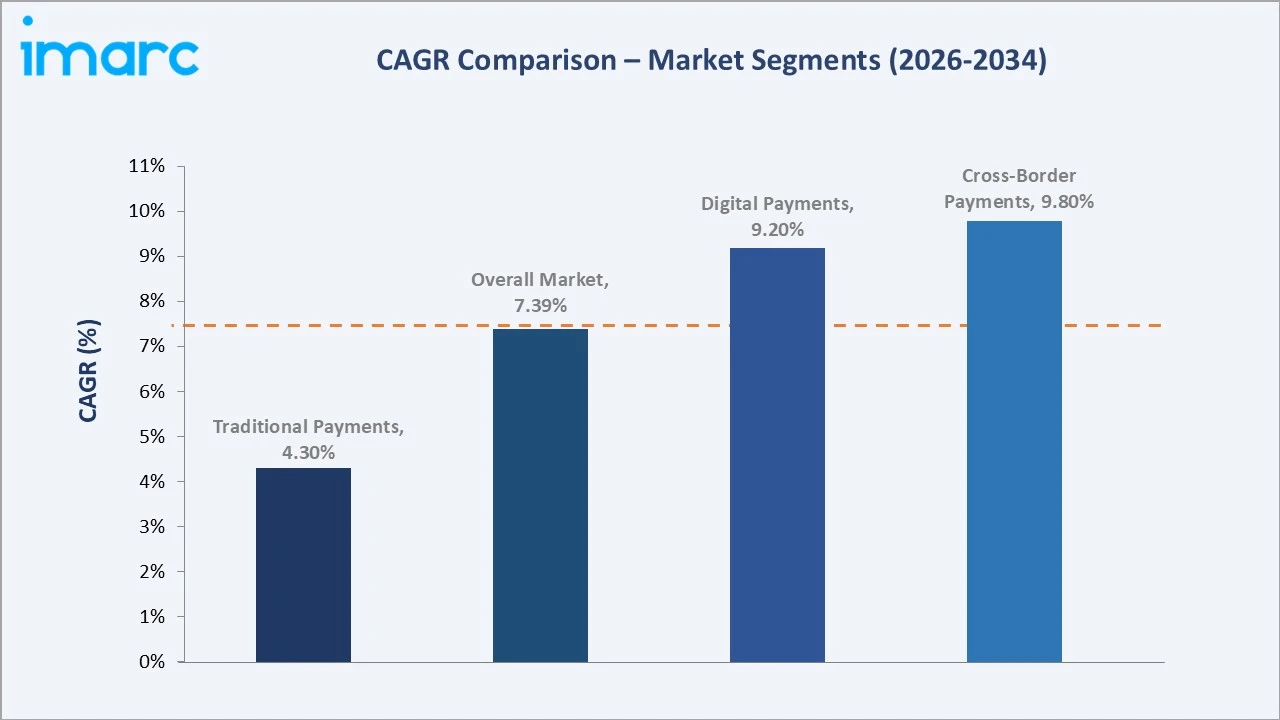
Cross-border payments are the fastest-growing segment at 9.8% CAGR through global trade digitalization and real-time cross-border payment network expansion. Digital payments grow at 9.2% CAGR through enterprise-wide digital transformation initiatives and declining reliance on paper-based check and ACH payment processes.
Executive Summary
The United States B2B payments market reached USD 451.0 Billion in 2025 and is estimated at USD 484.3 Billion in 2026, representing the world's largest B2B payments ecosystem. Growth is anchored by accelerating digital transformation across enterprise payment operations, AI-driven automation of accounts payable and receivable workflows, and expanding cross-border trade payment digitalization, supported by robust real-time payment infrastructure and cloud-based platform proliferation. The market is projected to grow from USD 451.0 Billion in 2025 to USD 873.6 Billion by 2034, representing sustained structural demand driven by enterprise digital transformation imperatives.
Market structure reflects the advanced digitalization of US corporate payment infrastructure. Digital payments lead at 62.8% by payment mode, driven by enterprise-wide ACH, wire transfer, and emerging real-time payment adoption. Domestic payments at 68.7% reflect the large and mature US domestic commercial transaction base. The South region commands 31.4% of national market share through its concentration of financial services infrastructure and corporate headquarters.
Key Market Insights
|
Insight |
Data |
|
Dominant Payment Mode |
Digital – 62.8% share (2025) |
|
Dominant Payment Type |
Domestic Payments – 68.7% market share (2025) |
|
Leading Region |
South – 31.4% share (2025) |
|
Market Opportunity |
Real-time payment infrastructure expansion; AI-driven AP/AR automation; cross-border trade digitalization; embedded finance integration into ERP and procurement platforms |
Key Analytical Observations Supporting the Above Data:
- Digital at 62.8%: Leads through enterprise-wide adoption of ACH, wire transfers, virtual cards, and real-time payment networks, replacing paper checks and reducing transaction costs across corporate payment workflows.
- Domestic Payments at 68.7%: Dominates through the large and mature US domestic commercial transaction base, encompassing supplier payments, payroll processing, and inter-company transfers within the extensive US business ecosystem.
- South at 31.4%: Atlanta, Dallas, and Charlotte's financial services infrastructure, concentration of Fortune 500 headquarters, and rapidly expanding fintech ecosystem drive the highest regional B2B payment transaction volume.
United States B2B Payments Market Overview
The United States B2B payments market is the world's largest and most sophisticated corporate payment ecosystem, processing trillions of transactions annually across domestic and international channels. The market integrates legacy banking infrastructure with emerging fintech platforms, real-time payment networks, and AI-powered automation tools, creating a rapidly evolving competitive landscape where traditional financial institutions and innovative payment technology companies compete for enterprise payment wallet share.
The ongoing migration from paper-based checks to digital payment methods is the primary structural growth driver across the forecast period. Enterprise digital transformation initiatives, ERP system modernization, and the proliferation of cloud-based accounts payable automation platforms are accelerating this migration. Real-time payment infrastructure through The Clearing House's RTP network and the Federal Reserve's FedNow service is establishing new payment speed benchmarks that are reshaping enterprise treasury management expectations and enabling new embedded finance use cases.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
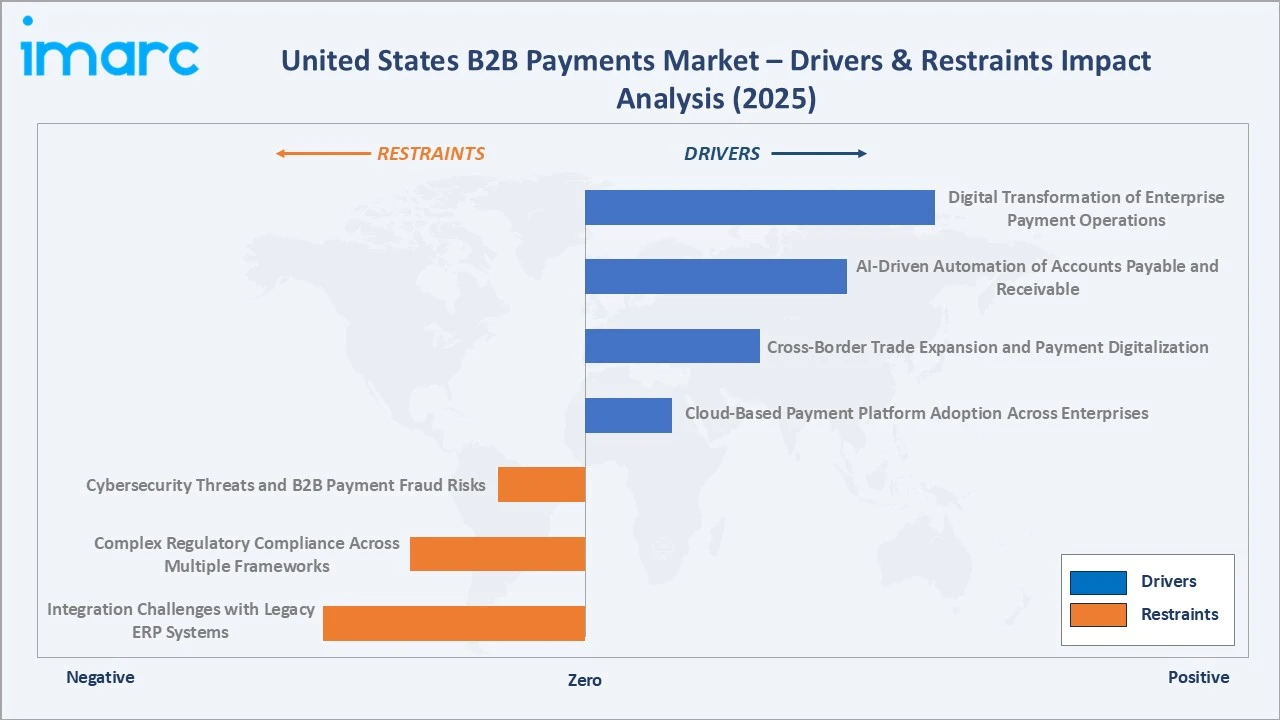
- Digital Transformation of Enterprise Payment Operations: Accelerating enterprise-wide digital transformation initiatives are driving systematic replacement of paper checks and manual invoice processing with integrated digital payment platforms, AP automation tools, and real-time payment network connectivity across US enterprises of all sizes.
- AI-Driven Automation of Accounts Payable and Receivable: Artificial intelligence and machine learning integration into AP/AR workflows is automating invoice matching, payment routing, fraud detection, and cash flow forecasting, delivering 60-80% cost reduction and straight-through processing rates above 90% that accelerate enterprise digital payment adoption.
- Cross-Border Trade Expansion and Payment Digitalization: Growing US cross-border trade volumes driven by global supply chain diversification and digital marketplace expansion are creating sustained demand for faster, transparent international B2B payment solutions, with cross-border digitalization growing at 9.8% CAGR through the forecast period.
- Cloud-Based Payment Platform Adoption Across Enterprises: Rapid adoption of cloud-native payment platforms, treasury management systems, and embedded finance APIs is enabling seamless payment workflow integration across enterprise ERP and procurement systems, with cloud B2B payment adoption growing at 22%+ CAGR through enterprise digital transformation.
Market Restraints
- Cybersecurity Threats and B2B Payment Fraud Risks: The rapid digitalization of B2B payment workflows has expanded the cybersecurity attack surface, with business email compromise, payment diversion fraud, and ransomware attacks targeting enterprise treasury and AP operations creating significant financial and reputational risks. Business email compromise attacks targeting B2B payment processes cost US enterprises over USD 2.9 Billion annually according to FBI IC3 data, with rising sophistication of AI-generated deepfake fraud targeting CFO and treasury authorization processes representing an emerging threat vector requiring investment in behavioral authentication systems.
- Complex Regulatory Compliance Across Multiple Frameworks: B2B payment providers and enterprise treasury teams must navigate increasingly complex and evolving regulatory requirements spanning BSA/AML, FinCEN beneficial ownership rules, state money transmission licensing, and emerging real-time payment compliance frameworks. FinCEN beneficial ownership reporting requirements add compliance complexity for B2B payment processors, while state-level money transmission licensing requirements across 50 jurisdictions create regulatory overhead adding 12-18 months to new market entry timelines for nationwide coverage seekers.
- Integration Challenges with Legacy ERP Systems: The prevalence of legacy ERP and accounting systems across mid-market and large enterprise segments creates technical integration barriers to digital payment adoption, requiring significant IT investment and multi-year migration timelines that slow overall market digitalization. Over 60% of US mid-market enterprises operate ERP systems more than 10 years old that lack native API connectivity for modern digital payment platforms, while large enterprise ERP consolidation programs averaging 3-5 years create extended periods of payment system fragmentation.
Market Opportunities
- Real-Time Payment Infrastructure Expansion: The Federal Reserve's FedNow service launch in 2023 and The Clearing House's RTP network expansion are establishing 24/7/365 real-time payment capabilities that create significant B2B payment value propositions through instant settlement, improved cash flow management, and reduced counterparty risk. FedNow's bank participation network growing to 600+ institutions by mid-2025 is approaching the critical mass needed for widespread enterprise adoption, with use cases including instant supplier payments, dynamic discounting, and just-in-time payroll delivery creating measurable working capital benefits.
- Embedded Finance and B2B Payment Platform Integration: The integration of payment capabilities directly into ERP, procurement, marketplace, and vertical SaaS platforms through embedded finance APIs is creating new B2B payment distribution channels that capture high-volume transaction flows within existing enterprise workflows. Embedded B2B payment volumes processed within non-payment platforms are projected to grow at 25%+ CAGR through 2030, with vertical SaaS platforms incorporating embedded B2B payments commanding 2-3x higher revenue per user and 40%+ lower churn versus non-payment-enabled competitors.
Market Challenges
- Interoperability Between Multiple Payment Networks and Standards: The fragmented US B2B payment landscape encompassing ACH, RTP, FedNow, wire transfers, virtual cards, and emerging blockchain-based networks creates interoperability challenges that increase enterprise payment infrastructure complexity and cost. Absence of universal B2B payment data standards forces enterprises to maintain multiple payment integrations, with ISO 20022 migration underway but full adoption across domestic networks expected to extend through 2028, while cross-network settlement gaps require separate banking relationships and treasury operations for different payment types.
- Talent Shortage in Payment Technology and Treasury Operations: Accelerating demand for payment technology expertise, treasury automation specialists, and compliance professionals significantly outpaces talent supply, creating hiring challenges and increasing labor costs for financial institutions and enterprise treasury operations. Payment technology and fintech talent shortages are driving 30-50% salary premiums for experienced payment engineers and treasury automation specialists, while treasury technology skill gaps in mid-market enterprises limit B2B payment digitalization speed and depth, creating demand for managed payment services and outsourced treasury automation solutions.
Emerging Market Trends
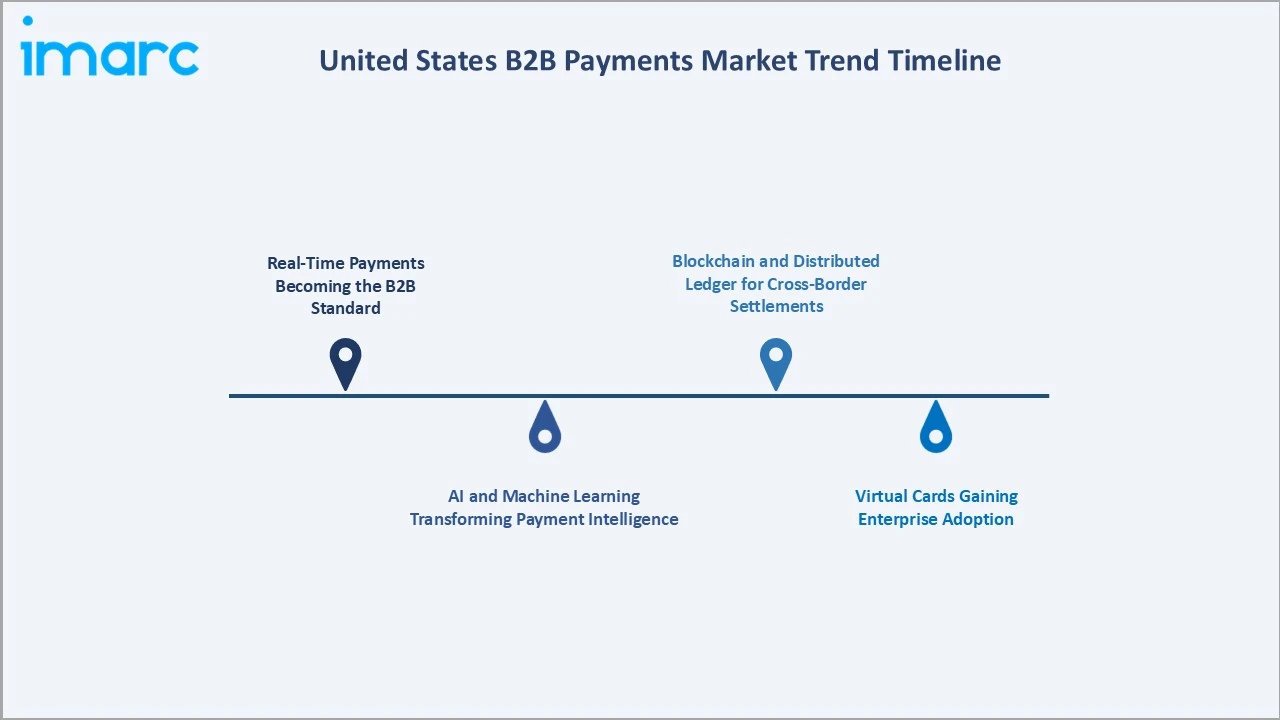
1. Real-Time Payments Becoming the B2B Standard
FedNow and RTP network expansion is progressively establishing real-time payment as the new B2B settlement baseline, replacing same-day and next-day ACH for time-sensitive supplier payments, emergency disbursements, and just-in-time trade finance. Enterprise treasury teams are reconfiguring cash management strategies around 24/7 payment availability.
2. AI and Machine Learning Transforming Payment Intelligence
Generative AI and machine learning are being deployed across B2B payment workflows for intelligent invoice processing, predictive cash flow forecasting, anomaly detection, and conversational treasury interfaces. Payment platforms integrating AI-native capabilities are capturing enterprise market share from legacy providers through demonstrable efficiency gains.
3. Virtual Cards Gaining Enterprise Adoption
Single-use virtual card programs are growing rapidly in B2B payments as enterprises recognize cash-back revenue generation, enhanced supplier payment controls, and automated reconciliation benefits. Virtual card B2B volume is growing at 12%+ CAGR as payment platforms integrate card issuance capabilities directly into AP automation workflows.
4. Blockchain and Distributed Ledger for Cross-Border Settlements
Blockchain-based cross-border B2B payment networks are gaining traction among multinational enterprises seeking faster settlement, reduced FX costs, and transparent transaction tracking versus SWIFT-based correspondent banking. Institutional stablecoin adoption for B2B trade settlements is emerging as a viable corporate treasury use case through the forecast period.
Industry Value Chain Analysis
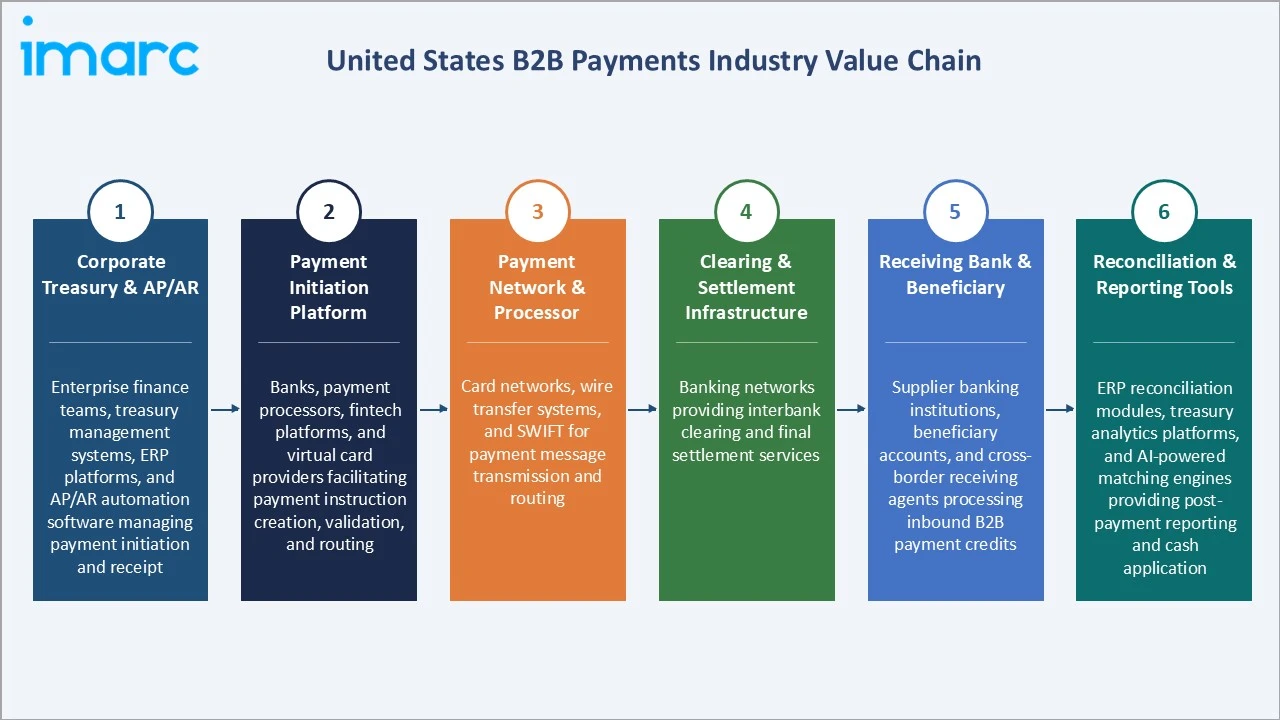
The US B2B payment value chain is evolving from a linear bank-centric model to a multi-participant ecosystem where fintech platforms, payment networks, and technology providers are capturing value at every stage.
|
Stage |
Key Participants |
|
Corporate Treasury & AP/AR |
Enterprise finance teams, treasury management systems, ERP platforms, and AP/AR automation software managing payment initiation and receipt |
|
Payment Initiation Platform |
Banks, payment processors, fintech platforms, and virtual card providers facilitating payment instruction creation, validation, and routing |
|
Payment Network & Processor |
Card networks, wire transfer systems, and SWIFT for payment message transmission and routing |
|
Clearing & Settlement Infrastructure |
Banking networks providing interbank clearing and final settlement services |
|
Receiving Bank & Beneficiary |
Supplier banking institutions, beneficiary accounts, and cross-border receiving agents processing inbound B2B payment credits |
|
Reconciliation & Reporting Tools |
ERP reconciliation modules, treasury analytics platforms, and AI-powered matching engines providing post-payment reporting and cash application |
Payment infrastructure layer participants network operators, clearing houses, and settlement systems represent the most structurally stable value chain positions, while payment initiation and reconciliation layers face the highest competitive disruption from fintech innovation and embedded finance platforms.
Technology Landscape in the United States B2B Payments Industry
Artificial Intelligence and Machine Learning Integration
AI and machine learning are being deployed across B2B payment workflows for intelligent invoice data extraction, automated payment matching, fraud pattern detection, and predictive cash flow analytics. Large language models integrated into AP automation platforms are enabling natural language invoice processing, conversational payment status queries, and automated exception handling that reduces human intervention requirements in enterprise payment operations.
Real-Time Payment Technology Infrastructure
The Federal Reserve's FedNow service and The Clearing House's RTP network are establishing 24/7/365 instant payment infrastructure that enables new B2B payment use cases including just-in-time supplier funding, instant trade settlement, and real-time supply chain finance disbursements. ISO 20022 messaging standard migration across US payment networks is enriching transaction data quality, enabling advanced straight-through processing and reducing reconciliation exceptions across enterprise treasury operations.
Blockchain and Distributed Ledger Technology
Permissioned blockchain networks including JPMorgan's Onyx, Visa B2B Connect, and various trade finance blockchain consortia are demonstrating production-grade B2B payment capabilities with improved settlement finality, reduced counterparty risk, and transparent transaction audit trails. Institutional stablecoin infrastructure development by major US banks and payment networks is establishing the foundation for tokenized B2B payment flows that can reduce cross-border settlement times from days to seconds.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Payment Type |
Domestic Payments |
68.7% |
2025 |
|
Payment Mode |
Digital |
62.8% |
2025 |
|
Enterprise Size |
🔒 |
🔒 |
2025 |
|
Industry Vertical |
🔒 |
🔒 |
2025 |
|
Region |
South |
31.4% |
2025 |

By Payment Mode
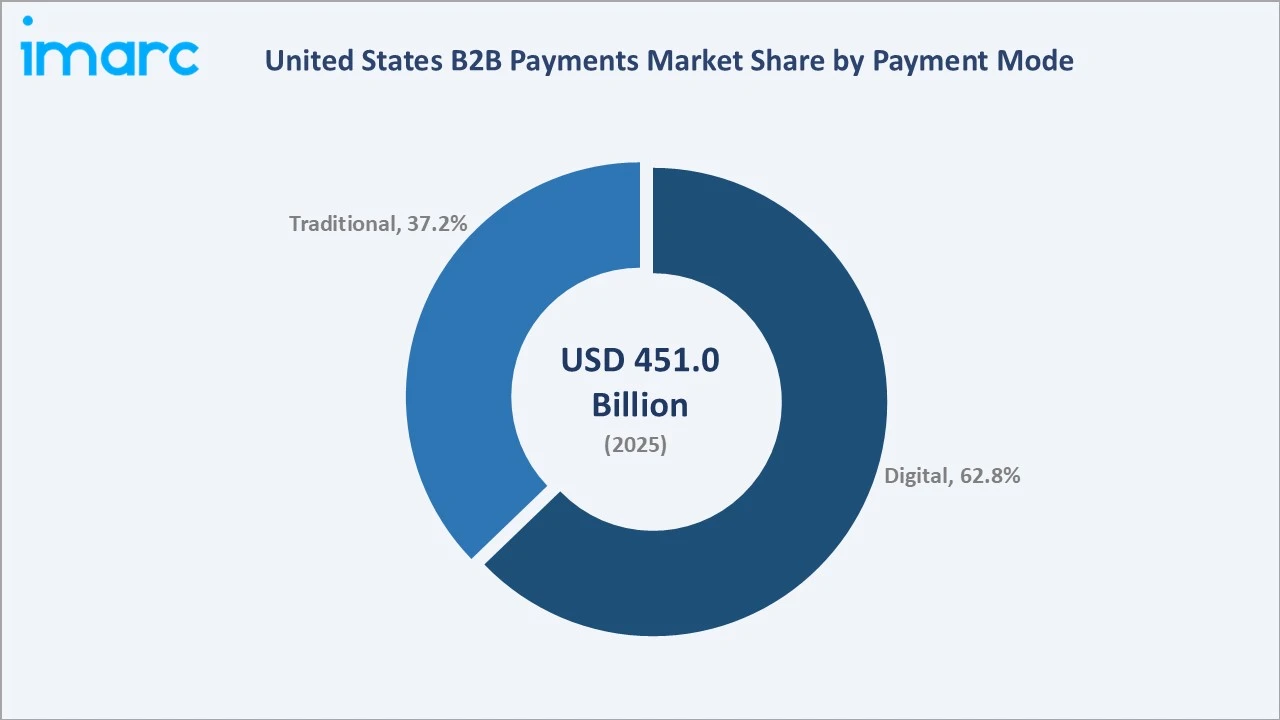
Digital payments lead at 62.8% (2025) through the accelerating enterprise adoption of ACH, wire transfers, virtual cards, real-time payment networks, and digital payment platforms replacing paper-based check transactions. Enterprise digital transformation initiatives are systematically migrating AP workflows from manual check printing and mailing to automated digital payment execution through integrated AP automation platforms.
To access detailed market analysis, Request Sample
Traditional payments at 37.2% retain significant share through entrenched check payment practices in specific industry segments including construction, healthcare, and professional services where payment term customization and remittance detail requirements have historically favored paper-based methods.
By Payment Type
Domestic payments dominate at 68.7% (2025), reflecting the large and mature US domestic commercial transaction base encompassing supplier payments, inter-company transfers, payroll disbursements, and government payment flows processed through domestic ACH and wire transfer networks.
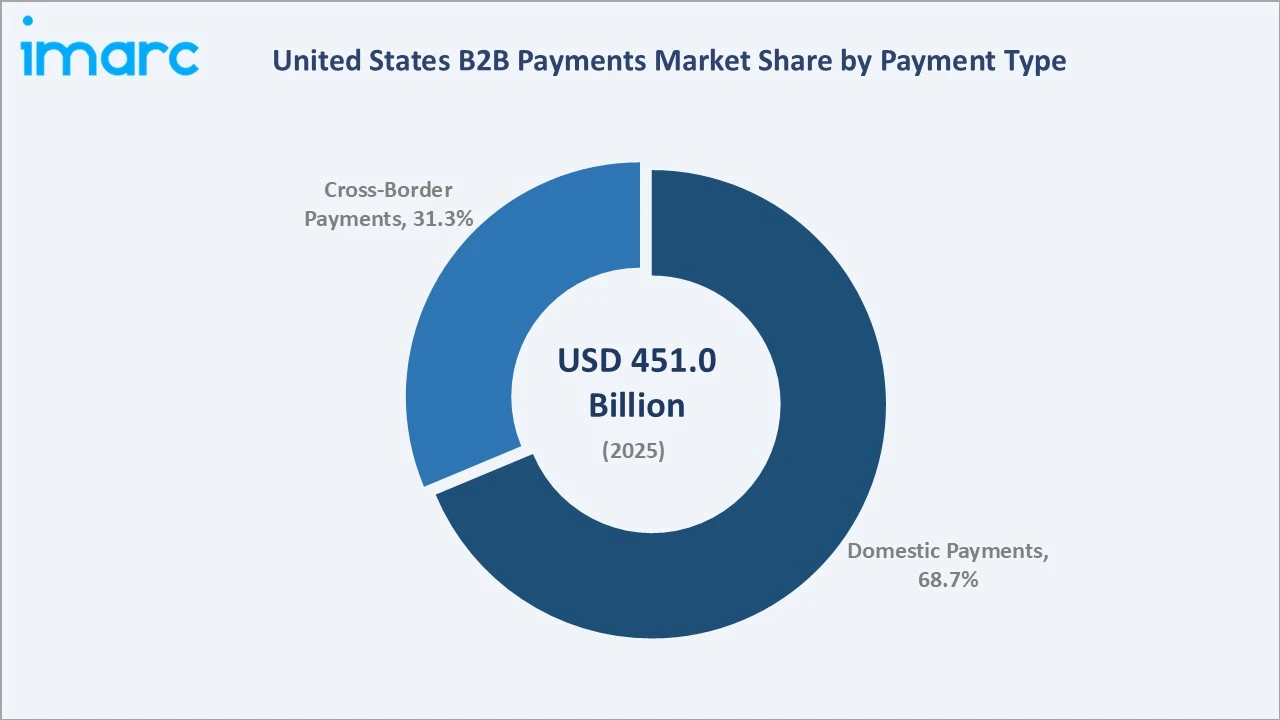
Cross-border payments at 31.3% are the fastest-growing payment type at 9.8% CAGR, driven by expanding US international trade volumes, global supply chain diversification, and the digitalization of cross-border supplier payment workflows.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
South |
31.4% |
Atlanta, Dallas, and Charlotte's financial services infrastructure, Fortune 500 concentration, and expanding fintech ecosystem drive the highest regional B2B payment transaction volume. |
|
West |
27.6% |
California's technology sector dominance, San Francisco's fintech hub, and Silicon Valley enterprise concentration create high digital payment adoption and innovation leadership. |
|
Northeast |
22.8% |
New York's global financial center status and concentration of banking, insurance, and professional services firms drive large-value B2B payment flows and advanced treasury adoption. |
|
Midwest |
18.2% |
Manufacturing, logistics, and agricultural sector concentration in Chicago and major Midwest centers generate substantial B2B payment volumes across domestic and cross-border trade flows. |
South's 31.4% regional leadership reflects the geographic concentration of US financial services infrastructure in Atlanta (payment processing hub), Dallas (Fortune 500 headquarters), and Charlotte (banking center), combined with rapidly expanding technology sector enterprises adopting advanced digital payment platforms.
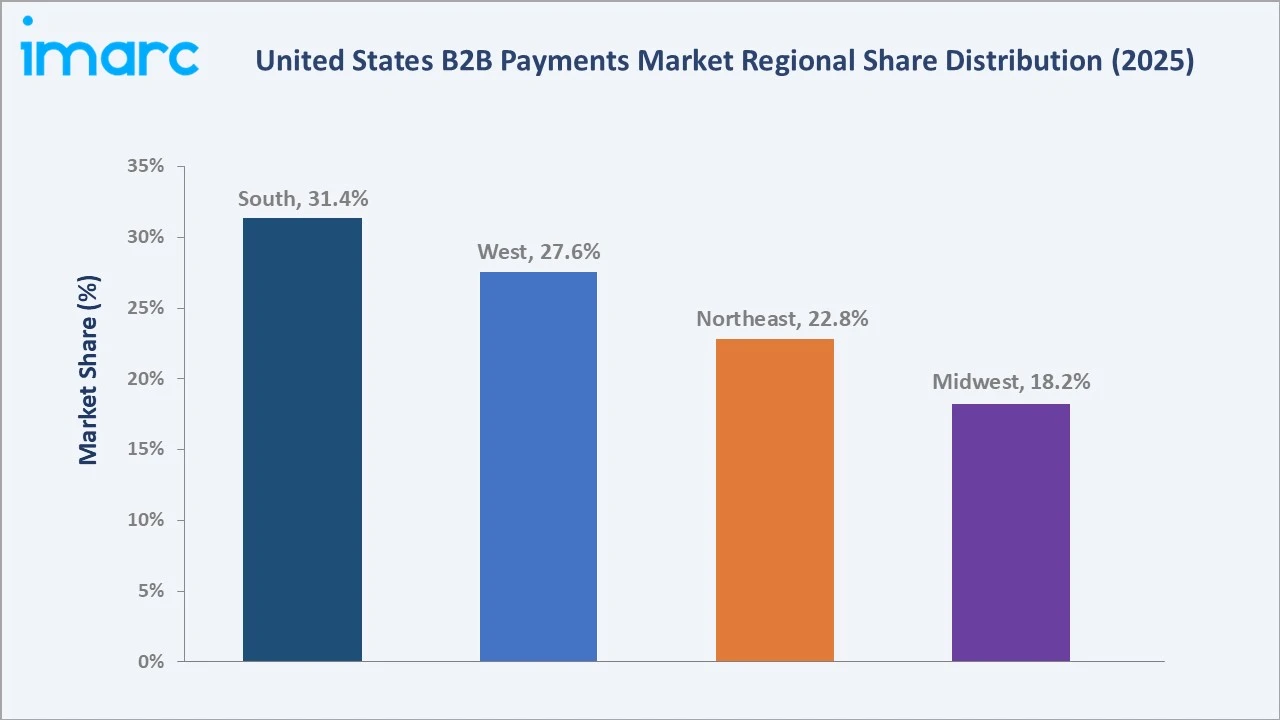
West's 27.6% is driven by California's technology sector dominance, with Silicon Valley enterprises deploying cutting-edge payment automation and embedded finance solutions that generate above-average digital B2B payment transaction values.
Northeast at 22.8% reflects New York's global financial center status, where large-value wire transfers, SWIFT-based international payments, and institutional treasury operations generate high per-transaction payment values that contribute disproportionately to regional market value share.
Midwest at 18.2% represents significant growth potential through manufacturing sector AP digitalization, agricultural trade finance technology adoption, and expanding fintech payment platform penetration in Chicago and secondary industrial centers.
Competitive Landscape
The US B2B payments competitive landscape is dominated by global payment networks and major financial institutions controlling infrastructure-level market positions, with a rapidly expanding fintech layer capturing enterprise workflow-level payment share.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Visa | Visa B2B Connect, Visa Commercial Pay, Visa Cross-Border Solutions | Market Leader | Global payment network infrastructure with deep enterprise and bank partnerships enabling B2B payment innovation at scale |
| Mastercard | Mastercard Track, Mastercard Send, Virtual Card Number programs | Market Leader | Comprehensive B2B payment suite with leading trade finance, virtual card, and cross-border payment capabilities for enterprises |
| American Express | American Express Business Payments, vPayment, Corporate Card | Strong Challenger | Strong enterprise commercial card and virtual payment programs with premium spending controls and cash-back economics for AP teams |
| JPMorgan Chase & Co. | JPMorgan Payments, Kinexys (formerly Onyx), commercial banking | Established Player | Largest US bank payment infrastructure with institutional-grade treasury management and pioneering blockchain B2B payment network |
| Block, Inc. | Square for Business, Cash App Pay, Afterpay B2B payment solutions | Established Player | Technology-first payment ecosystem with strong SME and mid-market payment processing capabilities and integrated financial services |
Key players include Visa, Mastercard, American Express, JPMorgan Chase & Co., Block, Inc., and others.
Key Company Profiles
Visa
Visa is the world's leading digital payments technology company and a dominant force in the United States B2B payments market. Headquartered in San Francisco, California, Visa operates VisaNet, one of the world's most reliable and secure payment processing networks, processing over 200 billion transactions annually across more than 200 countries and territories.
- Key Products: Visa B2B Connect for cross-border corporate payments, Visa Commercial Pay for integrated AP automation, Visa Direct for real-time push payments, and Virtual Card Number programs for enterprise AP control.
- Strategic Focus: Expanding B2B payment network infrastructure to capture the multi-trillion-dollar enterprise payment digitalization opportunity through bank partnerships, fintech integrations, and direct enterprise engagement programs, investing in Visa B2B Connect expansion for direct, multi-lateral cross-border B2B payment capabilities and developing Visa Commercial Pay embedded payment APIs for integration within leading ERP and procurement platforms.
Mastercard
Mastercard is a global technology company in the payments industry, operating one of the world's fastest payment processing networks. The company's B2B payment solutions span commercial cards, virtual payment programs, cross-border payment infrastructure, and trade finance technology platforms serving enterprises of all sizes in the United States market.
- Key Products: Mastercard Track Business Payment Service for domestic and cross-border B2B transactions, Mastercard Send for real-time B2B disbursements, virtual card number programs, and Mastercard Multi-Token Network for blockchain-based B2B settlements.
- Strategic Focus: Building comprehensive B2B payment solutions spanning the full payment lifecycle from invoice origination to settlement and reconciliation, with increasing emphasis on real-time and blockchain-based payment innovation, scaling Mastercard Track as the preferred B2B payment network and expanding blockchain and tokenized payment infrastructure through the Multi-Token Network for next-generation institutional B2B payment settlement flows.
Market Concentration Analysis
The US B2B payments market exhibits a moderately concentrated structure at the infrastructure layer, where key players network duopoly processes the majority of card-based B2B transactions, while the broader market across ACH, wire, and emerging real-time payment channels is more fragmented across major banks, fintech platforms, and specialized payment processors. The top five players collectively represent significant market value share across different payment method and customer segment dimensions.
Market concentration dynamics are being disrupted by fintech platforms capturing enterprise workflow-level payment share through AP automation, embedded finance, and real-time payment adoption.
Investment & Growth Opportunities
Highest Growth Segments
Cross-border payments (9.8% CAGR through trade digitalization), digital payment adoption (9.2% CAGR through check-to-digital migration), overall B2B market (7.39% CAGR), domestic real-time payments (6.5% CAGR through FedNow/RTP adoption), and traditional payment digitalization (4.3% CAGR through legacy check replacement) represent the US B2B payments market's priority investment growth segments through 2034.
Emerging Investment Opportunities
AP/AR automation platform investment represents the highest near-term return opportunity, where workflow integration creates durable enterprise switching costs and high payment volume capture from existing customer relationships. Cross-border B2B payment fintech capturing share from correspondent banking incumbents offers substantial margin improvement potential, given traditional 2-5% cross-border payment cost structures versus fintech sub-1% alternatives.
Investment Themes
- AP/AR automation and B2B payment workflow integration: Platforms capturing enterprise payment execution within accounts payable workflows command premium valuations and strong net revenue retention through embedded switching costs and payment volume growth aligned with client revenue expansion.
- Cross-border B2B payment fintech: Technology-first cross-border payment platforms delivering real-time FX conversion, transparent pricing, and compliance automation are capturing significant share from correspondent banking, offering 60-80% cost improvement for enterprise international payments.
Future Market Outlook (2026-2034)
The United States B2B payments market is projected to grow from USD 451.0 Billion in 2025 to USD 484.3 Billion in 2026, reaching USD 644.3 Billion by 2030 and USD 873.6 Billion by 2034 at a CAGR of 7.39% during 2026-2034. Growth is anchored by the sustained enterprise digital transformation imperative, expanding real-time payment infrastructure, AI-driven automation penetration, and accelerating cross-border trade digitalization.
Three structural forces define US B2B payments' growth trajectory through 2034: the multi-trillion-dollar check-to-digital migration still underway as paper-based payment volume converts to ACH, virtual cards, and real-time payment networks; the AI and automation revolution transforming enterprise treasury operations from cost centers into strategic financial infrastructure; and the cross-border trade digitalization wave enabling US enterprises to replace costly SWIFT-based correspondent banking with fintech and blockchain-native international payment solutions. The combination of deep digitalization runway in traditional payment segments, real-time infrastructure maturation, and embedded finance proliferation creates a structurally favorable long-term demand environment for sustained high-single-digit market growth through the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with US B2B payments market stakeholders including enterprise treasury professionals, AP automation platform executives, financial institution payment product leaders, fintech payment company management, and corporate finance technology consultants across domestic and cross-border payment segments.
Secondary Research
Secondary research encompassed Federal Reserve payment studies, NACHA ACH volume statistics, The Clearing House RTP transaction data, SWIFT financial messaging reports, Association for Financial Professionals treasury survey data, Nilson Report commercial card statistics, and financial disclosures from publicly listed payment companies. Over 50 secondary sources were reviewed.
Forecasting Models
Forecasts used an enterprise payment volume and digitalization migration model: domestic B2B payment value growth rates applied across enterprise segment revenue projections, adjusted for digital payment adoption curves, cross-border trade volume growth, and embedded finance capture rates within enterprise payment workflows.
United States B2B Payments Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Payment Types Covered | Domestic Payments, Cross-Border Payments |
| Payment Modes Covered | Traditional, Digital |
| Enterprise Sizes Covered | Large Enterprises, Small and Medium-sized Enterprises |
| Industry Verticals Covered | BFSI, Manufacturing, IT and Telecom, Metals and Mining, Energy and Utilities, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Visa, Mastercard, American Express, JPMorgan Chase & Co., Block, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States B2B payments market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States B2B payments market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States B2B payments industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States B2B Payments Market Report
The United States B2B payments market size is estimated at USD 484.3 Billion in 2026, driven by accelerating enterprise digital transformation, AI-driven AP/AR automation adoption, cross-border trade payment digitalization, and expanding real-time payment infrastructure deployment across domestic and international payment channels.
The United States B2B payments market grows at a CAGR of 7.39% during 2026-2034, reaching USD 873.6 Billion by 2034, driven by digital payment migration from paper checks, real-time payment network adoption, AI automation penetration, and cross-border trade volume expansion.
Digital payments lead at 62.8% (2025) through enterprise adoption of ACH, wire transfers, virtual cards, and real-time payment networks, with accelerating migration from paper-based check payments driven by AP automation platform adoption and ERP digital payment integration.
Domestic payments lead at 68.7% (2025) through the large and mature US domestic commercial transaction base, encompassing supplier payments, inter-company transfers, and payroll disbursements processed through ACH, wire, and emerging real-time payment networks.
The South leads at 31.4% (2025) through Atlanta's payment processing hub concentration, Dallas and Charlotte's Fortune 500 enterprise density, and rapidly expanding fintech ecosystem driving high digital B2B payment adoption rates across commercial and financial services sectors.
Leading companies include Visa, Mastercard, American Express, JPMorgan Chase & Co., Block, Inc., and others.
The United States B2B payments market is projected to reach USD 644.3 Billion by 2030, supported by sustained enterprise digital payment adoption, real-time payment infrastructure maturation, AI-driven treasury automation penetration, and cross-border trade payment digitalization expansion.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade