
U.S. Luxury Car Market Size, Share, Trends and Forecast by Vehicle Type, Fuel Type, Price Range, and Region, 2026-2034
U.S. Luxury Car Market Size, Share, Trends & Forecast (2026-2034)
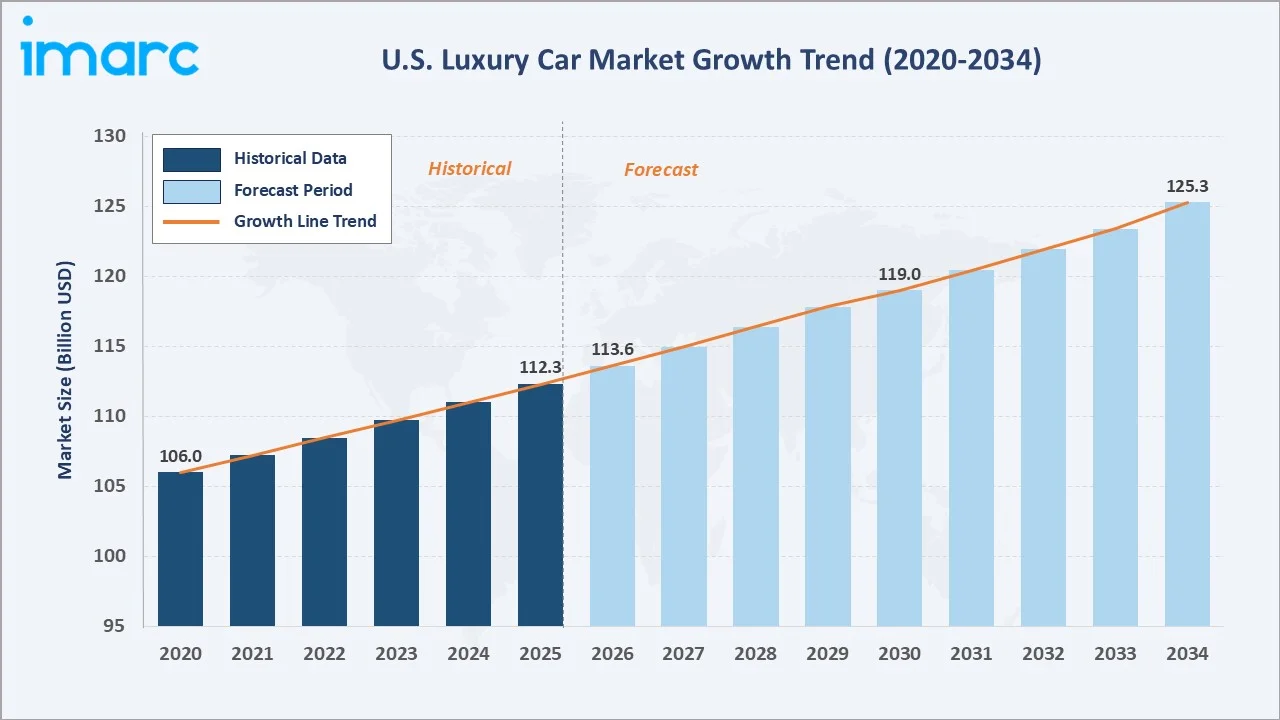
The United States luxury car market grew from USD 112.3 Billion in 2025 to USD 113.6 Billion in 2026 and is projected to reach USD 125.3 Billion by 2034, growing at a CAGR of 1.16% during 2026-2034. The market is driven by rising disposable incomes, technological advancements, increasing demand for electric luxury models, and growing consumer preference for premium, feature-rich vehicles.
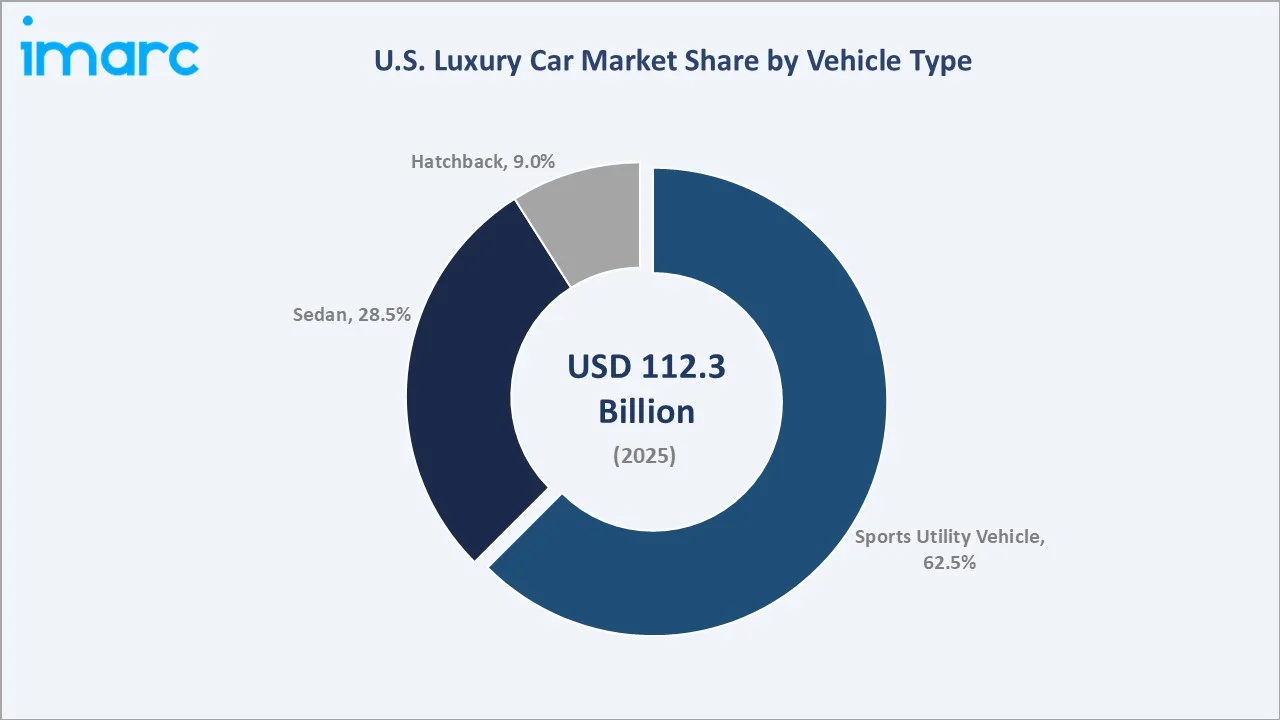
Sports Utility Vehicles dominate at 62.5% by vehicle type. Gasoline leads at 72.5% by fuel type. The South region commands 34.5% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 112.3 Billion |
|
Market Size (2026) |
USD 113.6 Billion |
|
Forecast Market Size (2034) |
USD 125.3 Billion |
|
CAGR (2026-2034) |
1.16% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Vehicle Type |
Sports Utility Vehicle (62.5%, 2025) |
|
Dominant Fuel Type |
Gasoline (72.5%, 2025) |
|
Leading Region |
South (34.5%, 2025) |
The U.S. luxury car market size increased from USD 106.0 Billion in 2020 to USD 112.3 Billion in 2025 and is estimated to reach USD 113.6 Billion in 2026. The market is further expected to grow to USD 119.0 Billion by 2030 and USD 125.3 Billion by 2034.
The U.S. luxury car market is commercially significant as a key driver of the automotive industry, reflecting affluent consumer spending on premium vehicles combining advanced technology, superior performance, and elevated brand prestige across all major vehicle segments.
To get more information on this market, Request Sample
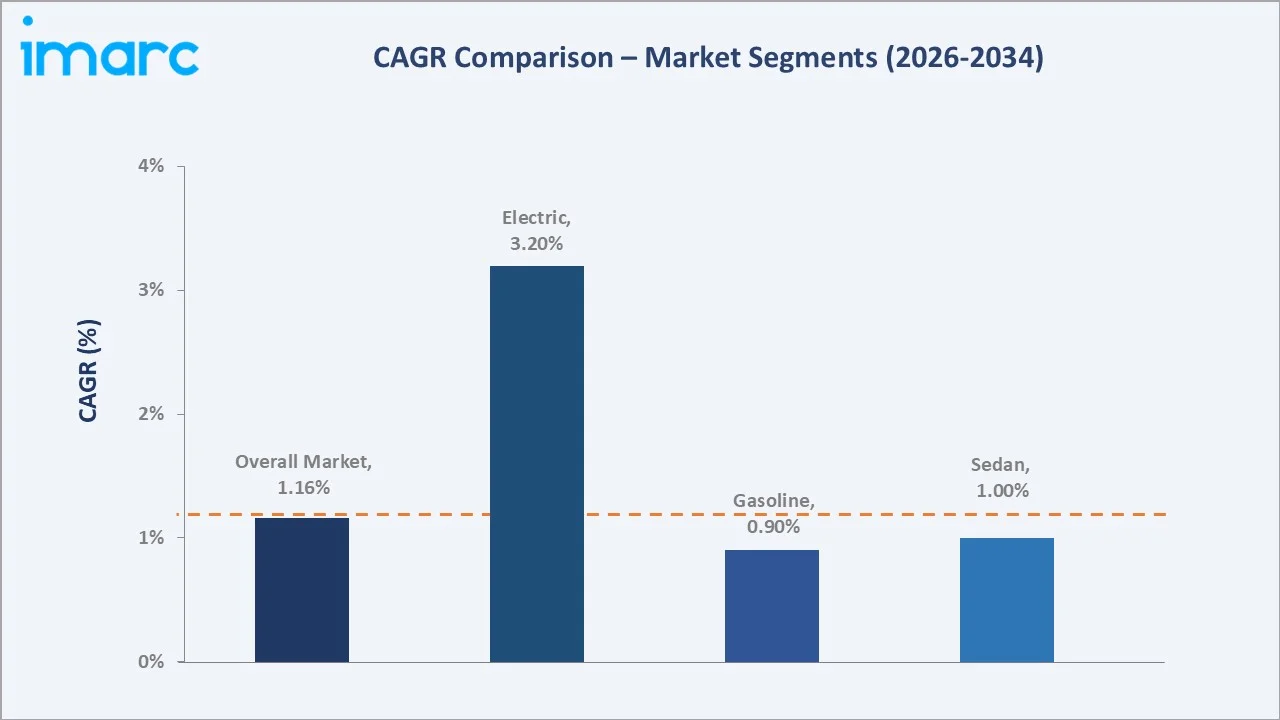
Electric luxury vehicles are the fastest-growing segment at approximately 3.2% CAGR, driven by government incentives, expanding charging infrastructure, and consumer appetite for sustainable premium mobility. SUVs remain the dominant vehicle type, growing faster than sedans across all regions.
Executive Summary
The U.S. luxury car market expanded from USD 112.3 Billion in 2025 to an estimated USD 113.6 Billion in 2026, supported by robust consumer spending on premium vehicles, accelerating EV adoption, and growing demand for connected and autonomous driving features. The market is projected to reach USD 125.3 Billion by 2034.
The U.S. luxury car market is commercially distinguished from mainstream automotive markets by its strong brand prestige dynamics, high-value consumer base, and above-average technology adoption rate. The confluence of premiumization trends and EV transition creates a dual growth engine that underpins the market's sustained expansion trajectory.
Sports Utility Vehicles lead at 62.5% of vehicle type share, reflecting consumer preference for spacious, versatile premium vehicles. Gasoline at 72.5% dominates fuel type, while electric luxury vehicles at 24.5% are growing rapidly. The South leads regionally at 34.5%, anchored by Texas, Florida, and Georgia's high-net-worth consumer concentrations.
Key Market Insights
|
Insight |
Data |
|
Dominant Vehicle Type |
Sports Utility Vehicle – 62.5% share (2025) |
|
Dominant Fuel Type |
Gasoline – 72.5% share (2025) |
|
Leading Region |
South – 34.5% share (2025) |
|
Market Opportunity |
Electric luxury SUV expansion, autonomous driving features, bespoke personalization, subscription-based ownership models, premium EV charging ecosystems |
Key Analytical Observations Supporting the Above Data:
- Sports Utility Vehicle at 62.5%: Luxury SUVs dominate due to their versatility, spaciousness, and ability to combine premium comfort with practical utility. Families and affluent consumers increasingly prefer SUVs for their elevated seating position, cargo capacity, and advanced all-wheel-drive capability. Models from BMW, Mercedes-Benz, and Cadillac lead this category with strong consumer loyalty and continuous product innovation.
- Gasoline at 72.5%: Gasoline-powered luxury vehicles maintain dominance through their established performance credentials, extensive refueling infrastructure, and superior driving range. High-displacement engines in premium segments deliver the power and refinement expected by luxury consumers, with turbocharged and hybrid gasoline powertrains extending efficiency without compromising performance.
- South at 34.5%: The South leads regionally through its large and growing high-net-worth individual population concentrated in states such as Texas, Florida, and Georgia. The region's favorable tax environment, absence of state income tax in key states, growing tech and financial sectors, and car-dependent culture collectively sustain strong luxury vehicle demand across all price segments.
U.S. Luxury Car Market Overview
The U.S. luxury car market operates at the intersection of consumer affluence, technological advancement, and brand prestige. It encompasses a diverse range of premium vehicles from entry-level luxury to ultra-high-end, spanning traditional gasoline powertrains through to cutting-edge electric and hybrid models serving the nation's most discerning automotive consumers.
The market ecosystem integrates tier-one automotive suppliers, global OEMs, authorized dealer networks, digital retail platforms, and luxury financing services. Macroeconomic factors supporting growth include sustained wealth accumulation among upper-income households, strong equity markets supporting discretionary spending, and a structural shift toward premiumization in consumer goods.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
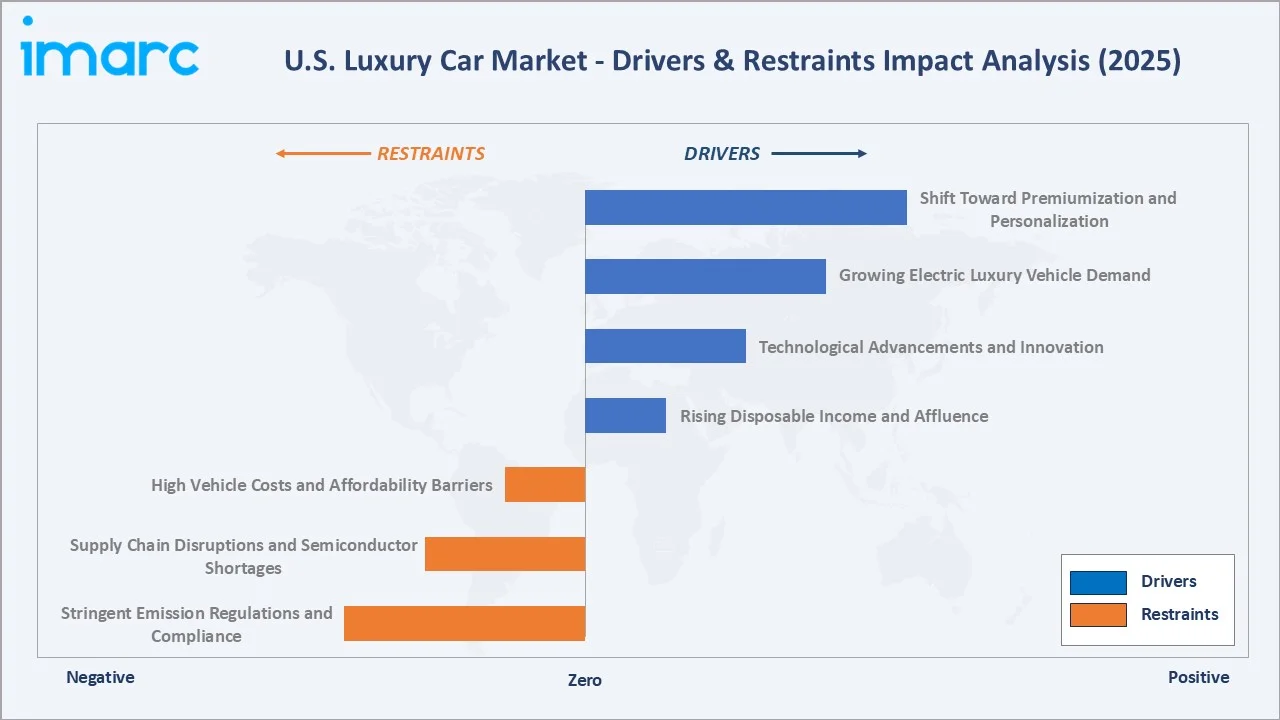
- Rising Disposable Income and Affluence: Growing wealth among upper-income American households continues to fuel sustained demand for luxury vehicles. According to Federal Reserve data, the top quintile of US households controls the majority of consumer net worth, creating a large and structurally stable addressable market for luxury automotive brands. The continued expansion of the technology, finance, and professional services sectors is creating new high-income consumers who prioritize premium mobility as a lifestyle expression. This income growth drives consistent upgrading behavior and repeat luxury vehicle purchases across generations of affluent consumers.
- Technological Advancements and Innovation: Consumers are increasingly drawn to luxury vehicles featuring autonomous driving capabilities, enhanced infotainment systems, and seamless connectivity. The Cadillac Escalade features cutting-edge technologies including autonomous Super Cruise driver assistance, a curved OLED display, and premium audio systems. Over-the-air software updates, AI-powered driver assistance, and augmented reality heads-up displays are redefining what constitutes luxury, elevating technology from a differentiator to a baseline expectation among premium consumers in an increasingly connected automotive landscape.
- Growing Electric Luxury Vehicle Demand: Accelerating adoption of electric luxury vehicles is creating a new growth vector within the premium automotive segment. Tesla, BMW, Mercedes-Benz, and Audi are expanding their luxury EV portfolios to capitalize on growing consumer interest in sustainable premium mobility. Government incentives including federal EV tax credits, expanding charging infrastructure, and improving battery technology with longer ranges are reducing adoption barriers.
- Shift Toward Premiumization and Personalization: Affluent consumers increasingly seek bespoke vehicles tailored to their individual preferences, driving demand for extensive customization programs. Luxury automakers are offering personalized interior options, advanced material choices, exclusive paint colors, and technology integrations. In September 2024, Lotus launched the Eletre Carbon, an ultra-luxury variant of its electric hyper-SUV featuring carbon fiber craftsmanship and dynamic quilted interiors. This trend toward individualization reinforces brand loyalty and enables premium pricing, strengthening manufacturer margins in the competitive luxury vehicle landscape.
Market Restraints
- High Vehicle Costs and Affordability Barriers: Despite strong demand from affluent consumers, the escalating base prices of luxury vehicles are creating market accessibility barriers. Supply chain challenges, advanced technology integration costs, and premium materials have driven significant price increases across luxury segments, pushing entry thresholds higher and narrowing the consumer base. Rising interest rates have increased the cost of luxury vehicle financing, making monthly payments less attractive for aspirational buyers who represent the lower end of the luxury market's addressable consumer population.
- Supply Chain Disruptions and Semiconductor Shortages: The luxury automotive industry remains vulnerable to supply chain disruptions, particularly semiconductor shortages that disproportionately impact feature-rich premium vehicles. Advanced driver assistance systems, infotainment platforms, and electrification components all depend on specialized chips and electronic components susceptible to supply volatility. Production delays caused by these constraints have frustrated consumers with long order wait times and limited inventory availability, creating revenue recognition timing issues that affect both manufacturers and dealer networks.
- Stringent Emission Regulations and Compliance: Increasingly rigorous federal and state emission standards are creating structural compliance challenges for luxury automakers. California's zero-emission vehicle mandates and federal CAFE standards require substantial capital investment in electrification programs that must be balanced against continued investment in traditional powertrain excellence. The cost of maintaining compliance across a diverse model range with varying fuel types while meeting consumer performance expectations creates operational complexity and financial pressure, particularly for brands with extensive gasoline-powered lineups transitioning toward electrification.
Market Opportunities
- Electric Luxury SUV Expansion: The convergence of the dominant luxury SUV segment with the rapidly growing electric vehicle category represents the single largest commercial opportunity in the U.S. luxury car market. As EV range anxiety diminishes and charging networks expand, affluent SUV-oriented consumers represent a highly receptive market for premium electric SUV offerings. BMW iX, Mercedes EQS SUV, and Cadillac LYRIQ are pioneering this combination, creating a growing addressable market segment with premium pricing and strong margins that will define market leadership through 2034.
- Autonomous and Connected Vehicle Technology: The integration of Level 2+ autonomous driving features, advanced connectivity, and over-the-air update capabilities creates significant revenue expansion opportunities for luxury automakers. Technology-as-a-service subscription models for autonomous features, premium connectivity packages, and personalized software upgrades represent new recurring revenue streams that complement traditional vehicle sales. These digital revenue vectors are particularly attractive to luxury consumers who associate technology sophistication with premium positioning.
Market Challenges
- Intensifying Competition from New Luxury EV Entrants: Established legacy luxury automakers face mounting competitive pressure from Tesla and emerging premium EV brands that have established strong consumer appeal, particularly among younger affluent buyers. Tesla's direct-to-consumer sales model, continuous over-the-air updates, and technology-first brand positioning have created a new paradigm of luxury vehicle ownership that challenges traditional dealership-based models and brand heritage positioning strategies of established European luxury automakers.
- Evolving Consumer Expectations and Digital Retail Shift: The luxury car purchasing journey is fundamentally transforming as affluent consumers expect seamless digital experiences, virtual configuration tools, and frictionless transaction processes comparable to other luxury goods categories. Meeting these evolving expectations requires substantial investment in digital retail infrastructure, consumer data management platforms, and omnichannel sales capabilities that many traditional dealers and legacy automakers are challenged to deploy at the speed and quality expected by premium consumers.
Emerging Market Trends
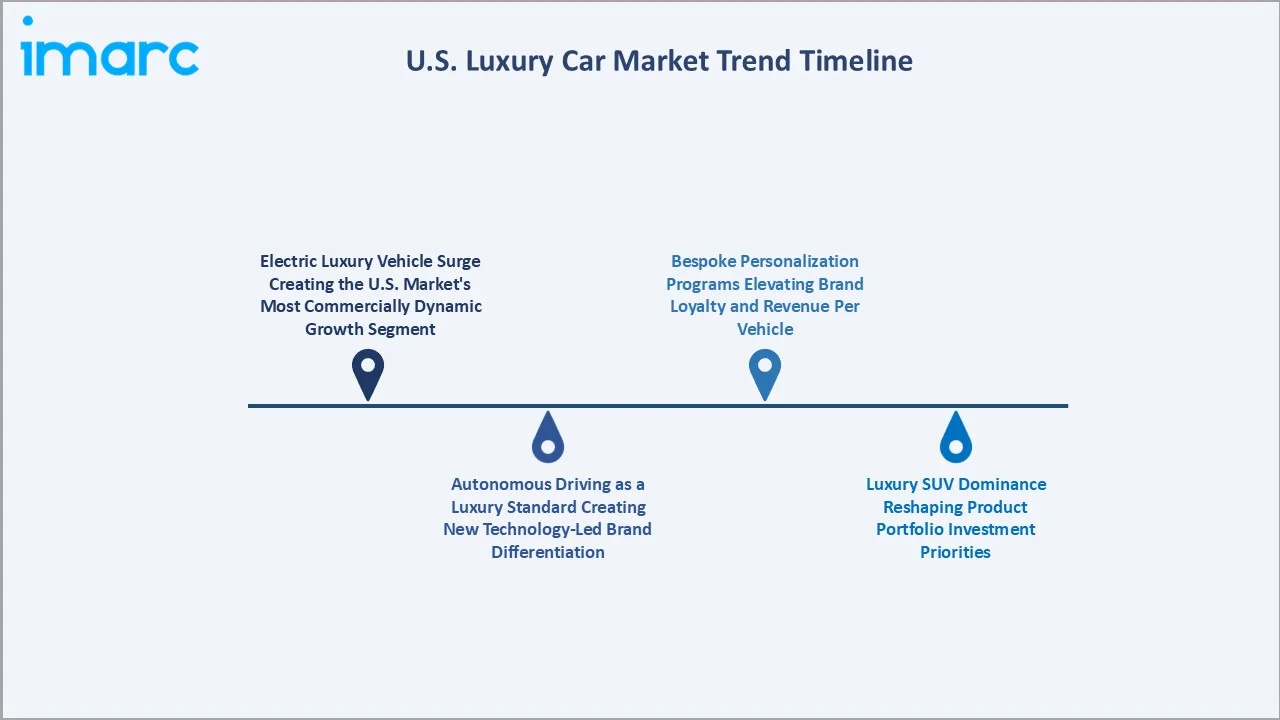
1. Electric Luxury Vehicle Surge Creating the U.S. Market's Most Commercially Dynamic Growth Segment
Electric luxury vehicles are fundamentally reshaping competitive dynamics and consumer expectations in the U.S. premium automotive market. Tesla's dominance has been challenged by established luxury brands rapidly expanding their EV portfolios. BMW, Mercedes-Benz, Cadillac, and Audi are all launching electric variants of their flagship models, creating an unprecedented breadth of premium EV choice that is accelerating consumer adoption beyond early-adopter demographics.
2. Autonomous Driving as a Luxury Standard Creating New Technology-Led Brand Differentiation
Advanced driver assistance systems are transitioning from optional extras to baseline luxury vehicle expectations. General Motors' Super Cruise, Mercedes-Benz's Drive Pilot, and BMW's Highway Assistant are establishing brand differentiation through autonomous capability breadth and reliability. Faraday Future unveiled its FX prototype focused on delivering "twice the performance at half the price," signaling intensifying technology competition in the intelligent EV luxury segment through 2034.
3. Luxury SUV Dominance Reshaping Product Portfolio Investment Priorities
The luxury SUV segment's 62.5% market share dominance is directing disproportionate product development investment toward premium SUV and crossover platforms. Lotus launched the Eletre Carbon, an ultra-luxury electric hyper-SUV in North America, featuring carbon fiber craftsmanship, advanced performance enhancements, and extensive customization. This trend is accelerating the shift of luxury automotive R&D spend toward utility formats over traditional sedan architectures.
4. Bespoke Personalization Programs Elevating Brand Loyalty and Revenue Per Vehicle
Ultra-premium personalization programs including dedicated bespoke studios, custom paint matching, exclusive interior materials, and personalized technology configurations are becoming key revenue differentiators for luxury brands. These programs enhance brand stickiness among ultra-high-net-worth consumers, create exclusivity that justifies premium pricing, and generate above-average gross margins that partially offset the higher development costs of increasingly technology-intensive luxury vehicles.
Industry Value Chain Analysis
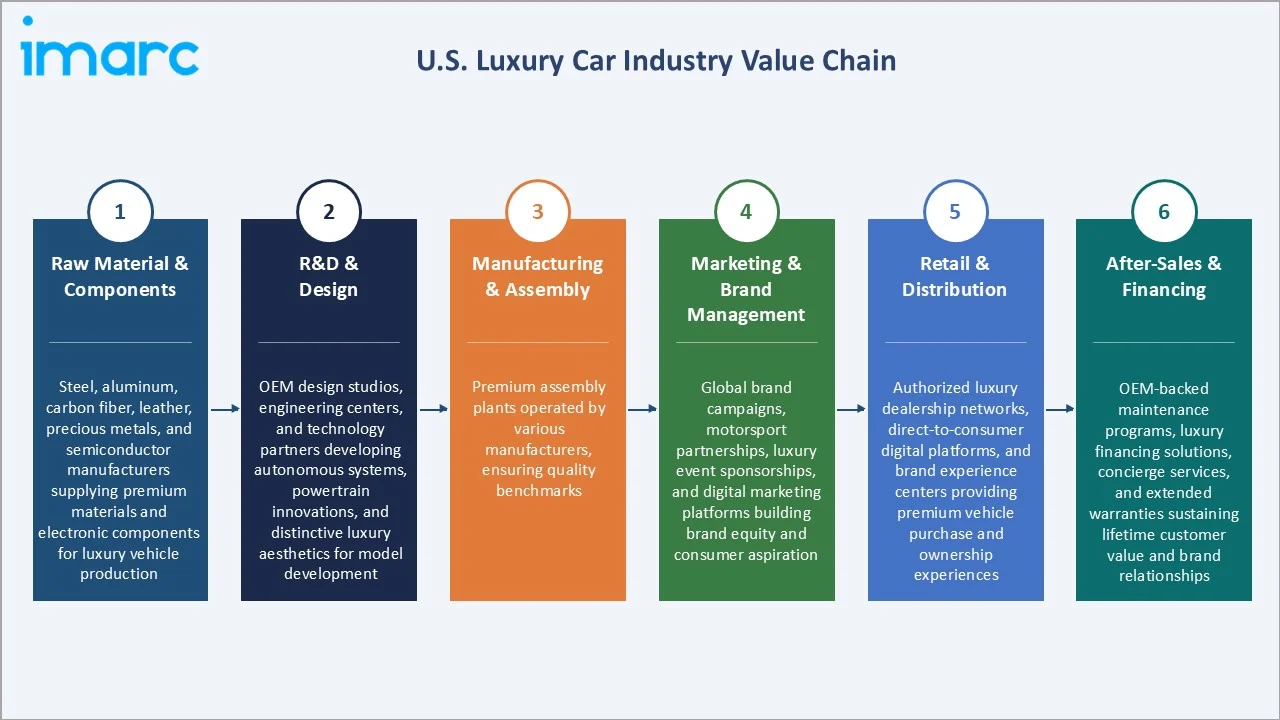
The U.S. luxury car market value chain is characterized by highly integrated global supply networks, sophisticated brand management operations, and premium retail experiences. Major players invest heavily across the full value chain to maintain quality standards and brand positioning.
|
Stage |
Key Participants |
|
Raw Material & Components |
Steel, aluminum, carbon fiber, leather, precious metals, and semiconductor manufacturers supplying premium materials and electronic components for luxury vehicle production |
|
R&D & Design |
OEM design studios, engineering centers, and technology partners developing autonomous systems, powertrain innovations, and distinctive luxury aesthetics for model development |
|
Manufacturing & Assembly |
Premium assembly plants operated by various manufacturers, ensuring quality benchmarks |
|
Marketing & Brand Management |
Global brand campaigns, motorsport partnerships, luxury event sponsorships, and digital marketing platforms building brand equity and consumer aspiration |
|
Retail & Distribution |
Authorized luxury dealership networks, direct-to-consumer digital platforms, and brand experience centers providing premium vehicle purchase and ownership experiences |
|
After-Sales & Financing |
OEM-backed maintenance programs, luxury financing solutions, concierge services, and extended warranties sustaining lifetime customer value and brand relationships |
The retail and brand management stage is the luxury car value chain's most commercially consequential stage, where brands invest heavily in creating aspirational purchase experiences that justify premium pricing and reinforce the emotional connection between consumer and brand.
Technology Landscape in the U.S. Luxury Car Industry
Electric Vehicle Powertrain and Battery Technology
Advanced lithium-ion and solid-state battery technologies are enabling longer driving ranges and faster charging in luxury EVs. OEMs are integrating high-capacity battery platforms with 300–400+ mile ranges, positioning electric powertrains as technically superior alternatives to traditional combustion engines in the premium segment.
Advanced Driver Assistance and Autonomous Systems
Level 2+ ADAS technologies including adaptive cruise control, lane-keeping assist, and semi-autonomous driving systems are becoming baseline features in luxury vehicles. Various drive pilot systems represent commercially deployed highway autonomous systems that are redefining the luxury vehicle technology value proposition for affluent consumers.
Connected Vehicle and Over-the-Air Software Technology
Luxury vehicles increasingly function as software-defined platforms, with OTA updates delivering new features, performance improvements, and autonomous capability enhancements post-purchase. Tesla's pioneering OTA architecture has compelled BMW, Mercedes-Benz, and others to deploy similar connected vehicle platforms, transforming the post-sale relationship between luxury automakers and consumers.
Market Segmentation Analysis
The report covers the following segments:
|
Segment |
Leading Segment |
Market Share |
Year |
|
Vehicle Type |
Sports Utility Vehicle |
62.5% |
2025 |
|
Fuel Type |
Gasoline |
72.5% |
2025 |
|
Price Range |
🔒 |
🔒 |
2025 |
|
Region |
South |
34.5% |
2025 |

By Vehicle Type
Sports Utility Vehicle leads at 62.5% (2025). The luxury SUV segment encompasses the U.S.'s most commercially dominant premium vehicle format, combining spaciousness, versatility, elevated driving position, and advanced technology in a configuration that resonates across families, executives, and lifestyle-driven affluent consumers. The segment's growth has been structurally driven by consumer lifestyle preferences favoring utility over traditional sedan form factors.
To access detailed market analysis, Request Sample
Sedan at 28.5% remains the traditional prestige format preferred by executive and business-focused buyers. Hatchback at 9.0% serves urban-focused luxury consumers who prioritize compactness combined with premium features, representing a niche but growing segment in dense metropolitan markets.
By Fuel Type
Gasoline leads at 72.5% (2025). The gasoline-powered luxury segment serves consumers seeking traditional high-performance powertrains delivering the refined engine sound, immediate power delivery, and extensive refueling convenience that remain defining characteristics of premium driving experiences. Turbocharged and naturally aspirated gasoline engines continue to define the performance benchmarks of iconic luxury nameplates.
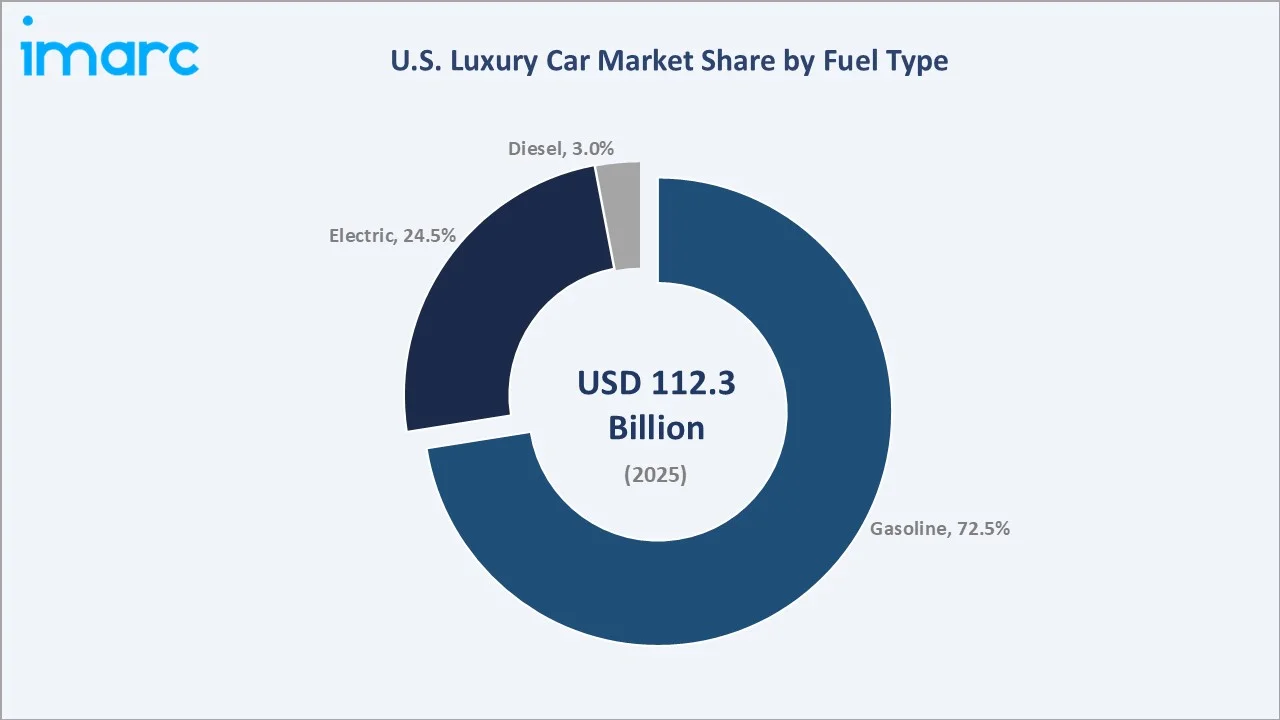
Electric at 24.5% is the fastest-growing fuel type at ~3.2% CAGR, driven by Tesla's market leadership, expanding luxury EV portfolios from BMW and Mercedes-Benz, and government incentives accelerating adoption. Diesel at 3.0% serves a niche segment of luxury buyers prioritizing long-range efficiency and torque for premium SUV and sedan applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
South |
34.5% |
Driven by high-net-worth consumer concentrations in Texas, Florida, and Georgia, favorable tax environments, car-dependent culture, and strong demand for luxury SUVs and performance vehicles. |
|
West |
27.5% |
Supporting leading demand for electric and hybrid luxury vehicles driven by California's progressive EV policy, tech-sector wealth concentration, and eco-conscious consumer preferences. |
|
Northeast |
21.0% |
Reflects New York, Connecticut, and Massachusetts affluent consumer base with strong preference for premium sedans, urban-ready luxury vehicles, and brand-heritage marques. |
|
Midwest |
17.0% |
Rising demand for durable luxury SUVs suited to varied climate conditions, with growing high-income professional base in Chicago, Detroit, and Minneapolis driving premium automotive purchasing. |
The South's 34.5% market leadership reflects the concentration of high-net-worth households in Texas's energy and technology sectors, Florida's retiree wealth and tourism economy, and Georgia's growing financial and logistics sectors. The region's car-dependent suburban geography and favorable vehicle ownership economics create structurally high luxury vehicle purchase rates.
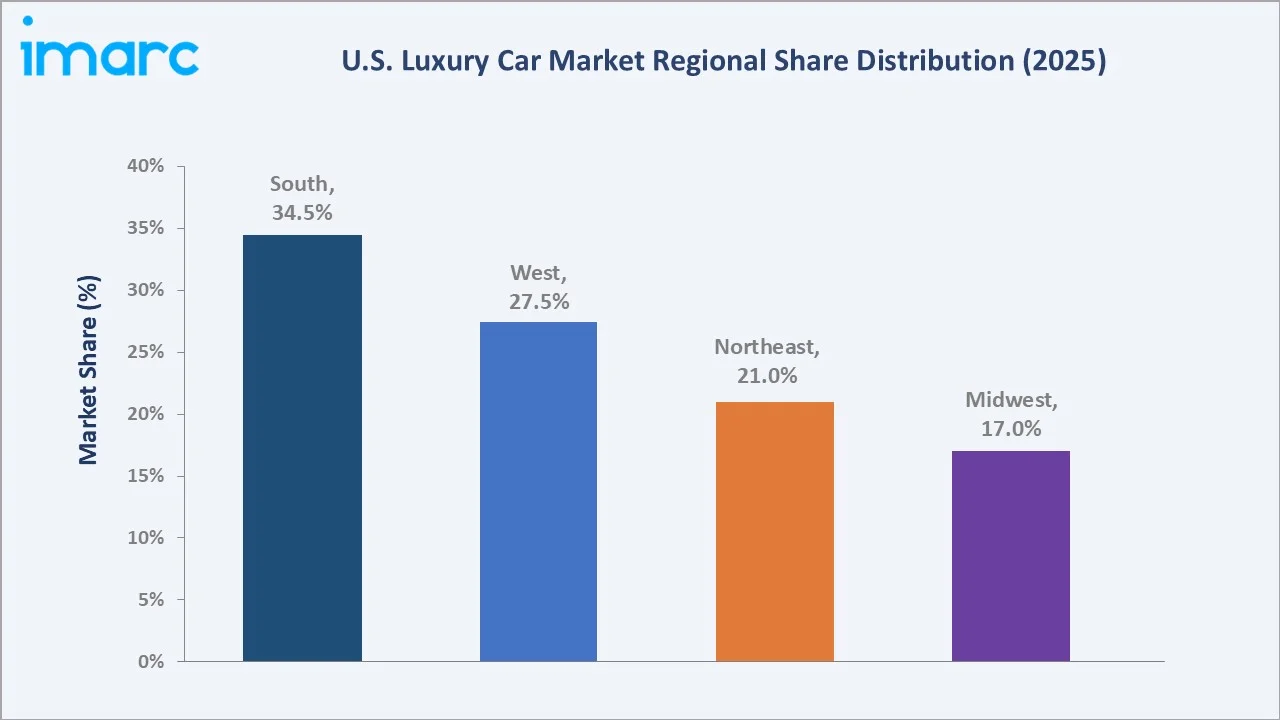
The West's 27.5% is driven by California's tech-sector wealth and the nation's highest electric luxury vehicle adoption rate. The Northeast's 21.0% reflects the region's concentration of financial sector wealth in New York and Connecticut, with strong preference for traditional luxury sedan and SUV marques that combine brand heritage with modern technology.
Competitive Landscape
The U.S. luxury car market competitive landscape is dominated by globally integrated premium automakers competing on brand prestige, technological innovation, EV portfolio breadth, and premium customer experience.
|
Company |
Key Models/Brands |
Market Position |
Core Strength |
|
Mercedes-Benz Group AG |
S-Class, E-Class, GLE, EQS, AMG, Maybach |
Market Leader |
Dominant global luxury brand with comprehensive EV and ICE portfolio; leading S-Class prestige positioning in US market. |
|
BMW AG |
3 Series, 5 Series, 7 Series, X5, X7, i4, iX, M Series |
Market Leader |
Strong US market presence with diversified luxury portfolio spanning performance, SUV, and electric vehicle segments. |
|
Tesla |
Model 3, Model Y, Cybertruck |
Market Leader |
Pioneer of luxury electric vehicles with direct sales model, OTA updates, and technology-first brand positioning. |
|
General Motors |
Cadillac CT5, Escalade, LYRIQ, CELESTIQ |
Strong Challenger |
Leading US domestic luxury brand with Super Cruise autonomous technology and growing EV lineup under Cadillac. |
|
Volkswagen Group |
A4, A6, A8, Q5, Q7, e-tron, RS Series |
Strong Challenger |
Premium German brand with strong US performance and SUV positioning; expanding electric e-tron portfolio presence. |
|
Stellantis NV |
Alfa Romeo Giulia, GranTurismo |
Niche Player |
Multi-brand luxury strategy through Alfa Romeo and Maserati catering to performance and Italian heritage segments. |
Key players include Mercedes-Benz Group AG, BMW AG, Tesla, General Motors, Volkswagen Group, Stellantis NV, and others.
Key Company Profiles
Mercedes-Benz Group AG
Mercedes-Benz Group AG is a global automotive leader headquartered in Stuttgart, Germany, widely recognized as one of the world's most prestigious luxury vehicle brands. The company's U.S. operations represent one of its largest and most strategically important markets across all vehicle segments.
- Key Models: S-Class, E-Class, C-Class, GLE, GLS, EQS, AMG performance variants, and ultra-luxury Maybach models across sedan, SUV, and electric vehicle segments.
- Strategic Focus: Mercedes-Benz focuses on maintaining its top-tier luxury positioning through continuous technology leadership, expanding its EV portfolio, and sustaining the S-Class as the definitive global luxury sedan benchmark. The company continues to invest in autonomous driving development and premium digital services.
BMW AG
BMW AG is a globally renowned luxury automotive and motorcycle manufacturer headquartered in Munich, Germany. Its U.S. operations consistently rank among the largest luxury automotive markets by volume, with strong demand across performance, SUV, and increasingly electric vehicle segments.
- Key Models: 3 Series, 5 Series, 7 Series luxury sedans; X3, X5, X7 luxury SUVs; i4, i5, iX electric vehicles; and M Series high-performance models commanding premium consumer loyalty.
- Recent Developments: In June 2026, BMW completed a USD 1.7 billion investment in its South Carolina operations, including the expansion of Plant Spartanburg and construction of Plant Woodruff. The investment strengthens the company's U.S. manufacturing capabilities and prepares the facilities for next-generation BMW X models, including fully electric vehicles.
- Strategic Focus: BMW focuses on delivering its "Ultimate Driving Machine" brand promise across increasingly electrified model lines while sustaining performance excellence that differentiates BMW from comfort-oriented competitors. The company is investing heavily in software-defined vehicle architecture and autonomous driving capabilities.
Tesla
Tesla is an American electric vehicle and clean energy company headquartered in Austin, Texas, that has fundamentally disrupted the luxury automotive market through its technology-first approach to premium vehicles, direct-to-consumer sales model, and continuous over-the-air software development.
- Key Models: Model S luxury sedan, Model X luxury SUV, Model 3 premium sedan, Model Y premium compact SUV, and Cybertruck; all sold through Tesla's direct-to-consumer online and retail platform.
- Recent Developments: In July 2024, Tesla launched the new Model 3 Long Range Rear-Wheel-Drive in the United States, priced at $34,990 after the federal EV tax credit, offering over 360 miles of range. In 2024, Tesla also unveiled the futuristic robotaxi autonomous vehicle concept, expected to launch by 2026.
- Strategic Focus: Tesla focuses on maintaining its technology leadership in electric luxury vehicles while expanding affordability through lower-priced variants and improving charging infrastructure. The company is investing in full self-driving capability commercialization and the robotaxi autonomous mobility service as its primary long-term growth platform.
Market Concentration Analysis
The U.S. luxury car market is moderately concentrated, with the key players collectively commanding a significant share of the domestic luxury vehicle market by value. This structure reflects decades of brand equity investment and the high cost of entry into the premium automotive segment.
Market concentration is evolving as various companies disrupt traditional luxury market dynamics through technology innovation and direct sales, while established brands invest aggressively in EV portfolios to defend market share. The competitive equilibrium is shifting toward technology capability as a primary differentiator alongside traditional luxury brand heritage and craftsmanship standards.
Investment & Growth Opportunities
Highest Growth Segments
Electric luxury SUV (~3.2% CAGR), autonomous driving features (~4.0% CAGR), ultra-luxury and bespoke segments (~2.5% CAGR), digital subscription services (~8-10% CAGR from small base), and premium EV charging ecosystem services represent the U.S. luxury car market's highest-growth investment vectors through 2034.
Emerging Investment Opportunities
The luxury electric vehicle ecosystem, including premium home charging equipment, concierge charging services, and OTA software subscription packages, represents a commercially significant adjacent investment opportunity. As EV penetration in the luxury segment approaches 40% by 2030, premium charging infrastructure and digital services will generate recurring revenue streams that complement traditional vehicle sales margins.
Investment Themes
- Electric luxury SUV platform investment targeting the convergence of the market's dominant vehicle type with its fastest-growing fuel type: luxury electric SUVs represent the single highest-value product investment in the U.S. premium automotive market through 2034.
- Software-defined vehicle and subscription service infrastructure investment for recurring revenue beyond the initial vehicle sale: autonomous feature subscriptions, premium connectivity packages, and over-the-air performance upgrades create high-margin digital revenue streams with strong consumer lifetime value metrics.
Future Market Outlook (2026-2034)
The U.S. luxury car market is projected to grow from USD 112.3 Billion in 2025 to USD 113.6 Billion in 2026, reaching USD 125.3 Billion by 2034 at a CAGR of 1.16%. The market's USD 119.0 Billion anchor value by 2030 reflects the industry at a structural inflection point where electric luxury vehicles begin representing a majority of new model launches across all segments.
Three structural forces define U.S. luxury car market growth through 2034: the accelerating EV transition creating new product excitement and technology-driven purchasing motivation; sustained affluent consumer spending insulated from broader economic cyclicality by upper-income household wealth concentration; and the growing importance of software and connectivity as luxury differentiators that enable ongoing revenue generation beyond the initial vehicle transaction.
Research Methodology
Primary Research
Primary research comprised structured interviews with U.S. luxury automotive industry stakeholders, including dealership general managers, luxury vehicle brand strategists, EV adoption specialists, affluent consumer researchers, and automotive retail analysts across all four major U.S. regions.
Secondary Research
Secondary research encompassed automotive industry association data from NADA and WardsAuto, company annual reports, EPA and NHTSA regulatory filings, consumer spending surveys, luxury automotive trade publications, and investor presentations. Over 60 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a consumer wealth stratification model: U.S. households by income tier multiplied by luxury vehicle purchase propensity rates and average transaction values per segment. EV adoption S-curve multipliers were applied across electric vehicle segment projections through 2034.
U.S. Luxury Car Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Vehicle Types Covered | Hatchback, Sedan, Sports Utility Vehicle |
| Fuel Types Covered | Gasoline, Diesel, Electric |
| Price Ranges Covered | Entry-Level, Mid-Level, High-End, Ultra |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Mercedes-Benz Group AG, BMW AG, Tesla, General Motors, Volkswagen Group, Stellantis NV, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the U.S. luxury car market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the U.S. luxury car market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the U.S. luxury car industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the U.S. Luxury Car Market Report
The U.S. luxury car market was valued at USD 113.6 Billion in 2026, driven by rising disposable incomes among affluent consumers, significant technological advancements, growing electric luxury vehicle demand, and strong consumer preference for premium, feature-rich vehicles combining performance with advanced connectivity.
The united states luxury car market is projected to exhibit a CAGR of 1.16% during 2026-2034, reaching USD 125.3 Billion by 2034. Growth is sustained by electric vehicle adoption, SUV dominance, technology innovation, expanding high-net-worth consumer base, and growing demand for personalized luxury automotive experiences.
Sports Utility Vehicles lead at 62.5% through their dominant appeal across families and affluent consumers who prioritize spaciousness, versatility, and advanced technology in a premium format. The luxury SUV segment benefits from strong consumer preference shifts away from traditional sedans across all income brackets in the premium vehicle market.
Gasoline leads at 72.5% through its established performance credentials, extensive refueling infrastructure, and superior driving range that remain preferred by the majority of luxury vehicle consumers. Electric vehicles at 24.5% are the fastest-growing fuel type, driven by Tesla's market leadership and expanding premium EV portfolios from established luxury brands.
The South leads at 34.5% through its large and growing high-net-worth consumer concentration in Texas, Florida, and Georgia, supported by favorable tax environments, car-dependent suburban geography, and strong demand for luxury SUVs across diverse consumer demographics in the nation's most economically dynamic regional market.
Leading companies include Mercedes-Benz Group AG, BMW AG, Tesla, General Motors, Volkswagen Group, Stellantis NV, and others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: sales@imarcgroup.com
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade