
United States Predictive Analytics Market Size, Share, Trends and Forecast by Business Function, Component, Deployment, Organization Size, End Use Industry, and Region, 2026-2034
United States Predictive Analytics Market Size, Share, Trends & Forecast (2026-2034)
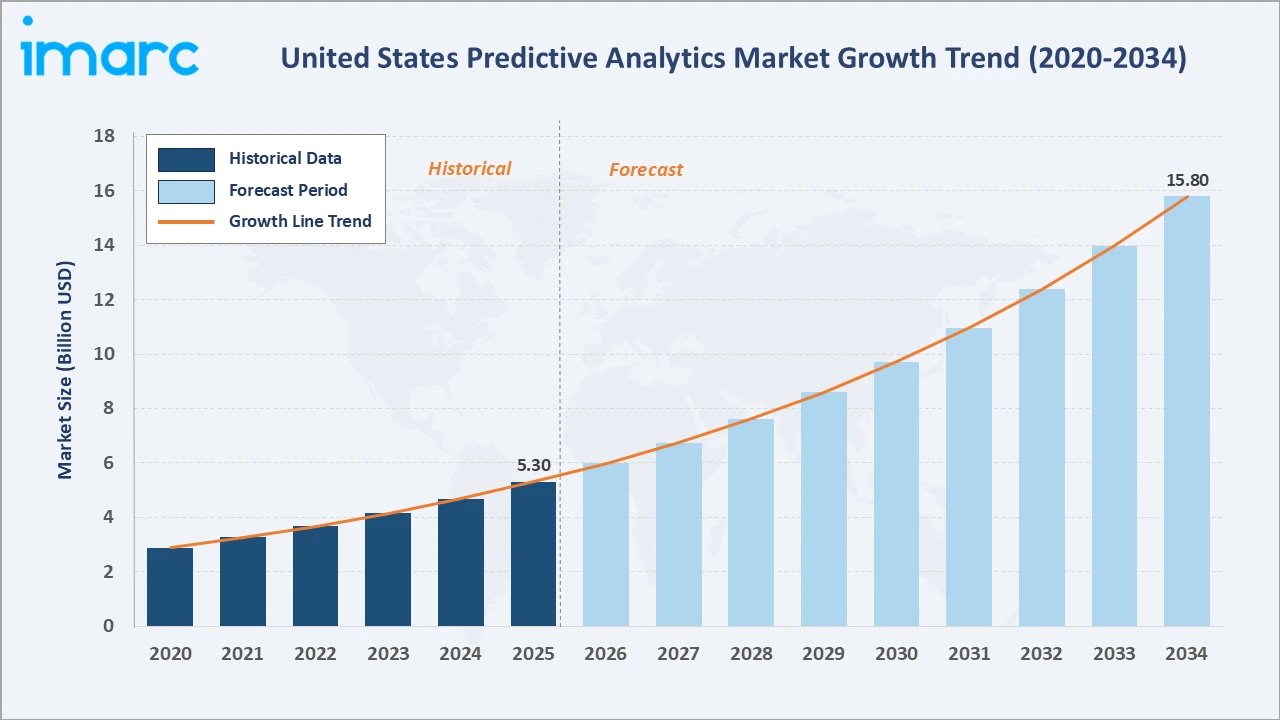
The United States predictive analytics market grew from USD 5.30 Billion in 2025 to USD 5.98 Billion in 2026 and is projected to reach USD 15.80 Billion by 2034, exhibiting a CAGR of 12.91% during 2026-2034. Surging adoption of cloud-based analytics platforms, rising demand for data-driven decision making across enterprises, and deepening integration of AI and ML into business operations are the primary forces shaping market growth.
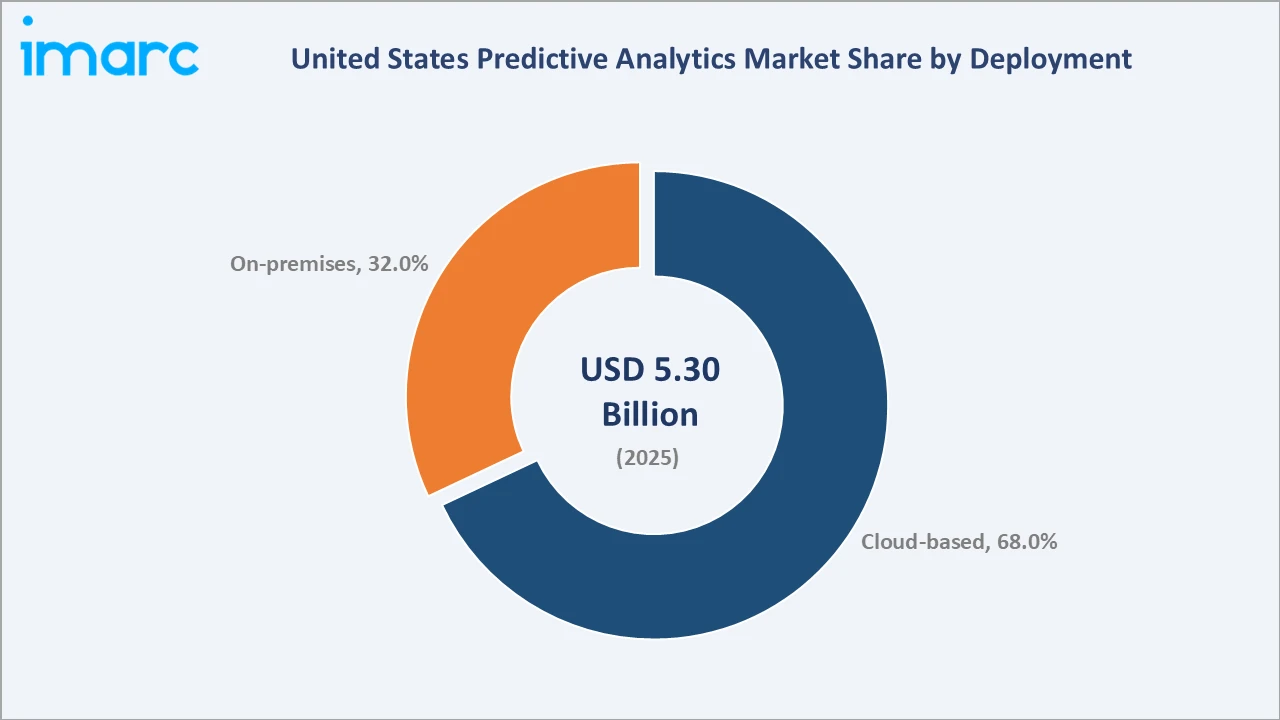
Cloud-based leads the deployment segment at 68.0%, large enterprises dominate the organization size segment at 62.0%, and South commands 35.0% of regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 5.30 Billion |
| Market Size (2026) | USD 5.98 Billion |
| Forecast Market Size (2034) | USD 15.80 Billion |
| CAGR (2026-2034) | 12.91% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | South (35.0%, 2025) |
| Second Largest Region | West (26.0%, 2025) |
| Leading Deployment | Cloud-based (68.0%, 2025) |
| Leading Organization Size | Large Enterprises (62.0%, 2025) |
The United States predictive analytics market size increased from USD 2.89 Billion in 2020 to USD 5.30 Billion in 2025 and is estimated to reach USD 5.98 Billion in 2026. The market is further expected to grow to USD 9.72 Billion by 2030 and USD 15.80 Billion by 2034. The market is commercially significant within the broader United States technology sector, underpinned by one of the world's largest enterprise software ecosystems, an expanding cloud infrastructure base, and a rapidly growing volume of enterprise data requiring advanced analytical processing.
To get more information on this market, Request Sample
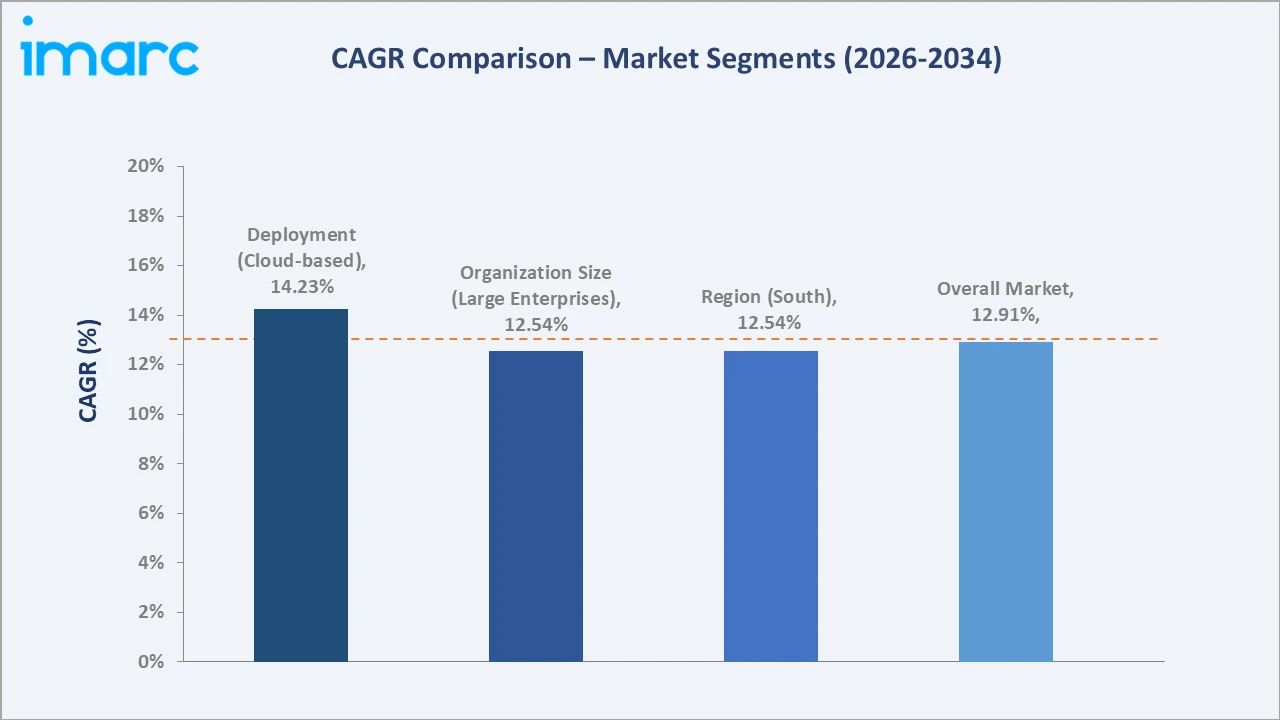
CAGR trajectories across deployment, organization size, and regional sub-segments show cloud-based and West expanding faster than the overall 12.91% market CAGR, reflecting ongoing digital transformation and increasing adoption of advanced analytics solutions.
Executive Summary
The United States predictive analytics market expanded from USD 5.30 Billion in 2025 to an estimated USD 5.98 Billion in 2026, positioning it among the most rapidly growing analytics segments in the United States technology industry. The market's scale is underpinned by accelerating enterprise adoption of cloud-native analytics, the increasing volume of structured and unstructured data generated across industries, and rising investment in AI-integrated forecasting and decision-support platforms.
Cloud-based commands 68.0% of the deployment segment, reflecting its scalability advantages, lower upfront capital requirements, and compatibility with modern enterprise data architectures. Large enterprises lead the organization size segment at 62.0%, anchored by their larger analytics budgets, complex operational data environments, and strategic investment in predictive modeling for supply chain, finance, and customer analytics. Among regions, South holds the largest share at 35.0%, supported by a concentration of large enterprises, expanding technology hubs in Texas and Florida, and growing demand for analytics-driven operational efficiency.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Deployment | Cloud-based – 68.0% share (2025) |
| Second Largest Deployment | On-premises – 32.0% share (2025) |
| Leading Organization Size | Large Enterprises – 62.0% share (2025) |
| Second Largest Organization Size | Small and Medium-sized Enterprises – 38.0% share (2025) |
| Leading Region | South – 35.0% share (2025) |
| Second Largest Region | West – 26.0% share (2025) |
| Top Companies | IBM, Microsoft Corporation, SAS Institute Inc., Oracle Corporation, Salesforce, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Cloud-based dominance at 68.0% reflects its lower capital requirement, rapid deployment timelines, and seamless integration with modern enterprise data lakes and cloud-native workflows.
- On-premises share at 32.0% is sustained by regulated industries including banking, insurance, and healthcare, where data sovereignty requirements and latency sensitivity favor in-house infrastructure.
- Large enterprises leadership at 62.0% is driven by their larger analytics budgets, complex multi-system data environments, and strategic investment in enterprise-wide predictive modeling platforms.
- Small and medium-sized enterprises at 38.0% are expanding their adoption as cloud-based solutions reduce implementation costs and as software-as-a-service delivery models lower the technical barrier to entry.
- South leads regional share at 35.0% due to its high concentration of large enterprises, growing technology ecosystems in Texas and Florida, and increasing cross-sector demand for analytics-enabled operational efficiency.
United States Predictive Analytics Market Overview
Predictive analytics refers to the use of statistical algorithms, ML models, and data mining techniques to identify the likelihood of future outcomes based on historical data. Applications span demand forecasting, risk management, fraud detection, customer churn prediction, supply chain optimization, and clinical decision support. As enterprise datasets grow in volume and complexity, predictive analytics platforms have become a core component of digital transformation strategies across the United States.
The United States ecosystem integrates raw data providers, cloud infrastructure operators, platform developers, system integrators, and enterprise end users. Supporting layers include regulatory bodies, academic research institutions, and professional services firms specializing in analytics implementation. Together, they enable a commercially mature, scalable, and increasingly AI-driven analytics ecosystem operating across all major sectors of the United States economy.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
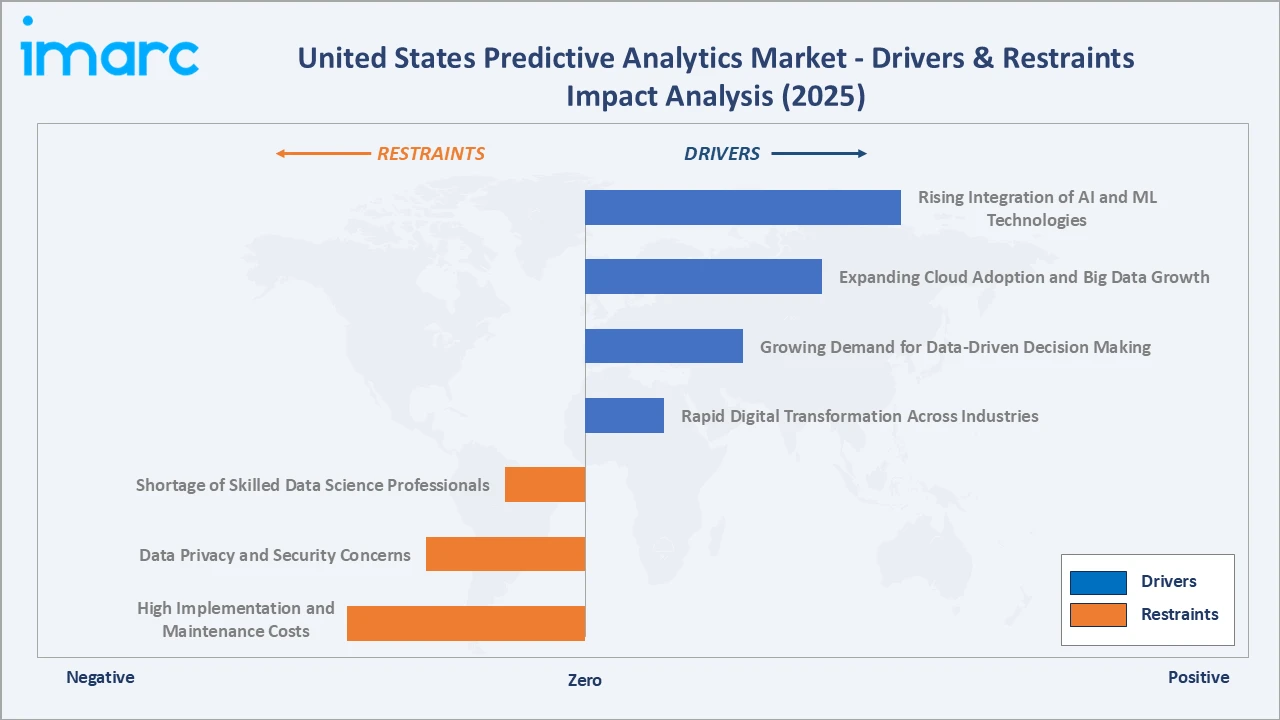
- Rapid Digital Transformation Across Industries: Accelerating adoption of digital technologies across manufacturing, retail, healthcare, and financial services is generating large volumes of enterprise data, increasing the demand for predictive analytics platforms that convert raw data into actionable business intelligence.
- Growing Demand for Data-Driven Decision Making: Competitive pressure across industries is driving enterprises to replace intuition-based decision making with model-driven forecasting and planning. Predictive insights also help organizations identify emerging trends, optimize resource allocation, and improve operational efficiency.
- Expanding Cloud Adoption and Big Data Growth: The widespread migration to cloud infrastructure is enabling scalable deployment of predictive analytics platforms without on-site capital expenditure. Growing data volumes from connected devices, transactional systems, and digital channels are expanding the addressable analytics processing opportunity.
- Rising Integration of AI and ML Technologies: As per IMARC Group, the United States AI market size increased from USD 41.53 Billion in 2025 to USD 46.39 Billion in 2026. Platform developers are embedding ML models, natural language processing, and automated feature engineering into predictive analytics suites. These capabilities are reducing the technical complexity of building and maintaining predictive models, expanding adoption among non-specialist business users.
Market Restraints
- High Implementation and Maintenance Costs: Deploying enterprise-grade predictive analytics platforms requires significant investment in software licensing, data integration, infrastructure, and ongoing model maintenance. These costs can be prohibitive for smaller organizations without dedicated analytics teams.
- Data Privacy and Security Concerns: Handling sensitive customer and operational data within analytics platforms raises compliance risks under stringent data protection and privacy regulations. Compliance complexity can slow deployment timelines, increase operational overhead, and create challenges in maintaining data security across analytics systems.
- Shortage of Skilled Data Science Professionals: Demand for qualified data scientists, ML engineers, and analytics architects significantly outpaces supply across the United States, increasing talent acquisition costs and extending implementation timelines for organizations building in-house predictive analytics capabilities.
Market Opportunities
- Expansion of Predictive Analytics in Healthcare and Life Sciences: Growing adoption of electronic health records, medical imaging data, and genomics information is creating substantial opportunity for predictive analytics platforms targeting patient outcome prediction, clinical trial optimization, and population health management.
- Growth of Embedded Analytics in Industry-Specific Platforms: Demand for pre-built predictive analytics functionality integrated within industry-vertical software is expanding. Vendors embedding analytics into ERP, CRM, and supply chain management platforms are reaching business users who would not purchase standalone analytics tools.
Market Challenges
- Data Quality and Integration Complexity: Predictive models are highly sensitive to the quality and consistency of input data. Enterprises with fragmented data environments across legacy systems, cloud platforms, and third-party sources face significant data preparation challenges that extend project timelines and reduce model reliability.
- Model Governance and Explainability Requirements: Regulated industries including banking and insurance face increasing scrutiny over algorithmic decision making. Ensuring model transparency, bias detection, and audit capability for regulatory compliance adds technical and operational complexity to predictive analytics deployments.
Emerging Market Trends
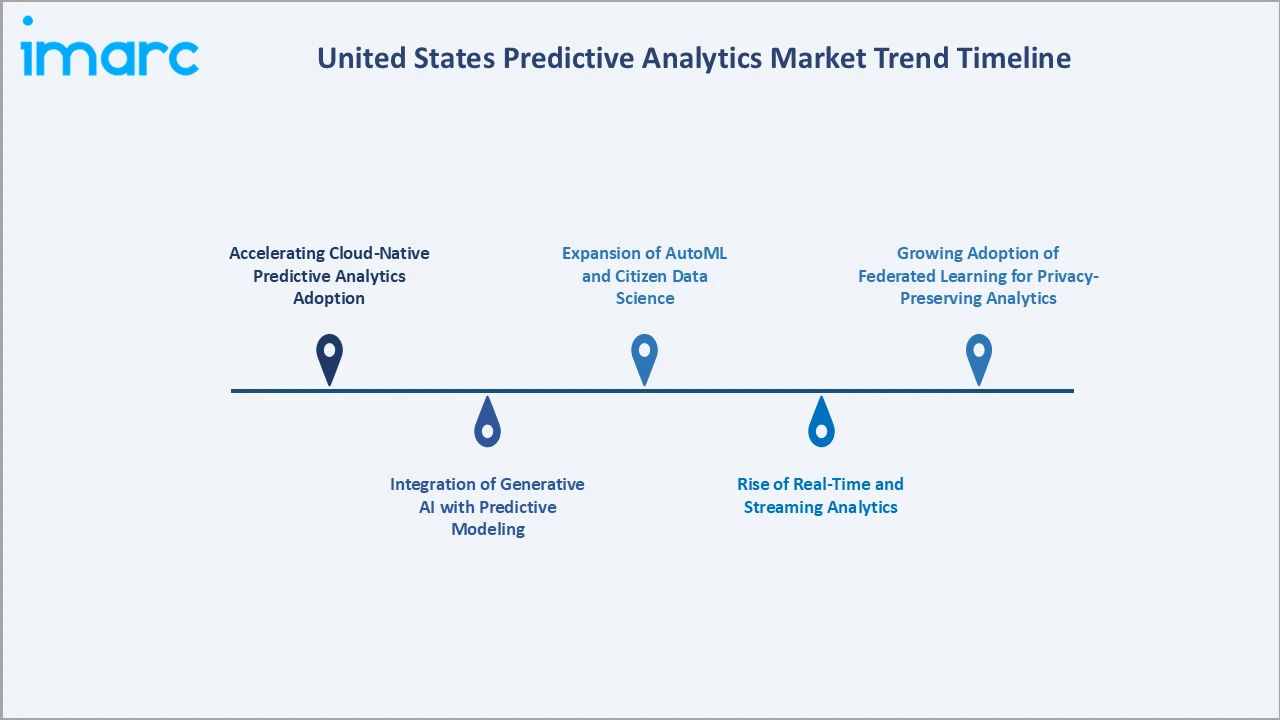
1. Accelerating Cloud-Native Predictive Analytics Adoption
Enterprise adoption of cloud-native predictive analytics platforms has surged as cloud infrastructure providers have expanded their ML services and analytics tooling. The scalability and pay-as-you-go economics of cloud deployment are removing capital barriers and enabling mid-market enterprises to access analytics capabilities previously available only to large technology-intensive organizations.
2. Integration of Generative AI with Predictive Modeling
Platform vendors are integrating large language models and generative AI capabilities into predictive analytics suites, enabling natural language query interfaces, automated insight narration, and AI-assisted model building. This trend is significantly broadening the accessibility of predictive analytics to business users without technical data science backgrounds.
3. Rise of Real-Time and Streaming Analytics
Demand for real-time predictive analytics is growing as enterprises seek to respond to customer behavior, supply chain signals, and operational events as they occur. Streaming data infrastructure and low-latency ML inference are enabling predictive models to generate and act on predictions within milliseconds, shifting analytics from periodic reporting to continuous operational intelligence.
4. Expansion of AutoML and Citizen Data Science
AutoML platforms are enabling business analysts and domain experts to build, validate, and deploy predictive models without deep programming expertise. This democratization of model development is expanding the internal analytics capacity of enterprises while reducing dependence on specialist data science teams for routine modeling tasks.
5. Growing Adoption of Federated Learning for Privacy-Preserving Analytics
Federated learning frameworks are enabling organizations in regulated industries to train predictive models across distributed data environments without centralizing sensitive data. Financial services, healthcare, and insurance firms are exploring federated approaches to collaborate on model training while maintaining data privacy compliance under applicable regulatory frameworks.
Industry Value Chain Analysis
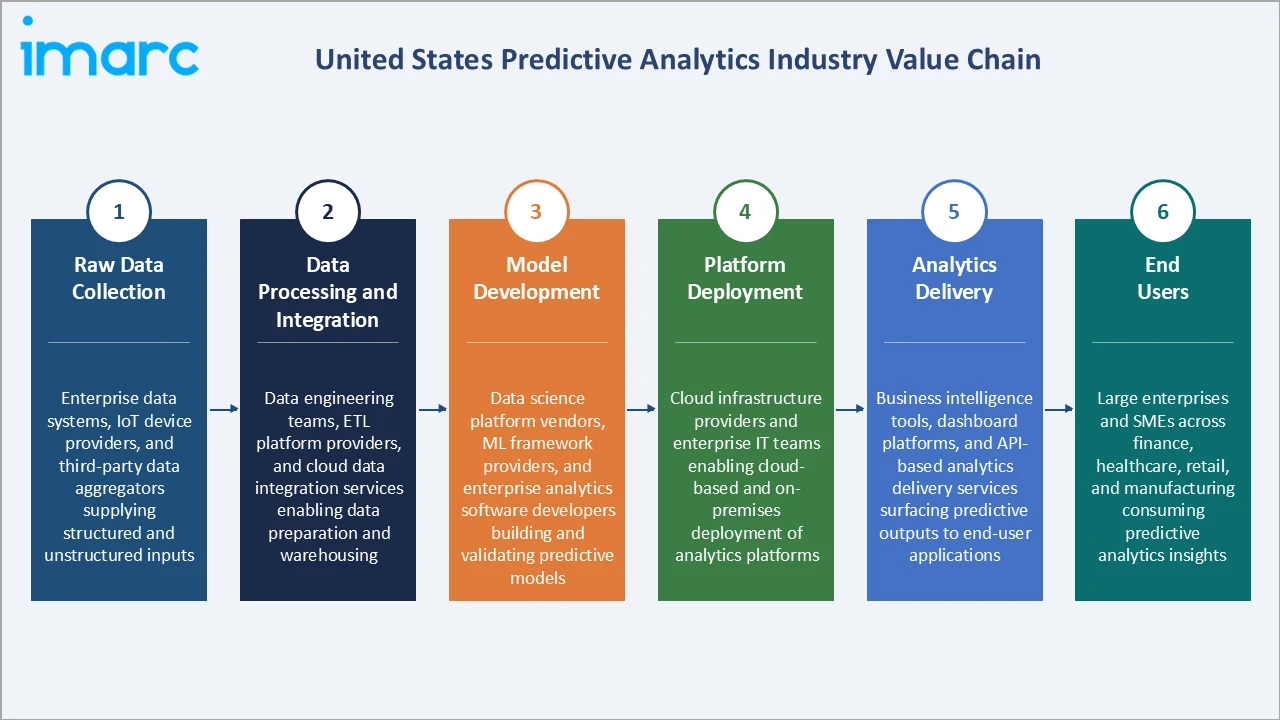
The United States predictive analytics market value chain spans six stages, from data collection and infrastructure provisioning through platform development, deployment, analytics delivery, and end-user adoption. Platform development and analytics delivery stages capture the highest value-add, while cloud infrastructure and integration services form the operational backbone enabling scalable market growth.
| Stage | Key Players / Examples |
|---|---|
| Raw Data Collection | Enterprise data systems, IoT device providers, public data repositories, and third-party data aggregators supplying structured and unstructured inputs for model training |
| Data Processing and Integration | Data engineering teams, ETL platform providers, and cloud data integration services enabling data preparation and warehousing |
| Model Development | Data science platform vendors, ML framework providers, and enterprise analytics software developers building and validating predictive models |
| Platform Deployment | Cloud infrastructure providers and enterprise IT teams enabling cloud-based and on-premises deployment of analytics platforms at scale |
| Analytics Delivery | Business intelligence tools, dashboard platforms, and API-based analytics delivery services surfacing predictive outputs to end-user applications |
| End Users | Large enterprises and small and medium-sized enterprises across finance, healthcare, retail, and manufacturing consuming predictive analytics for operational and strategic decision making |
Vertically integrated platform vendors controlling data ingestion, model development, and analytics delivery are positioned to capture greater value across the chain than point-solution providers dependent on third-party infrastructure or integration partners.
Technology Landscape in the United States Predictive Analytics Industry
ML and AI Engines
Core ML frameworks including supervised learning, ensemble methods, and deep neural networks form the algorithmic foundation of modern predictive analytics platforms. Leading vendors are embedding automated model selection, hyperparameter tuning, and feature engineering into their platforms to accelerate model development cycles.
Cloud Infrastructure and Scalable Computing
Cloud platforms from major hyperscalers provide the elastic compute, managed data services, and pre-built ML infrastructure enabling enterprises to deploy large-scale predictive models without on-premise capital investment. GPU-accelerated computing and distributed processing frameworks are enabling faster model training on increasingly large datasets.
Real-Time Data Streaming and Integration
Streaming data platforms and real-time integration tools are enabling organizations to feed continuously updated data into predictive models, shifting analytics from batch-oriented to continuous inference modes. Low-latency prediction serving infrastructure is enabling operational analytics applications in fraud detection, dynamic pricing, and personalization.
Explainability and Model Governance Platforms
Growing regulatory and business requirements for algorithmic transparency are driving adoption of model explainability tools, bias detection frameworks, and model monitoring systems. These technologies are becoming integral components of enterprise predictive analytics stacks, particularly in regulated sectors including financial services and healthcare.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Business Function | 🔒 | 🔒 | 2025 |
| Component | 🔒 | 🔒 | 2025 |
| Deployment | Cloud-based | 68.0% | 2025 |
| Organization Size | Large Enterprises | 62.0% | 2025 |
| End-Use Industry | 🔒 | 🔒 | 2025 |
| Region | South | 35.0% | 2025 |

By Deployment
Cloud-based commands a 68.0% majority share in 2025, driven by its scalability, lower total cost of ownership, and compatibility with the enterprise technology architectures of large and mid-market organizations alike. The segment benefits from continued investment by hyperscalers in managed ML services and pre-built analytics tooling, reducing the technical complexity of platform deployment and ongoing management.
To access detailed market analysis, Request Sample
On-premises at 32.0% remain the preferred deployment mode for regulated industries including banking, insurance, and healthcare, where data sovereignty requirements, low-latency inference needs, and established IT governance frameworks favor in-house infrastructure. Enterprises with significant legacy data environments and existing hardware investments are maintaining on-premises deployments while selectively extending to hybrid architectures.
By Organization Size
Large enterprises represent 62.0% of the organization size segment in 2025, directly reflecting their larger analytics budgets, complex multi-system data environments, and strategic commitment to enterprise-wide predictive modeling programs. Their scale enables investment in custom model development, dedicated data science teams, and enterprise platform licensing agreements that drive deeper and broader analytics integration across business functions.
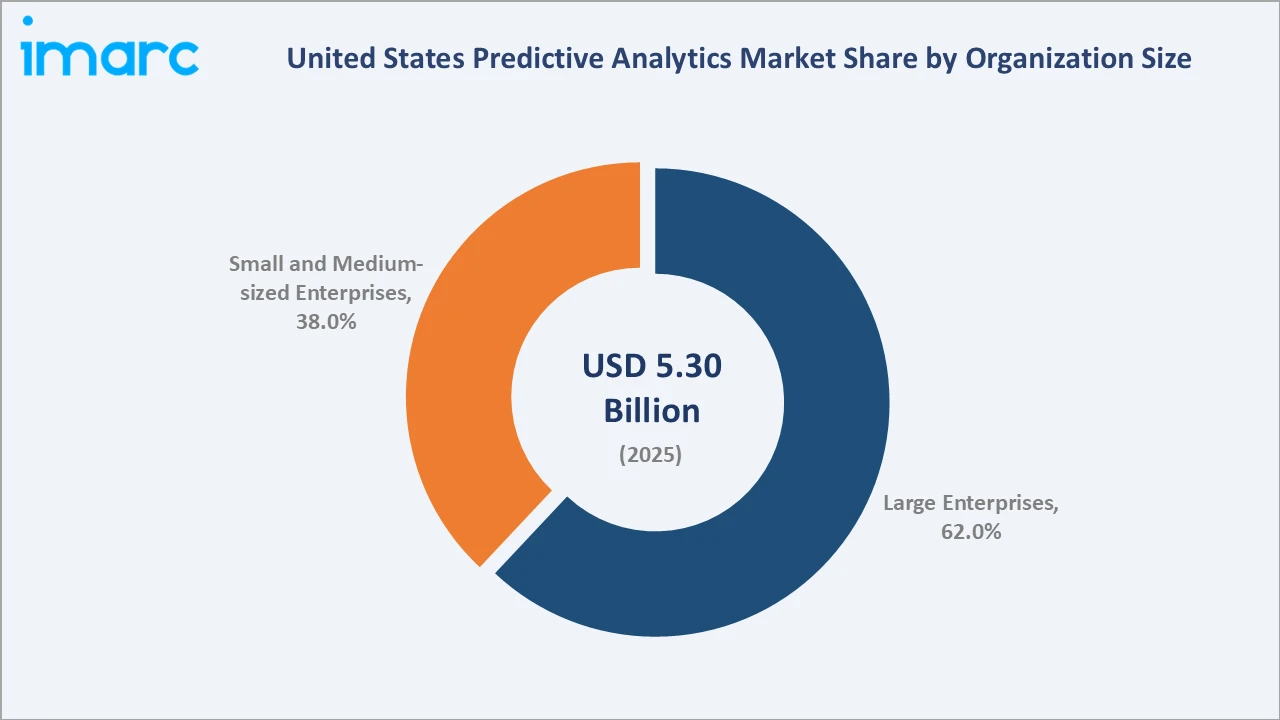
Small and medium-sized enterprises at 38.0% are a growing and strategically important segment, supported by increasing availability of affordable cloud-based analytics platforms and software-as-a-service delivery models. These organizations are adopting predictive analytics for sales forecasting, customer retention, and inventory optimization as platform costs decline and implementation complexity reduces.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| South | 35.0% | High concentration of large enterprises in Texas, Georgia, and Florida; expanding technology and financial services sectors; growing cross-industry demand for analytics-enabled operational efficiency |
| West | 26.0% | Silicon Valley technology ecosystem; high venture capital investment in AI and analytics startups; strong enterprise cloud adoption across California and Washington |
| Midwest | 21.0% | Growing manufacturing and logistics analytics adoption; expanding financial services sector in Illinois; increasing government and public sector investment in data infrastructure |
| Northeast | 18.0% | Established financial services and healthcare analytics markets in New York and Massachusetts; concentration of academic research institutions supporting analytics innovation |
South at 35.0% in 2025 leads the regional landscape, anchored by its large enterprise concentration and expanding multi-sector analytics demand. Growing investments in digital infrastructure and cloud technologies further support the adoption of predictive analytics solutions across the region.
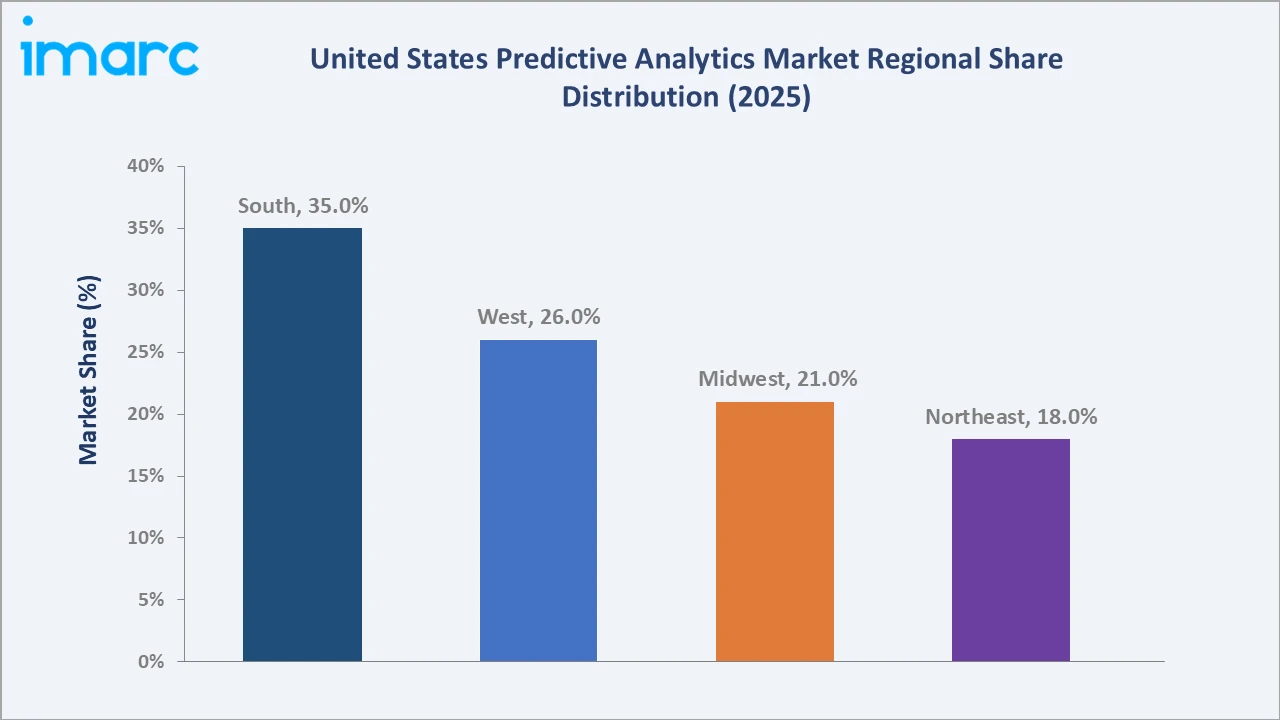
West at 26.0% follows, supported by its dominant technology ecosystem and strong capital flows into AI-driven analytics platforms.
Competitive Landscape
The United States predictive analytics market is moderately concentrated at the top, with a small number of global technology leaders commanding significant platform adoption and enterprise contract share, alongside a larger fragmented tier of specialized analytics vendors and emerging AI-native platforms. Scale, breadth of analytics functionality, cloud infrastructure integration, and established enterprise relationships form the key competitive differentiators.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| IBM | IBM watsonx.ai | Leader | Expanding AI-powered analytics portfolio through cloud and enterprise platform investment |
| Microsoft Corporation | Microsoft Foundry | Leader | Growing predictive analytics capabilities within integrated cloud and productivity ecosystem |
| SAS Institute Inc. | SAS Viya | Leader | Strengthening enterprise analytics platform through cloud modernization and AI model integration |
| Oracle Corporation | Oracle Analytics Cloud | Challenger | Expanding cloud analytics offerings through platform integration and enterprise database ecosystem leverage |
| Salesforce, Inc. | Salesforce CRM Analytics | Challenger | Building AI-driven analytics capabilities within enterprise CRM and cloud application ecosystem |
Key players include IBM, Microsoft Corporation, SAS Institute Inc., Oracle Corporation, and Salesforce, Inc., among others.
Key Company Profiles
IBM
IBM is a United States-based multinational technology company headquartered in Armonk, New York, with a long-established presence in enterprise analytics, AI, and cloud services.
- Product Portfolio: Enterprise AI and analytics platforms including IBM watsonx.ai and IBM SPSS Statistics, delivering predictive modeling, statistical analysis, and data science workflow capabilities.
- Recent Developments: IBM continues to advance its AI and analytics portfolio through investment in generative AI capabilities integrated within its watsonx.ai platform, targeting enterprise analytics and decision support applications.
- Strategic Focus: Expanding AI-powered analytics capabilities within the enterprise hybrid cloud environment, targeting regulated industries including financial services, healthcare, and manufacturing.
Microsoft Corporation
Microsoft Corporation is a United States-based multinational technology company headquartered in Redmond, Washington, operating a broad enterprise technology portfolio spanning cloud infrastructure, productivity applications, and advanced analytics platforms.
- Product Portfolio: Predictive analytics capabilities delivered through Azure ML, Power BI with AI integration, Microsoft Fabric, and Azure Synapse Analytics, supporting model development, deployment, and business intelligence visualization.
- Recent Developments: Microsoft Corporation continues to integrate OpenAI-powered capabilities across its analytics portfolio, including Copilot features in Power BI and Azure ML, expanding AI-assisted model building and natural language analytics interaction.
- Strategic Focus: Growing predictive analytics adoption within the Microsoft 365 and Azure ecosystem, targeting enterprise customers seeking integrated analytics and productivity platform solutions.
SAS Institute Inc.
SAS Institute Inc. is a United States-based privately held analytics software company headquartered in Cary, North Carolina. It is a leading provider of enterprise analytics, statistical modeling, and data management solutions.
- Product Portfolio: SAS Viya, an AI-driven cloud-native analytics platform, alongside industry-specific analytics solutions for banking, healthcare, and retail.
- Recent Developments: SAS Institute Inc. continues to advance its cloud-native analytics platform, expanding AI and ML capabilities within SAS Viya and deepening integration with major cloud infrastructure providers.
- Strategic Focus: Strengthening enterprise analytics platform through cloud modernization, AI model integration, and industry-vertical solution development targeting regulated and analytics-intensive sectors.
Market Concentration Analysis
The United States predictive analytics market exhibits moderate-to-high concentration at the top tier, with leading platform vendors including IBM, Microsoft Corporation, and SAS Institute Inc. collectively holding substantial share of enterprise analytics contracts. The broader market is fragmented, with a large population of specialized analytics vendors, AI-native startups, and industry-vertical solution providers competing alongside the global technology leaders.
Barriers to entry include the significant R&D investment required to build enterprise-grade ML platforms, the need for established cloud infrastructure partnerships, strong enterprise sales and integration capabilities, and the importance of reference customer relationships in regulated industries. These factors support the continued competitive advantage of established vendors while creating viable niches for specialized providers with differentiated AI, vertical, or deployment capabilities.
Consolidation activity is ongoing, with platform vendors pursuing acquisitions of AI-native analytics companies and industry-vertical solution providers to expand their capabilities and customer reach. Strategic partnerships between analytics platform vendors and cloud infrastructure providers are also becoming a key structure for scaling enterprise go-to-market in the United States market.
Investment & Growth Opportunities
Fastest-Growing Segments
Cloud-based is expanding fastest within the deployment segment, driven by continued migration of enterprise analytics workloads to cloud-native platforms and the scalability advantages of subscription-based analytics infrastructure. Within the organization size segment, small and medium-sized enterprises are growing faster than large enterprises, as lower-cost software-as-a-service analytics platforms reduce adoption barriers for organizations without dedicated data science infrastructure.
Emerging Markets
West is the fastest-growing regional market, supported by Silicon Valley's technology ecosystem, high venture capital concentration in AI and analytics, and strong enterprise cloud adoption across California and Washington state.
Venture & Investment Trends
Venture capital and private equity investment is concentrated in AI-native predictive analytics platforms, AutoML and no-code analytics tools, real-time inference infrastructure, and industry-vertical analytics solutions. Strategic corporate investment by cloud providers and enterprise software vendors in analytics AI capabilities reflects the central role of predictive analytics in next-generation enterprise platform competition.
Future Market Outlook (2026-2034)
The United States predictive analytics market is projected to grow from USD 5.30 Billion in 2025 to USD 5.98 Billion in 2026, reaching USD 15.80 Billion by 2034, registering a CAGR of 12.91% during 2026-2034.
Four forces will shape the market through 2034 continued enterprise cloud migration driving adoption of cloud-native analytics platforms; deepening integration of generative AI and large language models into predictive analytics workflows; expansion of real-time analytics infrastructure enabling operational decision intelligence; and growing regulatory requirements for model governance and algorithmic transparency across regulated industries.
By 2034, the United States predictive analytics market is expected to be characterized by a mix of AI-integrated enterprise platforms, embedded analytics within industry-specific software, and specialized AI-native vendors targeting high-value analytics use cases. Continued enterprise data growth and expanding AI capability will sustain strong demand through the forecast period.
Research Methodology
Primary Research
Primary research included structured discussions with enterprise analytics buyers, cloud platform architects, data science professionals, and software vendor executives, validating market sizing, segment adoption patterns, and competitive dynamics across the United States predictive analytics ecosystem.
Secondary Research
Secondary sources included technology industry publications, enterprise software vendor disclosures, cloud provider investor presentations, government technology procurement data, and market intelligence reports, providing the foundation for historical market sizing and segment analysis.
Forecasting Models
Market forecasts used top-down and bottom-up models combining enterprise technology spending projections, cloud analytics adoption rate assumptions, segment-level growth driver analysis, and competitive landscape assessment. Scenario analysis addressed cloud migration pace, AI platform investment trends, and macroeconomic conditions affecting enterprise software budgets.
United States Predictive Analytics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Business Functions Covered | Marketing, Sales, Finance, Human Resource, Operations, Others |
| Components Covered |
|
| Deployments Covered | Cloud-based, On-premises |
| Organization Sizes Covered | Small and Medium-sized Enterprises, Large Enterprises |
| End Use Industries Covered | Banking, Financial Services and Insurance, Telecommunication and IT, Retail and E-Commerce, Healthcare and Life Science, Manufacturing, Government and Defense, Energy and Utility, Transport and Logistics, Media and Entertainment, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | IBM, Microsoft Corporation, SAS Institute Inc., Oracle Corporation, Salesforce, Inc., etc. |
| Customization Scope | 10% Free Customization |
|
Post-Sale Analyst Support |
10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States predictive analytics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States predictive analytics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States predictive analytics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Predictive Analytics Market Report
The United States predictive analytics market size is estimated at USD 5.98 Billion in 2026, driven by enterprise cloud adoption, expanding AI and ML integration, and rising demand for data-driven decision making across the United States.
The market is projected to grow at a CAGR of 12.91% from 2026-2034, reaching USD 15.80 Billion by 2034, supported by continued cloud migration, AI platform investment, and expanding enterprise analytics adoption.
Cloud-based dominates the market at 68.0% deployment share in 2025, driven by its scalability, lower capital requirements, and compatibility with modern enterprise cloud architectures.
Large enterprises represent 62.0% of the organization size segment in 2025, driven by their larger analytics budgets, complex data environments, and strategic investment in enterprise-wide predictive modeling.
South commands 35.0% share in 2025, led by its high concentration of large enterprises and expanding technology ecosystems in Texas, Georgia, and Florida.
West is among the fastest-growing regions, supported by Silicon Valley's technology ecosystem, high AI and analytics venture investment, and strong enterprise cloud adoption across California and Washington.
Key players include IBM, Microsoft Corporation, SAS Institute Inc., Oracle Corporation, and Salesforce, Inc., among others.
Key drivers include rapid digital transformation, growing demand for data-driven decision making, expanding cloud adoption, and deepening integration of AI and ML into enterprise analytics platforms.
Key challenges include data quality and integration complexity, model governance and explainability requirements in regulated industries, and the ongoing shortage of skilled data science professionals.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade