
United States Tequila Market Size, Share, Trends and Forecast by Product type, Purity, Price Range, Distribution Channel, and Region, 2026-2034
United States Tequila Market Size, Share, Trends & Forecast (2026-2034)
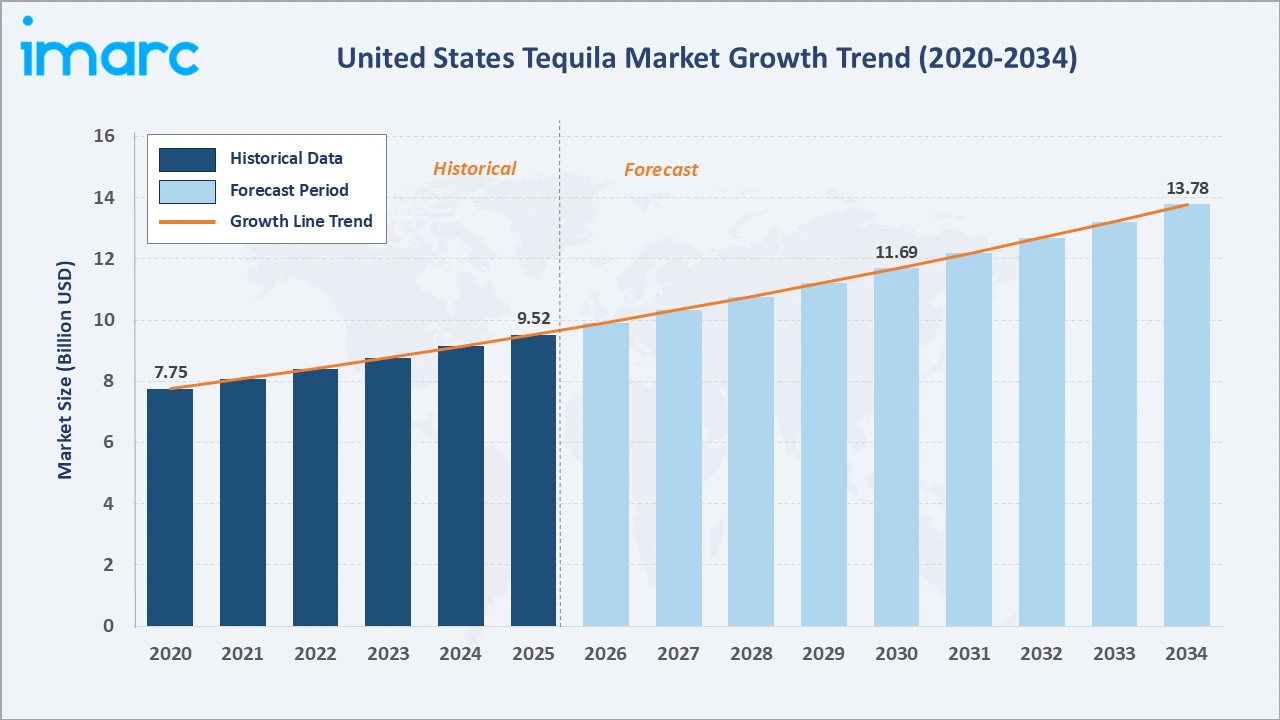
The United States tequila market size reached USD 9.52 Billion in 2025 and is estimated at USD 9.92 Billion in 2026. The market is projected to reach USD 13.78 Billion by 2034, growing at a CAGR of 4.19% during 2026-2034. Growth is driven by premiumization trends, rising cocktail culture, and the expanding popularity of artisanal and super-premium tequila expressions among American consumers.
The market is characterized by strong premiumization, celebrity-endorsed brand proliferation, and growing on-trade consumption. Blanco leads at 38.7% by product type. On-Trade dominates at 53.7% by distribution channel. The South region commands 31.6% of national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 9.52 Billion |
|
Market Size (2026) |
USD 9.92 Billion |
|
Forecast Market Size (2034) |
USD 13.78 Billion |
|
CAGR (2026-2034) |
4.19% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Blanco (38.7%, 2025) |
|
Dominant Distribution Channel |
On-Trade (53.7%, 2025) |
|
Leading Region |
South (31.6%, 2025) |
The United States tequila market size increased from USD 7.75 Billion in 2020 to USD 9.52 Billion in 2025 and is estimated to reach USD 9.92 Billion in 2026. The market is further projected to reach USD 11.69 Billion by 2030 and USD 13.78 Billion by 2034, supported by sustained premiumization momentum and expanding tequila consumer base across all US demographic segments.
To get more information on this market, Request Sample
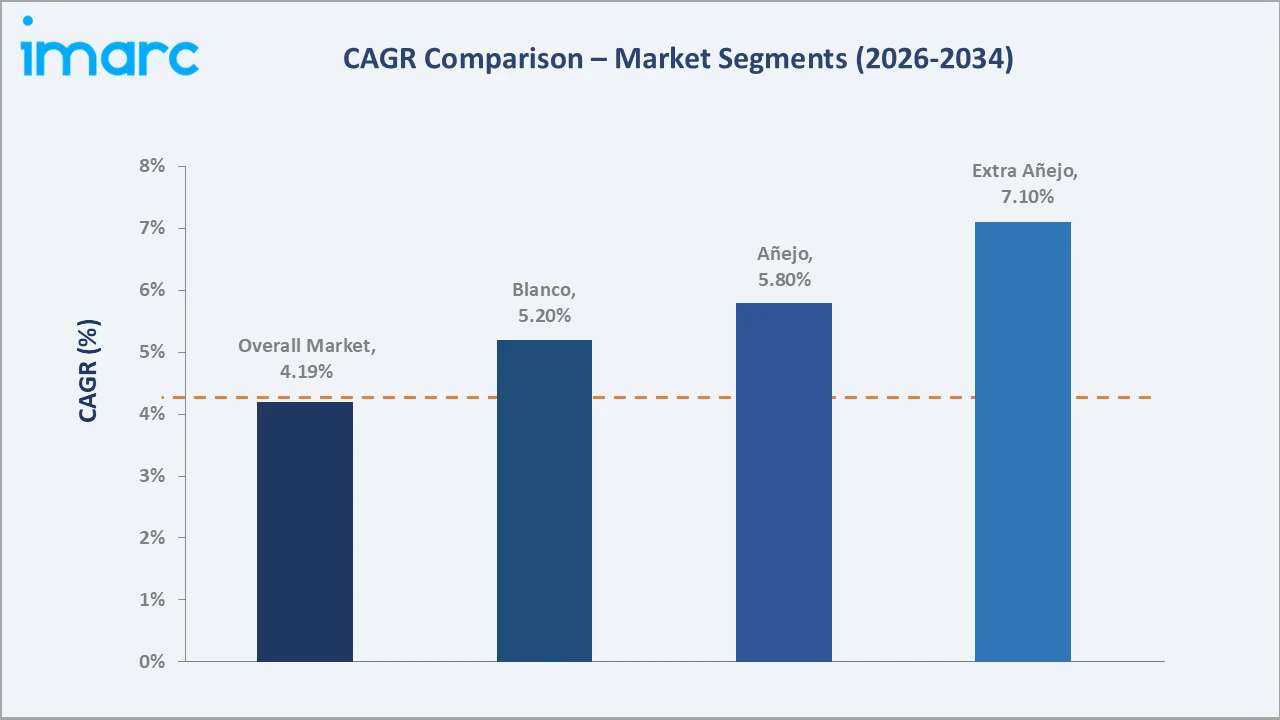
Extra Anejo is the fastest-growing product type at ~7.1% CAGR through the ultra-premium and luxury spirits shift among affluent American consumers. Anejo grows at ~5.8% CAGR through rising interest in aged and craft expressions as consumers trade up from standard blanco and mixto categories.
Executive Summary
The United States tequila market reached USD 9.52 Billion in 2025 and is estimated at USD 9.92 Billion in 2026, making it the world's largest single-country tequila market by value. Growth is anchored by the premiumization megatrend driving American consumers from standard and mixto expressions to 100% agave, aged, and super-premium tequila categories, supported by a vibrant cocktail culture, celebrity brand endorsements, and the growing American Hispanic consumer population.
Market structure reflects the broad appeal of tequila across all US consumer segments. Blanco leads at 38.7% by product type, driven by its versatility in cocktail applications and competitive price positioning. On-Trade at 53.7% reflects tequila's deep integration into America's bar and restaurant culture through margarita consumption and specialty tequila programs. The South region commands 31.6% of national market share, driven by Texas and Florida's large Hispanic consumer populations and vibrant hospitality sectors.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Blanco – 38.7% share (2025) |
|
Dominant Distribution Channel |
On-Trade – 53.7% market share (2025) |
|
Leading Region |
South – 31.6% share (2025) |
|
Market Opportunity |
Super-premium and ultra-premium segment expansion; agave spirits category diversification; e-commerce and DTC channel growth enabling direct brand-to-consumer relationships |
Key Analytical Observations Supporting the Above Data:
• Blanco at 38.7%: Dominates through its dual role as cocktail ingredient and sipping spirit, with broad appeal across bar programs, home consumption, and entry-level premium categories driving consistent volume.
• On-Trade at 53.7%: Leads through the deep integration of tequila into American bar and restaurant culture, margarita dominance in casual dining, and the expansion of premium tequila programs across upscale venues.
• South at 31.6%: Texas and Florida's large Hispanic consumer populations, vibrant tourism sectors, and established tequila drinking culture create the highest regional consumption density in the United States.
United States Tequila Market Overview
The United States tequila market is the world's largest import market for Mexican-produced tequila, accounting for approximately 80% of global tequila exports by volume. The market integrates premium Mexican distillation heritage, sophisticated US retail distribution infrastructure, and evolving consumer preferences toward artisanal and authentic spirits, creating a multi-tiered value chain from Jalisco agave farms to American consumer occasions.
Tequila's transformation from a party spirit to a premium sipping category has fundamentally altered consumption patterns and price dynamics. Average selling prices across the US tequila market have increased steadily as consumers trade up to 100% agave, reposado, anejo, and extra anejo expressions. Celebrity-backed brands from George Clooney (Casamigos/Diageo), Dwayne Johnson (Teremana), and others have accelerated premium category awareness, while e-commerce and DTC channels expand market accessibility beyond traditional retail footprints.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
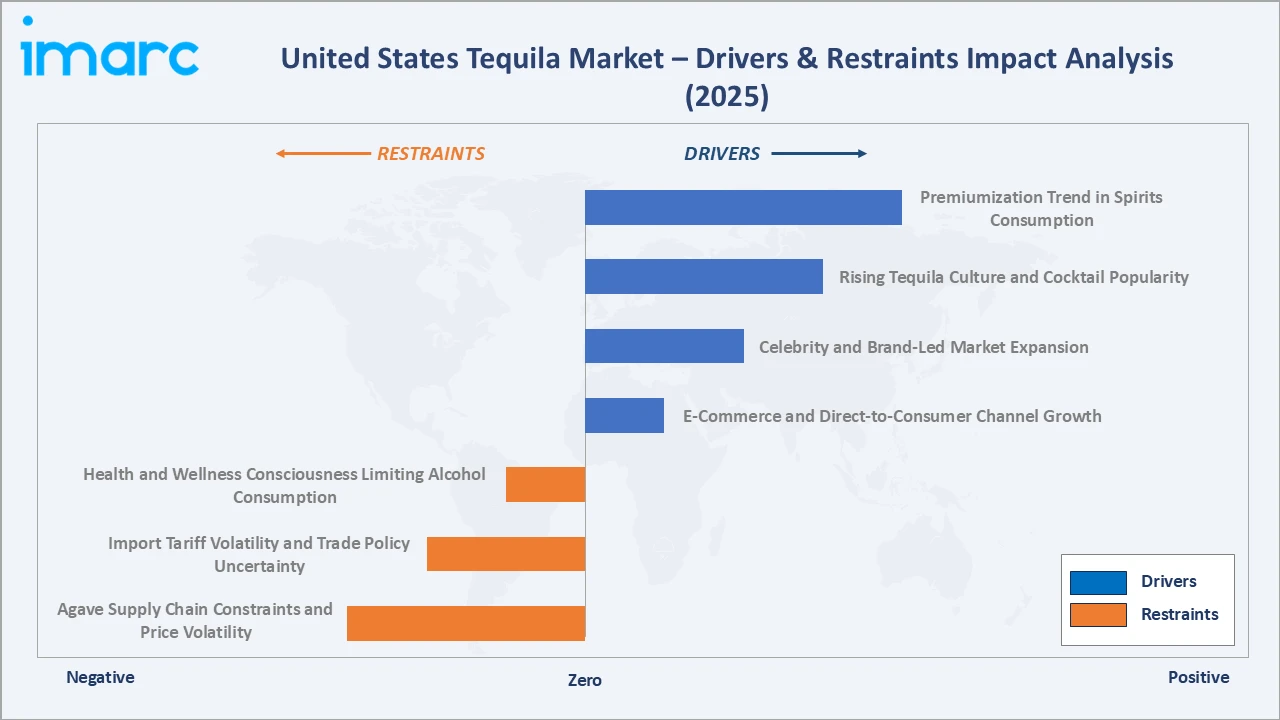
- Premiumization Trend in Spirits Consumption: American consumers are consistently trading up from standard and value-tier spirits to premium, super-premium, and ultra-premium tequila expressions, driving higher average selling prices and revenue growth across all distribution channels. US spirits premiumization has driven a shift toward 100% agave tequila expressions over the past decade, fundamentally reshaping category revenue distribution toward higher-margin products. Super-premium and ultra-premium tequila price points above USD 50 per bottle are growing at 2-3x the rate of standard category, creating above-average revenue contribution from a smaller volume base.
- Rising Tequila Culture and Cocktail Popularity: Tequila's centrality in American cocktail culture through margaritas, tequila sunrises, and palomas, combined with expanding craft cocktail menus, drives sustained on-trade volume growth across bars, restaurants, and entertainment venues. Margaritas consistently rank as the most ordered cocktail in the United States across casual dining, upscale bars, and Mexican restaurant segments, providing tequila with unmatched cocktail category anchoring. Craft cocktail proliferation in premium dining venues has elevated blanco and reposado tequila as bartender-preferred base spirits, driving menu penetration and consumer trial across non-traditional tequila occasions.
- Celebrity and Brand-Led Market Expansion: High-profile celebrity endorsements and ownership stakes from entertainment, sports, and music industries have accelerated premium tequila awareness, consumer trial, and brand loyalty at unprecedented rates in the United States market. Social media-driven brand storytelling and celebrity endorsement authenticity narratives resonate strongly with millennial and Gen Z consumers, creating outsized brand visibility relative to marketing investment levels.
- E-Commerce and Direct-to-Consumer Channel Growth: The legalization of online spirits retail across US states and the proliferation of alcohol delivery platforms including Drizly and Minibar have significantly expanded tequila market accessibility, driving incremental volume from non-traditional purchasing occasions. Online spirits retail is growing as state-level alcohol e-commerce regulations expanded and consumer comfort with digital spirits purchasing increased post-pandemic. DTC spirits platforms enable premium and craft tequila brands to reach target consumers nationwide without dependence on traditional distributor relationships, reducing market entry barriers for artisanal producers.
Market Restraints
- Health and Wellness Consciousness Limiting Alcohol Consumption: Growing health and wellness awareness among American consumers, particularly millennials and Gen Z, is moderating overall alcohol consumption frequency, creating headwinds for market volume growth across all spirits categories including tequila. Sober-curious and mindful drinking movements are gaining mainstream traction among younger US consumers, with low-alcohol and no-alcohol alternatives capturing increasing share of social occasions.
- Import Tariff Volatility and Trade Policy Uncertainty: Periodic trade policy tensions between the United States and Mexico create tariff and regulatory uncertainty for tequila importers and distributors, affecting pricing stability and investment planning across the supply chain. US-Mexico trade policy uncertainties including potential tariff escalations threaten to add USD 2-5 per bottle in import costs, with significant impact on price-sensitive mid-tier tequila category volumes. USMCA renegotiation risks and border policy uncertainties create multi-year investment planning challenges for US tequila importers, distributors, and retailers dependent on stable cross-border supply chains.
- Agave Supply Chain Constraints and Price Volatility: Blue Weber agave's 7-10 year cultivation cycle creates structural supply chain constraints that lead to periodic agave price spikes, increasing production costs and limiting tequila distillers' ability to scale production rapidly. Agave plant prices reached USD 30 per kilogram during supply shortage periods, compared to historical norms of USD 3-6 per kilogram, severely compressing distillery margins and constraining capacity expansion. Climate change impacts on Jalisco agave cultivation including drought, frost events, and pest outbreaks create increasing production volatility, with multi-year recovery cycles constraining responsive supply scaling.
Market Opportunities
- Super-Premium and Ultra-Premium Category Expansion: Continued premiumization momentum creates significant opportunity for super-premium (USD 30-50) and ultra-premium (USD 50+) tequila segments, where volume growth, price realization, and margin profiles are most favorable. Ultra-premium tequila priced above USD 100 per bottle is growing as high-net-worth consumers treat aged extra anejo and limited-edition expressions as luxury gifting and collecting categories. Super-premium 100% agave tequila between USD 30-50 is gaining share from whiskey, vodka, and gin as consumers seeking premium cocktail experiences shift spending toward authentic agave-based spirits.
- Mezcal and Agave Spirits Category Extension: Growing consumer interest in mezcal and other agave spirits creates an expanded agave spirits category that lifts overall consumer engagement with Mexican spirits, presenting cross-selling opportunities for established tequila brands. Mezcal's rapid growth in US on-trade is educating consumers about agave spirits complexity, creating upgrade pathways into premium anejo and extra anejo tequila expressions from category-curious consumers.
Market Challenges
- Intensifying Competition and Market Saturation in Standard Segments: The proliferation of tequila brands creates intense shelf competition, distribution challenges, and price compression in standard blanco and reposado segments. US retail shelf space limitations and distributor portfolio concentration mean that 90%+ of new tequila brand launches fail to achieve national distribution, restricting market entry economics for smaller producers. Mass-market blanco and reposado segments face intensifying price competition from private-label and value-positioning brands, compressing margins for mid-tier producers without differentiated positioning.
- Regulatory Compliance and Denomination of Origin Requirements: Tequila's strict Denomination of Origin regulations requiring production in designated Mexican states and compliance with CRT standards create operational complexity and limit supply chain flexibility for US importers. CRT certification requirements, NOM compliance, and Mexican denomination of origin rules require US importers to maintain dedicated Mexican sourcing relationships, limiting supply chain diversification options.
Emerging Market Trends
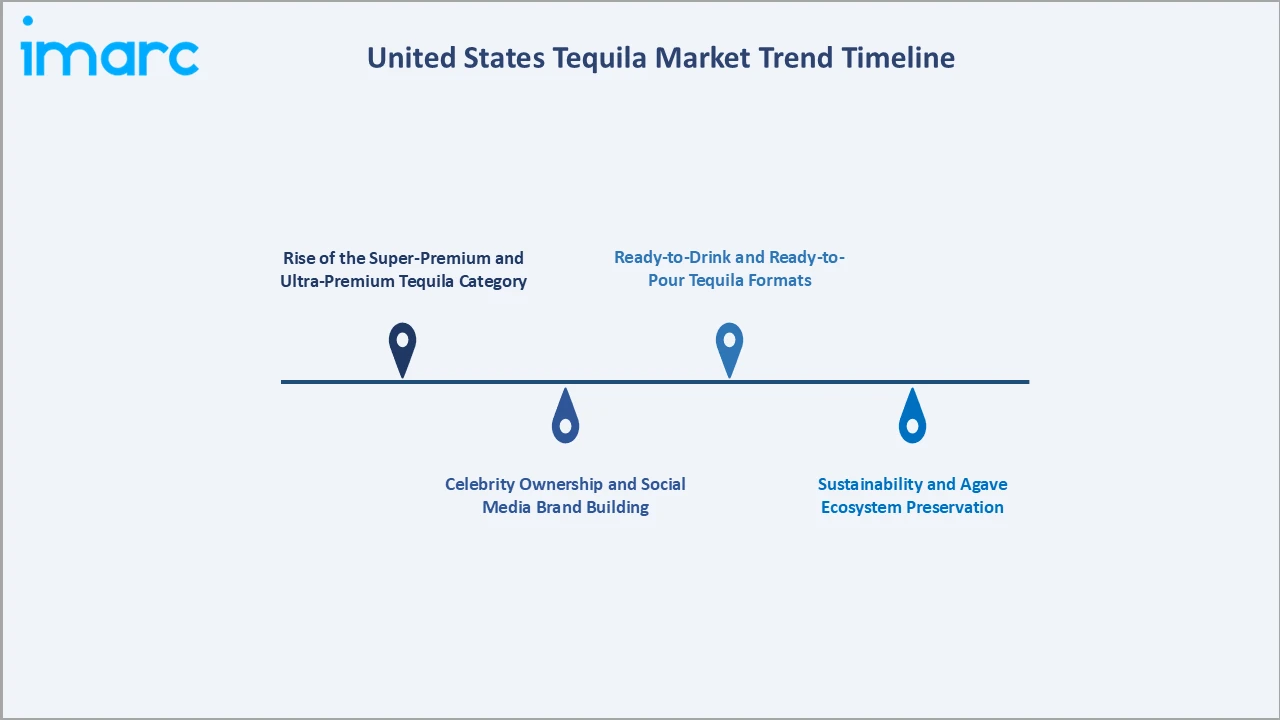
1. Rise of the Super-Premium and Ultra-Premium Tequila Category
The sustained premiumization wave is elevating consumer spending toward anejo, extra anejo, and limited-edition expressions priced above USD 50. Premium tequila is increasingly positioned as a luxury gifting category and collector's item, competing with Scotch whisky and cognac in high-value occasions.
2. Celebrity Ownership and Social Media Brand Building
Celebrity-owned tequila brands have transformed category marketing dynamics, leveraging massive social media followings to drive awareness and trial at unprecedented speed. This trend is accelerating launch timelines and reducing traditional marketing expenditure requirements for new premium brand entries.
3. Sustainability and Agave Ecosystem Preservation
Consumer and regulatory pressure for sustainable agave cultivation, responsible jimado practices, and environmental stewardship is shaping brand positioning and sourcing strategies. Tequila producers investing in agave replanting programs and sustainable distillation gain differentiation advantage with environmentally conscious US consumers.
4. Ready-to-Drink and Ready-to-Pour Tequila Formats
Tequila-based RTD cocktails including canned margaritas and tequila sodas are growing rapidly within the broader RTD spirits category, extending tequila's reach into outdoor, convenience, and at-home occasions previously dominated by beer, hard seltzer, and wine-based alternatives.
Industry Value Chain Analysis
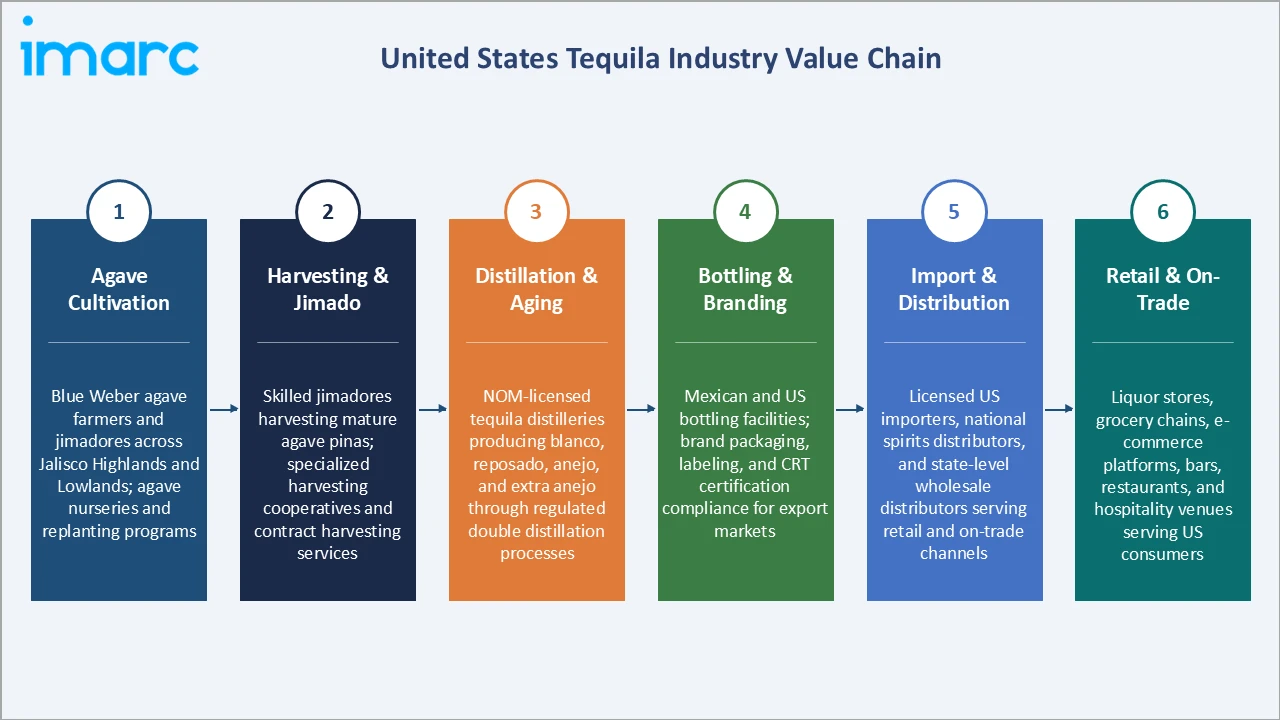
The US tequila value chain is uniquely cross-border, with production exclusively originating in Mexico under CRT-regulated denomination of origin rules and virtually all value realization occurring in the United States through distribution margins, marketing investment, and retail pricing.
|
Stage |
Key Participants |
|
Agave Cultivation |
Blue Weber agave farmers and jimadores across Jalisco Highlands and Lowlands; agave nurseries and replanting programs |
|
Harvesting & Jimado |
Skilled jimadores harvesting mature agave pinas; specialized harvesting cooperatives and contract harvesting services |
|
Distillation & Aging |
NOM-licensed tequila distilleries producing blanco, reposado, anejo, and extra anejo through regulated double distillation processes |
|
Bottling & Branding |
Mexican and US bottling facilities; brand packaging, labeling, and CRT certification compliance for export markets |
|
Import & Distribution |
Licensed US importers, national spirits distributors, and state-level wholesale distributors serving retail and on-trade channels |
|
Retail & On-Trade |
Liquor stores, grocery chains, e-commerce platforms, bars, restaurants, and hospitality venues serving US consumers |
Distributor relationships represent the critical commercial chokepoint in the value chain, with major national distributors' portfolio decisions determining brand accessibility across US retail and on-trade channels.
Technology Landscape in the United States Tequila Industry
Distillation and Aging Technology Innovation
Premium tequila distilleries are investing in advanced copper pot still systems, tahona wheel fermentation, and slow-distillation processes to differentiate product quality and complexity. Micro-oxygenation and precision temperature-controlled aging technologies enable accelerated maturation of reposado and anejo expressions while maintaining quality characteristics demanded by US premium consumers and spirit competition judging panels.
E-Commerce and Digital Distribution Technology
AI-powered recommendation engines on spirits e-commerce platforms analyze purchase history and flavor preference data to drive premium tequila upsell conversion. Digital age verification technology and state-specific compliance automation have significantly reduced friction in online spirits retail, enabling tequila brands to build direct consumer relationships and subscription-based delivery models that bypass traditional retail margin structures.
Agave Genomics and Sustainable Cultivation Technology
Leading tequila producers are investing in agave genomics research to develop disease-resistant, drought-tolerant blue Weber agave varieties capable of shorter maturation cycles. Precision agriculture technologies including drone monitoring, soil health analytics, and irrigation optimization are being deployed across Jalisco agave estates to improve yield consistency and reduce weather-related supply disruptions affecting US market supply stability and pricing.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | Blanco | 38.7% | 2025 |
| Purity | 🔒 | 🔒 | 2025 |
| Price Range | Premium Tequila | 🔒 | 2025 |
| Distribution Channel | On-Trade | 53.7% | 2025 |
| Region | South | 31.6% | 2025 |

By Product Type
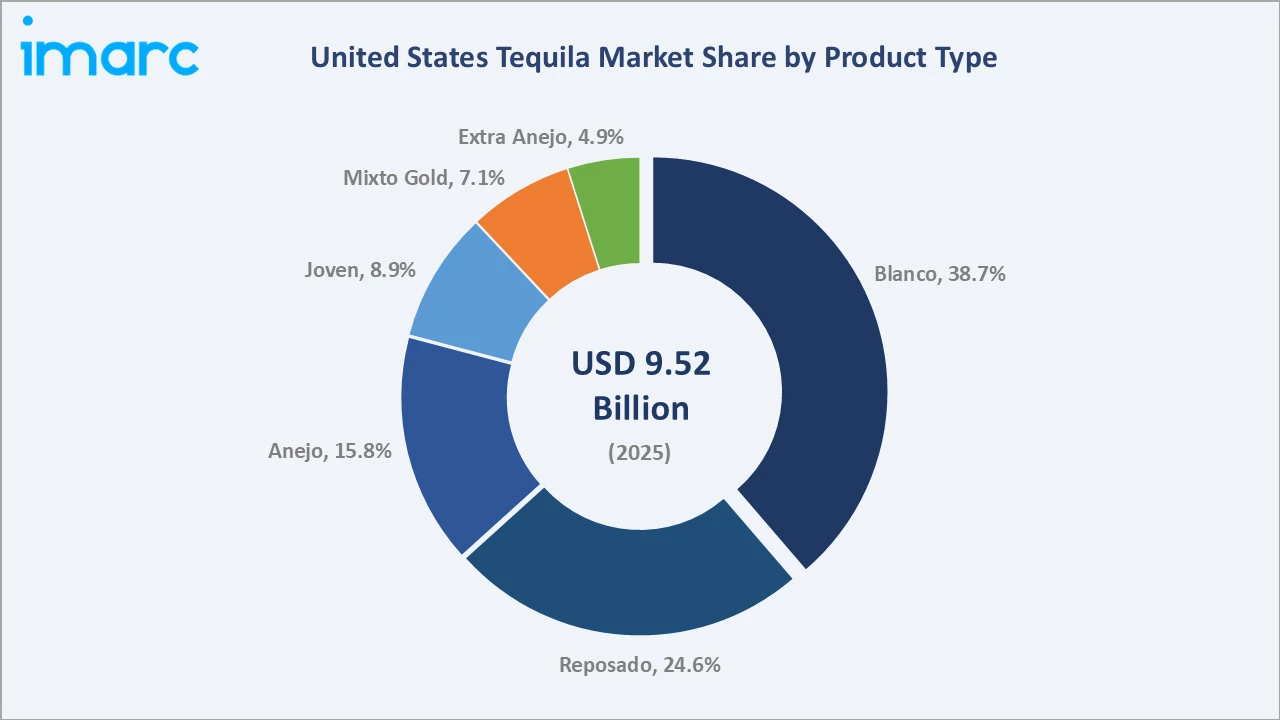
Blanco leads at 38.7% (2025) through its dual-market role as the foundational cocktail ingredient and an increasingly appreciated neat sipping spirit. Blanco's versatility in margaritas, palomas, and tequila-based cocktails drives consistent on-trade volume, while its authentic agave flavor profile attracts entry-level premium consumers beginning their tequila journey. Its competitive price positioning relative to aged expressions maintains strong off-trade retail velocity across mainstream and specialty liquor channels nationwide.
To access detailed market analysis, Request Sample
Reposado at 24.6% serves consumers seeking oak-barrel aged character at accessible price points, bridging blanco simplicity and anejo complexity. Anejo at 15.8% is growing through premium sipping occasions and luxury gifting applications. Joven at 8.9% serves value-conscious consumers with blended aged-unaged expressions. Mixto Gold at 7.1% remains relevant in budget segments. Extra Anejo at 4.9% commands highest average selling prices through ultra-premium positioning with luxury collectors.
By Distribution Channel
On-Trade at 53.7% (2025) leads through tequila's foundational role in American bar and restaurant culture. Margarita consumption across casual dining, Mexican restaurant chains, and upscale cocktail bars provides a consistent high-velocity on-trade platform.
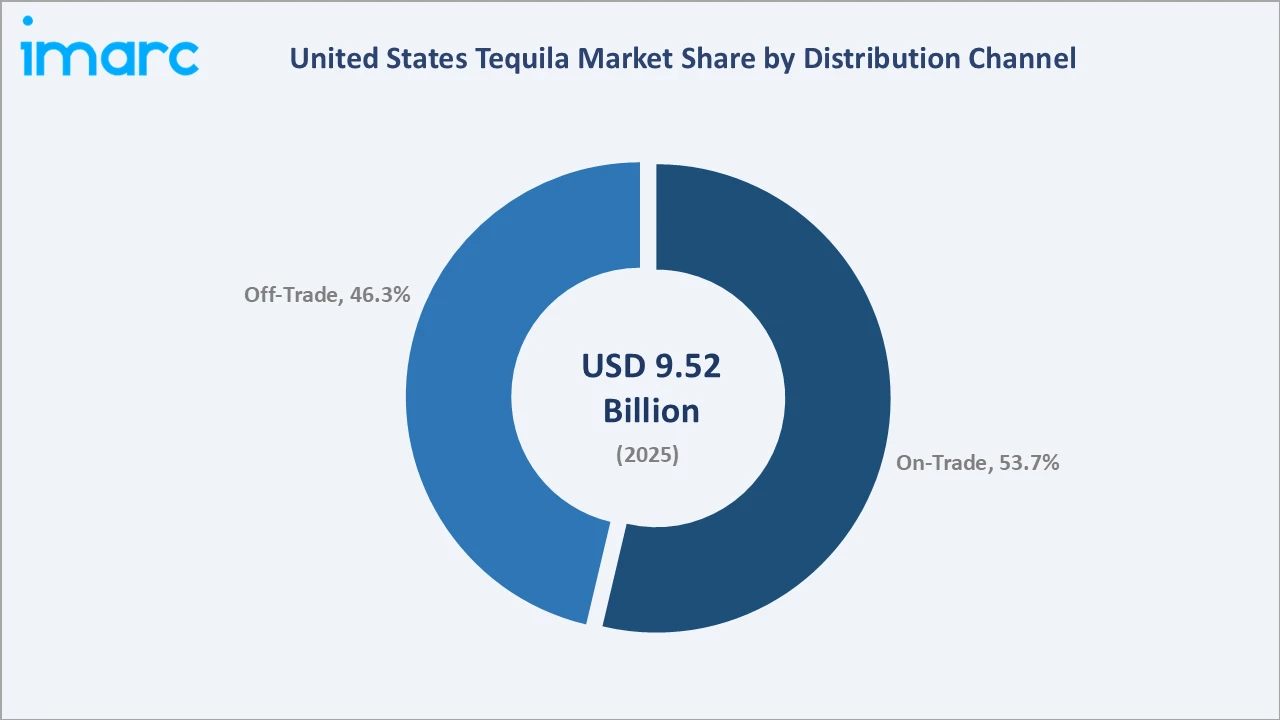
Off-Trade at 46.3% reflects robust retail performance across liquor stores, grocery chains, warehouse clubs, and e-commerce platforms. Home consumption occasions, gifting, and pantry stocking drive off-trade volume, with the premiumization trend most visible in retail premium shelf space expansion.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
|
South |
31.6% |
Texas and Florida's large Hispanic populations, vibrant hospitality sectors, and established tequila drinking occasions drive the highest regional per-capita tequila consumption. |
|
West |
28.4% |
California's Mexican-American cultural heritage, premium spirits market leadership, and strong on-trade tequila programming drive significant market volume and value share. |
|
Northeast |
22.3% |
New York and Massachusetts's high-income urban consumer bases drive premium and super-premium segment leadership, with sophisticated cocktail culture elevating high-margin tequila expressions. |
|
Midwest |
17.7% |
Growing tequila consumer base across Chicago and major Midwest urban markets, supported by expanding Mexican restaurant presence and increasing casual dining margarita penetration. |
South's 31.6% regional leadership reflects the demographic and cultural concentration of tequila consumption in Texas and Florida, where Mexican heritage, border culture, and high hospitality density combine to create the US market's highest tequila consumption density. West's 28.4% is driven by California's position as America's largest spirits market and its Mexican-American cultural influence on bar programming and retail category management.
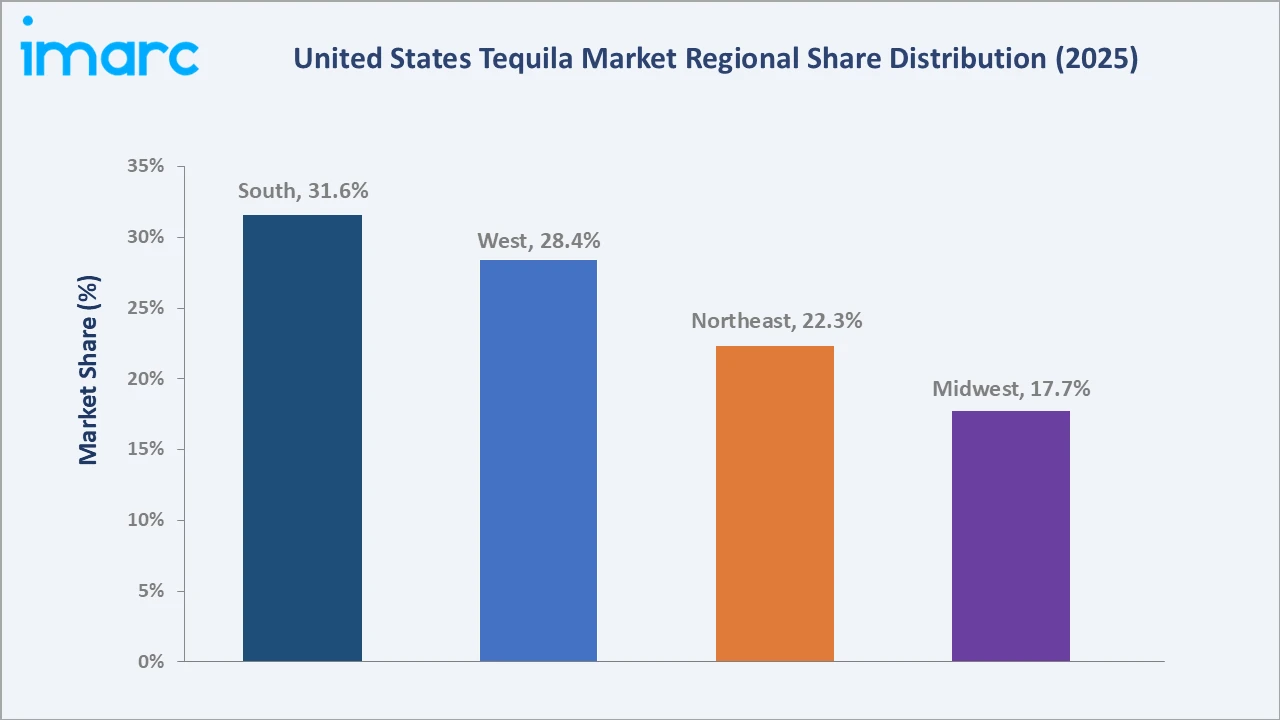
Northeast at 22.3% demonstrates strong premium segment leadership through New York's high-income consumer base and sophisticated spirits culture. Midwest at 17.7% represents the highest growth potential through expanding tequila consumer education, growing Mexican restaurant presence, and increasing premium spirits accessibility across Chicago and secondary urban markets.
Competitive Landscape
The US tequila competitive landscape is dominated by a handful of major spirits conglomerates controlling the highest-volume brands, while a large and growing tail of independent artisanal producers competes for premium shelf space and on-trade listings. Mid-tier competition intensifies as premium segment growth attracts new celebrity-backed entrants, and established spirits companies leverage existing distribution to accelerate premium tequila portfolio expansion.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Becle | Gran Coramino Tequila, Tequila 1800 | Market Leader | World's largest tequila producer; diversified portfolio spanning value to ultra-premium expressions |
| Diageo | Don Julio, Casamigos, Astral Tequila | Market Leader | Premium-focused portfolio anchored by Don Julio; Casamigos drives celebrity-endorsed super-premium growth |
| Suntory Global Spirits Inc. | Sauza, El Tesoro, Tres Generaciones, Hornitos | Strong Challenger | Diversified tequila portfolio across mass and premium segments; strong grocery and off-trade distribution |
| Brown-Forman | Herradura, El Jimador | Established Player | Herradura's premium heritage and El Jimador's accessible pricing deliver complementary market coverage |
| Constellation Brands, Inc. | Casa Noble, Mi CAMPO | Emerging Challenger | Growing tequila portfolio building on core beer distribution strength and three-tier market infrastructure |
Key players include Becle, Diageo, Suntory Global Spirits Inc., Brown-Forman, Constellation Brands, Inc., and others.
Key Company Profiles
Becle
Becle, the world's largest tequila producer and parent company of the Jose Cuervo brand family, is the market leader in the United States tequila market. The company operates across all price tiers from accessible Jose Cuervo expressions to ultra-premium Reserva de la Familia, commanding the broadest distribution footprint of any tequila producer in the US.
- Key Products: Jose Cuervo Tradicional, Maestro Dobel Diamante, 1800 Tequila, Cenote, and Reserva de la Familia across blanco, reposado, anejo, and extra anejo expressions.
- Strategic Focus: Strengthening premium and super-premium portfolio share in the United States while maintaining volume leadership through Jose Cuervo's mass-market positioning and extensive off-trade distribution. Investing in premium experiential marketing includes tequila tourism, distillery visits, and bartender education programs to deepen US trade and consumer engagement with premium brand portfolio.
Diageo
Diageo is a global beverages company with a commanding US tequila portfolio anchored by Don Julio, one of the world's most recognized premium tequila brands, and Casamigos, the celebrity-endorsed super-premium brand co-founded by George Clooney and acquired by Diageo.
- Key Products: Don Julio 1942, Don Julio Blanco, Don Julio Reposado, Casamigos Blanco, Casamigos Reposado, Casamigos Anejo, and DeLeón ultra-premium expressions.
- Strategic Focus: Driving US premium and super-premium tequila category value growth through Don Julio's heritage brand positioning and Casamigos' celebrity-amplified consumer engagement model. Accelerating Don Julio 1942 luxury positioning through targeted high-net-worth consumer experiences, fine dining partnerships, and VIP hospitality activations driving margin-accretive ultra-premium volume.
Market Concentration Analysis
The US tequila market exhibits a moderately concentrated structure with the top five players collectively controlling approximately 65-70% of market revenue. Market concentration is highest in the premium and super-premium segments where brand equity, distribution scale, and marketing investment create significant barriers to entry for independent producers.
The long tail of artisanal and craft tequila producers competes for the remaining 30-35% market share, largely concentrated in the premium on-trade channel and specialty spirits retail. Celebrity-backed emerging brands are disrupting traditional concentration patterns by achieving rapid scale through social media and celebrity audiences, while e-commerce and DTC channels are reducing traditional distribution barriers for independent producers reaching premium US consumers.
Investment & Growth Opportunities
Highest Growth Segments
Extra Anejo (~7.1% CAGR through luxury premiumization), Anejo (~5.8% CAGR through premium sipping growth), Blanco (~5.2% CAGR through cocktail culture expansion), and e-commerce off-trade channel represent the US tequila market's highest-growth investment segments through 2034.
Emerging Investment Opportunities
Super-premium and ultra-premium tequila brand development represents the highest-return investment opportunity in the US market, where USD 30-100+ price points deliver 60-80% higher gross margins than standard category. Investors with tequila distillery access, celebrity or cultural capital for brand storytelling, and premium on-trade distribution relationships are best positioned to capture this margin-rich segment's continued growth.
Investment Themes
- Premium and super-premium tequila brand development: Building authentic premium tequila brands targeting USD 30-100 price points offers the strongest risk-adjusted returns, leveraging sustained US premiumization momentum with proven consumer demand dynamics.
- Tequila e-commerce and DTC platform investment: Technology-enabled direct-to-consumer spirits platforms are capturing premium tequila share from traditional distribution, offering higher margins and proprietary consumer data for targeted marketing.
Future Market Outlook (2026-2034)
The United States tequila market is projected to grow from USD 9.52 Billion in 2025 to USD 9.92 Billion in 2026, reaching USD 11.69 Billion by 2030 and USD 13.78 Billion by 2034 at a CAGR of 4.19% during 2026-2034. Growth is anchored by the sustained premiumization megatrend, expanding tequila consumer base across demographics, and deepening integration of tequila into American dining, entertainment, and gifting occasions.
Three structural forces define US tequila's growth trajectory through 2034: continued premiumization driving consumers from mixto and standard blanco to 100% agave premium expressions; demographic tailwinds from the growing US Hispanic population and millennial-led spirits category exploration; and innovation-driven category expansion through RTD tequila formats, agave spirits diversification, and sustainability-positioned brand narratives resonating with environmentally conscious American consumers. The combination of deeply embedded cocktail culture, premiumization economics, and expanding consumer sophistication creates a structurally favorable long-term demand environment for the US tequila market.
Research Methodology
Primary Research
Primary research comprised structured interviews with US tequila market stakeholders, including importers, national distributors, bar and restaurant operators, specialty spirits retailers, and brand marketing executives across premium and super-premium tequila categories.
Secondary Research
Secondary research encompassed DISCUS (Distilled Spirits Council of the United States) consumption data, TTB statistical reports, Nielsen retail panel data, IWSR spirits market research, CRT tequila production statistics, and brand financial disclosures from publicly listed spirits companies. Over 45 secondary sources were reviewed.
Forecasting Models
Forecasts used a consumer expenditure and occasion-frequency model: per-capita tequila expenditure growth rates applied across demographic cohort projections, adjusted for premiumization-driven average price increases, on-trade recovery trajectory, and e-commerce channel penetration expansion estimates.
United States Tequila Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Blanco, Joven, Mixto Gold, Reposado, Anejo, Extra Anejo |
| Purities Covered | 100% Tequila, 60% Tequila |
| Price Ranges Covered | Premium Tequila, Value Tequila, Premium and Super-Premium Tequila, Ultra-Premium Tequila |
| Distribution Channels Covered |
|
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Becle, Diageo, Suntory Global Spirits Inc., Brown-Forman, Constellation Brands, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States tequila market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the United States tequila market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States tequila industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Tequila Market Report
The United States tequila market size is estimated at USD 9.92 Billion in 2026, driven by sustained premiumization trends, celebrity-endorsed brand expansion, and growing tequila cocktail culture across on-trade and off-trade channels nationwide.
The United States tequila market grows at a CAGR of 4.19% during 2026-2034, reaching USD 13.78 Billion by 2034, driven by premiumization, expanding consumer demographics, and sustained on-trade integration across dining and entertainment venues.
Blanco leads at 38.7% (2025) through its versatility as a cocktail ingredient and sipping spirit, competitive price positioning in entry-level premium segments, and foundational role in margarita and tequila-based cocktail consumption across US on-trade venues.
On-Trade leads at 53.7% (2025) through tequila's deep integration into American bar and restaurant culture, margarita dominance in casual dining, and expansion of premium tequila programs across upscale and fine dining establishments nationwide.
The South leads at 31.6% (2025) through Texas and Florida's large Hispanic consumer populations, vibrant hospitality and tourism sectors, and deeply established tequila drinking culture driving the highest per-capita tequila consumption in the United States.
Leading companies include Becle, Diageo, Suntory Global Spirits Inc., Brown-Forman, Constellation Brands, Inc., and others.
The United States tequila market is projected to reach approximately USD 11.69 Billion by 2030, supported by continued premiumization momentum, growing consumer demographics, expanding e-commerce spirits retail, and sustained on-trade tequila program investment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade