Vegan Food Market Size, Share, Trends, and Forecast by Product, Source, Distribution Channel, and Region, 2026-2034
Vegan Food Market Size, Share, Trends & Forecast (2026-2034)
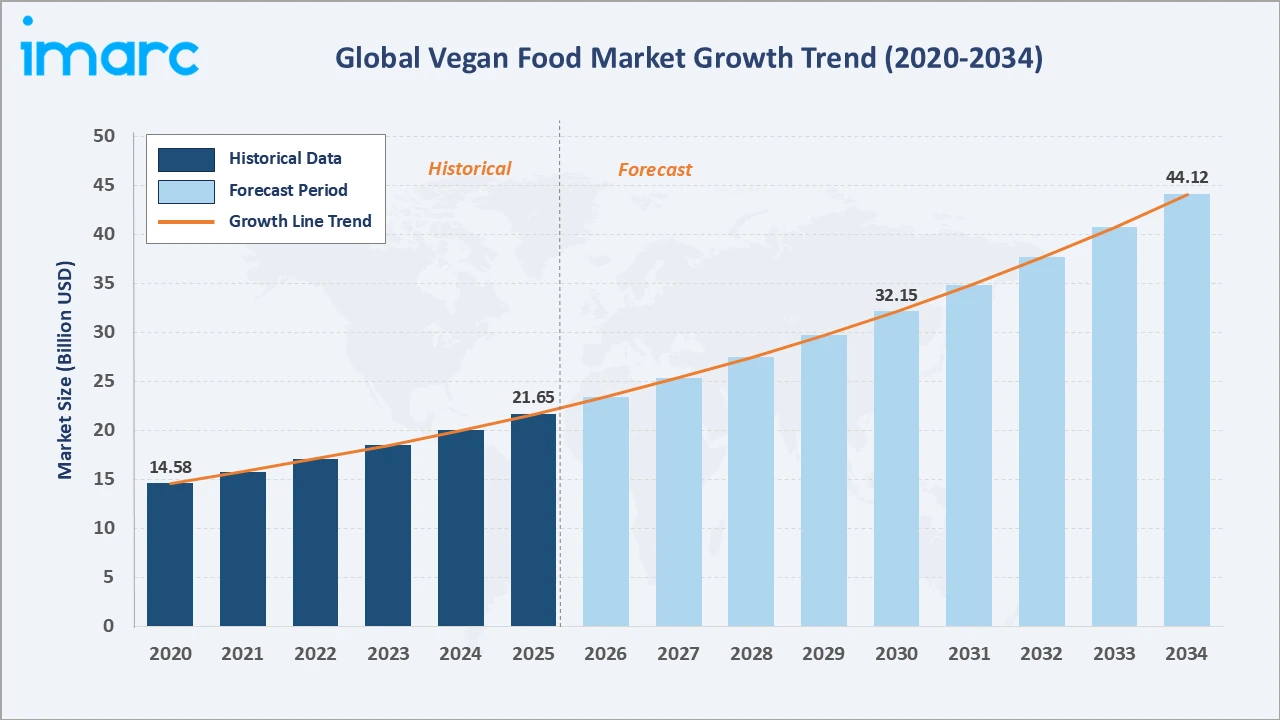
The vegan food market grew from USD 21.65 Billion in 2025 to USD 23.43 Billion in 2026 and is projected to reach USD 44.12 Billion by 2034, growing at a CAGR of 8.23% during 2026-2034. Rising health consciousness among consumers, growing environmental sustainability concerns, and rapid product innovation in plant-based proteins are the primary forces shaping demand across both developed and emerging economies.
Meat substitutes lead the product segment with 36.3% share, supermarkets and hypermarkets dominate distribution channel at 68.7% and North America holds the largest regional share at 38.2%.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 21.65 Billion |
| Market Size (2026) | USD 23.43 Billion |
| Forecast Market Size (2034) | USD 44.12 Billion |
| CAGR (2026-2034) | 8.23% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | North America (38.2%, 2025) |
| Second Largest Region | Europe (27.6%, 2025) |
| Leading Product | Meat Substitutes (36.3%, 2025) |
| Leading Distribution Channel | Supermarkets and Hypermarkets (68.7%, 2025) |
The vegan food market size increased from USD 14.58 Billion in 2020 to USD 21.65 Billion in 2025 and is estimated to reach USD 23.43 Billion in 2026. The market is further projected to expand to USD 32.15 Billion by 2030 and USD 44.12 Billion by 2034. The market reflects an accelerating shift in global consumer preferences toward sustainable, health-oriented diets, underpinned by strong product development investment, expanding retail footprints, and increasing institutional support for plant-based food systems across major economies.
To get more information on this market, Request Sample
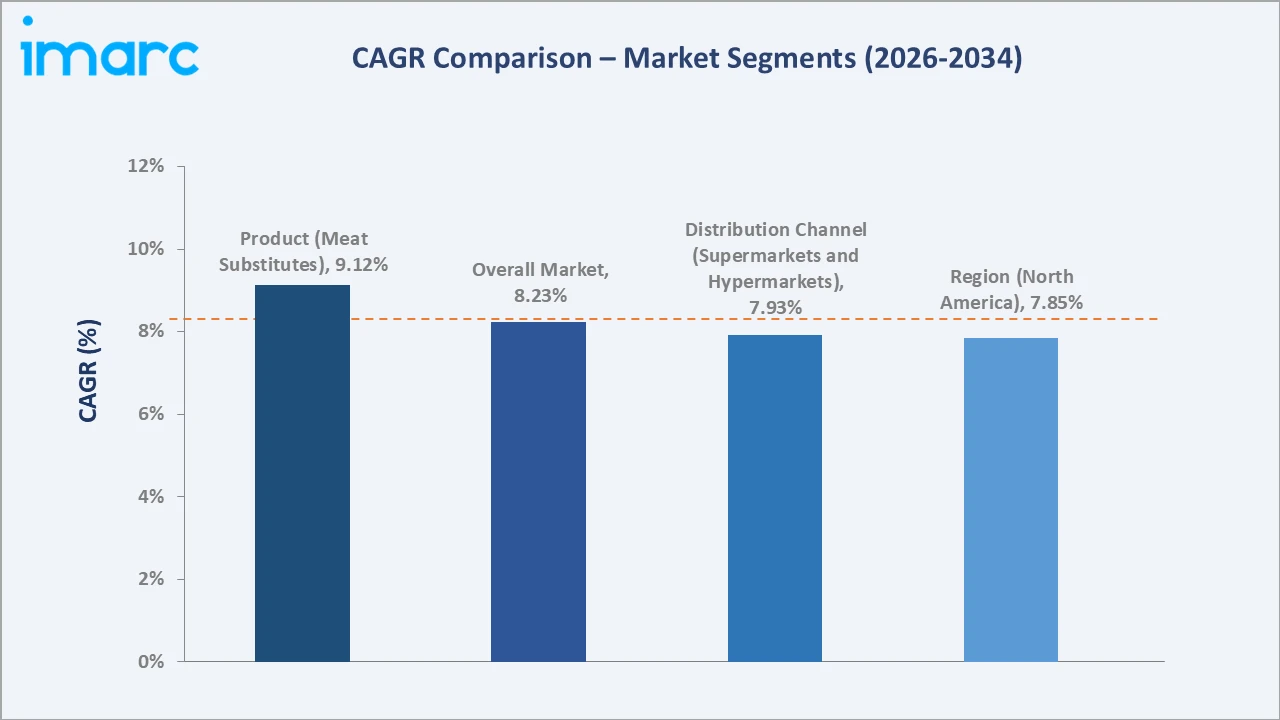
CAGR trajectories across product, distribution channel, and regional sub-segments show online stores and Asia-Pacific expanding faster than the overall 8.23% market CAGR, driven by digital commerce growth, rising health awareness in emerging markets, and government support for sustainable food systems.
Executive Summary
The vegan food market expanded from USD 21.65 Billion in 2025 to an estimated USD 23.43 Billion in 2026, reflecting consistent consumer adoption of plant-based diets. Market growth is supported by health consciousness, environmental sustainability imperatives, and rapid improvement in the taste and nutritional profile of vegan products across meat substitute and dairy alternative categories.
Meat substitutes command 36.3% product share in 2025, underpinned by improved protein equivalence and expanding affordability relative to conventional meat. Supermarkets and hypermarkets control 68.7% of distribution channel, reflecting the mainstreaming of vegan food in conventional retail. North America leads regional share at 38.2%, supported by high consumer awareness, robust retail networks, and significant brand investment in plant-based innovation.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Product | Meat Substitutes – 36.3% share (2025) |
| Second Largest Product | Dairy Alternatives – 35.8% share (2025) |
| Leading Distribution Channel | Supermarkets and Hypermarkets – 68.7% share (2025) |
| Second Largest Distribution Channel | Specialty Stores – 11.8% share (2025) |
| Leading Region | North America – 38.2% share (2025) |
| Second Largest Region | Europe – 27.6% share (2025) |
| Top Companies | Beyond Meat, Inc., Impossible Foods Inc., Oatly Group AB, Danone S.A. |
Key Analytical Observations Expanding On the Data Above:
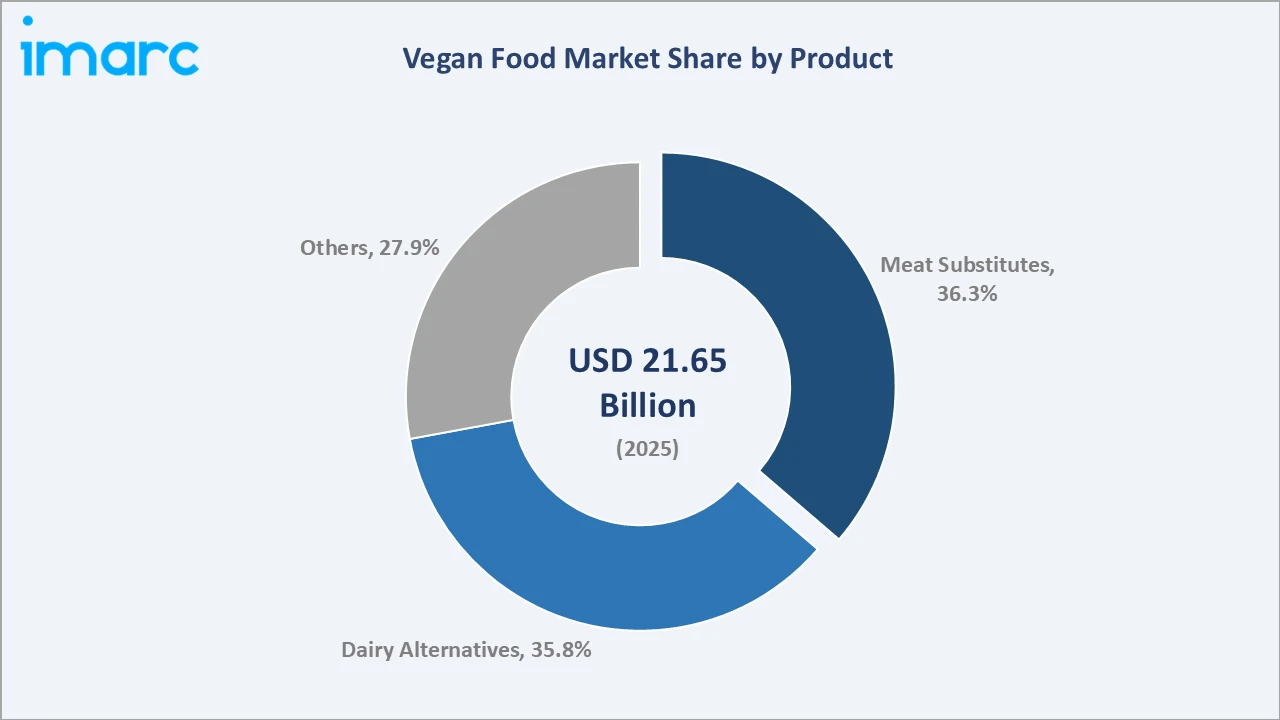
- Meat substitutes at 36.3% reflect advances in extrusion and blending technology that have significantly improved protein content, texture, and taste similarity to conventional meat, making the segment the primary driver of overall market expansion.
- Dairy alternatives at 35.8% are driven by rising lactose intolerance awareness, flexitarian dietary preferences, and expanding oat, almond, and pea-based product ranges offering improved nutrition and taste profiles.
- Supermarkets and hypermarkets at 68.7% dominate distribution channel, as plant-based brands gain mainstream shelf space, with dedicated vegan aisles and private-label development reinforcing consumer visibility and accessibility.
- Specialty stores at 11.8% cater to consumers seeking niche vegan products, organic options, and specialized nutritional offerings, with personalized assistance and curated product selections supporting segment demand.
- North America at 38.2% leads regional share, anchored by high consumer health awareness, well-established plant-based brand ecosystems, and strong foodservice adoption of vegan menu offerings across quick-service and casual dining formats.
Vegan Food Market Overview
Vegan food encompasses plant-based products formulated to replace conventional animal-derived foods, including meat substitutes, dairy alternatives, egg replacements, and plant-based seafood. Products range from whole-food items such as tofu and tempeh to advanced processed alternatives engineered to replicate the taste, texture, and nutritional profile of animal protein. The market addresses demand from vegans, vegetarians, flexitarians, and health-conscious consumers across retail and foodservice channels globally.
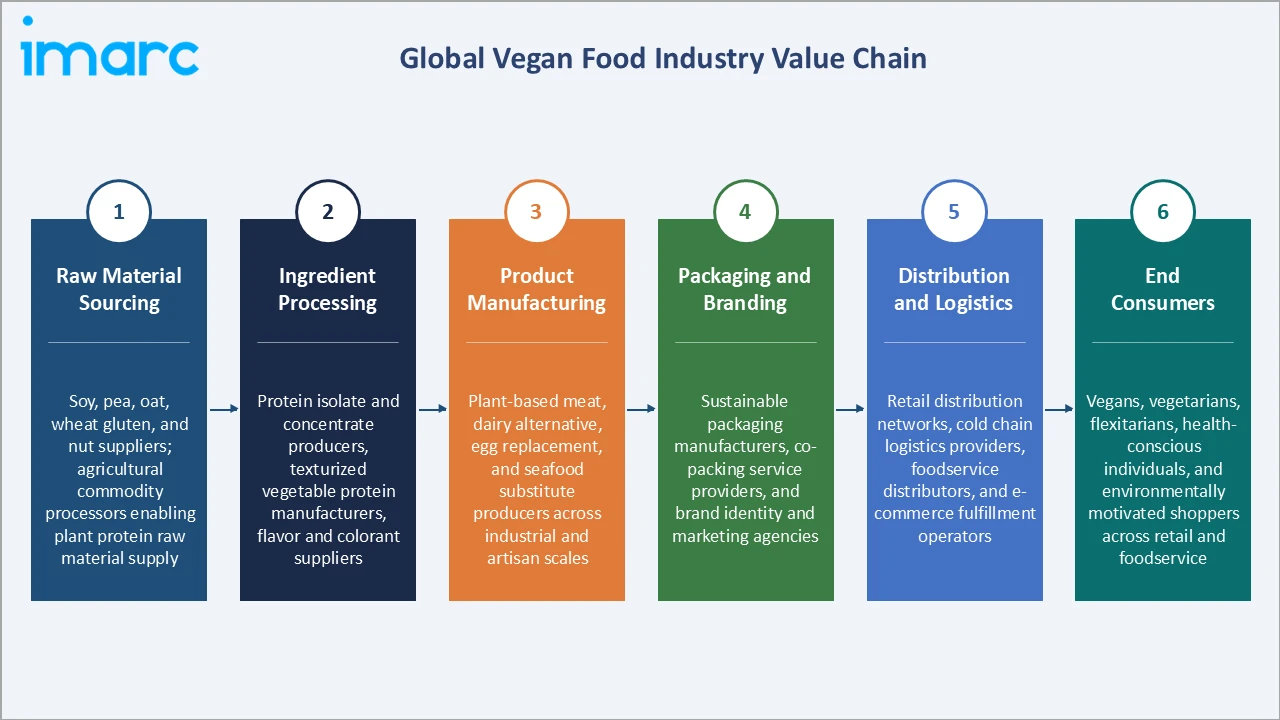
The ecosystem spans raw material suppliers, ingredient processors, product manufacturers, packaging providers, distribution networks, and end consumers. Technology providers, regulatory bodies, and sustainability advocacy organizations form the supporting layer. Together, they enable a commercially scalable, increasingly mainstream market for plant-based nutrition across diverse consumer demographics and geographies.
Market Dynamics
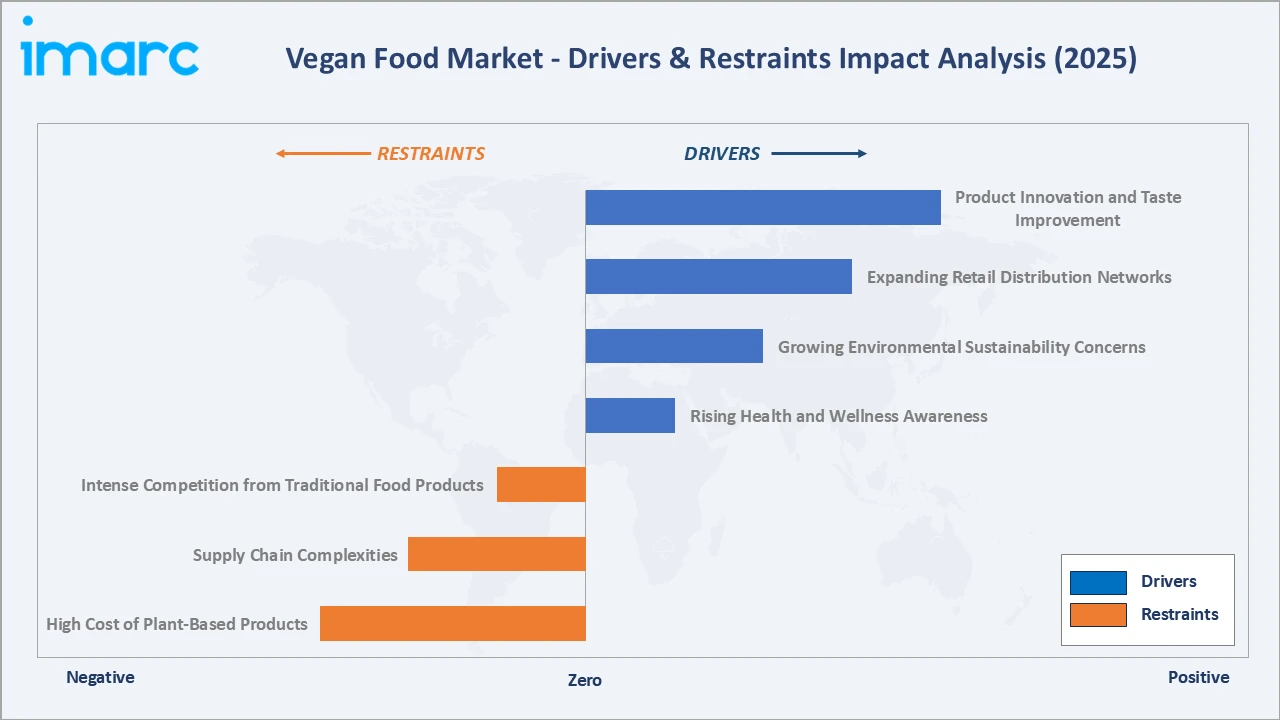
To evaluate market opportunities, Request Sample
Market Drivers
- Rising Health and Wellness Awareness: As per IMARC Group, the global health and wellness market was valued at USD 3,939.3 Billion in 2025. Consumers globally are increasingly linking plant-based diets with reduced risk of chronic diseases. This shift is supporting the growth of the vegan food products market as consumers increasingly prioritize balanced nutrition, preventive health, and healthier everyday eating habits.
- Growing Environmental Sustainability Concerns: Increasing consumer and institutional awareness of the environmental impact of conventional animal agriculture, including greenhouse gas emissions, land use, and water consumption, is accelerating the shift toward plant-based food alternatives as a sustainability imperative.
- Expanding Retail Distribution Networks: Plant-based food brands are benefiting from growing shelf space allocation in major supermarkets, hypermarkets, and convenience stores globally, alongside proliferating online grocery platforms that enable direct-to-consumer brand engagement and subscription purchasing models.
- Product Innovation and Taste Improvement: Continuous investment in protein science, extrusion technology, and flavor systems is enhancing product appeal across the vegan snacks market, improving taste, texture, and nutritional value to encourage wider consumer adoption.
Market Restraints
- High Cost of Plant-Based Products: Plant-based alternatives often carry a price premium over conventional animal-based products, limiting adoption among price-sensitive consumer segments and in lower-income markets where cost remains the primary purchasing determinant.
- Supply Chain Complexities: Sourcing consistent, high-quality plant protein raw materials, including pea, soy, and oat isolates, at commercial scale presents logistical and cost challenges, particularly for brands seeking to reduce ingredient origin dependency and geographic supply risk.
- Intense Competition from Traditional Food Products: Conventional meat and dairy manufacturers are investing in marketing, product reformulation, and value pricing strategies that intensify competition for consumer spending across primary food categories where vegan alternatives are seeking to gain share.
Market Opportunities
- Expansion into Foodservice and Quick-Service Restaurants: Growing partnership opportunities exist between vegan food brands and global quick-service restaurant chains seeking to offer plant-based menu options, providing high-volume distribution channels and significant consumer trial exposure.
- Growing Demand in Asia-Pacific Markets: Rapidly increasing health awareness, urbanization, and rising disposable income in China, India, and Southeast Asia are creating substantial growth opportunities for vegan food brands to establish early-mover positions in high-population consumer markets.
Market Challenges
- Regulatory and Labeling Complexity: Varying food labeling standards, ingredient disclosure requirements, and plant-based product classification rules across major markets create compliance complexity for companies seeking to operate globally with consistent product formulations.
- Consumer Skepticism Around Processing and Additives: A growing segment of health-conscious consumers express concern about the highly processed nature of some plant-based alternatives, preferring whole-food options and creating a market tension between ultra-processed vegan products and clean-label demand.
Emerging Market Trends
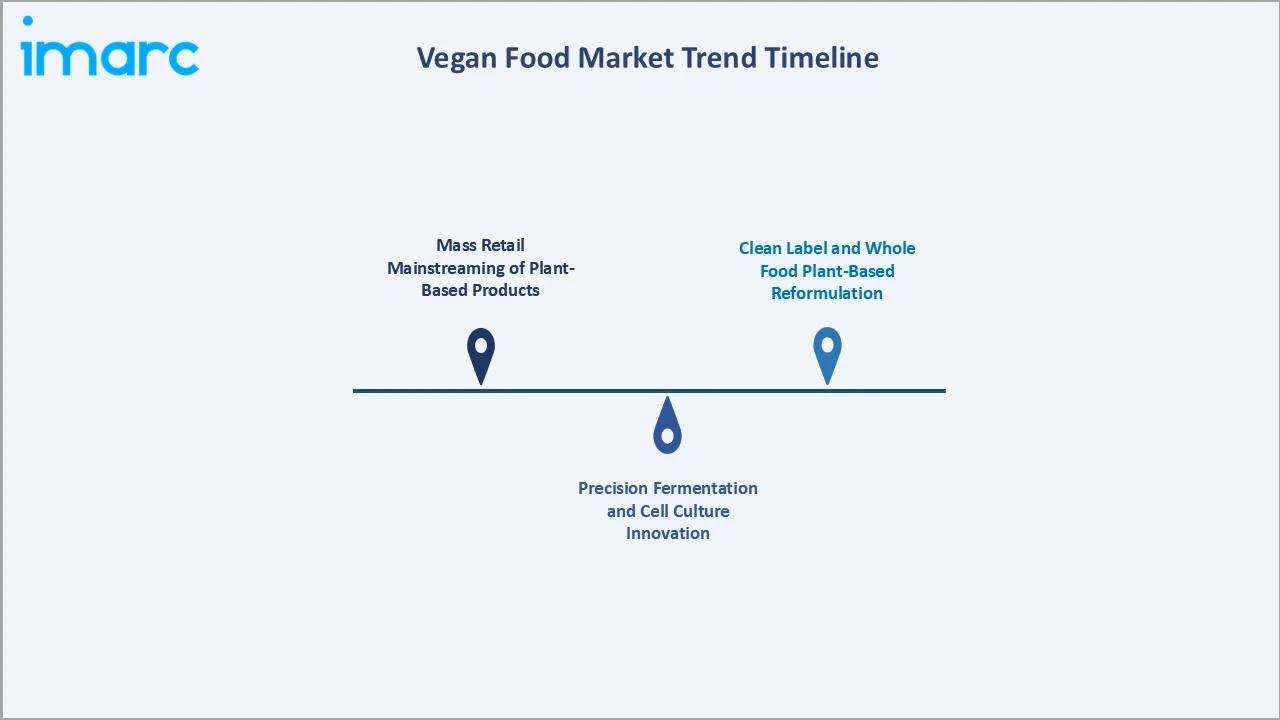
1. Mass Retail Mainstreaming of Plant-Based Products
Plant-based foods have transitioned from specialty health-food stores to mainstream supermarket shelves globally. Major retailers are dedicating permanent vegan aisles, developing private-label plant-based ranges, and actively increasing product variety to meet rising consumer demand across all income segments. This wider retail presence is also improving accessibility to convenient vegan meals, supporting growth in the vegan meal market.
2. Precision Fermentation and Cell Culture Innovation
The use of precision fermentation to produce animal-free dairy proteins, including whey and casein without cows, is gaining commercial traction. These innovations are expanding the availability of sustainable, protein-rich alternatives and creating new opportunities for product diversification across the vegan food industry.
3. Clean Label and Whole Food Plant-Based Reformulation
Consumer demand for shorter ingredient lists, recognizable components, and minimal processing is driving a clean-label reformulation wave across plant-based food brands. This trend is accelerating development of legume-forward, vegetable-based, and minimally processed vegan products that combine nutritional transparency with the convenience expected by mainstream grocery shoppers.
Industry Value Chain Analysis
The vegan food market value chain spans six core stages, from raw material sourcing through product manufacturing, distribution, and end consumer delivery. Ingredient processing and product manufacturing stages capture the highest value-add, while retail distribution is increasingly determining competitive position through shelf space allocation and private-label development.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Soy, pea, oat, wheat gluten, and nut suppliers; agricultural commodity processors enabling plant protein raw material supply |
| Ingredient Processing | Protein isolate and concentrate producers, texturized vegetable protein manufacturers, flavor and colorant suppliers |
| Product Manufacturing | Plant-based meat, dairy alternative, egg replacement, and seafood substitute producers across industrial and artisan scales |
| Packaging and Branding | Sustainable packaging manufacturers, co-packing service providers, and brand identity and marketing agencies |
| Distribution and Logistics | Retail distribution networks, cold chain logistics providers, foodservice distributors, and e-commerce fulfillment operators |
| End Consumers | Vegans, vegetarians, flexitarians, health-conscious individuals, and environmentally motivated shoppers across retail and foodservice |
Vertically integrated manufacturers controlling ingredient sourcing and product manufacturing are positioned to capture greater margin than single-stage operators dependent on spot protein commodity markets and third-party co-manufacturers.
Technology Landscape in the Vegan Food Industry
Plant-Based Protein Technology
High-moisture extrusion and shear-cell technology are the primary manufacturing platforms enabling plant proteins to replicate the fibrous texture of conventional meat. Ongoing advances in protein blending, combining pea, soy, and mycoprotein, are improving nutritional completeness and sensory performance across product formats.
Precision Fermentation and Biotechnology
Precision fermentation allows the production of animal-identical proteins, fats, and flavors without animal inputs. This technology is reducing the processing gap between conventional dairy and plant-based alternatives, enabling higher-quality cheese, yogurt, and whey protein formulations at improving cost economics.
Food Processing Innovation
Advances in clean-label ingredient processing, including aquafaba extraction, cold-press protein concentration, and enzymatic texturization, are enabling brands to reduce additive dependency while maintaining product functionality. These innovations support the clean-label reformulation trend accelerating across the sector.
Smart Supply Chain and Distribution Technology
Digital platforms for cold-chain monitoring, demand forecasting, and direct-to-consumer order management are improving supply chain efficiency for vegan food brands. Blockchain-based ingredient traceability is also gaining adoption as consumer demand for supply chain transparency increases across premium vegan product segments.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product | Meat Substitutes | 36.3% | 2025 |
| Source | Soy | 🔒 | 2025 |
| Distribution Channel | Supermarkets and Hypermarkets | 68.7% | 2025 |
| Region | North America | 38.2% | 2025 |

By Product
Meat substitutes lead with a 36.3% share in 2025, driven by strong consumer demand for familiar meal formats like burgers, sausages, and nuggets made with plant-based proteins. Rapid improvement in taste and texture through extrusion innovation, combined with expanding foodservice adoption, positions the segment for continued above-average growth.
To access detailed market analysis, Request Sample
Dairy alternatives at 35.8% represent the second-largest segment, supported by widespread lactose intolerance, growing flexitarian demand, and expanding oat-based beverage ranges. The segment benefits from high everyday consumption frequency across coffee, cereal, and cooking applications.
By Distribution Channel
Supermarkets and hypermarkets command 68.7% of distribution channel in 2025, reflecting the mainstreaming of vegan food in conventional grocery retail. Dedicated plant-based aisles, growing private-label ranges, and high foot traffic make this the primary channel for consumer discovery and volume sales of vegan food products.
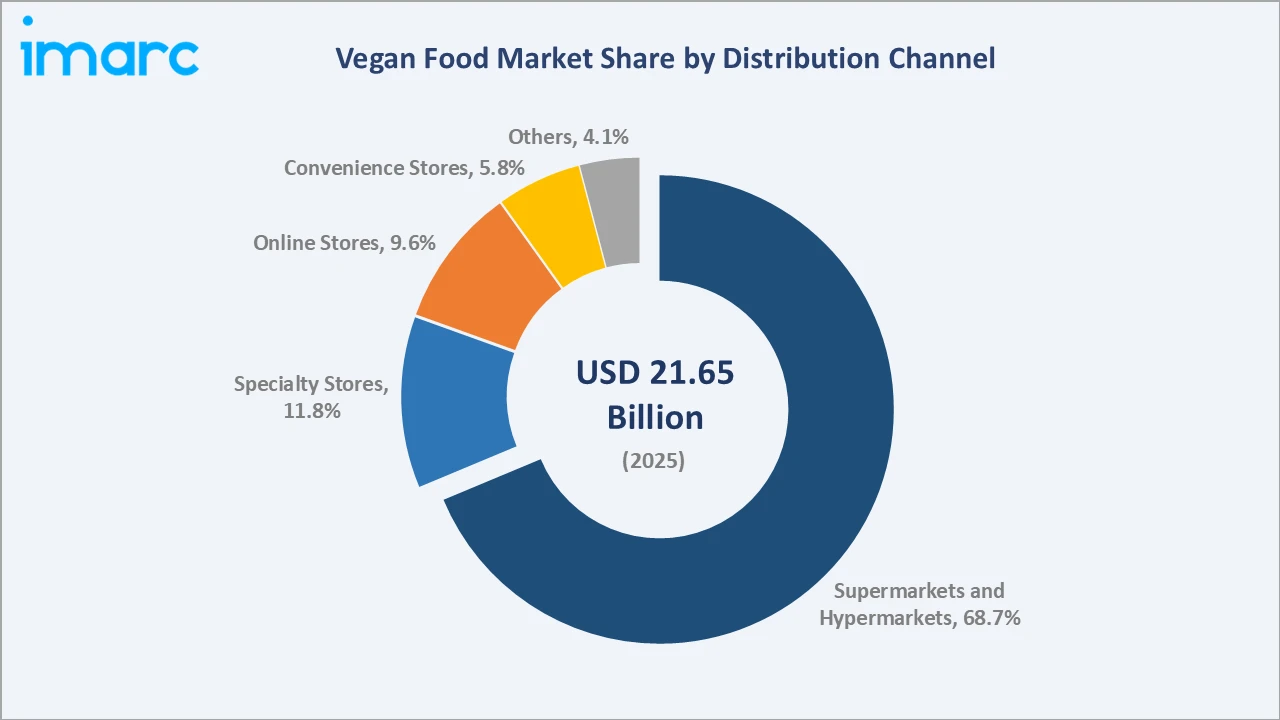
Online stores at 9.6% are the fastest-growing distribution channel, driven by direct-to-consumer brand strategies, subscription meal kit services, and the convenience of home grocery delivery.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| North America | 38.2% | High consumer health awareness, established plant-based brand ecosystem, strong retail infrastructure, and significant foodservice adoption of vegan menu offerings |
| Europe | 27.6% | Strong sustainability regulation, high environmental awareness, established dairy alternative brands, and growing flexitarian dietary adoption across Western European markets |
| Asia-Pacific | 21.8% | Rising health consciousness, rapid urbanization, increasing disposable income, and growing modern retail penetration supporting plant-based product adoption in China, India, and Southeast Asia |
| Latin America | 7.2% | Growing urban middle-class health awareness, expanding modern retail formats, increasing government support for sustainable food systems, and rising interest in plant-protein nutrition |
| Middle East and Africa | 5.2% | Expanding young consumer base with health awareness, growing modern retail presence, increasing vegan product availability through e-commerce channels, and rising environmental sustainability consciousness |
North America commands 38.2% regional share in 2025, anchored by well-funded plant-based brands, high retail distribution depth, and strong consumer willingness to pay a premium for health-oriented and sustainable food products.
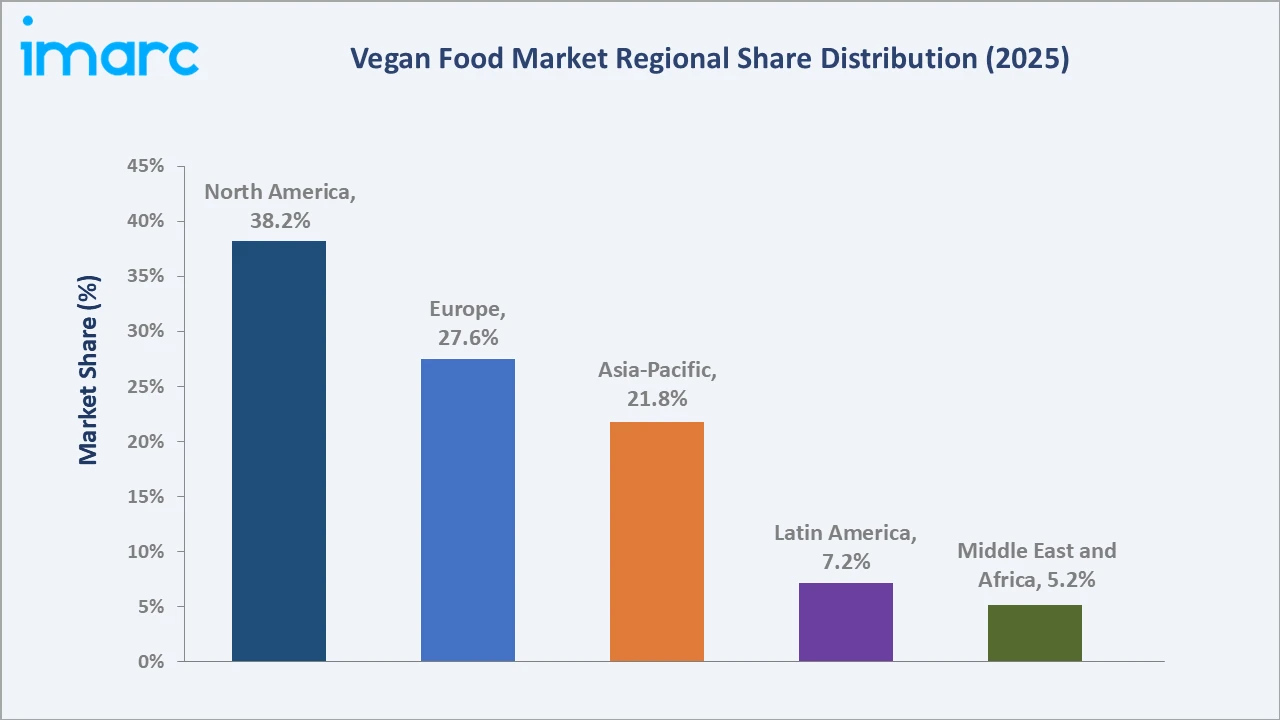
Asia-Pacific at 21.8%, while currently third-largest, represents the fastest-growing regional opportunity, supported by expanding middle-class health awareness, government sustainability initiatives, and rising modern retail infrastructure across China, India, and Southeast Asian markets.
Competitive Landscape
The vegan food market is moderately concentrated, with a mix of dedicated plant-based specialists and diversified food conglomerates competing across product innovation, brand equity, distribution depth, and price positioning. Scale, ingredient sourcing efficiency, and brand trust are the key competitive differentiators shaping market position across product and regional segments.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Beyond Meat, Inc. | Beyond Burger | Leader | Expanding plant-based meat portfolio through retail and foodservice partnerships and continuous protein science investment |
| Impossible Foods Inc. | Impossible Burger | Leader | Growing plant-based meat and dairy presence through strategic retail expansion and ongoing product innovation |
| Oatly Group AB | Oat Drink | Leader | Scaling oat-based food and beverage production globally through capacity investment and category diversification |
| Danone S.A. | Alpro | Challenger | Strengthening dairy alternative portfolio across global markets through brand investment and distribution expansion |
Key players include Beyond Meat, Inc., Impossible Foods Inc., Oatly Group AB, and Danone S.A., among others.
Key Company Profiles
Beyond Meat, Inc.
Beyond Meat, Inc. is a United States-based plant-based meat company headquartered in El Segundo, California. The company develops and markets plant-based meat products designed to replicate the taste, texture, and nutritional profile of conventional animal-based meat.
- Product Portfolio: Plant-based burger patties, sausages, ground meat, chicken strips, and jerky distributed across retail and quick-service restaurant channels globally.
- Recent Developments: The company continues to expand its global retail and foodservice distribution partnerships and invest in next-generation protein science to improve product cost and taste performance.
- Strategic Focus: Achieving cost parity with conventional meat through supply chain optimization and production scale while expanding its global retail and foodservice distribution footprint, while undertaking operational restructuring to improve cost efficiency and path to profitability.
Impossible Foods Inc.
Impossible Foods Inc. is a United States-based food technology company headquartered in Redwood City, California. The company uses molecular biology and food science to develop plant-based meat products.
- Product Portfolio: Plant-based burger patties, ground meat, sausages, chicken nuggets, and pork alternatives, with distribution across retail grocery chains and foodservice partners globally.
- Recent Developments: The company is advancing its ingredient innovation platform and expanding retail distribution partnerships across North America, Asia-Pacific, and European markets.
- Strategic Focus: Scaling global distribution of plant-based protein products and investing in proprietary ingredient technology to improve taste, nutritional profile, and cost competitiveness.
Oatly Group AB
Oatly Group AB is a Sweden-based oat-based food and beverage company headquartered in Malmö, Sweden. The company specializes in oat-derived dairy alternative products distributed across retail and foodservice channels globally.
- Product Portfolio: Oat-based barista editions, cooking creams, yogurt alternatives, ice cream, and spread products distributed across grocery retail and specialty coffee channels.
- Recent Developments: The company continues to invest in production capacity expansion and broaden its product portfolio across dairy alternative formats beyond core beverage offerings.
- Strategic Focus: Expanding oat drink category leadership globally through retail and foodservice channel deepening and developing adjacent dairy alternative product lines.
Market Concentration Analysis
The vegan food market exhibits moderate concentration, with the top four players, Beyond Meat, Inc., Impossible Foods Inc., Oatly Group AB, and Danone S.A., collectively controlling a meaningful but non-dominant share of global plant-based food revenues. The market retains significant fragmentation at regional and category levels, with hundreds of specialist brands competing in meat substitute, dairy alternative, and snack sub-segments.
Barriers to entry are moderate, as brand building, retail shelf access, and protein sourcing infrastructure require meaningful capital, but they are not prohibitive. Fragmentation is maintained by the relative ease of entering niche premium or regional sub-categories. Consolidation is progressing steadily, with large food conglomerates acquiring specialist vegan brands to accelerate portfolio expansion and reduce go-to-market costs.
The market is expected to exhibit continued consolidation through 2034, with major diversified food companies acquiring established plant-based brands and scaling their distribution advantages. However, niche innovation brands will continue to enter and challenge incumbents in fast-moving product categories such as precision-fermented dairy, whole-food plant-based snacks, and sustainable seafood alternatives.
Investment & Growth Opportunities
Fastest-Growing Segments
Online stores represent the fastest-growing distribution channel, supported by direct-to-consumer brand strategies, subscription services, and digital grocery platform expansion. Improved product discovery and convenient home delivery are further encouraging consumers to purchase vegan food products online.
Emerging Markets
Asia-Pacific is the fastest-growing regional opportunity, with China, India, and Southeast Asian markets offering large addressable consumer bases at early adoption stages. Rising health awareness, urbanization, and expanding retail networks are creating favorable conditions for broader market penetration.
Venture & Investment Trends
Investment activity is concentrated in precision fermentation platforms, whole-food plant-based ingredient development, and technology-enabled distribution models. Capital is also flowing into cost-reduction technologies for pea and soy protein processing, targeting price parity with conventional animal protein across mass-market retail formats. ESG-driven institutional investment in sustainable food systems is providing additional tailwinds for the sector.
Future Market Outlook (2026-2034)
The vegan food market is projected to grow from USD 21.65 Billion in 2025 to USD 23.43 Billion in 2026, reaching USD 44.12 Billion by 2034, registering a CAGR of 8.23% during 2026-2034.
Three structural forces will shape the market through 2034: continued cost reduction in plant protein manufacturing; expansion of precision fermentation commercialization; and accelerating mainstream consumer adoption driven by health, sustainability, and affordability improvements.
By 2034, the vegan food market is expected to be characterized by a mature competitive landscape combining large diversified food companies with strong brand and distribution assets, specialist innovation brands driving category evolution, and technology platforms enabling precision nutrition and direct-to-consumer engagement.
Research Methodology
Primary Research
Primary research included structured discussions with plant-based food company executives, retail category managers, foodservice procurement professionals, and ingredient technology specialists, validating market sizing, segmentation mix, and regional demand patterns across the global vegan food ecosystem.
Secondary Research
Secondary sources included industry publications from the Good Food Institute, FAO nutrition reports, OECD food system analyses, national retail sales data, corporate annual reports from publicly listed plant-based food companies, and investment research from sector-focused financial institutions.
Forecasting Models
Market forecasts combined top-down macroeconomic and consumer trend models with bottom-up category-level analysis covering product segment penetration, distribution channel growth rates, and regional adoption curves. Scenario analysis addressed technology adoption pace, raw material cost trajectories, and regulatory development.
Vegan Food Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered |
|
| Sources Covered | Almond, Soy, Oats, Wheat, Others |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Convenience Stores, Specialty Stores, Online Stores, Others |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Beyond Meat, Inc., Impossible Foods Inc., Oatly Group AB, Danone S.A., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the vegan food market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global vegan food market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the vegan food industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Vegan Food Market Report
The vegan food market size is estimated at USD 23.43 Billion in 2026, driven by rising consumer health awareness, growing environmental sustainability concerns, and rapid expansion of plant-based product ranges across retail and foodservice channels globally.
The vegan food market is projected to grow at a CAGR of 8.23% from 2026-2034, reaching USD 44.12 Billion, supported by product innovation, expanding distribution, and growing mainstream consumer adoption of plant-based diets.
Meat substitutes dominate with 36.3% share in 2025, driven by improved taste and texture innovation and expanding retail and foodservice distribution of plant-based burger, sausage, and nugget product formats.
Supermarkets and hypermarkets lead with 68.7% distribution channel share in 2025, as dedicated vegan aisles, private-label development, and high consumer foot traffic make conventional grocery retail the primary vegan food channel.
North America leads with 38.2% regional share in 2025, underpinned by high consumer health awareness, strong plant-based brand investment, well-established retail distribution networks, and significant foodservice adoption.
Asia-Pacific is the fastest-growing region, supported by rapid health awareness growth, urbanization, rising disposable income, and expanding modern retail infrastructure across China, India, and Southeast Asian markets.
Key players include Beyond Meat, Inc., Impossible Foods Inc., Oatly Group AB, and Danone S.A., among others.
Key drivers include rising consumer health consciousness, growing environmental sustainability awareness, continuous product innovation improving taste and texture, and expanding retail distribution of plant-based food products globally.
Main challenges include high product pricing relative to conventional alternatives, limited consumer acceptance in emerging markets, supply chain complexity in raw material sourcing, and consumer skepticism around heavily processed plant-based products.
Key opportunities include precision fermentation platforms, Asia-Pacific market expansion, direct-to-consumer digital channels, whole-food plant-based ingredient development, and cost-reduction technology for pea and soy protein processing.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade