
Biological Safety Cabinet Market Size, Share, Trends and Forecast by Type, End User, and Region, 2026-2034
Biological Safety Cabinet Market Size, Share, Trends & Forecast (2026-2034)
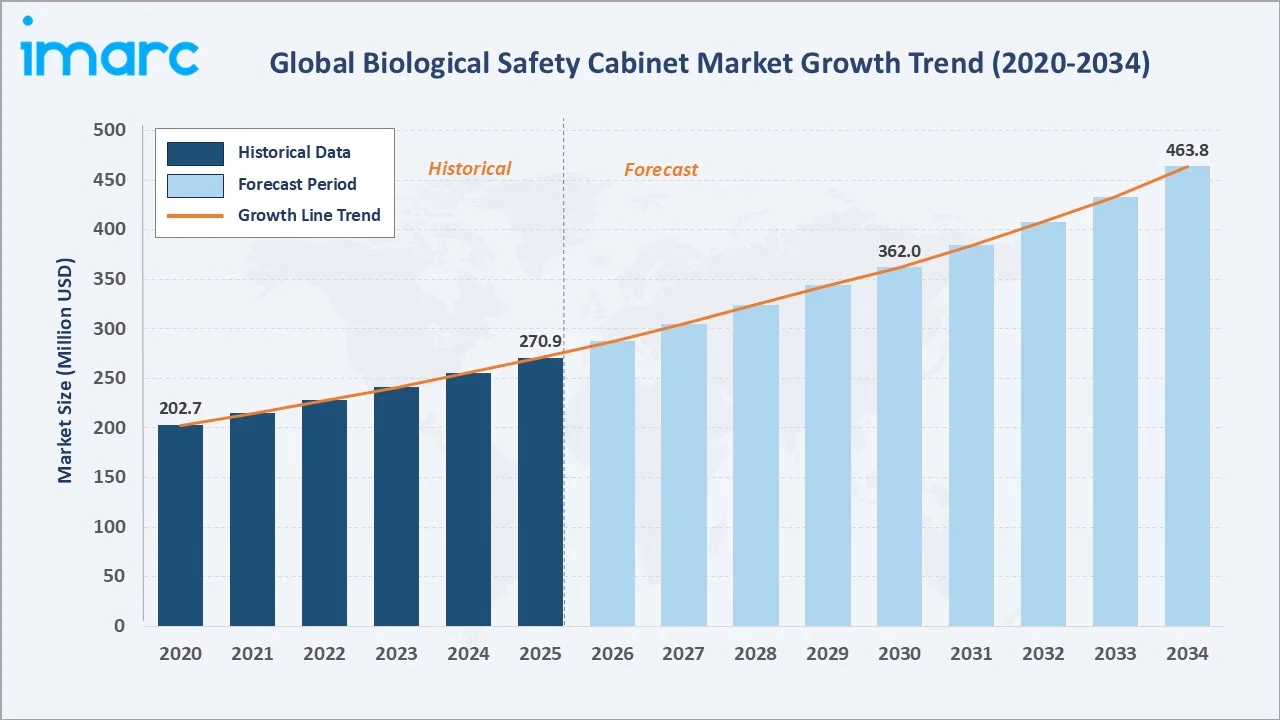
The global biological safety cabinet (BSC) market grew from USD 270.9 Million in 2025 to USD 287.0 Million in 2026 and is projected to reach USD 463.8 Million by 2034, exhibiting a CAGR of 5.97% during 2026-2034. Market expansion is driven by increasing biosafety compliance mandates, expanding pharmaceutical R&D pipelines, and the surge in infectious disease research following the COVID-19 pandemic. Class II cabinets lead with a 61.4% type share in 2025, pharmaceutical and biopharmaceutical companies represent 46.8% of end-user demand, and North America holds the largest regional share at 37.9%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 270.9 Million |
|
Market Size (2026) |
USD 287.0 Million |
|
Forecast Market Size (2034) |
USD 463.8 Million |
|
CAGR (2026-2034) |
5.97% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Class II (61.4%, 2025) |
|
Dominant End User |
Pharmaceutical and Biopharmaceutical Companies (46.8%, 2025) |
|
Leading Region |
North America (37.9%, 2025) |
The biological safety cabinet market size grew from approximately USD 202.7 Million in 2020 to USD 270.9 Million in 2025, reflecting strong historical growth. The market reached USD 287.0 Million in 2026 and is estimated to cross USD 362.0 Million by 2030, driven by sustained pharmaceutical manufacturing expansion and laboratory infrastructure investments across emerging economies.
To get more information on this market, Request Sample
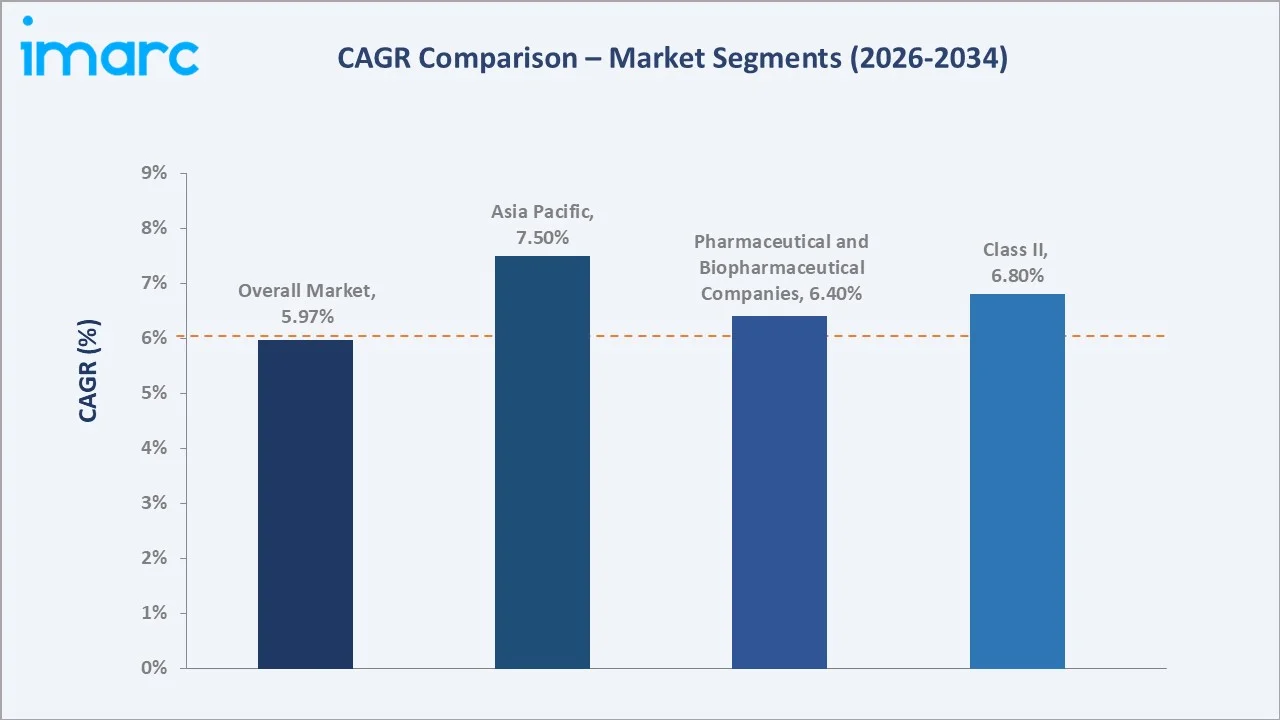
Asia Pacific is the fastest-growing region at ~7.50% CAGR, led by China, India, and South Korea expanding their biotech and pharmaceutical manufacturing capacity. Class II cabinets grow at ~6.80% CAGR as stricter chemical handling protocols require externally exhausted containment systems. Pharmaceutical and biopharmaceutical companies are growing at 6.40% CAGR.
Executive Summary
The global biological safety cabinet market is experiencing robust expansion, anchored by heightened global awareness of biosafety protocols, escalating pharmaceutical R&D expenditure, and increasing regulatory scrutiny around laboratory containment standards. The market growth underscores the sector's resilience and growing criticality in life sciences infrastructure.
Class II cabinets command a dominant 61.4% type share in 2025, favored for their dual-protection capability encompassing personnel, environment, and sample integrity through HEPA filtration and inward airflow design. Pharmaceutical and biopharmaceutical companies account for 46.8% of end-user demand, reflecting the integration of BSCs into drug discovery, sterile compounding, and biologic manufacturing workflows. North America leads with a 37.9% regional share in 2025, underpinned by the United States' extensive biomedical research ecosystem and stringent biosafety guidelines.
Key Market Insights
|
Insight |
Data |
| Largest Type |
Class II (61.4%, (2025) |
| Largest End-User |
Pharmaceutical and Biopharmaceutical Companies (46.8%, (2025) |
|
Leading Region |
North America (37.9%, (2025) |
|
Market Opportunity |
IoT-enabled smart BSCs and emerging market lab expansion |
Key Data-Driven Insights Shaping the BSC Market Landscape:
- Class II at 61.4%: Class II cabinets dominate, with Type A2 sub-variants accounting for the largest portion due to their versatility in pharmaceutical and research applications requiring both personnel and sample protection.
- Pharmaceutical and Biopharmaceutical Companies at 46.8%: Pharmaceutical and biopharmaceutical companies, reflecting the mandatory integration of certified containment equipment into GMP drug discovery, biologics manufacturing, and sterile processing workflows.
- North America at 37.9%: North America is supported by an extensive biomedical research ecosystem, stringent biosafety guidelines, and a well-developed network of pharmaceutical and contract research organizations.
Global Biological Safety Cabinet Market Overview
A biological safety cabinet is a ventilated, enclosed workspace engineered to protect laboratory personnel, the surrounding environment, and experimental samples from exposure to biological hazards including infectious agents, toxic compounds, and aerosolized pathogens. BSCs operate through HEPA or ULPA filtration systems that capture particles as small as 0.3 microns with high efficiency, providing controlled containment environments across three protection classes.
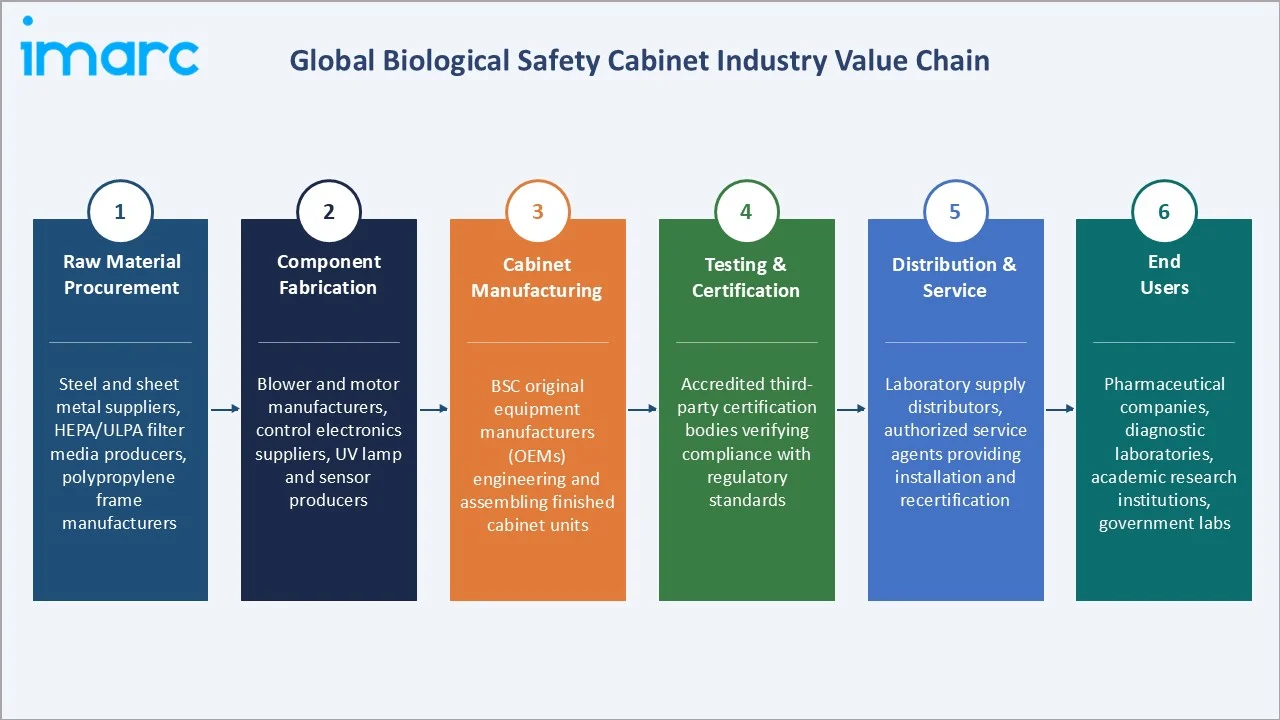
The ecosystem encompasses raw material suppliers (steel, HEPA filter media), cabinet manufacturers, certification bodies, and service networks providing installation, calibration, and maintenance. Macroeconomic factors including pandemic preparedness funding, pharmaceutical outsourcing trends, and government biosafety regulation upgrades shape demand dynamics globally.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
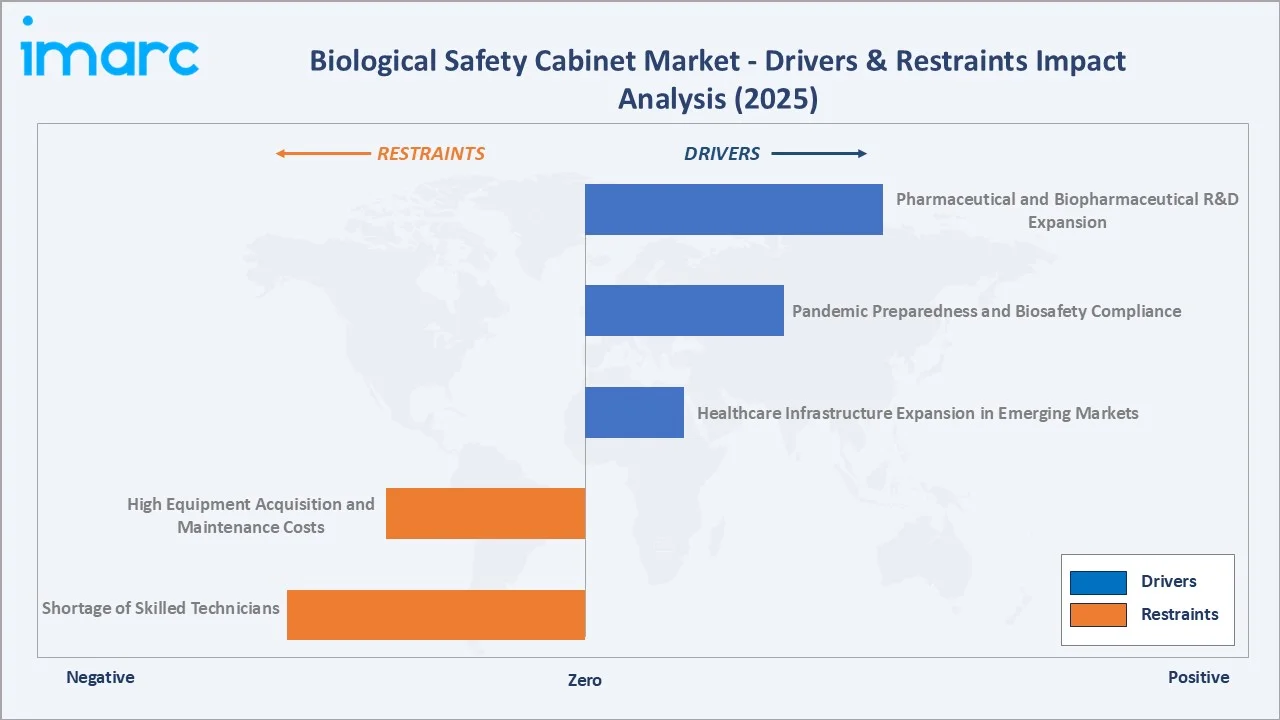
- Pharmaceutical and Biopharmaceutical R&D Expansion: Rising investment in biopharmaceutical research and drug development is driving sustained demand for certified biological safety cabinets across drug discovery, sterile manufacturing, and aseptic processing environments.
- Pandemic Preparedness and Biosafety Compliance: Heightened global awareness of biosafety risks following the COVID-19 pandemic has prompted governments and institutions to strengthen laboratory containment standards and upgrade existing safety infrastructure worldwide.
- Healthcare Infrastructure Expansion in Emerging Markets: According to the Economic Survey 2024–25, India’s public healthcare expenditure is projected at 1.9% of GDP in FY2025–26. Meanwhile, the healthcare sector attracted US$3.5 billion through 46 M&A transactions during FY2025–26. Emerging economies in Asia Pacific and Latin America are establishing new pharmaceutical manufacturing facilities, research institutions, and diagnostic laboratories, each requiring standardized BSC installations under WHO GMP guidelines.
Market Restraints
- High Equipment Acquisition and Maintenance Costs: High upfront acquisition costs for biological safety cabinets, particularly for Class III maximum containment models, create procurement barriers for smaller research institutions and diagnostic laboratories in price-sensitive markets.
- Shortage of Skilled Technicians: Proper BSC operation, decontamination, and annual recertification require trained laboratory personnel. A shortage of biosafety officers and qualified field service technicians in developing regions limits effective utilization and market penetration.
Market Opportunities
- Smart and Workflow-Optimized Biosafety Cabinets: In August 2024, Labconco introduced a redesigned Logic Biosafety Cabinet equipped with an upgraded operating system aimed at streamlining laboratory workflows. The new cabinet also incorporates enhanced safety, performance, and operational efficiency features to support modern laboratory environments. Growing demand for efficient, user-friendly, and digitally enabled laboratory solutions can support adoption across research institutions, pharmaceutical companies, hospitals, and biotechnology facilities.
- Gene Therapy and Advanced Biologics Research Growth: Accelerating biologics and gene therapy drug development is driving demand for specialized high-containment BSCs, as each advanced therapy program requires validated biological containment solutions throughout its development lifecycle.
Market Challenges
- Complex Multi-Standard Regulatory Compliance: Biological safety cabinets must comply with multiple overlapping standards and various national equivalents. Navigating divergent certification requirements across country-specific regulatory frameworks increases compliance complexity and market entry costs for manufacturers.
- Supply Chain Disruptions and Long Lead Times: Extended installation lead times for customized Class III cabinet configurations and supply chain disruptions affecting HEPA filter media and specialized electronic components create procurement delays for end users operating under time-sensitive research timelines.
Emerging Market Trends
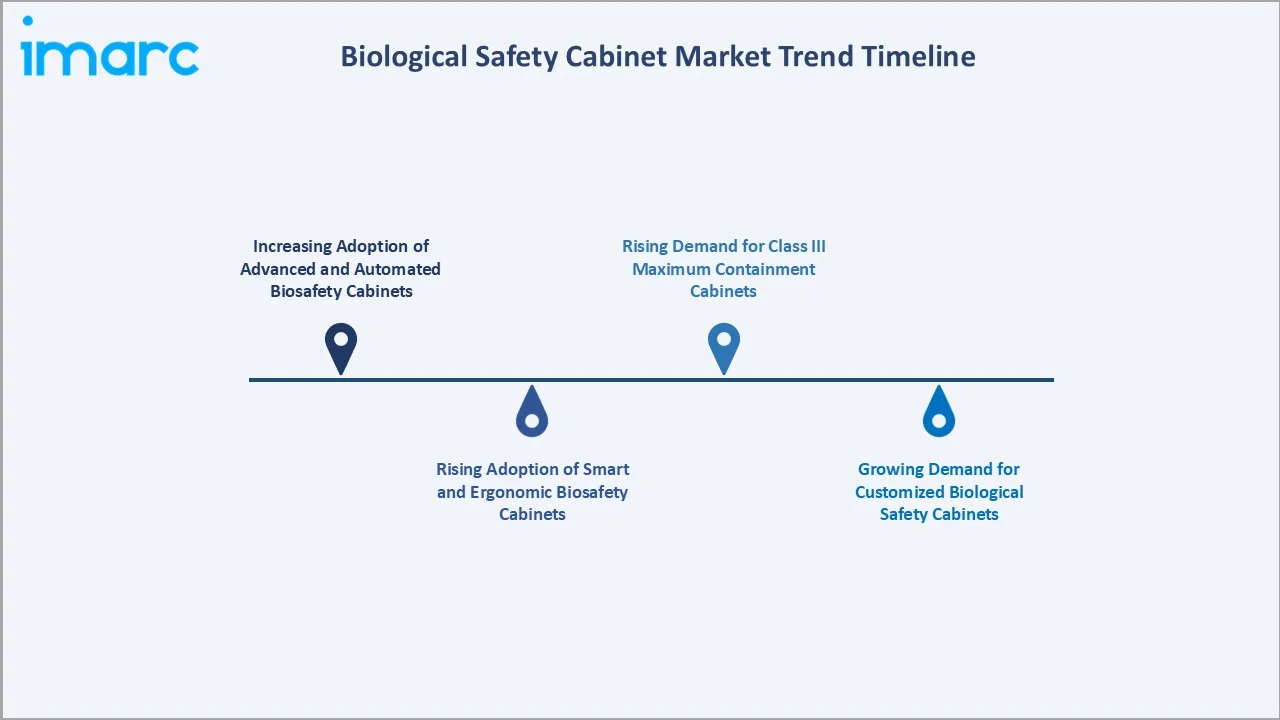
1. Increasing Adoption of Advanced and Automated Biosafety Cabinets
In October 2026, Piramal Pharma Solutions opened a new GMP microbiology laboratory and sterility testing suite at its sterile injectable facility in Lexington, Kentucky, as part of its US$85 million expansion. The facility includes a dedicated sterility testing isolator, three biosafety cabinets, and expanded laboratory capacity, while the broader commercial-scale manufacturing expansion is expected to be operational by late 2027. These innovations are helping laboratories enhance contamination control, operational efficiency, and user safety across pharmaceutical, biotechnology, healthcare, and research applications.
2. Rising Adoption of Smart and Ergonomic Biosafety Cabinets
Biological safety cabinet manufacturers are increasingly integrating advanced controls, ergonomic features, and user-friendly designs to improve laboratory safety and operational efficiency. In May 2025, Thermo Fisher introduced the Thermo Scientific 1500 Series Class II, Type A2 Biological Safety Cabinet (BSC), designed to deliver enhanced protection, ergonomic user comfort, and operational convenience. The cabinet is intended to support routine laboratory applications across academic, pharmaceutical, and biotechnology settings.
3. Rising Demand for Class III Maximum Containment Cabinets
Biosafety Level 3 (BSL-3) and BSL-4 research programs addressing high-consequence pathogens are driving demand for gas-tight Class III biological safety cabinets. Increasing government investment in high-containment biosafety laboratory construction globally is creating a growing procurement pipeline for Class III units, which represent the highest-value segment of the BSC product range.
4. Growing Demand for Customized Biological Safety Cabinets
Laboratories are increasingly seeking biological safety cabinets with flexible dimensions and customized configurations to suit specific workflows and space requirements. In February 2024, Nordic Labtech developed advanced laboratory containment solutions, including biological safety cabinets, fume hoods, and customized systems for pharmaceutical, biotechnology, healthcare, research, and other industries. The company expanded its BSC portfolio with the n-Safe Premium Class II Biological Safety Cabinets, available in sizes from 900 mm to 1,800 mm and customized configurations.
Industry Value Chain Analysis
The biological safety cabinet market value chain integrates multiple specialized stakeholders from raw material sourcing through end-user deployment. Upstream suppliers of HEPA filter media, steel, and electronic components feed into cabinet manufacturing, where engineering and certification value is added.
|
Stage |
Key Participants |
| Raw Material Procurement | Steel and sheet metal suppliers, HEPA/ULPA filter media producers, polypropylene frame manufacturers. |
| Component Fabrication | Blower and motor manufacturers, control electronics suppliers, UV lamp and sensor producers. |
| Cabinet Manufacturing | BSC original equipment manufacturers (OEMs) engineering and assembling finished cabinet units. |
| Testing & Certification | Accredited third-party certification bodies verifying compliance with regulatory standards. |
| Distribution & Service | Laboratory supply distributors, authorized service agents providing installation and recertification. |
| End Users | Pharmaceutical companies, diagnostic laboratories, academic research institutions, government labs. |
Cabinet manufacturing is the most value-added stage, as it integrates critical components such as HEPA/ULPA filters, blowers, control systems, sensors, and cabinet structures into a complete BSC. Engineering design, precision assembly, airflow optimization, and ergonomic features significantly enhance the product’s performance, safety, and overall value.
Technology Landscape in the Biological Safety Cabinet Industry
DC Brushless Motor and Variable Airflow Technology
Variable-speed DC brushless motors automatically adjust airflow velocity to compensate for filter loading, maintaining NSF-specified inflow velocity throughout cabinet life. This eliminates manual airflow adjustments, delivers meaningful energy savings versus traditional AC motor designs, and extends motor service life in high-utilization laboratory environments.
IoT Connectivity and Remote Monitoring
Cloud-connected BSCs transmit real-time performance data to laboratory information management systems (LIMS), enabling predictive filter replacement scheduling and automated compliance documentation. IoT-enabled cabinet fleets support reduced unplanned downtime and streamline annual recertification workflows for laboratory operators managing large installed bases.
Antimicrobial Surface Treatments and UV-C Integration
Antimicrobial worksurface materials and UV-C LED decontamination systems integrated into BSC interiors help reduce surface bioburden between experimental runs without the need for chemical decontamination cycles. Growing adoption of UV-C LED technology across laboratory equipment is driven by its germicidal effectiveness and the elimination of mercury-containing lamp disposal requirements.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Class II |
61.4% |
2025 |
| End User | Pharmaceutical and Biopharmaceutical Companies |
46.8% |
2025 |
|
Region |
North America |
37.9% |
2025 |

By Type
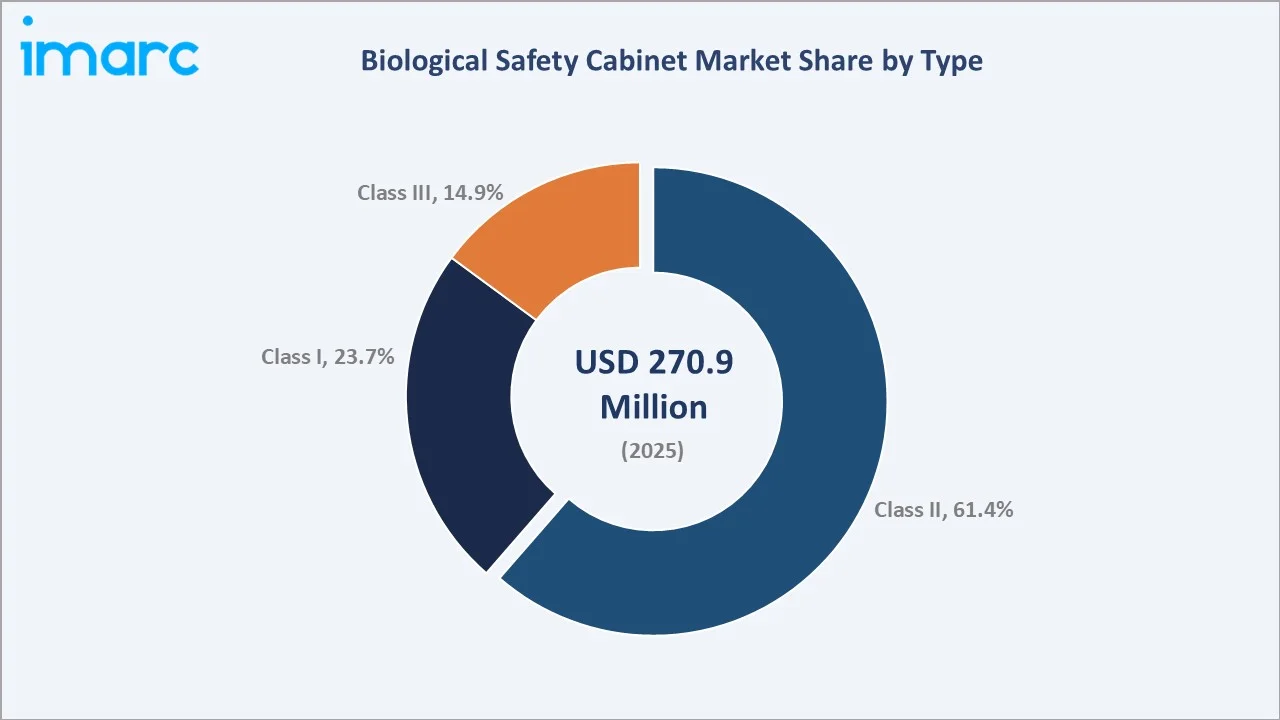
Class II cabinets represent the dominant segment with 61.4% market share in 2025, reflecting their widespread adoption across pharmaceutical manufacturing, cell culture, and virology research environments where dual personnel and sample protection are required.
To access detailed market analysis, Request Sample
Class I cabinets account for 23.7% of the market, serving laboratories requiring basic personnel and environmental protection without sample containment, including chemical fume handling and general BSL-2 work in academic and industrial settings. Class III at 14.9% share, driven by increasing global investment in high-containment biosafety laboratories and BSL-3 and BSL-4 research programs addressing emerging infectious diseases
By End User
Pharmaceutical and biopharmaceutical companies are the largest end-user segment, accounting for 46.8% of BSC demand in 2025. Diagnostic and testing laboratories represent 31.5% of end-user demand, driven by expanding clinical pathogen testing, food safety testing, and in vitro diagnostics development globally.
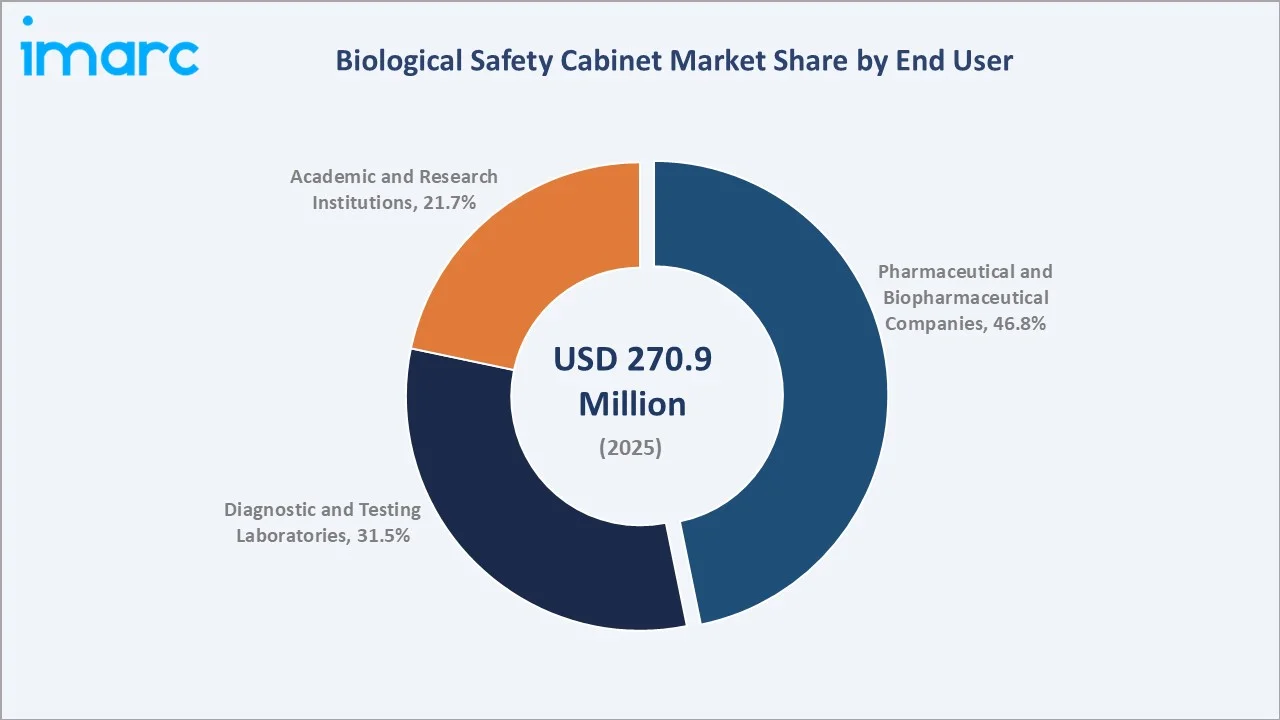
Academic and research institutions account for 21.7%, with consistent demand supported by government research funding, university life science programs, and grant-driven laboratory equipment procurement cycles that provide stable baseline demand.
Regional Market Insights
|
Region |
Share (2025) |
Key Characteristics |
| North America |
37.9% |
Mature pharmaceutical and biotech sector, stringent biosafety compliance requirements, well-established laboratory infrastructure. |
| Europe |
28.3% |
Strong pharmaceutical manufacturing base, robust regulatory framework, active life sciences research ecosystem. |
| Asia Pacific |
20.4% |
Fastest-growing region, rapid pharmaceutical capacity build-out in China and India, expanding research institution network. |
| Latin America |
7.6% |
Growing pharmaceutical manufacturing sector, increasing healthcare infrastructure investment, evolving biosafety regulations. |
| Middle East & Africa | 5.8% | Rising healthcare investment, laboratory infrastructure development, growing awareness of biosafety standards. |
North America holds the largest regional share at 37.9% in 2025, underpinned by its mature pharmaceutical and biomedical research ecosystem, extensive university laboratory networks, and stringent institutional biosafety compliance requirements. Europe follows with a 28.3% share, supported by a strong pharmaceutical manufacturing base, alongside a robust regulatory environment that mandates certified containment equipment in life sciences research facilities.
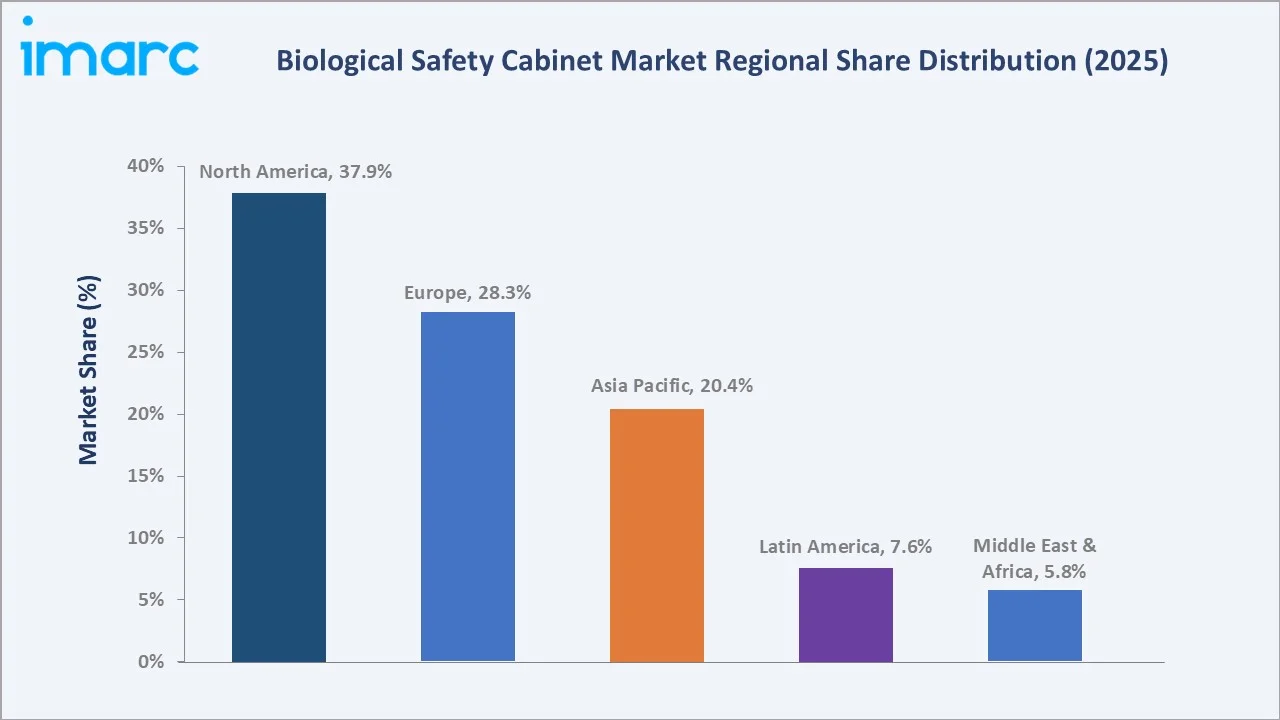
Asia Pacific represents 20.4% and is the fastest-growing region, with expanding pharmaceutical manufacturing capacity in China and India and rising laboratory infrastructure investment across Southeast Asian economies driving sustained demand. Latin America accounts for 7.6%, with growing pharmaceutical manufacturing activity and increasing healthcare infrastructure investment creating a developing demand base. The Middle East and Africa region holds a 5.8% share, with rising government healthcare investments and laboratory modernization initiatives gradually strengthening biosafety awareness and BSC procurement across the region.
Competitive Landscape
The global biological safety cabinet market exhibits moderate concentration. The market also hosts a tier of specialized regional manufacturers serving specific geographic and application niches.
|
Company |
Key Brands |
Market Position |
Core Strength |
| Thermo Fisher Scientific Inc. | 1300 Series, 1500 Series, Herasafe 2030i Class II A2 Biological Safety Cabinet |
Market Leader |
Thermo Fisher Scientific Inc. designs, manufactures, and supplies Class II and specialized biological safety cabinets (BSCs). |
| Labconco Corporation | Logic Class II, Type B2 Biosafety Cabinets, Axiom Class II, Type C1 Biosafety Cabinets, Cell Logic Class II, Type A2 Biosafety Cabinets | Market Leader | Labconco Corporation has been a leading manufacturer and innovator in biological safety cabinets (BSCs). |
| Esco Lifesciences Group | Airstream Class I Biological Safety Cabinet, Labculture G4 Class II Type A2 Biological Safety Cabinet, Airstream Class III Biological Safety Cabinet | Established Player | Esco Lifesciences Group designs, manufactures, and services Biological Safety Cabinets (BSCs) that protect laboratory personnel, research samples, and the surrounding environment from biohazards. |
| Biobase Group | Class I Biological Safety Cabinet, NSF Certified Class II A2 Biological Safety Cabinet, EN Certified Biological Safety Cabinet |
Challenger |
The BIOBASE Group manufactures and supplies primary containment equipment designed to protect laboratory personnel, experimental samples, and the surrounding environment. |
| Berner International GmbH | Safety cabinet class II claire neo, Safety cabinet class II claire neo xl, Safety cabinet class II claire lh | Established Player | Berner International GmbH is a manufacturer and developer of pharmaceutical and biotechnological protection systems, specializing in biological safety cabinets (BSCs). |
The competitive landscape reflects a market where established leaders maintain advantage through global service networks, broad product portfolios, and deep regulatory expertise, while challenger brands compete on pricing, regional manufacturing proximity, and application-specific customization. Innovation in IoT connectivity and energy-efficient cabinet design is increasingly becoming a key differentiator among mid-tier and premium manufacturers seeking to command higher average selling prices in developed market segments.
Key Company Profiles
Thermo Fisher Scientific Inc.
Thermo Fisher Scientific is the market leader in biological safety cabinets, with a comprehensive BSC portfolio spanning all three protection classes and a broad range of configurations suited to pharmaceutical, research, and clinical laboratory applications. The company leverages its global service organization to provide installation qualification, annual certification, and preventive maintenance services that generate recurring revenue and support long-term customer relationships. Its integrated laboratory solutions portfolio and digital connectivity capabilities reinforce its technology leadership position in the premium BSC segment.
- Key Offerings: 1300 Series, 1500 Series, Herasafe 2030i Class II A2 Biological Safety Cabinet.
- Strategic Focus: Broadening digital service offerings, expanding presence in pharmaceutical CDMO and bioprocessing laboratory segments, and strengthening global distribution and service network
Labconco Corporation
Labconco Corporation is a long-established manufacturer of biological safety cabinets with a strong heritage of engineering innovation and product reliability. The company has built its reputation on energy-efficient cabinet designs incorporating DC brushless motor technology that reduces energy consumption while maintaining performance standards. Labconco holds strong market share in the North American academic and pharmaceutical research segments and is recognized for consistent product quality and high customer satisfaction driven by its engineering-focused organizational culture.
- Key Offerings: Logic Class II, Type B2 Biosafety Cabinets, Axiom Class II, Type C1 Biosafety Cabinets, Cell Logic Class II, Type A2 Biosafety Cabinets
- Strategic Focus: Advancing smart cabinet connectivity features, maintaining engineering quality leadership in the North American market, targeting pharmaceutical and research laboratory segments with premium product differentiation.
Market Concentration Analysis
The biological safety cabinet market demonstrates moderate concentration, with the top five players, Thermo Fisher Scientific Inc., Labconco Corporation, Esco Lifesciences Group, Biobase Group, and Berner International GmbH collectively holding approximately 55-60% of global revenue in 2025. The remaining 40-45% is distributed among regional and niche manufacturers.
The market is consolidating as large players acquire regional specialists to expand geographic reach and technology capabilities. However, the market remains competitive due to strong regional preferences, differing certification requirements across geographies, and the technical specialization required for Class III maximum containment configurations, which smaller niche manufacturers serve effectively.
Investment & Growth Opportunities
Fastest Growing Segments
Class II cabinets are growing at ~6.80% CAGR. Pharmaceutical and biopharmaceutical companies are growing at 6.40% CAGR. Asia Pacific region is growing at ~7.5% CAGR as China, India, and Southeast Asian nations invest in pharmaceutical self-sufficiency and research infrastructure.
Investment Themes
- Smart Cabinet Technology: IoT connectivity, cloud-based performance monitoring, and predictive maintenance platforms represent the most compelling technology investment theme, enabling manufacturers to differentiate on digital services and command premium pricing in developed markets.
- Emerging Market Expansion: Emerging market laboratory infrastructure build-out across Southeast Asia, Africa, and Latin America presents a long-term volume growth opportunity for manufacturers with cost-competitive product offerings and established distribution networks in these regions.
- Advanced Research Biosafety Demand: Growing demand for gene therapy, advanced biologics, and high-containment pathogen research is creating sustained demand for specialized Class III and customized Class II B2 cabinets, representing a high-value niche investment opportunity for technically capable manufacturers.
Future Market Outlook (2026-2034)
The global biological safety cabinet market grew from USD 270.9 Million in 2025 to USD 287.0 Million in 2026 and is projected to reach USD 463.8 Million by 2034, exhibiting a CAGR of 5.97% during 2026-2034. This sustained growth trajectory reflects the structural integration of biological safety cabinets into pharmaceutical manufacturing, clinical diagnostics, and academic research workflows globally. Pandemic preparedness investments and evolving biosafety regulations will continue to embed BSC procurement as a compliance-driven, non-discretionary expenditure across institutional laboratory operators.
Three structural forces will define the biological safety cabinet market through 2034. First, deepening integration of digital connectivity and IoT-enabled monitoring into cabinet design will progressively shift competitive differentiation from hardware specifications to software-driven service capabilities, rewarding manufacturers that invest in cloud platforms and data analytics. Second, the continued expansion of pharmaceutical manufacturing and clinical research infrastructure across emerging economies will drive volume growth at the base of the market, requiring suppliers to offer regionally certified, cost-optimized product lines. Third, the escalation of high-containment biosafety research programs globally will sustain premium demand for specialized Class III and customized Class II B2 configurations, supporting a bifurcated market structure serving both volume and value segments simultaneously.
Research Methodology
Primary Research
Primary research involved structured interviews with BSC manufacturers, laboratory managers, procurement officers, biosafety officers, and industry consultants across North America, Europe, and Asia Pacific. Over 150 primary interactions informed market sizing, competitive positioning, technology assessments, and demand-side dynamics, including procurement cycles and product selection criteria.
Secondary Research
Secondary research encompassed regulatory filings, patent databases, company annual reports, certification records, scientific journals, trade association publications, government biosafety laboratory construction data, and pharmaceutical industry investment reports.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches. Bottom-up analysis aggregated demand across end-user segments, product types, and geographies. Top-down validation cross-referenced total addressable market estimates against pharmaceutical industry capital expenditure trends and laboratory infrastructure investment data. CAGR projections incorporate regulatory scenario analysis and technology adoption rate assumptions validated through primary interviews.
Biological Safety Cabinet Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Class I, Class II, Class III |
| End Users Covered | Pharmaceutical and Biopharmaceutical Companies, Diagnostic and Testing Laboratories, Academic and Research Institutions |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Companies Covered | Thermo Fisher Scientific Inc., Labconco Corporation, Esco Lifesciences Group, Biobase Group, Berner International GmbH, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the Biological Safety Cabinet Market Report
The global BSC market reached USD 287.0 Million in 2026, supported by pharmaceutical R&D expansion, biosafety regulation upgrades, and rising infectious disease research investments worldwide.
The market is projected to grow at a CAGR of 5.97% during 2026-2034, reaching USD 463.8 Million by 2034, driven by pharmaceutical sector growth and laboratory infrastructure modernization.
The BSC market is forecast to reach USD 463.8 Million by 2034, as pharmaceutical manufacturing, diagnostics, and research laboratory investments accelerate globally.
Class II cabinets dominate with 61.4% market share in 2025, favored for their dual protection of personnel, environment, and samples through HEPA filtration in pharmaceutical and research applications.
Pharmaceutical and biopharmaceutical companies represent 46.8% of BSC end-user demand in 2025, driven by GMP manufacturing requirements, expanding biologic pipelines, and CDMO capacity growth.
North America leads with 37.9% market share in 2025, driven by the United States' extensive biomedical research ecosystem, NIH funding, and stringent biosafety compliance requirements.
Asia Pacific is the fastest-growing region at 7.50% CAGR, led by China and India expanding domestic pharmaceutical manufacturing and government laboratory infrastructure investments.
Key players include Thermo Fisher Scientific Inc., Labconco Corporation, Esco Lifesciences Group, Biobase Group, and Berner International GmbH, among others.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade