
Europe Virtual Reality Gaming Market Size, Share, Trends and Forecast by Segment, Device, Age Group, Types of Games, and Country, 2026-2034
Europe Virtual Reality Gaming Market Size, Share, Trends & Forecast (2026-2034)
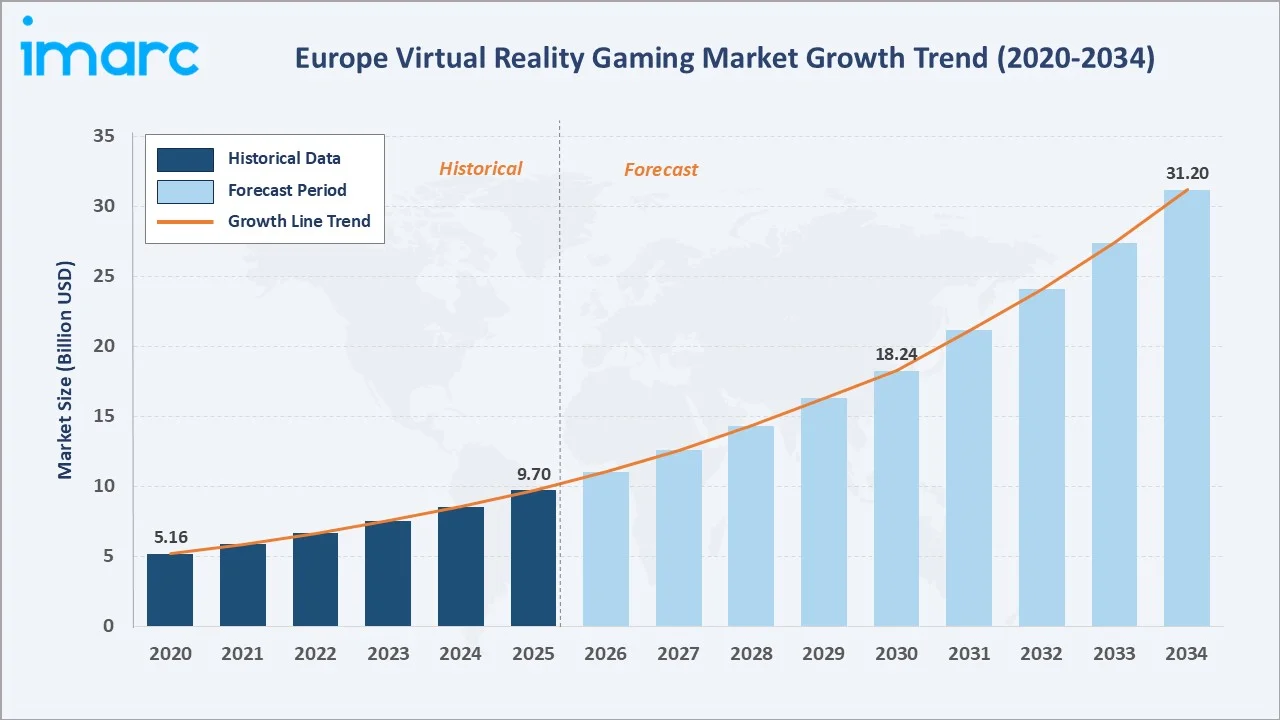
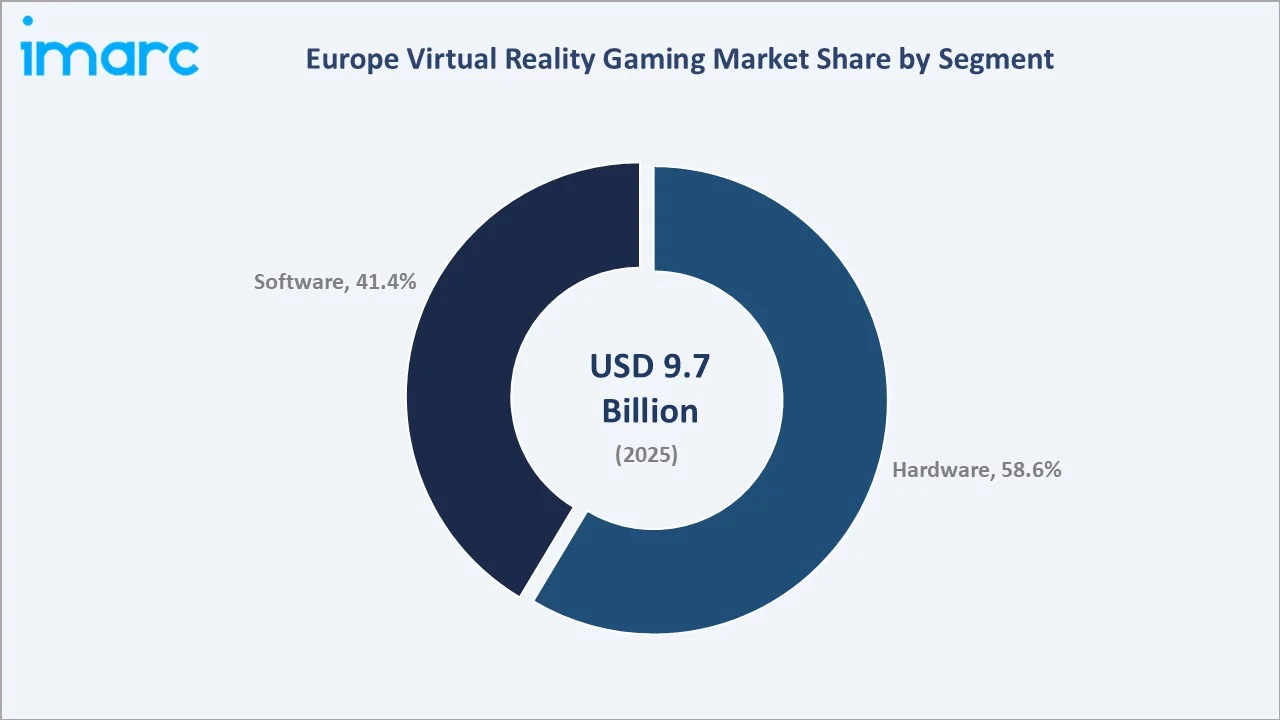
The Europe virtual reality gaming market grew from USD 9.7 Billion in 2025 to USD 11.4 Billion in 2026 and is projected to reach USD 31.2 Billion by 2034, growing at a CAGR of 13.45% during 2026-2034. The market is driven by growing consumer demand for immersive entertainment experiences, rapid advancements in VR hardware technology, and expanding enterprise applications. Broadband connectivity and 5G networks enhance VR streaming quality. Hardware leads at 58.6%. Adults account for 68.3% of the market. Germany commands 28.5% of the country share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 9.7 Billion |
|
Market Size (2026) |
USD 11.4 Billion |
|
Forecast Market Size (2034) |
USD 31.2 Billion |
|
CAGR (2026-2034) |
13.45% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Segment |
Hardware (58.6%, 2025) |
|
Dominant Age Group |
Adults (68.3%, 2025) |
|
Leading Country |
Germany (28.5%, 2025) |
The Europe virtual reality gaming market expanded from USD 5.16 Billion in 2020 to USD 9.7 Billion in 2025, reaching USD 11.4 Billion in 2026, anchored at USD 18.24 Billion in 2030, and forecast to reach USD 31.2 Billion by 2034. COVID-19 accelerated VR gaming adoption in 2020 as lockdowns drove demand for immersive home entertainment across Europe. Post-pandemic momentum has sustained above-trend market growth through 2022-2025.
To get more information on this market, Request Sample
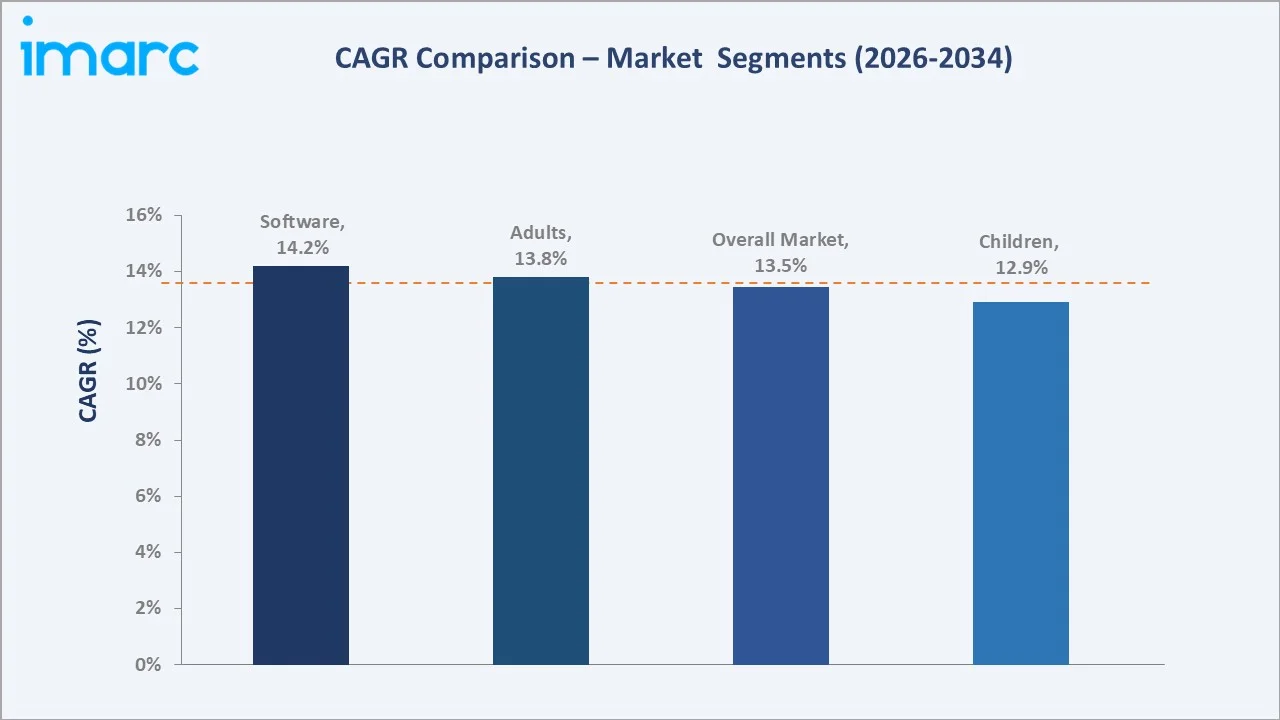
The software segment grows fastest at ~14.2% CAGR as expanding VR content libraries, subscription services, and cross-platform gaming drive sustained demand. Hardware grows at ~12.7% CAGR through continuous technological improvements and price reductions making VR gaming accessible to broader consumer segments across Europe.
Executive Summary
The Europe virtual reality gaming market reached USD 9.7 Billion in 2025 to an estimated USD 11.4 Billion in 2026, representing one of the most dynamic and fastest-growing segments in the broader digital entertainment landscape. The market encompasses VR headsets, motion controllers, haptic accessories, VR game software, platform subscriptions, and enterprise VR applications across gaming-adjacent sectors.
Hardware at 58.6% dominates through the essential nature of headset investment in enabling VR experiences. Adults at 68.3% lead adoption driven by higher purchasing power and gaming engagement. Germany, at 28.5%, leads through its large gaming community, strong technology adoption culture, and robust digital infrastructure enabling broad VR distribution.
Key Market Insights
|
Insight |
Data |
|
Dominant Segment |
Hardware - 58.6% share (2025) |
|
Dominant Age Group |
Adults - 68.3% market share (2025) |
|
Leading Country |
Germany - 28.5% market share |
|
Market Opportunity |
Enterprise VR adoption; AI-enhanced gaming; cloud VR streaming; social virtual worlds; metaverse content development |
Key Analytical Observations Supporting the Above Data:
- Hardware at 58.6%: The hardware segment dominates due to the fundamental requirement for VR headsets, controllers, and accessories to enable immersive gaming experiences. Rapid innovation, price reductions, and improving specifications are driving wider consumer adoption across European markets.
- Adults at 68.3%: Adults lead VR gaming through higher discretionary income for premium hardware investments, greater familiarity with gaming ecosystems, and stronger engagement with both consumer and enterprise VR applications across professional and entertainment contexts.
- Germany at 28.5%: Germany leads the European VR gaming market due to its large and engaged gaming population, high technology adoption rates, strong e-sports culture, and robust digital retail infrastructure enabling broad VR hardware and software distribution.
Europe Virtual Reality Gaming Market Overview
The Europe virtual reality gaming market encompasses the hardware, software, and services that enable immersive gaming experiences through virtual reality technology. The market covers standalone and PC-tethered VR headsets, motion controllers, haptic feedback devices, VR game titles, platform subscriptions, and enterprise gaming applications.
Macroeconomic factors include rising consumer spending on digital entertainment, growing broadband and 5G infrastructure investment, and increasing corporate adoption of VR for training and simulation. Additionally, government digital economy initiatives and strong European gaming culture are accelerating market development.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
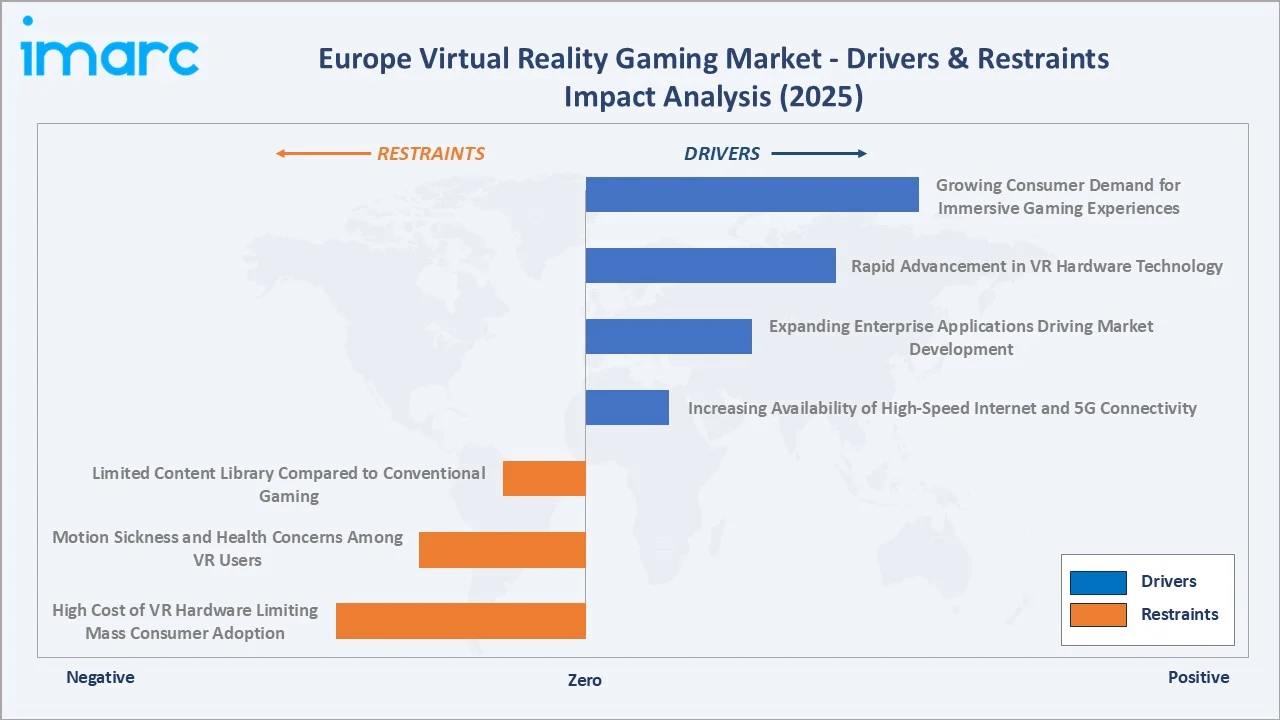
- Growing Consumer Demand for Immersive Gaming Experiences: Consumer appetite for deeply immersive and interactive entertainment is accelerating VR gaming adoption across Europe. Advanced VR platforms deliver unprecedented levels of presence and interactivity that traditional flat-screen gaming cannot replicate. In March 2026, Meta announced exclusive European content partnerships with leading game studios, expanding its Quest library with region-specific VR titles and attracting new consumer segments to the VR gaming ecosystem.
- Rapid Advancement in VR Hardware Technology: Continuous improvements in display resolution, processing power, battery life, and ergonomics are making VR headsets more compelling and accessible. Standalone wireless headsets eliminate PC dependency barriers, dramatically expanding the addressable consumer market. Lighter form factors, improved refresh rates, and eye-tracking capabilities enhance comfort and visual quality, converting previously reluctant consumers and creating upgrade cycles among early adopters.
- Expanding Enterprise Applications Driving Market Development: The growing adoption of VR technology in enterprise training, healthcare simulation, architectural visualization, and employee engagement is expanding the overall VR market. Enterprise VR generates revenue across both hardware and software segments while validating VR technology credibility to consumer audiences. In February 2026, European automotive manufacturers expanded VR-based engineering training programs significantly, increasing enterprise headset deployments.
- Increasing Availability of High-Speed Internet and 5G Connectivity: The expansion of 5G networks and high-speed broadband across Europe is enabling cloud VR streaming and reducing hardware requirements for immersive experiences. Enhanced connectivity reduces latency in wireless VR gaming and enables new streaming-based VR service models. Major European telecom operators are partnering with VR content providers to bundle cloud VR gaming with 5G subscriptions, driving user acquisition.
Market Restraints
- High Cost of VR Hardware Limiting Mass Consumer Adoption: Premium VR headsets and associated computing hardware represent a significant financial barrier for many European consumers. The combined cost of a high-end VR headset, compatible PC or console, and essential software can exceed consumer entertainment budgets, limiting market penetration among lower-income demographics and restricting VR gaming to higher-income segments in European markets.
- Motion Sickness and Health Concerns Among VR Users: Cybersickness, eye strain, and disorientation effects experienced by a subset of VR users create barriers to adoption and limit session durations. Health concerns around prolonged VR use, particularly for younger users, prompt parental restrictions and regulatory attention, constraining market growth by deterring potential users and limiting daily engagement hours that drive software and subscription revenue.
- Limited Content Library Compared to Conventional Gaming: Despite growth, the VR game library remains substantially smaller than traditional gaming platform catalogs. Limited AAA VR title availability constrains consumer motivation to invest in VR hardware. High development costs and uncertain return on investment deter some major studios from prioritizing VR-native titles, creating a content-hardware investment cycle challenge that slows mainstream adoption.
Market Opportunities
- Enterprise VR Adoption Expanding Across European Sectors: Growing corporate investment in VR-based training, simulation, and collaboration platforms represents a significant revenue opportunity. European manufacturing, healthcare, education, and defense sectors are accelerating VR training deployment for professional skill development and operational efficiency improvements across the continent.
- Cloud VR Gaming and Streaming Service Models: The emergence of cloud-based VR gaming services reduces hardware barriers by enabling high-fidelity VR experiences on lower-specification devices. Subscription-based cloud VR gaming models create recurring revenue streams and expand market accessibility to consumers who cannot justify premium hardware investments.
Market Challenges
- Content Fragmentation Across Competing VR Platforms: The division of VR gaming content across incompatible proprietary platforms creates ecosystem fragmentation that confuses consumers and limits cross-platform content investment. Exclusive content strategies create switching costs and complicate developer portfolio decisions, potentially slowing overall market growth across European gaming markets.
- Regulatory Complexity Around VR Health and Data Privacy: The European regulatory environment, particularly GDPR compliance for biometric data collected by eye-tracking and physiological sensors, creates compliance complexity for manufacturers and developers. Emerging regulations around VR use by minors and health data protection requirements increase operational costs and market entry barriers.
Emerging Market Trends
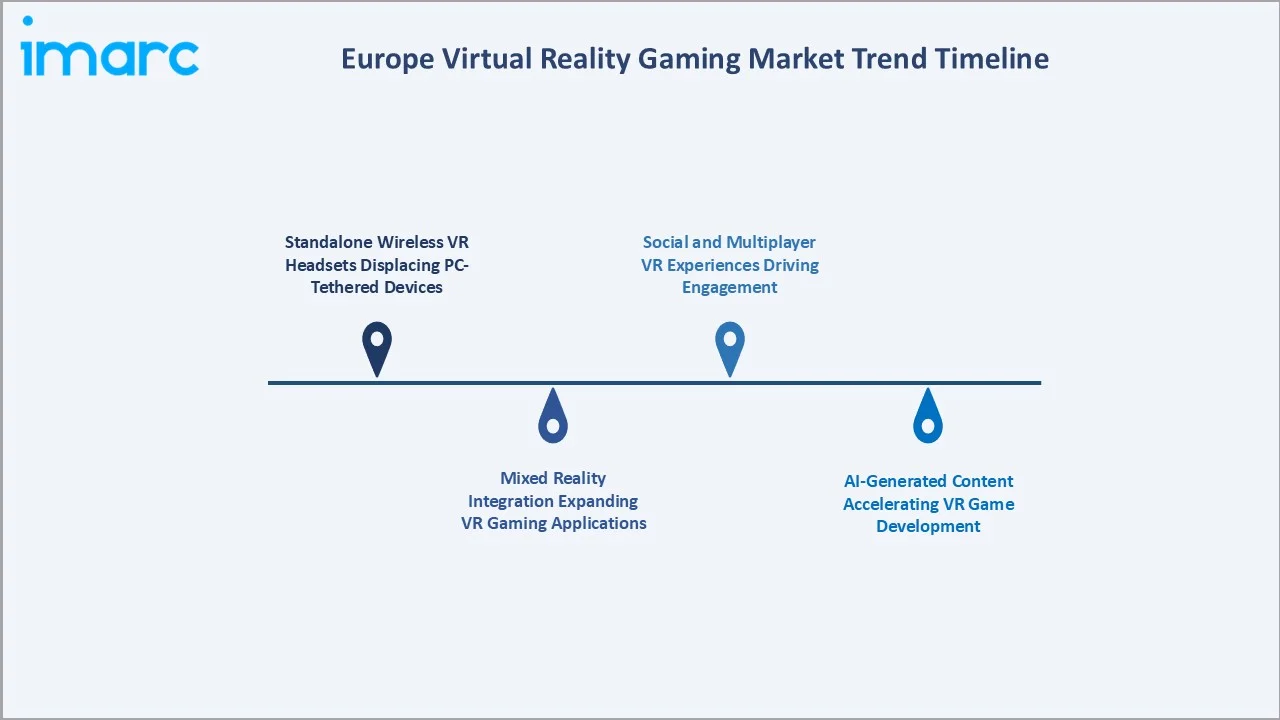
1. Standalone Wireless VR Headsets Displacing PC-Tethered Devices
Standalone VR headsets with on-device processing are rapidly displacing PC-tethered devices as the dominant hardware form factor. This shift eliminates the need for dedicated gaming PCs, dramatically reducing total system cost and setup complexity. Market leaders are investing heavily in standalone processing capability improvements that close the performance gap with PC VR, expanding the addressable consumer market beyond early adopter demographics.
2. Social and Multiplayer VR Experiences Driving Engagement
Social VR platforms and multiplayer gaming environments are emerging as key engagement drivers for VR gaming retention. Virtual social spaces combining gaming, communication, and shared entertainment experiences increase daily active usage and reduce churn. European developers are creating culturally relevant social VR experiences tailored to regional gaming preferences, transforming VR from a solo entertainment device into a shared interactive platform.
3. Mixed Reality Integration Expanding VR Gaming Applications
The integration of mixed reality capabilities, overlaying virtual elements onto real-world environments, is expanding VR gaming applications beyond fully immersive experiences. Mixed reality gaming creates new genres blending physical and virtual interaction, attracting users who previously found full VR immersion uncomfortable. In January 2026, Sony unveiled enhanced mixed reality features for PSVR2, expanding its European gaming application portfolio significantly.
4. AI-Generated Content Accelerating VR Game Development
Artificial intelligence tools are reducing VR game development costs and accelerating content creation timelines, directly addressing the limited content library challenge. AI-powered procedural generation creates expansive VR environments and adaptive gameplay without proportionally increasing development budgets. This technology democratizes VR game development, enabling smaller European studios to produce high-quality VR content that previously required major publisher resources.
Industry Value Chain Analysis
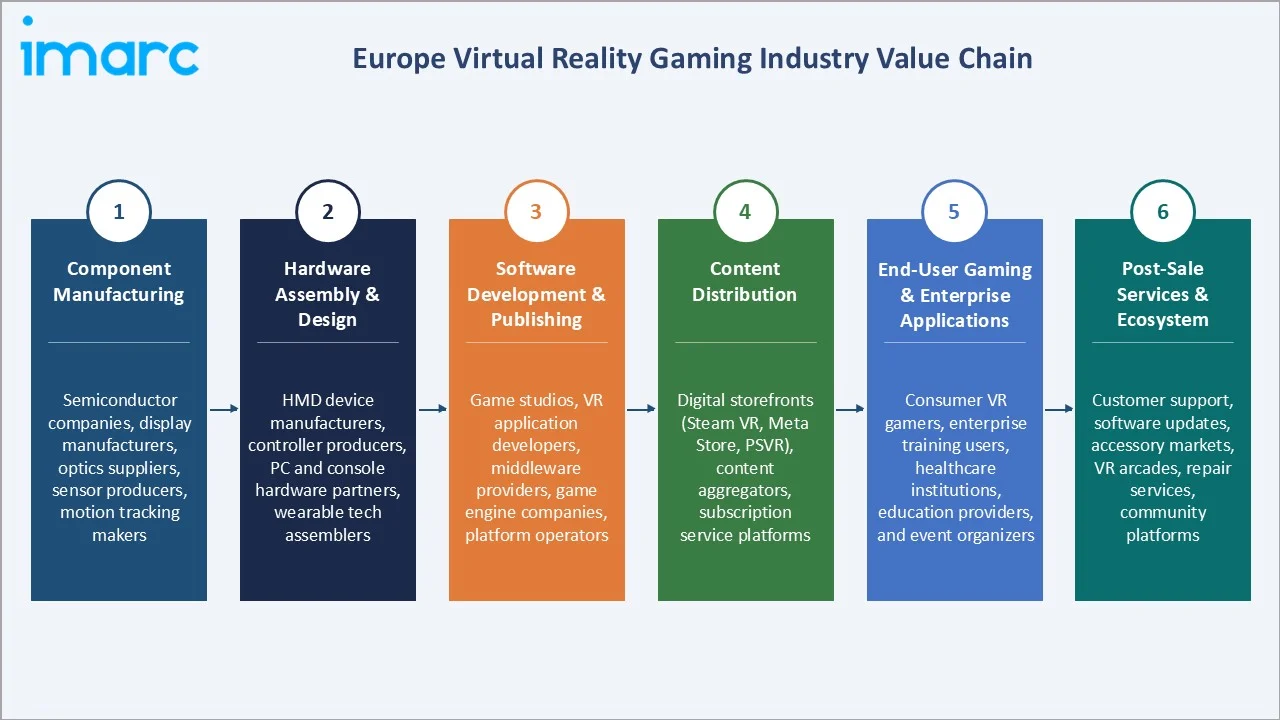
The Europe virtual reality gaming industry value chain integrates component manufacturing, hardware assembly and design, software development and publishing, content distribution, end-user gaming and enterprise applications, and post-sale services and ecosystem support.
| Value Chain Stage | Key Participants |
| Component Manufacturing | Semiconductor companies, display manufacturers, optics suppliers, sensor producers, and motion tracking component makers |
| Hardware Assembly & Design | HMD device manufacturers, controller producers, PC and console hardware partners, and wearable technology assemblers |
| Software Development & Publishing | Game studios, VR application developers, middleware providers, game engine companies, and platform operators |
| Content Distribution | Digital storefronts (Steam VR, Meta Store, PSVR), content aggregators, and subscription service platforms |
| End-User Gaming & Enterprise Applications | Consumer VR gamers, enterprise training users, healthcare institutions, education providers, and event organizers |
| Post-Sale Services & Ecosystem | Customer support, software updates, accessory markets, VR arcades, repair services, and community platforms |
The software development and publishing stage is the value chain's most commercially dynamic and margin-rich phase. The content distribution layer creates platform dependency and ecosystem lock-in generating ongoing revenue through marketplace commissions and subscription fees. Post-sale services and community ecosystems sustain long-term user engagement and retention.
Technology Landscape in the Europe Virtual Reality Gaming Industry
Head-Mounted Display (HMD) Technology
Modern VR headsets utilize micro-OLED and LCD panel technologies delivering high resolutions and wide field-of-view optics. Pancake lens systems reduce headset thickness while maintaining optical quality. Inside-out tracking systems using onboard cameras eliminate external sensor requirements. These technical advances are improving user comfort, reducing setup complexity, and enhancing visual immersion across both standalone and PC-tethered VR gaming platforms.
Haptic Feedback and Controller Technology
Advanced haptic feedback systems in VR controllers deliver nuanced tactile sensations that increase immersion and gameplay realism. Adaptive trigger mechanisms providing variable resistance feedback enhance gaming interaction authenticity. Hand-tracking capabilities using optical sensors enable controller-free VR interaction. These controller innovations expand interaction possibilities and attract gaming audiences seeking experiences beyond conventional gamepad interfaces.
Eye-Tracking and Foveated Rendering
Eye-tracking technology enables foveated rendering, concentrating processing resources on the specific area of the display where the user is looking. This optimization dramatically improves rendering efficiency, enabling higher visual quality on given hardware specifications. Eye-tracking also enables new interaction paradigms and accessibility features, expanding VR gaming to users with physical limitations restricting conventional controller use.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Segment | Hardware | 58.6% | 2025 |
| Device |
Personal Computers |
🔒 |
2025 |
| Age Group | Adults | 68.3% | 2025 |
| Types of Games | Shooting | 🔒 | 2025 |
| Country | Germany | 28.5% | 2025 |

By Segment
Hardware leads at 58.6% (2025), growing at a CAGR of ~12.7% during 2026-2034. The hardware segment encompasses standalone VR headsets, PC-tethered headsets, gaming consoles with VR capability, motion controllers, haptic accessories, and peripheral tracking equipment. Continuous improvements in processing power, display resolution, and form factor are driving both new user adoption and upgrade cycles among existing VR gamers across Europe.
To access detailed market analysis, Request Sample
Software accounts for 41.4% (2025), growing at a faster CAGR of ~14.2% during 2026-2034, outpacing hardware growth. The software segment encompasses VR game titles, platform subscriptions, enterprise VR applications, in-game purchases, and software development tools. The expanding headset install base is accelerating content demand, and rising subscription-based revenue models are creating predictable recurring income streams for platform operators and publishers.
By Age Group
Adults lead at 68.3% (2025), growing at a CAGR of ~13.8% during 2026-2034. The adults segment encompasses consumers aged 18 and above who represent the primary VR gaming demographic due to higher disposable income, stronger gaming engagement histories, and greater comfort with technology investment. Adult adoption spans casual gaming, enthusiast gaming, and enterprise VR applications across professional and entertainment contexts.
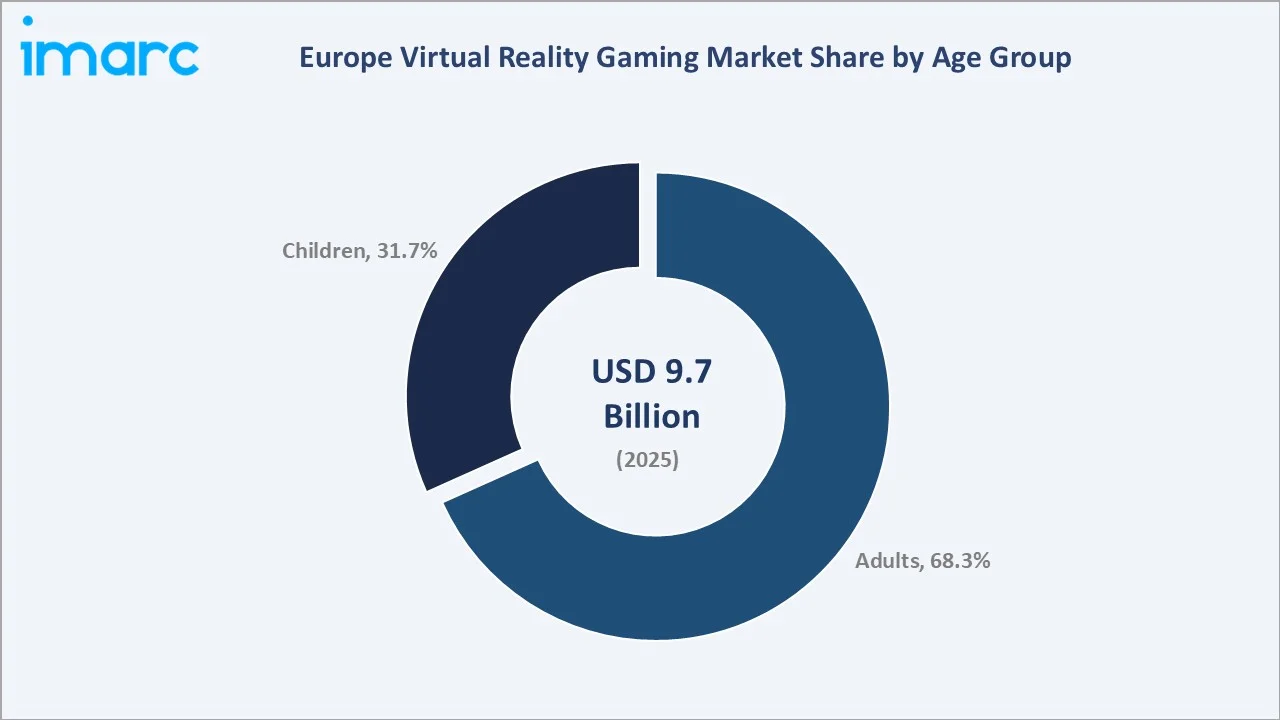
Children account for 31.7% (2025), growing at a CAGR of ~12.9% during 2026-2034. The children segment is driven by parental purchase decisions expanding VR gaming to younger demographics. Content tailored for younger audiences, educational VR applications, and family-oriented gaming experiences are expanding the addressable market. Health guideline considerations and content curation requirements create both regulatory challenges and specialized development opportunities.
Regional Market Insights
| Country |
Share (2025) |
Key Europe VR Gaming Market Drivers & Characteristics |
| Germany | 28.5% | Driven by a strong gaming culture, high disposable income, and early adoption of immersive entertainment technologies including VR gaming platforms. |
| United Kingdom | 23.1% | Supported by a large gaming community, advanced digital infrastructure, and growing enterprise VR adoption across professional sectors. |
| France | 18.7% | Driven by increasing consumer spending on entertainment technology, strong gaming culture, and rising enterprise VR applications in automotive and aerospace. |
| Italy | 12.6% | Supported by growing youth gaming demographics, increasing digital entertainment penetration, and expanding VR content availability across platforms. |
| Spain | 9.4% | Driven by rising internet penetration, increasing gaming adoption among youth, and growing VR arcade and enterprise applications across industries. |
| Others | 7.7% | Includes Netherlands, Poland, Sweden, and other European markets with growing VR adoption and expanding digital and 5G infrastructure. |
Germany's 28.5% market leadership reflects its large and deeply engaged gaming culture, extensive digital retail infrastructure, and strong consumer spending on entertainment technology. The United Kingdom's 23.1% represents a sophisticated gaming market with high broadband penetration and strong enterprise VR adoption across professional sectors.
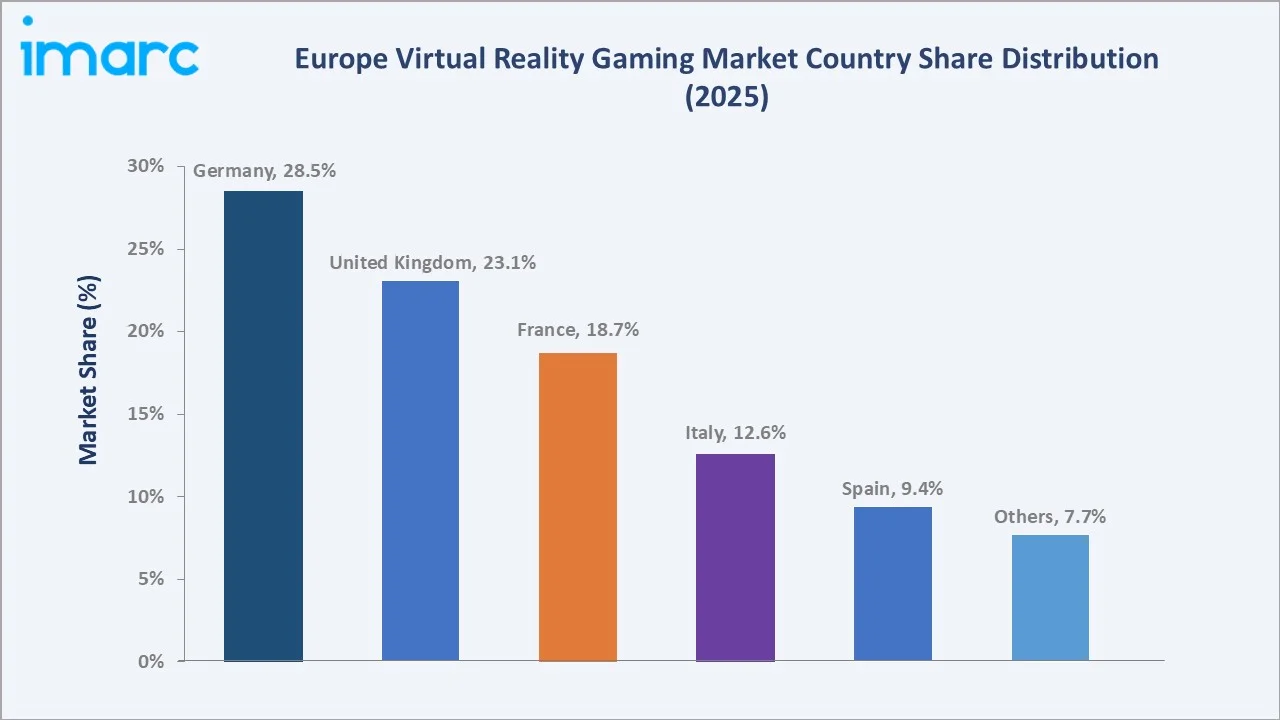
France's 18.7% encompasses a growing gaming community and increasing enterprise VR adoption in automotive and aerospace sectors. Italy and Spain represent emerging VR markets with growing youth gaming demographics and expanding digital infrastructure that will support accelerating VR adoption through 2034.
Competitive Landscape
The Europe virtual reality gaming market competitive landscape encompasses distinct tiers: global VR platform leaders, standalone headset manufacturers, PC VR specialists, content publishers, and enterprise VR solution providers operating across consumer and professional segments.
|
Company Name |
Key Products | Market Position | Core Strength |
| Meta Platforms, Inc. (Oculus) | Meta Quest 3, Meta Quest Pro, Quest 2 | Market Leader | Meta leads VR gaming by delivering affordable standalone HMD solutions and a robust content ecosystem through its Meta Horizon Store, driving mainstream VR adoption across European markets. |
| Sony Interactive Entertainment LLC | PlayStation VR2, PlayStation VR | Market Leader | Sony dominates console-based VR gaming through its PSVR2 platform, leveraging its vast PlayStation user base and exclusive AAA VR game titles to capture European console gaming audiences. |
| Valve Corporation | Valve Index, SteamVR Platform | Market Leader | Valve drives PC VR gaming through its Steam platform, offering the largest VR game library and supporting multiple headsets through its open SteamVR runtime for enthusiast gamers. |
| HTC Corporation | VIVE XR Elite, VIVE Pro 2, VIVE Focus 3 | Established Player | HTC serves enterprise and consumer VR through its VIVE product lineup, focusing on standalone and PC-tethered high-fidelity experiences for gaming and professional applications. |
| ByteDance Ltd. (Pico) | Pico 4, Pico 4 Enterprise | Established Player | Pico Technology competes in the standalone VR market with competitively priced headsets and a growing content library targeting both consumer and enterprise users across Europe. |
Platform ecosystem concentration creates dependency relationships between hardware manufacturers and software developers. Leading hardware platforms control content distribution through proprietary stores, enabling platform margin capture on software revenue. Enterprise VR adoption diversifies the competitive landscape by creating demand for specialized high-performance solutions beyond consumer gaming.
Key Company Profiles
Meta Platforms, Inc. (Oculus)
Meta Platforms is the global leader in consumer VR hardware and the dominant force in the Europe VR gaming market. The company's Quest product line delivers standalone VR experiences with industry-leading content ecosystems through its Meta Horizon Store, making premium VR gaming accessible to European consumers.
- Key Products: Meta Quest 3, Meta Quest Pro, Quest 2.
- Recent Developments: On September 23, 2026, Meta unveiled its new Meta VR Glasses, a lightweight VR device weighing about 100 grams, scheduled for launch in spring 2027. Meta says the glasses will function as a gaming console and support the existing Quest game library, with more than 75 games available at launch. The device also introduces hands-only gaming controls, using eye tracking and hand gestures instead of traditional controllers.
- Strategic Focus: Focuses on standalone VR hardware democratization, social VR platform development, and enterprise VR adoption through Meta Horizon Workrooms across the European market.
Sony Interactive Entertainment LLC
Sony Interactive Entertainment is the leading console-integrated VR gaming provider in Europe through its PlayStation VR2 platform. The company leverages its extensive PlayStation user base and exclusive AAA gaming relationships to drive VR gaming adoption among European console gaming communities.
- Key Products: PlayStation VR2, PlayStation VR.
- Strategic Focus: Centered on console-integrated VR gaming, exclusive AAA VR content development, and expanding PlayStation ecosystem engagement through immersive gaming experiences for European audiences.
Valve Corporation
Valve Corporation drives the PC VR gaming segment through its Steam platform and Valve Index hardware, providing the largest VR game library and supporting multiple headsets through the SteamVR runtime environment for European enthusiast and professional gaming audiences.
- Key Products: Valve Index, SteamVR Platform, Half-Life: Alyx.
- Recent Developments: In September 2026, Valve launched its new Steam Frame VR headset, expanding its hardware presence in virtual reality gaming. The wireless headset supports both standalone VR gaming and PC game streaming, runs on SteamOS with a Qualcomm Snapdragon 8 Gen 3 processor, and can run titles such as Half-Life: Alyx natively. It also supports access to Android-based VR content, broadening the potential game library.
- Strategic Focus: Focused on PC VR platform development, open ecosystem support, and high-fidelity VR gaming experiences targeting enthusiast and professional gaming audiences across European markets.
Market Concentration Analysis
The Europe virtual reality gaming market is moderately concentrated at the hardware tier, with Meta, Sony, and Valve collectively commanding significant market share. The software tier is more fragmented across thousands of VR game developers and publishers. Enterprise VR solutions represent a competitive niche with specialized providers serving professional training and simulation applications.
Investment & Growth Opportunities
Highest Growth Segments
Software (~14.2% CAGR), Adults (~13.8% CAGR), Children (~12.9% CAGR), and Hardware (~12.7% CAGR) represent the report’s defined segments, as shown in the CAGR comparison figure. The overall market grows at 13.45% CAGR through 2034 in the European market.
Emerging Investment Opportunities
The European enterprise VR training market represents the largest near-term revenue opportunity beyond consumer gaming. Automotive, aerospace, healthcare, and defense sectors are accelerating VR training deployment. VR solution providers establishing enterprise sales capabilities and sector-specific content partnerships are positioned for above-market revenue growth through 2034.
Investment Themes
- Standalone VR hardware technology investment targeting performance-per-watt improvements: Continued investment in mobile VR processing efficiency creates performance parity with PC VR at standalone price points, expanding the addressable consumer market. Companies investing in next-generation standalone processing technology by 2026-2027 are positioned to capture the mainstream consumer VR adoption wave across Europe.
- VR content platform development for recurring subscription revenue: The shift from per-title sales to subscription-based VR content models creates predictable recurring revenue streams. A curated European VR gaming subscription service delivering monthly new content generates above-hardware-margin returns as the European VR install base continues expanding through 2034.
Future Market Outlook (2026-2034)
The Europe virtual reality gaming market is projected to grow from USD 9.7 Billion in 2025 to USD 11.4 Billion in 2026 reaching USD 31.2 Billion by 2034, delivering a 13.45% CAGR over the forecast period. The forecast period marks the beginning of accelerated growth as hardware affordability improvements drive broader consumer adoption. The anchor value of USD 18.24 Billion in 2030 represents the European VR gaming industry at commercial mainstream inflection.
Three structural forces define VR gaming market growth through 2034. Hardware price reduction is making premium VR gaming experiences accessible to middle-income European consumers, expanding the total addressable market beyond early adopter demographics. Content library expansion is resolving the chicken-and-egg challenge that historically constrained VR adoption. Enterprise VR adoption creates commercial credibility and technology refinement cascading into consumer product improvements.
Research Methodology
Primary Research
Primary research comprised structured interviews with 45+ industry stakeholders (2025-2026) including VR hardware executives, game studio creative directors, VR platform operators, enterprise VR solution providers, and European gaming market specialists providing first-hand market intelligence and validation.
Secondary Research
Secondary research encompassed VR industry publications, European gaming market data, IDC hardware shipment reports, company annual reports, gaming association data, and digital entertainment market analyses. Over 55 secondary sources were reviewed and cross-referenced for accuracy.
Forecasting Models
Market revenue forecasts developed using a segment bottom-up model: (i) hardware component including headsets, controllers, and peripherals; (ii) software and content component including game titles and subscriptions; (iii) enterprise and professional services component.
Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Segments Covered | Software, Hardware |
| Devices Covered | Personal Computers, Gaming Consoles, Mobile Devices |
| Age Groups Covered | Adults, Children |
| Types of Games Covered | Racing, Adventure, Fighting, Shooting, Mystery Thriller, Puzzle, Science Fiction, Others |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain, Others |
| Companies Covered | Meta Platforms, Inc. (Oculus), Sony Interactive Entertainment LLC, Valve Corporation, HTC Corporation, ByteDance Ltd. (Pico), etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Frequently Asked Questions About the Europe Virtual Reality Gaming Market Report
The Europe virtual reality gaming market size is estimated at USD 11.4 Billion in 2026, driven by hardware affordability improvements and expanding VR content libraries. The market is propelled by growing consumer demand for immersive gaming, rapid VR hardware advancement, and expanding enterprise applications across European sectors.
The market grows at 13.45% CAGR during 2026-2034, reaching USD 31.2 Billion by 2034. Software grows fastest at ~14.2% CAGR through content library expansion and subscription service adoption. Adults grow at ~13.8% CAGR, Children at ~12.9% CAGR, and Hardware at ~12.7% CAGR across the forecast period.
Hardware leads at 58.6% through the essential requirement for VR headsets, controllers, and computing infrastructure to enable immersive gaming experiences. Hardware grows at ~12.7% CAGR, while software grows at ~14.2% CAGR through content and subscription expansion. Standalone headsets are growing fastest within hardware by eliminating PC dependency requirements.
Adults lead at 68.3%, growing at ~13.8% CAGR, through higher purchasing power, established gaming engagement, and enterprise VR involvement. Children at 31.7%, growing at ~12.9% CAGR, represent the growth demographic as parental investment in family entertainment technology expands and VR content for younger audiences increases.
Germany leads at 28.5% through its large and engaged gaming population, strong technology adoption culture, and robust digital retail infrastructure. The United Kingdom at 23.1% reflects a sophisticated gaming market with high broadband penetration and strong enterprise VR adoption.
Leading companies include Meta Platforms, Inc. (Oculus), Sony Interactive Entertainment LLC, Valve Corporation, HTC Corporation and ByteDance Ltd. (Pico), among others operating in the European VR gaming ecosystem.
The market is projected to reach approximately USD 18.24 Billion by 2030, with standalone VR headsets achieving mass market price points, cloud VR streaming entering commercial deployment at scale, enterprise VR training achieving mainstream corporate adoption, and social VR gaming platforms reaching critical user mass across major European markets.
Cloud VR gaming streams high-fidelity virtual reality experiences from remote servers to consumer devices without requiring powerful local hardware. The technology reduces VR hardware barriers and enables subscription-based access models. Cloud VR gaming is an emerging delivery mechanism within the Software segment (~14.2% CAGR) and supports growth across both the Software and Hardware segments through 2034 as 5G network coverage expands and cloud rendering technology matures.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade