
India Cancer Diagnostics Market Size, Share, Trends and Forecast by Product, Technology, Application, End User, and Region, 2026-2034
India Cancer Diagnostics Market Size, Share, Trends & Forecast (2026-2034)
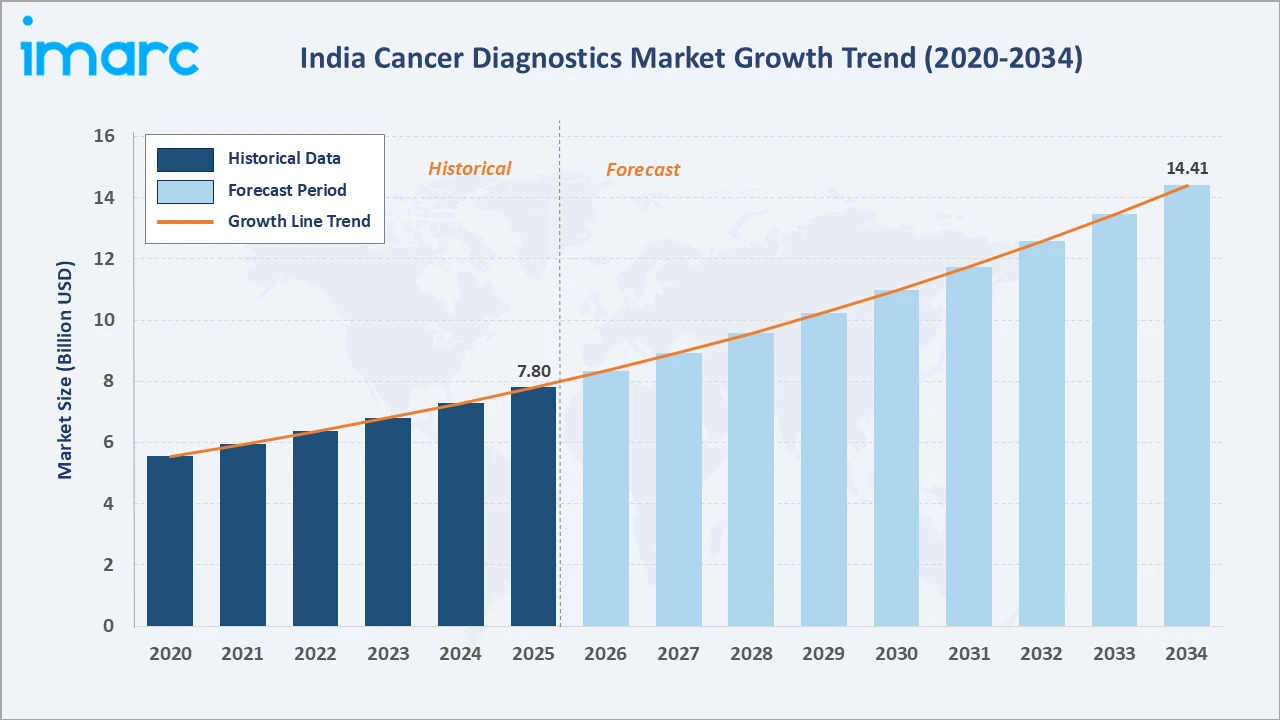
The India cancer diagnostics market grew from USD 7.80 Billion in 2025 to USD 8.35 Billion in 2026 and is projected to reach USD 14.41 Billion by 2034, exhibiting a CAGR of 7.06% during 2026-2034. Rising cancer incidence across the country, expanding government screening programs, surging adoption of advanced imaging and molecular diagnostic technologies, and increasing healthcare expenditure are the primary forces shaping market growth.
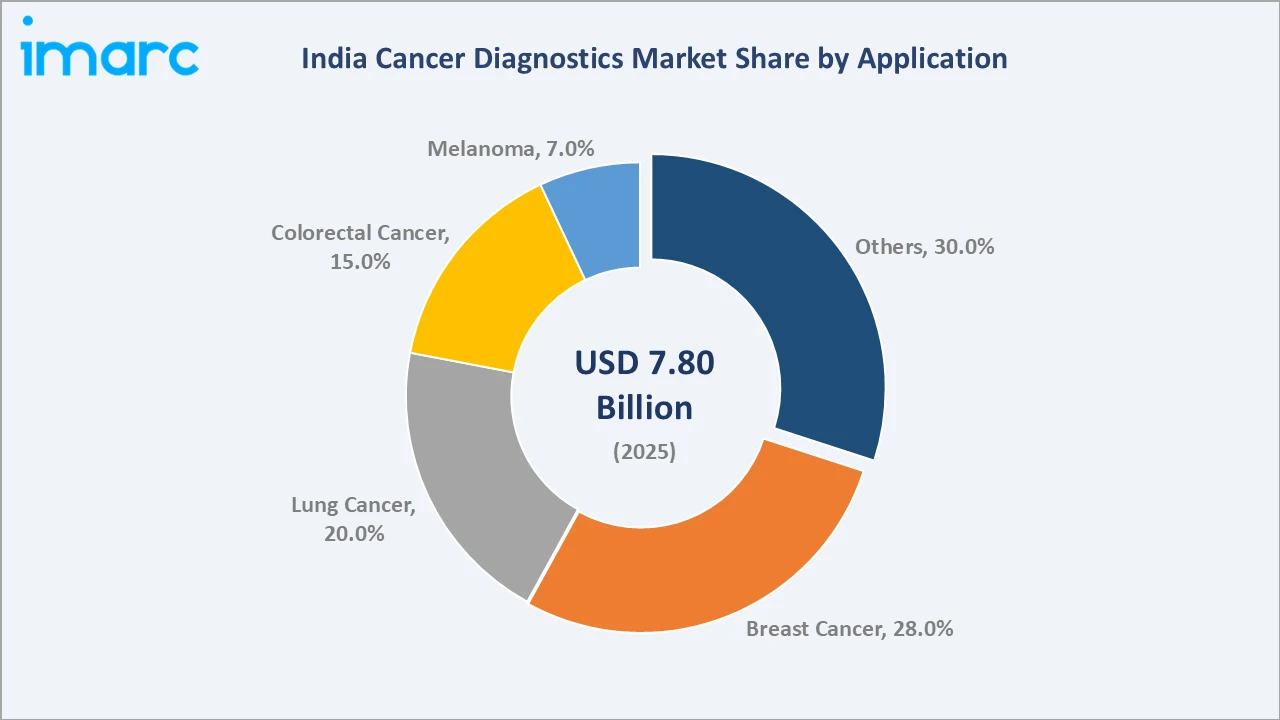
Breast cancer leads the application segment at 28.0%, hospitals and clinics dominate the end user segment at 55.0%, and West and Central India commands 32.0% of regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 7.80 Billion |
| Market Size (2026) | USD 8.35 Billion |
| Forecast Market Size (2034) | USD 14.41 Billion |
| CAGR (2026-2034) | 7.06% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | West and Central India (32.0%, 2025) |
| Second Largest Region | North India (28.0%, 2025) |
| Leading Application | Breast Cancer (28.0%, 2025) |
| Leading End User | Hospitals and Clinics (55.0%, 2025) |
The India cancer diagnostics market size increased from USD 5.55 Billion in 2020 to USD 7.80 Billion in 2025 and is estimated to reach USD 8.35 Billion in 2026. The market is further expected to grow to USD 10.97 Billion by 2030 and USD 14.41 Billion by 2034. The market is commercially significant in the Indian healthcare ecosystem, underpinned by one of the world's largest cancer burden profiles, a rapidly expanding organized diagnostics infrastructure, and growing adoption of advanced imaging and molecular diagnostic technologies across public and private healthcare settings.
To get more information on this market, Request Sample
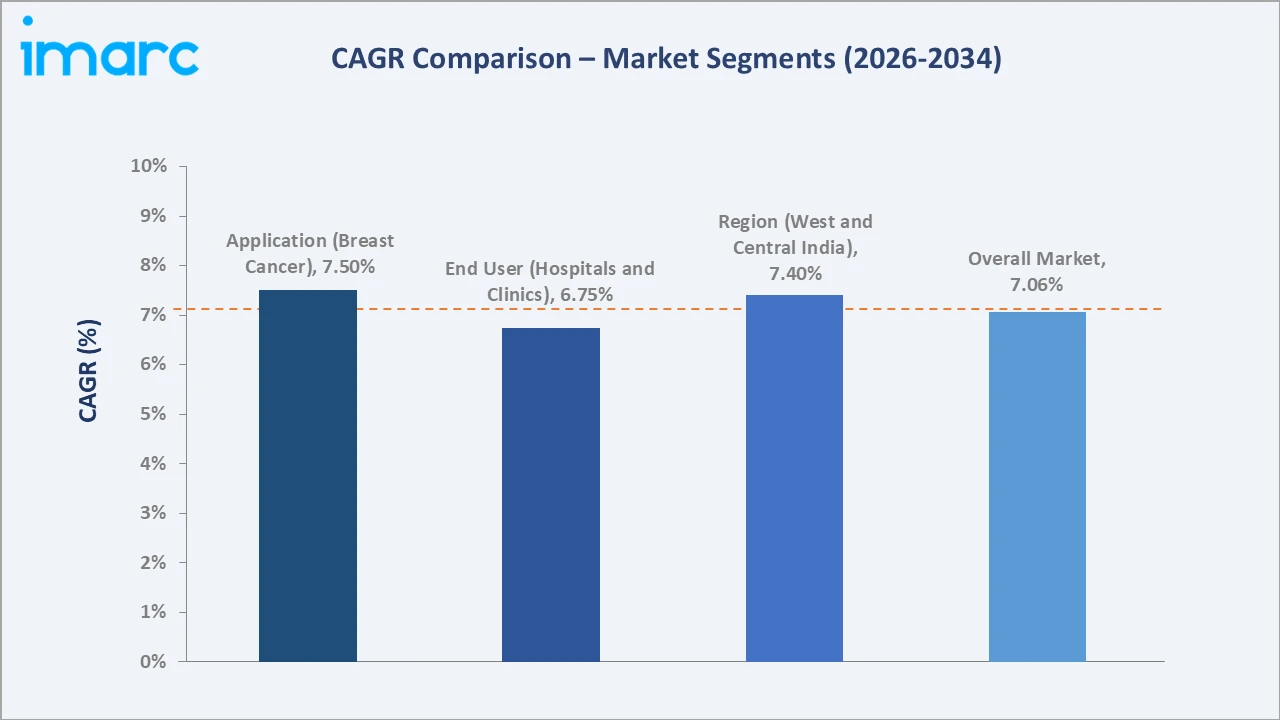
CAGR trajectories across application, end user, and regional sub-segments show melanoma and East and Northeast India expanding faster than the overall 7.06% market CAGR, driven by rising awareness of early cancer detection, increasing adoption of advanced diagnostic technologies, improving access to specialized oncology services, and growing healthcare infrastructure.
Executive Summary
The India cancer diagnostics market expanded from USD 7.80 Billion in 2025 to an estimated USD 8.35 Billion in 2026, positioning it among the world's fastest-growing cancer diagnostics markets by growth rate. The market's scale is underpinned by India's rapidly growing cancer incidence, the increasing shift toward early detection diagnostics, and rising investment in organized, technology-enabled diagnostic infrastructure.
Breast cancer commands 28.0% application share, reflecting its high incidence and established screening protocols across government and private diagnostic facilities. Hospitals and clinics represent 55.0% of the end user segment, driven by their role as primary access points for cancer diagnosis and their capacity to deploy advanced imaging systems. West and Central India leads regional share at 32.0%, anchored by Maharashtra and Gujarat's large urban hospital networks and the concentration of diagnostic service providers in Tier 1 and Tier 2 cities.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Application | Breast Cancer – 28.0% share (2025) |
| Leading End User | Hospitals and Clinics – 55.0% share (2025) |
| Leading Region | West and Central India – 32.0% share (2025) |
| Top Companies | Siemens Healthineers AG, Roche Holding AG, Abbott Laboratories, Danaher Corporation |
Key Analytical Observations Expanding On the Data Above:
- Breast cancer dominance at 28.0% reflects its high incidence rate across Indian women, well-established government-backed breast cancer screening initiatives, and widespread availability of mammography and biopsy diagnostic infrastructure at hospitals and specialized centers.
- Hospitals and clinics leadership at 55.0% is underpinned by their role as primary entry points for cancer diagnosis, their ability to integrate imaging, pathology, and molecular diagnostic capabilities under one roof, and growing patient preference for comprehensive oncology care in institutional settings.
- West and Central India at 32.0% leads regional share due to the concentration of large multi-specialty hospitals in Mumbai, Pune, and Ahmedabad, strong private healthcare infrastructure, and high patient volume from densely populated urban clusters.
India Cancer Diagnostics Market Overview
Cancer diagnostics refers to the range of medical tests, imaging technologies, laboratory assays, and molecular procedures used to detect, identify, classify, and monitor cancer in patients. The India cancer diagnostics market encompasses imaging modalities such as MRI, CT, PET scans, and ultrasound, alongside laboratory services including histopathology, cytopathology, tumor biomarker testing, and next-generation sequencing (NGS) for genetic profiling.
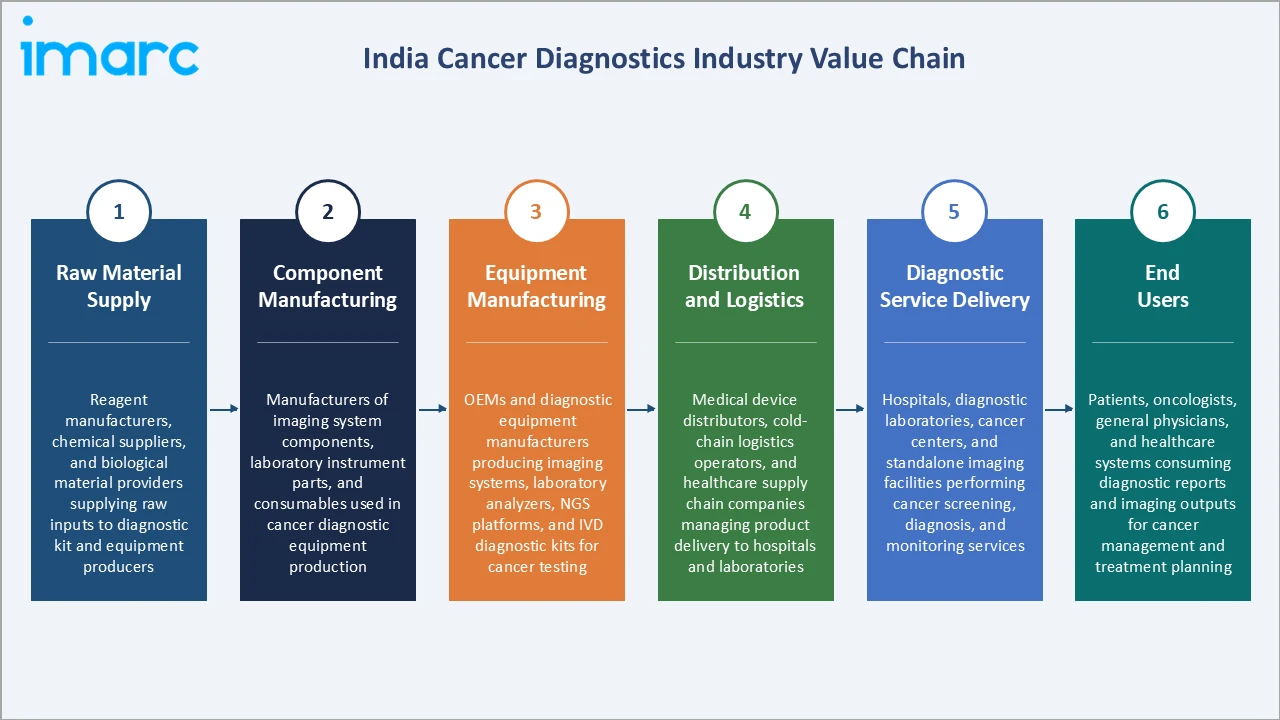
The Indian ecosystem integrates raw material suppliers, diagnostic equipment manufacturers, reagent and consumable providers, diagnostic service operators, hospital oncology departments, and digital health technology companies. Regulatory bodies form the oversight layer, ensuring quality standards and enabling a compliant, scalable diagnostics ecosystem across India's public and private healthcare sectors.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
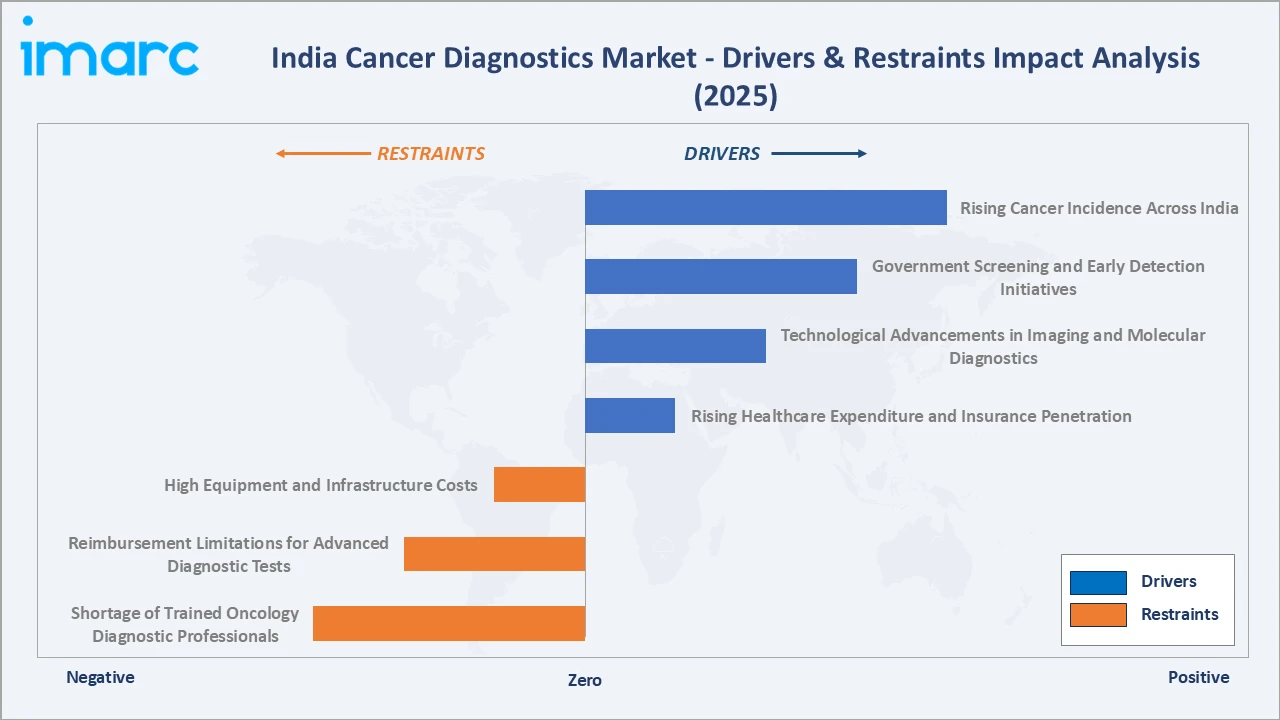
- Rising Cancer Incidence Across India: The steadily increasing burden of cancer across India is the most fundamental demand driver for the diagnostics market. This is expanding the addressable patient population for screening, diagnostic, and monitoring services across all cancer types. According to ICMR, India was estimated to report 1.57 Million new cancer cases by 2025, directly enlarging the diagnostics opportunity.
- Government Screening and Early Detection Initiatives: National programs including the National Program for Prevention and Control of Cancer, Diabetes, Cardiovascular Diseases and Stroke (NPCDCS) and Ayushman Bharat are expanding cancer screening access across underserved populations, driving demand for affordable and scalable diagnostic services.
- Technological Advancements in Imaging and Molecular Diagnostics: Rapid adoption of AI-assisted imaging interpretation, NGS, and liquid biopsy technologies is expanding the clinical utility and commercial scope of cancer diagnostics, enabling earlier and more accurate diagnosis while creating new service and product categories.
- Rising Healthcare Expenditure and Insurance Penetration: Growing private healthcare expenditure, increased health insurance penetration driven by government and commercial schemes, and expanding corporate wellness programs are improving patient access to diagnostic services, broadening the paying patient base.
Market Restraints
- High Equipment and Infrastructure Costs: Advanced cancer diagnostic equipment such as PET-CT scanners, MRI systems, and NGS platforms require substantial capital investment, limiting deployment to large hospitals and well-capitalized diagnostic chains and creating infrastructure gaps in smaller cities and rural areas.
- Shortage of Trained Oncology Diagnostic Professionals: The limited availability of trained oncologists, radiologists, pathologists, and laboratory specialists constrains diagnostic throughput at both hospital and standalone laboratory levels, particularly in Tier 2 and Tier 3 cities.
- Reimbursement Limitations for Advanced Diagnostic Tests: Many advanced molecular diagnostic procedures and specialized imaging protocols are not fully covered under government insurance schemes, creating out-of-pocket affordability barriers for a significant share of the Indian patient population.
Market Opportunities
- Expansion of Organized Diagnostic Networks in Tier 2 and Tier 3 Cities: Established diagnostic chains are actively expanding their geographic footprint into India's secondary and tertiary cities, where cancer incidence is rising but organized diagnostic infrastructure remains underdeveloped, offering significant untapped patient volume.
- Growing Adoption of AI-Powered Diagnostic Solutions: AI tools for radiology image interpretation, pathology slide analysis, and clinical decision support are creating opportunities to improve throughput, reduce diagnostic error rates, and differentiate service offerings in an increasingly competitive marketplace.
Market Challenges
- Affordability and Price Sensitivity: India's diagnostics market remains price-sensitive, with a significant portion of patients either uninsured or underinsured. Balancing service quality and technology investment against accessible price points represents a persistent operational challenge for diagnostic service providers.
- Fragmented Regulatory Environment for Novel Diagnostic Technologies: Evolving regulatory pathways for new diagnostic modalities, including liquid biopsy tests, companion diagnostics, and AI-based tools, create approval timeline uncertainty and compliance complexity for companies seeking to introduce innovative products into the Indian market.
Emerging Market Trends
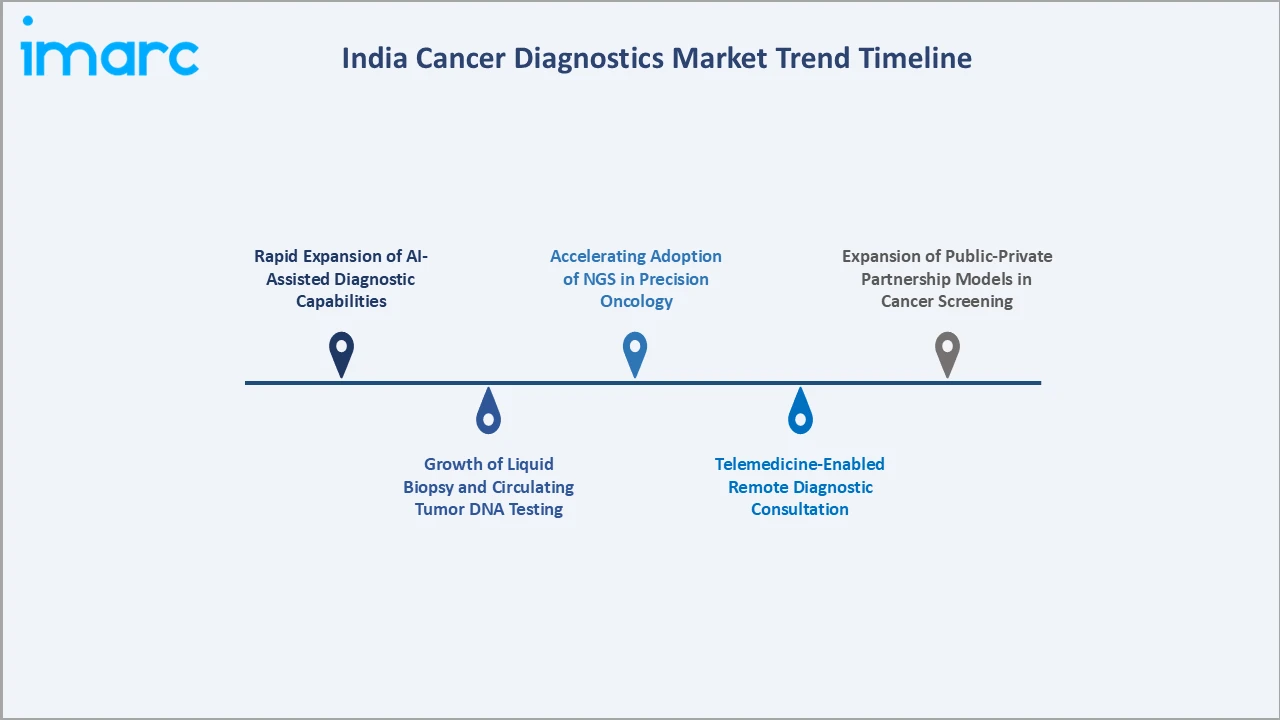
1. Rapid Expansion of AI-Assisted Diagnostic Capabilities
AI and machine learning applications in radiology, pathology, and endoscopy are increasingly being deployed across Indian diagnostic facilities to improve image interpretation accuracy and throughput. AI-assisted cancer screening tools are demonstrating improved sensitivity and specificity in detecting early-stage breast, lung, and colorectal cancers.
2. Growth of Liquid Biopsy and Circulating Tumor DNA Testing
Liquid biopsy, which involves the analysis of circulating tumor DNA (ctDNA), cell-free DNA (cfDNA), and circulating tumor cells (CTCs) from blood samples, is gaining clinical acceptance as a minimally invasive alternative to tissue biopsy for cancer detection and monitoring. Indian diagnostic laboratories are expanding their liquid biopsy portfolios, targeting applications in treatment response monitoring and recurrence detection, particularly impactful for patients who cannot undergo surgical biopsy procedures.
3. Accelerating Adoption of NGS in Precision Oncology
NGS is becoming increasingly central to cancer diagnostics in India, enabling comprehensive genomic profiling that informs targeted therapy selection. Major diagnostic chains and hospital oncology centers are deploying NGS platforms for tumor mutational burden assessment, microsatellite instability testing, and companion diagnostic applications aligned with approved targeted therapies, creating a structurally growing service category.
4. Telemedicine-Enabled Remote Diagnostic Consultation
The integration of telemedicine with remote pathology consultation, digital radiology review, and molecular diagnostics reporting is extending specialist oncology diagnostic access to patients in geographically remote markets. Digital pathology platforms enabling remote tissue image analysis and virtual tumor board consultations are reducing diagnostic delays and improving treatment initiation timelines across India's secondary and tertiary cities.
5. Expansion of Public-Private Partnership Models in Cancer Screening
Collaborative models between government health agencies and private diagnostic service providers are enabling cost-effective mass cancer screening programs across India. These partnerships are creating structured, recurring demand for standardized diagnostic protocols and strengthening population-level early detection rates, supporting the long-term volume growth of the cancer diagnostics services market.
Industry Value Chain Analysis
The India cancer diagnostics value chain spans six stages, from raw material and component supply through diagnostic service delivery and end user consumption. Processing, analytical, and reporting stages capture the highest value-add, while technology differentiation and regulatory compliance are increasingly determining competitive position in a quality-driven and accreditation-conscious market.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Supply | Reagent manufacturers, chemical suppliers, and biological material providers supplying raw inputs to diagnostic kit and equipment producers |
| Component Manufacturing | Manufacturers of imaging system components, laboratory instrument parts, and consumables used in cancer diagnostic equipment production |
| Equipment Manufacturing | OEMs and diagnostic equipment manufacturers producing imaging systems, laboratory analyzers, NGS platforms, and IVD diagnostic kits for cancer testing |
| Distribution and Logistics | Medical device distributors, cold-chain logistics operators, and healthcare supply chain companies managing product delivery to hospitals and laboratories |
| Diagnostic Service Delivery | Hospitals, diagnostic laboratories, cancer centers, and standalone imaging facilities performing cancer screening, diagnosis, and monitoring services |
| End Users | Patients, oncologists, general physicians, and healthcare systems consuming diagnostic reports and imaging outputs for cancer management and treatment planning |
Vertically integrated operators controlling equipment supply, laboratory operations, and reporting services are positioned to capture greater margin than single-stage service providers dependent on third-party equipment and outsourced analytical services.
Technology Landscape in the India Cancer Diagnostics Industry
Imaging Technologies
Imaging technologies, including MRI, CT, PET-CT, ultrasound, and digital mammography, remain the foundation of cancer detection and staging in India. AI-integrated imaging platforms are improving detection accuracy, reducing scan interpretation time, and enabling earlier identification of malignancies across breast, lung, and abdominal cancers.
Molecular Diagnostics and Genomic Testing
Molecular diagnostics, encompassing PCR-based assays, FISH testing, immunohistochemistry, and NGS, are driving significant market expansion. NGS platforms enable comprehensive genomic profiling for treatment selection, while companion diagnostics tools are aligning cancer diagnosis with targeted therapy pathways, expanding the clinical and commercial value of the molecular diagnostics segment.
Liquid Biopsy Technologies
Liquid biopsy platforms analyzing circulating tumor DNA, CTCs, and exosomes are gaining adoption across Indian cancer centers for minimally invasive cancer detection, treatment monitoring, and recurrence surveillance. These technologies are particularly impactful for patients with inaccessible tumor locations or contraindications to conventional tissue biopsy.
AI and Digital Pathology
AI-powered digital pathology solutions enabling automated tissue slide analysis, tumor cell classification, and remote pathology consultation are increasingly deployed across large hospital systems and reference laboratories in India. Integration with laboratory information management systems and electronic medical records is improving diagnostic workflow efficiency and reporting turnaround times.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product | 🔒 | 🔒 | 2025 |
| Technology | 🔒 | 🔒 | 2025 |
| Application | Breast Cancer | 28.0% | 2025 |
| End User | Hospitals and Clinics | 55.0% | 2025 |
| Region | West and Central India | 32.0% | 2025 |

By Application
Breast cancer commands a 28.0% majority share in 2025, driven by high incidence rates, well-established screening protocols, and widespread deployment of mammography and breast ultrasound systems across both government and private diagnostic facilities in India. The segment benefits from government-supported breast cancer awareness programs and the expansion of affordable screening services.
To access detailed market analysis, Request Sample
Lung cancer at 20.0% is driven by the high prevalence of the disease, increasing awareness of early diagnosis, and rising adoption of advanced imaging and molecular diagnostic techniques for accurate detection and treatment planning.
By End User
Hospitals and clinics represent 55.0% of the end user segment in 2025, directly reflecting their role as the primary site of cancer diagnosis in India. Their capacity to integrate imaging, pathology, molecular diagnostics, and oncology consultation under one roof drives patient concentration and sustains high diagnostic service volumes.
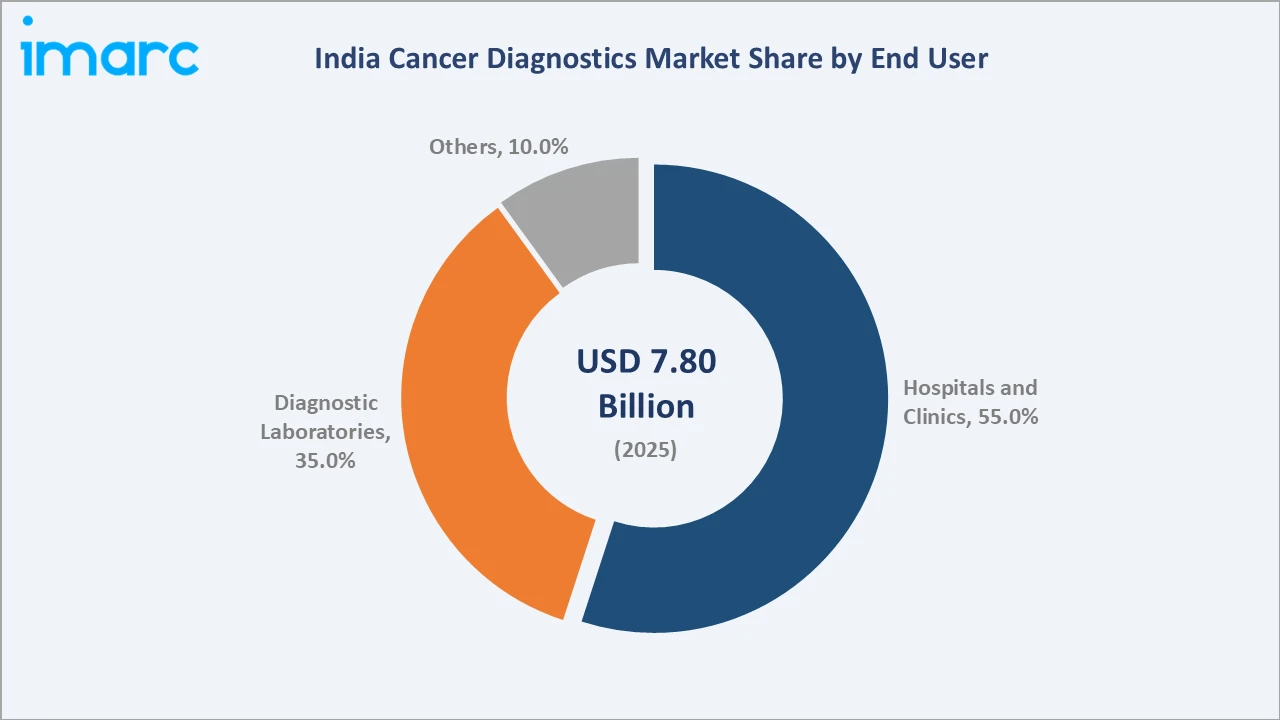
Diagnostic laboratories at 35.0% are expanding rapidly as organized diagnostic chains increase geographic coverage and offer cost-competitive cancer testing services. Their growing role in biomarker testing, cancer antigen panels, and molecular assays is expanding their share of the diagnostics value chain.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| West and Central India | 32.0% | Large urban hospital networks in Mumbai, Pune, and Ahmedabad, high private healthcare investment, concentration of multi-specialty cancer centers, and strong patient referral volumes from Gujarat and Maharashtra |
| North India | 28.0% | Major tertiary cancer centers in Delhi, Lucknow, and Chandigarh, growing organized diagnostic chain penetration, high population density driving patient volumes, and expanding health insurance coverage |
| South India | 27.0% | Strong private healthcare ecosystem in Chennai, Bengaluru, and Hyderabad, well-established oncology research institutions, high medical tourism activity, and growing adoption of advanced molecular diagnostics |
| East and Northeast India | 13.0% | Expanding public hospital infrastructure in Kolkata and Bhubaneswar, increasing government investment in healthcare access, rising cancer awareness programs, and growing private diagnostic service entry in underserved states |
West and Central India at 32.0% in 2025 leads the regional landscape, anchored by Maharashtra's extensive hospital infrastructure and Gujarat's rapidly developing private healthcare ecosystem, which together drive high diagnostic service demand across imaging, pathology, and molecular testing categories.
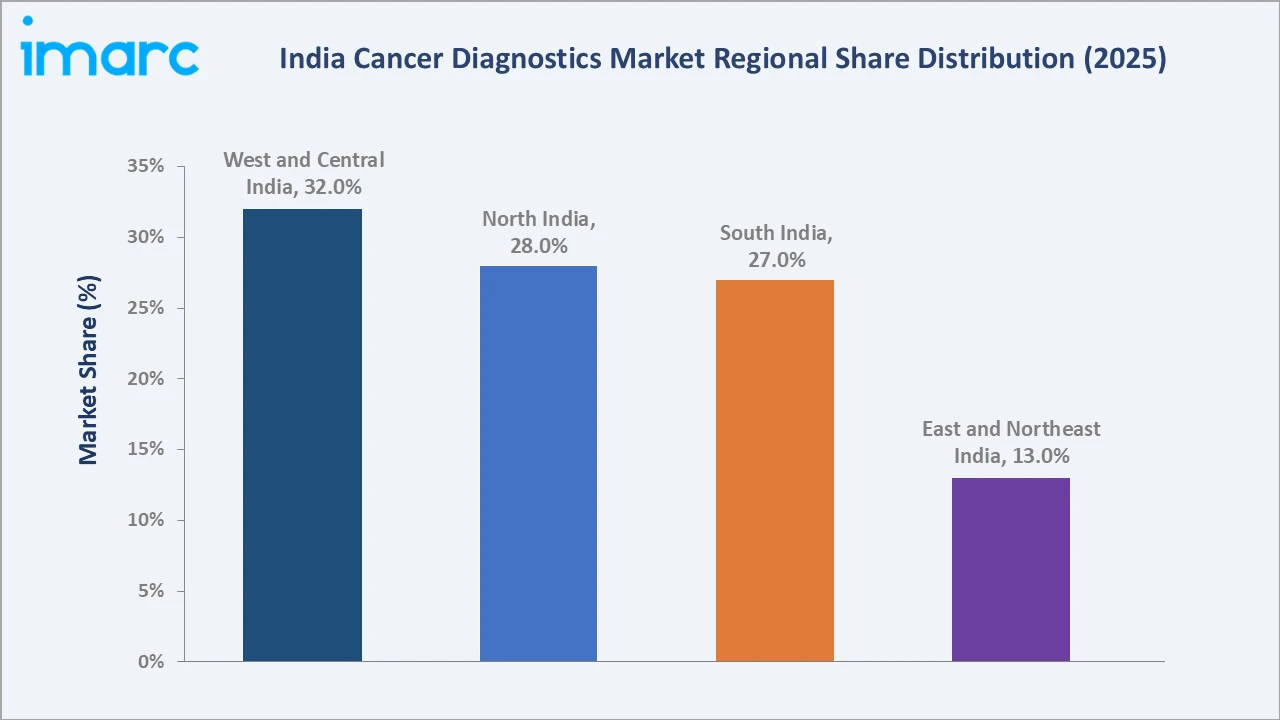
East and Northeast India, while currently the smallest regional contributor at 13.0%, is expanding as cancer screening awareness improves, government healthcare infrastructure investment accelerates, and organized diagnostic service providers establish facilities in Kolkata, Bhubaneswar, and emerging markets.
Competitive Landscape
The India cancer diagnostics market is fragmented, with a mix of global medical technology companies, international in vitro diagnostics manufacturers, and established domestic diagnostic service chains competing on technology depth, diagnostic accuracy, service network scale, and regulatory compliance credentials. Technology differentiation, accreditation status, geographic coverage, and pricing strategy form the key competitive differentiators across the industry.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Siemens Healthineers AG | MAGNETOM / SOMATOM / Atellica | Leader | Expanding advanced imaging and laboratory diagnostics portfolio through technology investment and service network growth |
| Roche Holding AG | cobas / VENTANA / navify | Leader | Growing molecular diagnostics and digital pathology capabilities through proprietary technology platforms and companion diagnostic development |
| Abbott Laboratories | Alinity / i-STAT | Challenger | Strengthening immunoassay and molecular diagnostics presence through expanding laboratory systems and point-of-care testing capabilities |
| Danaher Corporation | Beckman Coulter / Leica Biosystems | Challenger | Building oncology diagnostics scale through multi-brand portfolio integration and expanding clinical laboratory systems presence |
Key players include Siemens Healthineers AG, Roche Holding AG, Abbott Laboratories, and Danaher Corporation, among others.
Key Company Profiles
Siemens Healthineers AG
Siemens Healthineers AG is a Germany-based global medical technology company. The company operates a comprehensive portfolio spanning medical imaging systems, in vitro diagnostics, advanced therapies, and digital health solutions, with a significant presence across Indian hospitals and diagnostic centers.
- Product Portfolio: MRI systems (MAGNETOM series), CT scanners (SOMATOM series), PET-CT systems, clinical chemistry and immunoassay analyzers, and AI-powered imaging solutions for oncology diagnostics.
- Recent Developments: The company continues to expand its AI-integrated imaging and laboratory diagnostics infrastructure in India, investing in service network capacity and digital health platform deployment across major hospital systems.
- Strategic Focus: Strengthening integrated oncology diagnostic capabilities through advanced imaging technology investment, digital health platform expansion, and service network growth across India's large hospital segment.
Roche Holding AG
Roche Holding AG is a Switzerland-based global healthcare company headquartered in Basel. The company operates through its diagnostics and pharmaceuticals divisions, providing a broad range of cancer testing solutions including molecular diagnostics, immunohistochemistry, and digital pathology platforms.
- Product Portfolio: cobas molecular and clinical chemistry systems, VENTANA digital pathology platforms, navify digital oncology solutions, and a comprehensive range of cancer biomarker and companion diagnostic assays.
- Recent Developments: The company is advancing its digital pathology and companion diagnostics capabilities in India, supporting precision oncology workflows and expanding molecular diagnostic test coverage.
- Strategic Focus: Expanding molecular diagnostics and companion diagnostic portfolios to support targeted cancer therapy pathways, while growing digital pathology platform adoption across Indian oncology centers.
Abbott Laboratories
Abbott Laboratories is a United States-based diversified healthcare company headquartered in Abbott Park, Illinois. The company's diagnostics division provides immunoassay, molecular, and hematology testing solutions widely used in cancer screening and monitoring applications across Indian hospital and laboratory settings.
- Product Portfolio: Alinity immunoassay systems, i-STAT point-of-care analyzers, and cancer antigen testing panels.
- Recent Developments: Abbott Laboratories continues to expand its Alinity platform presence in India through hospital laboratories and large diagnostic chains.
- Strategic Focus: Integrating Exact Sciences' oncology portfolio with its established immunoassay and point-of-care infrastructure to build a comprehensive cancer diagnostics offering, targeting expanded oncology workflows across Indian hospital and reference laboratory settings.
Market Concentration Analysis
The India cancer diagnostics market is fragmented, with the top tier of operators comprising global medical technology companies and established domestic diagnostic chains, accounting for a moderate share of overall diagnostic service volumes. The market's dual-layer character, with large hospital-integrated diagnostics alongside independent laboratory chains, limits concentration and maintains competitive diversity across service segments.
Barriers to entry include substantial capital investment requirements for advanced imaging equipment, the need for NABL accreditation and CDSCO regulatory clearances, technical expertise in specialized oncology diagnostics, and the challenge of building a geographic service network capable of attracting sufficient patient volume to achieve operational scale. These factors favor established global equipment manufacturers, large multi-specialty hospital chains, and organized national diagnostic chains over greenfield entrants without existing healthcare infrastructure or brand recognition.
Consolidation is progressing through acquisition activity among national diagnostic chains and strategic partnerships between global equipment manufacturers and Indian hospital systems. Technology-led differentiation through AI diagnostics, liquid biopsy, and NGS-based genomic profiling is emerging as a key competitive boundary, with well-capitalized operators investing in these capabilities to establish service differentiation ahead of their mid-market competitors.
Investment & Growth Opportunities
Fastest-Growing Segments
Melanoma, though currently the smallest application segment, is growing at an above-average rate driven by improving dermatology diagnostic capabilities and rising skin cancer awareness. Among end user segments, diagnostic laboratories are expanding faster than the overall market, supported by organized chain expansion into Tier 2 and Tier 3 cities and increasing adoption of cancer biomarker panels outside of hospital settings.
Emerging Markets
East and Northeast India is the fastest-growing regional market, supported by expanding public hospital infrastructure, increasing cancer screening awareness, and growing entry of national diagnostic chains into Kolkata, Bhubaneswar, and northeastern states. The region represents significant untapped opportunity for operators able to establish early-mover diagnostic service infrastructure ahead of intensifying competition.
Venture & Investment Trends
Investment activity in the India cancer diagnostics sector is concentrated in AI-powered diagnostic software platforms, liquid biopsy technology development, molecular diagnostics laboratory build-out, and digital health infrastructure enabling remote diagnostic access. Capital is also flowing into organized diagnostic chain expansion programs targeting Tier 2 and Tier 3 city penetration, and into genomic testing laboratories aligned with India's growing precision oncology market.
Future Market Outlook (2026-2034)
The India cancer diagnostics market is projected to grow from USD 7.80 Billion in 2025 to USD 8.35 Billion in 2026, reaching USD 14.41 Billion by 2034, registering a CAGR of 7.06% during 2026-2034.
Four forces will shape the market through 2034: expanding public and private cancer screening programs driving early-stage diagnosis volumes; maturing precision oncology workflows increasing demand for molecular and genomic diagnostic tests; geographic expansion of organized diagnostic chains into previously underserved markets; and progressive integration of AI, digital pathology, and telehealth platforms improving diagnostic efficiency and access.
By 2034, the India cancer diagnostics market is expected to be characterized by a mix of technology-differentiated global medical technology companies, large organized national diagnostic chains, and hospital-integrated oncology diagnostic programs. Continued growth in cancer incidence will sustain strong volume demand through the forecast period, while technology differentiation and geographic expansion will drive competitive positioning among leading operators.
Research Methodology
Primary Research
Primary research included structured discussions with oncologists, radiologists, pathologists, diagnostic laboratory operators, hospital procurement executives, and healthcare policy specialists, validating market sizing, segment share, and regional demand patterns across the India cancer diagnostics ecosystem.
Secondary Research
Secondary sources included Indian Council of Medical Research (ICMR) publications, National Cancer Registry Programme data, Ministry of Health and Family Welfare reports, CDSCO regulatory filings, NABL accreditation data, and public disclosures from listed diagnostic companies and global medical technology manufacturers operating in India.
Forecasting Models
Market forecasts used top-down and bottom-up models combining cancer incidence projections, diagnostic penetration rate assumptions, segment revenue buildup from patient volume and average test value estimates, and regional healthcare infrastructure development trajectories. Scenario analysis addressed technology adoption pace, government program implementation timelines, and insurance penetration expansion rates.
India Cancer Diagnostics Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered |
|
| Technologies Covered |
|
| Applications Covered | Breast Cancer, Lung Cancer, Colorectal Cancer, Melanoma, Others |
| End Users Covered | Hospitals and Clinics, Diagnostic Laboratories, Others |
| Regions Covered | North India, West and Central India, South India, East and Northeast India |
| Companies Covered | Siemens Healthineers AG, Roche Holding AG, Abbott Laboratories, Danaher Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India cancer diagnostics market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India cancer diagnostics market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India cancer diagnostics industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Cancer Diagnostics Market Report
The India cancer diagnostics market size is estimated at USD 8.35 Billion in 2026, driven by rising cancer incidence, expanding diagnostic infrastructure, and growing adoption of advanced imaging and molecular diagnostic technologies across the country.
The market is projected to grow at a CAGR of 7.06% from 2026-2034, reaching USD 14.41 Billion by 2034, supported by rising cancer incidence, expanding organized diagnostic infrastructure, and surging adoption of AI-integrated and molecular diagnostics.
Breast cancer dominates the market at 28.0% application share in 2025, driven by high incidence rates, well-established screening protocols, and widespread mammography infrastructure across hospitals and diagnostic facilities in India.
Hospitals and clinics lead with 55.0% end user share in 2025, driven by their role as the primary point of cancer diagnosis and their integrated capacity to offer imaging, pathology, and molecular diagnostics in a single institutional setting.
West and Central India commands 32.0% regional share in 2025, led by Maharashtra and Gujarat's large hospital networks, high private healthcare investment, and concentrated multi-specialty cancer center infrastructure.
East and Northeast India is the fastest-growing region, supported by expanding public healthcare infrastructure, increasing cancer awareness programs, and growing entry of organized diagnostic service providers into underserved states.
Key players include Siemens Healthineers AG, Roche Holding AG, Abbott Laboratories, and Danaher Corporation, among others.
Key drivers include rising cancer incidence, government screening programs, technological advancements in AI and molecular diagnostics, expanding insurance coverage, and growing organized diagnostic chain penetration across Tier 2 and Tier 3 cities.
Key trends include AI-assisted imaging adoption, growth of liquid biopsy and NGS-based genomic testing, telemedicine-enabled remote diagnostics, expansion of organized diagnostic chains, and increasing public-private partnerships for cancer screening.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade