India Energy Storage Systems (ESS) Market Size, Share, Trends and Forecast by Technology, Application, End User, and Region, 2026-2034
India Energy Storage Systems (ESS) Market Size, Share, Trends & Forecast (2026-2034)
The India energy storage systems market grew from 8.92 GW in 2025 to 9.53 GW in 2026 and is projected to reach 16.19 GW by 2034, growing at a CAGR of 6.84% during 2026-2034. This growth is driven by rapid expansion of renewable energy capacity, rising grid modernization investments, and increasing adoption of battery energy storage systems (BESS) across utility, commercial, and industrial segments. India has a record 92 GWh of battery energy storage system (BESS) projects currently in the pipeline, reflecting the country's growing focus on energy storage infrastructure. Pumped hydro storage leads with a 42.8% technology share (2025). Stationary applications dominate at 68.4%, and South India holds the largest regional share at 29.8%.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | 8.92 GW |
| Market Size (2026) | 9.53 GW |
| Forecast Market Size (2034) | 16.19 GW |
| CAGR (2026-2034) | 6.84% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Technology | Pumped Hydro (42.8%, 2025) |
| Dominant Application | Stationary (68.4%, 2025) |
| Leading Region | South India (29.8%, 2025) |
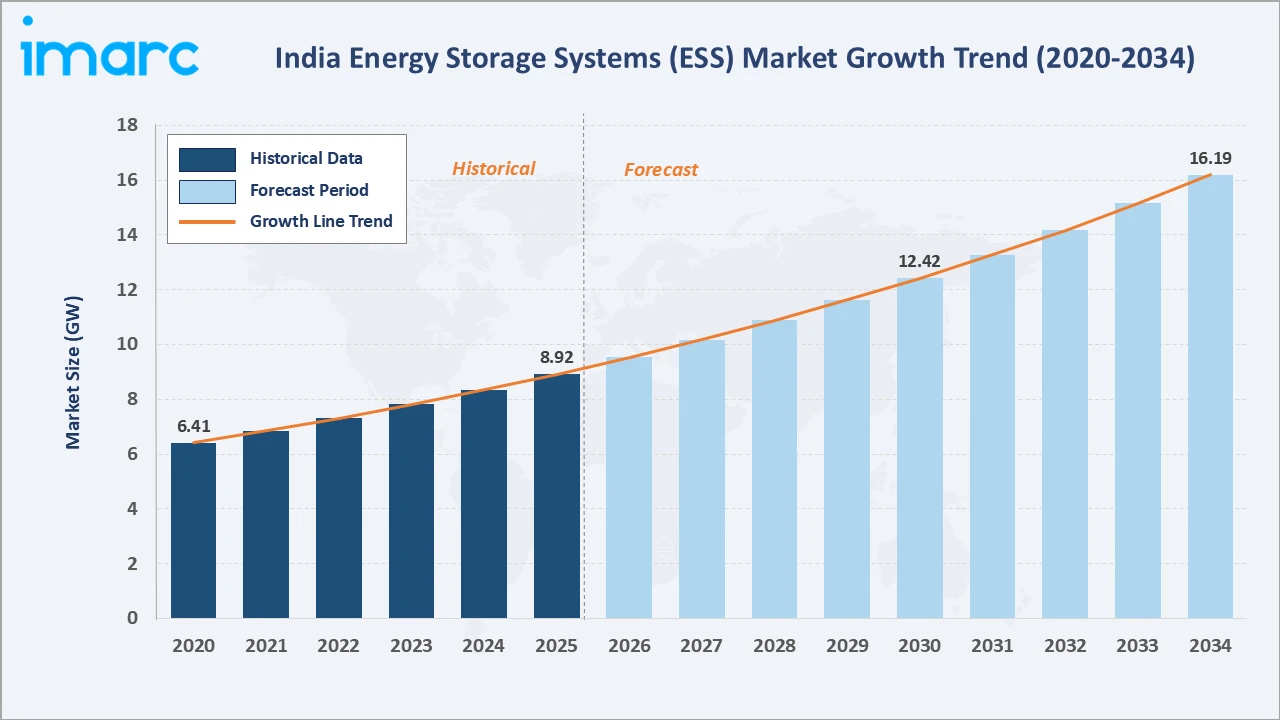
The India energy storage systems market grew from 6.41 GW in 2020 to 8.92 GW in 2025 and to 9.53 GW in 2026 and is projected to reach 12.42 GW in 2030 and to 16.19 GW by 2034, growing at a CAGR of 6.84% during 2026-2034. By December 2025, India had installed 258 GW of renewable energy capacity, advancing toward its target of 500 GW of non-fossil fuel-based energy capacity by 2030, creating structural demand for large-scale energy storage to manage intermittency and grid stability.
To get more information on this market, Request Sample
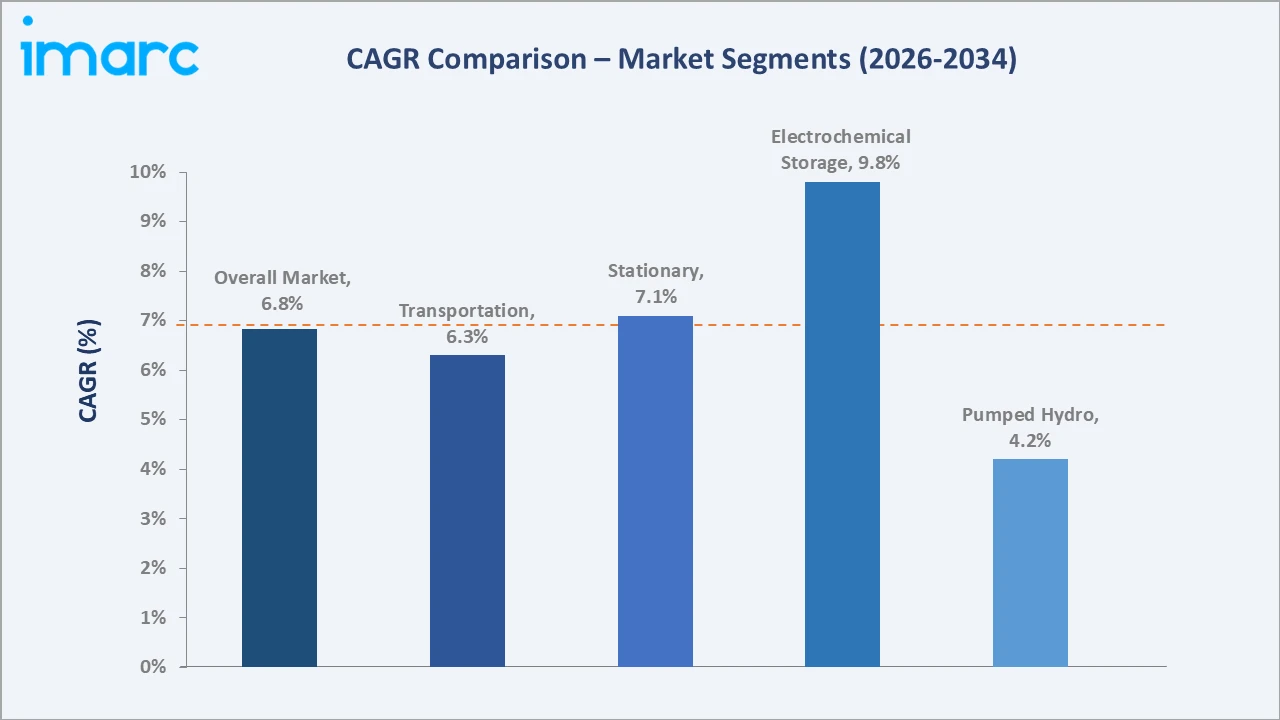
Electrochemical storage, growing at approximately 9.8% CAGR, reflects falling lithium-ion battery costs and rapid utility-scale BESS project announcements. The transportation segment, growing at 6.3% CAGR, driven by EV fleet expansion, is also emerging as a significant demand contributor to the broader ESS ecosystem.
Executive Summary
The India ESS market is on an accelerated growth trajectory, underpinned by India’s 500 GW non-fossil capacity target by 2030. The market grew from 8.92 GW in 2025 to 9.53 GW in 2026, projected to reach 16.19 GW by 2034. The PLI scheme for advanced chemistry cell storage (INR 18,100 Crore outlay) is accelerating domestic manufacturing and deployment.
Pumped hydro leads at a 42.8% share in 2025, anchoring the technology landscape, while electrochemical storage is gaining rapidly with declining lithium-ion costs. Stationary applications at 68.4% include grid-scale BESS, C&I backup, and distributed energy resources. South India leads with a 29.8% regional share.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Technology | Pumped Hydro – 42.8% share (2025) |
| Dominant Application | Stationary – 68.4% share (2025) |
| Leading Region | South India – 29.8% (2025) |
| Key Market Opportunity | PLI scheme for advanced chemistry cells and grid-scale BESS mandates are creating large, policy-backed deployment pipelines across utility and C&I segments. |
Key Analytical Observations Supporting the Above Data:
- Pumped Hydro at 42.8%: Pumped hydro dominates because it offers the largest capacity per installation, making it the preferred long-duration storage solution for grid operators and state utilities managing peak demand cycles.
- Stationary at 68.4%: Stationary applications lead because grid integration, frequency regulation, and industrial backup represent large, immediate demand pools, particularly given India’s renewable curtailment challenges in high-solar states.
- South India at 29.8%: South India leads in ESS deployment driven by its role as India’s largest solar energy hub, accounting for a major share of operational utility-scale solar capacity requiring storage support.
India Energy Storage Systems (ESS) Market Overview
The India energy storage systems market spans pumped hydro, electrochemical, electromechanical, and thermal storage technologies. ESS addresses renewable intermittency, provides grid ancillary services, and supports decarbonization across power, industry, and mobility sectors. The market serves central and state utilities, renewable energy developers, commercial and industrial consumers, and EV OEMs.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
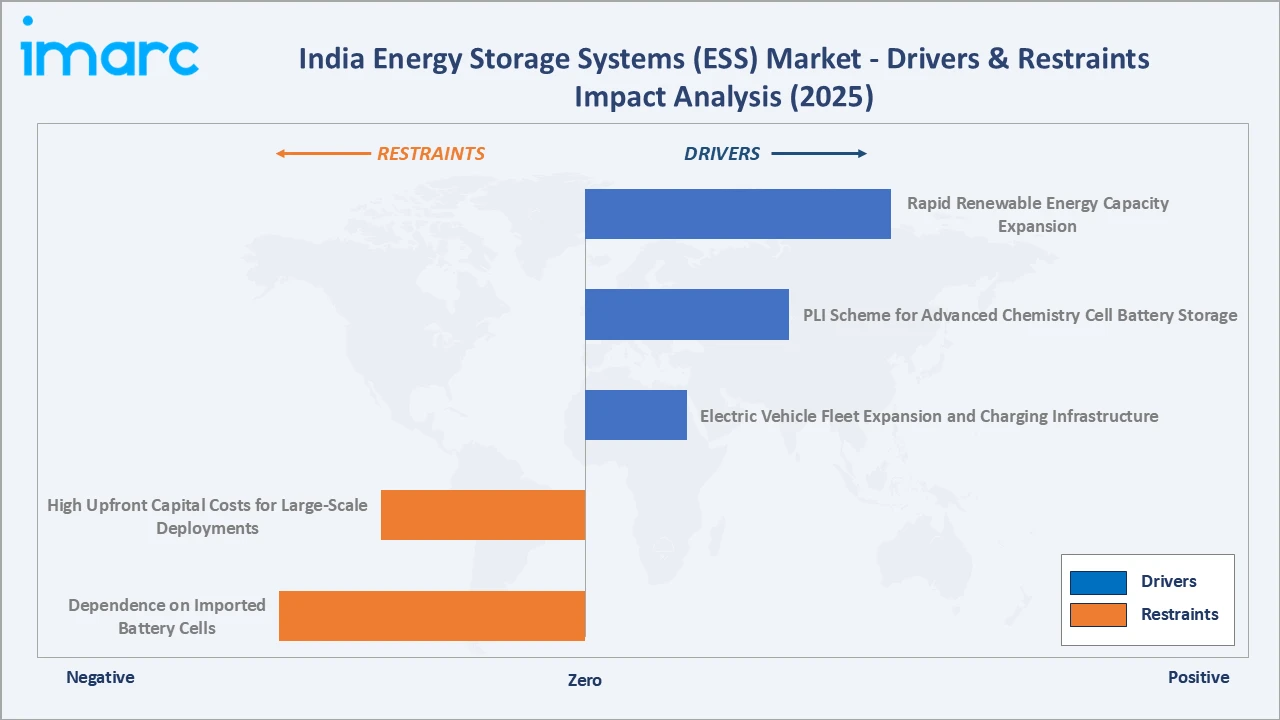
- Rapid Renewable Energy Capacity Expansion: India’s installed renewable energy capacity is 258 GW by December 2025, with a target of 500 GW by 2030. Every GW of wind and solar added creates incremental demand for storage to manage generation variability, frequency regulation, and grid stability.
- PLI Scheme for Advanced Chemistry Cell Battery Storage: The Government of India’s PLI scheme with an INR 18,100 Crore outlay to establish 50 GWh of domestic Advanced Chemistry Cell manufacturing capacity directly incentivizes domestic BESS manufacturing, reducing import dependence and lowering system costs for utility and C&I buyers.
- Electric Vehicle Fleet Expansion and Charging Infrastructure: India recorded 28.2 million vehicle registrations in 2025, with electric vehicle sales exceeding 2.3 million units and achieving an EV penetration rate of 8%, with EV fleet growth creating parallel demand for battery storage in public charging hubs, V2G-ready infrastructure, and EV OEM supplier ecosystems.
Market Restraints
- High Upfront Capital Costs for Large-Scale Deployments: Despite significant cost reductions, large-scale pumped hydro and battery storage systems require substantial capital investment that constrains deployment pace in markets without long-term revenue certainty or viability gap funding.
- Dependence on Imported Battery Cells: Domestic lithium-ion cell manufacturing capacity remains limited, creating supply chain vulnerability to global commodity prices and geopolitical disruptions affecting cell availability and cost.
Market Opportunities
- Green Hydrogen Production and Long-Duration Storage: India’s National Green Hydrogen Mission target of 5 million metric tons/year by 2030 is creating new applications for electrolyzers and hydrogen storage, extending ESS demand into long-duration and seasonal storage segments.
- Distributed Solar-Plus-Storage for Agricultural and Rural Markets: The PM KUSUM scheme and state agricultural feeder separation programs are creating viable distributed solar-storage deployment pipelines reaching rural and semi-urban markets.
Market Challenges
- Absence of Standardized Revenue Streams and Market Mechanisms for Storage: ESS project developers face difficulty in monetizing multiple value streams simultaneously due to the absence of well-defined ancillary service markets and merchant storage revenue frameworks at scale.
- Battery Safety, End-of-Life Management, and Recycling Infrastructure: Large-scale BESS deployment is creating emerging concerns around thermal management, fire safety protocols, and end-of-life battery recycling infrastructure, which remain underdeveloped across the sector.
Emerging Market Trends
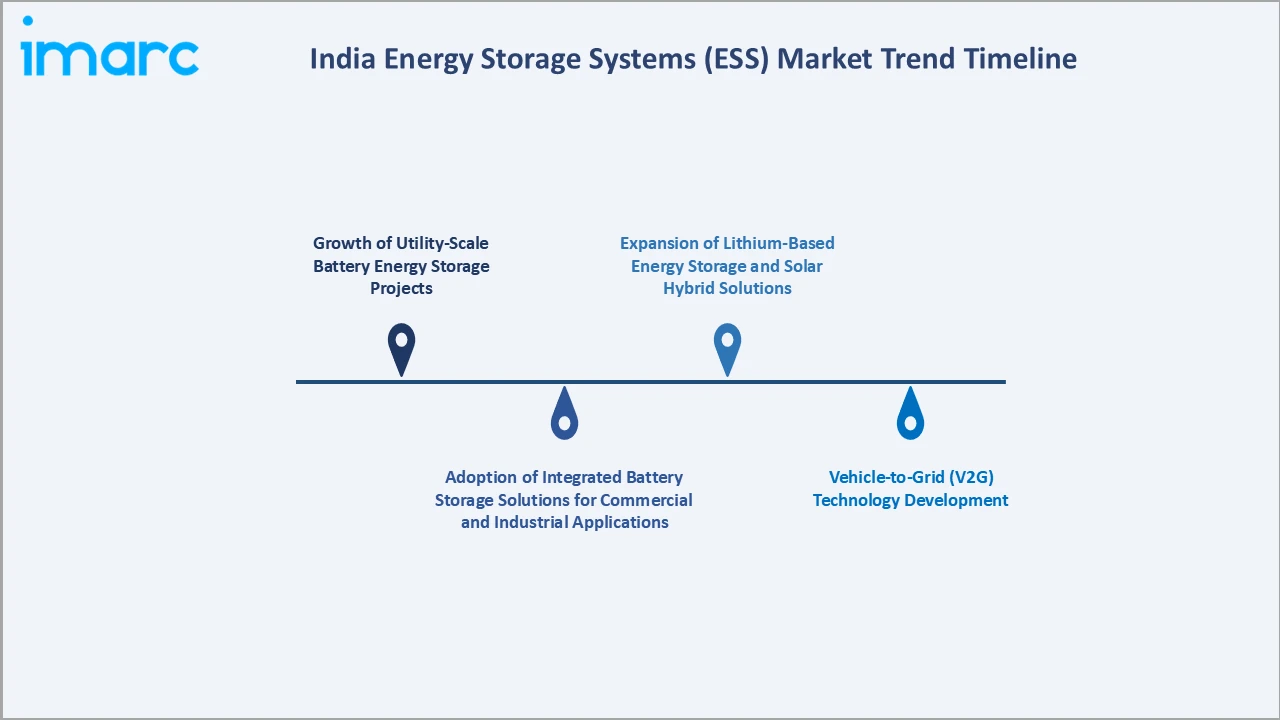
1. Growth of Utility-Scale Battery Energy Storage Projects
In May 2025, the Global Energy Alliance Leadership Council (GLC) announced the launch of India’s first utility-scale standalone Battery Energy Storage System (BESS) project, the largest of its kind in South Asia. The project marks the first major milestone for the BESS Consortium, a multi-stakeholder partnership led by the GLC. This trend is expected to drive investments in energy storage infrastructure and strengthen India’s capacity to manage fluctuations in solar and wind power generation.
2. Adoption of Integrated Battery Storage Solutions for Commercial and Industrial Applications
In October 2026, GoodWe unveiled its ESA 125 kW/251 kWh Battery Energy Storage System (BESS) at the Renewable Energy India Expo 2026, targeting commercial and industrial applications. The integrated system simplifies installation and maintenance while supporting scalable energy storage capacity of up to 3.91 MWh through parallel connections. These solutions support efficient energy management, grid reliability, and renewable energy integration while offering flexible capacity expansion to meet growing energy demands.
3. Expansion of Lithium-Based Energy Storage and Solar Hybrid Solutions
In October 2026, Electrent introduced a new range of lithium energy storage systems (ESS) and solar hybrid inverters at the Renewable Energy India Expo 2026 in Greater Noida. The expanded portfolio caters to residential, commercial, and industrial users, supporting power backup, solar integration, and efficient energy management. This trend reflects increasing adoption of integrated solutions for reliable power backup, solar energy utilization, and efficient energy management.
4. Vehicle-to-Grid (V2G) Technology Development
V2G technology, enabling bidirectional power flow between EV batteries and the grid, is entering early pilot stages in India. With India’s growing EV fleet, the aggregate battery storage capacity represented by on-road EVs will become a significant flexible resource for grid operators, creating new commercial models for EV-linked storage services.
Industry Value Chain Analysis
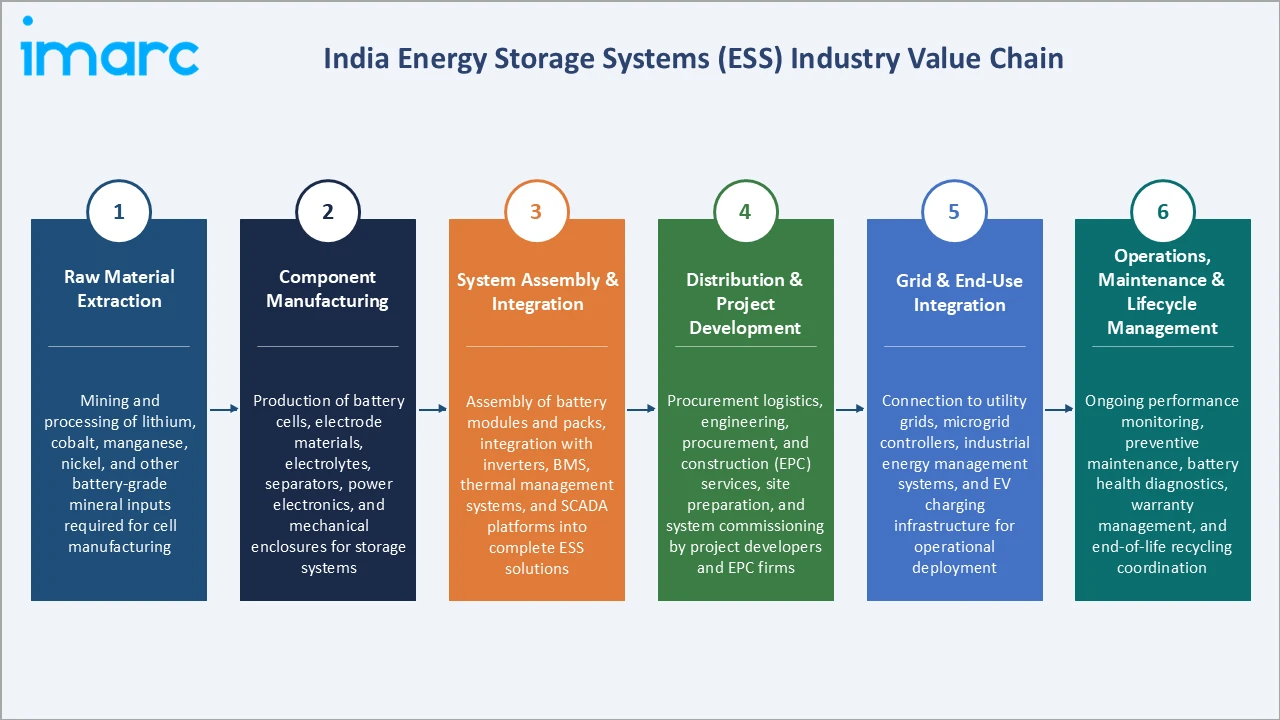
The India ESS value chain is structured across six integrated stages, from raw material extraction through end use and lifecycle management. Each stage contributes distinct value and faces unique competitive dynamics as the market scales.
| Stage | Description |
|---|---|
| Raw Material Extraction | Mining and processing of lithium, cobalt, manganese, nickel, and other battery-grade mineral inputs required for cell manufacturing. |
| Component Manufacturing | Production of battery cells, electrode materials, electrolytes, separators, power electronics, and mechanical enclosures for storage systems. |
| System Assembly & Integration | Assembly of battery modules and packs, integration with inverters, BMS, thermal management systems, and SCADA platforms into complete ESS solutions. |
| Distribution & Project Development | Procurement logistics, engineering, procurement, and construction (EPC) services, site preparation, and system commissioning by project developers and EPC firms. |
| Grid & End-Use Integration | Connection to utility grids, microgrid controllers, industrial energy management systems, and EV charging infrastructure for operational deployment. |
| Operations, Maintenance & Lifecycle Management | Ongoing performance monitoring, preventive maintenance, battery health diagnostics, warranty management, and end-of-life recycling coordination. |
The system assembly and integration stage holds the greatest strategic significance in the ESS value chain. System integrators combine battery packs, power conversion systems, energy management software, and grid interface hardware into deployable, warranted ESS solutions. As battery costs decline, integration quality, software intelligence, and safety assurance are becoming the primary value differentiators for project developers and utility buyers.
Technology Landscape in the India Energy Storage Systems (ESS) Industry
Electrochemical Storage Battery Systems
Lithium-ion battery systems, particularly LFP and NMC chemistry variants, dominate the electrochemical storage segment, accounting for the majority of new BESS procurement in utility and C&I segments. Advanced battery management systems (BMS) incorporating AI-driven predictive algorithms are extending battery cycle life and improving state-of-health diagnostics, reducing total lifecycle costs for project operators.
Electromechanical and Thermal Storage
Flywheel energy storage systems are deployed for short-duration frequency regulation applications in industrial facilities and data centers where cycle frequency and response speed are critical. Thermal storage using molten salt, phase change materials, and chilled water systems is gaining relevance in concentrating solar power (CSP) projects and industrial cooling applications, addressing demand peaks with zero direct carbon emissions.
Smart Grid and Digital Integration
Advanced energy management systems (EMS) and cloud-based monitoring platforms are being integrated with ESS installations to enable real-time optimization of charge-discharge cycles, grid signal response, and revenue stacking across multiple value streams. AI and machine learning applications are extending into predictive maintenance, yield forecasting, and automated dispatch strategies for grid-scale storage assets.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Technology | Pumped Hydro | 42.8% | 2025 |
| Application | Stationary | 68.4% | 2025 |
| End User | 🔒 | 🔒 | 2025 |
| Region | South India | 29.8% | 2025 |

By Technology
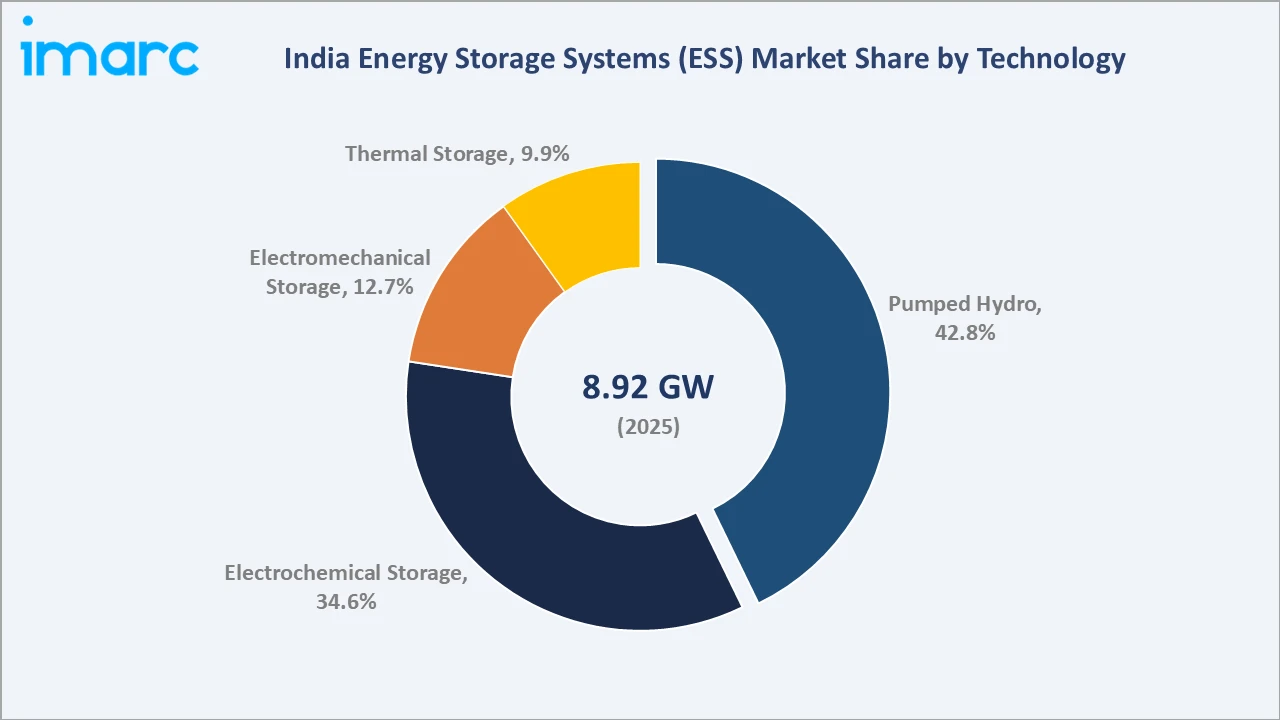
Pumped hydro leads at 42.8% in 2025, reflecting its role as India’s primary large-scale, long-duration storage resource. Its dominance is anchored by existing installed capacity serving peak demand management and seasonal balancing for state utilities and central grid operators.
To access detailed market analysis, Request Sample
Electrochemical storage at 34.6% is the fastest-growing segment, driven by rapidly falling lithium-ion battery costs and a growing pipeline of utility-scale BESS projects. This segment is projected to increase its share significantly through 2034 as new capacity additions favor battery storage for its modularity and faster deployment timelines. Electromechanical storage at 12.7% serves niche applications in frequency response and industrial power quality, while thermal storage at 9.9% supports CSP and industrial process cooling demand.
By Application
Stationary lead at 68.4% in 2025, encompassing grid-scale BESS, C&I backup and peak shaving, data center UPS, and renewable integration storage. This segment’s dominance reflects the immediate, policy-driven demand from utility and grid operators managing India’s rapidly scaling renewable energy fleet.
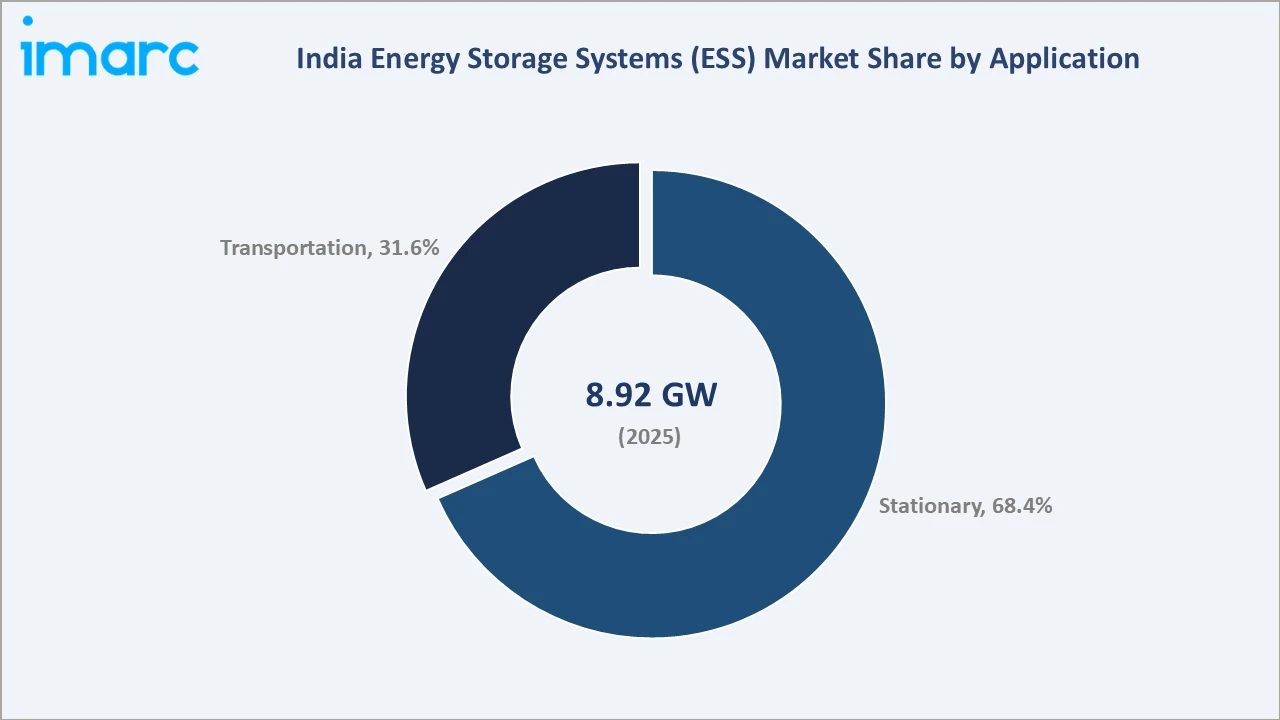
Transportation at 31.6% represents EV battery storage capacity and supporting charging infrastructure. Future growth will be driven by EV fleet electrification programs for public transit, commercial logistics, and three-wheeler segments, with transportation’s share expected to increase toward 2034 as the EV market matures.
Regional Market Insights
| Region | Share (2025) | Key Drivers & Characteristics |
|---|---|---|
| South India | 29.8% | Highest solar generation capacity with significant renewable curtailment, driving large-scale BESS demand for grid balancing and RTC power supply contracts. |
| North India | 27.3% | Large renewable energy zones in Rajasthan and Himachal hydro assets, combined with industrial demand and government smart grid programs. |
| West India | 26.7% | Strong industrial base in Gujarat and Maharashtra generating C&I peak shaving demand, alongside growing solar-plus-storage project pipeline. |
| East India | 16.2% | Expanding grid infrastructure, coal-to-clean energy transition programs, and growing industrial power demand are creating emerging storage opportunities. |
South India leads with a 29.8% share in 2025, supported by its position as India’s largest solar energy hub. States including Tamil Nadu, Andhra Pradesh, Telangana, and Karnataka have announced large-scale BESS procurement programs to manage high renewable penetration and improve grid reliability.
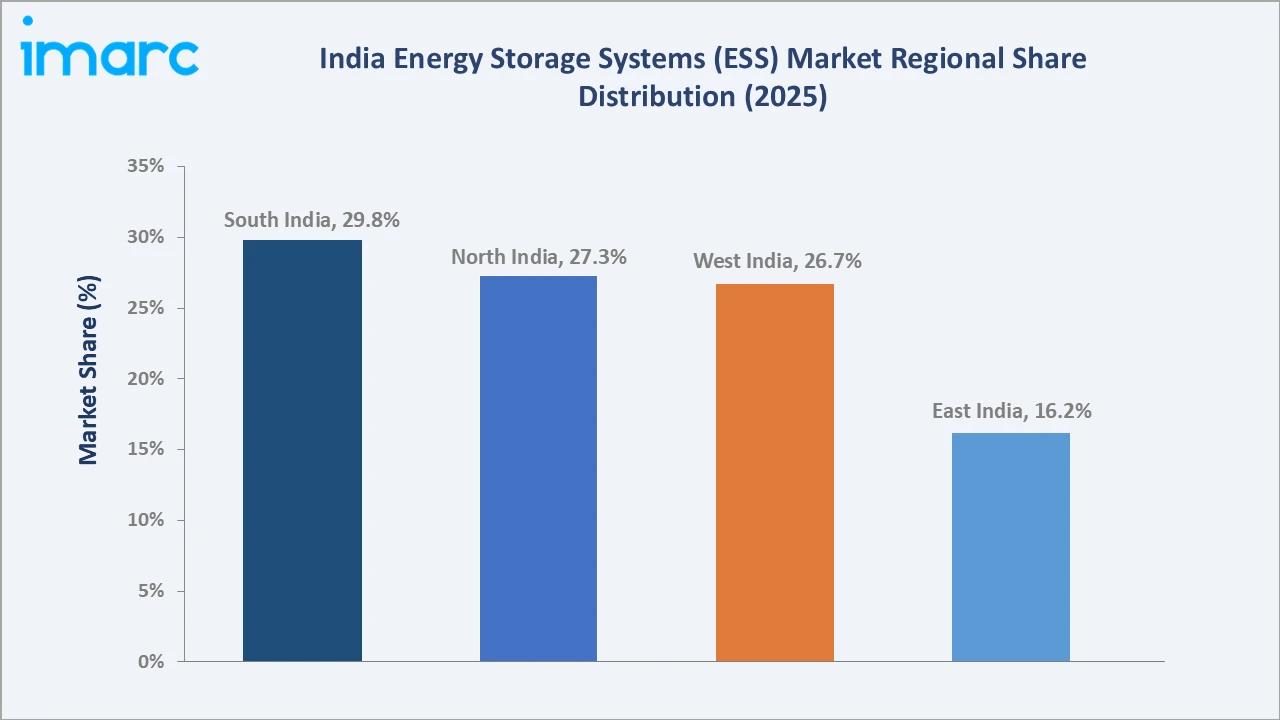
North India at 27.3% benefits from a vast solar development pipeline and existing pumped hydro capacity. West India at 26.7% is anchored by renewable energy leadership and industrial and commercial storage demand. East India at 16.2%, while currently the smallest region, represents a significant growth opportunity as grid infrastructure investment and industrial expansion accelerate across the region.
Competitive Landscape
The India ESS market exhibits moderate concentration at the utility-scale segment level, where a limited number of large integrated energy companies, public sector undertakings (PSUs), and specialized storage technology providers compete for large project awards. The broader market, encompassing distributed, C&I, and transportation storage, is significantly more fragmented, with numerous domestic battery manufacturers, EPC firms, and system integrators participating across regional markets.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Tata Group | MySine Prime, MySine Prime Plus | Market Leader | The Tata Group plays a leading role in India's energy storage systems sector through integrated power generation, grid-scale battery installations, and domestic manufacturing joint ventures. |
| Adani Group | Adani BESS Projects | Market Leader | The Adani Group, primarily through Adani Green Energy Limited, plays a leading role in India's Battery Energy Storage Systems (BESS) sector. |
| Solar Energy Corporation of India Limited (SECI) | 250 MW/500 MWh Standalone BESS tender | Established Player | The Solar Energy Corporation of India Limited (SECI) acts as a primary catalyst, tender issuer, and intermediary for scaling Energy Storage Systems (ESS) in India's power grid. |
| NTPC Limited | Thermal Energy Storage Systems (TESS), Long Duration Energy Storage (LDES) | Established Player | NTPC Limited plays a central role in India’s energy storage landscape as the country’s largest power utility, driving large-scale grid stabilization, peak-load management, and the integration of variable renewable energy. |
| Waaree Energies Ltd. | WOLT - C&I Series, Residential/Home ESS | Innovator | Waaree Energies Ltd. plays a critical role in building India's integrated Battery Energy Storage System (BESS) and clean energy manufacturing ecosystem. |
Competition is intensifying as large renewable developers vertically integrate storage capabilities, PSUs receive mandates for storage-coupled renewable portfolios, and domestic battery manufacturers invest in scaling production. International technology partners and battery cell suppliers are entering strategic partnerships with Indian project developers to combine technology expertise with local market access.
Key Company Profiles
Tata Group
Tata Group is strengthening its presence in India’s Energy Storage Systems Market through its companies, particularly Tata Power. Tata Power is expanding its battery energy storage system (BESS) projects to support renewable energy integration, grid stability, and reliable power supply.
- Key Offerings: MySine Prime, MySine Prime Plus.
- Strategic Focus: The company is expanding its energy storage footprint through integrated solar-plus-storage EPC offerings, strategic partnerships with battery technology providers, and long-term service agreements for C&I storage deployments across India.
Adani Group
Adani Group is strengthening its position in India’s Energy Storage Systems Market through Adani Green Energy Limited, focusing on large-scale battery energy storage systems (BESS) and pumped hydro storage projects. The group is integrating energy storage with its renewable energy portfolio to improve grid stability, manage peak electricity demand, and enable reliable, round-the-clock clean power supply. Its flagship BESS project at Khavda, Gujarat, represents a major investment in utility-scale storage infrastructure.
- Key Offerings: Adani BESS Projects.
- Key Developments: In June 2026, Adani Green Energy Limited (AGEL) increased its operational Battery Energy Storage System (BESS) capacity at Khavda, Gujarat, to 6.63 GWh, up from 3.55 GWh. This accounts for over 50% of India’s total operational BESS capacity of approximately 12.6 GWh, establishing Khavda as the world’s largest operational battery storage installation at a single location.
- Strategic Focus: The company is pursuing vertical integration across the renewable-storage value chain, investing in domestic solar module manufacturing, co-located BESS deployment, and long-term O&M capability to reduce project lifecycle costs and strengthen competitiveness in large-scale tenders.
Market Concentration Analysis
The India ESS market exhibits moderate concentration at the utility-scale level, where a limited number of integrated renewable developers, PSUs, and storage technology providers compete for large project awards. These players benefit from established utility relationships, balance sheet strength for long-tenor financing, and the ability to package storage with generation assets in hybrid tenders.
The broader ESS market, encompassing C&I, industrial backup, and transportation segments, is significantly fragmented, with regional EPC firms, battery integrators, and technology resellers serving diverse end users. As procurement standards mature, consolidation through partnerships and vertical integration is expected to gradually increase market concentration.
Investment & Growth Opportunities
Highest Growth Segments
Electrochemical storage at 34.6% (2025) represents the fastest-growing and highest investment priority segment, driven by utility-scale BESS procurement mandates, declining LFP battery costs, and corporate renewable + storage PPAs.
Investment Themes
- Domestic Battery Cell Manufacturing: The PLI scheme for advanced chemistry cells is channeling investment into domestic lithium-ion cell production. Cell manufacturing capacity building represents a multi-billion-dollar investment opportunity for both domestic industrial groups and international battery manufacturers seeking an India manufacturing presence.
- Green Hydrogen and Long-Duration Storage: India’s National Green Hydrogen Mission is creating investment opportunities across electrolyzers, hydrogen storage infrastructure, and downstream fuel cell applications, extending the ESS investment universe into long-duration and seasonal storage solutions.
Future Market Outlook (2026-2034)
The India energy storage systems market grew from 8.92 GW in 2025 to 9.53 GW in 2026 and is projected to reach 16.19 GW by 2034, growing at a CAGR of 6.84% during 2026-2034. This trajectory reflects sustained policy momentum, rapidly declining battery technology costs, and structural demand from India’s renewable energy scale-up across both utility and distributed segments.
Three structural forces will define the India ESS market through 2034. First, India’s 500 GW renewable target mandates commensurate storage for grid stability and RTC power supply. Second, declining lithium-ion prices will unlock merchant storage deployment at scale. Third, the EV transition will add distributed storage capacity, with V2G integration creating a flexible grid-accessible pool.
Research Methodology
Primary Research
Primary research comprised structured consultations with ESS project developers, utility procurement executives, battery manufacturers, and EPC contractors. Expert interviews validated market sizing, technology adoption trends, and project pipeline data.
Secondary Research
Secondary research was drawn from published data along with company annual reports. PLI scheme documentation, project databases, and international energy storage association reports supplemented primary findings on technology trends and cost curves.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling incorporating historical capacity data, government renewable targets, PLI mandates, and technology cost trajectories. Scenario analysis using GDP growth and policy timelines provided cross-validation.
India Energy Storage Systems (ESS) Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | GW |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Technologies Covered |
Pumped Hydro, Electrochemical Storage, Electromechanical Storage, Thermal Storage |
| Applications Covered | Stationary, Transportation |
| End Users Covered | Residential, Non-Residential, Utilities |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Tata Group, Adani Group, Solar Energy Corporation of India Limited (SECI), NTPC Limited, Waaree Energies Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India energy storage systems (ESS) market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India energy storage systems (ESS) market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India energy storage systems (ESS) industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Energy Storage Systems (ESS) Market Report
The India energy storage systems (ESS) market reached 9.53 GW in 2026, driven by renewable integration demand, PLI scheme support, and expanding grid modernization programs.
The market is projected to grow at a CAGR of 6.84% during 2026-2034, supported by renewable scale-up, battery cost declines, and EV fleet expansion.
The market is projected to reach approximately 12.42 GW by 2030, driven by large utility-scale BESS deployments and growing transportation storage demand.
Pumped hydro leads with a 42.8% share in 2025, reflecting large installed capacity and India’s significant technical potential for additional PSH development.
Stationary applications lead with a 68.4% share in 2025, driven by utility grid integration, C&I backup, and renewable energy storage requirements.
South India leads with a 29.8% share in 2025, anchored by high solar capacity and large-scale BESS procurement programs in Tamil Nadu, Andhra Pradesh, and Karnataka.
Key players include Tata Group, Adani Group, Solar Energy Corporation of India Limited (SECI), NTPC Limited, and Waaree Energies Ltd., among others.
The market is projected to reach 16.19 GW by 2034, driven by renewable buildout, EV fleet growth, and expanding C&I and industrial storage adoption.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade