
India Microgreens Market Size, Share, Trends and Forecast by Type, Farming Method, End Use, Distribution Channel, and Region, 2026-2034
India Microgreens Market Size, Share, Trends & Forecast (2026-2034)
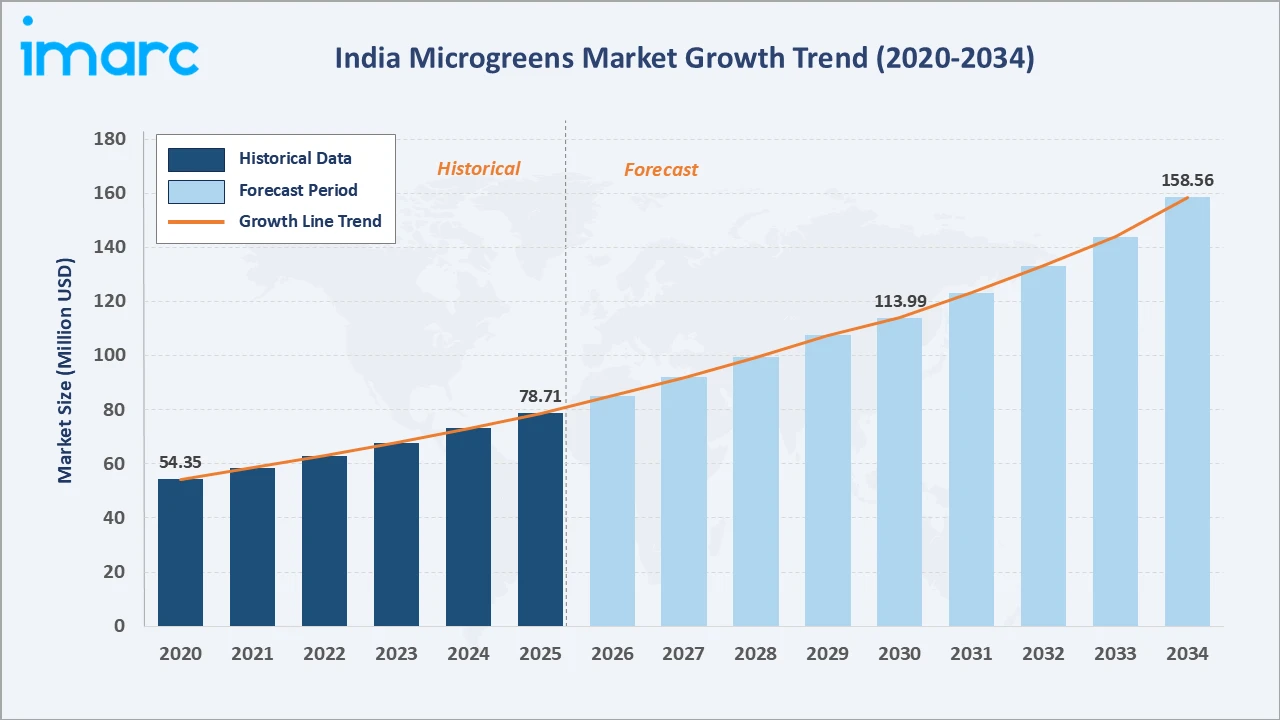
The India microgreens market grew from USD 78.71 Million in 2025 to USD 87.67 Million in 2026 and is projected to reach USD 158.56 Million by 2034, growing at a CAGR of 7.69% during 2026-2034. The market is propelled by rising consumer awareness of nutrient-dense superfoods, expanding urban farming infrastructure, and increasing adoption of plant-based diets across India's health-conscious urban demographics. Indoor vertical farming leads at 48.7% by farming method, broccoli dominates at 18.6% by type, and West and Central India command the largest regional share at 32.6% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 78.71 Million |
|
Market Size (2026) |
USD 87.67 Million |
|
Forecast Market Size (2034) |
USD 158.56 Million |
|
CAGR (2026-2034) |
7.69% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Broccoli (18.6%, 2025) |
|
Dominant Farming Method |
Indoor Vertical Farming (48.7%, 2025) |
|
Leading Region |
West and Central India (32.6%, 2025) |
The India microgreens market grew from USD 54.35 Million in 2020 to USD 78.71 Million in 2025, and further to USD 87.67 Million in 2026, reflecting sustained growth across health food and urban agriculture segments. The market is projected to reach USD 113.99 Million by 2030 before attaining USD 158.56 Million by 2034.
To get more information on this market, Request Sample
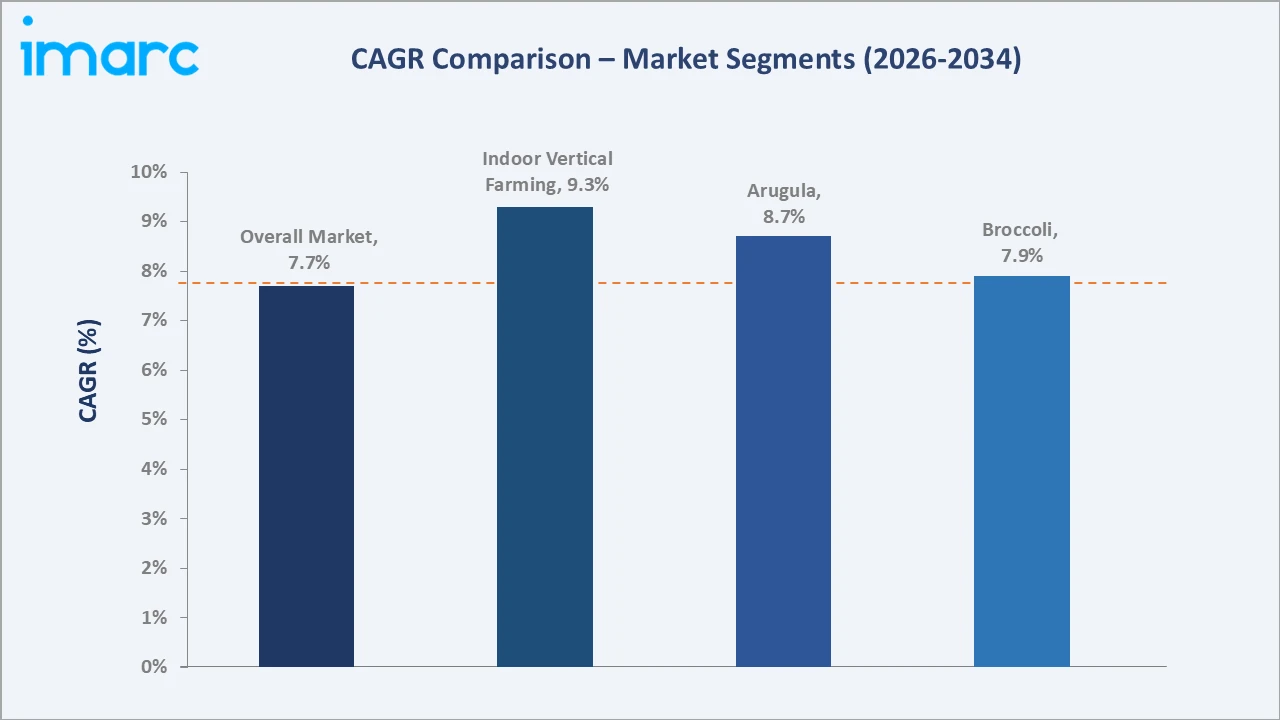
Indoor vertical farming expands at approximately 9.3% CAGR, driven by controlled environment agriculture adoption enabling year-round, pesticide-free production. Arugula, at an 8.7% CAGR, benefits from rising gourmet food demand across restaurants and premium retail. Broccoli microgreens grow at 7.9% CAGR, underpinned by institutional procurement and strong health-store consumer recognition.
Executive Summary
The India microgreens market is on an accelerating growth trajectory, underpinned by rising consumer health consciousness, rapid urbanization, and the expanding availability of locally grown, nutrient-dense functional foods. Microgreens are harvested within 7-14 days of germination and are recognized for containing higher nutrient concentrations than mature vegetables, positioning them as premium functional foods within India's fast-growing health economy.
Indoor vertical farming commands 48.7% of the market in 2025, reflecting the scalability, year-round productivity, and quality consistency advantages of controlled environment agriculture. Broccoli leads by type at 18.6%, followed by arugula at 14.7% and cabbage at 13.2%. West and Central India lead regionally at 32.6%, supported by health-conscious urban consumer bases in Mumbai, Pune, and Ahmedabad, alongside an active premium restaurant and hospitality ecosystem.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Type | Broccoli - 18.6% share (2025) |
| Dominant Farming Method | Indoor Vertical Farming - 48.7% share (2025) |
| Leading Region | West and Central India - 32.6% (2025) |
| Key Market Opportunity | Expanding institutional demand from the hospitality sector and premium retail chains, combined with growing e-commerce adoption, is creating high-value distribution channels for microgreens producers. |
Key Analytical Observations Supporting the Above Data:
- Broccoli at 18.6%: Broccoli microgreens command the largest share due to strong sulforaphane content, high consumer name recognition, and wide availability across health food retail and online grocery platforms in major metros.
- Indoor Vertical Farming at 48.7%: Controlled environment agriculture enables year-round, pesticide-free production with consistent quality, making it the preferred method among commercial growers targeting premium retail and institutional buyers.
- West and Central India at 32.6%: The region leads due to a dense health-conscious urban consumer base, combined with an active restaurant and premium hospitality sector that sources fresh specialty ingredients locally.
India Microgreens Market Overview
Microgreens are young greens harvested at the cotyledon leaf stage, typically within 7-14 days after germination, and are valued for exceptional nutrient density, vibrant flavor profiles, and culinary versatility. The India microgreens market encompasses the growing, processing, packaging, and distribution of microgreens across residential, institutional, and commercial foodservice channels nationwide.
The market ecosystem spans seed and input suppliers, controlled environment agriculture technology providers, urban and peri-urban growers, cold-chain packaging specialists, and retail, e-commerce, and institutional end-user channels. Macroeconomic drivers include rising urban disposable income, an expanding middle-class preference for premium health foods, and India's nutraceutical sector growth, creating a strong complementary demand environment for microgreens.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
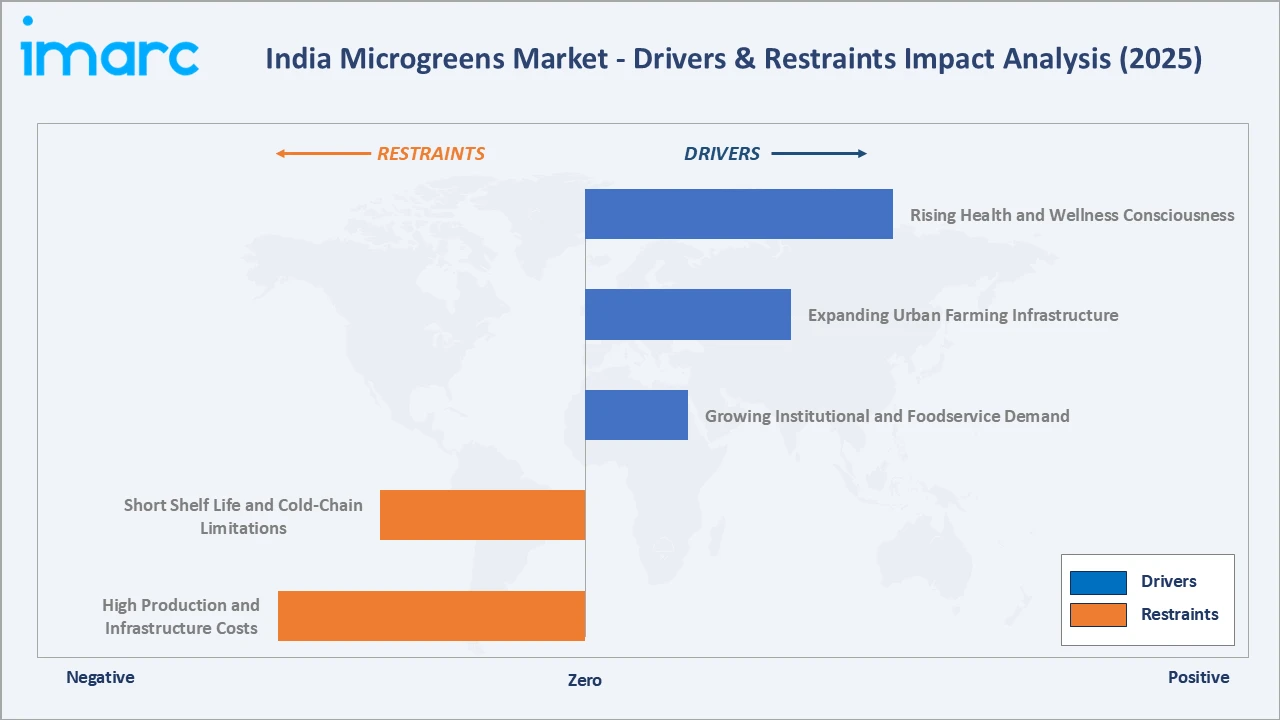
- Rising Health and Wellness Consciousness: Urban population in India is projected to reach 600 million by 2036. Urban Indian consumers increasingly prioritize nutrient-dense functional foods, with health food sales growing. Microgreens, containing 4-40 times the nutrients of mature vegetables, are gaining mainstream acceptance across health-conscious urban demographics.
- Expanding Urban Farming Infrastructure: Growing availability of controlled environment agriculture equipment, hydroponic grow kits, and urban farming training programs is lowering barriers to entry for commercial producers. India's urban farming sector is expected to grow 10% by 2026, creating scalable supply capacity.
- Growing Institutional and Foodservice Demand: Hotels, specialty restaurants, and wellness cafes are sourcing microgreens for culinary differentiation and menu premiumization. India's foodservice sector creates a large and growing institutional demand base for fresh, locally grown microgreens.
Market Restraints
- High Production and Infrastructure Costs: Controlled environment agriculture setups require significant upfront investment in lighting, climate control, and hydroponic systems, limiting scalability for small and medium-scale growers entering the market.
- Short Shelf Life and Cold-Chain Limitations: Microgreens have a limited post-harvest shelf life of 5-10 days, requiring efficient cold-chain logistics that remain underdeveloped across many secondary and tertiary Indian markets.
Market Opportunities
- Export Market Potential: Growing global demand for Indian specialty food products and organic greens presents an emerging export opportunity, particularly in Middle East, Southeast Asia, and North America markets where Indian diaspora communities drive specialty food demand.
- Corporate Wellness Programs: Growing corporate interest in employee wellness and healthy canteen offerings is creating new B2B demand for regular microgreens supply across corporate campuses in India's technology and business hub cities.
Market Challenges
- Quality Standardization: Absence of uniform quality grading standards creates variability in product quality and consumer expectations, making it difficult for institutional buyers to ensure consistency across multiple suppliers.
- Seasonal Supply Variability: Traditional outdoor microgreens production faces seasonal challenges affecting consistent supply, while indoor farming infrastructure investments remain financially prohibitive for many small-scale producers.
Emerging Market Trends
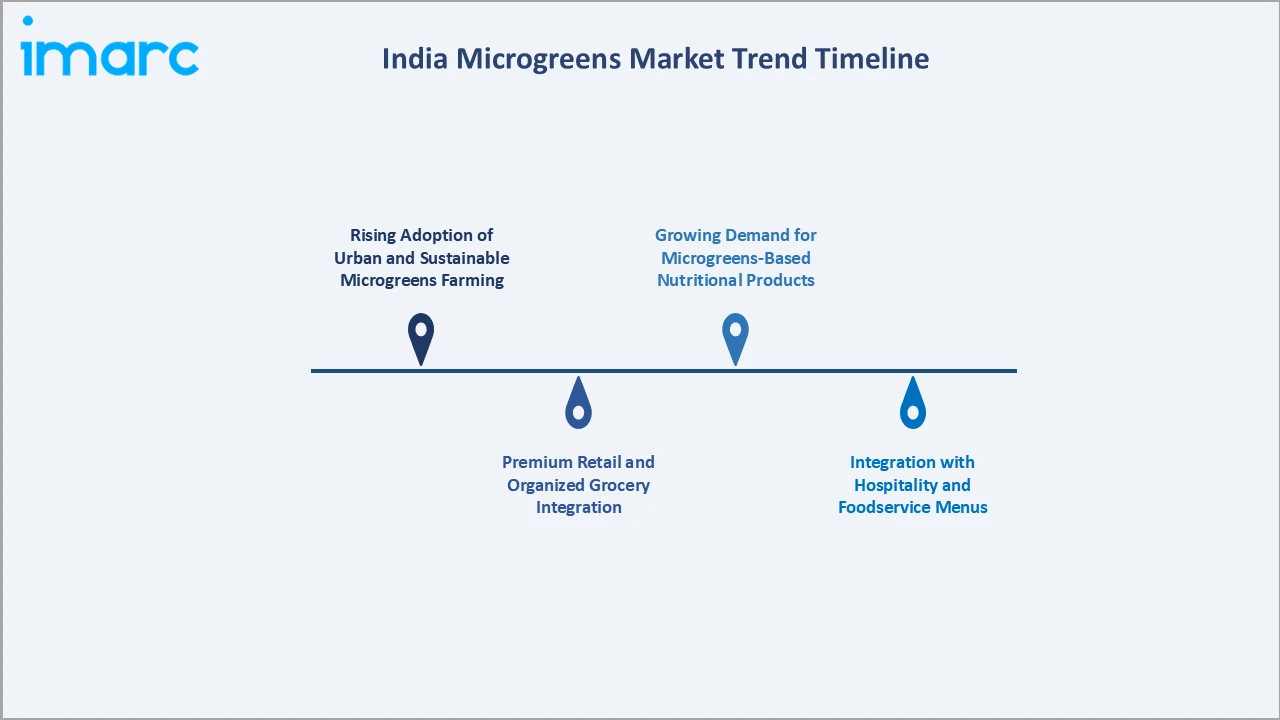
1. Rising Adoption of Urban and Sustainable Microgreens Farming
The adoption of space-efficient indoor farming, organic cultivation methods, and controlled-environment agriculture is creating opportunities for startups, urban farmers, and local suppliers to expand production and distribution. Former pharma executive Mohit Nijhawan built Greenu into a ₹12 lakh-per-month organic microgreens business, cultivating over 75 varieties and training more than 300 farmers across India using sustainable farming methods.
2. Premium Retail and Organized Grocery Integration
Organized retail supermarkets, specialty health food stores, and premium grocery chains are expanding fresh microgreens shelf sections in response to growing consumer demand. Retail presence in organized trade channels accelerates mainstream adoption beyond niche health food consumers, broadening the urban shopper base for fresh microgreens.
3. Growing Demand for Microgreens-Based Nutritional Products
Products combining microgreens are gaining attention among health-conscious consumers seeking easy ways to incorporate nutrient-rich ingredients into their daily diets. In September 2026, Keystone NeoGreens introduced Daily Greens in India, a powdered microgreens blend combining alfalfa, kale, broccoli, coriander, and sunflower. The supplement is designed to support gut health and provide convenient daily nutrition.
4. Integration with Hospitality and Foodservice Menus
Five-star hotels, specialty restaurants, and wellness cafes are incorporating microgreens as signature garnishes, salad bases, and premium ingredient differentiators. Institutional adoption drives premium pricing for producers while simultaneously building consumer awareness through dining experiences that subsequently translate into retail purchasing behavior.
Industry Value Chain Analysis
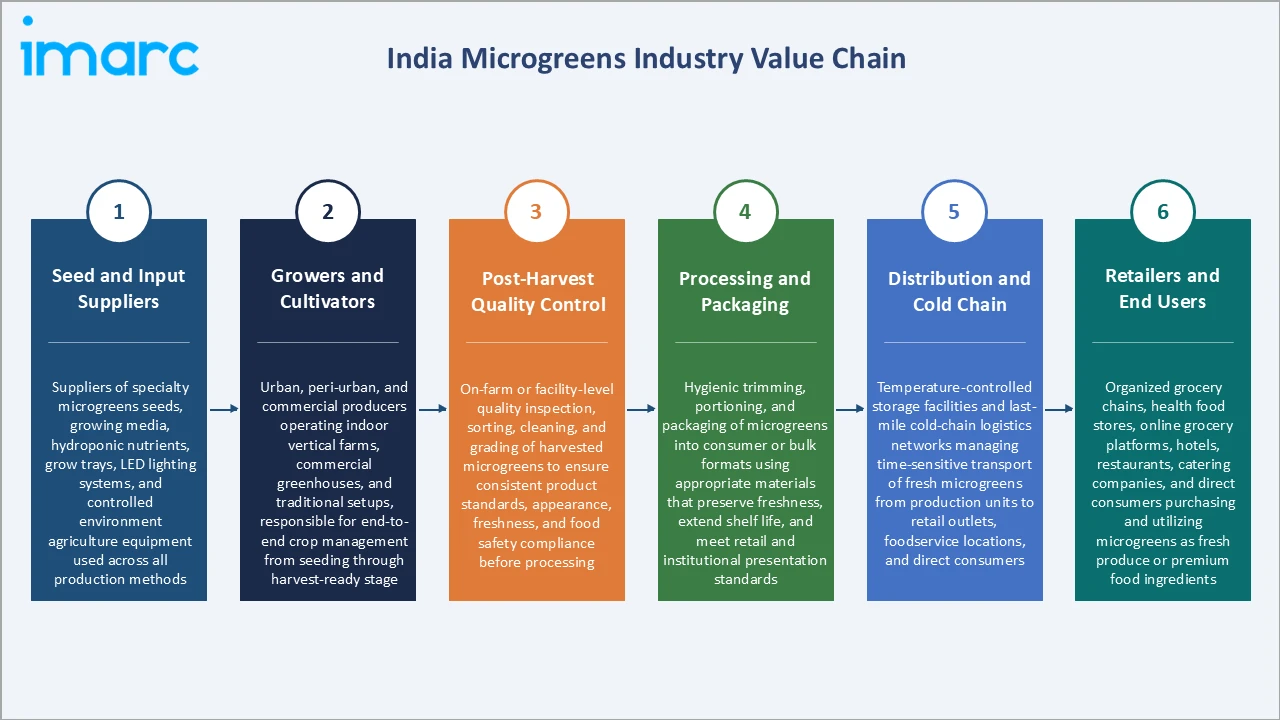
The India microgreens value chain spans six integrated stages from seed and input supply through end-user consumption. Each stage creates distinct value through cultivation, quality control, processing, packaging, and distribution, with the highest value addition occurring at the growing and cultivation stage where controlled environment agriculture expertise and consistent quality management create durable competitive advantages.
| Stage | Key Functions |
|---|---|
| Seed and Input Suppliers | Suppliers of specialty microgreens seeds, growing media, hydroponic nutrients, grow trays, LED lighting systems, and controlled environment agriculture equipment used across all production methods. |
| Growers and Cultivators | Urban, peri-urban, and commercial producers operating indoor vertical farms, commercial greenhouses, and traditional setups, responsible for end-to-end crop management from seeding through harvest-ready stage. |
| Post-Harvest Quality Control | On-farm or facility-level quality inspection, sorting, cleaning, and grading of harvested microgreens to ensure consistent product standards, appearance, freshness, and food safety compliance before processing. |
| Processing and Packaging | Hygienic trimming, portioning, and packaging of microgreens into consumer or bulk formats using appropriate materials that preserve freshness, extend shelf life, and meet retail and institutional presentation standards. |
| Distribution and Cold Chain | Temperature-controlled storage facilities and last-mile cold-chain logistics networks managing time-sensitive transport of fresh microgreens from production units to retail outlets, foodservice locations, and direct consumers. |
| Retailers and End Users | Organized grocery chains, health food stores, online grocery platforms, hotels, restaurants, catering companies, and direct consumers purchasing and utilizing microgreens as fresh produce or premium food ingredients. |
The growing and cultivation stage holds the greatest strategic significance in the microgreens value chain. Producers operating controlled environment agriculture facilities benefit from year-round production capability, pesticide-free certification, and superior crop consistency that enable premium pricing in retail and institutional supply channels.
Technology Landscape in the India Microgreens Industry
Controlled Environment Agriculture
Advanced indoor growing systems with LED spectrum-optimized lighting, automated climate control, and precision nutrient delivery enable consistent product quality, higher crop yields, and faster harvest cycles. These systems typically achieve 6-8 growing cycles per year per production unit, dramatically improving capital efficiency compared to seasonal outdoor growing.
Hydroponic and Aeroponic Growing Systems
Soil-free growing systems, including hydroponic deep-water culture and nutrient film techniques, are gaining adoption for microgreens production. These methods consume less water than soil-based cultivation, enable faster root development, and produce cleaner harvests requiring minimal washing, directly improving post-harvest shelf life.
Smart Farm Management Platforms
IoT-enabled farm management software is increasingly used by commercial producers to monitor temperature, humidity, CO2 levels, and nutrient concentrations in real time. Automated alerts and data analytics enable producers to optimize growing conditions and minimize crop loss, improving operational efficiency and supply reliability for institutional buyers.
Sustainable Packaging Innovation
Biodegradable, compostable, and modified atmosphere packaging solutions are gaining traction as producers respond to retail and consumer demand for sustainable packaging. Modified atmosphere packaging can extend microgreens' shelf life, significantly improving supply chain flexibility for producers serving non-local markets.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Broccoli | 18.6% | 2025 |
| Farming Method | Indoor Vertical Farming | 48.7% | 2025 |
| End Use | 🔒 | 🔒 | 2025 |
| Distribution Channel | 🔒 | 🔒 | 2025 |
| Region | West and Central India | 32.6% | 2025 |

By Type
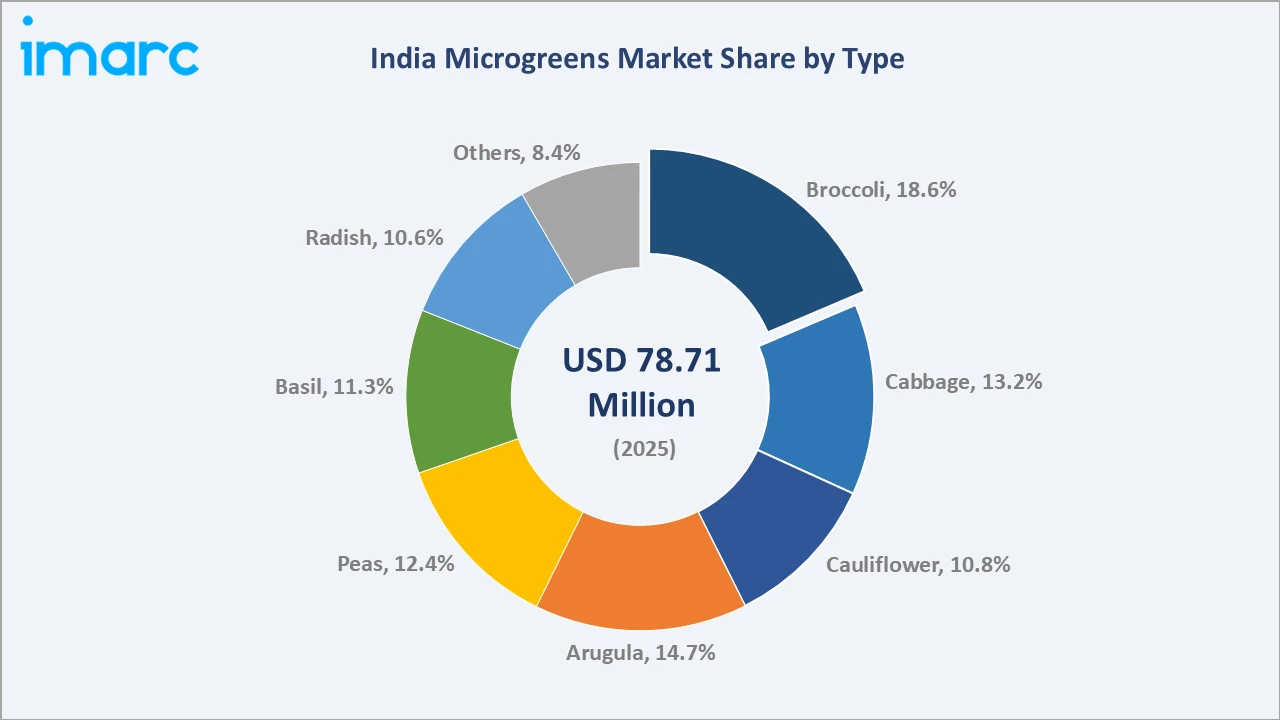
Broccoli leads with 18.6% share in 2025, driven by strong consumer recognition, high sulforaphane antioxidant content, and widespread availability across health food retail and online grocery. Arugula follows at 14.7%, favored for its distinctive peppery flavor and culinary versatility in premium restaurant and home cooking applications.
To access detailed market analysis, Request Sample
Cabbage accounts for 13.2% and offers a mild flavor profile with broad consumer appeal. Peas at 12.4% are valued for sweet flavor and high protein content, particularly among fitness-oriented consumers. Basil at 11.3% serves strong demand from gourmet cooking, while cauliflower at 10.8% and radish at 10.6% complete the core variety range. Others, including sunflower, amaranth, and edible flowers, account for 8.4%.
By Farming Method
Indoor vertical farming dominates with a 48.7% share in 2025, reflecting strong preference among commercial producers targeting premium urban retail and institutional buyers. This method enables year-round production, eliminates pesticide use, and delivers superior quality consistency compared to outdoor and greenhouse alternatives.
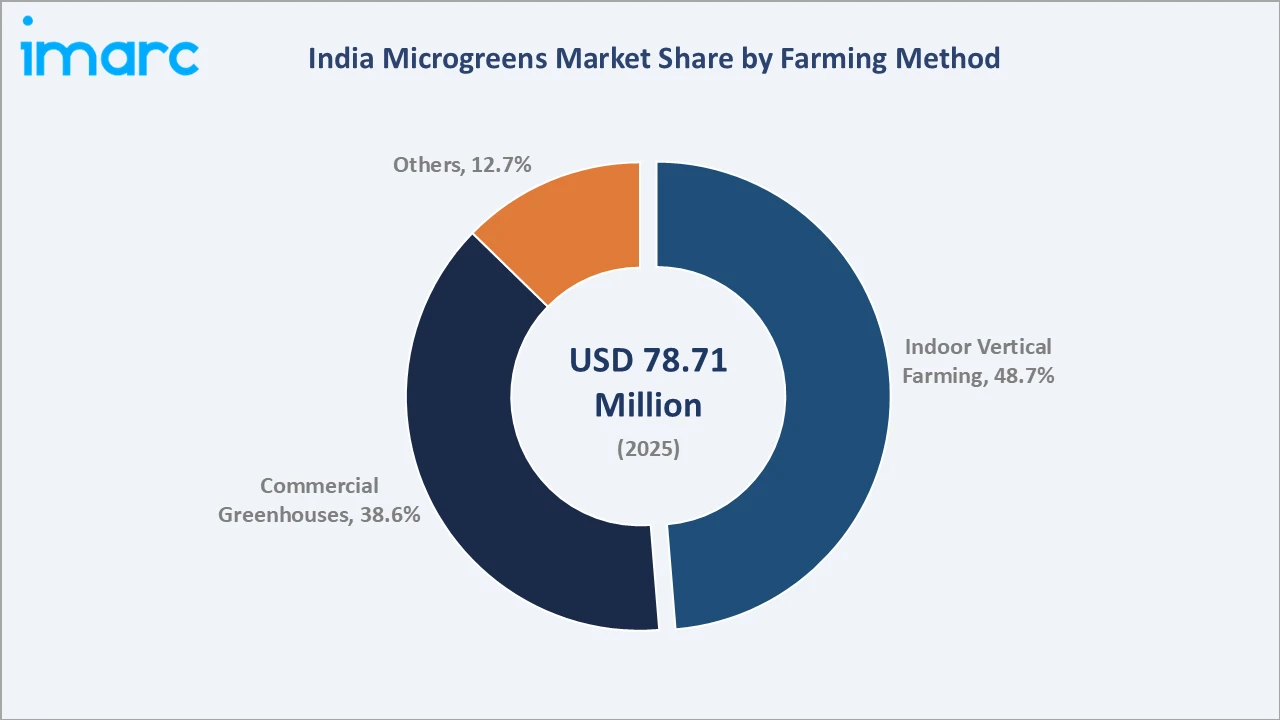
Commercial greenhouses account for 38.6%, representing established producers who leverage natural light supplemented by artificial lighting to balance production costs with quality output, suitable for medium-to-large scale operations requiring higher volumes at lower per-unit infrastructure investment. Others at 12.7% include traditional soil-based and hobby-scale producers serving local direct-to-consumer markets through farmers' markets and community agriculture programs.
Regional Market Insights
| Region | Share (2025) | Key India Microgreens Market Drivers & Characteristics |
|---|---|---|
| West and Central India | 32.6% | Dense urban health-conscious consumer base, active premium restaurant and hospitality sector, and strong direct-to-consumer e-commerce adoption driving premium microgreens demand. |
| South India | 29.8% | Technology sector-driven wellness culture, expanding premium retail and specialty food channels, and rising institutional demand from corporate campuses and five-star hospitality. |
| North India | 24.1% | Large urban population base, growing awareness of functional foods, expanding organized retail presence, and institutional demand from hospitality and catering sectors in metro cities. |
| East and Northeast India | 13.5% | Emerging market with growing urban consumer awareness, increasing presence of organized retail, and developing urban farming initiatives creating new production and consumption capacity. |
West and Central India lead at 32.6%, reflecting the high concentration of health-conscious urban consumers and an active premium restaurant ecosystem. South India at 29.8% is anchored by technology-sector-driven wellness culture and growing premium institutional demand.
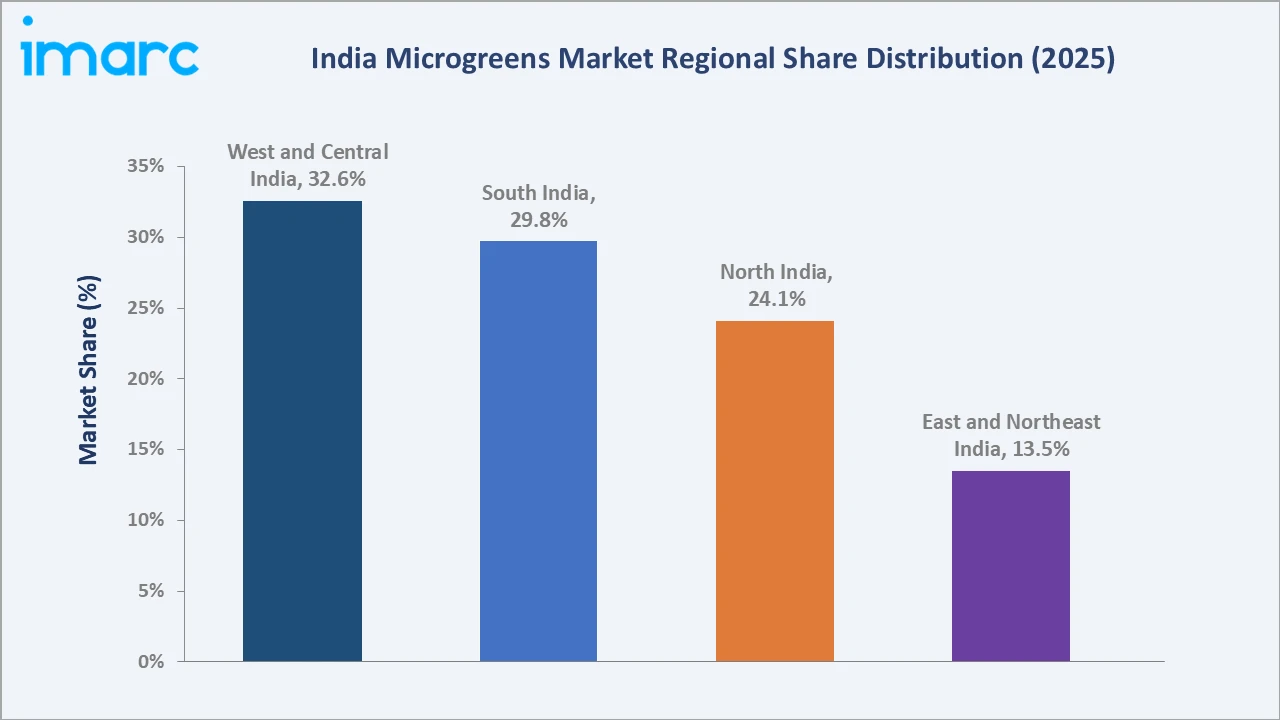
North India at 24.1% benefits from a large urban consumer base in Delhi NCR and growing organized retail penetration. East and Northeast India at 13.5% remains the smallest contributor but exhibits emerging growth momentum as urban farming awareness expands and organized retail reaches secondary cities across the region.
Competitive Landscape
The India microgreens market is highly fragmented, with a mix of specialized urban farming startups, established fresh produce companies, and commercial greenhouse operators. Market differentiation is driven by production quality consistency, cold-chain reliability, organic certification, and the ability to supply institutional buyers at scale.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Greenu | Alfalfa, Arugula, Basil, Broccoli | Market Leader | Greenu Microgreens plays a pioneering role in India's urban farming and functional food market by supplying over 75 varieties of organic, hydroponically grown microgreens, DIY grow kits, and non-GMO seeds. |
| NeoGreens | Daily Greens | Market Leader | NeoGreens (Keystone NeoGreens) plays a pioneering role in the Indian microgreens and daily wellness market by launching Daily Greens, marketed as the multi-microgreens powder blend. |
| Waraah Green Technologies Private Limited | NIRAAN, KIDDYCO | Established Player | Waraah Green Technologies Private Limited is an Indian wellness and FMCG company that builds plant-based foods, functional energy drinks, kids' nutrition, and Ayurvedic skincare around a single core ingredient: microgreens. |
| Red Otter Farms | Beet Microgreens | Niche Player | Red Otter Farms is a pioneer in India's sustainable and soilless agriculture, known for producing varieties of microgreens alongside specialty salad greens. |
Competition in India's microgreens market is intensifying as urban farming startups and fresh produce companies expand production capacity and distribution reach. Differentiation is driven by organic certification, consistent quality, cold-chain reliability, and the ability to service institutional buyers at volume and price points that sustain long-term supply contracts.
Key Company Profiles
Greenu
Greenu is an Indian microgreens company founded by Mohit Nijhawan under Embryonic Greens. The company focuses on producing fresh, nutrient-rich microgreens using indoor farming and sustainable cultivation practices. Its product portfolio includes over 75 varieties of microgreens, along with seeds, grow kits, and edible flowers. Greenu also promotes microgreens cultivation through farmer training and entrepreneurship support. The company aims to encourage healthier food choices while supporting sustainable agriculture in India.
- Key Offerings: Alfalfa, Arugula, Basil, Broccoli.
- Strategic Focus: Expanding its microgreens product portfolio, promoting sustainable farming practices, and increasing access to fresh, nutrient-rich produce. The company also emphasizes farmer training, cultivation techniques, and strengthening its distribution network to support the growth of India’s microgreens market.
NeoGreens
NeoGreens is an India-based nutrition and wellness company focused on developing microgreens-based nutritional products. The company combines nutrition science, food technology, and agricultural innovation to create convenient daily nutrition solutions. Its flagship product, Daily Greens, features a blend of microgreens, including alfalfa, kale, broccoli, coriander, and sunflower. NeoGreens aims to make plant-based nutrition more accessible through easy-to-consume products. The company focuses on product innovation, quality, and promoting everyday nutritional wellness.
- Key Offerings: Daily Greens.
- Strategic Focus: Developing convenient, microgreens-based nutritional products that cater to growing consumer demand for plant-based wellness solutions. The company emphasizes product innovation, ingredient diversity, and expanding market reach by promoting easy-to-consume nutrition blends for health-conscious consumers in India.
Market Concentration Analysis
The India microgreens market is characterized by a high degree of fragmentation, with no single company commanding dominant national market share. The market is served by a combination of early-stage urban farming startups, regional fresh produce specialists, and growing numbers of small-scale independent producers operating within specific city markets. This fragmentation reflects low capital barriers to entry at small production scales and the predominantly localized nature of fresh produce distribution driven by short shelf life constraints.
Market consolidation is at an early stage, with leading players beginning to differentiate through organic certification, technology-enabled production capabilities, and institutional supply contracts. As the market matures, consolidation is expected to accelerate as producers with superior distribution reach, consistent quality standards, and institutional supply capabilities establish competitive advantages that smaller, locally focused operators will find increasingly difficult to replicate at scale through 2034.
Investment & Growth Opportunities
Highest Growth Segments
Indoor vertical farming growing at 9.3% CAGR represents the highest-return investment segment, driven by year-round production capability, premium pricing power, and growing institutional demand. Arugula and specialty microgreens varieties offer superior margin profiles compared to commodity greens, reflecting premium positioning in gourmet foodservice and organized retail.
Investment Themes
- Controlled Environment Agriculture Technology: Investment in advanced indoor growing systems, including LED grow lights, automated climate control, and precision hydroponic systems, offers strong returns as production scale increases and unit economics improve through technology optimization and operational efficiency gains.
- Cold Chain Infrastructure: Development of temperature-controlled storage and last-mile delivery infrastructure for fresh produce creates strategic value in the microgreens supply chain, enabling producers to serve wider geographic markets and reduce post-harvest losses that currently constrain distribution reach.
- Organic Certification and Premium Positioning: Producers investing in certified organic production methods and premium retail positioning achieve price premiums over conventional microgreens, reflecting strong consumer willingness to pay for quality-assured, clean-label fresh produce.
Future Market Outlook (2026-2034)
The India microgreens market grew from USD 78.71 Million in 2025 to USD 87.67 Million in 2026, reaching USD 158.56 Million by 2034, exhibiting a CAGR of 7.69% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 113.99 Million by 2030, as expanding urban farming infrastructure, growing institutional demand, and rising mainstream consumer adoption converge to accelerate market penetration across India's major urban centers.
Three structural forces will define India's microgreens market through 2034. First, continued urbanization and rising health consciousness will sustain premium food demand, creating a growing consumer base for functional foods including microgreens across an expanding range of Indian cities beyond current metro concentrations. Second, technology-driven reductions in controlled environment agriculture costs will progressively lower production costs, enabling market expansion into mid-tier cities and improving affordability for a broader consumer base. Third, growing institutional integration across hospitality, corporate catering, and organized retail will build supply chain maturity and distribution scale that enables the market to transition from a niche premium segment toward mainstream fresh produce category status by 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with microgreens producers, urban farming entrepreneurs, organized retail produce buyers, institutional foodservice procurement managers, and food technology investors. These discussions validated market sizing estimates, identified regional demand dynamics, assessed competitive positioning, and provided forward-looking insights on technology adoption and distribution channel evolution across the India microgreens sector.
Secondary Research
Secondary research drew on published data including Ministry of Agriculture and Farmers Welfare reports, functional food market publications, company filings, investor presentations, horticultural industry trade publications, and academic research on microgreens nutrition and production technology. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources to ensure accuracy.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling incorporating historical market growth rates, urbanization and disposable income projections, institutional foodservice market growth modeling, e-commerce fresh produce channel expansion data, controlled environment agriculture cost trend analysis, and macroeconomic indicators including urban consumer spending and premium food market growth benchmarks.
India Microgreens Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Broccoli, Cabbage, Cauliflower, Arugula, Peas, Basil, Radish, Others |
| Farming Methods Covered | Indoor Vertical Farming, Commercial Greenhouses, Others |
| End Uses Covered | Residential, Commercial |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Retail Stores, Others |
| Regions Covered | North India, West and Central India, South India, East and Northeast India |
| Companies Covered | Greenu, NeoGreens, Waraah Green Technologies Private Limited, Red Otter Farms, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India microgreens market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India microgreens market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India microgreens industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Microgreens Market Report
The India microgreens market reached USD 87.67 Million in 2026, driven by rising health consciousness, expanding urban farming infrastructure, and growing institutional demand from hospitality and foodservice sectors.
The market is projected to grow at a CAGR of 7.69% during 2026-2034, supported by health-driven consumer demand, urban farming expansion, and growing institutional and e-commerce distribution channels.
The market is projected to reach approximately USD 113.99 Million by 2030, driven by expanding urban consumer adoption, growing foodservice integration, and increasing e-commerce fresh produce delivery coverage.
Broccoli leads with an 18.6% share in 2025, reflecting strong consumer recognition, high sulforaphane nutrient content, and widespread retail and online grocery channel availability across metros.
Indoor vertical farming leads with a 48.7% share in 2025, driven by year-round production capability, pesticide-free growth, and consistent quality for premium retail and institutional supply.
West and Central India lead with a 32.6% share in 2025, driven by a dense urban health-conscious consumer population and an active premium restaurant and hospitality ecosystem.
Key players include Greenu, NeoGreens, Waraah Green Technologies Private Limited, and Red Otter Farms, among others.
The market is projected to reach USD 158.56 Million by 2034, driven by sustained health food demand growth, urban farming infrastructure expansion, and increasing mainstream retail and foodservice integration.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade