India Test Preparation Market Size, Share, Trends and Forecast by Exam, Learning Model, Gender, End User, and Region, 2026-2034
India Test Preparation Market Size, Share, Trends & Forecast (2026-2034)
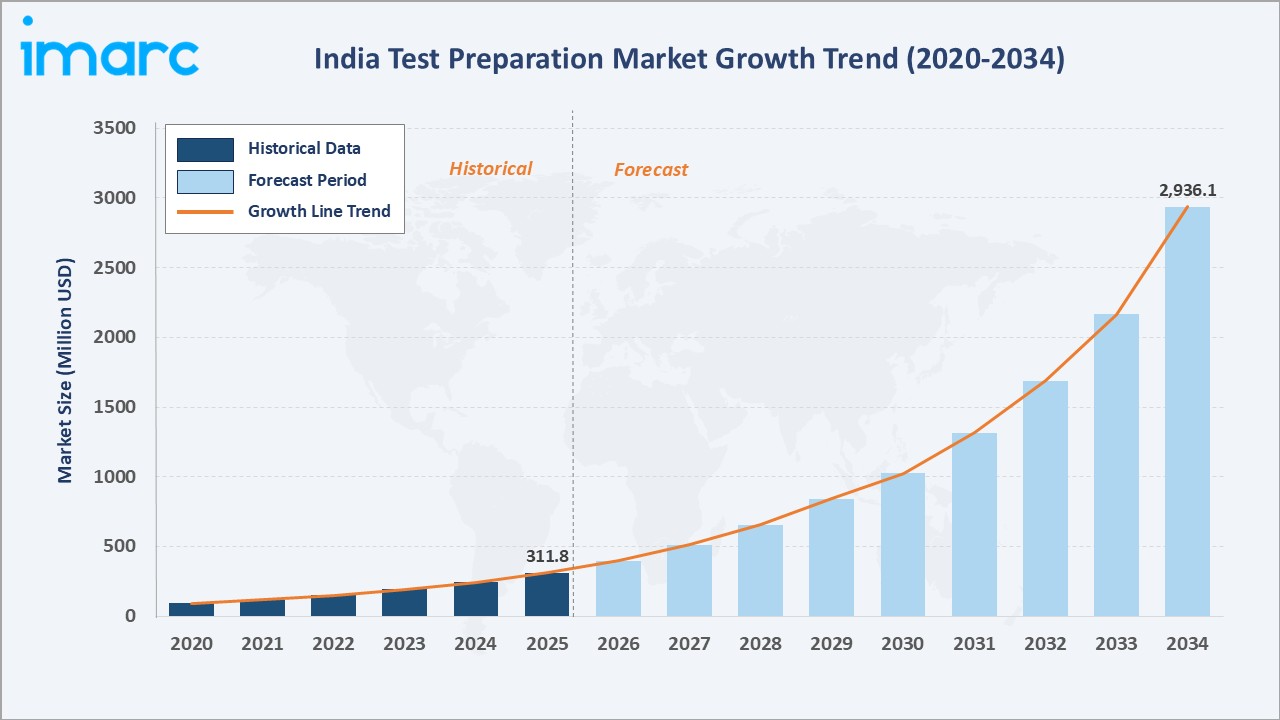
The India test preparation market grew from USD 311.8 Million in 2025 to USD 395.6 Million in 2026 and is projected to reach USD 2,936.1 Million by 2034, growing at a CAGR of 26.88% during 2026-2034. Over 60 million students participate in competitive examinations across India annually, underscoring the structural depth of exam preparation demand. University exams lead at 35.0% by exam type, K-12 dominates at 30.0% by end user, and North India commands the largest regional share at 30.0% in 2025, driven by highly competitive exam aspirant density.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 311.8 Million |
| Market Size (2026) | USD 395.6 Million |
| Forecast Market Size (2034) | USD 2,936.1 Million |
| CAGR (2026-2034) | 26.88% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Exam | University Exams (35.0%, 2025) |
| Dominant End User | K-12 (30.0%, 2025) |
| Leading Region | North India (30.0%, 2025) |
The India test preparation market grew from USD 94.8 Million in 2020 to USD 311.8 Million in 2025, and further to USD 395.6 Million in 2026, reflecting accelerating digital adoption and intensifying competitive exam participation. The market is projected to reach USD 1,025.3 Million by 2030 before achieving USD 2,936.1 Million by 2034.
To get more information on this market, Request Sample
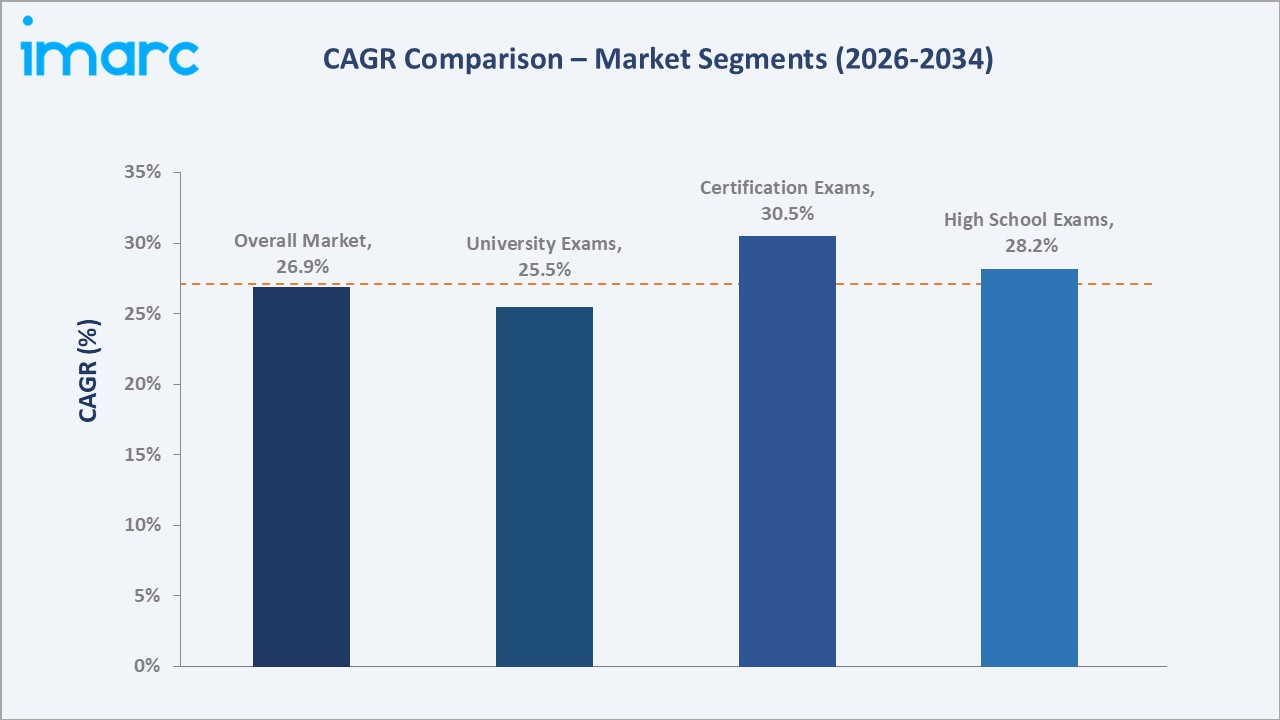
Certification exams grow at approximately 30.5% CAGR as professional credentialing gains priority among working professionals and job seekers. High school exams, at a 28.2% CAGR, benefit from assessment reforms and rising parental investment in board exam preparation.
Executive Summary
The India test preparation market is on a high-growth trajectory, underpinned by rising competition for limited seats in premier educational institutions, expanding digital learning infrastructure, and policy-driven educational reforms. The market growth is driven by both offline coaching institute enrollments and accelerating adoption of online and hybrid preparation platforms. India conducts competitive examinations across engineering, medical, management, government service, banking, and professional certification categories, maintaining structurally high and recurring demand for organized exam preparation services.
University exams represent the dominant segment at 35.0% in 2025, sustained by the high number of aspirants for engineering, medical, and liberal arts colleges relative to available institutional seats. K-12 at 30.0% is the leading end user segment, as parental investment in board exam support and foundation courses for future competitive exam preparation has become mainstream across urban and semi-urban households. North India commands the largest regional share at 30.0%, driven by dense concentrations of competitive exam aspirants.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Exam | University Exams - 35.0% share (2025) |
| Dominant End User | K-12 - 30.0% share (2025) |
| Leading Region | North India - 30.0% (2025) |
| Key Market Opportunity | Growing digital penetration and a rising aspirational student base in tier-2 and tier-3 cities present significant white space for scalable, affordable test preparation platforms targeting vernacular and hybrid learning segments. |
Key Analytical Observations Supporting the Above Data:
- University Exams at 35.0%: University exams lead because millions of students compete annually for limited undergraduate and postgraduate seats in engineering, medical, and management colleges.
- K-12 at 30.0%: K-12 leads end users as early preparation becomes mainstream. Parental investment in board exam support, school-level competitive coaching, and foundation courses for future entrance exam preparation drives consistent enrollment across this segment in both urban and semi-urban markets.
- North India at 30.0%: North India's leadership reflects the region's deep-rooted coaching culture centered in cities, which collectively attract a substantial national student enrollment base for engineering and medical exam preparation.
India Test Preparation Market Overview
The India test preparation market encompasses the production, distribution, and delivery of academic and professional exam preparation services across coaching institutes, ed-tech platforms, and hybrid learning models. The market serves students preparing for university entrance exams, school board assessments, government service examinations, banking and insurance tests, professional certification exams, and competitive aptitude tests. India's standardized examination system creates a structurally large and recurring addressable market, as a new cohort of exam aspirants enters the preparation cycle each year.
The industry ecosystem spans subject-matter content developers, curriculum designers, coaching institute operators, digital learning platform providers, examination bodies, and technology solution providers. Macroeconomic influences include rising per-capita income enabling greater educational spending, and government digital infrastructure investment improving online accessibility across the K-12 and higher education segments. India's large youth population and consistent governmental emphasis on expanding access to quality education form the foundational demand drivers supporting sustained market growth through the forecast period.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
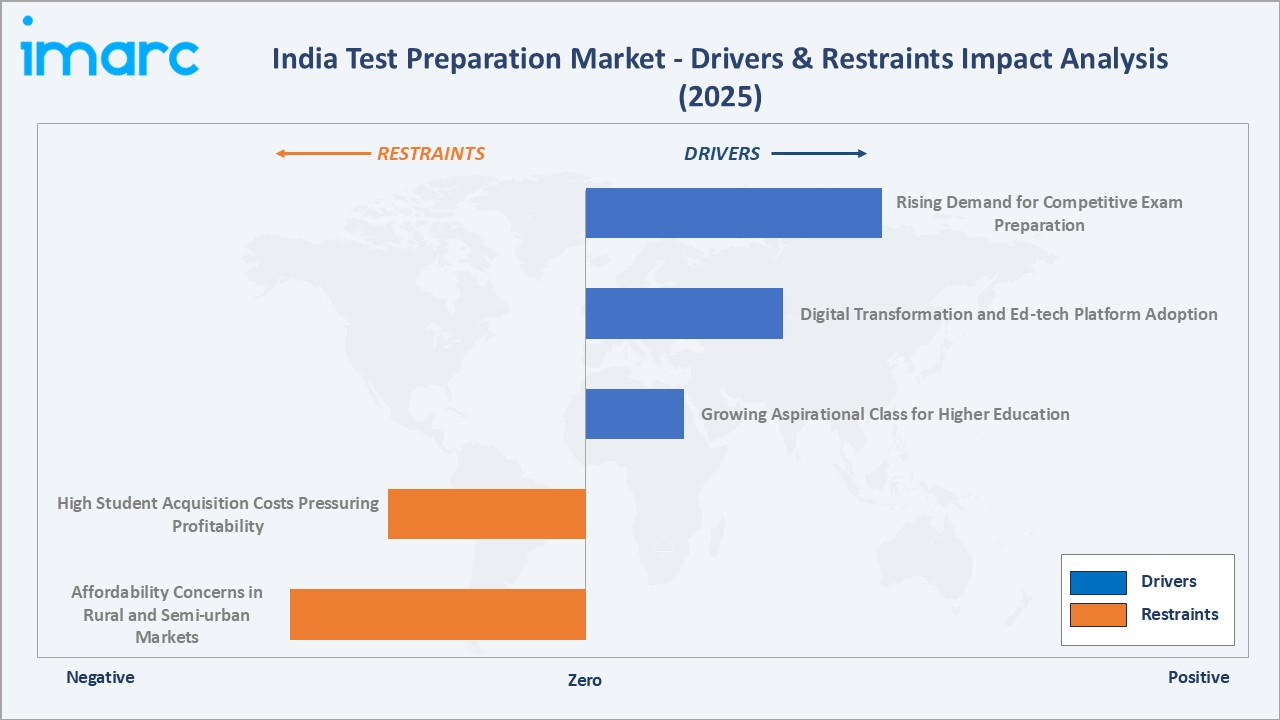
- Rising Demand for Competitive Exam Preparation: India's education system is highly examination-centric, with over 60 million students participating in competitive examinations annually. Acceptance rates at top-tier medical and engineering colleges are compelling structured test preparation and creating recurring demand across diverse coaching and ed-tech platforms serving the engineering, medical, management, government service, and banking examination segments.
- Digital Transformation and Ed-tech Platform Adoption: India's internet user base exceeding 950 million users in 2025, affordable mobile data, and improved digital literacy are enabling online test prep platforms to reach students in locations previously unserved by organized coaching. Live class delivery, AI-driven mock tests, and adaptive learning tools are expanding the market's geographic and demographic addressable base across tier-2 and tier-3 cities.
- Growing Aspirational Class for Higher Education: India's growing middle class is increasing investment in children's education, treating competitive exam preparation as essential career infrastructure. Household education expenditure on private tutoring and test prep is expanding the addressable market value across both offline and online segments.
Market Restraints
- High Student Acquisition Costs Pressuring Profitability: Ed-tech platforms face significant marketing and promotional spending to acquire students in a competitive landscape with multiple well-funded providers. High customer acquisition costs combined with student churn after exam cycles pressure margins and limit the profitability of digital-first players, particularly in mass-market price-sensitive segments.
- Affordability Concerns in Rural and Semi-urban Markets: Despite digital democratization, premium test preparation services remain unaffordable for a large segment of rural and semi-urban students. This limits market penetration depth in areas with the highest population density of exam aspirants, constraining the ability of organized providers to fully capture the total addressable market.
Market Opportunities
- Vernacular Content and Tier-2/Tier-3 City Penetration: Students from Tier 2 and Tier 3 cities account for 50% of India’s study-abroad aspirants, with 30% from Tier 2 and 20% from Tier 3 cities, with many preferring preparation content in regional languages. Platforms offering high-quality Hindi and regional language test prep content can unlock a substantially underserved and high-growth market segment across the government job and state board examination categories.
- AI-Powered Personalized Learning: AI and machine learning technologies enabling adaptive question selection, real-time performance analytics, and personalized study plans represent a significant product differentiation and monetization opportunity for technology-first test prep platforms targeting premium student segments.
Market Challenges
- High Dropout and Completion Rates: A significant proportion of enrolled test preparation students do not complete their preparation programs or fail to achieve target scores, creating high churn and repeat enrollment dependency that complicates revenue planning and limits lifetime customer value for providers.
- Regulatory Uncertainty Around Online Education: Evolving regulatory frameworks for online education, data privacy requirements, and potential government mandates on ed-tech pricing and content could create operational challenges for platforms scaling rapidly without established regulatory compliance frameworks.
Emerging Market Trends
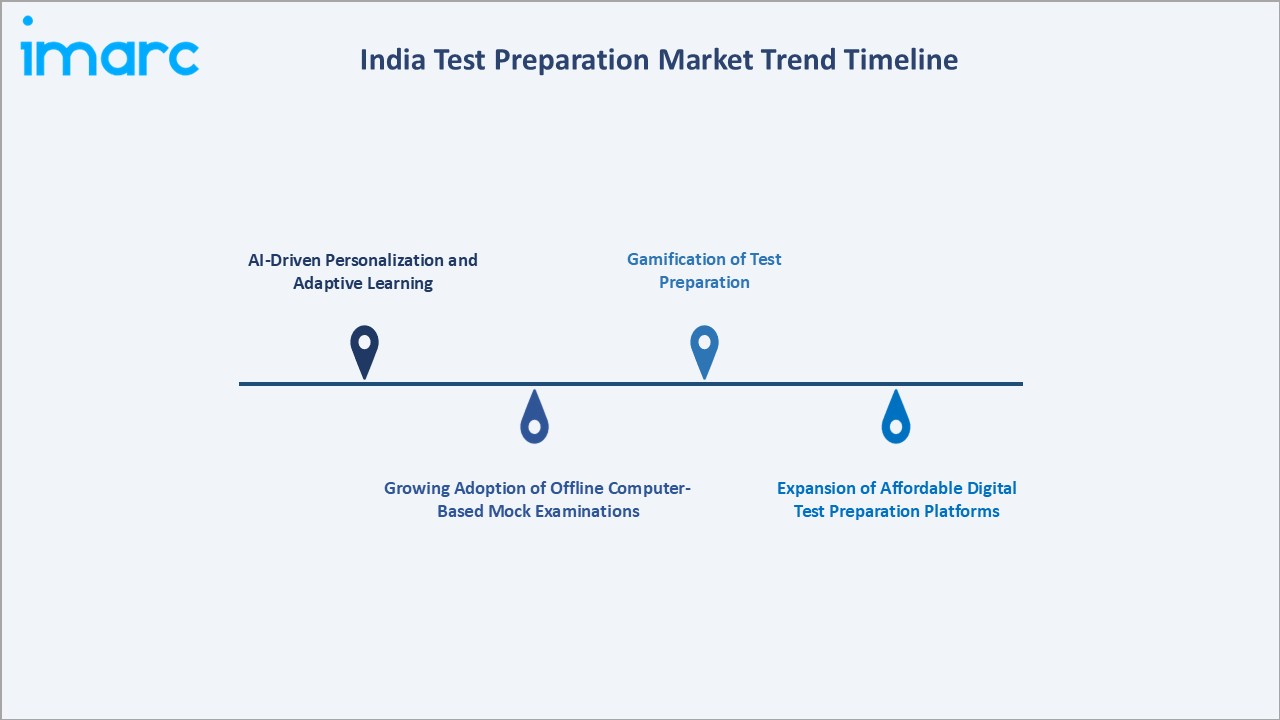
1. AI-Driven Personalization and Adaptive Learning
Artificial intelligence is transforming India's test preparation landscape by enabling adaptive question delivery, real-time performance gap analysis, and personalized study schedules calibrated to individual student readiness levels. In August 2025, IIT Palakkad launched Tutoz, India’s first AI-powered learning application for competitive exam aspirants, offering affordable, accessible, and personalized learning solutions nationwide.
2. Growing Adoption of Offline Computer-Based Mock Examinations
Test preparation providers are increasingly replicating actual competitive examination environments through physical CBT mock tests, enabling aspirants to gain hands-on experience with exam interfaces, time management, and test-center procedures. In June 2026, Vidyavriti introduced India’s first pan-India, center-based CBT mock examinations for SSC CGL and IBPS PO, offering aspirants a real exam-like experience at physical test centers nationwide.
3. Gamification of Test Preparation
Gamified learning mechanics, including leaderboards, achievement badges, streak tracking, and reward systems, are being integrated into test prep platforms to improve engagement and reduce dropout rates. Platforms leveraging gamification have demonstrated meaningfully higher daily active user metrics and session durations compared to conventional content-only models, particularly among the K-12 and high school segments.
4. Expansion of Affordable Digital Test Preparation Platforms
Government-backed initiatives are promoting free digital learning platforms to make competitive exam preparation more accessible and affordable. In March 2026, the Ministry of Education, in collaboration with IIT Kanpur, launched the free SATHEE digital learning platform to support students preparing for major competitive examinations, particularly those unable to afford expensive coaching.
Industry Value Chain Analysis
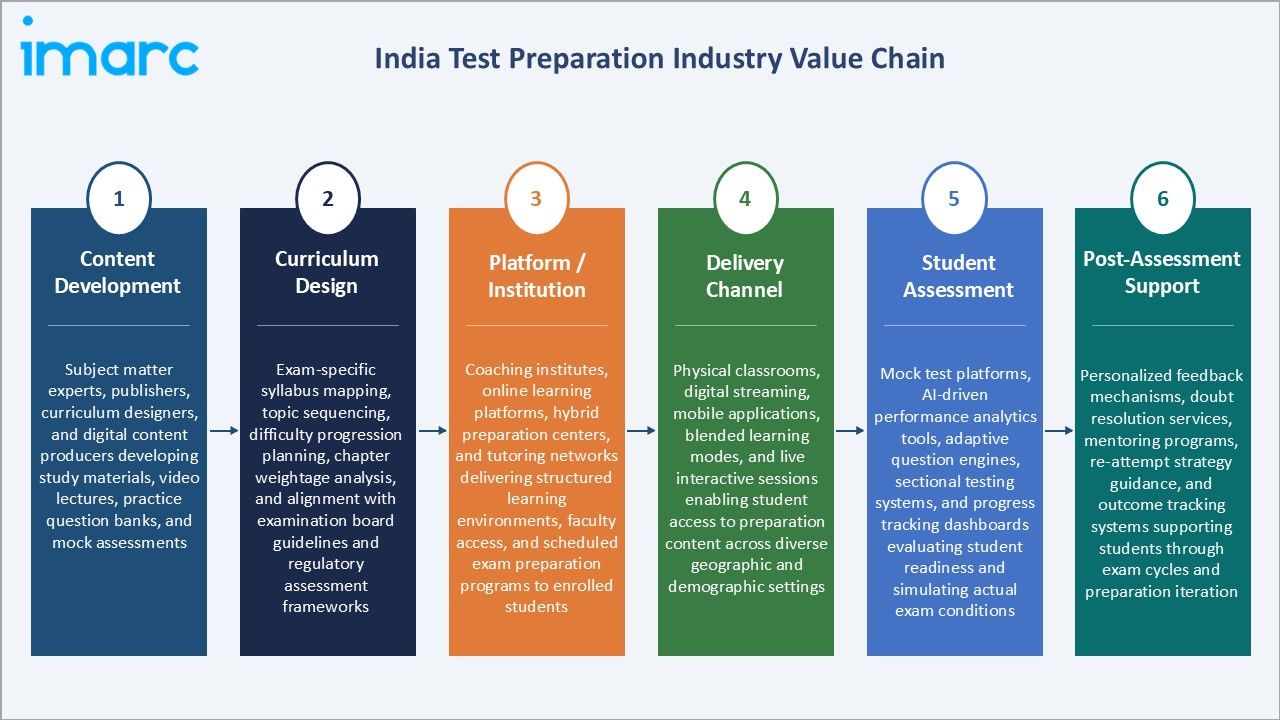
The India test preparation market value chain spans six integrated stages from content development through post-assessment outcomes. Each stage creates distinct value through expertise, technology, and reach, with the highest value addition occurring at the platform, delivery, and assessment stages where proprietary content, brand trust, and technology infrastructure create durable competitive advantages.
| Stage | Key Activities & Role |
|---|---|
| Content Development | Subject matter experts, publishers, curriculum designers, and digital content producers developing study materials, video lectures, practice question banks, and mock assessments. |
| Curriculum Design | Exam-specific syllabus mapping, topic sequencing, difficulty progression planning, chapter weightage analysis, and alignment with examination board guidelines and regulatory assessment frameworks. |
| Platform / Institution | Coaching institutes, online learning platforms, hybrid preparation centers, and tutoring networks delivering structured learning environments, faculty access, and scheduled exam preparation programs to enrolled students. |
| Delivery Channel | Physical classrooms, digital streaming, mobile applications, blended learning modes, and live interactive sessions enabling student access to preparation content across diverse geographic and demographic settings. |
| Student Assessment | Mock test platforms, AI-driven performance analytics tools, adaptive question engines, sectional testing systems, and progress tracking dashboards evaluating student readiness and simulating actual exam conditions. |
| Post-Assessment Support | Personalized feedback mechanisms, doubt resolution services, mentoring programs, re-attempt strategy guidance, and outcome tracking systems supporting students through exam cycles and preparation iteration. |
The delivery channel stage is undergoing the most rapid transformation, as mobile-first digital platforms continue to displace traditional classroom-only models across metro and tier-1 city markets. The post-assessment support stage is gaining strategic significance as platforms differentiate on outcome accountability, with result-linked fee models and performance guarantees emerging as commercial innovation areas.
Technology Landscape in the India Test Preparation Industry
Artificial Intelligence and Machine Learning
AI and ML are the most transformative technologies in India's test preparation sector, enabling adaptive question delivery, real-time performance prediction, automated content tagging, and personalized study path generation. AI-powered systems analyze student interaction patterns to identify knowledge gaps and dynamically adjust content difficulty, improving preparation efficiency. The integration of large language models for instant doubt resolution is an emerging application area gaining traction across premium preparation platforms.
Adaptive Learning Systems
Adaptive learning platforms adjust content delivery based on individual student performance signals, ensuring that preparation time is allocated to high-impact areas rather than equally distributed across the entire syllabus. These systems have demonstrated measurable improvements in student outcomes, particularly in time-constrained exam preparation scenarios across engineering and medical entrance categories.
Gamification and Engagement Technologies
Gamification technologies, including real-time leaderboards, achievement systems, and social learning tools, are being integrated into test prep platforms to maintain student motivation across multi-month preparation cycles. Engagement technology reduces dropout rates and increases daily active user metrics, improving platform monetization efficiency and student outcome consistency.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Exam | University Exams | 35.0% | 2025 |
| Learning Model | 🔒 | 🔒 | 2025 |
| Gender | 🔒 | 🔒 | 2025 |
| End User | K-12 | 30.0% | 2025 |
| Region | North India | 30.0% | 2025 |

By Exam
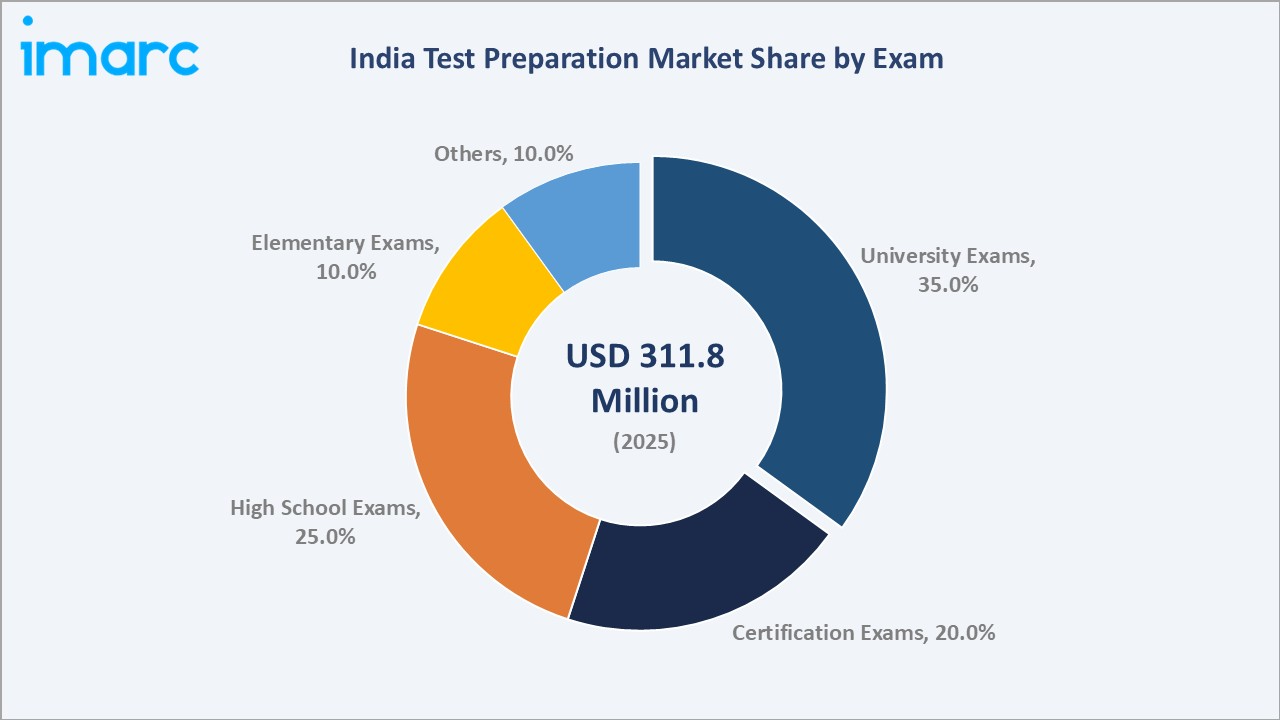
University exams lead with a 35.0% share in 2025, reflecting the intense competition for seats in premier engineering (JEE), medical (NEET), management (CAT/XAT), law, and liberal arts institutions that motivates structured exam preparation investments by millions of students annually.
To access detailed market analysis, Request Sample
High school exams at 25.0% represent the second-largest segment, driven by increasing parental focus on board exam performance as a critical differentiator for college admissions. Certification exams at 20.0% are the fastest-growing segment at approximately 30.5% CAGR, fueled by rising employer demand for validated professional credentials and the proliferation of international certification programs across technology, finance, and healthcare sectors. Elementary exams at 10.0% and others at 10.0% collectively reflect growing early-stage preparation trends and government job examination coaching, respectively.
By End User
K-12 students dominate the end user segment at 30.0% in 2025, as parental investment in school-level exam preparation and foundation courses for future competitive exams drives consistent enrollment. College students at 25.0% represent the largest cohort preparing for university entrance and postgraduate admission tests. Job seekers at 20.0% are a rapidly growing segment as banking, government service, and public sector examination preparation gains scale.
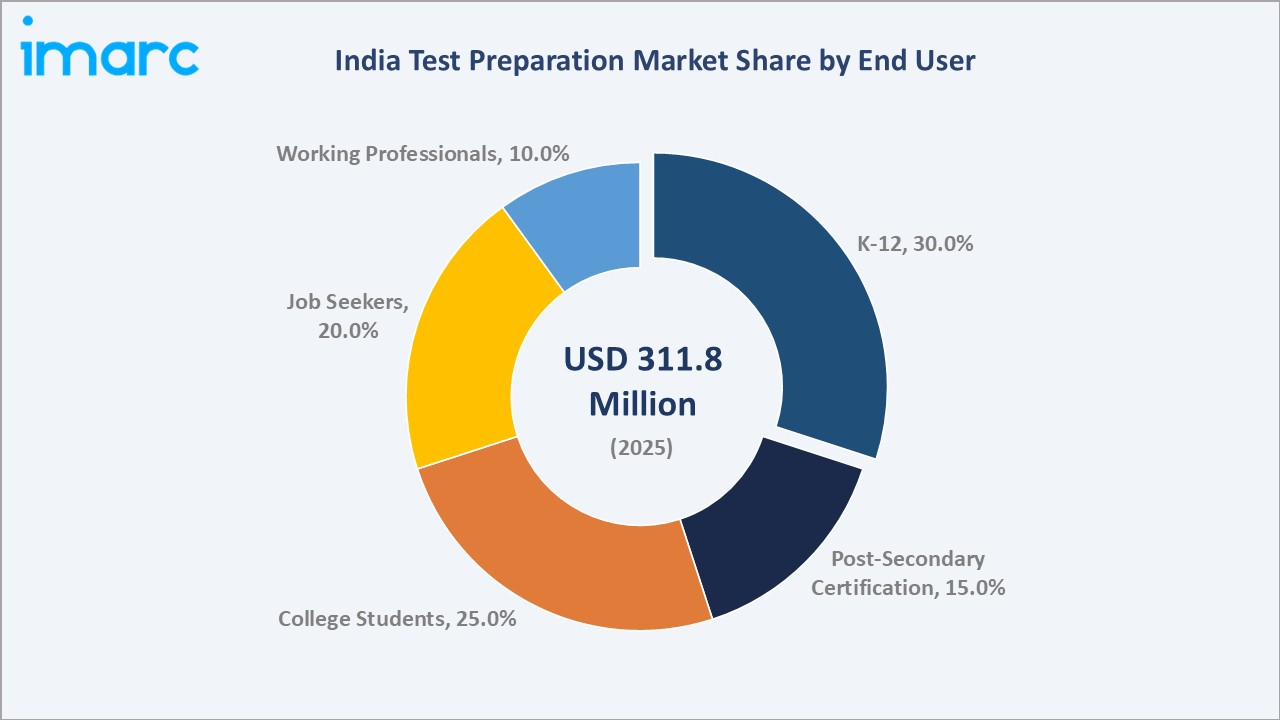
Post-secondary certification at 15.0% reflects the growing importance of professional credentialing in technology, finance, and healthcare sectors, while working professionals at 10.0% represent an emerging premium segment seeking upskilling through certification and graduate entrance exam preparation.
Regional Market Insights
| Region | Share (2025) | Key India Test Preparation Market Drivers & Characteristics |
|---|---|---|
| North India | 30.0% | Dominant test prep ecosystem driven by high competitive exam aspirant density and large student enrollment in engineering and medical coaching centers, with coaching hub cities attracting substantial national student enrollment for structured preparation programs. |
| South India | 28.0% | Strong ed-tech adoption and high penetration of online platforms serving large K-12 and college student populations aspiring for professional certifications, government service examinations, and state board competitive assessments. |
| West India | 27.0% | Growing demand driven by business and finance exam preparation, significant college-going population, and rising adoption of digital learning platforms among urban student demographics in major metropolitan centers. |
| East India | 15.0% | Expanding market with increasing internet access enabling online test prep platforms to reach students in underserved locations, with government job examination segments and state board preparation driving primary demand. |
North India's regional leadership at 30.0% reflects the region's deep-rooted coaching culture centered in prominent coaching hub cities, which collectively attract a large national student enrollment base for engineering and medical exam preparation. South India at 28.0% benefits from high digital literacy and technology-sector-driven professional certification demand.
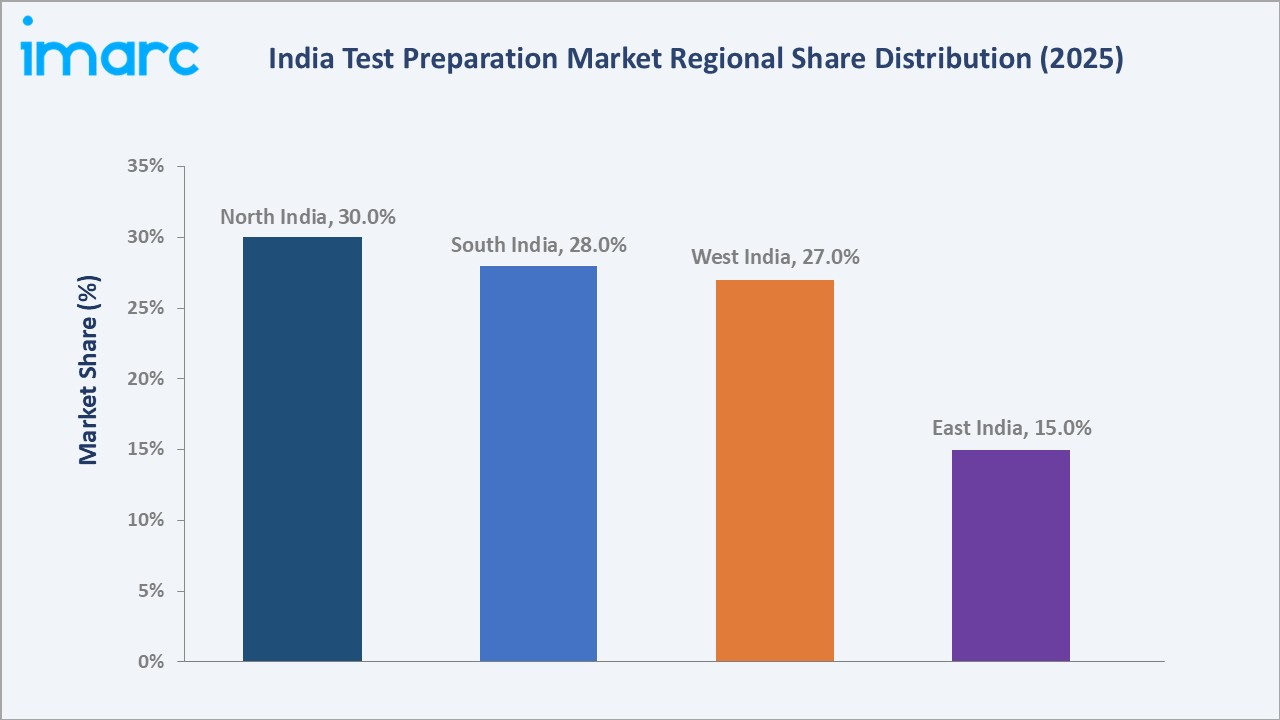
West India at 27.0% is anchored by the large student populations in major metropolitan centers pursuing management and professional exam preparation. East India at 15.0% represents the highest-potential growth region as digital infrastructure investment and rising student aspirations expand the organized preparation market across underserved geographies.
Competitive Landscape
The India test preparation market is moderately fragmented. The market includes large-scale offline coaching institute chains, well-funded ed-tech platforms, and thousands of small regional tutoring centers and individual tutors serving localized demand across specific exam segments.
| Company | Key Products | Market Position | Core Strength |
|---|---|---|---|
| Physicswallah Limited | PW Test Pass | Market Leader | Physics Wallah Limited (PW) plays a major role in democratizing test preparation across India by offering low-cost online, offline, and hybrid coaching for competitive and academic exam categories. |
| BYJU'S | BYJU’S All India Test Series | Established Player | BYJU'S transformed India's test preparation landscape by shifting coaching from traditional brick-and-mortar classrooms to digital, app-driven, and video-based learning models. |
| CL Educate Ltd | CAT Test Series | Innovator | CL Educate Ltd is a prominent education and test-preparation company in India, best known for its flagship brand Career Launcher. |
| Vedantu | Vedantu e-learning app | Challenger | Vedantu plays a major role in India’s test preparation ecosystem by providing live interactive online classes, structured courses, and personalized mentorship for competitive and board exams. |
Competition in the India test preparation market is intensifying as ed-tech platforms with large venture capital backing compete aggressively on content quality, pricing, and feature richness against established offline coaching institute brands. Offline leaders are building digital capabilities, while digital-first platforms are establishing physical learning centers to offer hybrid preparation models appealing to students seeking accountability and structured study environments.
Key Company Profiles
Physicswallah Limited
Physicswallah Limited is a prominent test preparation organization serving students across competitive examination segments through an integrated mix of offline learning centers, digital platforms, and hybrid delivery models. The organization has established a broad geographic presence across key student markets in India, offering structured study programs, comprehensive practice materials, and technology-supported preparation solutions to a large and growing student base.
- Key Offerings: PW Test Pass.
- Strategic Focus: Expanding digital delivery infrastructure alongside established offline operations, investing in adaptive content and AI-driven performance analytics, broadening geographic reach into tier-2 and tier-3 city markets, and strengthening curriculum alignment with evolving exam patterns to improve student preparation outcomes.
BYJU'S
BYJU'S is a prominent test preparation organization serving students across competitive examination segments through an integrated mix of offline learning centers, digital platforms, and hybrid delivery models. The organization has established a broad geographic presence across key student markets in India, offering structured study programs, comprehensive practice materials, and technology-supported preparation solutions to a large and growing student base.
- Key Offerings: BYJU’S All India Test Series.
- Strategic Focus: Expanding digital delivery infrastructure alongside established offline operations, investing in adaptive content and AI-driven performance analytics, broadening geographic reach into tier-2 and tier-3 city markets, and strengthening curriculum alignment with evolving exam patterns to improve student preparation outcomes.
Market Concentration Analysis
The India test preparation market exhibits moderate concentration at the organized segment level, where the leading players collectively hold a minority share of total market revenues, with the remainder distributed across a large and fragmented base of regional coaching institutes, independent tutors, and small-scale preparation service providers. Organized players command a premium positioning through brand recognition, proven student outcomes, structured curriculum delivery, and proprietary technology platforms, while the unorganized segment continues to serve a large volume of demand through affordable, locally accessible preparation services.
The market is progressively consolidating as digital platforms lower barriers to reach, enabling organized players to serve students across geographies previously dominated by local tutors and regional coaching centers. Mergers, acquisitions, and strategic partnerships between offline coaching institutes and digital platforms are gradually formalizing market structure, improving content standards, and strengthening the competitive positioning of organized providers relative to fragmented regional alternatives. This consolidation trend is expected to accelerate through the forecast period as technology investment and brand equity increasingly favor larger integrated players.
Investment & Growth Opportunities
Highest Growth Segments
Certification exam preparation at 30.5% CAGR represents the highest growth segment, driven by rising employer demand for validated professional credentials and the proliferation of globally recognized certification programs in technology, finance, and healthcare. University exam preparation at 25.5% CAGR offers sustained volume growth underpinned by consistently high and growing student aspirant numbers relative to available institutional seats. High school exam preparation at 28.2% CAGR benefits from assessment reforms expanding the addressable preparation requirement across the K-12 segment.
Investment Themes
- Vernacular Language Platforms: Platforms offering high-quality Hindi, Tamil, Telugu, Marathi, and Bengali test prep content are addressing a significantly underserved and high-volume demand segment with limited organized competition, representing a compelling investor opportunity.
- AI-Powered Test Analytics: Investment in AI-driven personalized mock test platforms and performance analytics tools represents a high-margin differentiation opportunity, as students and institutions increasingly value data-driven preparation tracking over generic content delivery. AI-first platforms command a meaningful premium pricing capability over conventional alternatives.
- Tier-2 and Tier-3 City Physical Centers: The hybrid learning model preference in smaller cities creates a compelling opportunity for organized operators to establish physical learning touchpoints that serve as anchors for digital subscription upsell, combining local trust with digital scale to capture the large, underserved demand base.
Future Market Outlook (2026-2034)
The India test preparation market grew from USD 311.8 Million in 2025 to USD 395.6 Million in 2026, reaching USD 2,936.1 Million by 2034, exhibiting a CAGR of 26.88% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 1,025.3 Million by 2030, as digital platform adoption reaches critical mass across tier-2 and tier-3 student demographics and AI-driven personalization becomes the standard expectation for premium test prep services.
Three structural forces will define India's test preparation market through 2034. First, India's consistently high and growing aspirant-to-seat ratio across premier educational institutions will sustain structurally high demand for competitive exam preparation independent of economic cycles. Second, digital infrastructure investment by both government and private sector players will progressively reduce the cost and geographic barriers to quality test preparation access, expanding the total addressable market to include the large, underserved tier-2 and tier-3 student base. Third, the integration of AI, adaptive learning, and gamification technologies will drive product innovation cycles that continuously expand the value proposition of organized test preparation platforms, supporting premium pricing and improving student retention through 2034.
Research Methodology
Primary Research
Primary research comprised structured consultations with test preparation institute operators, ed-tech platform executives, educators, student counselors, and examination board representatives. These discussions validated market sizing estimates, assessed regional demand dynamics, identified key growth drivers, and provided insights into competitive positioning and pricing across the India test preparation market.
Secondary Research
Secondary research drew on published government data, including Ministry of Education reports, National Testing Agency enrollment statistics, University Grants Commission data, company annual reports and investor presentations, ed-tech industry association publications, and financial media coverage of funding rounds and market developments across the India education and test preparation sectors. Historical market data spanning 2020 through 2025 was cross-validated across primary and secondary sources.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical exam enrollment growth rates, digital platform adoption curves, government examination reform timelines, ed-tech venture investment trends, competitive pricing dynamics, and macroeconomic indicators including GDP growth, education spending trends, and internet penetration projections. Scenario analysis was applied to assess upside and downside market trajectories under varying policy and technology adoption conditions.
India Test Preparation Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Exams Covered | University Exams, Certification Exams, High School Exams, Elementary Exams, Others |
| Learning Types Covered | Blended, Online |
| Genders Covered | Male, Female |
| End Users Covered | Post-Secondary Certification, K-12, College Students, Job Seekers, Working Professionals |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | Physicswallah Limited, BYJU'S, CL Educate Ltd, Vedantu, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India test preparation market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India test preparation market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India test preparation industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Test Preparation Market Report
The India test preparation market reached USD 395.6 Million in 2026, driven by rising competitive exam participation, digital platform adoption, and growing aspirational students targeting higher education and professional certifications across the country.
The market is projected to grow at a CAGR of 26.88% during 2026-2034, supported by sustained competitive exam enrollment growth, digital adoption, and expansion of test prep platforms into tier-2 and tier-3 city markets.
The market is projected to reach approximately USD 1,025.3 Million by 2030, driven by digital platform maturation, vernacular content expansion, and rising K-12 and university exam preparation enrollment across geographies.
University exams lead with a 35.0% share in 2025, reflecting intense competition for limited seats in engineering, medical, and management colleges, driving structured preparation investment by millions of annual aspirants.
K-12 students lead with a 30.0% share in 2025, driven by increasing parental investment in board exam support and foundation courses for future competitive exam preparation across urban and semi-urban markets.
North India leads with a 30.0% share in 2025, reflecting high competitive exam aspirant density, established coaching center ecosystems, and large student enrollment concentrations in engineering and medical exam segments.
Key players include Physicswallah Limited, BYJU'S, CL Educate Ltd, and Vedantu, among others.
The market is projected to reach USD 2,936.1 Million by 2034, driven by sustained competitive exam demand, digital infrastructure growth, AI-driven personalization adoption, and vernacular content expansion across tier-2 and tier-3 markets.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade