
Kosher Food Market Size, Share, Trends and Forecast by Type, Application, Distribution Channel, and Region, 2026-2034
Kosher Food Market Size, Share, Trends & Forecast (2026-2034)
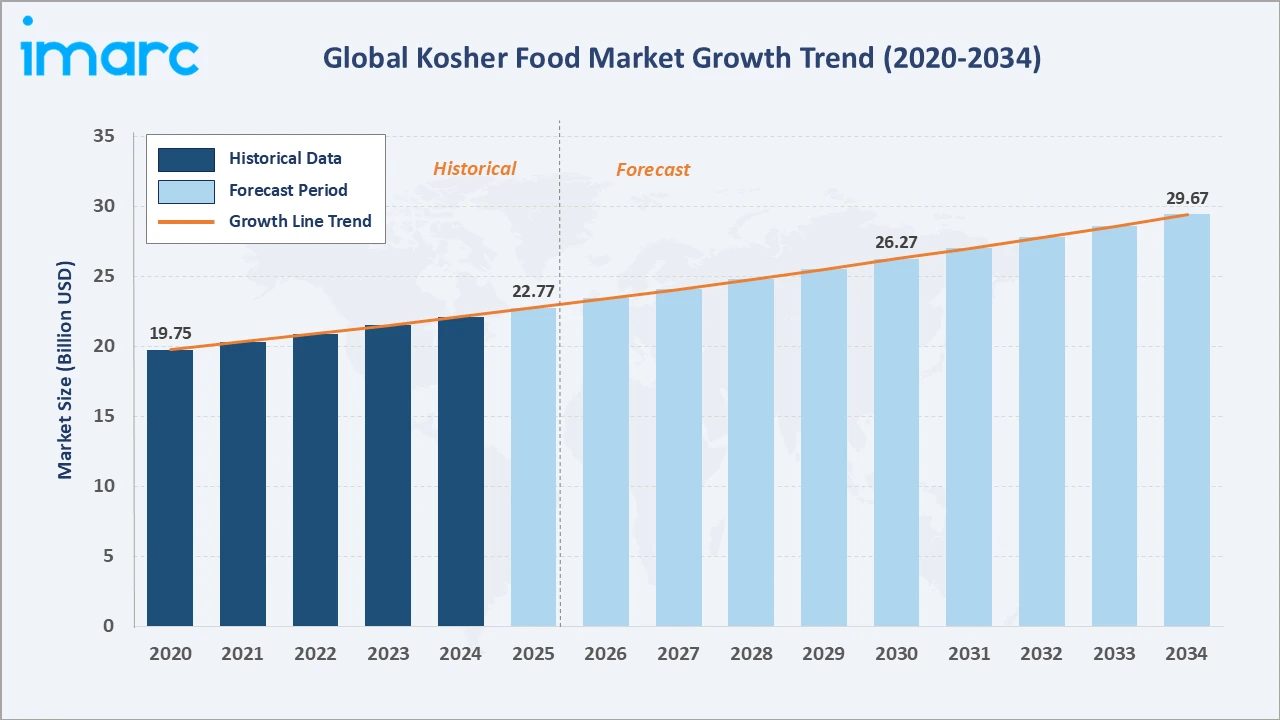
The kosher food market grew from USD 22.77 Billion in 2025 to USD 23.43 Billion in 2026 and is projected to reach USD 29.67 Billion by 2034, growing at a CAGR of 2.89% during 2026-2034. Expanding certification coverage across food categories and rising demand from health-conscious and clean-label-oriented consumers are among the primary drivers shaping market growth.
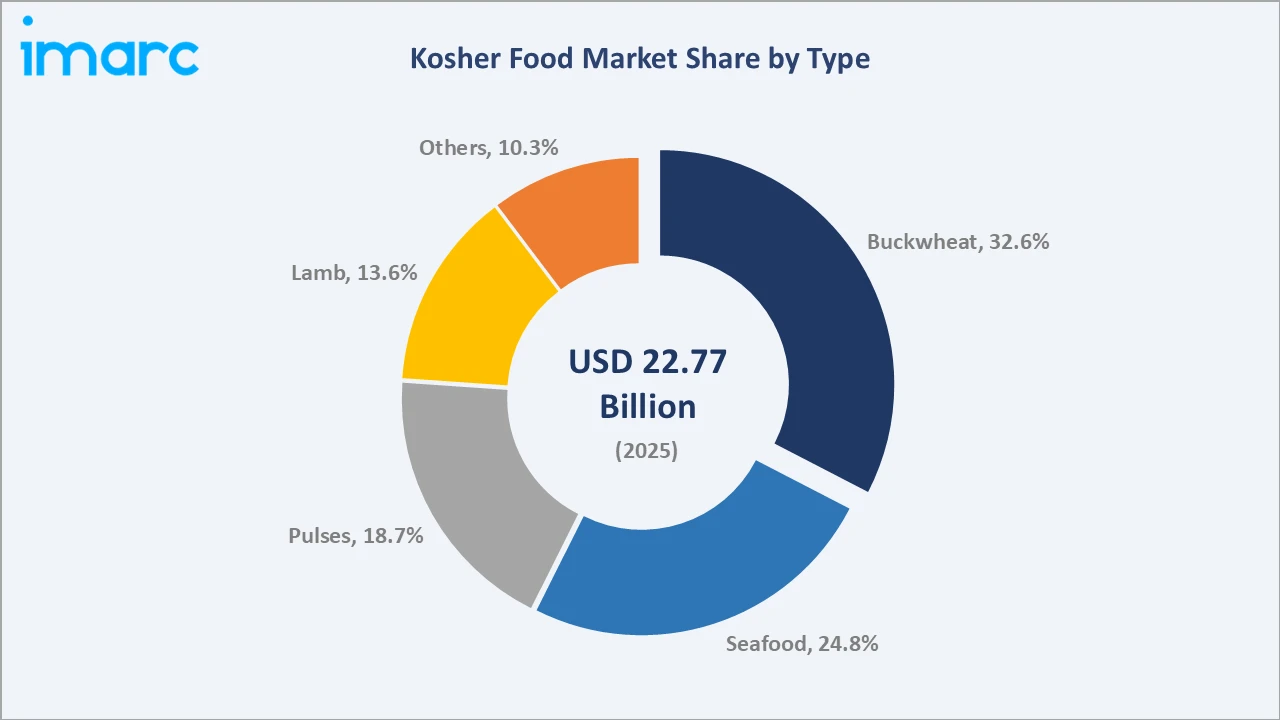
Buckwheat leads the type segment at 32.6%, supermarkets and hypermarkets dominate distribution channel at 48.5%, and North America commands the largest regional share at 39.8%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 22.77 Billion |
|
Market Size (2026) |
USD 23.43 Billion |
|
Forecast Market Size (2034) |
USD 29.67 Billion |
|
CAGR (2026-2034) |
2.89% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
North America (39.8%, 2025) |
|
Second Largest Region |
Europe (30.6%, 2025) |
|
Leading Type |
Buckwheat (32.6%, 2025) |
|
Leading Distribution Channel |
Supermarkets and Hypermarkets (48.5%, 2025) |
The global kosher food market size increased from USD 19.75 Billion in 2020 to USD 22.77 Billion in 2025 and is estimated to reach USD 23.43 Billion in 2026. The market is further expected to grow to USD 26.27 Billion by 2030 and USD 29.67 Billion by 2034. This trajectory is underpinned by an expanding non-Jewish consumer base, rising online availability of certified products, and growing institutional and foodservice adoption of kosher-certified ingredients.
To get more information on this market, Request Sample
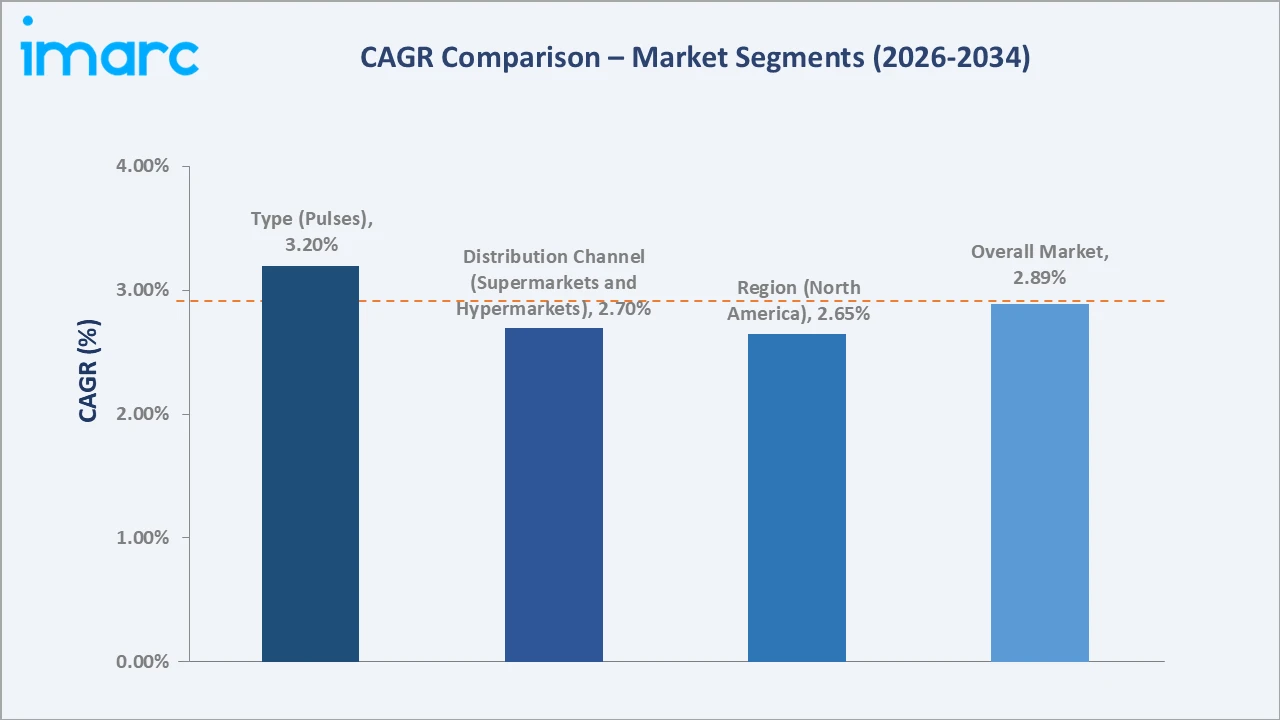
CAGR trajectories across type and distribution channel sub-segments, alongside regional patterns, indicate that pulses, online stores, and Middle East and Africa are expanding faster than the overall market CAGR of 2.89% during 2026–2034, driven by rising demand for plant-based food products, increasing online grocery adoption, and growing awareness of kosher food options across emerging markets.
Executive Summary
The kosher food market expanded from USD 22.77 Billion in 2025 to an estimated USD 23.43 Billion in 2026. The industry has evolved from a niche religious food category into a mainstream certified food segment, driven by growing consumer interest in dietary transparency, food purity, and label integrity.
Buckwheat commands the largest type segment share at 32.6% in 2025, supported by established kosher slaughter and certification infrastructure. Supermarkets and hypermarkets remain the dominant distribution channel at 48.5%, fueled by wide product availability, consumer preference for in-store grocery shopping, and the presence of dedicated kosher food sections. North America leads the global market with a 39.8% share in 2025, anchored by a concentrated Jewish consumer base and a mature kosher retail and foodservice ecosystem.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Buckwheat – 32.6% share (2025) |
|
Second Largest Type |
Seafood – 24.8% share (2025) |
|
Leading Distribution Channel |
Supermarkets and Hypermarkets – 48.5% share (2025) |
|
Second Largest Distribution Channel |
Grocery Stores – 32.4% share (2025) |
|
Leading Region |
North America – 39.8% share (2025) |
|
Second Largest Region |
Europe – 30.6% share (2025) |
|
Top Companies |
Conagra Brands, TableTrust Brands LLC, Kayco, PepsiCo, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Buckwheat dominance at 32.6% reflects its suitability for kosher food formulations, offering a versatile ingredient for various traditional and specialty food products.
- Seafood at 24.8% is the second largest type segment, underpinned by high demand for kosher-certified fish and shellfish-free seafood, particularly among Jewish consumers observing dietary laws on permitted and forbidden sea creatures.
- Supermarkets and hypermarkets at 48.5% dominate distribution channel, supported by dedicated kosher aisles, refrigerated sections, and increasing shelf space allocated to certified food products in mainstream retail outlets.
- Grocery stores at 32.4% reflect the importance of neighborhood retailers and local grocery outlets in providing convenient access to kosher-certified products for regular household consumption.
- North America leadership at 39.8% is supported by a large Jewish population base, extensive kosher certification infrastructure, and strong institutional demand from restaurants, hotels, and catering operations.
Kosher Food Market Overview
Kosher food refers to products that comply with Jewish dietary laws known as kashrut, covering permitted and forbidden ingredients, preparation methods, and separation of meat and dairy products. Beyond its religious origins, kosher certification has gained recognition among health-conscious, halal-adjacent, vegan, and allergen-aware consumers globally.
Macroeconomic factors including rising disposable income, growing ethnic food adoption, and expanding e-commerce infrastructure support market growth across North America, Europe, and Asia-Pacific. Increasing availability of certified products through mainstream retail channels further improves consumer access and supports market expansion.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
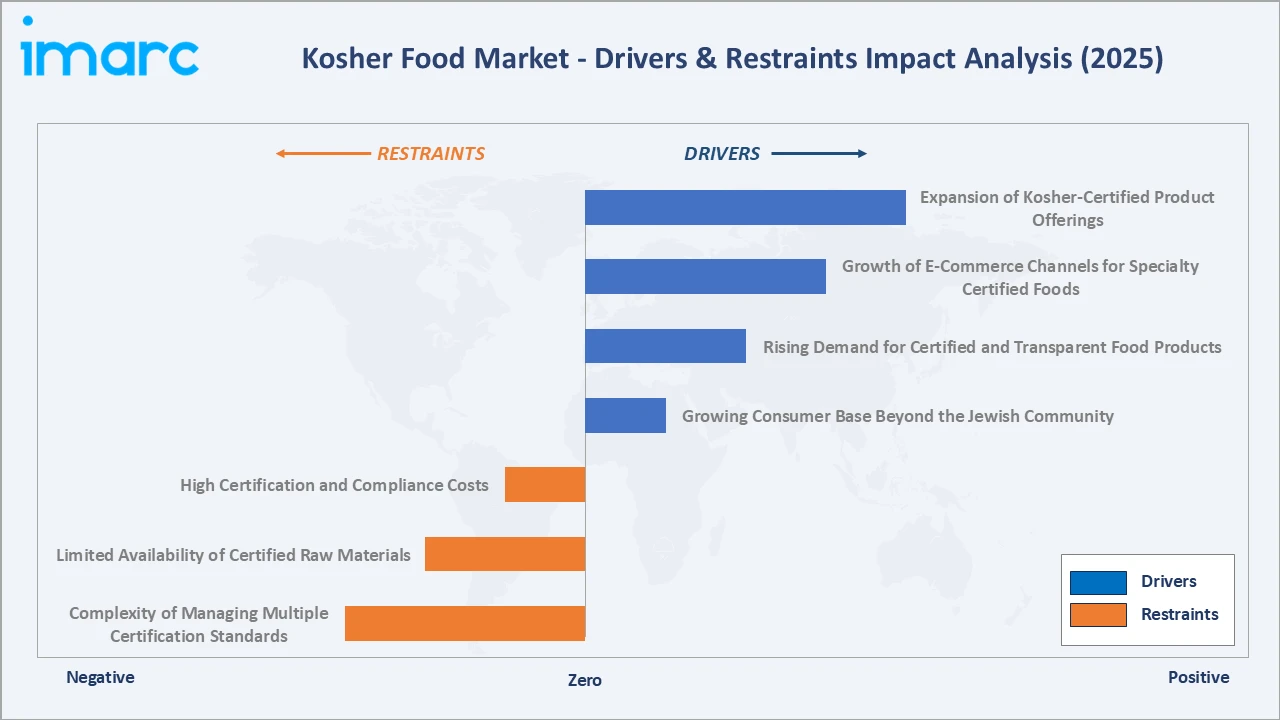
- Growing Consumer Base Beyond the Jewish Community: Rising interest in clean-label, minimally processed, and ethically certified foods is expanding the consumer base to include Muslim, vegan, and vegetarian consumers, broadening the global kosher market value beyond traditional Jewish households.
- Rising Demand for Certified and Transparent Food Products: Consumer preference for food products with third-party certification is growing, as shoppers increasingly associate kosher labeling with quality assurance, ingredient integrity, and manufacturing oversight, supporting broader adoption across mainstream retail channels.
- Growth of E-Commerce Channels for Specialty Certified Foods: As per IMARC Group, the global e-commerce market size was valued at USD 33.80 Trillion in 2025. Online platforms are enabling kosher food brands to reach geographically dispersed consumers, including Jewish diaspora communities in markets with limited local kosher retail availability, driving sustained channel expansion and distribution efficiency gains.
- Expansion of Kosher-Certified Product Offerings: Food manufacturers are expanding their portfolios of kosher-certified snacks, packaged meals, beverages, and plant-based alternatives to cater to diverse dietary preferences, strengthen retail presence, and capture demand across mainstream consumer segments.
Market Restraints
- High Certification and Compliance Costs: Maintaining continuous kosher certification requires ongoing investment in rabbinic supervision, separate production lines, and ingredient sourcing from approved suppliers, increasing operational costs for food manufacturers across product categories.
- Limited Availability of Certified Raw Materials: Access to kosher-certified raw materials remains constrained in certain geographies, particularly in emerging markets where certification infrastructure is less developed, restricting the ability of manufacturers to expand certified product lines.
- Complexity of Managing Multiple Certification Standards: Variability in kosher certification standards across certifying bodies and regional markets adds operational complexity for manufacturers exporting certified products across multiple geographies, requiring additional compliance management resources.
Market Opportunities
- Expansion into Emerging Markets: Growing Jewish diaspora communities and rising consumer interest in certified food products across Asia-Pacific, Latin America, and the Middle East and Africa present significant expansion opportunities for kosher food manufacturers and distribution networks.
- Product Innovation in Plant-Based and Organic Kosher Categories: Rising demand for plant-based proteins and organic certified foods is creating new product development opportunities within the kosher segment, particularly in pulses, grains, and plant-derived seafood alternatives.
Market Challenges
- Consumer Awareness Gaps in Emerging Geographies: Limited awareness of kosher certification standards and their benefits among mainstream consumers in emerging markets slows adoption rates and requires sustained consumer education and marketing investment from brands and certification bodies.
- Supply Chain Disruptions and Ingredient Sourcing Complexity: Disruptions in global food supply chains can disproportionately affect kosher food manufacturers, whose sourcing options are restricted to certified suppliers, limiting flexibility to substitute ingredients during periods of raw material scarcity.
Emerging Market Trends
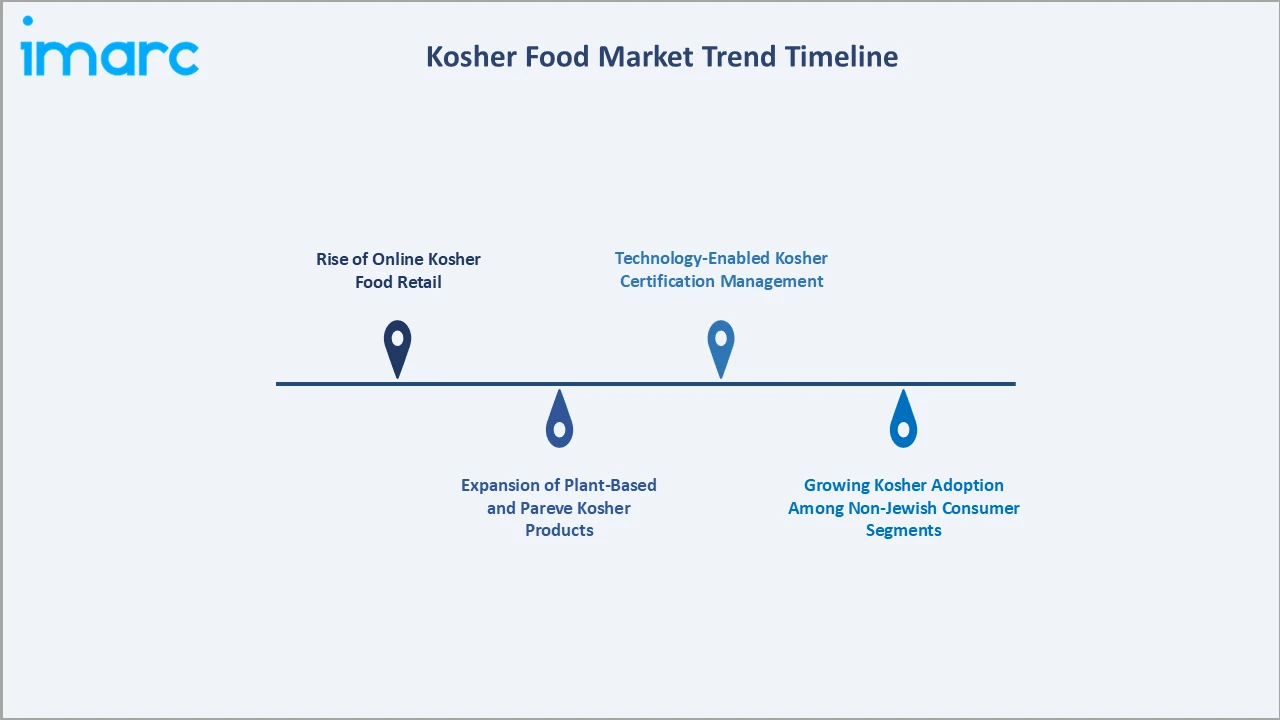
1. Rise of Online Kosher Food Retail
Online stores are gaining traction in kosher food distribution, reflecting increasing digital adoption among kosher consumers. Specialty kosher e-commerce platforms and mainstream online grocers are expanding their certified product ranges, enabling consumers in geographically underserved markets to access a wider variety of kosher-certified products with greater convenience.
2. Expansion of Plant-Based and Pareve Kosher Products
Growing demand for plant-based proteins and dairy-free food alternatives is driving innovation in the pareve kosher product category, which includes products containing neither meat nor dairy. This trend aligns with broader consumer shifts toward flexitarian and vegan diets, expanding the addressable market for kosher-certified food manufacturers.
3. Technology-Enabled Kosher Certification Management
Digital platforms and mobile applications are emerging as tools for real-time kosher status verification, supply chain monitoring, and consumer-facing product information. Technology adoption across certification agencies is streamlining the audit and supervision process, reducing operational complexity for manufacturers maintaining multiple certified production lines.
4. Growing Kosher Adoption Among Non-Jewish Consumer Segments
Muslim consumers, who view kosher certification as a proxy for halal compliance in certain categories, along with health-conscious and clean-label shoppers, are increasingly purchasing kosher-certified products. This cross-demographic demand is encouraging food manufacturers to expand kosher certification across mainstream product lines beyond traditional Jewish food categories.
Industry Value Chain Analysis
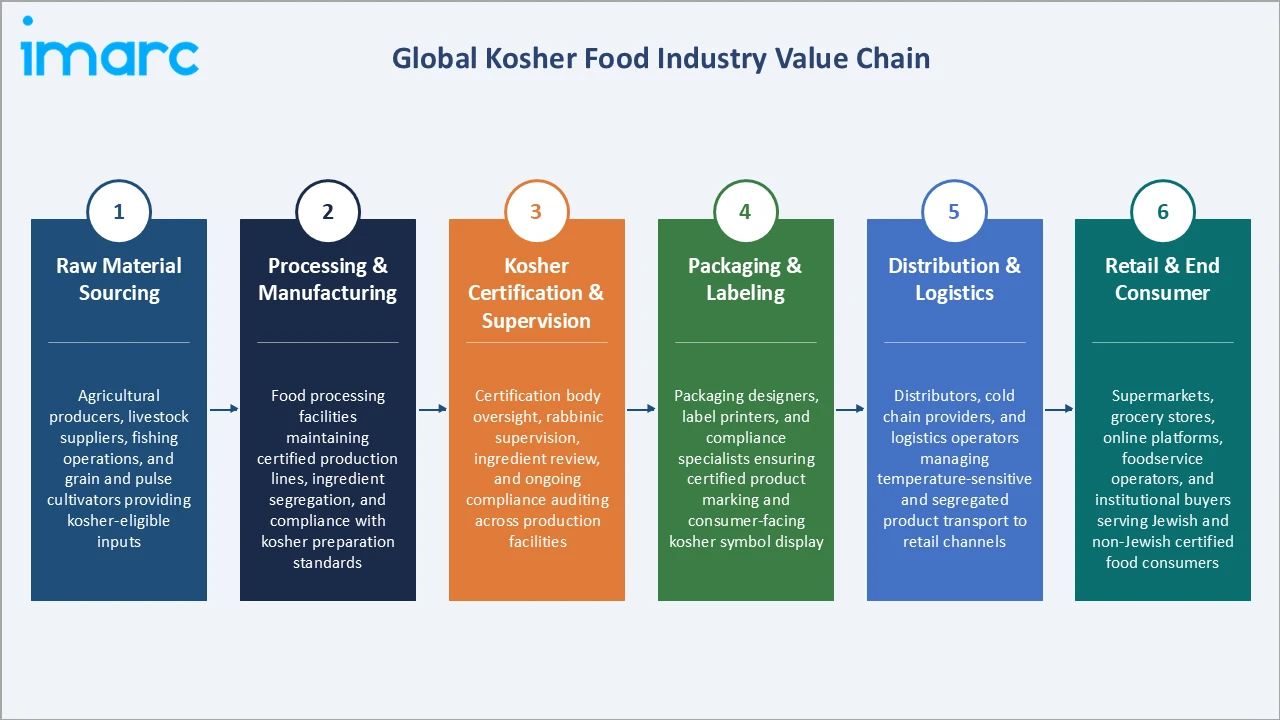
The global kosher food market value chain spans six stages, from raw material sourcing through end consumer engagement. Kosher certification and supervision, along with processing and manufacturing, capture the highest value-add within the chain, as they determine product eligibility for certified market segments.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Agricultural producers, livestock suppliers, fishing operations, and grain and pulse cultivators providing kosher-eligible inputs |
| Processing & Manufacturing | Food processing facilities maintaining certified production lines, ingredient segregation, and compliance with kosher preparation standards |
| Kosher Certification & Supervision | Certification body oversight, rabbinic supervision, ingredient review, and ongoing compliance auditing across production facilities |
| Packaging & Labeling | Packaging designers, label printers, and compliance specialists ensuring certified product marking and consumer-facing kosher symbol display |
| Distribution & Logistics | Distributors, cold chain providers, and logistics operators managing temperature-sensitive and segregated product transport to retail channels |
| Retail & End Consumer | Supermarkets, grocery stores, online platforms, foodservice operators, and institutional buyers serving Jewish and non-Jewish certified food consumers |
Manufacturers that own certified production lines and maintain direct relationships with certification bodies are positioned to capture greater value within the chain than those dependent on third-party co-manufacturers, due to greater control over compliance timelines, ingredient approvals, and certification renewal processes.
Technology Landscape in the Kosher Food Industry
Digital Certification and Compliance Platforms
Kosher certification agencies are adopting cloud-based platforms for managing audit records, facility registrations, and ingredient approval workflows. These systems reduce manual oversight requirements and improve transparency across distributed manufacturing operations.
Blockchain for Supply Chain Traceability
Blockchain technology is emerging as a tool for tracking kosher-eligible ingredients from origin through processing and retail, enabling tamper-resistant documentation of certification status at each supply chain stage and improving consumer trust in product label integrity.
E-Commerce and Digital Retail Platforms
Dedicated kosher e-commerce platforms and mainstream online grocery services are integrating certification filters and kosher product search tools, improving product discoverability and broadening consumer access to certified food products across geographically diverse markets.
Automation in Kosher Food Processing
Automated processing and packaging technologies are being deployed in kosher food manufacturing to reduce cross-contamination risks, streamline production line transitions between certified product categories, and support consistent compliance with kosher preparation standards at scale.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Buckwheat |
32.6% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Distribution Channel |
Supermarkets and Hypermarkets |
48.5% |
2025 |
|
Region |
North America |
39.8% |
2025 |

By Type
Buckwheat commands a 32.6% majority share of the kosher food market in 2025, reflecting its versatility in food preparation and suitability for a range of specialty food applications. Its use in flour, cereals, and baked goods supports its incorporation into diverse kosher product offerings.
To access detailed market analysis, Request Sample
Seafood at 24.8% is the second largest segment, driven by consumer demand for kosher-certified fish varieties excluding shellfish, consistent with Jewish dietary laws.
By Distribution Channel
Supermarkets and hypermarkets dominate distribution channel with a 48.5% share in 2025, benefiting from dedicated kosher sections, refrigerated certified product displays, and large-format product assortments that attract regular kosher shoppers. The channel's broad geographic footprint and consumer convenience position it as the primary purchase point for both Jewish and non-Jewish certified food consumers.
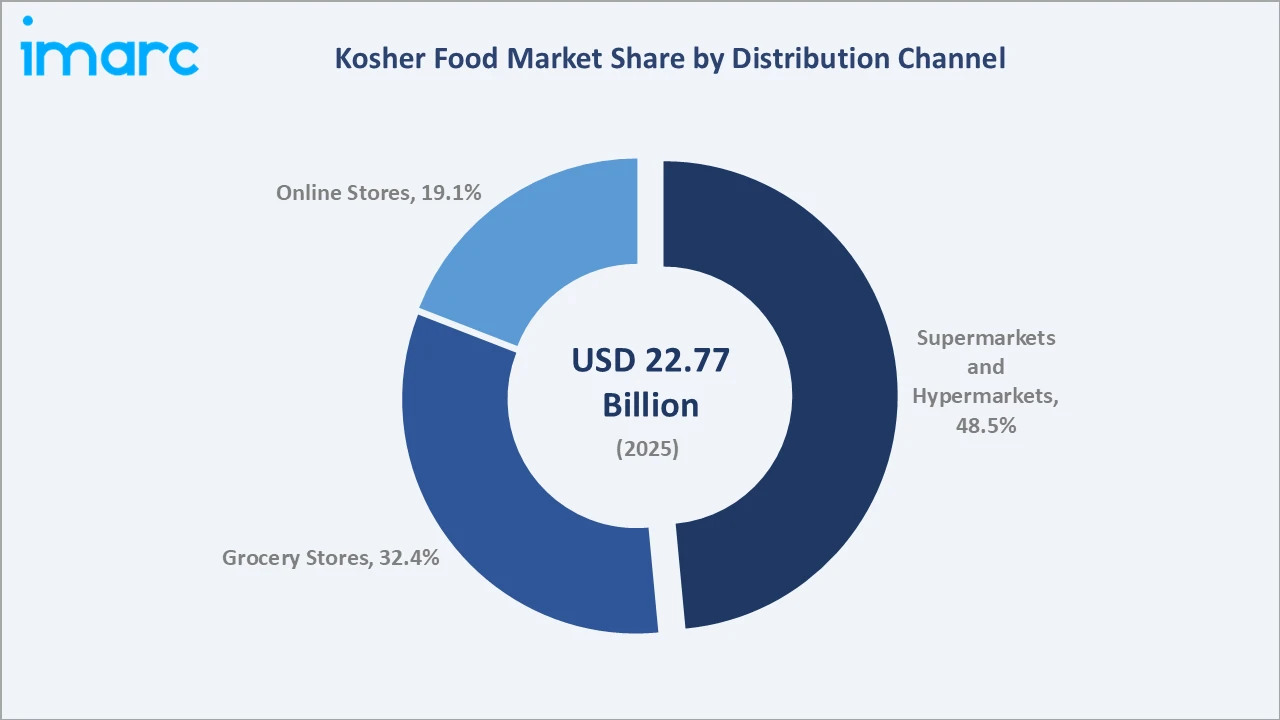
Grocery stores at 32.4% remain important for neighborhood-level access, particularly in areas with concentrated Jewish communities where specialty kosher grocery stores serve as primary shopping destinations.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| North America | 39.8% | Large Jewish population base, mature kosher certification infrastructure, extensive retail kosher sections, and strong institutional demand |
| Europe | 30.6% | Growing Jewish consumer base, expanding retail kosher availability, and rising non-Jewish certified food adoption in Western Europe |
| Asia-Pacific | 17.4% | Rising awareness of kosher food, growing Jewish diaspora communities, and expanding certified product distribution through online channels |
| Latin America | 7.1% | Established Jewish communities in major urban centres, growing health food interest, and expanding certified food retail availability |
| Middle East and Africa | 5.1% | Jewish community concentration in Israel, growing regional demand for certified food products, and rising export-oriented kosher food production |
North America leads the kosher food market with a 39.8% share, anchored by a large and geographically concentrated Jewish consumer base in the United States and Canada. A mature kosher retail infrastructure, extensive certified restaurant and foodservice sectors, and deep institutional demand from caterers and hospitality operators support sustained regional market leadership through the forecast period.
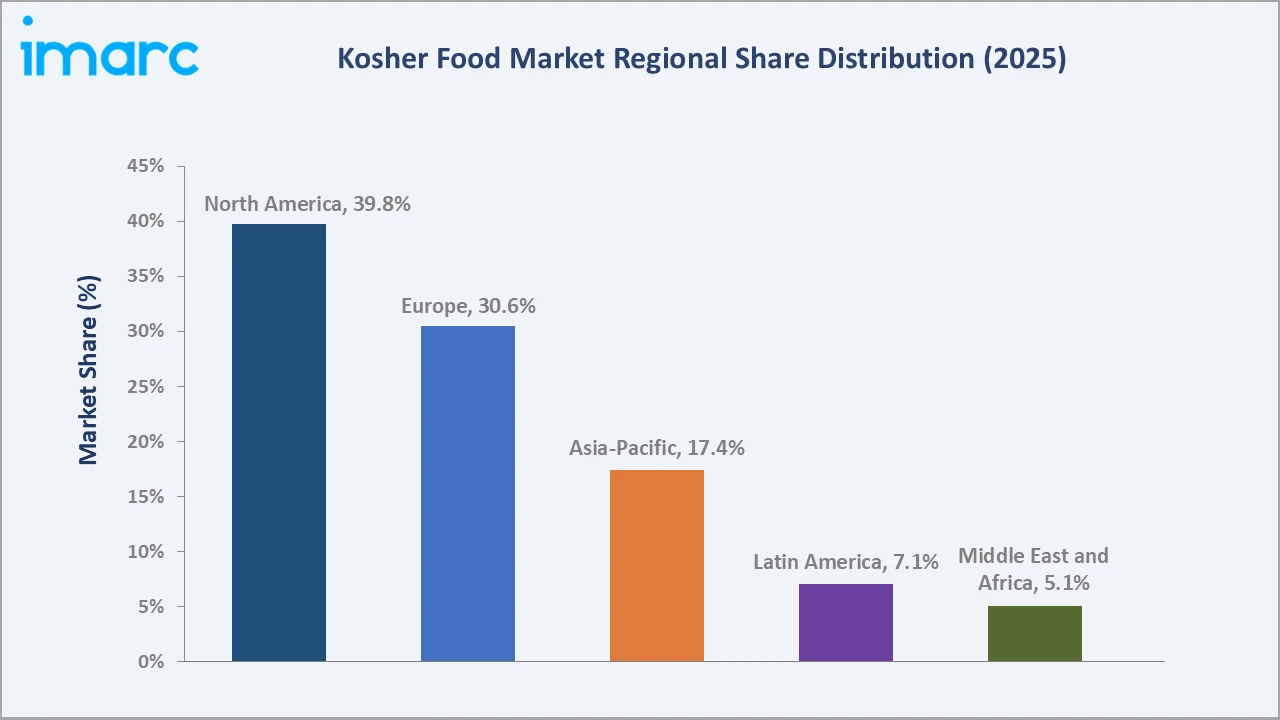
Europe at 30.6% represents the second largest regional market, led by established Jewish communities in the United Kingdom, France, Germany, and Belgium. Growing consumer interest in certified food products among non-Jewish shoppers seeking clean-label assurance is expanding the addressable market beyond the core Jewish consumer segment.
Competitive Landscape
The kosher food market is moderately concentrated, with established food multinationals and specialized kosher brands competing across type, distribution channel, and regional segments. Product portfolio breadth, certification credentials, and retail distribution reach form the primary competitive differentiators across the industry.
| Company Name | Brand / Key Product | Market Position | Strategic Focus |
|---|---|---|---|
| Conagra Brands | Hebrew National | Leader | Expanding kosher protein portfolio through brand investment and enhanced retail distribution |
| TableTrust Brands LLC | Empire Kosher | Leader | Growing Empire Kosher certified poultry market share through product quality and retail distribution development |
| Kayco | Manischewitz | Leader | Strengthening core kosher grocery offerings through product line extensions and seasonal assortment development |
| PepsiCo, Inc. | Sabra | Challenger | Expanding kosher certified refrigerated dip and spread categories through retail and foodservice channel investment |
Key players include Conagra Brands, TableTrust Brands LLC, Kayco, and PepsiCo, Inc., among others.
Key Company Profiles
Conagra Brands
Conagra Brands is a major United States-based food company with a diversified portfolio spanning packaged foods, refrigerated products, and frozen foods, including its well-known Hebrew National brand of kosher beef products.
- Product Portfolio: Kosher beef hot dogs, sausages, and processed meat products certified under kosher dietary standards.
- Recent Developments: The company continues to invest in its Hebrew National brand through product line modernization and expanded retail distribution, maintaining its position as a leading kosher beef product brand.
- Strategic Focus: Strengthening brand equity in kosher protein categories through consumer marketing investment and retail distribution expansion across mainstream grocery and club store channels.
TableTrust Brands LLC
TableTrust Brands LLC is a United States-based specialty poultry holding company comprising the Empire Kosher brand. Empire Kosher is one of the most recognized kosher poultry brands in North America, serving retail and foodservice customers with certified chicken and turkey products.
- Product Portfolio: Kosher-certified chicken, turkey, and poultry products under the Empire Kosher brand, distributed through supermarkets, kosher specialty stores, and foodservice operators.
- Recent Developments: The company continues to develop its Empire Kosher certified poultry range, maintaining rigorous kosher certification standards while expanding product variety and retail distribution across the market.
- Strategic Focus: Growing certified poultry market share through product quality, kosher certification integrity, and expanded distribution in kosher retail and specialty grocery channels.
Kayco
Kayco is a leading United States-based kosher food company and the owner of the Manischewitz brand, one of the most widely recognized kosher food brands globally, specializing in matzo, wines, grape juice, soups, and Passover specialty products.
- Product Portfolio: Kosher matzo, wines, grape juice, soups, broths, and a broad range of Passover and year-round certified food products under the Manischewitz brand.
- Recent Developments: The company continues to extend its core product lines across grocery and specialty retail channels, focusing on maintaining certified product quality and expanding seasonal and year-round product availability for kosher consumers.
- Strategic Focus: Broadening kosher grocery product assortment and reinforcing brand positioning through seasonal product launches and continued retail presence in mainstream grocery channels.
Market Concentration Analysis
The kosher food market is moderately concentrated, with leading food multinationals and established kosher specialty brands holding significant share across key product categories and distribution channels.
High entry barriers, including the cost of maintaining certified production infrastructure and the time required to build certification credentials, favor established players with existing rabbinic supervision relationships and retail distribution networks.
Consolidation activity within the market has been gradual, as larger food companies selectively acquire established kosher brands to capture certified consumer segments without building certification capabilities from scratch. Smaller, category-focused kosher food producers continue to serve niche segments and regional markets, maintaining competitive relevance through product specialization, seasonal expertise, and deep relationships with kosher certification authorities.
Investment & Growth Opportunities
Fastest-Growing Segments
Online stores are the fastest-growing distribution channel, expanding rapidly as kosher e-commerce platforms and mainstream online grocers broaden their certified food product assortments. Pulses are among the fastest-growing type segments, driven by rising plant-based diet adoption among health-conscious and vegan kosher consumers.
Emerging Markets
Middle East and Africa represents the fastest-growing region, supported by rising awareness of kosher-certified products, expanding modern retail infrastructure, and increasing availability of specialty food products through online and offline distribution channels.
Venture & Investment Trends
Investment activity within the kosher food market is concentrated in plant-based certified product innovation, digital certification management platforms, and e-commerce distribution infrastructure. Capital is also flowing into kosher foodservice and catering operations, reflecting growing institutional demand for certified food services across hospitality, healthcare, and education sectors.
Future Market Outlook (2026-2034)
The kosher food market is projected to grow from USD 22.77 Billion in 2025 to USD 23.43 Billion in 2026, reaching USD 29.67 Billion by 2034, registering a CAGR of 2.89% during 2026-2034.
Four forces will shape the market through 2034: continued growth in non-Jewish certified food adoption; expansion of plant-based and organic kosher product innovation; rising e-commerce penetration for specialty certified food categories; and geographic expansion of kosher certification networks into Asia-Pacific and Latin American markets.
By 2034, the kosher food market is expected to be defined by broader mainstream certification integration, with certified products increasingly available across conventional food categories and mainstream retail formats. Technology-enabled certification management and digital traceability will support sustained compliance efficiency and consumer transparency.
Research Methodology
Primary Research
Primary research included structured discussions with kosher food manufacturers, certification agency representatives, retail buyers, and foodservice procurement specialists, validating market sizing, segment distribution, and regional demand patterns across key geographies.
Secondary Research
Secondary sources included company annual reports, investor presentations, regulatory publications from kosher certification bodies, trade association data, and published financial filings from publicly listed food companies with kosher product portfolios.
Forecasting Models
Market forecasts used top-down and bottom-up models combining certified product volume data, retail distribution penetration rates, consumer spending trends, and macroeconomic variables. Scenario analysis addressed certification expansion pace, e-commerce channel growth, and shifts in non-Jewish certified food consumer purchasing behavior.
Kosher Food Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Buckwheat, Seafood, Lamb, Pulses, Others |
| Applications Covered | Culinary Products, Snacks and Savory, Bakery and Confectionery Products, Meat, Beverages, Dietary Supplements |
| Distribution Channels Covered | Supermarkets and Hypermarkets, Grocery Stores, Online Stores |
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Countries Covered | United States, Canada, Germany, France, United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Mexico |
| Companies Covered | Conagra Brands, TableTrust Brands LLC, Kayco, PepsiCo, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, kosher food market forecast, and dynamics of the market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global kosher food market.
- The study maps the leading, as well as the fastest-growing, regional markets. It further enables stakeholders to identify the key country-level markets within each region.
- Porter's five forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the kosher food industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Kosher Food Market Report
The kosher food market size is estimated at USD 23.43 Billion in 2026, driven by rising consumer demand for certified food products, urbanization, and expanding distribution across mainstream retail and online channels.
The market is projected to grow at a CAGR of 2.89% from 2026-2034, reaching USD 29.67 Billion by 2034, supported by expanding non-Jewish adoption and online distribution.
Buckwheat leads the type segment at 32.6% in 2025, driven by its versatility in food preparation and use across various kosher food products.
Supermarkets and hypermarkets dominate at 48.5% share in 2025, supported by dedicated kosher sections and broad geographic retail footprints serving Jewish and non-Jewish consumers.
North America commands 39.8% share in 2025, anchored by a large Jewish consumer base, mature certification infrastructure, and extensive kosher retail and foodservice ecosystems.
Leading players include Conagra Brands, TableTrust Brands LLC, Kayco, and PepsiCo, Inc., among others.
Growth is driven by rising clean-label demand, expansion of certified product categories, growing non-Jewish consumer adoption, and increasing online availability of kosher food products.
High certification compliance costs, limited availability of certified raw materials in emerging markets, and consumer awareness gaps in non-traditional kosher markets are primary challenges.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade