
Mexico Calibration Services Market Size, Share, Trends and Forecast by Service Type, Calibration Type, End-Use Industry, and Region, 2026-2034
Mexico Calibration Services Market Size, Share, Trends & Forecast (2026-2034)
The Mexico calibration services market reached USD 73.56 Million in 2025, is estimated to reach USD 77.14 Million in 2026, and is projected to reach USD 115.30 Million by 2034, growing at a CAGR of 4.86% during 2026-2034. Growth is driven by increasing demand for precision measurement in automotive, aerospace, and electronics manufacturing, underpinned by ISO/IEC 17025 compliance requirements and USMCA trade expansion.
Rising adoption of accredited third-party calibration services, expansion of digital and remote calibration capabilities, and Mexico's growing role as a global manufacturing hub are further supporting market growth through 2034. Third-party service commands 46.8% of service type share; electronics manufacturing leads end-use at 31.6%; Northern Mexico holds 45.0% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 73.56 Million |
|
Market Size (2026) |
USD 77.14 Million |
|
Forecast Market Size (2034) |
USD 115.30 Million |
|
CAGR (2026-2034) |
4.86% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Service Type |
Third-Party Service (46.8%, 2025) |
|
Leading End-Use Industry |
Electronics Manufacturing (31.6%, 2025) |
|
Leading Region |
Northern Mexico (45.0%, 2025) |
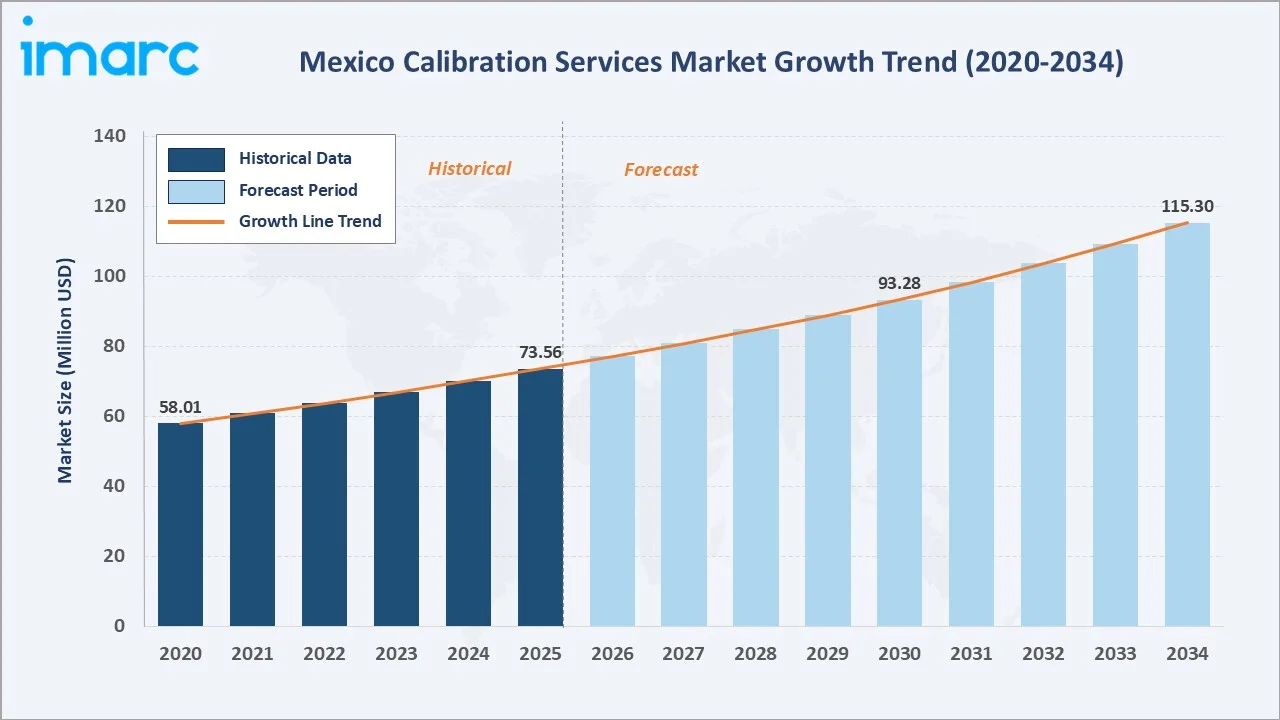
The Mexico calibration services market reached USD 58.01 Million in 2020, growing steadily to USD 73.56 Million in 2025. The market is projected to reach USD 77.14 Million in 2026, advancing to USD 93.28 Million by 2030 and USD 115.30 Million by 2034 at a CAGR of 4.86%, driven by manufacturing sector expansion and regulatory compliance demand.
To get more information on this market, Request Sample
Third-party service leads at 46.8% through its cost efficiency and ISO/IEC 17025 accreditation advantages for manufacturers. Electronics manufacturing dominates end-use at 31.6%, reflecting Mexico's expanding semiconductor and consumer electronics production base requiring precision calibration.
Executive Summary
The Mexico calibration services market expanded from USD 73.56 Million in 2025 to USD 77.14 Million in 2026, projected to reach USD 115.30 Million by 2034. Growth is anchored by Mexico's expanding automotive and aerospace manufacturing sectors, strict ISO/IEC 17025 accreditation requirements, and USMCA-driven precision manufacturing investment.
Third-party service commands 46.8% of service type share; electronics manufacturing leads end-use at 31.6%; Northern Mexico holds 45.0% regional share.
Key Market Insights
|
Insight |
Data |
|
Dominant Service Type |
Third-Party Service – 46.8% share (2025) |
|
Leading End-Use Industry |
Electronics Manufacturing – 31.6% market share (2025) |
|
Leading Region |
Northern Mexico – 45.0% share (2025) |
|
Market Opportunity |
Digital & remote calibration; ISO/IEC 17025 compliance demand; EV & semiconductor sector expansion |
Key Analytical Observations Supporting the Above Data:
- Third-Party Service at 46.8%: Third-party service dominates through cost efficiency, ISO/IEC 17025 accreditation, and comprehensive coverage of electrical, mechanical, thermal, and dimensional calibration for Mexico's diverse industrial base without capital-intensive in-house laboratory investment.
- Electronics Manufacturing at 31.6%: Electronics manufacturing leads end-use due to Mexico's growing semiconductor, consumer electronics, and PCB assembly sectors requiring high-frequency, precision calibration of test and measurement equipment per international quality standards.
- Northern Mexico at 45.0%: Northern Mexico leads regionally through concentration of automotive, aerospace, and electronics manufacturing in Monterrey, Saltillo, and border industrial parks, where ISO/IEC 17025 accredited calibration is required for USMCA supply chain compliance.
Mexico Calibration Services Market Overview
Mexico calibration services market is structurally anchored in the country's position as a leading global manufacturing hub across automotive, aerospace, electronics, and medical device sectors. Over 3 million vehicles produced annually and a rapidly growing electronics manufacturing sector create consistent demand for accredited calibration services.
Mexico calibration services ecosystem integrates global third-party service providers, OEM calibration centres, in-house laboratory operations, and digital calibration platforms. ISO/IEC 17025:2017 remains the foundational accreditation standard driving quality and compliance across the market.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
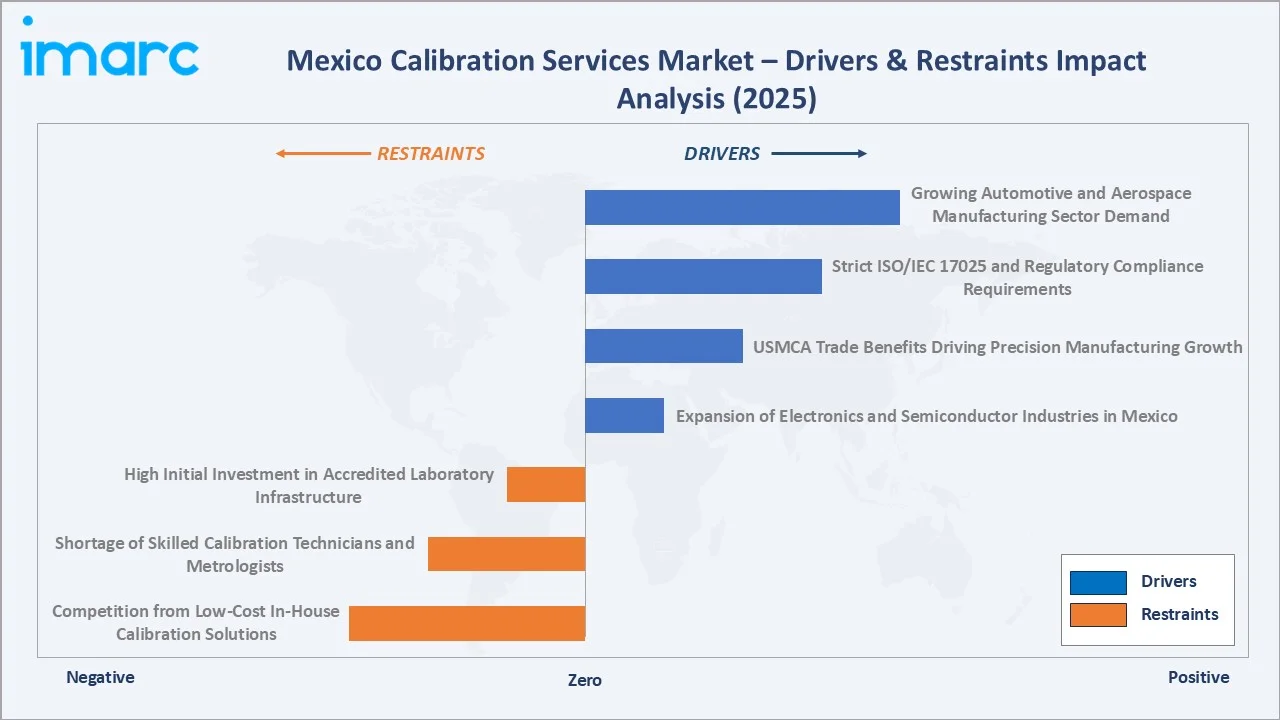
- Growing Automotive and Aerospace Manufacturing Sector Demand: Mexico's position as a top-five global automotive manufacturer creates sustained demand for accredited calibration services for precision production equipment. Aerospace manufacturing expansion in Querétaro and Monterrey further drives high-value calibration service requirements aligned with AS9100 and NADCAP standards.
- Strict ISO/IEC 17025 and Regulatory Compliance Requirements: Mandatory ISO/IEC 17025 accreditation requirements for calibration laboratories serving automotive, aerospace, and pharmaceutical sectors are driving systematic investment in third-party calibration services. CENAM traceability requirements and NOM standards reinforce the compliance-driven demand for accredited calibration.
- USMCA Trade Benefits Driving Precision Manufacturing Growth: USMCA trade framework requirements for supply chain quality documentation and measurement traceability are compelling Mexican manufacturers to invest in accredited calibration services. Cross-border automotive supply chains require ISO-traceable calibration certificates for quality system compliance at both US and Mexican facilities.
- Expansion of Electronics and Semiconductor Industries in Mexico: Mexico's growing electronics manufacturing sector, including semiconductor assembly, PCB production, and consumer electronics manufacturing, requires high-frequency calibration of precision test and measurement instruments. New fab investments and NEARSHORING trends are creating expanding calibration service demand.
Market Restraints
- High Initial Investment in Accredited Laboratory Infrastructure: Establishing ISO/IEC 17025-accredited calibration laboratories requires significant capital investment in reference standards, environmental controls, personnel qualification, and accreditation audit processes, creating financial barriers for domestic calibration service providers attempting market entry or scope expansion.
- Shortage of Skilled Calibration Technicians and Metrologists: Mexico faces a persistent skills gap in trained calibration technicians, metrologists, and quality engineers with proficiency in ISO/IEC 17025 laboratory management and measurement uncertainty analysis, limiting capacity expansion for accredited calibration service providers in high-demand industrial regions.
- Competition from Low-Cost In-House Calibration Solutions: Larger manufacturers are increasingly investing in in-house calibration capabilities to reduce service costs and downtime, particularly for high-volume, lower-complexity electrical and dimensional calibration. This trend moderates third-party service market growth in some manufacturing segments.
Market Opportunities
- Digital and Remote Calibration Technology Adoption: Emerging digital calibration solutions, cloud-based calibration management software, and remote calibration capabilities are creating new service delivery models that reduce customer downtime and extend calibration service reach beyond traditional lab-based formats.
- EV and Semiconductor Manufacturing Expansion: Growing electric vehicle battery manufacturing and semiconductor assembly investment in Mexico is creating specialised calibration demand for new instrument types including high-current measurement equipment, torque calibration, and precision electrical test systems.
Market Challenges
- Maintaining International Accreditation Scope and Currency: Calibration laboratories must continuously update their CENAM-traceable reference standards, maintain personnel qualification, and expand calibration scope to serve evolving industry needs, requiring ongoing investment that creates operational pressure for smaller service providers.
- Managing Instrument Turnaround Time and Customer Downtime: Minimising calibration turnaround time while maintaining accreditation-required quality processes remains a persistent operational challenge, particularly in automotive and electronics sectors where equipment downtime directly impacts production throughput and delivery schedules.
Emerging Market Trends
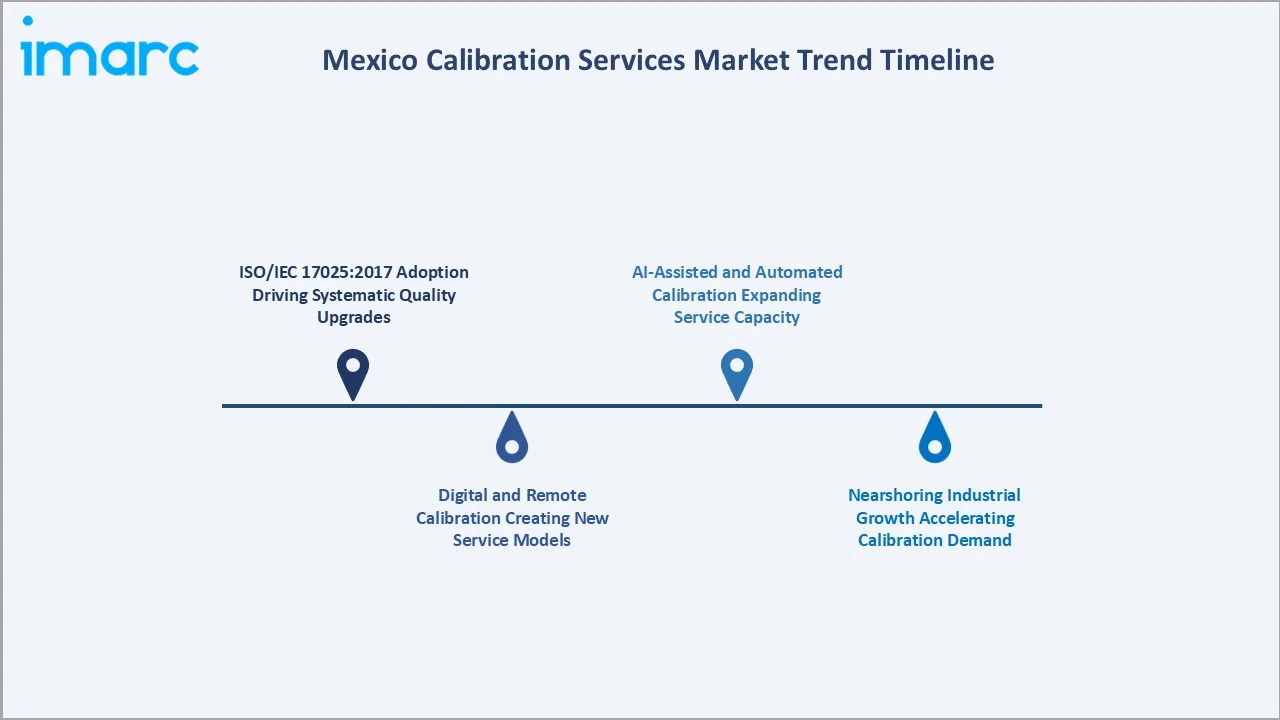
1. ISO/IEC 17025:2017 Adoption Driving Systematic Quality Upgrades
ISO/IEC 17025:2017 adoption across Mexico's manufacturing sectors is systematically elevating calibration quality requirements. The standard's competence, impartiality, and consistent operation requirements are compelling manufacturers to select fully accredited third-party providers over lower-cost unaccredited alternatives.
2. Digital and Remote Calibration Creating New Service Models
Digital calibration solutions and remote measurement verification technologies are transforming service delivery, reducing instrument off-site time and enabling calibration of in-situ installed equipment. Cloud-based calibration asset management platforms are becoming integral to quality management system integration.
3. AI-Assisted and Automated Calibration Expanding Service Capacity
Artificial intelligence and automated calibration systems are increasing laboratory throughput, reducing human measurement error, and enabling data-driven predictive calibration scheduling. These technologies are helping accredited service providers expand capacity without proportional headcount increases.
4. Nearshoring Industrial Growth Accelerating Calibration Demand
Mexico's nearshoring manufacturing boom, attracting electronics, semiconductor, and EV battery investment from Asia and North America, is creating new geographic pockets of calibration demand in Central and Northern Mexico industrial parks beyond established manufacturing centres.
Industry Value Chain Analysis
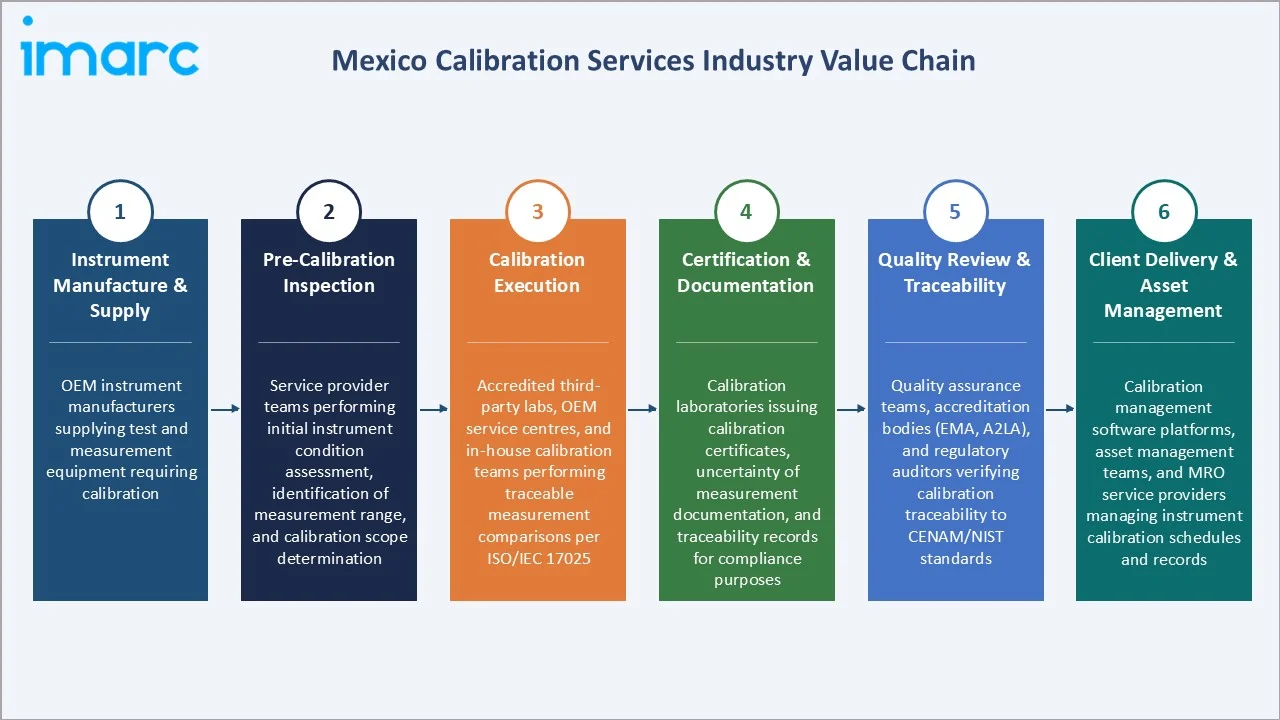
Mexico calibration services value chain begins with instrument manufacture and procurement, progressing through pre-calibration inspection, calibration execution, certification documentation, quality review, and client delivery with ongoing asset management support for calibration cycle management.
|
Stage |
Key Participants |
|
Instrument Manufacture & Supply |
OEM instrument manufacturers supplying test and measurement equipment requiring calibration |
|
Pre-Calibration Inspection |
Service provider teams performing initial instrument condition assessment, identification of measurement range, and calibration scope determination |
|
Calibration Execution |
Accredited third-party labs, OEM service centres, and in-house calibration teams performing traceable measurement comparisons per ISO/IEC 17025 |
|
Certification & Documentation |
Calibration laboratories issuing calibration certificates, uncertainty of measurement documentation, and traceability records for compliance purposes |
|
Quality Review & Traceability |
Quality assurance teams, accreditation bodies (EMA, A2LA), and regulatory auditors verifying calibration traceability to CENAM/NIST standards |
|
Client Delivery & Asset Management |
Calibration management software platforms, asset management teams, and MRO service providers managing instrument calibration schedules and records |
The calibration execution and certification documentation stage is the value chain's most commercially critical segment, where measurement comparison against CENAM-traceable reference standards and uncertainty of measurement documentation determine service accreditation status and client compliance certificate validity.
Technology Landscape in the Mexico Calibration Services Industry
Automated and Semi-Automated Calibration Systems
Automated calibration systems using PC-controlled reference standards and automated measurement routines are improving laboratory throughput, reducing human error, and enabling consistent calibration quality across high-volume instrument populations. These systems are becoming standard in accredited third-party laboratories serving Mexico's automotive and electronics sectors.
Cloud-Based Calibration Management Software
Cloud-based calibration asset management platforms are enabling manufacturers to digitise calibration records, automate recall scheduling, and integrate calibration status into quality management systems. These platforms reduce administrative burden and ensure audit-ready calibration documentation for ISO 9001 and IATF 16949 compliance.
Remote and On-Site Mobile Calibration Technologies
Mobile calibration laboratories and portable reference standard kits are enabling calibration service providers to perform on-site calibration at customer facilities, minimising instrument transport time and production disruption. This technology is particularly valuable for large or fixed-installation measurement equipment in Mexico's automotive and petrochemical sectors.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Service Type |
Third-Party Service |
46.8% |
2025 |
|
Calibration Type |
🔒 |
🔒 |
2025 |
|
End-Use Industry |
Electronics Manufacturing |
31.6% |
2025 |
|
Region |
Northern Mexico |
45.0% |
2025 |

By Service Type
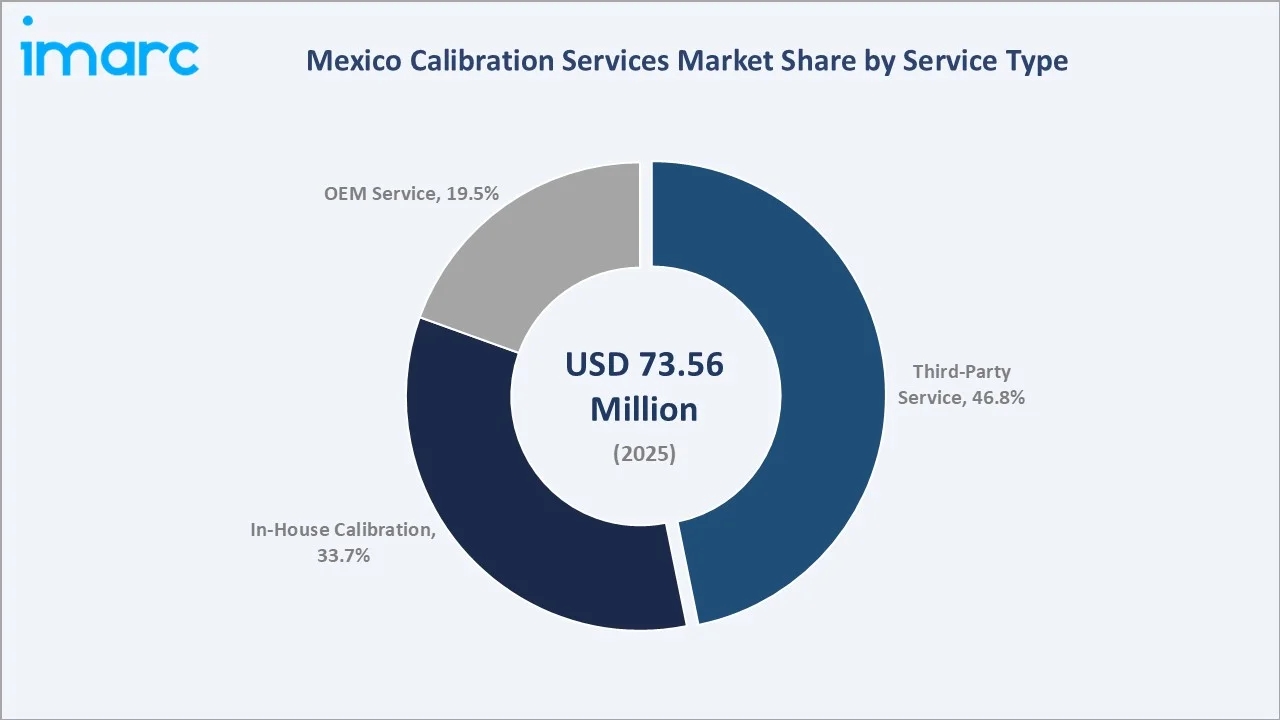
Third-party service leads at 46.8% (2025). Third-party calibration service providers dominate by offering ISO/IEC 17025-accredited calibration across multiple disciplines, eliminating the need for capital-intensive in-house laboratory infrastructure while providing full measurement traceability and compliance documentation required by international quality standards.
To access detailed market analysis, Request Sample
In-house calibration at 33.7% serves larger manufacturers with high instrument volumes and investment capacity. OEMs at 19.5% provide calibration specifically for their own instrument lines, with Fluke, Keysight, and Tektronix offering factory-level traceability for their respective product portfolios.
By End-Use Industry
Electronics manufacturing leads at 31.6% (2025). Mexico's expanding electronics production base — encompassing semiconductor assembly, PCB manufacturing, consumer electronics, and communication equipment — requires high-frequency precision calibration of test and measurement equipment to maintain product quality and international certification compliance.
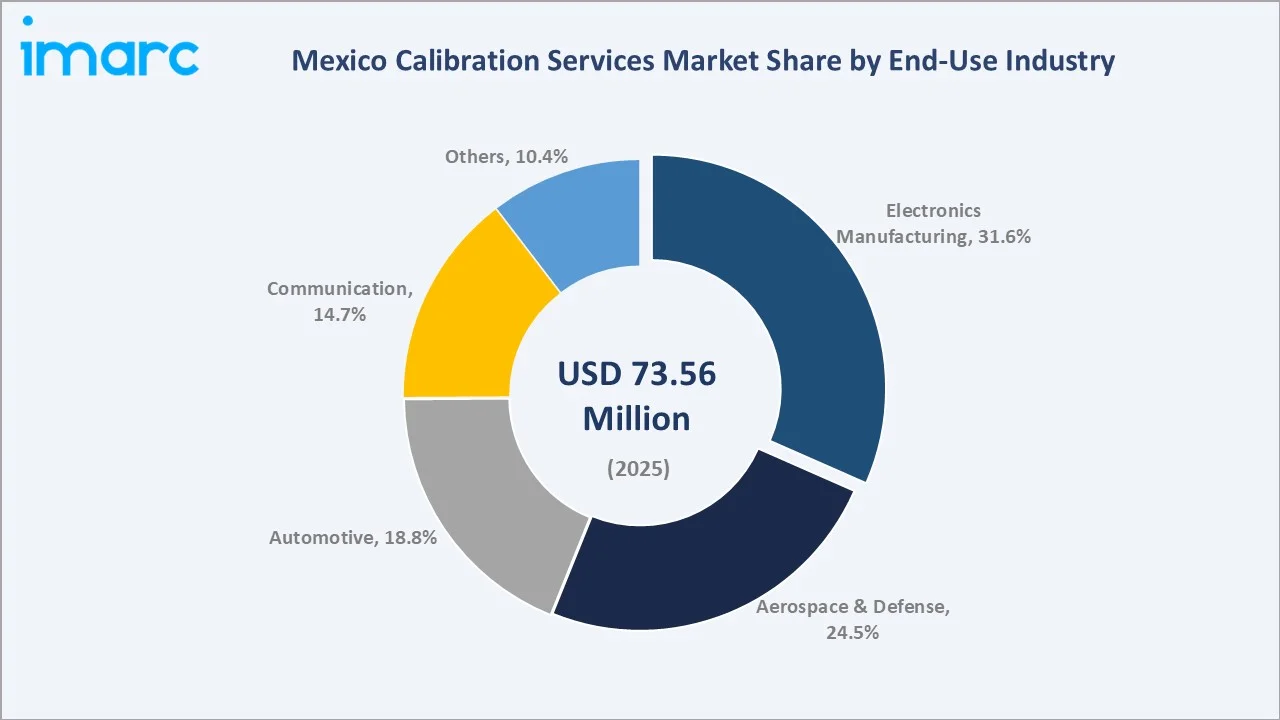
Aerospace and defense at 24.5% demands the highest calibration precision with NADCAP and AS9100 requirements. Automotive at 18.8% is growing through IATF 16949 compliance. Communication at 14.7% serves the expanding telecom infrastructure sector. Others (10.4%) includes pharma and energy.
Regional Market Insights
|
Region |
Share (2025) |
Key Mexico Calibration Services Market Drivers & Characteristics |
|
Northern Mexico |
45.0% |
Dominated by Monterrey and Tamaulipas automotive and aerospace manufacturing clusters requiring high-frequency, accredited calibration services for precision production equipment. |
|
Central Mexico |
35.0% |
Mexico City and Bajío region host the highest concentration of electronics, semiconductor, and advanced manufacturing facilities driving diverse calibration service demand. |
|
Southern Mexico |
15.0% |
Emerging industrial zones in Veracruz and Oaxaca with growing pharmaceutical, food processing, and petrochemical sectors requiring calibration compliance services. |
|
Others |
5.0% |
Border region industrial parks and smaller manufacturing centres served through mobile calibration services and periodic on-site calibration visits. |
Northern Mexico's 45.0% market share reflects Monterrey's industrial manufacturing cluster, Tamaulipas's border automotive and electronics parks, and the Bajío region's aerospace corridor, collectively requiring Mexico's highest concentration of accredited calibration services.
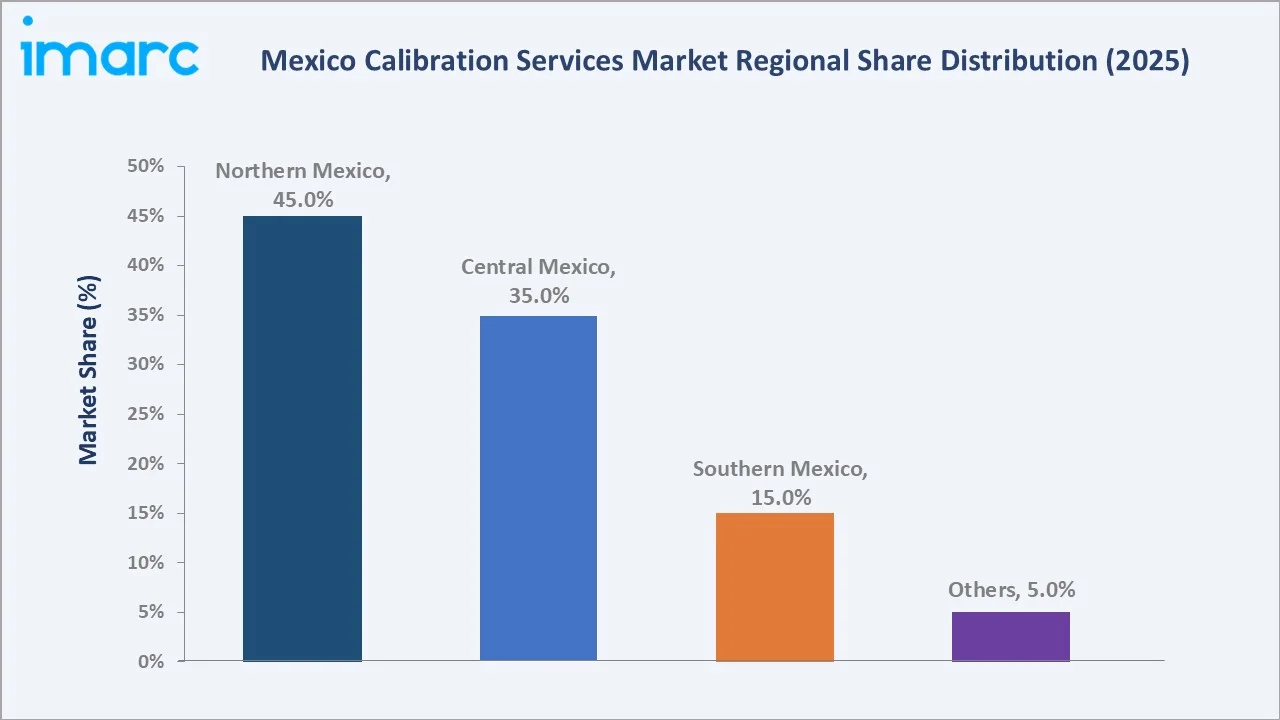
Central Mexico's 35.0% reflects Mexico City's diverse industrial base, Querétaro's aerospace and automotive sector, and the Bajío's growing semiconductor and electronics manufacturing parks driving broad calibration service demand across multiple disciplines.
Competitive Landscape
Mexico calibration services market competitive landscape is led by global third-party service specialists, complemented by OEM calibration providers serving their respective instrument installed bases.
| Company | Key Services | Market Position | Core Strength |
|---|---|---|---|
| SGS Société Générale de Surveillance SA | Testing, Inspection, Calibration, Certification | Strong Challenger | Expanding Mexico labs with automotive, furniture, and electronics testing; added BIFMA and ASTM F963 calibration capabilities serving Mexico's manufacturing sectors. |
| Bureau Veritas | Inspection, Testing, Calibration, Certification | Regional Player | Strong Mexico presence across industrial inspection and calibration; ISO/IEC 17025 accredited labs serving oil & gas, food, pharmaceutical, and manufacturing end-use sectors. |
| Keysight Technologies | Electronic Test & Measurement Calibration | Regional Player | Leading electronic test and measurement OEM providing calibration services for its extensive instrument portfolio; strong presence in electronics and aerospace sectors in Mexico. |
| UL LLC | Safety Testing, Calibration, EMC, Certification | Niche Player | Expanded Mexico laboratory in December 2024; ISO/IEC 17025 accredited services covering EMC testing, product safety, and calibration for electronics and consumer products manufacturers. |
Key players include SGS Société Générale de Surveillance SA, Bureau Veritas, Keysight Technologies, UL LLC, and others.
Key Company Profiles
SGS Société Générale de Surveillance SA
SGS Société Générale de Surveillance SA is a global leader in testing, inspection, and certification services, with expanding laboratory operations in Mexico serving automotive, electronics, furniture, and consumer products sectors through ISO/IEC 17025-accredited calibration, testing, and certification services.
- Key Services: Product testing, calibration, inspection, certification, and conformity assessment across automotive, electronics, food, and industrial sectors in Mexico.
- Strategic Focus: Expanding Mexico laboratory capabilities across emerging testing and calibration sectors, investing in automotive and electronics service capabilities aligned with USMCA supply chain requirements, and growing integrated testing and calibration service offerings for Mexico's manufacturing clients.
Keysight Technologies
Keysight Technologies is a global electronic test and measurement company providing calibration, repair, and uptime services for its extensive instrument portfolio, with an established presence in Mexico serving electronics, aerospace, automotive, and semiconductor manufacturing sectors through ISO/IEC 17025-accredited calibration capabilities.
- Key Services: Electronic test and measurement calibration, instrument repair and uptime services, asset management, start-up assistance, application services, and calibration agreements across automotive, electronics, aerospace, and semiconductor industries in Mexico.
- Strategic Focus: Expanding calibration and services revenue through customer agreements providing contractual uptime and calibration coverage for installed instrument bases; deepening Mexico market penetration by serving nearshoring electronics and EV manufacturing sectors requiring precision test and measurement calibration aligned with ISO/IEC 17025 traceability standards.
Market Concentration Analysis
Mexico calibration services market is moderately fragmented, with global players collectively serving the accredited third-party segment, while OEM providers serve their respective installed base, and large manufacturers operate in-house calibration capabilities.
Market concentration is shifting toward accredited third-party service providers as ISO/IEC 17025 compliance requirements increase across automotive, aerospace, and electronics sectors. Digital calibration management platforms and mobile lab capabilities are creating competitive differentiation beyond traditional laboratory-based service models.
Investment & Growth Opportunities
Highest Growth Segments
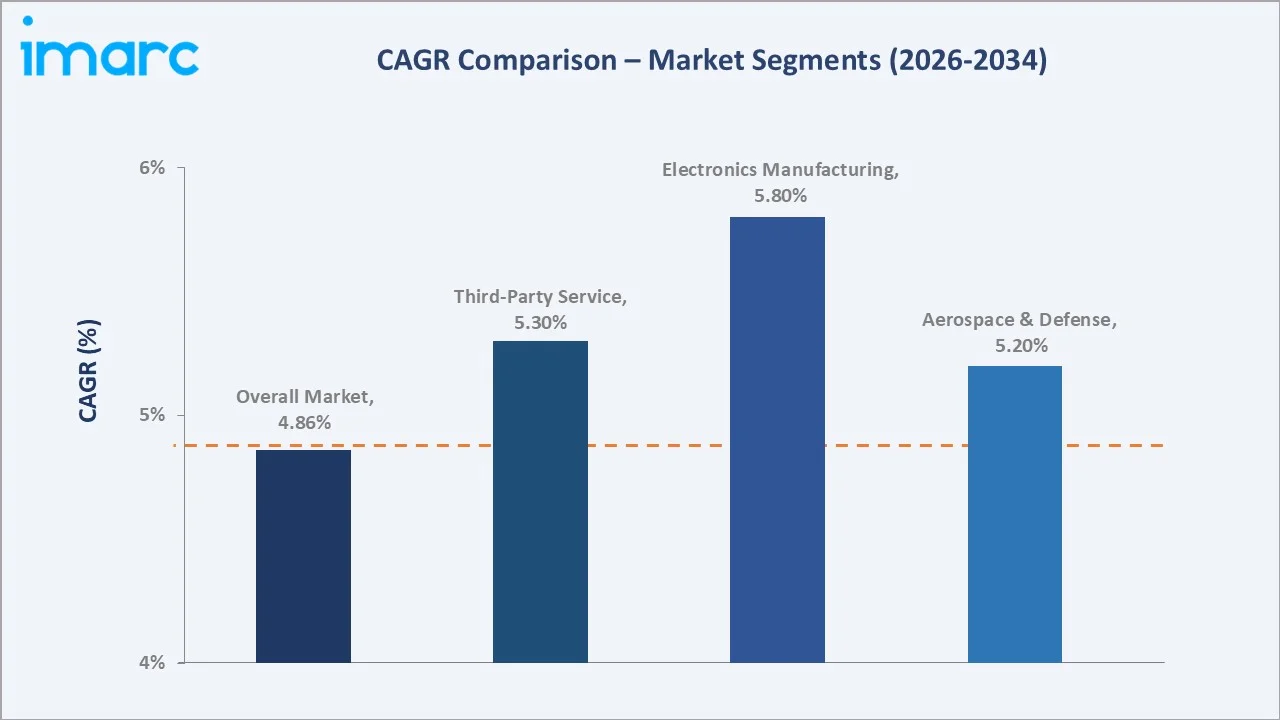
Electronics manufacturing calibration (~5.8% CAGR), aerospace and defense precision calibration (~5.2% CAGR), and digital calibration management platforms represent Mexico's highest-growth calibration service segments through 2034, driven by nearshoring, manufacturing expansion, and compliance requirements.
Emerging Investment Opportunities
Mexico's nearshoring-driven electronics and EV battery manufacturing expansion, ISO/IEC 17025 compliance market growth, and digital calibration technology adoption represent the market's highest-potential commercial investment themes through the forecast period.
Investment Themes
- Accredited third-party calibration laboratory network expansion in Central and Northern Mexico industrial parks to serve nearshoring electronics, semiconductor, and EV manufacturing investment, capturing high-growth compliance-driven calibration demand.
- Digital calibration asset management platform investment integrating IoT-enabled instrument monitoring, predictive calibration scheduling, and cloud-based certificate management for Mexico's quality-intensive automotive and aerospace manufacturers.
Future Market Outlook (2026-2034)
The Mexico calibration services market is projected to grow from USD 73.56 Million in 2025 to USD 77.14 Million in 2026, advancing to USD 115.30 Million by 2034 at a CAGR of 4.86%, driven by manufacturing sector expansion, regulatory compliance intensification, and digital calibration technology adoption.
Three structural forces define Mexico calibration services market growth through 2034: USMCA-driven nearshoring manufacturing investment creating new calibration demand; ISO/IEC 17025 compliance requirements systematically increasing third-party service adoption; and digital calibration platforms enabling service delivery expansion beyond traditional laboratory boundaries.
Research Methodology
Primary Research
Primary research comprised structured interviews with Mexico calibration services market participants including laboratory managers, quality directors, accreditation body representatives, equipment OEMs, and end-user procurement teams across automotive, aerospace, and electronics sectors.
Secondary Research
Secondary research encompassed CENAM accreditation databases, ISO/IEC 17025 laboratory registries, industry association publications, Mexico manufacturing sector reports, USMCA trade documentation, and global calibration services market research publications.
Forecasting Models
Market revenue forecasts were developed using manufacturing sector output models, ISO accreditation growth trajectory analysis, and demand-supply equilibrium frameworks calibrated against verified historical market performance data spanning the 2020-2025 base period.
Mexico Calibration Services Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Service Types Covered | In-House, OEMs, Third-Party Service |
| Calibration Types Covered | Electrical, Mechanical, Thermodynamic, Physical/Dimensional, Others |
| End-Use Industries Covered | Electronics Manufacturing, Communication, Aerospace and Defense, Automotive, Others |
| Regions Covered | Northern Mexico, Central Mexico, Southern Mexico, Others |
| Companies Covered | SGS Société Générale de Surveillance SA, Bureau Veritas, Keysight Technologies, UL LLC |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Mexico calibration services market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Mexico calibration services market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Mexico calibration services industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Mexico Calibration Services Market Report
Mexico calibration services market size reached USD 77.14 Million in 2026, driven by rising precision manufacturing demand, ISO/IEC 17025 compliance requirements, USMCA supply chain quality standards, and Mexico's expanding automotive, aerospace, and electronics manufacturing sectors.
Mexico calibration services market grows at a CAGR of 4.86% during 2026-2034, reaching USD 115.30 Million by 2034, supported by manufacturing sector expansion, nearshoring investment, regulatory compliance growth, and digital calibration technology adoption.
Third-party service leads at 46.8% (2025) through ISO/IEC 17025 accreditation advantages, cost efficiency versus in-house investment, comprehensive multi-discipline calibration coverage, and full measurement traceability documentation required by international quality standards.
Electronics manufacturing leads at 31.6% (2025) through Mexico's growing semiconductor, PCB, and consumer electronics production base requiring high-frequency precision calibration of test and measurement equipment to international quality certification standards.
Northern Mexico leads at 45.0% (2025) through concentration of automotive, aerospace, and electronics manufacturing in Monterrey, Tamaulipas, and border industrial parks, requiring Mexico's highest density of accredited ISO/IEC 17025 calibration services.
Leading companies include SGS Société Générale de Surveillance SA, Bureau Veritas, Keysight Technologies, UL LLC, and others.
Mexico calibration services market is projected to reach approximately USD 93.28 Million by 2030, with electronics manufacturing and aerospace calibration segments growing fastest as nearshoring manufacturing investment and ISO/IEC 17025 compliance requirements accelerate.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade