Saudi Arabia Offshore Wind Energy Market Size, Share, Trends and Forecast by Component, Foundation Type, Capacity, Location, and Region, 2026-2034
Saudi Arabia Offshore Wind Energy Market Size, Share, Trends & Forecast (2026-2034)
The Saudi Arabia offshore wind energy market grew from USD 152.3 Million in 2025 to USD 170.3 Million in 2026 and is projected to reach USD 415.3 Million by 2034, growing at a CAGR of 11.79% during 2026-2034. The market is driven by Saudi Arabia Vision 2030 target of 16 GW of wind energy capacity by 2030, the massive NEOM green hydrogen project requiring 1,670 MW of wind power, and the Red Sea coastline's proven offshore wind resource. Fixed foundation leads at 72.4% by foundation type, capacity of greater than or equal to 5 MW dominates at 82.3% by capacity, and the Western region commands the largest regional share at 42.8% in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 152.3 Million |
|
Market Size (2026) |
USD 170.3 Million |
|
Forecast Market Size (2034) |
USD 415.3 Million |
|
CAGR (2026-2034) |
11.79% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Foundation Type |
Fixed Foundation (72.4%, 2025) |
|
Dominant Capacity |
Greater than or Equal to 5 MW (82.3%, 2025) |
|
Leading Region |
Western Region (42.8%, 2025) |
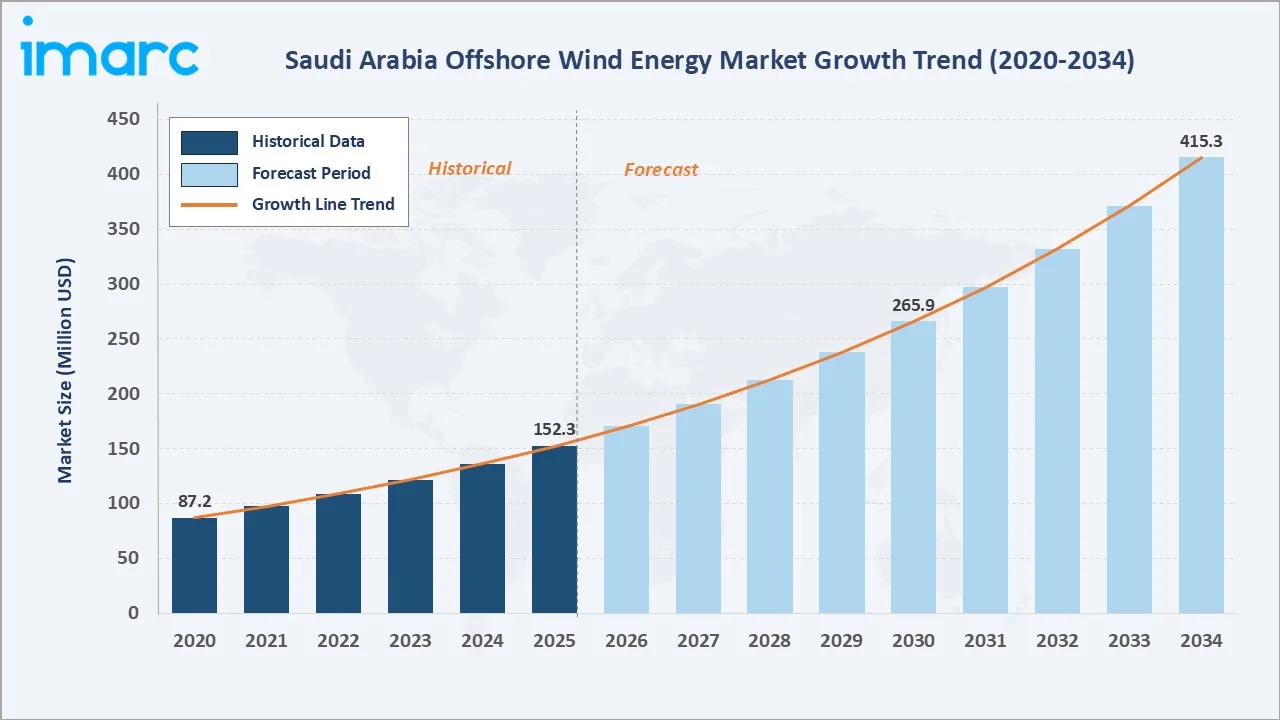
The Saudi Arabia offshore wind energy market grew from USD 87.2 Million in 2020 to USD 152.3 Million in 2025, and further to USD 170.3 Million in 2026, reflecting accelerating investment in offshore wind feasibility, resource assessment, and initial project development activities driven by the National Renewable Energy Program (NREP). The market is projected to reach USD 265.9 Million by 2030 before reaching USD 415.3 Million by 2034.
To get more information on this market, Request Sample
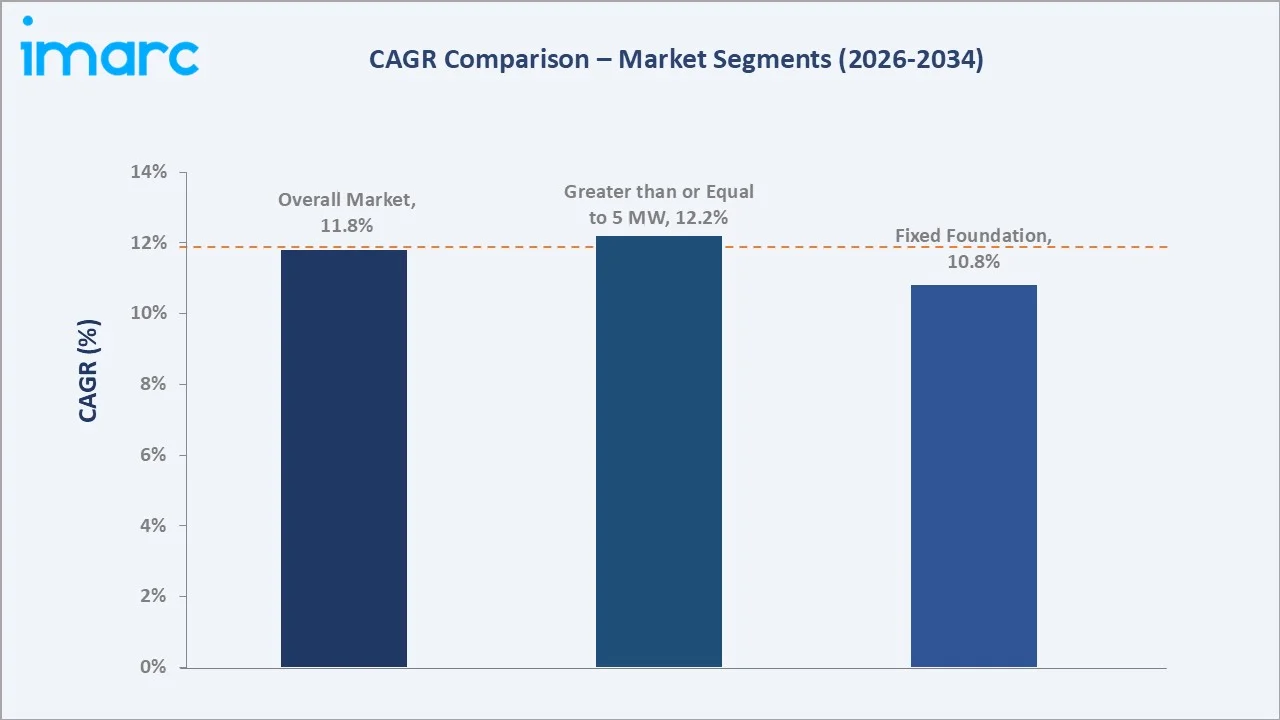
Fixed foundation offshore wind is growing at 10.8% CAGR as bottom-fixed monopile and jacket foundation structures serve the near-shore and shallow Red Sea areas with proven technology at competitive cost, validated by turbine installations in Gulf and Red Sea comparable conditions. The capacity segment of greater than or equal to 5 MW is at 12.2% CAGR as Saudi Arabia offshore wind tenders specifically target utility-scale projects requiring high-megawatt turbines that maximize energy output per installation for the NEOM green hydrogen and grid supply applications.
Executive Summary
The Saudi Arabia offshore wind energy market is in an accelerating transition from the feasibility and resource assessment phase that characterized 2020-2024 into active project development and initial construction activity that defines the 2025-2030 period. The convergence of three structural imperatives creates an unprecedented policy and technical foundation for offshore wind market development.
Fixed foundation at 72.4% leads by foundation type, serving the shallower Red Sea shelf areas where proven monopile and jacket foundation technology provides the lowest-cost offshore deployment solution appropriate for near-term commercial projects. Greater than or equal to 5 MW leads at 82.3% by capacity. The Western region at 42.8% leads all regions, reflecting its direct access to the Red Sea coastline, the proximity to NEOM on the northwest Red Sea coast generating the highest offshore wind project demand, and the Western region port infrastructure providing the marine logistics base for offshore wind installation vessel operations.
Key Market Insights
|
Insight |
Data |
|
Dominant Foundation Type |
Fixed Foundation - 72.4% share (2025) |
|
Dominant Capacity |
Greater than or Equal to 5 MW - 82.3% share (2025) |
|
Leading Region |
Western Region - 42.8% (2025) |
|
Key Market Opportunity |
Growing demand for floating offshore wind, offshore wind-to-green hydrogen integration, and utility-scale project development driven by the NREP pipeline and Vision 2030 renewable energy targets. |
Key Analytical Observations Supporting the Above Data:
- Fixed Foundation at 72.4%: Fixed foundation technology dominates because Red Sea nearshore areas offer water depths where monopile, jacket, and gravity-base foundations are technically and economically optimal for initial commercial offshore wind development.
- Greater than or Equal to 5 MW at 82.3%: The utility-scale turbine capacity class dominates because NEOM green hydrogen requirement for 1,670 MW of wind power, NREP offshore wind tenders targeting gigawatt-scale projects, and commercial interest in maximizing energy production per offshore installation position all favor high-megawatt turbines.
- Western Region at 42.8%: The Red Sea western coastline directly hosts Saudi Arabia highest offshore wind resources and is the geographic base for NEOM northwest coast wind project development, and the Red Sea Global coastal development programs whose offshore infrastructure requirements include marine-based renewable energy supply.
Saudi Arabia Offshore Wind Energy Market Overview
The Saudi Arabia offshore wind energy market encompasses all investment, engineering, procurement, installation, and operations activities associated with wind energy generation systems deployed in Saudi Arabia coastal and offshore marine environments, including the Red Sea western coastline, the Arabian Gulf eastern coastline, and the Gulf of Aqaba northern Red Sea extension. Key market activities span resource assessment and site survey, foundation and turbine design and manufacture, marine installation and commissioning, offshore grid connection, and operational maintenance over the 25-30 year asset life.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
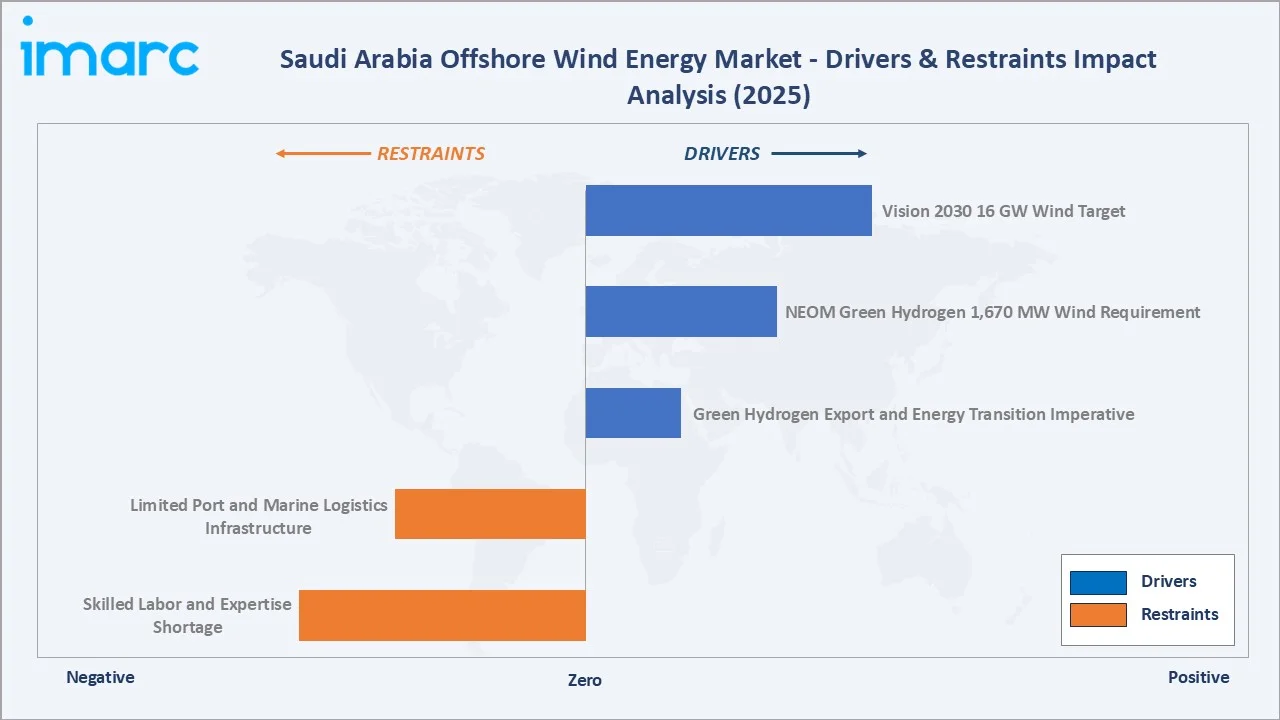
- Vision 2030 16 GW Wind Target: Saudi Arabia has committed to 16 GW of wind energy capacity by 2030, with offshore wind identified as a distinct high-CAGR component of this target as the kingdom moves beyond onshore wind to access Red Sea and Arabian Gulf offshore resources. The offshore category is specifically cited as having a higher CAGR within Saudi Arabia wind energy market, driven by technological advances in floating wind turbine foundations.
- NEOM Green Hydrogen 1,670 MW Wind Requirement: A 1,670 MW wind power project is currently being developed in NEOM, Saudi Arabia, further expanding the region’s renewable energy infrastructure, a project that represents the single largest offshore and nearshore wind demand source in Saudi Arabia history and the primary driver for developing Western Region offshore wind infrastructure.
- Green Hydrogen Export and Energy Transition Imperative: Saudi Arabia strategic interest in green hydrogen export as a post-oil economy revenue stream directly drives offshore wind demand, as electrolysis-based green hydrogen requires large volumes of low-cost zero-emission electricity that offshore wind can provide at scale proximate to Red Sea export terminals. Saudi Arabia net-zero greenhouse gas emissions by 2060 commitment create a long-term structural driver for offshore wind deployment as part of the kingdom's decarbonization trajectory.
Market Restraints
- Limited Port and Marine Logistics Infrastructure: Saudi Arabia offshore wind development faces significant logistical challenges associated with limited specialized port capacity for handling large offshore wind turbine components, including blades up to 100 meters and monopile foundations.
- Skilled Labor and Expertise Shortage: Saudi Arabia wind energy sector requires highly specialized skills in offshore marine engineering, subsea cable installation, turbine erection at sea, and offshore operations and maintenance that are not currently available domestically at the scale required for commercial offshore wind program delivery. The skilled labor needed for Saudi Arabia wind energy sector expansion is a recognized challenge, and offshore wind technical requirements exceed onshore wind complexity significantly.
Market Opportunities
- Localization of Offshore Wind Supply Chains: The development of offshore wind can create opportunities to localize turbine components, cables, foundations, vessels, and maintenance services. Local manufacturing can reduce logistics costs and strengthen supply-chain resilience. Saudi industrial development initiatives can encourage partnerships between global OEMs and domestic companies. This could support job creation and development of renewable-energy capabilities.
- Green Hydrogen Export Value Chain Integration: Offshore wind integration with green hydrogen production through proton exchange membrane electrolyzers positioned directly adjacent to offshore wind generation reduces transmission losses and creates an integrated offshore renewable energy-to-hydrogen value chain that positions Saudi Arabia as a cost-competitive green hydrogen exporter.
Market Challenges
- Harsh Marine and Environmental Conditions: High temperatures, salinity, humidity, and challenging marine conditions can increase equipment degradation and maintenance requirements. Offshore turbines and electrical infrastructure require specialized materials and protective technologies. Environmental and marine assessments can also add complexity to project development. These factors may increase lifecycle costs compared with projects in more favorable climates.
- Competition from Low-Cost Solar Energy: Saudi Arabia has strong solar resources and is rapidly developing large-scale solar power projects. Solar generation can offer highly competitive electricity costs due to abundant sunlight and declining technology costs. This creates pressure on offshore wind developers to demonstrate cost and reliability advantages. Offshore wind may therefore need to target specific applications where it complements solar generation.
Emerging Market Trends
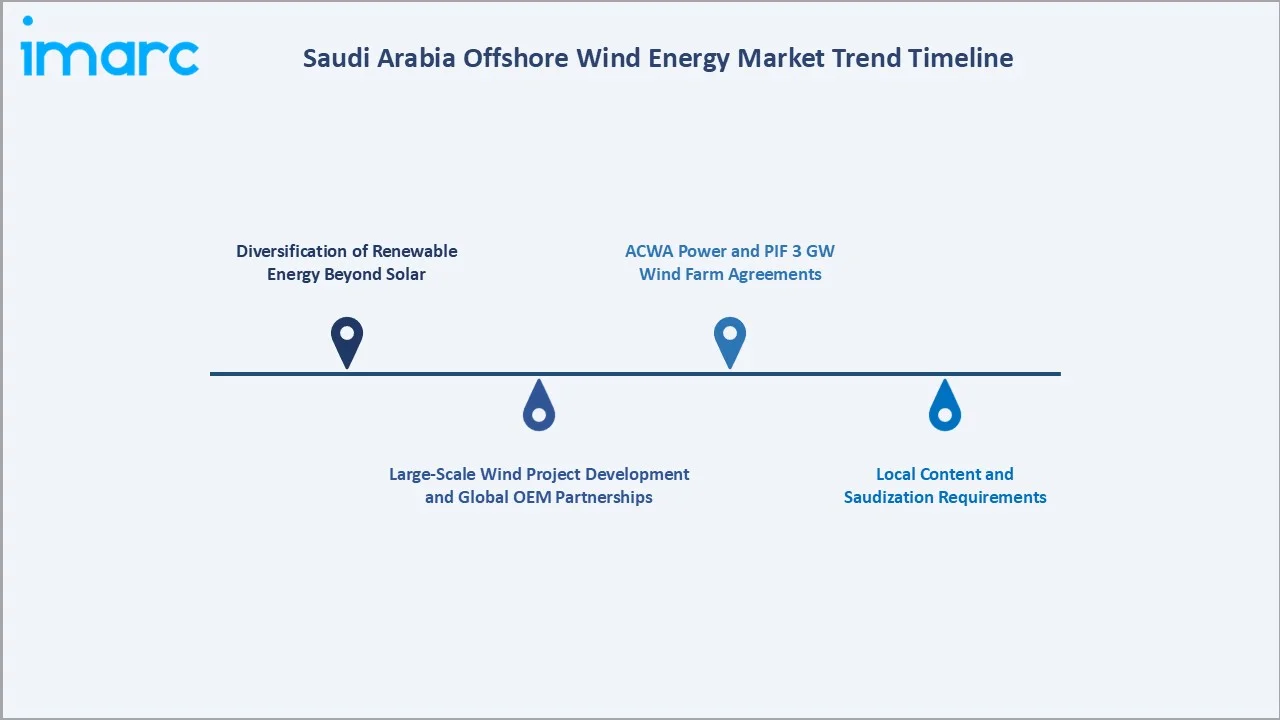
1. Diversification of Renewable Energy Beyond Solar
Saudi Arabia is significantly expanding its renewable energy ambitions, targeting 100–130 GW of solar PV capacity by 2030, up from the previous 58.7 GW goal. The National Renewable Energy Program (NREP) is driving this expansion, with PIF expected to develop 70% of renewable capacity. By mid-2025, 38.7 GW of PPAs had been signed, with 10.2 GW already connected to the grid and around 20 GW expected by the end of 2026. Large-scale renewable targets and growing electricity demand are encouraging exploration of complementary clean-energy sources. Offshore wind could support grid diversification, green hydrogen production, and large-scale industrial projects, particularly along Saudi Arabia’s extensive coastline.
2. Large-Scale Wind Project Development and Global OEM Partnerships
In June 2026, Goldwind shipped the first batch of equipment for Saudi Arabia’s 3 GW PIF5 wind project, marking the project’s transition toward installation. The project is being developed by ACWA Power, PIF, and Saudi Aramco, highlighting growing collaboration in Saudi Arabia’s large-scale wind energy sector. The project highlights Saudi Arabia’s move toward utility-scale wind energy projects as part of its renewable energy expansion. Partnerships with international turbine manufacturers such as Goldwind are supporting the deployment of advanced wind technology.
3. ACWA Power and PIF 3 GW Wind Farm Agreements
Saudi Arabia’s PIF and ACWA Power are developing two wind power projects with a combined capacity of 3 GW, consisting of 2 GW and 1 GW facilities. The projects are part of the 2025 round of the National Renewable Energy Program. These projects are being procured through direct negotiations as the designated national champion is expected to match tariffs from the latest publicly tendered schemes. This procurement structure positions ACWA Power as the dominant Saudi offshore wind developer for the forecast period, with offshore wind forming a growing share of its renewable portfolio alongside solar PV expansions.
4. Local Content and Saudization Requirements
Saudi Arabia's offshore wind program incorporates mandatory local content requirements as part of Vision 2030's economic diversification agenda, creating a trend toward joint ventures between international developers and Saudi industrial groups. This is driving feasibility assessments for the domestic manufacture of offshore wind components, technician training programmes at Saudi universities, and the development of port and logistics infrastructure tailored to offshore wind installation and O&M requirements.
Industry Value Chain Analysis
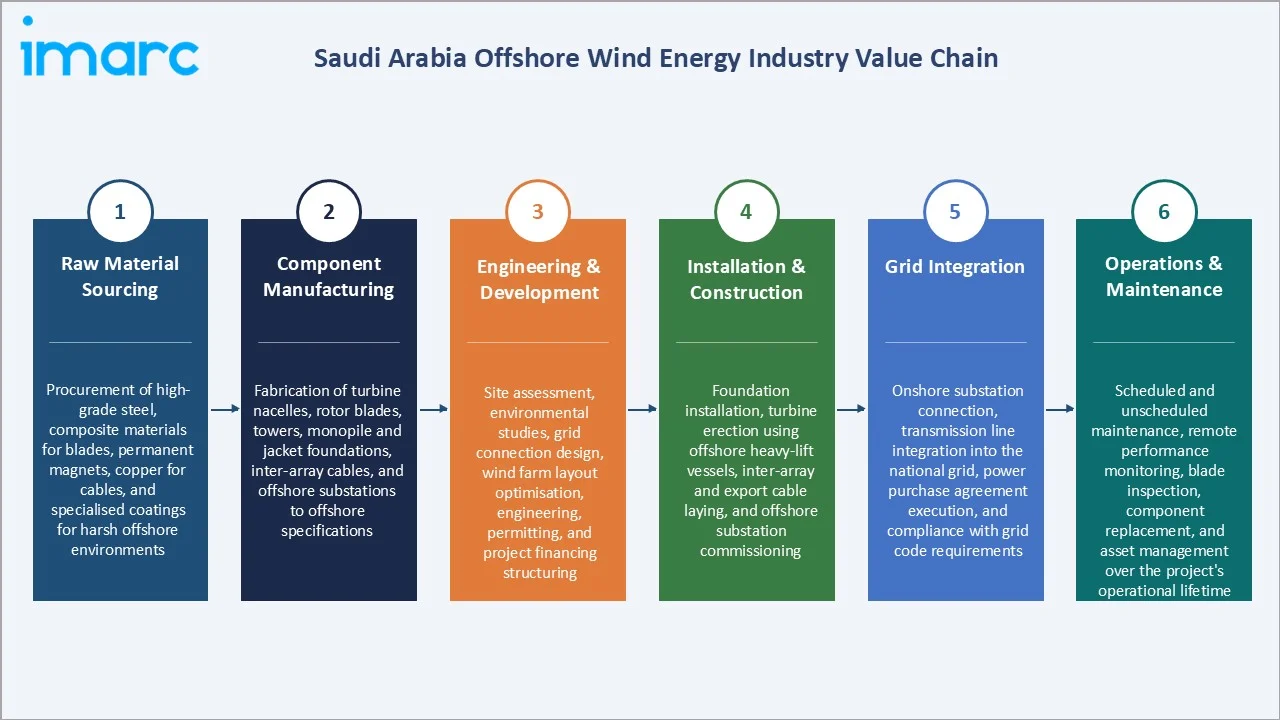
The Saudi Arabia offshore wind energy market value chain encompasses six stages from raw material sourcing through long-term operations and maintenance, with each stage representing distinct capability requirements and economic value.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Procurement of high-grade steel, composite materials for blades, permanent magnets, copper for cables, and specialised coatings for harsh offshore environments. |
|
Component Manufacturing |
Fabrication of turbine nacelles, rotor blades, towers, monopile and jacket foundations, inter-array cables, and offshore substations to offshore specifications. |
|
Engineering & Development |
Site assessment, environmental studies, grid connection design, wind farm layout optimisation, engineering, permitting, and project financing structuring. |
|
Installation & Construction |
Foundation installation, turbine erection using offshore heavy-lift vessels, inter-array and export cable laying, and offshore substation commissioning. |
|
Grid Integration |
Onshore substation connection, transmission line integration into the national grid, power purchase agreement execution, and compliance with grid code requirements. |
|
Operations & Maintenance |
Scheduled and unscheduled maintenance, remote performance monitoring, blade inspection, component replacement, and asset management over the project's operational lifetime. |
Engineering and development represent the highest-value differentiation stage, where specialised site assessment expertise, permitting knowledge, and project financing capability are the primary sources of competitive advantage over the project lifecycle.
Technology Landscape in the Saudi Arabia Offshore Wind Energy Industry
Fixed Foundation Offshore Wind Technology
Fixed foundation offshore wind technology, primarily monopile and jacket foundations, is designed for water depths up to approximately 60 meters, which covers significant portions of the Red Sea shallow shelf and near-coastal zones where Saudi Arabia initial offshore wind projects are being sited. The Red Sea marine environment presents specific design challenges, including high temperatures up to 35 degrees Celsius, high humidity, biofouling from warm water marine organisms, and seismicity considerations in portions of the Red Sea rift zone that require engineering adaptations from standard North Sea offshore wind designs.
Floating Offshore Wind Technology
Floating offshore wind uses turbines mounted on floating platforms, allowing deployment in deeper waters where fixed foundations are less practical. It expands the potential for offshore wind development by accessing stronger and more consistent wind resources farther offshore. The technology can reduce seabed constraints but currently involves higher costs and complex installation and maintenance requirements. Advances in floating platforms, mooring systems, and subsea cables are expected to improve its commercial viability.
High-Megawatt Turbine Technology for Utility-Scale Offshore Applications
High-capacity offshore turbines generate more electricity from each installation, improving the efficiency of large-scale wind projects. Larger rotor diameters and taller towers help capture stronger and more consistent offshore winds. These turbines can reduce the number of units, foundation requirements, and installation needs for a project. Advancements in turbine design and reliability are supporting the development of cost-effective utility-scale offshore wind farms.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
🔒 |
🔒 |
2025 |
|
Foundation Type |
Fixed Foundation |
72.4% |
2025 |
|
Capacity |
Greater than or Equal to 5 MW |
82.3% |
2025 |
|
Location |
🔒 |
🔒 |
2025 |
|
Region |
Western Region |
42.8% |
2025 |

By Foundation Type
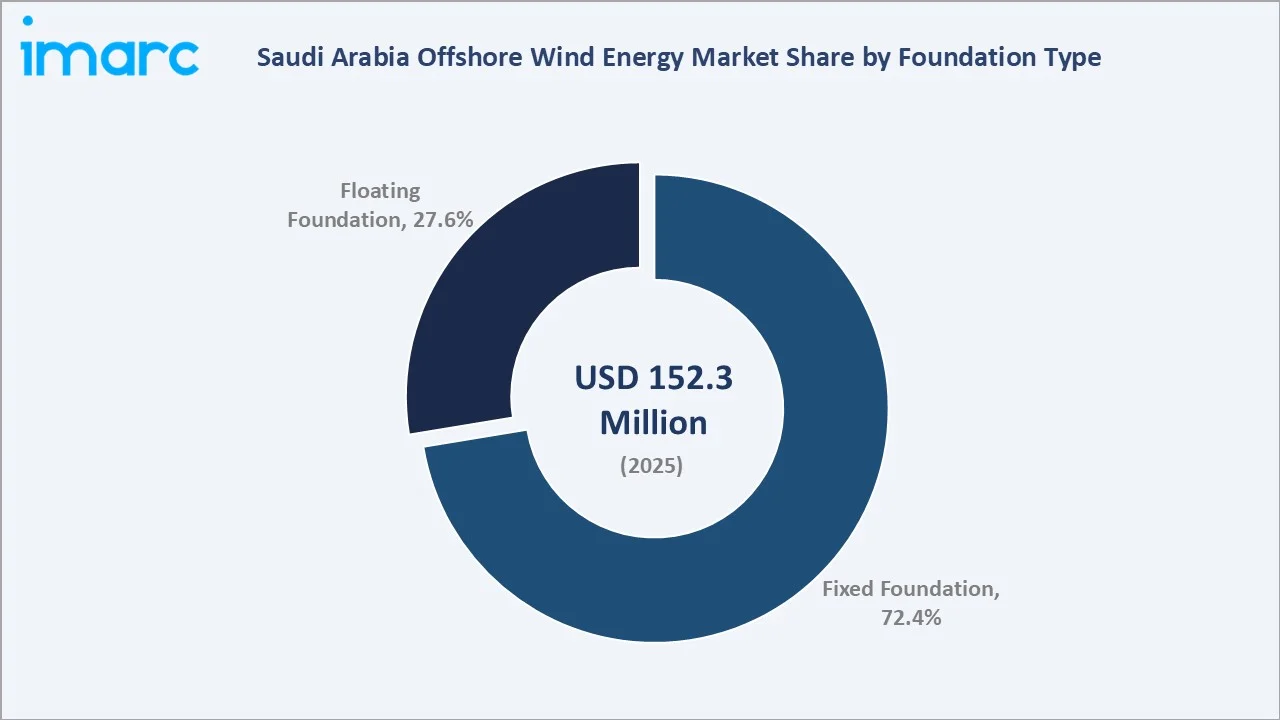
Fixed foundation leads at 72.4% in 2025, reflecting the technical and commercial maturity of monopile and jacket foundation systems for near-shore Red Sea applications and the early-stage status of floating foundation commercialization.
To access detailed market analysis, Request Sample
Floating foundation at 27.6% is the fastest-growing sub-segment and the strategic frontier of Saudi Arabia offshore wind market development.
By Capacity
Capacity greater than or equal to 5 MW leads at 82.3% in 2025, reflecting the commercial logic of deploying the largest available turbines for offshore applications where the high cost of marine foundations and installation motivates maximizing the energy output per structure.
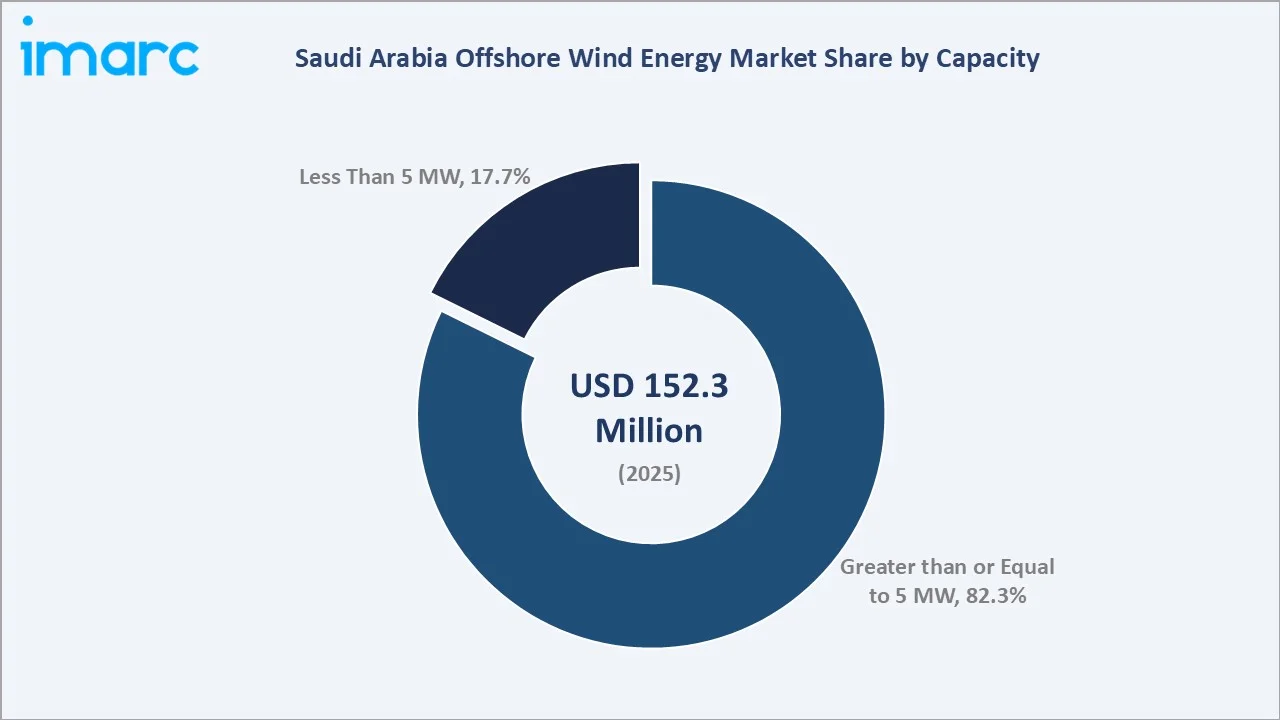
The less than 5 MW capacity at 17.7% serves demonstration, pilot, and research project applications where smaller turbines reduce initial capital exposure during the early market development phase and provide operational learning for O&M capability building.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Offshore Wind Energy Market Drivers & Characteristics |
|
Western Region |
42.8% |
Largest regional market, supported by extensive Red Sea coastline, renewable energy projects, and proximity to major industrial and development zones. |
|
Eastern Region |
28.6% |
Strong potential driven by coastal infrastructure, industrial activity, and growing demand for renewable power. |
|
Northern and Central Region |
19.7% |
Emerging demand supported by large-scale renewable initiatives, grid expansion, and energy-intensive development projects. |
|
Southern Region |
8.9% |
Smaller but developing market, with opportunities linked to coastal resources, infrastructure expansion, and renewable energy diversification. |
Saudi Arabia’s offshore wind market is led by the Western region, accounting for 42.8%, supported by its extensive Red Sea coastline and renewable energy development potential. The Eastern region represents 28.6%, benefiting from coastal infrastructure and strong industrial activity.
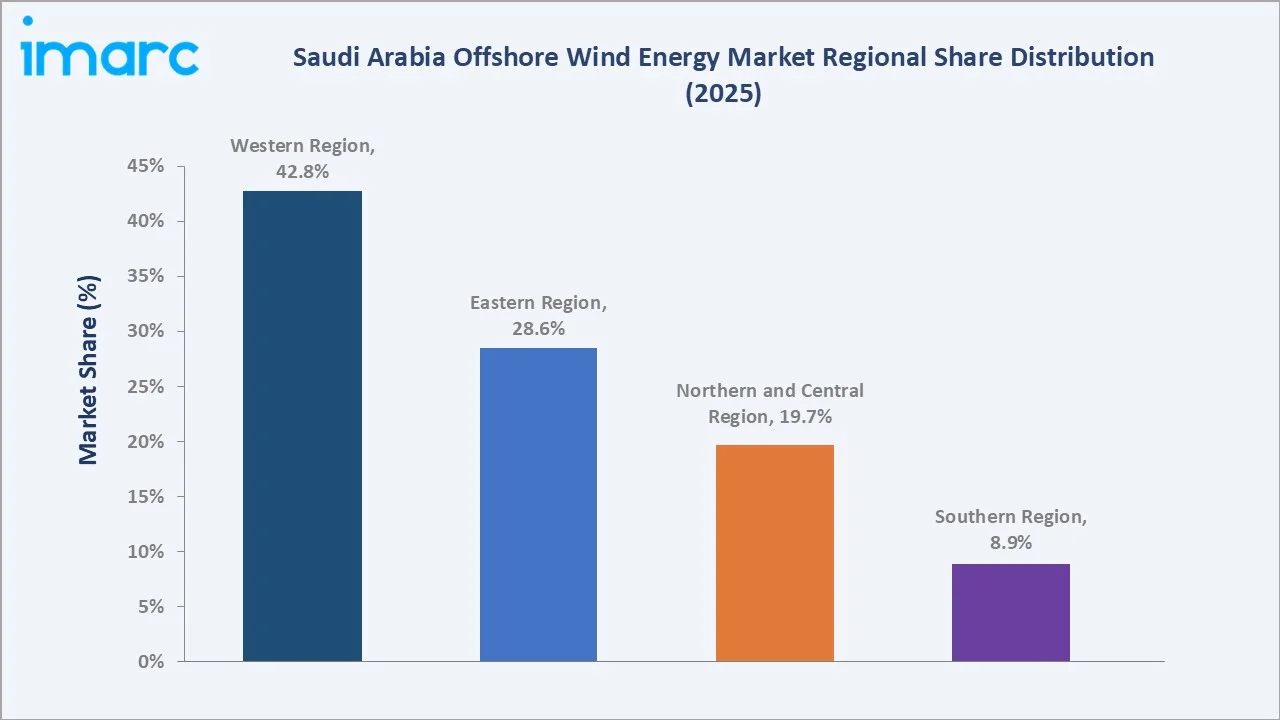
The Northern and Central region holds 19.7%, with opportunities driven by renewable energy investments and expanding grid infrastructure. The Southern region accounts for 8.9%, representing an emerging market with potential for future renewable energy projects.
Competitive Landscape
The Saudi Arabia offshore wind energy market features an emerging competitive structure dominated by international technology leaders and experienced offshore energy developers. Market entry barriers include offshore engineering expertise, balance-sheet capacity for large capital commitments, and the ability to navigate the procurement process.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Siemens AG | SG 14-222, SG 11-200, SG 14-236, SG 8.0-167 | Market Leader | Siemens AG (through its Siemens Gamesa) is a market leader in the offshore wind industry, having pioneered the sector by installing the world's first offshore wind farm. |
| Vestas | V236-15.0 MW | Established Player | Vestas plays a foundational and leading role in the offshore wind energy sector, acting as a primary technology designer, manufacturer, installer, and service provider. |
| General Electric Company | Haliade-X offshore turbine | Innovator | General Electric Company (operating through GE Vernova) plays a major role in the offshore wind market by manufacturing and supplying ultra-large capacity wind turbines. |
The competitive landscape is evolving as the Saudi Arabia offshore wind market transitions from resource assessment to active project development, anchoring the domestic champion developer tier and global OEMs providing turbine technology, while floating technology creates a distinctive competitive position for accessing the highest-resource deep Red Sea sites.
Key Company Profiles
Siemens AG
Siemens AG is a technology company with capabilities across electrification, automation, digitalization, and energy infrastructure. In Saudi Arabia’s renewable energy market, Siemens supports grid infrastructure, power systems, and digital energy solutions. Its technologies can enable the integration of variable renewable generation, including potential offshore wind projects. The company’s expertise in power transmission, grid management, and digital solutions supports Saudi Arabia’s broader clean-energy transition.
- Key Offerings: SG 14-222, SG 11-200, SG 14-236, SG 8.0-167.
- Strategic Focus: Enabling renewable energy integration through advanced grid infrastructure, power transmission, and digital energy solutions. The company aims to support Saudi Arabia’s offshore wind development by improving grid reliability, renewable power integration, and energy-system efficiency.
Vestas
Vestas is a leading wind energy company specializing in the design, manufacturing, installation, and servicing of wind turbines. Its portfolio includes technologies for utility-scale wind projects, supported by digital monitoring and long-term maintenance services. In Saudi Arabia, Vestas can support the Kingdom’s renewable energy expansion through wind turbine technology, project services, and operational expertise. The company’s capabilities in turbine performance and lifecycle management position it as a potential technology partner for large-scale wind developments.
- Key Offerings: V236-15.0 MW.
- Strategic Focus: Expanding its wind energy technology and project capabilities to support Saudi Arabia’s growing renewable energy ambitions. The company emphasizes high-efficiency turbines, digital monitoring, and lifecycle services to improve wind project performance and reliability.
Market Concentration Analysis
The Saudi Arabia offshore wind energy market is currently concentrated among a small number of active developers and technology providers in the pre-commercial development phase. Market concentration is expected to evolve significantly as issues formal offshore wind tenders and international offshore wind developers seek to qualify for Saudi Arabia offshore IPP procurement processes. The NREP procurement structure concentrates a significant share of offshore wind project ownership in a single domestic entity while opening turbine supply, EPC, and offshore installation to competitive international bidding. The floating offshore wind segment specifically is less concentrated and more open to innovative technology providers given the absence of an established incumbent, creating a competitive market structure.
Investment & Growth Opportunities
Highest Growth Segments
Floating offshore wind represents the highest absolute growth rate segment as Saudi Arabia offshore wind market matures from fixed to floating foundation technology through the 2028-2034 period, driven by the long-term resource imperative to access deeper Red Sea sites where the highest wind power densities have been confirmed.
Investment Themes
- Port Infrastructure for Offshore Wind Component Handling: Investment in Saudi Arabia Red Sea port upgrade for offshore wind turbine blade, nacelle, and monopile handling creates the marine logistics infrastructure prerequisite that is currently the binding constraint on Saudi Arabia offshore wind installation capacity.
- Green Hydrogen Integration with Offshore Wind: Investment in electrolysis capacity co-located with offshore wind generation creates the integrated offshore renewable energy-to-hydrogen value chain that positions Saudi Arabia as a cost-competitive green hydrogen exporter, with the NEOM joint venture demonstrating the commercial template for offshore wind-powered green hydrogen at scale.
Future Market Outlook (2026-2034)
The Saudi Arabia offshore wind energy market stood at USD 152.3 Million in 2025 and is projected to grow from USD 170.3 Million in 2026 to USD 415.3 Million by 2034, exhibiting a CAGR of 11.79% during the forecast period. The market is expected to reach an intermediate milestone of approximately USD 265.9 Million by 2030, as NEOM wind capacity begins construction, the offshore wind tender projects reach financial close, and floating offshore wind projects progress through development toward installation contract award in the 2028-2030 window.
Three structural forces will define Saudi Arabia offshore wind energy market through 2034. First, Saudi Arabia’s push to expand renewables beyond solar will create opportunities for offshore wind as a complementary clean-energy source. Second, Vision 2030, giga-projects, and rising electricity demand will support utility-scale renewable investments and related infrastructure. Third, advances in high-capacity and floating turbines, alongside local supply-chain development and global partnerships, will improve offshore wind deployment potential.
Research Methodology
Primary Research
Primary research comprised structured consultations with Ministry of Energy offshore wind policy officers, renewable energy development executives, international offshore wind turbine manufacturer representatives, marine installation contractor technical directors, offshore geotechnical survey companies active in Red Sea site characterization, and project finance advisors specializing in MENA renewable energy IPP transactions. These discussions validated market sizing, assessed project development pipeline status, identified key technical and logistical challenges for Saudi Arabia offshore wind, and provided competitive intelligence on developer positioning.
Secondary Research
Secondary research drew on IMARC Group Saudi Arabia offshore wind energy market database, Red Sea offshore wind power resource study, Saudi Arabia wind energy market analysis, Saudi Arabia wind logistics assessment, and company annual reports and press releases.
Forecasting Models
Market forecasts incorporated offshore wind project pipeline phasing aligned with tender schedule and financial close projections, NEOM green hydrogen wind capacity construction timeline, floating offshore wind project development schedule, floating foundation technology cost reduction trajectory through 2034, Saudi Arabia port and marine logistics infrastructure investment capacity, and global offshore wind LCOE reduction trajectory through 2034.
Saudi Arabia Offshore Wind Energy Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Turbine, Substructure, Electrical Infrastructure, Others |
| Foundation Types Covered | Fixed Foundation, Floating Foundation |
| Capacities Covered | Less Than 5 MW, Greater than or Equal to 5 MW |
| Locations Covered | Shallow Water, Transitional Water, Deep Water |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Siemens AG, Vestas, General Electric Company, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia offshore wind energy market from 2020-2034
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia offshore wind energy market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia offshore wind energy industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Offshore Wind Energy Market Report
The Saudi Arabia offshore wind energy market reached USD 170.3 Million in , driven by Vision 2030 NREP 16 GW wind target, NEOM 1,670 MW wind-to-green hydrogen project development, and a floating offshore wind farm MOU.
The market is projected to grow at a CAGR of 11.79% during 2026-2034, driven by wind farm agreements, NREP offshore wind project financial close activity, NEOM green hydrogen wind capacity construction, floating offshore wind project progression, and the resource-driven imperative to deploy offshore wind along the high-potential Saudi Red Sea coastline.
The market is projected to reach approximately USD 265.9 Million by 2030, as NEOM wind capacity begins construction and floating offshore wind projects progress toward installation contract award aligned with the Vision 2030 milestone delivery target.
Fixed foundation leads with a 72.4% share in 2025, reflecting the technical and commercial maturity of monopile and jacket foundation systems for Red Sea shelf applications and the early-stage status of the floating foundation in Saudi Arabia commercial development phase.
Greater than or equal to 5 MW leads with an 82.3% share in 2025, reflecting universal adoption of utility-scale turbines for Saudi Arabia offshore projects where NEOM 1,670 MW wind requirements and NREP commercial scale targets demand high-megawatt turbine platforms minimizing foundations required per gigawatt.
The Western region leads with a 42.8% share in 2025, reflecting direct Red Sea coastline access with high wind power densities, the NEOM northwest Red Sea coast 1,670 MW wind project, and floating offshore wind farm siting on the Red Sea.
Key players include Siemens AG, Vestas, and General Electric Company, among others.
The market is projected to reach USD 415.3 Million by 2034, driven by NREP offshore wind project construction and commissioning activity, floating offshore wind farm potential delivery, an expanded offshore wind portfolio, and a growing Saudi Arabia offshore wind operational fleet generating O&M service revenue.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade