UAE Artificial Intelligence Market Size, Share, Trends and Forecast by Type, Offering, Technology, System, End-Use Industry, and Region, 2026-2034
UAE Artificial Intelligence Market Size, Share, Trends & Forecast (2026-2034)
The UAE artificial intelligence market grew from USD 705.7 Million in 2025 to USD 859.8 Million in 2026 and is projected to reach USD 4,387.3 Million by 2034, growing at a CAGR of 21.84% during 2026-2034. The market is driven by the UAE National AI Strategy 2031, robust government investment, and rapid digital transformation across sectors. Software leads at 48.7%. Narrow/Weak AI dominates at 78.6%. Dubai commands 45.6% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 705.7 Million |
|
Market Size (2026) |
USD 859.8 Million |
|
Forecast Market Size (2034) |
USD 4,387.3 Million |
|
CAGR (2026-2034) |
21.84% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Offering |
Software (48.7%, 2025) |
|
Dominant Type |
Narrow/Weak Artificial Intelligence (78.6%, 2025) |
|
Leading Region |
Dubai (45.6%, 2025) |
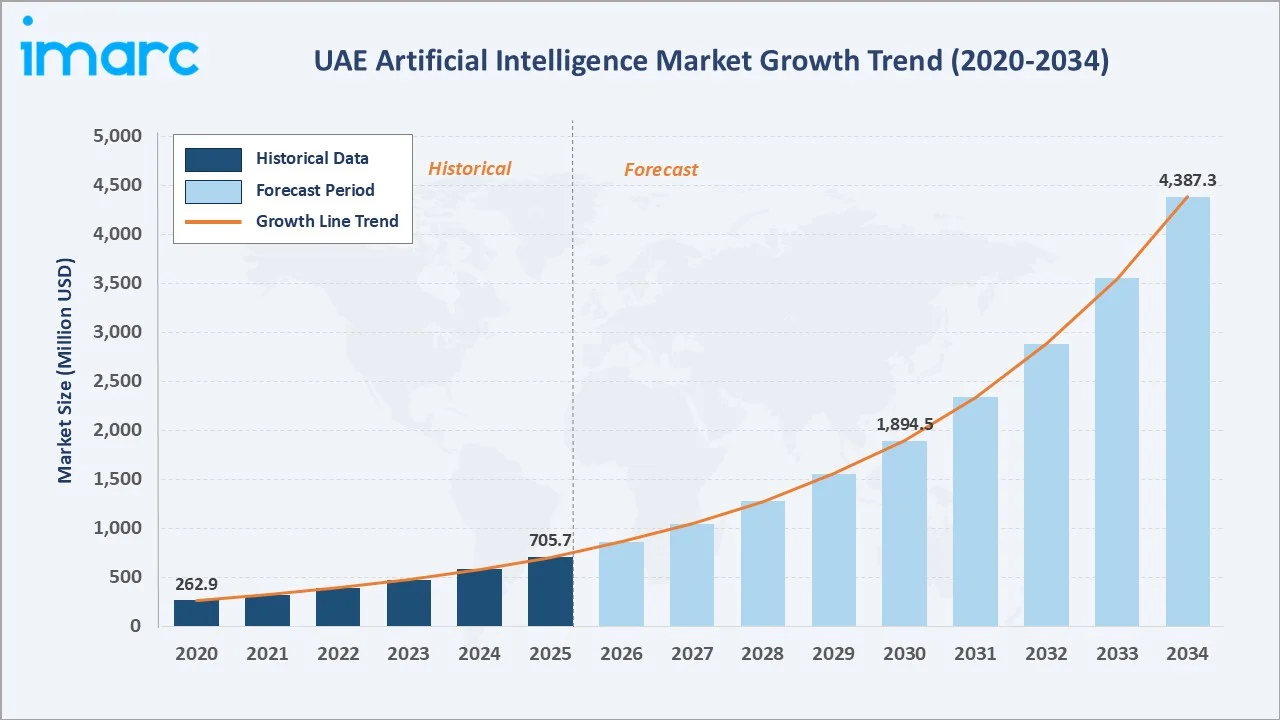
The UAE artificial intelligence market size increased from USD 262.9 Million in 2020 to USD 705.7 Million in 2025 and is estimated to reach USD 859.8 Million in 2026. The market is further expected to grow to USD 1,894.5 Million by 2030 and USD 4,387.3 Million by 2034.
To get more information on this market, Request Sample
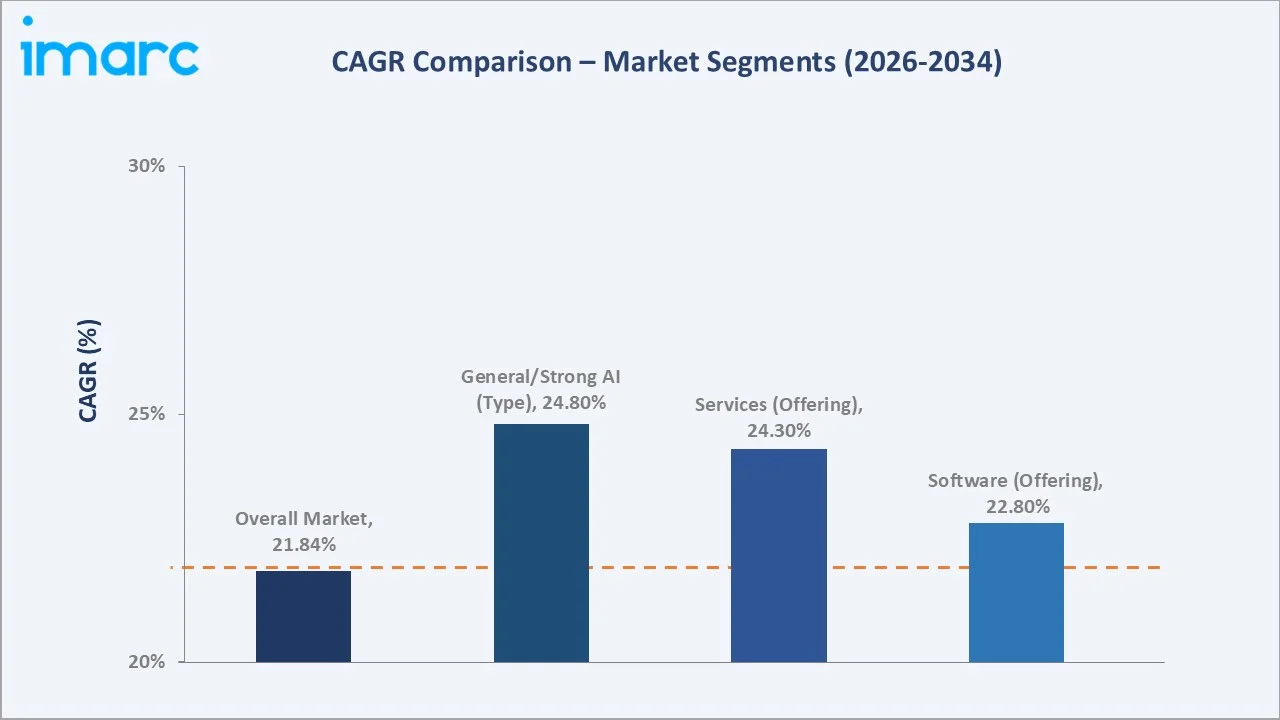
Services registers the fastest segment CAGR at approximately 24.3% through enterprise AI consulting and managed services expansion. General/Strong AI grows fastest by type at approximately 24.8% CAGR through UAE's sovereign AI research programs and next-generation model development.
Executive Summary
The UAE artificial intelligence market expanded from USD 705.7 Million in 2025 to an estimated USD 859.8 Million in 2026, establishing itself as the Middle East's most dynamic AI market. The market's scale is underpinned by the UAE National AI Strategy 2031, government-led digital transformation, and growing enterprise adoption across healthcare, finance, and oil and gas sectors.
The market is projected to reach USD 4,387.3 Million by 2034 at a CAGR of 21.84%. Software at 48.7% leads through enterprise AI platforms and cloud-native applications. Narrow/Weak AI at 78.6% reflects the current dominance of task-specific AI deployments. Dubai commands 45.6% as the market's leading emirate.
Key Market Insights
|
Insight |
Data |
|
Dominant Offering |
Software – 48.7% share (2025) |
|
Dominant Type |
Narrow/Weak Artificial Intelligence – 78.6% market share (2025) |
|
Leading Region |
Dubai – 45.6% share (2025) |
|
Market Opportunity |
AI-powered smart city infrastructure; Arabic language AI models; healthcare AI deployment; financial services automation |
Key Analytical Observations Supporting the Above Data:
- Software at 48.7%: Software dominates due to enterprise AI platform adoption, cloud-based machine learning services, and growing demand for sector-specific AI applications. Government digitalization programs are accelerating software procurement across healthcare, finance, and logistics sectors at scale.
- Narrow/Weak AI at 78.6%: Narrow AI dominates through task-specific deployments including fraud detection, predictive maintenance, image recognition, and NLP chatbots deployed at scale across UAE's financial services, healthcare, and government sectors, reflecting the commercially mature deployment base of purpose-built AI applications.
- Dubai at 45.6%: Dubai leads through its Smart Dubai initiative, UAE's highest concentration of multinational technology company regional headquarters, and the Dubai International Financial Centre's AI-focused fintech ecosystem supporting enterprise AI adoption at scale across regulated industries.
UAE Artificial Intelligence Market Overview
UAE artificial intelligence market is positioned at a strategic intersection of government ambition, sovereign capital deployment, and enterprise digital transformation. The market benefits from a dedicated AI governance infrastructure through the UAE AI Office, the world's first dedicated AI ministry, and large-scale sovereign investment in AI infrastructure through national entities.
UAE's geographic position bridging global AI innovation with MENA regional demand enhances its role as the region's primary AI hub. Macroeconomic factors including UAE's oil revenue-funded technology investment, diversification agenda, and population of highly educated technology professionals create structural AI demand conditions unmatched in comparable emerging markets.
Market Dynamics
To evaluate market opportunities, Request Sample
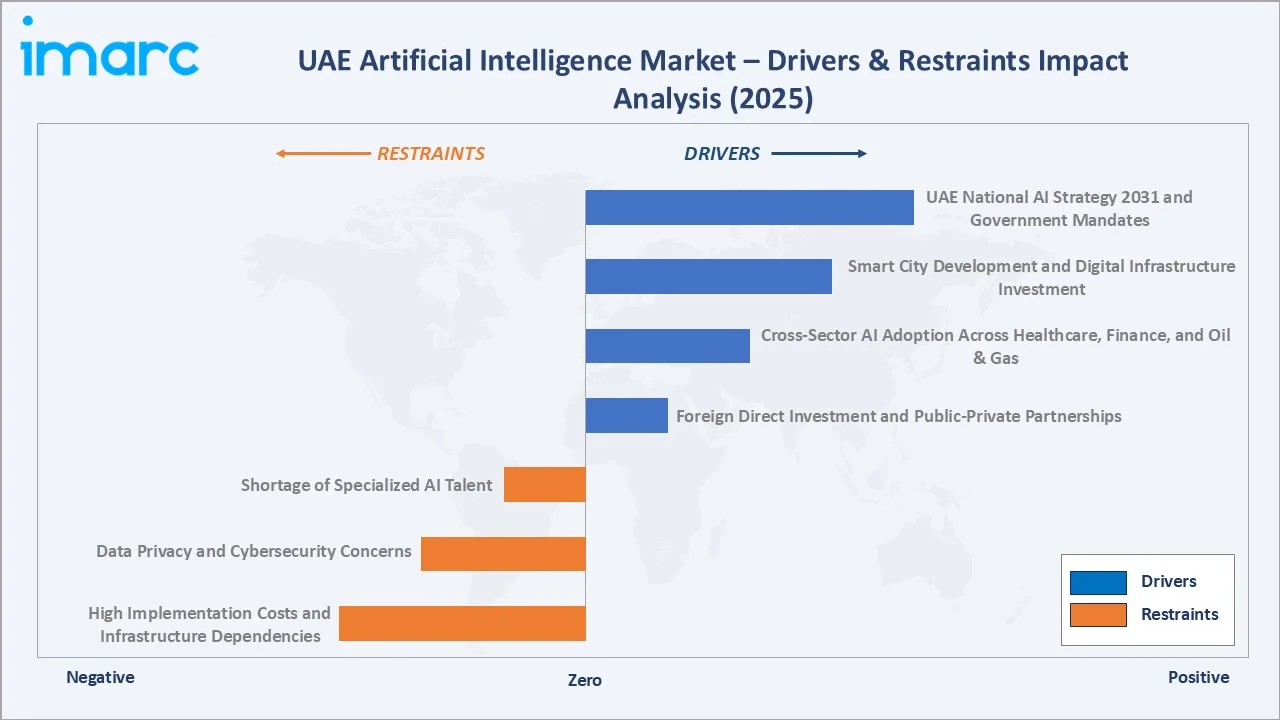
Market Drivers
- UAE National AI Strategy 2031 and Government Mandates: The UAE's National Artificial Intelligence Strategy 2031 provides a structured government mandate for AI integration across all public services and economic sectors, targeting positioning UAE among the world's top AI economies. The appointment of the world's first Minister of State for Artificial Intelligence and creation of the UAE AI Office provide institutional infrastructure that accelerates both public and private AI investment, creating market conditions unmatched in any comparable emerging economy. UAE's AI regulatory framework, designed to be innovation-enabling rather than restrictive, reduces compliance barriers and accelerates enterprise AI adoption timelines above comparable regulatory environments globally.
- Smart City Development and Digital Infrastructure Investment: Dubai's Smart Dubai initiative and Abu Dhabi's digital transformation programs create systemic AI adoption across urban infrastructure, transportation, utilities, and public services, establishing the physical and computational infrastructure required for large-scale AI deployment. These investments create a permanent demand floor for AI software, hardware, and services across the UAE, with recurring procurement cycles providing revenue predictability for AI vendors. The Abu Dhabi AI and Advanced Technology Council's dedicated innovation fund further creates structured demand for AI start-up and enterprise solutions across eleven critical economic sectors.
- Cross-Sector AI Adoption Across Healthcare, Finance, and Oil & Gas: Healthcare AI for diagnostic imaging, predictive analytics, and telemedicine; financial services AI for fraud detection, credit modeling, and investment automation; and oil and gas AI for predictive maintenance and reservoir modeling represent UAE's three largest sectoral AI demand centers.
- Foreign Direct Investment and Public-Private Partnerships: Large-scale international technology investment, the U.S.-UAE AI Acceleration Partnership enabling access to advanced AI chips annually, and major hyperscaler data center expansions represent a structural FDI inflow into UAE's AI ecosystem, accelerating technology transfer and local talent development. These partnerships create above-market enterprise AI deployment velocity through co-development programs and joint go-to-market agreements tailored for UAE's government and enterprise sectors. UAE-France and UAE-UK digital economy agreements further diversify foreign technology partnerships, reducing single-country dependency and broadening UAE's AI technology access across the global innovation ecosystem. Amazon Web Services' multi-year UAE infrastructure investment reinforces hyperscaler confidence in UAE as MENA's primary cloud and AI infrastructure destination through 2034.
Market Restraints
- Shortage of Specialized AI Talent: The UAE faces a structural shortage of specialized AI talent including machine learning engineers, data scientists, and AI research professionals, limiting deployment velocity and raising costs for enterprise AI programs. Heavy reliance on expatriate AI professionals introduces workforce continuity risk in a competitive regional talent market with attractive competing destinations offering comparable compensation packages. While dedicated AI university programs address the talent gap over the medium term, creating persistent workforce dependency on international professionals with above-market salary expectations.
- Data Privacy and Cybersecurity Concerns: Evolving data governance frameworks across individual Emirates create regulatory fragmentation, complicating enterprise AI deployments requiring cross-emirate data flows and restricting training data availability for AI model development in regulated sectors. Cybersecurity concerns around AI system vulnerabilities increase compliance costs and slow enterprise AI adoption cycles in regulated industries including financial services and healthcare. The absence of a unified federal personal data protection law creates compliance uncertainty for AI companies operating across multiple Emirates, increasing legal overhead and slowing data-intensive AI deployment programs significantly. Cross-border data transfer restrictions further limit enterprise AI implementation options for organizations subject to UAE Central Bank or healthcare ministry data residency requirements.
- High Implementation Costs and Infrastructure Dependencies: Enterprise AI implementation requires substantial investment in cloud infrastructure, GPU computing, and system integration that exceeds budget thresholds for mid-sized UAE businesses, creating a structural dependency on large government and enterprise clients. Dependence on advanced AI chip supply chains creates supply vulnerability that can affect procurement timelines and technology selection for UAE government and enterprise AI programs. Energy and cooling demands for large AI data centers add operational cost complexity for infrastructure providers, with GPU infrastructure costs creating a financial barrier limiting AI market penetration to the top tier of UAE businesses by revenue scale.
Market Opportunities
- Arabic Language AI and Regional Market Expansion: Arabic language AI model development represents a commercially underserved opportunity across MENA's 400 million Arabic speakers, with major global providers delivering accuracy rates 35-40% below English-language performance benchmarks. The commercialization potential extends to government AI, enterprise NLP, media automation, and consumer-facing applications across Saudi Arabia, Egypt, and the broader Arabic-speaking world. UAE's sovereign Arabic AI capability creates durable competitive barriers that global AI providers cannot replicate without equivalent UAE-specific institutional investment commitments.
- Healthcare AI Commercialization: UAE's advanced healthcare infrastructure, AI-integrated hospital networks, and government-funded healthcare AI programs create commercialization opportunities for AI diagnostic tools, precision medicine platforms, and telehealth AI systems across both public and private healthcare networks.
Market Challenges
- Rapid Technological Evolution and Model Obsolescence: The fast pace of AI model development creates continuous upgrade requirements for enterprise AI deployments, increasing total cost of ownership and compressing the ROI realization window for organizations with multi-year AI investment business cases. Organizations must balance continuous AI investment with ROI expectations in a technology environment where current-generation models are superseded within 18–24 months, challenging IT procurement frameworks designed for longer asset lifecycles. Continuous upgrade cycles create pressure on enterprise IT budgets, potentially delaying AI adoption among cost-sensitive organizations operating outside UAE's largest enterprise and government segments.
- Geopolitical and Export Control Risks: UAE's dependence on advanced AI hardware and cloud infrastructure from specific geographies exposes its AI market to geopolitical risk, with export control frameworks and bilateral AI access agreements introducing regulatory uncertainty that can affect procurement timelines. Policy continuity for chip access agreements beyond their initial terms creates strategic planning uncertainty for long-cycle UAE AI infrastructure investments requiring reliable component supply over multi-year program horizons. UAE AI market participants must continuously monitor geopolitical developments affecting AI technology access to mitigate procurement disruption risk across large-scale government and enterprise AI infrastructure programs.
Emerging Market Trends
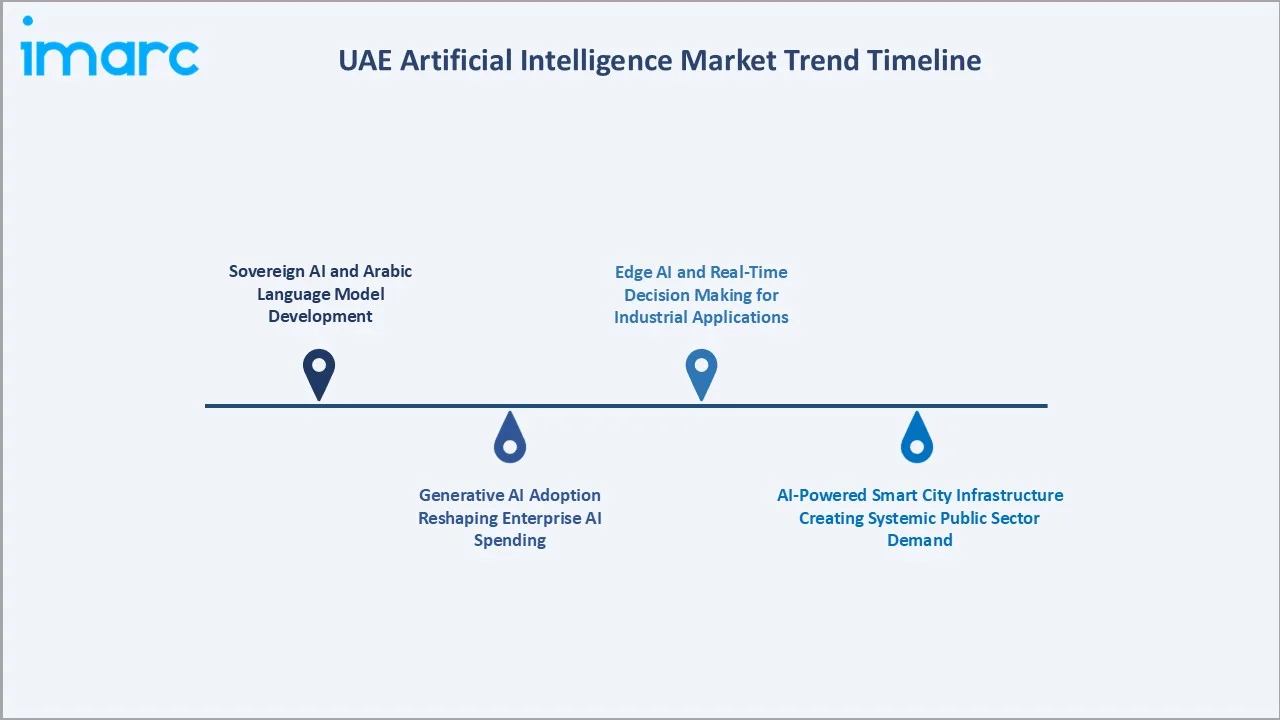
1. Sovereign AI and Arabic Language Model Development
Sovereign AI model development represents UAE's transition from AI consumer to AI developer. National AI champions and dedicated research institutions position UAE as MENA's premier AI model developer, creating commercial opportunities beyond UAE borders through Arabic language AI as the standard for a speaker language market that remains commercially underserved by global AI providers.
2. Generative AI Adoption Reshaping Enterprise AI Spending
Generative AI adoption is shifting enterprise investment from narrow task-specific tools toward foundation model-based applications across content, code, and customer service automation. Enterprise generative AI solutions targeting UAE's financial services, government, and healthcare sectors are driving above-market AI software spending growth as organizations replace traditional software tools with AI-native alternatives.
3. AI-Powered Smart City Infrastructure Creating Systemic Public Sector Demand
Smart city AI deployment in Dubai and Abu Dhabi is creating UAE's largest and most stable AI demand stream through traffic management, utility optimization, public safety, and government service automation representing large-scale, multi-year procurement programs with recurring revenue characteristics for AI platform and services vendors.
4. Edge AI and Real-Time Decision Making for Industrial Applications
Edge AI deployment for industrial IoT, smart manufacturing, and autonomous systems is emerging as UAE's highest-growth AI technology segment, enabling real-time decision-making without cloud latency for industrial automation, autonomous vehicles, and smart grid management. This trend creates new demand for AI hardware optimized for edge deployment and real-time inference across UAE's expanding industrial and clean energy sector.
Industry Value Chain Analysis
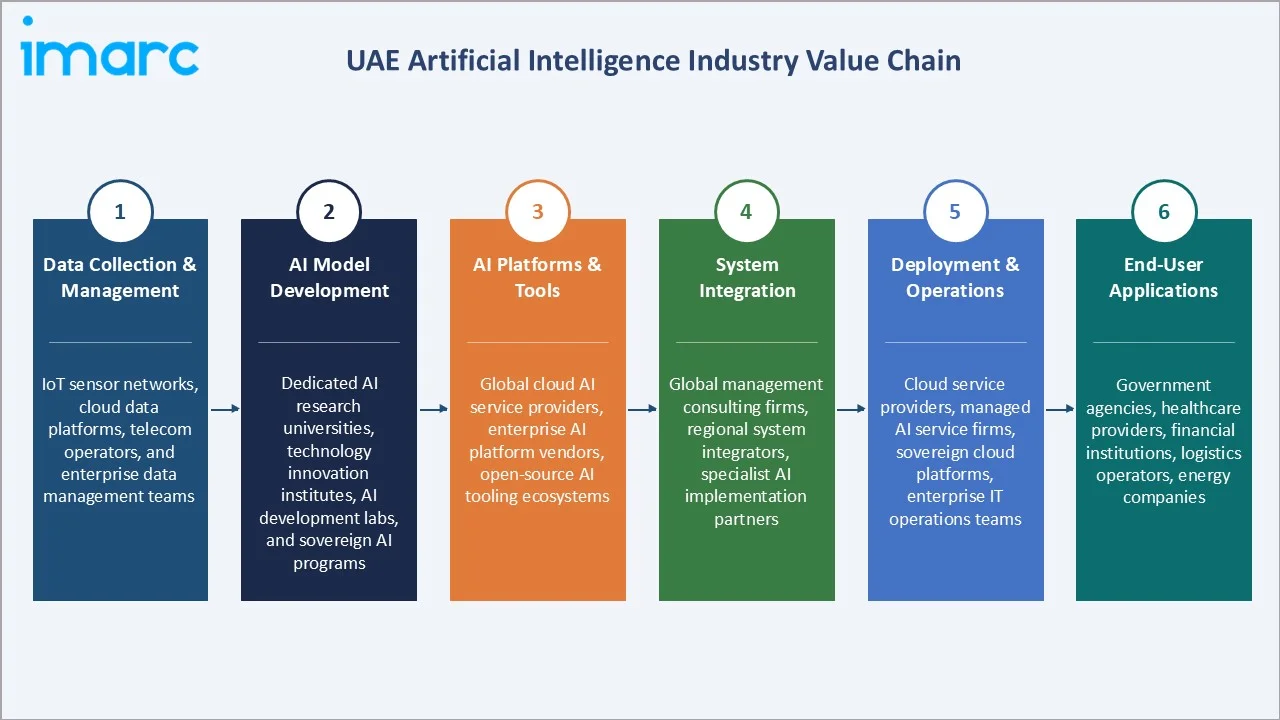
UAE AI value chain reflects the country's position as a technology integrator and increasingly as an AI developer. The value chain spans AI research collaboration, infrastructure investment, model development, enterprise platform deployment, sector-specific customization, and end-use application across government, healthcare, finance, and logistics sectors.
|
Stage |
Key Participants |
| Data Collection & Management | IoT sensor networks, cloud data platforms, telecom operators, enterprise data management teams |
| AI Model Development | Dedicated AI research universities, technology innovation institutes, AI development labs, sovereign AI programs |
| AI Platforms & Tools | Global cloud AI service providers, enterprise AI platform vendors, open-source AI tooling ecosystems |
| System Integration | Global management consulting firms, regional system integrators, specialist AI implementation partners |
| Deployment & Operations | Cloud service providers, managed AI service firms, sovereign cloud platforms, enterprise IT operations teams |
| End-User Applications | Government agencies, healthcare providers, financial institutions, logistics operators, energy companies |
The system integration stage is UAE AI value chain's most commercially intensive stage, where technology providers compete for large-scale government and enterprise AI implementation contracts.
Technology Landscape in the UAE Artificial Intelligence Industry
Machine Learning and Deep Learning
Machine learning and deep learning provide the computational foundation for UAE's dominant AI applications including predictive analytics, recommendation systems, and automated decision-making. ML models deployed across UAE's financial services for fraud detection and healthcare sector for diagnostic support represent the largest technology-by-deployment base, through proven commercial ROI across multiple sectors at scale.
Natural Language Processing and Arabic Language AI
NLP and Arabic language AI development are transforming enterprise and government service delivery in UAE. Sovereign language AI capabilities for Arabic document processing, customer service automation, and government service delivery are developed through dedicated UAE AI research programs and joint development with global technology partners.
Computer Vision and Edge AI
Computer vision and edge AI enable UAE's smart city applications including traffic monitoring, retail analytics, facility security, and industrial inspection across urban infrastructure. Investment in AI-enabled surveillance, autonomous vehicle infrastructure, and smart grid monitoring creates sustained demand for computer vision solutions that enable real-time processing critical for industrial and infrastructure applications.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Offering |
Software |
48.7% |
2025 |
| Type | Narrow/Weak Artificial Intelligence |
78.6% |
2025 |
| Technology | 🔒 | 🔒 | 2025 |
| System | 🔒 | 🔒 | 2025 |
| End-Use Industry | 🔒 | 🔒 | 2025 |
|
Region |
Dubai |
45.6% |
2025 |

By Offering
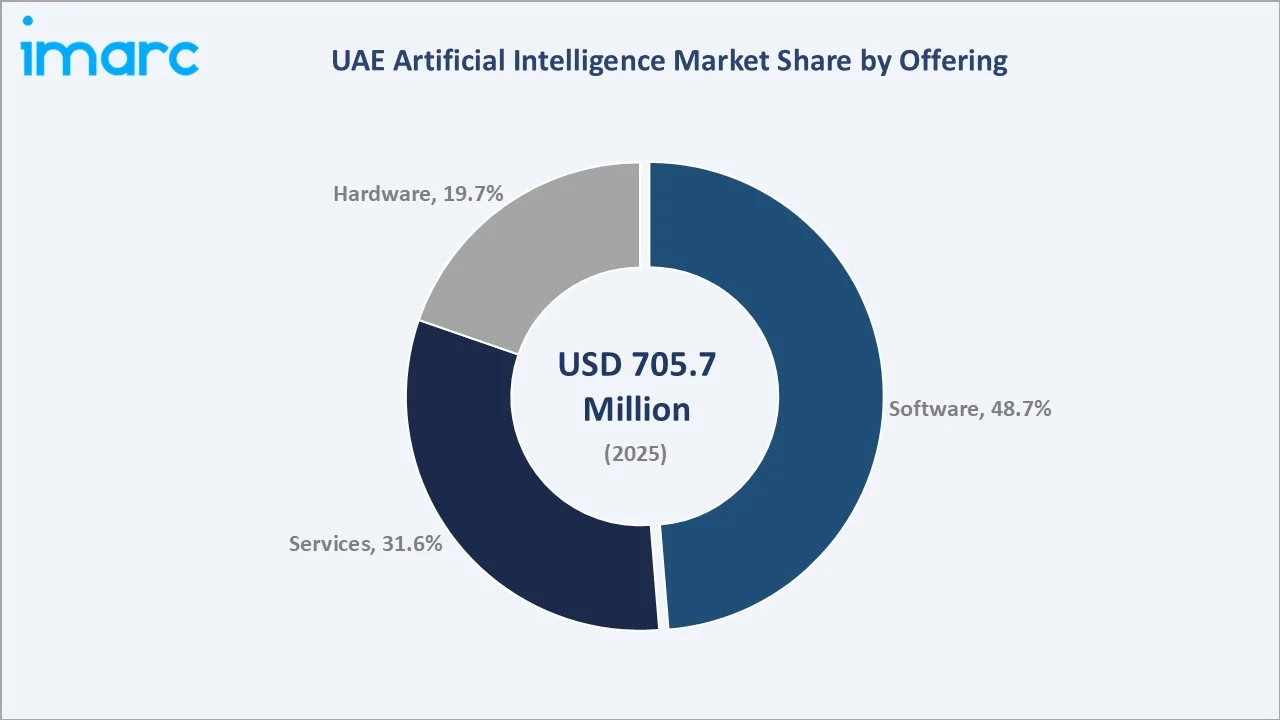
Software leads at 48.7% (2025). The software segment encompasses enterprise AI platforms, machine learning frameworks, AI-as-a-Service applications, and sector-specific AI software. UAE's strong cloud infrastructure, enterprise platform adoption, and sovereign cloud programs drive software dominance.
To access detailed market analysis, Request Sample
Services at 31.6% grows fastest at approximately 24.3% CAGR through enterprise AI consulting, implementation, and managed AI services expansion driven by large-scale digital transformation programs. Hardware at 19.7% reflects data center GPU infrastructure, edge AI devices, and specialized AI chip procurement growing in line with UAE's AI infrastructure build-out programs.
By Type
Narrow/Weak Artificial Intelligence leads at 78.6% (2025). This segment encompasses task-specific AI applications across fraud detection, predictive maintenance, image recognition, NLP chatbots, and recommendation engines currently deployed at scale across UAE's financial services, healthcare, and government sectors.
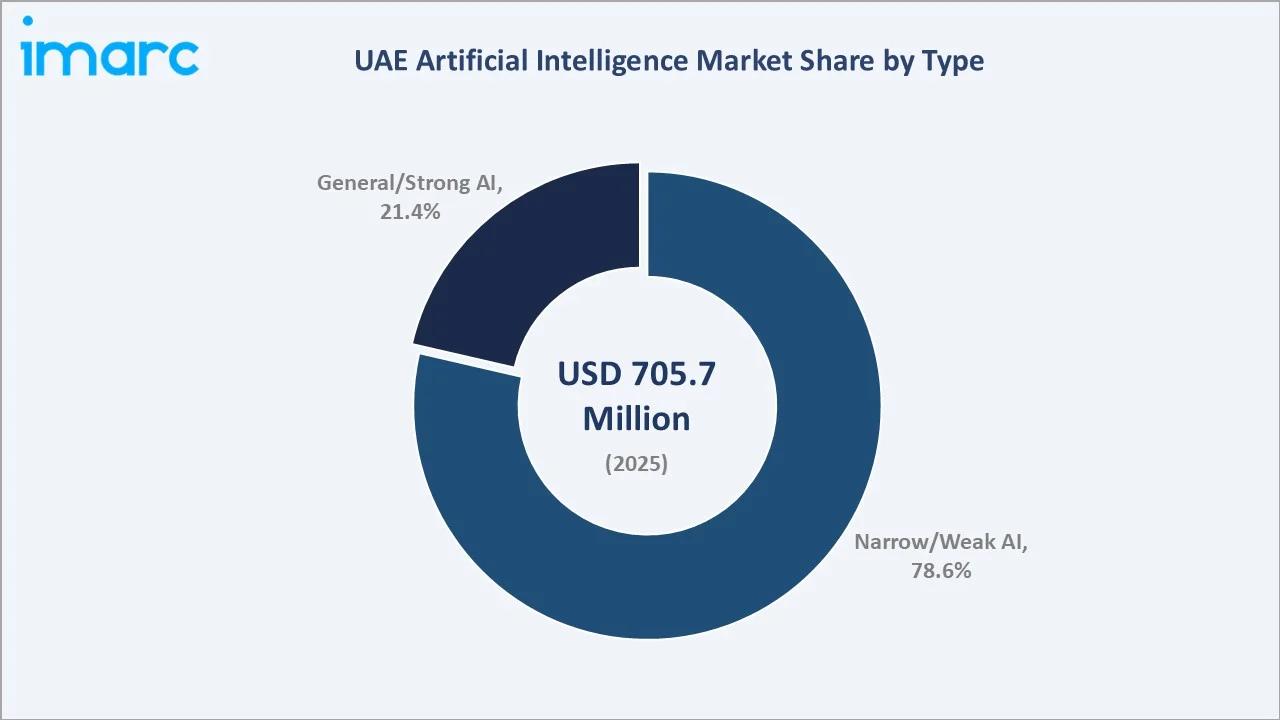
General/Strong Artificial Intelligence at 21.4% is growing fastest at approximately 24.8% CAGR through UAE's sovereign AI research programs, advanced AI research initiatives, and technology investor interest in next-generation AI capabilities.
Regional Market Insights
|
Region |
Share (2025) |
Key UAE AI Market Drivers & Characteristics |
| Dubai |
45.6% |
Advanced digital infrastructure, high enterprise and technology company density, developed fintech and smart city AI ecosystem. |
| Abu Dhabi |
37.8% |
Sovereign AI capital concentration, leading AI research institutions, large-scale industrial and energy sector AI deployment. |
| Sharjah |
11.9% |
Growing academic AI research ecosystem, expanding technology parks, increasing SME technology adoption and digital transformation programs. |
| Others |
9.9% |
Rising food processing investment in Jizan Economic City, agricultural processing machinery for Asir region fruit and vegetable production, and Vision 2030 southern economic development programs |
Dubai's 45.6% market leadership reflects its Smart Dubai initiative, UAE's highest concentration of technology company regional headquarters, and the fintech AI ecosystem supporting enterprise AI adoption at scale across regulated industries. Abu Dhabi's 37.8% reflects sovereign AI capital concentration and large-scale industrial AI deployment programs.
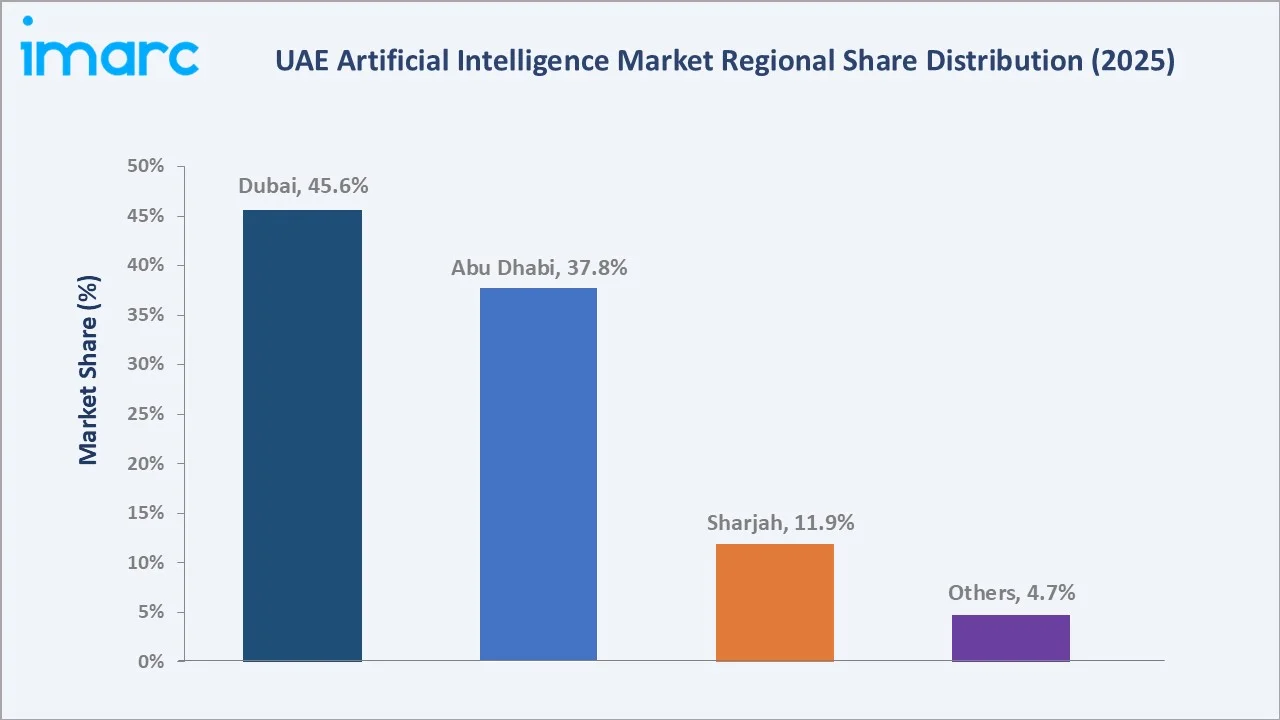
Sharjah's 11.9% reflects a growing academic research-to-commercialization pipeline, while Others at 4.7% represents emerging industrial AI adoption as UAE's digital infrastructure investment reaches secondary economic centers.
Competitive Landscape
UAE artificial intelligence market competitive landscape is defined by the interplay between global technology giants, UAE's sovereign AI champion, and specialized regional providers. The market features a dual competitive structure where global cloud providers compete on platform scale while sovereign AI platforms leverage government access and Arabic language AI specialization.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Microsoft | Azure AI, Copilot, OpenAI Partnership, Azure ML | Market Leader | Microsoft leverages sovereign AI partnerships and Azure AI cloud infrastructure to lead UAE's enterprise AI software and cloud AI market. |
| IBM Corporation | IBM Watson AI, IBM Cloud, Granite Foundation Models | Strong Challenger | IBM Corporation focuses on enterprise AI integration services and hybrid cloud AI for UAE's regulated industries. |
| Oracle | Oracle AI, OCI AI Services, Oracle Cloud | Innovator | Oracle integrated AI within enterprise cloud applications drives adoption across UAE's government and large enterprise deployments. |
| Accenture | AI & Data Services, Gen AI Studios, Intelligent Operations | Strong Challenger | Accenture drives AI market growth through large-scale enterprise AI transformation programs for UAE government and financial services clients. |
Key players include Microsoft, IBM Corporation, Oracle, Accenture, and others.
Key Company Profiles
Microsoft
Microsoft is a leading global technology company and the UAE artificial intelligence market's largest enterprise AI platform provider, operating through its Azure AI cloud infrastructure and strategic sovereign AI partnerships in the UAE and MENA region.
- Key Brands: Azure AI, Microsoft Copilot, Azure Machine Learning, Power BI AI, OpenAI Partnership.
- Strategic Focus: Expanding Azure AI and Copilot adoption across UAE's government, financial services, and healthcare sectors through sovereign AI co-development and regional channel partnerships. Building UAE's largest enterprise generative AI deployment base through Azure AI Services integration with UAE government digital transformation programs and sovereign AI platforms. Microsoft targets positioning Azure as UAE's primary cloud AI infrastructure through multi-year government contracts, creating competitive barriers above independent global cloud AI providers in the UAE enterprise and public sector market.
IBM Corporation
IBM Corporation is a global technology and consulting company with a strong UAE market presence through enterprise AI, hybrid cloud solutions, and AI integration services for regulated industries requiring data privacy compliance and governance.
- Key Brands: IBM Watson AI, IBM Cloud, IBM Consulting AI Services, IBM Granite Foundation Models.
- Strategic Focus: Delivering AI-powered automation and hybrid cloud AI solutions to UAE's financial services institutions, government agencies, and large enterprises requiring data privacy compliance and regulatory alignment across multi-emirate deployments. IBM's UAE AI Center of Excellence focuses on Arabic language NLP, financial services AI governance, and government digital transformation, creating a differentiated consulting capability above generalist technology providers in UAE's compliance-intensive regulated sectors.
Market Concentration Analysis
UAE artificial intelligence market is moderately concentrated, with the top two enterprise AI platform providers collectively commanding an estimated 35–40% of the organized enterprise AI market by value, creating a dual-leadership structure where global platform scale competes with sovereign AI specialization.
Government sector AI procurement is most concentrated, with sovereign AI platforms holding a structurally advantaged position through sovereign investor relationships and Arabic language AI capabilities that global providers cannot replicate without equivalent UAE-specific investment. Market concentration is evolving through two forces: global cloud AI consolidating enterprise share while UAE's government encourages multi-vendor sourcing for strategic risk management, moderating concentration above the dual-leader level.
Investment & Growth Opportunities
Highest Growth Segments
General/Strong AI (~24.8% CAGR through UAE research investment), services (~24.3% CAGR through enterprise digital transformation), hardware (~19.6% CAGR from industrial and smart city applications), and software (~22.8%+ CAGR from MENA market expansion), represent UAE's highest-growth AI investment vectors through 2034.
Emerging Investment Opportunities
UAE’s Arabic language AI market represents the highest-value regional AI investment opportunity. The Arabic NLP and language model market remains commercially underserved relative to English-language AI, creating first-mover advantage for UAE-developed and UAE-hosted Arabic AI platforms extending across Arabic speakers.
Investment Themes
- Sovereign AI infrastructure development: UAE's AI data center investment, with large-scale planned AI infrastructure campuses positioning UAE as MENA's primary AI compute hub, creating sustained infrastructure demand and co-location services revenue for AI infrastructure investors through 2034.
- Arabic language AI commercialization across MENA: UAE-developed Arabic large language models deployed across Saudi Arabia, Egypt, and other Arabic-speaking markets represent the most commercially scalable AI revenue expansion opportunity for UAE-based AI companies beyond domestic market boundaries, creating a sustainable first-mover advantage in MENA's commercially underserved Arabic AI market.
Future Market Outlook (2026-2034)
The UAE artificial intelligence market is projected to grow from USD 705.7 Million in 2025 to USD 859.8 Million in 2026, reaching USD 4,387.3 Million by 2034, registering a CAGR of 21.84% during 2026-2034. The market's anchor value of USD 1,894.5 Million in 2030 represents UAE AI industry reaching a scale inflection where domestic AI model development generates measurable economic return above the base of enterprise and government AI platform adoption.
The AI services segment is becoming UAE's primary AI revenue growth driver as enterprise digital transformation programs mature and sovereign AI platforms attract regional enterprise adoption across MENA. Three structural forces define UAE AI market growth through 2034: government commitment to the National AI Strategy 2031 creating sustained public sector AI demand; sovereign AI capital funding the transition from AI consumer to AI developer; and global technology partnerships accelerating enterprise AI deployment velocity above comparable emerging markets globally.
Research Methodology
Primary Research
Primary research comprised structured interviews with UAE AI industry stakeholders including AI Strategy Directors, Chief Technology Officers, AI Startup Founders, Cloud Service Managers, and enterprise AI buyers across Dubai and Abu Dhabi's financial services, healthcare, and government sectors. Consumer survey data from UAE enterprise AI decision-makers across multiple industries was incorporated to validate demand trends.
Secondary Research
Secondary research encompassed UAE AI Office strategic publications, company annual reports, UAE government digital transformation reports, research publications from leading AI universities and innovation institutes, investor presentation data, and sector-specific AI deployment reports. Press releases from key market participants, industry analyst reports, and UAE federal and emirate-level technology policy documents were reviewed. Over 50 secondary sources consulted.
Forecasting Models
Market revenue forecasts were developed using a sector-by-sector AI adoption model combining government AI procurement data, enterprise technology spending indices, and cross-sector AI maturity assessments calibrated to UAE's digital infrastructure investment commitments. Sovereign AI investment flows were modeled separately to capture above-market growth from national AI capital deployment programs.
UAE Artificial Intelligence Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Narrow/Weak Artificial Intelligence, General/Strong Artificial Intelligence |
| Offerings Covered | Hardware, Software, Services |
| Technologies Covered | Machine Learning, Natural Language Processing, Context-Aware Computing, Computer Vision, Others |
| Systems Covered | Intelligence Systems, Decision Support Processing, Hybrid Systems, Fuzzy Systems |
| End-Use Industries Covered | Healthcare, Manufacturing, Automotive, Agriculture, Retail, Security, Human Resources, Marketing, Financial Services, Transportation and Logistics, Others |
| Regions Covered | Dubai, Abu Dhabi, Sharjah, Others |
| Companies Covered | Microsoft, IBM Corporation, Oracle, Accenture, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the UAE artificial intelligence market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the UAE artificial intelligence market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the UAE artificial intelligence industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the UAE Artificial Intelligence Market Report
UAE artificial intelligence market size is estimated at USD 859.8 Million in 2026, driven by the National AI Strategy 2031, government digital transformation mandates, and enterprise AI adoption across healthcare, finance, and oil and gas sectors. The market reflects UAE's position as the Middle East's most active AI investment and deployment destination.
UAE artificial intelligence market grows at 21.84% CAGR during 2026-2034, reaching USD 4,387.3 Million by 2034. Growth is sustained by sovereign AI capital deployment, National AI Strategy 2031 execution, Arabic language AI model commercialization, and UAE's strategic positioning as MENA's primary AI infrastructure hub.
Software leads at 48.7% through enterprise AI platform adoption, cloud-based machine learning services, and growing demand for sector-specific AI applications. UAE's strong cloud infrastructure and government AI platform procurement drive software's dominant market position above services and hardware.
Narrow/Weak Artificial Intelligence leads at 78.6% through commercially deployed task-specific AI across fraud detection, predictive maintenance, image recognition, and NLP chatbots at scale across UAE's financial services, healthcare, and government sectors. General/Strong AI grows fastest at approximately 24.8% CAGR.
Dubai leads at 45.6% through its Smart Dubai initiative, UAE's highest concentration of multinational technology company regional headquarters, and the Dubai International Financial Centre's AI-focused fintech ecosystem. Abu Dhabi follows at 37.8% through sovereign AI investment concentration and large-scale industrial AI programs.
Leading companies include Microsoft, IBM Corporation, Oracle, Accenture, and others.
UAE artificial intelligence market is projected to reach USD 1,894.5 Million by 2030, with the AI services segment growing as enterprise digital transformation programs mature, Arabic language AI commercialization expands across MENA, and sovereign AI platforms generate above-market CAGR through government and regional enterprise deployment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade