
United States Propylene Glycol Market Size, Share, Trends and Forecast by Source, Application, End Use Industry, and Region, 2026-2034
United States Propylene Glycol Market Size, Share, Trends & Forecast (2026-2034)
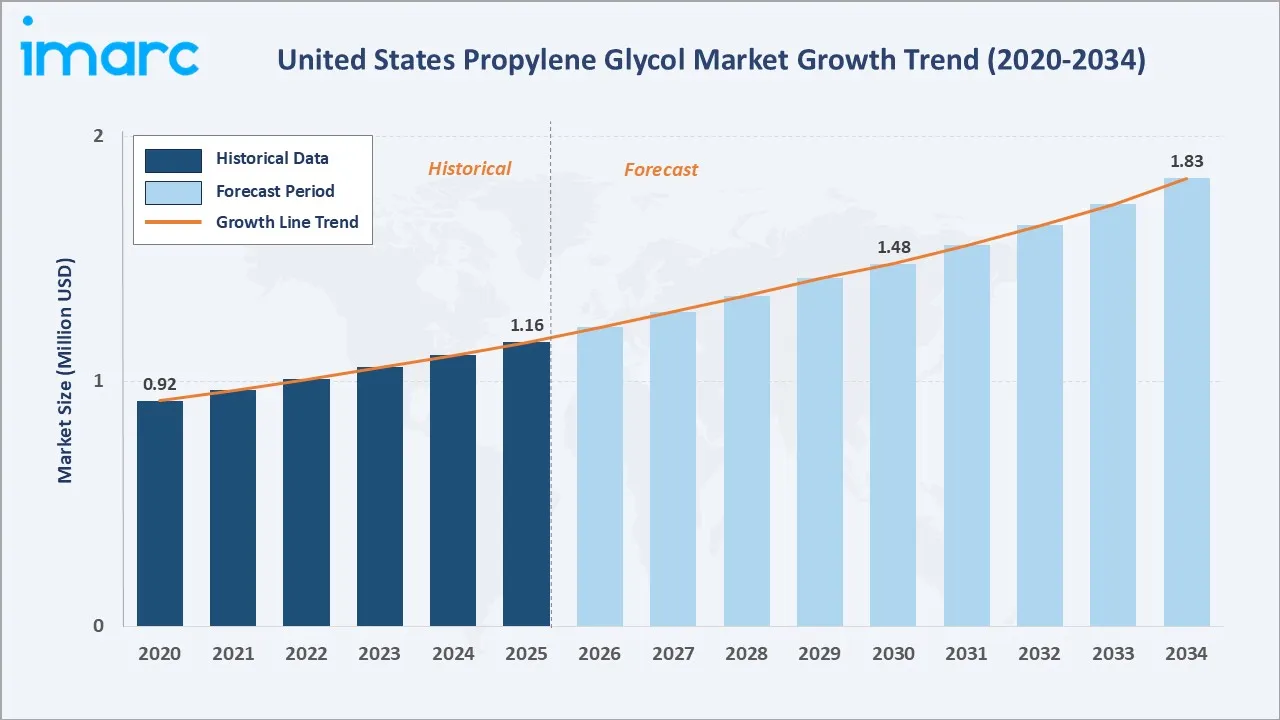
The us propylene glycol market grew from USD 1.16 Million in 2025 to USD 1.22 Million in 2026 and is projected to reach USD 1.83 Million by 2034, growing at a CAGR of 4.88% during 2026-2034. The market is driven by expanding pharmaceutical applications, growing antifreeze demand, and rising adoption of bio-based propylene glycol.
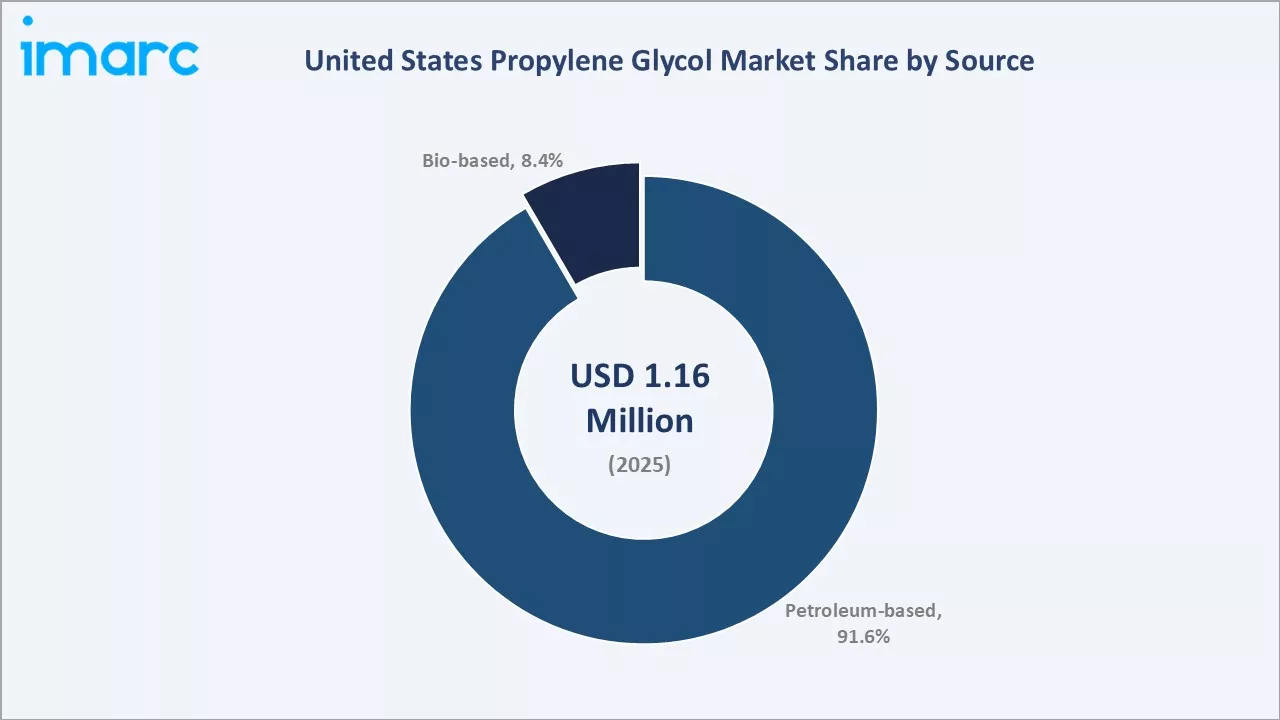
Petroleum-based propylene glycol commands 91.6% of the us glycol market. Antifreeze and functional fluids lead applications at 31.7%. The South region accounts for 42.8% of national consumption, anchored by Gulf Coast petrochemical manufacturing infrastructure.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.16 Million |
|
Market Size (2026) |
USD 1.22 Million |
|
Forecast Market Size (2034) |
USD 1.83 Million |
|
CAGR (2026-2034) |
4.88% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Source |
Petroleum-based (91.6%, 2025) |
|
Dominant Application |
Antifreeze & Functional Fluids (31.7%, 2025) |
|
Leading Region |
South (42.8%, 2025) |
The US propylene glycol market grew from USD 0.92 Million in 2020 to USD 1.16 Million in 2025. The market is projected to reach USD 1.22 Million in 2026, USD 1.48 Million in 2030, and USD 1.83 Million by 2034.
To get more information on this market, Request Sample
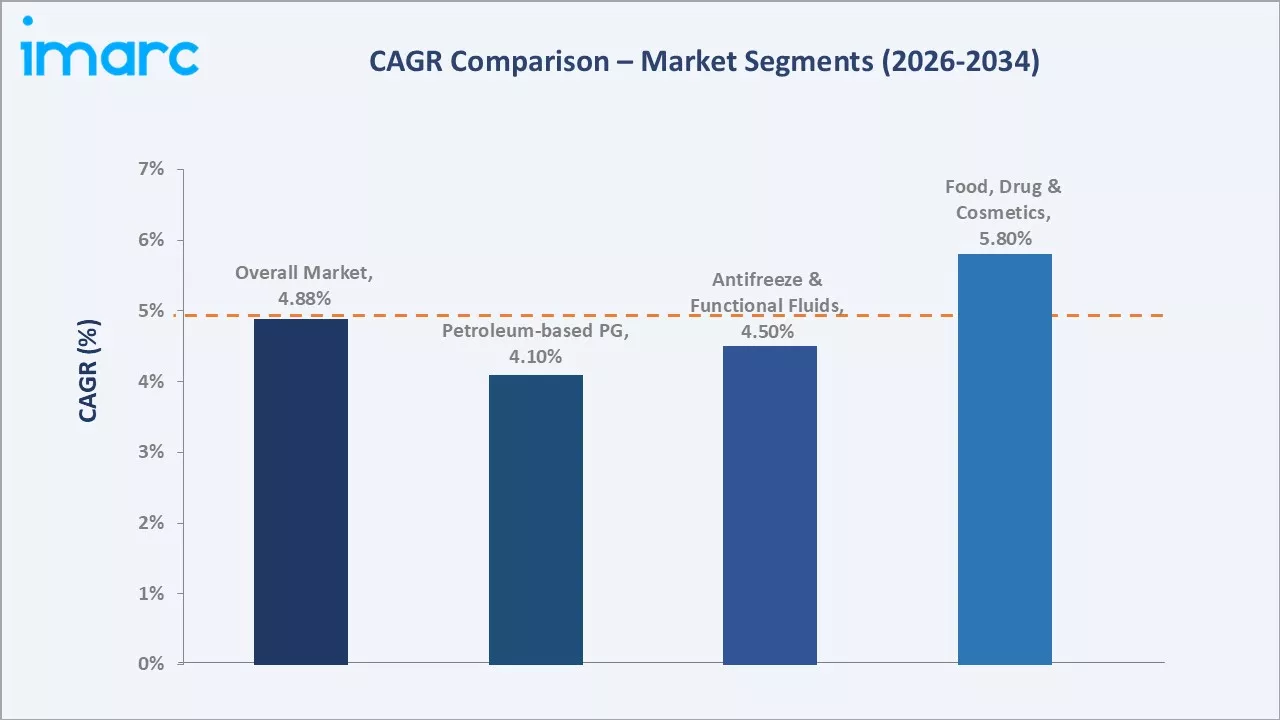
Bio-based propylene glycol registers the fastest CAGR of ~7.2%, driven by USDA BioPreferred mandates and corporate ESG targets. Food, drug, and cosmetics applications grow at ~5.8% CAGR through pharmaceutical sector expansion.
Executive Summary
The United States propylene glycol market reached USD 1.16 Million in 2025 and is estimated to reach USD 1.22 Million in 2026. The market is positioned at the intersection of petrochemical manufacturing, regulated food and pharmaceutical applications, and emerging bio-based chemistry.
Petroleum-based propylene glycol commands 91.6% market share, supported by established propylene oxide production infrastructure on the Gulf Coast. The South leads regionally at 42.8%, anchored by petrochemical production capacity in Texas and Louisiana.
The market is projected to reach USD 1.83 Million by 2034, supported by pharmaceutical manufacturing growth, EV thermal management applications, and continued antifreeze and functional fluid demand.
Key Market Insights
|
Insight |
Data |
|
Dominant Source |
Petroleum-based - 91.6% (2025) |
|
Dominant Application |
Antifreeze & Functional Fluids - 31.7% (2025) |
|
Leading Region |
South - 42.8% (2025) |
|
Key Market Opportunity |
Bio-based expansion; pharmaceutical-grade demand; EV thermal management; sustainable ingredient sourcing |
Key Analytical Observations Supporting the Above Data:
- Petroleum-based at 91.6%: Petroleum-based propylene glycol dominates through cost efficiency, established production infrastructure, and versatile applicability across all grades. Propylene oxide hydrolysis remains the primary commercial production route, supporting high-volume output and competitive pricing at industrial scale.
- Antifreeze and Functional Fluids at 31.7%: The transportation and aviation sectors drive sustained propylene glycol demand through coolant, de-icing fluid, and HVAC heat transfer applications. The US vehicle fleet of over 290 million registered vehicles and commercial aviation operations collectively underpin structural demand for this leading application segment.
- South at 42.8%: Gulf Coast petrochemical production concentration in Texas and Louisiana creates both supply capacity and downstream industrial demand. The region hosts major propylene glycol manufacturing facilities and serves as the primary national distribution hub for industrial and commercial buyers.
United States Propylene Glycol Market Overview
The US propylene glycol market is commercially structured around three distinct quality tiers: industrial-grade, food-grade, and pharmaceutical-grade. Each tier operates under different regulatory requirements and commands distinct pricing. FDA, EPA, and USDA BioPreferred regulations define the quality standards governing each tier.
The us bio-based propylene glycol market is gaining commercial traction within this tiered structure, with USDA BioPreferred certification enabling market access to federal procurement and corporate sustainability-mandated supply chains. The bio-based segment differentiates on renewable sourcing and sustainability credentials.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
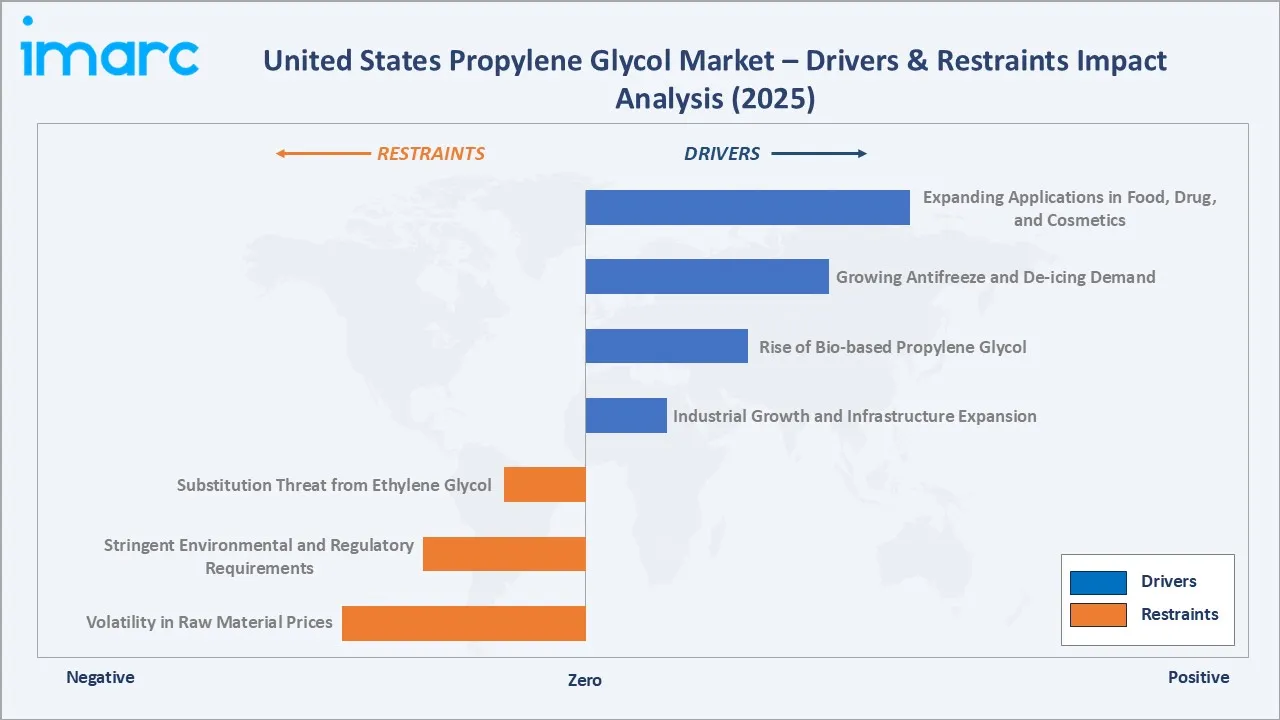
- Expanding Applications in Food, Drug, and Cosmetics: Propylene glycol is widely used as a humectant, solvent, and preservative in food processing, pharmaceutical formulations, and personal care products. Rising consumption of packaged foods, OTC medications, and cosmetics in the United States is driving sustained demand for food-grade and pharmaceutical-grade propylene glycol. The food and drug application segment accounts for 24.8% of total propylene glycol consumption, reflecting its essential role across GRAS-listed food ingredient supply chains and FDA-regulated pharmaceutical excipient markets.
- Growing Antifreeze and De-icing Demand: Propylene glycol is the primary active ingredient in aircraft de-icing fluids and automotive antifreeze formulations, serving transportation and aviation sectors. Increasing commercial air traffic, fleet expansion, and vehicle production in the US sustain robust demand for propylene glycol-based coolants and de-icing fluids. With over 290 million registered vehicles in the United States and commercial aviation handling high passenger volumes annually, structural demand for functional fluids containing propylene glycol remains consistently high across all weather conditions and climate zones.
- Rise of Bio-based Propylene Glycol: Growing environmental regulations and sustainability mandates drive investment in bio-based propylene glycol production from renewable feedstocks such as glycerol. The USDA BioPreferred Program creates federal procurement incentives, expanding bio-based propylene glycol adoption in personal care and food segments. Bio-based propylene glycol commands a 15-25% price premium over petroleum-based equivalents in certified organic personal care formulations and USDA-certified food ingredient supply chains, attracting investment from agricultural chemical producers seeking premium-margin specialty chemical markets.
- Industrial Growth and Infrastructure Expansion: Strong industrial activity in manufacturing, construction, and chemical processing drives demand for propylene glycol as a heat transfer fluid, hydraulic fluid, and industrial solvent. US infrastructure investment programs and manufacturing reshoring trends expand propylene glycol consumption in building systems and industrial applications. The US industrial chemicals market, positions propylene glycol as a critical functional fluid across HVAC, specialty chemical manufacturing, and food-grade lubrication applications.
Market Restraints
- Volatility in Raw Material Prices: Propylene glycol production depends heavily on propylene oxide from crude oil refining. Crude oil price fluctuations directly impact raw material costs, causing unstable production economics and pricing variability for manufacturers and buyers. Propylene oxide feedstock typically accounts for 60-70% of total propylene glycol production costs, creating high structural exposure to petrochemical price cycles and limiting manufacturers' ability to offer stable long-term pricing contracts to pharmaceutical, food processing, and automotive fluid buyers.
- Stringent Environmental and Regulatory Requirements: Manufacturing propylene glycol involves chemical processes subject to EPA regulations on emissions, waste disposal, and chemical handling. Compliance with evolving environmental standards increases operational costs and quality control requirements. Pharmaceutical-grade production requires USP, EP, and FCC-compliant manufacturing environments, demanding capital-intensive facility investments, extensive batch documentation, and third-party audit cycles that significantly increase production overhead and create barriers for smaller or new-entrant propylene glycol producers.
- Substitution Threat from Ethylene Glycol: Ethylene glycol offers comparable performance in antifreeze and industrial fluid applications at lower cost, posing a competitive substitution threat. In industrial segments where food safety and low toxicity requirements do not apply, ethylene glycol constrains propylene glycol market penetration and volume growth. Ethylene glycol trades at a 20-35% discount versus propylene glycol in commodity antifreeze and HVAC fluid applications, creating ongoing substitution pressure in price-sensitive industrial procurement decisions where regulatory-mandated low toxicity is absent.
Market Opportunities
- Electric Vehicle Thermal Management Applications: The rapid growth of electric vehicles in the United States creates new demand for propylene glycol in battery thermal management systems requiring non-toxic, non-corrosive heat transfer fluids. EV battery packs require approximately 5-10 liters of heat transfer fluid per vehicle, and with EV sales projected to represent over 30% of new US vehicle sales by 2030, the EV sector represents a structurally expanding new demand vector that positions propylene glycol for significant volume growth in a high-value, technically demanding application segment.
- Pharmaceutical Sector Expansion and Drug Innovation: Expanding pharmaceutical manufacturing in the United States, driven by domestic drug supply security initiatives, creates sustained demand for pharmaceutical-grade propylene glycol. Its role as a critical excipient in oral, injectable, and topical drug formulations positions it for above-market-average growth. US pharmaceutical manufacturing expansion under domestic supply chain security programs directly increases consumption of FDA-certified pharmaceutical excipients including propylene glycol across solid, liquid, and semi-solid dosage form production lines.
Market Challenges
- Supply Chain Concentration and Feedstock Dependency: US propylene glycol production is concentrated among a limited number of large chemical manufacturers, creating supply chain vulnerabilities during plant shutdowns or feedstock disruptions. Dependence on propylene oxide from petrochemical refining creates structural exposure to energy market volatility. Historical Gulf Coast supply disruptions have demonstrated that single-source or regionally concentrated propylene glycol supply creates significant inventory risk for pharmaceutical, food processing, and automotive manufacturers dependent on uninterrupted propylene glycol supply.
- Scaling Bio-based Production Economically: Achieving cost parity with petroleum-based production remains a technical and commercial challenge for bio-based propylene glycol producers. Glycerol feedstock availability, conversion efficiency, and capital-intensive production infrastructure limit the pace of bio-based capacity expansion. Current bio-based propylene glycol capacity in the US covers less than 10% of domestic demand, requiring significant capital investment in glycerol hydrogenolysis facilities to achieve competitive production economics at commercial scale relative to established petroleum-based production infrastructure.
Emerging Market Trends
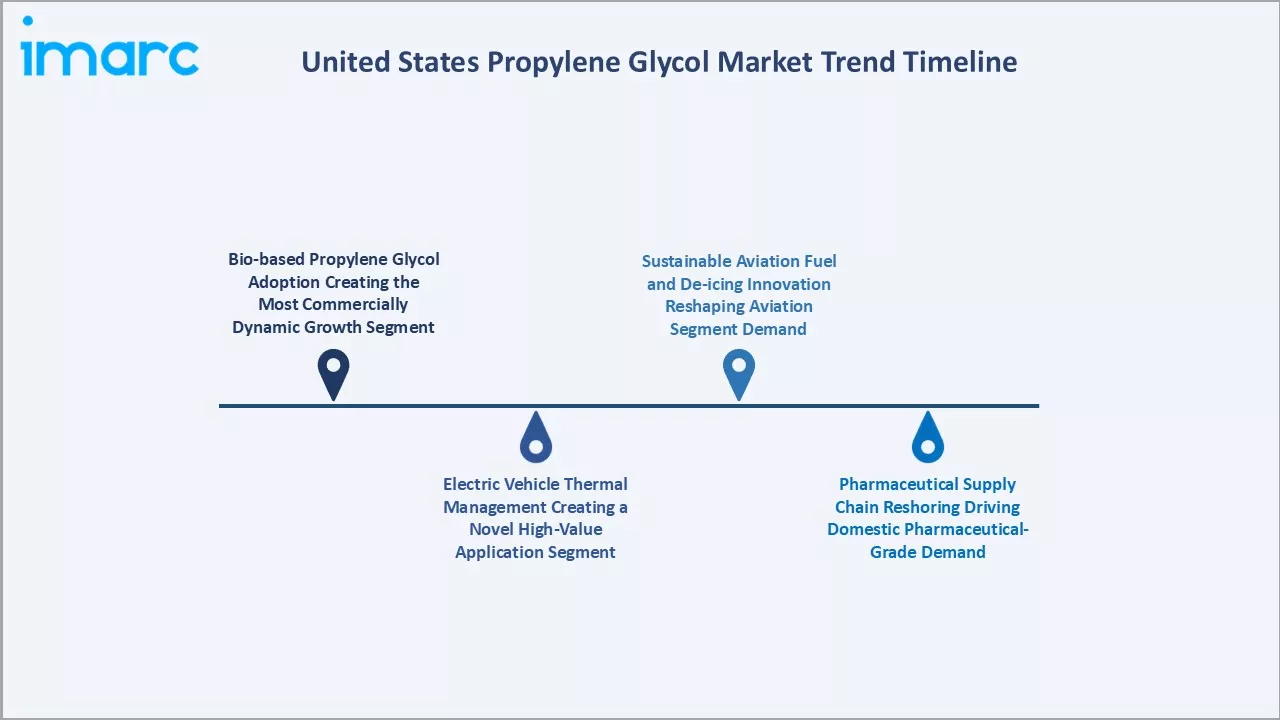
1. Bio-based Propylene Glycol Adoption Creating the Most Commercially Dynamic Growth Segment
Bio-based propylene glycol from glycerol and other renewable feedstocks is gaining commercial traction through USDA BioPreferred mandates and corporate sustainability commitments. Demand from personal care and food processing companies seeking green-certified ingredients is accelerating adoption and investment in bio-based capacity.
2. Electric Vehicle Thermal Management Creating a Novel High-Value Application Segment
The US transition to electric vehicles generates structured demand for propylene glycol in battery cooling and thermal management systems. EV manufacturers require non-toxic heat transfer fluids with precise thermal properties, creating a premium application niche growing in tandem with the expanding domestic EV production base.
3. Pharmaceutical Supply Chain Reshoring Driving Domestic Pharmaceutical-Grade Demand
US government initiatives to reshore pharmaceutical manufacturing are increasing domestic production of medicines, vaccines, and drug formulations. Propylene glycol, as a critical pharmaceutical excipient, benefits directly from this structural shift toward domestic drug manufacturing capacity across multiple dosage forms.
4. Sustainable Aviation Fuel and De-icing Innovation Reshaping Aviation Segment Demand
The US aviation sector’s sustainability commitments and growing air travel volumes drive innovation in propylene glycol-based de-icing formulations. Research into more efficient, environmentally compatible de-icing fluids combined with FAA-mandated safety standards supports structural demand for propylene glycol in aviation ground operations.
Industry Value Chain Analysis
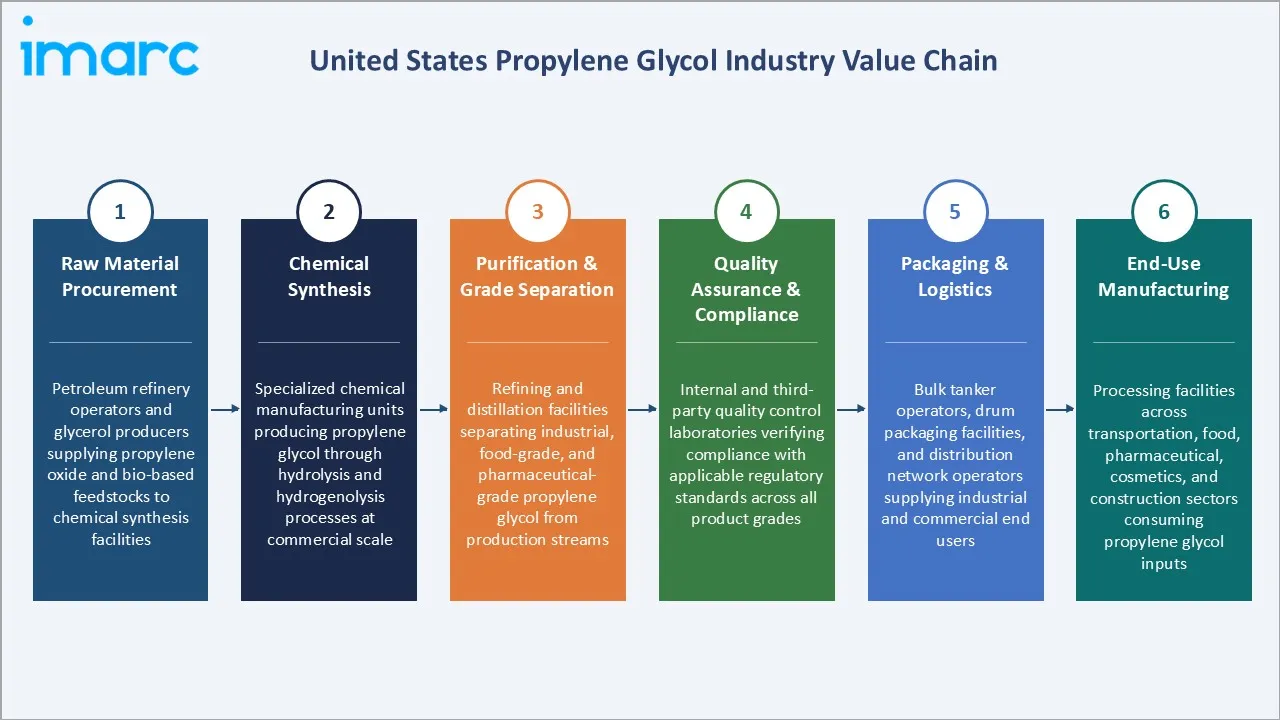
The US propylene glycol value chain integrates petrochemical raw material supply, large-scale chemical synthesis, multi-grade purification, and diversified end-use distribution. The value chain’s commercial structure creates distinct pricing tiers from industrial-grade to food-grade and pharmaceutical-grade propylene glycol.
|
Stage |
Key Participants |
|
Raw Material Procurement |
Petroleum refinery operators and glycerol producers supplying propylene oxide and bio-based feedstocks to chemical synthesis facilities |
|
Chemical Synthesis |
Specialized chemical manufacturing units producing propylene glycol through hydrolysis and hydrogenolysis processes at commercial scale |
|
Purification & Grade Separation |
Refining and distillation facilities separating industrial, food-grade, and pharmaceutical-grade propylene glycol from production streams |
|
Quality Assurance & Compliance |
Internal and third-party quality control laboratories verifying compliance with applicable regulatory standards across all product grades |
|
Packaging & Logistics |
Bulk tanker operators, drum packaging facilities, and distribution network operators supplying industrial and commercial end users |
|
End-Use Manufacturing |
Processing facilities across transportation, food, pharmaceutical, cosmetics, and construction sectors consuming propylene glycol inputs |
The quality assurance and compliance stage is the most commercially significant, as pharmaceutical-grade propylene glycol commands a 30-50% price premium over industrial-grade. Regulatory certification requirements create barriers that differentiate premium-grade producers from commodity suppliers.
Technology Landscape in the United States Propylene Glycol Industry
Propylene Oxide Hydrolysis Technology
The dominant commercial production technology involves propylene oxide hydrolysis, where propylene oxide reacts with water to produce propylene glycol. Modern processes utilize advanced reactor designs and catalytic systems to improve conversion efficiency and reduce energy consumption at commercial scale.
Bio-based Production via Glycerol Hydrogenolysis
Glycerol hydrogenolysis converts glycerol from biodiesel by-products into bio-based propylene glycol through catalytic hydrogenation. Ongoing R&D focuses on improving catalyst selectivity, glycerol conversion rates, and production economics to close the cost gap with petroleum-based propylene glycol production.
Precision Distillation and Multi-Grade Purification
Advanced distillation and purification technologies enable separation of pharmaceutical, food-grade, and industrial-grade propylene glycol from a single production stream. Precision purification supports compliance with USP, EP, and FCC monographs required for pharmaceutical and cosmetics market access.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
| Source | Petroleum-based |
91.6% |
2025 |
|
Application |
Antifreeze and Functional Fluids |
31.7% |
2025 |
| End Use Industry | 🔒 | 🔒 | 2025 |
|
Region |
South |
42.8% |
2025 |

By Source
Petroleum-based propylene glycol leads at 91.6% (2025) through cost efficiency, established production infrastructure, and versatility across industrial, food-grade, and pharmaceutical-grade applications. The established propylene oxide hydrolysis technology supports consistent large-scale production volumes.
To access detailed market analysis, Request Sample
Bio-based at 8.4% is growing fastest (~7.2% CAGR) through federal sustainability mandates and corporate ESG procurement requirements. Strategic investments in glycerol hydrogenolysis capacity are expanding bio-based production volumes.
By Application
Antifreeze and functional fluids lead at 31.7% (2025), serving automotive coolant, aviation de-icing, and HVAC heat transfer markets. The transportation and aviation sectors provide consistent structural demand across all seasonal and geographic segments of the United States market.
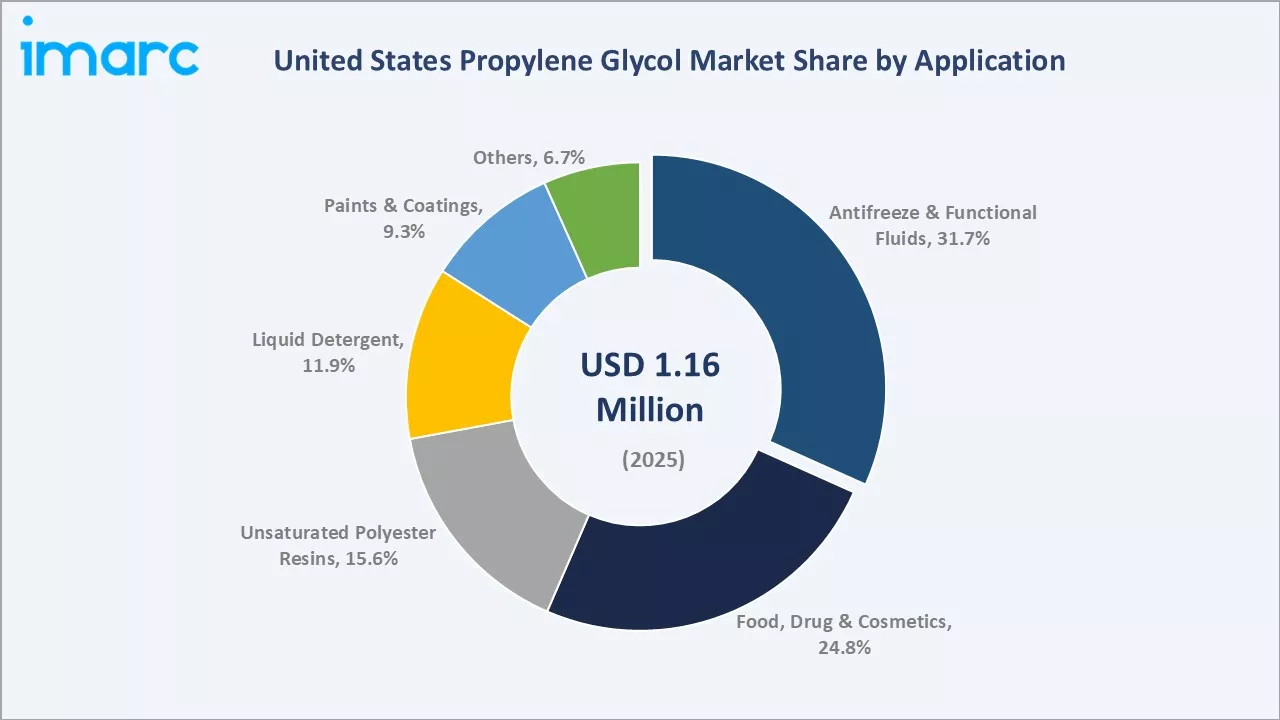
Food, drug, and cosmetics at 24.8% represents the highest-margin application. Unsaturated polyester resins at 15.6% serve construction and marine composites. Liquid detergent at 11.9% and paints and coatings at 9.3% complete the commercial application landscape.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Characteristics |
|
South |
42.8% |
Dominant production and consumption region with concentrated chemical manufacturing infrastructure and high industrial activity supporting propylene glycol demand. |
|
Midwest |
21.6% |
Strong agricultural processing, food manufacturing, and automotive sector demand driving consistent propylene glycol consumption across the region. |
|
West |
20.7% |
Growing pharmaceutical and biotechnology manufacturing demand with increasing adoption of sustainable and bio-based chemical products. |
|
Northeast |
14.9% |
High pharmaceutical and personal care manufacturing concentration driving demand for premium food-grade and pharmaceutical-grade propylene glycol. |
The South’s 42.8% market leadership reflects the Gulf Coast petrochemical corridor’s concentration of production capacity. The Midwest’s 21.6% reflects agricultural-linked demand from food processing and grain operations.
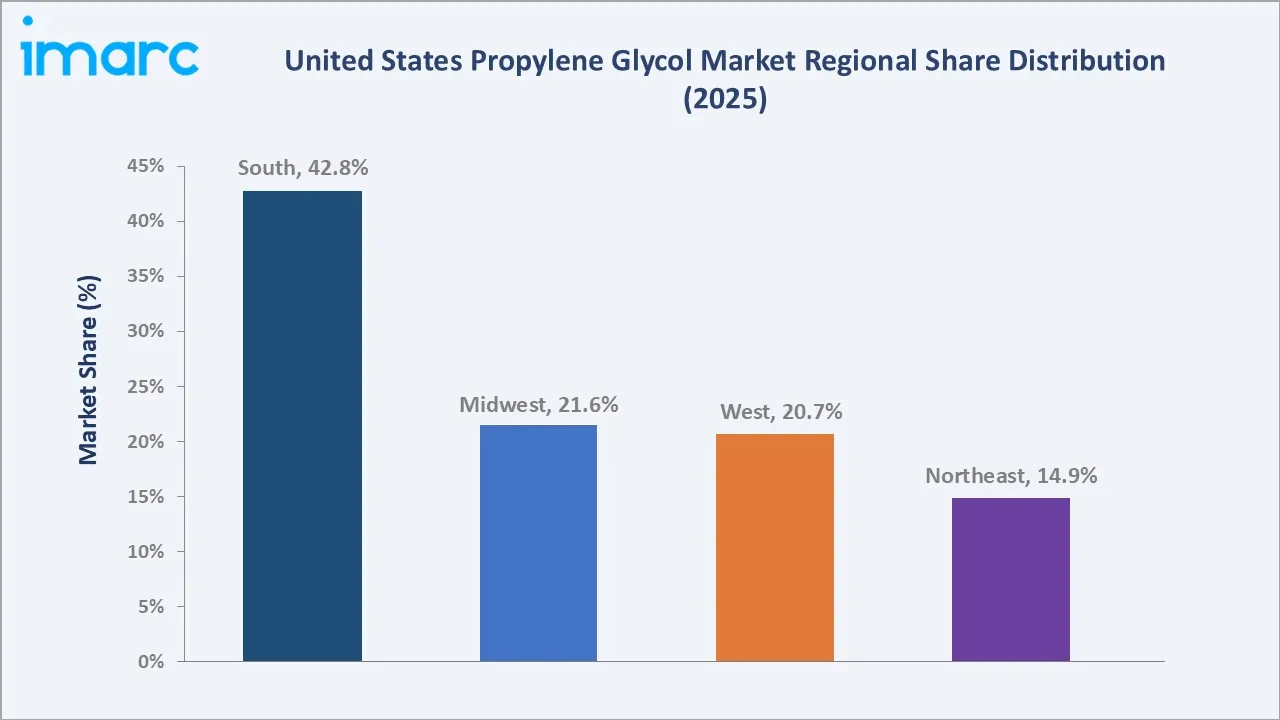
The West’s 20.7% is driven by pharmaceutical manufacturing and state sustainability policies. The Northeast’s 14.9% reflects pharmaceutical and cosmetics manufacturing demand in metro industrial corridors.
Competitive Landscape
The US propylene glycol market is moderately concentrated, with Dow Inc., BASF SE, and LyondellBasell Industries collectively accounting for an estimated 55-60% of domestic production capacity. Bio-based producers ADM and Cargill are gaining share in sustainability-driven segments, intensifying competitive dynamics.
|
Company |
Key Products/Brands |
Market Position |
Core Strength |
|
Dow |
Propylene Glycol |
Market Leader |
Vertically integrated propylene oxide and PG production; multi-grade portfolio; Gulf Coast manufacturing scale. |
|
BASF |
Propylene Glycol |
Strong Challenger |
Comprehensive PG grade range; pharmaceutical excipient leadership; North American distribution network. |
|
LyondellBasell Industries Holdings B.V. |
Propylene Glycol |
Strong Challenger |
Captive propylene oxide production advantage; large-scale US manufacturing; broad industrial customer base. |
|
ADM |
Propylene Glycol |
Innovator |
Pioneer in bio-based PG from renewable glycerol feedstocks; USDA BioPreferred certified production. |
Key players include Dow, BASF, LyondellBasell Industries Holdings B.V., ADM, and others.
Key Company Profiles
Dow
Dow is one of the largest specialty chemical companies globally and a dominant producer of propylene glycol in the United States, operating integrated propylene oxide and propylene glycol production facilities across the Gulf Coast and supplying industrial, food-grade, and pharmaceutical-grade propylene glycol at commercial scale.
- Key Offerings: Propylene Glycol
- Strategic Focus: Maintaining integrated production advantage in propylene oxide and propylene glycol; expanding pharmaceutical-grade certified manufacturing capacity to capture growth from domestic drug manufacturing reshoring; advancing low-carbon chemical manufacturing aligned with sustainability commitments; and strengthening multi-grade product portfolio to serve pharmaceutical, food, and industrial end markets from a single integrated production and quality infrastructure.
BASF
BASF is a leading global chemical company with a strong presence in the US propylene glycol market through its integrated chemical manufacturing and specialty chemical distribution network, supplying a broad range of propylene glycol grades and derivatives for industrial, pharmaceutical, and personal care applications.
- Key Offerings: Propylene Glycol
- Strategic Focus: Expanding pharmaceutical-grade propylene glycol supply capacity aligned with domestic drug manufacturing growth; growing sustainable formulation portfolio for personal care and food applications; leveraging global R&D and application development network to create differentiated specialty grades; and strengthening US market distribution infrastructure to improve service levels for pharmaceutical and specialty chemical customers requiring consistent quality and supply reliability.
Market Concentration Analysis
The US propylene glycol market exhibits moderate concentration at the production level, with the leading three producers accounting for an estimated 55-60% of domestic production capacity. Market concentration is higher in pharmaceutical-grade supply, where FDA certification requirements create significant barriers to entry and limit the number of qualified suppliers available to regulated end users.
Market concentration is evolving through two competing forces. Established integrated chemical manufacturers maintain production dominance through scale advantages and capital-intensive infrastructure. Bio-based chemical producers are gradually increasing market share in sustainability-driven segments, creating a slow but structural shift in competitive dynamics that is expected to gradually reduce concentration over the forecast period as bio-based production capacity expands.
Investment & Growth Opportunities
Highest Growth Segments
Bio-based propylene glycol represents the fastest-growing segment in the US market, projected to expand at a 7.2% CAGR during 2026–2034, followed by food, drug, and cosmetics applications at 5.8%, the South region is expected to grow at 5.1%, while antifreeze and functional fluids are projected to expand at 4.5%. Petroleum-based propylene glycol records the slowest growth at 4.1%, reflecting increasing demand for sustainable alternatives and expanding applications across consumer and industrial sectors.
Emerging Investment Opportunities
Electric vehicle battery thermal management represents the highest-CAGR emerging application for propylene glycol. Battery pack cooling requirements in expanding US EV production create structured demand for non-toxic, high-performance heat transfer fluids, driving innovation and volume growth beyond traditional automotive antifreeze applications.
Investment Themes
- Bio-based Production Capacity: Expanding glycerol hydrogenolysis capacity with USDA BioPreferred certification to capture premium pricing from sustainability-mandated procurement in food, cosmetics, and government markets representing the fastest-growing propylene glycol investment segment with 7.2% CAGR through 2034.
- Pharmaceutical-grade Expansion: US pharmaceutical manufacturing reshoring creates structural demand growth for FDA-certified USP-grade propylene glycol excipients, supporting above-market-average revenue growth for certified pharmaceutical-grade suppliers through 2034.
Future Market Outlook (2026-2034)
The US propylene glycol market is projected to grow from USD 1.16 Million in 2025 to USD 1.22 Million in 2026, reaching USD 1.48 Million by 2030 and USD 1.83 Million by 2034, at a CAGR of 4.88% during 2026-2034. The 2030 inflection point is driven by accelerating EV adoption and pharmaceutical manufacturing capacity expansion.
Three structural forces define market growth through 2034: domestic pharmaceutical manufacturing expansion creating sustained pharmaceutical-grade demand; EV thermal management establishing a new high-value application segment; and bio-based production scaling supported by USDA mandates and corporate ESG commitments, gradually shifting the source mix toward renewable feedstocks.
Research Methodology
Primary Research
Primary research comprised structured interviews with US propylene glycol industry stakeholders including production plant managers, procurement directors at major end-user companies, supply chain executives, pharmaceutical excipient buyers, and regulatory compliance specialists across food-grade and industrial-grade markets.
Secondary Research
Secondary research encompassed US chemical trade data, EPA production reports, FDA ingredient databases, company annual reports, USDA BioPreferred program data, ACC industry publications, and ICIS chemical market analysis. Over 50 secondary sources were systematically reviewed and cross-referenced for data validation.
Forecasting Models
Market revenue forecasts were developed using a bottom-up end-use demand model: US consumption volumes by application segment multiplied by average selling prices per grade, with source mix adjustments for petroleum-based versus bio-based production. CAGR was validated against historical production data and capacity expansion plans.
United States Propylene Glycol Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Sources Covered | Petroleum-based, Bio-based |
| Applications Covered | Unsaturated Polyester Resins, Antifreeze and Functional Fluids, Food, Drug, and Cosmetics, Liquid Detergent, Paints and Coatings, Others |
| End Use Industries Covered | Transportation, Building and Construction, Food and Beverage, Pharmaceuticals, Cosmetics and Personal Care, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Companies Covered | Dow, BASF, LyondellBasell Industries Holdings B.V., ADM, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States propylene glycol market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States propylene glycol market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States propylene glycol industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Propylene Glycol Market Report
The us propylene glycol market reached USD 1.16 Million in 2025. Demand spans antifreeze, pharmaceutical, food, and industrial chemical applications, with bio-based adoption and pharma reshoring supporting growth.
The us glycol market grows at 4.88% CAGR during 2026-2034, reaching USD 1.83 Million by 2034. Growth is sustained by pharmaceutical demand, EV thermal management, and consistent antifreeze consumption.
Petroleum-based propylene glycol leads at 91.6% through established production infrastructure and cost efficiency. Bio-based at 8.4% is the fastest-growing segment, driven by USDA mandates and sustainability demand.
Antifreeze and functional fluids lead at 31.7% through extensive use in automotive coolants, aviation de-icing, and HVAC systems. The US vehicle fleet and aviation activity sustain structural demand for this segment.
The South leads at 42.8% through Gulf Coast petrochemical production concentration in Texas and Louisiana. Strong industrial activity and regional distribution infrastructure reinforce this leadership.
Leading companies include Dow, BASF, LyondellBasell Industries Holdings B.V., ADM, and others.
The market is projected to reach USD 1.48 Million by 2030, with pharmaceutical-grade demand growing from domestic manufacturing expansion and EV thermal management emerging as a significant new application.
Three priority opportunities: bio-based production capacity expansion for the fastest-growing segment; pharmaceutical-grade supply for domestic drug manufacturing growth; and EV battery thermal management fluid development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade