
Australia Online Gambling Market Size, Share, Trends and Forecast by Game Type, Device, and Region, 2026-2034
Australia Online Gambling Market Size, Share, Trends & Forecast (2026-2034)
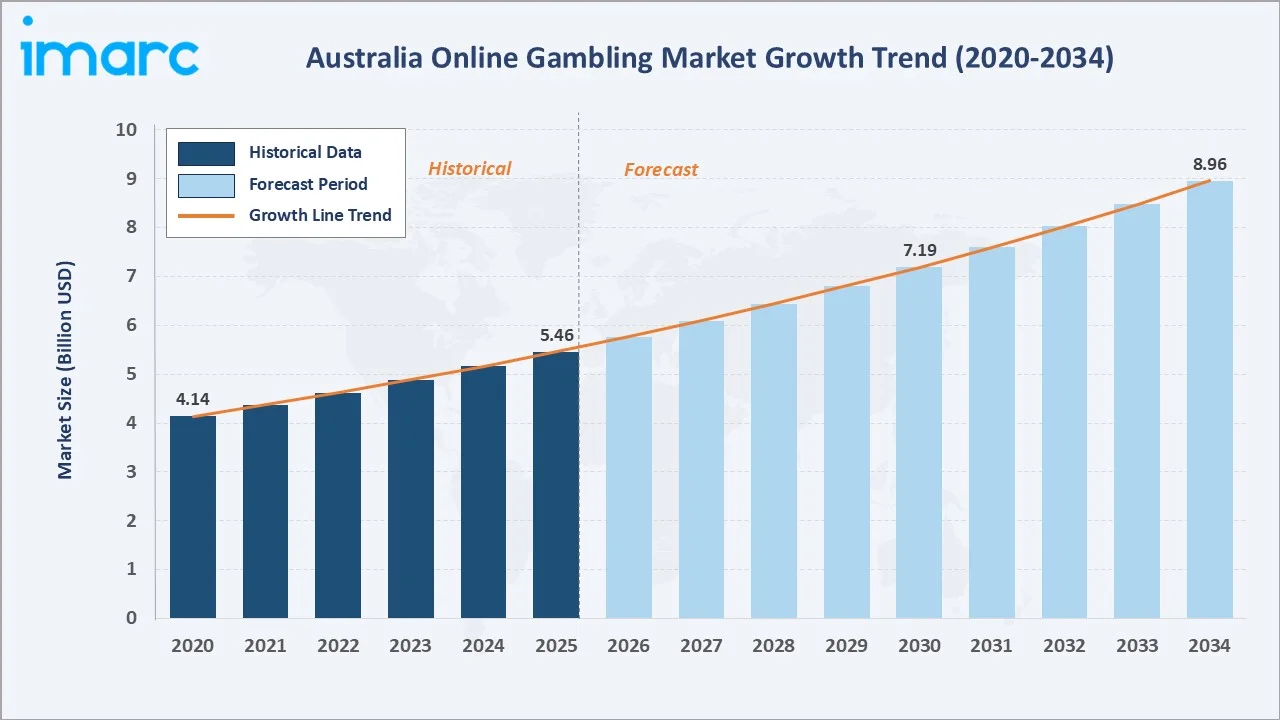
The Australia online gambling market size increased from USD 5.46 Billion in 2025 to USD 5.76 Billion in 2026 and is projected to reach USD 8.96 Billion by 2034, growing at a CAGR of 5.67% during 2026-2034. The market is driven by a favorable regulatory environment, changing consumer preferences toward digital entertainment, and the ongoing expansion of sports betting and casino game offerings. By late 2025, internet penetration had reached 97.1% of the population, while the country recorded 34.1 million active cellular mobile connections, equivalent to 126% of its population. This extensive mobile and internet connectivity enables consumers to conveniently access online betting, casino, and other gambling platforms through smartphones from virtually any location. Sports betting leads with a 58.4% share in 2025. Desktop remains the dominant device at 54.3%. The Australia Capital Territory and New South Wales region holds the largest share at 38.6%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 5.46 Billion |
| Market Size (2026) | USD 5.76 Billion |
|
Forecast Market Size (2034) |
USD 8.96 Billion |
|
CAGR (2026-2034) |
5.67% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Game Type |
Sports Betting (58.4%, 2025) |
|
Dominant Device |
Desktop (54.3%, 2025) |
|
Leading Region |
Australia Capital Territory and New South Wales (38.6%, 2025) |
The Australia online gambling market has grown consistently from USD 4.14 Billion in 2020 to USD 5.46 Billion in 2025 and an estimated USD 5.76 Billion in 2026, reflecting a robust structural expansion underpinned by digital penetration and shifting consumer behavior. The market is projected to reach USD 7.19 Billion by 2030 and USD 8.96 Billion by 2034.
To get more information on this market, Request Sample
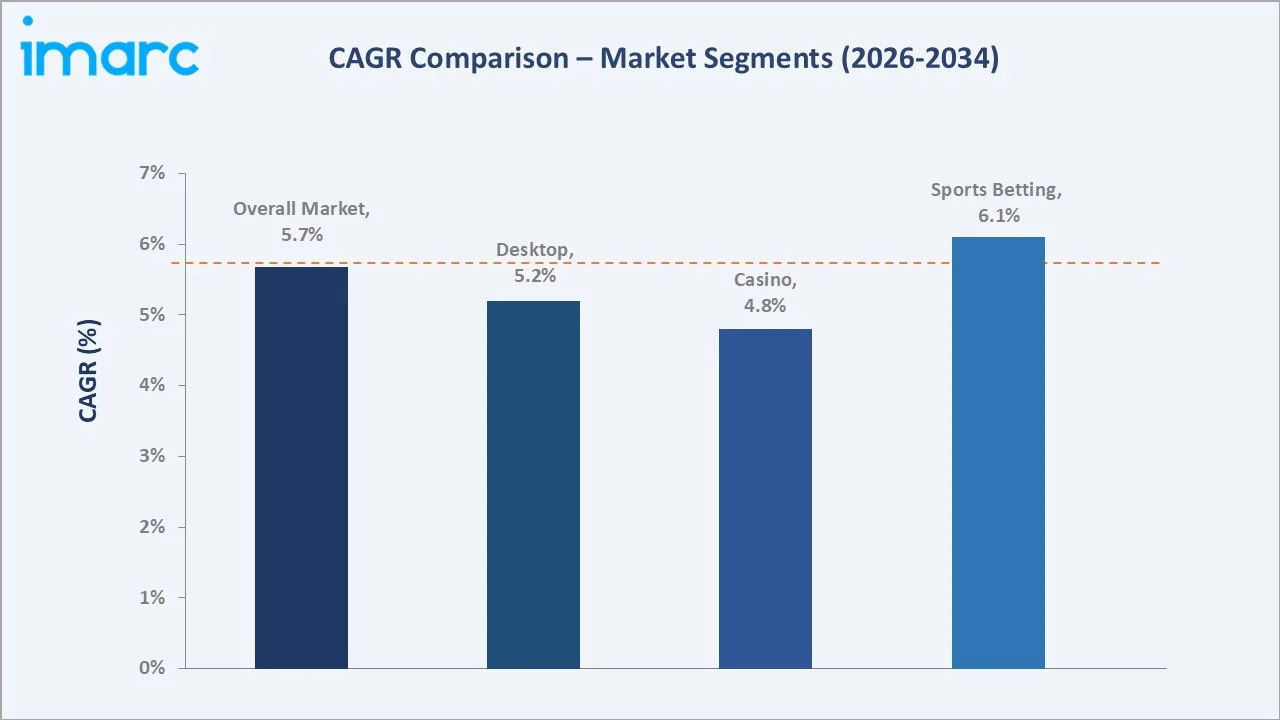
Sports betting grows at ~6.1% CAGR through 2034, driven by deep integration into Australia's sporting culture. Casino grows at ~4.8% CAGR supported by live dealer games, slots, and blackjack adoption. Desktop maintains its leading position at ~5.2% CAGR through immersive, feature-rich interfaces preferred by experienced bettors.
Executive Summary
The Australia online gambling market is witnessing sustained growth, driven by one of the highest rates of per-capita gambling participation combined with rapid digital infrastructure expansion. The convenience of mobile applications, competitive odds, and sophisticated live betting interfaces have significantly widened the addressable user base. Sports betting leads with a 58.4% share in 2025. Desktop remains the dominant device at 54.3%. The Australia Capital Territory and New South Wales lead regionally with the largest share at 38.6%.
Key Market Insights
|
Insight |
Data |
|
Dominant Game Type |
Sports Betting - 58.4% share (2025) |
|
Dominant Device |
Desktop - 54.3% share (2025) |
|
Leading Region |
Australia Capital Territory and New South Wales - 38.6% share (2025) |
|
Market Opportunity |
AI personalization, esports wagering, and responsible gambling technology |
Key Analytical Observations:
- Sports Betting at 58.4%: Sports betting dominates due to its deep integration into Australian sporting culture. AFL, NRL, cricket, and horse racing events generate massive wagering volumes, supported by sophisticated real-time odds platforms, in-play betting features, and social engagement tools that encourage frequent user participation.
- Desktop at 54.3%: Desktop leads because it provides an immersive environment with larger screens, high-resolution graphics, multi-window support, and faster processing that enhance complex betting strategies. Experienced gamblers prefer desktop for stability and comprehensive dashboard access during major sporting events.
- Australia Capital Territory and New South Wales at 38.6%: The ACT and NSW region dominates due to high population density, strong economic profiles, high disposable incomes, and a long-established gambling tradition. NSW's extensive sports betting and casino user base, combined with ACT's well-regulated framework and superior internet connectivity, creates the ideal environment for online gambling.
Australia Online Gambling Market Overview
The Australia online gambling market encompasses licensed online platforms offering a comprehensive range of wagering and gaming products to Australian consumers aged 18 and above. The market spans sports betting on domestic and international events, online casino games including live dealer formats, poker, slots, baccarat and blackjack, lottery-style games, and emerging esports wagering. Macroeconomic factors include Australia's high household disposable income, one of the highest per-capita broadband penetration rates, strong smartphone adoption exceeding 90% of the population as of early 2026, and an established gambling culture that dates back generations.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
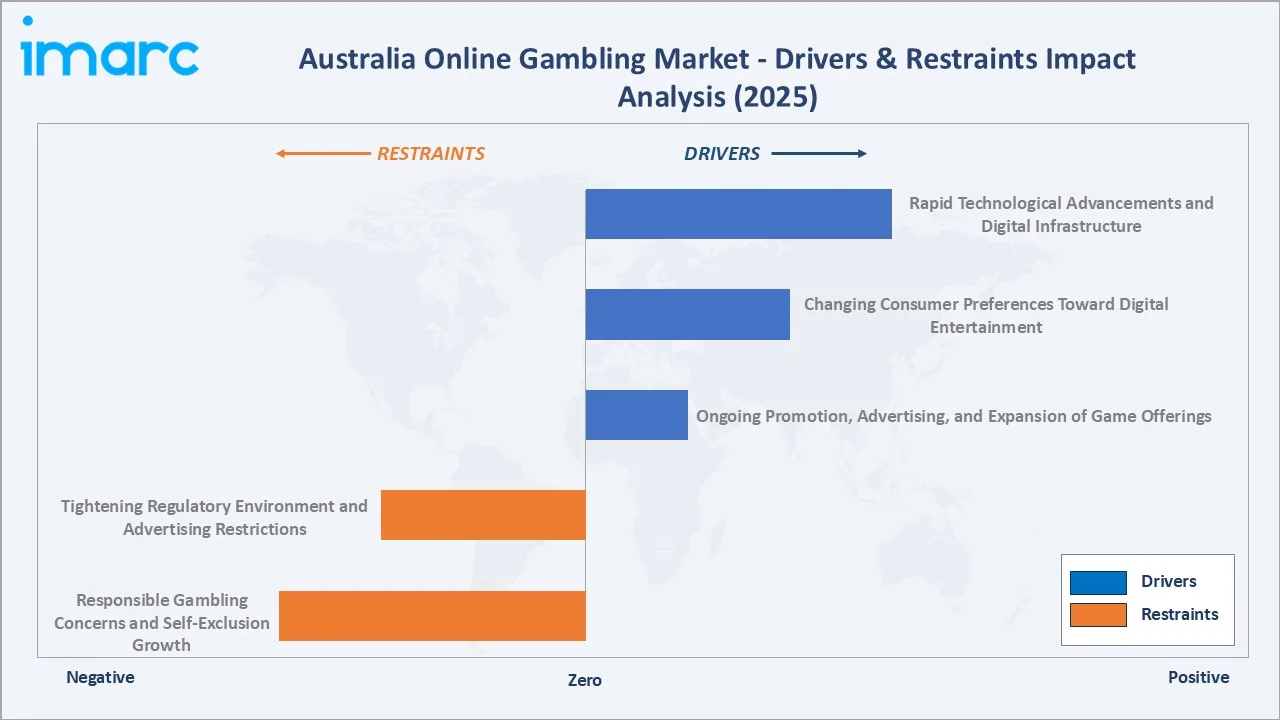
- Rapid Technological Advancements and Digital Infrastructure: As of early 2026, Australia recorded a notably high level of smartphone adoption, with penetration estimated at more than 90% of the population. Moreover, approximately 34.1 million cellular mobile connections were active across the country in late 2025, equivalent to around 126% of the total population. The widespread adoption of smartphones and high-speed internet has significantly increased Australians' access to online gambling. The integration of secure payment platforms, advanced mobile applications, and immersive graphics has enhanced user confidence and engagement across platforms.
- Changing Consumer Preferences Toward Digital Entertainment: The increasing demand for accessible digital entertainment is a primary growth driver. The convenience of 24/7 access, live betting features, and personalized promotions drive sustained engagement.
- Ongoing Promotion, Advertising, and Expansion of Game Offerings: In Australia, over one million gambling advertisements are broadcast annually across free-to-air television and radio. The diversification of offerings, including live dealer casinos, esports wagering, and innovative lottery formats, has attracted a broader demographic and sustained operator revenue growth.
Market Restraints
- Tightening Regulatory Environment and Advertising Restrictions: Australia's ban on credit card use for online gambling reflects the government's increasing regulatory intervention. A parliamentary committee has recommended a complete ban on all forms of online gambling advertising over a phased three-year period. These regulatory tightening measures could reduce customer acquisition efficiency and increase compliance costs for operators.
- Responsible Gambling Concerns and Self-Exclusion Growth: To the end of the second quarter of FY 2024–2025, BetStop registered 35,671 individuals for self-exclusion, with 26,020 active exclusions as of 31 December 2024. The ACMA investigated 301 complaints in Q4 2024, identifying 16 breaches and referring 75 illegal websites for blocking. These indicators of gambling-related harm create regulatory pressure and reputational risk that could constrain market growth.
Market Opportunities
- Esports Wagering and New Demographic Penetration: The growing popularity of esports is creating opportunities for online gambling operators to diversify their betting portfolios and reach younger, digitally engaged consumer segments. Expanding wagering options across competitive gaming events can support user acquisition and create additional revenue streams for market participants.
- Fixed Payout Lottery Innovation and New Game Formats: Innovation in fixed-payout lottery products and the introduction of new digital game formats are creating opportunities to enhance player engagement and broaden product offerings. Operators can leverage interactive features, simplified gameplay, and varied prize structures to attract new users and encourage greater participation.
Market Challenges
- Illegal Offshore Gambling Platform Competition: Offshore unlicensed platforms offering prohibited casino-style games continue to attract Australian users, creating unfair competitive pressure on licensed operators and potential revenue leakage from the regulated market.
- Payment Processing Complexity Following Credit Card Ban: The ban on credit card use for online gambling has increased the complexity and cost of payment infrastructure for operators. Adapting to alternative payment methods, including digital wallets, bank transfers, and emerging cryptocurrency options, requires significant technical investment while managing user friction and potential churn.
Emerging Market Trends
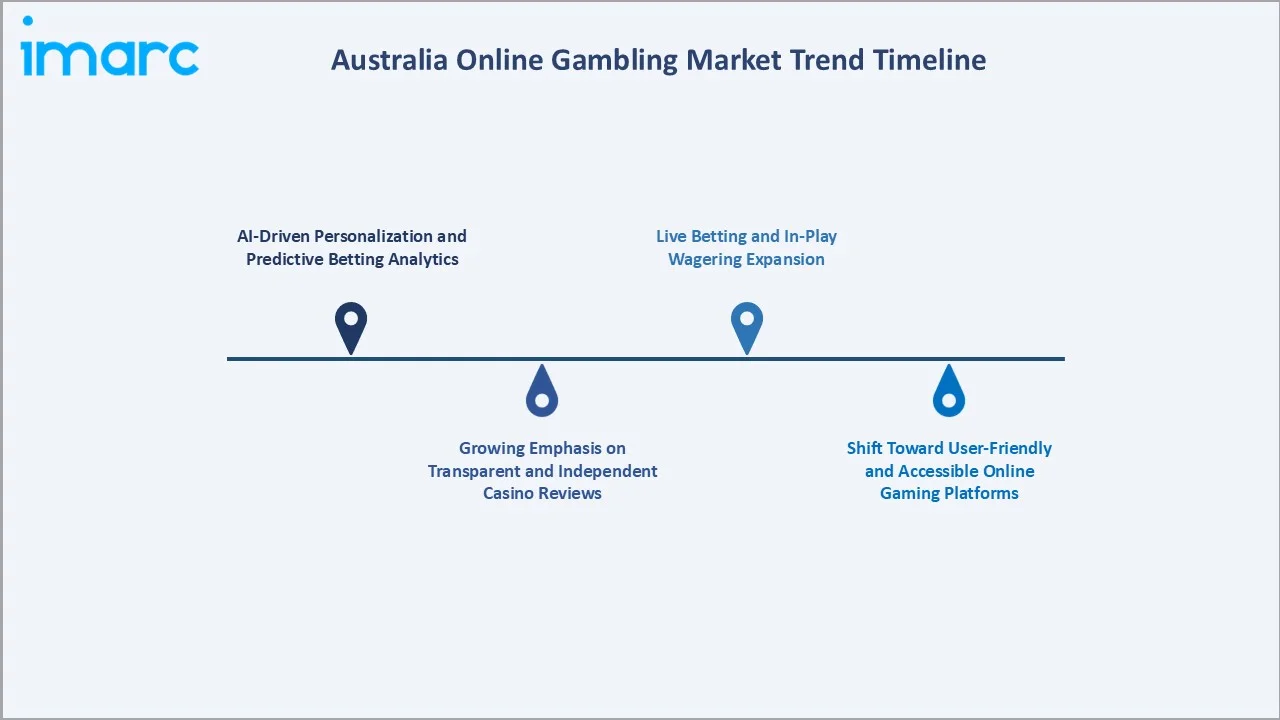
1. AI-Driven Personalization and Predictive Betting Analytics
Artificial intelligence and machine learning are fundamentally reshaping the online gambling experience in Australia. Leading operators are deploying AI-driven recommendation engines that analyze individual betting histories, risk profiles, and preferences to deliver personalized odds, promotions, and game suggestions. Predictive analytics are being used for real-time odds adjustment during live sporting events, improving engagement and reducing operator risk. AI is also central to responsible gambling tools, with machine learning models identifying at-risk behavioral patterns to trigger early intervention measures.
2. Growing Emphasis on Transparent and Independent Casino Reviews
In July 2026, Online Pokies Time introduced an independent real-money casino testing framework, a long-term editorial initiative aimed at strengthening transparency and reliability in the evaluation of online casinos. The framework focuses on improving how casino reviews for Australian players are researched, independently verified, and regularly updated. Market participants are increasingly focusing on trustworthy review practices and regularly updated platform assessments to strengthen player confidence and improve informed decision-making.
3. Live Betting and In-Play Wagering Expansion
In-play betting, placing wagers on events as they unfold in real time, is the fastest-growing wagering format in Australia. Live streaming integration within gambling platforms allows users to watch sporting events and place bets simultaneously, significantly increasing session length and frequency of wagers. AFL, NRL, and horse racing live betting volumes have grown substantially, with operators developing proprietary real-time data feeds and pricing models to support in-play markets at scale.
4. Shift Toward User-Friendly and Accessible Online Gaming Platforms
In August 2026, Spinfina launched an online gaming platform for Australian players, offering a secure and user-friendly digital experience. The platform features intuitive navigation, flexible payment options, and responsive customer support, enabling convenient access to online entertainment across the country. The launch reflects a growing market trend toward digital gaming platforms that prioritize convenience, secure access, and seamless user experiences. Operators are increasingly integrating intuitive interfaces, flexible payment methods, and responsive support to attract and retain a broader base of online players.
Industry Value Chain Analysis
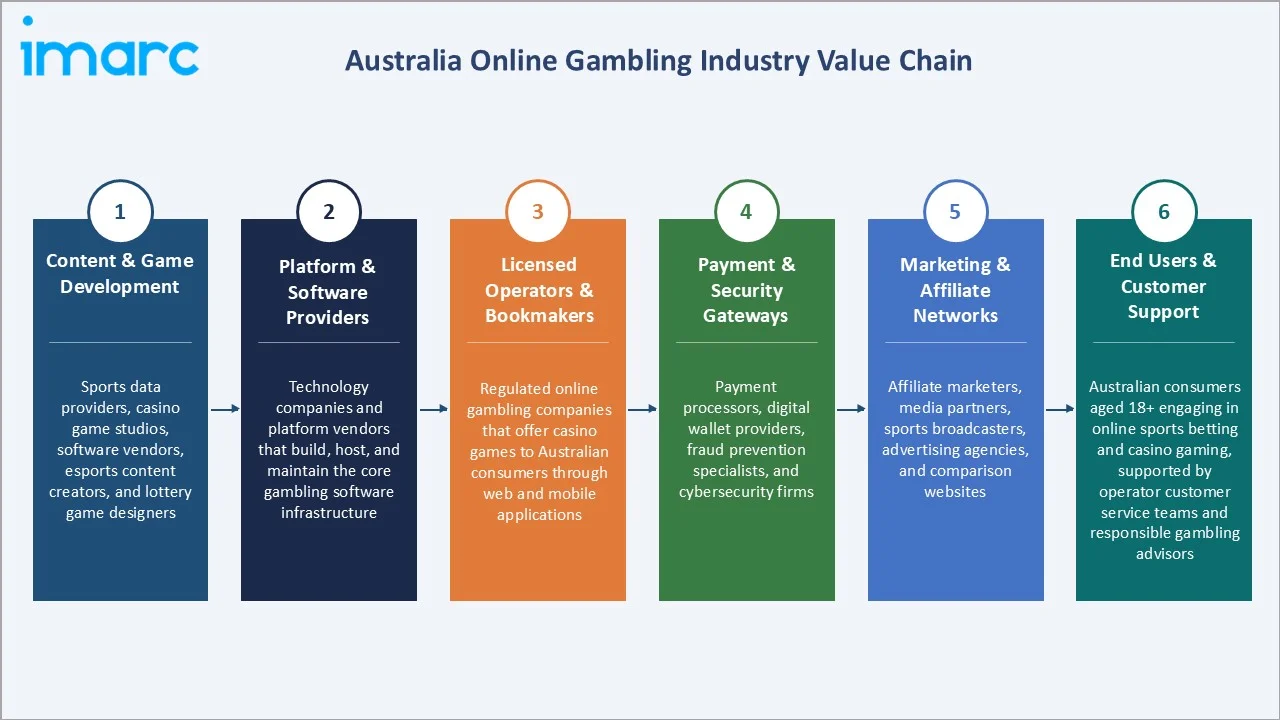
The Australia online gambling value chain integrates content and game development, platform and software provision, licensed operator and bookmaker services, payment and security infrastructure, marketing and affiliate networks, and end-user engagement and customer support across the regulated digital wagering ecosystem.
|
Stage |
Key Participants |
|
Content & Game Development |
Sports data providers, casino game studios, software vendors, esports content creators, and lottery game designers. |
|
Platform & Software Providers |
Technology companies and platform vendors that build, host, and maintain the core gambling software infrastructure. |
|
Licensed Operators & Bookmakers |
Regulated online gambling companies that offer casino games to Australian consumers through web and mobile applications. |
|
Payment & Security Gateways |
Payment processors, digital wallet providers, fraud prevention specialists, and cybersecurity firms. |
|
Marketing & Affiliate Networks |
Affiliate marketers, media partners, sports broadcasters, advertising agencies, and comparison websites. |
|
End Users & Customer Support |
Australian consumers aged 18+ engaging in online sports betting and casino gaming, supported by operator customer service teams and responsible gambling advisors. |
Licensed operators and bookmakers represent the most value-added stage, as they integrate content, technology, payments, and regulatory compliance into a seamless consumer experience. This stage requires the highest capital investment, regulatory expertise, and consumer trust, creating significant barriers to entry that reinforce the market dominance of established players.
Technology Landscape in the Australia Online Gambling Industry
Digital and Data Technology
Digital and data technologies underpin every aspect of modern online gambling operations in Australia. Cloud-based platform infrastructure enables operators to scale capacity during peak events, ensuring platform stability under high concurrent user loads. Advanced analytics platforms process millions of real-time betting data points to optimize odds margins, detect fraudulent patterns, and generate personalized user insights.
Mobile Application and User Experience Technology
Native mobile application development has become the primary investment priority for Australian online gambling operators. iOS and Android applications now incorporate biometric login, one-tap bet placement, real-time push notifications for odds changes and promotions, and integrated live streaming capabilities. The mobile segment is expected to approach desktop parity by 2030 as 5G network rollout further reduces latency for live betting applications and as younger demographics who exclusively use mobile devices enter the legal gambling age bracket.
Payment Technology and Security Infrastructure
Following the credit card gambling ban, Australian operators have accelerated investment in alternative payment technology including digital wallets, instant bank transfer systems, and prepaid voucher solutions. Cybersecurity investment has increased significantly in response to growing data breach risks associated with KYC (Know Your Customer) compliance requirements. Blockchain-based transaction verification is an emerging area being explored by operators seeking immutable, auditable records of gambling transactions for regulatory reporting purposes.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Game Type |
Sports Betting |
58.4% |
2025 |
|
Device |
Desktop |
54.3% |
2025 |
|
Region |
Australia Capital Territory and New South Wales |
38.6% |
2025 |

By Game Type
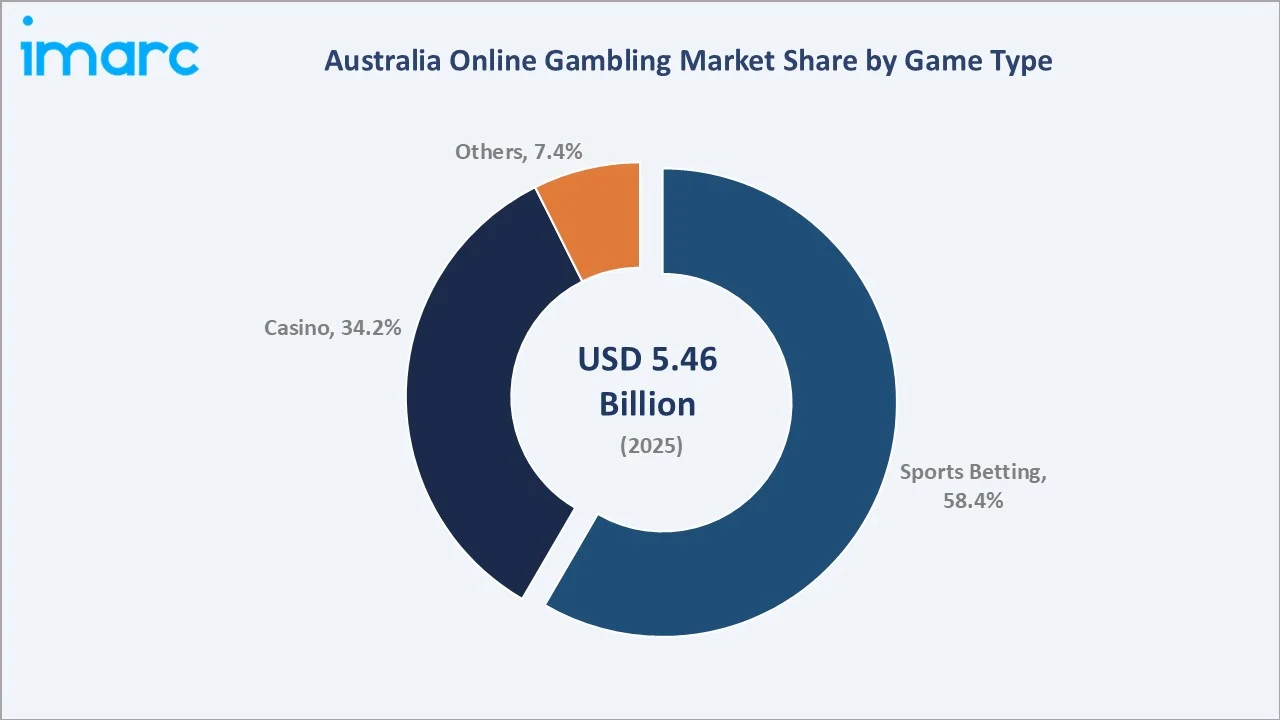
Sports betting leads at 58.4% (2025), through its deep integration with Australia's sporting culture and the proliferation of sophisticated in-play wagering platforms that support AFL, NRL, cricket, horse racing, and emerging esports markets.
To access detailed market analysis, Request Sample
Casino at 34.2% reflects strong demand for online live dealer games, slots, blackjack, baccarat, and poker that provide an immersive experience comparable to physical casinos. Others at 7.4% include lottery-style games and novelty wagering formats.
By Device
Desktop leads at 54.3% (2025), preferred by experienced gamblers for its large-screen interface, multi-tab betting capability, faster processing, and stable connection reliability during high-stakes live betting sessions.
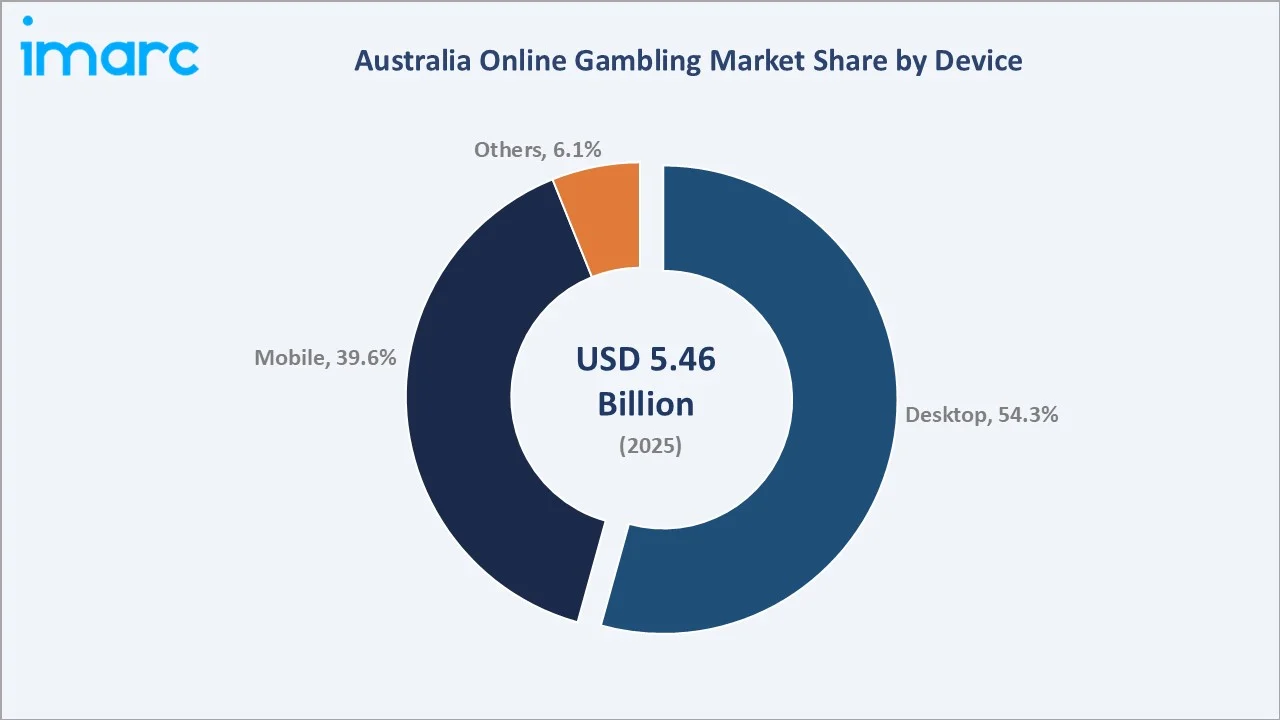
Mobile at 39.6% represents the fastest-growing access channel and is expected to narrow the gap with desktop through 2034 as native app experiences improve and younger demographics drive usage growth. Others at 6.1% include tablet devices and emerging connected TV gambling applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Australia Online Gambling Market Drivers & Characteristics |
|
Australia Capital Territory and New South Wales |
38.6% |
Reflecting the high population density, strong economic profiles, elevated disposable incomes, and a long-established sports betting tradition with broad user engagement across AFL, NRL, horse racing, and casino gaming platforms. |
|
Victoria & Tasmania |
24.7% |
Reflecting the large gambling-active population base, Melbourne's status as a major sporting event hub, advanced digital infrastructure, and strong consumer preference for live sports betting. |
|
Queensland |
18.5% |
Driven by a growing population base, increasing smartphone penetration, strong sports culture, and the rising adoption of mobile-first sports betting platforms. |
|
Western Australia |
10.2% |
Reflecting a distinct regulatory environment, creating a unique competitive structure with concentrated market participation through the state-owned platform. |
|
Northern Territory & Southern Australia |
8.0% |
Reflecting a relatively smaller population base alongside the strategic significance as the primary licensing jurisdiction for major Australian online gambling operators. |
The ACT and NSW region's 38.6% dominance is underpinned by Australia's two most economically active jurisdictions, combining Sydney's large urban gambling user base with the ACT's well-regulated framework and high-income population. Victoria and Tasmania's 24.7% reflect Melbourne's status as a major sporting event destination and the state's high engagement in AFL betting, racing wagering, and online casino gaming.
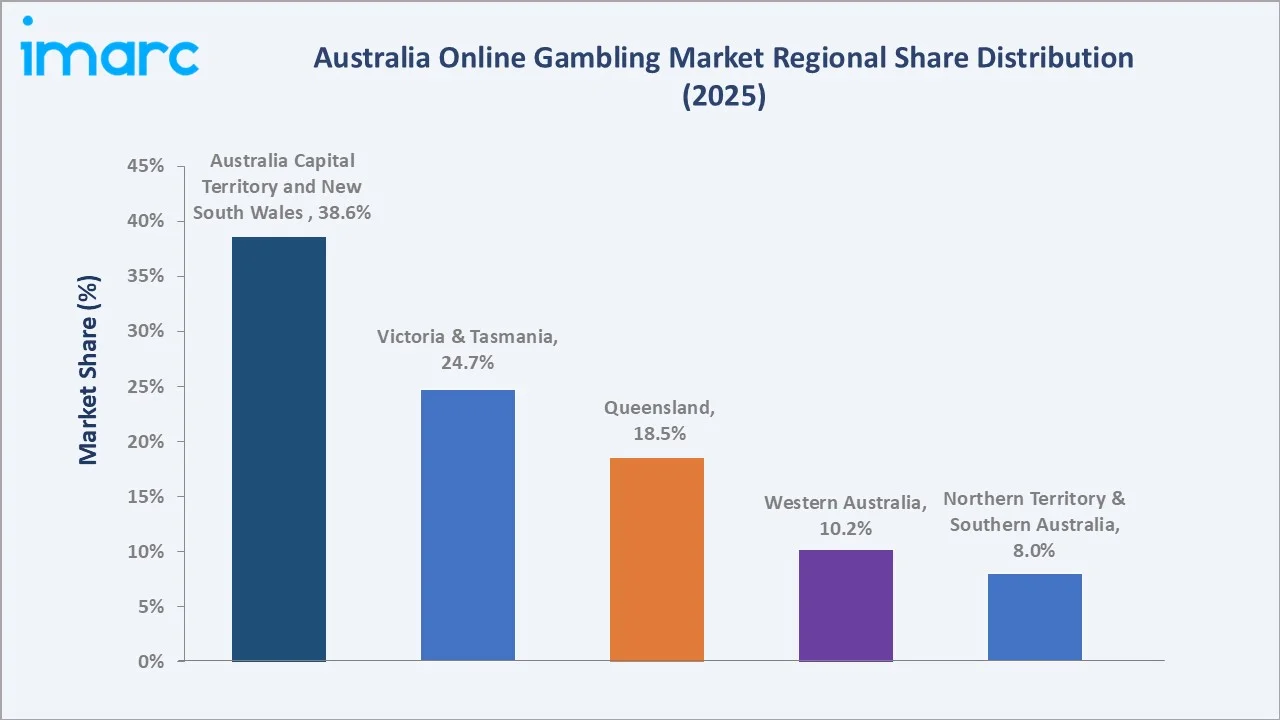
Queensland's 18.5% reflects a growing, younger population base with high mobile gambling adoption. Western Australia's 10.2% represents a unique market structure as the only state-licensed online bookmaker, creating a concentrated competitive environment. The Northern Territory and Southern Australia's combined 8.0% belies the NT's outsized strategic importance as the primary licensing jurisdiction for Australia's largest online gambling operators.
Competitive Landscape
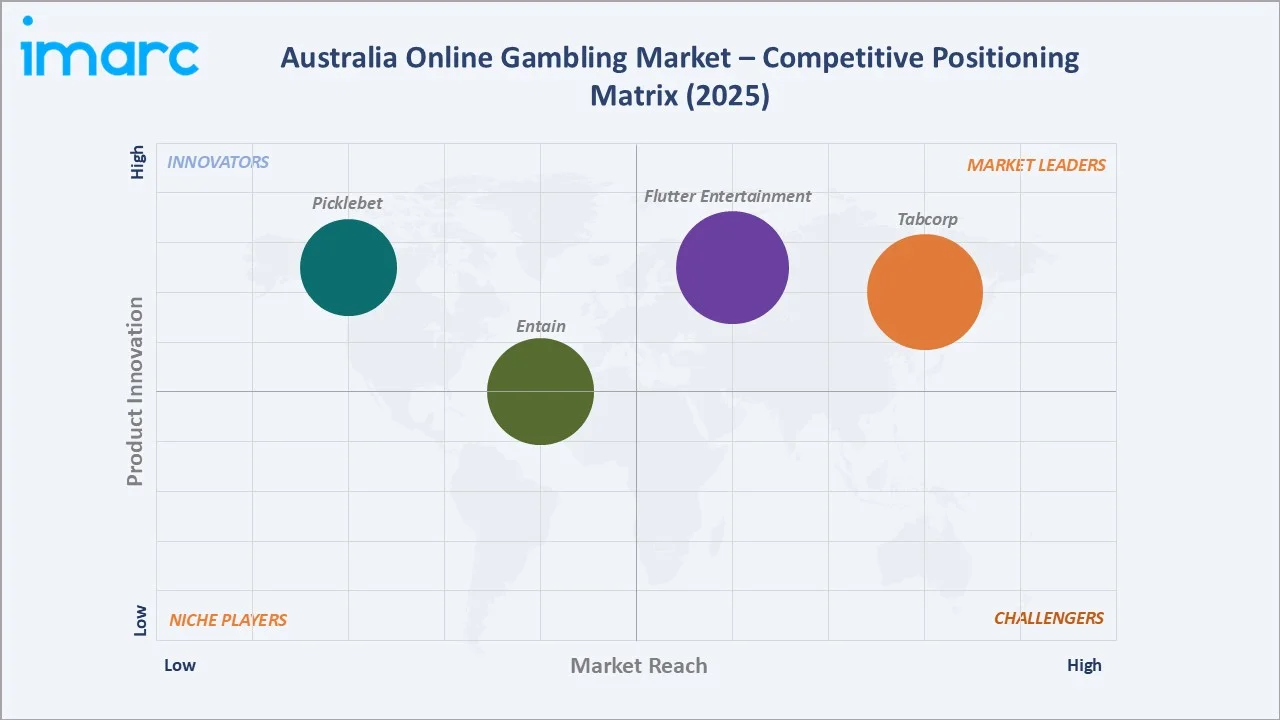
The Australia online gambling market is moderately consolidated. The competitive landscape is characterized by aggressive promotional spending, technology investment, and product differentiation through live betting features, odds competitiveness, and responsible gambling tool integration. Leading players are expanding into esports wagering and AI-driven personalization to capture younger demographics.
|
Company |
Key Brands |
Market Position |
Core Strength |
|
Flutter Entertainment |
Sportsbet |
Market Leader |
Australia represents one of Flutter’s most mature and cash-generative regions, serving as a cornerstone for the company's expansion and technological development. |
|
Tabcorp |
TAB |
Market Leader |
Tabcorp operates its flagship TAB brand across both extensive retail networks and expanding digital online platforms. |
|
Entain |
Ladbrokes Australia |
Established Player |
Entain plays a major role in the Australian online gambling market as one of the country's largest licensed wagering operators. |
|
Picklebet |
Picklebet |
Innovator |
Picklebet serves as a leading, next-generation niche bookmaker in the Australian online gambling landscape, bridging the gap between traditional sports betting and modern esports. |
Operators across the competitive landscape are intensifying investments in technology innovation, with particular focus on AI-driven personalization, esports market expansion, cryptocurrency payment integration, and enhanced responsible gambling compliance tools. The market is expected to experience further consolidation as global operators continue to strengthen their Australian portfolios through bolt-on acquisitions and product investment.
Key Company Profiles
Flutter Entertainment
Flutter Entertainment is a sports betting, gaming, and entertainment company operating a diversified portfolio of consumer-facing brands across multiple international markets. The company provides online sports betting, iGaming, and related digital gaming services, supported by proprietary technology and data capabilities. Its strategy focuses on delivering engaging customer experiences, expanding its digital presence, and strengthening its position across regulated gambling markets.
- Key Brands: Sportsbet.
- Strategic Focus: Aims to grow its local brands through continued organic investment and strategic M&A, while using geographic and product diversification to enhance long-term earnings.
Tabcorp
Tabcorp is a major Australian gambling and entertainment company with operations spanning wagering, media, and gaming services. The company provides betting products across racing and sports, supported by a broad retail and digital distribution network. It also operates media assets that strengthen customer engagement and wagering activity. Tabcorp’s business model centers on regulated market participation, brand recognition, and integrated betting and media capabilities.
- Key Brands: TAB
- Strategic Focus: Strengthening its digital wagering capabilities, enhancing customer engagement, and improving operational efficiency across its core betting and media businesses. The company also emphasizes responsible gambling, regulatory compliance, and sustainable growth in the Australian market.
Market Concentration Analysis
The Australia online gambling market exhibits moderate concentration, with the top four players, Flutter Entertainment, Tabcorp, Entain, and Picklebet collectively accounting for approximately 65-70% of total regulated market revenues in 2025. The remaining share is distributed among mid-tier operators and emerging players. Market concentration is supported by significant regulatory compliance costs, brand recognition requirements, and technology investment thresholds that create barriers to entry for new competitors.
Consolidation pressure continues through M&A activity, with the global parent companies of leading Australian operators actively seeking portfolio optimization opportunities. The dual-brand strategy in Australia reflects a broader industry trend toward market segmentation through complementary brand positioning rather than direct competition. Emerging niche operators focused on esports betting and lottery innovation represent potential acquisition targets for larger incumbents seeking to capture younger demographic cohorts.
Investment & Growth Opportunities
Highest Growth Segments
Esports wagering (emerging from a small base at ~15%+ CAGR), mobile platform wagering (~6.5% CAGR), live in-play betting, fixed payout lottery innovations, and responsible gambling technology platforms represent the highest-growth investment vectors in the Australia online gambling market through 2034.
Investment Themes
- Esports and new demographic capture: With 18-34 year-old Australians representing the fastest-growing gambling demographic and esports viewership expanding significantly, licensed esports wagering platforms can capture users who may not engage with traditional sports betting products.
- Responsible gambling technology and regulatory compliance platforms: Increasing regulatory scrutiny is creating commercial opportunity for technology providers offering compliance automation, AI-based harm detection, self-exclusion registry integration, and responsible gambling analytics. Operators that can demonstrate superior responsible gambling frameworks will achieve regulatory goodwill and consumer trust advantages.
Future Market Outlook (2026-2034)
The Australia online gambling market is projected to grow from USD 5.46 Billion in 2025 to USD 5.76 Billion in 2026, reaching USD 8.96 Billion by 2034, exhibiting a CAGR of 5.67% during 2026-2034. The market is expected to reach an anchor value of USD 7.19 Billion by 2030, reflecting the mid-period acceleration driven by esports betting mainstream adoption, mobile platform maturity, and the post-regulatory stabilization period following the implementation of the credit card ban and advertising reform measures.
Three structural forces will define the Australia online gambling market through 2034. First, the progressive maturation of mobile gambling as the primary access channel will narrow the gap with desktop, with mobile projected to approach parity by 2030, and the growing share of digital-native consumers entering the legal gambling age bracket. Second, the regulatory environment will continue to evolve, with advertising reform likely to reshape customer acquisition strategies and drive higher investment in organic and affiliate-based marketing channels. Third, technology-driven product innovation in esports wagering, fixed payout lottery formats, AI personalization, and blockchain-based transparent wagering will expand the total addressable market by attracting new demographic segments.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with senior executives from licensed online gambling operators, technology platform providers, payment gateway specialists, regulatory affairs experts, and industry analysts. These discussions validated market size estimates, assessed consumer behavior trends, evaluated competitive dynamics, and provided insights into regulatory developments, technology investment priorities, and future growth opportunities in the Australia online gambling market.
Secondary Research
Secondary research encompassed enforcement reports, company annual reports and press releases, gambling statistics, Australian Gambling Research Centre surveys, online gambling participation data, press releases from major operators, and industry publications focused on the Australian gaming and wagering market.
Forecasting Models
Forecasting models were developed using historical market revenue trends, consumer participation data, regulatory impact assessments, and macroeconomic indicators including household disposable income and internet penetration. Both top-down and bottom-up approaches were applied, with CAGR-based regression models adjusted for regulatory headwinds, advertising reform scenarios, and technology adoption acceleration trajectories.
Australia Online Gambling Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Game Types Covered |
|
| Devices Covered | Desktop, Mobile, Others |
| Regions Covered | Australia Capital Territory and New South Wales, Victoria and Tasmania, Queensland, Northern Territory & Southern Australia, Western Australia |
| Companies Covered | Flutter Entertainment, Tabcorp, Entain, Picklebet, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Australia online gambling market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Australia online gambling market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Australia online gambling industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Australia Online Gambling Market Report
The Australia online gambling market size is estimated at USD 5.76 Billion in 2026, driven by a favorable regulatory environment, high consumer gambling participation rates, rapid digital adoption, and the growing appeal of sports betting and in-play wagering across AFL, NRL, cricket, and horse racing.
The Australia online gambling market grows at a 5.67% CAGR during 2026-2034, reaching USD 8.96 Billion by 2034, reflecting sustained sports betting demand, mobile platform expansion, esports wagering growth, and ongoing digital infrastructure improvement.
Sports betting leads with a 58.4% share in 2025, underpinned by Australia's deep sporting culture and high consumer engagement with AFL, NRL, horse racing, and cricket wagering through sophisticated real-time in-play betting platforms.
Desktop leads with a 54.3% share in 2025, preferred by experienced bettors for larger screens, multi-tab betting, superior graphics, and stable connectivity during live sports betting events, though mobile is the fastest-growing access channel.
The ACT and New South Wales region lead with a 38.6% share in 2025, driven by high population density, elevated disposable incomes, long-established gambling traditions, and the concentration of major operator digital infrastructure and marketing in Sydney and Canberra.
Leading companies include Flutter Entertainment, Tabcorp, Entain, and Picklebet, among others.
The market is projected to reach approximately USD 7.19 Billion by 2030, representing the mid-period milestone driven by mobile platform maturity, in-play betting expansion, esports wagering growth, and progressive stabilization of the post-credit card ban regulatory environment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade